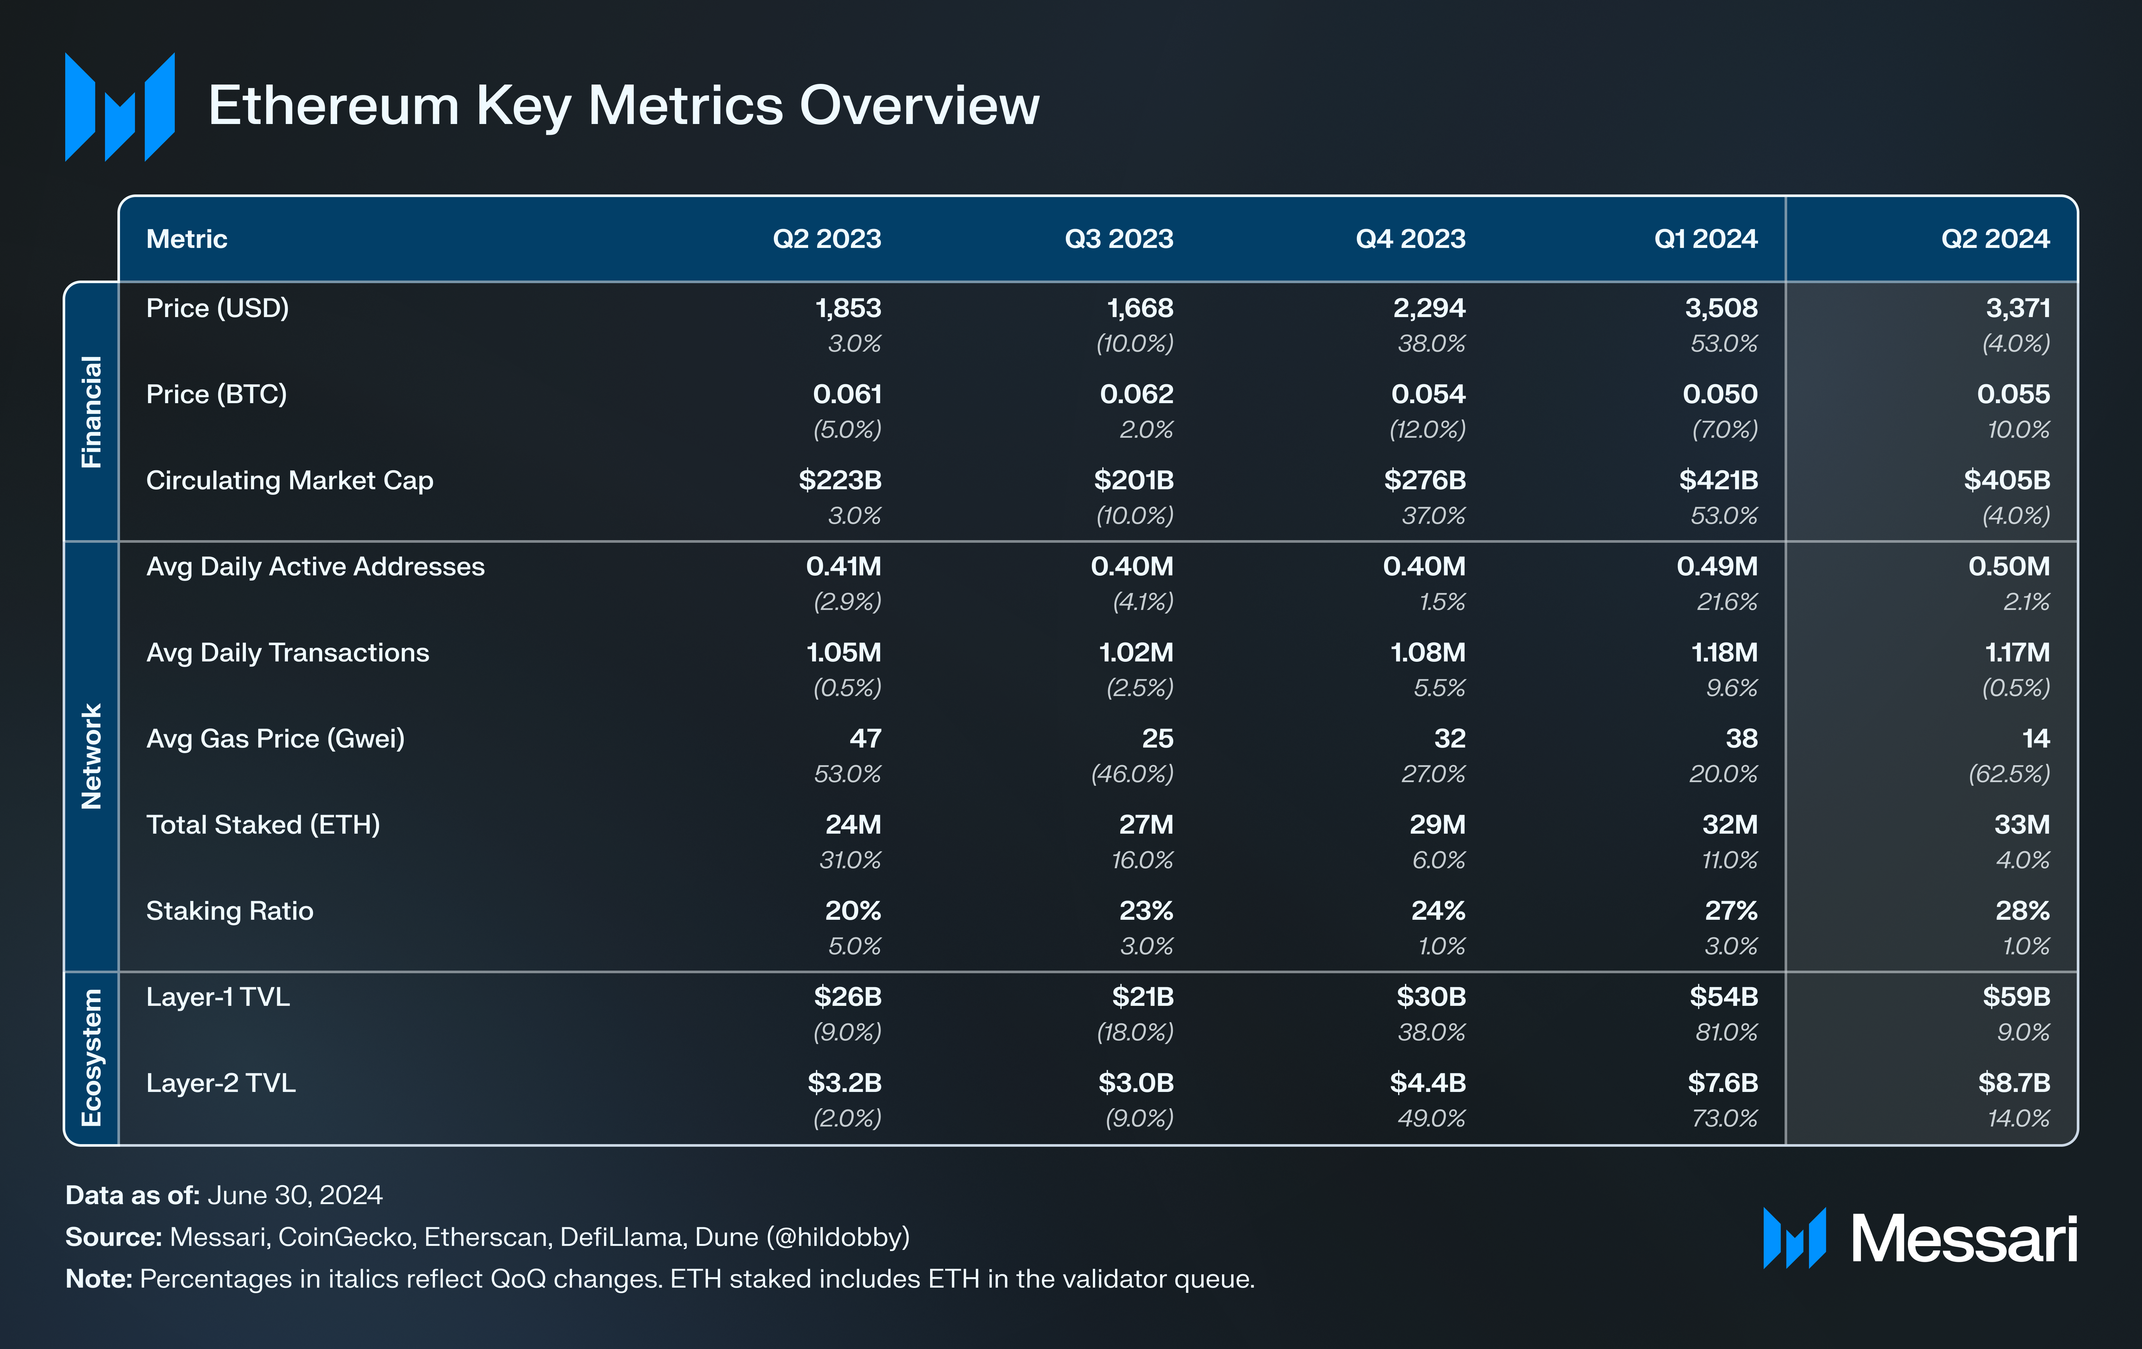
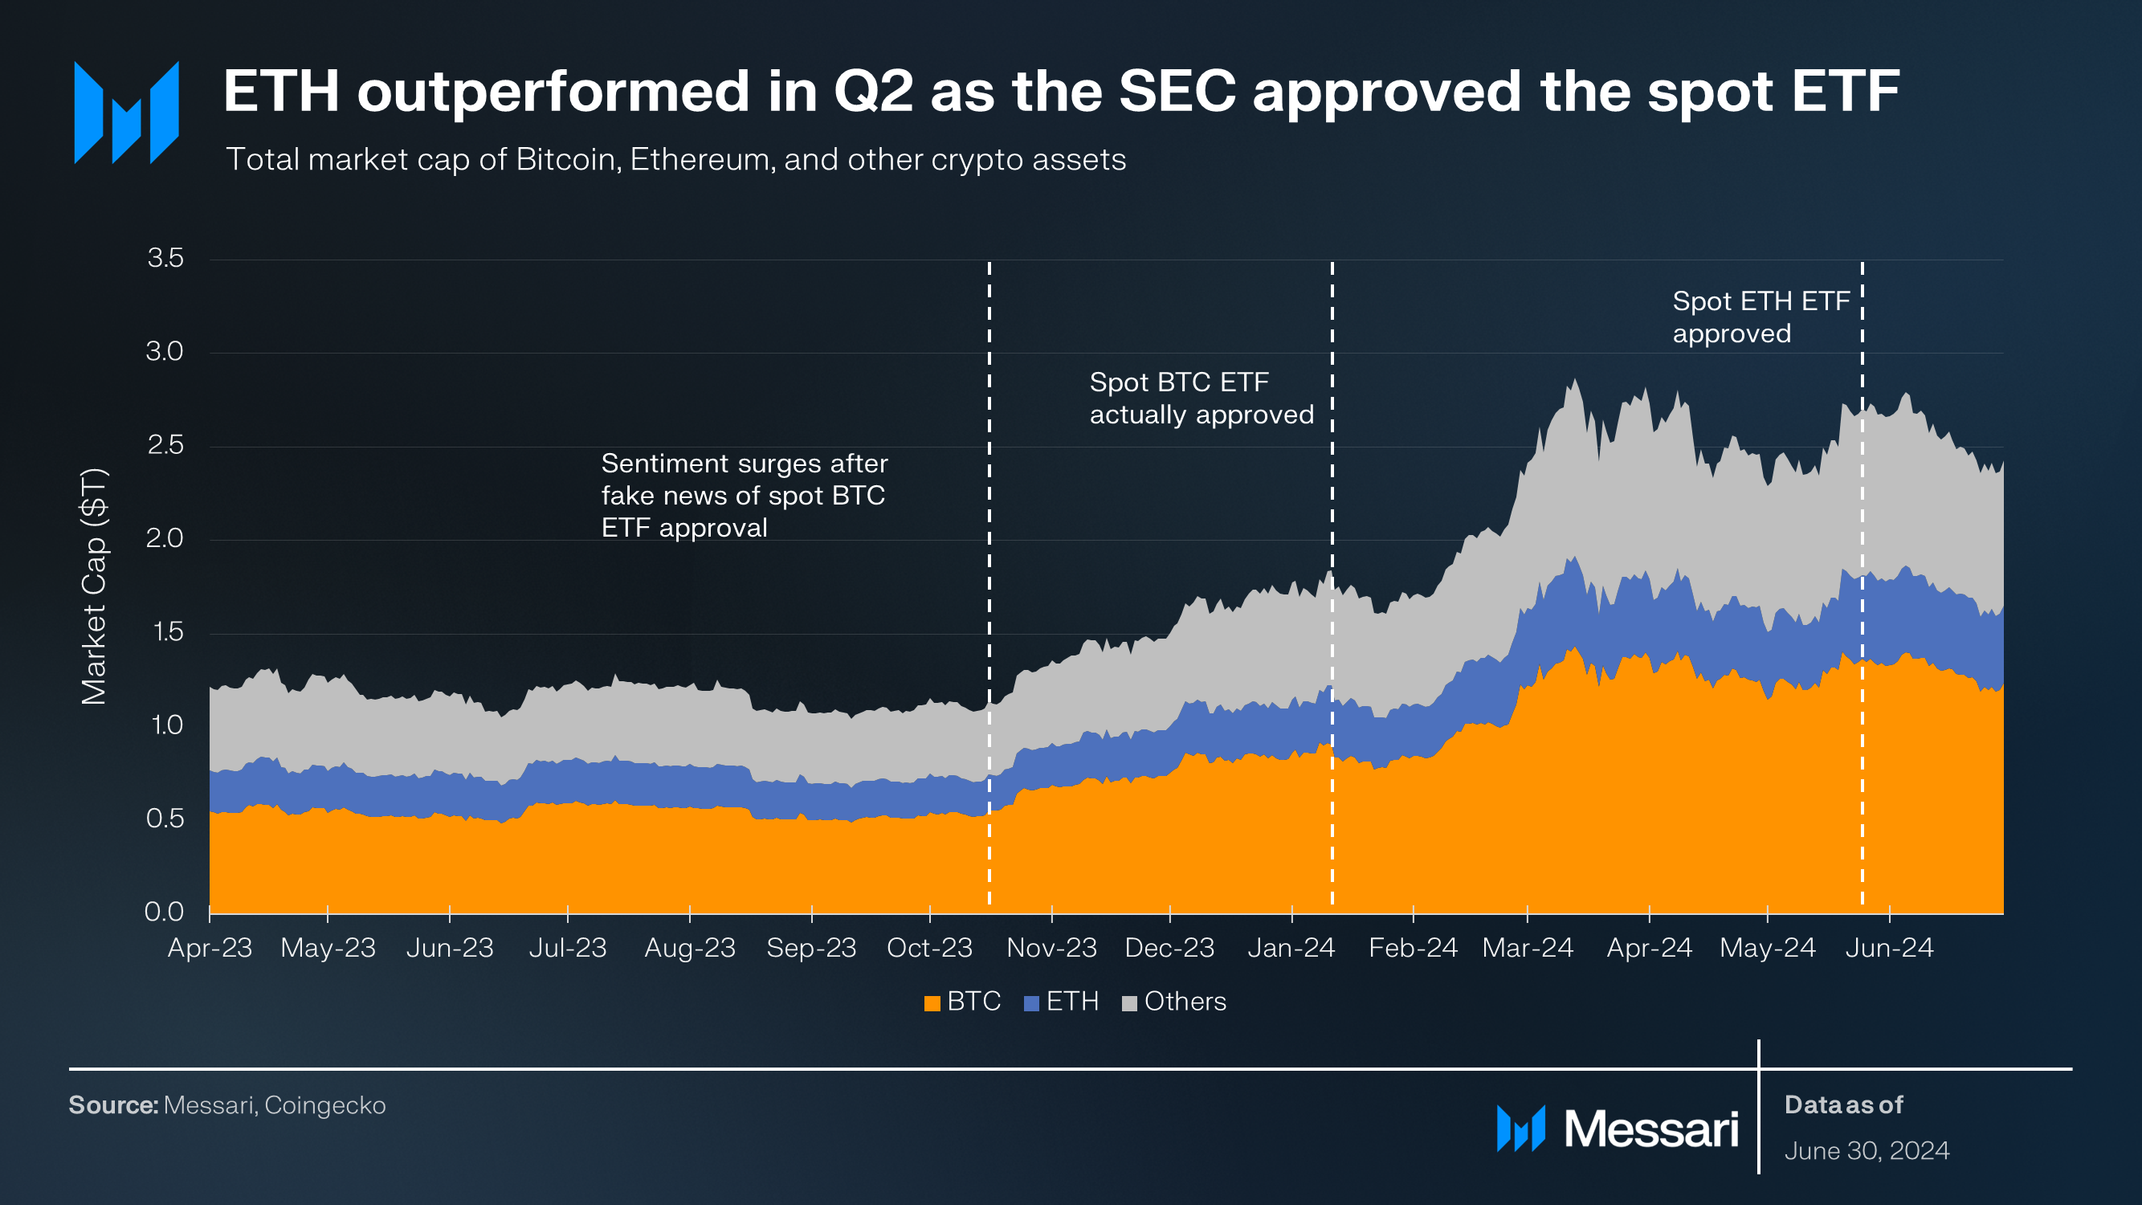
The quarter's story was the SEC's surprise turnaround and approval of the spot ETH ETF. Despite regulatory tailwinds, most crypto asset prices declined over the quarter.
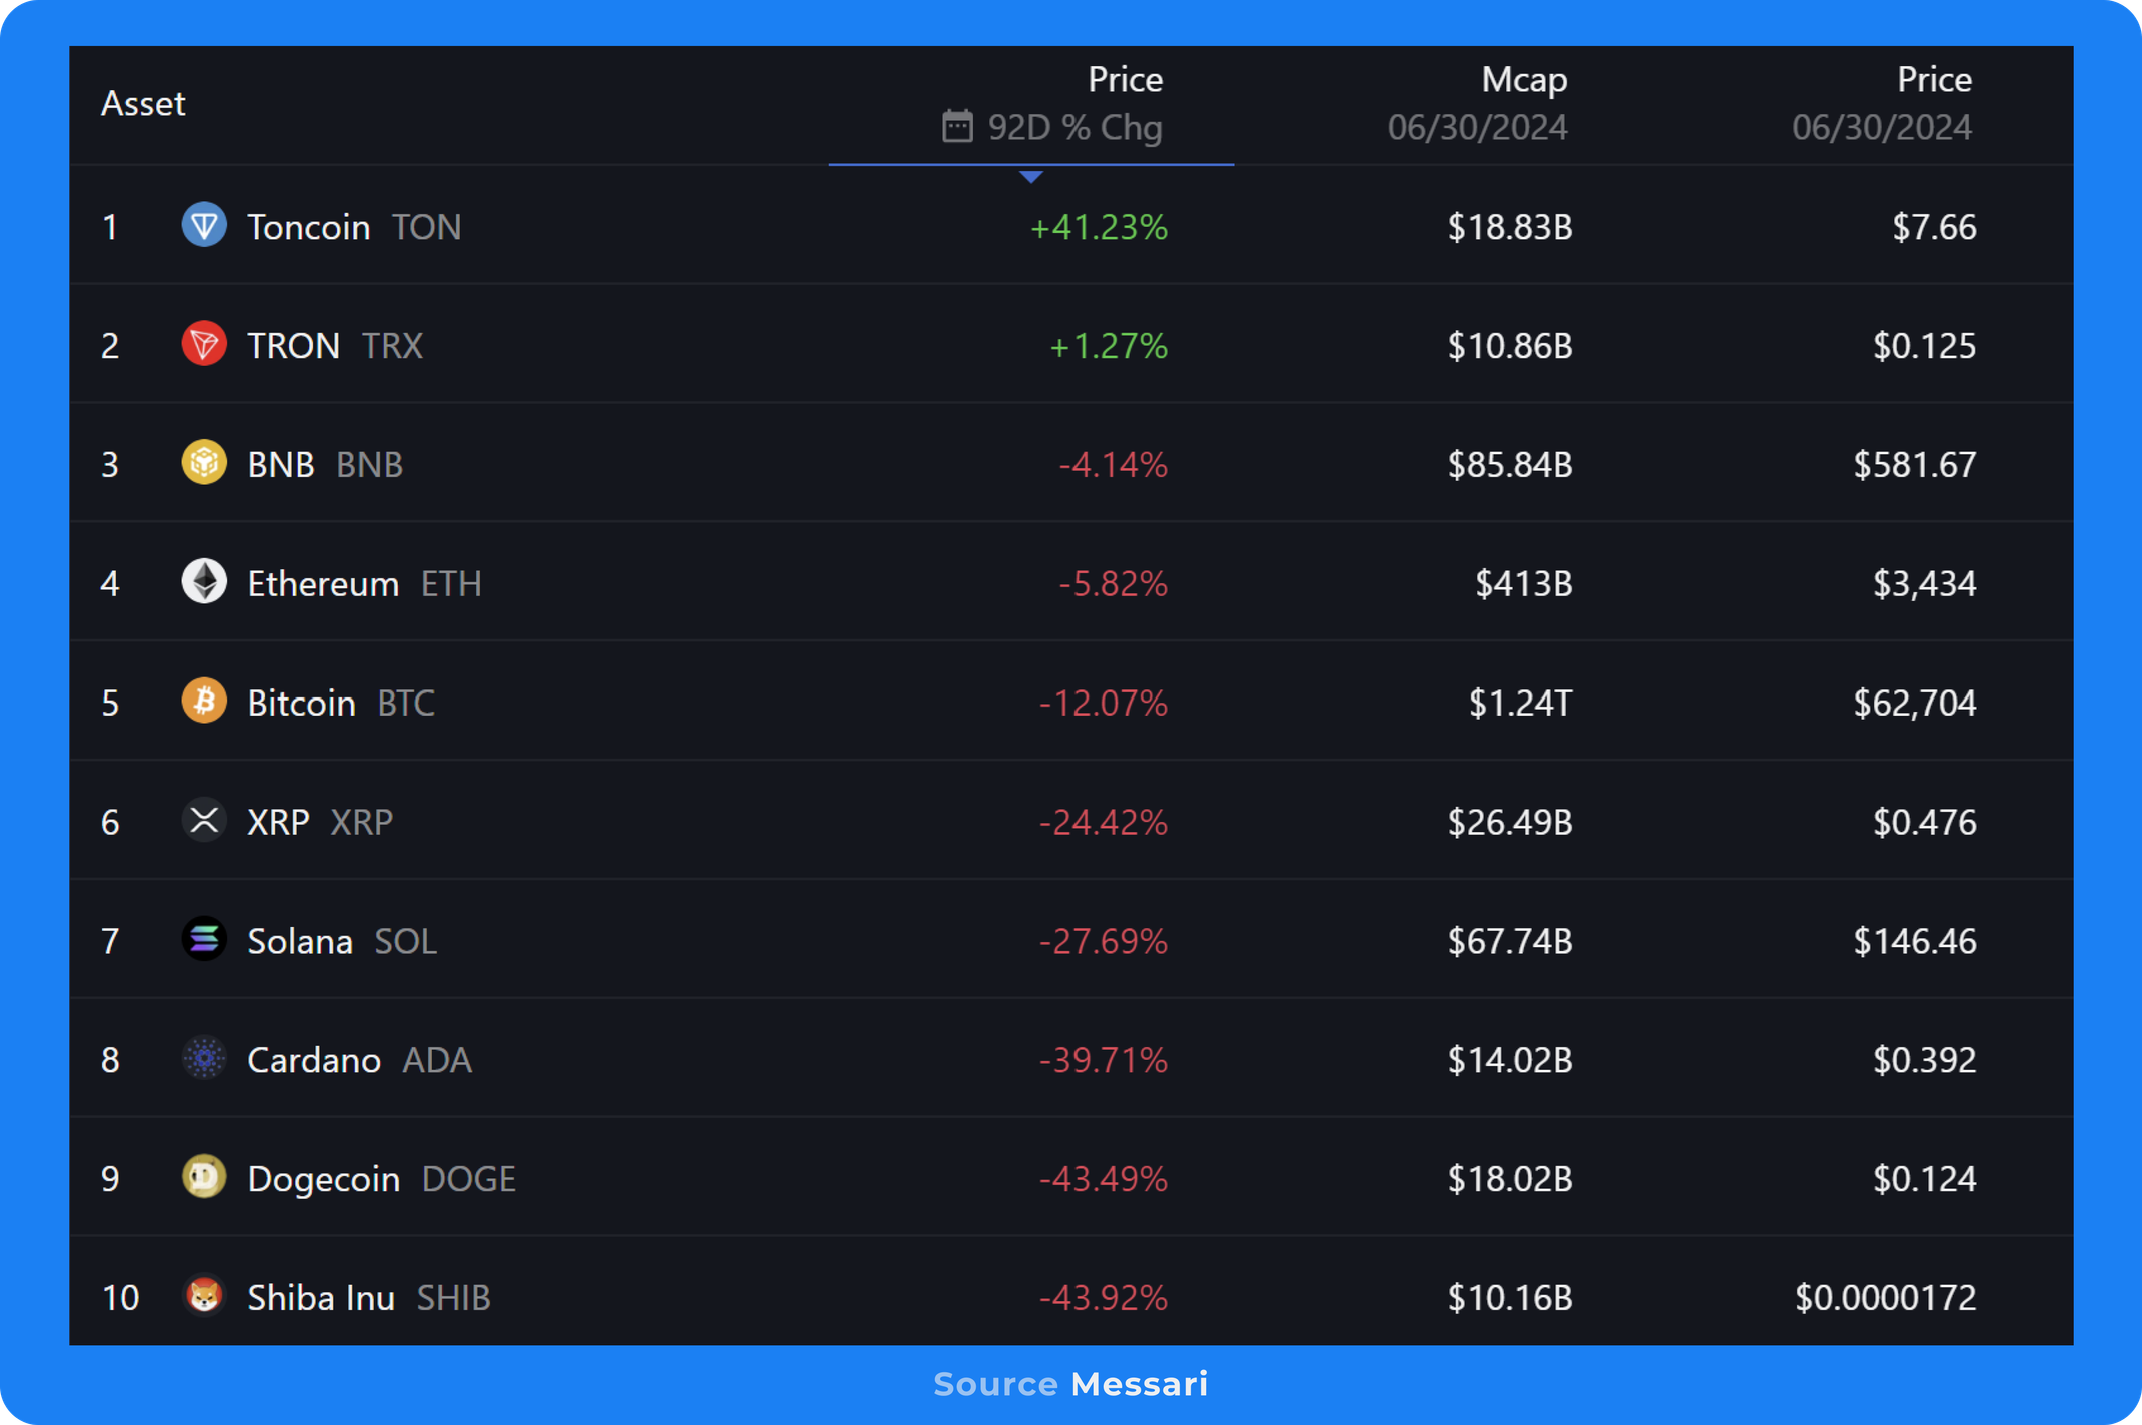
ETH outperformed, with its price declining less than other major assets. ETH fell by 6%, while BTC fell by 12%, and prominent top-10 crypto assets fell by more than 20%.
Ethereum’s annualized inflation came in hot at 0.4%. Real yields continued to fall, prompting discussions of changes to issuance.
Ethereum’s fundamental metrics remained largely flat over the quarter. Active addresses,transaction activity, TVL, and DEX volumes saw no material change.
Rollup transaction fees fell sharply after Dencun, and L2 transaction activity grew 65% sequentially. The strong growth in rollup activity bodes well for Ethereum’s scaling vision.
Primer
Ethereum (ETH) is a distributed blockchain computing platform for smart contracts and decentralized applications. Ethereum’s smart contracts have enabled the creation of various new assets and industries, such as Decentralized Finance (DeFi), Non-Fungible Tokens (NFTs), Decentralized Autonomous Organizations (DAOs), and more. It features an execution engine optimized for smart contract processing, the Ethereum Virtual Machine (EVM).
Ethereum has chosen a scaling strategy through a network of Layer-2 protocols to meet the growing demand for blockspace. Through this strategy, Ethereum plans to scale while maintaining a high degree of decentralization. These protocols rely on Ethereum for data availability and security, while they only focus on fast execution. Ethereum underwent a network upgrade in Q1 2024 that allows it to better serve the needs of these protocols by creating a separate transaction type to store data and reduce the costs for the Layer-2s.
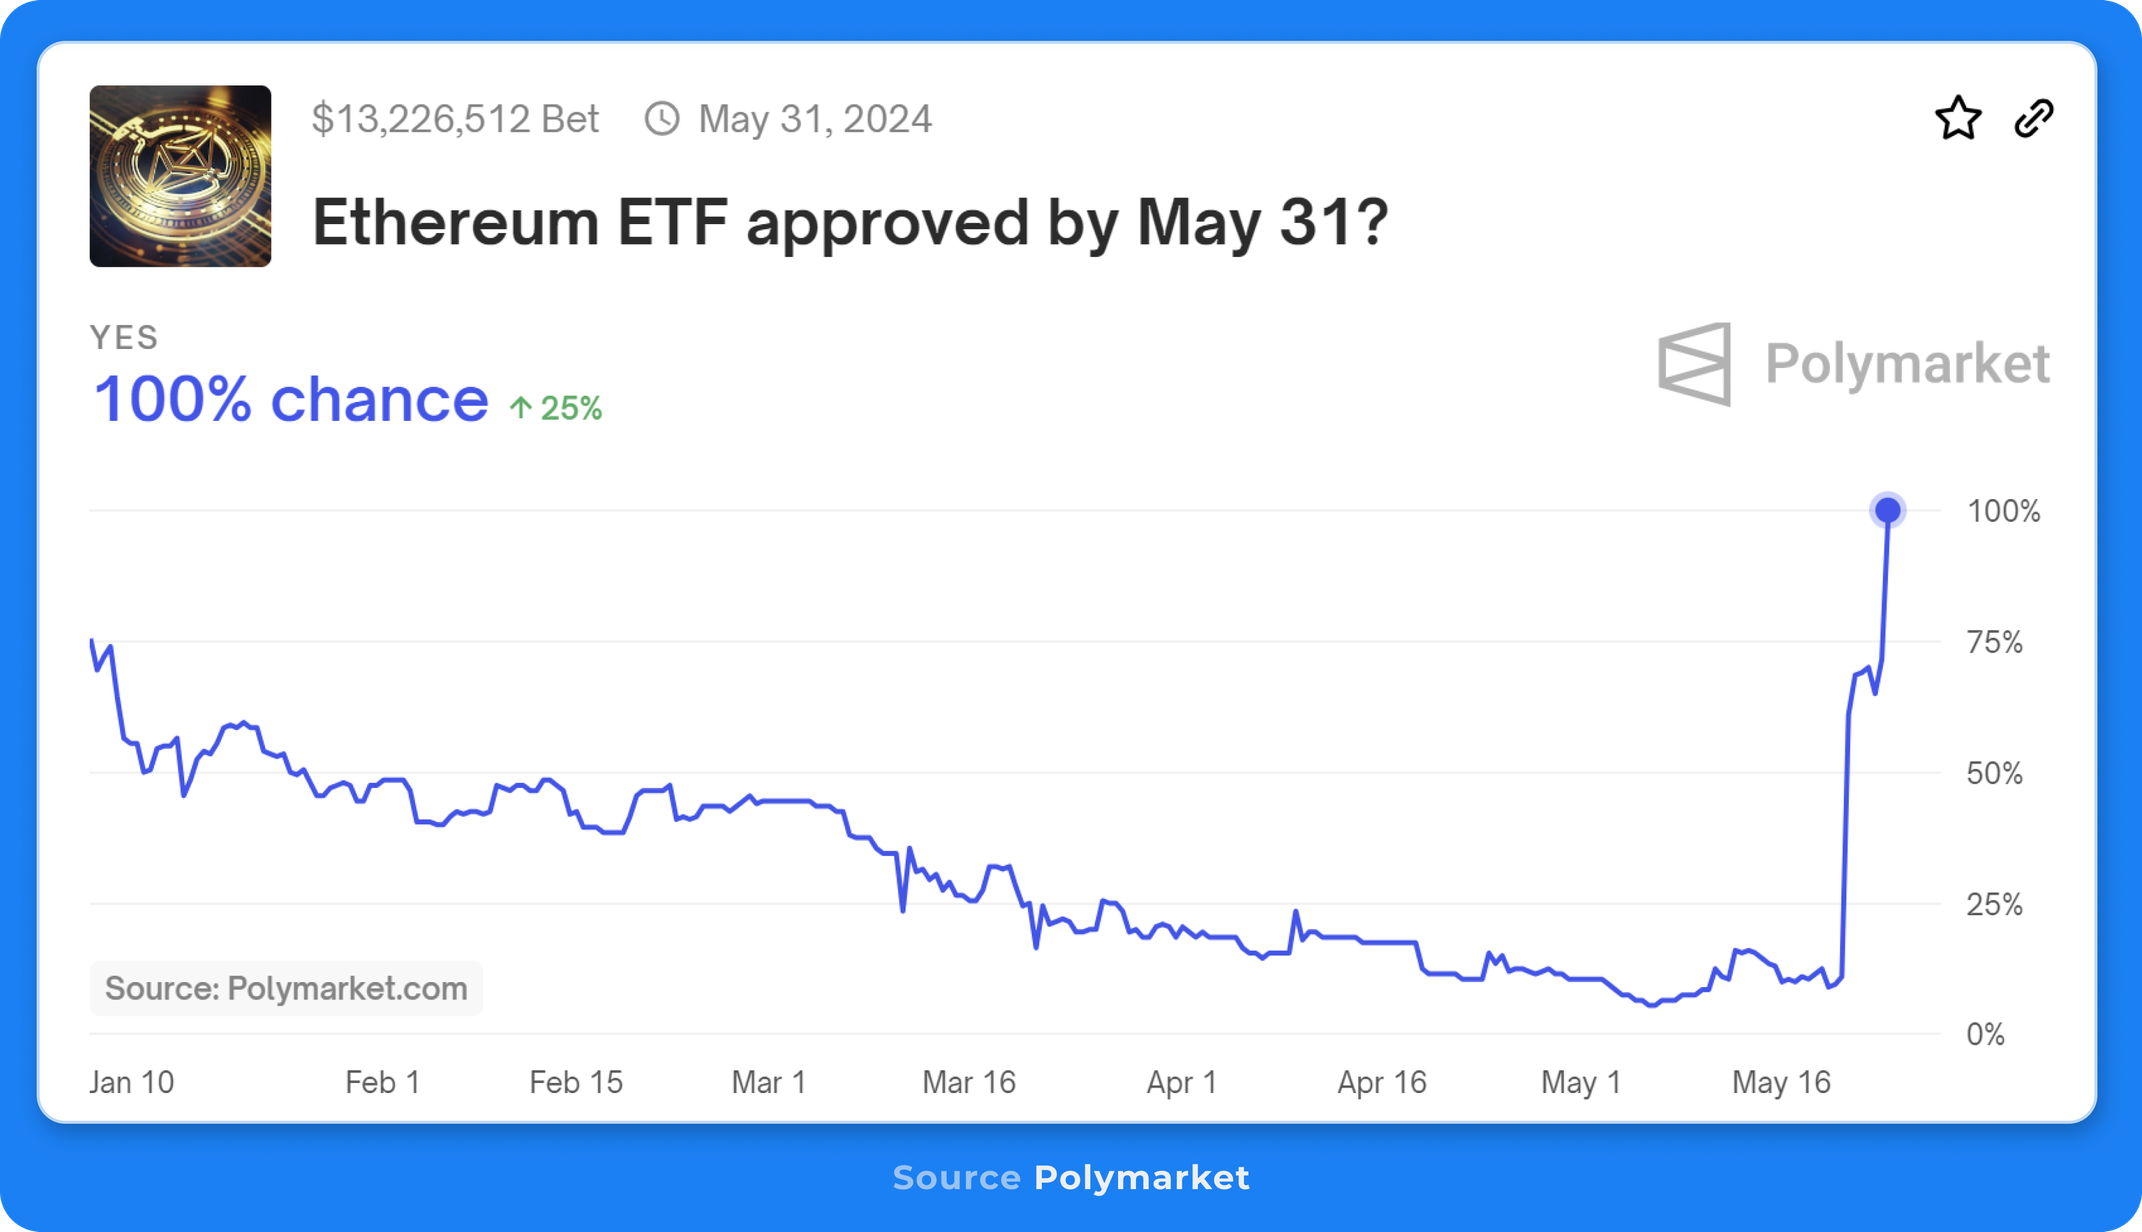
The story of the quarter was the U.S. Securities and Exchange Commission (SEC)'s surprise approval of the spot Ethereum ETF. ETF experts and Polymarket’s prediction market suggested a low approval probability until the SEC’s apparent turnaround in late May. The surprise approval breathed much-needed life into the market just as investor interest was waning. Across crypto, the regulatory overhang is reducing as silver linings emerge among the historically dark clouds.
Following the ETF approval, crypto prices appreciated somewhat, but the market gave it all back by the end of the quarter. Perhaps investors are waiting for the trading of the spot ETH ETFs to begin. Even for the Bitcoin spot ETF, BTC appreciated more sharply after large net inflows were reported compared to the initial market reaction after its ETF approval.
Despite the surprise ETF approval and improving regulatory outlook, crypto assets had poor performance through Q2 as the market cooled down after a very hot Q1. TON was a notable exception among the top assets, with 40% quarterly price growth. ETH outperformed once again in a down market with only a 6% price drop. Its fall was lower than BTC’s and much lower than other prominent top-10 assets like Solana, Cardano, and Dogecoin, which fell by 25%+.
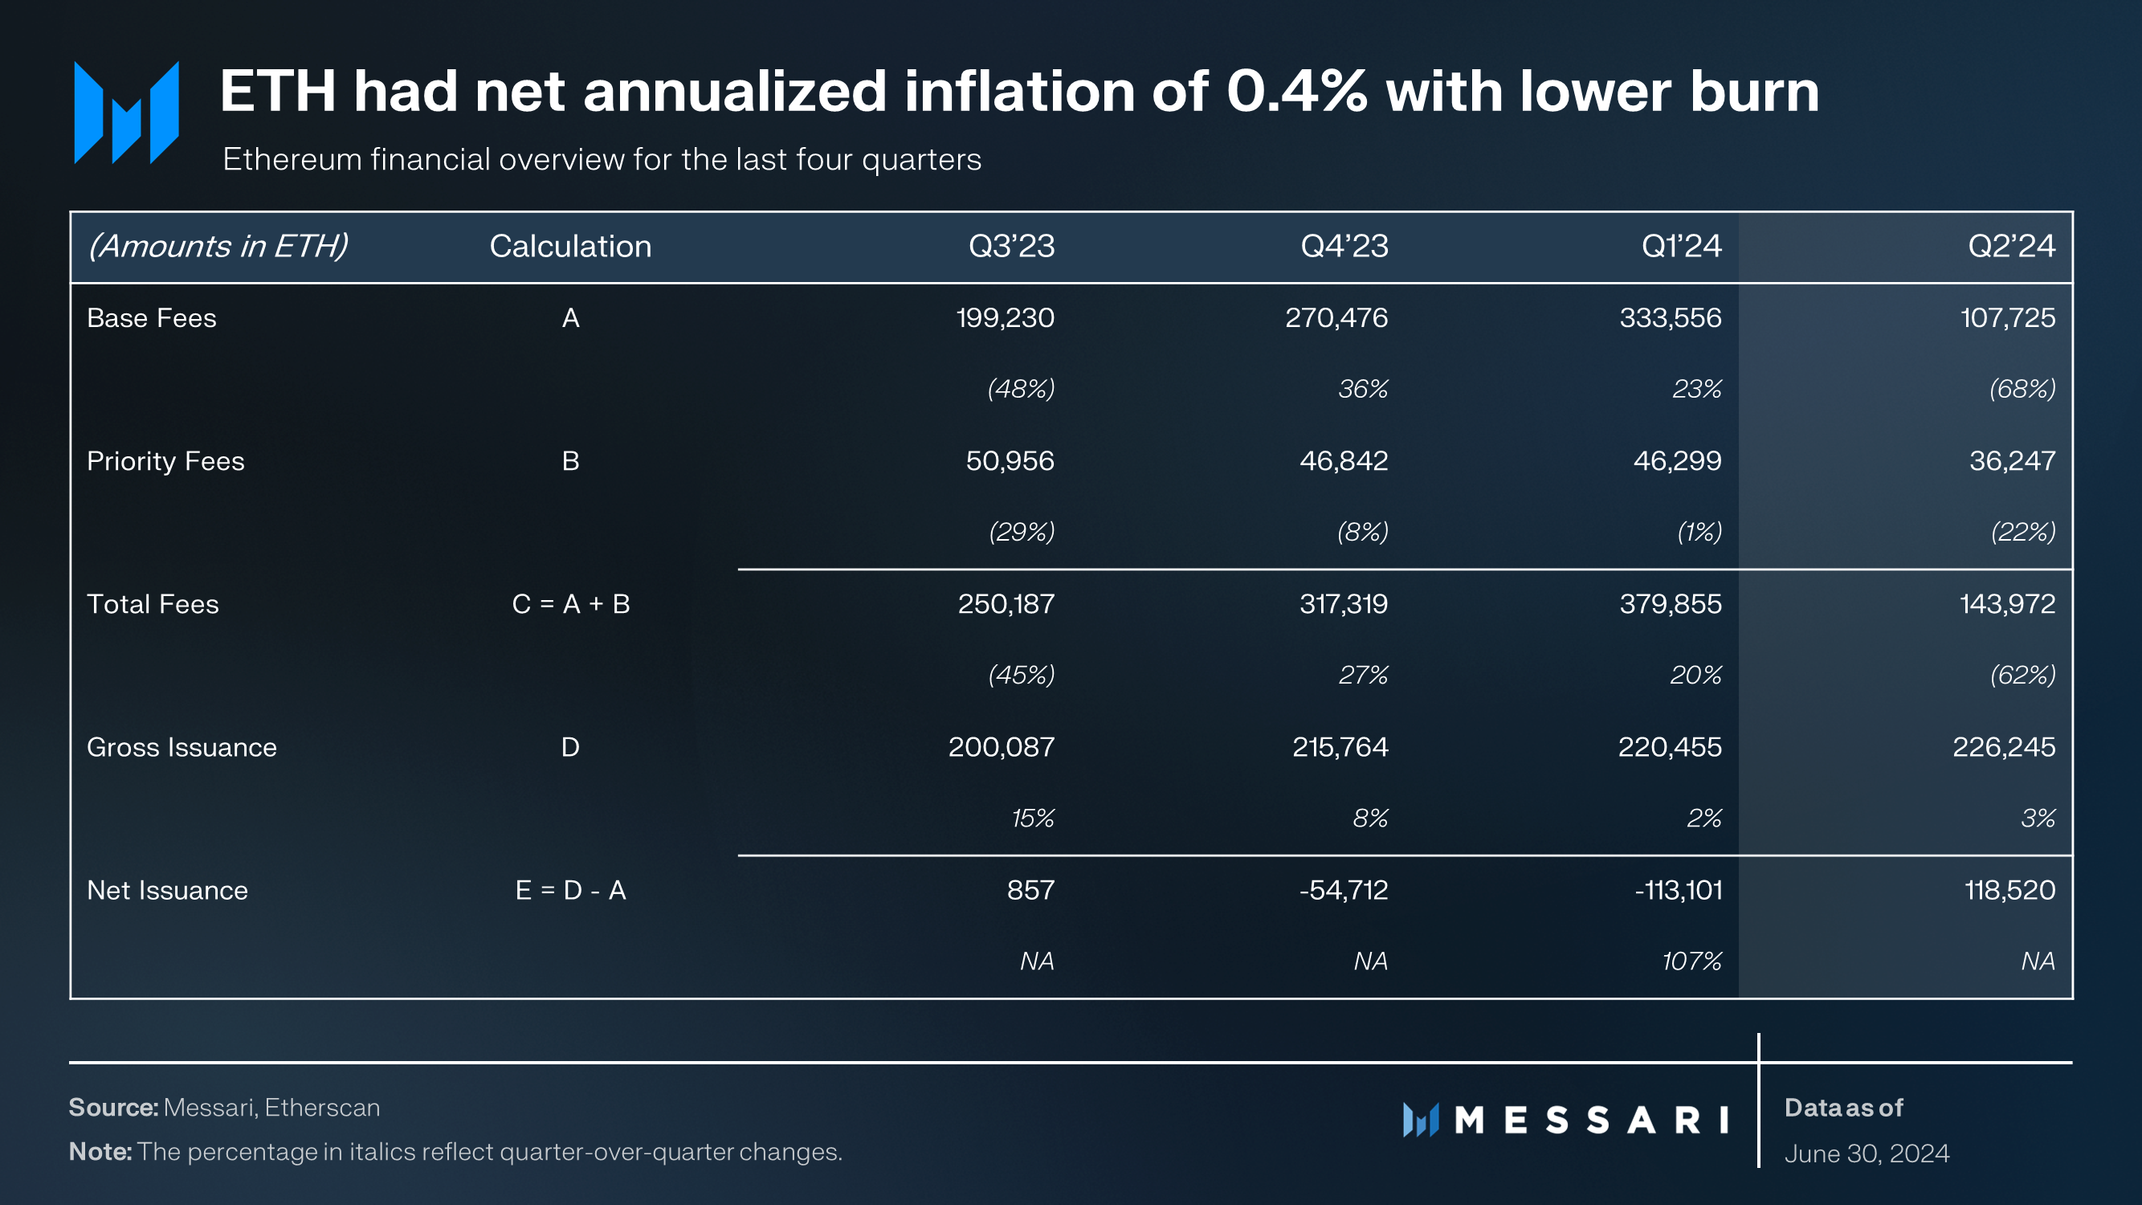
A falling market and lower investor interest meant significantly lower mainnet activity. For only the second time since the Merge, ETH had positive net issuance over an entire quarter. While 226,000 ETH was issued, only 108,000 ETH was burnt through transaction fees, leading to a net issuance of ~119,000 ETH at an annualized inflation rate of 0.4%.
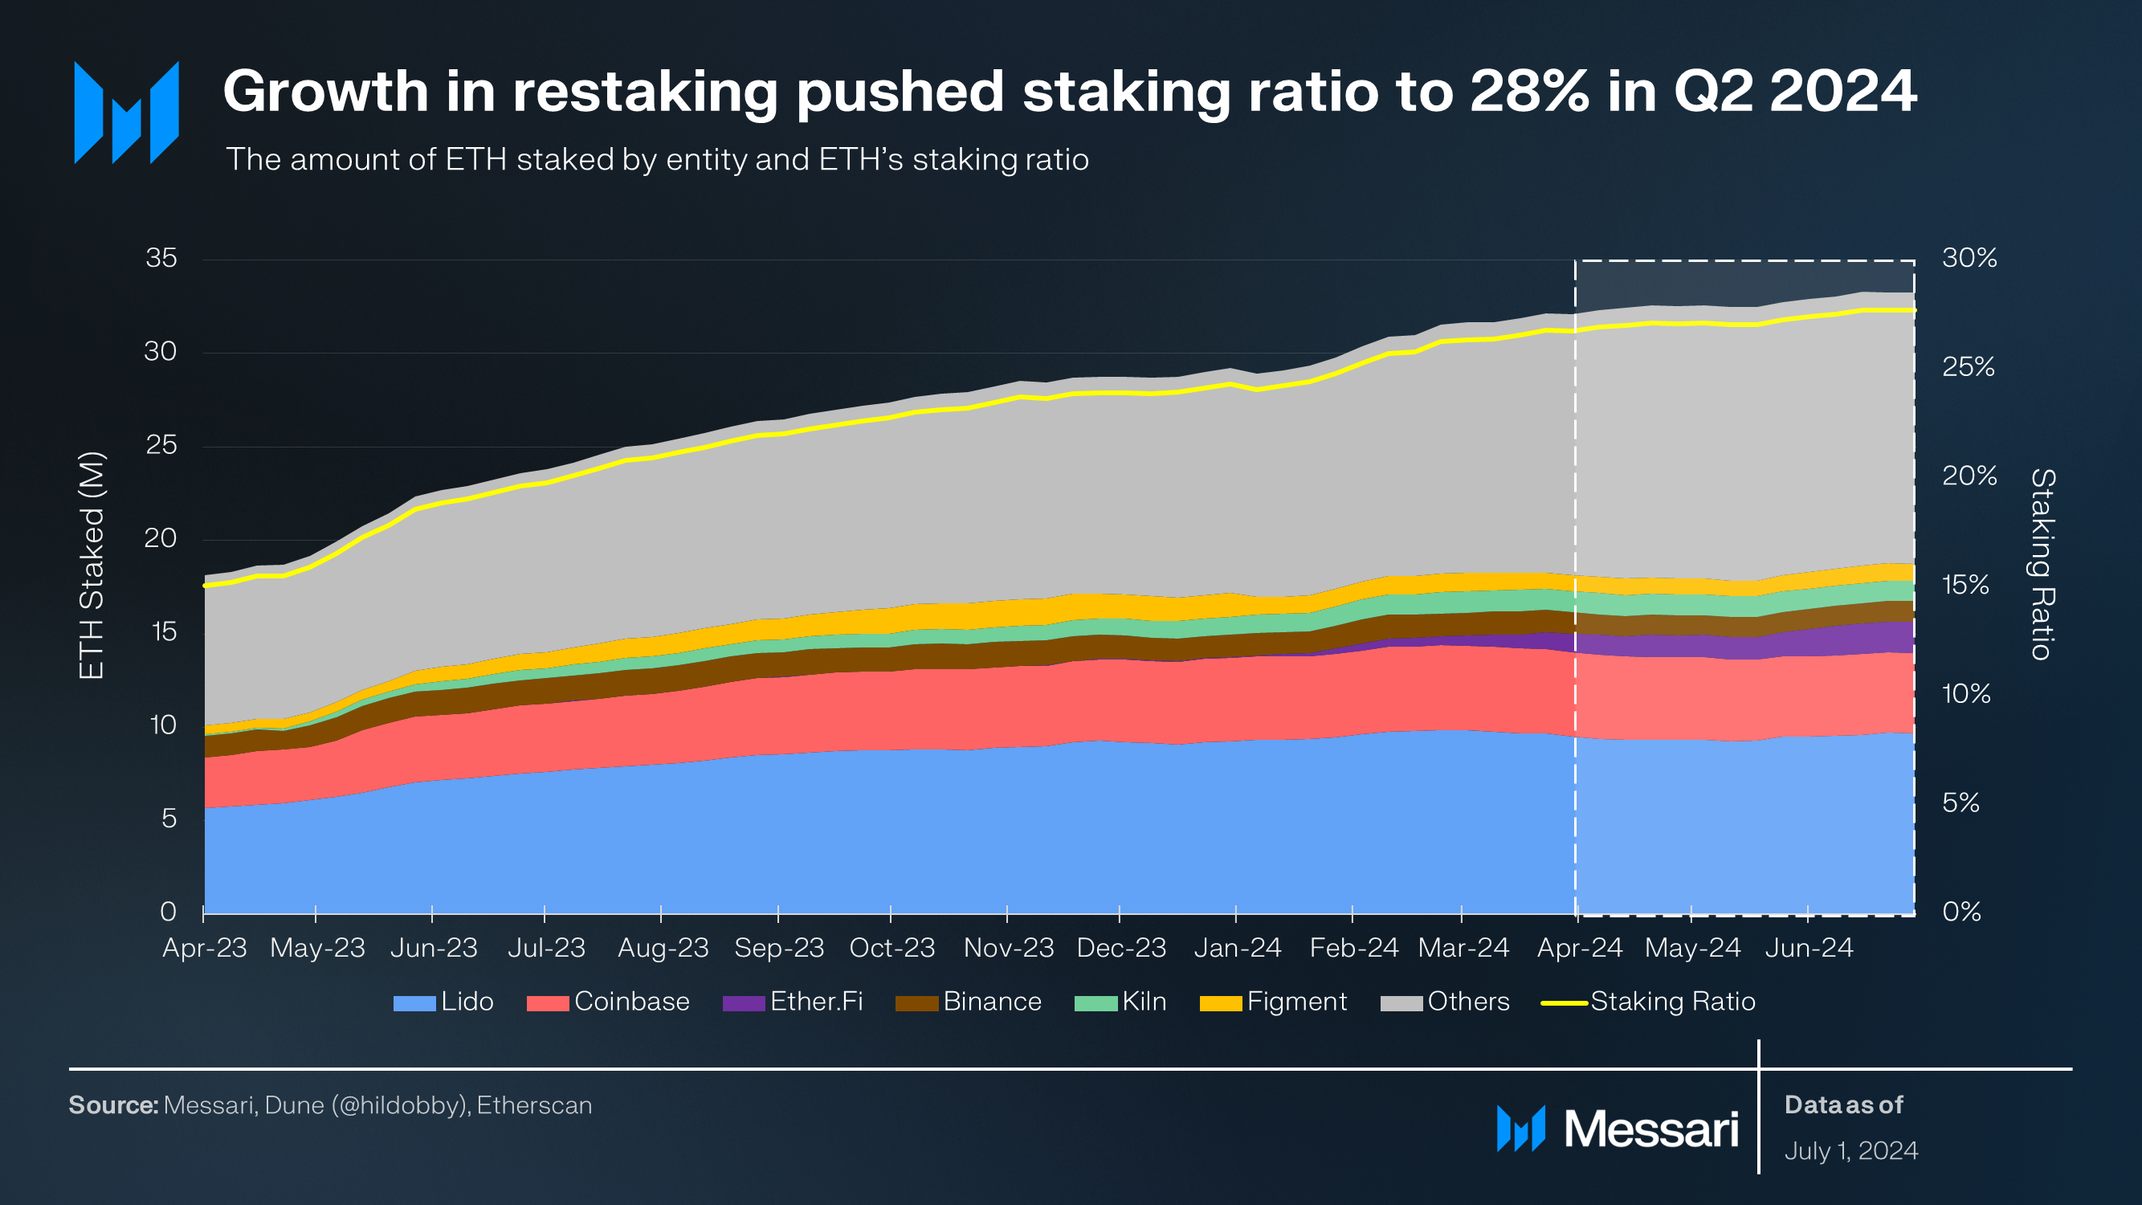
Since the beginning of 2023, ETH’s staking ratio has grown steadily. At the end of Q2 2024, it stood at 28%, up from 27% at the beginning of the quarter. Q2 recorded net inflows of 1.2 million ETH into the staking contract, compared to 3 million in Q1 2024.
The excitement around EigenLayer and restaking, with the consequent growth in liquid restaking protocols, primarily drove the growth in ETH staking. Ether.Fi, the largest liquid restaking protocol (LRT), grew its TVL by a whopping 690,000 ETH over the quarter. Its increase alone contributed to almost 60% of total staking growth.
LRT growth may have come at the cost of other large staking entities, which experienced slowing growth or even decline. Lido’s TVL grew by a meager 2%, and Coinbase saw outflows of 200,000 ETH, the highest among the top staking entities.
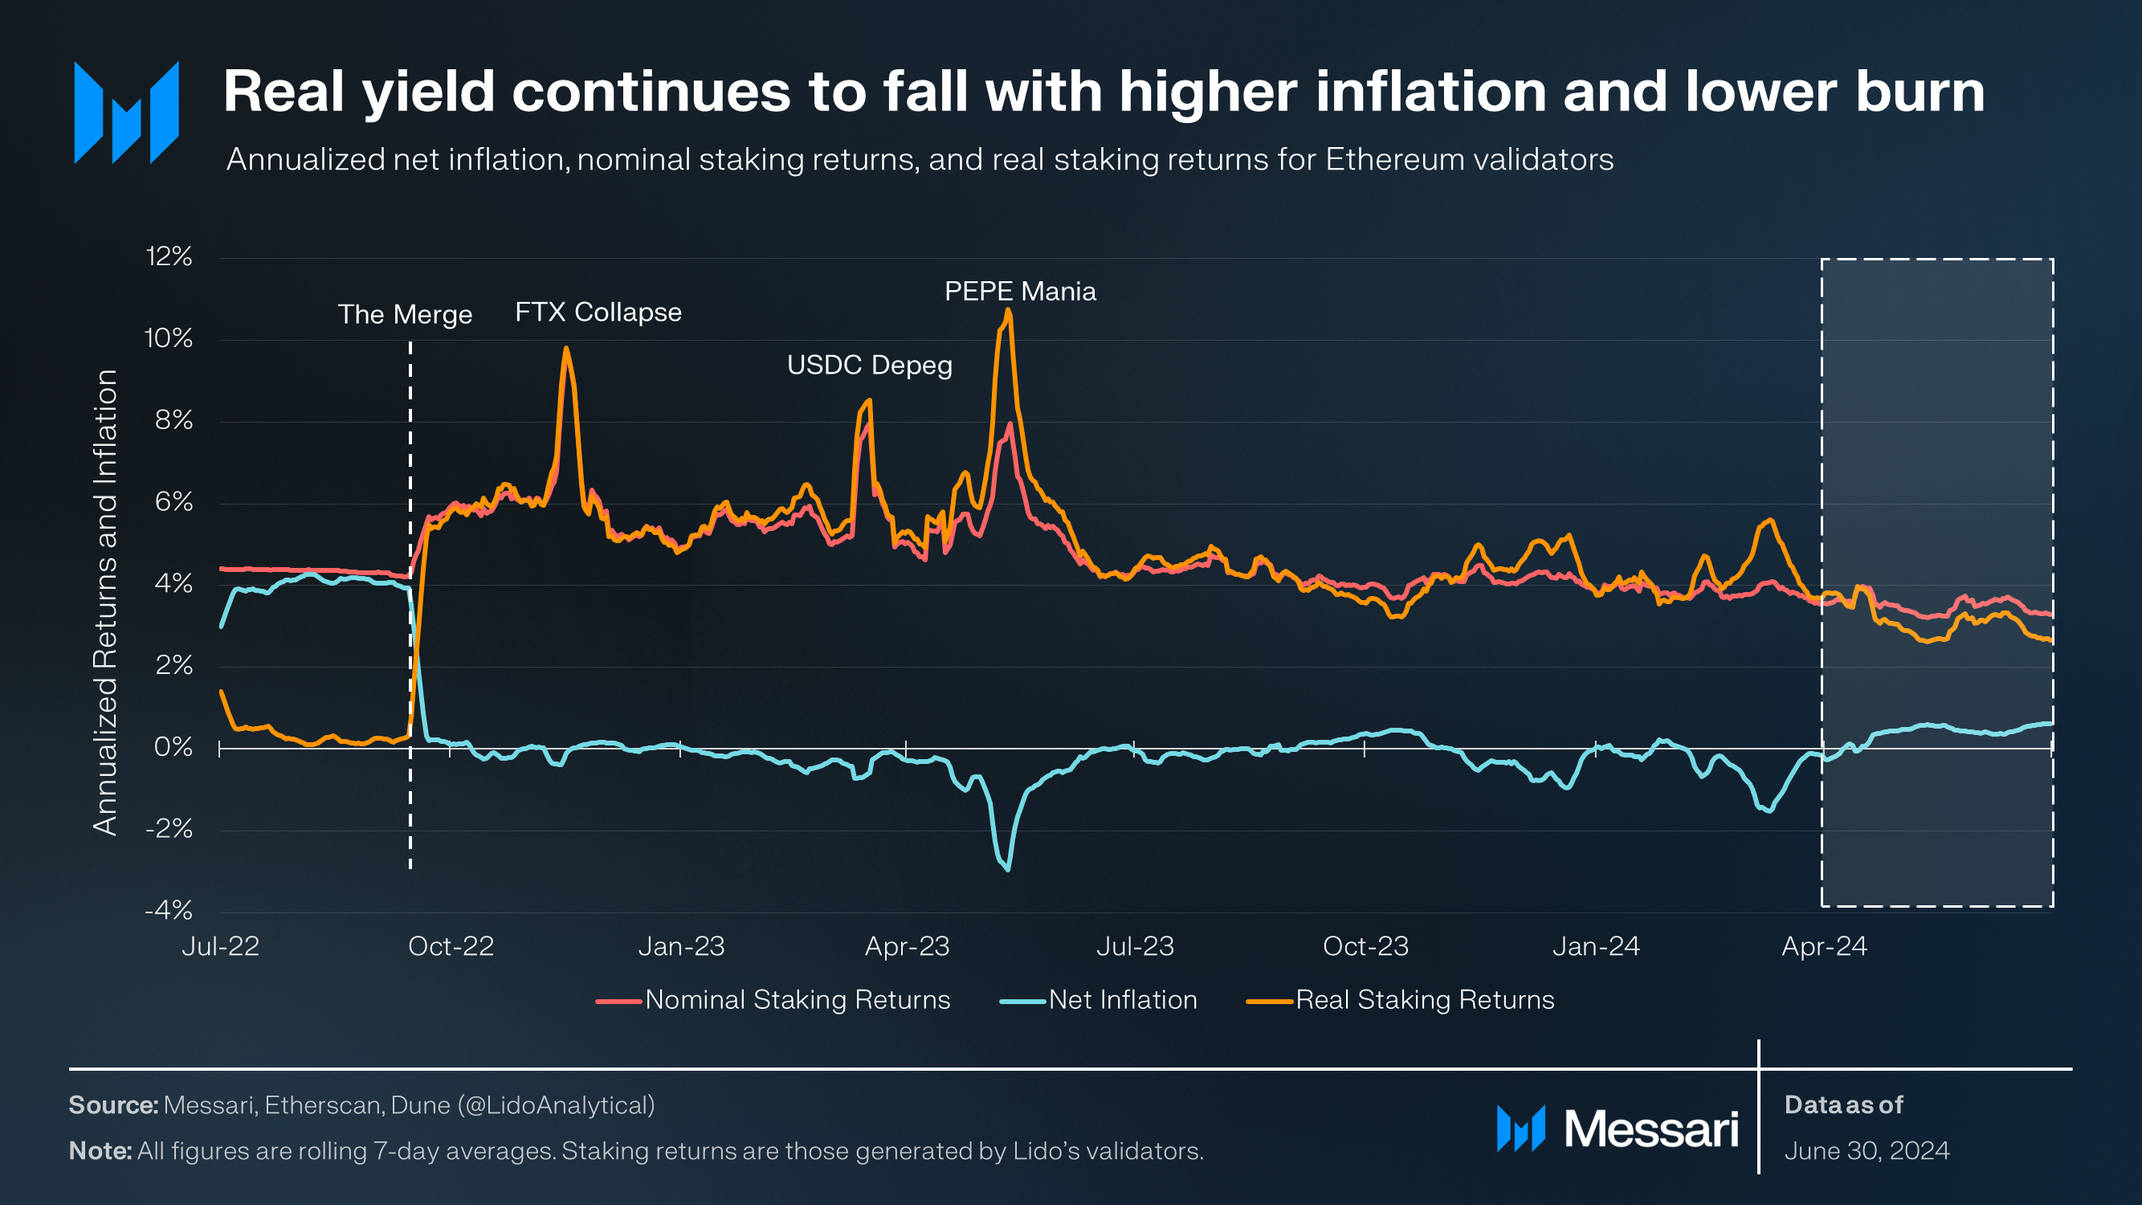
Real yield has fallen significantly since Q2 2023. In Q2 2024, annualized real yield was down to 3.1% compared to 4.2% in the previous quarter and 6% in Q2 2023. Multiple factors have led to this decline in real yield –
As ETH’s staking ratio grows, more ETH is issued per block but at a lower rate than validator growth. This decreases the nominal yield per validator but increases inflation, thus negatively impacting real yield.
Mainnet activity has trended downwards, with Ethereum’s Layer-2 (L2) network supporting most of the speculative activity. Lower activity has meant lower burn. Additionally, EIP-4844 has kept data availability fees low, further lowering burn.
The Ethereum community is split on whether to reduce inflation under the goal of Minimum Viable Issuance (MVI). Those in favor of lower inflation argue that it will reduce liquid staking concentration, while those against it counter that CEX centralization may be worse. Some even question whether it will have much of an impact at all. As such, it remains a contentious topic with no clear consensus. In our opinion, there isn’t a pressing need to change issuance with inflation at a meager 0.4% in a quiet quarter. Any change to the issuance curve must be made thoughtfully.
Network Overview
Layer-2 Activity
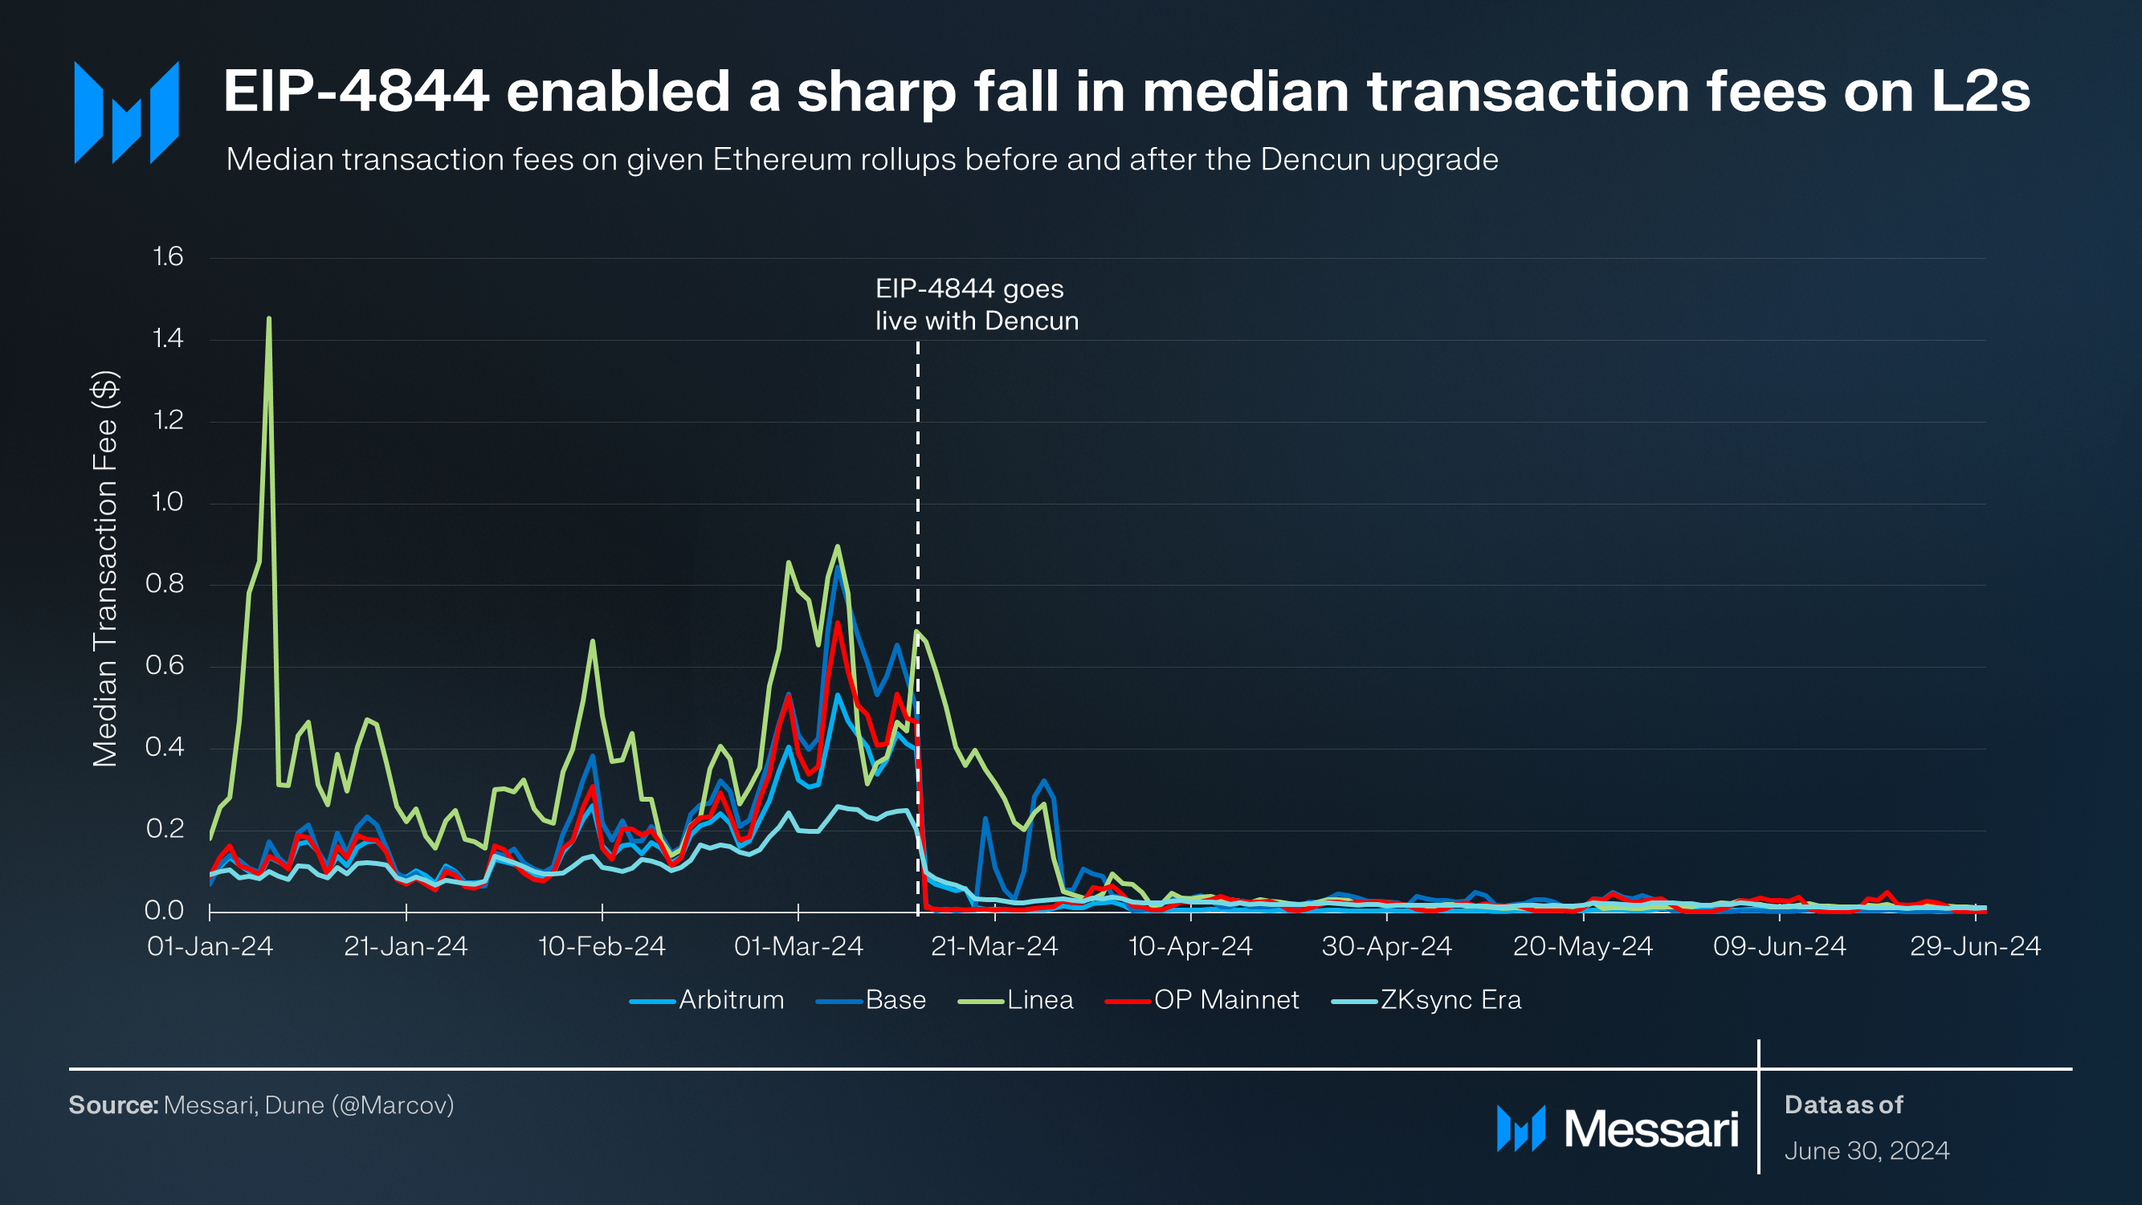
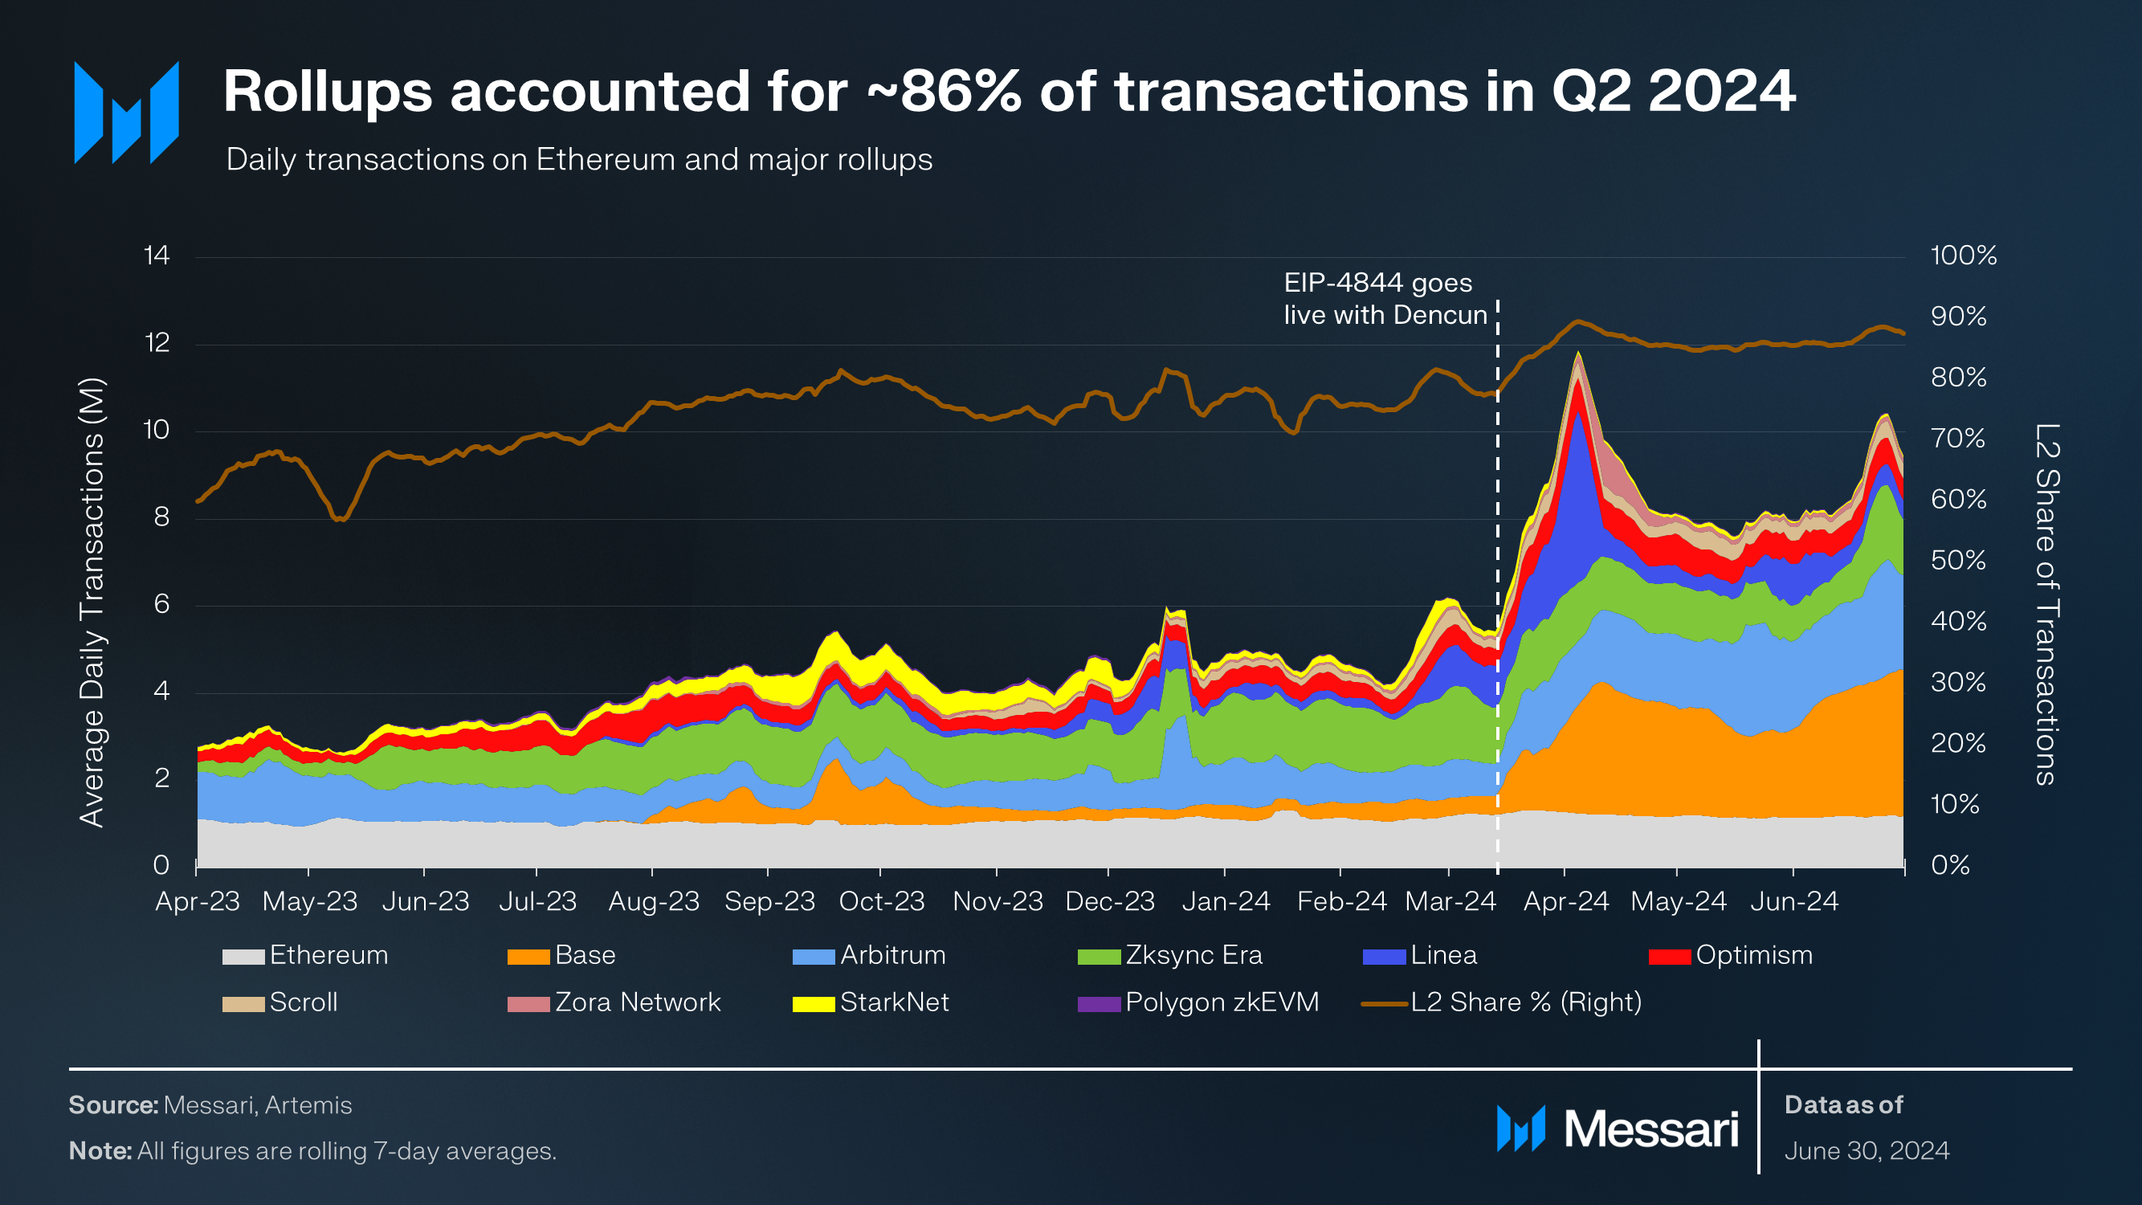
Ethereum mainnet underwent the Cancun-Deneb (Dencun) upgrade on March 13, 2024. One of the most anticipated features of this upgrade was the inclusion of EIP-4844. EIP-4844 introduced a new transaction type to Ethereum where rollups may post data to be stored in blobs by Ethereum validators for a short period of time. This data is stored on the Ethereum consensus layer (CL) clients and does not interact with the execution layer (EL). As such, blobs make Layer-2 costs independent of any Layer-1 transactions while providing a dedicated space to post transaction data.
Transaction fees on Ethereum rollups have fallen sharply because of the upgrade. In Q2 2024, median transaction fees on rollups ranged between sub-1 cents to 5 cents, compared to 5 cents to 100+ cents before Dencun. As predicted, rollup transaction fees are now competitive with major alt-Layer-1s like Solana. The bottleneck for transaction throughput is now at the execution layer for rollups, not Ethereum's data availability. L2s are experimenting with higher gas limits to scale execution.
Lower fees on L2s have led to significant transaction growth. By the end of Q2 2024, Ethereum rollups were cumulatively conducting 6.4 times as many transactions as the base layer. Over the last year, rollup transactions have multiplied and are now 3.7 times higher than Q2 2023.
Among the rollups, Coinbase’s Base has been the breakout performer of 2024 with strong adoption in social apps like Farcaster and as a home for memecoin mania. It had the highest activity in the quarter, with average daily transactions of a whopping 2.6 million. It also had the highest sequential growth and was the most significant contributor to overall growth. Average daily transactions on Base grew by 338% or 2 million, contributing two-thirds of the overall transaction growth of 3 million. Starknet and ZKsync Era were the only L2s that noted a decline in transaction activity as they concluded their respective airdropcampaigns.
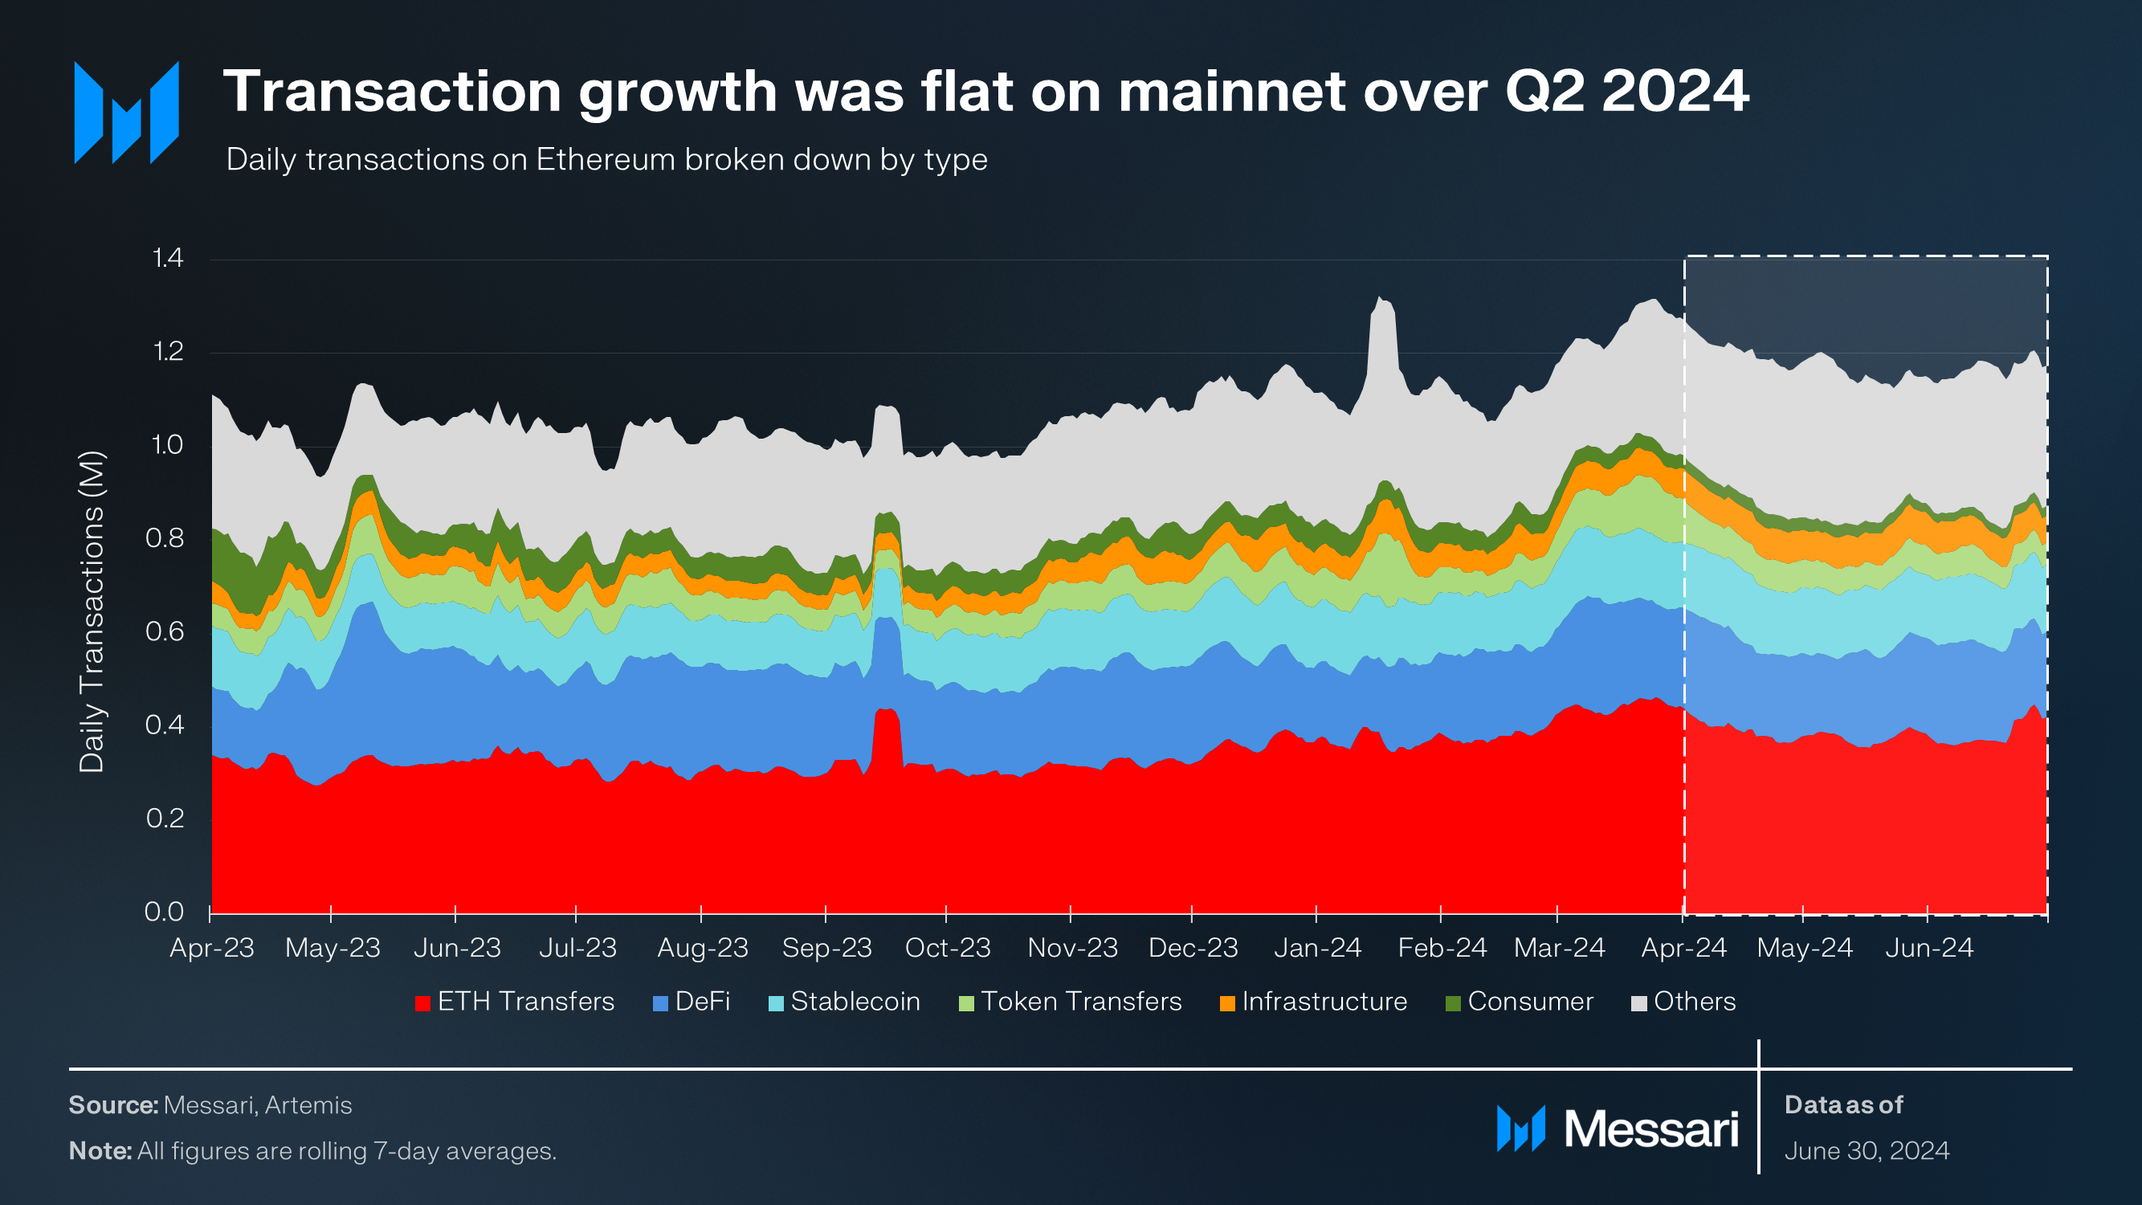
In Q2 2024, average daily transactions on the base layer declined marginally by 1% to 1.17 million. As activity moved to L2s, bridging transactions and MEV bots were the only categories with meaningful growth on the L1. Consumer transactions (NFTs, gaming, and social) and token transfers had the sharpest declines over the quarter, at 41% and 28%, respectively.
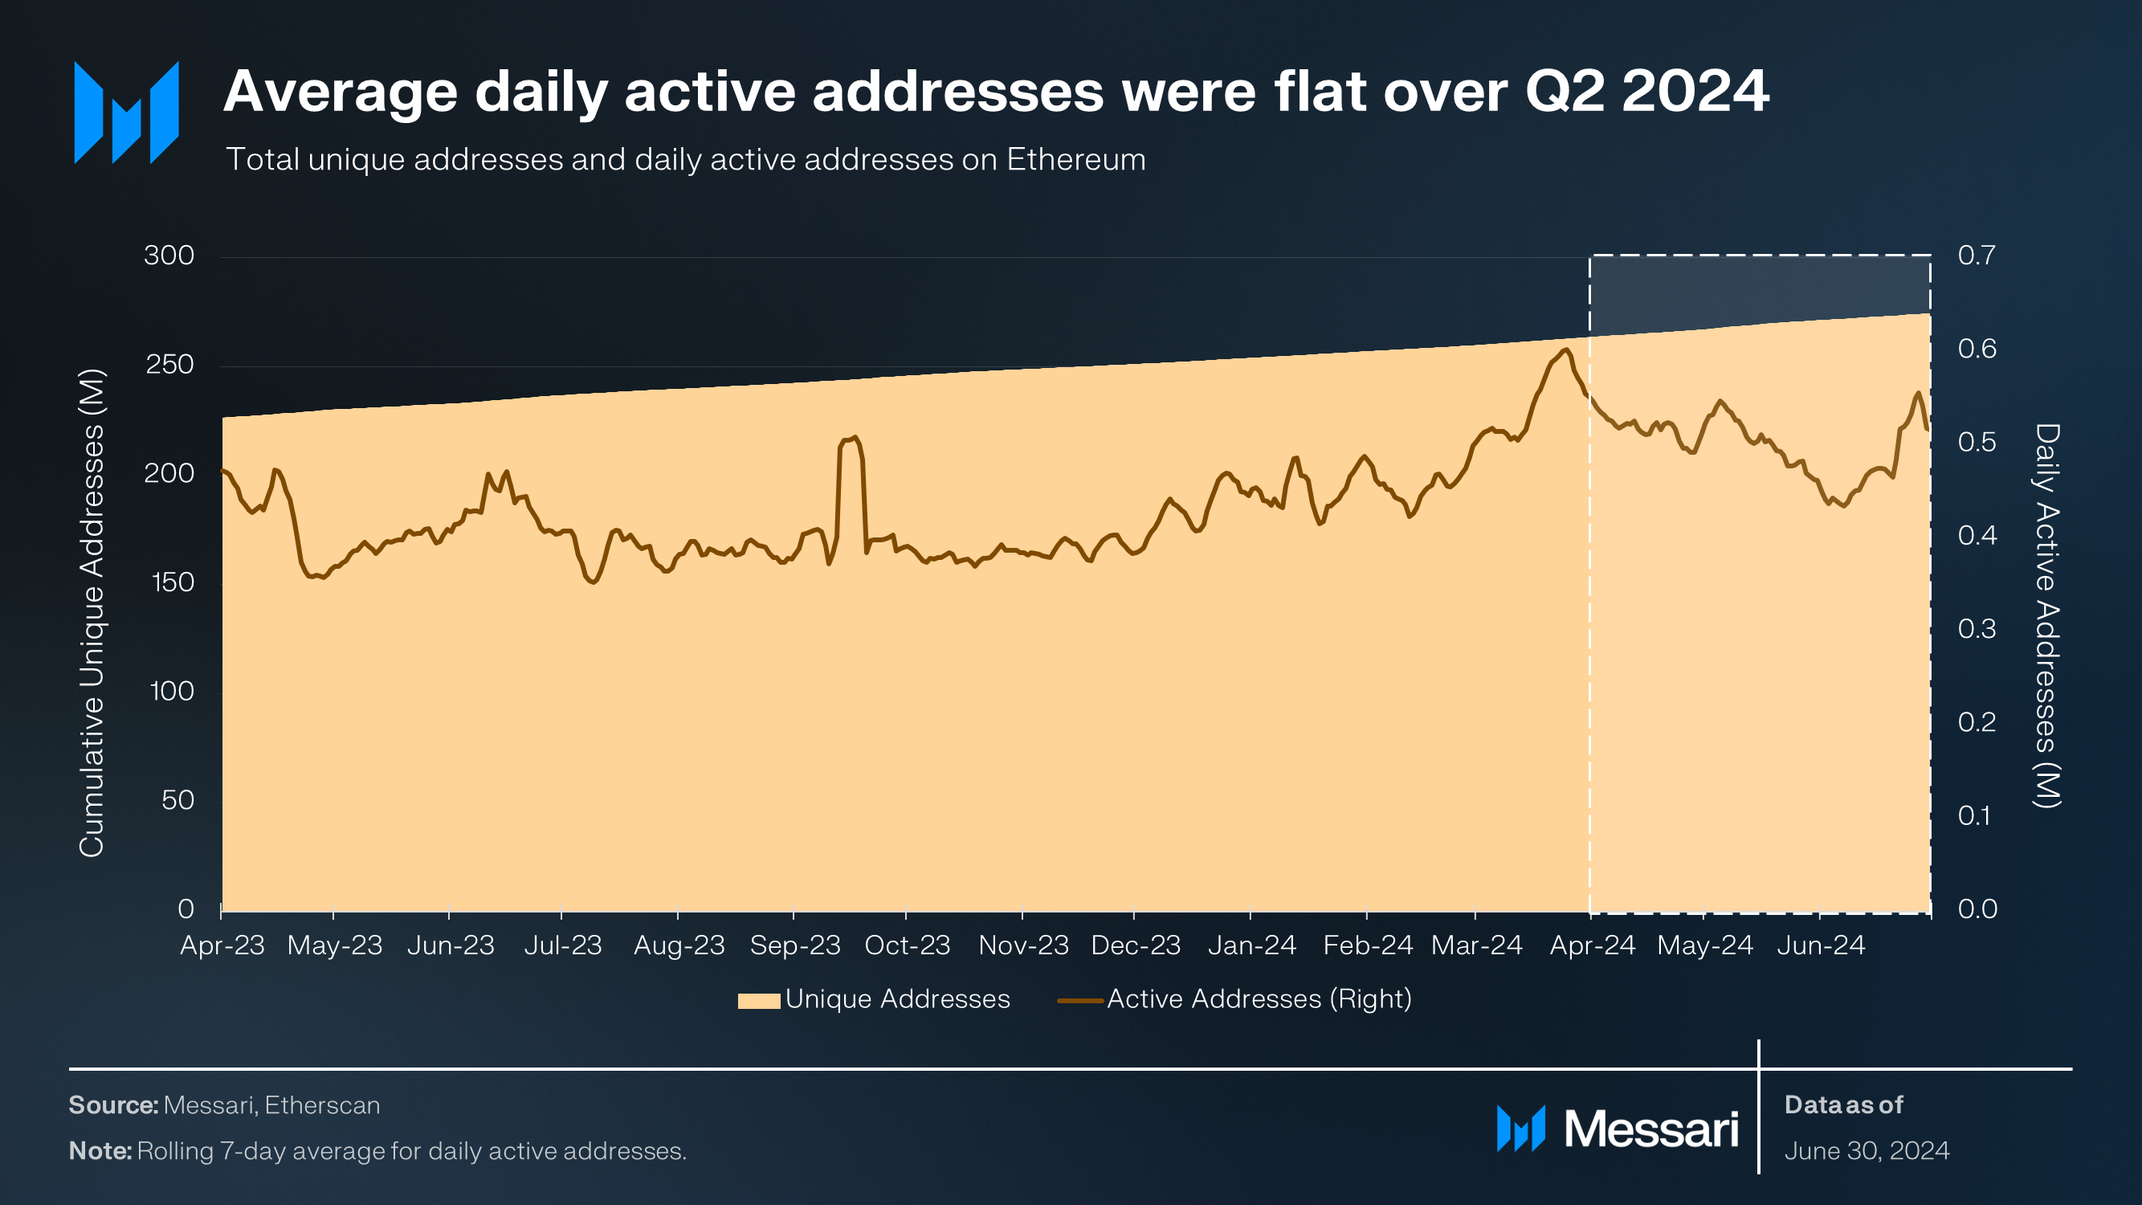
Daily active addresses typically trend similar to transactions. They saw marginal growth of 2% to 500,000. However, this was the highest average of daily active addresses since Q3 2022.
In Q2 2024, Ethereum added 10.9 million unique addresses, 12% higher than the growth rate in the previous quarter. The growth in unique addresses may indicate new joiners, although it is, at least, partly power users with new wallets for airdrop farming and better security.
Ecosystem Overview
Total Value Locked
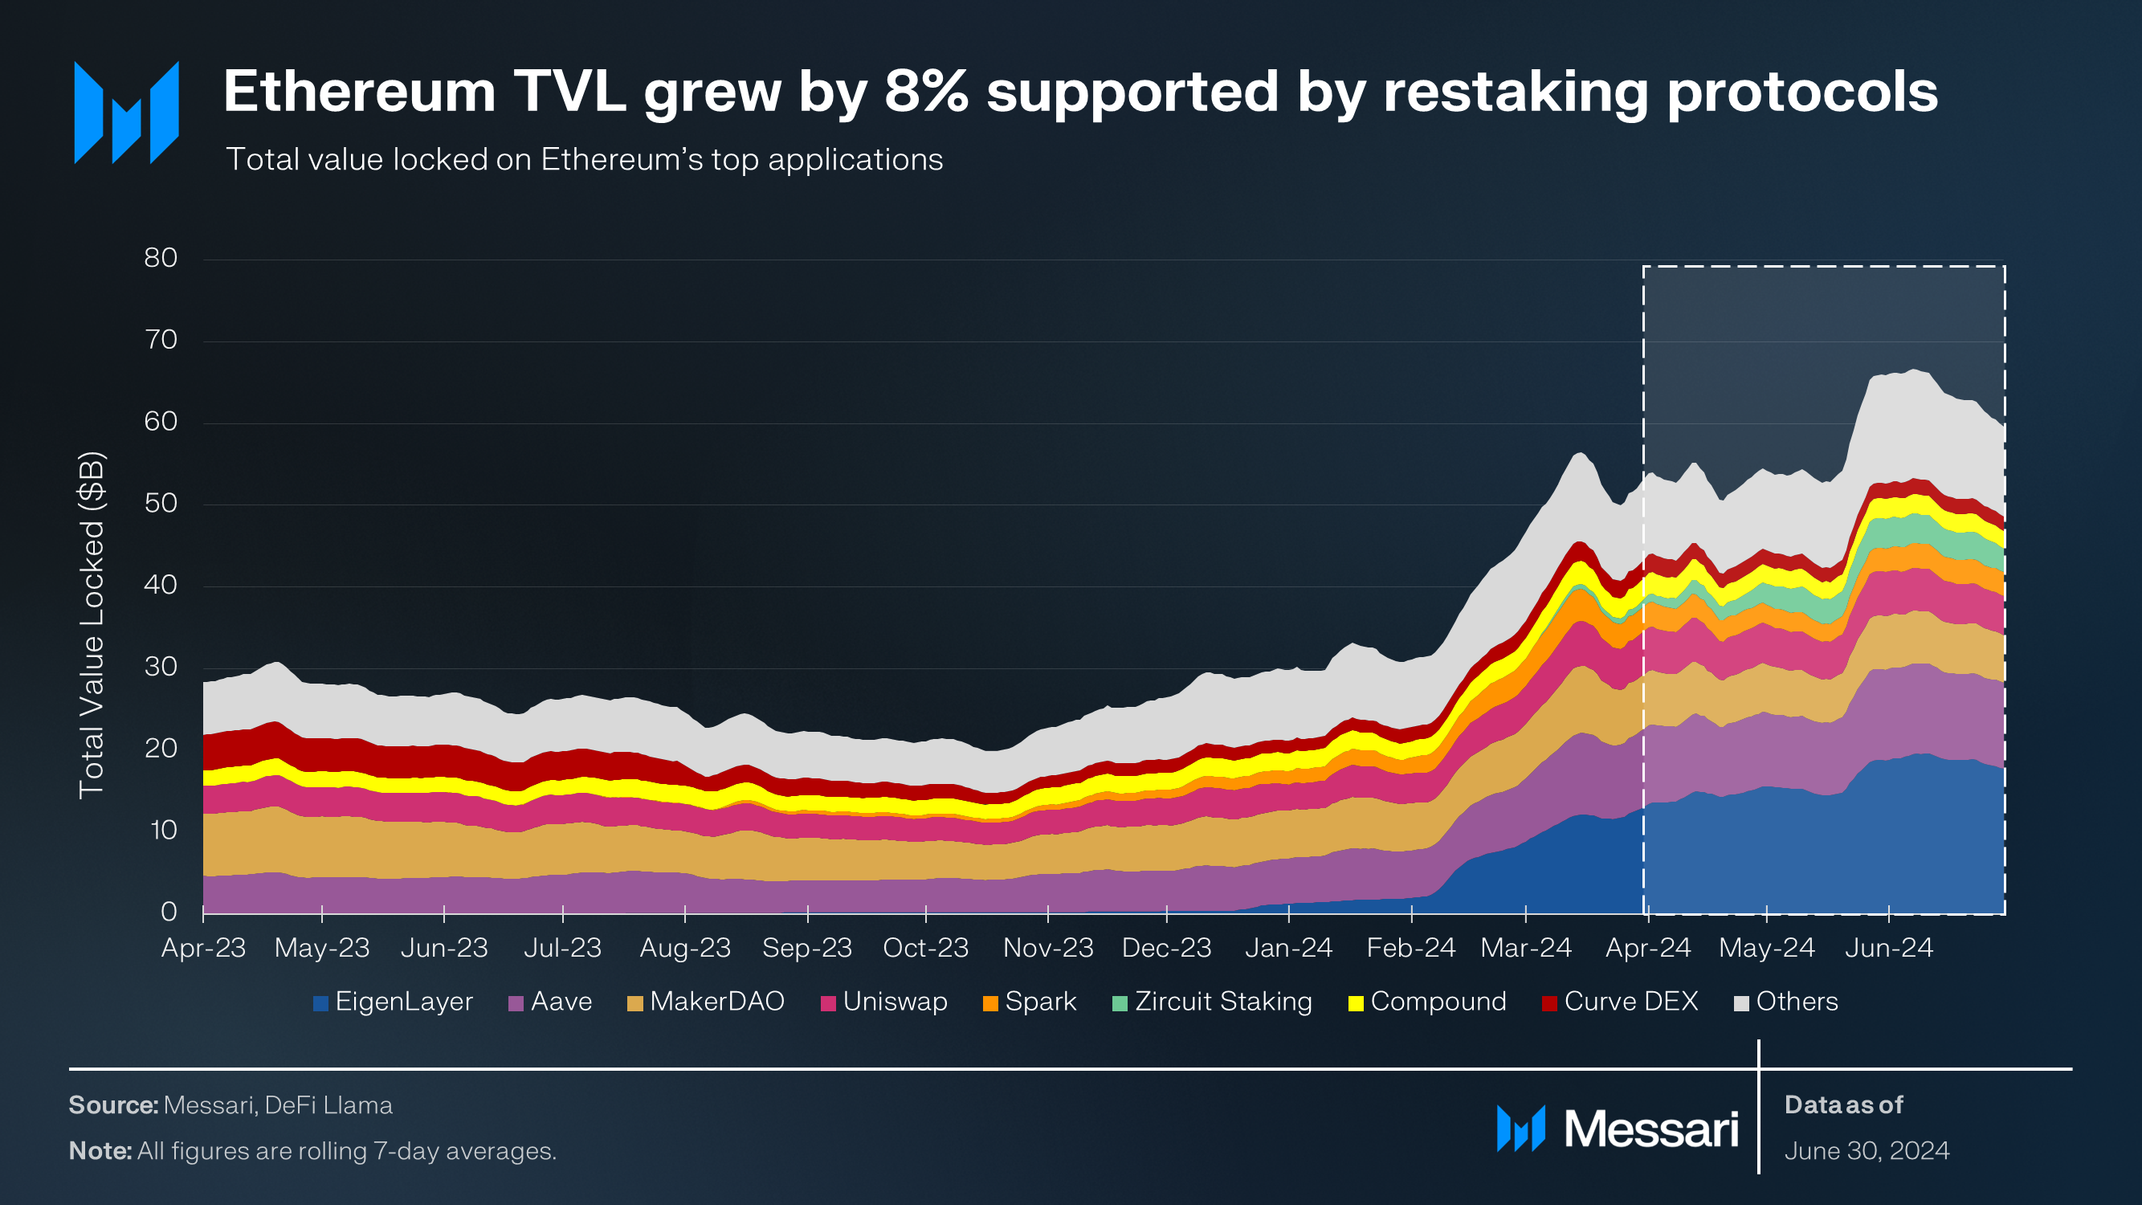
Price and investor sentiment directly affect TVL. However, Ethereum’s TVL showed surprising resilience and grew by 9% to $59 billion. EigenLayer led with $3.5 billion in TVL growth to an industry-leading $17 billion. After EigenLayer, Zircuit and Aave had the highest sequential growth of $1.5 and $1.1 billion, respectively.
In our methodology, we ignore some protocols as they can lead to “double counting” of the same assets. Liquid restaking protocols and the stablecoin protocol Ethena are among those which are excluded, but they also saw TVL growth over Q2 2024.
Decentralized Exchanges
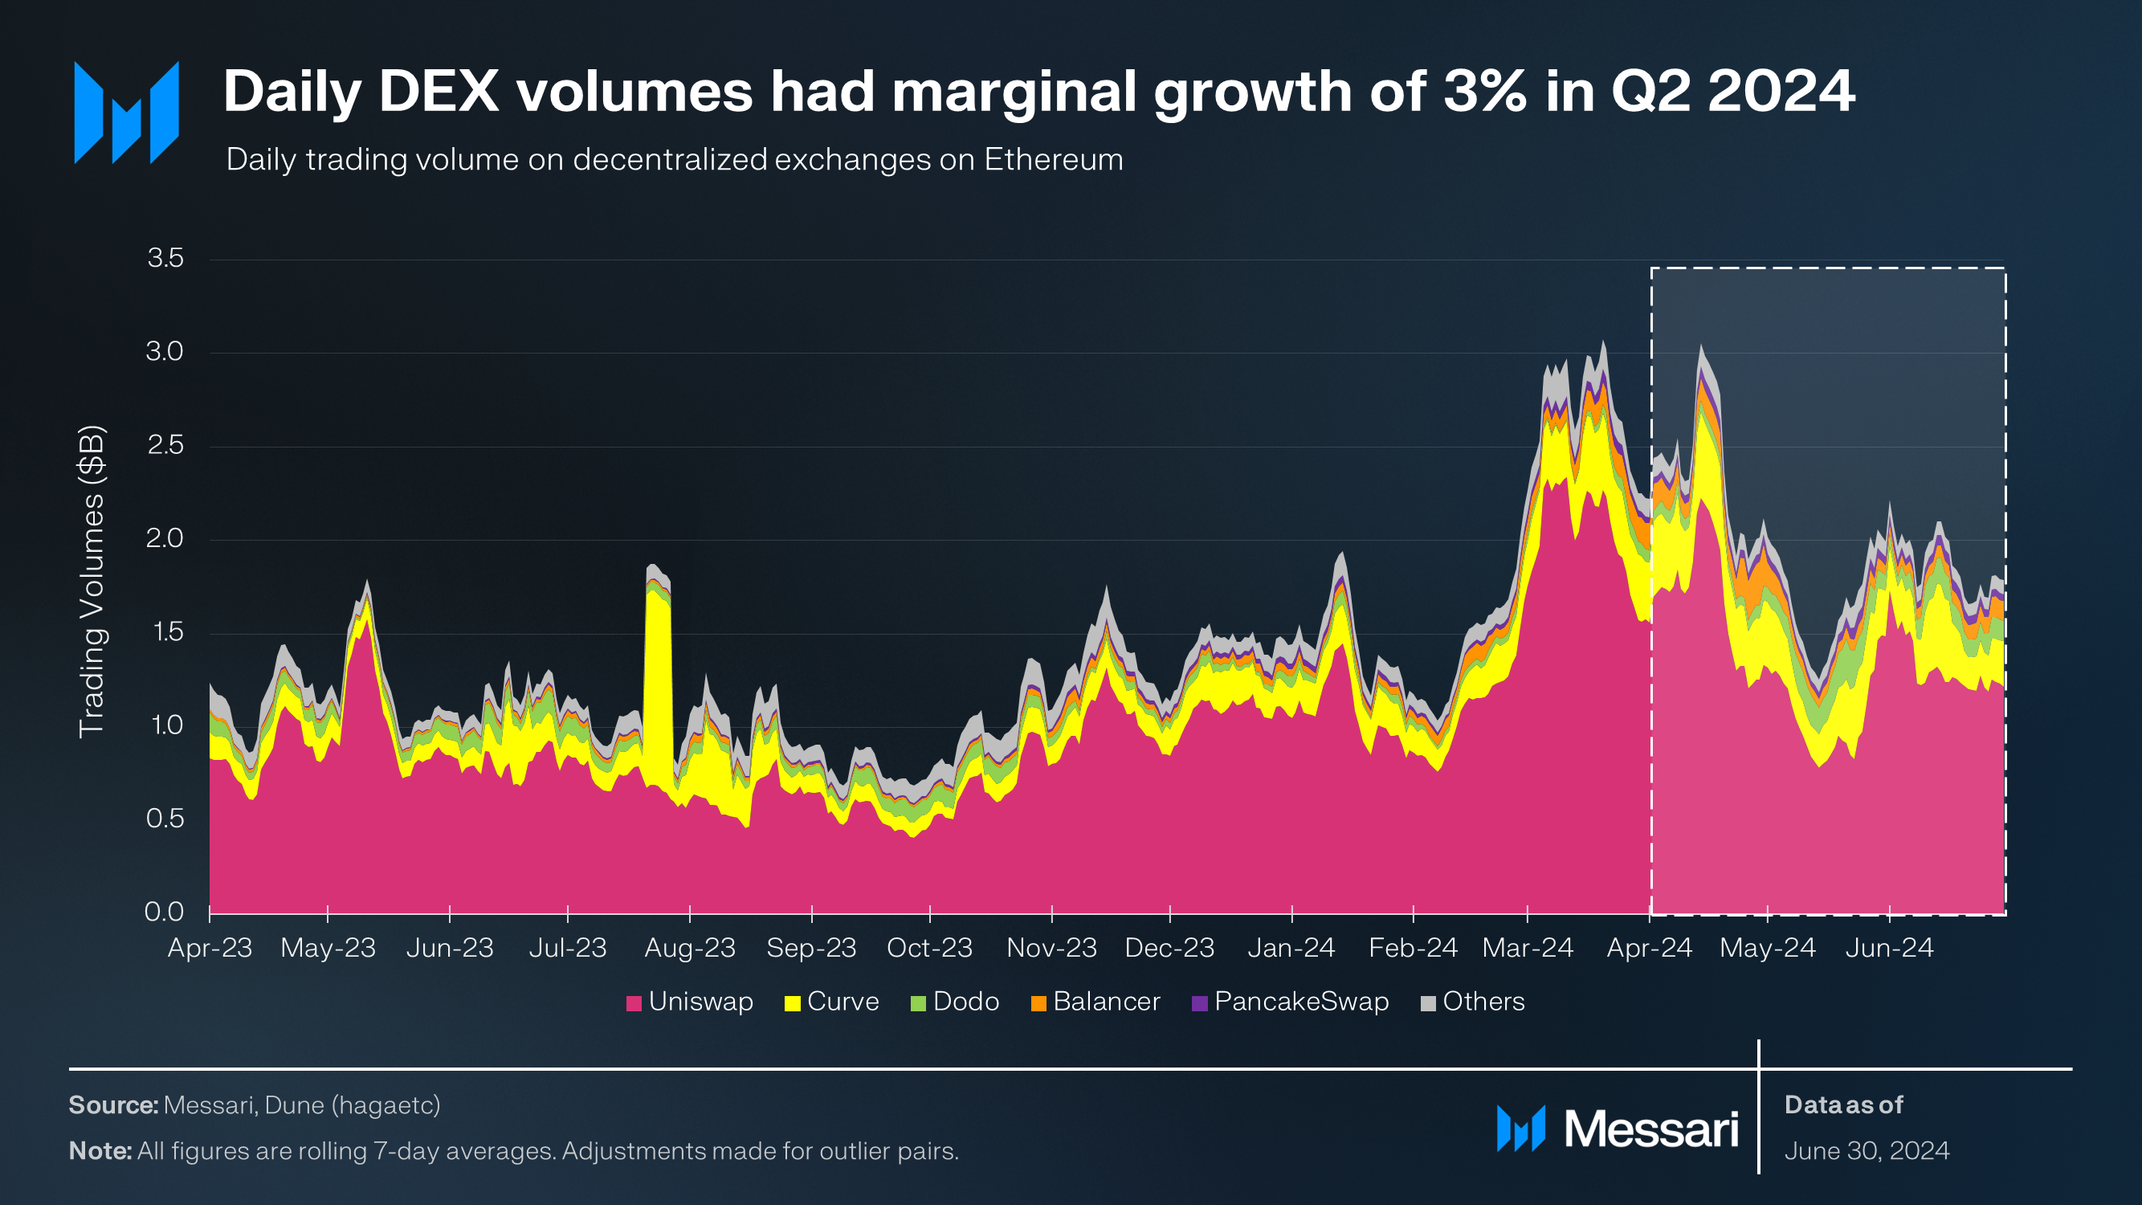
DEX volumes trended similarly to price and transaction activity and were marginally higher by 3% over Q2 2024. Daily volumes through Q2 2024 averaged $2 billion. Among major DEXs, DODO and PancakeSwap had the highest sequential growth of 177% and 38%, respectively.
Uniswap contributes to two-thirds of all Ethereum DEX volume. Its daily average volume fell 6% to $1.3 billion through the quarter. Uniswap’s continued market dominance is a testament to the Uniswap team, which plans to build on its lead further with its upcoming upgrade to V4.
NFT Marketplaces
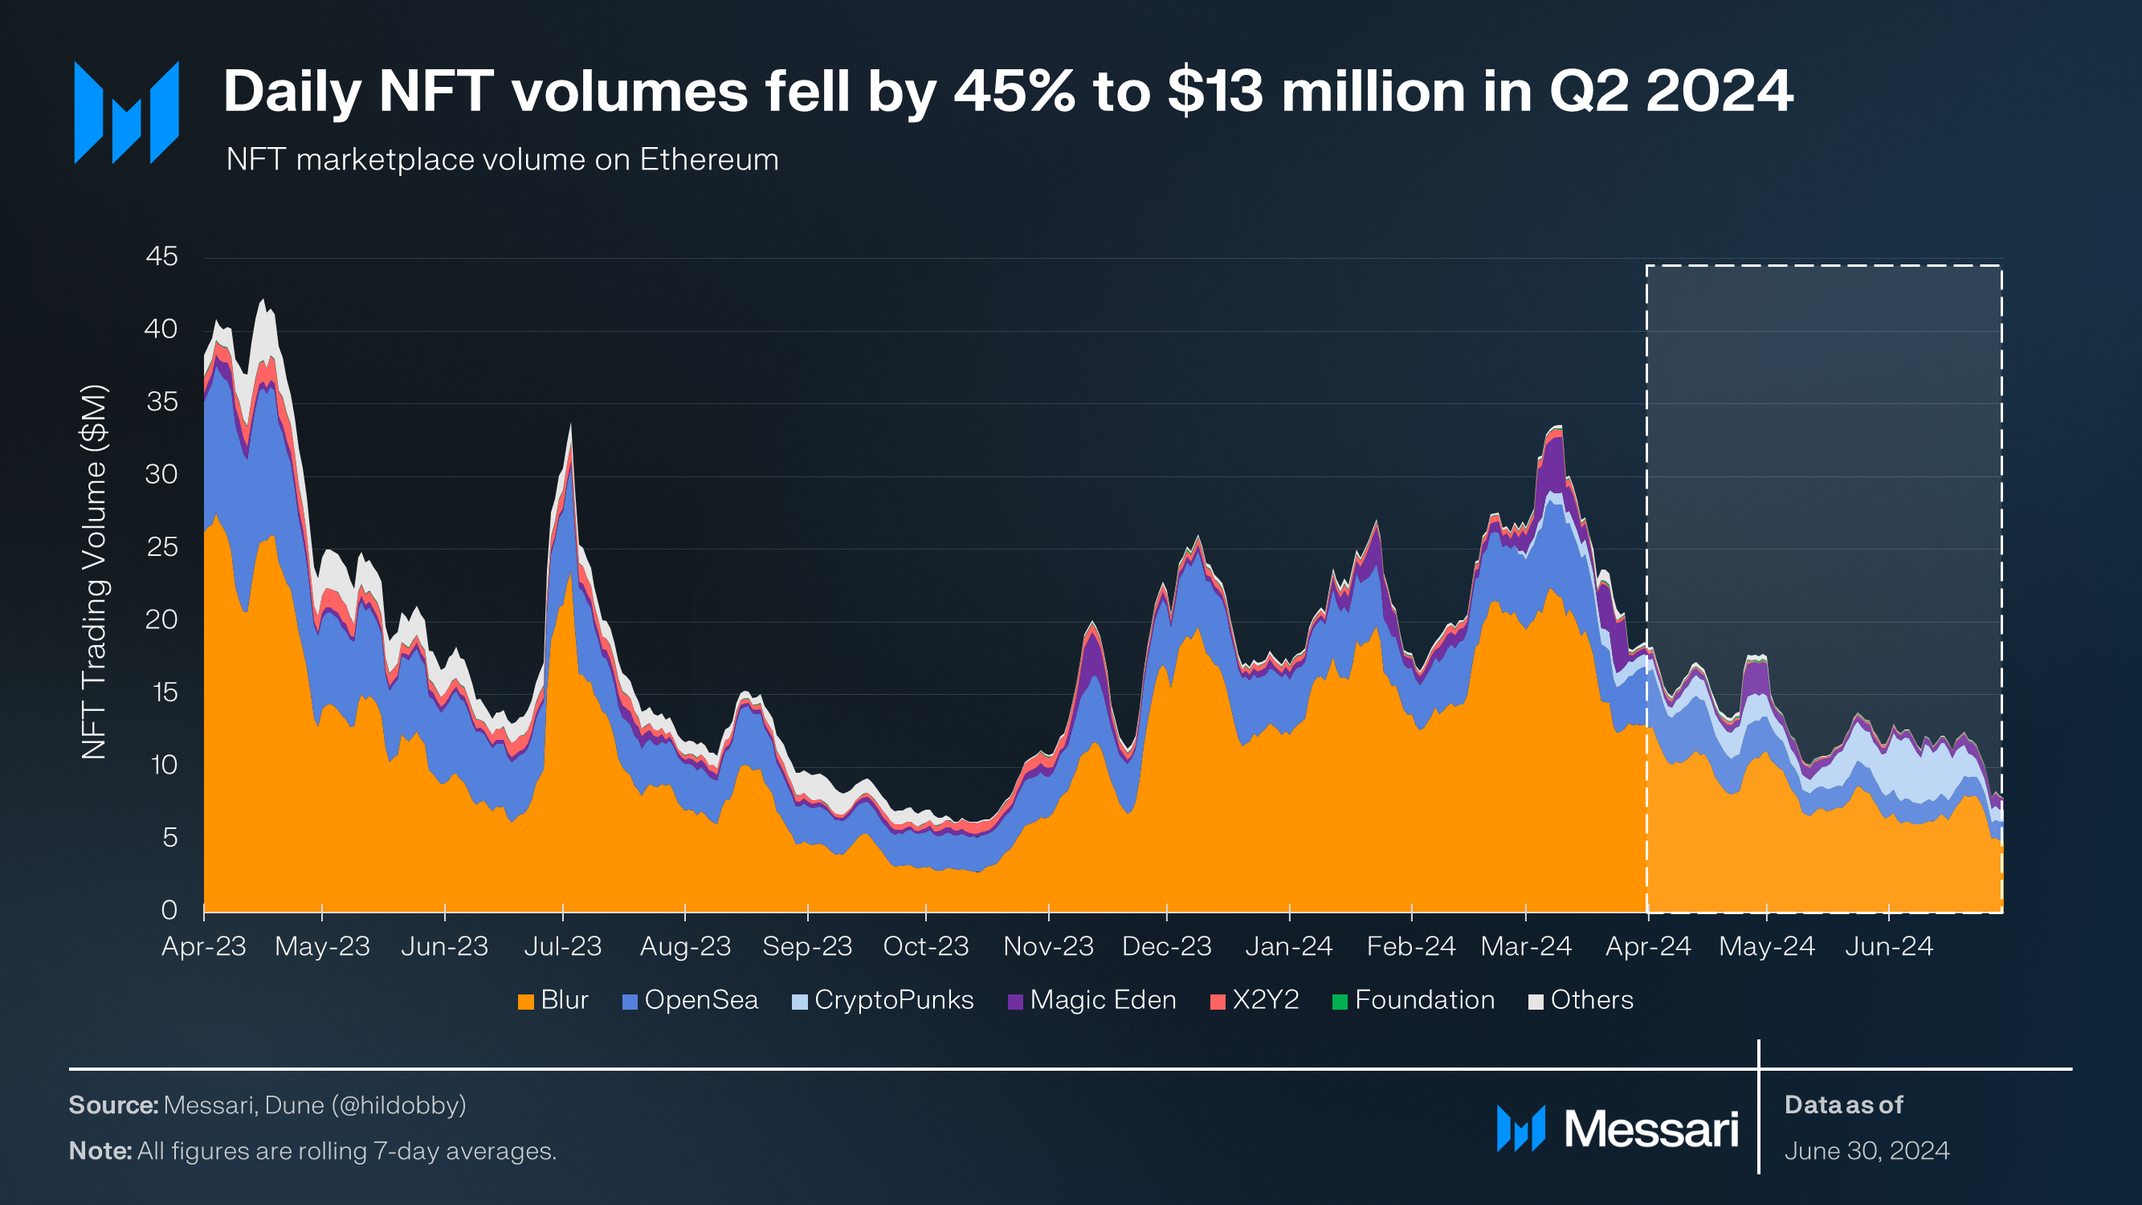
NFT volumes fell sharply, bucking the flattish trend of other metrics. In Q2 2024, daily average NFT volumes declined by 45% to $13 million. New entrant Magic Eden was the only major marketplace with sequential growth, as its daily average volumes surged by 158% to almost $2 million. Blur volumes fell by 52%, but it retained a dominant market share of 62% with $8 million in average daily volumes.
Stablecoins
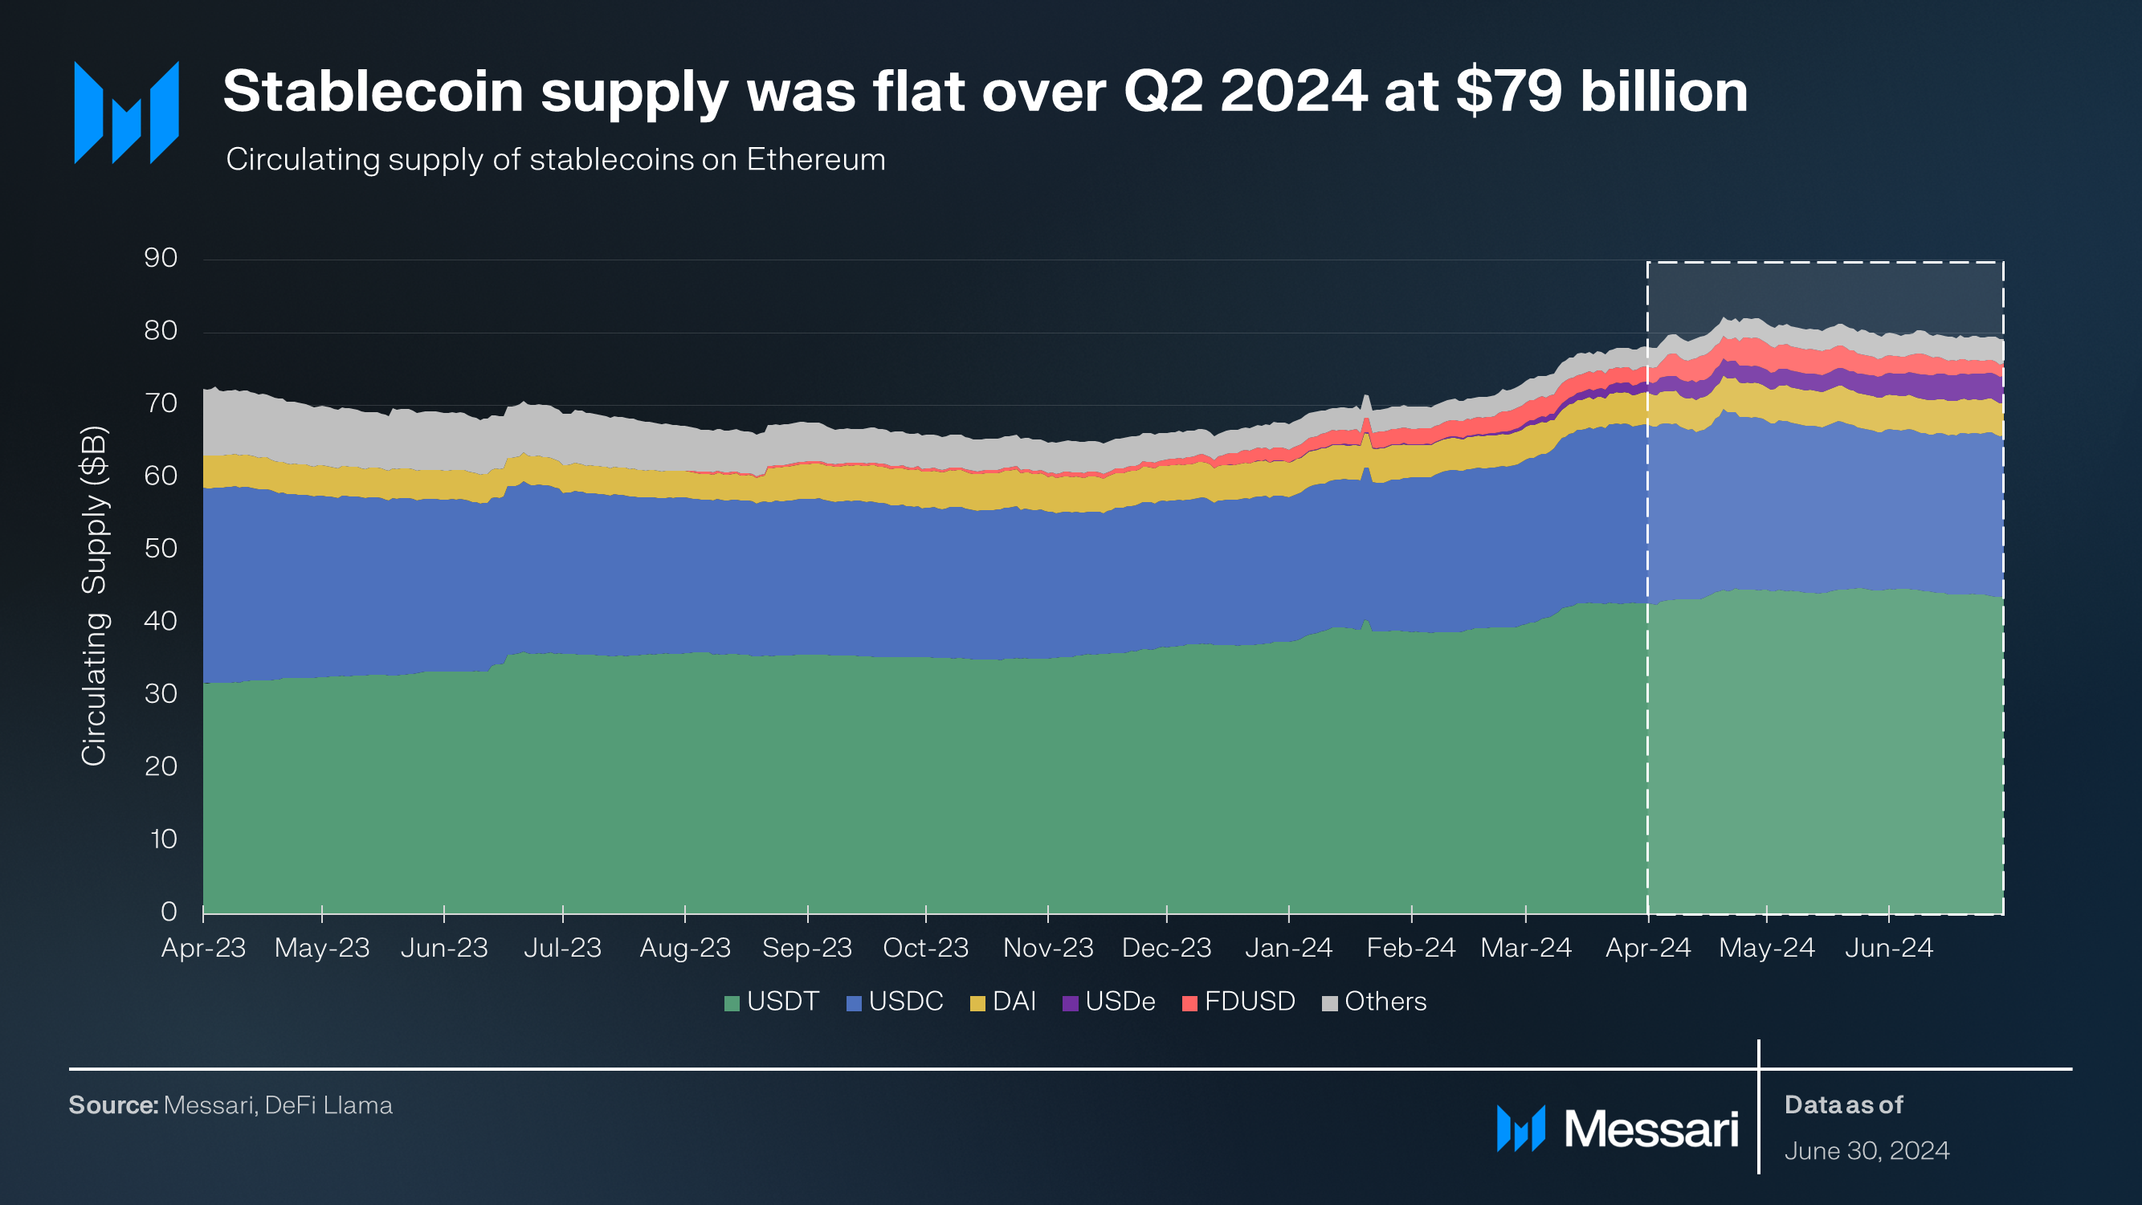
In Q2 2024, stablecoin supply grew marginally by 1% to $79 billion. Decentralized stablecoins, Ethena’s USDe and Maker’s DAI, grew by 135% and 5%, respectively. On the other hand, centralized stablecoins, FDUSD and USDC, declined by 16% and 10%, respectively. New entrants, Blackrock’s BUIDL and PayPal’s PYUSD, grew by 75% and 167%, becoming the sixth and seventh-largest stable assets on Ethereum, respectively.
Qualitative Analysis
Prague-Electra Upgrade
The last few upgrades have delivered massive improvements for Ethereum. The transition to Proof-of-Stake in The Merge, staking withdrawals in Shapella, and blobs in Dencun significantly improved Ethereum’s fundamentals while also growing the network. The next planned upgrade is called the Prague and Electra upgrade, or Pectra for short. The full list of upgrades for Pectra is not finalized yet; however, the following are some of the expected upgrades:
EVM Object Format (EOF) is a collection of EIPs (EIP-3540, EIP-3541, EIP-3670, EIP-4200, EIP-5450) that aim to improve the EVM by changing how instructions to the EVM are structured and introducing the concept of code validation when a smart contract is deployed. Validating code during the contract creation process allows code versioning without an additional version field in the account. Versioning is useful for introducing or deprecating features such as account abstraction.
EIP-3074 allows for the delegation of an externally owned account (EOA) to a smart contract, allowing for sponsored transactions and batch transactions.
EIP-7002 will let execution layer transactions trigger exits on the consensus layer. This upgrade helps liquid staking protocols kick any offending validators.
EIP-7251 allows the maximum effective balance on the consensus layer to exceed 32 ETH, allowing for easier compounding for solo stakers and fewer validators for large node operators.
The core developers are targeting early 2025 for the launch of Pectra, although timelines may be affected by changes in the scope of the upgrade.
Closing Summary
Crypto markets had a strong H1 2024. The most important development was perhaps the regulators finally adopting a more favorable stance towards the maturing asset class. ETH became the second spot crypto ETF to be approved by the SEC in the United States, with trading beginning in early Q3. Early reports of inflows and adoption are highly encouraging.
On the fundamental side, ETH had a stable quarter on most metrics. L2 adoption remains the brightest spot, with transaction activity growing consistently, irrespective of market conditions. However, this was also the quarter when ETH had significant positive inflation for the first time since the Merge. The community is working on managing inflation and increasing the utility of the base layer in the upcoming upgrades.
All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Nothing contained in this report is a recommendation or suggestion, directly or indirectly, to buy, sell, make, or hold any investment, loan, commodity, or security, or to undertake any investment or trading strategy with respect to any investment, loan, commodity, security, or any issuer. This report should not be construed as an offer to sell or the solicitation of an offer to buy any security or commodity. Messari does not guarantee the sequence, accuracy, completeness, or timeliness of any information provided in this report. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Kunal previously worked in equity research and now considers himself a financial analyst in crypto. He specializes in valuation and bottom-up analysis for Layer-1 and DeFi protocols because he has yet to learn of a way to value NFTs.
Kunal previously worked in equity research and now considers himself a financial analyst in crypto. He specializes in valuation and bottom-up analysis for Layer-1 and DeFi protocols because he has yet to learn of a way to value NFTs.