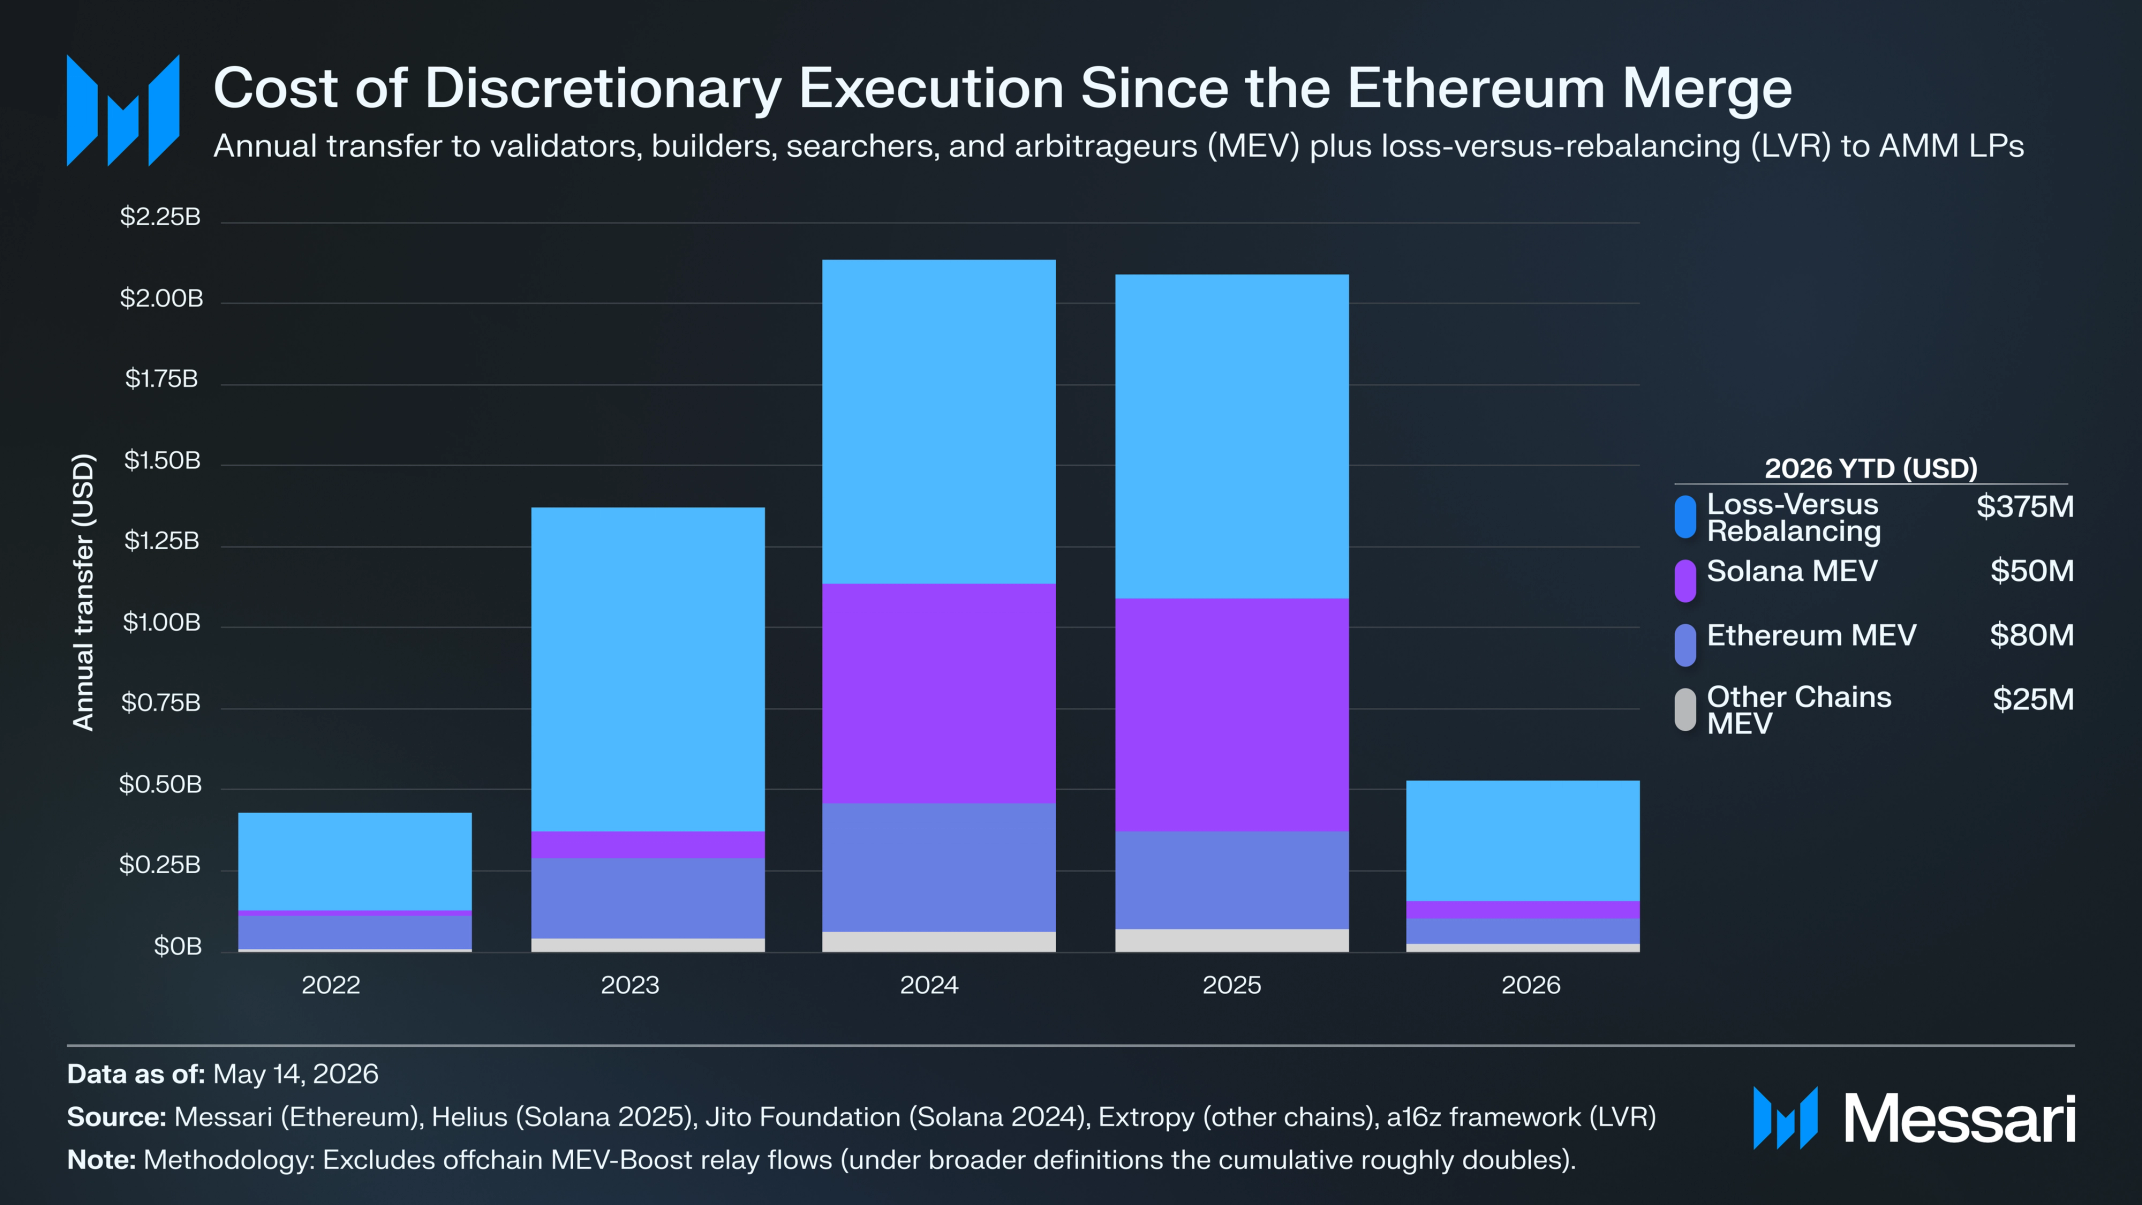
Public blockchains have transferred ~$6.5 billion to validators, builders, searchers, and arbitrageurs since the Ethereum Merge through discretionary execution.
Institutional execution today sits on CEX desks and OTC brokers, not on public blockchains. Sei Giga aims to bring institutional-grade execution onchain without requiring users to sacrifice self-custody or composability with onchain applications.
Sei Giga combines Multiple Concurrent Proposer consensus, deterministic protocol-enforced transaction ordering, and a private transaction dissemination layer to move MEV mitigation into the protocol rather than relying on offchain services.
Current MEV mitigation relies heavily on offchain services. Ethereum users route through systems such as Flashbots Protect, MEV-Blocker, and CoW Swap, while Solana increasingly relies on Jito's Block Assembly Marketplace. These systems reduce some forms of extraction, but they introduce trusted intermediaries and operational dependencies that may not satisfy institutional execution requirements.
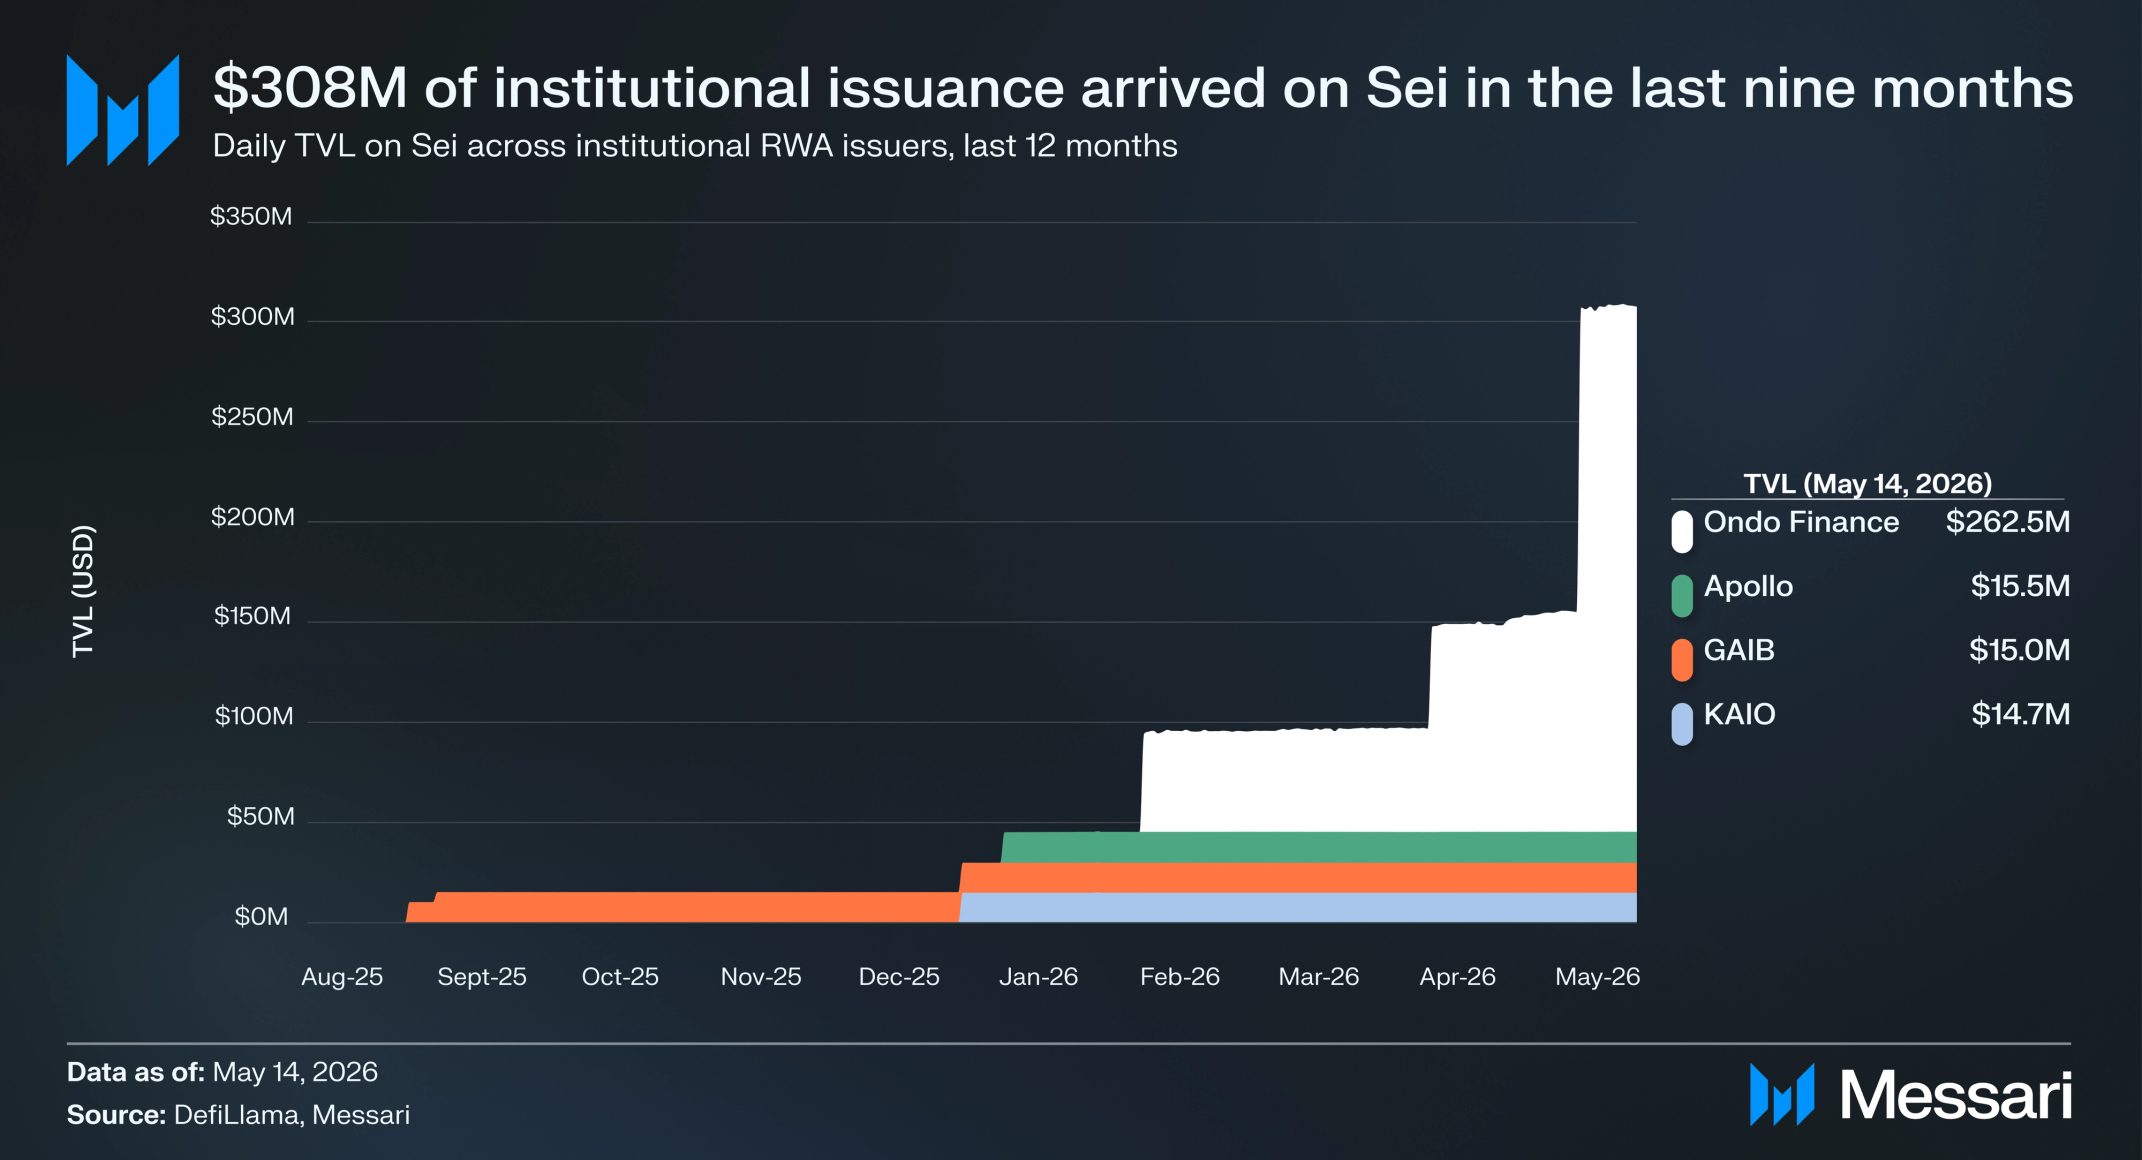
Institutional issuance on Sei is already live, with Ondo Finance, Apollo, Libre Capital, and GAIB collectively holding ~$308 million in tokenized real-world assets on Sei, accounting for ~72% of the network TVL.
Introduction
On May 19, 2025, Sei published the Giga whitepaper following the Sedna research pre-print published in December 2025, formalizing the network’s pivot from consumer-throughput L1 to institutional-execution L1. Public blockchains have transferred ~$6.5 billion to validators, builders, searchers, and arbitrageurs since the Ethereum Merge through discretionary execution, the cost traders and liquidity providers pay for validators, builders, and arbitrageurs exercising discretion over inclusion, ordering, and information that should belong to the trader. The leading mitigations today operate above the consensus layer, shifting key execution guarantees from the protocol itself to external operators and infrastructure providers.
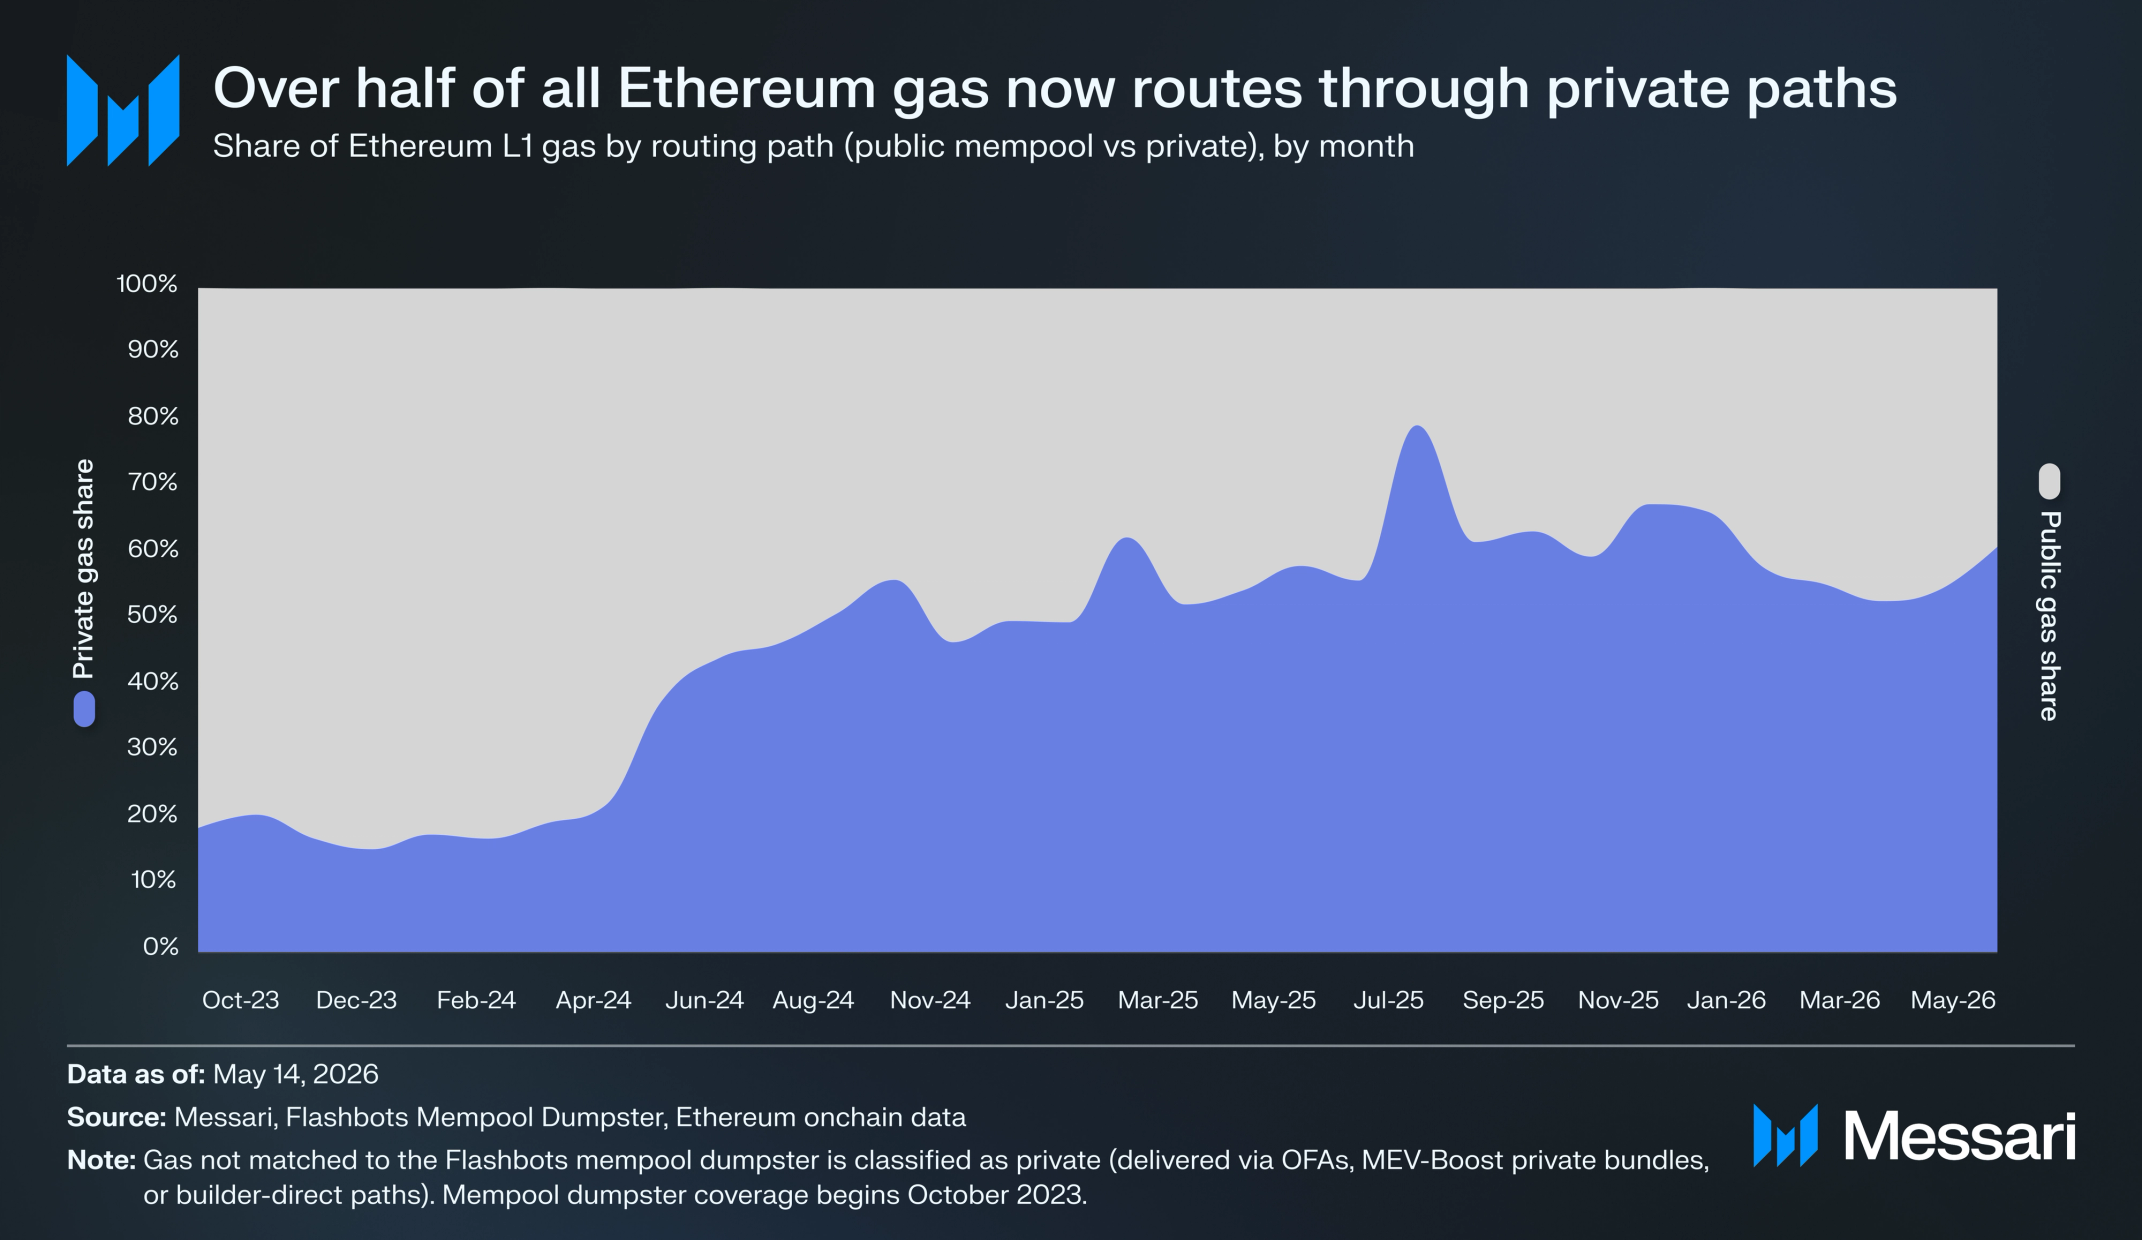
Over half of all Ethereum gas already routes through private order-flow channels, and Jito's centralized Block Assembly Marketplace supports 28% of Solana's network stake. Giga reduces value extracted from users at the protocol layer by combining Multiple Concurrent Proposer (MCP) consensus, deterministic tip-priority ordering, and a private transaction dissemination layer as native base-layer primitives. While Jito and Flashbots have built the mitigation layer on top of the protocol, Sei’s Giga is building it within the protocol.
The MEV Problem
Between September 2022 and May 2026, users transferred approximately $2.87 billion to validators, builders, and searchers through sandwich attacks, arbitrage, and Just-In-Time (JIT) liquidity, with the funds paid by users whose transactions were intercepted. Counting the broader MEV-Boost relay-bid economics on Ethereum would double the figure, but these flows reflect validator competition for blockspace rather than direct extraction from user trades. AMM liquidity providers lost another $3.68 billion to arbitrageurs over the same period through loss-versus-rebalancing (LVR), a separate AMM-layer problem Giga improves at the margin but does not solve.
The cumulative $6.55 billion is subject to a different governance regime than its closest tradfi reference point. Institutional FX has spent a decade legislating its discretionary execution cost (last look) down to 10ms hold windows and a per-trade cost of roughly $25 to $49 per million dollars traded, or under half a basis point. That per-trade cost is bounded by a published code that the entire market operates against.
Institutional traders do not expect free execution. They pay spreads, accept bounded information leakage, and operate in accordance with the published FX Global Code, which binds liquidity providers' discretion. The problem with crypto's MEV economy is not value extraction at execution, but unpriced, discretionary, unbounded extraction without any governance layer to bound it. Crypto sits where FX did before the Global Code.
Annual extraction has begun to fall. Solana network revenue fell 68% year-over-year in Q1 2026, with MEV now contributing only 0.36% of Solana staking rewards. Some of the decline is cyclical, as MEV scales with trading volume, and the market contraction in Q1’26 pulled the entire fee economy down with it. When volumes return, extraction returns. Part of the decline also reflects the growing adoption of private transaction routing and execution services. These systems reduce some forms of observable extraction, though they introduce new intermediaries and fee layers into the execution stack.
The structural component of the decline is happening because the market built external mitigation layers. Nearly half of all Ethereum gas now routes through transaction submission channels via Flashbots Protect, MEV-Blocker, CoW Swap, and builder-direct submission. Flashbots Protect alone has served 2.1 million accounts and protected $43 billion in volume. On Solana, validators running Jito's Block Assembly Marketplace (BAM) now control 28% of network stake, up from 14% at the start of Q1 2026. BAM is a centralized block-building service equipped with specialized encryption hardware that keeps transactions encrypted until execution.
While these systems can reduce some forms of extraction, they shift part of the execution stack to third-party operators. Users rely on specialized operators and infrastructure providers for transaction routing and execution quality rather than protocol-level mechanisms alone. These systems also create new economic intermediaries. For example, Jito’s TipRouter retains 3% of distributed tips, introducing an additional fee layer between users and validators.
Multi-Proposer Consensus
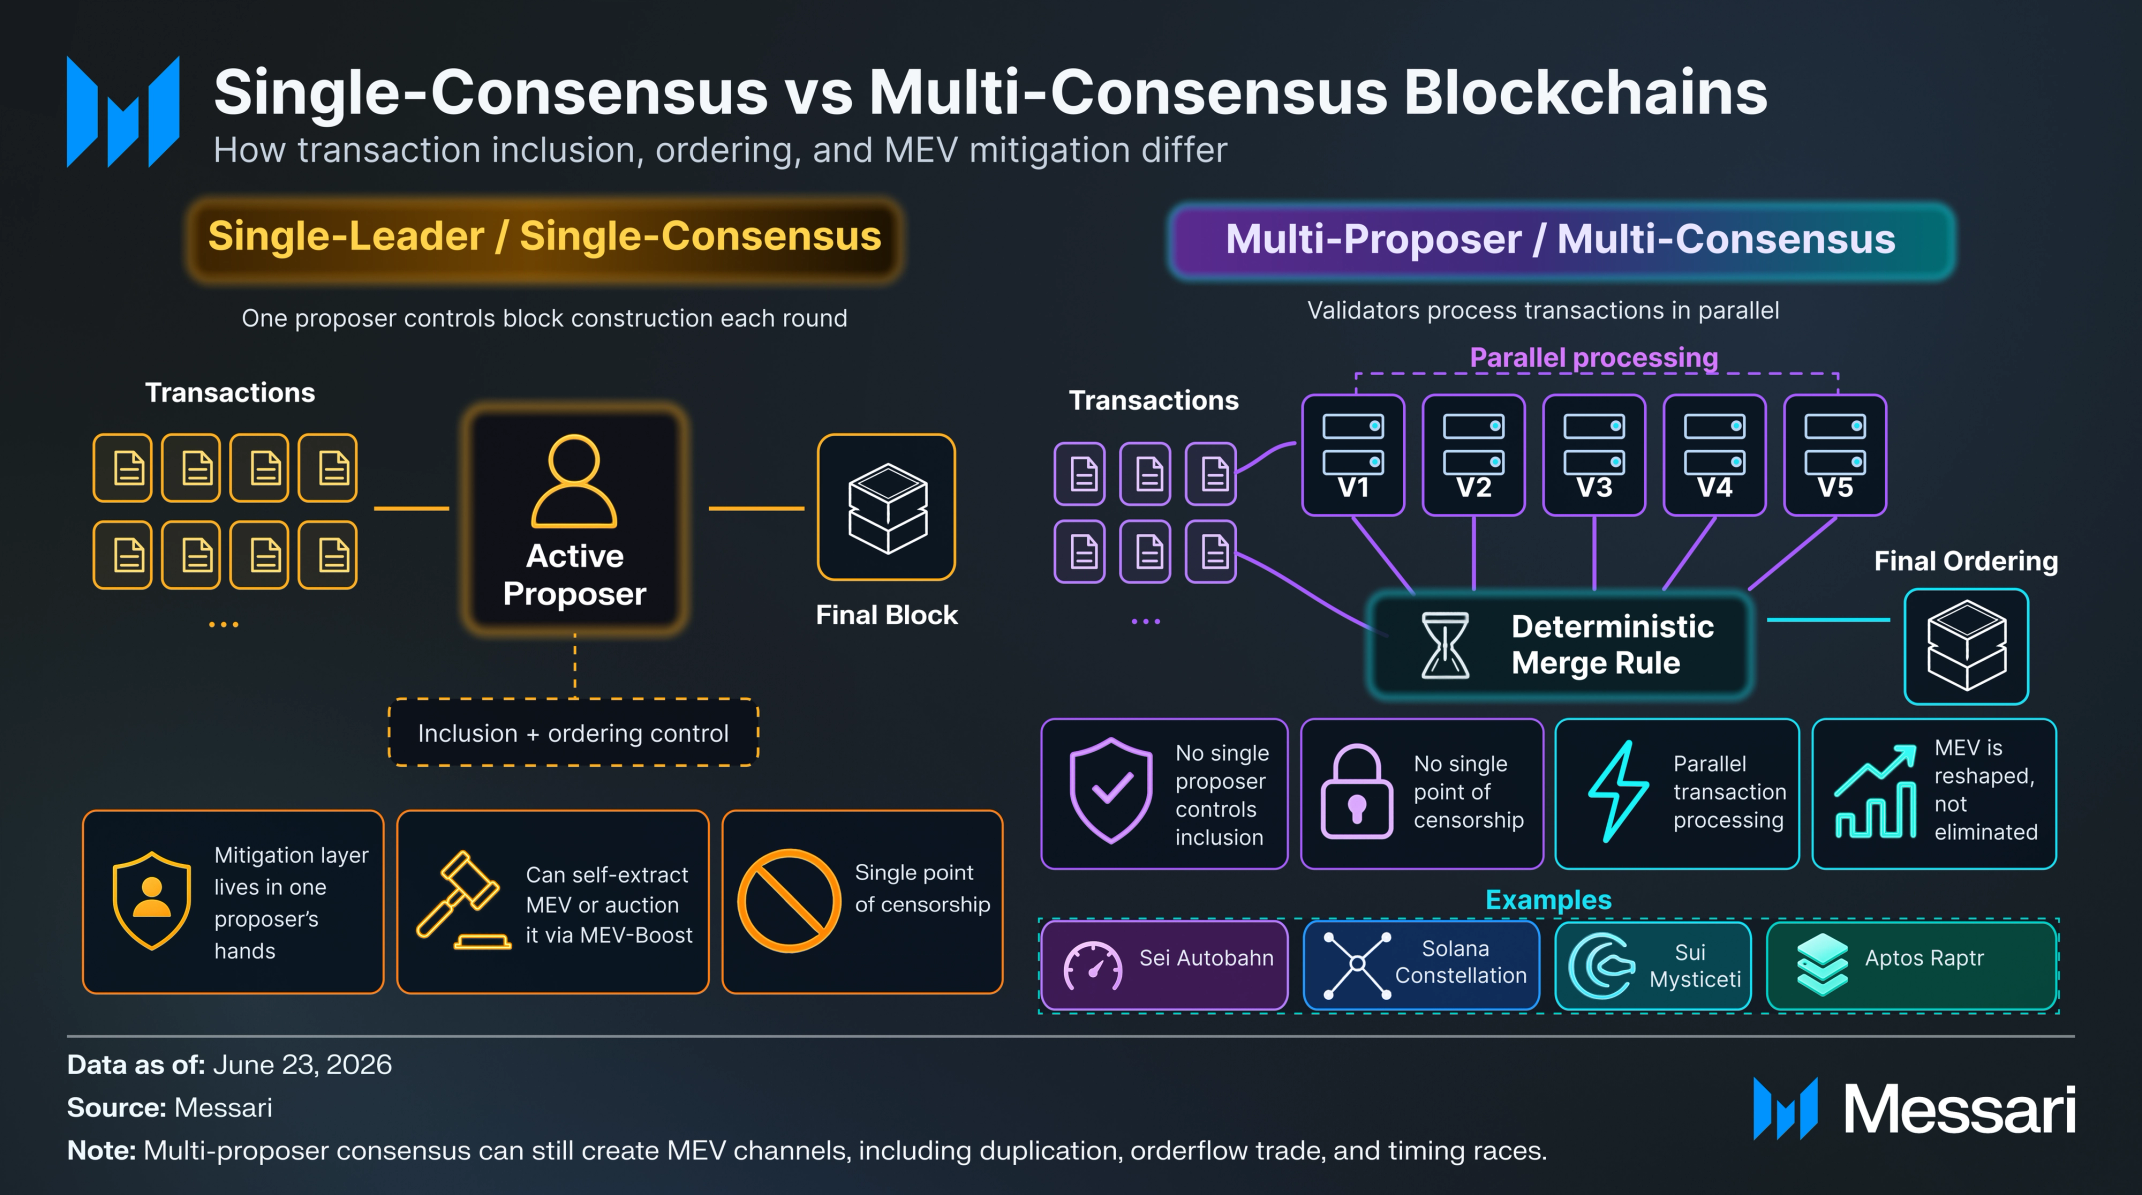
On a single-leader chain, the mitigation layer lives in one proposer's hands at a time, meaning the proposer has unilateral control over inclusion and ordering of transactions in the block. How MEV is mitigated depends on what they choose to do with that control, choosing whether to extract MEV themselves or auction it via MEV-Boost. Under multi-proposer consensus, every validator processes transactions in parallel, and a deterministic rule merges their outputs into a final ordering. Autobahn, Solana’s Constellation, Sui's Mysticeti, and Aptos’s parallel execution all converge on the multi-proposer design. Because no single proposer controls inclusion, there is no single point of censorship.
MCP consensus alone does not eliminate MEV. MCP architectures create new MEV channels that single-leader chains lack:
Same-tick duplicate steal: A proposer can copy a profitable transaction from another lane and race to win the merge.
Proposer-to-proposer orderflow trade: Proposers and relays can sell advance visibility of incoming transactions to peers who can build sandwich or arbitrage transactions in response.
Timing races: Faster proposers can see and react to incoming transactions before slower ones can, even when the final ordering rule is deterministic.
All three channels stem from broadcasting transactions to multiple proposers for censorship resistance. Every additional proposer that sees the transaction is another potential MEV extractor. Production chains have removed the single-leader monopoly without closing the new MEV channels MCP creates, but protocol-native MEV mitigation requires both.
The Mitigation Layer
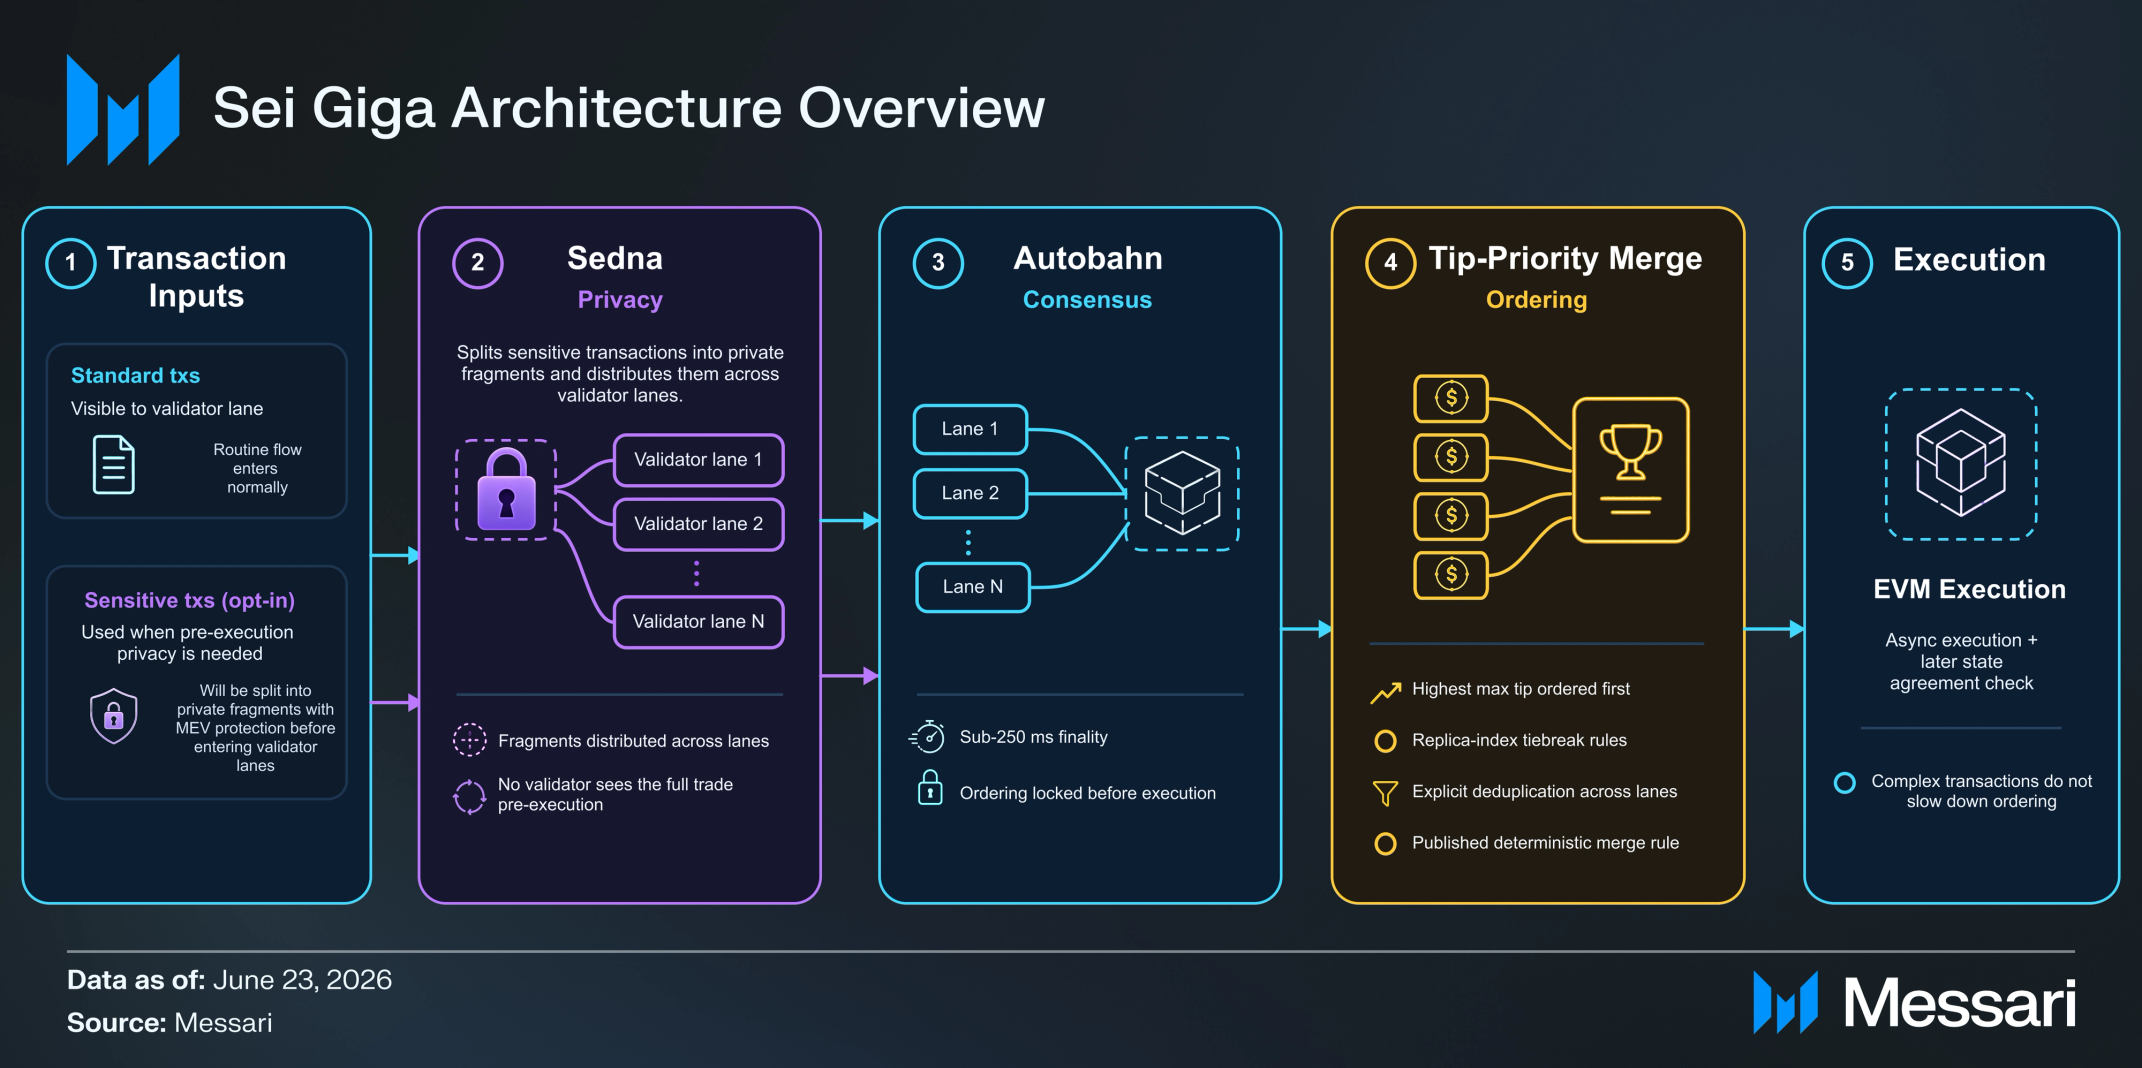
Sei Giga combines three primitives to counteract these new MEV channels: Autobahn handles consensus, the tip-priority merge handles ordering, and Sedna handles pre-execution privacy. No prior EVM Layer-1 (L1) has combined all three at execution-grade throughput.
Autobahn
Autobahn consensus finalizes transaction ordering in under 250 milliseconds. For comparison, a typical institutional FX Request-for-Quote (RFQ) round-trip runs 500 to 2,000 milliseconds.
In internal devnet testing, Sei achieved approximately 200,000 transactions per second. Using a representative Ethereum transaction cost of 25,000 gas, that throughput corresponds to roughly 5 gigagas per second. The architecture commits a snapshot of every lane's latest proposal at sub-second intervals to lock transaction order, then runs EVM execution off the consensus critical path while nodes verify state agreement by comparing results in a later block. Because execution sits off the consensus path, complex transactions don't slow down ordering, although mainnet has not been tested at scale.
Tip-Priority Merge
Giga sorts transactions across validator lanes by descending maximum tip offered, with replica-index tiebreaks and explicit deduplication. The lane carrying the highest-tip transaction in a given tipcut gets its transactions ordered first, and transactions in each lane execute in submission order. Identical transactions submitted across multiple lanes execute only once. All of these rules are published in advance, apply identically to every participant, and leave the proposer no room to deviate. Institutional trading desks need to know what priority access will cost before they submit an order, which a published merge rule provides. On Ethereum, the marginal MEV-Boost builder bid for extractive transactions routinely runs in the tens to hundreds of basis points without giving the bidder deterministic inclusion. The Giga merge converts the same auction into a transparent fee.
Sedna
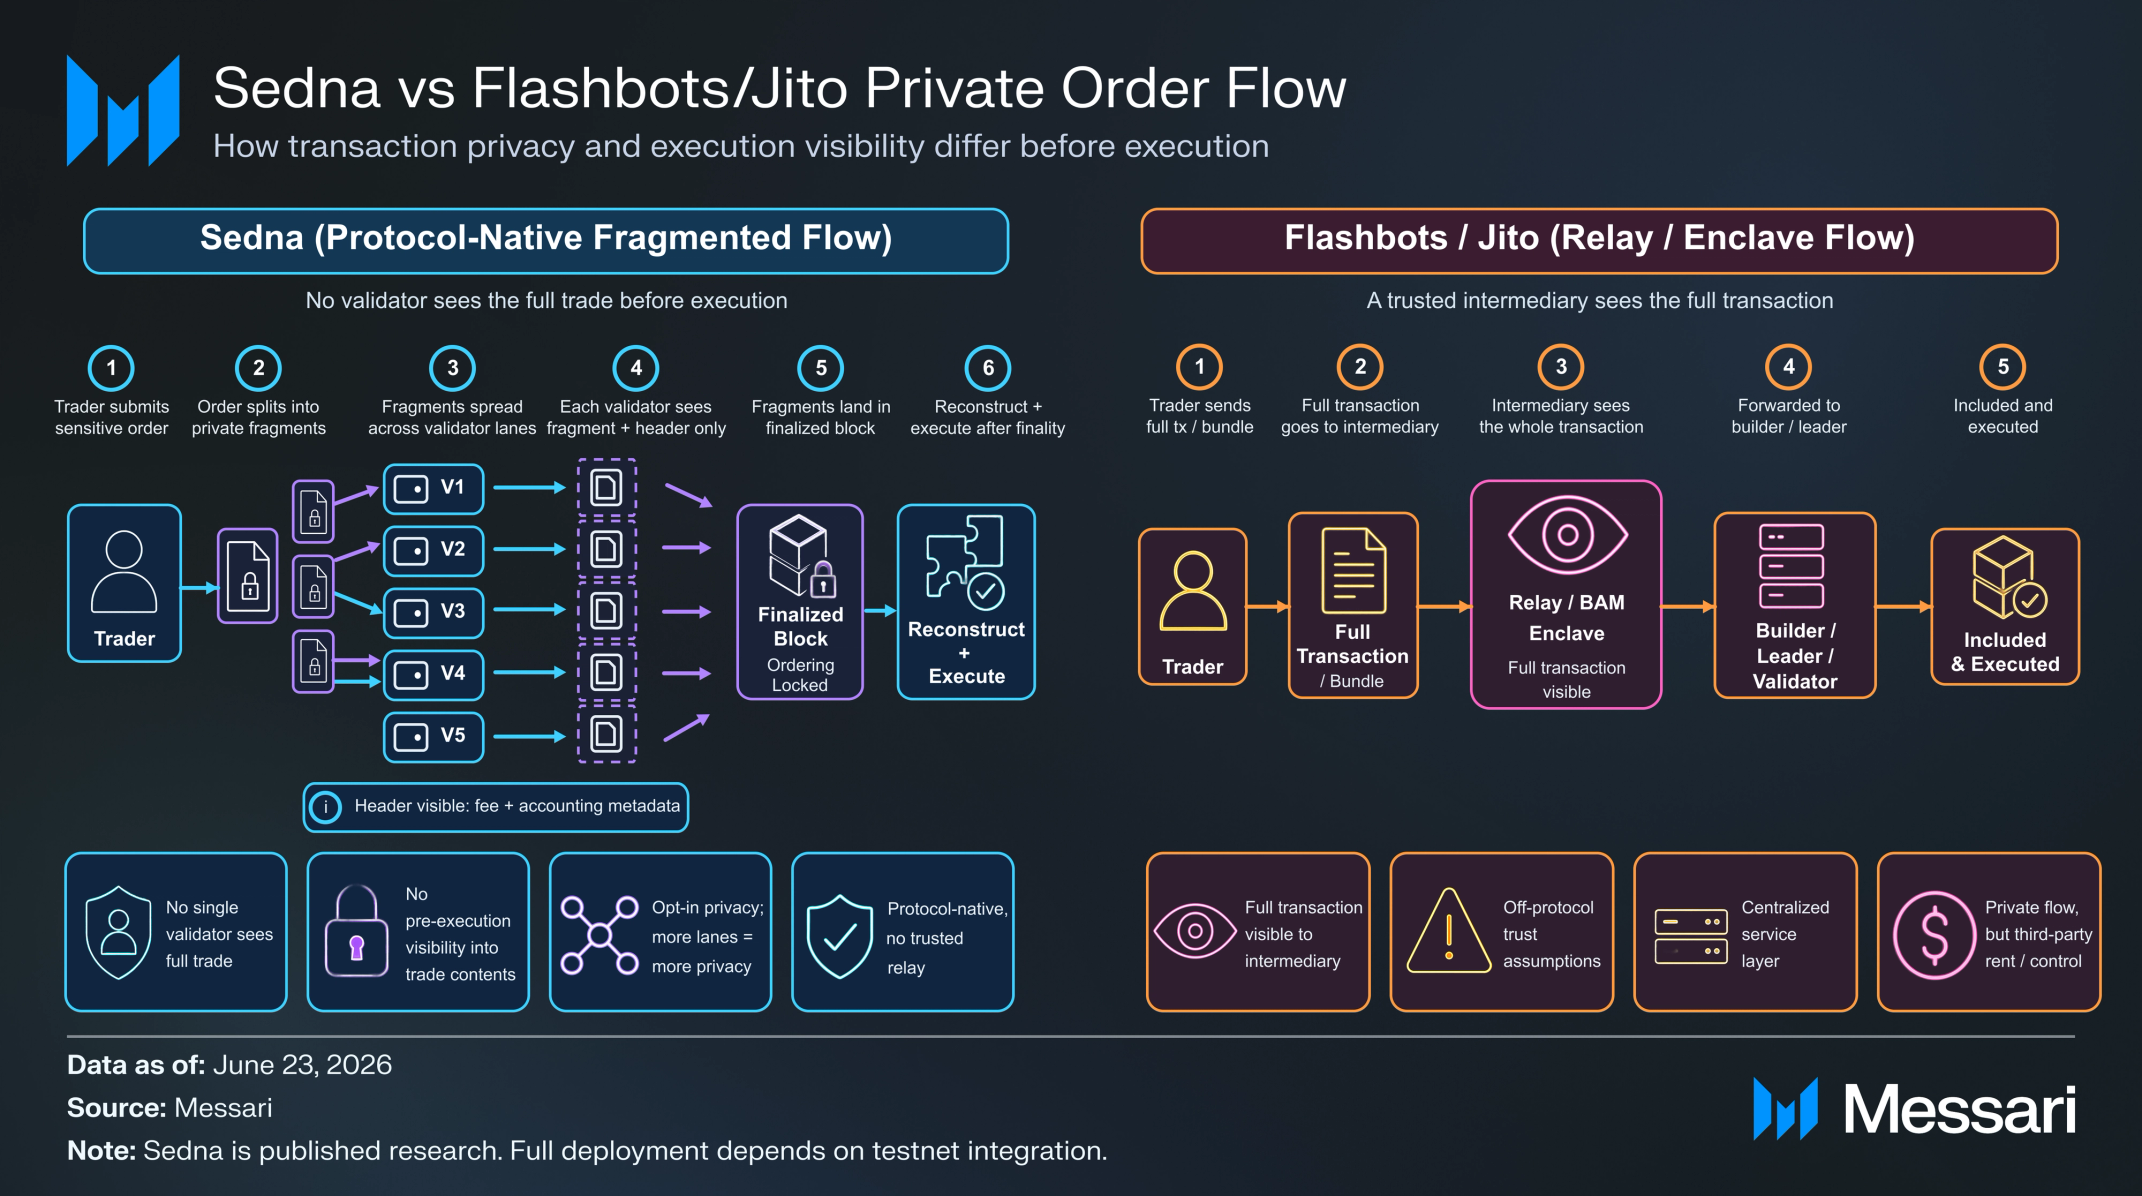
Sedna works the same way an institutional FX desk splits a large order across counterparties, so no single counterparty sees the whole trade. The sender splits each transaction into many small private fragments and distributes them across multiple validator lanes, so no single validator sees the entire transaction. The system reconstructs and executes the transaction only after enough fragments have been finalized. By that point, ordering is locked, and the transaction remains unreadable until reconstruction, preventing validators from observing its contents early enough to front-run it.
Sedna hides trade contents from validators during dissemination and ordering, exposing only limited transaction metadata such as fees and accounting information. Sedna shares some similarities with threshold-encryption systems such as Shutter, which conceal transaction contents until ordering commitments have been made. Unlike network-wide encrypted mempool designs, Sedna operates on an opt-in basis. Routine flow uses standard transactions, while sensitive flow is encoded into private fragments distributed across multiple validator lanes. Increasing the number of lanes increases the privacy guarantees.
The three primitives translate to three trader-relevant outcomes:
Fast and stable latency from asynchronous execution and 250-millisecond finality.
Deterministic and priced execution priority from the deterministic merge rule.
Zero pre-execution information leakage from Sedna's fragment-based delivery.
Sei Giga vs. Solana Constellation
Sei Giga and Solana Constellation are converging on multi-proposer consensus from opposite starting points. Solana has institutional flow today and is upgrading the consensus layer to support it long-term, while Sei has a cleaner architectural slate and is upgrading the entire stack to attract flow.
Solana's current MEV mitigation in 2026 runs through Jito's Block Assembly Marketplace, a centralized block-building service that keeps transactions encrypted until execution. BAM grew to ~28% of Solana's network stake during Q1 2026. The service works, but it operates offchain with explicit trust assumptions and extracts ongoing rent. The encryption hardware sits above the consensus layer, and the entire arrangement depends on Jito's continued operation as a third party. Solana Constellation, announced in March 2026, proposes removing the leader's ordering monopoly via multi-proposer consensus but does not include a pre-execution privacy primitive such as Sedna.
Sei Giga delivers the same outcome inside the protocol rather than above it. Pre-execution privacy lives within Sedna as a protocol-level submission mechanism, with no centralized block builder, no trusted relay, and no third-party rent extraction. Solana's distribution runs through an offchain architecture that works for the institutional flows already onchain. Scaling further into the TradFi institutional segment will require integrating with risk frameworks that resist third-party operator dependencies.
Tiered fee schedules for higher-volume participants
RFQs for size
OTC desks for blocks
Venue discretion bounded by published rulebooks and regulatory oversight
All-in execution cost in the low single-digit basis points at institutional size, paid as commissions or absorbed into the spread
Sei Giga brings this same market structure into the protocol itself. The tip-priority merge creates a protocol-native market for transaction ordering based on explicit tips, while Sedna provides a private transaction dissemination layer. Both operate under rules published in advance rather than at the venue's discretion. Sei isn't trying to beat a centralized matching engine on raw speed, as CEX engines run sub-millisecond against Sei Giga's ~250 milliseconds to ordering finality. Onchain execution carries properties no offchain venue can replicate at any latency. Giga delivers them with the same market-structure controls institutions trade against today.
Giga is built for the workflows where being onchain matters more than being fastest, such as basis trades between tokenized treasuries and onchain perps, RWA-collateralized lending, programmatic portfolio rebalancing, and intent-based execution where solvers compete on the path. These are trades CEXes don't serve well today.
CEXes currently hold most institutional flow, run the regulated rails, host the deepest liquidity on major trading pairs, and bundle prime brokerage with execution. Together, those advantages explain why institutional activity remains concentrated on centralized venues. Sei does not replicate those advantages directly. Instead, it aims to deliver institutional-grade execution while preserving the atomic settlement, composability, transparency, and self-custody that public blockchains can provide.
What is Live Today
Three of Sei Giga's architectural mechanisms ship today. The fourth, the full Sedna deployment, is finalizing its specification for mainnet following the release of three research publications.
Giga ships with Autobahn consensus, asynchronous execution, and a redesigned execution stack. Autobahn has been tested in an internal devnet at the throughput levels corresponding to roughly 5 gigagas per second. The migration itself is engineered to avoid regenesis or network downtime, which is meaningful for institutions integrating custody, bridges, and exchanges.
The Giga roadmap also includes post-quantum security enhancements. The initial implementation uses ML-DSA signatures, while the whitepaper notes that future work targets a fully post-quantum-native account model.
Sei has already attracted material institutional issuance, with Ondo Finance, Apollo, Libre Capital, and GAIB collectively holding ~$308 million in tokenized real-world assets there, about 72% of network TVL, though execution flow against those assets has yet to follow.
Conclusion
Sei Giga is one of the most integrated EVM L1 attempts to address discretionary execution at the protocol layer. Multi-proposer consensus removes the single-leader monopoly. Tip-priority ordering converts what is currently an off-protocol auction into a transparent fee that applies equally to all participants. Sedna brings pre-execution privacy inside the protocol rather than into a third-party enclave. No EVM L1 has combined all three before.
Improvements continue to be made, as Sedna's full deployment has not yet been completed on mainnet. The execution side of the institutional thesis remains in its early stages. Sei has attracted institutional issuers including Ondo, Apollo, Libre, and GAIB, but the execution workflows those assets are intended to support have yet to emerge at meaningful scale.
Institutional finance is moving onchain, and the workflows institutions are building against those assets can't run through an intermediary. CEXes can hold tokenized assets in custody, but can't be the venue for execution that requires no intermediary. The next several quarters will start to answer three questions: whether Sedna ships, whether internal devnet throughput translates to mainnet at scale, and whether the institutional issuers already on Sei use it as an execution venue.
All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Nothing contained in this report is a recommendation or suggestion, directly or indirectly, to buy, sell, make, or hold any investment, loan, commodity, or security, or to undertake any investment or trading strategy with respect to any investment, loan, commodity, security, or any issuer. This report should not be construed as an offer to sell or the solicitation of an offer to buy any security or commodity. Messari does not guarantee the sequence, accuracy, completeness, or timeliness of any information provided in this report. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.