What to Expect from dYdX V4

The perps/margin DEX landscape has shifted dramatically over the past few years with dozens of applications within the vertical launching on various L1s, L2s, or as standalone app-chains throughout 2022 and 2023. It is one of the few application sectors that has consistently generated ‘real-yield’ for token holders throughout the bear market, while the gap between CEXs and DEXs in relation to performance, cost, and overall UX continually narrows. Margin DEXs have a large runway for growth based solely on their current market share over crypto derivatives trading volume, but this potential could expand further as the broader industry matures and crypto trading volume increases across both centralized and decentralized venues. The primary risks associated with these products boils down to regulatory concerns, the lack of decentralization within the vertical, and general smart contract/protocol design risk. The launch of dYdX chain (V4) has investors wondering if the pioneer of onchain perps can retain its market share and deliver substantial value to token holders, or if the move away from an Ethereum L2 was a mistake and the token unlocks slated for December 1, 2023 are too large of a headwind to overcome.
The Opportunity
The derivatives market in crypto looks quite different from the derivatives market in traditional finance, in large part due to the popularization of perpetual futures by Bitmex when they launched the product in 2016. Tens of billions of dollars of perps trades are settled on centralized crypto exchanges each day, with futures and options volume paling in comparison. This is in stark contrast to traditional finance where perps have seen lackluster adoption, with futures and options being the instrument of choice for leveraged exposure. Binance, OKX, ByBit, and Bitget are the crypto CEX leaders, and Coinbase will soon be joining the battle for market share after Bermuda regulators recently gave the exchange the go-ahead to offer perps to non-US retail customers. Perps held a ~95% market share over daily derivatives volume traded on the two highest volume CEXs between October 3rd and 9th with nearly $230B of notional volume settled. The two most well known derivatives DEXs, GMX and dYdX, saw a combined $5.3B of volume over the same period, which equates to just 2% of CEX (Binance + OKX) volume.
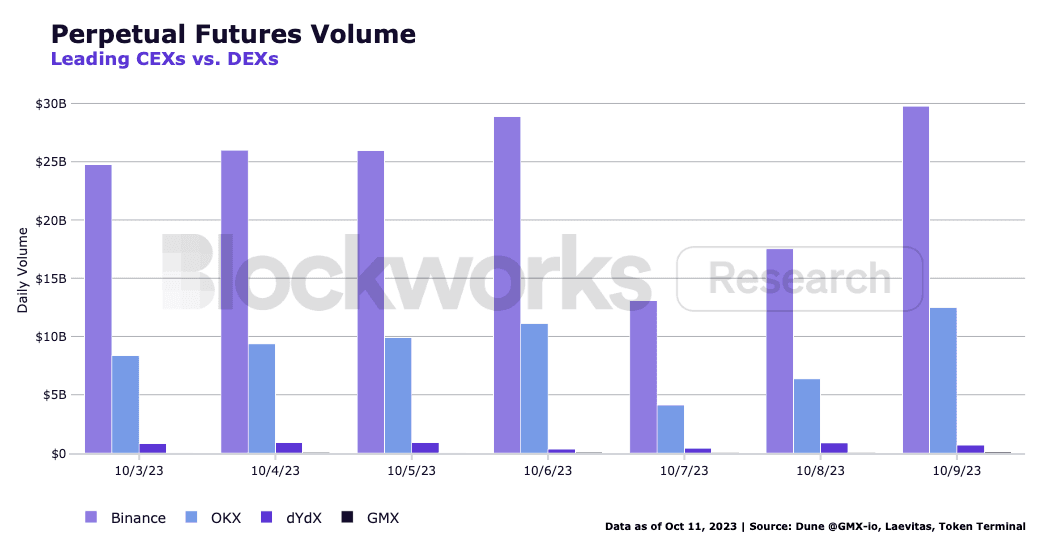
We view the sheer size of the perps market on CEXs and the lack of DEX market share penetration as a bullish tailwind for the vertical over the next 5 years as more trading firms become comfortable with self-custody and as these dapps become more decentralized and battle tested. We also believe that the broader crypto derivatives market will continue to grow over the next 5-10 years, so even if DEXs fail to gain market share from CEXs there is still plenty of room for growth.
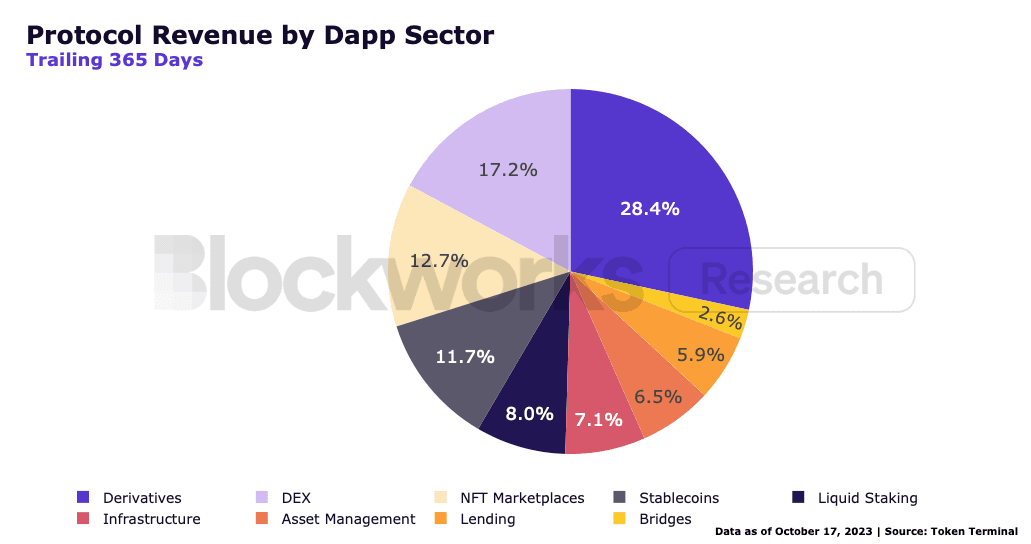
Perps/margin DEXs have also demonstrated their ability to generate substantial fee revenue, which is more often internalized by the protocol when compared to other DeFi applications. For example, Uniswap generates substantially higher fees than dYdX or any other perps DEX, but it must pay LPs for their service instead of internalizing the swap fees. The below chart shows that onchain derivatives, which is dominated by perps/margin DEXs, generate the most revenue out of any dapp vertical. Additionally, many perps protocols utilize synthetic leverage and oracle price feeds from leading CEXs to improve capital efficiency while reducing supply-side costs (revenue owed to LPs), which enables a high margin business model.

Sam leads coverage on Ethereum, L2s, Aave, Compound, as well as NFTs and gaming. Previously worked on a hedge desk at UGC.