The following report was written by Messari Hub Analyst(s) and commissioned by Blockdaemon, a member of Messari Hub. For additional information, please see the disclaimers following the article.
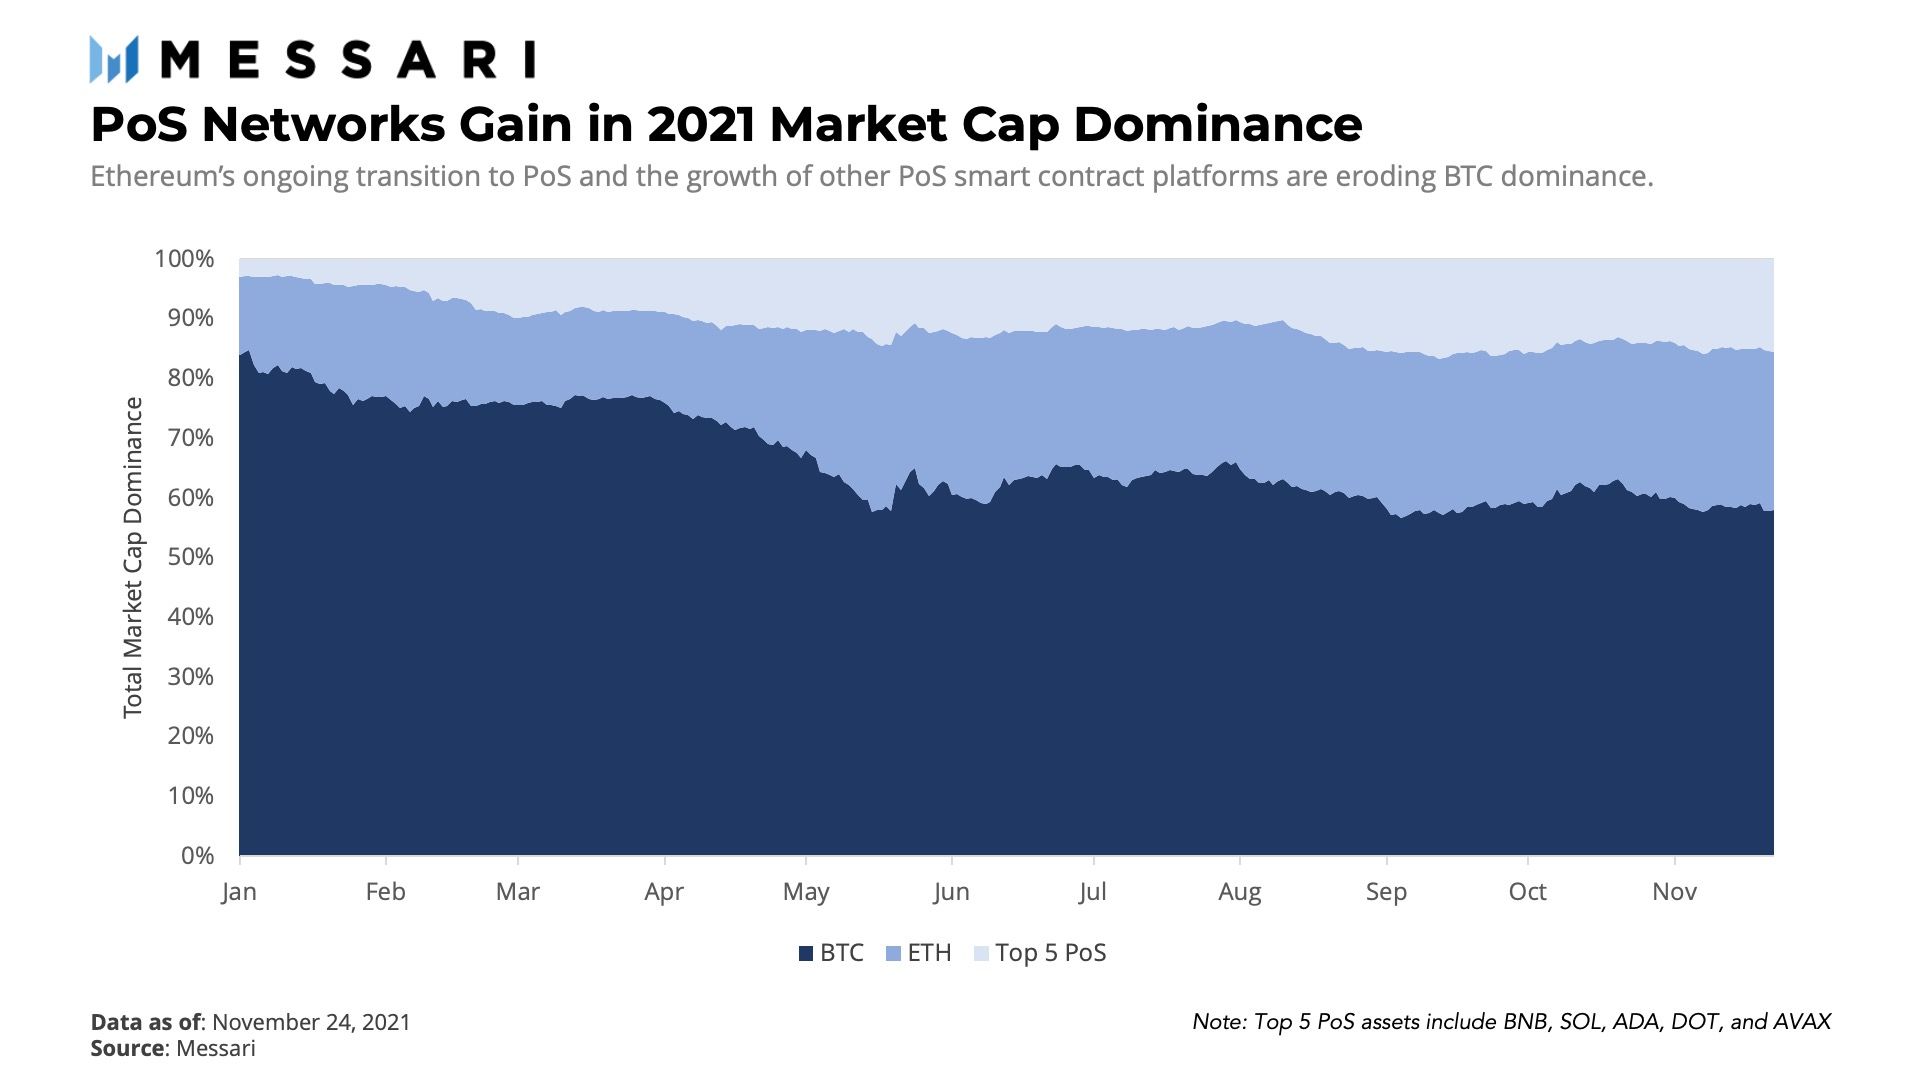
Today’s leading blockchains are undergoing a massive shift from Proof of Work (PoW) to Proof of Stake (PoS) consensus mechanisms. The original PoW model pioneered by Satoshi Nakamoto has fallen out of favor as critics point to the negative externalities created by its security model and its trend towards centralized mining pools. In its place, PoS designs are witnessing tremendous growth for their promises of energy efficiency and greater decentralization. If the Ethereum 2.0 (Eth2) “merge” to PoS were finalized today, PoS based chains would account for 44% of Layer 1 market capitalization. If we ignored Bitcoin from that calculation, PoS chains would balloon to a 91% share. This shift away from PoW dominated networks is already creating second-order effects in the form of new business models that earn rewards for securing PoS networks.
Since the inception of Bitcoin in 2008, PoW chains have enabled companies to build business models centered around maximizing mining rewards. Early mining companies understood they would benefit from economies of scale and began establishing “server farms” in locations with cheap energy costs to maximize their probability to earn mining rewards. In just 13 years, crypto mining has swelled into a roughly $31 billion industry. PoS chains open up similar business opportunities for individuals and companies that seek to capitalize on PoS rewards. JP Morgan estimates that staking already generates $9 billion worth of revenue annually and will grow into a $40 billion industry by 2025. Given this lucrative forecast, it’s essential to understand the nuances of staking and how they interplay with the rising staking-as-a-service industry (STaaS).
* To avoid confusion with the established SaaS acronym within the tech industry (software-as-a-service), we will refer to staking-as-a-service as STaaS for the remainder of this report.
A Background on Proof of Stake
For a permissionless blockchain to function, only one entity may update the network’s shared ledger at any given time. A consensus mechanism is the set of rules that the security providers within a blockchain network use to determine which participant’s update should be adopted by the network. The entity responsible for inputting a series of transactions (block) at any time is known as the block producer. In return for producing a new block and thereby upholding the network’s security, the block producer earns block rewards from the network (the composition of block rewards will be explored in greater detail below).
As mentioned above, PoW and PoS are two of the most widely used consensus engines powering today’s blockchains. In a PoW system, “miners” expend physical resources (time and energy) in a competition to become the next block producer. This burning of external resources gives the network its sense of security. Should a bad actor wish to halt or alter the state of the network, they would need to control > 50% of the network’s computing power.
In a PoS system, the competition for exogenous, physical resources (power), is replaced by the competition to attract the native cryptocurrency. This endogenous resource is known as stake.This key difference allows PoS networks to operate without expending large amounts of electricity and allows for wider participation in the consensus process compared to PoW. Participants that wish to become a network validator must stake, or lock up, a portion of the network’s native cryptocurrency as a pledge to contribute to the consensus process in good faith. The value of the network’s total stake is what provides it with security, which makes different forms of 51% attacks more expensive than PoW - as Vlad Zamfir said “it’s as though your ASIC farm burned down if you mined an invalid block”.
Aside from its primary function as a security barrier, a validator’s stake is important for two additional reasons. First, a validator’s stake amount is directly proportional to its probability of being elected to input new transactions to the ledger, thereby influencing the amount of rewards earned by the validator. A validator’s stake also serves as collateral to disincentivize adverse behaviors. Should a validator act maliciously towards the network, it will generally be penalized by losing a portion of its stake or losing the right to participate in the consensus process for a period of time. Together, this system incentivizes healthy network behavior. Validators stake more collateral for a greater proportion of block rewards. The greater the amount of collateral staked, the more likely validators will perform to network norms, thereby ensuring chain security.
The Rise of STaaS
The Incentive to Stake
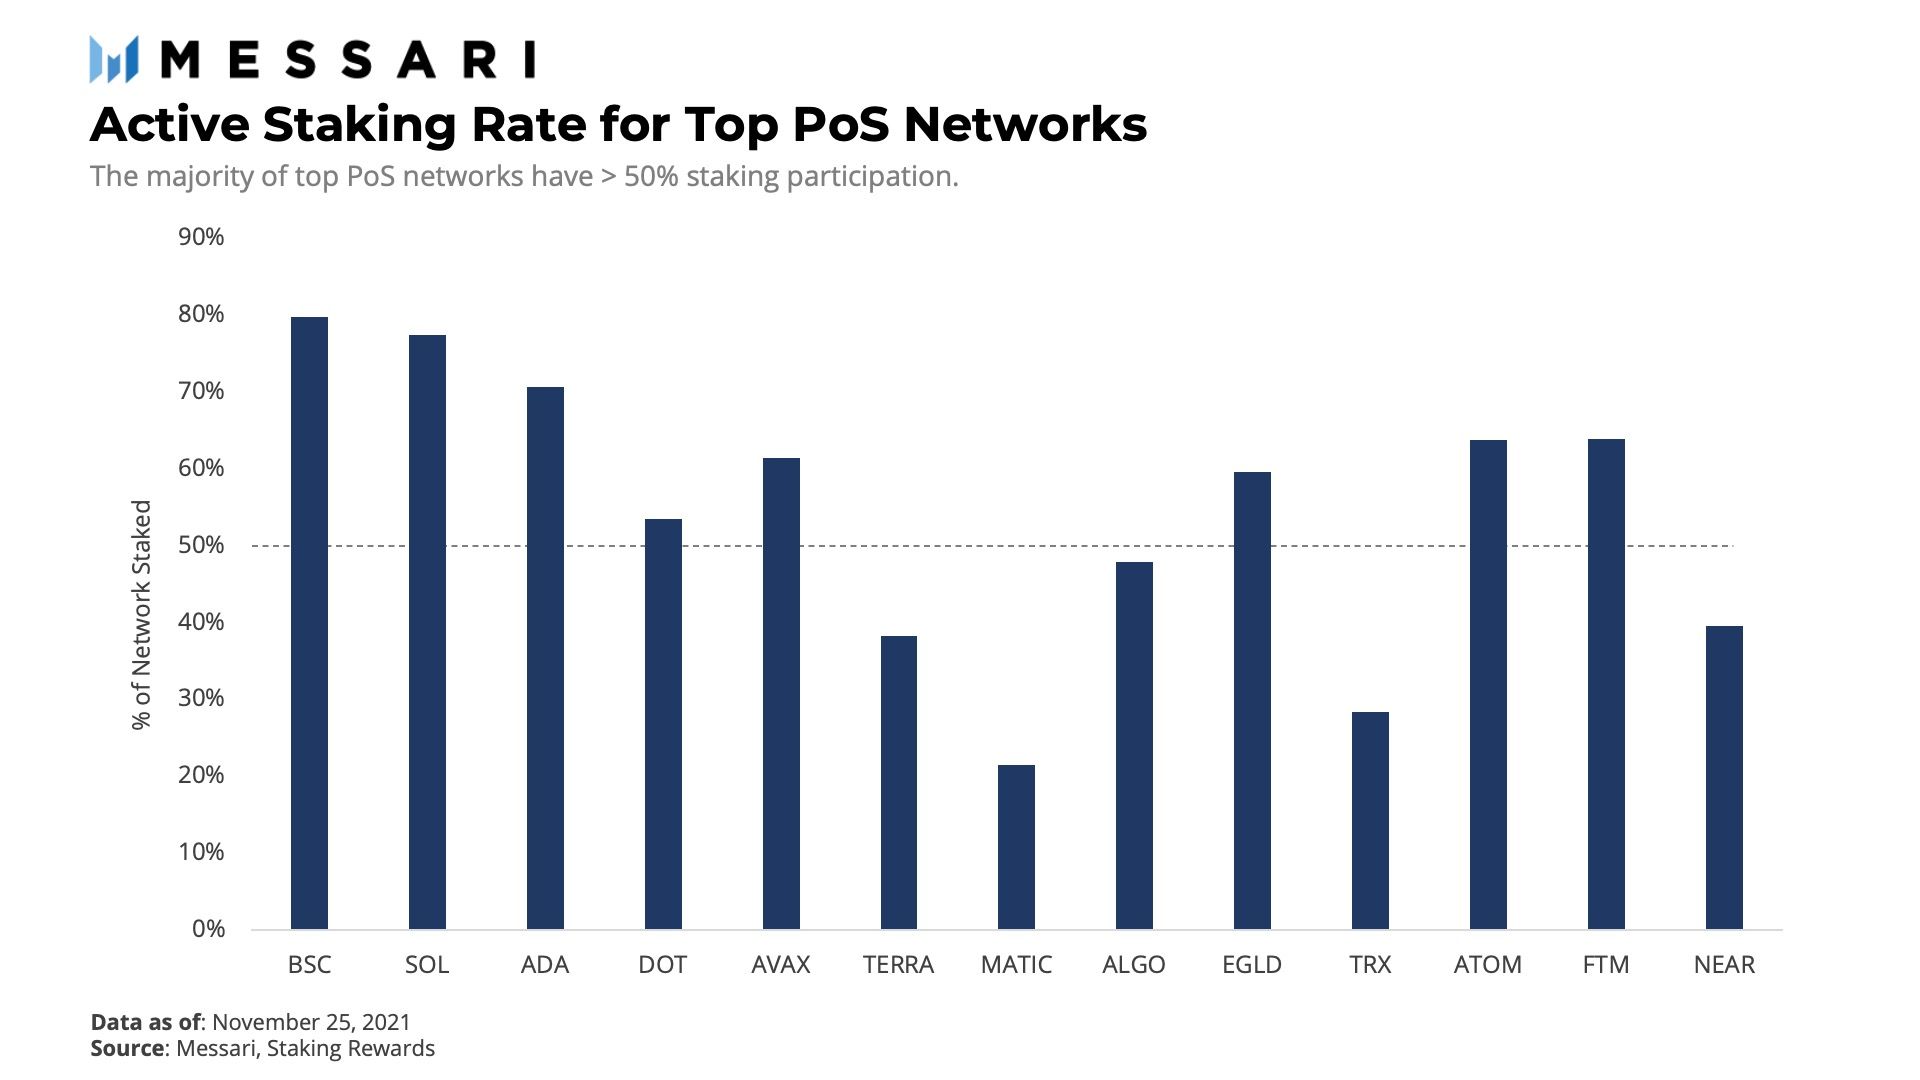
With this basic technical understanding of how PoS consensus functions, we can explore the economic opportunities it creates. A PoS network incentivizes stakers to contribute to its security by rewarding validators with block rewards composed of network inflation and transaction fees. The inflationary rewards can be thought of as the network’s native incentive to encourage users to put their assets to work. Those that choose to hold rather than stake will be subject to dilution in networks with inflationary supply schedules. Should 100% of the network stake, there would be no relative change in network ownership as all of the inflationary rewards would be distributed to all existing holders. This is very unlikely to ever happen considering it would mean that no one is actually running applications on the network or making transactions. Therefore, each PoS network exhibits different active staking rates depending on the activity and incentives at play within each respective network.
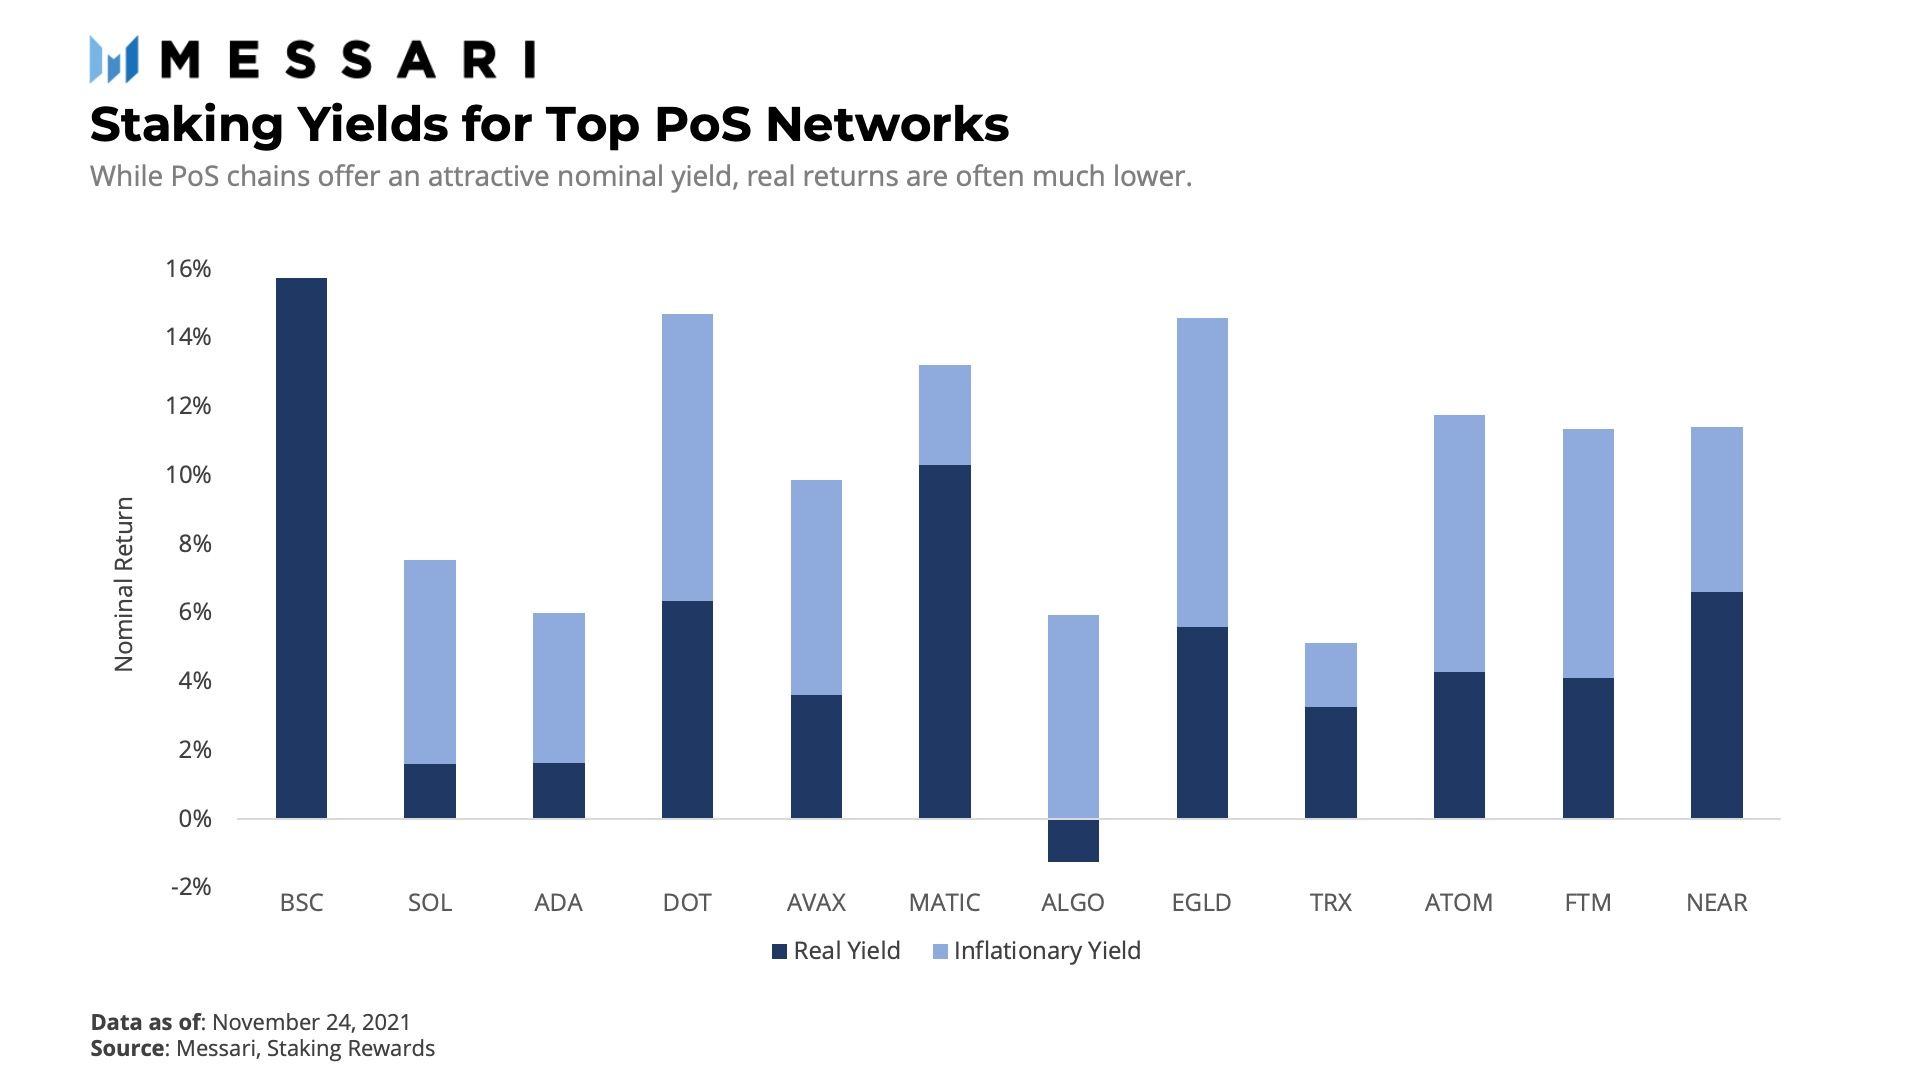
The ever-changing staking rate results in a dynamic reward rate for a network’s stakers. As more stake enters the network, the active rewards rate decreases as staking rewards must be distributed to a larger group and vice versa. This overall staking return is known as the nominal staking rate, which includes transaction fees and inflation. The nominal rewards rate less the amount of rewards attributed to overall network inflation is referred to as the real rate. While the nominal yields for many PoS chains can reach double digits, the real rate typically ends up in the single digits at current levels. The main exception to this trend is Binance Smart Chain (BSC), where block rewards are composed entirely of transaction fees.
Obstacles Create Opportunities
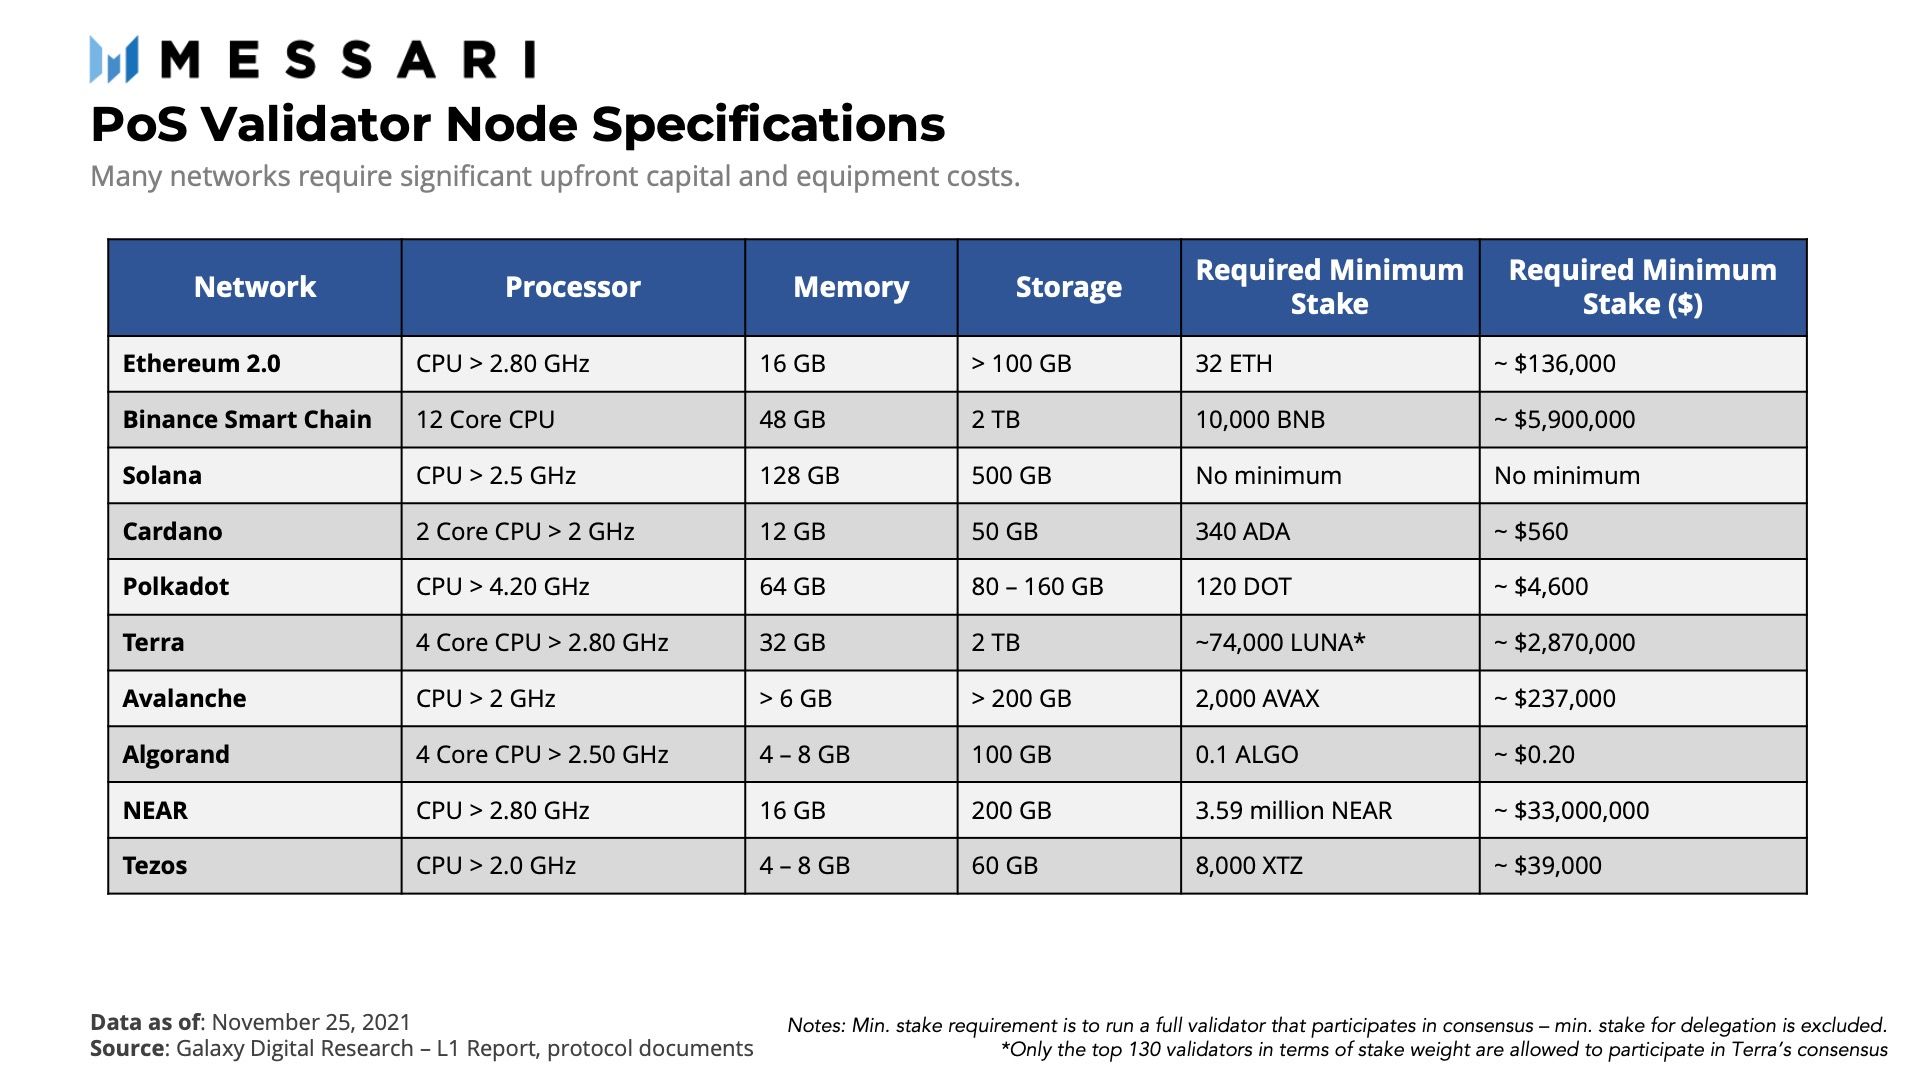
If staking is the native revenue channel for participants in a PoS network, why doesn’t everyone run a validator? There are several factors at play here. First, there is generally a minimum capital requirement to become a validator which ends up pricing out the majority of retail users.
Even chains like Solana that have no minimum stake requirement still demand capital in other forms such as high-end computers, voting fees (currently estimated at 2 SOL per day or ~$500), and sufficient capital staked for the validator to be elected. If a participant has enough capital to meet the minimum stake threshold, they are tasked with the ongoing chore of ensuring their validator is always online and performing correctly. Most PoS networks will punish offline or misbehaving validators using slashing penalties. Finally, staking comes with an opportunity cost - assets are locked up for a period of time and can’t be used for other purposes such as borrowing and lending in DeFi. This problem applies to most PoS networks that use a bonded staking mechanism but are avoided in networks such as Cardano that support native liquid staking. Altogether, these problems are exactly what the STaaS industry aims to solve for its users.
The STaaS industry was originally created to offer the economic benefits of staking to the masses while solving the challenge of ongoing validator maintenance for non-technical users. As the industry has matured, we’ve begun to see the addition of liquid staking derivatives to help offset the opportunity cost of locking up staked assets. STaaS is a relatively straightforward business model - users transfer or delegate their assets to a STaaS provider that manages a set of validators. This allows even the smallest of users to enjoy the benefits of staking. By using a STaaS provider, a user can easily stake almost any PoS asset in a few clicks.
In return for maintaining the necessary validator services for its customers, a STaaS provider will charge its customers a fee. This can be a fixed fee per month but is more commonly a percentage of the rewards generated on its customers’ stake. Such commissions generally range from 5 - 20% of customers’ staking rewards. Over time, we can expect fee percentages to grind lower as a result of more competition from a growing population of staking providers joining the ecosystems. Additionally, the nominal amount of fees generated per customer is expected to decline as protocols mature and taper their rewards schedule.
STaaS Categorization
Similar to today’s wallet and exchange offerings, we can classify today’s STaaS businesses as either custodial or non-custodial. Regardless of these classifications, all STaaS may offer a liquid staking feature.
Custodial STaaS
Custodial STaaS providers are characterized by taking control of and maintaining customers’ assets throughout the entire staking process. The most common examples of centralized staking providers are centralized exchanges such as Coinbase or Kraken.
Custodial STaaS is generally targeted towards retail users that want a simple way to earn a return on their holdings without worrying about the backend processes. Any rewards generated on customers’ stake is distributed first to the staking provider before being passed on to customers. This is analogous to how a bank works; the bank retains power over its customers by dictating the fees charged on its depositors’ interest while maintaining custody of such deposits. Since customers are already trusting these third parties to custody their assets, staking with these providers doesn’t require any additional trust assumptions other than the STaaS provider’s ability to competently manage a validator or outsource this responsibility to yet another third party. However, the same risk of custodial wallets and exchanges applies for custodial STaaS providers - not your keys, not your crypto.
It’s common for custodial STaaS providers to partner with a backend Node-as-a-Service (NaaS) provider to outsource their staking infrastructure. In this case, the infrastructure provider maintains the hardware and day-to-day validating node operations while the STaaS provider focuses on the custodial aspect (key management and cold storage). Popular white label providers include Blockdaemon and Staked. NaaS providers are also used by large enterprises or VCs that wish to have their own validator but lack the in-house expertise to host or manage one. These parties can afford the extra costs of a dedicated team of specialists focused on ensuring maximal uptime and security. In early 2021, Coinbase’s purchase of Bison Trails for $80 million marked the first major acquisition of a NaaS infrastructure provider. Given the synergies between these two types of businesses, this likely won’t be the only deal we see made.
Non-Custodial STaaS
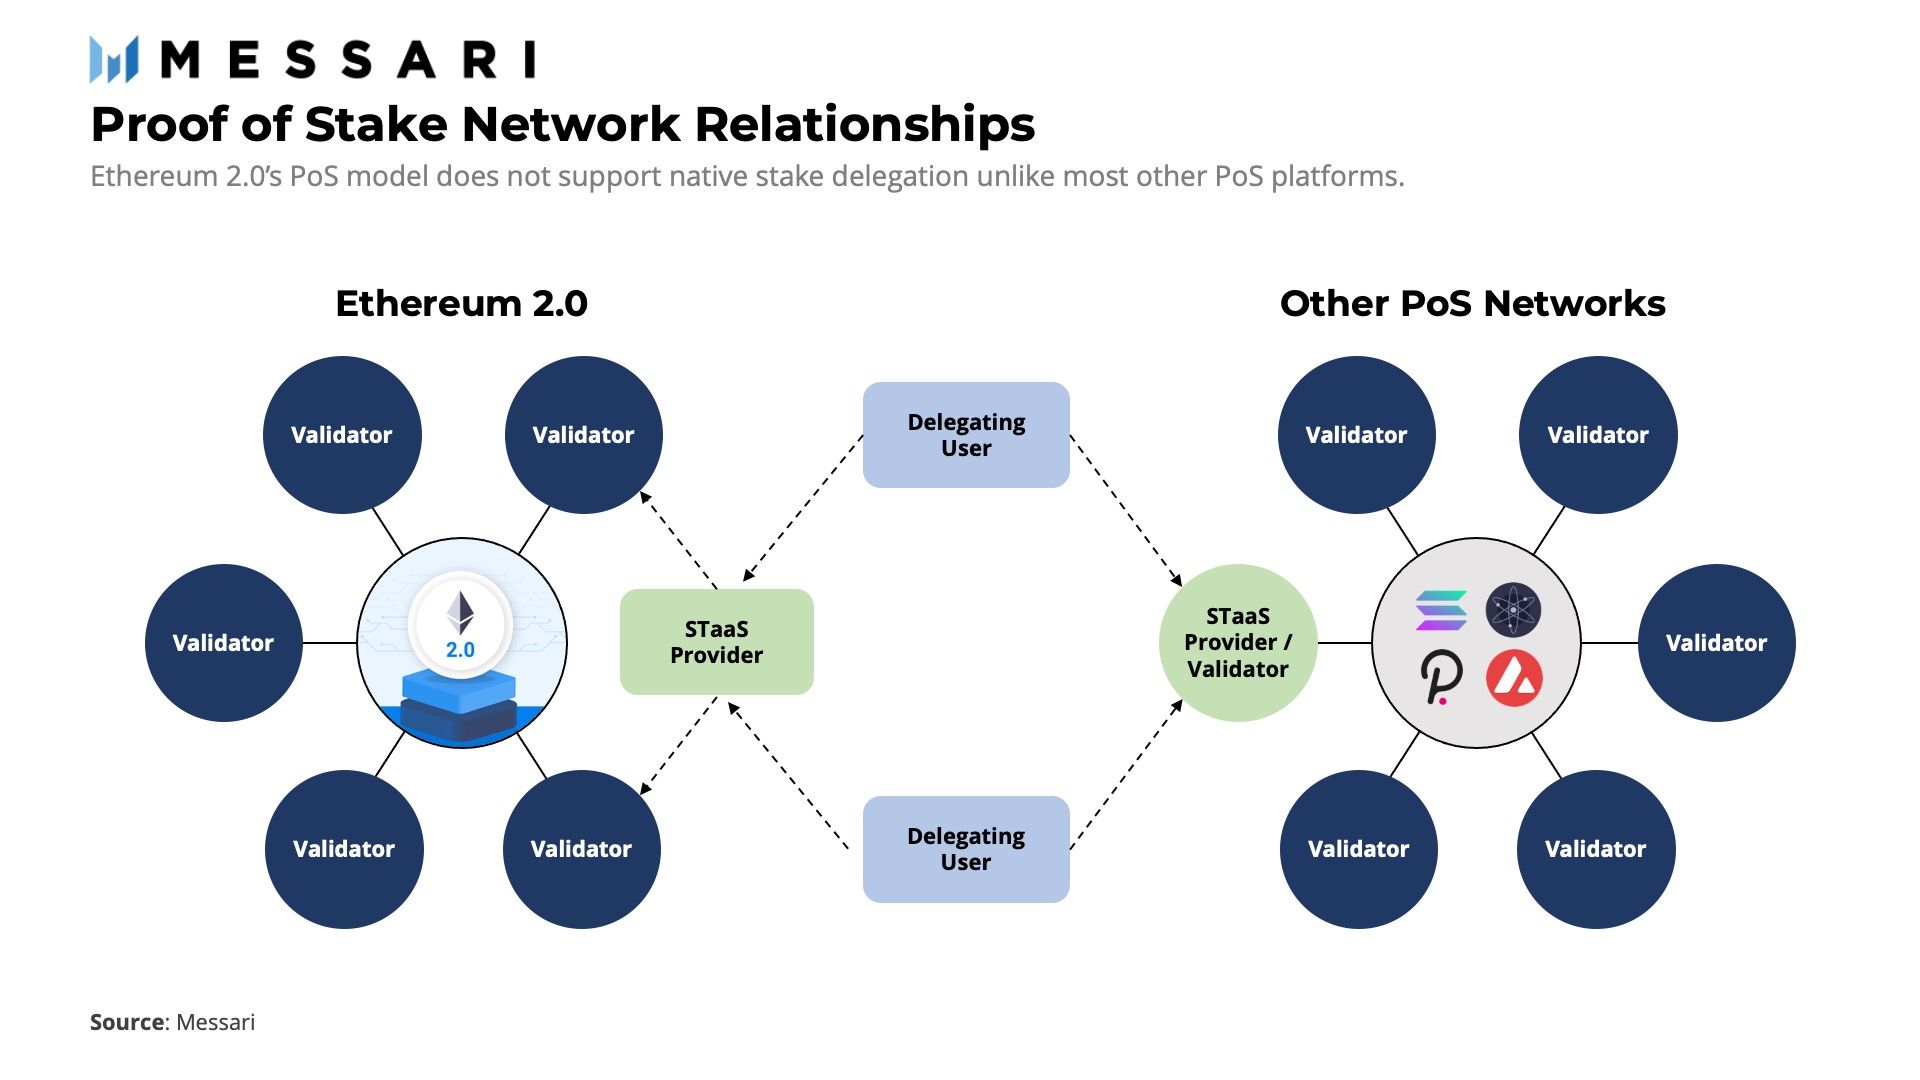
STaaS wouldn't be a true Web 3.0 service without the ability to participate while maintaining custody of one’s assets. The process of transferring stake to a non-custodial STaaS provider is known as delegation. Most PoS networks support native delegation, which means that the process of delegation is built into the network itself. Anyone that already runs a validator may accept delegations to increase their proportion of staked assets, thereby earning more staking rewards. These validators charge a commission similar to custodial STaaS providers. However, the reward distribution method is slightly different. Since the network recognizes and supports delegations, it can distribute a delegator’s share of rewards directly to the delegator rather than leaving it up to the validator to pass the rewards on. This helps to reduce some of the counterparty risk associated with the custodial STaaS business model.
While supporting delegation at the network level may sound like a no-brainer, there is always the risk that stake may become too centralized with a few large validators in the network. In an effort to promote decentralization, Ethereum decided to leave this feature out of its Eth2 PoS design and let the market build delegation features on top of the network.
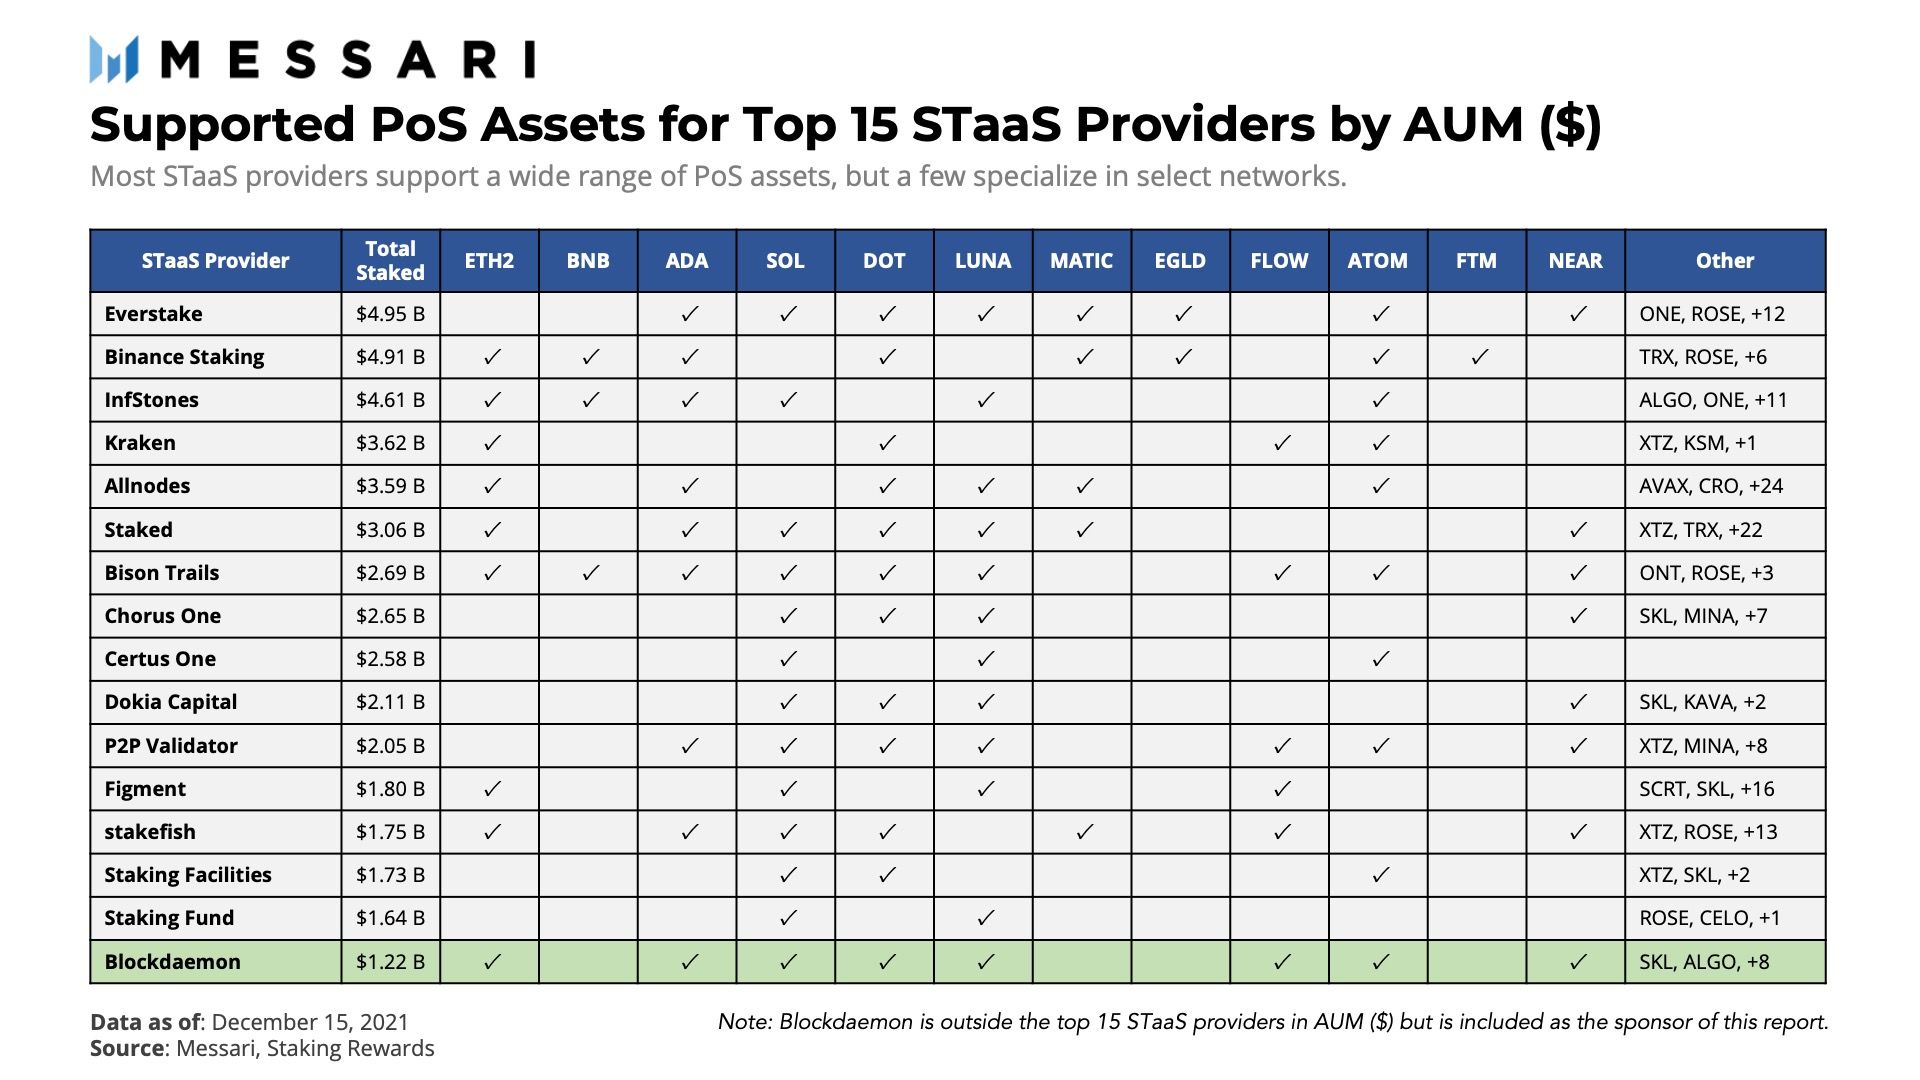
This makes Eth2 STaaS an interesting subcategory of its own. It’s also a reason some of the largest staking providers, both by value staked and by number of chains supported, don’t support Eth2 staking. For example, Everstake is the largest STaaS by $ value staked, offers support for 27 different PoS networks, but doesn't support Eth2. This is likely due to there being no native staking features built into the network, making it impossible to just run a validator with its own assets and accept delegations without any extra steps.
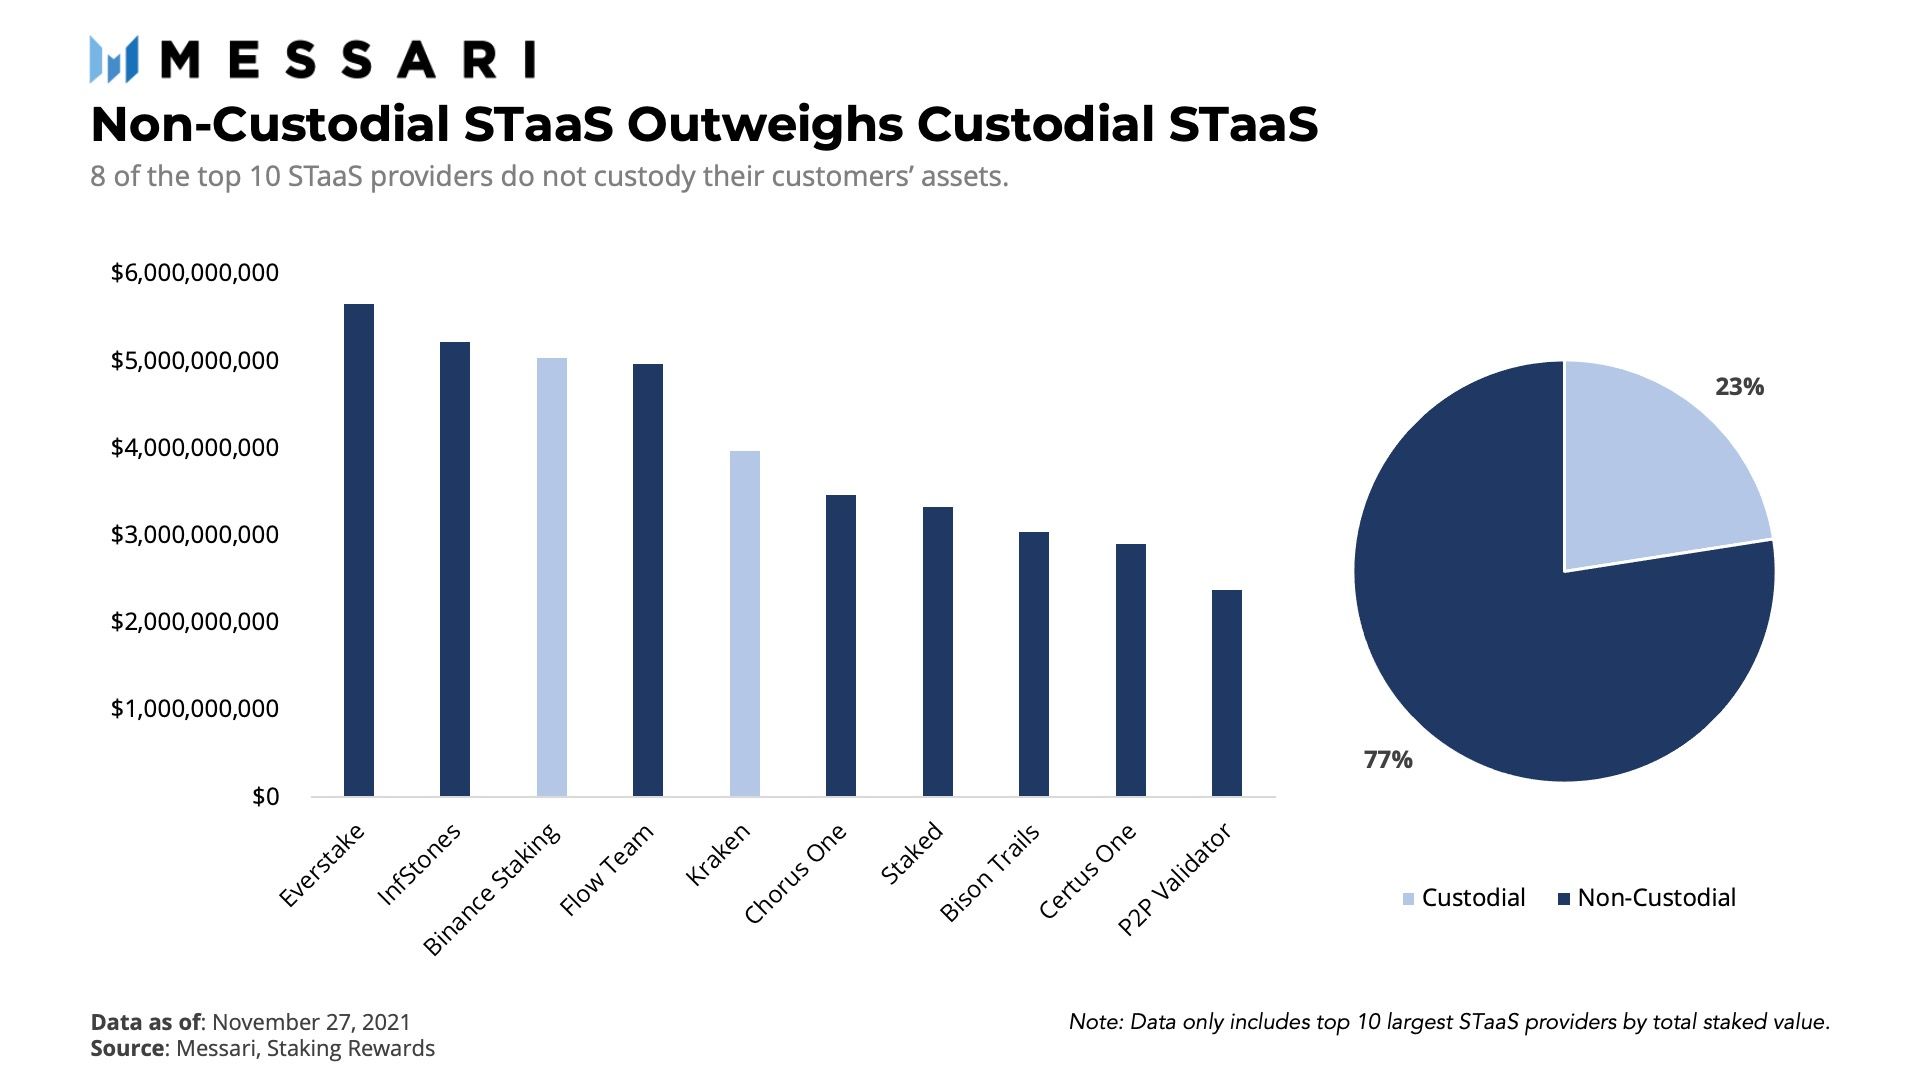
Overall, we can see that non-custodial STaaS is the clear leader in the market today. This is unsurprising given the decentralized nature of these networks. A contributing factor to note is that most of the NaaS infrastructure providers mentioned above run public validators that anyone may delegate to. Since they’re already specializing in infrastructure for their large institutional customers, it’s a simple addition to offer a generic service for smaller players as well.
Liquid Staking Solutions
Since staking is a commitment to the security of the network, assets need to be locked up in order to prevent a “bank run” scenario where all the stake is quickly withdrawn and the network’s security collapses. The lockup period is unique to each network. Unstaking for Solana only takes two days, whereas stake in Eth2 is locked indefinitely until it completes its transition to PoS. Liquid staking provides depositors with a derivative asset that represents their staked position, accrues staking rewards, and can be traded and potentially used as collateral for DeFi activities. While liquid staking is a feature that both custodial and non-custodial STaaS providers may offer customers, it’s most commonly used in decentralized staking pools. These protocols don’t run validators themselves. Instead, they accumulate staking deposits and distribute them to validators already operating in a given network. For this reason, rewards and penalties are generally shared by all depositors in a staking pool.
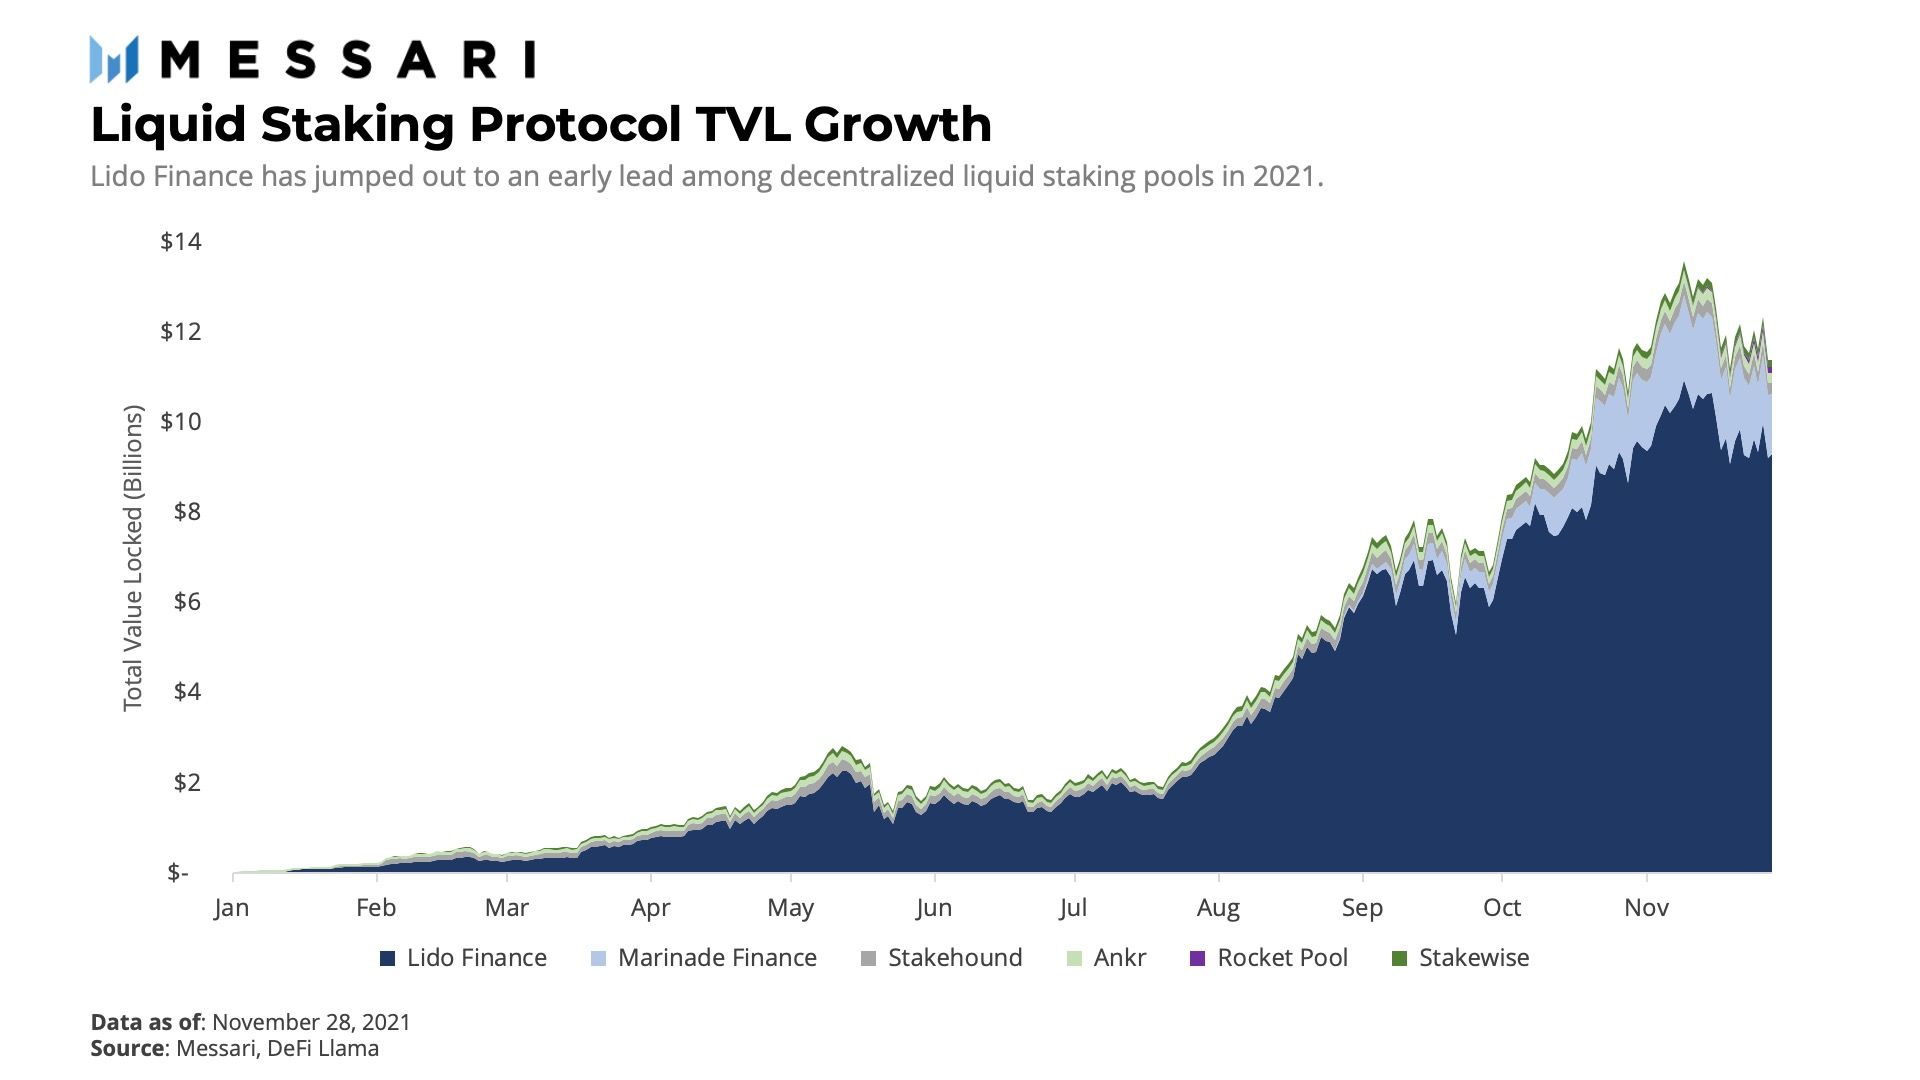
Liquid staking solutions are still in their early stages of development. Lido’s early mover advantage and support for multiple networks (Eth2, Terra, Solana) has allowed it to jump out to an early lead. Its stETH derivative is the most liquid staking derivative across DeFi and can be used within protocols such as Maker, Yearn, and Curve. With more time, other protocols’ staked asset derivatives should establish themselves as trustworthy collateral options. Additionally, we can expect more chains to feature liquid staking derivatives. Liquid staking is an established tool on chains like Ethereum, Solana, and Terra, but protocols on other chains are starting to launch their first liquid staking derivatives. Most recently, Acala released its LKSM derivative to allow for liquid staking on Kusama.
A Critical Evaluation of STaaS
Risks
While STaaS democratizes the staking process for crypto users, it doesn’t come without risks. As we discussed previously, staking itself isn’t risk-free. Any validator is subject to penalties for slashing events such as downtime or double signing that prevent the network from reaching consensus. Downtime refers to any time a validator is offline and misses its duties in the consensus process. Double signing occurs when a STaaS provider keeps a backup validator running (to prevent downtime) and both of its validators use a single private key to vote for a block. Slashing refers to the network stripping a validator of all or a portion of its staked assets. Some protocols, especially those that are early in their growth cycle, have relaxed slashing policies in order to maximize network growth. These should be viewed as temporary measures that will be reversed in the future as more validators are onboarded to the networks.
Although STaaS providers help to mitigate slashing risks with their staking expertise, it’s important to note that this risk will always exist in some non-zero form, and it’s up to the STaaS provider to decide if it will cover losses that do manage to occur. Today’s providers have ranging policies. When Staked.us uncovered a bug that caused its validators to mis-sign transactions, it chose to refund $30,000 in delegator losses. Blockdaemon offers a 100% insurance policy on slashing events that may occur. Coinbase states in its terms that it may or may not compensate delegators, depending on the reason for the slashing penalty. As the STaaS industry matures, we can expect slashing insurance to be demanded by risk-averse participants to mitigate any losses that end up not being covered by STaaS providers.
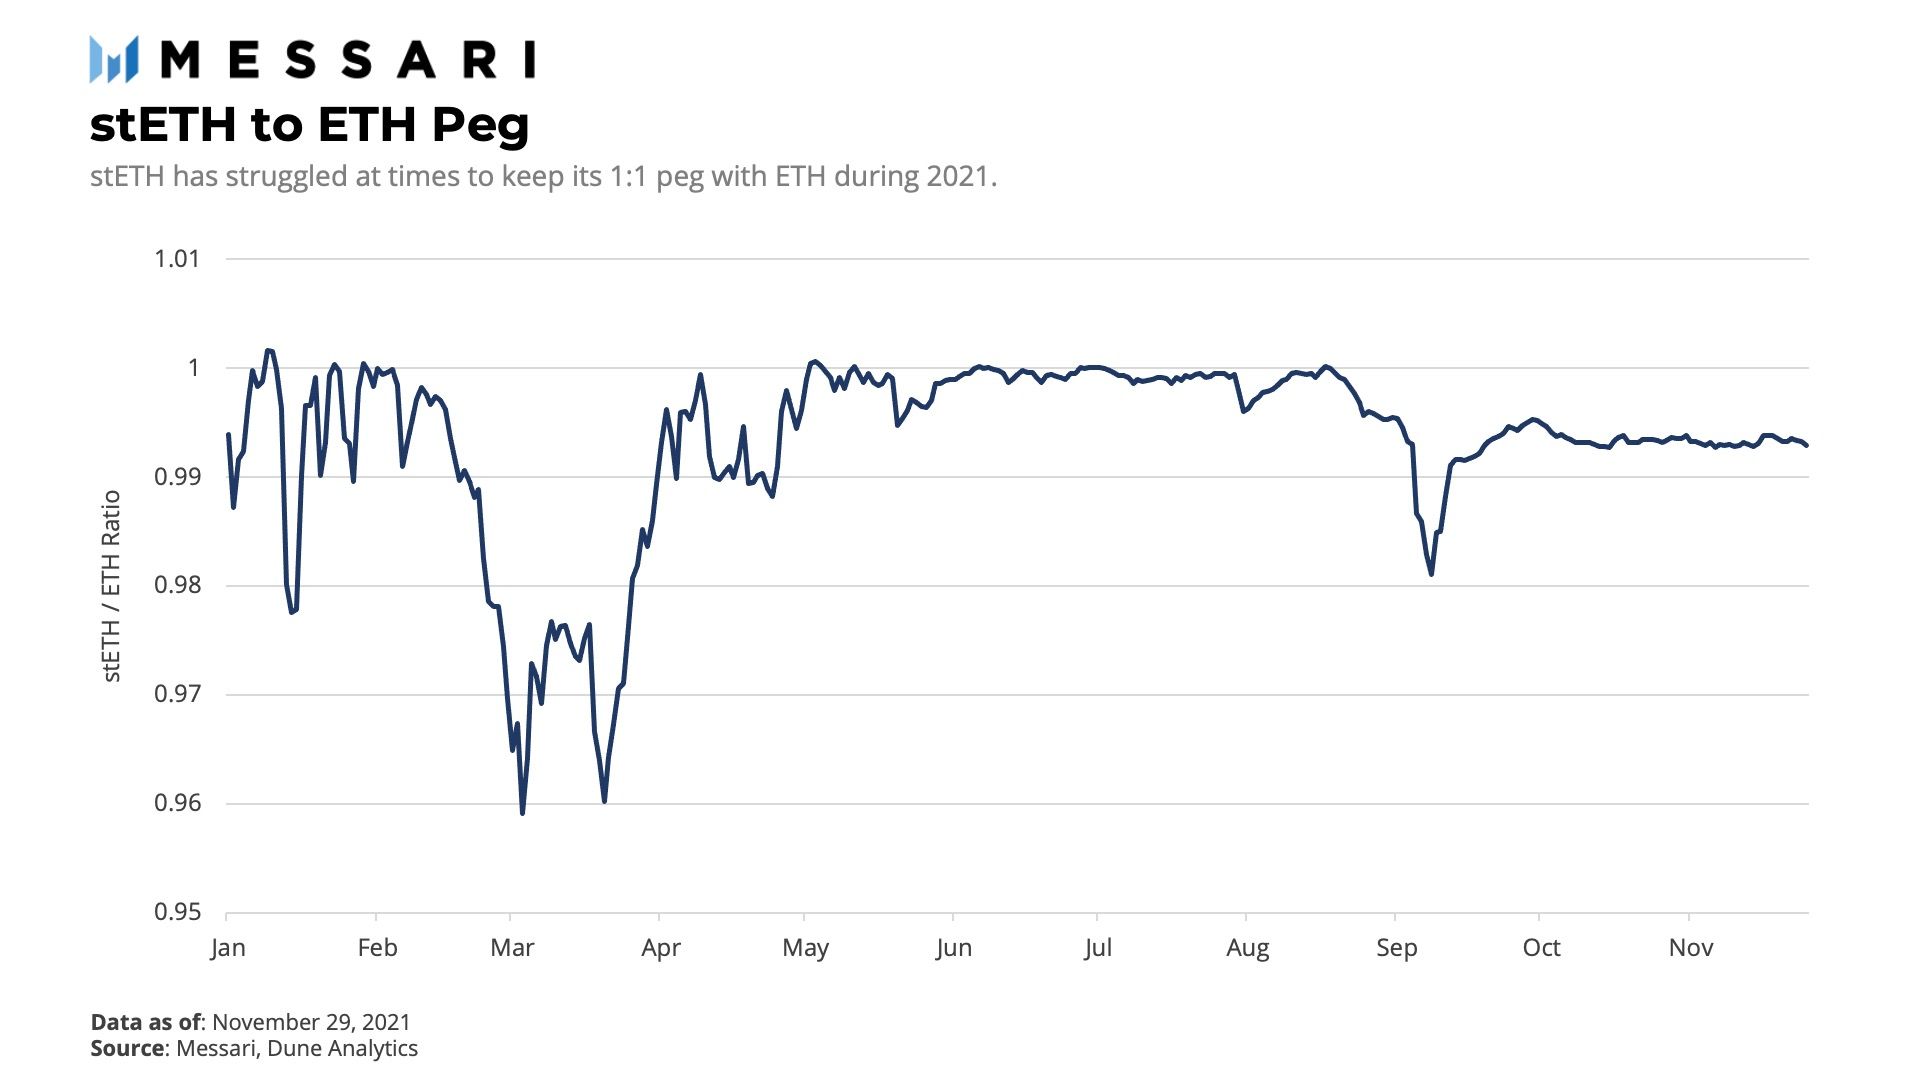
The creation of liquid staking derivatives leads to a set of intertwined risks of its own. First, since these derivatives are synthetic assets, they need to maintain the peg to their underlying staked asset. This is no easy task. Despite being the most reliable liquid staking derivative, Lido’s stETH has at times struggled to maintain its 1:1 peg to ETH. This can be attributed to the fact that stETH can’t be redeemed 1:1 to ETH through Lido until Ethereum completes its transition to PoS. Until then, stETH must rely on decentralized exchanges for actual price discovery.
This makes it riskier to use these types of assets in DeFi where sudden price variations can kickstart a liquidation domino effect. The second risk of dealing with staking derivatives is a matter of liquidity. If the staking derivative can’t be exchanged for any other assets in the market, it doesn’t really serve any purpose other than being a deposit receipt. This is directly related to the peg risk as well - the more a staking derivative deviates from its peg, the more illiquid it becomes.
A final risk regarding the STaaS industry applies only to decentralized staking pools designed to aggregate and distribute stake across various validators. These pools may dampen any counterparty risk associated with choosing a specific validator, but they add smart contract risk since the protocol must route stake across its network of approved validators. Recent DeFi exploits demonstrate that hackers will stop at nothing to find protocol exploits. Only time can tell whether or not these contracts will survive the attempts of bad actors.
Decentralization
No examination of crypto networks would be complete without a discussion on decentralization. A common criticism of the PoW mining industry is that it encourages the centralization of resources and therefore security providers. Any point of centralization in a network’s security system makes it easier to compromise the network. While PoS networks don’t benefit from the same economies of scale as PoW networks, the STaaS industry is a critical variable that will influence the decentralization of PoS networks.
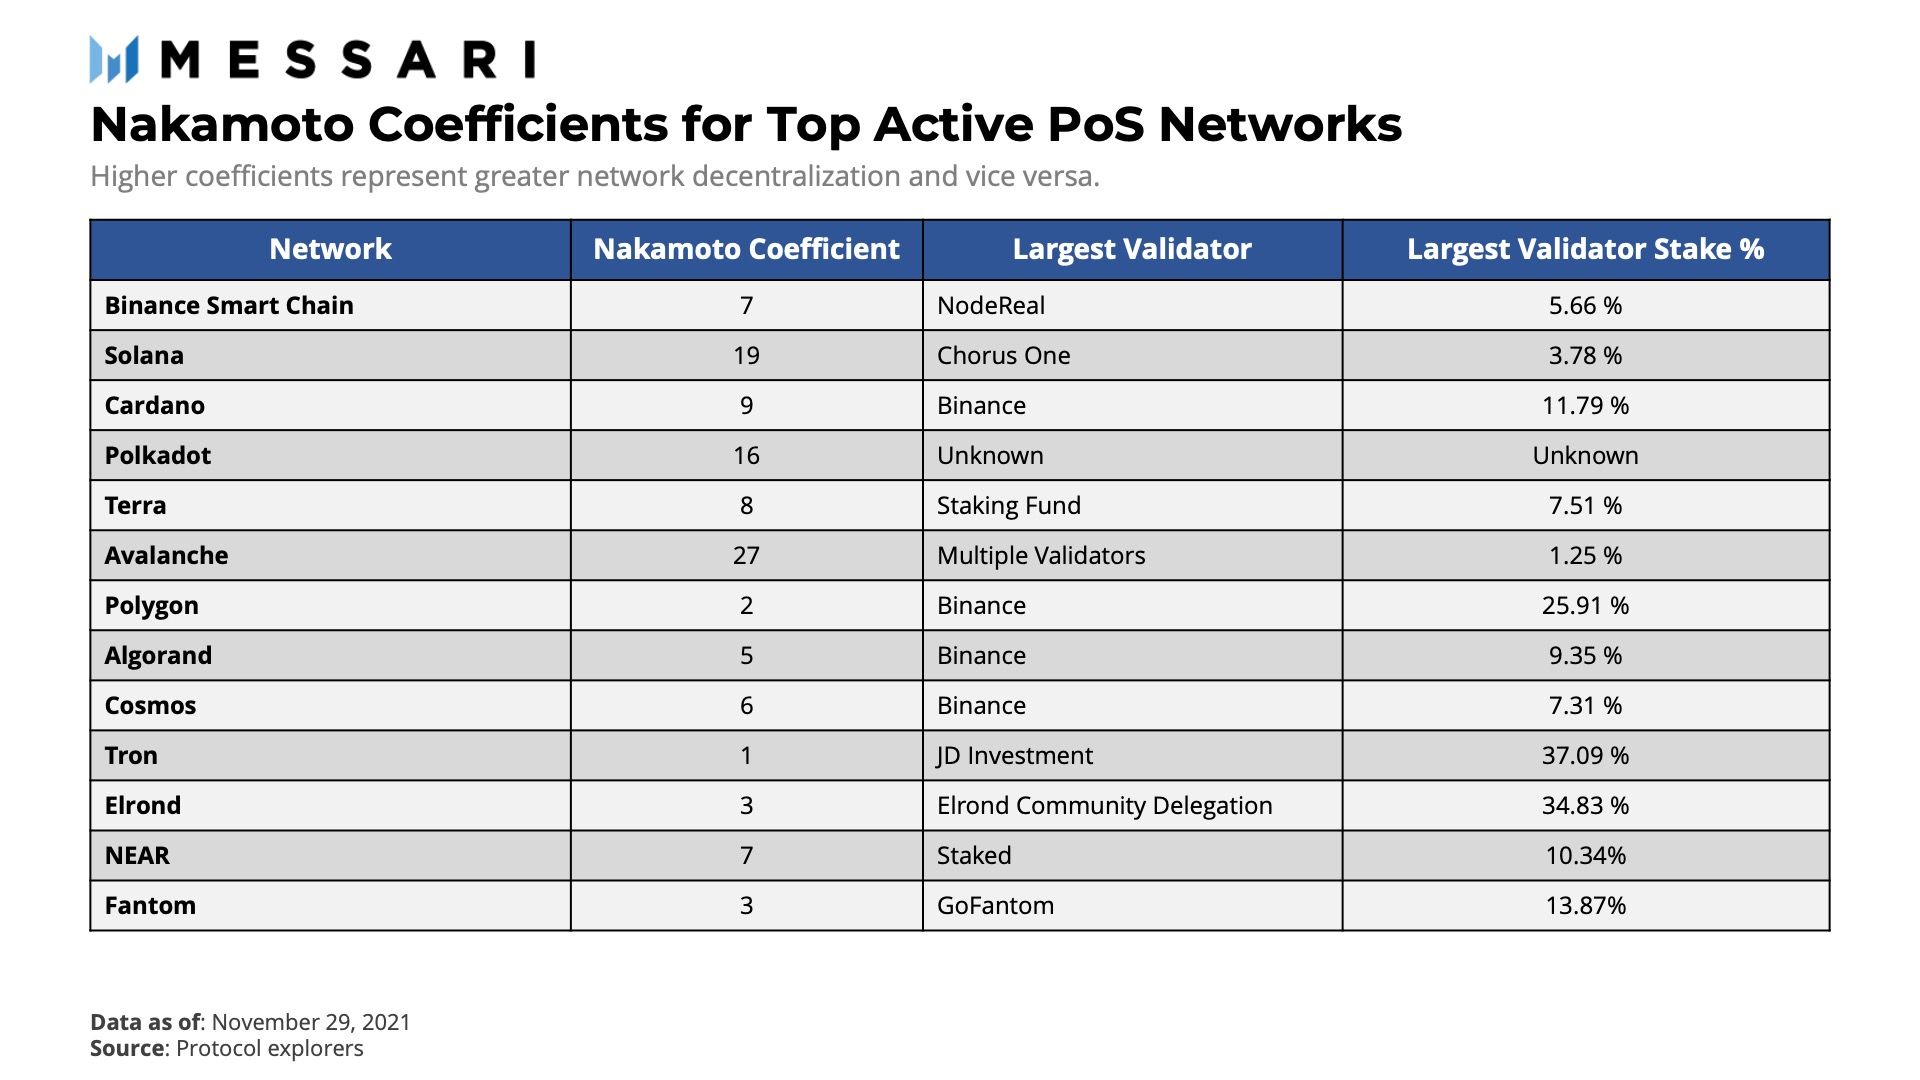
To quantify the decentralization of a blockchain network, Balaji Srinivasan introduced the concept of the Nakamoto coefficient to measure the number of entities a bad actor would need to compromise at least one essential subsystem; a higher Nakamoto coefficient signifies greater decentralization of a network. Given the consensus properties of a PoS network, the minimum threshold for compromising the network is acquiring ⅓ of the network’s stake.
Applying the Nakamoto coefficient to the leading PoS networks paints a varied picture. An attack on one of the larger networks such as Cardano, Solana, and Avalanche would require a highly coordinated approach. Taking over other networks like Tron, Polygon, Elrond, or Fantom would be much more straightforward - compromise the top two or three staking providers and the network is yours. Again, part of this concentrated distribution has to do with the immaturity of these networks; as they mature, we can expect the Nakamoto coefficient to increase slowly.
It will be necessary for the crypto industry to keep large STaaS providers in check to prevent this kind of centralization. Delegating to smaller validators and encouraging STaaS providers to maximize the number of validators under their management are two ways the community can help these PoS networks to remain as decentralized as possible.
Projections for the STaaS Industry
If the crypto market has made one thing clear during its current bull run, it’s that PoS is replacing PoW as the dominant consensus mechanism for public blockchain networks. Bitcoin will continue to keep PoW relevant, but any general purpose smart contract network will require an alternative consensus engine to support mass adoption. The early STaaS providers that recognized this opportunity have already positioned themselves for continued success as more investors seek a way to earn a reliable yield on their PoS assets.
We’ve already discussed the emerging product-market fit of the STaaS industry in great detail. But what does the future hold?
It can be argued that staking is the closest thing we can get to a blockchain network’s “risk-free rate”. In traditional economic systems, the risk-free rate is represented by the rate of return for a government’s bonds. The government is the underpinning of a nation’s economic system. Similarly, a blockchain’s security is the underpinning of a blockchain’s economic system. The maturation of the crypto economy should lure more long-term investors into seeking out this native form of yield for their PoS assets. As they do, we can expect to see continued growth of the STaaS industry.
Within the STaaS industry itself, liquid staking solutions stand to benefit the most from this continued growth. We’ve already begun to see the first large custodial providers pick up on this trend. For example, Binance offers a liquid BETH derivative to offset the opportunity cost associated with the indefinite Eth2 lockup. This trend should continue as liquid staking pools grow their network effects across various chains and staking providers.
We can expect to see STaaS commission rates exhibit a similar pattern to consumer banking fees over the last two decades. Increased competition from FinTechs forced banks to offer lower and lower fees to retain their customers. Similarly, the growing number of STaaS solutions will put downward pressure on the commissions charged on customers’ staking rewards. One variable that may keep these rates higher in the short term are high switching costs that can be attributed to the immaturity of liquid staking solutions. If a new competitor enters the market offering lower commissions, STaaS customers that don’t use a liquid staking solution will need to wait out their lockup period in order to switch to the new provider. By the time they’re able to switch, another new provider could be offering even lower fees, creating a race to the bottom for fees.
Finally, given the simplicity of the industry’s business model, STaaS providers will likely compete primarily on a brand and reputation basis as we see with consumer banking today. The actual difference in services offered by Wells Fargo and Chase Bank is minimal. The main way these banks win customers is through marketing channels and offering a simplified user experience.
Similarly, STaaS providers that boast the greatest safety, risk management, and reliable liquid staking derivatives will likely amass the most customers in the long term. We can already see this thesis playing out with Lido’s cross-chain growth.
As always, it’s important to remember how early we are. A new breakthrough consensus mechanism could be created tomorrow and make PoS irrelevant. However, given the years of research that has gone into consensus designs, this is highly unlikely to happen anytime soon. In the meantime, as PoS continues its ascent to mass adoption, the outlook for the STaaS industry remains in “up only” mode.
Disclaimer: On Feb. 16, 2023, the SEC stated that LUNA and UST are "securities". A couple notes: (1) Messari does not provide financial or trading advice - our services are for informational purposes only; and (2) Messari's services are impersonal - do your own due diligence. Please refer to our Terms of Use for more info.
On March 9, 2023, the State of New York alleged that LUNA and UST are "securities". A couple notes: (1) Messari does not provide financial or trading advice - our services are for informational purposes only; and (2) Messari's services are impersonal - do your own due diligence. Please refer to our Terms of Use for more info.
On June 5, 2023, the U.S. Securities & Exchange Commission stated that ATOM is a "crypto asset security." Note: (1) Messari does not provide financial or trading advice - our services are for informational purposes only; and (2) Messari's services are impersonal - do your own due diligence. Please refer to our Terms of Use for more info.
This report was commissioned by Blockdaemon. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.