After a weekend that saw Coronavirus cases explode in Italy, Iran, and South Korea, markets worldwide were sent into chaos as investors began to come to terms with the potential economic impacts of a global pandemic.
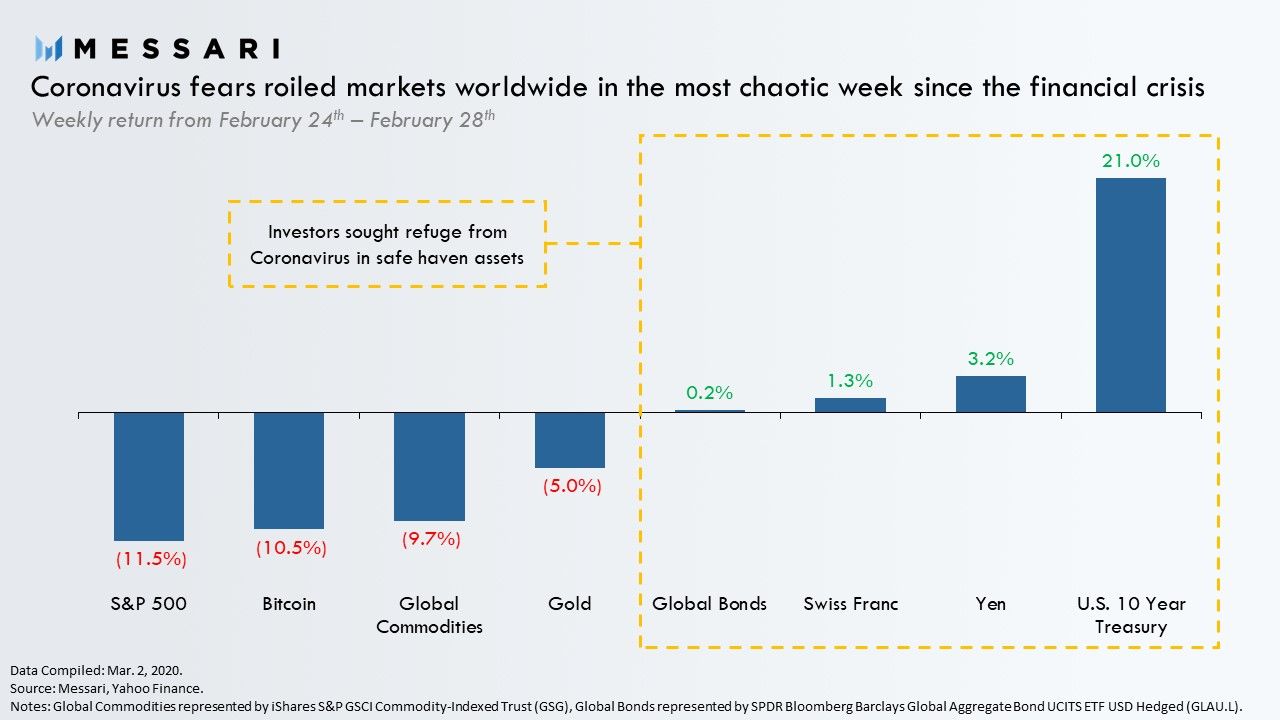
Stock markets worldwide experienced their worst week since the global financial crisis in 2008. United States treasury bonds rallied hard, with yields plummeting to their lowest point in history. Traditional safe haven currencies such as the Japanese Yen and Swiss Franc also caught bids as investors looked to protect themselves from the turmoil, liquidating nearly everything else in the process.
Bitcoin was not immune to the action, falling more than 10% on the week alongside risk-on assets and even gold. However, while bitcoin did fall alongside risk-on assets last week, Bitcoin's case as a safe haven asset is not invalidated.
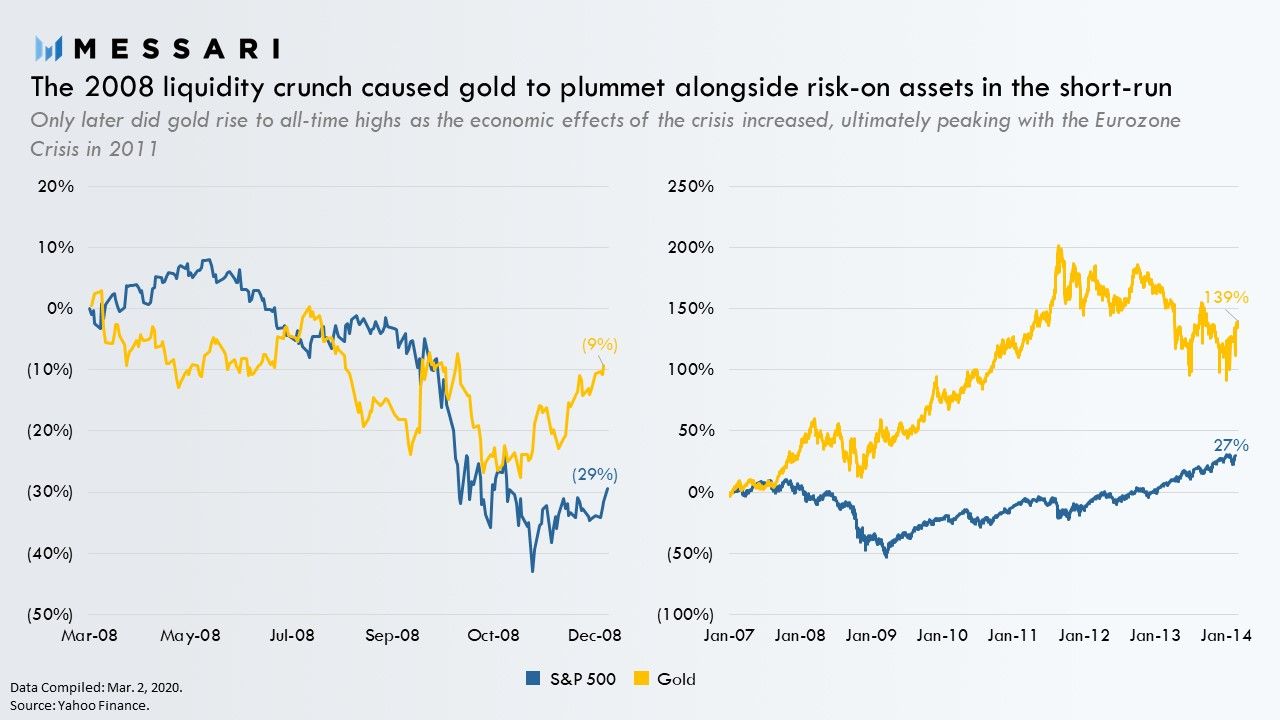
Bitcoin is not a hedge against a recession. Similar to gold which is also held for speculative purposes in the short-run, liquidity crunches like we experienced last week can cause investors to sell bitcoin in order to meet the liquidity constraints of their other portfolio holdings. Bitcoin should not be expected to reliably hold value in times of severe market stress, and it’s performance last week should not come as a surprise. Gold did exactly this during the 2008 financial crisis.
Instead, Bitcoin is a hedge against fiat currency. What Bitcoin provides protection against is not a slowdown in the economy, but the mismanagement of fiat monetary systems. What is a better dynamic to track is not how Bitcoin performs as markets sink due to Coronavirus fears, but how Bitcoin performs in response to central bank stimulus to mitigate the economic impacts of the virus.
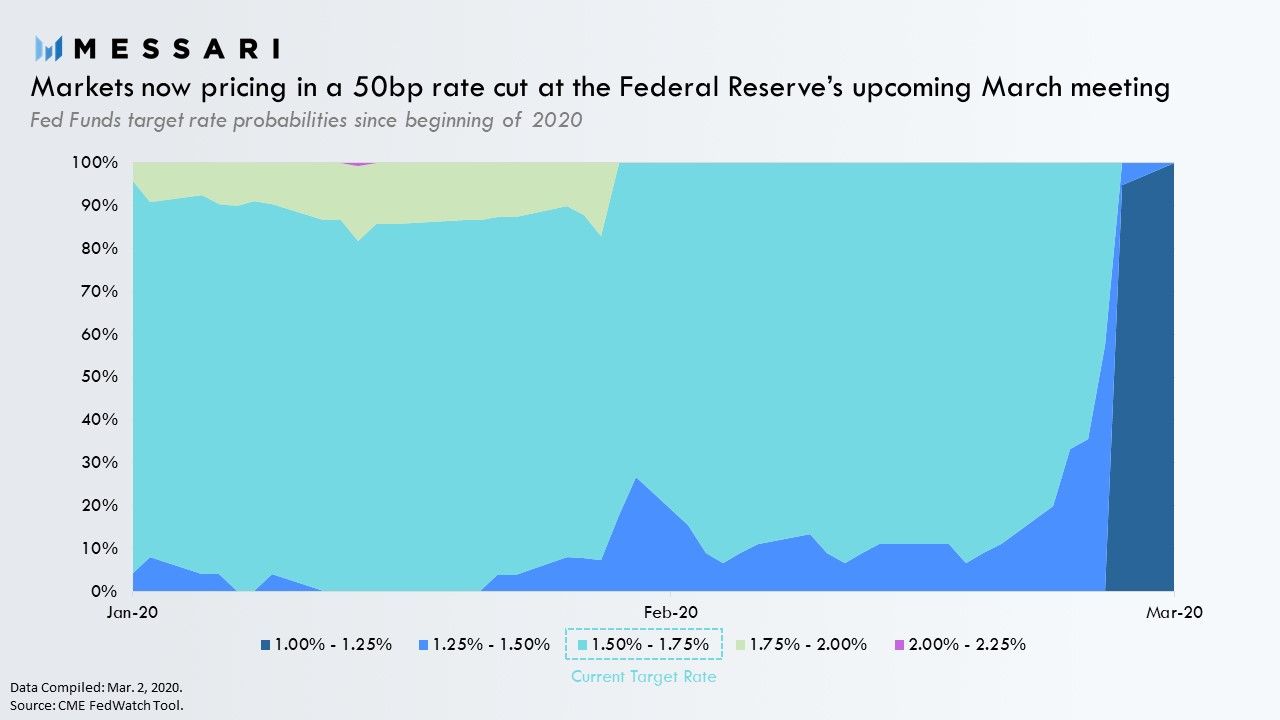
While Bitcoin has failed to respond to central bank stimulus so far, upcoming central bank stimulus could prove much different. In response to the Coronavirus, G7 central banks appear ready to take first coordinated action since 2011. Despite many economists believing that the potential economic impacts of the virus cannot be relieved through monetary policy, markets are now expecting the Federal Reserve to cut rates 50 basis points at their upcoming March 18th meeting, the largest since the financial crisis. The rate cut may come even sooner, if the Fed decides to act faster.
Bitcoin was too small and insignificant to realistically respond to big time monetary events in the past such as QE3 in 2012. At the time of QE3 Bitcoin had only been trading for a year and was just barely over $10 per coin.
At a $160 billion market capitalization, it may still prove too small to be a real option for investors to protect themselves. But, perhaps this time is different. As opposed to previous monetary stimulus, upcoming actions could be larger and more reactionary than they have been since QE3. The institutional infrastructure is here now and Bitcoin may be ready.
All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Nothing contained in this report is a recommendation or suggestion, directly or indirectly, to buy, sell, make, or hold any investment, loan, commodity, or security, or to undertake any investment or trading strategy with respect to any investment, loan, commodity, security, or any issuer. This report should not be construed as an offer to sell or the solicitation of an offer to buy any security or commodity. Messari does not guarantee the sequence, accuracy, completeness, or timeliness of any information provided in this report. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.