Vertex LBA: What to Expect

The genesis supply of VRTX will include 100M tokens earned by traders over the past 7 months based on fees paid to the protocol, 50M VRTX for the protocol treasury, and 10M for the ecosystem development fund. This represents 16% of the 1B total VRTX token supply, with a projected annualized inflation rate north of 100% over the first year. To establish a long term thesis, we recommend our previous report which covered Vertex in depth, and to read the protocol’s updated tokenomics documentation.
For the short term, however, we believe that the fair VRTX price can be deduced by projecting the amount of VRTX and USDC.e that will be deposited in the LBA, and taking the remaining supply and estimating a staking yield based on historical fee revenue. The 60M tokens allocated to the ecosystem development fund and protocol treasury will be excluded in the staking yield calculations, considering the unlikeliness of these tokens being spent or staked over the coming weeks.
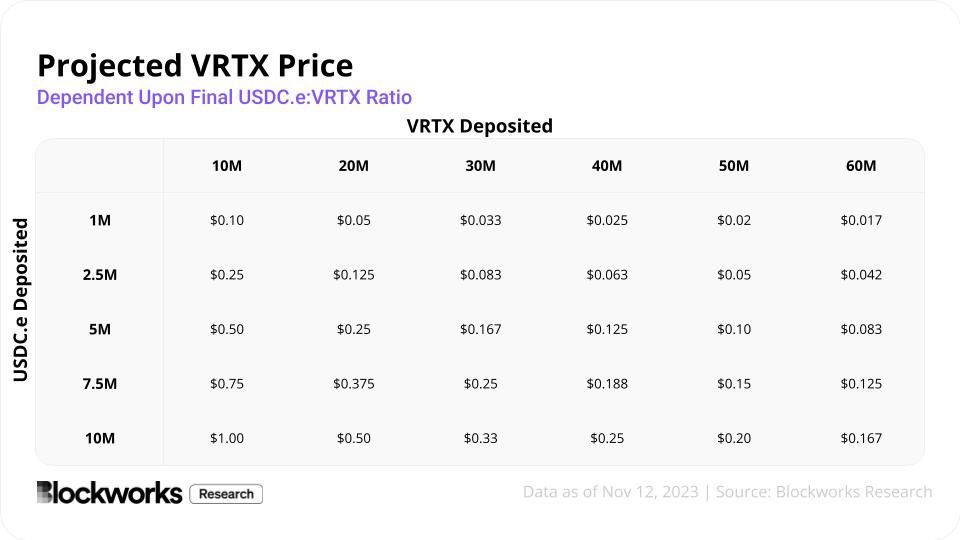
The table above lays out potential VRTX prices, depending on the amount of USDC.e and VRTX that get deposited. There is ~$17.3M USDC.e deposited into Vertex's embedded money market as of this writing, and 100M VRTX tokens that can be deposited. We believe the most likely outcome will fall near the middle of the above table, with $5M of USDC.e deposited and 30M VRTX. Many early Vertex traders may dump the VRTX earned in the initial token phase as soon as the liquidity pool goes live and VRTX becomes fully transferable on the 20th. It is worth noting that LBA depositors will have a 120 day lock up period. Therefore, we expect less than half of the VRTX circulating supply to be deposited, which lands the VRTX market cap and FDV at $26.8M and $167M respectively with a spot price of $0.167. However, day 1 of the LBA is underway and the market is pricing VRTX at ~$0.68 as of this writing. We expect the projected APR and token price to vary substantially over the coming week.
What is interesting about this token is the minimal circulating supply post-TGE and the ability to stake for a share of protocol revenue (paid out in USDC.e). Between the LBA locking mechanism and a 14 day unbonding period for stakers, a vast majority of the supply prior to the end of Epoch 8 in early December will likely be locked. Additionally, the ARB incentives from the STIP in combination with Vertex’s ongoing Trade and Earn program are likely to boost volume and protocol revenue over the near term, and thus increase the VRTX staking yield.
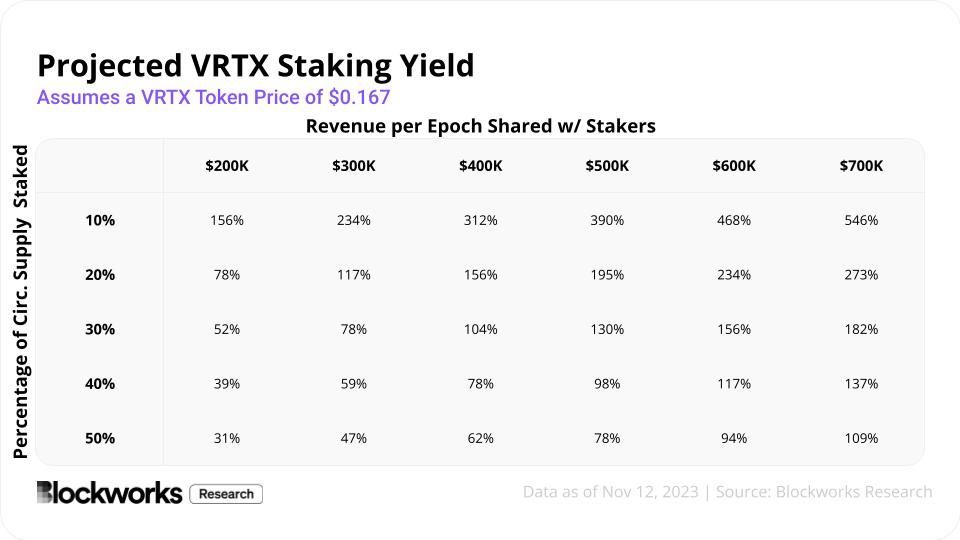
Vertex’s protocol revenue over the past 30 days was ~$740K after market maker rebates. Given the aforementioned ARB and VRTX incentives, as well as the ongoing collaboration with Elixir, we expect fees and volume to be higher than they historically have been. Additionally, we expect anywhere from 20-40% of VRTX circulating supply to be locked in the LBA, so there isn’t a ton of supply that can be staked to earn protocol revenue (which should boost everyone else’s share of the yield). The following table projects the staking yield based upon the amount of USDC.e paid out to stakers each Epoch and the percentage of the 100M VRTX supply that is staked assuming a 0.167 VRTX spot price.

Sam leads coverage on Ethereum, L2s, Aave, Compound, as well as NFTs and gaming. Previously worked on a hedge desk at UGC.