At the heart of Fluid is its Liquidity Layer, which unifies liquidity across the DeFi protocols built on it, improving composability and capital efficiency. Currently, Fluid has three in-house protocols that use its Liquidity Layer: a lending, a vault, and a DEX protocol.
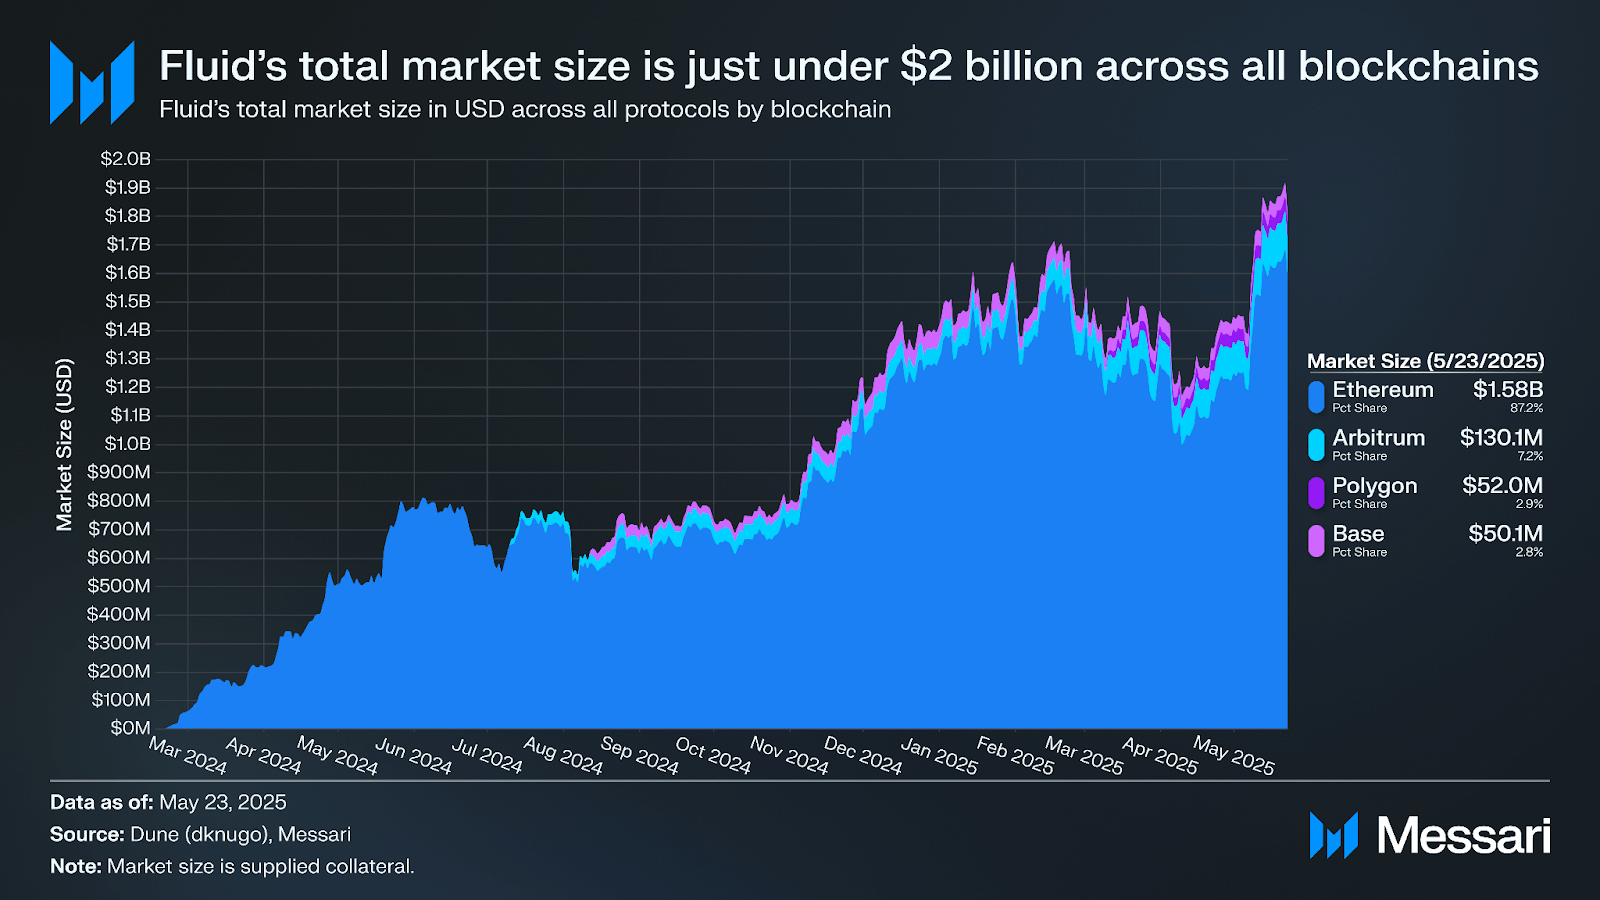
Fluid’s total market size (deposited collateral) has grown to just under $2 billion. Ethereum has the largest market size, at $1.58 billion, followed by Arbitrum at $130.1 million, Polygon at $52.0 million, and Base at $50.1 million.
Fluid’s Vault protocol uses range-based positions to unlock a 100x improvement in liquidations. This improvement enables Fluid to safely offer LTV’s up to 95% while reducing liquidation penalties to as low as 0.1%.
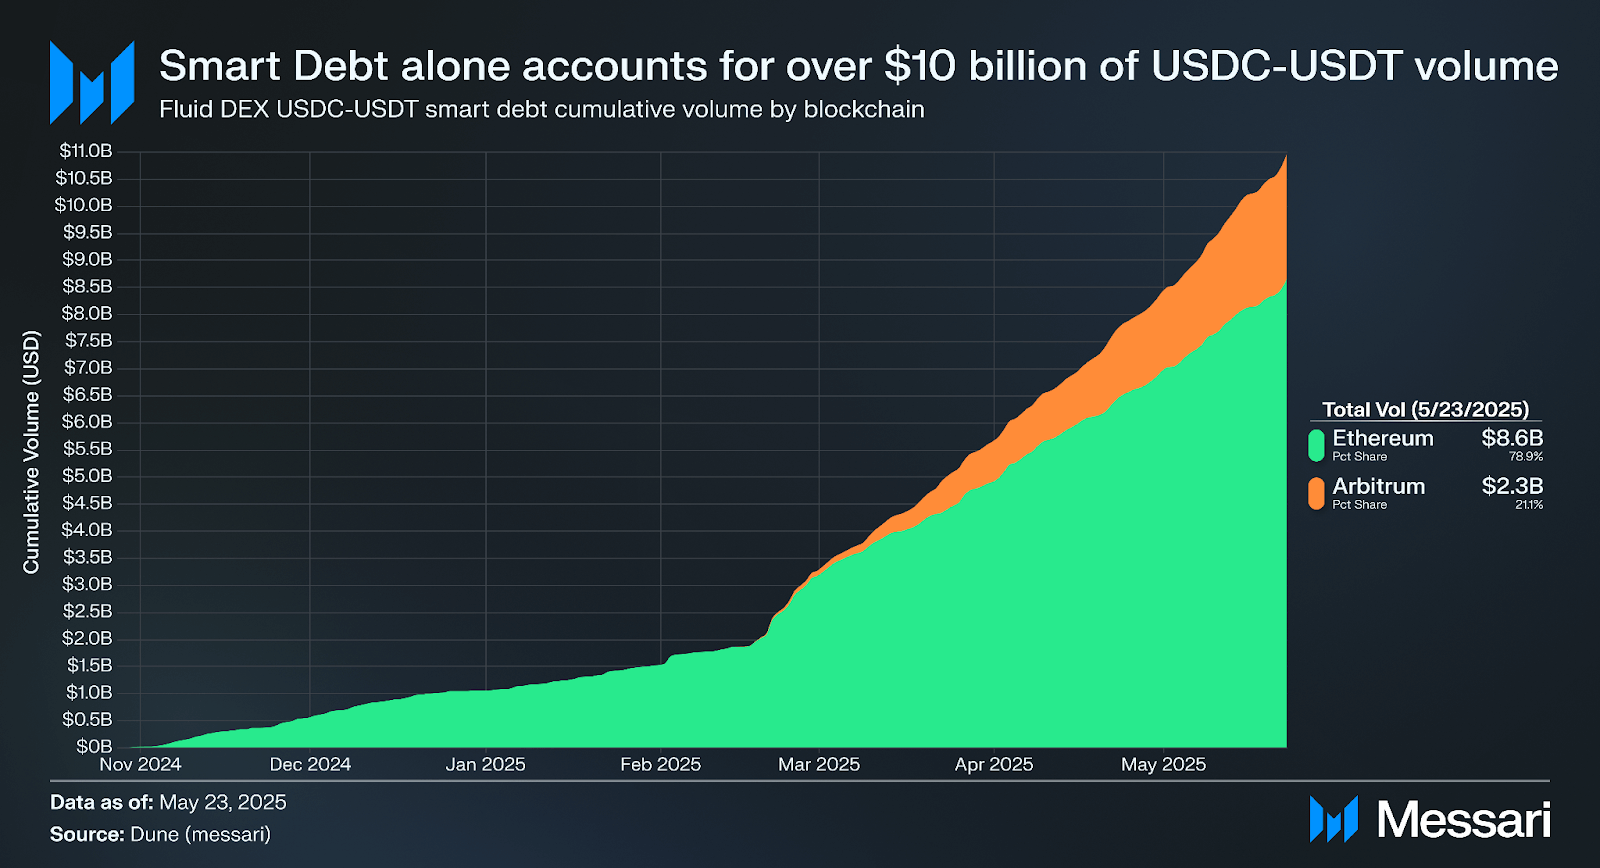
Fluid introduces Smart Collateral and Smart Debt, enabling liquidity provisions to be used as collateral and debt. Smart Debt alone has facilitated over $10 billion of USDC-USDT volume across Ethereum and Arbitrum, with all liquidity for the pair coming from borrower liabilities.
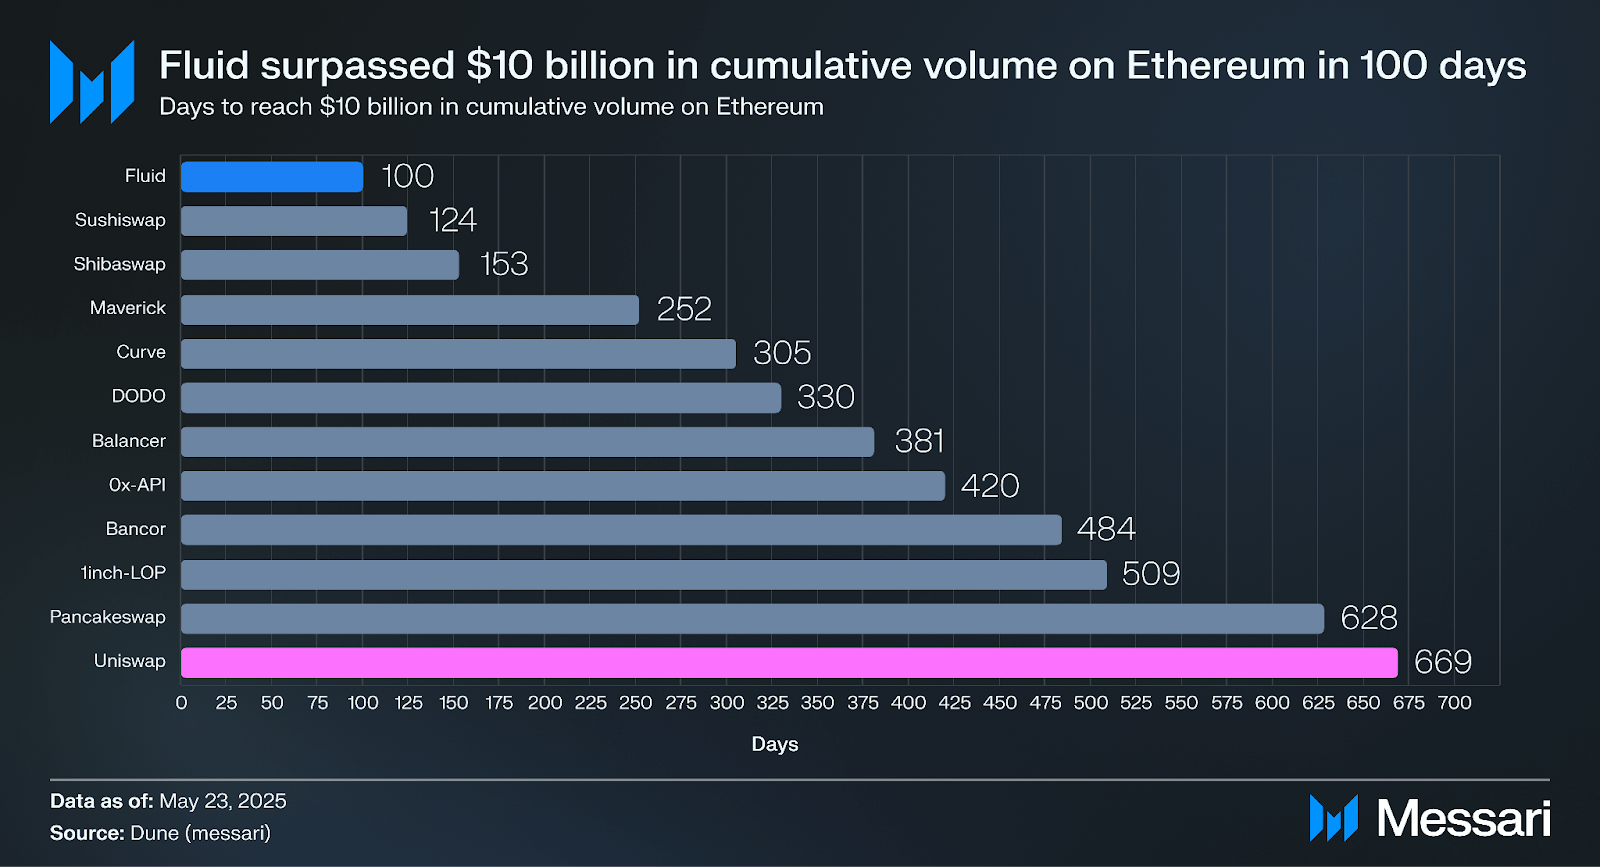
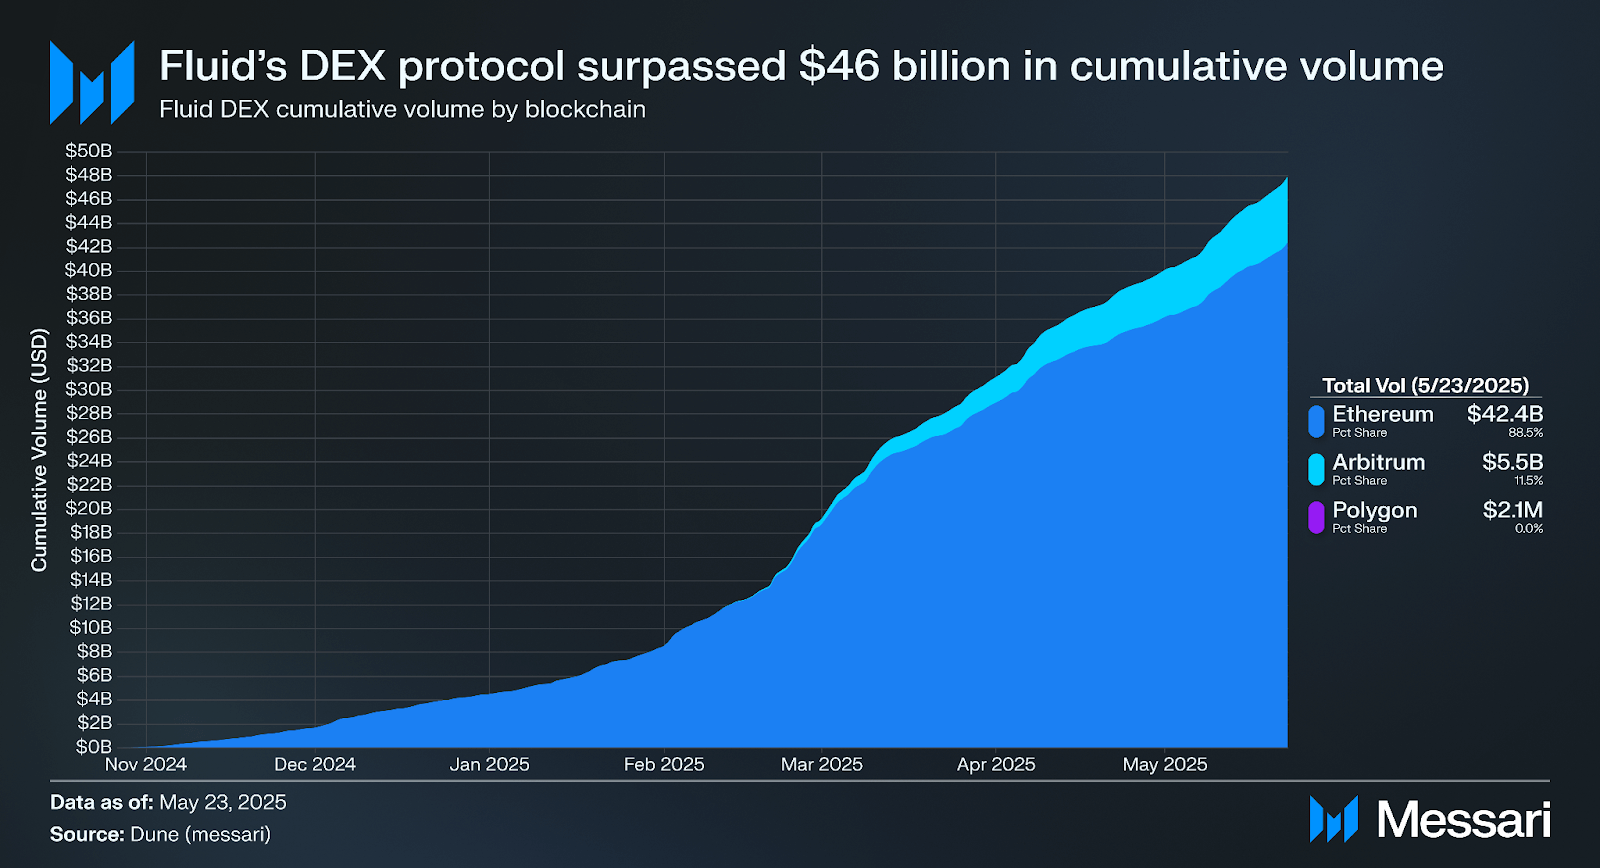
Fluid’s DEX protocol has facilitated over $46 billion of volume, relying solely on borrowers' collateral and debt. To date, the DEX is the fastest on Ethereum to surpass the milestones of $5 billion, $10 billion, and $20 billion in cumulative volume, doing so in 72, 100, and 127 days, respectively.
Introduction
Liquidity across blockchains and protocols is increasingly fragmented, causing inefficiencies and limiting interoperability. To address this, protocols focus on improving composability (how well they integrate with others), increasing capital efficiency (doing more with less), or amassing more liquidity (easier said than done). The latest DeFi innovation aiming to solve this challenge is Fluid.
Fluid’s Liquidity Layer unifies liquidity across the DeFi protocols built on it, improving composability and capital efficiency. Currently, Fluid has three in-house protocols that use its Liquidity Layer: a lending protocol, a vault protocol, and a decentralized exchange (DEX) protocol.
The lending protocol allows users to lend assets to the Liquidity Layer in exchange for yield, while the vault protocol enables the creation of overcollateralized debt positions through asset locking and borrowing. The DEX protocol facilitates asset swaps within the Liquidity Layer and introduces Smart Collateral and Smart Debt. These features enable collateral and debt from the Vault protocol to simultaneously be liquidity provisions for the DEX protocol, transforming idle assets into productive ones and significantly boosting Fluid’s capital efficiency.
To date, Fluid’s Liquidity Layer, lending protocol, and vault protocol have been deployed on Ethereum, Arbitrum, Base, and Polygon, while Fluid’s DEX protocol has been deployed on Ethereum, Arbitrum, and Polygon. Fluid plans to expand to Solana by partnering with Jupiter to launch under Jupiter’s branding as Jupiter Lend (announced May 22, 2025). The Fluid protocol is governed by the Fluid DAO, which is controlled by FLUID tokenholders.
Background
Fluid rebranded from Instadapp in December 2024 after the early success of its DEX protocol, which went live at the end of October 2024. As part of this rebrand, the project’s token ticker changed from INST to FLUID.
Instadapp was founded in 2018 at the ETHIndia Hackathon by brothers Samyak Jain and Sowmay Jain to make DeFi more efficient. After winning prizes at the hackathon, the project released its first product in August 2019, a bridge between MakerDAO and Compound, which allowed capital to move between them to get the best lending and borrowing rates. In October 2019, Instadapp raised $2.4 million in a seed round from Pantera Capital, Coinbase Ventures, Naval Ravikant, and Balaji Srinivasan, among others.
Over time, Instadapp evolved into a DeFi middleware solution, increasing composability in DeFi and simplifying its user experience. This started with their DeFi Smart Wallets launched in 2019, which gave way to their DeFi Smart Accounts (DSAs) launched in March 2020. By February 2021, DSAs reached $1 billion in TVL and had facilitated over $1 billion worth of swaps. This success led to the launch of the Instadapp protocol in April 2021, providing a platform to interact with all of DeFi. During this period of time, Instadapp simplified many common DeFi user actions like leveraging, looping, swapping collateral, and shifting positions between protocols. Additionally, functionality was added to migrate positions from Aave V1 to Aave V2 and V3, as well as for MakerDAO’s transition from single-collateral DAI to multi-collateral DAI. Collectively, these products were released as part of the protocol’s efforts to make all of DeFi composable and asset movement as simple as a single click.
Instadapp’s transition to a DeFi middleware product made the team acutely aware of the inefficiencies that could only be addressed at the protocol level. However, as an outside third party, the team could not make the necessary changes to the underlying protocols Instadapp had integrated. As such, the team set out to build its own protocol.
Inspired by the March 2021 Uniswap V3 announcement, the team realized that math and algorithms could be used to innovate on an existing protocol, in this case, an automated market maker (AMM). The team took a similar approach to improving onchain money markets (lending and borrowing protocols), spending two years researching and developing Fluid’s core concepts and technology. Their goal was to create an evolving DeFi protocol that is not just a money market—it could be anything.
The team introduced Fluid on Oct. 10, 2023, and launched the DEX protocol a little over a year later on Oct. 29, 2024.
Technology
Liquidity Layer
At the heart of Fluid is its Liquidity Layer, which unifies liquidity across the DeFi protocols built on it, improving composability and capital efficiency. Currently, Fluid has three in-house protocols that use its Liquidity Layer: a lending protocol, a vault protocol, and a DEX protocol.
Protocols integrated with the Liquidity Layer interact through four functions: deposit, withdrawal, borrow, and payback. Assets deposited into the Liquidity Layer earn interest (supply APR) while they are available for borrowing, and borrowers pay interest (borrow APR) when they repay their loans. To mitigate risks from new protocols, Fluid’s Liquidity Layer uses automated ceilings that dynamically limit the amount of liquidity that can be withdrawn by a protocol per block. New protocols begin with lower limits that gradually increase, limiting their initial risk to the Liquidity Layer. This safeguards the Liquidity Layer from sudden collateral or debt changes caused by exploits or manipulation, allowing governance time to intervene.
To date, building on top of Fluid’s Liquidity Layer is not permissionless. Governance controls what assets are supported by the Liquidity Layer, what protocols are built on top of it, and the parameters of these protocols. This includes which tokens/token pairs can be deposited and borrowed from each vault, the type of collateral and debt offered by each vault (normal or smart), and token pairs for which liquidity is provided to the DEX protocol.
Lending Protocol
Fluid’s Lending protocol enables users to earn variable yield on assets that are deposited into the Liquidity Layer. One of the main advantages of Fluid’s Lending protocol is that users are loaning to a unified liquidity layer instead of a single protocol. Therefore, user deposits can be used by any protocol built on top of the Liquidity Layer. This means that users do not need to actively manage their positions to get access to new yield opportunities or migrate their positions to take advantage of a new protocol. For example, when Fluid’s DEX V2 protocol is integrated into the Liquidity Layer later this year, users deposited into the Lending protocol will not need to make any changes for their deposits to be used by DEX V2.
The Lending protocol uses the ERC-4626 standard, enabling protocols outside of the Fluid stack to easily integrate the Lending protocol. The ERC-4626 standard tokenizes vaults representing shares of the vault in an ERC-20 compliant standard. Fluid’s adoption of this standard in the Lending Protocol increases the protocol’s composability with other DeFi protocols. For example, you could deposit USDC into the Lending Protocol and use the receipt token (fUSDC) as collateral to mint Pendle’sPT and YT derivatives of fUSDC, splitting it into two distinct assets (PT-fUSDC and YT-fUSDC). A user may do this if they want to speculate on the future yield of USDC deposited into the Liquidity Layer.
Vault Protocol
Fluid’s Vault protocol enables users to deposit collateral and borrow against it.
All onchain overcollateralized borrowing protocols (money markets) like Fluid’s Vault protocol function the same at their core. They let users deposit specific collateral and withdraw specific debt, up to a limit. The limit or Loan-to-Value (LTV) specifies the maximum percentage of dollar-denominated debt that can be withdrawn given the dollar-denominated value of collateral. Past this threshold, a borrower’s position may be partially or fully liquidated. Liquidations exist to protect protocols from bad debt, i.e., having the debt of an outstanding loan be more than the value of the collateral backing it. In order to protect against bad debt, onchain overcollateralized borrowing protocols set LTV requirements in accordance with their risk tolerance. Lower LTV requirements give protocols more time to liquidate collateral while it is still more valuable than debt, whereas increasing liquidation efficiency enables protocols to act faster, therefore enabling higher LTV while maintaining the same risk tolerance. Fluid has completely reimagined how liquidations could work in a borrowing protocol, leading to its novel liquidation engine.
Liquidation Engine
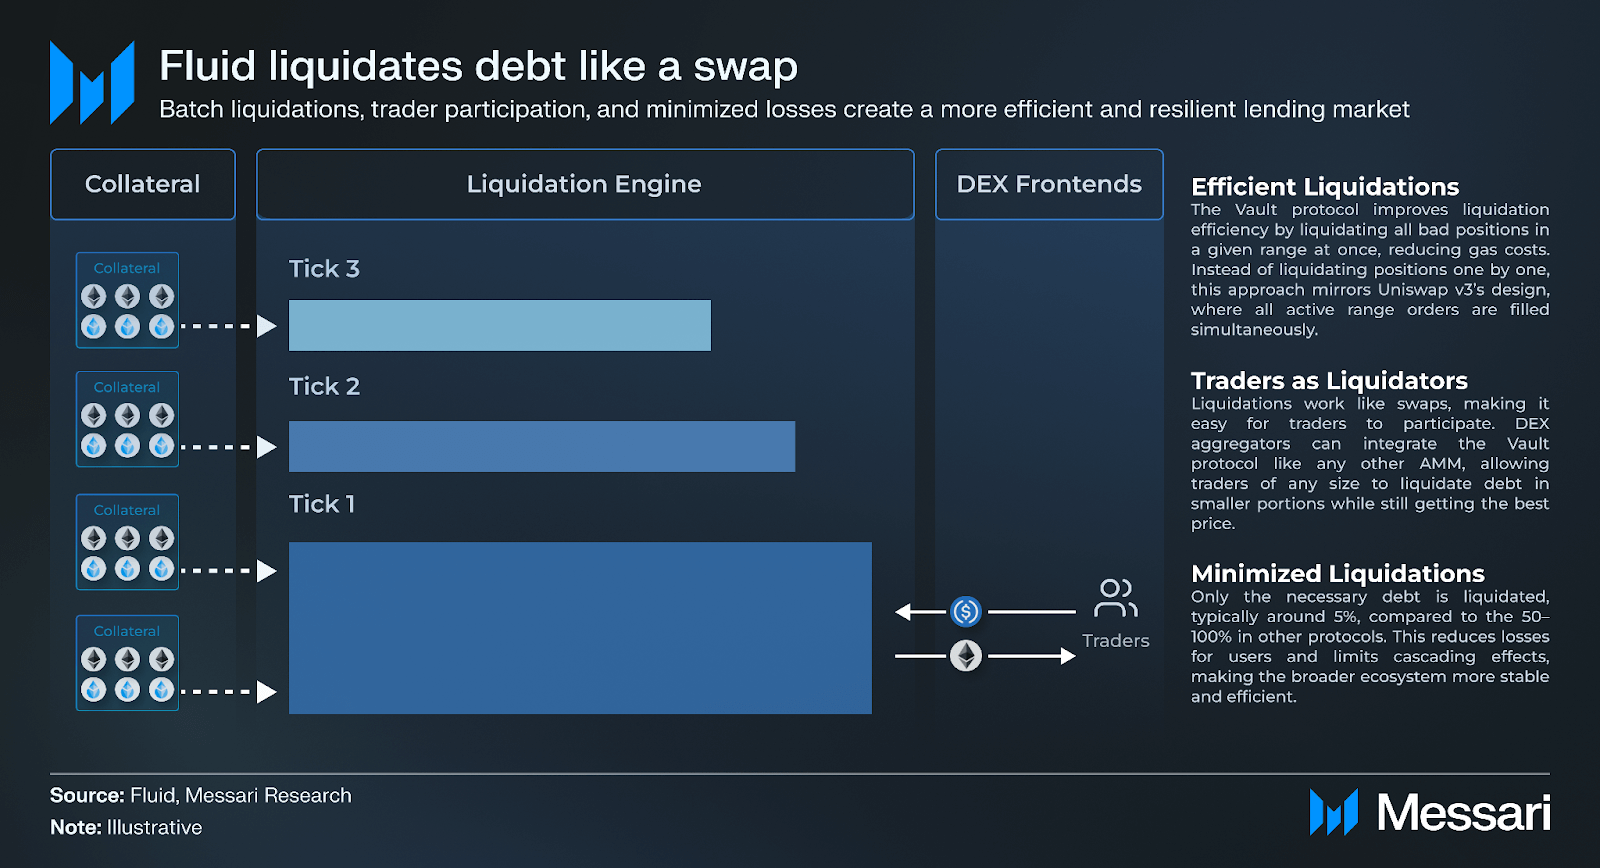
Fluid’s liquidation engine is inspired by the design of Uniswap V3, specifically the way that Uniswap V3 is able to aggregate users’ positions over multiple ranges and facilitate trades through all of them. Fluid builds on this by enabling liquidations over a range of positions, allowing multiple users’ debt positions to be liquidated simultaneously. This method of position liquidation represents a 100x improvement (according to the team) over the traditional liquidation mechanism in DeFi money markets. This is because, traditionally, onchain money markets liquidate positions one-by-one, meaning that to liquidate 100 positions it would take 100 transactions, whereas on Fluid it could be done in a single transaction. Fluid’s range order design makes this possible as it decreases the gas required for position liquidation down to approximately 150,000 gas, which is close to the approximately 120,000 gas required for a Uniswap V3 swap. This enables liquidations to essentially be discounted trades.
As an example, in the ETH-USDC vault, ETH is the collateral, and USDC is the debt. If the price of ETH decreases by 30%, some positions in the vault will likely have their LTVs increase past the acceptable limit for this vault (92% LTV) and move into a range where they need to be partially liquidated. In order to repay the debt, Fluid’s liquidation engine prices a portion of the collateral at a discount to the debt, creating an incentive for any trader to sell USDC back to the Vault in exchange for more ETH than they would get at the market price. Moreover, because of the inherent properties of the Vault’s range-based positions, the Vault protocol is able to offer borrowers additional benefits seldom found elsewhere.
Borrowers can get higher LTVs and pay less liquidation penalties than with other borrowing protocols. Fluid’s LTVs can be as high as 95% for correlated assets, whereas other protocols like Aave V3 top out at 90%. Fluid's liquidation penalties are as low as 0.1%, representing a 50-100x savings compared to other protocols’ penalties of 5-10%. Moreover, Fluid uses soft liquidations to only liquidate the portion of collateral (typically around 5%) needed to bring the position back under the vault’s specific liquidation threshold. Since Fluid does not require that all outstanding liquidations be completed in one transaction, users’ positions may be above the liquidation threshold for multiple blocks. However, if the LTV for a given position continued to increase without any liquidations occurring, it would hit the liquidation max limit, and the entire position would be liquidated. The liquidation max limit can be thought of as a maximum LTV at which point the entire position's collateral becomes redeemable once the position's corresponding debt has been paid. In the case of the aforementioned ETH-USDC vault, the maximum liquidation threshold is 95%, so once the value of the debt reaches 95% of the value of the collateral, all of the position’s collateral becomes redeemable. This gives liquidators a 5% discount on the collateral, which is effectively a 5% risk-free return for liquidators. The liquidator for these positions tends to be a maximum extractable value (MEV) bot that performs all the necessary actions to profit in a single transaction. However, it also incentivizes other sophisticated market participants, such as DEX aggregators, market makers, and solvers, to mitigate the risk of bad debt.
One of the most important components of onchain borrowing protocols is price feeds. Price feeds enable these protocols to accurately determine the LTV of a user’s position by pricing both collateral and debt against an underlying asset, typically U.S. dollars. Because onchain protocols need access to offchain price data for assets traded across venues, blockchain oracles are essential. Fluid’s Vault protocol mitigates price manipulation risk by using a multi-oracle setup for each vault. This setup can include Chainlink oracles, Uniswap time-weighted average price (TWAP), contract-backed pricing (such as wstETH to ETH), and custom rate limits that restrict how much collateral can be withdrawn or debt can be borrowed in a given period. Fluid’s oracle system is further differentiated by its adaptive use of price data depending on the user’s action. For instance, when a user is borrowing, the protocol references the lowest recent moving average price for the asset to minimize risk. For liquidations, it uses the most up-to-date market price or contract backing to avoid unnecessary liquidations.
DEX Protocol
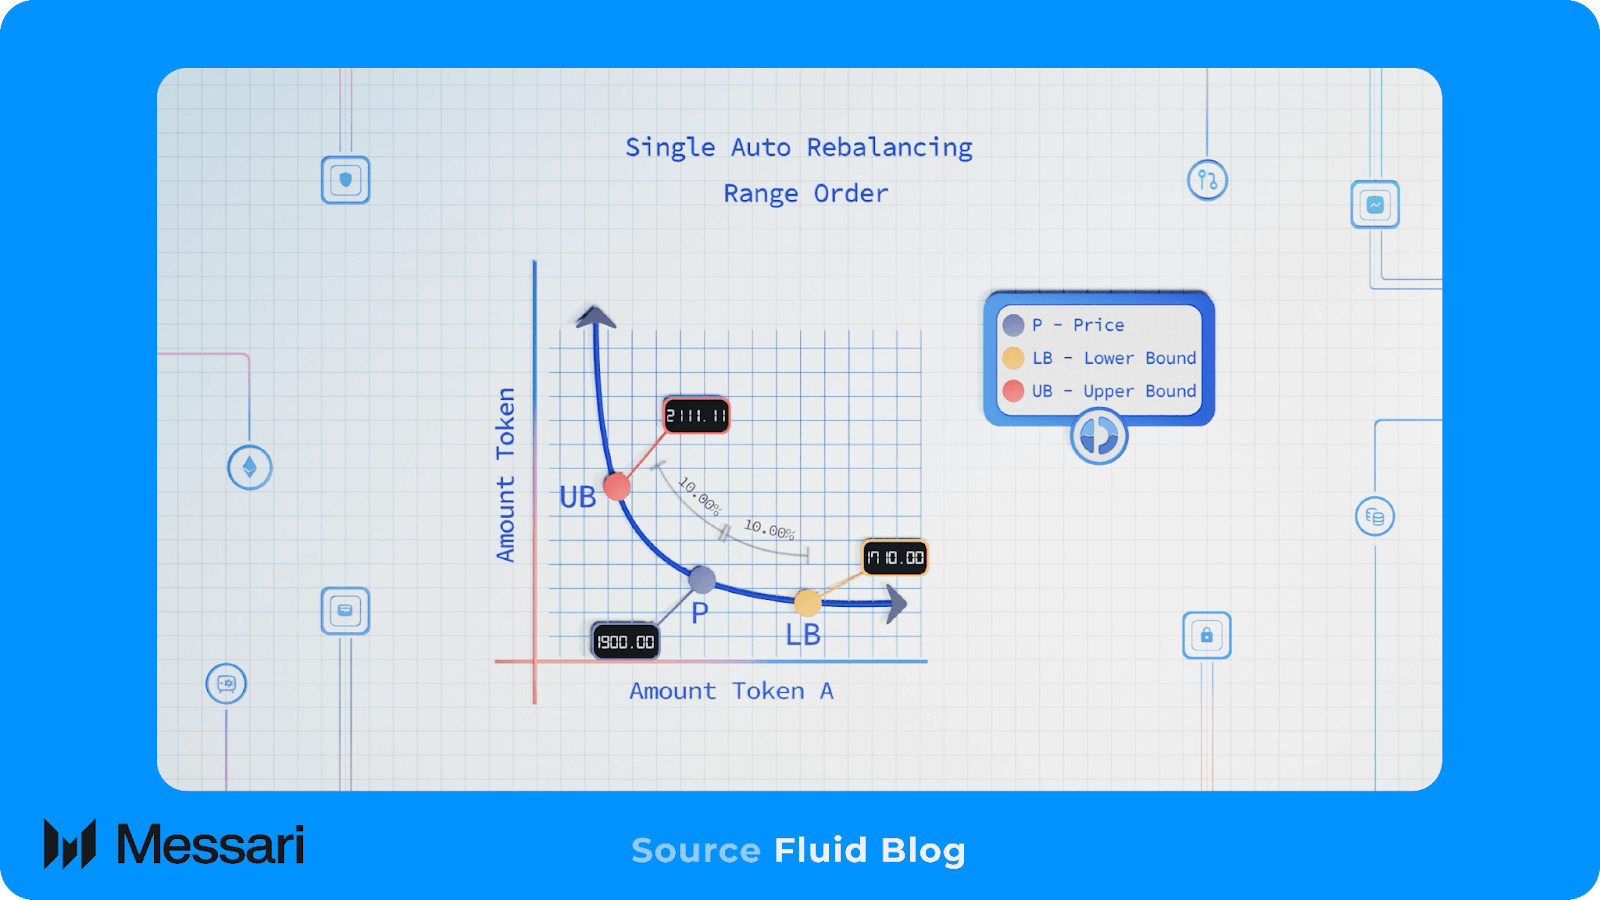
Fluid’s DEX protocol facilitates asset trading through auto-rebalancing single-range order pools. This pool type is a combination of Uniswap V2 and V3. The single range order has an upper and lower price bound that concentrates liquidity within a certain range, similar to Uniswap V3, while the auto-rebalancing adjusts the liquidity range when either the upper or lower price bounds are breached. Fluid governance sets the initial pool conditions, which include whether or not the pool is able to be rebalanced, alongside other conditions. However, the DEX’s pool structure is not the protocol’s biggest novelty. Rather, it is the two primitives it establishes for borrowers: smart collateral and smart debt.
Smart Collateral
Smart Collateral is collateral that is also a liquidity provision on the DEX protocol. Vault protocol users can deposit either one or both assets needed to form the liquidity provision as collateral. Regardless of the initial ratio of deposited assets, Smart Collateral will be shifted to match the current composition of the DEX pair. Like all assets deposited into the Liquidity Layer, Smart Collateral earns yield (supply APR). In addition, Smart Collateral earns trading fees from the DEX, which accrue to the user’s position.
An example of Smart Collateral is Vault 52 on Ethereum, where WBTC and cbBTC can be deposited to borrow USDC. In this example, a user could deposit WBTC, which would be partially swapped for cbBTC to create the liquidity provision. Over time, the user’s portion of collateral that is WBTC and cbBTC shifts due to traders buying and selling into the Fluid DEX WBTC-cbBTC pair, changing the balance of assets. Once the user has repaid their borrowed USDC, they can withdraw their collateral as WBTC, cbBTC, or a combination of the two assets.
Smart Debt
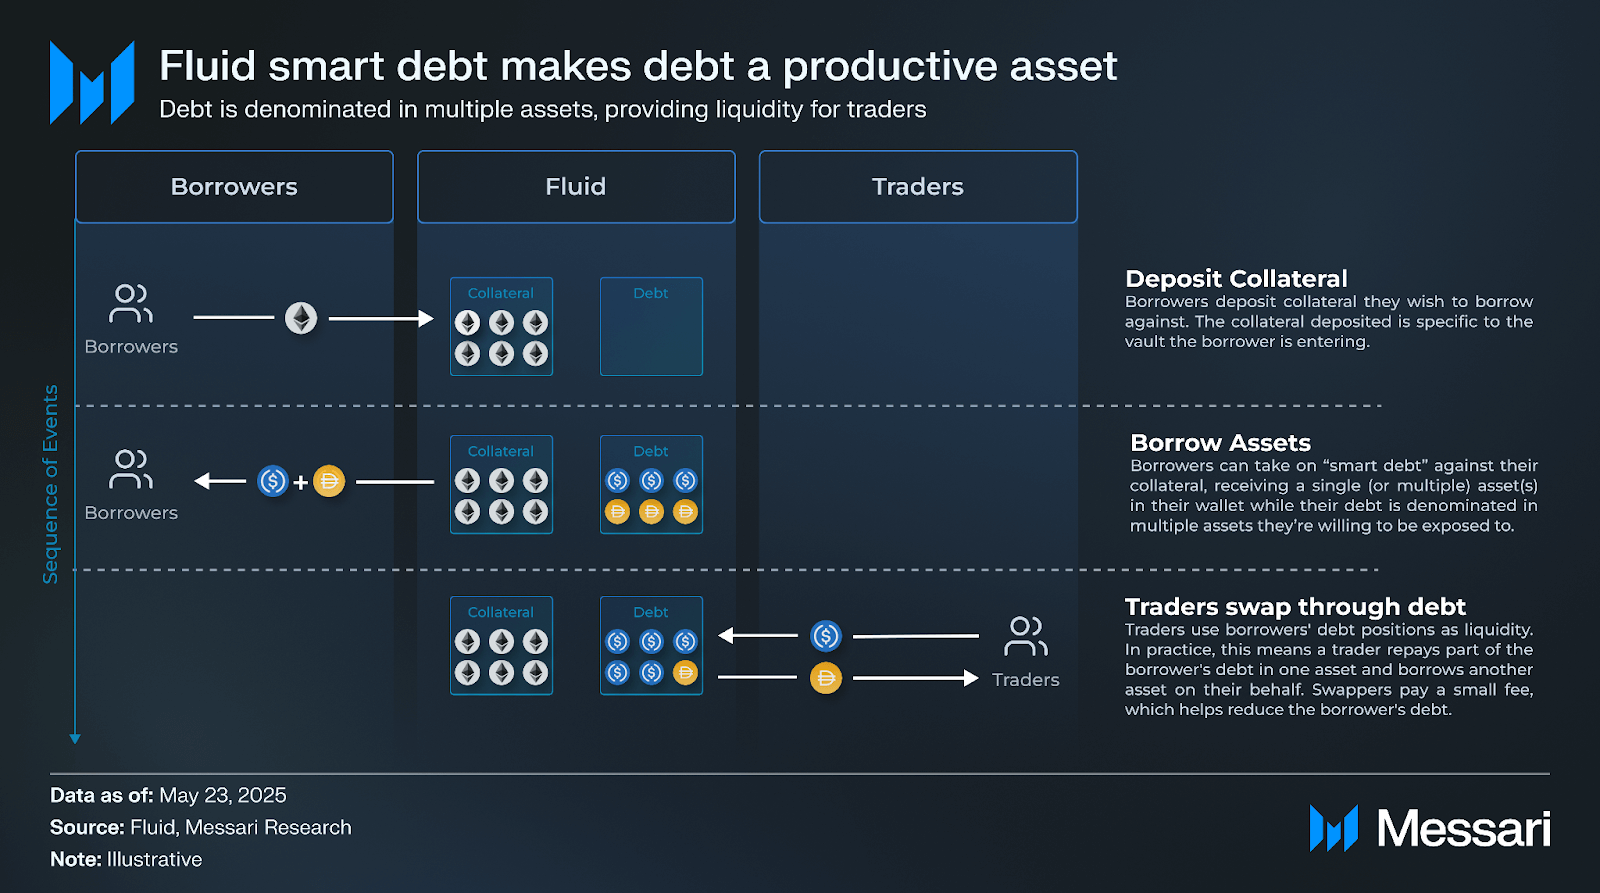
Smart debt is debt that is also a liquidity provision on the DEX protocol. Vault protocol users can borrow either one or both assets needed to form the liquidity provision. Regardless of the initial ratio of borrowed assets, Smart Debt will be shifted to match the current composition of the DEX pair. Like all assets borrowed from the Liquidity Layer, Smart Debt pays interest (borrow APR). However, Smart Debt earns trading fees from the DEX, which reduces a user’s debt.
An example of Smart Debt is Vault 45 on Ethereum, where ETH can be deposited to borrow USDC, USDT, or a combination of the two assets. In this example, a user could deposit ETH and then borrow USDC and USDT, which would create the liquidity provision. Over time, a user’s portion of debt that is USDC and USDT shifts due to traders buying and selling into the Fluid DEX USDC-USDT pool, changing the pool’s balance of assets. Once the user has repaid their debt with USDC, USDT, or a combination of the two assets, they will be able to withdraw their collateral.
Most of the time, providing liquidity to a DEX protocol requires a user to supply two assets, like USDC and USDT, in exchange for a fungible or non-fungible receipt token that can be used to withdraw their portion of USDC and USDT from the liquidity pool (including any fees earned). Smart debt can be thought of as the inverse of this operation. Instead of depositing USDC and USDT, the user withdraws them from the Vault protocol as debt backed by their collateral. However, even though the user has withdrawn what would otherwise be the USDC and USDT reserves to facilitate the trade, the DEX protocol is able to execute the trade by borrowing USDC and/or USDT from the Liquidity Layer. The shifting liabilities of the DEX protocol are reflected via shifting liabilities of Smart Debt borrowers to the Vault protocol, with all liabilities ultimately secured by the collateral in Smart Debt vaults. So, when a trader comes to exchange USDC for USDT, they are technically repaying a portion of the USDC debt and increasing a portion of the USDT debt, which is facilitated via the Liquidity Layer. Moreover, since the debt is in the form of a liquidity provision, it earns trading fees, reducing a user’s debt.
Smart collateral and smart debt are what make Fluid’s DEX protocol possible. In stark contrast to every other permissionless DEX protocol ever built, the only way to provide liquidity to the DEX protocol is by either lending to the Liquidity Layer via the Lending protocol (indirectly) or depositing collateral and/or borrowing from the Liquidity Layer via a vault that uses smart collateral and/or smart debt from the Vault protocol (directly).
Tokenomics / Governance
All of Fluid’s product offerings (Fluid, Instadapp PRO, Instadapp Lite, and Avacoda) are governed by FLUID token holders or delegates, as token holders can delegate their voting power. Fluid’s governance structure requires that all proposals be submitted by a proposee who has, or has been delegated, the voting rights of 1% of the total FLUID supply (1 million FLUID), with 4% of the supply needed to reach quorum. In addition, proposals are subject to a voting period of approximately three days, followed by a two-day timelock delay before execution. Fluid has both onchain and offchain voting, with discussions for either typically beginning in the forum. Fluid’s onchain voting is for matters that require onchain execution, e.g., setting Fluid DEX pool parameters or transferring tokens, while offchain voting pertains to matters regarding the strategic direction of Fluid, e.g., which multichain bridge provider to use.
FLUID Distribution
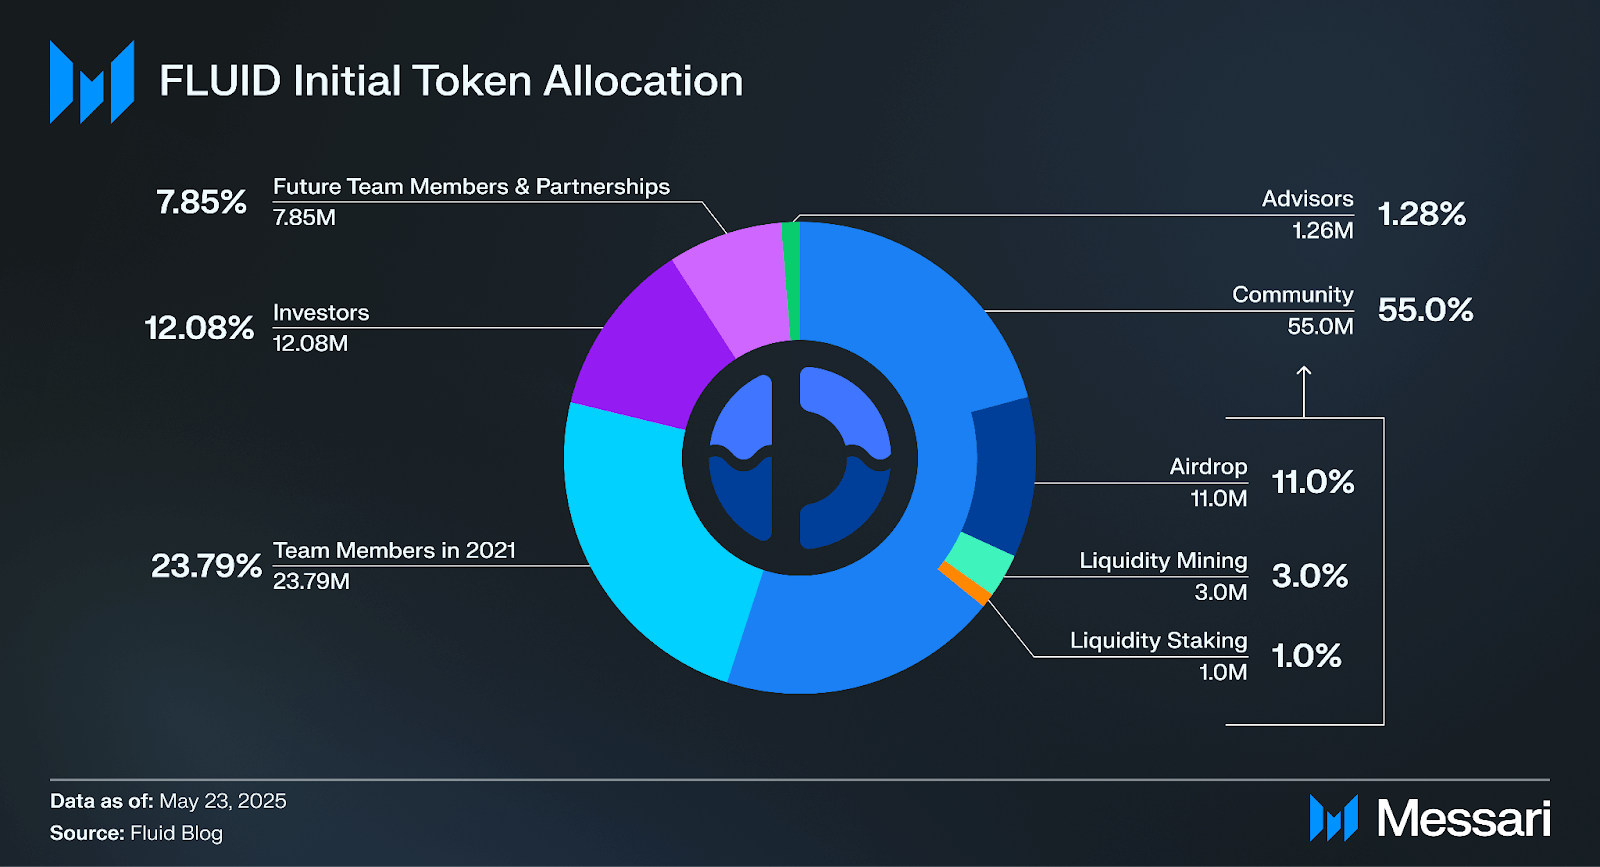
FLUID was launched on June 16, 2021 (originally under the ticker INST) with a maximum supply of 100 million tokens. 37.1 million FLUID collectively allocated to team members, investors, and advisors is subject to a 4-year vesting schedule that began at launch. As of May 23, 99% of these tokens have vested and are unlocked, with the remaining tokens unlocking by the end of June 2025. The DAO is the largest individual tokenholder, with its treasury wallet holding just over 24 million tokens at the time of writing.
Since FLUID’s creation, there have been two noteworthy distributions of the token from the DAO’s treasury. The first occurred on Dec. 3, 2024, when the DAO approved a $4 million sale of 1.145 million FLUID tokens to the Aave DAO. This $4 million was paid with 4.0 million GHO (Aave’s stablecoin). The sale valued FLUID at roughly a fully diluted market capitalization of $350 million. The terms of the sale stipulated that the Aave DAO would use one-third of the FLUID tokens it received to incentivize GHO liquidity on Fluid, and the remaining two-thirds would be vested for 1 year, with the Aave DAO able to participate in Fluid governance for all 1.145 million tokens immediately via delegation to the Aave Protocol Embassy. After both DAOs (Aave & Fluid) approved the transaction, the Fluid DAO subsequently deposited all of the GHO it received into its Lending protocol.
The second distribution of note occurred 13 days later on Dec. 16, 2024, when 12 million FLUID was transferred from the DAO treasury to the Instadapp Labs team wallet as part of a larger initiative to rebrand and grow Fluid. The terms of the distribution were as follows: 2 million to be used for exchange listings, 2 million to be used for market making, 5 million for fundraising initiatives, and 3 million for team growth initiatives.
Protocol Activity
Since launching, Fluid’s total market size (USD value of all collateral deposited into Fluid’s Liquidity Layer) has grown to just under $2 billion. As of May 23, Fluid’s Ethereum deployment had the largest market size by blockchain at $1.58 billion (87.2% market share), followed by Arbitrum at $130.1 million (7.2% market share), Polygon (deployed in March) at $52.0 million (2.9% market share), and Base at $50.1 million (2.8% market share).
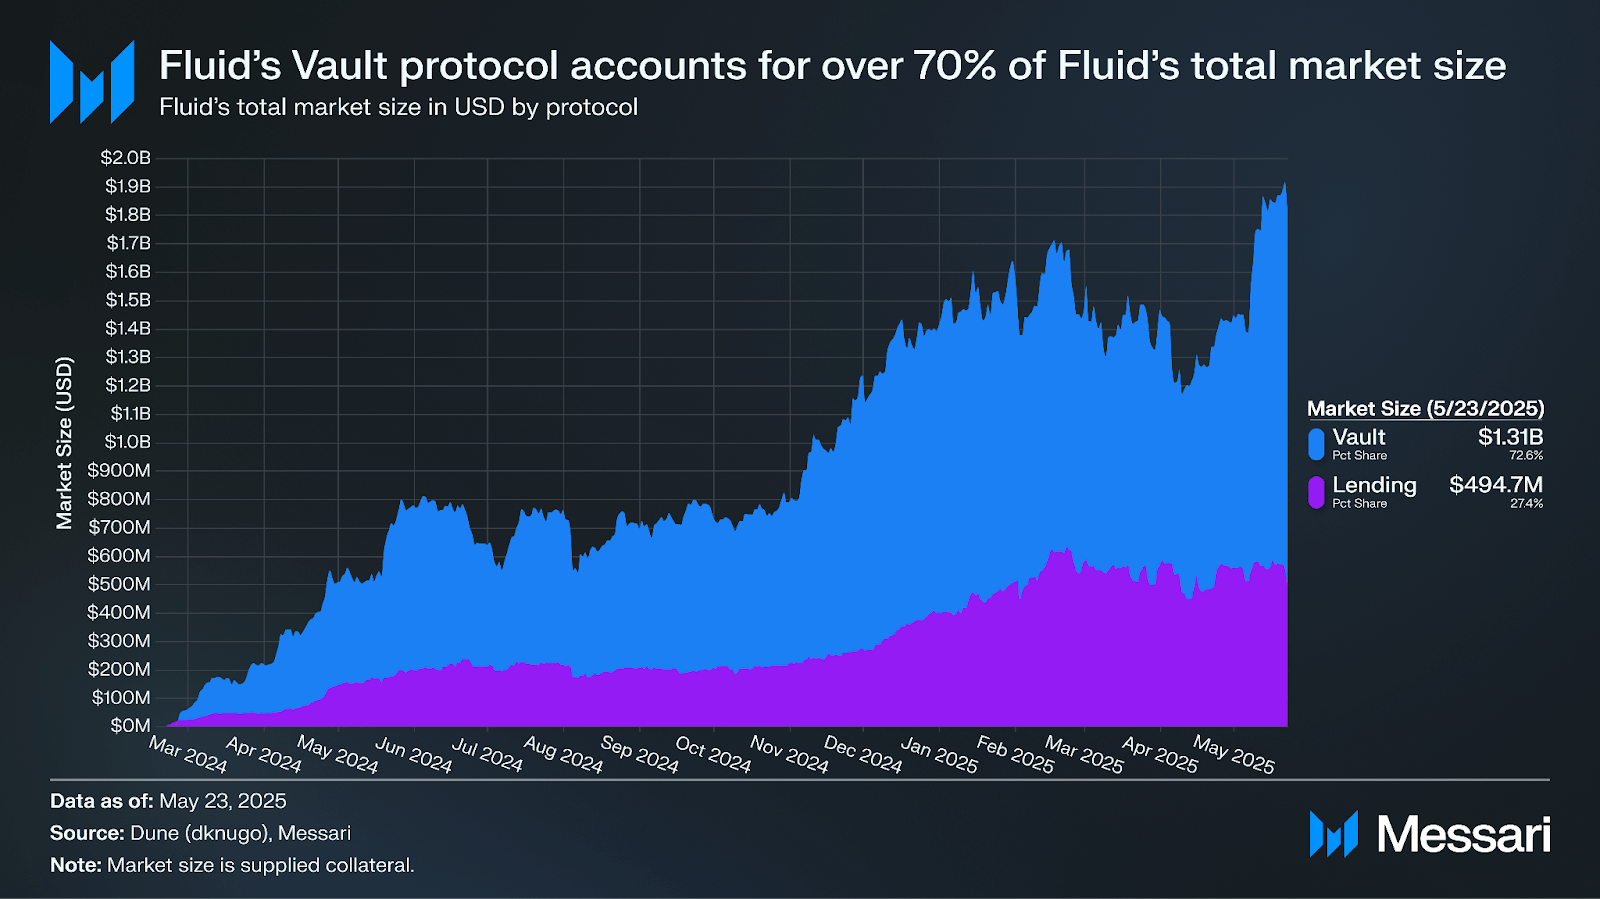
Of Fluid’s three protocols, only the Vault and Lending protocols contribute to its market size. This is because, currently, the only way for users to provide liquidity for the DEX protocol is to deposit and/or borrow from a Vault that supports Smart Collateral, Smart Debt, or both. The Vault protocol had a market size of $1.31 billion (72.6% market share), while the Lending protocol had a market size of $494.7 million (27.4% market share).
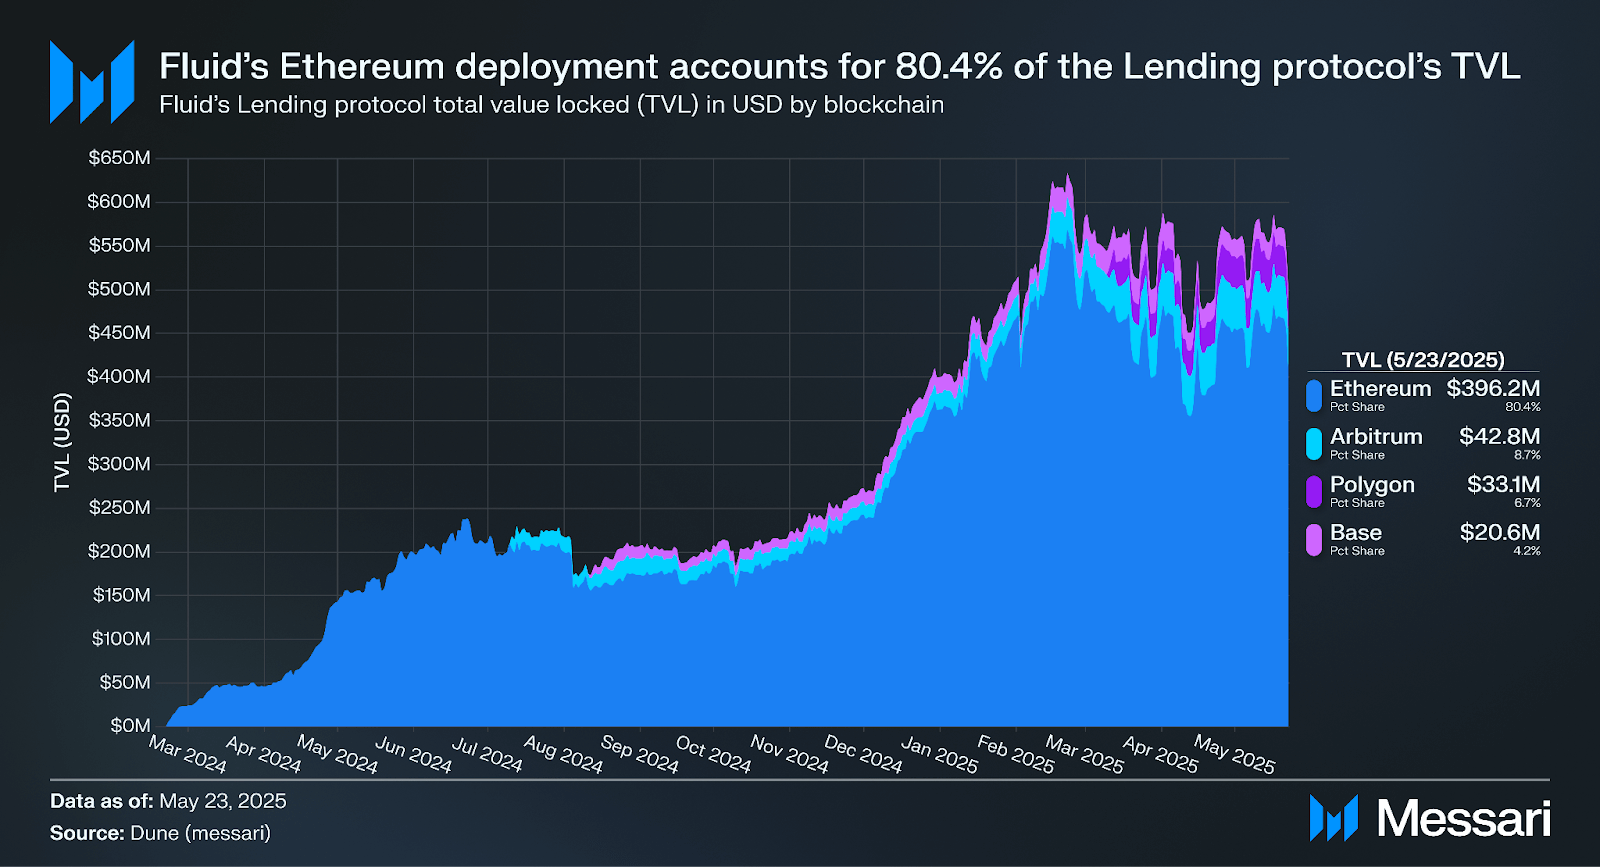
For the Lending protocol, TVL and market size are effectively synonymous, since TVL equals supplied collateral minus borrowed debt, and the protocol itself does not take on any debt. As of May 23, Fluid’s Ethereum deployment accounted for 80.4% of all TVL in Fluid’s Lending protocol. Across all of Fluid’s deployments, the Lending protocol’s TVL was roughly $500 million.
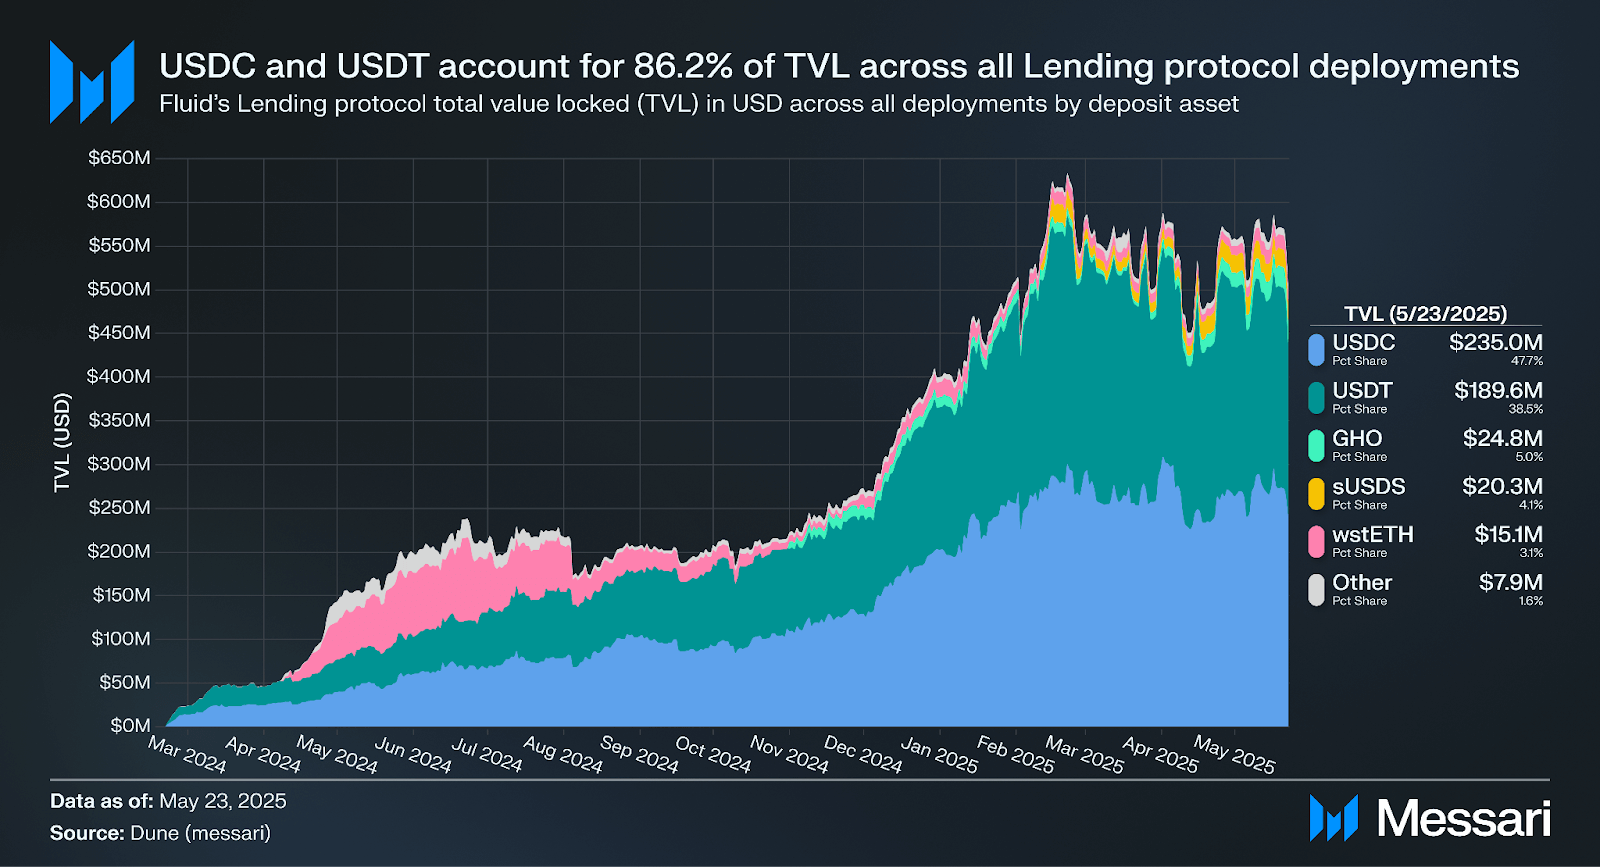
The Lending protocol currently supports the following assets across its deployments: USDC, USDT, GHO, sUSDS, wstETH, ETH, ARB, EURC, POL, and AUSD. Some assets are only available on specific blockchains, e.g., ARB is only available on Arbitrum. Across all deployments as of May 23, USDC accounts for the majority of TVL, with $235.0 million in deposits (47.7% share). USDT follows closely behind with $189.6 million in TVL (38.5% share). Collectively, USDC and USDT account for 86.2% of TVL across all of Fluid’s Lending protocol deployments.
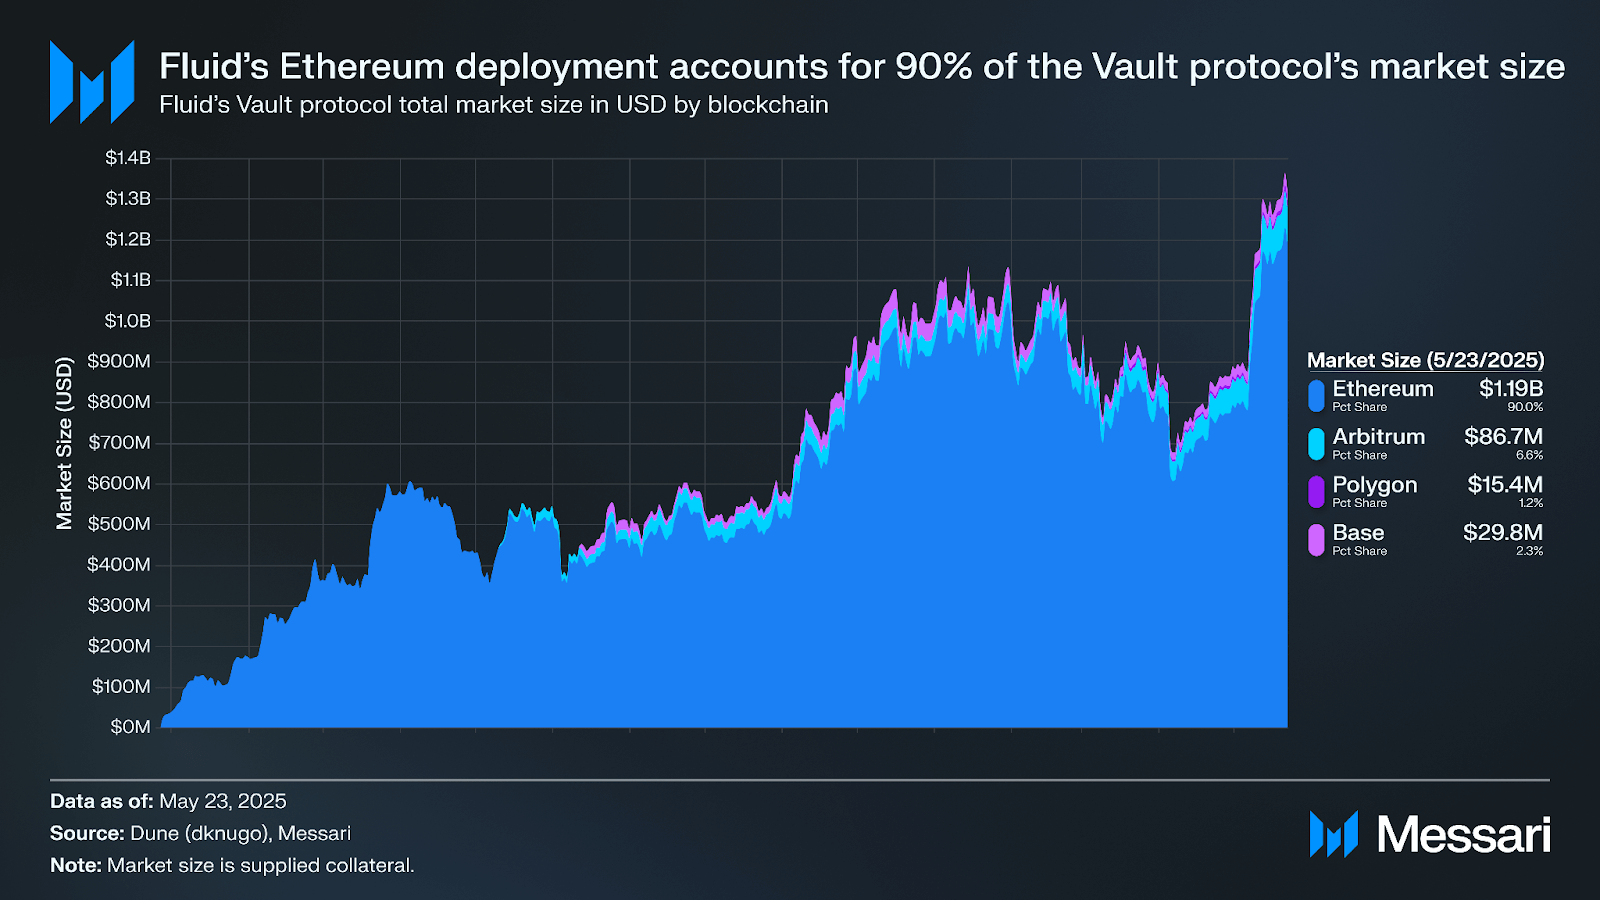
The Vault protocol’s largest deployment by market size is on Ethereum, which represented 90% of its market size across all deployments as of May 23.
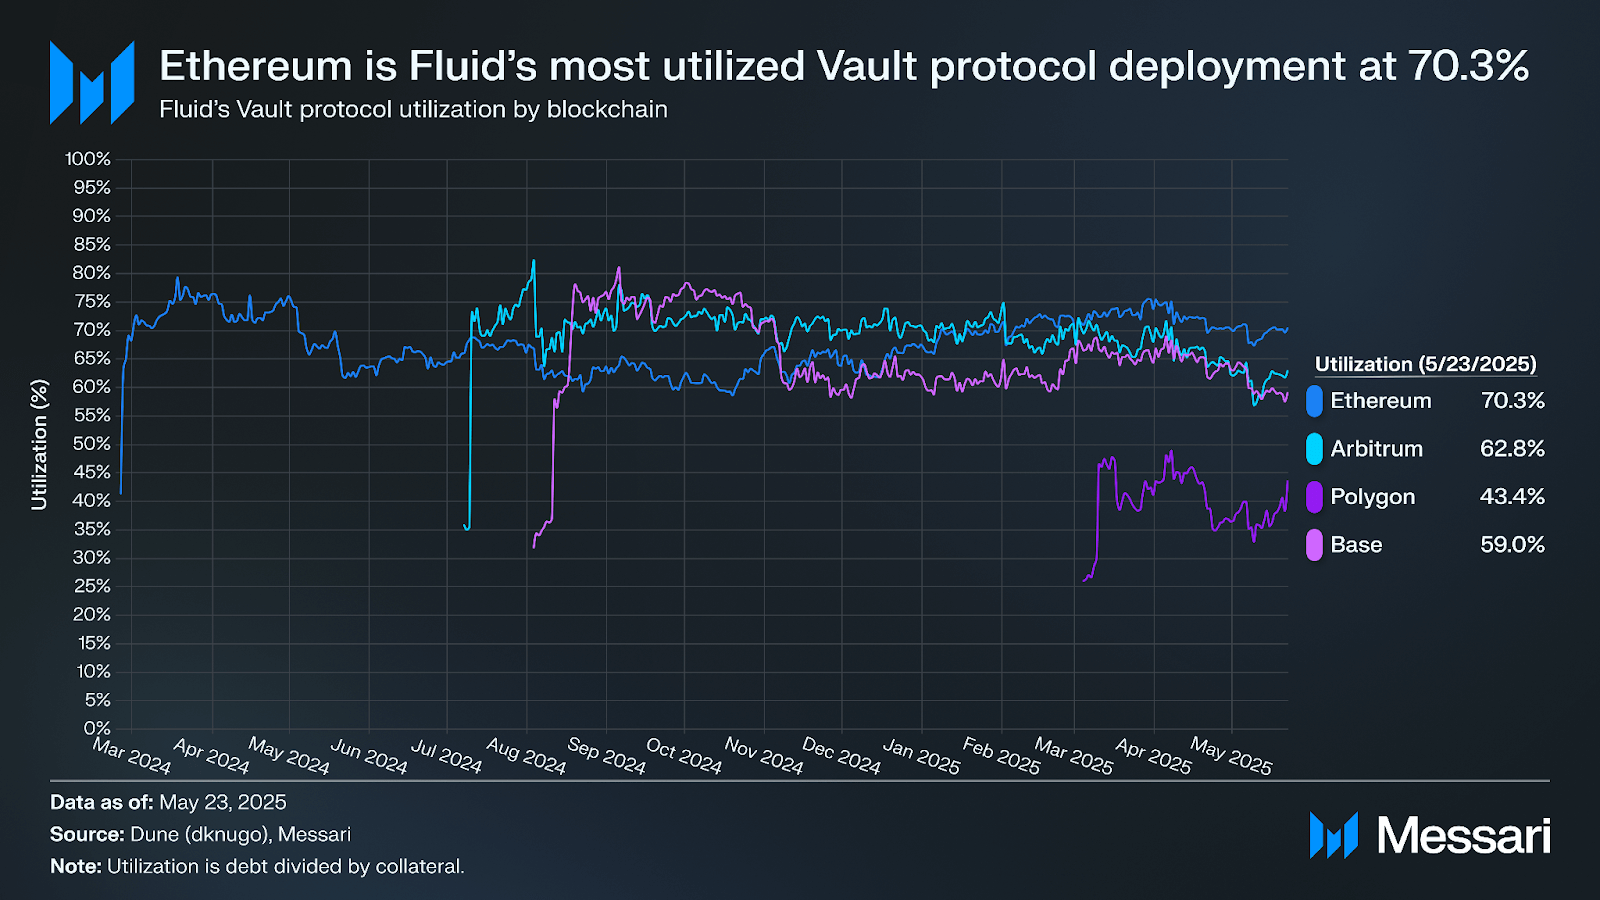
One of the most important metrics to understand a borrowing protocol is its utilization, which is its debt-to-collateral percentage. Since its deployment in July 2024, Fluid’s Vault protocol on Arbitrum had the highest utilization rate among all deployments until March 2025. However, as of May 23, Fluid’s utilization was the highest on Ethereum at 70.3%, while the Arbitrum deployment was the second most utilized at 62.8%. Base is not too far behind Arbitrum at 59.0% utilization, while Polygon had the lowest utilization at 43.4%.
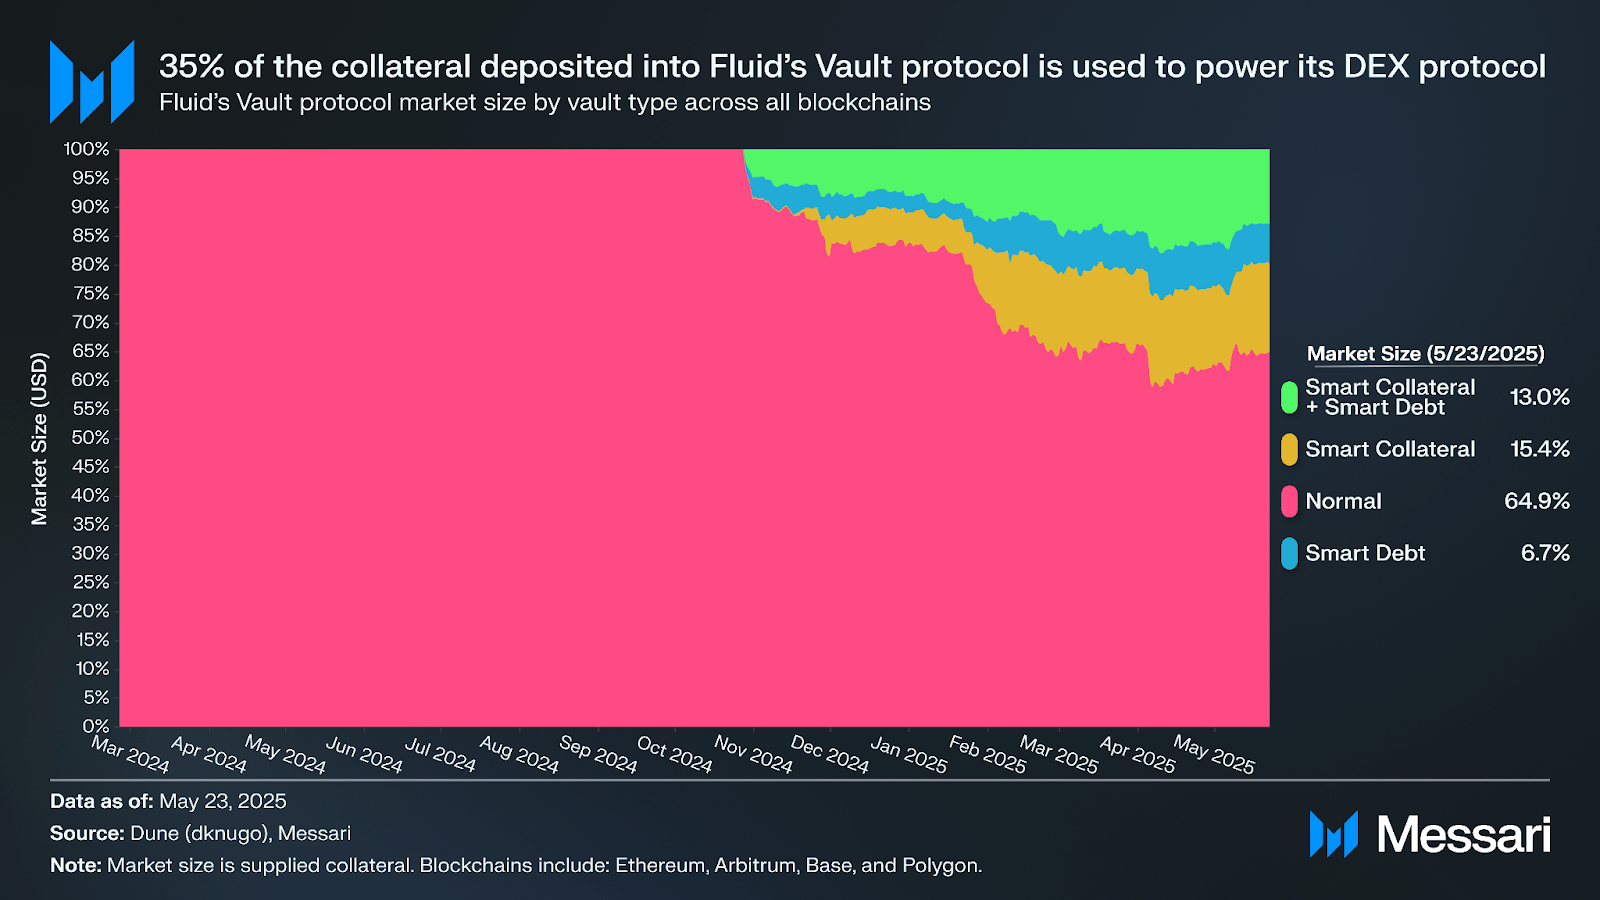
As previously mentioned, Fluid’s DEX protocol does not allow users to directly deposit liquidity. Rather, users provide liquidity by depositing to and/or borrowing from Vaults that use Smart Collateral, Smart Debt, or both. As of May 23, 35% of all collateral deposited into the Vault protocol is deposited into a vault that uses Smart Collateral, Smart Debt, or both. Of these three categories, vaults that only use Smart Collateral accounted for the largest share of the Vault protocol’s collateral at 15.4%, while vaults that use Smart Collateral and Smart Debt accounted for the second most at 13.0%. Smart Debt only vaults accounted for the smallest share of the Vault protocol’s collateral at 6.7%. Normal vaults that have no smart features accounted for 64.9% of the Vault protocol’s total collateral deposits.
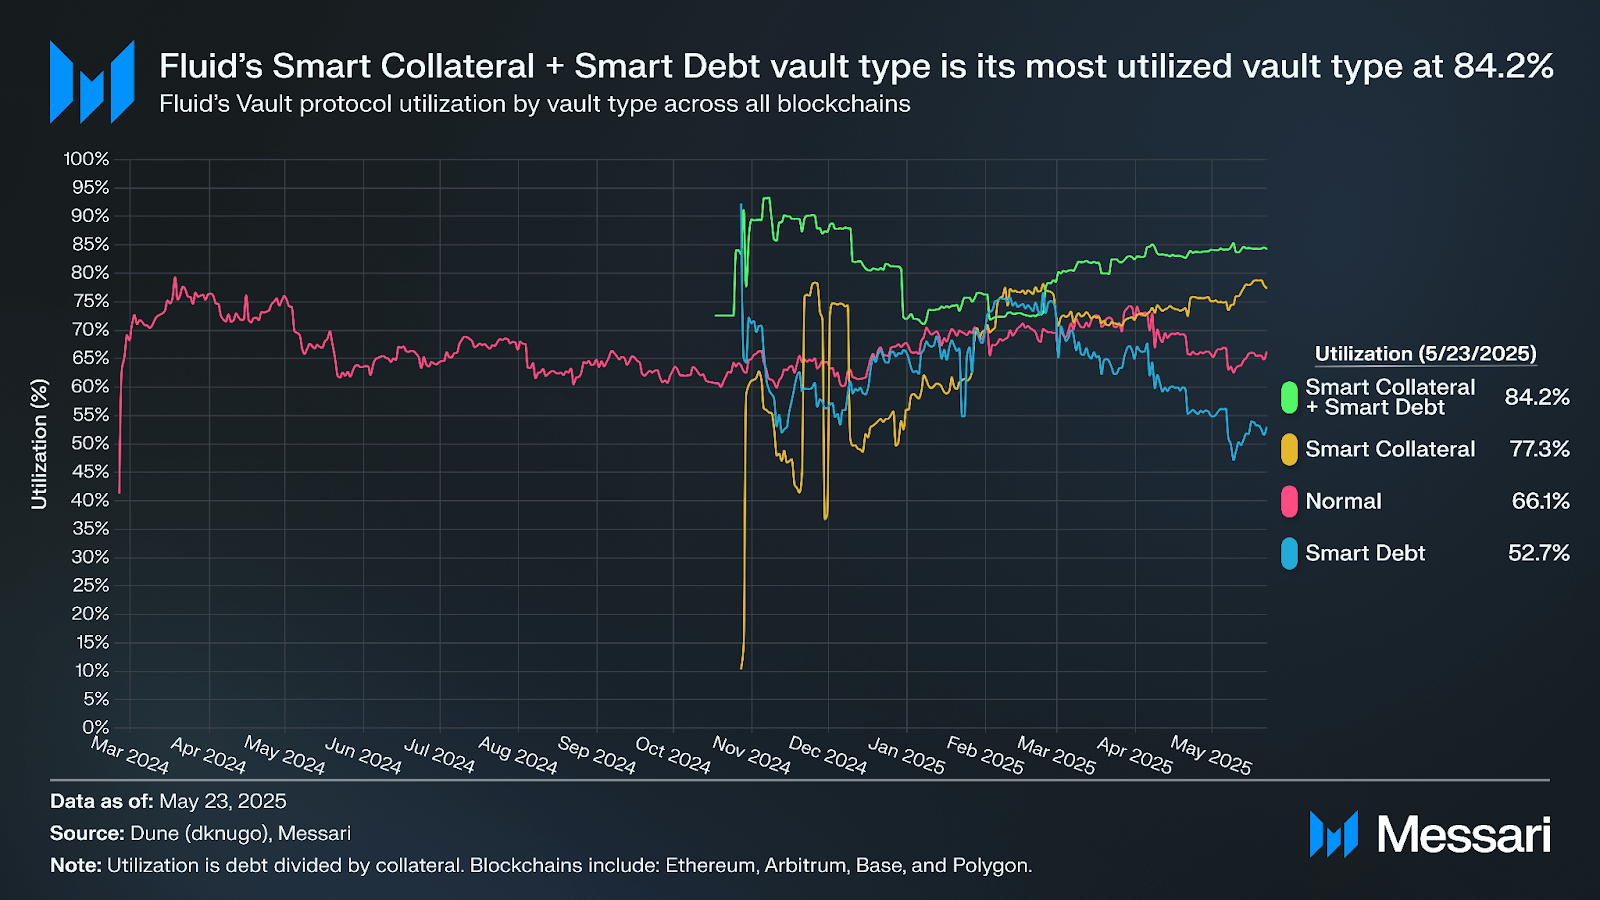
Collectively, Vaults that use Smart Collateral and Smart Debt had the highest utilization of any vault type at 84.2% as of May 23. Smart Collateral only vaults had the second highest utilization at 77.3%, while normal vaults ranked third in utilization at 66.1%. Smart Debt only vaults had the lowest utilization at 52.7%.
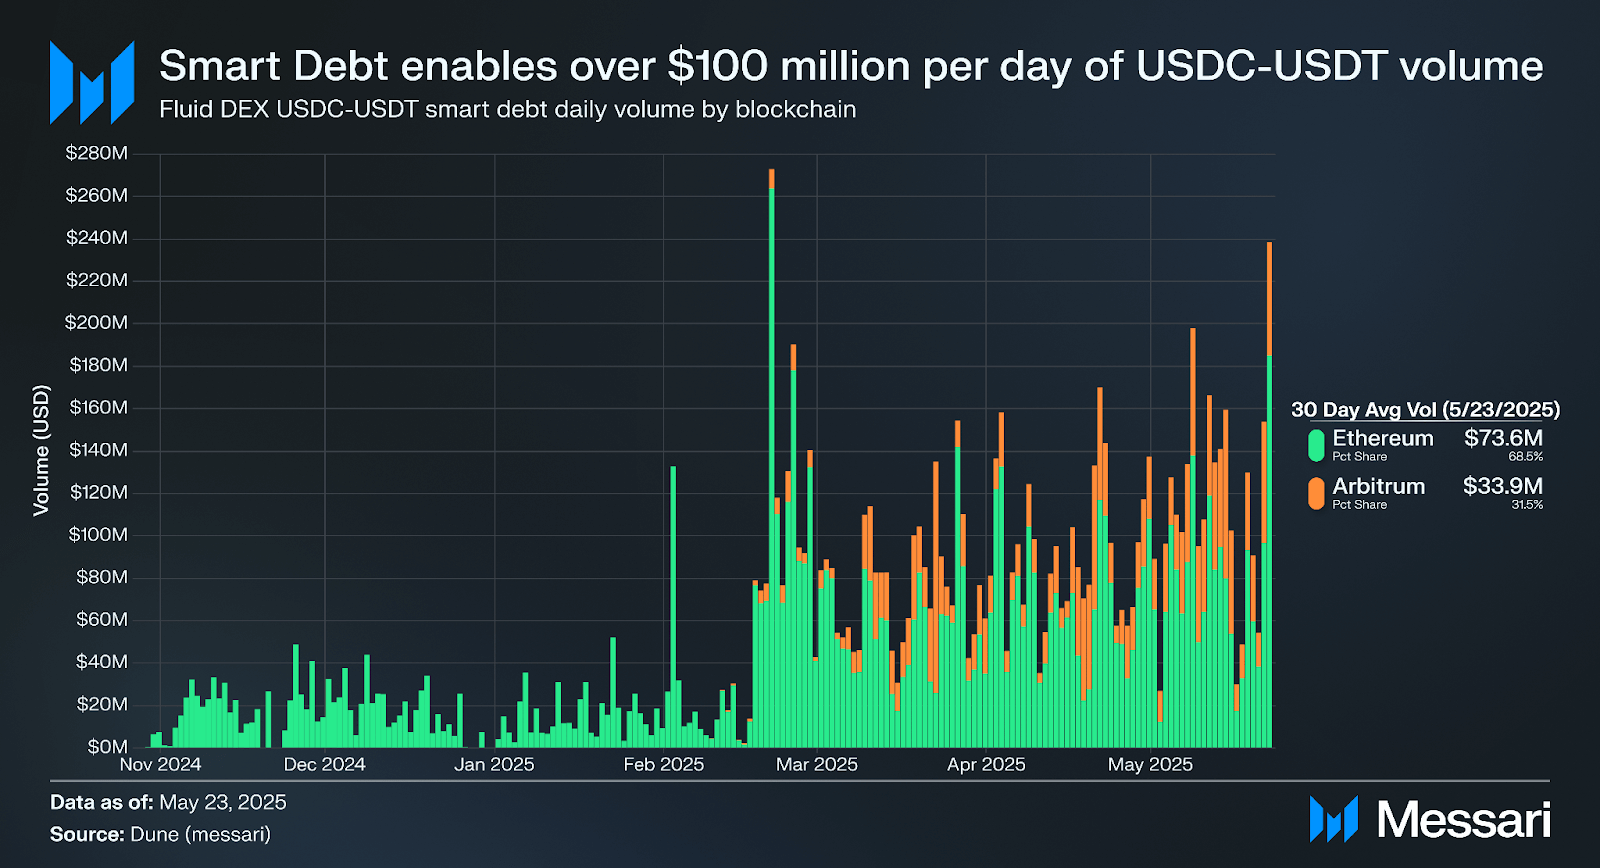
As of May 23, Smart Debt alone powers the second-largest DEX pair by volume of USDC-USDT, as smart collateral is currently not enabled for the pair. As such, the only way to provide liquidity to this pair is to borrow USDC and/or USDT through a USDC-USDT Smart Debt vault. This DEX pair routinely has $100 million in daily volume between its Ethereum and Arbitrum deployments.
Not only does Smart Debt enable $100 million in daily volume for the USDC-USDT DEX pair, but it has also accounted for over $10 billion in cumulative volume for the pair. Of that $10 billion, Ethereum has accounted for $8.6 billion while Arbitrum has accounted for $2.3 billion.
Fluid’s DEX protocol launched on Oct. 29, 2024, and quickly became the fastest DEX protocol on Ethereum to surpass $5 billion and $10 billion in cumulative volume, doing so in 72 and 100 days, respectively. Thereafter, Fluid’s DEX protocol became the fastest DEX to break $20 billion in cumulative volume on Ethereum, doing so in 127 days.
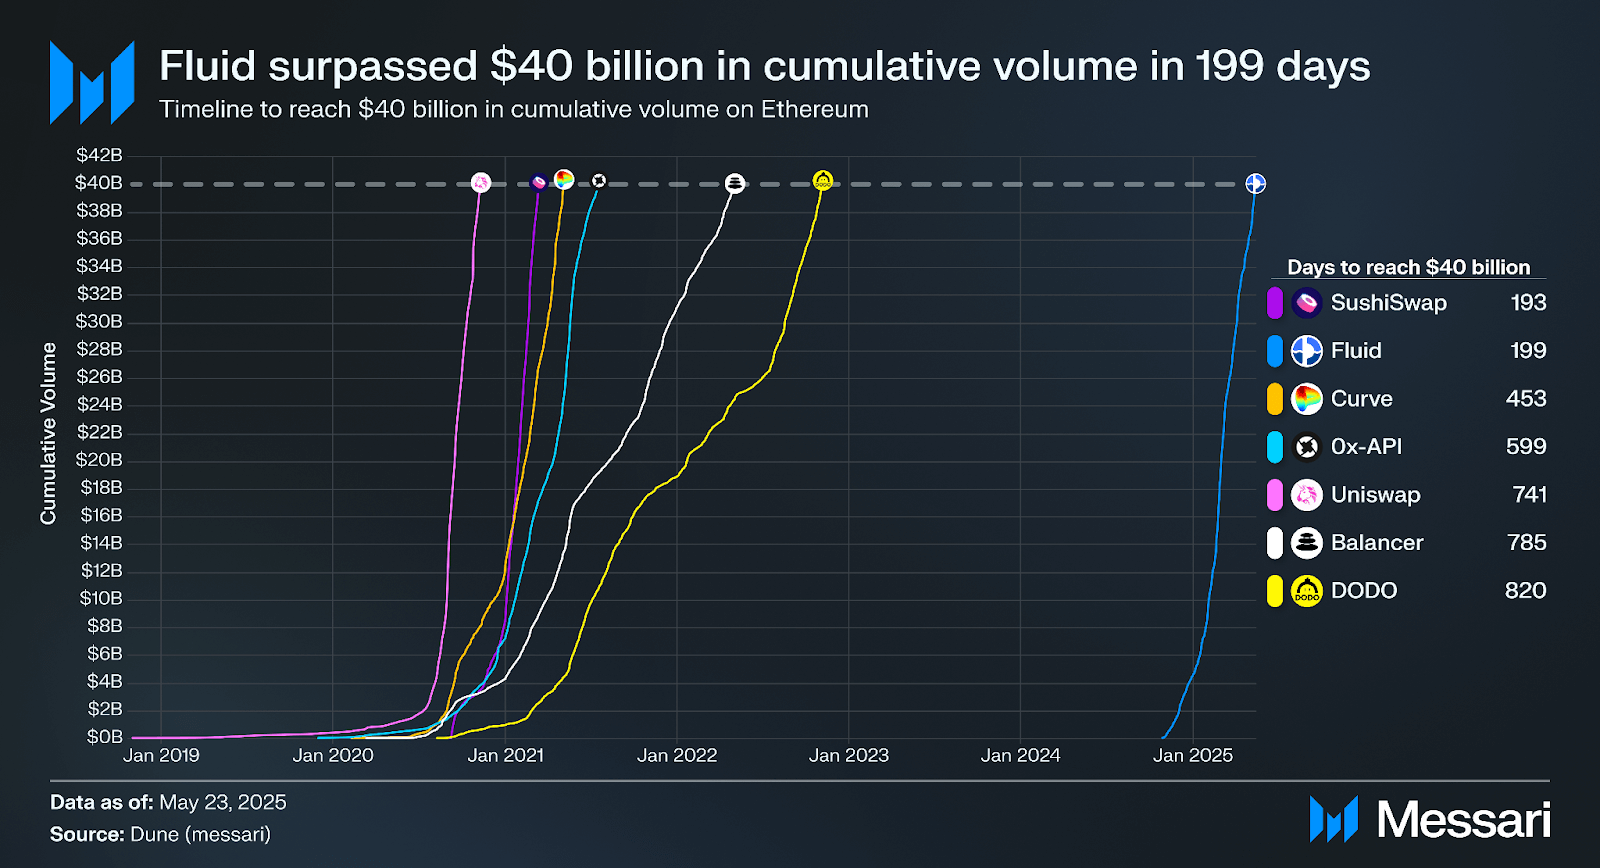
While Fluid was not the fastest DEX to surpass $40 billion in cumulative volume on Ethereum, as SushiSwap holds that title, it was the second fastest and most recent DEX to accomplish the feat. Prior to Fluid, the last DEX to surpass $40 billion in cumulative volume on Ethereum was DODO in late 2022. In reaching this milestone, Fluid joined an exclusive club of only seven DEXes to accomplish the feat.
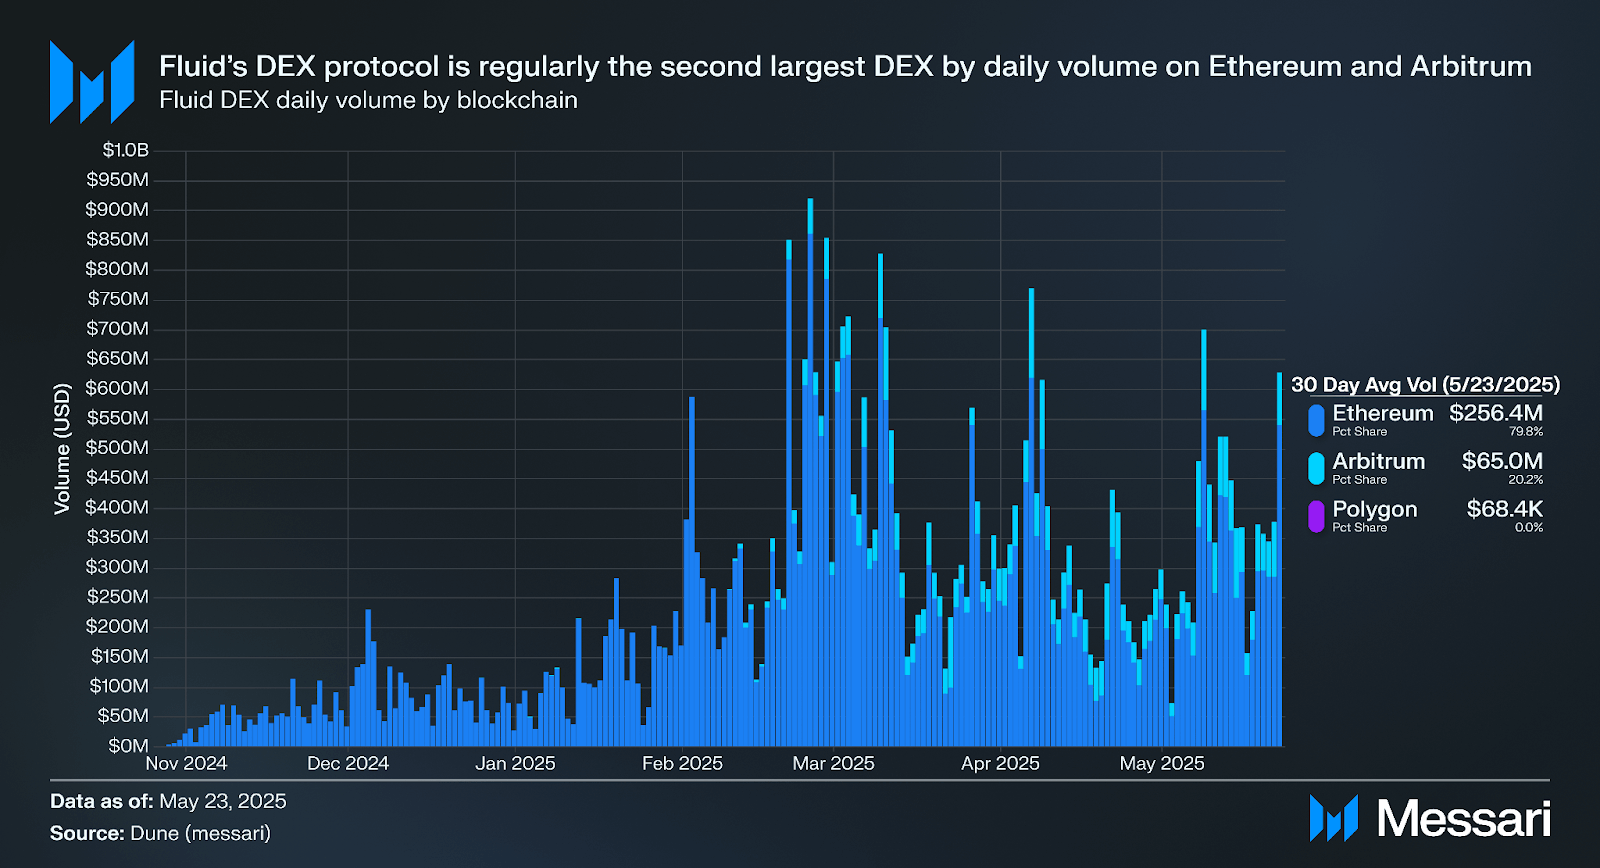
Over the last 30 days, Fluid’s DEX protocol averaged $256.4 million in volume, while on Arbitrum, it averaged $65.0 million.
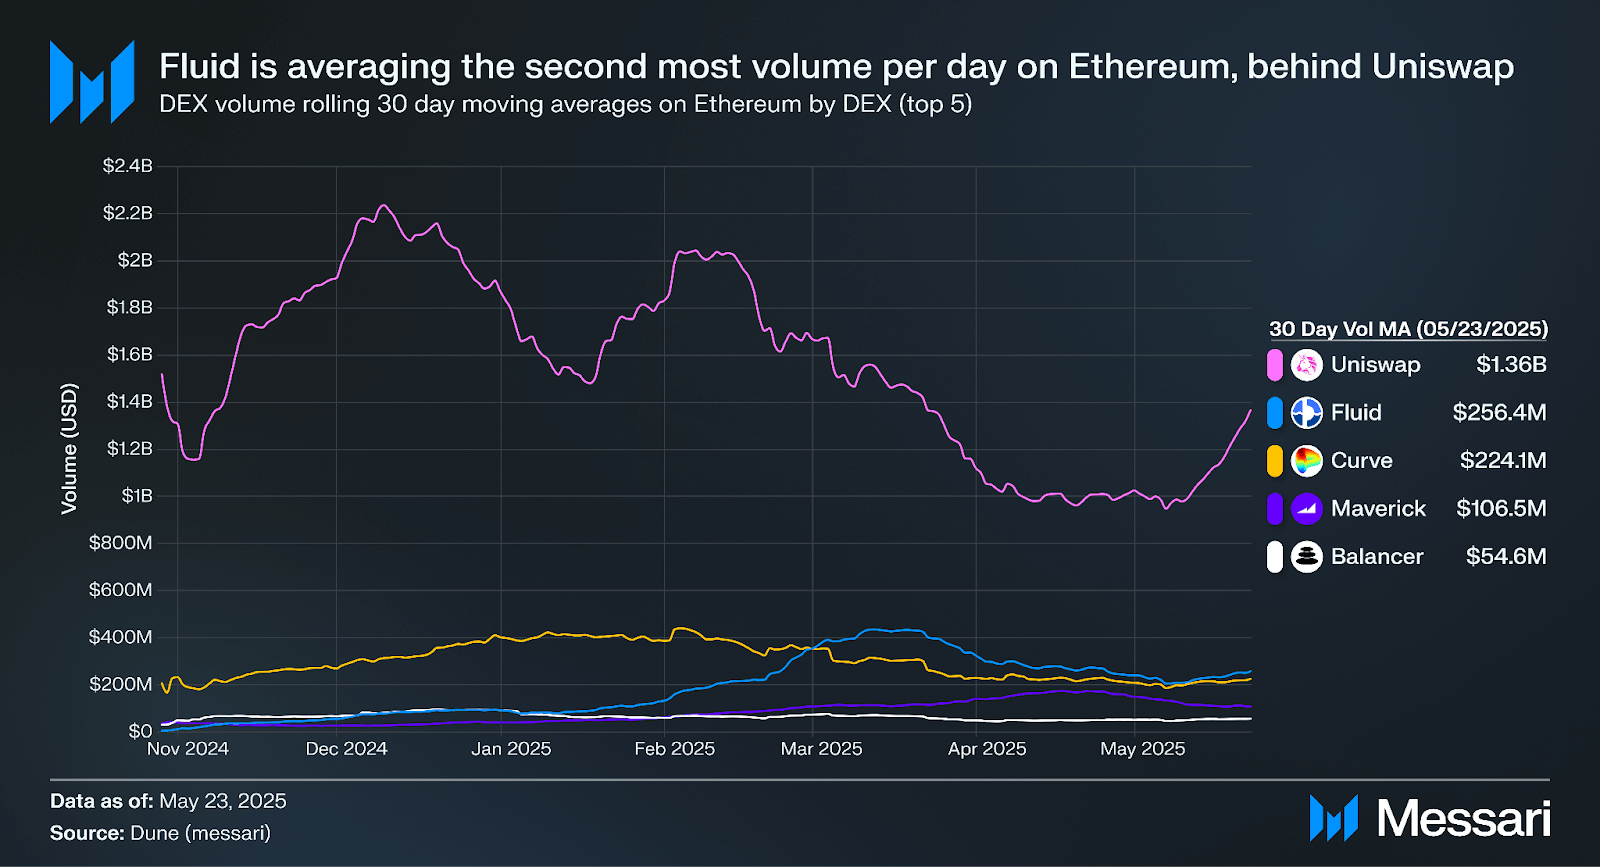
As of May 23, Fluid’s DEX protocol is live on Ethereum, Arbitrum, and Polygon and is the second-largest DEX protocol by daily volume on both Ethereum and Arbitrum, only behind Uniswap. Over the last 30 days, Fluid’s DEX protocol averaged $256.4 million in volume, while on Arbitrum, it averaged $65.0 million.
As of May 23, Fluid’s DEX protocol has surpassed $46 billion in cumulative volume, with its Ethereum deployment responsible for $42.4 billion. Its Arbitrum deployment has accounted for $5.5 billion, while its recently released Polygon deployment has accounted for $2.1 million.
Roadmap
DEX V2
On April 25, Fluid announced DEX V2, the second version of its record-breaking DEX protocol. The new version focuses on modularity and will be powered by a singleton contract that centralizes core pool functions while improving gas efficiency. Furthermore, DEX V2’s design modularizes pool logic, thereby enabling new pool types to be developed without deploying a new protocol. At launch, DEX V2 will support four pool types: Smart Collateral, Smart Debt, Smart Collateral Range Orders, and Smart Debt Range Orders. Range orders enable liquidity to be concentrated, increasing capital efficiency. DEX V2 will enable trading fees to be dynamically adjusted and/or controlled by custom logic via Hooks, which is inspired by Uniswap V4. Additionally, DEX V2 will use Flash Accounting (also inspired by Uniswap V4). Flash Accounting is an optimization that reduces gas costs by minimizing external token transfers during swaps and liquidity operations. Finally, DEX V2 enables users to submit onchain limit orders that earn lending APR while they are waiting to be filled. With DEX V2, Fluid aims to overtake Uniswap as the number one DEX by volume.
Solana Expansion
On May 22, 2025, Fluid and Jupiter announced a partnership to launch Jupiter Lend, a money market lending protocol on the Solana blockchain powered by Fluid. Jupiter Lend is scheduled for release in July 2025.
Closing Summary
Amid a DeFi landscape with fragmented liquidity and isolated protocols, Fluid has established itself as a protocol-layer solution to unify liquidity, increase capital efficiency, and improve composability across protocols. Rebranded from Instadapp in late 2024, Fluid introduces a unified Liquidity Layer that powers three seamlessly integrated protocols: Lending, Vault, and DEX, with each using the same liquidity to optimize capital efficiency. The Lending protocol provides passive yield opportunities, the Vault protocol enables high-LTV, overcollateralized borrowing with a novel range-based liquidation engine, and the DEX introduces Smart Collateral and Smart Debt, turning collateral and debt positions into productive, fee-earning assets. This modular architecture abstracts liquidity provisioning, automates complex protocol interactions, and powers innovative DeFi strategies. Since launch, Fluid has scaled to nearly $2 billion in market size and facilitated over $46 billion in cumulative DEX volume across Ethereum, Arbitrum, Base, and Polygon. Governed by the Fluid DAO, the protocol’s rapid adoption underscores the usefulness of its architecture. With the planned launch of DEX V2 and expansion to Solana via Jupiter Lend, Fluid is positioned to solidify its role as one of DeFi’s most advanced and powerful projects.
This report was commissioned by Interop Labs Ltd. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Troy enjoys exploring the dark forest, piecing together data puzzles, and following the frontier. Prior to joining Messari, Troy was a data analyst at Balancer Labs.
Troy enjoys exploring the dark forest, piecing together data puzzles, and following the frontier. Prior to joining Messari, Troy was a data analyst at Balancer Labs.