This research report was produced independently by Blockworks. No third party commissioned, funded, or had input on its content. All analysis and conclusions are the author(s)' own. All published Blockworks research is reviewed internally to ensure accuracy and objectivity. Researchers submit financial conflict of interest (FCOI) disclosures on a monthly basis, which are reviewed by appropriate internal parties. The author(s) of this report may hold positions in the assets discussed. This report is for informational purposes only and does not constitute investment advice. Readers should conduct their own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results.
The UNIverse Expands

Key Takeaways
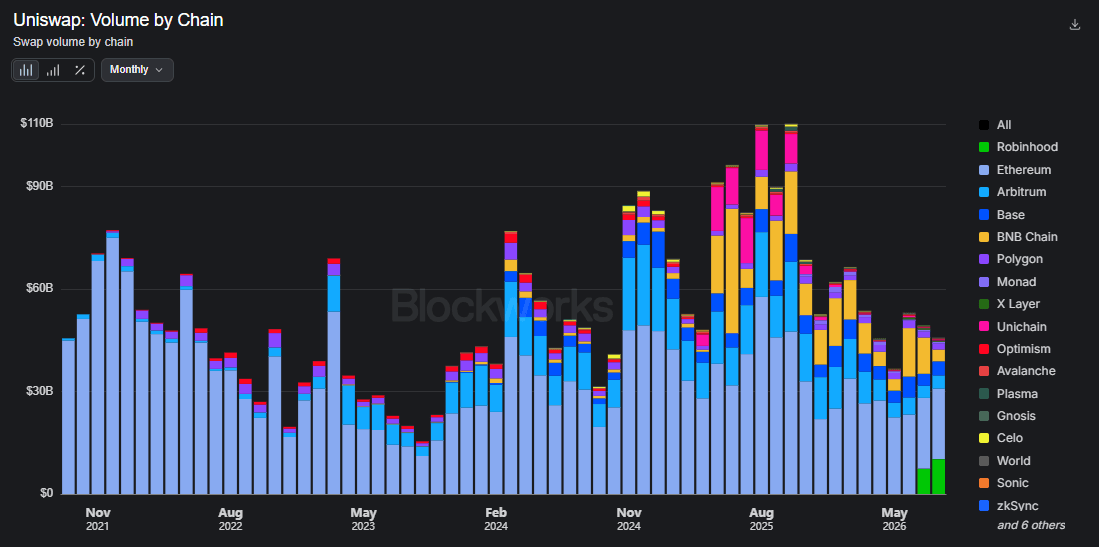
- Uniswap has maintained a monthly volume of around $40B to $60B despite growing competition. Robinhood is now its largest short-term catalyst, accounting for 22% of August volume while Uniswap controls 92% of DEX activity on the chain.
- V4 now accounts for 54% of Uniswap’s Ethereum volume, with stablecoins leading adoption. Hook volume remains small, but new projects are beginning to use hooks for token launches, dynamic fees and more experimental markets.
- We expect the next wave of speculation to extend beyond memecoins, with v4 hook projects competing for capital and attention. Over time, permissioned pools and correlated asset pairs could turn this experimentation into more durable tokenized asset volume.
- The fee switch burned $9.3M of UNI in August and does not appear to have materially weakened liquidity or execution. Annualised burns would offset most of Uniswap’s 20M UNI growth budget, though they remain dependent on current volume levels.
- UNI trades at a premium to the average and median revenue multiples of its peers. Its position as the dominant DEX and early lead on Robinhood help justify this, but the higher valuation leaves less room for volume and burns to disappoint.
Introduction
Uniswap is back in focus following a 44% rally in UNI over the past month. Much of that move can be traced to Robinhood Chain, where a surge in memecoin and tokenized equity trading has made Uniswap the main venue for speculative activity.
Two months after launch, Robinhood accounted for 22% of Uniswap’s August volume. The fee switch was activated less than a month after the chain went live, allowing this growth to flow back to UNI through token burns.
The question is how long the activity can last. Memecoin cycles eventually cool, but they have also introduced a large group of users to tokenized equities and new ways of trading them. V4 gives Uniswap the infrastructure to build on that demand through hooks, permissioned pools and markets between correlated assets.
This report looks at whether Uniswap can use v4 to turn its early lead on Robinhood into a more durable source of volume from tokenized assets. We also examine what the fee switch means for UNI, whether it has come at the expense of LPs, and how Uniswap is valued relative to its peers.
Uniswap Has Held Its Ground
Robinhood is the latest source of growth for Uniswap, but its volumes have remained resilient across several shifts in market activity. Over the past two years, monthly volume has generally ranged between $40B and $60B, with peaks approaching $100B after the US election in late 2024 and during the DAT rally in the summer of 2025.
This resilience stands out in a DEX market that has become far more competitive. Uniswap’s share of volume across all chains fell from 45% in January 2024 to 29% in August 2026, but has started to recover in recent months.
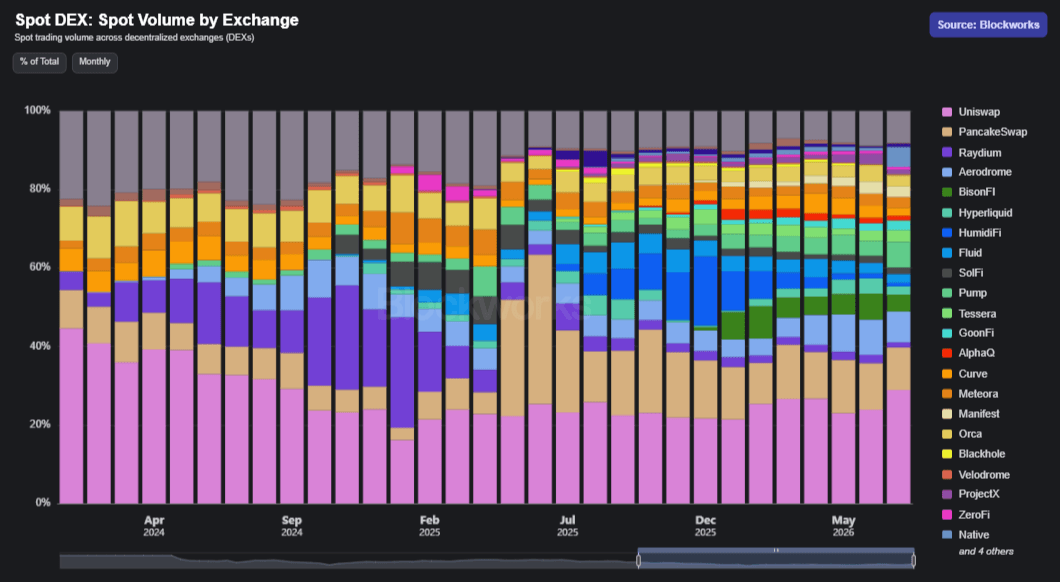
Many protocols from the last cycle struggled once activity moved to new chains and applications. Uniswap has bucked that trend by following users wherever new pockets of activity emerge.
Following Activity to New Chains
Uniswap’s changing chain mix shows how this has played out. Ethereum still accounts for the largest share of its volume, but this has fallen from 60% in 2024 to 45% in August 2026 as activity expanded elsewhere. Base was an early example. It contributed just 1% of Uniswap’s volume in 2024, but now accounts for close to 10%. Uniswap was able to establish itself on Base despite strong competition from Aerodrome.
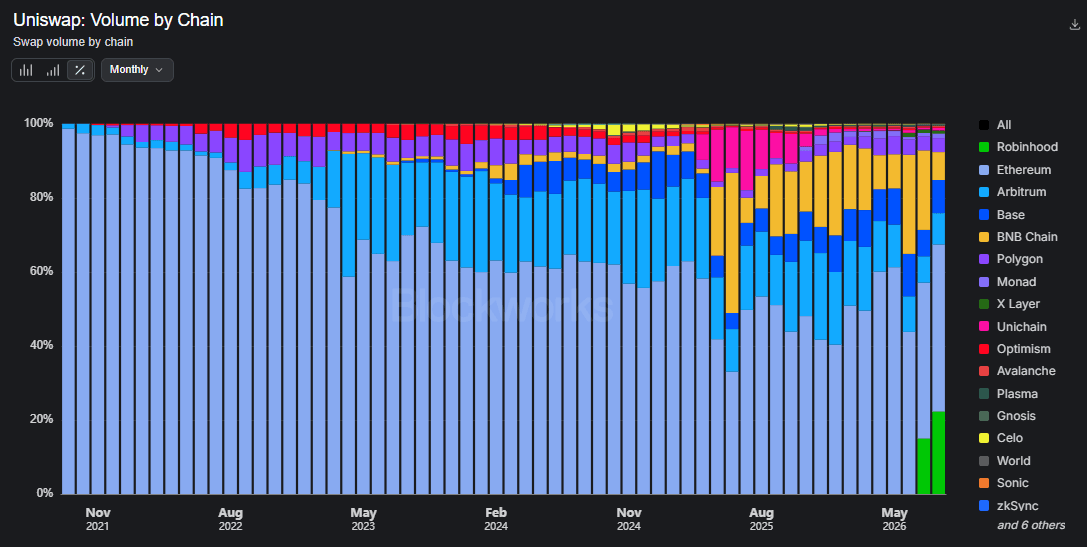
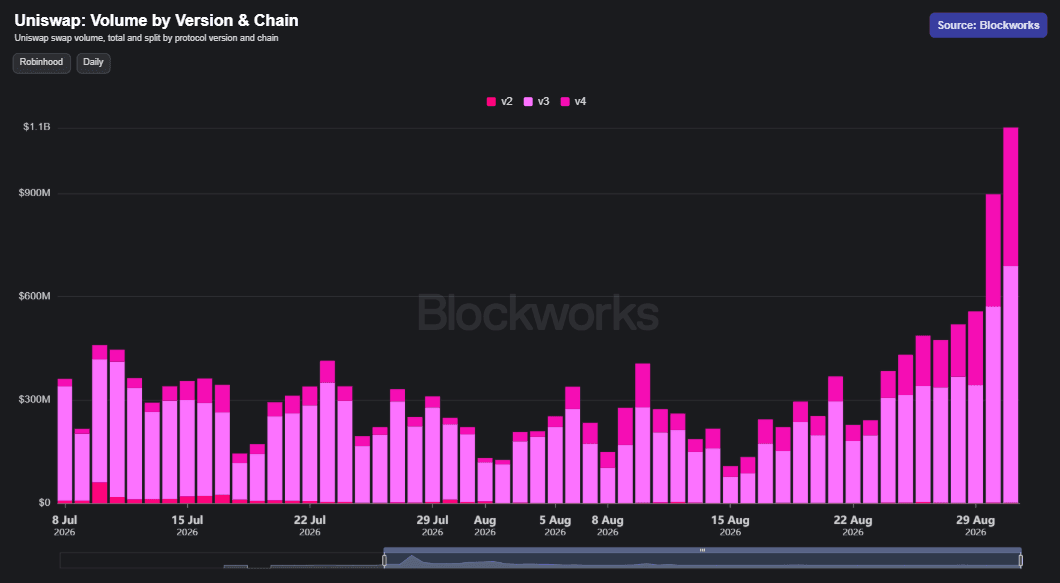
Robinhood has moved even faster. Just two months after launch, the chain accounted for 22% of Uniswap’s August volume. Daily volume crossed an average of $1B over the final week of August as tokens such as PONS and AI created a wealth effect that brought more traders and capital onto the chain.
A lot of that speculation has spilled into tokenized equities. Memecoins paired against stocks became one of the dominant trades in the trenches, helping tokenized equities generate $220M of Uniswap volume on the final day of August. Robinhood accounted for 87% of it.
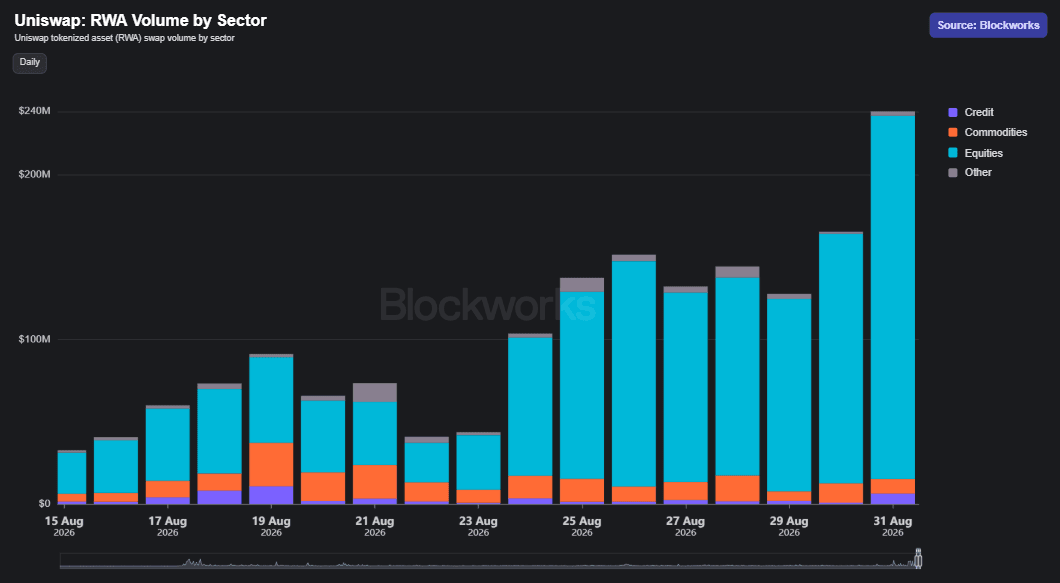
With 92% of DEX volume on Robinhood, Uniswap has captured almost the entire wave. If Robinhood remains a hub for speculative activity, Uniswap could play a role similar to Pumpfun on Solana by becoming the main venue that benefits regardless of which individual tokens win. For now, Robinhood is the most important short-term driver of Uniswap’s growth.
V4 Opens the Next Market
Earlier versions of Uniswap focused on making token swaps more flexible and improving how efficiently LP capital was used. V4 goes further by allowing developers to add custom logic directly to a pool through hooks.
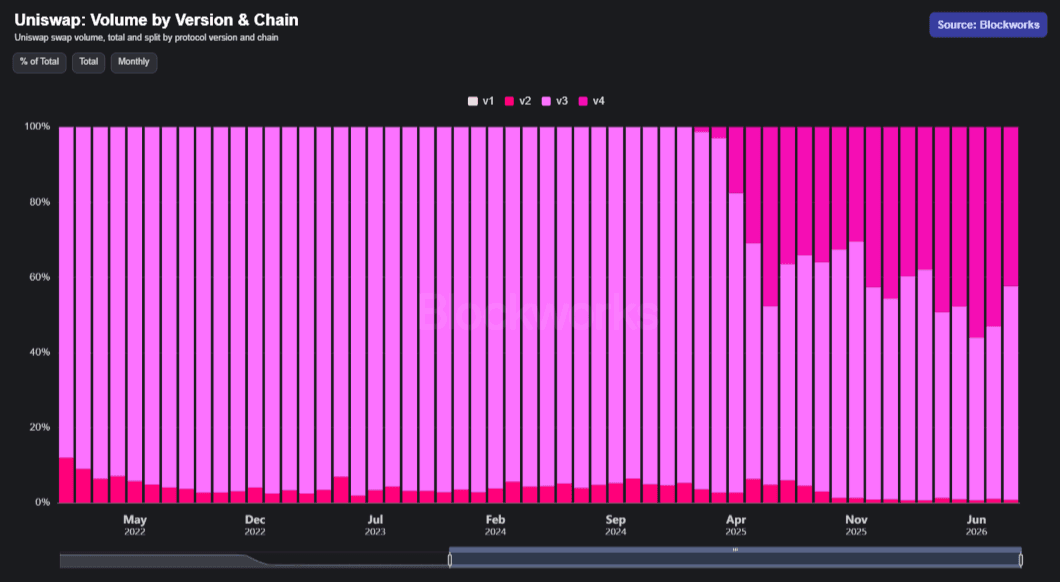
Adoption has grown steadily since v4 launched in February 2025. It has now surpassed v3 in recent months and accounts for 54% of Uniswap volume on Ethereum. The transition has been slower elsewhere, with v4 accounting for 12% of volume on Base and 27% on Robinhood.
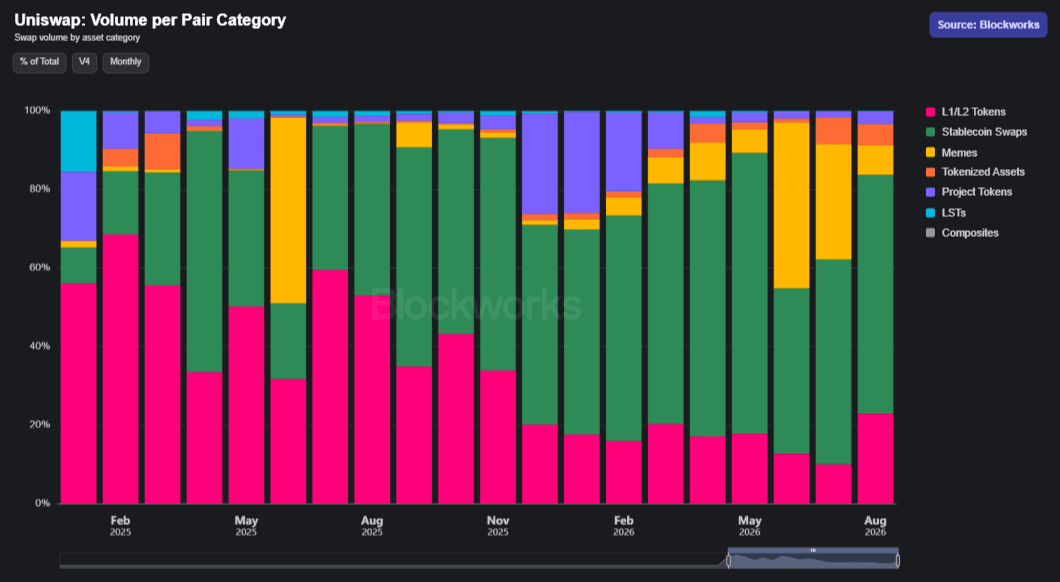
The mix of activity also varies considerably from month to month. Memecoins and stablecoins accounted for 52% and 29% of v4 volume respectively in July. The share from memecoins then fell to 8% in August.
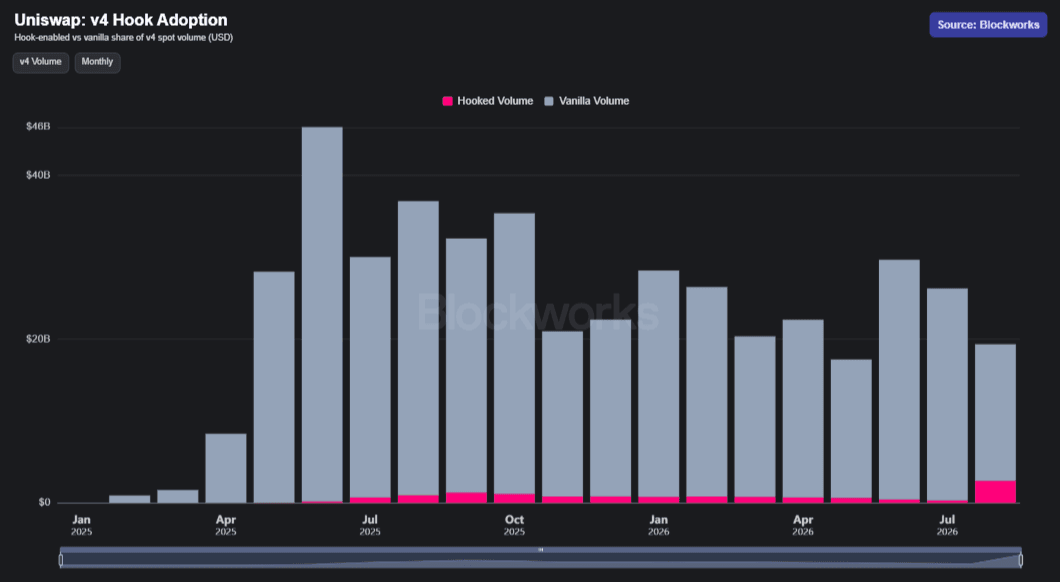
Most v4 activity still comes from vanilla pools. Hook volume accounted for around 1% of v4 volume in most months before rising to 14% in August. Some of this increase came from pools showing clear signs of wash trading, so the August surge should be treated cautiously.
For now, stablecoins provide the clearest evidence that a major category can move to v4 at scale.
Why Stablecoin Moved to V4
Among stablecoin markets, eight of the ten largest pairs by volume on Uniswap v4 over the past 30 days were stablecoin pairs.
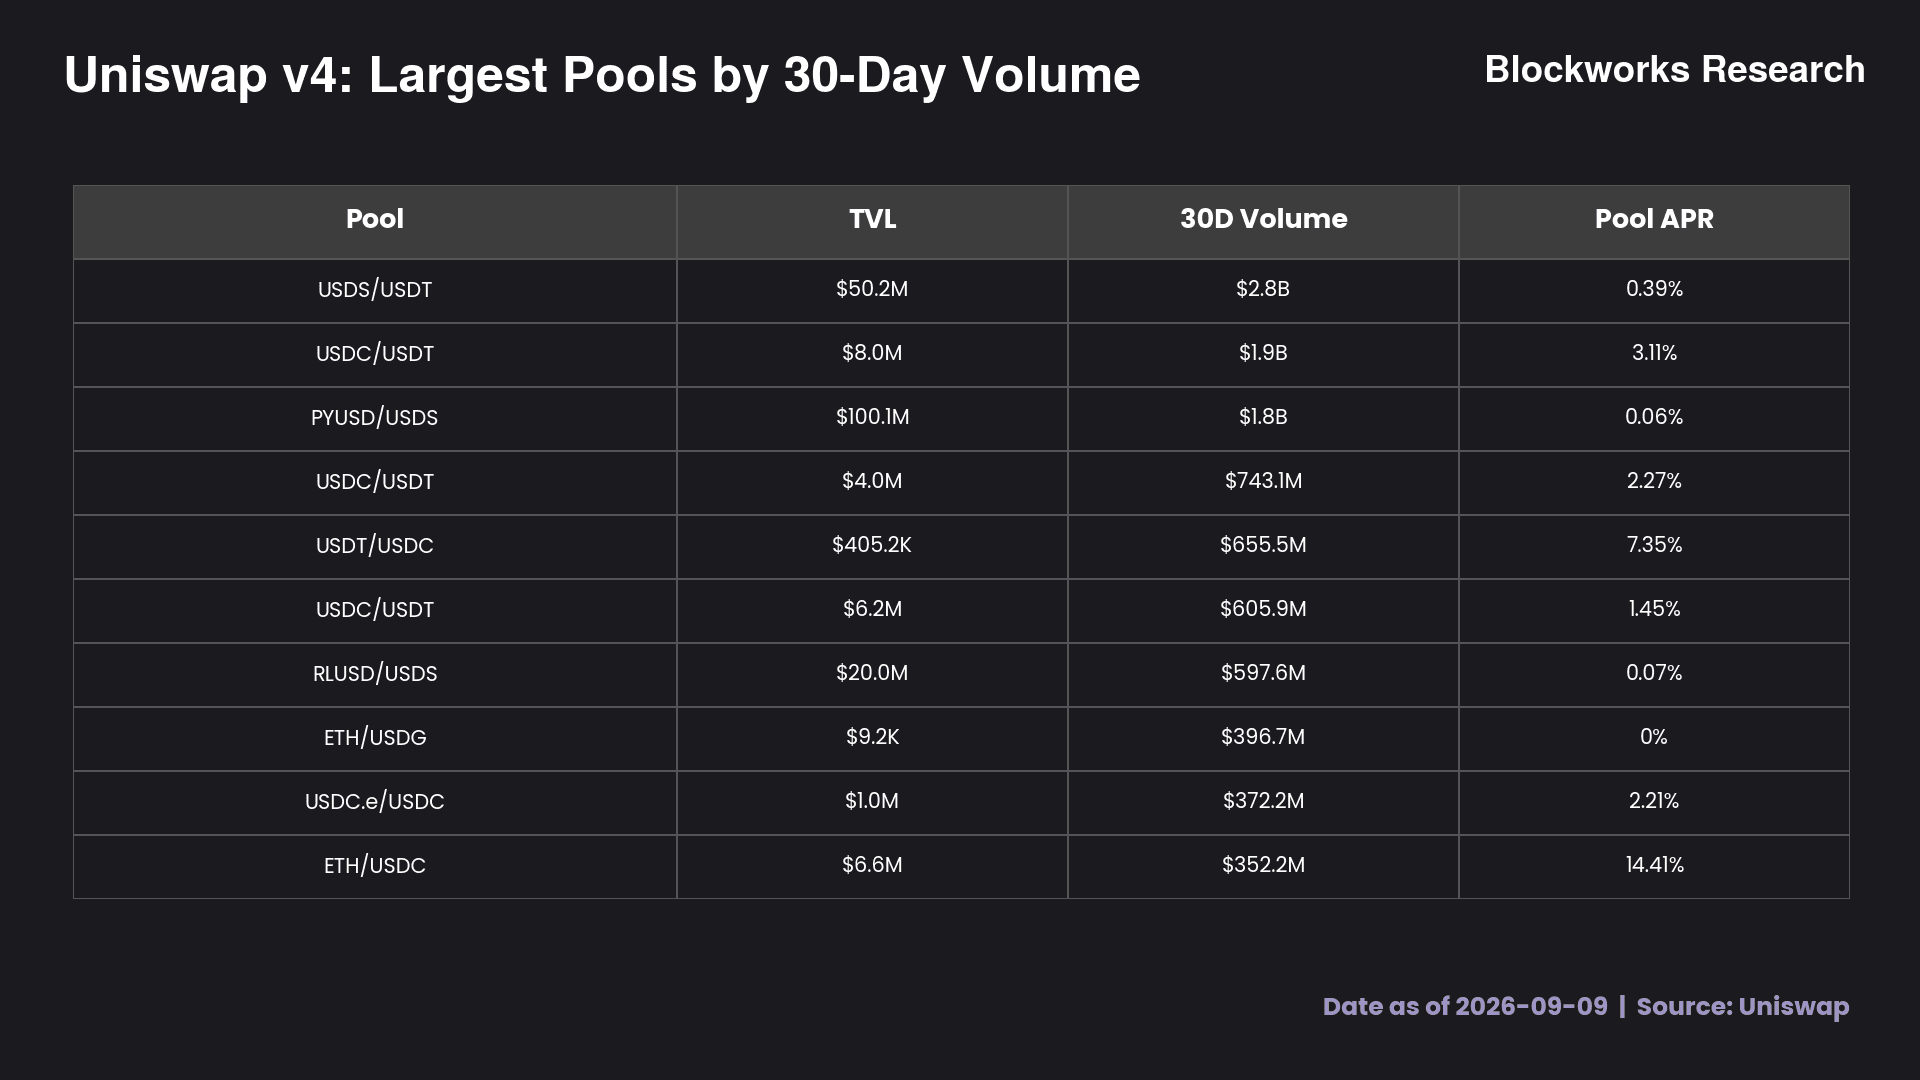
Stablecoin volumes dominate Uniswap v4 because stablecoin trading is highly sensitive to execution costs, and v4 is particularly well suited to minimizing them. V4’s flexible fee design enables ultra-low fee pools. As shown in the table above, major stablecoin pairs on v4 charge fees of roughly 0.0005%-0.0008%, compared with 0.01% for the lowest fee tier on v3.
On top of this, v4’s singleton architecture and flash accounting reduce the cost of routing trades across multiple pools. This is particularly useful for Uniswap’s router and outside aggregators, which direct trades toward the best available route. Around 40% of Uniswap volume came through these channels in July and 20% in August, with most of that flow going to v4.
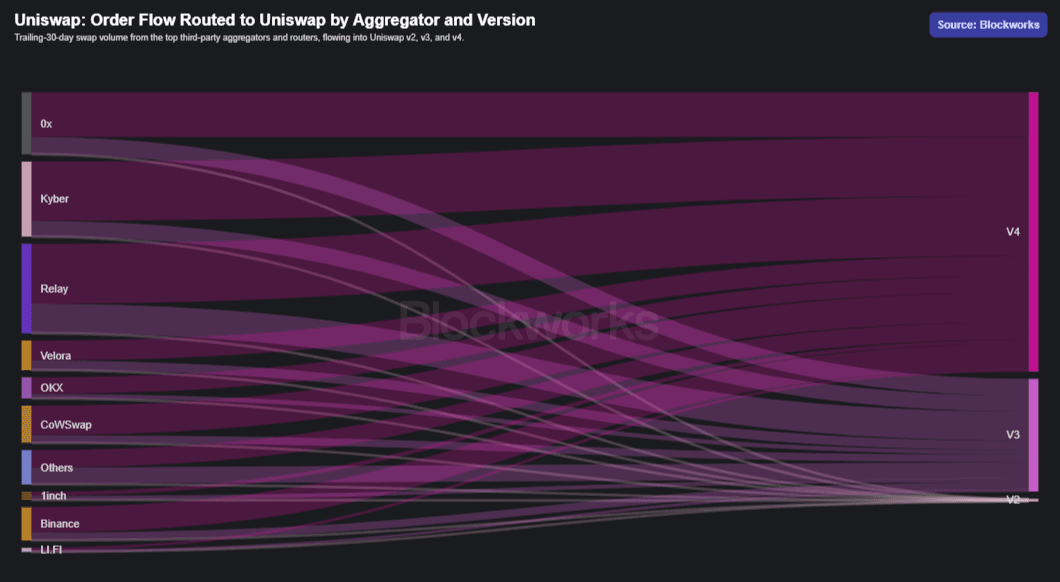
Lower fees and cheaper routing have made stablecoins one of the first use cases to move to v4 at scale. Hooks could now expand v4 beyond conventional token swaps.
What Developers Are Building With Hooks
Hooks allow developers to add their own rules to how a pool charges fees, manages liquidity and executes trades. Features that previously required a separate protocol can now be built directly into a Uniswap pool.
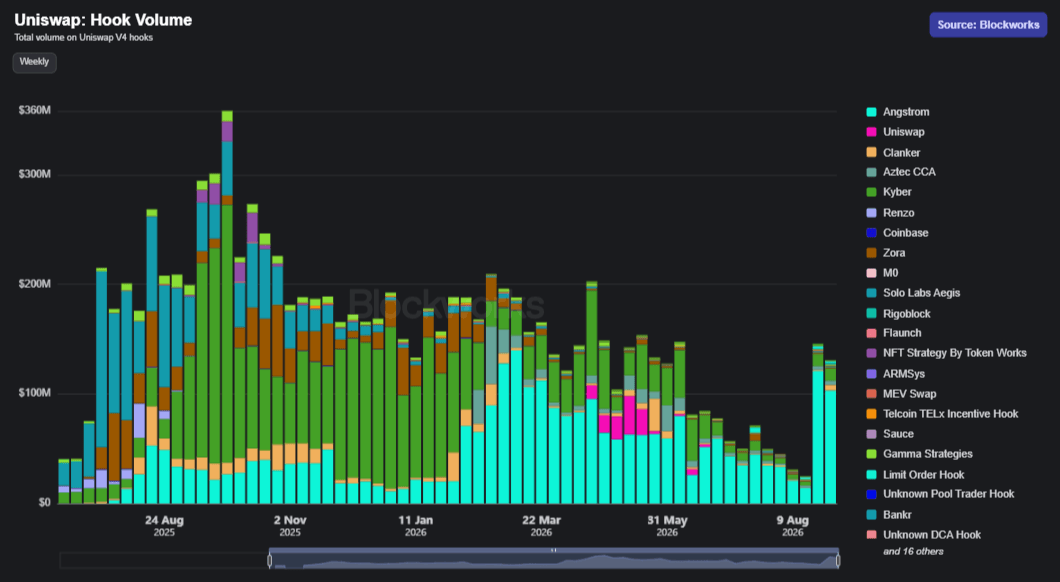
MEV internalization: Angstrom and Kyber use v4 hooks to capture some of the value that would normally go to arbitrage bots and redirect it back to LPs. Angstrom does this by charging an MEV-related fee during swaps, while Kyber captures arbitrage profits and shares them with liquidity providers.
Dynamic fees: AEGIS adjusts fees as market conditions change, charging more when volatility increases and LPs take on greater risk. It can also direct a share of fees into protocol owned liquidity, helping deepen the pool over time.
Token launches: Clanker uses hooks to manage token launches, fee splits and MEV protection while relying on Uniswap as its trading layer.
Application-specific markets: Unipeg goes in a different direction by linking trades to the creation of generative onchain art, turning the pool into part of the application itself.
This flexibility has started to appear in a new group of speculative projects. Fake World Assets, Stonkbrokers and NetNet Capital have all used v4 hooks to create products that look very different from a conventional AMM. Flaunch and Pons v2 are also using them to build memecoin markets paired against tokenized stocks.
These projects are still early and have yet to generate enough organic volume to move Uniswap as a whole. However, they allow Uniswap to benefit from new experiments without having to build each application itself. Developers bring the product and custom logic, while Uniswap provides the liquidity layer underneath it.
If speculative activity remains strong, we believe that these launches could begin competing with conventional memecoins for capital and attention. The larger opportunity in the long run, however, comes from applying the same flexibility to tokenized assets that can support more durable trading demand.
Bringing More Traditional Assets Onchain
Tokenized assets accounted for 8% of spot DEX volume in August, but much of the recent growth on Robinhood has still been tied to speculation. Turning that early activity into a lasting market will require products designed around the liquidity, compliance and pricing needs of traditional assets. V4 gives Uniswap several ways to address those constraints.
Permissioned Pools
Uniswap recently introduced Permissioned Pools using v4 hooks. These pools allow compliance rules to be enforced directly at the pool level, including checks on whether a wallet is approved to trade or provide liquidity.
These controls matter for tokenized funds, equities and securities, where issuers may need to enforce KYC, investor eligibility and transfer restrictions. Permissioned Pools give regulated assets access to onchain liquidity while allowing issuers to retain those safeguards.
The involvement of firms such as Superstate and Securitize in developing the standard gives the model greater credibility. If more regulated assets move onchain, Permissioned Pools could open a new source of volume that was previously difficult for Uniswap to serve. However, as more assets move onchain, Uniswap will need enough liquidity for investors to trade them efficiently.
Correlated Asset Pairs
As Hayden Adams recently argued, tokenized assets do not need to trade only against dollars. Stocks can trade against indexes, while gold can trade against silver. Because these assets tend to move together, their relative prices fluctuate less than they would against dollars. This can reduce impermanent loss for passive LPs and lower hedging costs for professional market makers.
Investors could still enter and exit through USDC because routing happens automatically. A trade from USDC into Nvidia could first move through a deep USDC to SPY market before being routed through a Nvidia to SPY pool.
This reduces the need for every stock to maintain its own deep dollar market. Passive LPs could provide liquidity to correlated pairs with less exposure to relative price divergence, while professional market makers focus on the smaller number of bridge pools carrying most of the volume.
The model is already being tested on Robinhood. Tokenized stocks paired against SPY generated close to $20M in volume on September 1, with many trades moving directly between stocks rather than passing through dollars.
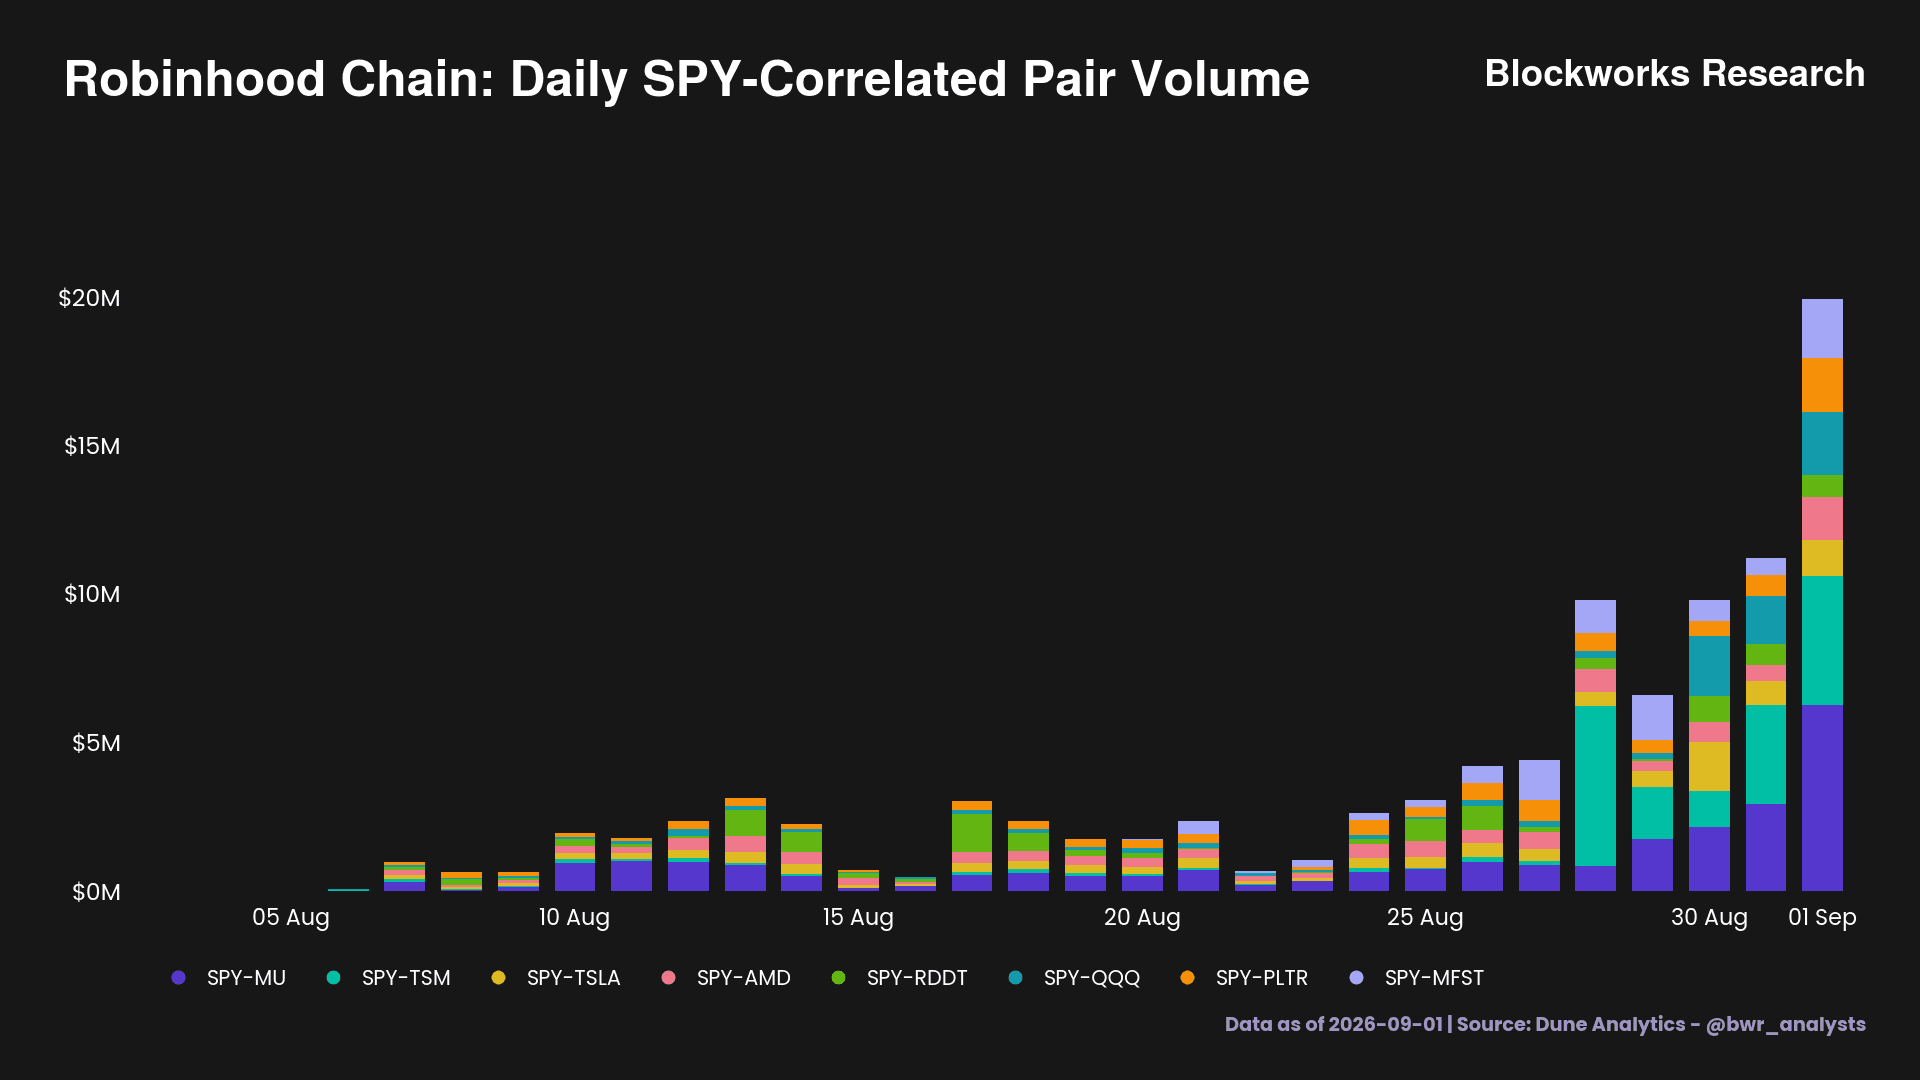
The high early APRs also show that LPs are being paid well to seed these markets, although those returns will likely fall as more liquidity arrives.
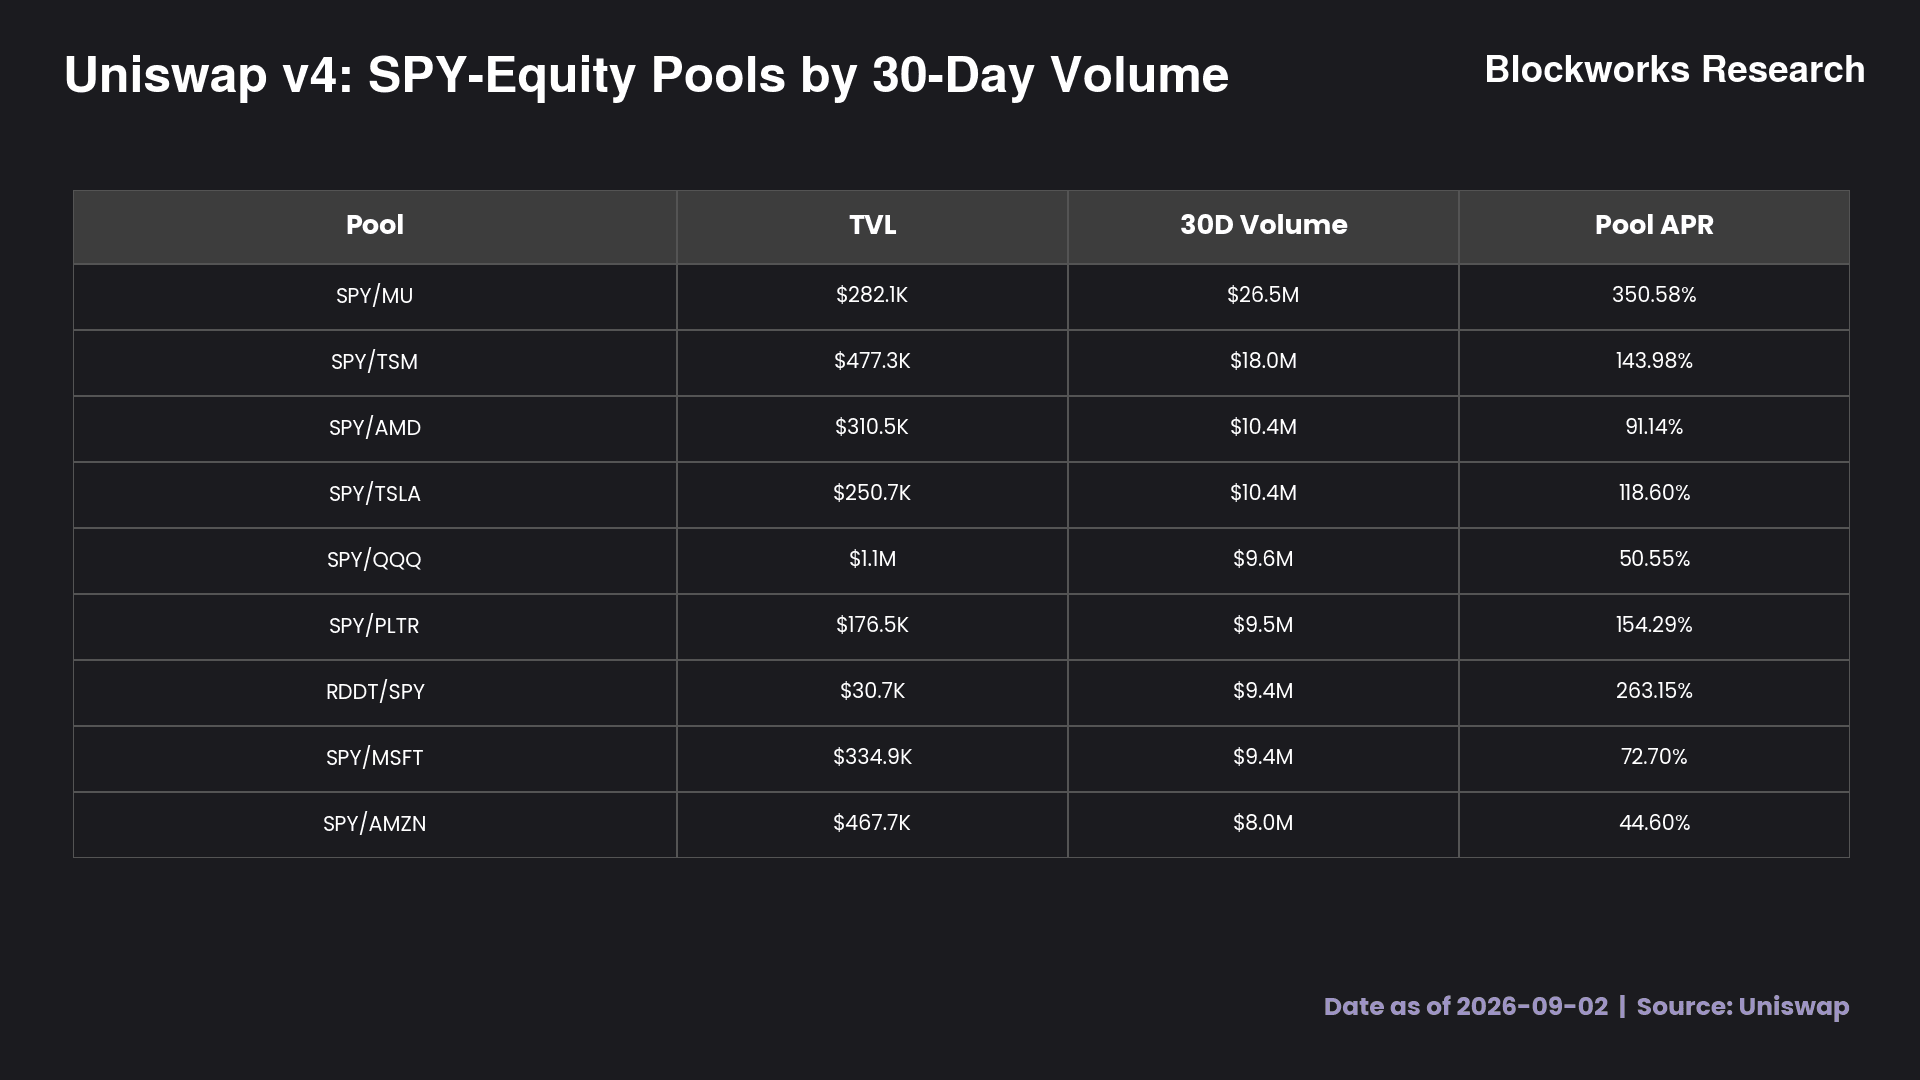
Most of these markets currently use vanilla v4 pools. Hooks could eventually add dynamic fees or move idle liquidity into lending strategies when it is not being used for swaps. If this reduces the cost of market making and helps create deeper pools, tokenized assets could become a more durable source of v4 volume. While Uniswap has the early lead, it will not have this market to itself.
The Leader Has Kept Changing
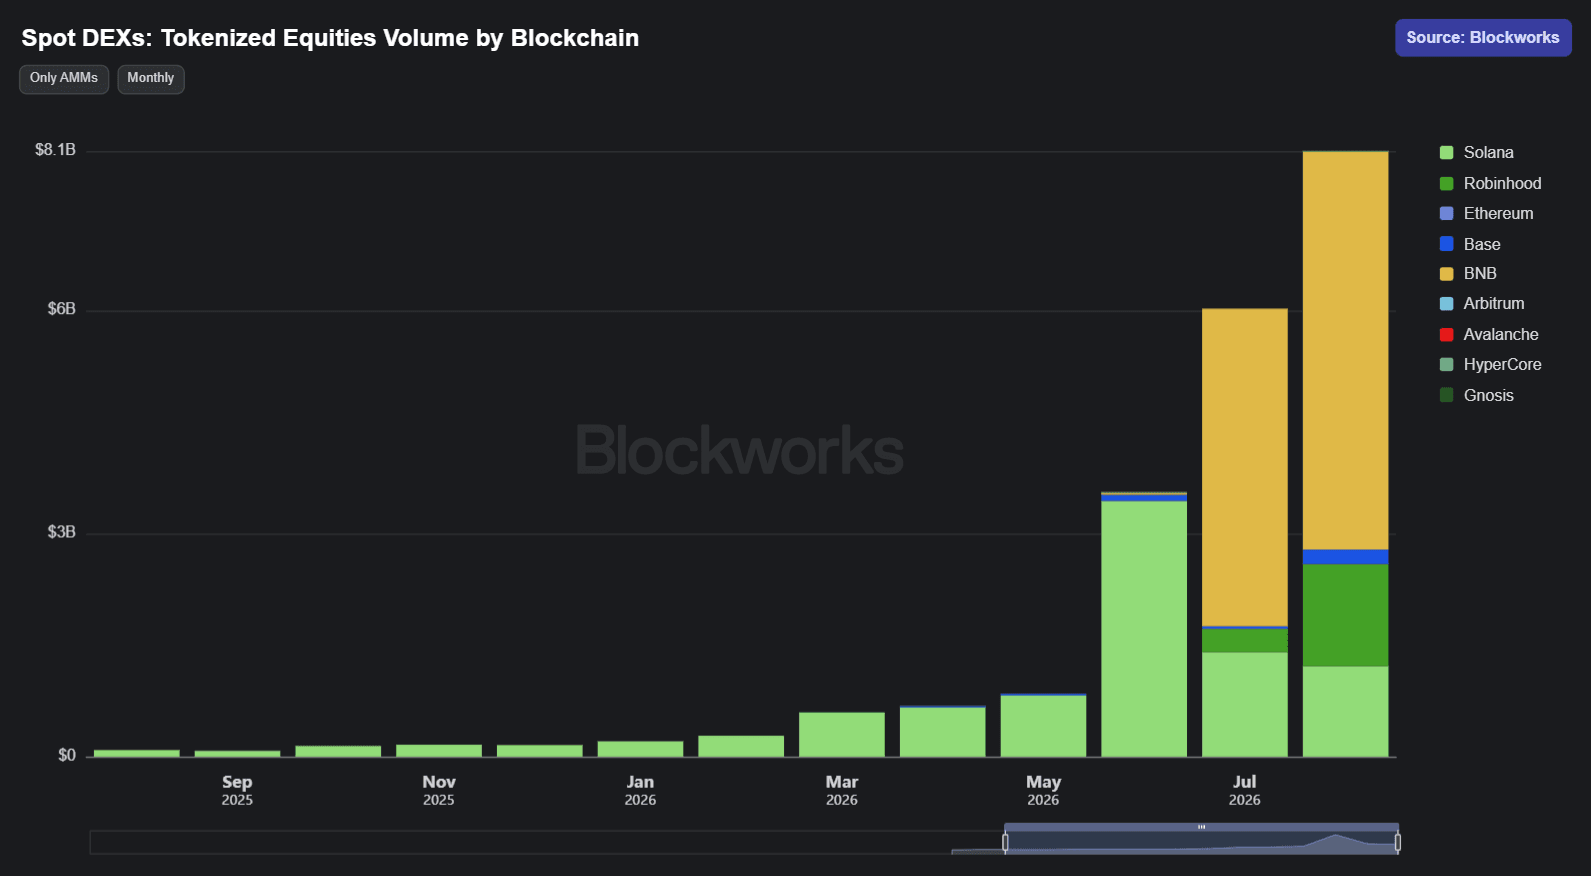
Uniswap has an early lead on Robinhood, but tokenized equity volumes have moved quickly between chains. Solana drove most of the activity through June, before BNB Chain became the largest market in July and August. Robinhood has since gained share as trading between memecoins and tokenized equities picked up.
This rotation shows how early the market still is. Liquidity has followed new listings and pockets of user activity rather than settling around one chain or venue.
Beyond the AMMs, Hyperliquid could become one of Uniswap’s strongest competitors for tokenized spot volume. XStocks recently launched five tokenized equities and ETFs as native spot markets on HyperCore, including NVDAx, SPYx and QQQx.
These assets trade through an onchain order book with visible depth, limit orders and price time priority. This structure is more familiar to professional traders than an AMM, although early traction has been slow. XStocks generated just $7M in spot volume on Hyperliquid during its first 21 days.
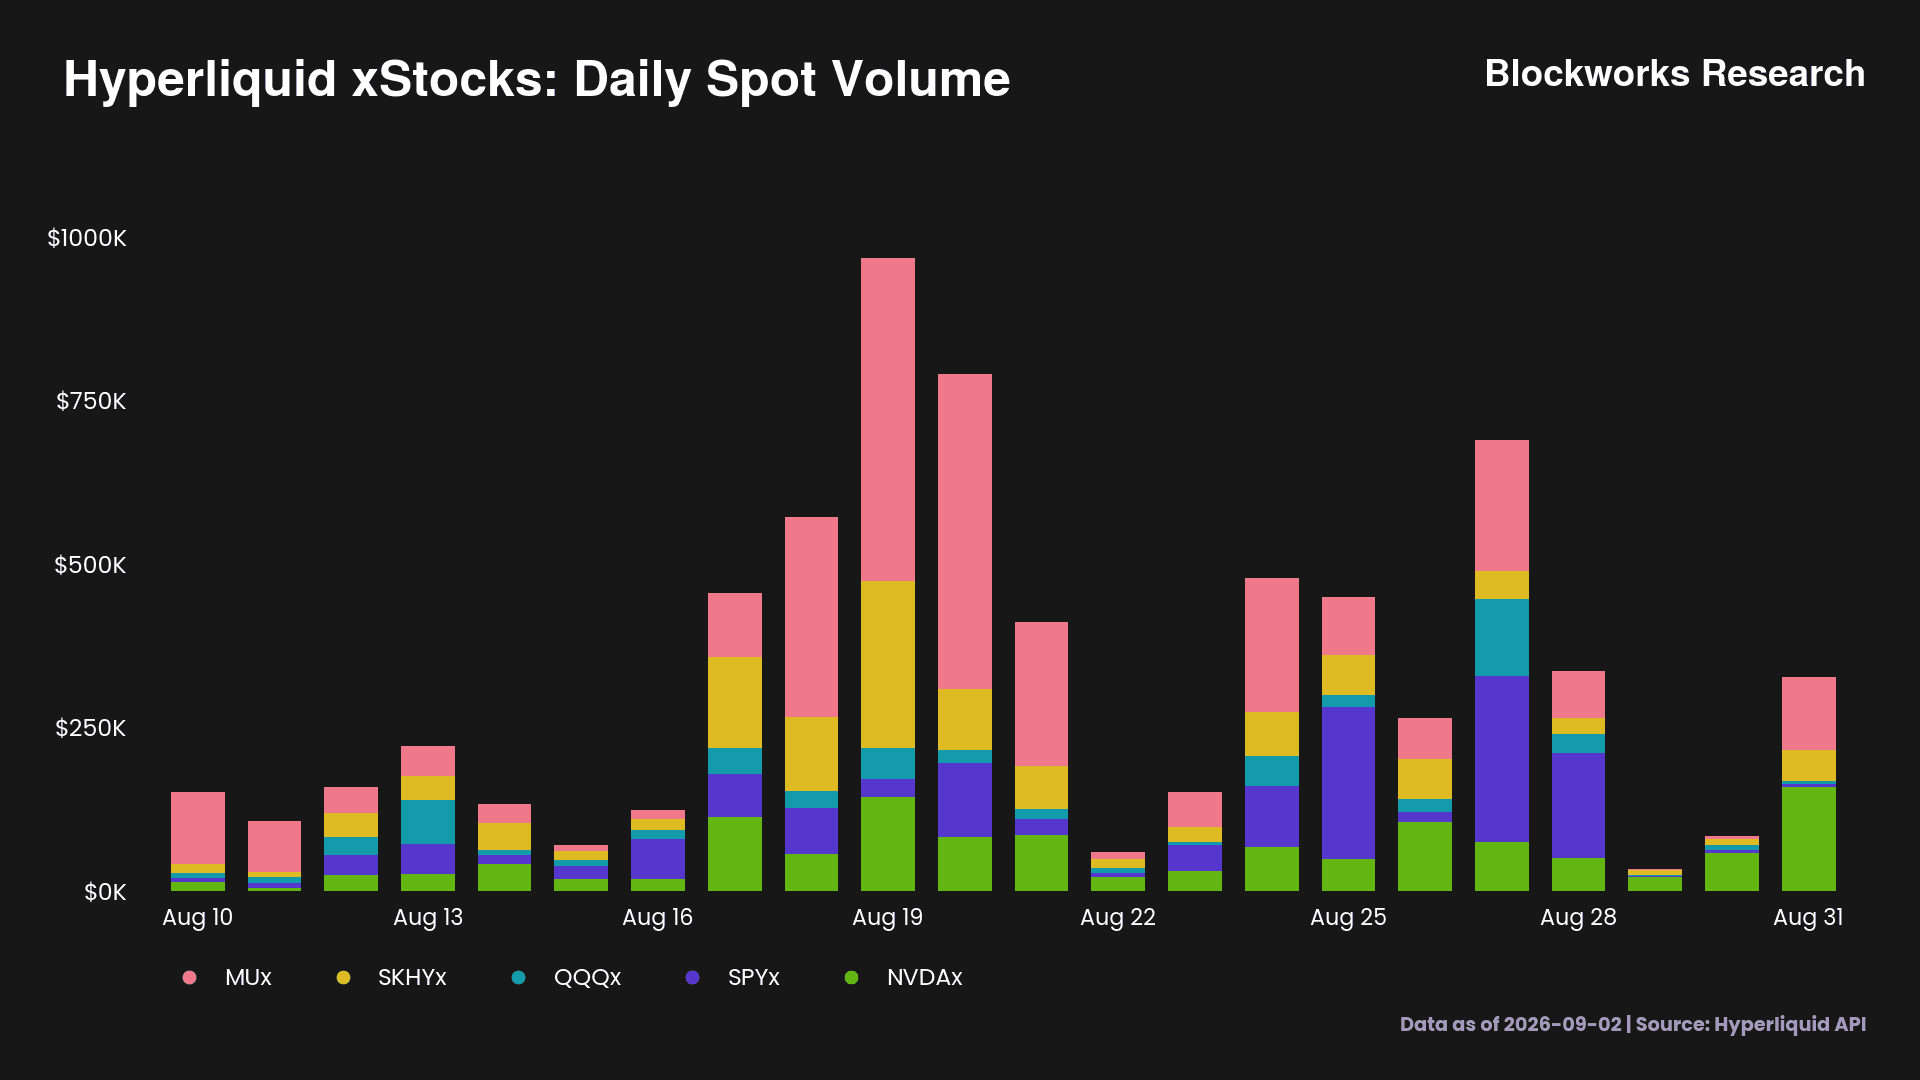
Uniswap processed $1.6B in equity volume over the same period, giving it a clear early lead, but Hyperliquid’s threat comes from the rest of the platform it is building around these assets.
Star gating on the HIP 3 testnet allows deployers to restrict the opening or increasing of positions to approved wallets. The feature currently applies only to HIP 3 markets, but it shows how regulated operators could introduce KYC at the deployer level while leaving the rest of the platform permissionless. This could provide an alternative to the permissioned pools being developed through v4 hooks.
Tokenized spot assets could also sit alongside HIP 3 perpetuals and HIP 4 outcome contracts. Traders would then be able to buy an asset, hedge it and construct more complex strategies through one platform. That experience more closely resembles an integrated broker than a standalone exchange.
It is too early to call a winner. Leadership has already rotated between chains, and the market should be large enough to support several venues. Uniswap has the liquidity advantage today, but will need to turn its early volumes into deeper markets and better applications to maintain that lead.
The Path to Monetization Has Opened
This growth carries more weight for UNI now that the fee switch is live. Uniswap spent years processing some of the largest volumes in crypto without passing any of its trading fees to the protocol. That has started to change.
The fee switch first went live in December 2025 across v2 pools and selected v3 pools on Ethereum mainnet. During 2026, it was expanded to the remaining v2 and v3 pools on chains including BNB Chain, Base and Arbitrum. Uniswap governance also moved quickly to monetize the spike in activity on Robinhood, activating protocol fees less than a month after the chain launched. Fees were also introduced more selectively on v4, covering vanilla pools, continuous clearing auction pools and aggregator hook pools from July 27.
Daily UNI burns have since approached $600,000. During August, $9.3M of UNI was burned, with Robinhood accounting for 45%. The same speculative activity that pushed Uniswap’s volumes higher has therefore become a major source of demand for UNI.
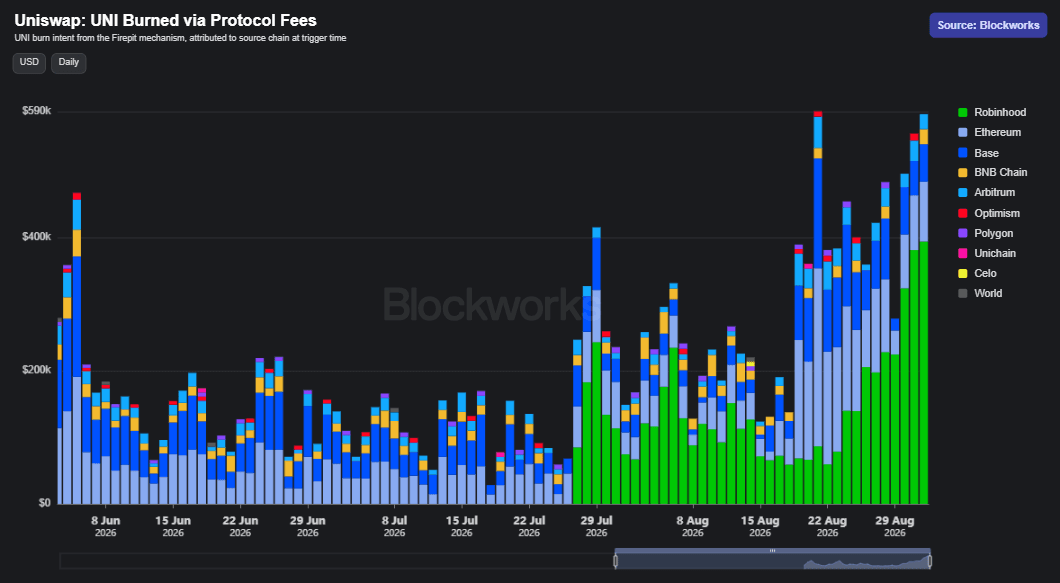
Annualising August burns implies around $111.6M of annual buybacks, equivalent to 18.6M UNI at current prices or roughly 3% of circulating supply. Uniswap’s annual growth budget is 20M UNI, so burns at the August run rate would offset most, but not all, of the new emissions.
Has the Fee Switch Hurt LPs?
The main argument against the fee switch was that it would reduce LP returns. If enough liquidity moved elsewhere, traders would face worse execution and Uniswap could lose volume to competing DEXs.
The impact depends on which version of Uniswap is being used. For v2 and v3 pools, protocol fees are taken from the total pool fees and reduce the share received by LPs. An example of this can be seen below from Uniswap’s documentation.
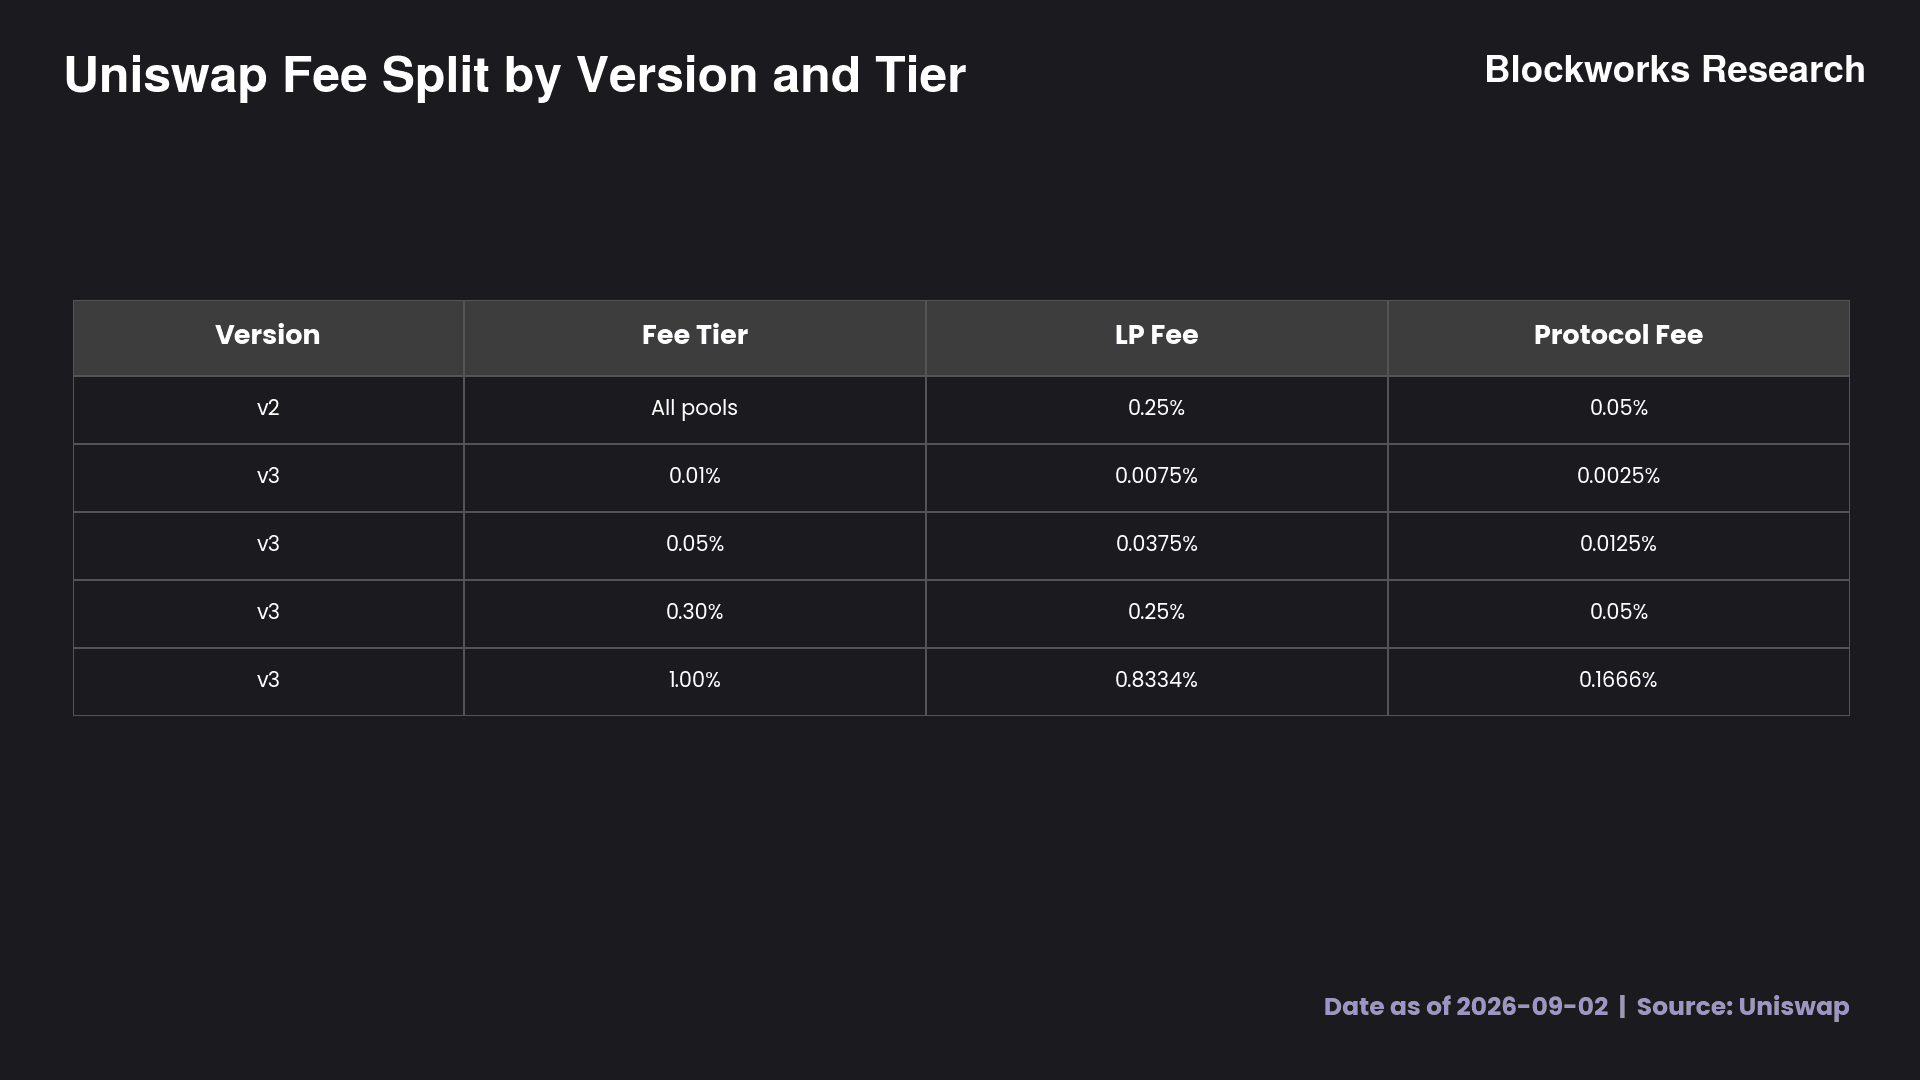
However, V4 uses a different formula.
S = F + P − floor(F × P / 1,000,000)
S is the total fee paid by the trader, F is the LP fee and P is the protocol fee. The final term is the only reduction to the LP cut, and it is a rounding scale amount. LPs retain almost all of the fees, while traders bear almost all of P.
V4 therefore gives Uniswap a way to monetize activity without directly taking the protocol fee from LPs. The tradeoff is that traders pay more, which could still push volume elsewhere if competing venues offer better execution. The early data provides a useful test.
What Happened on Base
Uniswap’s volume on Base fell sharply after the fee switch, dropping from around $370M to $26M. On the surface, this appears to support the argument that higher fees drove traders away.
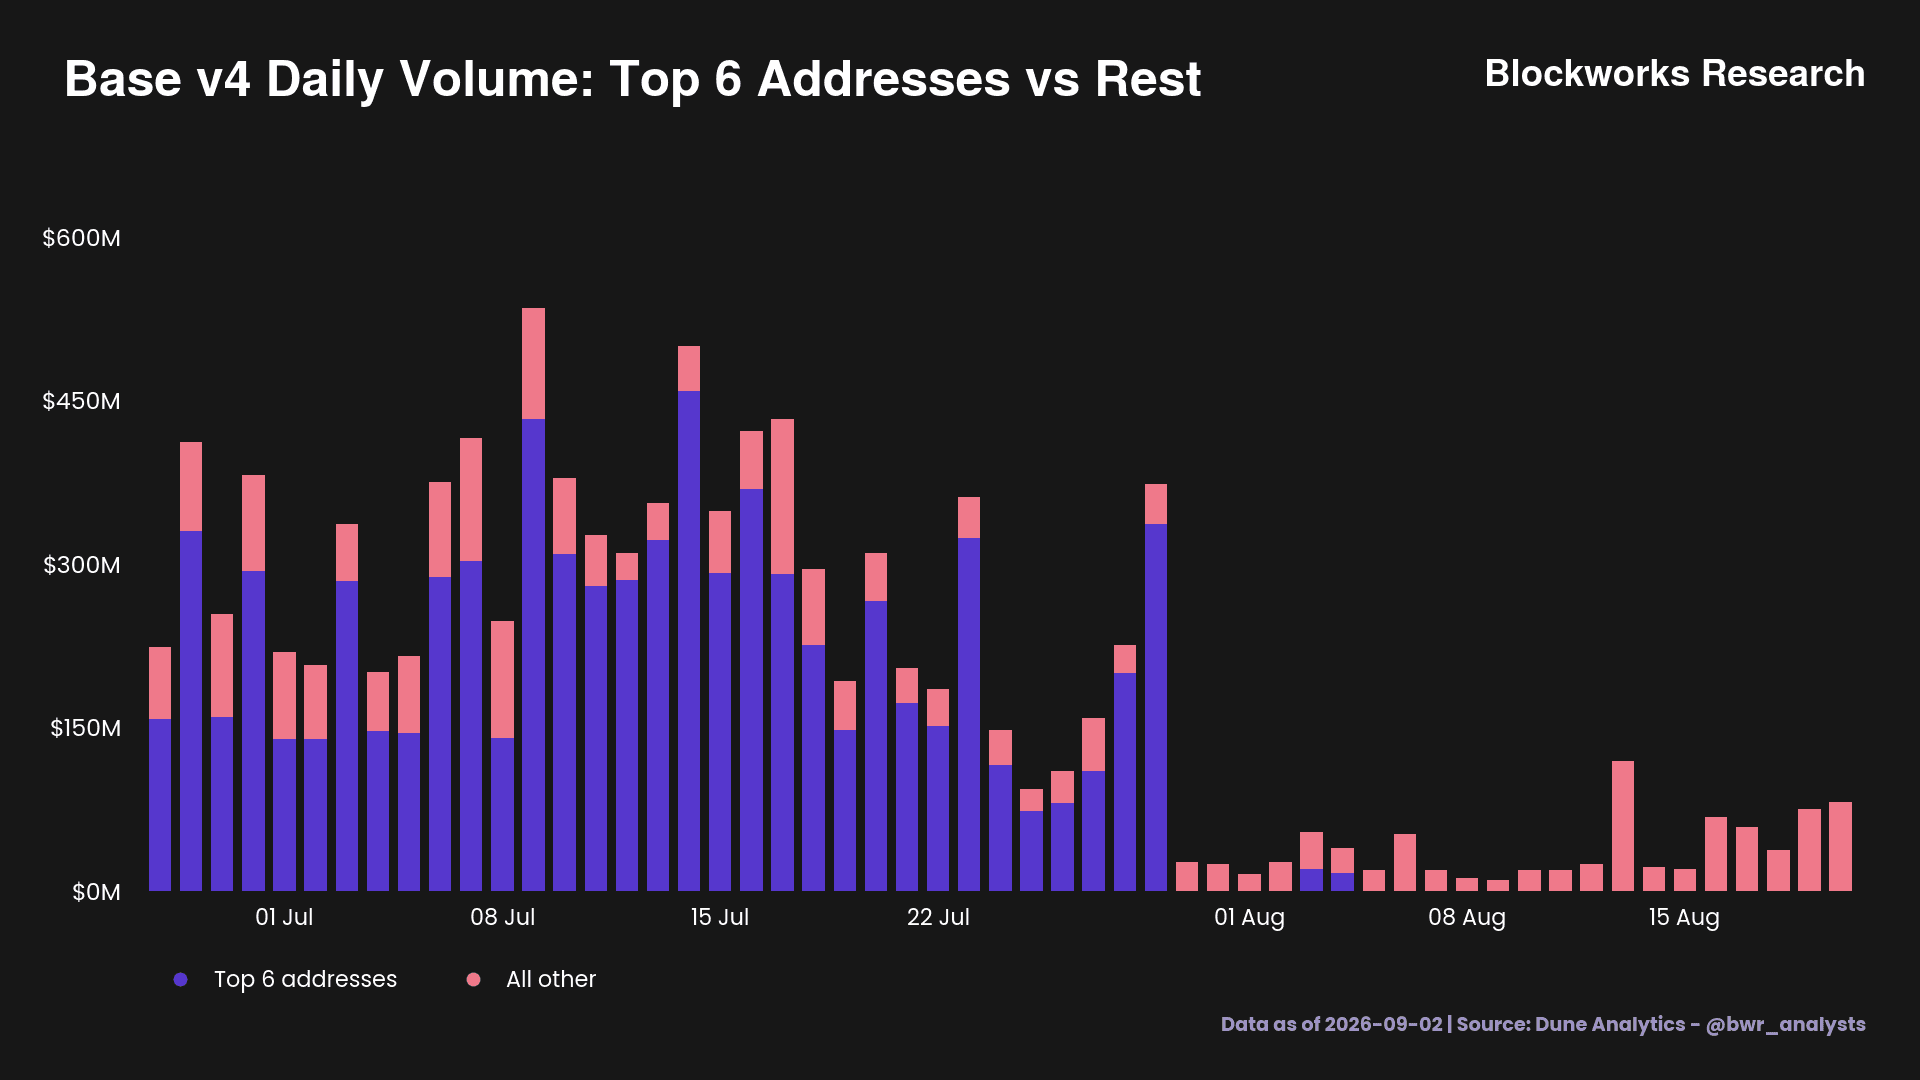
However, most of the lost volume was not organic. Before the fee switch, six traders accounted for 90% of Uniswap’s Base volume, with 53% of them coming from a fake OpenAI/USDC pair. The median time between swaps was six seconds, which is consistent with high frequency wash trading. Post the fee switch, since traders incurred an additional cost to swap that did not go to LPs, it became unprofitable to run this bot, causing there to be a sharp drop in volumes.
The fall in headline volume therefore says little about whether regular traders abandoned Uniswap. It mainly shows that the fee switch removed activity that produced impressive volume figures without adding much economic value.
Liquidity and Execution Have Held Up
Liquidity has also remained resilient since most of the fee switches went live in late July. TVL across Uniswap’s largest chains has increased alongside the broader market rather than moving to competing venues.
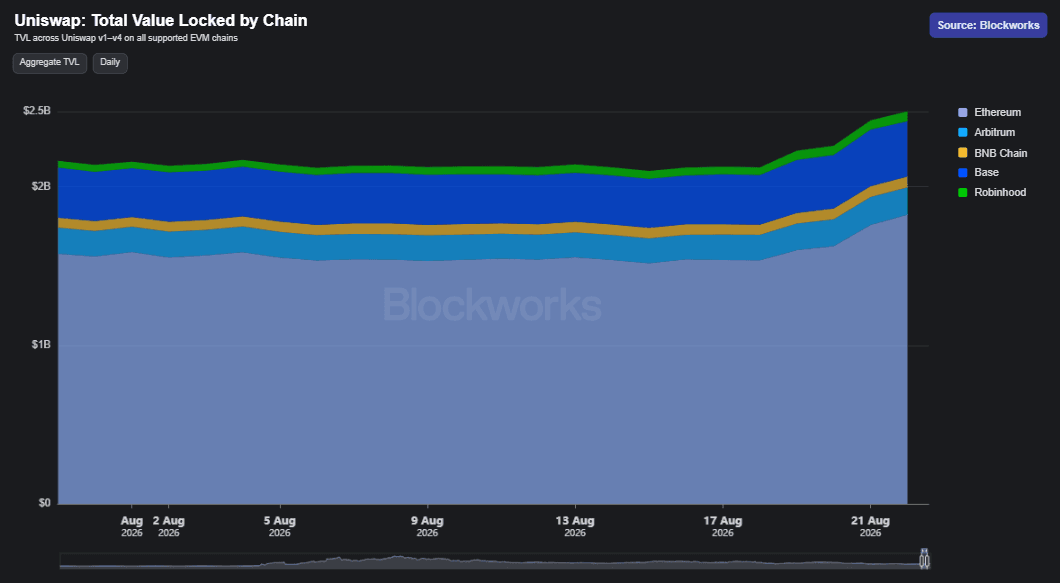
Execution quality has continued to improve as well. Price impact across different trade sizes has fallen for native asset to stablecoin pairs and for stablecoin to stablecoin pairs.
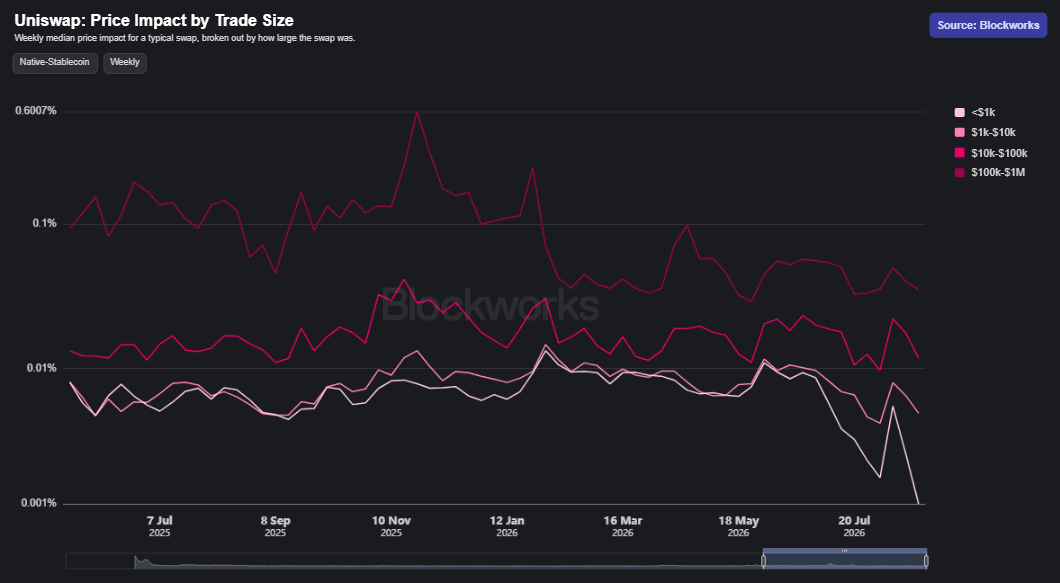
Together, these categories account for around 70% of Uniswap’s volume.
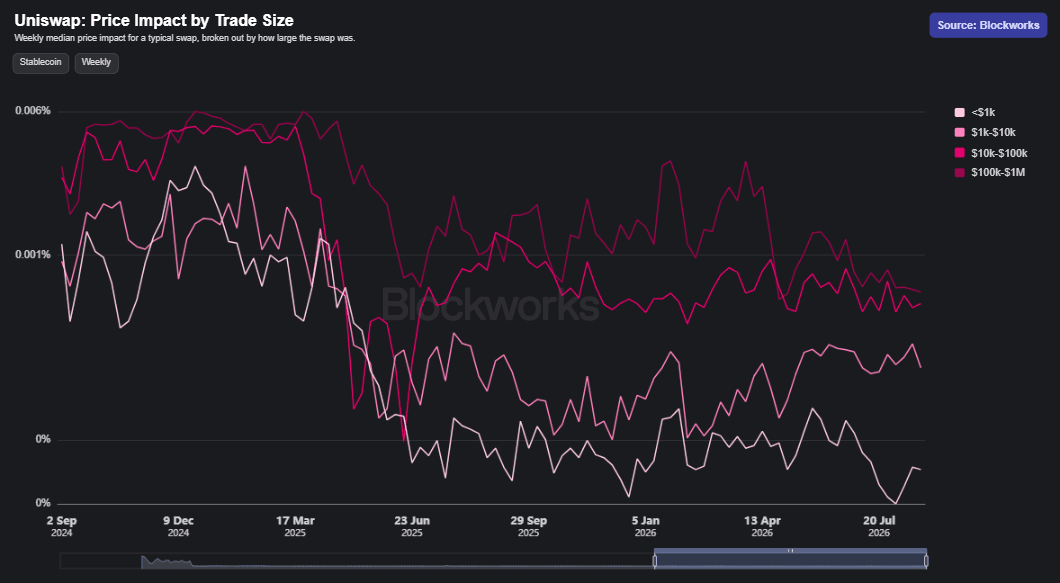
So far, there is little evidence that the fee switch has made LPs sufficiently worse off to withdraw capital or caused traders to receive worse prices. LPs have remained, execution has improved, and Uniswap is finally generating protocol revenue. A rare win, win, win situation across all the parties involved.
What UNI Is Pricing In
Uniswap trades at a premium to the average and median revenue multiple of other DEXs and several leading revenue generating protocols. That premium is understandable. Uniswap remains the dominant DEX, has maintained its position across multiple cycles, and now controls most trading activity on Robinhood.
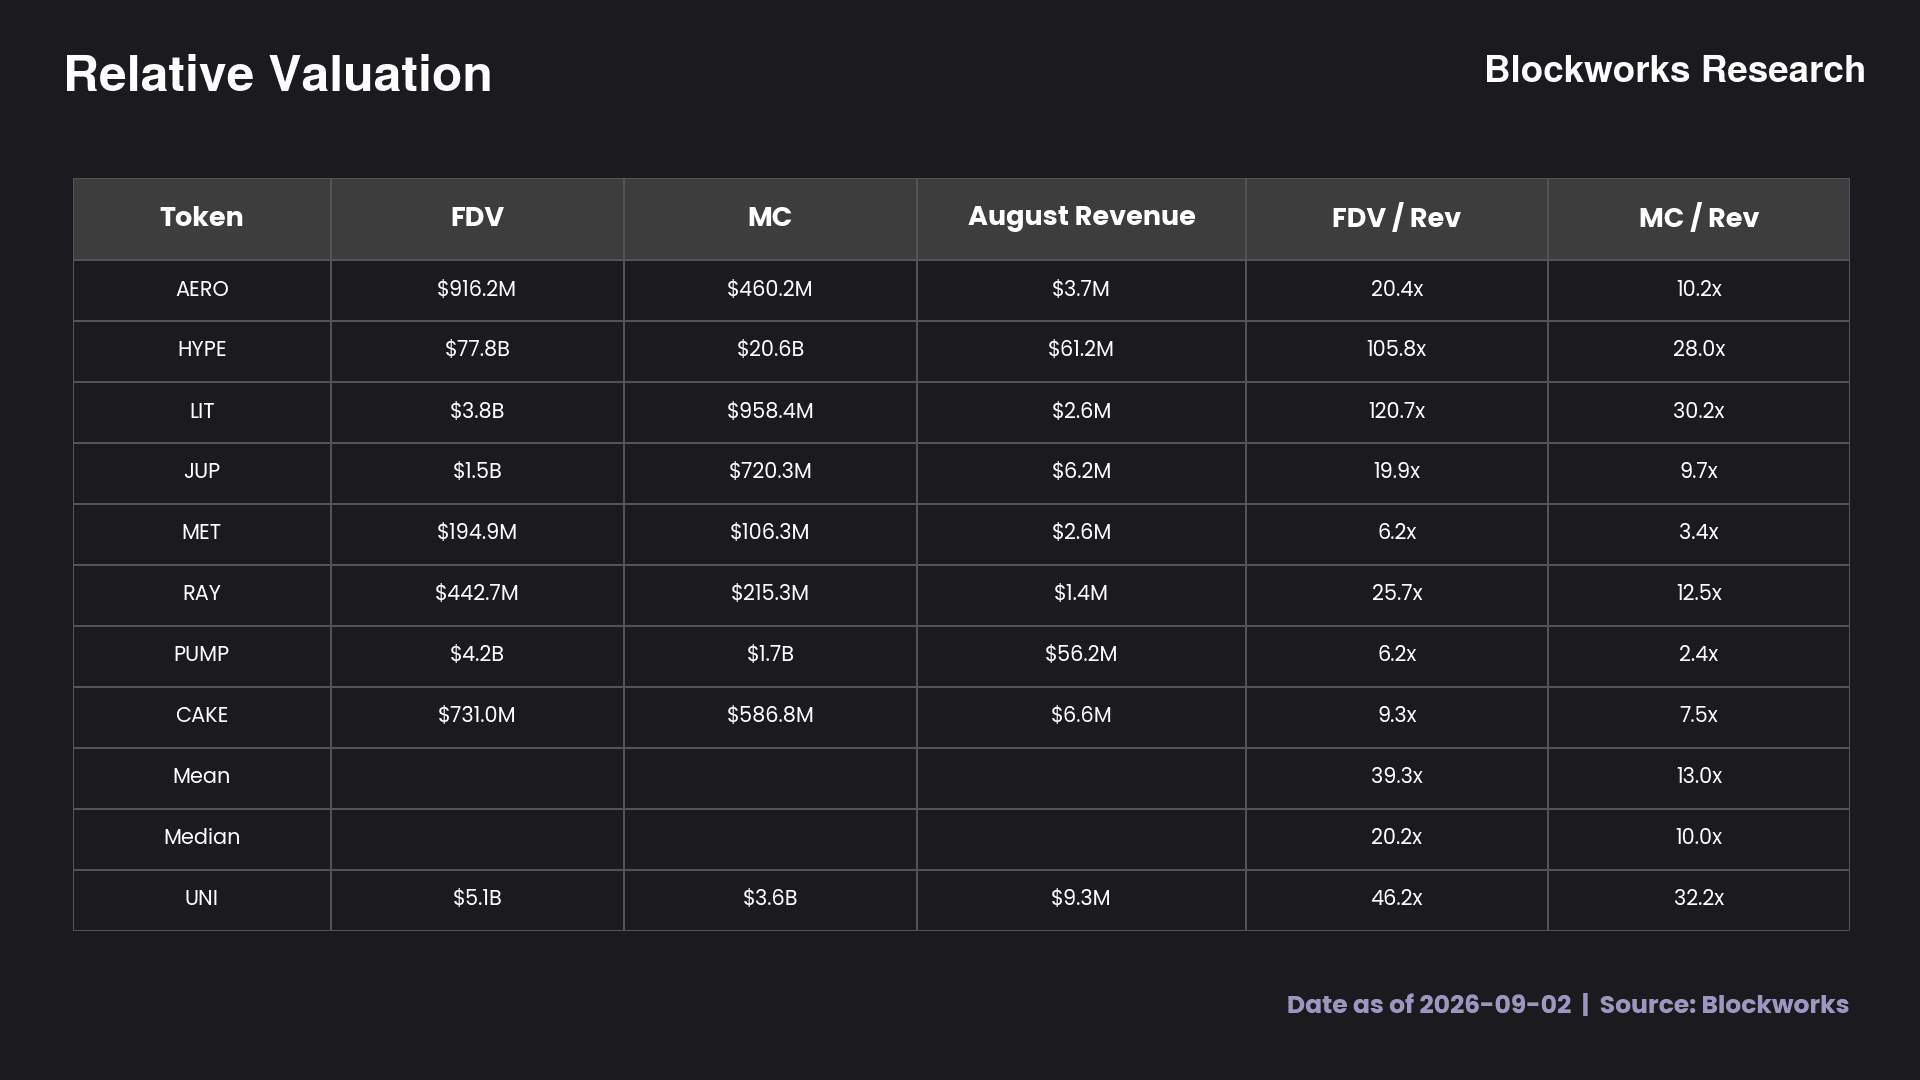
Sector leaders such as HYPE, MORPHO and PUMP also trade well above their closest competitors. The market generally assigns a higher multiple to sector leaders who have a level of moat versus their peers.
In the short term, UNI will remain closely tied to Robinhood. Memecoin and tokenized equity activity have driven the chain’s recent growth, and Uniswap captures almost all of its DEX volume. If Robinhood becomes one of the main speculative venues of this cycle, UNI should continue to benefit.
The opposite is also true. Most speculative themes cool after a few months, and a pullback in Robinhood activity would reduce both Uniswap’s volume and token burns. UNI’s premium leaves less room for this growth to disappoint.
Over a longer period, Uniswap will need to turn some of the users and liquidity brought in by speculation towards more sustainable markets. Tokenized assets provide the clearest opportunity. The recent activity has already brought equities onchain at a record scale, even if much of it has been driven by memecoins paired against stocks.
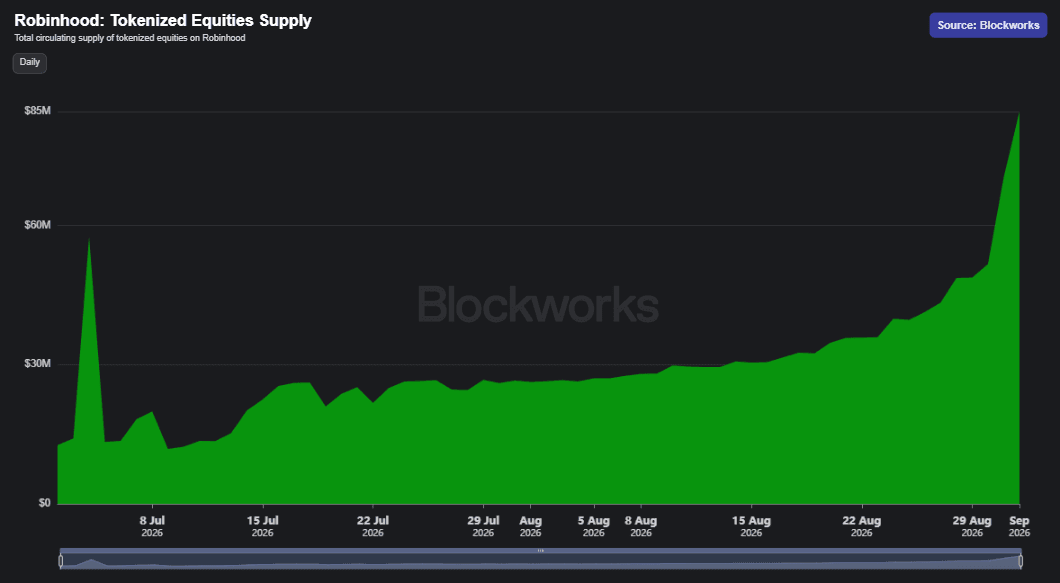
Building deep equity markets that continue trading on weekends would make that liquidity more useful. Using hooks to build or integrate lending, options and other products around the same assets could help Uniswap compete with the integrated experience Hyperliquid is working towards.
Risks
The biggest risk in our opinion is that their dominance on Robinhood will likely attract competitors. For example, Pumpfun has a financial incentive to bring its launchpad and DEX to the chain if speculative activity remains strong. Over the past 24 hours, Pons and Uniswap each generated around $1.6M in revenue, only slightly below Pumpfun at $1.94M. If Pumpfun can incentivize activity on its platform, Uniswap could lose part of the activity it currently captures.
Aerodrome presents a separate threat across the EVM ecosystem. Its planned MetaDEX 03 expansion could give LPs outside Base another venue for their capital. AERO emissions may allow it to offer higher returns across major pools, creating a stronger test of whether LPs remain on Uniswap after the fee switch.
The early evidence from Base is encouraging. Legitimate volume and TVL have held up, while execution has continued to improve. However, that data covers a short period and predates the full rollout of Aerodrome’s new mechanics and Slipstream v3.
Conclusion
Robinhood has brought Uniswap back to the centre of onchain speculation. Its dominance on the chain has driven volumes and UNI burns, while the early data suggests the fee switch has not materially reduced liquidity or execution quality.
Our thesis is that the next wave of speculation will extend beyond conventional memecoins. As risk appetite returns, investors are looking for newer and more experimental opportunities, with many of these projects being built around v4 hooks. We expect hooked volume to become a much larger part of v4 activity and a new source of growth for Uniswap.
Over the long term, the larger opportunity comes from using the same hook infrastructure to build deeper markets for tokenized assets. Uniswap’s ability to turn today’s experimentation into durable volume will determine whether UNI can sustain its premium.

Suggested Research Based on your Watchlists
Create a new watchlist
- Introduction
- Uniswap Has Held Its Ground
- Following Activity to New Chains
- V4 Opens the Next Market
- Why Stablecoin Moved to V4
- What Developers Are Building With Hooks
- Bringing More Traditional Assets Onchain
- The Leader Has Kept Changing
- The Path to Monetization Has Opened
- Has the Fee Switch Hurt LPs?
- What UNI Is Pricing In
- Risks
- Conclusion