Quarterly revenue declined 18% as the UST implosion and subsequent centralized lender collapse reduced the demand for Aave loans.
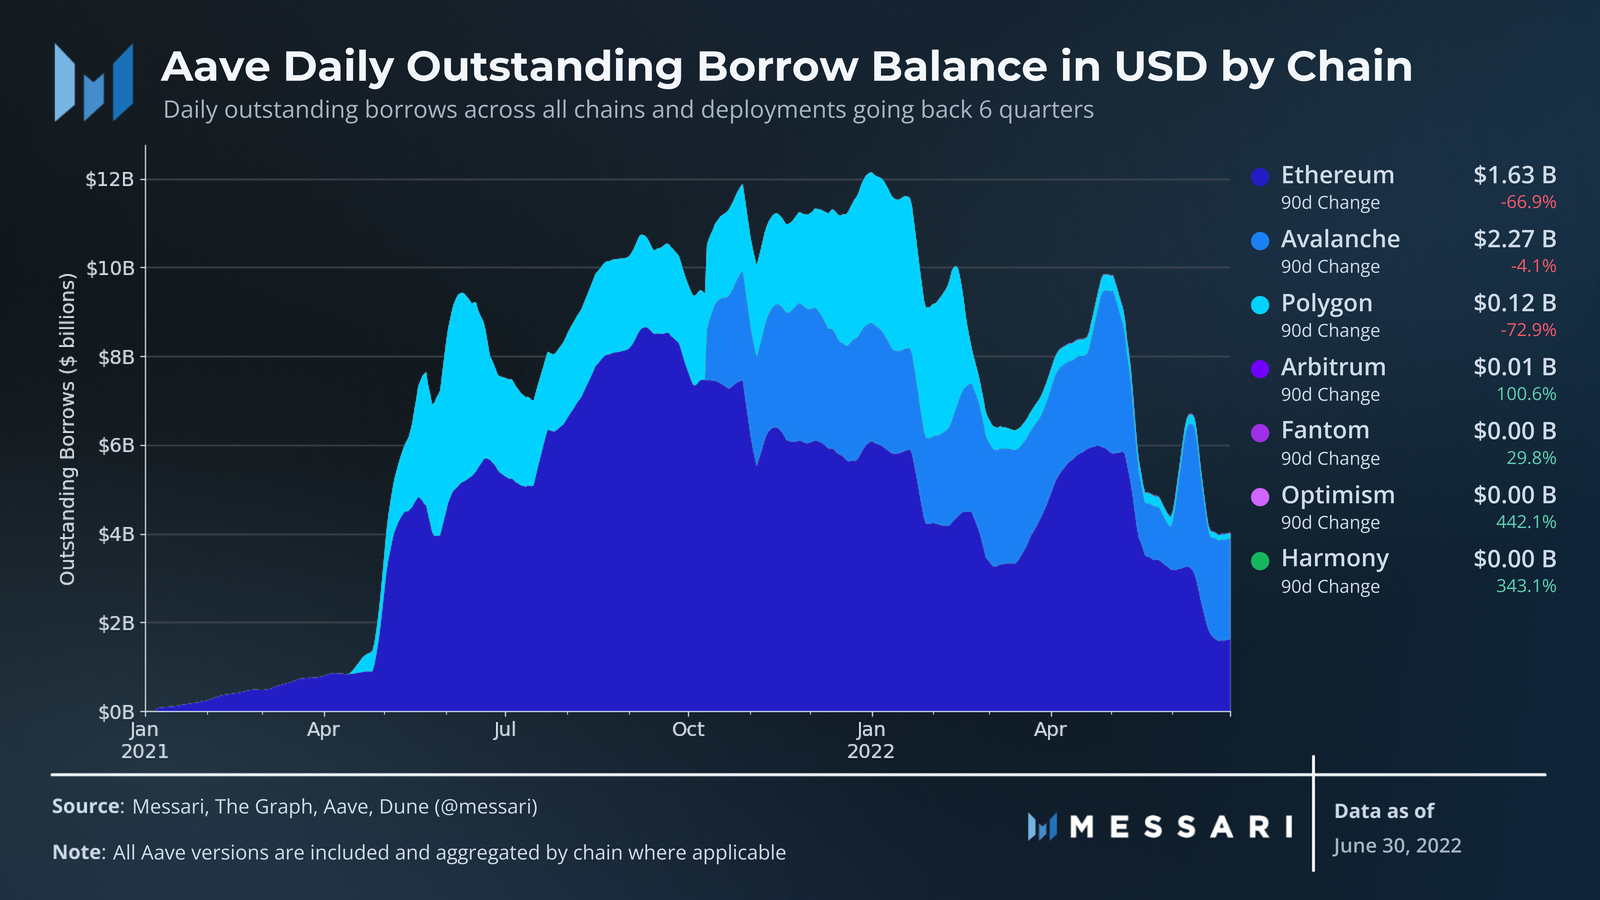
Fueled by Avalanche Rush incentives, Aave’s Avalanche deployments finished the quarter with a higher outstanding loan balance than Aave’s Ethereum deployments for the first time.
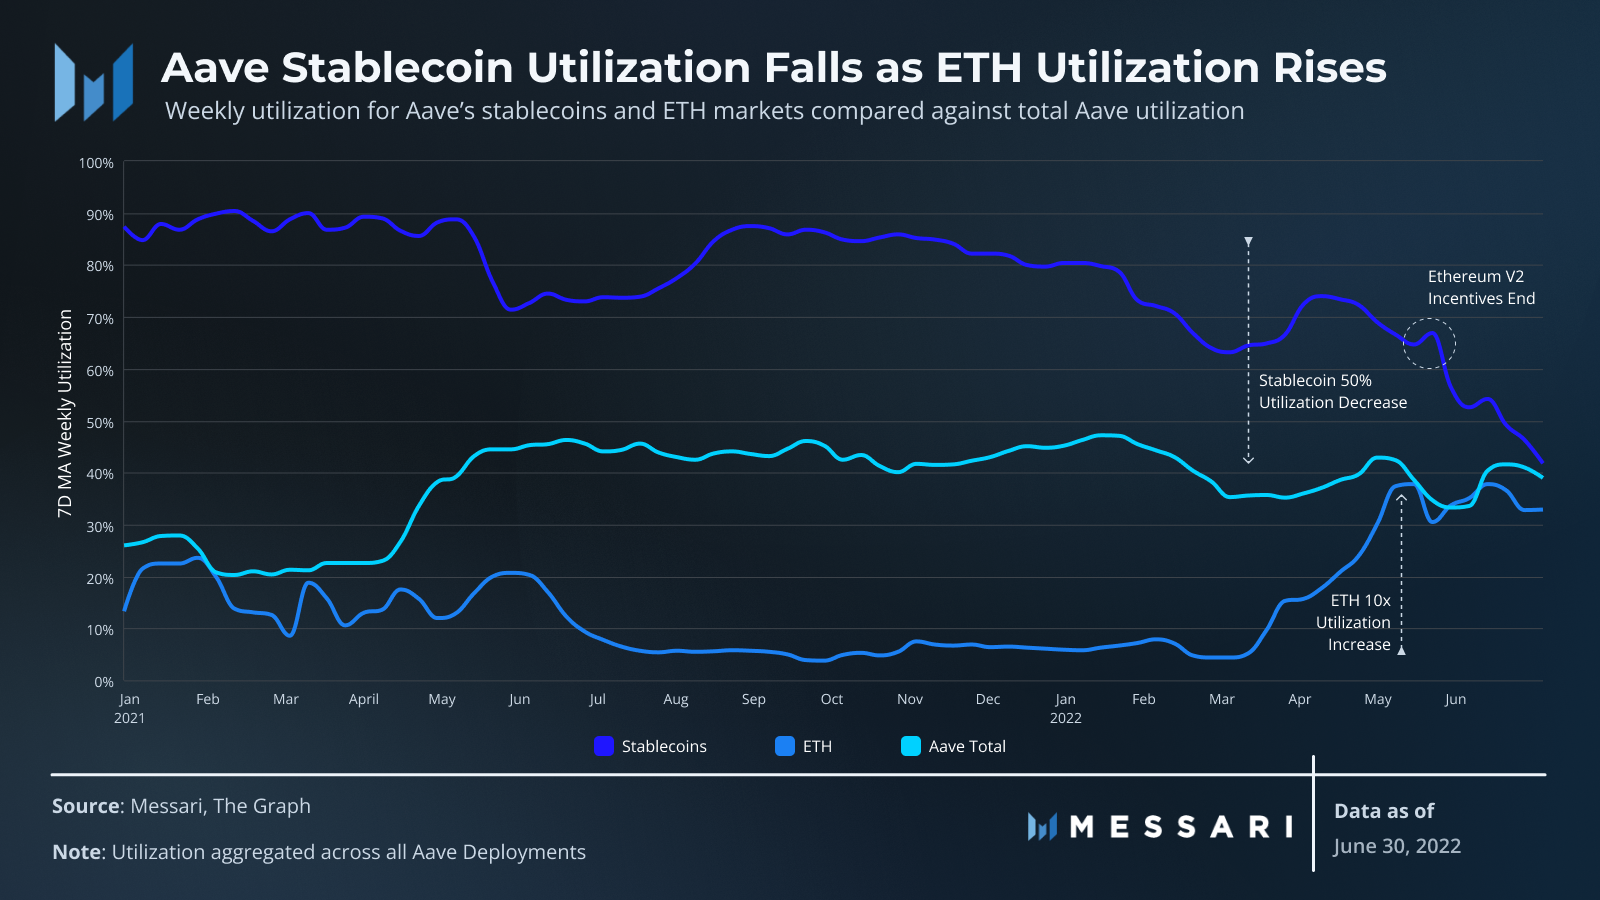
While stablecoins hit the lowest utilization ratio (60%) seen in the last 6 quarters, the demand for ETH loans balanced out the overall utilization in Aave.
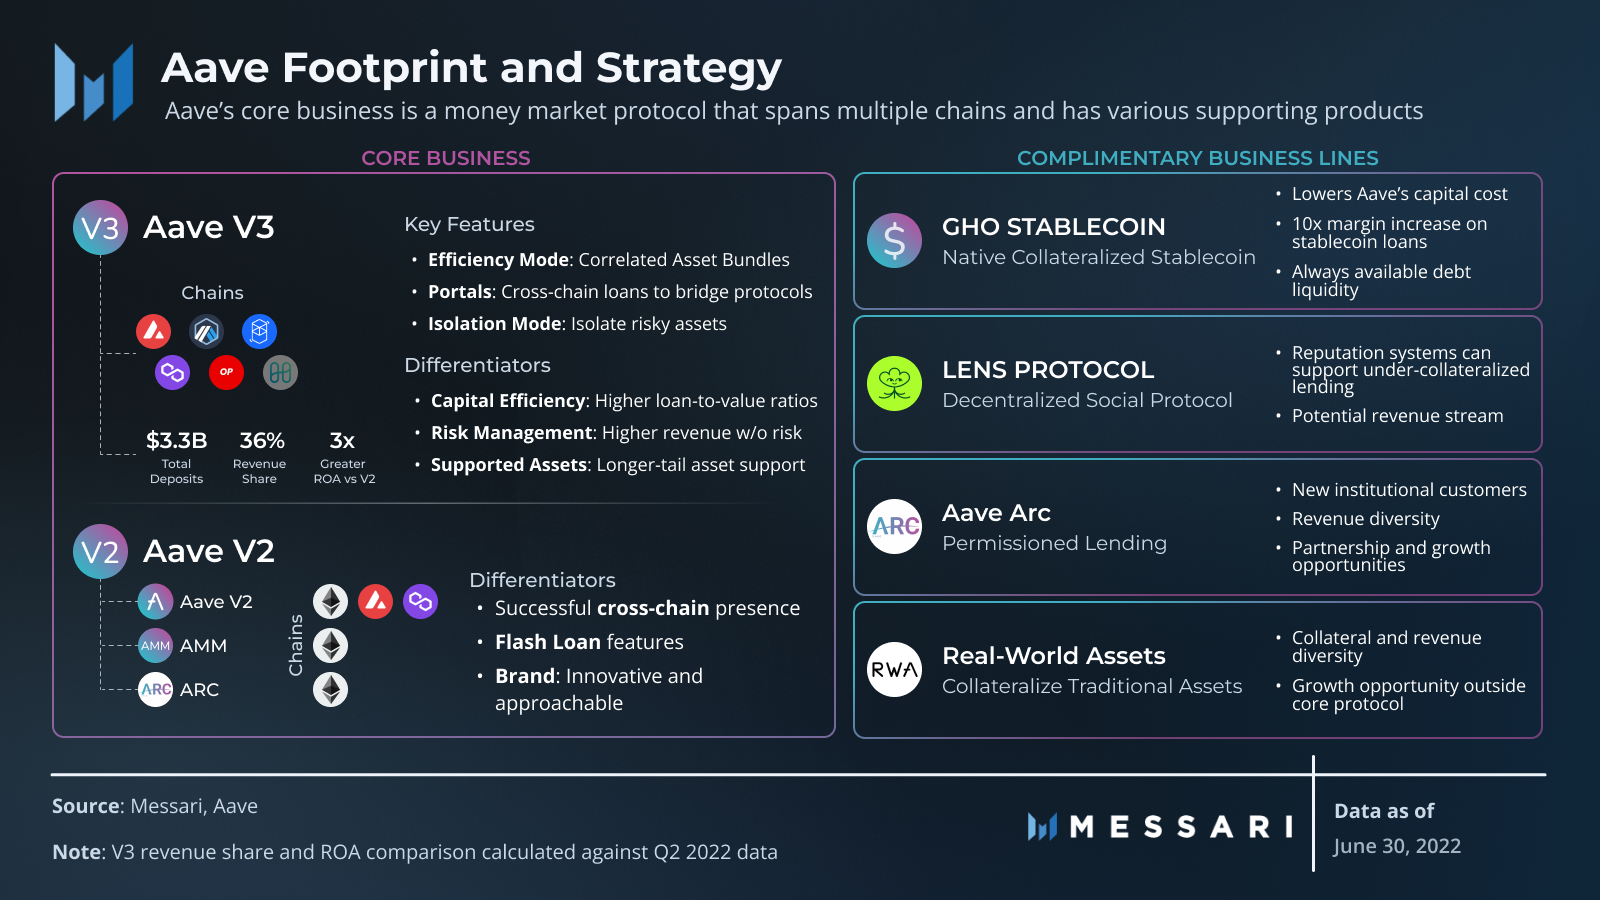
Aave recently released a few key products which all will either improve revenue capture or capital efficiency: Aave V3, the GHO stablecoin, and Lens Protocol.
A Primer on Aave
Aave is a decentralized money market protocol that facilitates depositing and borrowing of various crypto assets. The protocol has two main versions; Aave V2 and V3, and is deployed across various Layer-1 chains and Layer-2 networks with the majority of activity on Ethereum, Avalanche, and Polygon. Outside of the core lending business, the protocol has introduced various complementary products: a stablecoin (GHO), an open social protocol (Lens Protocol), and a permissioned instance of the core Aave protocol (Aave Arc).
Financial Performance
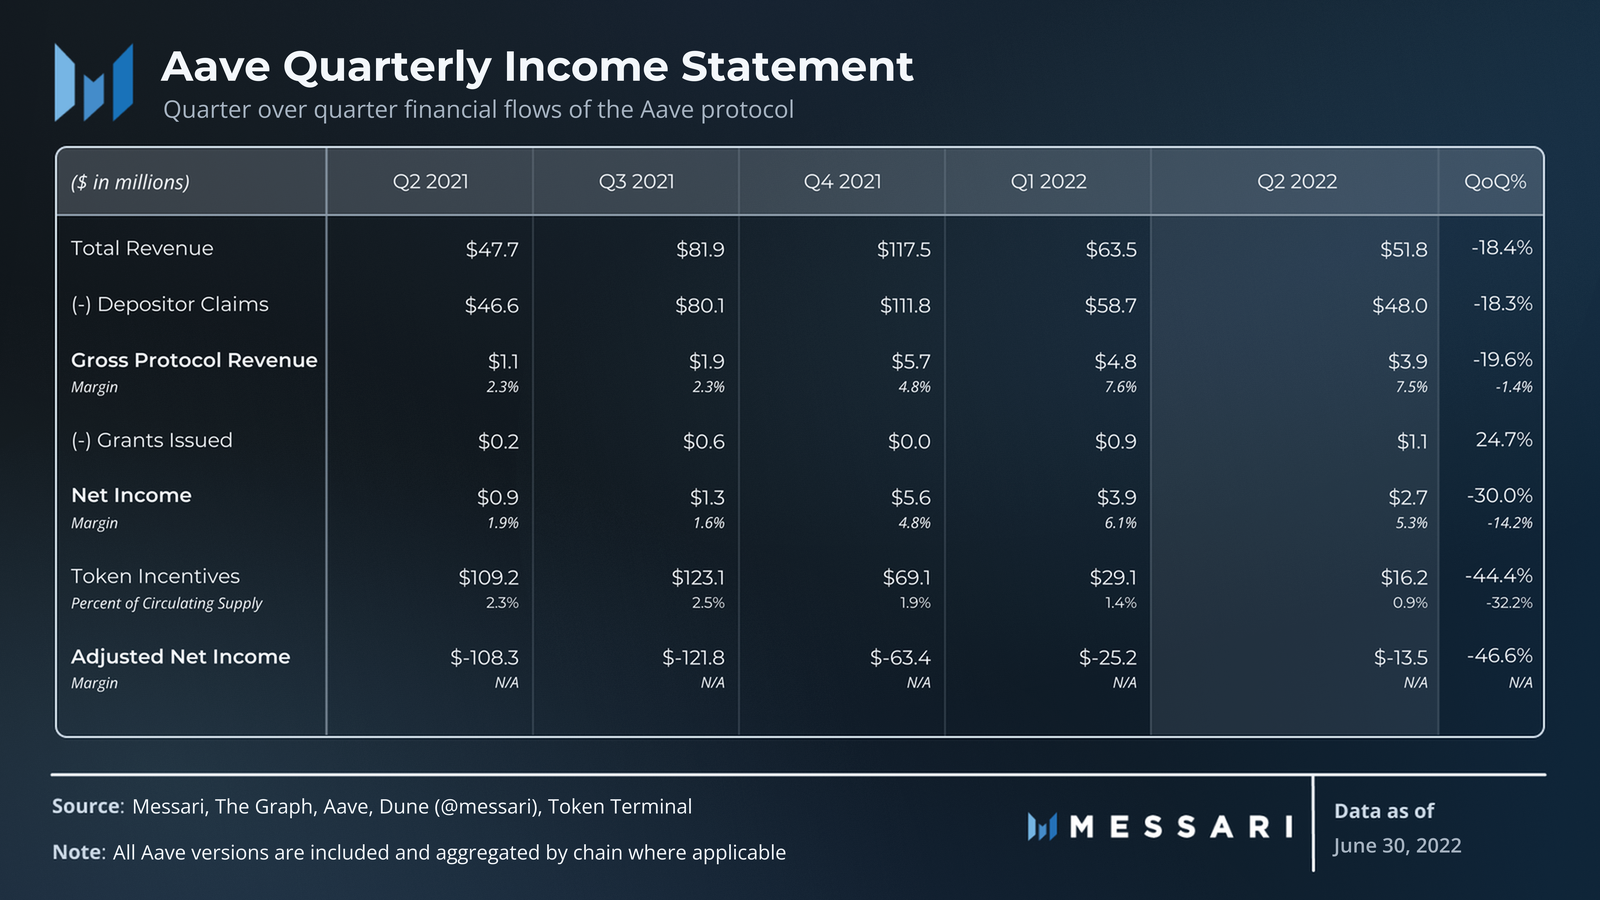
Like many protocols, Aave's Q2 2022 was defined by two severe market drawdowns. First, the UST collapse in May triggered the beginning of a large leverage unwind. Subsequently, bad debt from crypto hedge fund, Three Arrows Capital, sparked a centralized lender collapse in June led by Celsius, one of Aave's largest users. Borrowers’ leverage demand contracted as prices sharply fell, leading to Aave’s total revenue decline of 18% in the quarter. The reinstatement of the Aave Grants Program in May drove expenses and helped push net income down 30% in the quarter to $2.7 million. While Aave’s overall revenue declined in the quarter, the decline was not proportionately shared across its various cross-chain deployments.
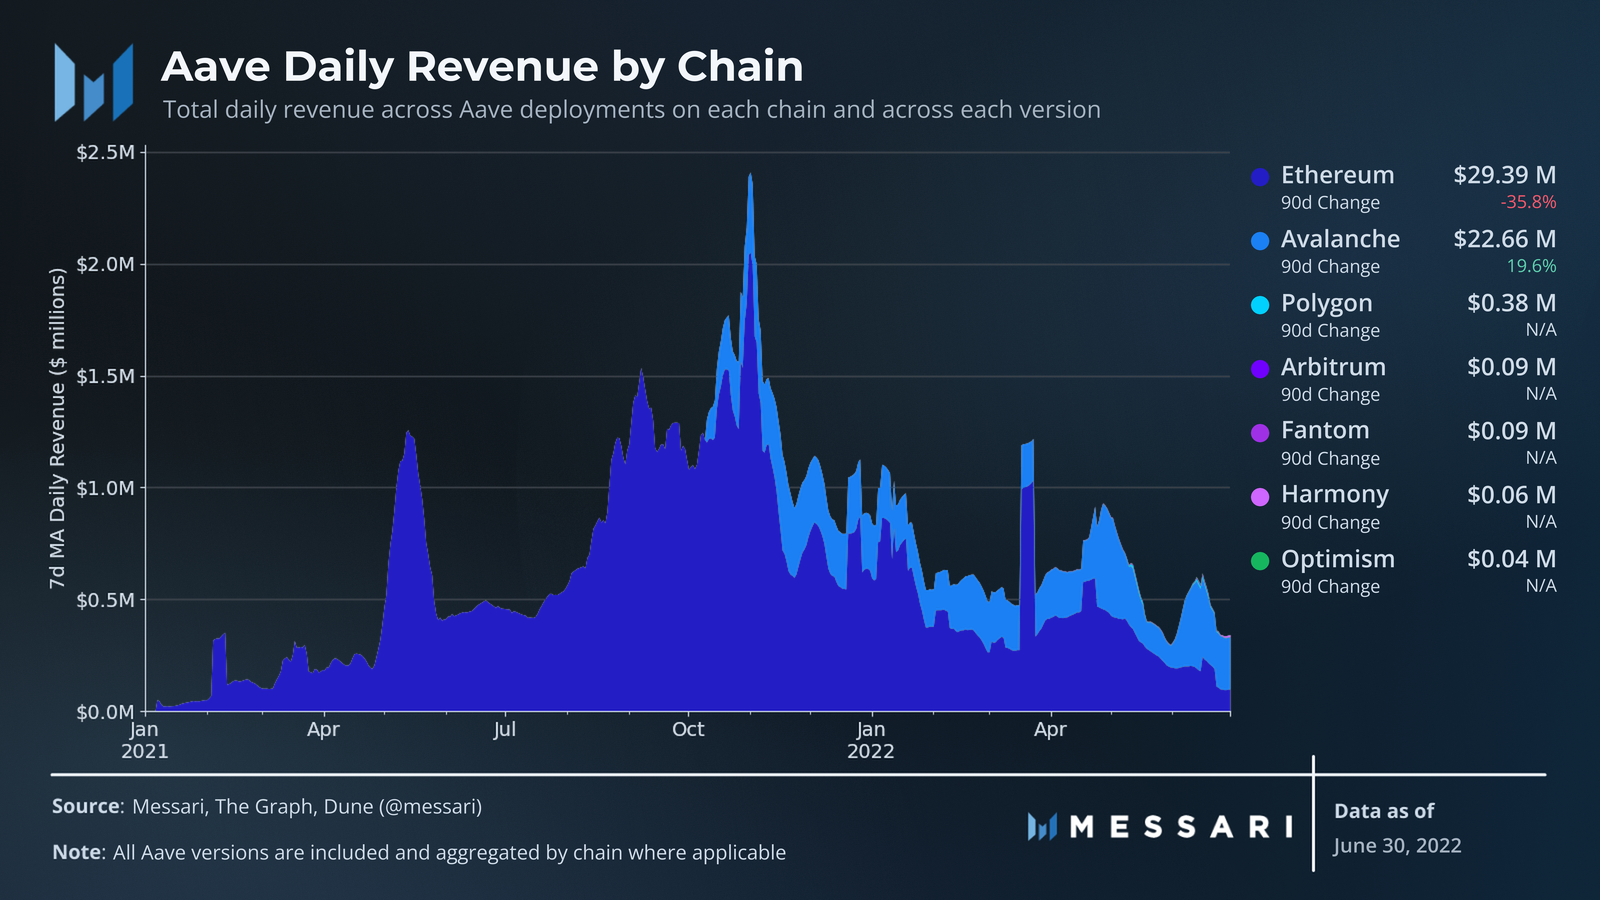
The main Ethereum V2 deployment was the major source of the revenue decline as these markets were hit hardest by the Celsius collapse. Nearly 20% of all the outstanding debt on Aave Ethereum was repaid by Celsius’s main trading wallet from June 9 to July 13. These significant debt repayments in conjunction with over 50% broader price declines drove Aave’s Ethereum quarterly revenue down nearly 36% to $30 million.
Conversely, Aave’s Avalanche deployments actually grew revenue by 20% in the quarter. In fact, Aave’s total revenue on Avalanche outpaced Ethereum-based revenues for the last two months of the quarter. While this marked the first time another chain’s revenue outpaced Aave’s Ethereum deployments, it shouldn’t be expected to continue.
A large amount of the activity behind Aave’s total revenue on Avalanche is currently subsidized by the Avalanche Rush incentives in the form of native AVAX tokens. For example, the Aave Avalanche USDT markets are currently at an abnormally high 90% utilization rate for a bear market, due to the incentives. The incentives offset the borrowing rate below the rate paid to depositors, allowing borrowers to earn nearly risk-free yield by repeatedly redepositing borrowed funds. Incentives to this degree don’t add true value and are unsustainable. However, since the Rush rewards are issued by Ava Labs, the incentives come at no tangible cost to Aave and have helped keep quarterly revenues moderately healthy in a down market.
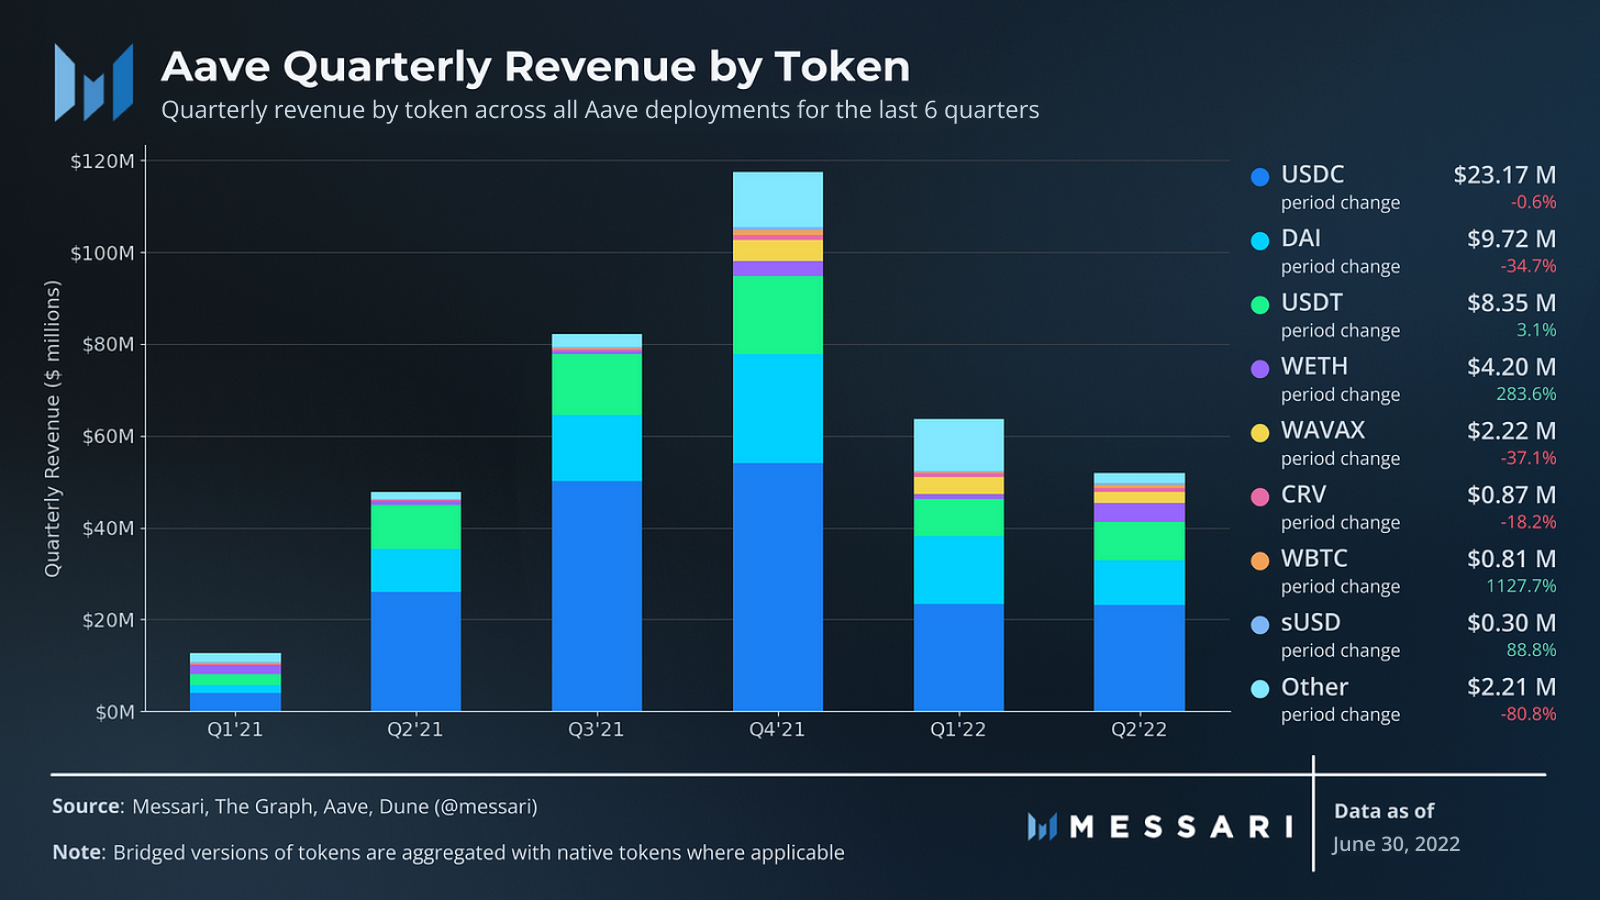
Over the previous four quarters, stablecoin loans have contributed as much as 98% of Aave’s revenue on a quarterly basis. While still significant, the Q2 2022 revenue contribution from stables dropped to a six-quarter low of 82%. The decline in stablecoin revenue share was largely due to two factors: the repayment of DAI, and the surge in demand to borrow ETH and BTC. Since DAI is issued as debt, its market cap dropped by a third as debtors unwound many of their positions following May’s Terra implosion. The jump in ETH and BTC interest revenues came as users sought to profit from the broader market declines by borrowing and selling these assets (i.e. shorting these assets).
Operational Performance
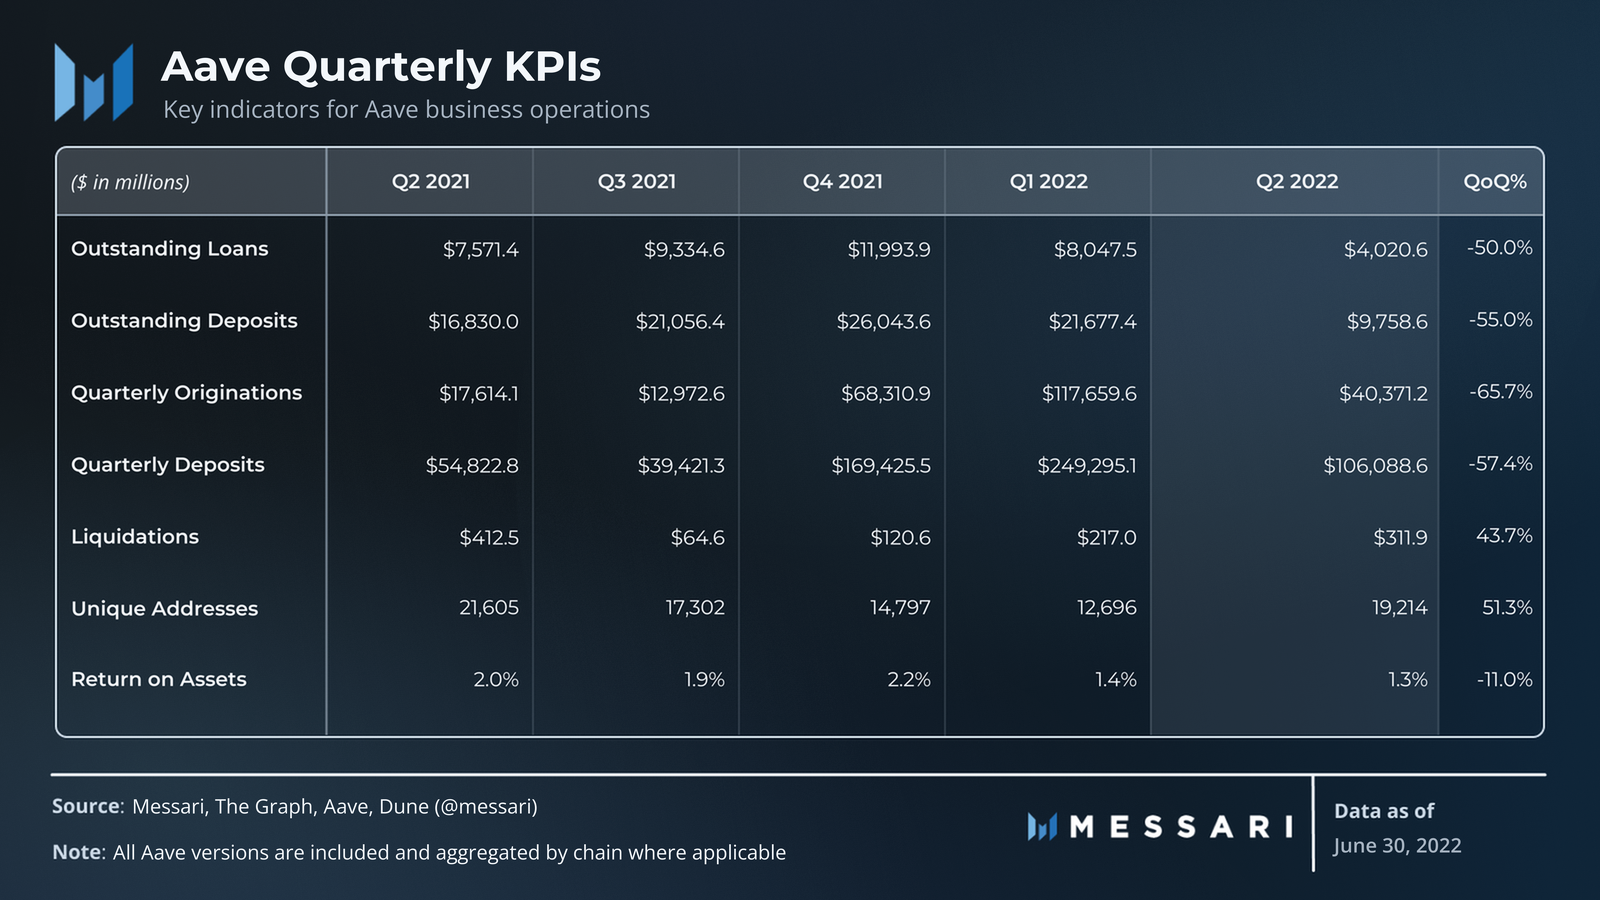
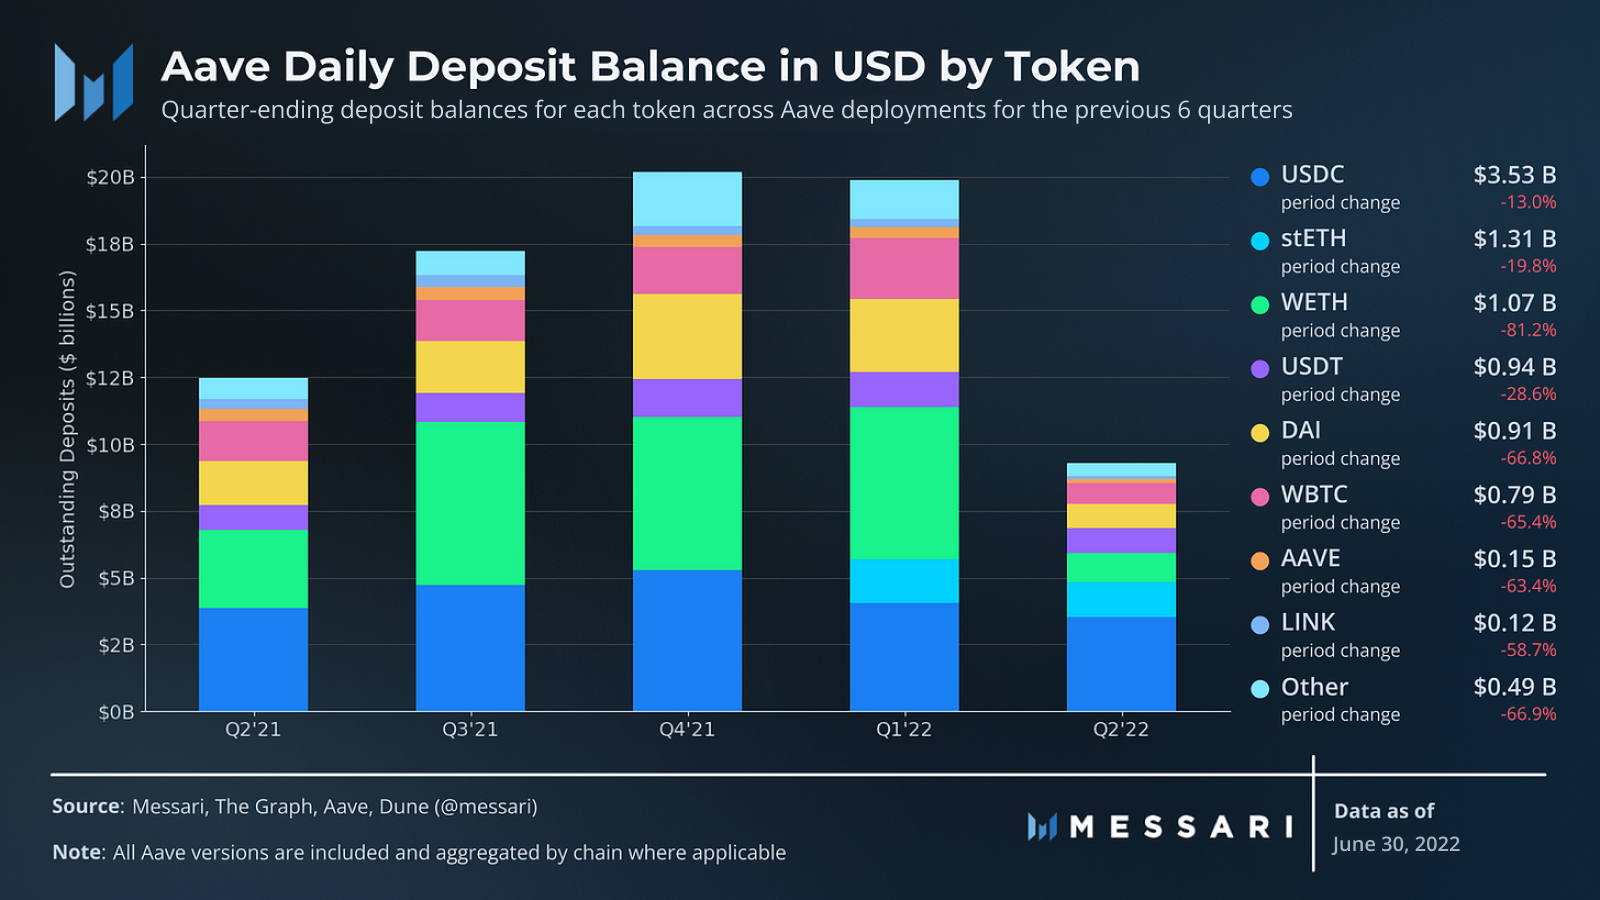
The decline of the outstanding loan and deposit balances on the quarter closely mirrored the 50% quarterly price decline of ETH. In addition to price impacts, user demand for leverage has dramatically shrunk over the last two quarters. Together, these forces culminated in a $3.9 billion quarter-ending loan balance marking a five-quarter low.
Aave's Ethereum deployments contributed significantly more to Aave's outstanding loan decline than the Avalanche deployment due to the same two factors that affected revenue: Celsius repayments and Avalanche incentives. The Avalanche incentives pushed the outstanding loan balance nearly 40% higher than Aave’s Ethereum loans for the first time. However, like Aave’s Avalanche revenue, this trend shouldn’t be expected to continue or be a long-term source of growth.
Currently, 87% of Aave’s Avalanche deposits are stablecoins. These deposits are being used as collateral to farm other stablecoins’ incentives on the protocol. The stable portion of deposits on all other non-incentivized Aave deployments is roughly half that of the Avalanche deployment. Therefore, once the incentives cease, the deposit levels of the Avalanche deployment will likely fall by roughly $1.4 billion (note: this is nearly half of the entire Avalanche ecosystem TVL as well). However, the exact end date for the incentives isn’t known as the schedule isn’t publicly available.
While the Celsius withdrawals and repayments negatively impacted the overall outstanding loans on Aave Ethereum, they naturally impacted some markets disproportionately. On the deposit side, WETH supply fell 81% due to both price impact as well as the $300 million in WETH withdrawn by Celsius. Celsius also withdrew nearly 20% of the WBTC from Aave’s Ethereum deployment over the course of June and July. Celsius’ main position, however, was in stETH. Over the quarter, Celsius withdrew a third of all of Aave’s stETH deposits (most of it in a single day — July 11).
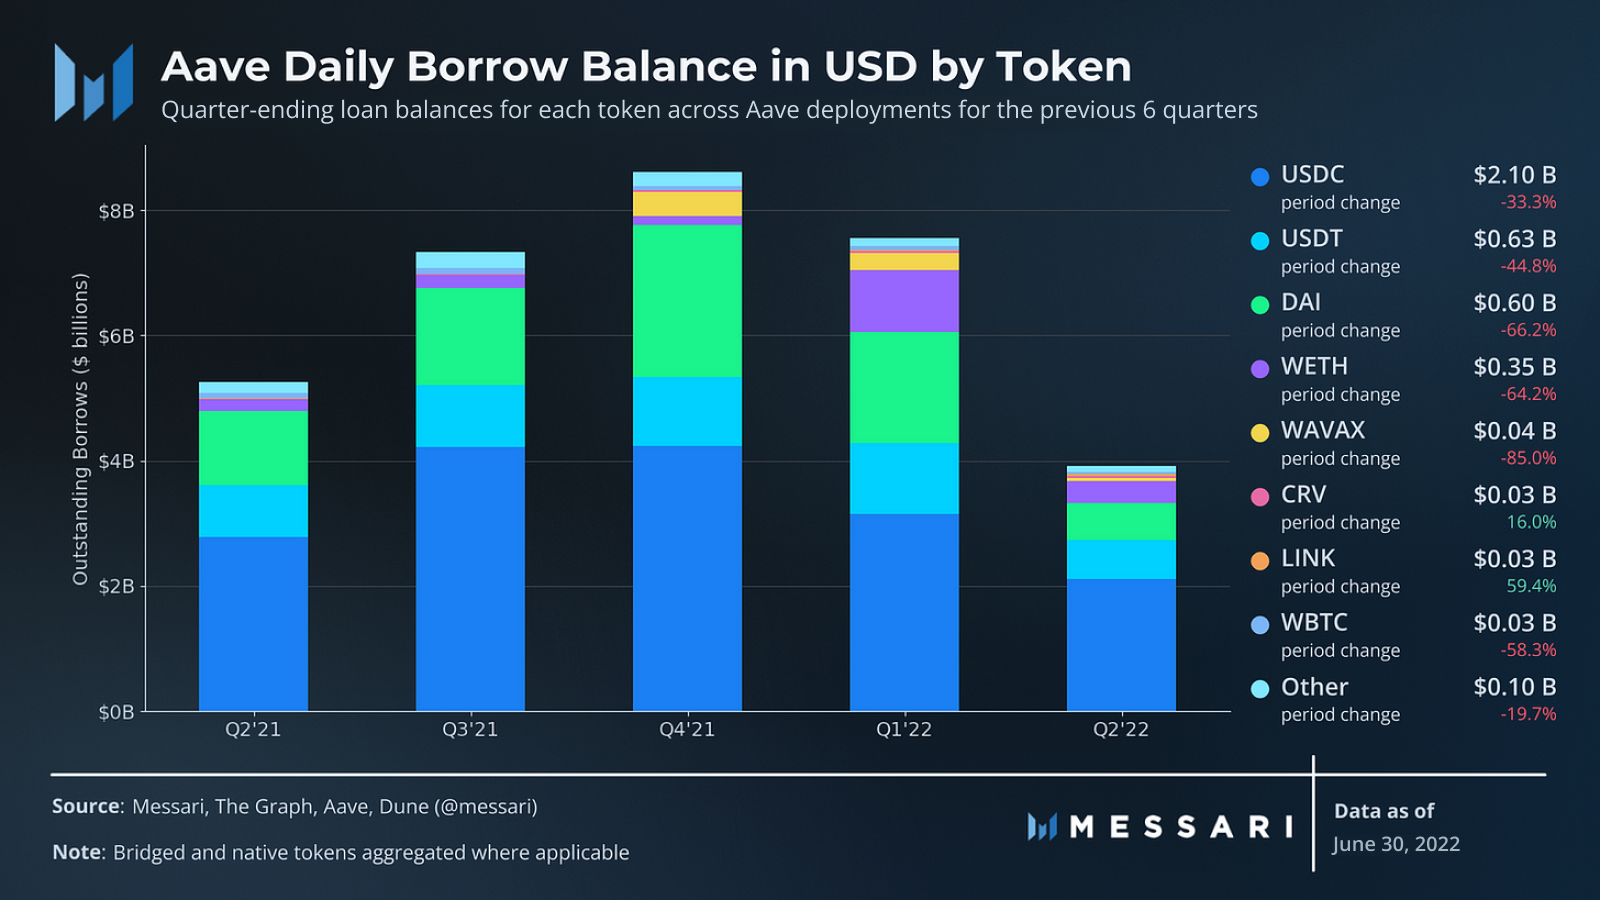
On the borrow side, the bulk of Celsius’ loans were in USDC and accounted for almost 40% of the borrowed USDC on Aave Ethereum prior to repayments. Through the quarter, Celsius paid down its USDC debt by nearly $500 million. While this impacted Aave’s USDC market, it still didn’t make USDC the most negatively impacted stablecoin market. Both USDT and DAI saw their outstanding borrows contract more than USDC on a percentage basis. DAI in particular was negatively impacted, with a 66% decline in outstanding loans. During the UST implosion, debtors unwound rather complex, cross-protocol leverage schemes, decreasing Aave’s DAI deposits and loans. Additionally, this event led to Maker defunding their DAI Direct Deposit Module (D3M) which led to an additional $300 million reduction in DAI liquidity. The overall contraction in stablecoin borrows dropped the stablecoin utilization in Aave to a practical all-time-low.
While the stablecoin utilization rate fell from 75% to its new record low of 60%, the overall utilization rate on Aave actually increased on the quarter. Considering that stables have made up nearly 98% of Aave’s revenue in the past due to high utilization rates, it's impressive that other markets have filled the void left as Aave's most important markets declined. The primary market providing the uplift is ETH and is now paying a higher APY on deposits than stables in Aave Ethereum. The ETH borrow demand is coming from two fronts: short-exposure and ETH’s Proof-of-Stake (PoS) yield.
By far the largest of the two is the PoS yield as the increase in ETH loans coincided with the rise in stETH deposits. ETH's borrow demand was further fueled by users' ability to leverage yield returns. When users deposited Lido's stETH as collateral in Aave, they could borrow more ETH for staking (which is what Celsius was doing), and continue looping their deposits for increased yield.
The decision to approve stETH as collateral in February proved to be a savvy move. It made Aave the premier destination to perform one of the quarter’s most popular trades and buoyed the overall performance of the protocol amidst the market contraction.
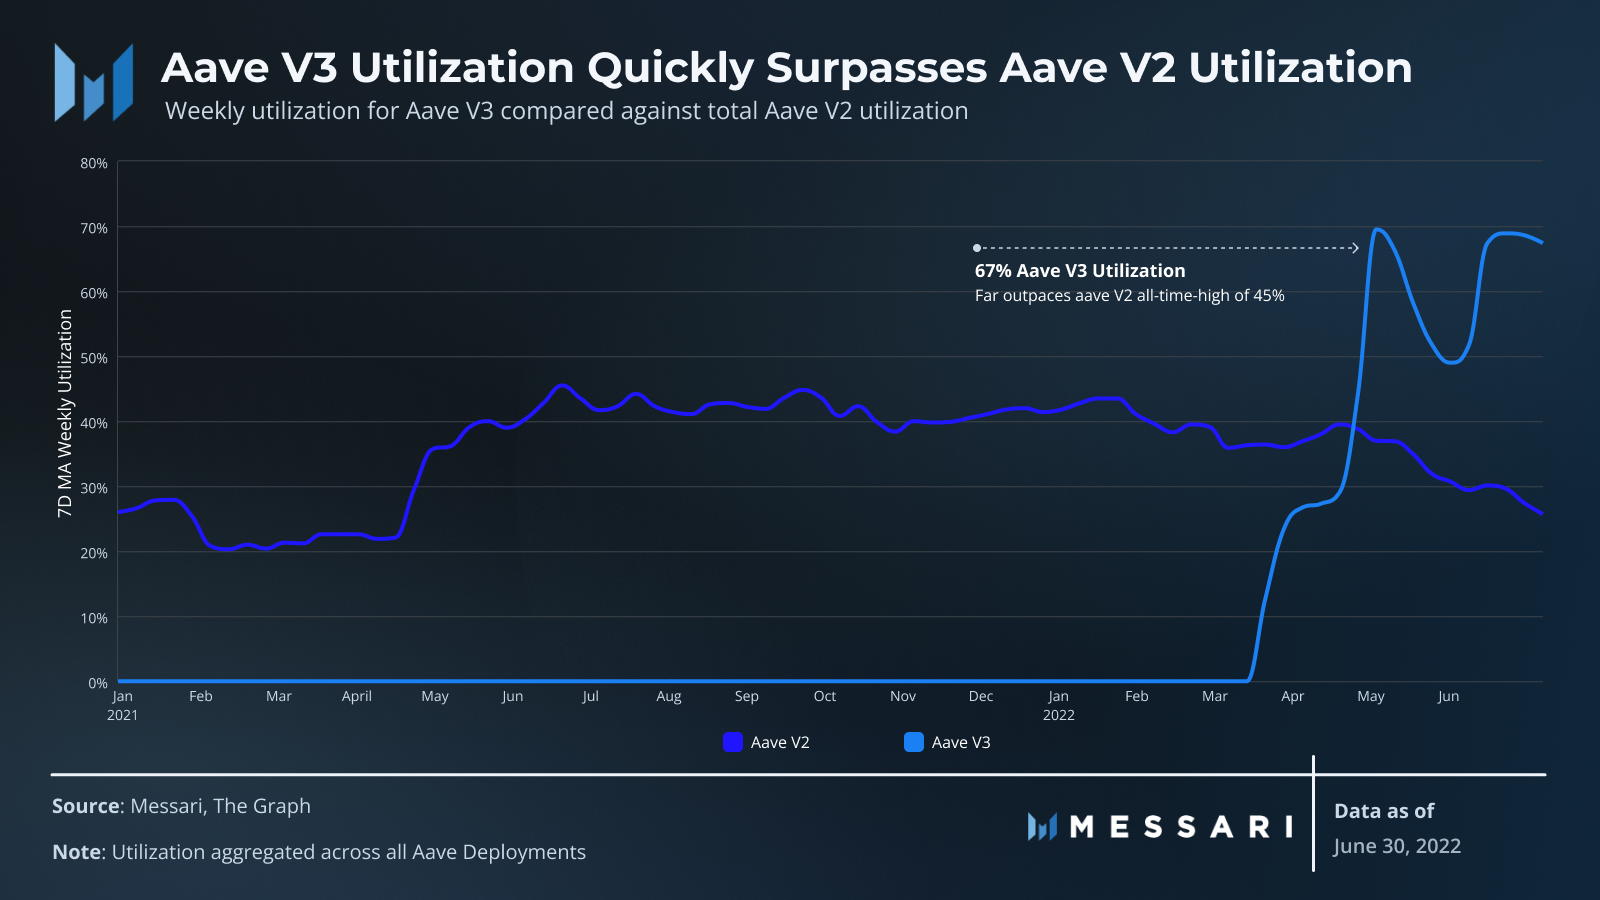
The protocol’s overall utilization was also boosted by the launch of Aave V3 late in Q1. The higher utilizations of Aave V3 are only partly attributable to the Avalanche incentives. There were also some key features like Efficiency Mode that boosted the capital efficiency of the protocol by grouping assets with similar risk profiles.
Overall, the protocol generated an annualized 1.3% return on assets (ROA) during Q2. However, Aave V3 generated nearly triple the return on assets compared to Aave V2. While some of the V3 ROA impacts are incentive driven, Aave V3 should enable higher deposits utilization and thus revenue in the future once the Ethereum instance is migrated to the upgraded protocol.
Strategy and Outlook
Aave’s core business is earning interest revenue from its lending operations. To maximize its lending revenue and profitability, there are three key levers it can adjust outside of simply raising fees: capital efficiency, new customers, and increasing profit margins. Over the last two quarters, Aave has had a core product enhancement (Aave V3) and a number of complementary product announcements (GHO and Lens Protocol) all aimed at adjusting one or more of these three key strategic levers.
Aave V3
Introduced in mid-March 2022, Aave V3 added new features to the core protocol which are largely aimed at safely maximizing the borrowing thresholds (also known as increasing capital efficiency). To maintain a safe risk tolerance in an overcollateralized system, only a certain portion of the deposited assets can be lent out. However, interest revenue is only earned on the portion lent out to borrowers. If the protocol can safely increase the portion of the assets being lent out, then it is able to raise its interest income without directly raising fees.
Aave V3 aims to safely increase the portion of lent-out assets with features like Efficiency Mode, Isolation Mode, and various risk management features. Each feature compartmentalizes or manages risk so that more borrowing power can be safely extended to less risky assets. For example, Efficiency Mode enables the protocol to bucket similarly risked assets in order to increase loan ratios and thus interest revenues.
Another key feature of Aave V3 is Portals – a cross-chain service that enables bridges to source liquidity on-demand for their users. Instead of attracting liquidity themselves, bridges can borrow the exact amount of liquidity they need to fulfill a customer’s migration from one chain to another. The borrowed liquidity opens the door for new customers for Aave and poses a viable growth opportunity if a multichain or rollup-centric thesis does play out in the future.
In a multichain world, Aave is positioned well given its widely deployed V3 protocol. Each new chain deployment can attract new users and thus revenues at minimal marginal cost. So far, Aave has successfully gone cross-chain as it has become the top lending protocol in nearly every ecosystem it has been deployed to. While the initial cost is minimal, the cross-chain expansions still carry risks and costs as markets have to be continually monitored. A key example is last quarter’s freezing of the Harmony deployment following the Harmony bridge hack.
GHO - The Native Aave Stablecoin
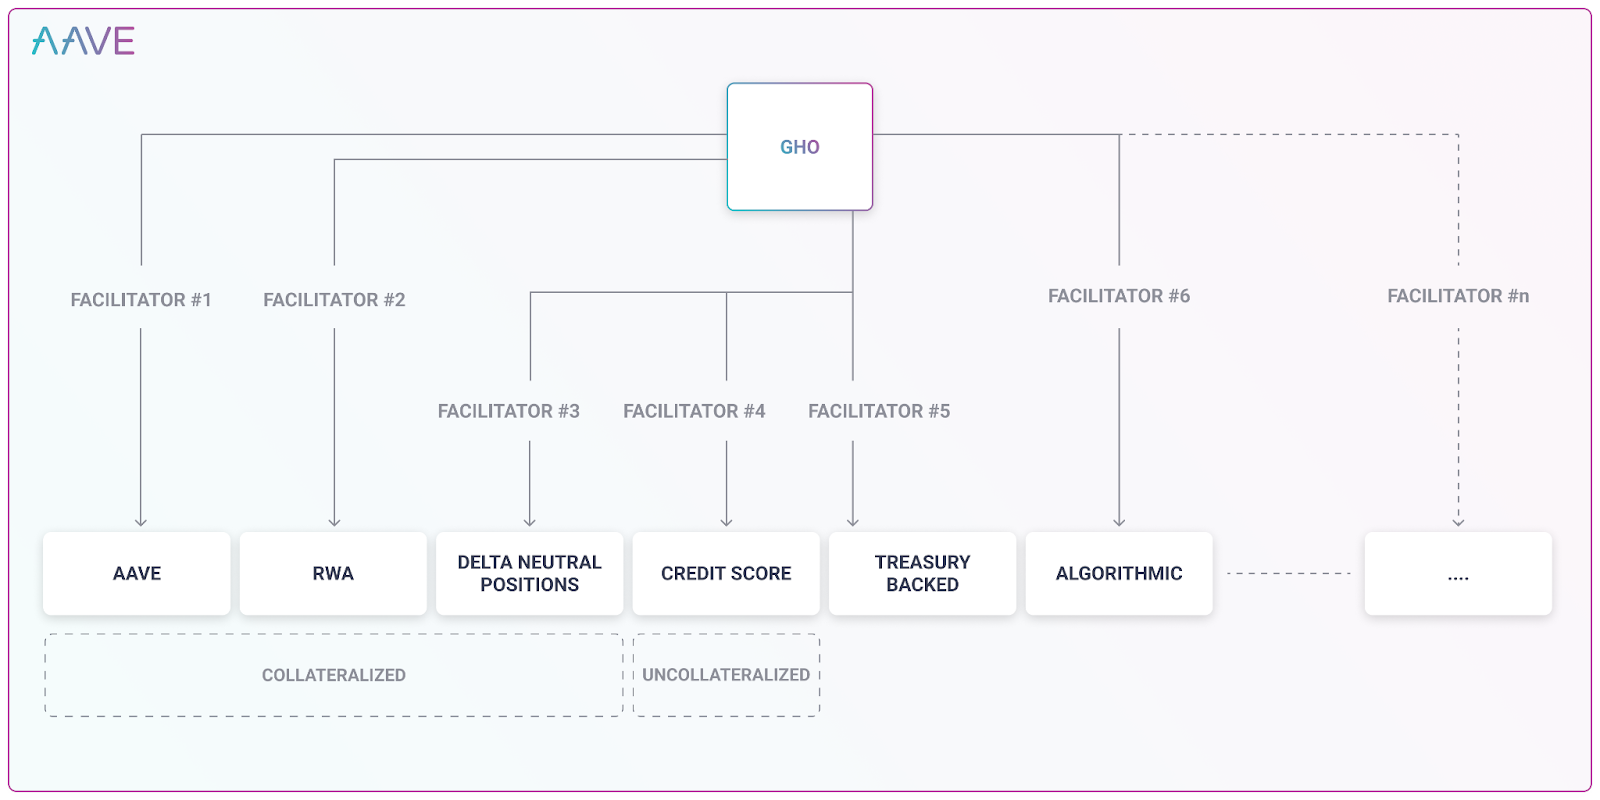
Aave announced its intention to launch the native, overcollateralized stablecoin GHO in early July 2022. GHO will be minted by Aave depositors looking to take out stablecoin debt. The key difference between GHO-denominated debt versus USDC-denominated debt in Aave is the split of the interest revenues. With USDC, Aave has to share revenues with depositors and only ends up retaining 10% of the revenue. The 90% paid to depositors can be seen as the cost of capital for Aave. With GHO, 100% of the interest revenue is retained by the Aave protocol.
Therein lies the strategic angle, as over 88% of Aave’s revenue over the last 6 quarters has come from stables. By launching the GHO stablecoin, Aave can dramatically increase its bottom-line margin without directly raising fees and cannibalizing demand for its other markets like USDC. For example, if GHO at a $1 billion supply were loaned out at the current rate for USDC on Aave Ethereum (1.7%), it would increase the protocol’s Q2 2022 annualized net income by nearly 150%.
However, it’s not as straightforward as simply increasing margins without additional cost burdens. New stables often are faced with a bootstrapping problem to initially establish deep liquidity and organic usage. This problem has historically been overcome with incentives paid by the protocol. Aave will likely have to partake in some initial incentives or artificially set the borrowing rates low. Aave won’t realize the real benefits until GHO can achieve self-sufficient organic adoption. This adoption can take the form of supporting cross-chain transfers via Aave V3’s Portal feature or supporting a version of undercollateralized borrowing powered by Lens Protocol.
Lens Protocol — The Open Social Graph
Lens Protocol is a decentralized social graph framework, and it’s Aave’s long-term bet on significantly increasing capital efficiency by introducing on-chain reputations. Aave V3 improved capital efficiency so significantly that it's hard to imagine additional features which would result in another efficiency step change within the overcollateralized system. The next frontier of efficiency requires breaking down the barrier between overcollateralized and undercollateralized lending. To safely conduct undercollateralized lending on-chain, natively trusted reputation and identity systems would need to be leveraged to extend more favorable borrowing thresholds.
Lens is the biggest growth potential for Aave. The Lens protocol acts as the base layer in the social stack upon which developers can build social applications with custom monetization models. Lens growing into a reputable social protocol is valuable in its own right, but it also represents significant growth potential for the core Aave lending protocol. The GHO token would presumably be adopted within Lens and its creator monetization features. As social commerce is conducted in the GHO token, it creates organic demand rooted in real-world applications. Additionally, tokenized subscriptions and other payment models adopted in decentralized social protocols represent a viable path for Aave to service loans against future cash flows — the foundation of lending in traditional markets.
Governance and Grant Expenses
Governance
In May, Bored Ghosts Developing (BGD) was funded to support Aave’s development. BGD is founded by three developers who were part of Aave’s Genesis Team. In the forum post, BGD outlined its mission and tasks which include supporting the full migration from Aave V2 to V3, implementing Aave Governance V3, and the overall technical maintenance and improvement of the protocol. The proposal funded BGD for 15 months with a pay of $8 million in stables and 21,000 AAVE.
Other notable governance decisions include the extension of two key programs within Aave: the Grants DAO and the Aave Safety Model incentives. Aave Grants DAO will have $6 million in funding, split between AAVE and aUSDC, over the next two quarters to incentivize building within the Aave ecosystem. The Aave Safety Module will continue receiving 401,500 AAVE per year for two years to incentivize users to backstop the protocol by staking AAVE.
As usual, governance continued to make adjustments to various risk parameters. The most influential adjustments were the freezing of UST and de-risking the stETH in light of losing price parity with ETH. Additional details regarding Aave governance can be found through Messari Governor.
Grants
The grants program was extended in May with a total Q2 and Q3 budget of $3 million for grants, around $2.5 million for general marketing, and $350,000 for operations. With the grant specific allocation, 68 grants were issued in Q2 totaling $1.1 million. Notable grants followed two themes: new products and risk monitoring. Aztec, Mean Finance, Mango, and Yieldgate each received $50,000–$100,000 to build new products and services related to Aave. Aztec will enable Aave access on its zk-rollup while the other three grant recipients aim to integrate Aave’s yield into their products. On the risk monitoring side, Block Analitica and Chaos Labs each received grants to build out risk monitoring dashboards.
Closing Summary
Aave’s Q2 2022 was defined by the two key events: the UST implosion and the centralized lender collapse. The aftermath of these events drove Aave’s outstanding loans and deposits down roughly 50% and the quarterly revenue down nearly 20%. While Aave’s leading revenue generating stablecoin markets declined, there was an increase in ETH borrowing demand that balanced out quarterly revenue. Looking ahead, Aave has released a few products that should all drive additional revenue and efficiency for the protocol. They include Aave V3, the GHO stablecoin, and Lens Protocol.
Let us know what you loved about the report, what may be missing, or share any other feedback by filling out this short form.
All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Nothing contained in this report is a recommendation or suggestion, directly or indirectly, to buy, sell, make, or hold any investment, loan, commodity, or security, or to undertake any investment or trading strategy with respect to any investment, loan, commodity, security, or any issuer. This report should not be construed as an offer to sell or the solicitation of an offer to buy any security or commodity. Messari does not guarantee the sequence, accuracy, completeness, or timeliness of any information provided in this report. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Dustin was previously the Enterprise research director at Messari. He has a broad focus across crypto with a particular interest in AI x Crypto, Consumer financialization, DeFi, and general infrastructure.
Dustin was previously the Enterprise research director at Messari. He has a broad focus across crypto with a particular interest in AI x Crypto, Consumer financialization, DeFi, and general infrastructure.