This report was commissioned by ZKsync. By providing this disclosure, we aim to ensure that the research reported in this document is conducted with objectivity and transparency. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Blockworks. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Blockworks maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) submit financial conflict of interest (FCOI) disclosures on a monthly basis that are reviewed by appropriate internal parties and may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
The Race to Reinvent the Deposit

Key Takeaways
- Stablecoins and deposit tokens are not substitutes. Stablecoins are open, permissionless dollars for settlement and DeFi. Deposit tokens are regulated bank money for vetted counterparties and the onchain economy needs both.
- Bank issuance is gated by three requirements no stack has met at once: confidentiality, compliance, and interoperability with public liquidity. This is the problem Matter Labs' Prividium was built to solve, and the Cari Network is its first deployment.
- Stablecoins are a ~$310B market, other tokenized securities constitute $35B, but tokenized deposits barely register. There are tens of trillions of deposits worldwide waiting for a new tech stack.
Overview
A tokenized deposit is a commercial-bank deposit recorded as a transferable token on a blockchain. Each token is a direct claim on a specific bank's balance sheet, and it redeems back into an ordinary deposit at that bank. The money never leaves the bank's books; only its representation moves. It settles around the clock and reconciles onchain (even across multiple ledgers).
That balance-sheet detail is the whole distinction from a payment stablecoin. A stablecoin such as USDC is a claim on a segregated reserve held by a non-bank issuer. A deposit token is a claim on the issuing bank itself. In essence, stablecoins behave as safe money for payments, while tokenized deposits stay inside the conventional bank-money framework and keep funding lending. One instrument sits beside the banking system while the other is the banking system on faster rails.
The consequences follow from that structure. Because a deposit token is bank money, it can carry interest, it stays inside the capital, liquidity, and supervisory regime already applied to deposits, and holders may fall under deposit insurance where the bank and product qualify. Because a payment stablecoin is not bank money, the GENIUS Act (and OCC) bars its issuer from paying yield to holders or extending credit.
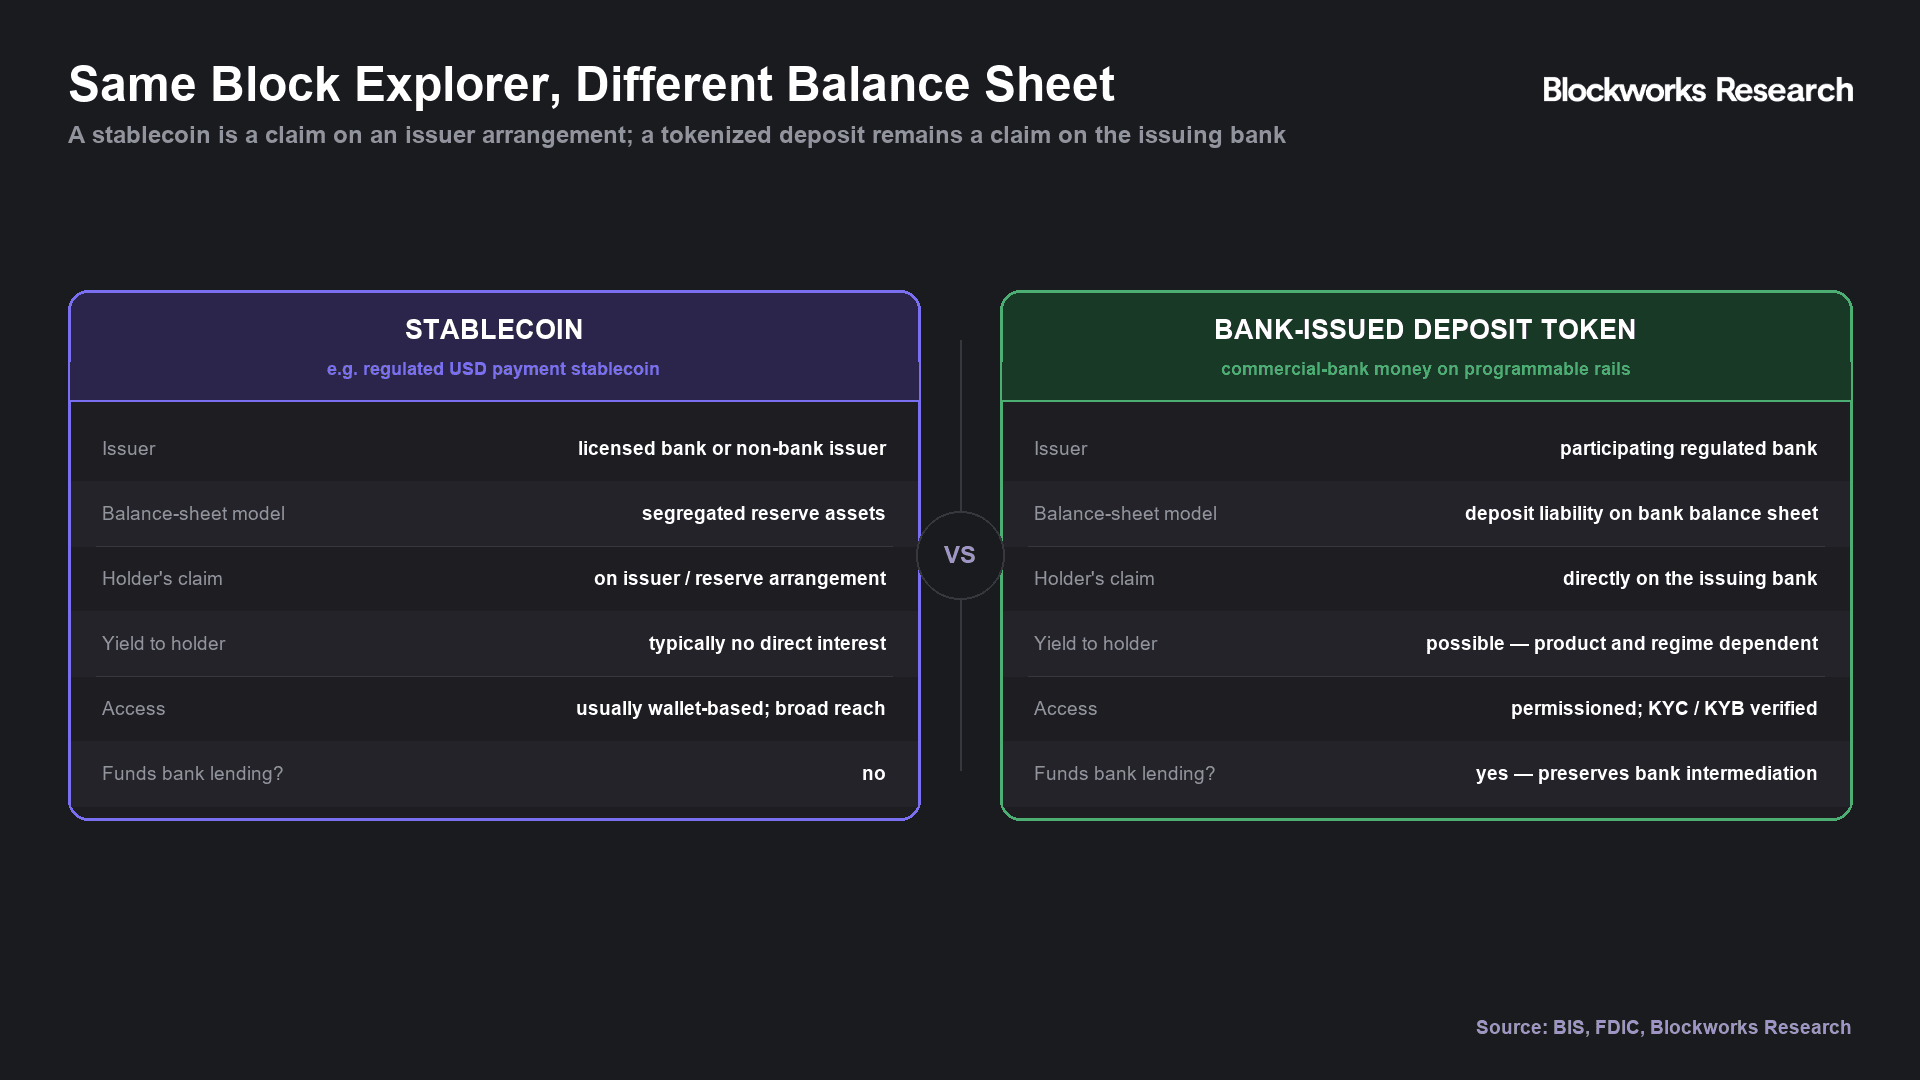
Stablecoins x Deposit Tokens
It is tempting to read this as a fight, with banks reclaiming ground from Tether and Circle. The structure argues otherwise. The two instruments serve different holders and different jobs.
Stablecoins are open. Anyone with a wallet can hold one, which is why roughly 270 million addresses do and why stablecoins have become the default settlement asset across exchanges and DeFi. However, that openness is also their regulatory ceiling, as a permissionless bearer instrument is hard to fit inside bank supervision. Deposit tokens invert both traits. Access is restricted to vetted, KYC-verified counterparties of the issuing bank, which is the source of their regulatory strength and the main limit on their reach. A deposit token will not circulate freely through DeFi and a stablecoin will not hold a corporate treasurer's balance inside a supervised, interest-bearing, insured account.
The result is a division of labor rather than a winner. Stablecoins are the retail- and crypto-facing dollar; deposit tokens are the institutional and interbank dollar. Both run on the same rails and feed the same onchain economy, one supplying permissionless liquidity, the other supplying regulated balance-sheet money that keeps credit creation intact. The BIS has sketched the same layered picture: central-bank money for final settlement, tokenized deposits for commercial-bank money, stablecoins at the edges.
In practice, banks are beginning to treat stablecoins as payment infrastructure rather than a source of deposit flight. These services include fiat conversion for crypto firms, cross-border settlement, and cash movement outside normal banking hours. Each gives banks a way to earn fees or use liquidity more efficiently while responding to demand that already exists. Stablecoins, in this reading, extend a bank’s reach beyond its own ledger.
Deposit tokens solve a different problem. Approved clients transfer bank money around the clock while preserving the deposits, controls and commercial relationships that banks care about. Stablecoins become useful when funds need to leave that controlled network and reach another institution, market or wallet. A bank that supports both can keep balances in deposit form while they are idle, then convert them when customers need wider circulation. The boundary between the two instruments matters more than the underlying technology.
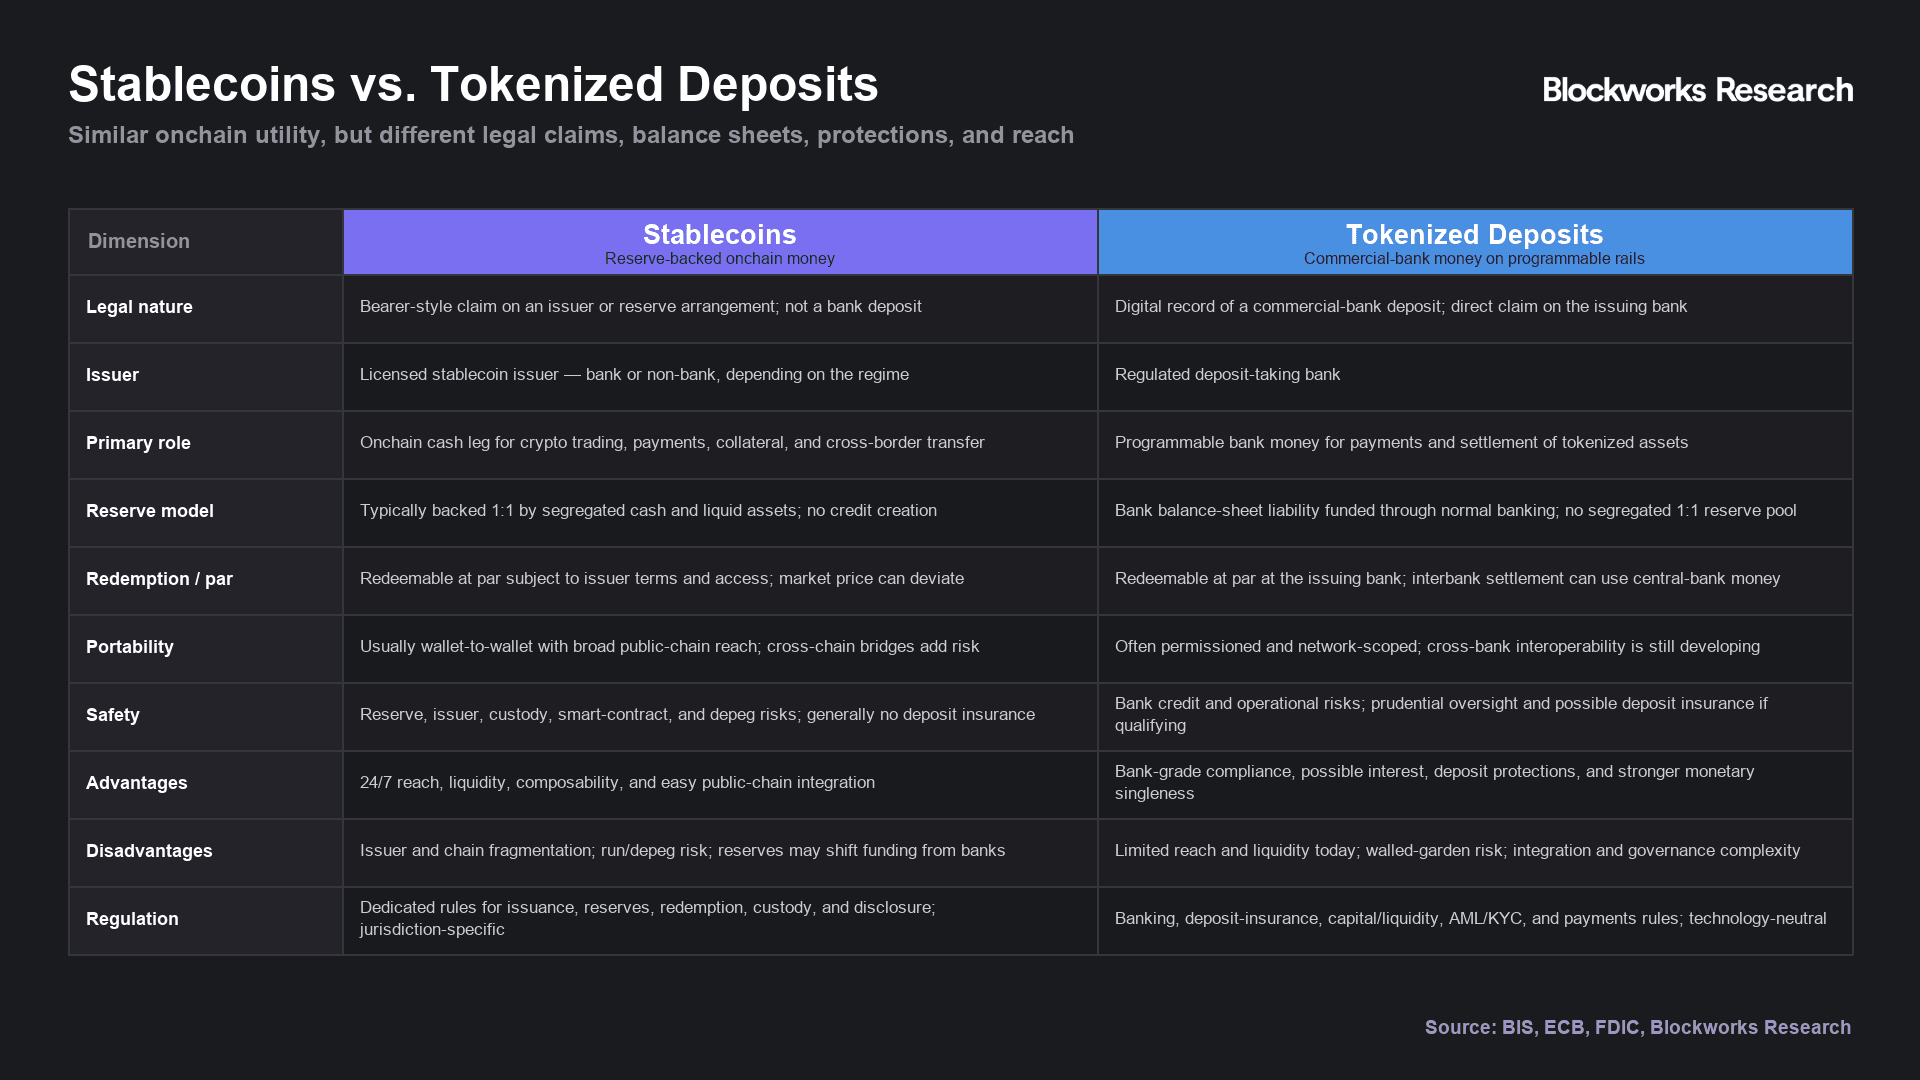
The Market Today
The onchain dollar is, for now, almost entirely a stablecoin story. Total stablecoin supply sat near $310 billion in mid-2026, up about 23% year over year and roughly 99% dollar-denominated, with USDT (~58%) and USDC (~24%) accounting for most of it. Tokenized real-world assets outside stablecoins add about $35 billion, of which tokenized US Treasuries are near $11 billion. Against those figures, tokenized bank deposits barely register. Issuance is still concentrated in pilots, and the large numbers banks cite are transaction flow, not outstanding balances.
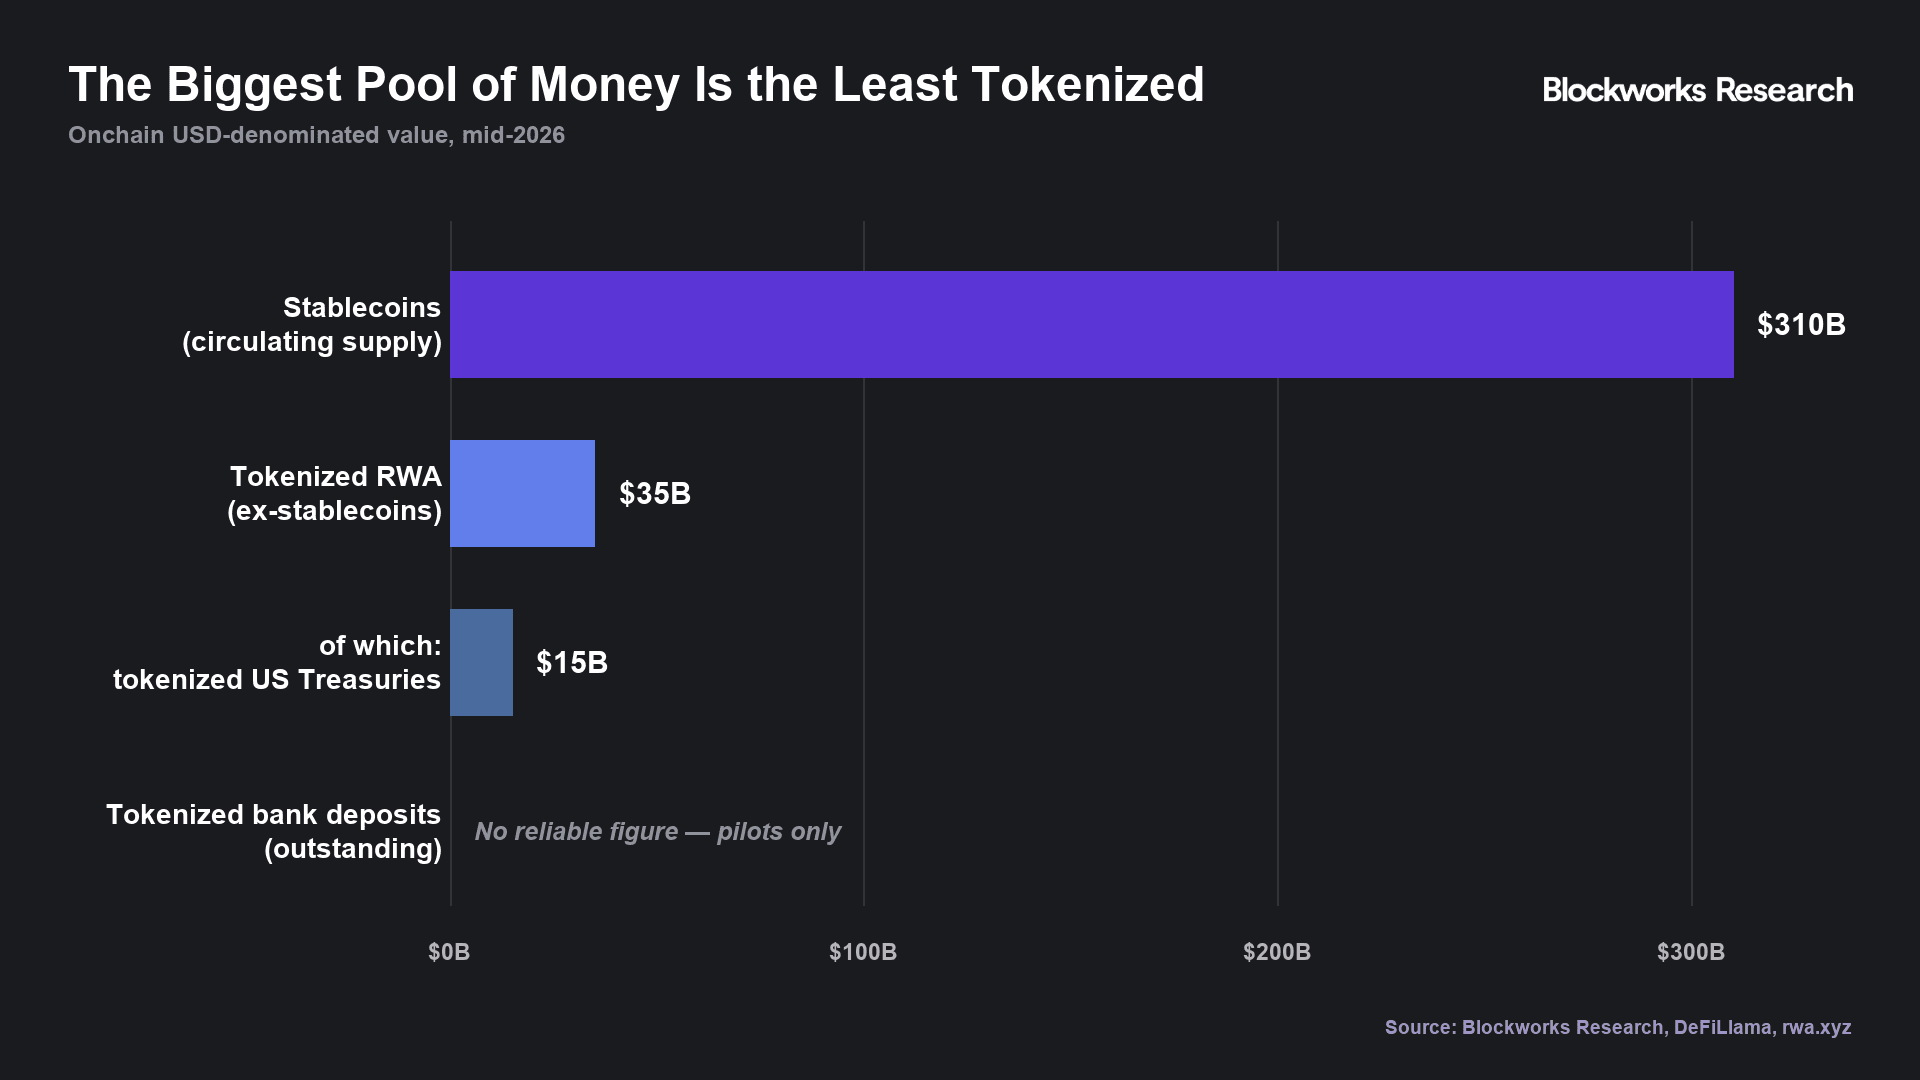
Flow is where the bank programs look big. JPMorgan runs its deposit-token activity through Kinexys, formerly Onyx, which processes more than $5 billion a day and has cleared over $3 trillion cumulatively, growing roughly tenfold year over year. Citi, DBS, BNY, and State Street have each launched or expanded tokenized-deposit or onchain-cash programs, and JPMorgan and DBS have said they are exploring interoperability between their two networks, an early sign that the wholesale side already treats fragmentation as the problem to solve.
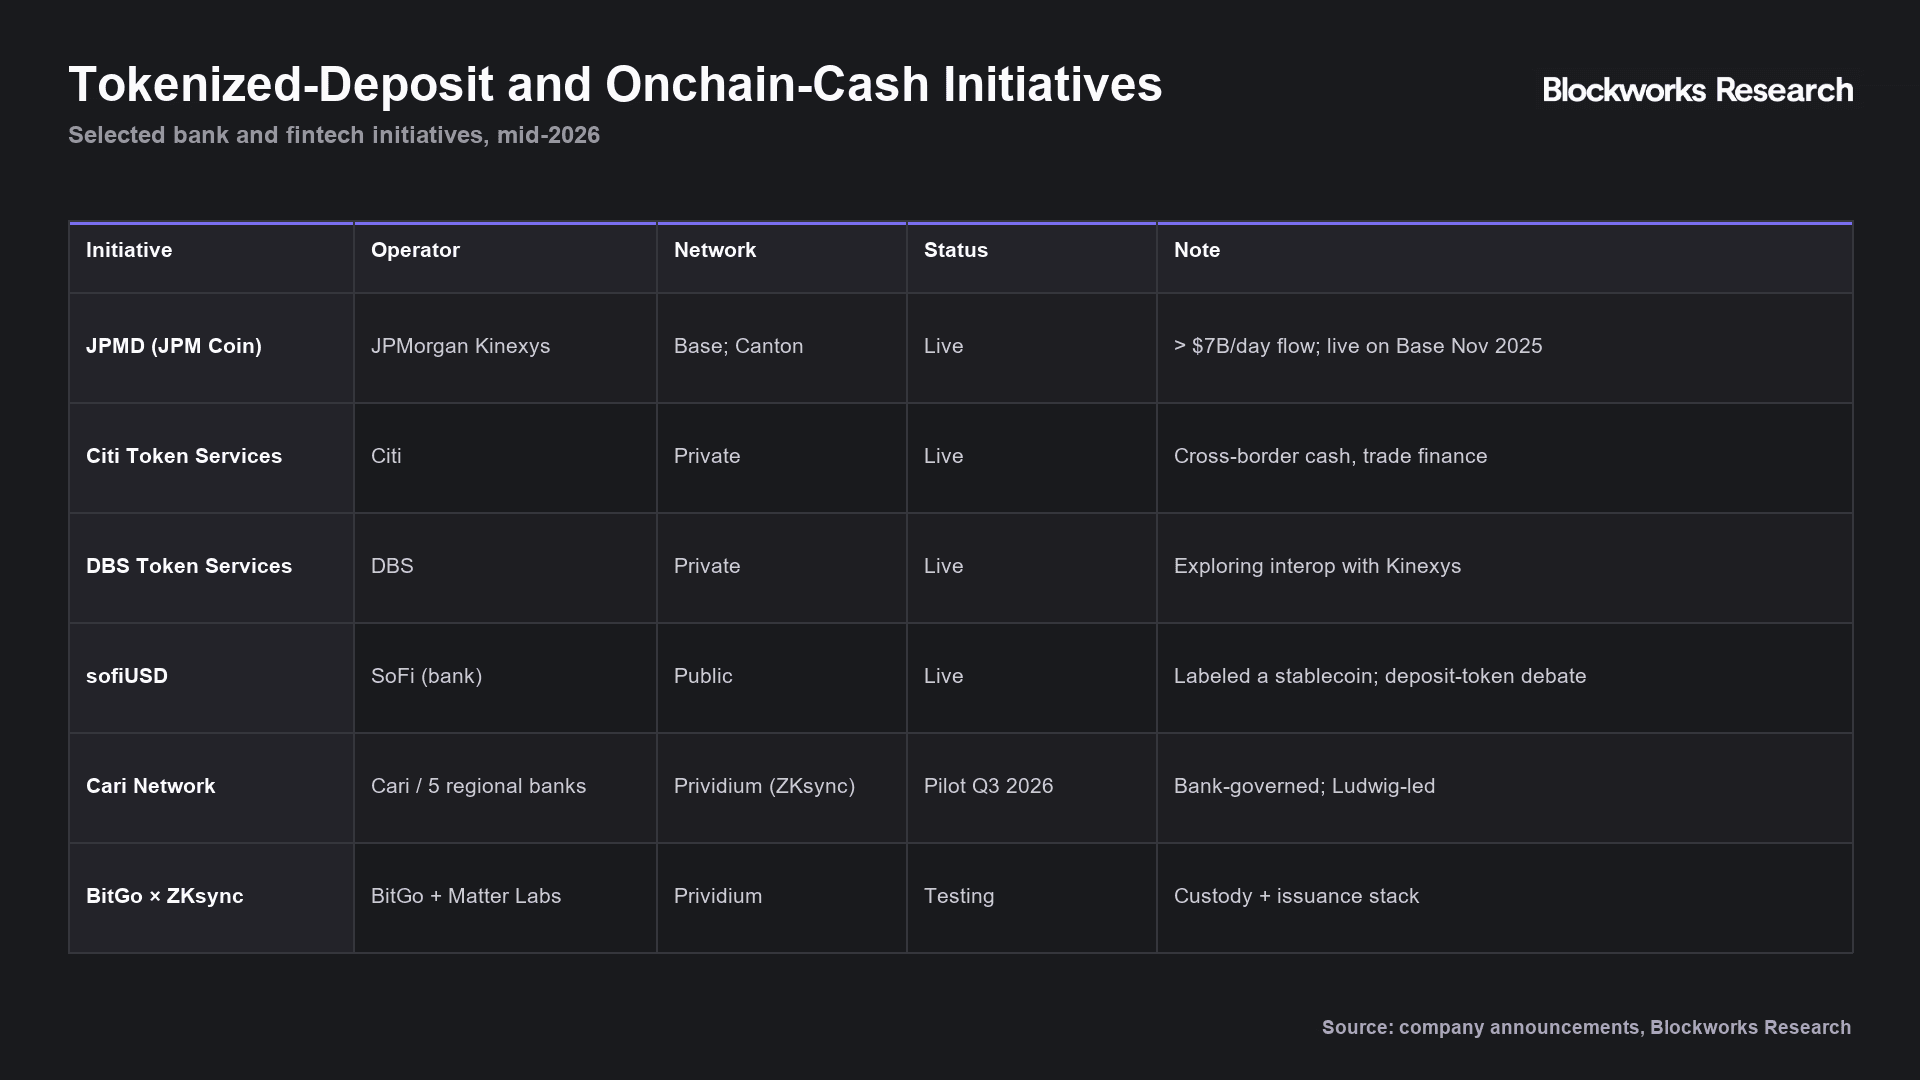
Notably, the deposit-versus-stablecoin taxonomy is not always clean. SoFi's sofiUSD, issued by a chartered bank but backed primarily by short-term Treasuries and FDIC-insured cash rather than standard bank deposits, was debated as a deposit token wearing a stablecoin label.
What it takes for a bank to issue onchain
Banks have wanted onchain settlement for years: cheaper clearing, programmable treasury operations, liquidity that does not stop at 5pm. Infrastructure is what stopped them. A public chain exposes balances and counterparties. A fully private chain gives up the public liquidity and neutral settlement that make the exercise worth doing. Three requirements have to hold at once, and until recently no stack met all three.
- **Confidentiality - **A bank cannot publish client balances, positions, and payment flows to a public ledger. It needs transaction-level privacy while still proving the ledger is correct.
- **Compliance - **KYC, AML, sanctions screening, and auditability have to be enforceable in the protocol, not bolted on afterward. Regulators need selective visibility; competitors and the public need none.
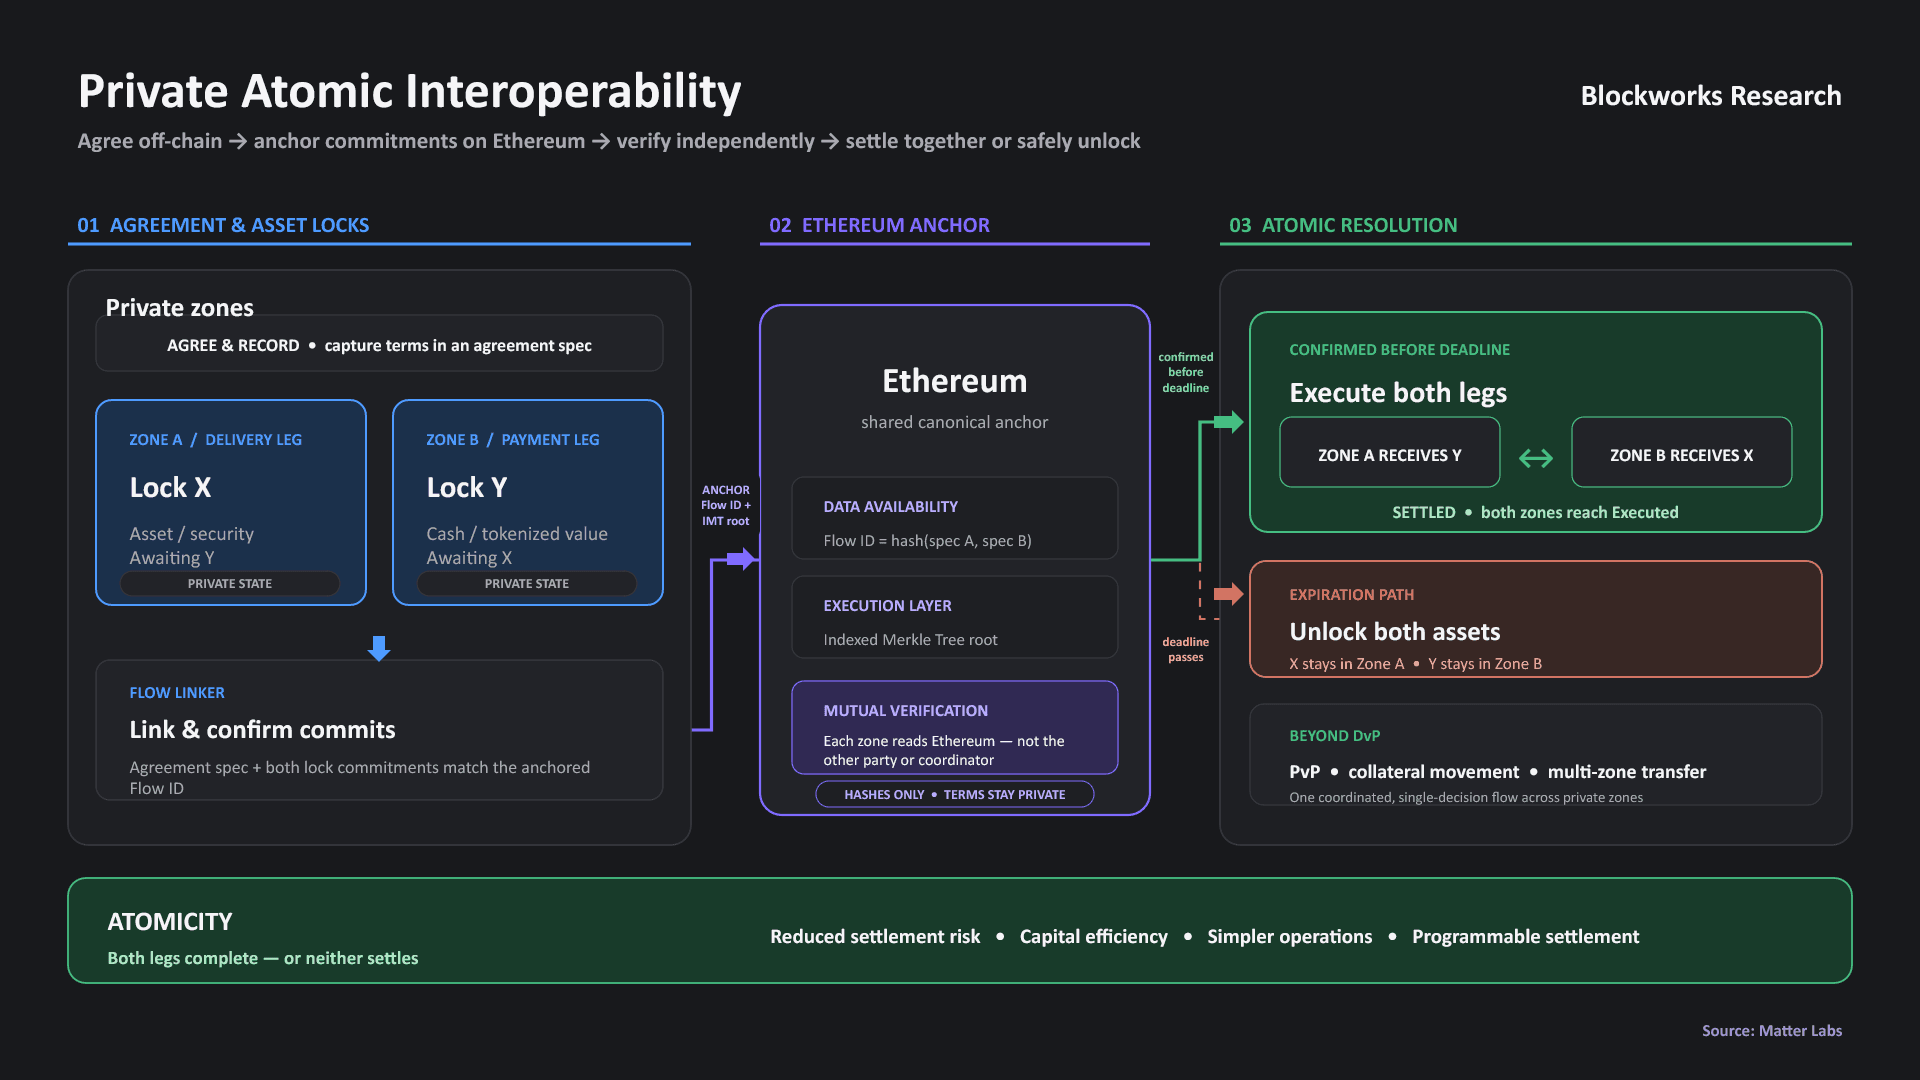
- **Interoperability - **Onchain money is worth less if it is trapped. A deposit token has to reach public liquidity, other institutions, and other networks with atomic delivery-versus-payment, or it becomes another walled garden no better than the correspondent system it was meant to replace.
Banks expect to govern their own environment, from transaction ordering to policy enforcement to upgrade authority, rather than rent it from someone else. The market has tried three answers. Bank-proprietary chains, such as JPMorgan's early Onyx work, solve control and privacy but are islands. Public L2 deployments solve interoperability and liquidity but struggle with confidentiality. Permissioned, zero-knowledge chains try to hold privacy and public settlement together at the same time, and this is the category Matter Labs is targeting with Prividium.
Prividium is a private, permissioned L2 built on the ZKsync Stack and anchored to Ethereum. Each institution runs its own chain under its own governance. Execution happens privately, while zero-knowledge proofs posted to Ethereum attest that the chain's state transitions are valid without revealing the underlying transactions. Compliance is handled through selective disclosure: the operator can prove sanctions screening, reserves, or specific balances to a regulator on demand, without exposing them to the public. ZKsync’s private interoperability is designed to move value across chains with atomic settlement so a deposit token can reach public liquidity without leaving the compliance perimeter. ZKsync also uses CCIP to connect Prividium to other networks as well.
The appeal is that a bank does not have to choose between a private ledger and decentralized settlement. Institutions can also join without operating their own infrastructure. The tradeoff, as with any young stack, is that these guarantees are still being proven under production load. Prividium is one credible implementation of the private-execution with public-settlement pattern, not the only one. Canton, proprietary bank chains, and other L2s are chasing variants of the same goal. For a bank, the question is less about which cryptography and more about which stack reaches a compliant, interoperable deployment fastest, and who else is already on it. Whether tokenized deposits become a network or a set of islands depends on how that interoperability works.
Against legacy rails
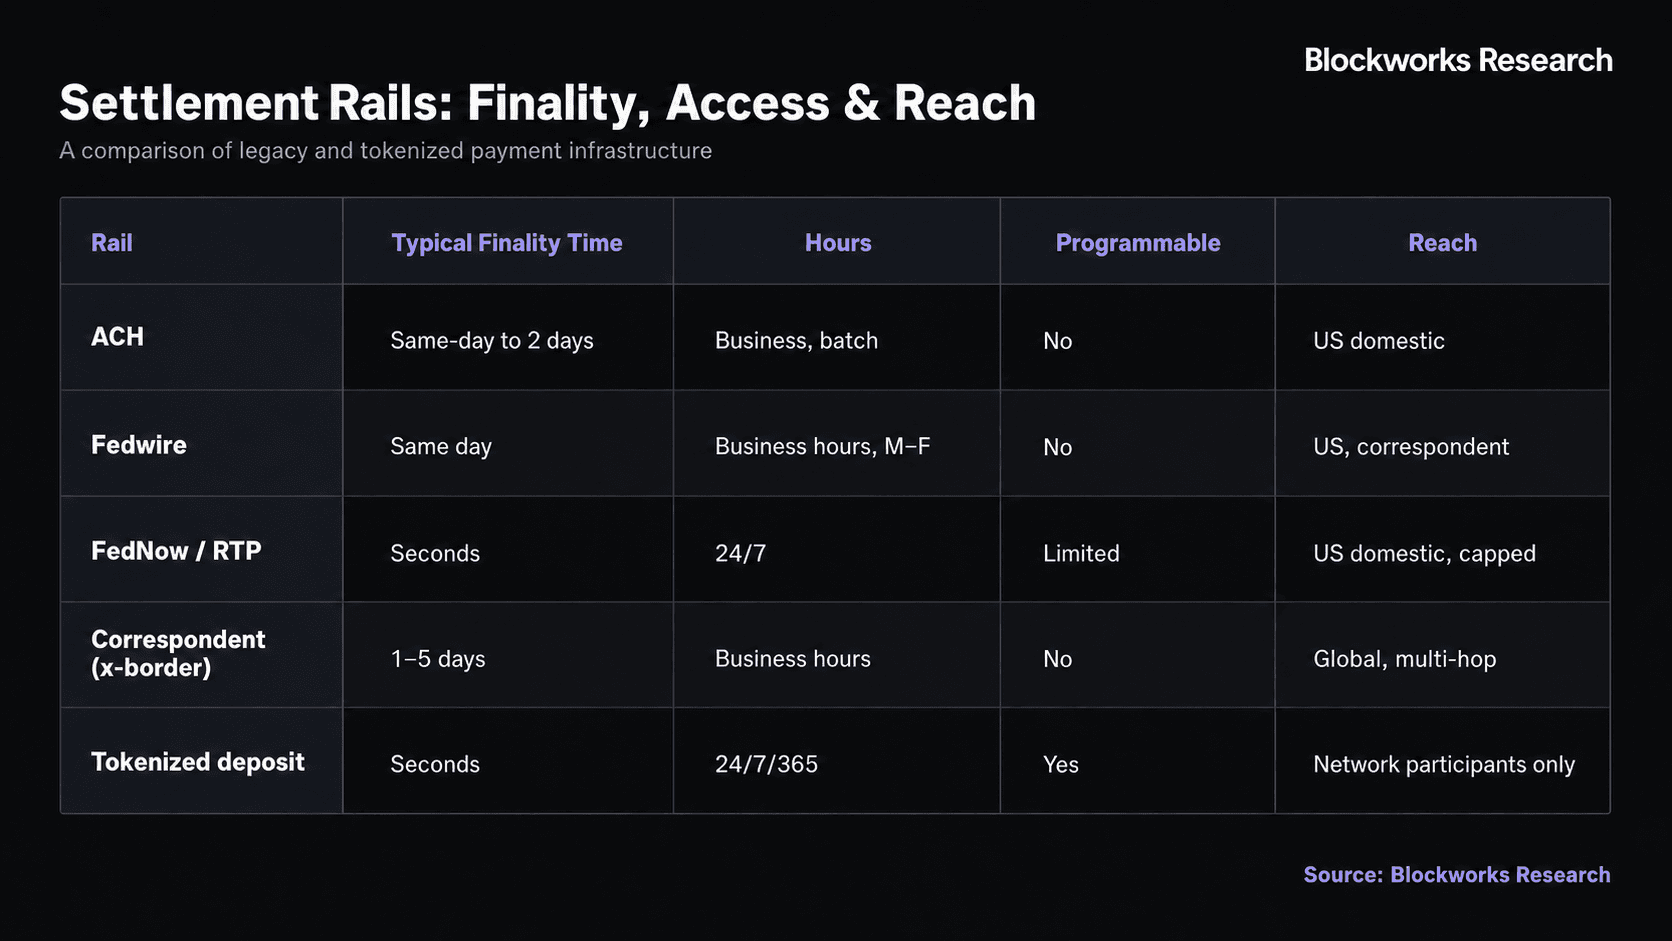
The reason any of this is worth the effort is the comparison with what banks use now. Domestic batch and wire systems clear on business-day timelines or inside limited windows; correspondent cross-border payments still take days and pass through several intermediaries. FedNow and RTP closed part of the speed-and-hours gap, but they are domestic (US-based), capped, and not programmable. A tokenized deposit is near-instant, runs every day of the year, settles with onchain finality, and is programmable, as long as the counterparty is on the network. A deposit token's value scales with reach, and reach is exactly what a permissioned system limits by design.In securities settlement the problem is not speed. Cash and the asset move on separate rails, so firms post collateral against the gap between them and keep staff on hand for the trades that break. Atomic DvP removes the gap, so the collateral and reconciliation burden associated with that gap can be reduced.
The first live tests: Cari and BitGo
Cari and BitGo provide the first announced deployment pathways for Prividium.
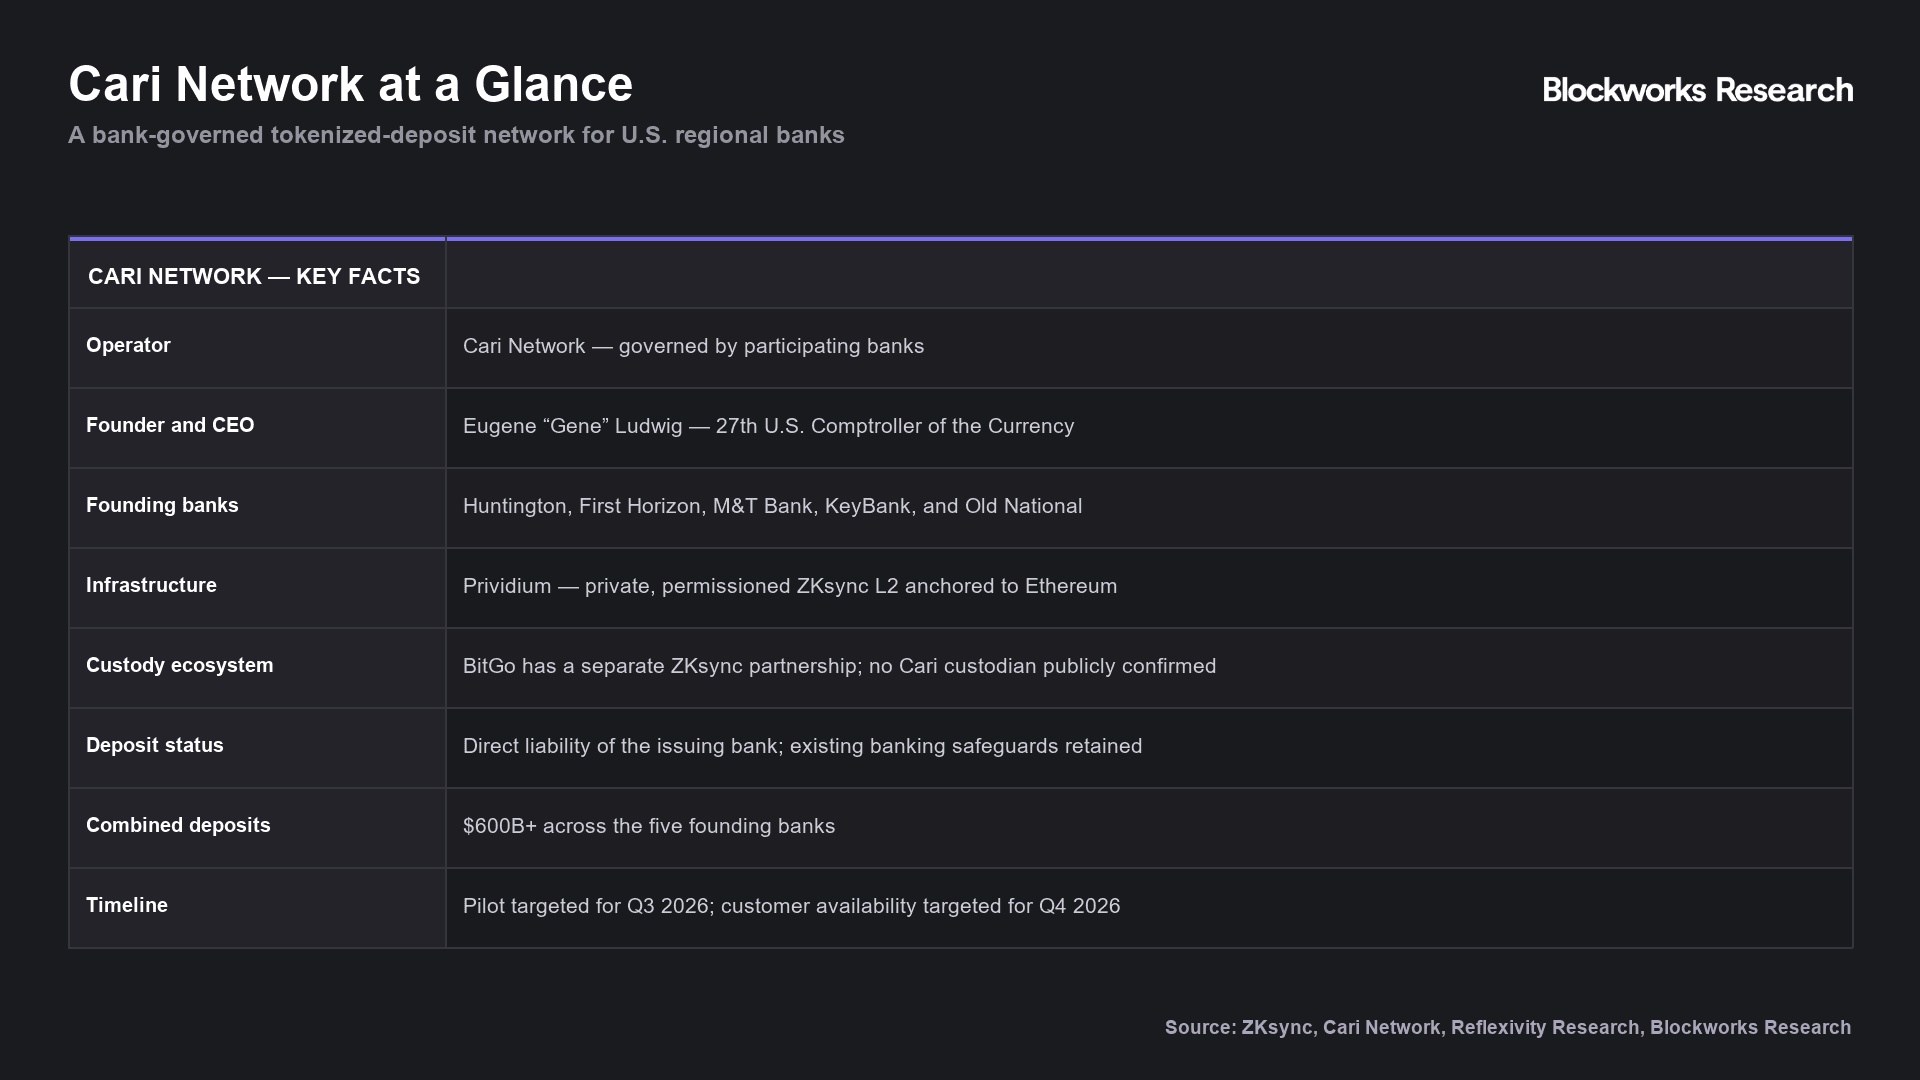
Cari Network is a bank-governed tokenized-deposit network built on Prividium and led by Eugene Ludwig, the 27th Comptroller of the Currency. Its five founding banks, Huntington, First Horizon, M&T, KeyBank, and Old National, are regional and mid-size institutions, the segment most exposed to deposit flight toward stablecoins and large-bank programs. Total participation has expanded to more than 30 institutions, with another 40 in active discussions. The network and pipeline represent banks with more than $10 trillion in combined assets. Cari has also joined the American Bankers Association’s Premier Partner Network, giving it a platform to work with ABA members on tokenized deposits and digital-money infrastructure. Deposits on Cari remain on each bank's balance sheet as regulated deposit liabilities, retaining the same regulatory and insurance treatment as the underlying deposit. The network adds around-the-clock settlement, programmability, and cross-institution transfers. The Mid-Size Bank Coalition of America has signaled support, and the network targets a Q3 2026 pilot with customer availability by Q4.
BitGo, a federally chartered digital-asset institution, is the second deployment. It pairs BitGo's custody and wallet infrastructure with Prividium so a bank can issue, hold, and settle deposit tokens without building the custody stack itself. Whether the BitGo-Prividium stack becomes a default depends on production performance and on how many banks adopt it.
Regulatory backdrop
The GENIUS Act drew the bright line the market now runs on. Payment stablecoins are permitted, but their issuers cannot pay holders yield and cannot extend credit, which keeps them structurally separate from deposits. Tokenized deposits inherit the existing bank rulebook, from capital and liquidity to supervision and insurance, precisely because they are deposits. The proposed CLARITY Act's market-structure framework and the OCC's posture on bank participation fill in where digital assets sit relative to securities and commodities. For deposit tokens, though, it’s much simpler, as they were already regulated. A deposit is a deposit whether it lives in a core banking ledger or on a chain. That is the category's biggest advantage and the reason banks can move relatively quickly.
Outlook
The near-term evidence will come from a handful of live deployments rather than from headline market-size forecasts. If Cari's pilot produces real settlement data in the second half of 2026 and the network signs banks beyond its five founders, the regional-bank tokenized-deposit thesis gets its first proof point. If interoperability stalls, the category stays a set of private ledgers with better latency than the old rails and little else to distinguish them. Either way, stablecoins and deposit tokens look set to coexist rather than converge: the open dollar and the bank dollar, running on shared infrastructure for different reasons.

Marc covers Ethereum, Bitcoin and their L2s. Previously led Ethereum and DeFi research at CoinShares.