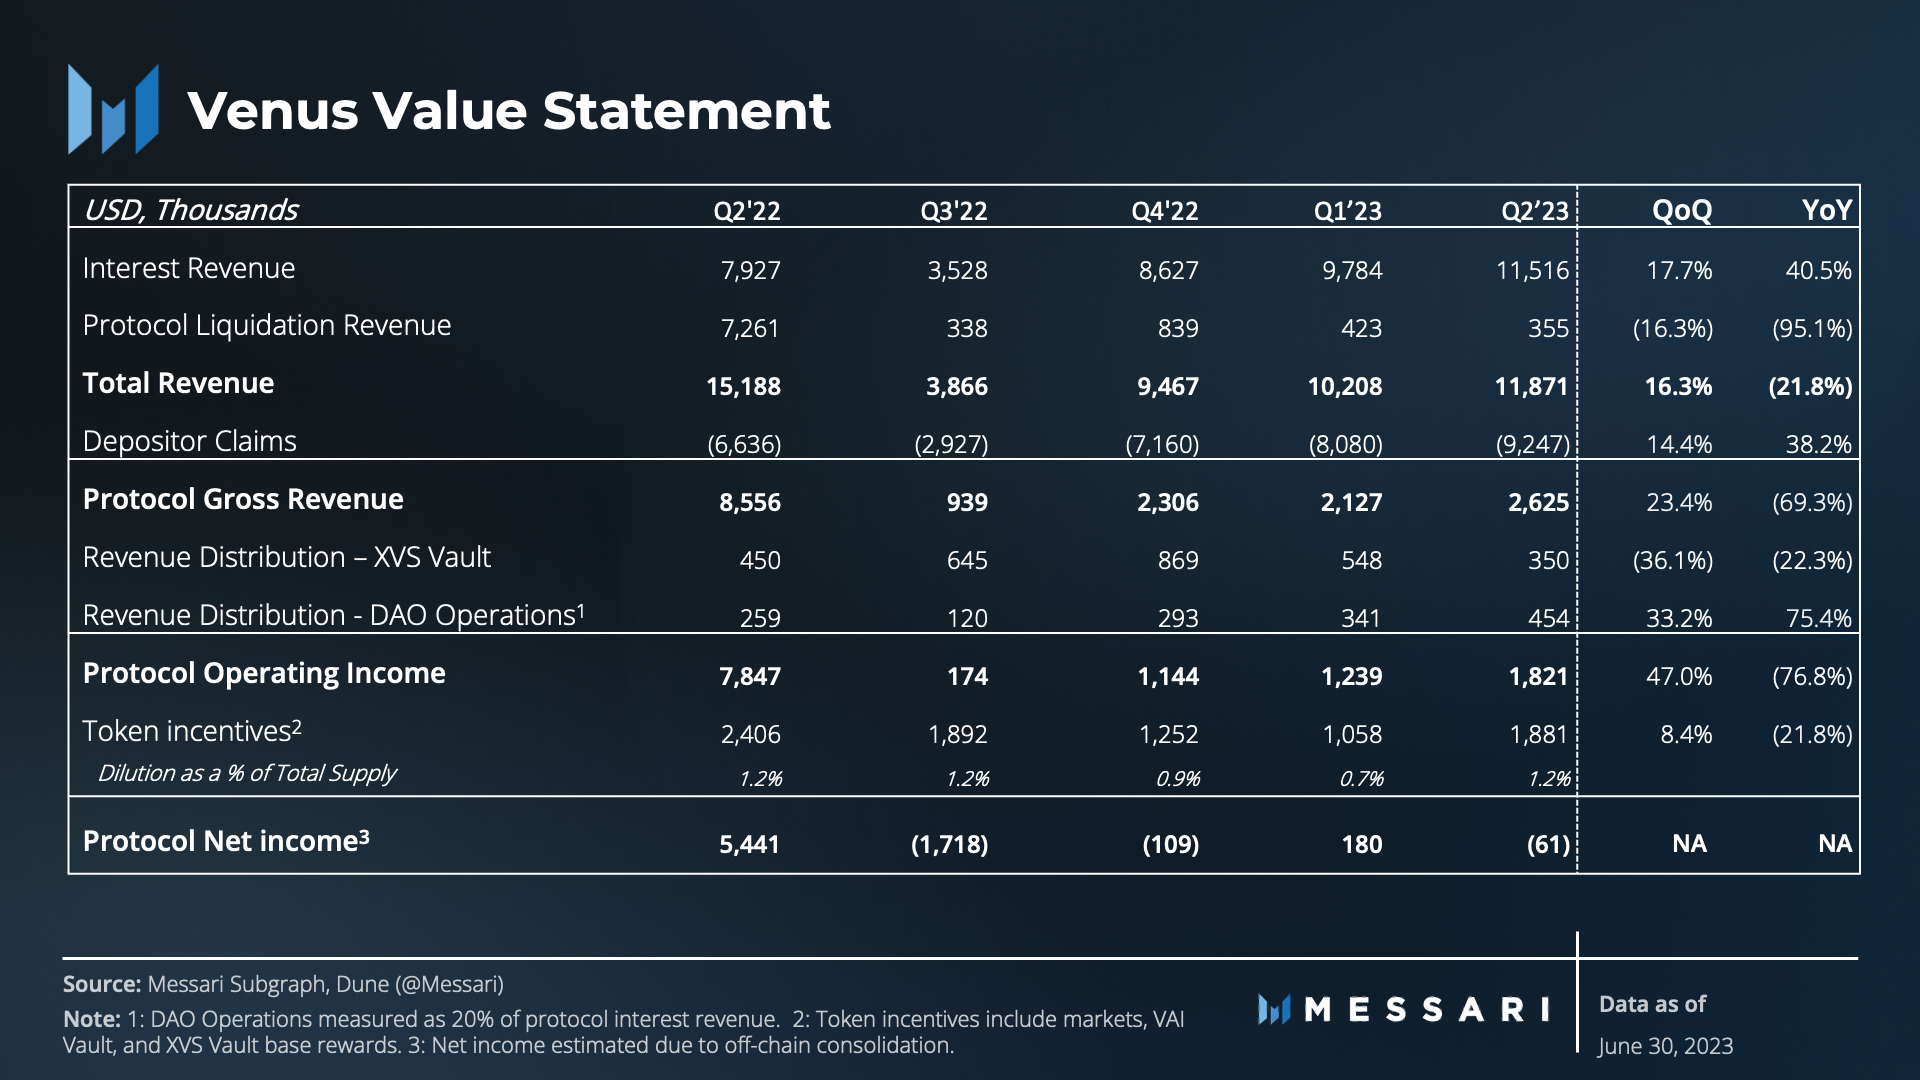
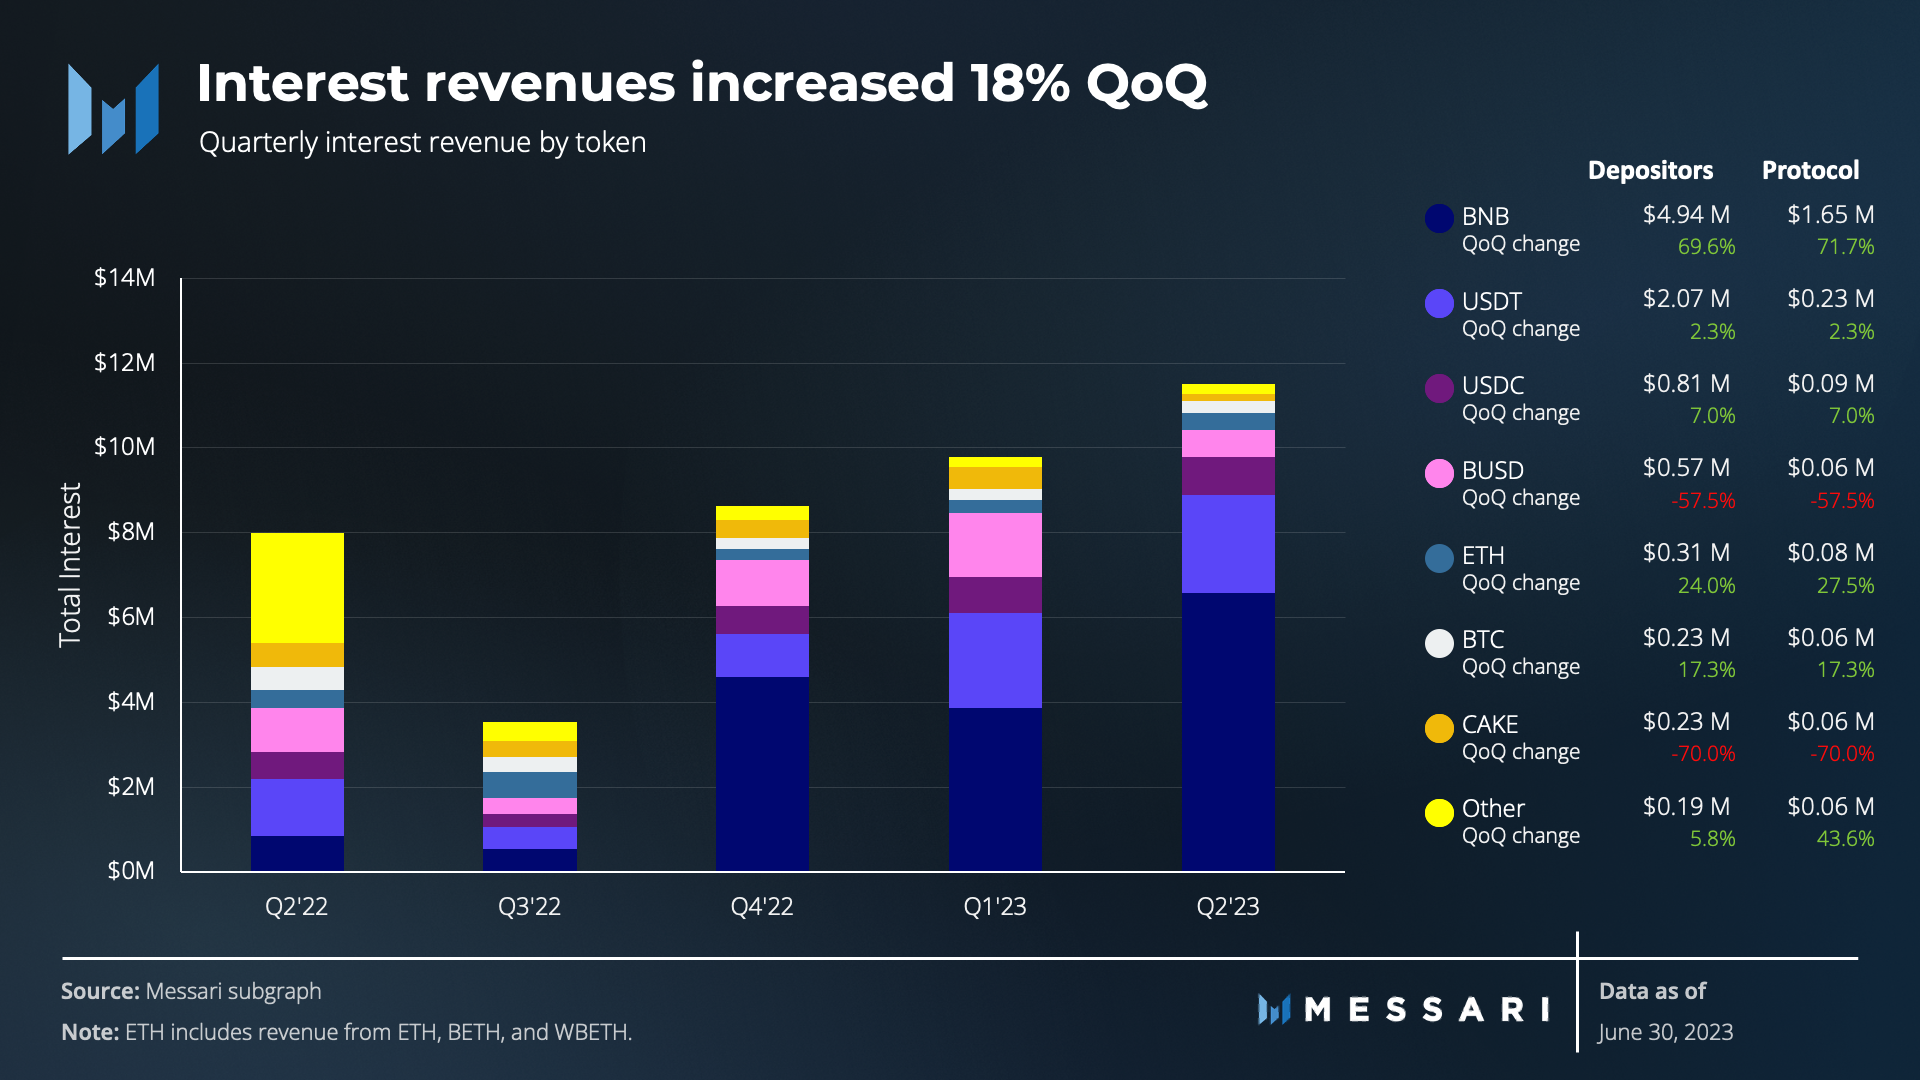
Venus experienced its fourth consecutive quarter of interest revenue growth, generating $2.3 million for the DAO and $9.2 million for depositors.
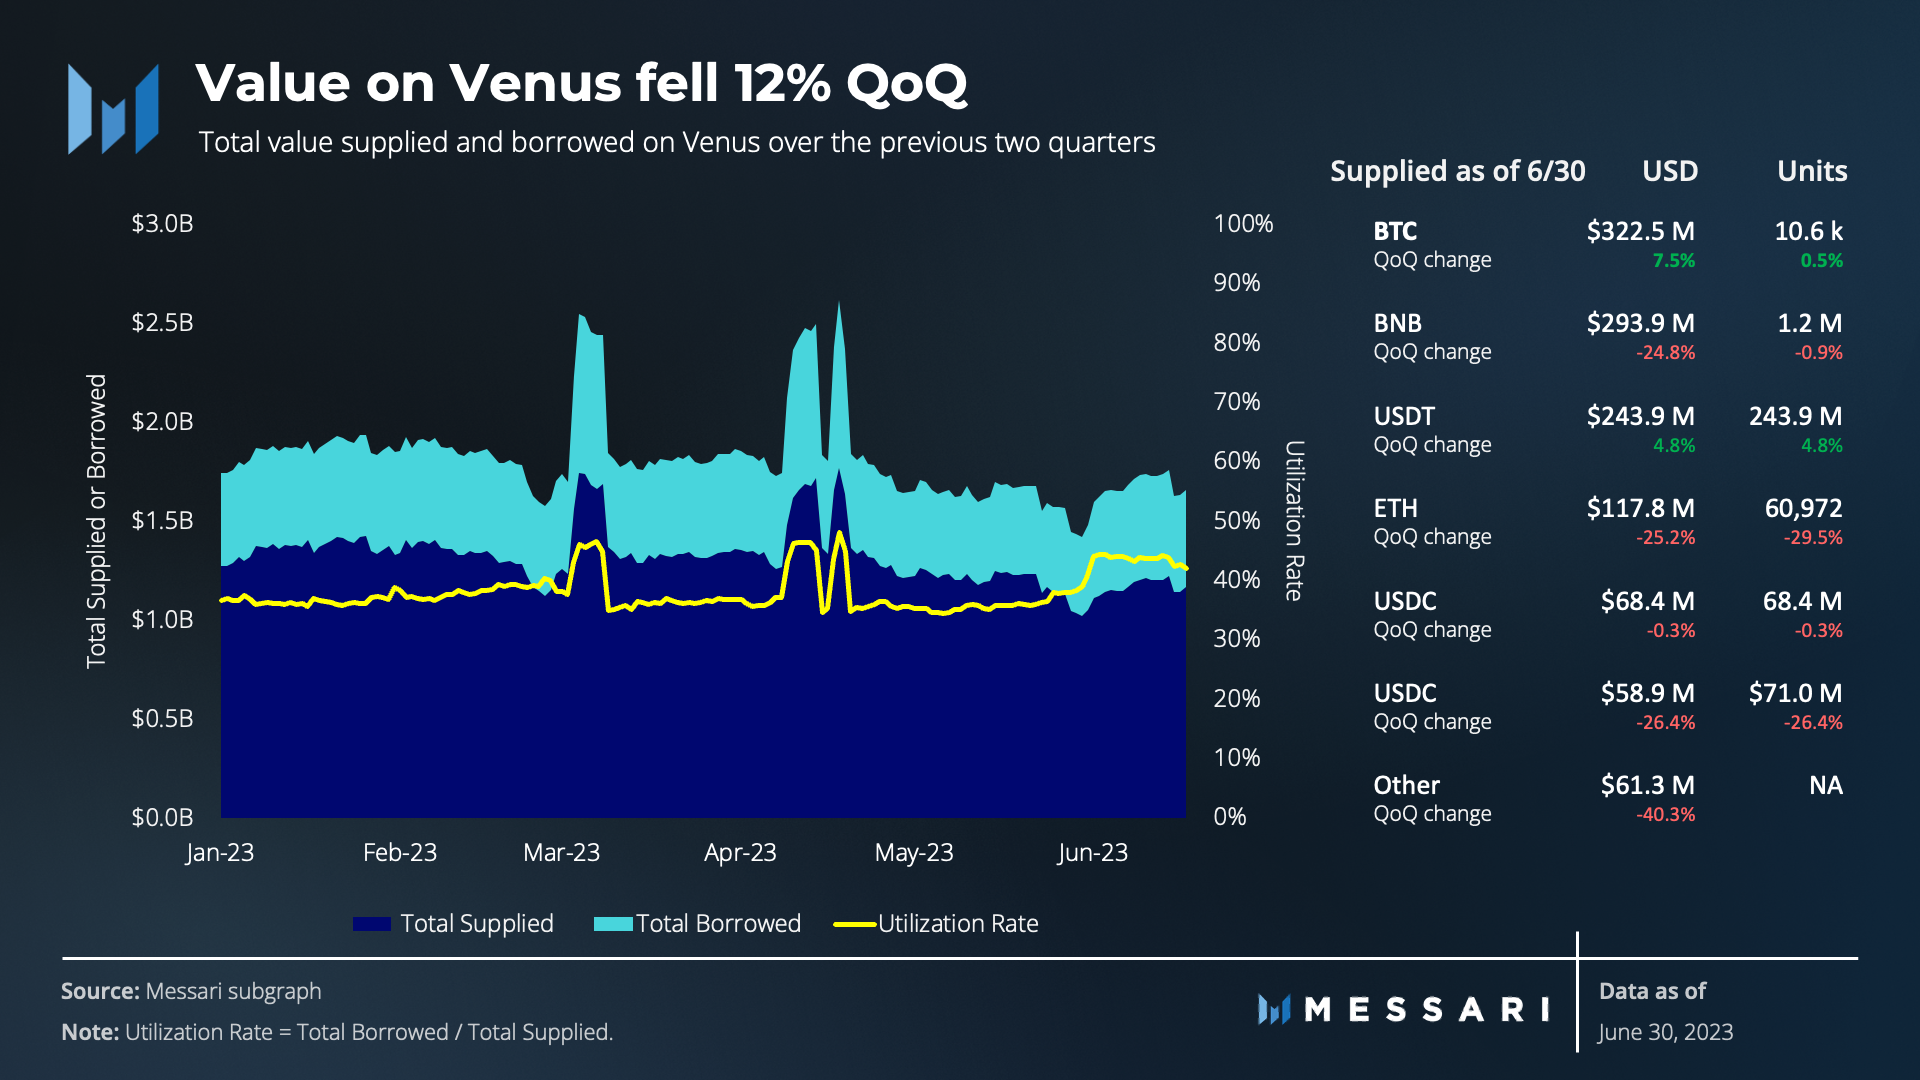
A 32% drop in the price of BNB following SEC charges against various Binance entities affected the total value of assets on Venus, leading to a 12% quarter-over-quarter decrease in total value supplied.
Venus continued to ship its V4 features, including isolated pools and Resilient Price Feeds to enhance the platform's security, flexibility, and reliability.
Adjustments to the interest rate parameters led to higher borrow rates and a decline in user activity in Q2, including a lower-than-usual spike in activity during the Maverick Launchpool event.
Primer on Venus
Venus is a decentralized money market protocol on the BNB Chain that facilitates depositing and borrowing of various cryptoassets. The interest rates for these assets are set algorithmically using an interest rate model that triggers updates based on the proportion of deposited assets lent. This is known as the utilization ratio. The protocol is managed by the Venus DAO community and governed by the XVS token. Users can stake the governance token in a vault to participate in governance and receive a portion of the protocol revenue.
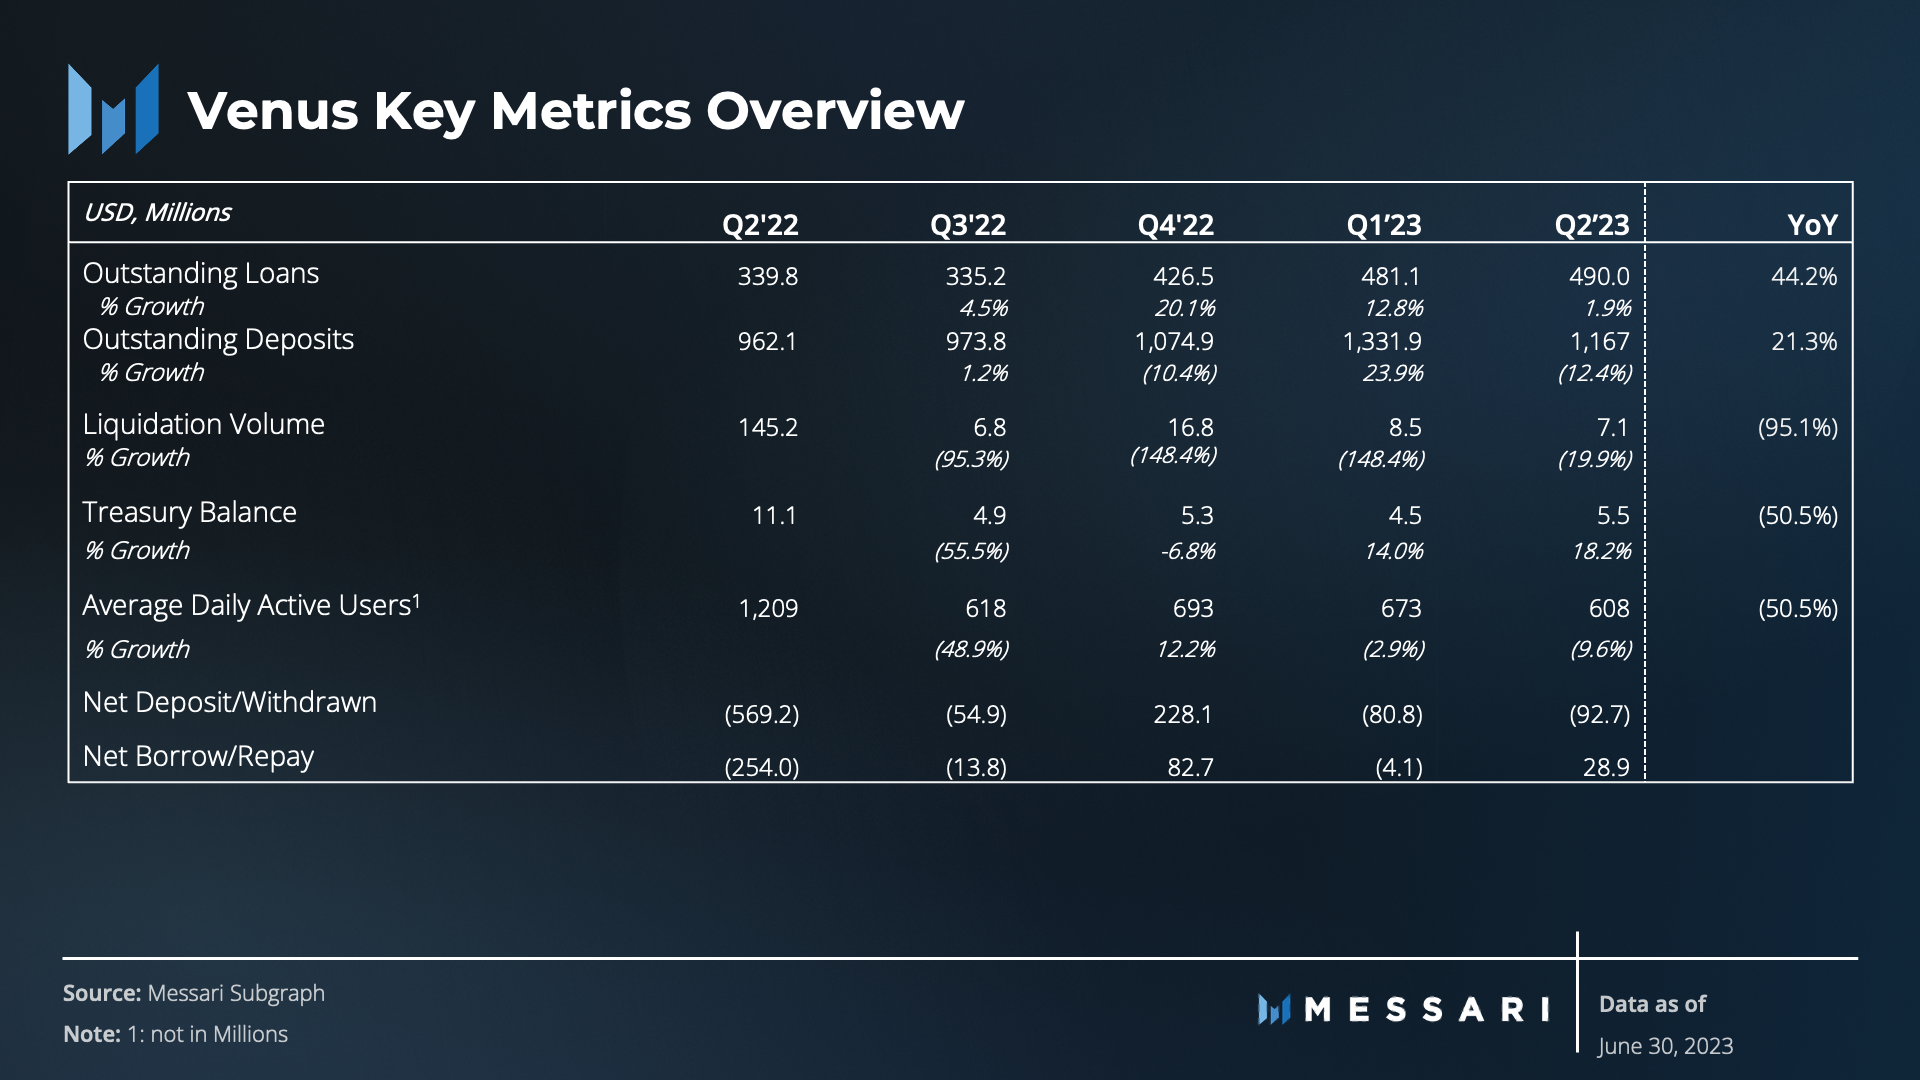
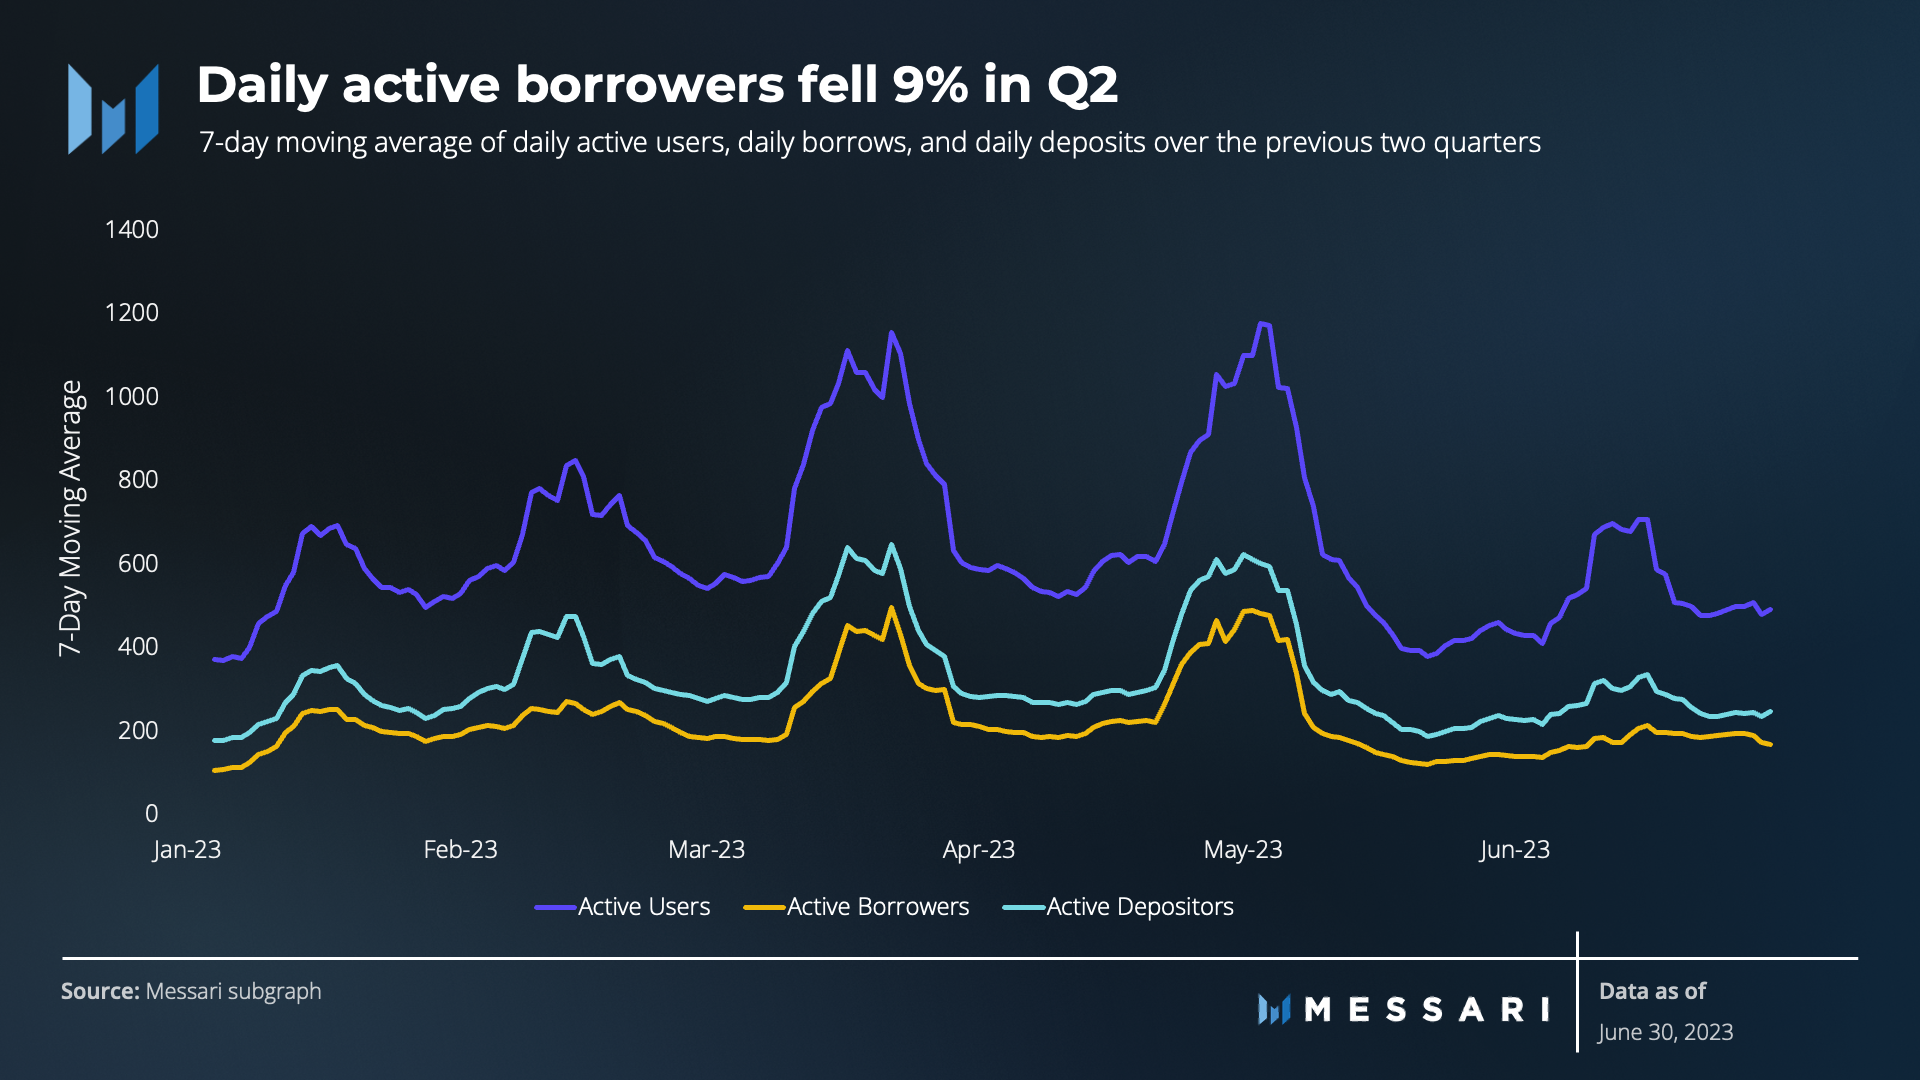
The Venus protocol saw a decline in user activity in Q2, marked by the 9% and 10% QoQ decreases in the number of active borrowers and active depositors, respectively. The fall was largely due to adjustments to the interest rate parameters, which ultimately led to higher borrow rates and subsequently dampened the profitability of leverage strategies.
The Binance Launchpool event, typically a driver of borrowing activity on Venus, also demonstrated the impact of these modifications. Historically, Venus has seen a 100%-200% surge in active borrowers during such events. However, activity didn't spike upon initiation of the Maverick Launchpool in June. Additionally, on June 10, BNB borrowing fell to lows not experienced since January 2021, with only 89,140 units of BNB borrowed.
Total Value Supplied
The total value supplied on Venus experienced a 12% QoQ decrease, even as most cryptoasset prices remained relatively stable. This dip was primarily attributable to a 32% drop in the price of BNB, following the Securities and Exchange Commission's (SEC) decision to file 13 civil charges against various Binance entities. The fallout of this regulatory action impacted the value of assets held on Venus with every non-stablecoin asset experiencing outflows except for BTC, XVS, CAKE, ADA, and MATIC.
Revenue
Interest revenues climbed for the fourth consecutive quarter, reaching $11.5 million. This growth during Q2 was largely due to the further adjustment of interest rate curves as recommended by Gauntlet and the sustained borrowing activities that remain relatively insensitive to rate changes. These adjustments boosted the protocol's interest revenues by 33% and depositor revenues by 14%.
Within this revenue growth, BNB stood out as its revenues surged by 70% QoQ. This uptick will likely continue provided the depositor yields from Binance Launchpool events can retain their high level, and provided the BSC Token Hub exploiter's position does not fall to liquidation levels.
During Launchpool events, large amounts of stablecoins are deposited, and the maximum amount of BNB is borrowed. By holding BNB on Binance Exchange, users can receive tokens from new projects.
By the end of the quarter, the exploiter’s position was approximately 10% away from being subject to liquidation (liquidatable with BNB at ~$220). It landed in this position following $1.3 million of interest expensed on USDC and USDT loans in Q2, and a depositor yield of around ~11,000 BNB (which depreciated with the price of BNB).
Available Liquidity
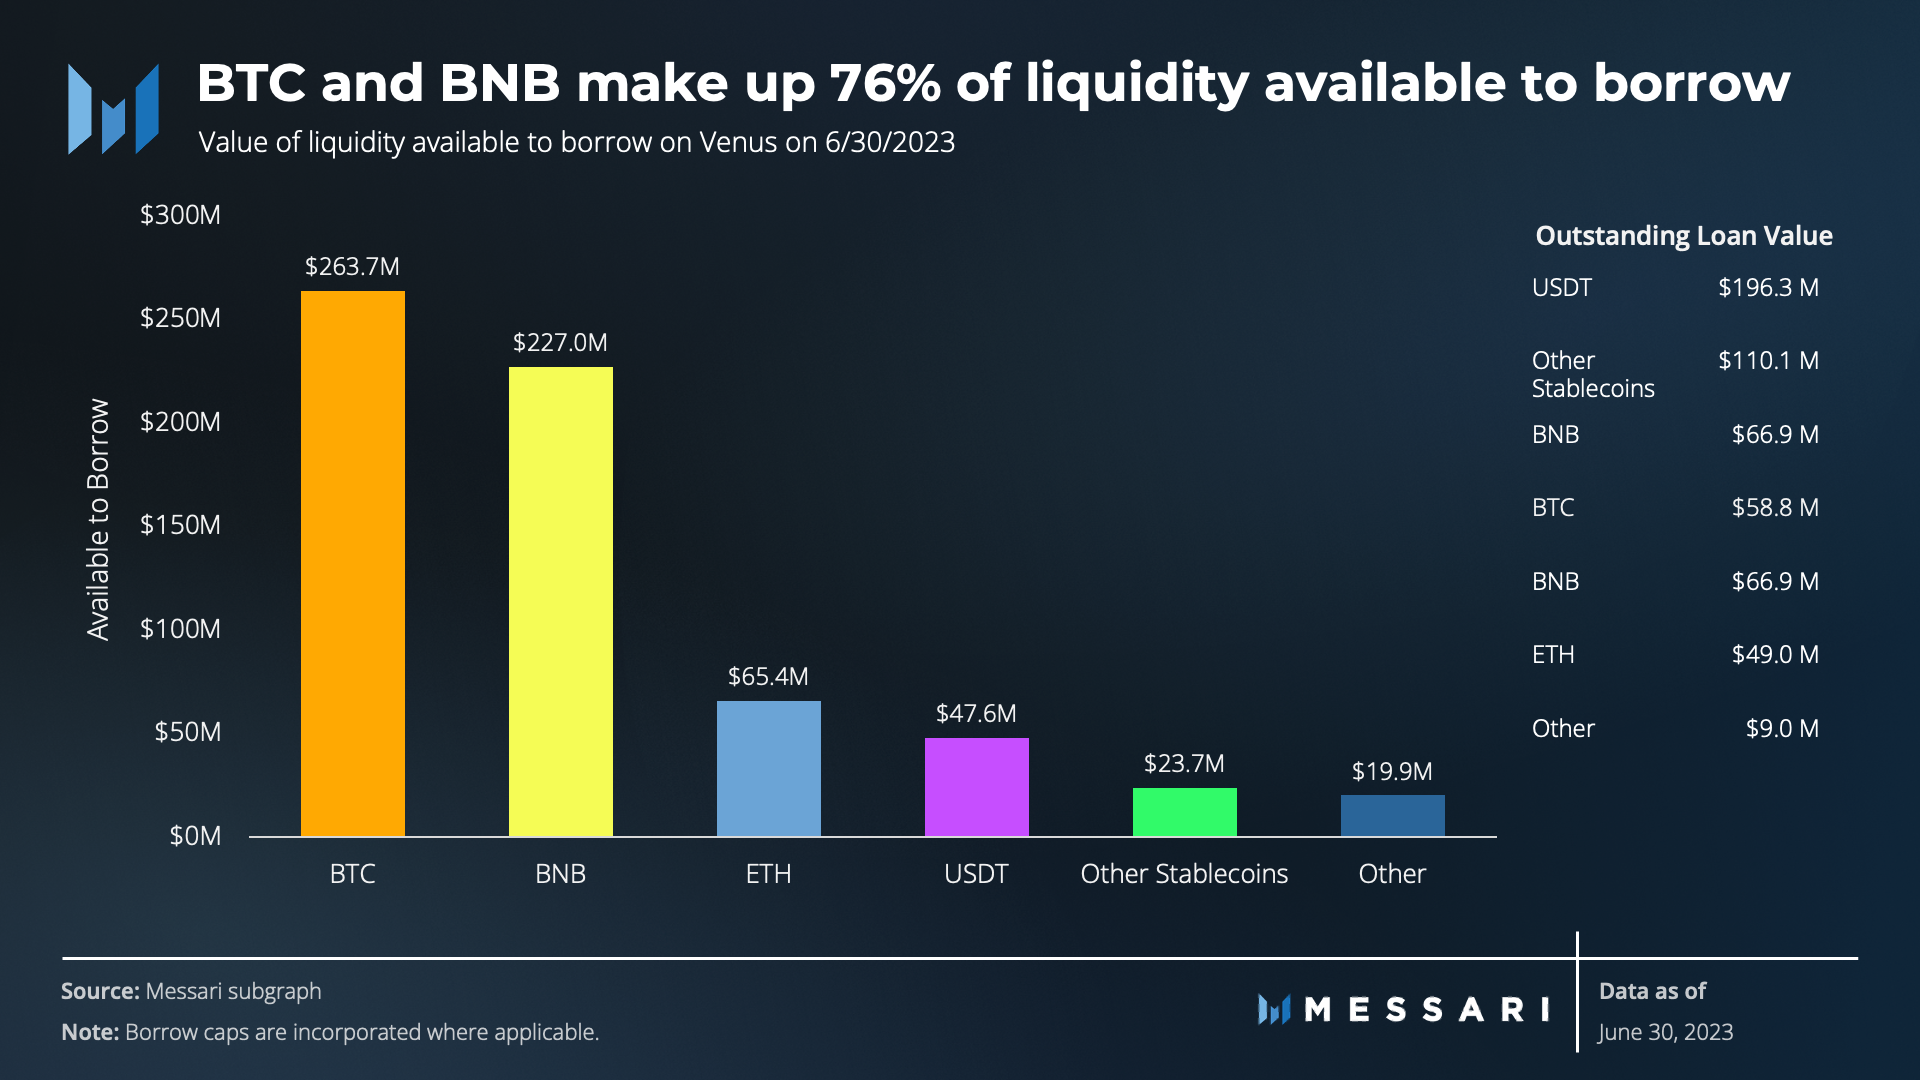
By the end of the quarter, liquidity valued at $647 million remained available for borrowing, with BTC and BNB collectively contributing to 76% of that value. The high utilization of stablecoins largely comes from the outsized position held by the BSC Token Hub attacker, which constitutes 59% of the total outstanding USDT debt and 64% of USDC debt.
Furthermore, a significant portion of the outstanding loans has been outstanding since the liquidation events involving CAN, XVS, and LUNA in 2021 and 2022. Specifically, at least 95% of the BTC loan balance, 24% of the BUSD balance, and 29% of the ETH balance have not been repaid and are currently undercollateralized. Not including the debt of the BSC Token Hub attacker, Venus currently has $83 million of bad debt in the protocol. Collectively, these debts of $238 million represent nearly half of the total outstanding loan value on Venus. With its focus on managing the debt, the Venus team has stated it is almost ready to ship new smart contract automations for repaying shortfalls with interest income.
Revenue vs. XVS Rewards
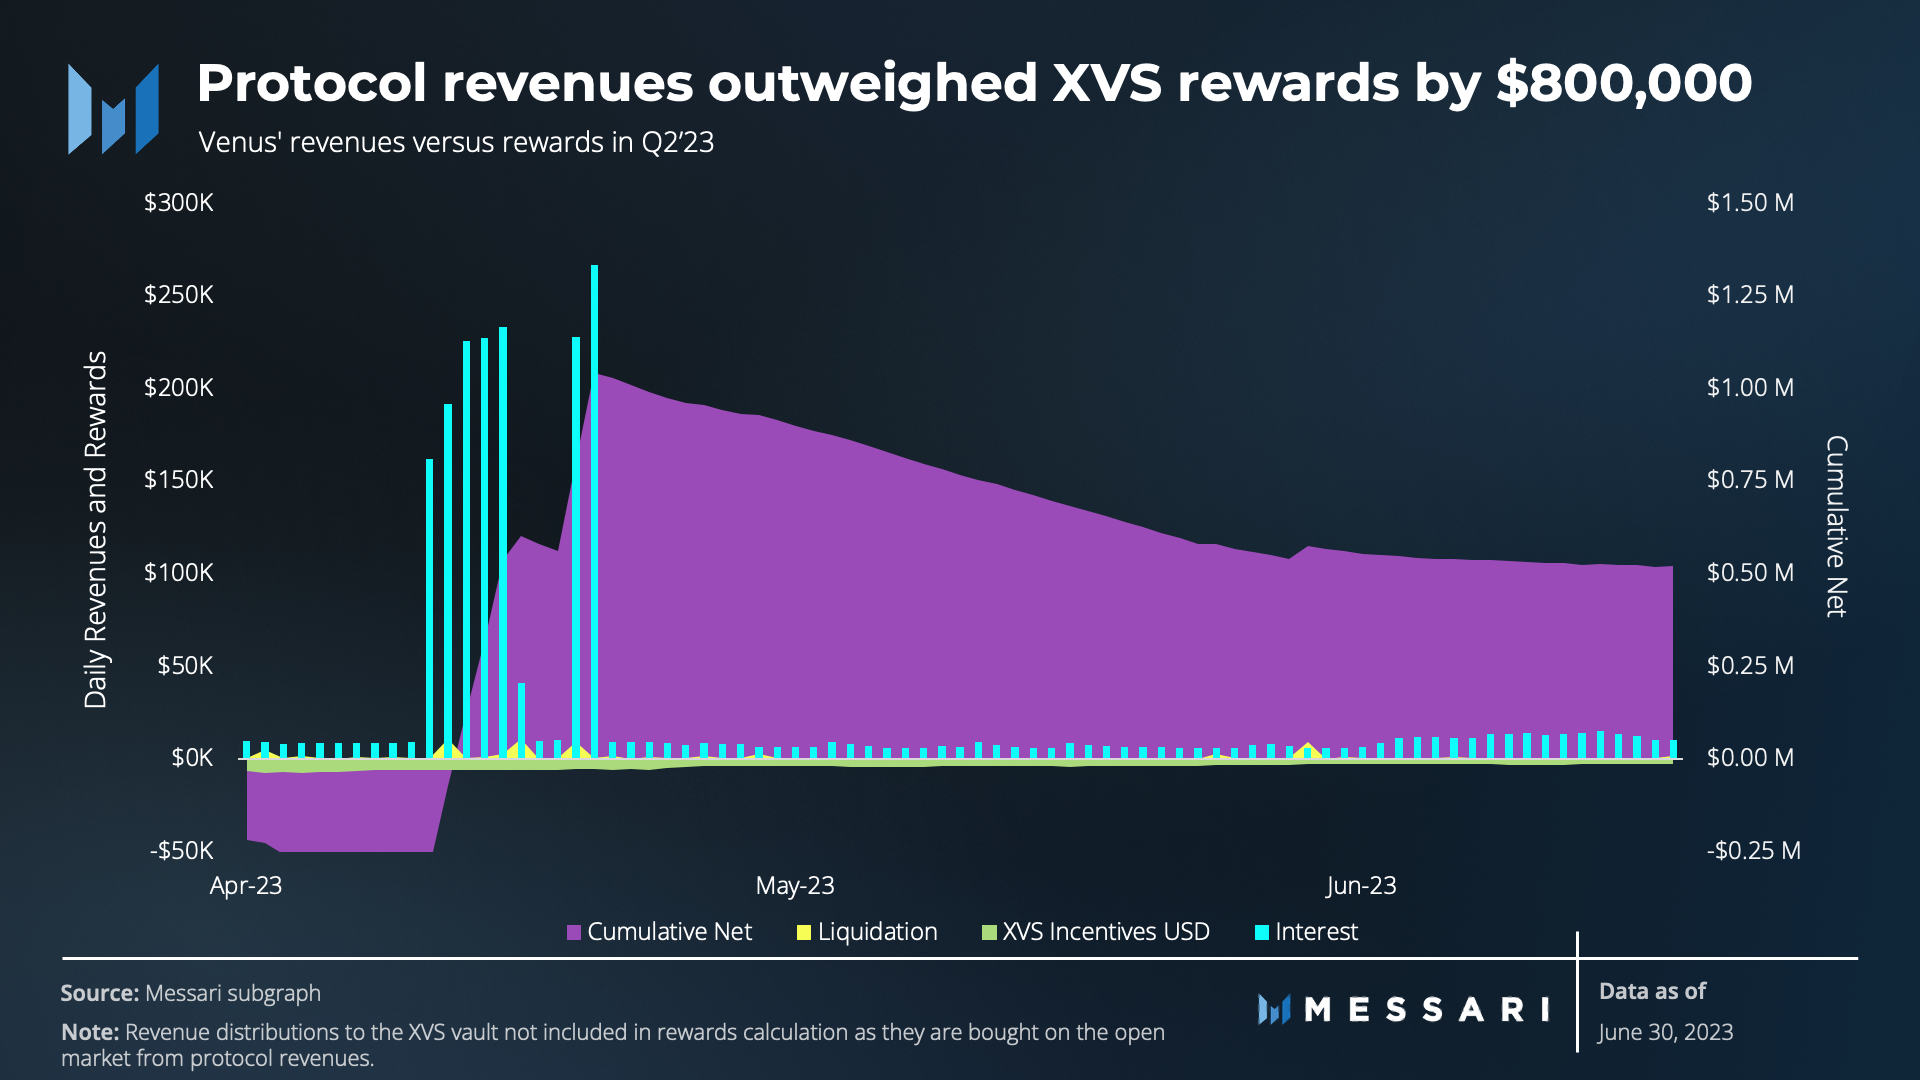
In the second quarter, protocol interest and liquidation revenues surpassed the XVS incentives disbursed to users by a margin of $800,000. This surplus was largely generated during the SUI Launchpool and Open Campus Launchpad events. They accounted for 68% of the quarterly interest revenue as represented by the spikes in interest revenue.
However, the Maverick Launchpool event, which commenced on June 14, didn't exhibit a corresponding surge in interest revenues. This suggests that BNB leverage may have been sourced from other platforms, despite the BNB borrow rate on Venus hitting a yearly low.
The effect of Gauntlet’s interest curve optimizations, implemented on June 1, is also evident. Following the adjustments, daily interest revenues in June saw a significant uptick of 34% compared to May, after isolating to after the SUI Launchpool on May 3. The interest curve modifications had a positive impact on revenue generation, affirming the importance of managing borrowing costs on the platform.
XVS Vault
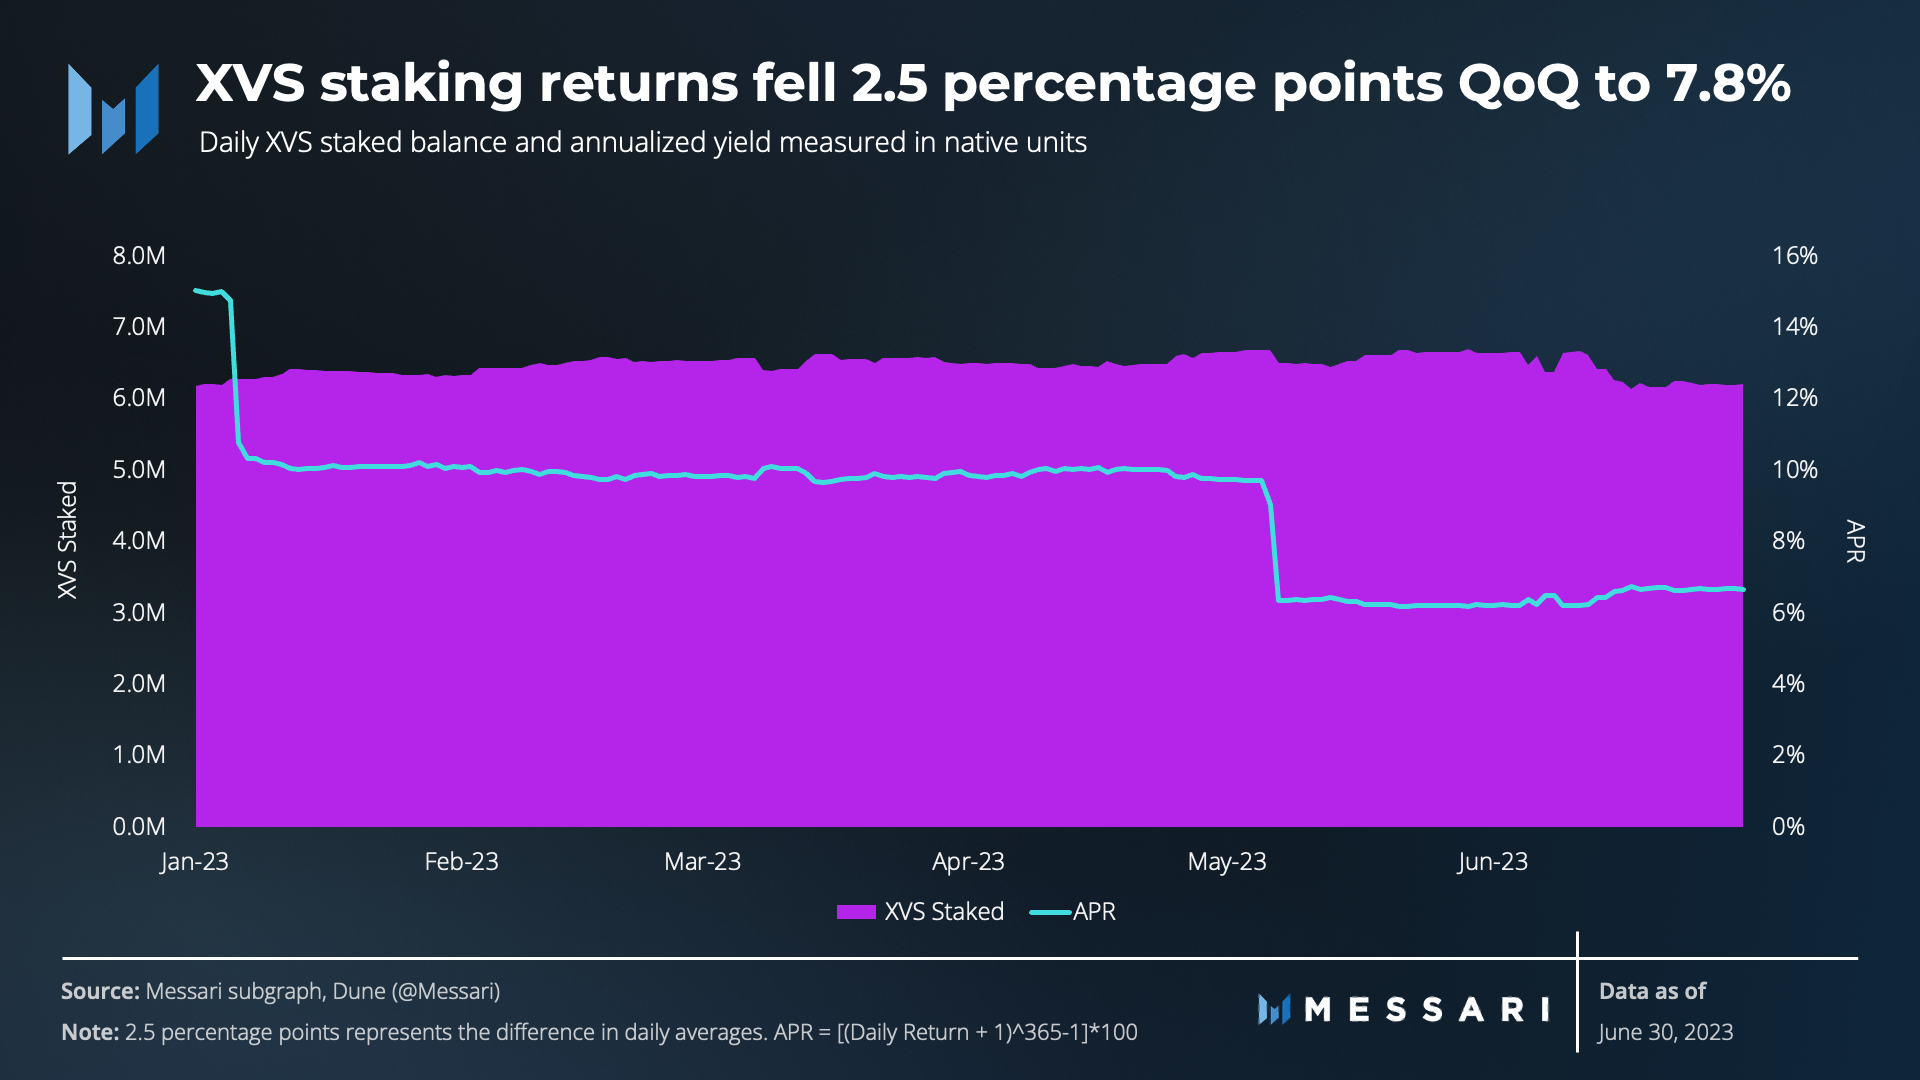
In addition to $354,000 in base rewards, XVS stakers received $350,000 in XVS tokens from protocol revenue distributions. While base rewards saw a considerable surge of 46%, revenue distributions experienced a drop of 36%. The enactment of VIP-113 effectively doubled the daily base rewards from 525 to 1,100 XVS. Additionally, the vault saw a net outflow of 290,000 XVS compared to a net inflow of 337,000 XVS in Q1. The proposal also included the following expectations about getting back to 9% APR in the next quarter:
"Due to various ongoing changes and audits, we were not able to adjust the XVS Vault distribution APR until today and more XVS have been distributed in the earlier weeks, thus the need to further lower the APR for the remainder of this quarter to compensate for the extra XVS that were already distributed. We expect the APR will return to above 9% in our next Quarter due to the excellent performances Venus has seen over the past few weeks."
Borrower Perspective
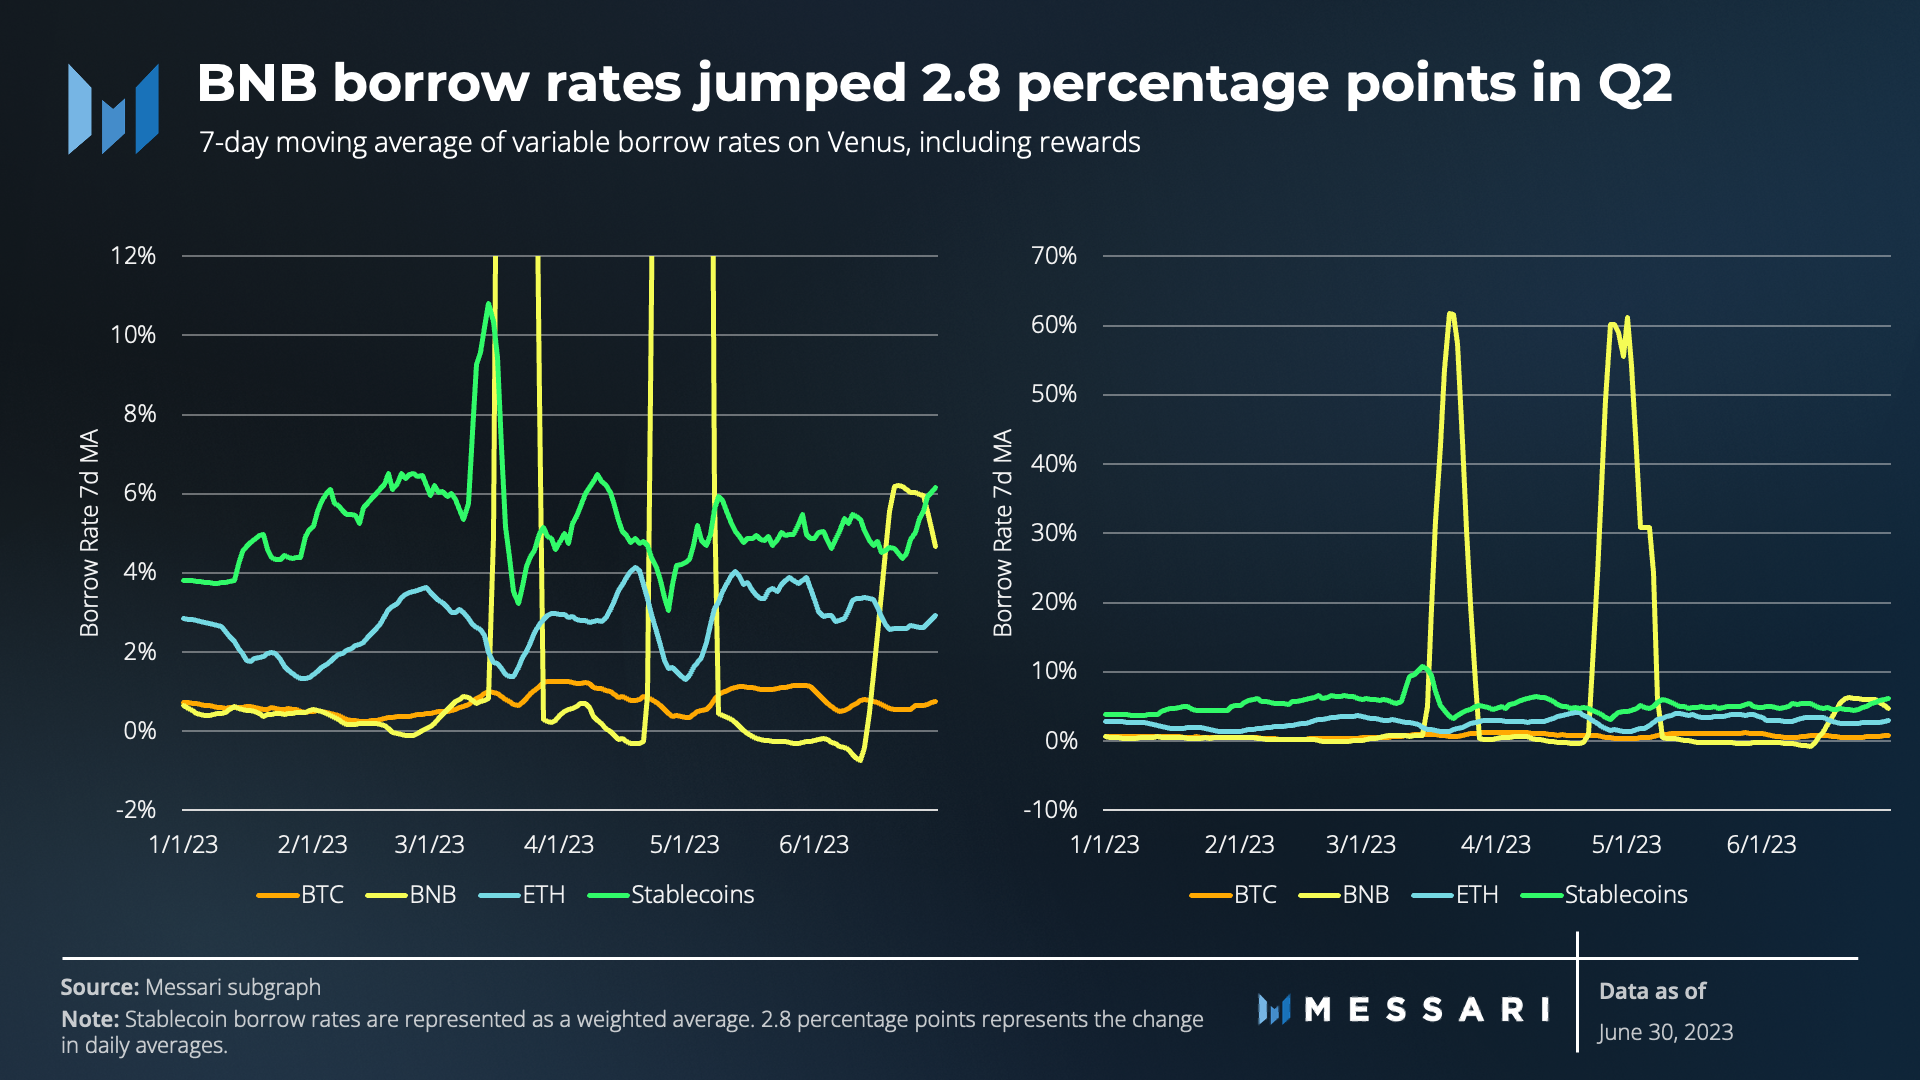
Overall, BNB Borrow rates experienced the largest increase out of the categories above, with the daily average increasing by 2.8 percentage points in Q2. However, from May 12 to June 12, the XVS incentives earned from BNB borrowing outweighed the cost of borrowing by an average of 36 basis points. When this happens, users borrowing BNB effectively receive boosted yields, assuming prices remain constant. In short, these users earn positive returns on both their collateral and loans. While the average stablecoin borrow rate remained relatively flat, elevated rates at the end of the quarter look to be sticky due to withdrawn liquidity.
Qualitative Analysis
Isolated Pools
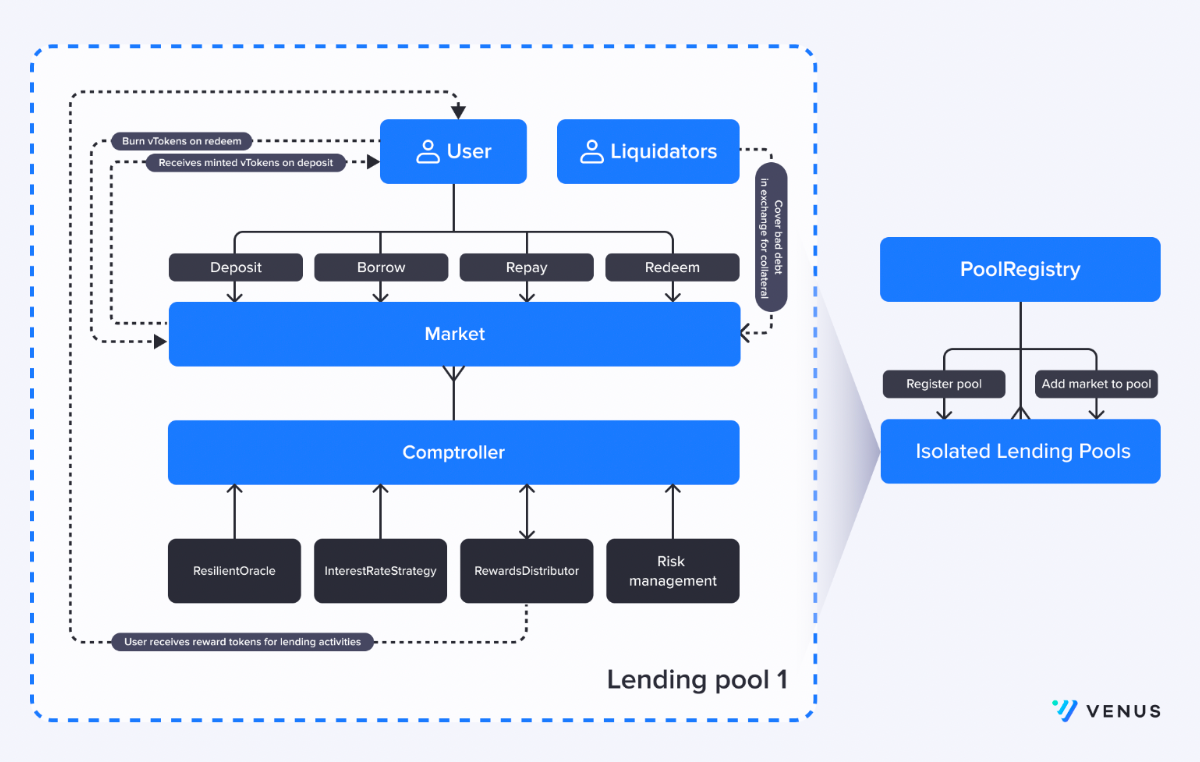
The Venus team continues to roll out new features and is moving closer to realizing the Venus V4 vision. One of the Q2 developments was the introduction of the "isolated pool" feature, including categories such as stablecoins, DeFi, Liquid Staked BNB, GameFi, and TRON as well as the initial support for nearly 20 new markets.
These isolated pools are separate from the Venus Core Pool. Instead, they represent individual lending markets with unique parameters. The creation of these isolated pools expands the horizons for users, offering a broader spectrum of assets to leverage within the DeFi space and beyond.
As shown above, Venus’ isolated pools offer various advantages over traditional pools. Foremost, isolated pools promise an extra layer of security because disturbances in one pool do not ripple across to others within the protocol. With systematic risks being mitigated, users can better assess their investment considerations based on a specific pool. This flexibility empowers users to better align their investments with their financial goals.
Continuing on this trajectory, Venus is set to release the second stage of isolated lending in Q3, featuring the launch of four new isolated pools in categories such as DeFi, GameFi, Liquid Staking BNB, and TRON.
Resilient Price Feeds
In Q2, Venus V4 reached another significant milestone with the introduction of Resilient Price Feeds via VIP-123.
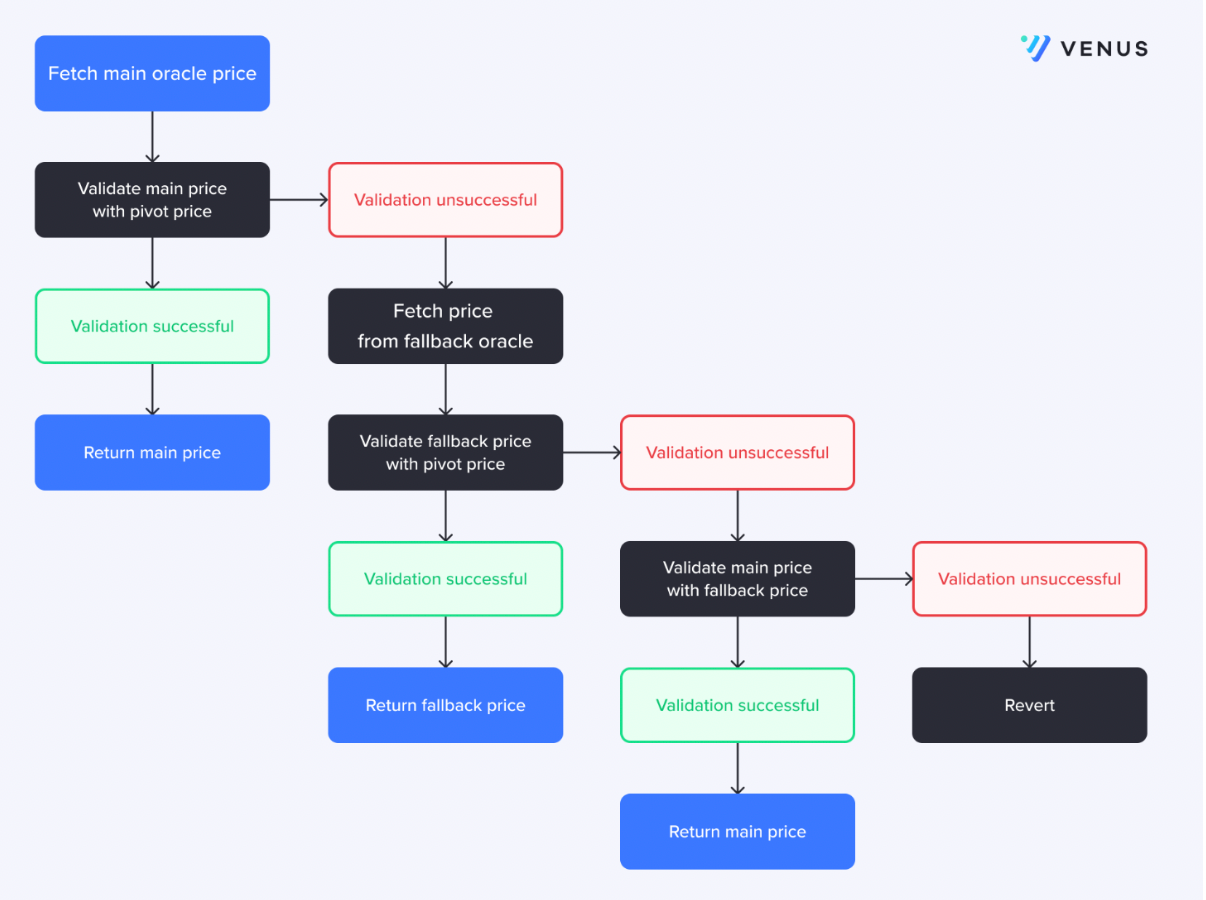
Resilient Price Feeds provide an additional layer of security to the Venus protocol by incorporating multiple oracle support, sense checking, and fallback mechanisms. Their design primarily aims to eradicate the risk of a single point of failure when fetching real-time asset prices.
For context, when LUNA was included as a collateral asset on Venus in May 2022, it was exclusively dependent on Chainlink price feeds for real-time pricing updates. This LUNA price feed contract was hard-coded with a minimum value of approximately $0.10, accompanied by a circuit breaker that halted pricing updates once this threshold was reached.
When LUNA's market price significantly fell below its hard-coded minimum of $0.10, the Venus market continued to process transactions at this minimum value, due to the lack of stale price detection in the Venus market. This discrepancy between the actual and processed prices led to the creation of bad debt for the protocol. Users exploited the bug before the Venus team could pause the system for security maintenance.
To prevent similar instances in the future, Venus implemented Resilient Price Feeds to effectively handle such situations. The current implementation incorporates integrations with a multitude of reputable sources including Chainlink, Pyth Network, Binance Oracle, PancakeSwap, and soon, RedStone Oracles. This multi-source approach ensures a more accurate and reliable representation of asset prices, thereby enhancing the stability of the Venus protocol.
Bad Debt Repayment
Venus Protocol has encountered multiple instances of bad debt since its inception in 2020. However, a rise in revenues from BNB loans has positioned the protocol to start addressing these bad debts and liberate liquidity.
In Q2, the protocol's risk fund successfully repaid 1,437.5 ETH and 90.3 BTC, amounting to a total value of approximately $5 million, as per VIP-118 and VIP-121. However, the balance of the risk fund cannot be confirmed publicly on-chain. Upon examination of the repayment transactions, it was observed that the funds for the BTC and ETH repayments were transferred to the treasury from distinct addresses approximately 4 days and 3 days prior to proposal execution, respectively. The wallet for which ETH was repaid still carries a debt of 2,945 ETH, and the BTC wallet has an outstanding debt of 1,825 BTC. It was also observed that the BTC borrower was liquidating XVS to repay the BTC up until September 2022, and currently possesses approximately 73,000 XVS rewards which Venus considers to be burned for accounting.
Closing Summary
The Venus community experienced activity growth in Q2, executing a total of 27 proposals, a significant increase from 18 in Q1, and hosting over 100 AMAs in a variety of languages. Despite experiencing a downturn in daily usage during Q2, the protocol has continued to advance in its development. The heightened borrow rates impacted the profitability of leveraging strategies and altered user behavior during the most recent, typically high-activity, Binance Launchpool event. Notably, the total value supplied on Venus suffered a 12% QoQ decrease, primarily due to BNB’s price drop following SEC charges against various Binance entities.
Despite these challenges, the protocol saw its fourth consecutive quarter of growth in revenue, reaching $11.5 million. This growth can be attributed to interest rate adjustments and borrowing activities that were relatively insensitive to rate changes. By the end of Q2, liquidity valued at $647 million remained available for borrowing, with BTC and BNB making up the lion's share.
This report was commissioned by VenusDAO. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Looking to dive deeper? Subscribe to Messari Pro. Messari Pro memberships provide access to daily crypto news and insights, exclusive long-form daily research, advanced screener, charting & watchlist features, and access to curated sets of charts and metrics. Learn more at messari.io/pro.
Prior to joining Messari, Kentrell worked in real estate finance. After first diving into crypto in 2019, he became fascinated with DeFi in 2020, drawn to its data transparency, real-time settlement capabilities, and high yields. Today, Kentrell spends his time researching more sustainable yield strategies and writing about DeFi protocols at Messari.
Prior to joining Messari, Kentrell worked in real estate finance. After first diving into crypto in 2019, he became fascinated with DeFi in 2020, drawn to its data transparency, real-time settlement capabilities, and high yields. Today, Kentrell spends his time researching more sustainable yield strategies and writing about DeFi protocols at Messari.