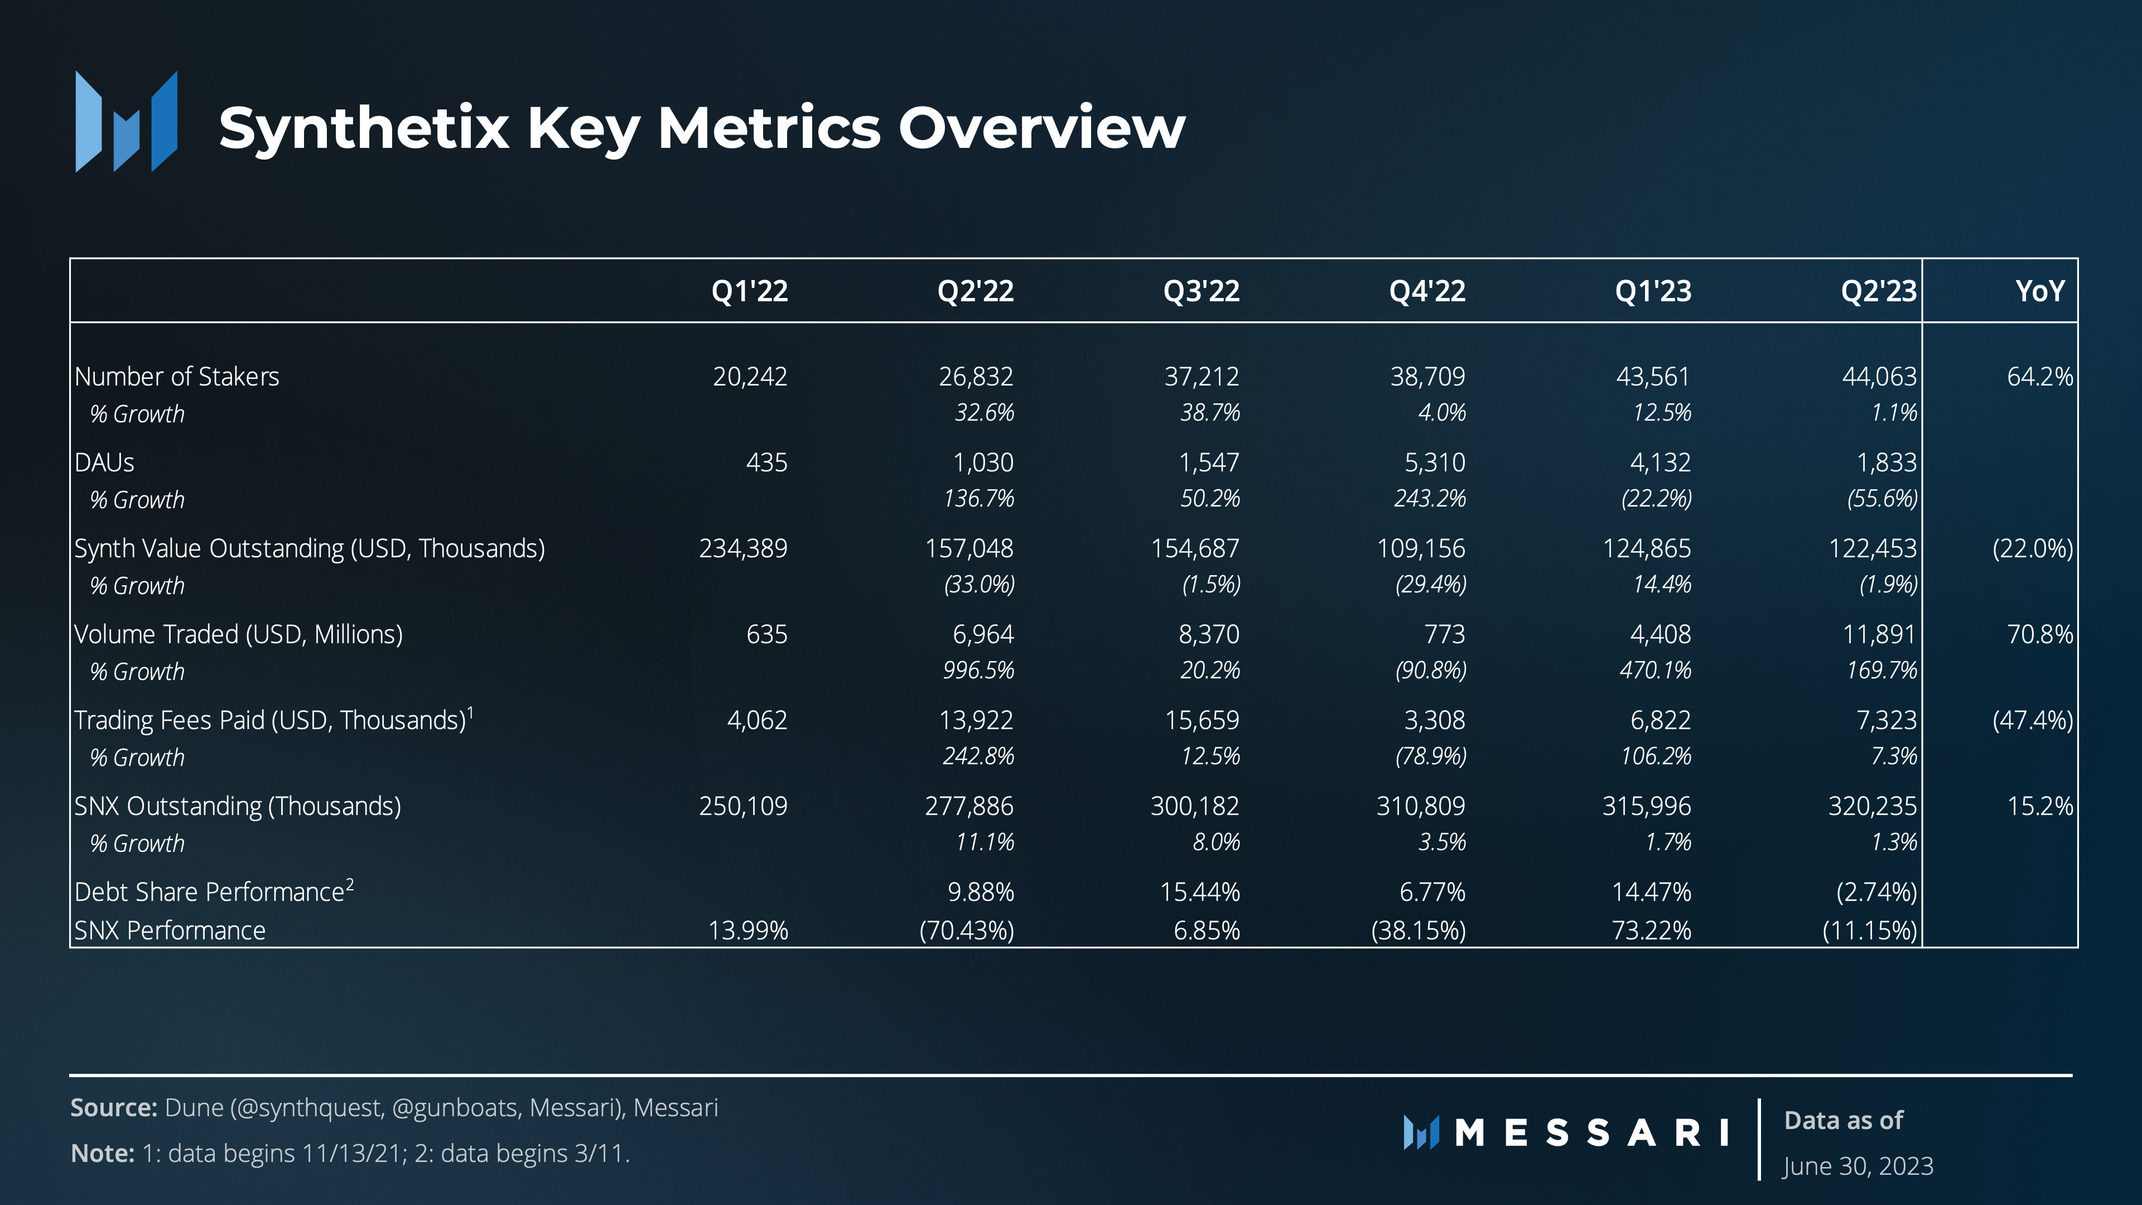
Product improvements for Synthetix Perps continue to drive adoption, with volumes jumping 170% quarter over quarter and total trading volume surpassing 11 billion. In Q2, product enhancements included reduced execution delays, cheaper trading fees, and more underliers to trade.
Part of the improved product is much cheaper trading, with ETH/BTC fees of only 2bp maker and 6bp taker now competitive with CEX pricing. Fees increased only 7.3%, to $7.3 million, despite the jump in volumes.
Synthetix paid out $3.4 million in OP incentives in Q2. The incentives will continue until September 6, after which their long-term efficacy can be better understood.
snxETH, the new spot synthetic ETH on V3, went live in Q2, as Synthetix begins to roll out features for V3. The DAO will continue to release with tight risk controls as it introduces the new version.
Primer on Synthetix
Synthetix is a decentralized synthetic asset issuance and liquidity protocol that allows users to trade synthetic cryptocurrencies, fiat currencies, and commodities. Each synthetic asset tracks the price of an external asset through the use of Chainlink, Pyth, or Uniswap V3 TWAP oracles. Users can either trade in spot or in perpetual futures markets for synthetic assets. SNX is the native protocol token, responsible for governance as well as the primary collateral that backs the liquidity of the network. SNX can be staked as collateral for sUSD, the Synthetix stablecoin, which can be traded on Synthetix for any other synth (sAsset). The DAO uses a novel V3 Governance Module (V3GM), which uses councils of appointees who are voted on by SNX holders.
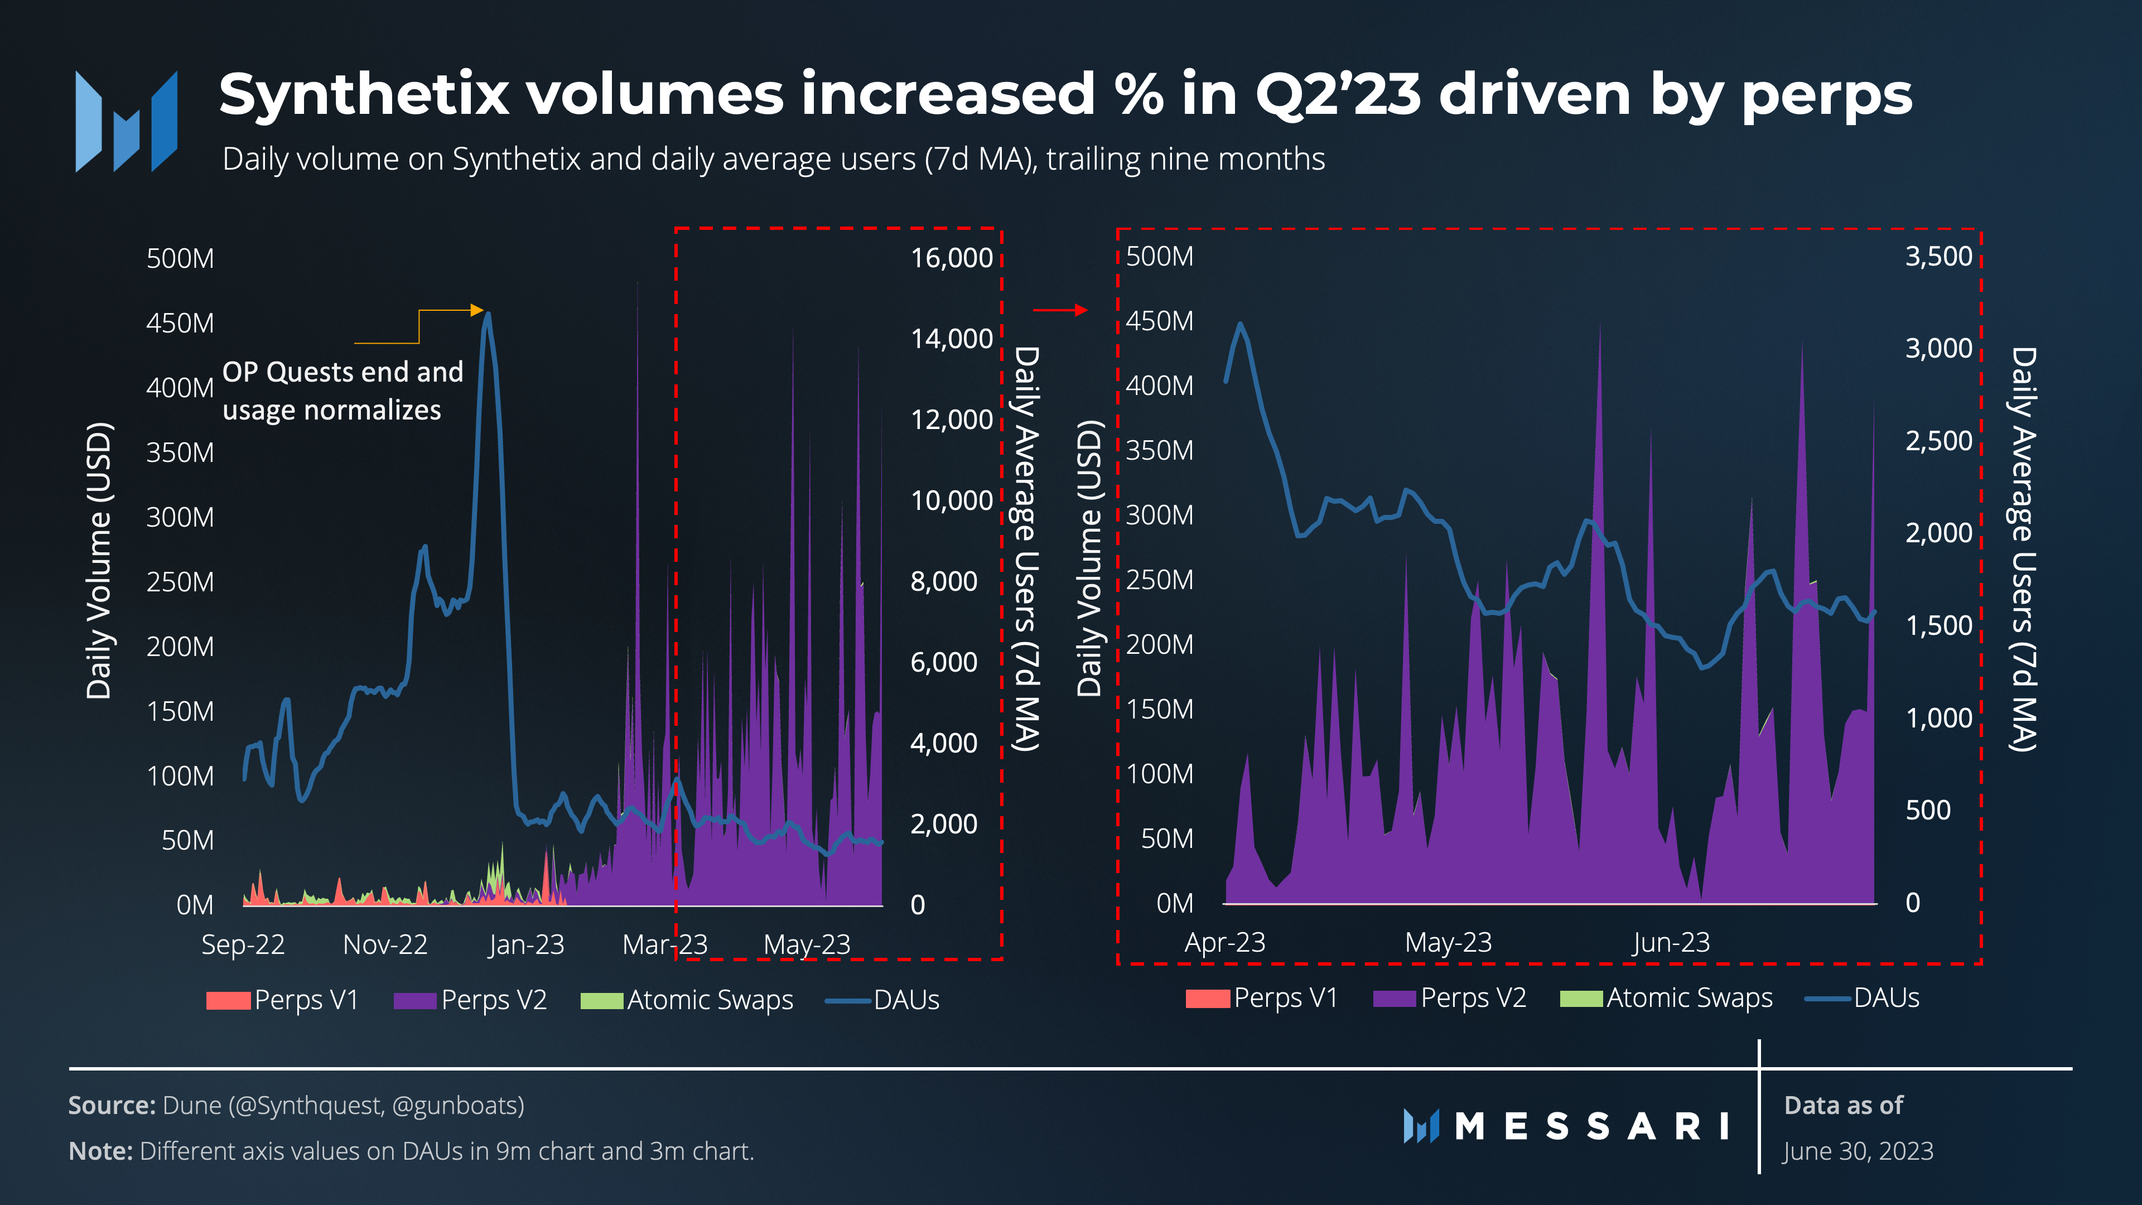
The quarter brought record-setting volumes for the protocol. This growth was attributed to a variety of factors: consistent product traction from Synthetix Perps; enhancements in front-end platforms such as Kwenta and Polynomial; improved UX from reduced execution delay; more underliers than any competitor (now 42 listed perps); increased market activity; the cost-reducing Optimism Bedrock upgrade; reductions in trading fees to competitive levels with CEXs; and the OP incentives program. It's important to mention that the volumes experienced a brief interruption around June 4 in preparation for the Bedrock upgrade. Despite the record volumes and OP rewards program, Synthetix experienced a downward trend in daily active users (DAUs) over the quarter.
There are some signs of reward farming, which is to be expected. For example, since rewards began on April 19, 24% of trading volume occurred on Tuesdays, doubling the Tuesday volume share from the rest of the year. The concentration was likely a result of reward epochs ending on Wednesdays, meaning farmers would be more active on Tuesdays as they have a better idea of what the future payout will be.
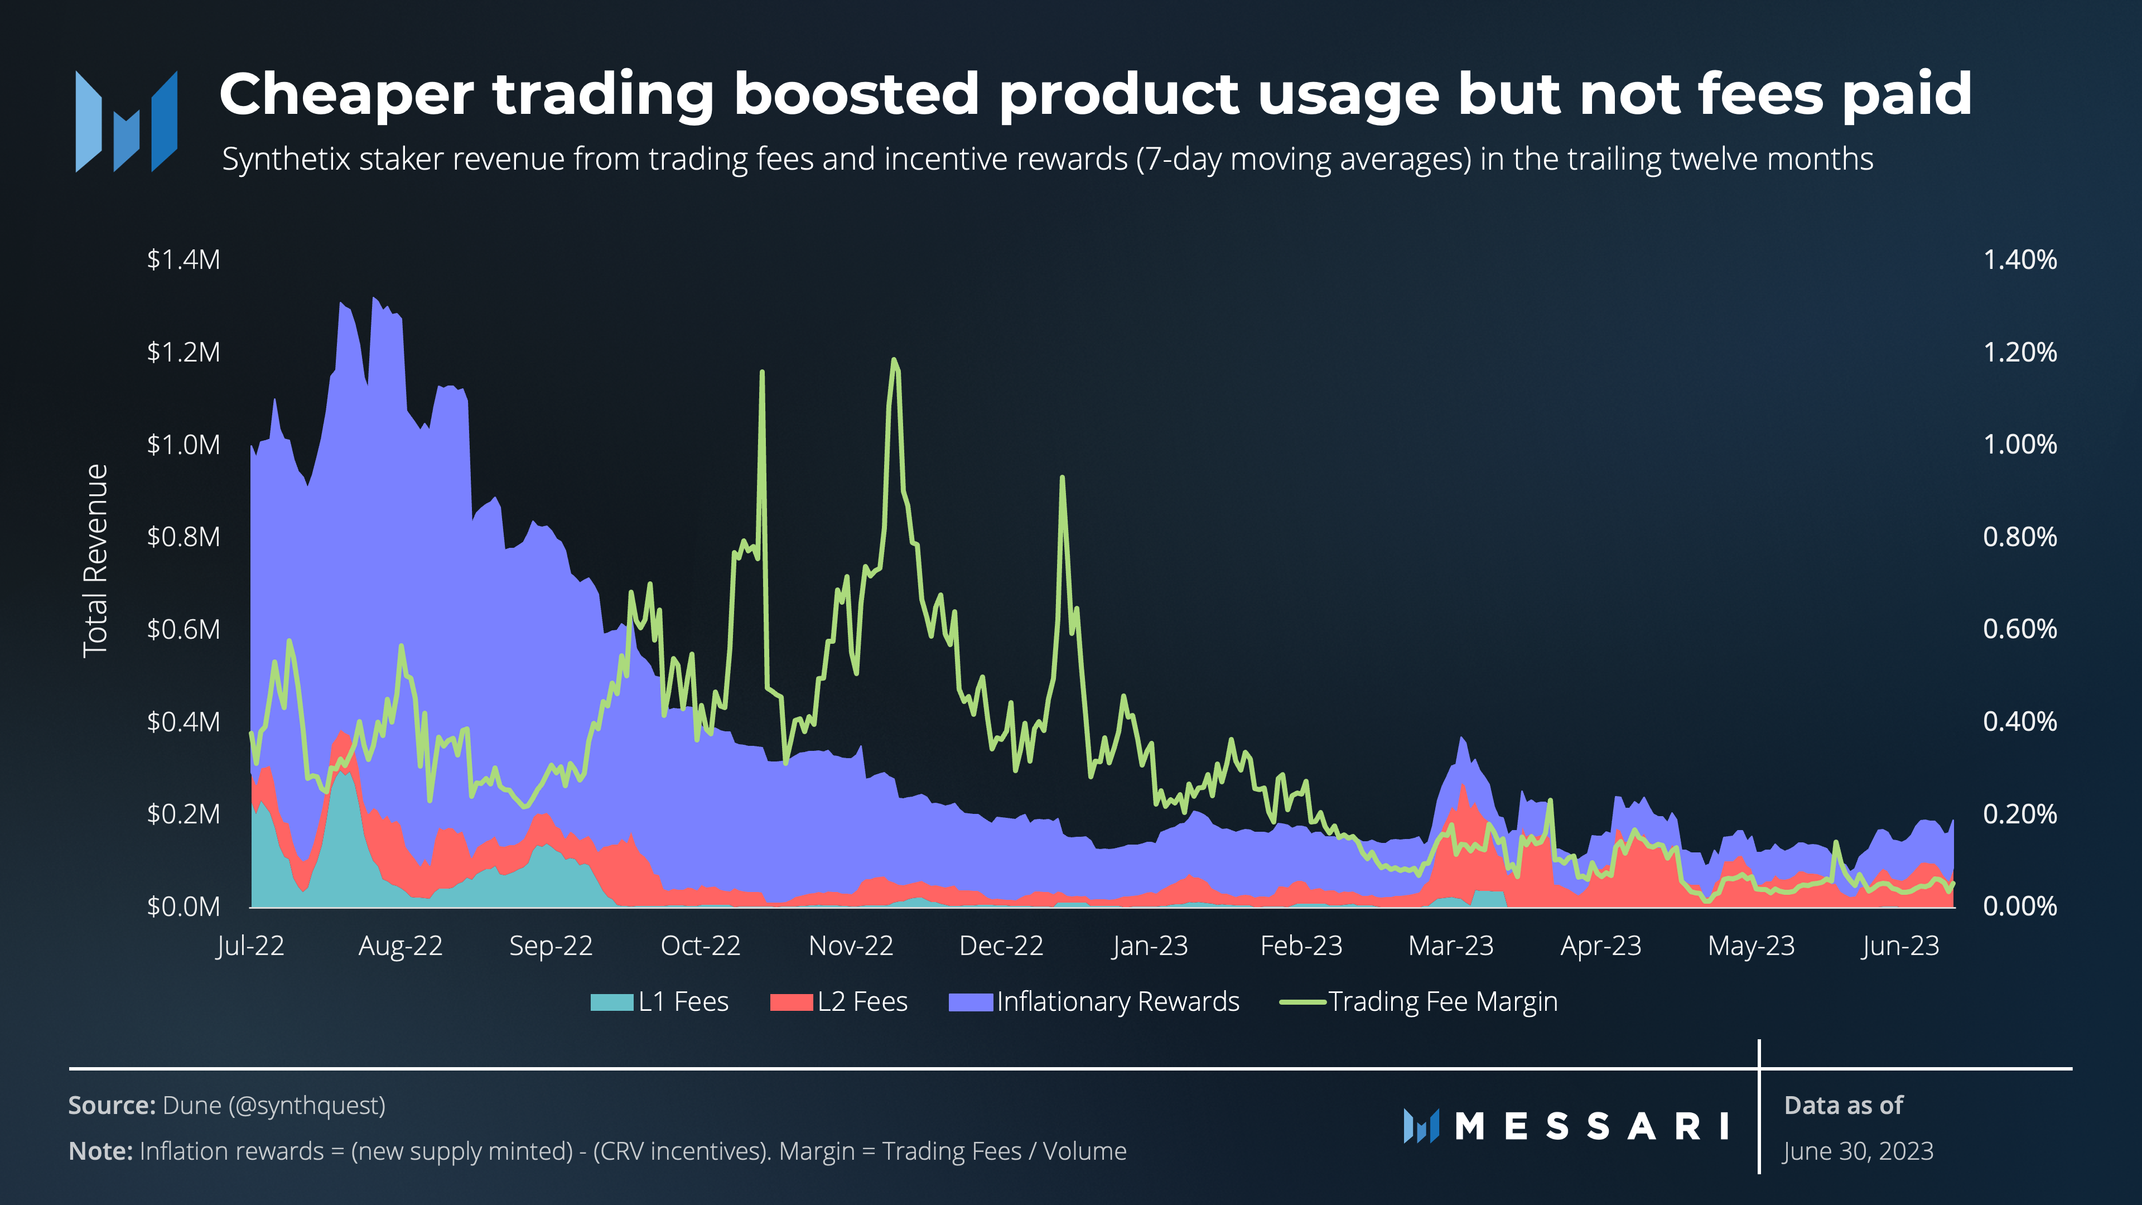
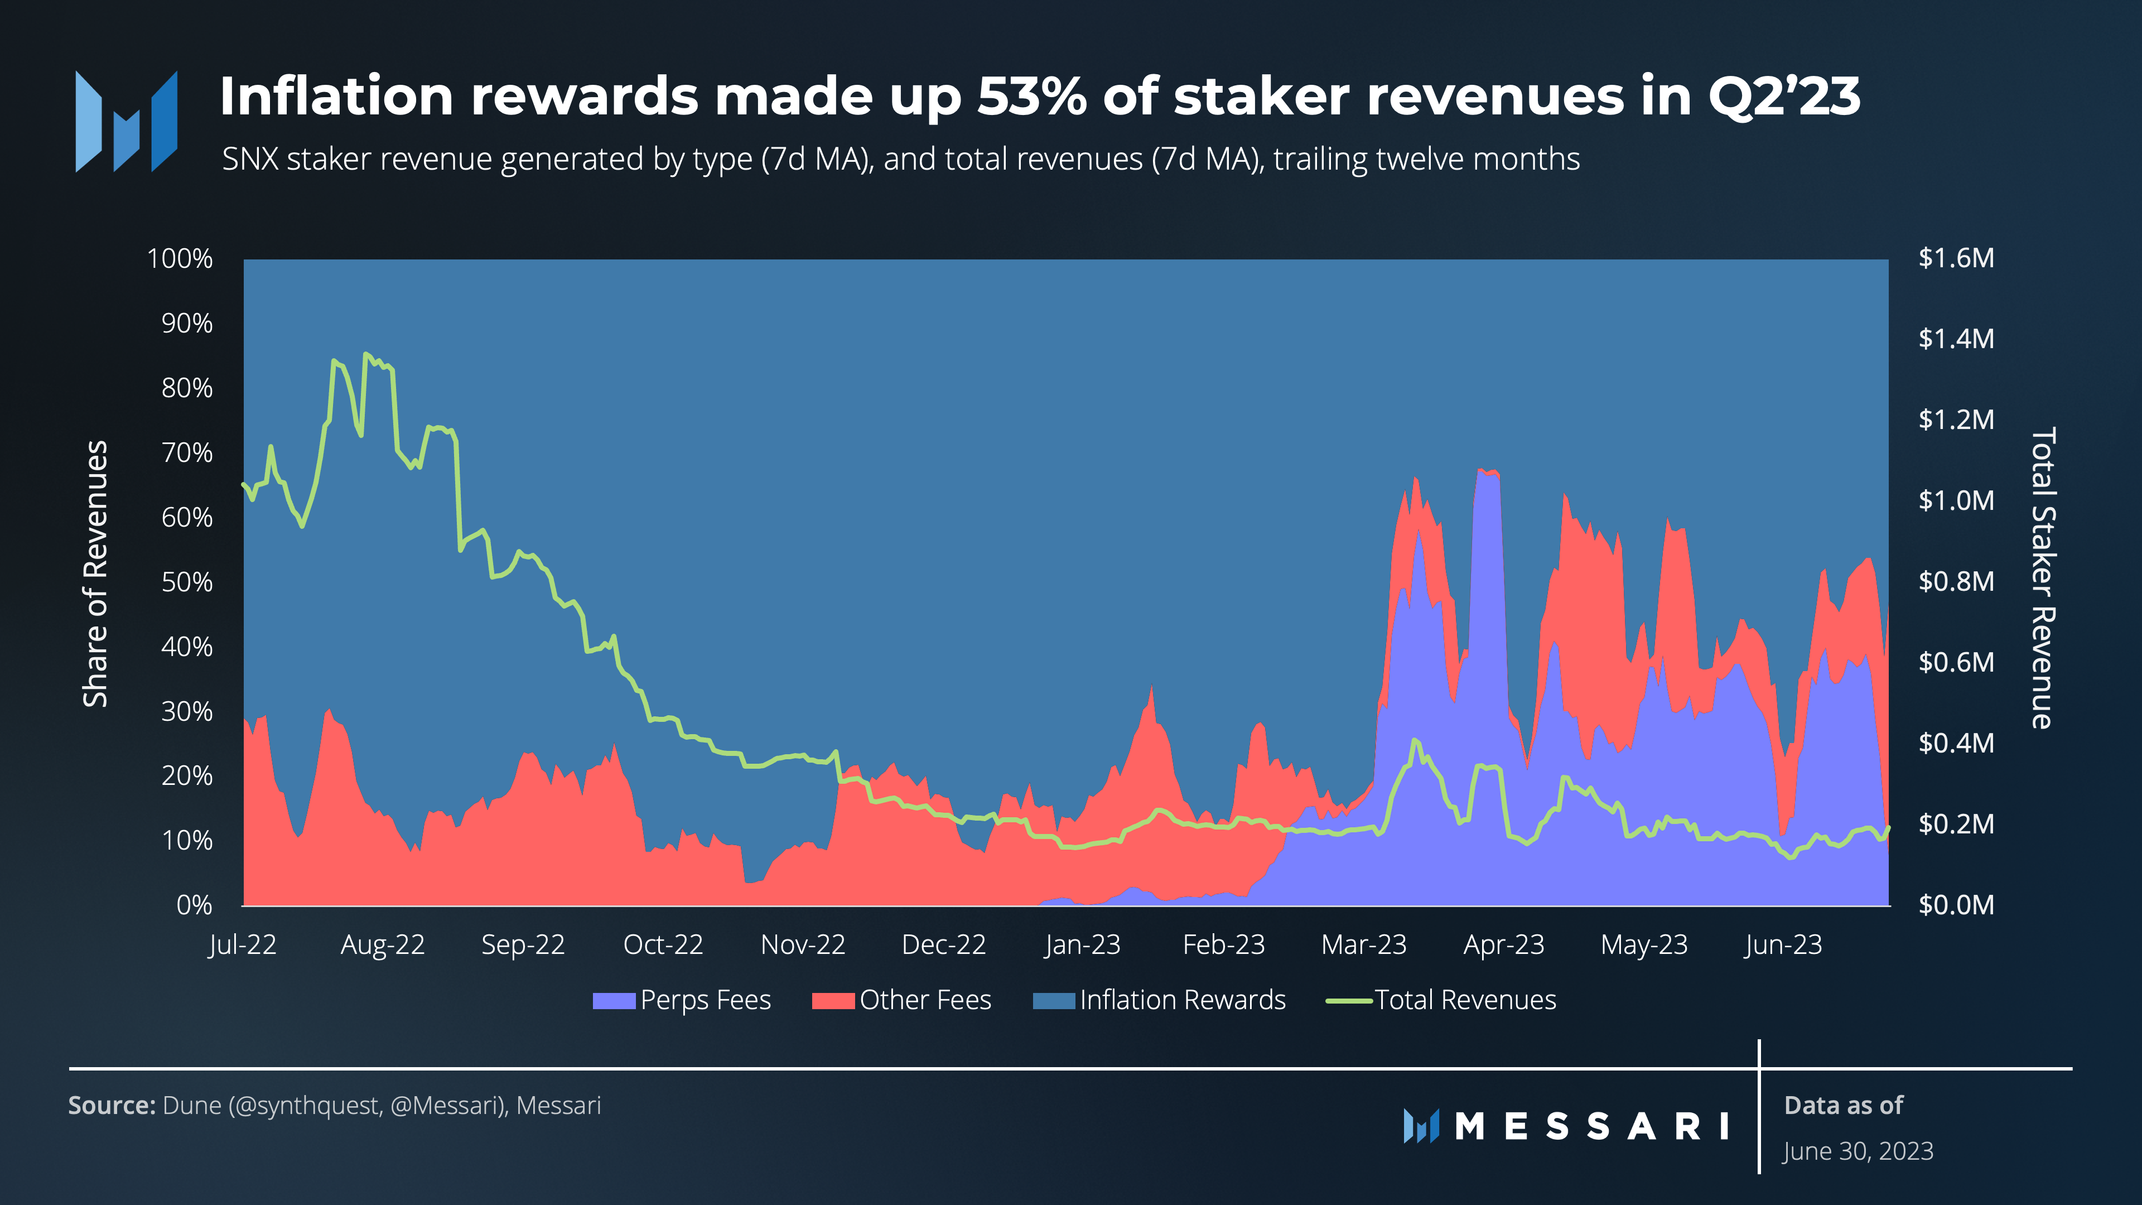
In April, Synthetix Council approved SCCP 293, which updated parameters like the maker and taker fees for many perps markets. It reduced costs anywhere from 30%-75% for traders. From a product perspective, this certainly has brought benefits in the form of increased volumes and perps market share. Trading fees on Synthetix are now competitive with CEX and the lowest of competing DEXs. But from a staker perspective, it delivered a hit to margins: the amount of fees paid in the quarter only marginally surpassed the prior quarter, despite the increase in product usage.
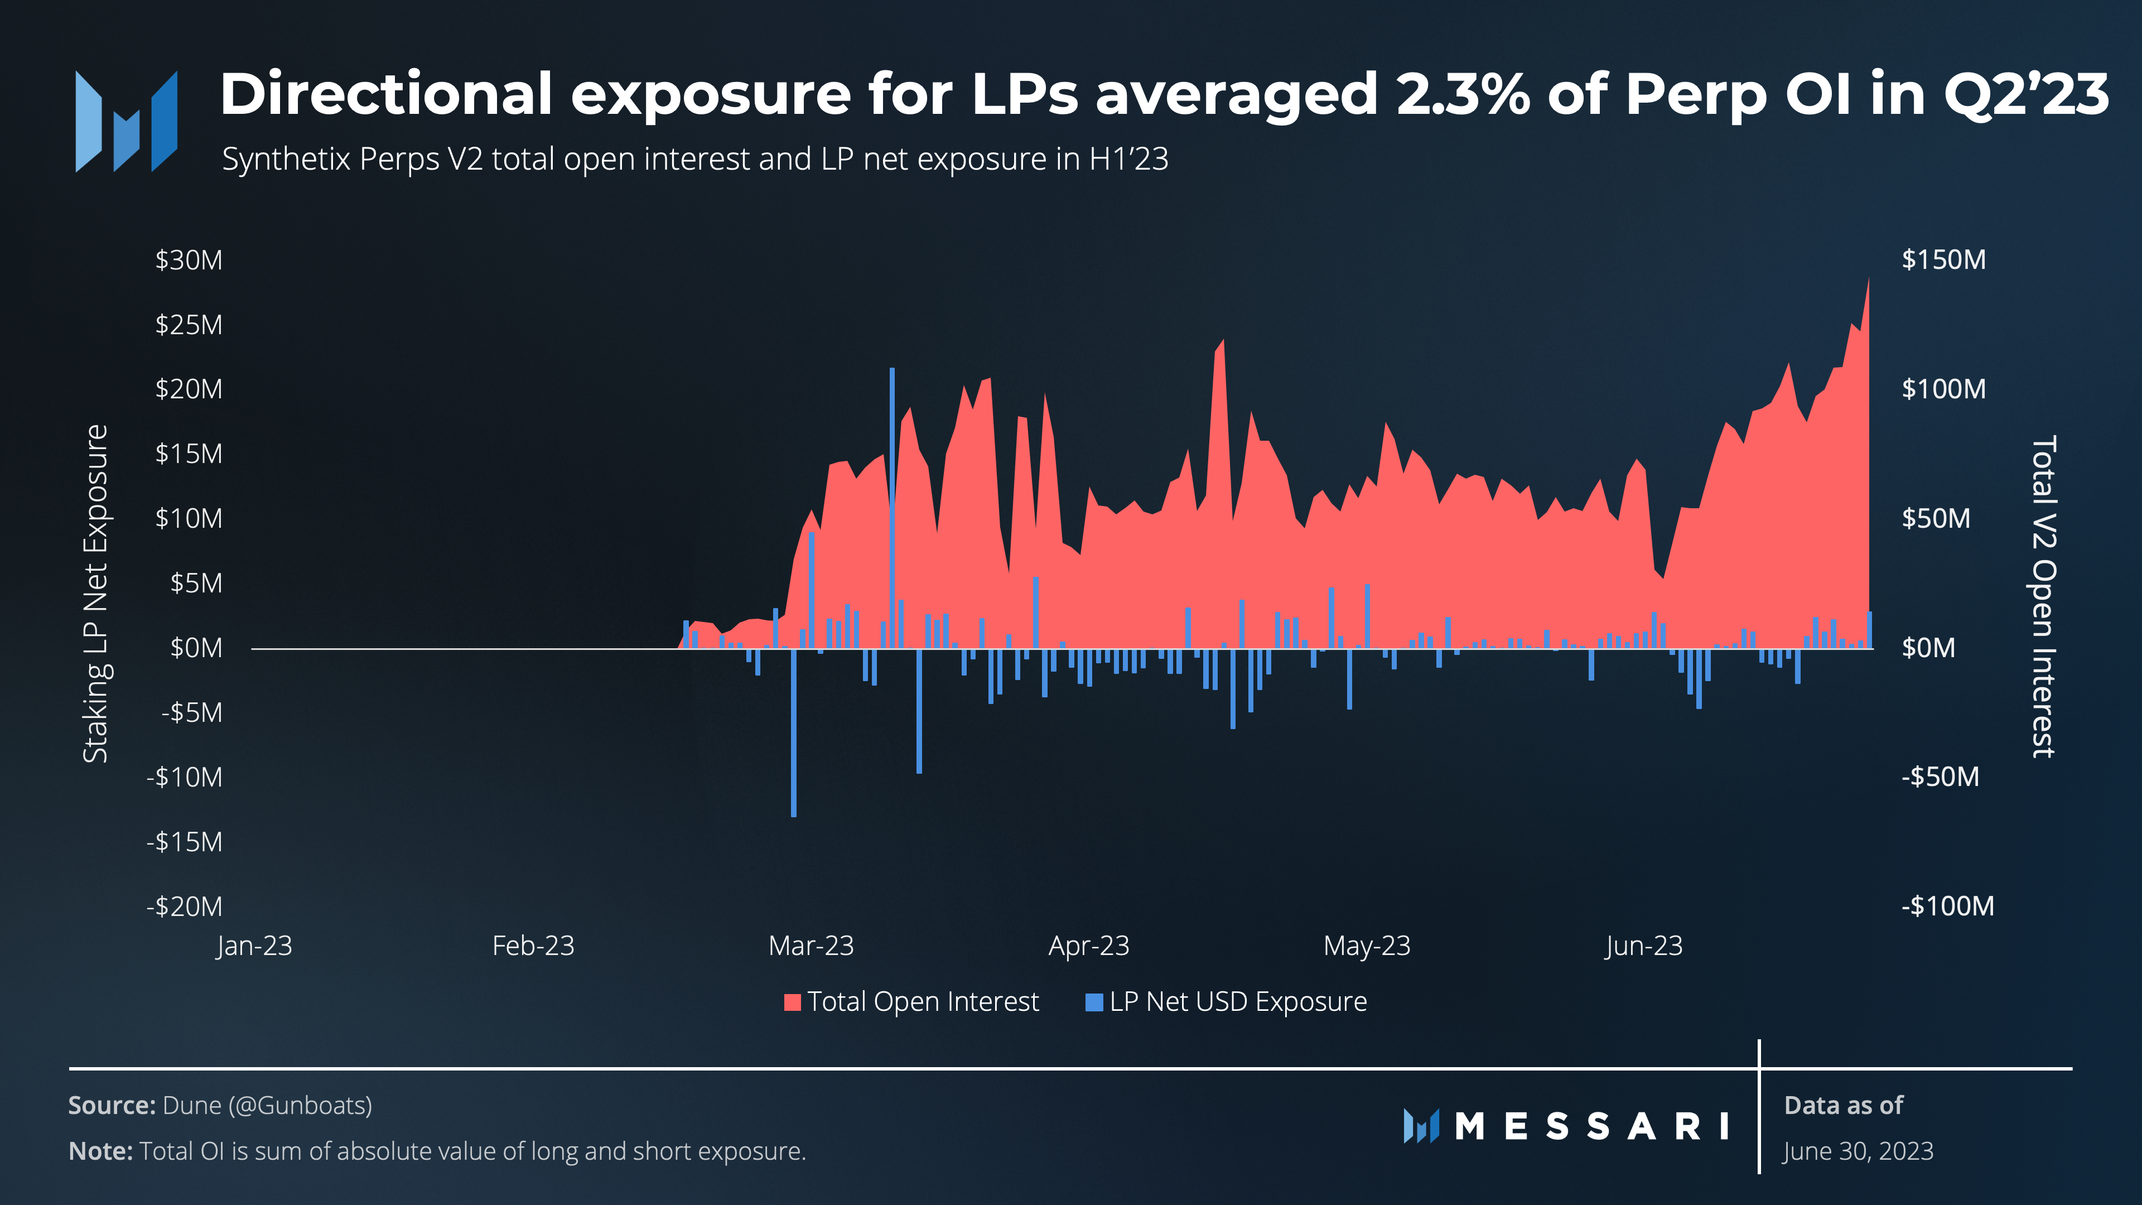
Net net, the new product design continues to work well in insulating LPs from directional exposure and isolating yields. Synthetix Perps utilize dynamic funding rates and a unique price impact function to achieve LP delta neutrality. In the past six months, it has successfully allowed LPs to provide liquidity without having to manage the dynamic risk of taking the other side of user trades. In this sense, the lower margins are less of an issue, and the team should continue focussing on winning market share and increasing usage.
While daily open interest (OI) averaged over $69 million in Q2 and ended the quarter with over $140 million, daily LP exposure averaged just $1.5 million (in absolute value terms). Given the lack of a strong relationship between OI and LP exposure, OI should be able to continue to grow faster than the risks to LPs.
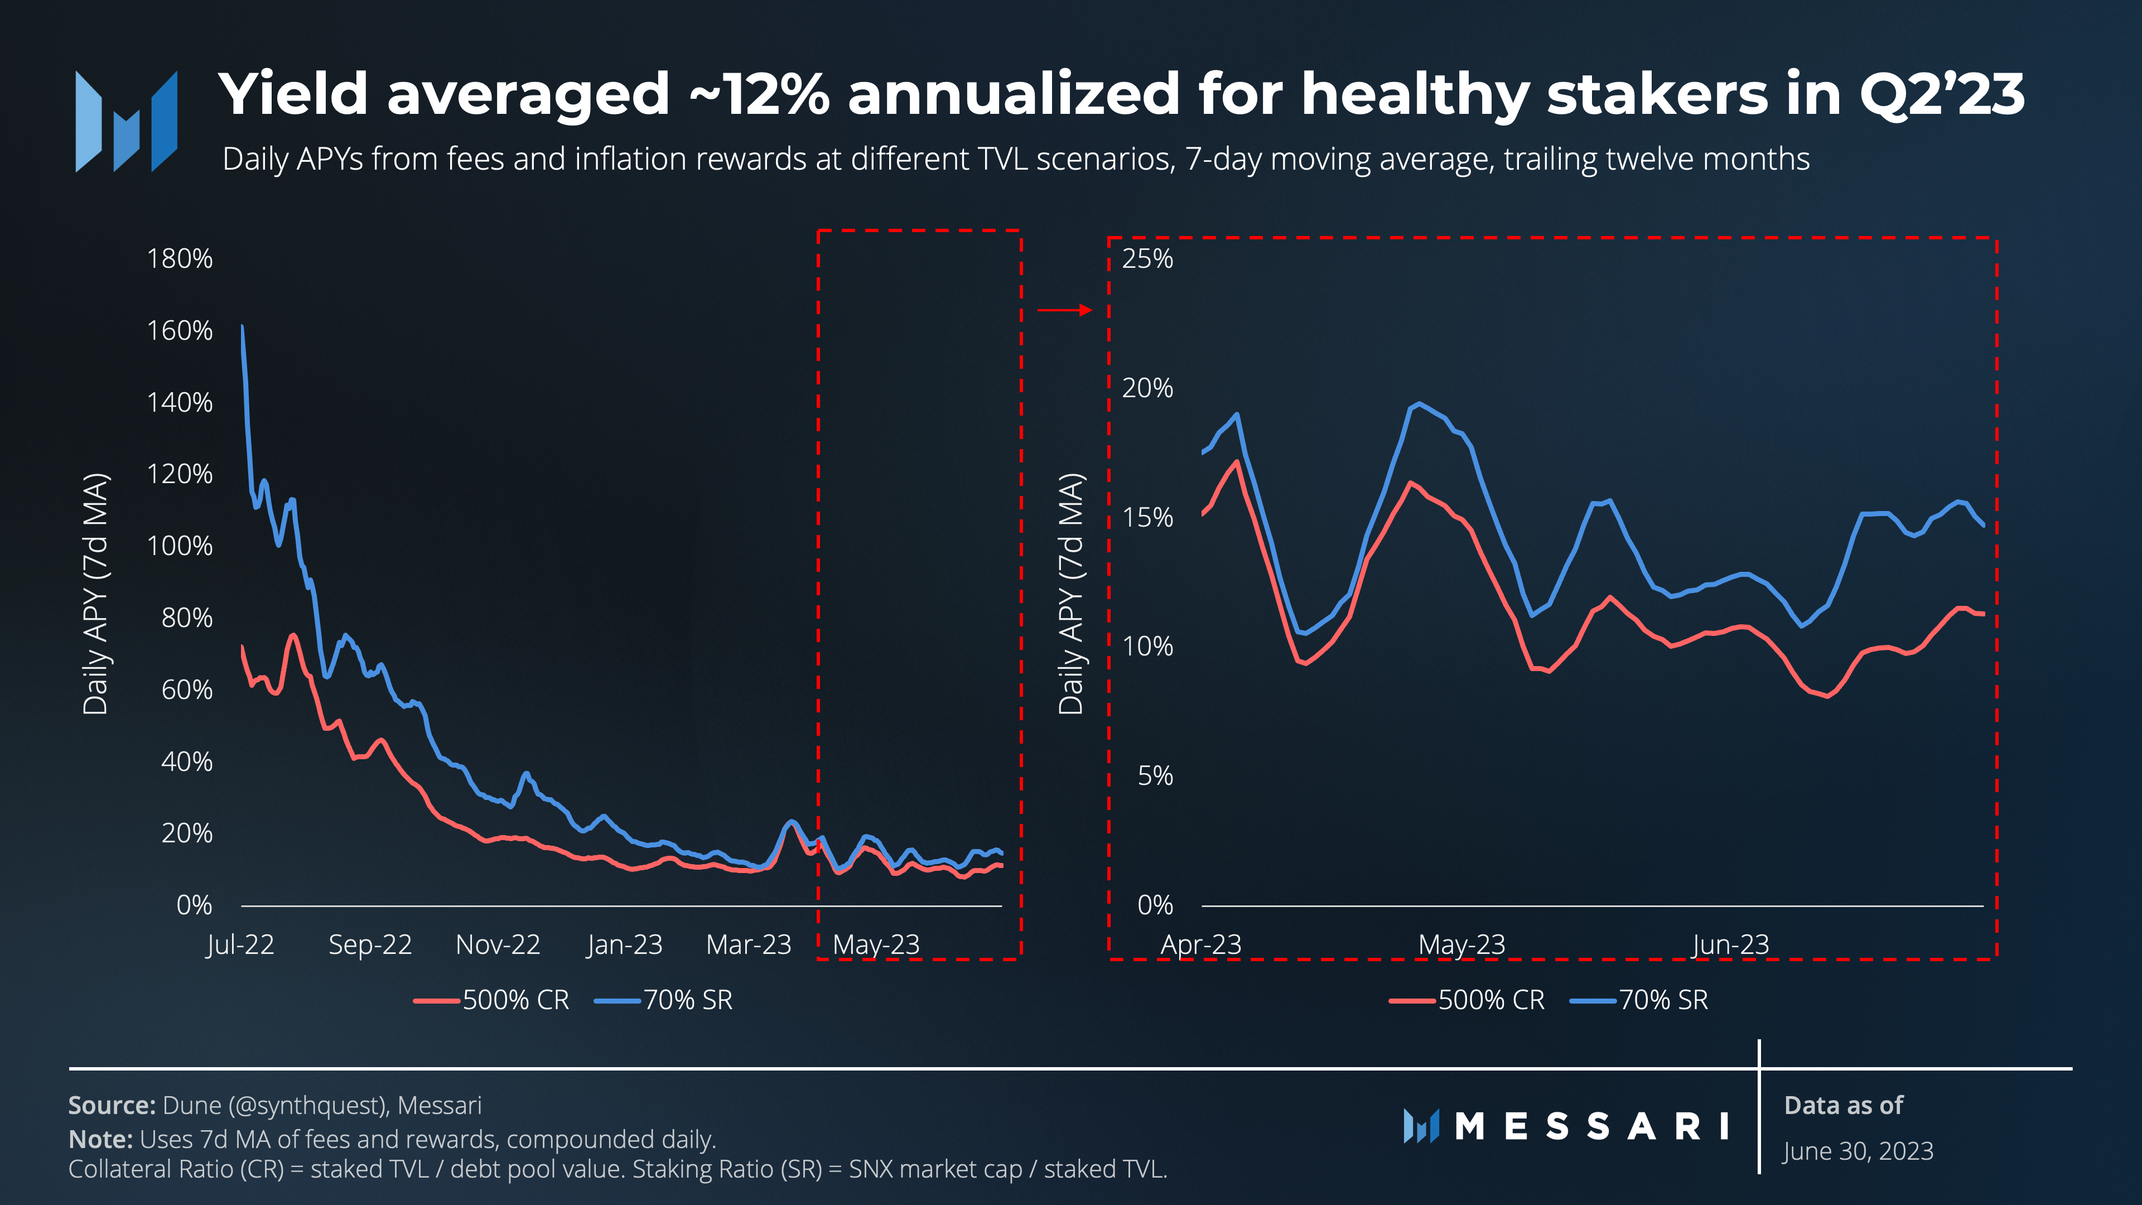
SNX staker yield trended downwards over the last year, primarily due to the reduction in inflation rewards from summer 2022. More recently, yields have settled to 11%-16% for stakers. In addition, the makeup of yields has become more sustainable. Stakers cannot claim yield on their stake if they are below the required minimum 500% collateral ratio.
Without the activity reduction around the Bedrock upgrade, more than half of the staker revenues would likely have come from trading fees in Q2. Excluding inflation rewards, the yield from fees was between 5% and 8% for the quarter, mapping to a price-to-sales ratio for SNX between 12.5 and 20.
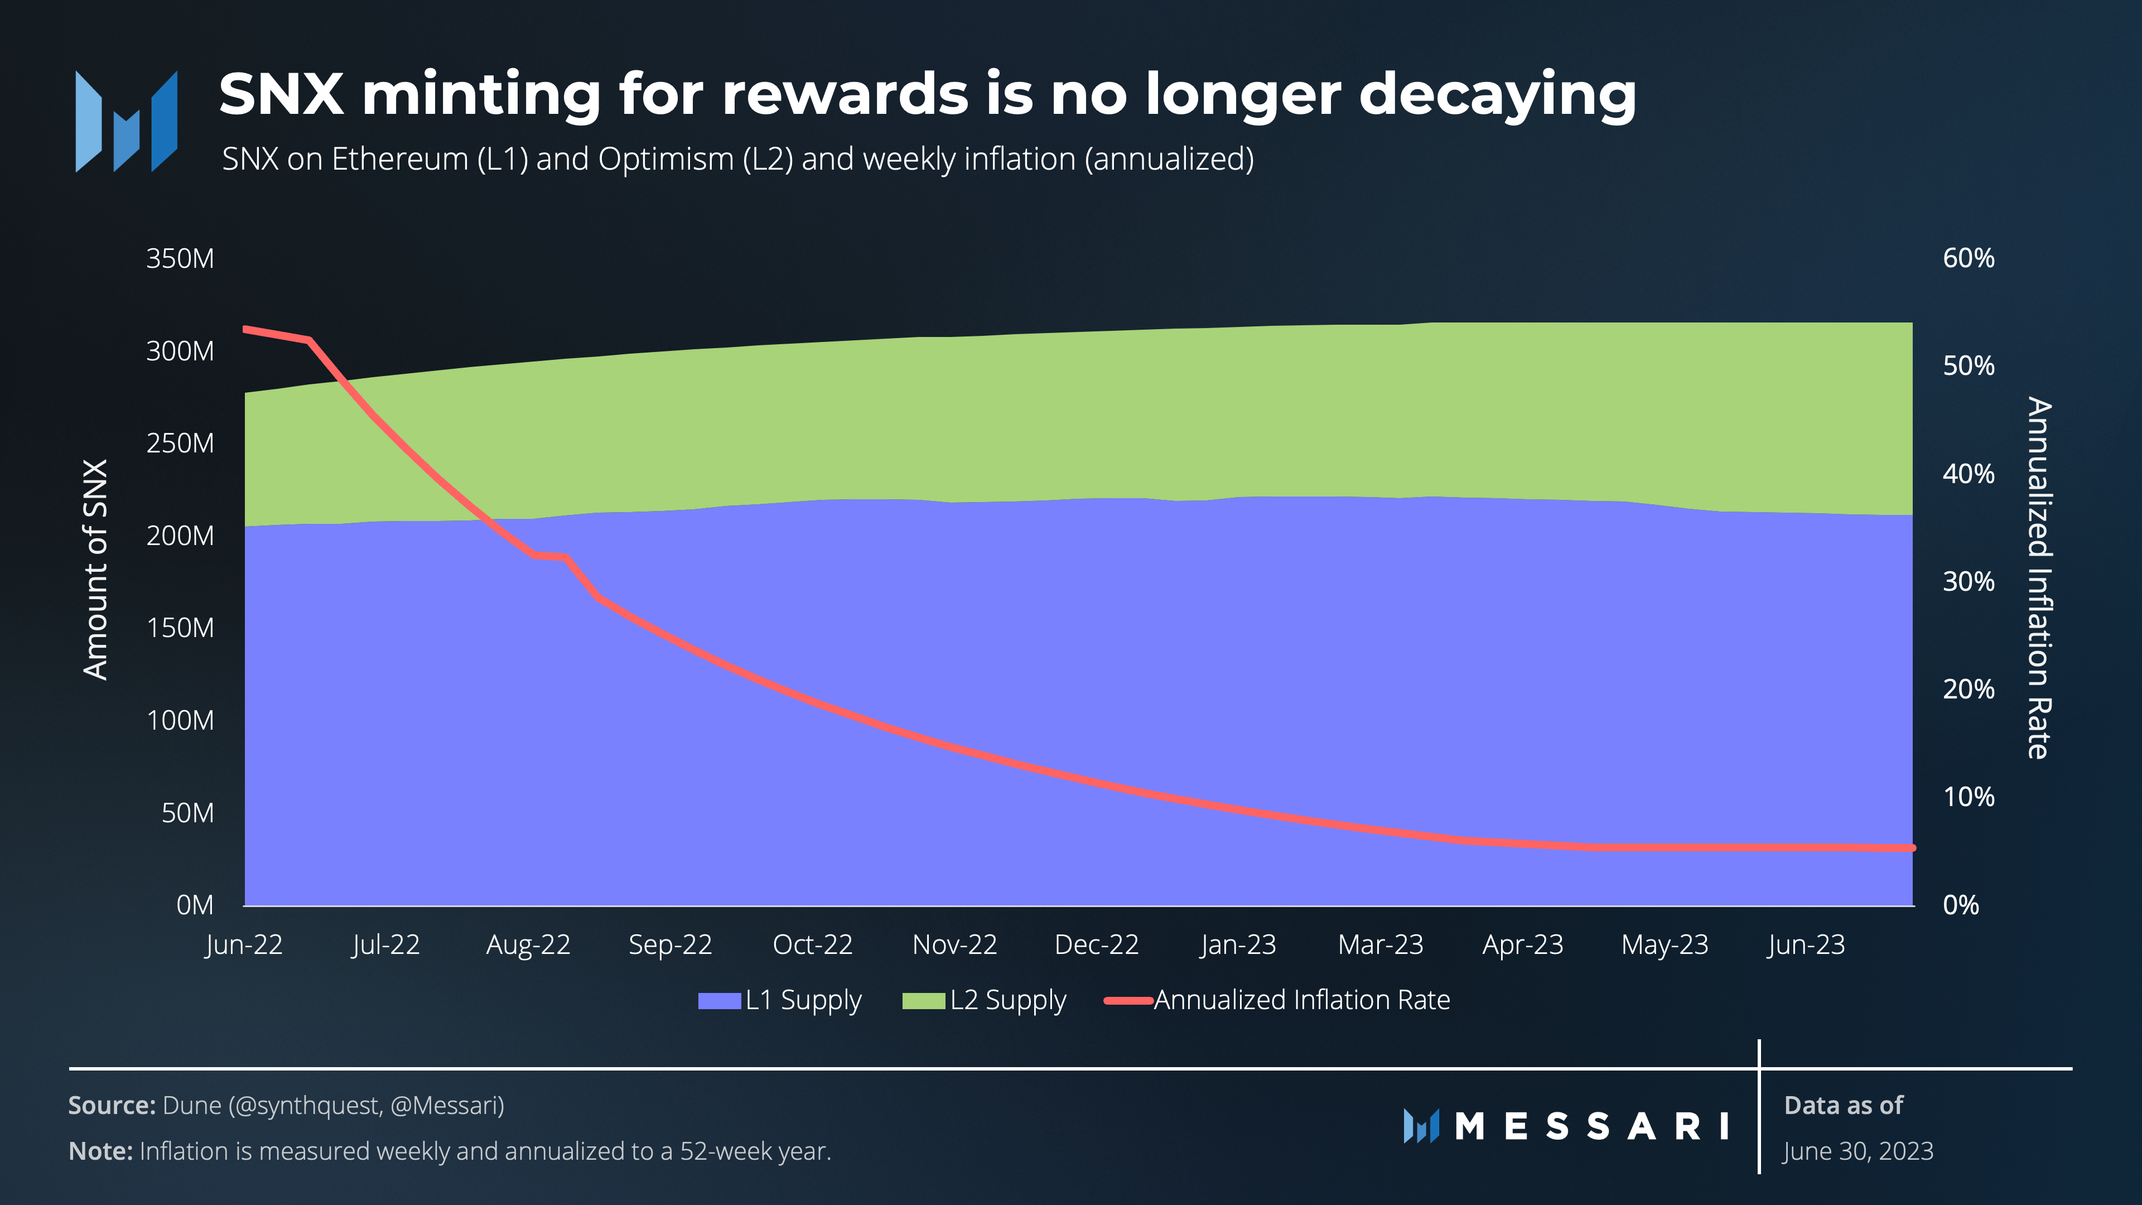
SNX stakers still receive inflation rewards, though the amount had been reduced by 10% every week while the staking ratio was above 70%. SIP 2017 and SIP 2019 were also approved in June and will each be redirecting 10,000 SNX from liquidity and volume incentives to stakers instead.
In April, Synthetix changed its inflation schedule by adjusting the target staking ratio response function. The staking ratio is the amount of SNX staked as a percent of the total amount outstanding. With SCCP 294, inflation will remain unchanged (currently 325,445 SNX each week) within a 12% band of the 70% target staking ratio. If the staking ratio moves below 58% or above 82%, inflation will increase or decrease by 10% each week. This function leaves inflation below a 5.5% annualized rate going into Q3.
Synthetix’s more predictable inflation should have a positive effect on future stakers and token buyers. After the near hyperinflation of summer 2022, Synthetix faces a final cliff in Q3 when over 7% of existing supply will be released from escrow — more than half of the entire SNX currently in escrow.
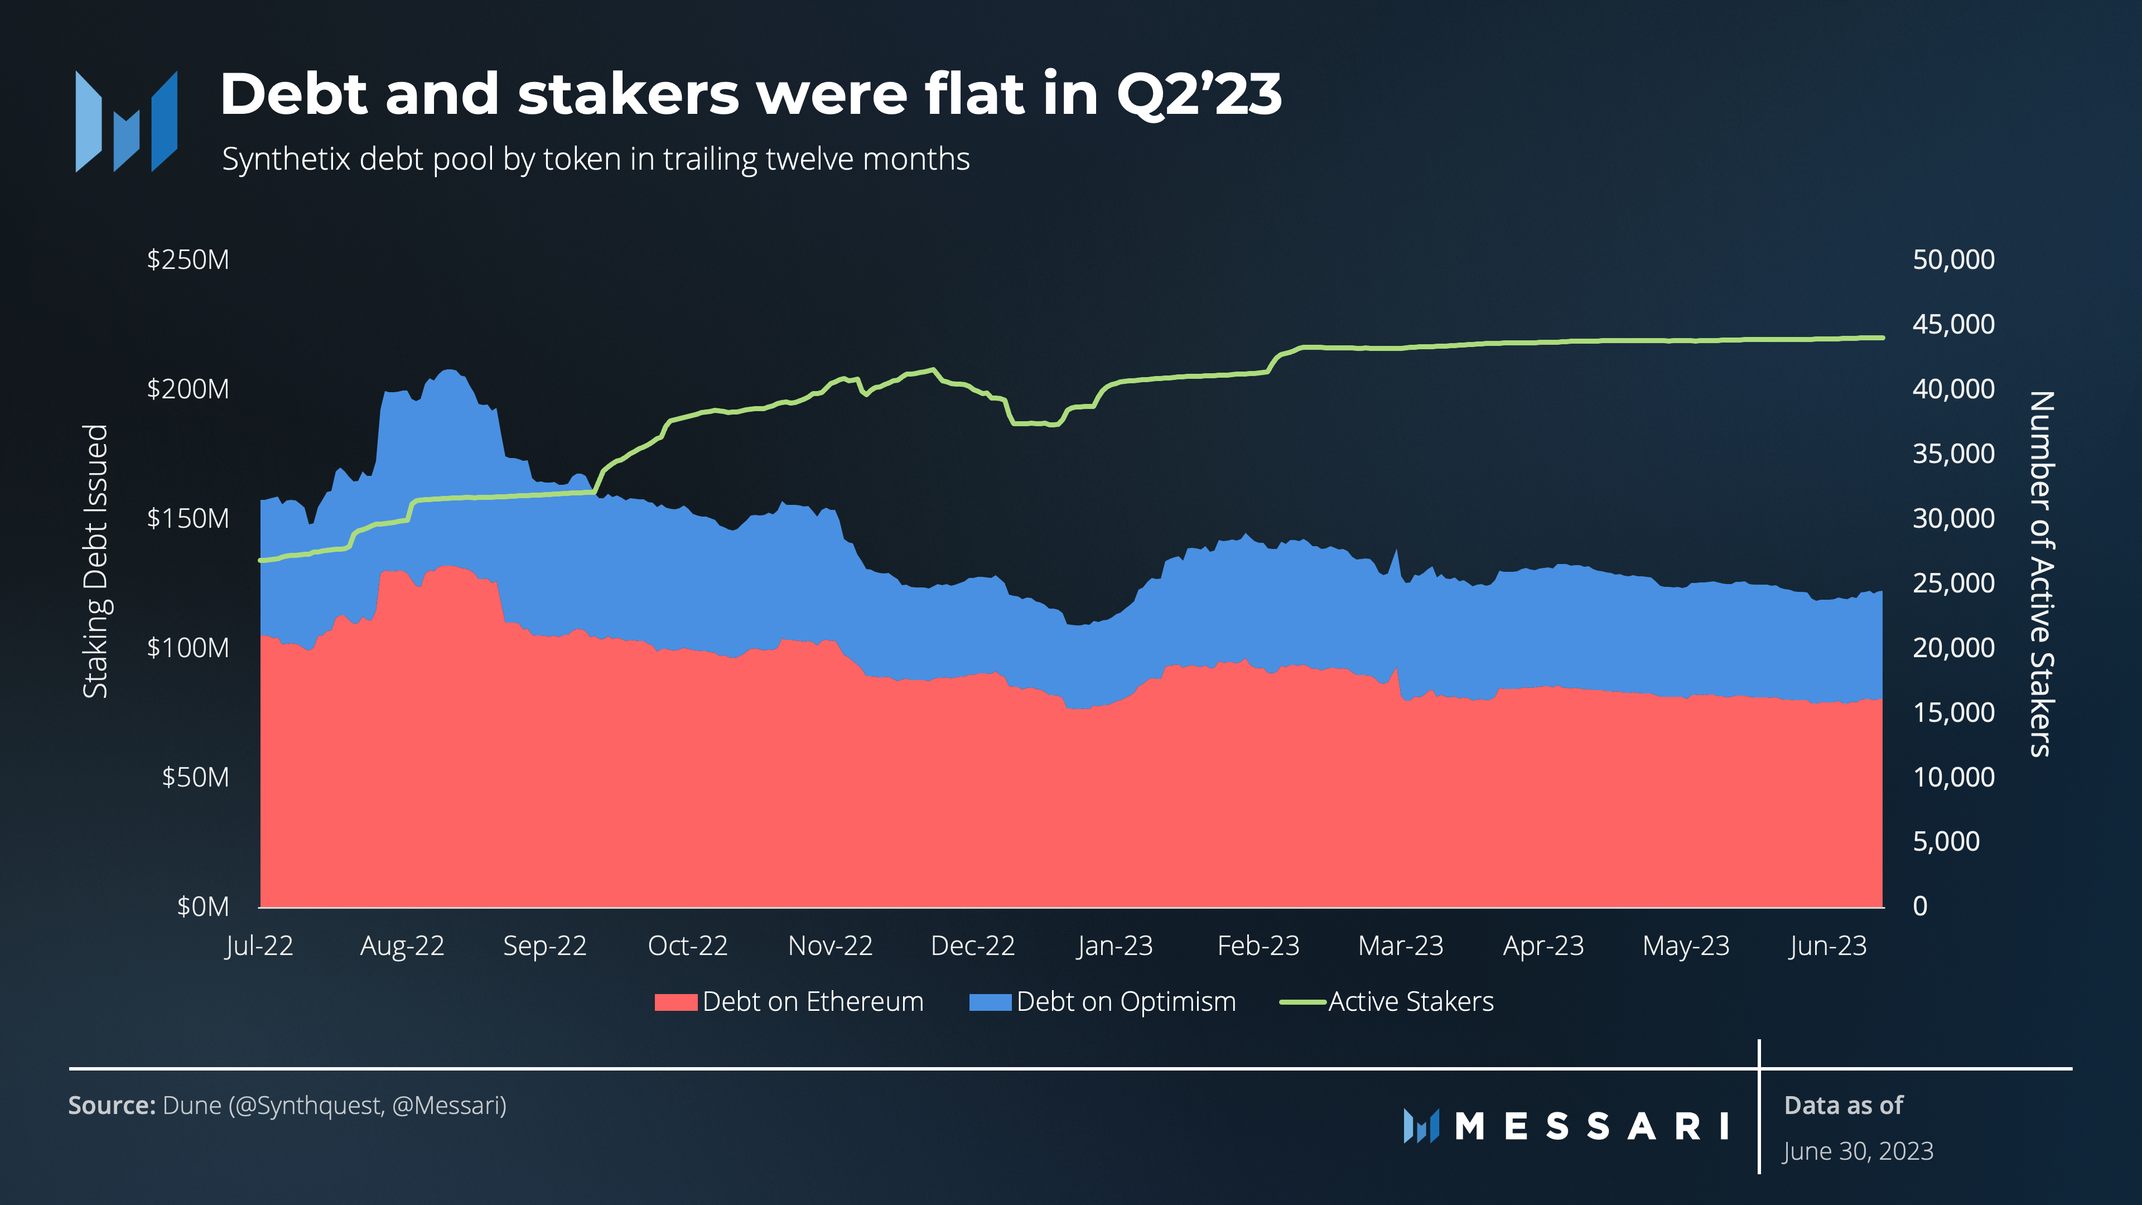
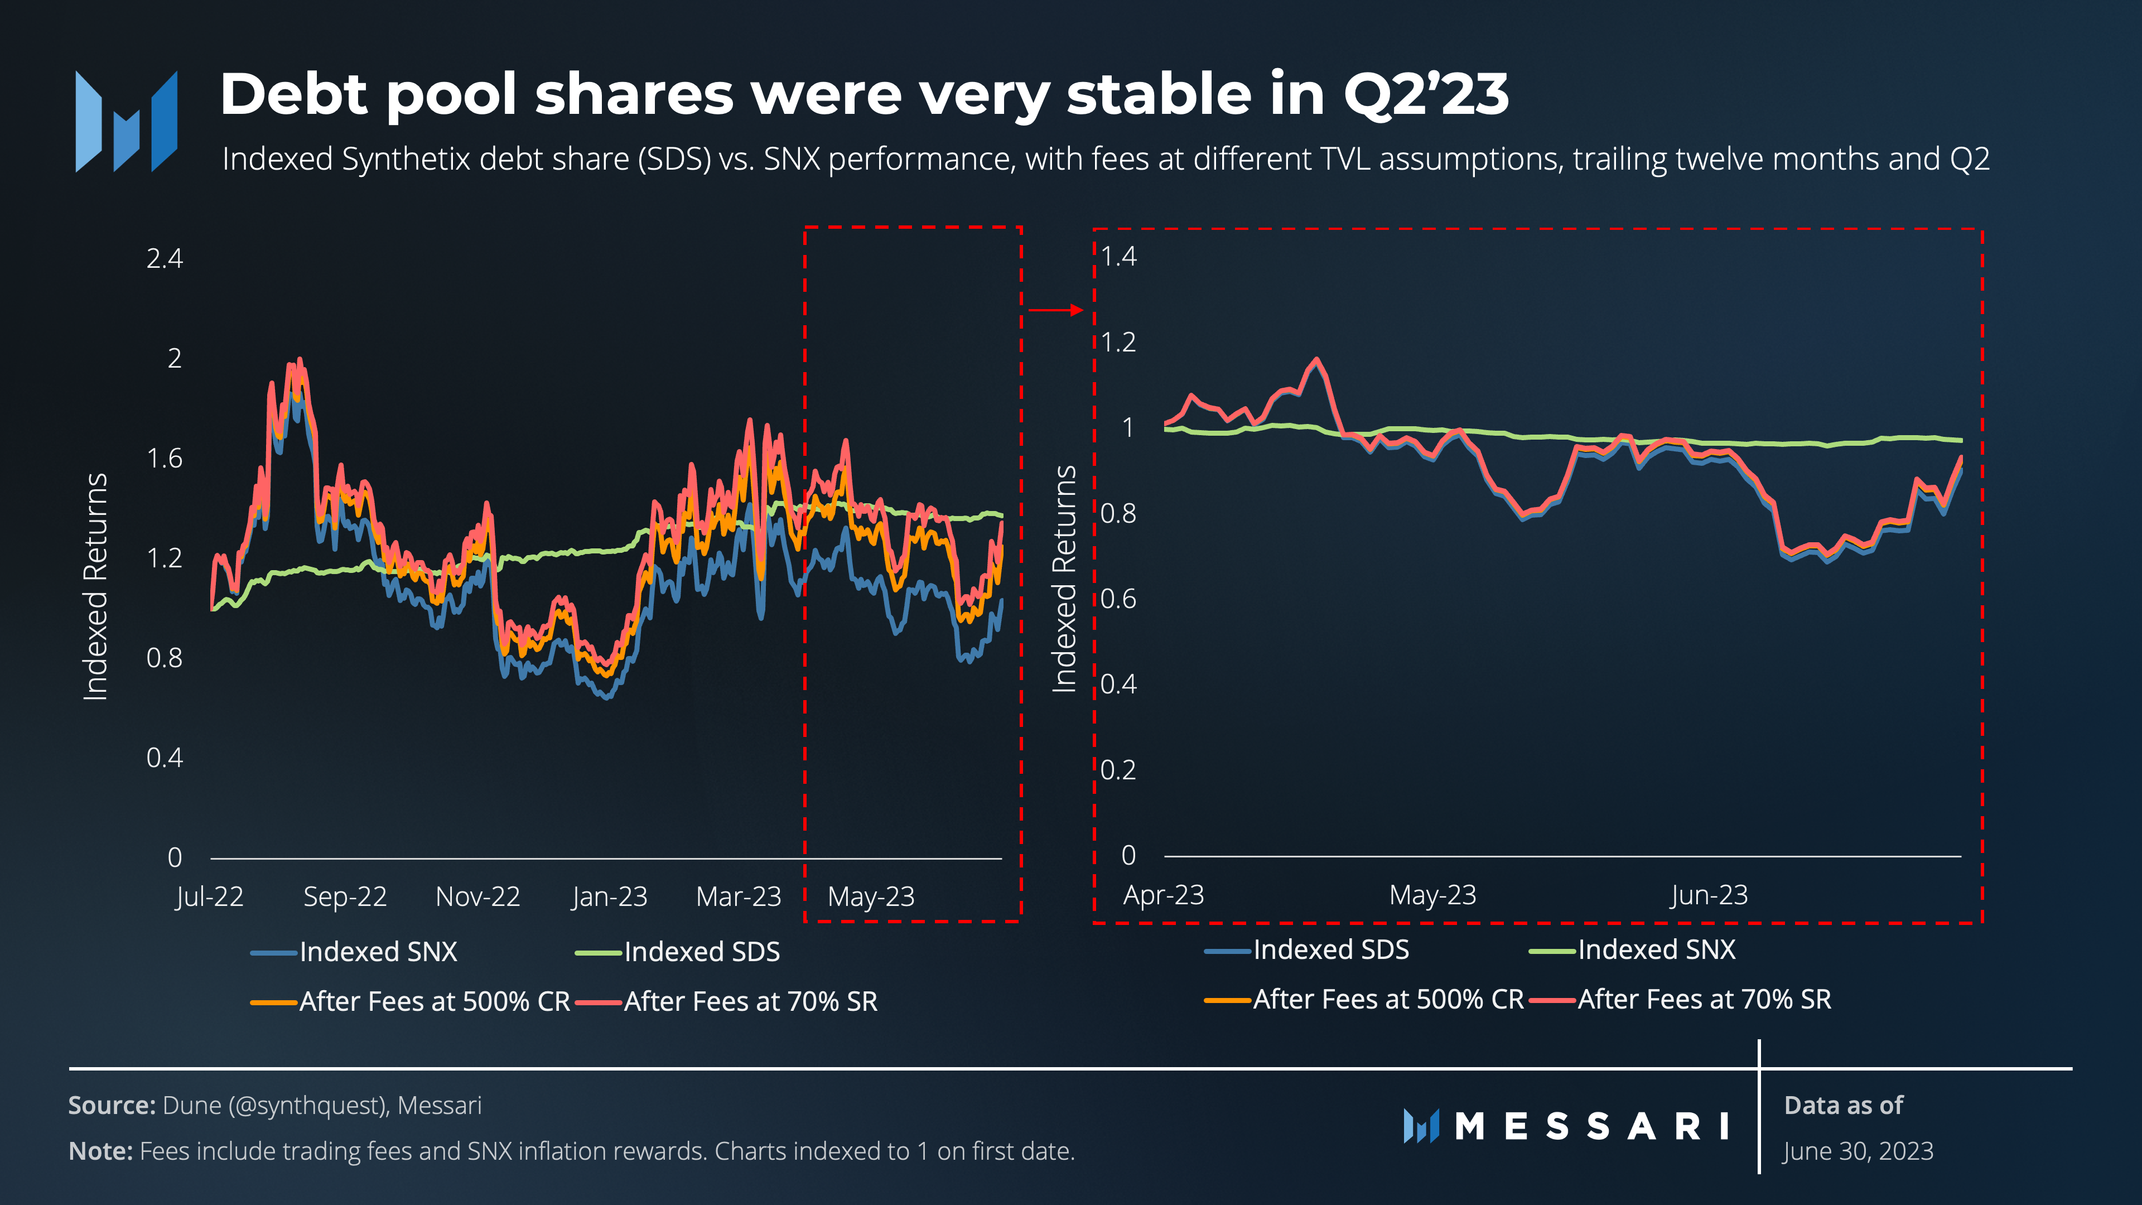
Despite the double-digit yields, only 500 new stakers deposited SNX in Q2. With the market roughly flat for the quarter and the debt pool heavily weighted to sUSD, the debt pool barely changed in the quarter, falling only 2.7%. Q3 was the first full quarter where trading fees were used to burn sUSD and reduce the size of the debt pool.
Stakers are encouraged by the DAO to hedge their debt pool exposure. When SNX stakers mint sUSD, they receive debt shares, which represent their share of the debt pool. In Q2, the shares of the debt pool were very stable, making for a friendly hedging environment. Another contributing factor to the hedging environment was the lack of liquidations in Q2, where less than $300,000 of collateral was liquidated. Because liquidations are socialized amongst stakers, their staking ratios are hurt whenever undercollateralized debt is accrued by healthy stakers. Once the dust settles, this interaction can be seen as an outperformance of the debt pool shares.
Qualitative Analysis
In June 2022, Synthetix launched a new governance structure, Synthetix V3GM. For more information on the governance process and many of the initiatives, please see our State of Synthetix Governance report.
Synthetix V3 Update
June marked an exciting milestone with the implementation of the first active features for V3, highlighted by the alpha release of the spot market for snxETH.
The recent release allows for atomic swaps along with innovations that are unique to V3. Similar to how swaps are conducted on the current version, v2x, users can buy or sell in an atomic order, utilizing the chainlink price. Atomic orders encourage composability with the Synthetix protocol, enabling traders to minimize slippage and to specify an amount to receive prior to committing to the trade. Atomic orders carry the major risk of front-running, which is actively managed by governance who balance the trade-offs using trading fees.
Alongside atomic orders, asynchronous orders went live with the alpha spot release. The name reflects how these trades are executed in two separate on-chain transactions: commitment and settlement. In the commitment transactions, users set specific prices using cryptographic signatures, similar to a limit order, at which they would acquire or sell tokens. Then, in the settlement transactions, these trades are settled via either on-chain or off-chain oracle updates similar to Perps V2. Although asynchronous orders help with front-running, they do complicate composability.
The alpha release also enabled new fee innovations that can be applied to any spot market on V3. The novel fee levers for market designers include the skew fee, utilization fee, and interest rate. These added features create a more dynamic design environment, allowing market designers to fine-tune their strategies depending on their preferred risk. Wrappers, or contracts that allow users to exchange non-synthetic assets (like ETH) for the Synthetix version (like sETH) have been used in the protocol before, but could take on a much larger and more directed role with the addition of skew fee and incentives to balance LP exposure. Looking ahead, Synthetix is finalizing plans for cross-chain functionality and different collateral types for perpetual futures in V3.
OP Incentives
Synthetix Perps OP incentives began on April 19 with 10,000 OP rewards in the first week. Beginning May 10, the weekly rewards increased to 300,000 OP (Note: Rewards were halted the week of May 31 for the Bedrock upgrade). More rewards also came from Synthetix front ends like Kwenta, Polynomial, Decentrex, and dHedge.
Having such a large incentive makes it difficult to distinguish between organic demand and incentivized demand. To add clarity, the team at Optimism put together a helpful dashboard that tracks many user metrics during the incentivized period. Synthetix’s own Gunboats also built a dashboard primarily to compare the fees earned with the incentives paid during the reward period.
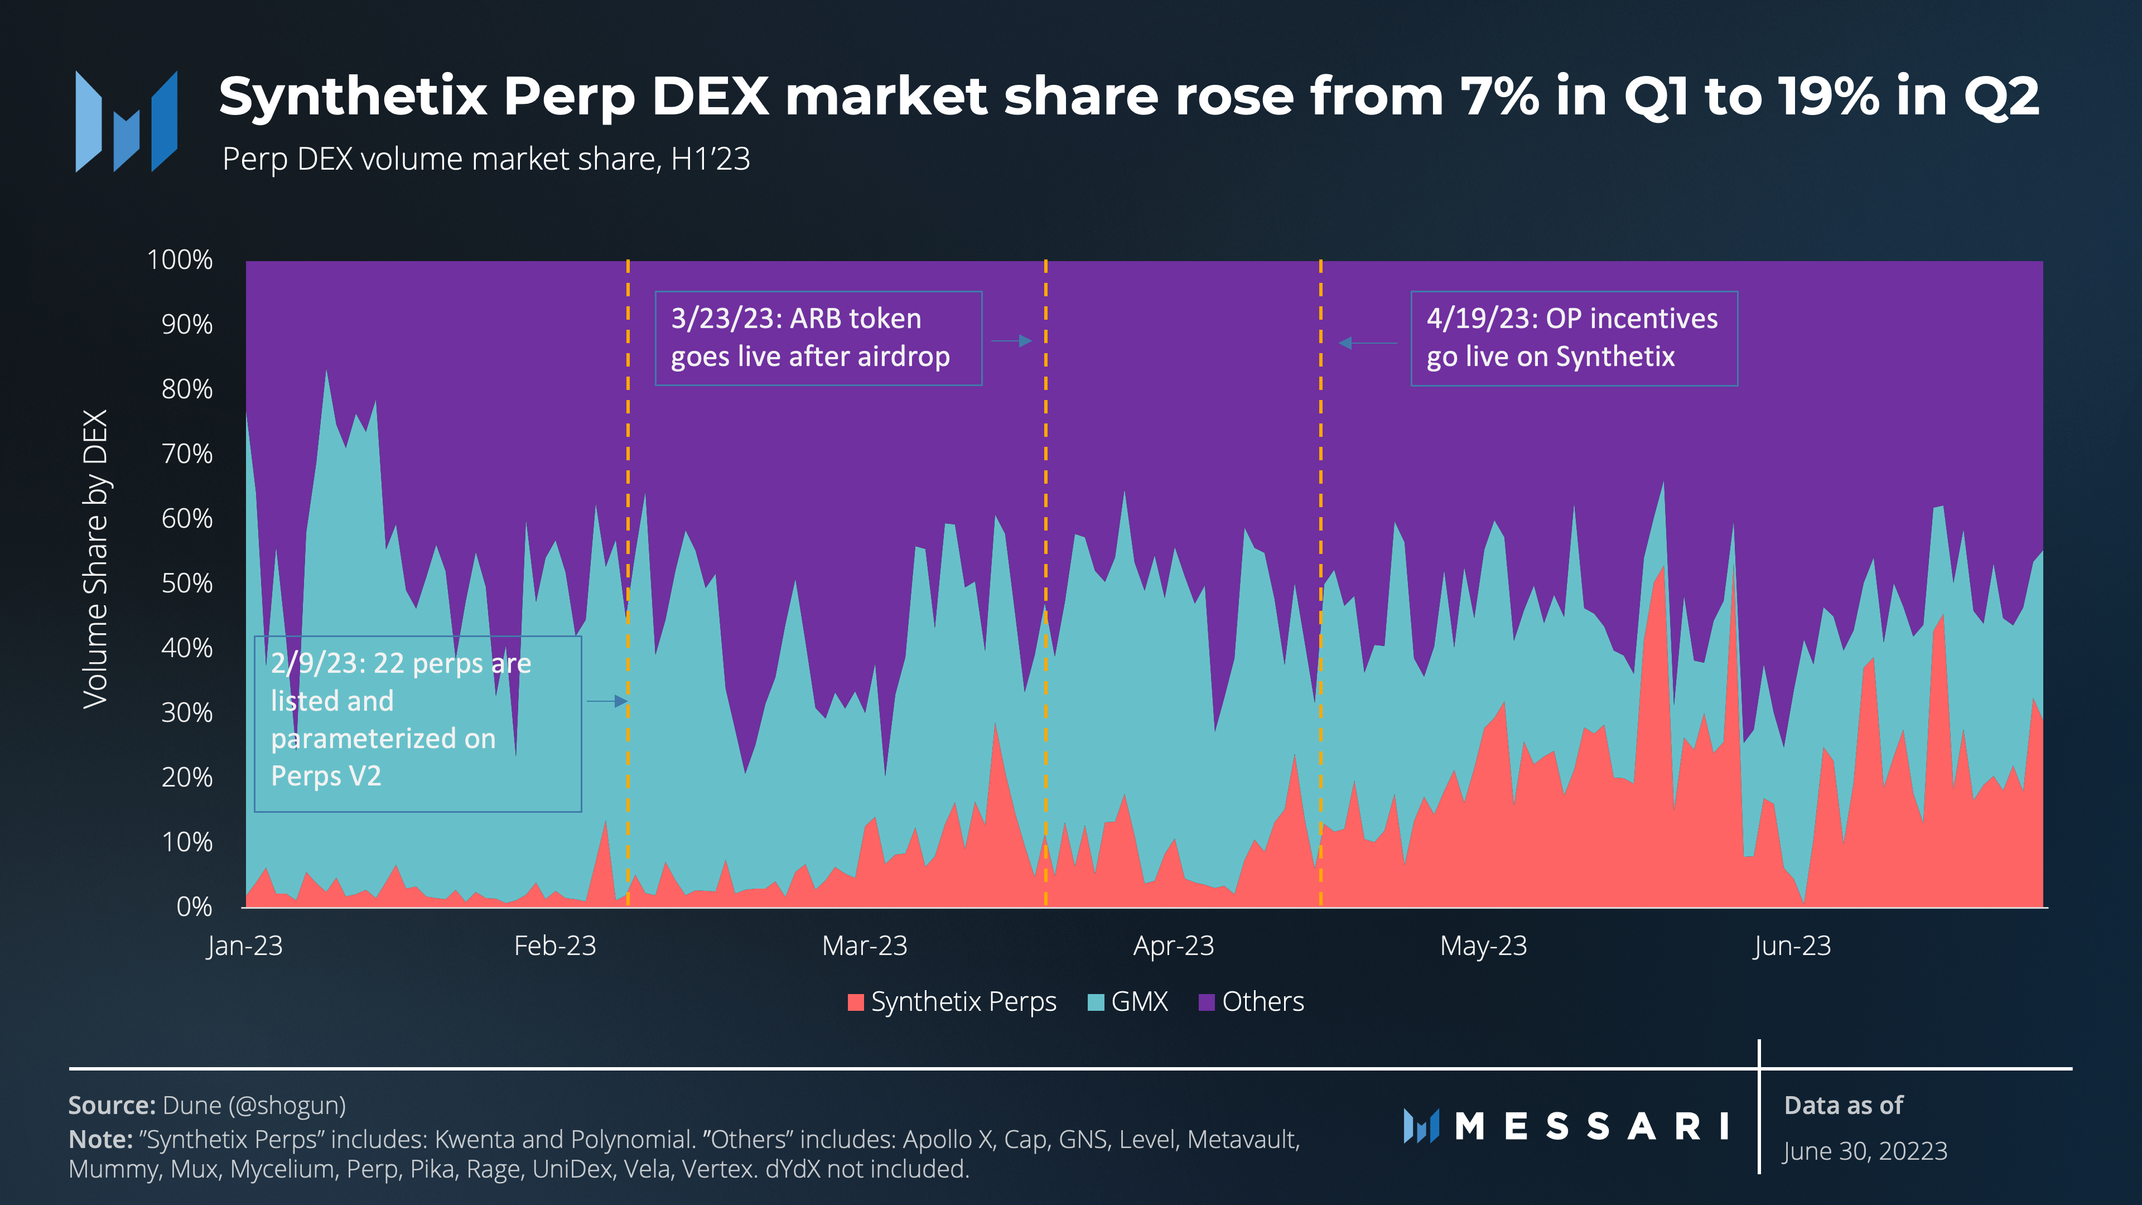
Roughly halfway through the 21 week cycle, the takeaways reveal increases in user activity but not an increase in users. For traders, OP incentives covered roughly 80% of the trading fees spent on Synthetix. Since the start of the program, Synthetix also increased its market share versus its largest decentralized competitor, GMX. Despite the volume numbers, neither transactions nor users have been meaningfully impacted by the program. In fact, daily, weekly and monthly transactions were lower than before the incentives. User data (measuring the number of addresses) showed similar trends, implying that the biggest impact was an increase in the activity of existing users.
Because the program runs until September 13, it will be easier to understand retention rates after Q3. At the moment, stakers are earning more in fees than the DAO is paying in incentives, as the heavily subsidized trading is a strong tailwind for activity.
Closing Summary
The explosion of trading on Synthetix Perps continued in Q2, and the design has greatly benefited both traders and stakers. Volumes and fees were up, with inflation leveling off, delivering low double-digit yields to SNX stakers. As the OP incentives program continues through most of Q3, there is continued opportunity for SNX stakers and users to enjoy subsidized usage. The Synthetix V3 feature rollout continues as the team executes on the evolution to a more modular and composable platform.
This report was commissioned by Synthetix DAO. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization does not influence editorial decision or content. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research, and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
This report was commissioned by Synthetix DAO. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Looking to dive deeper? Subscribe to Messari Pro. Messari Pro memberships provide access to daily crypto news and insights, exclusive long-form daily research, advanced screener, charting & watchlist features, and access to curated sets of charts and metrics. Learn more at messari.io/pro.
Before joining Messari as a Senior Research Analyst, John worked in Equity Derivatives on the buy-side and sell-side for over five years. He studied macroeconomics and markets for almost a decade. Now, John spends time thinking about token design, DeFi protocols, and governance.
Before joining Messari as a Senior Research Analyst, John worked in Equity Derivatives on the buy-side and sell-side for over five years. He studied macroeconomics and markets for almost a decade. Now, John spends time thinking about token design, DeFi protocols, and governance.