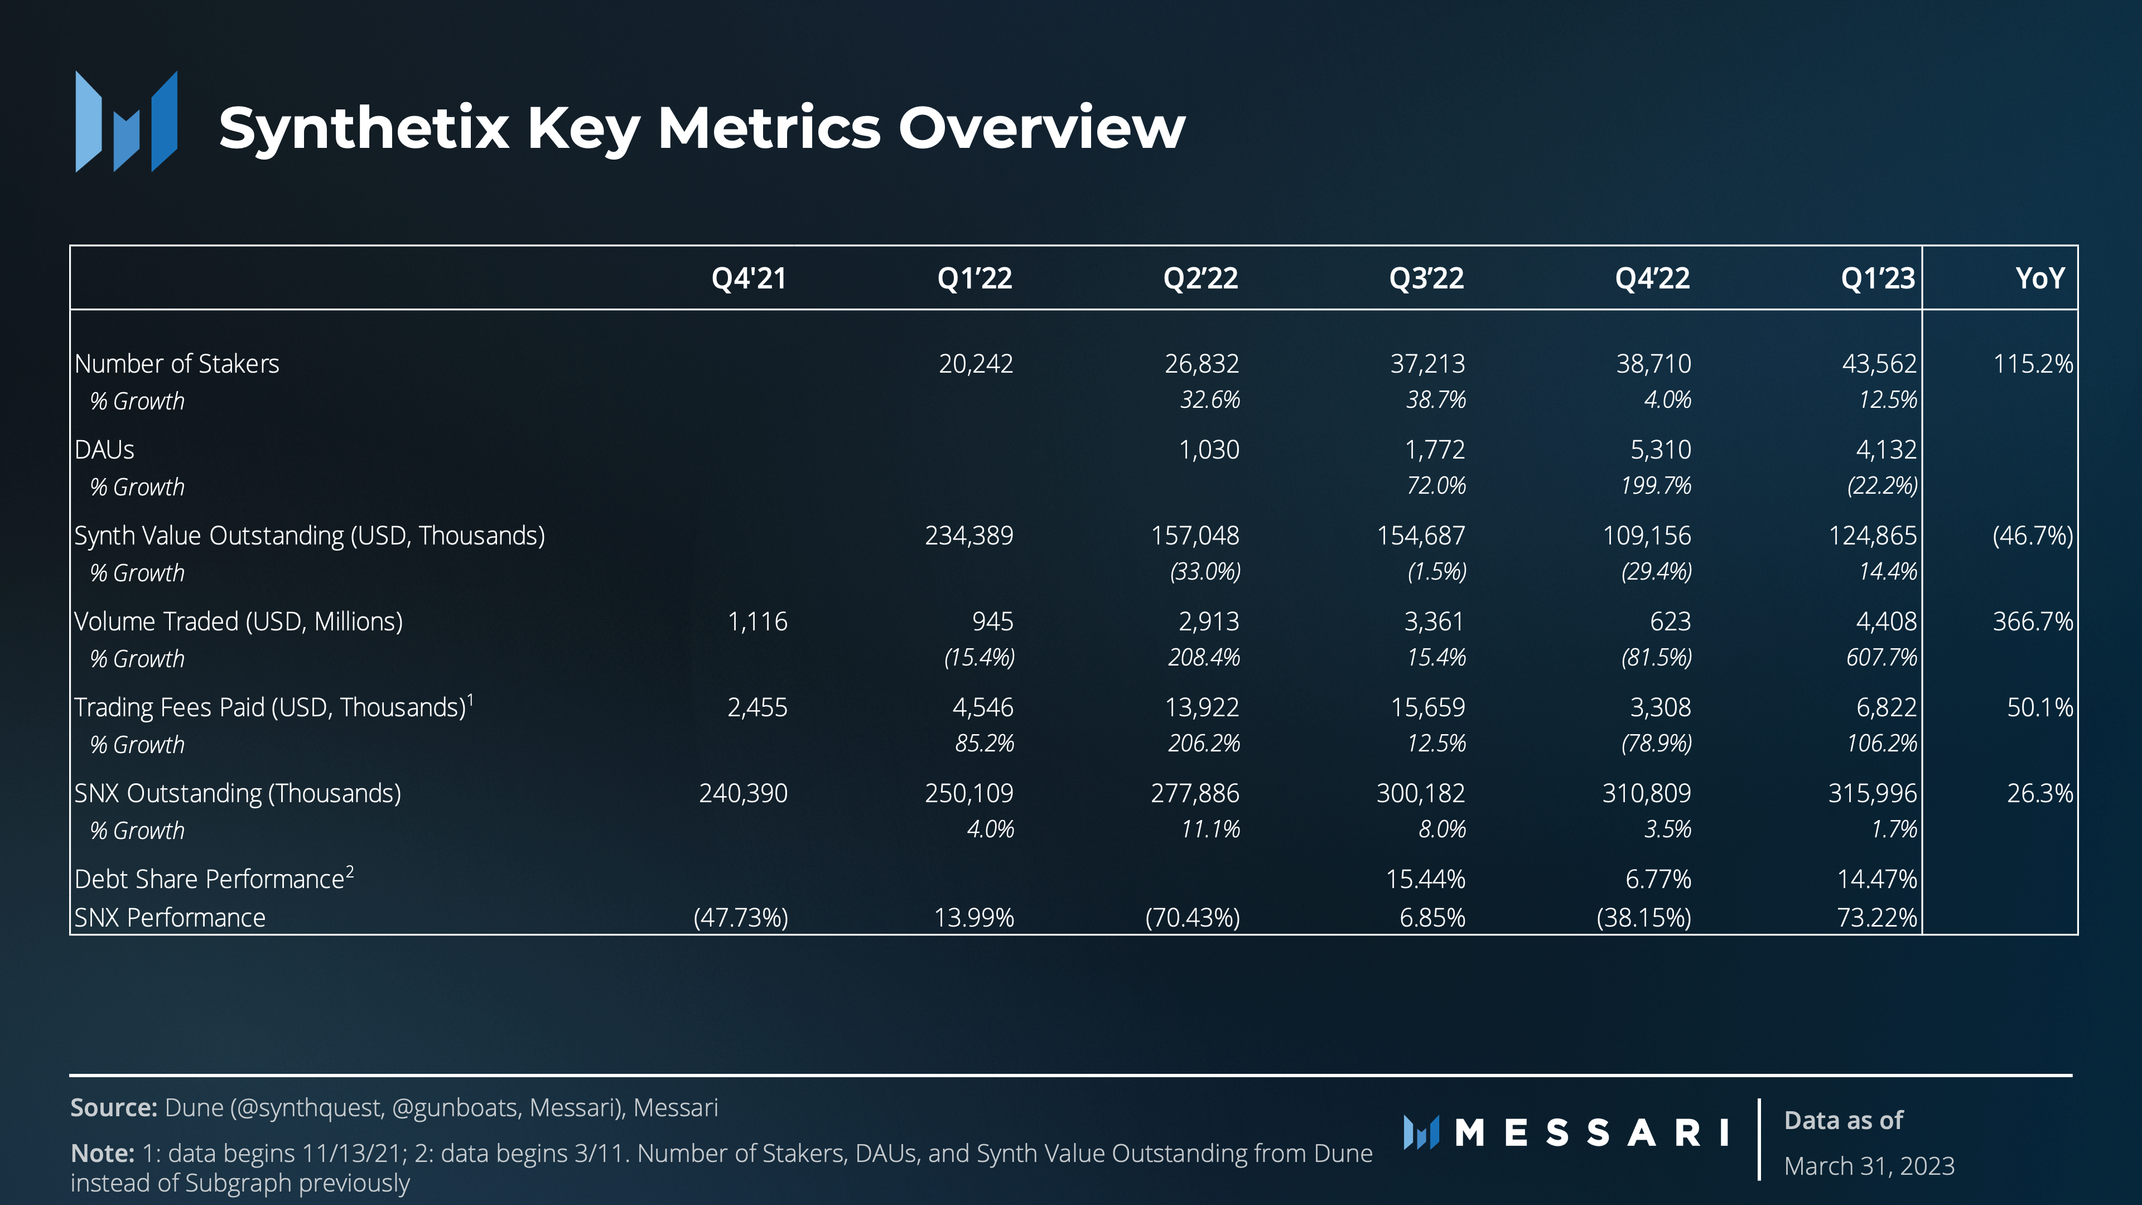
Volumes bounced back from a quiet Q4 to post the highest usage in at least seven quarters, with users executing $4.4 billion in Q1’23. Nearly 90% was driven by Synthetix Perps.
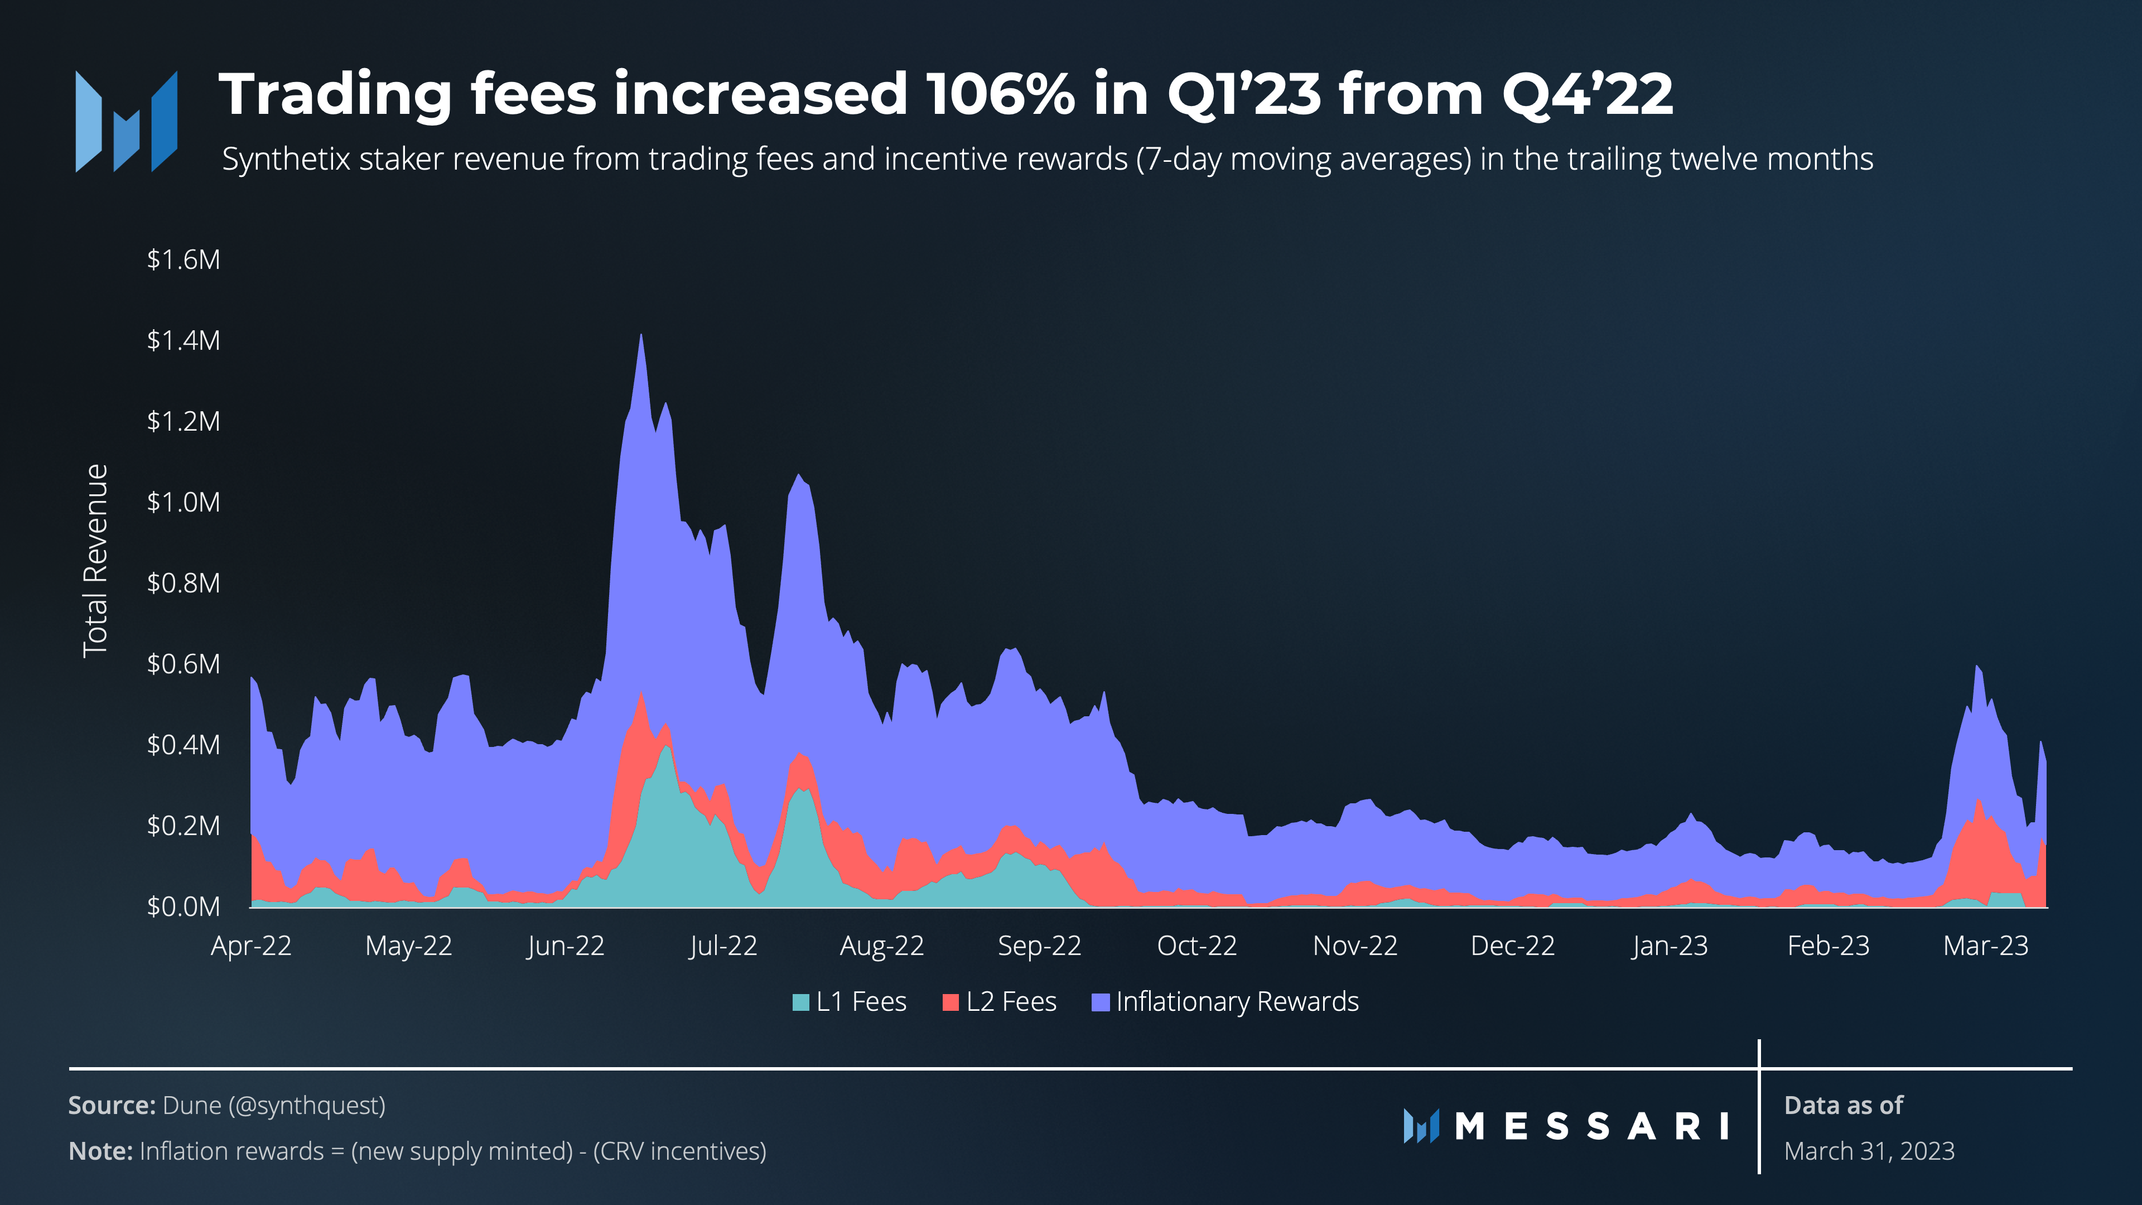
Fees paid to stakers doubled from Q4’22 to $6.8 million in Q1’23. Lower fees helped onboard new traders and increased the number of arbitrage traders, driving significant volume,though also leading to lower margins.
The number of stakers increased 12.5% QoQ to 43,562 at quarter end, up 115% from a year earlier.
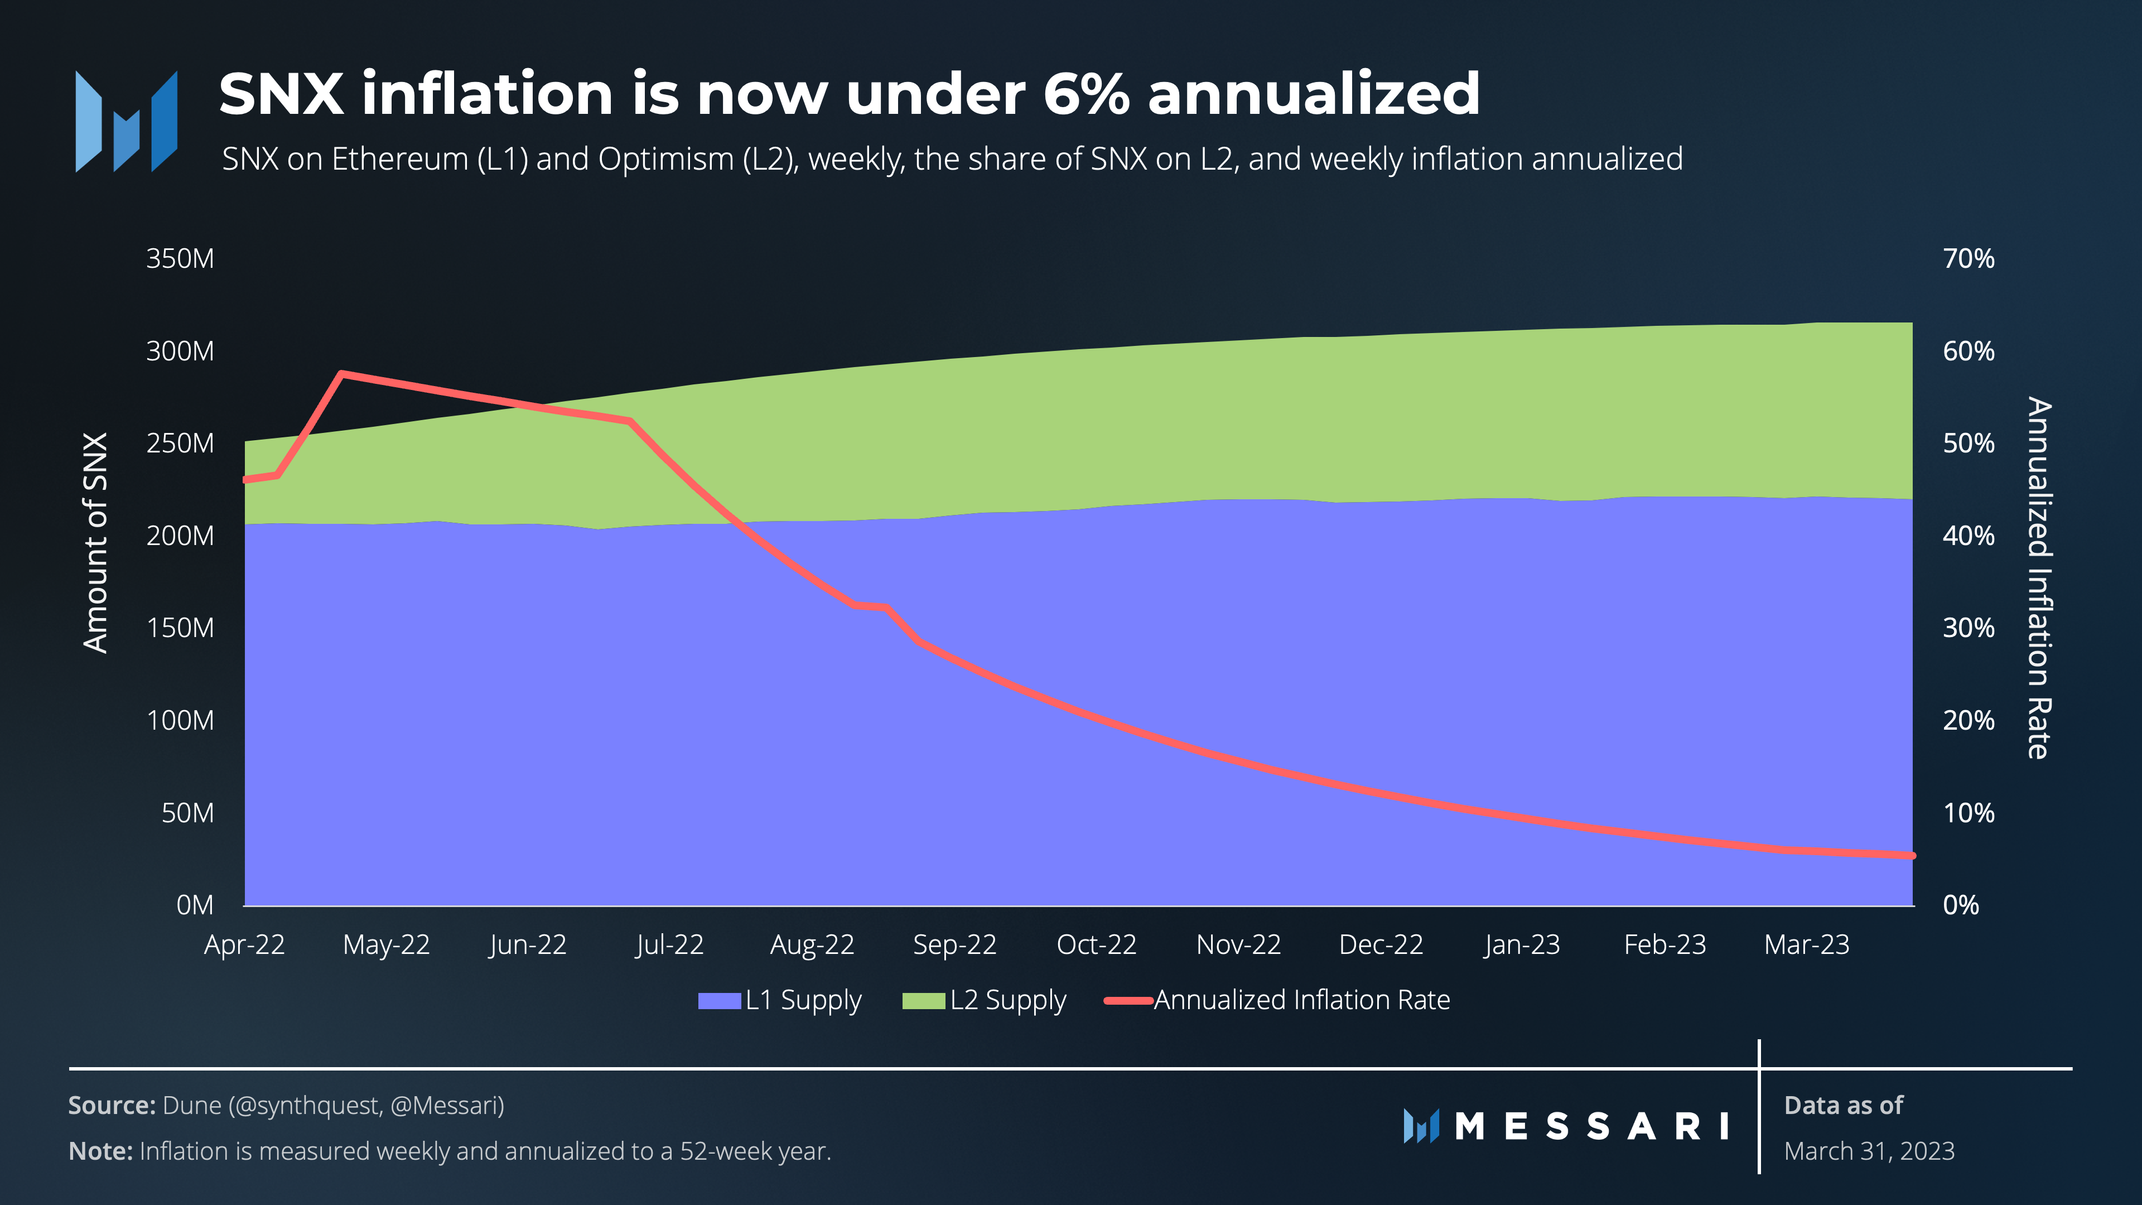
Inflation fell to under a 6% annualized rate at quarter end. Revenue for stakers is now mostly trading fees rather than inflation rewards.
V3 began a phased rollout in February with features to be added incrementally. The upgrade aims to make Synthetix more modular, configurable for protocols and stakers, and composable.
Primer on Synthetix
Synthetix is a decentralized synthetic asset issuance and liquidity protocol that allows users to trade synthetic cryptocurrencies, fiat currencies, and commodities. Each synthetic asset tracks the price of an external asset through the use of Chainlink, Pyth, or Uniswap V3 TWAP oracles. Users can either trade in spot or in perpetual futures markets for synthetic assets. SNX is the native protocol token, responsible for governance as well as the primary collateral that backs the liquidity of the network. SNX can be staked as collateral for sUSD, the Synthetix stablecoin, which can be traded on Synthetix for any other synth (sAsset). The DAO uses a novel V3 Governance Module (V3GM), which uses councils of appointees who are voted on by SNX holders.
Key Metrics
Performance Analysis
Network Overview
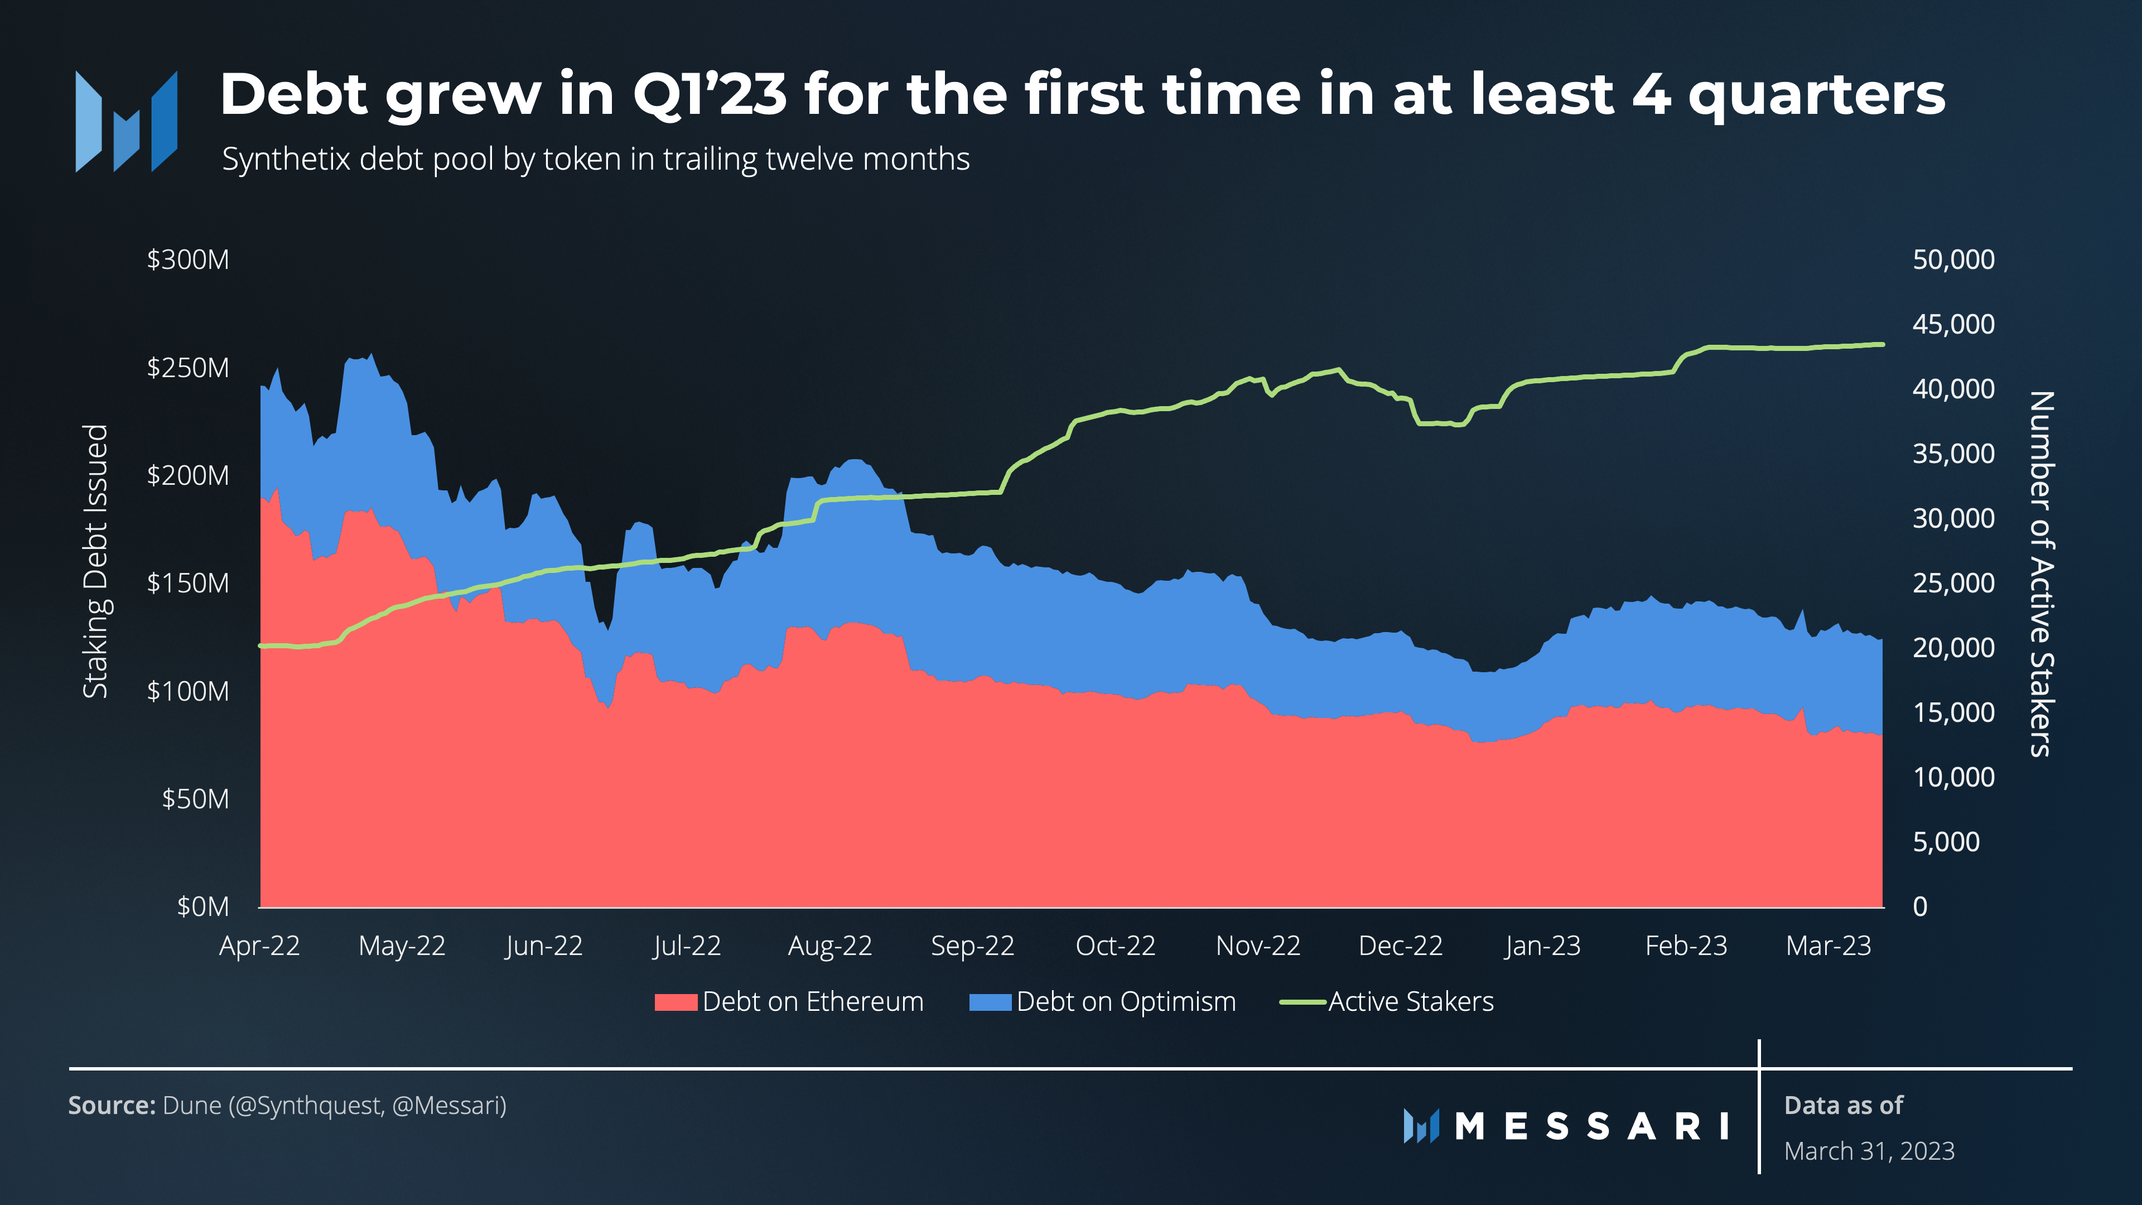
SNX stakers provide the collateral for traders to hold and trade synths, which make up the debt on the other side of the SNX collateral. The value of the debt pool rose 14% in aggregate, with synths on L2 increasing 37% while synths on L1 increased only 5%.
By exposure, debt increased significantly in sBTC terms from $6 million to over $15 million, a 144% increase. sUSD exposure fell 13% to end the quarter at $40 million, leaving stakers with $84 million of non-stable exposure, or 67.2% of the debt pool, up from 56.9% at the end of Q4’22. SNX stakers, who receive fees for trading, are effectively short the debt pool. In other words, having less stablecoin exposure makes it slightly harder for stakers to hedge their debt pool exposure. SNX stakers can hedge their debt exposure with partners like dhedge, or they can manually hedge debt pool exposures, to reduce the risk of debt pool price changes.
This is the first quarter with data to measure active stakers across instances. The data shows robust participation, especially on Optimism. Active stakers on the Layer-2 instance increased 13.6% in Q1 to end the quarter with ~40,000 stakers. Between the two instances, total stakers increased 12.5% to ~44,000.
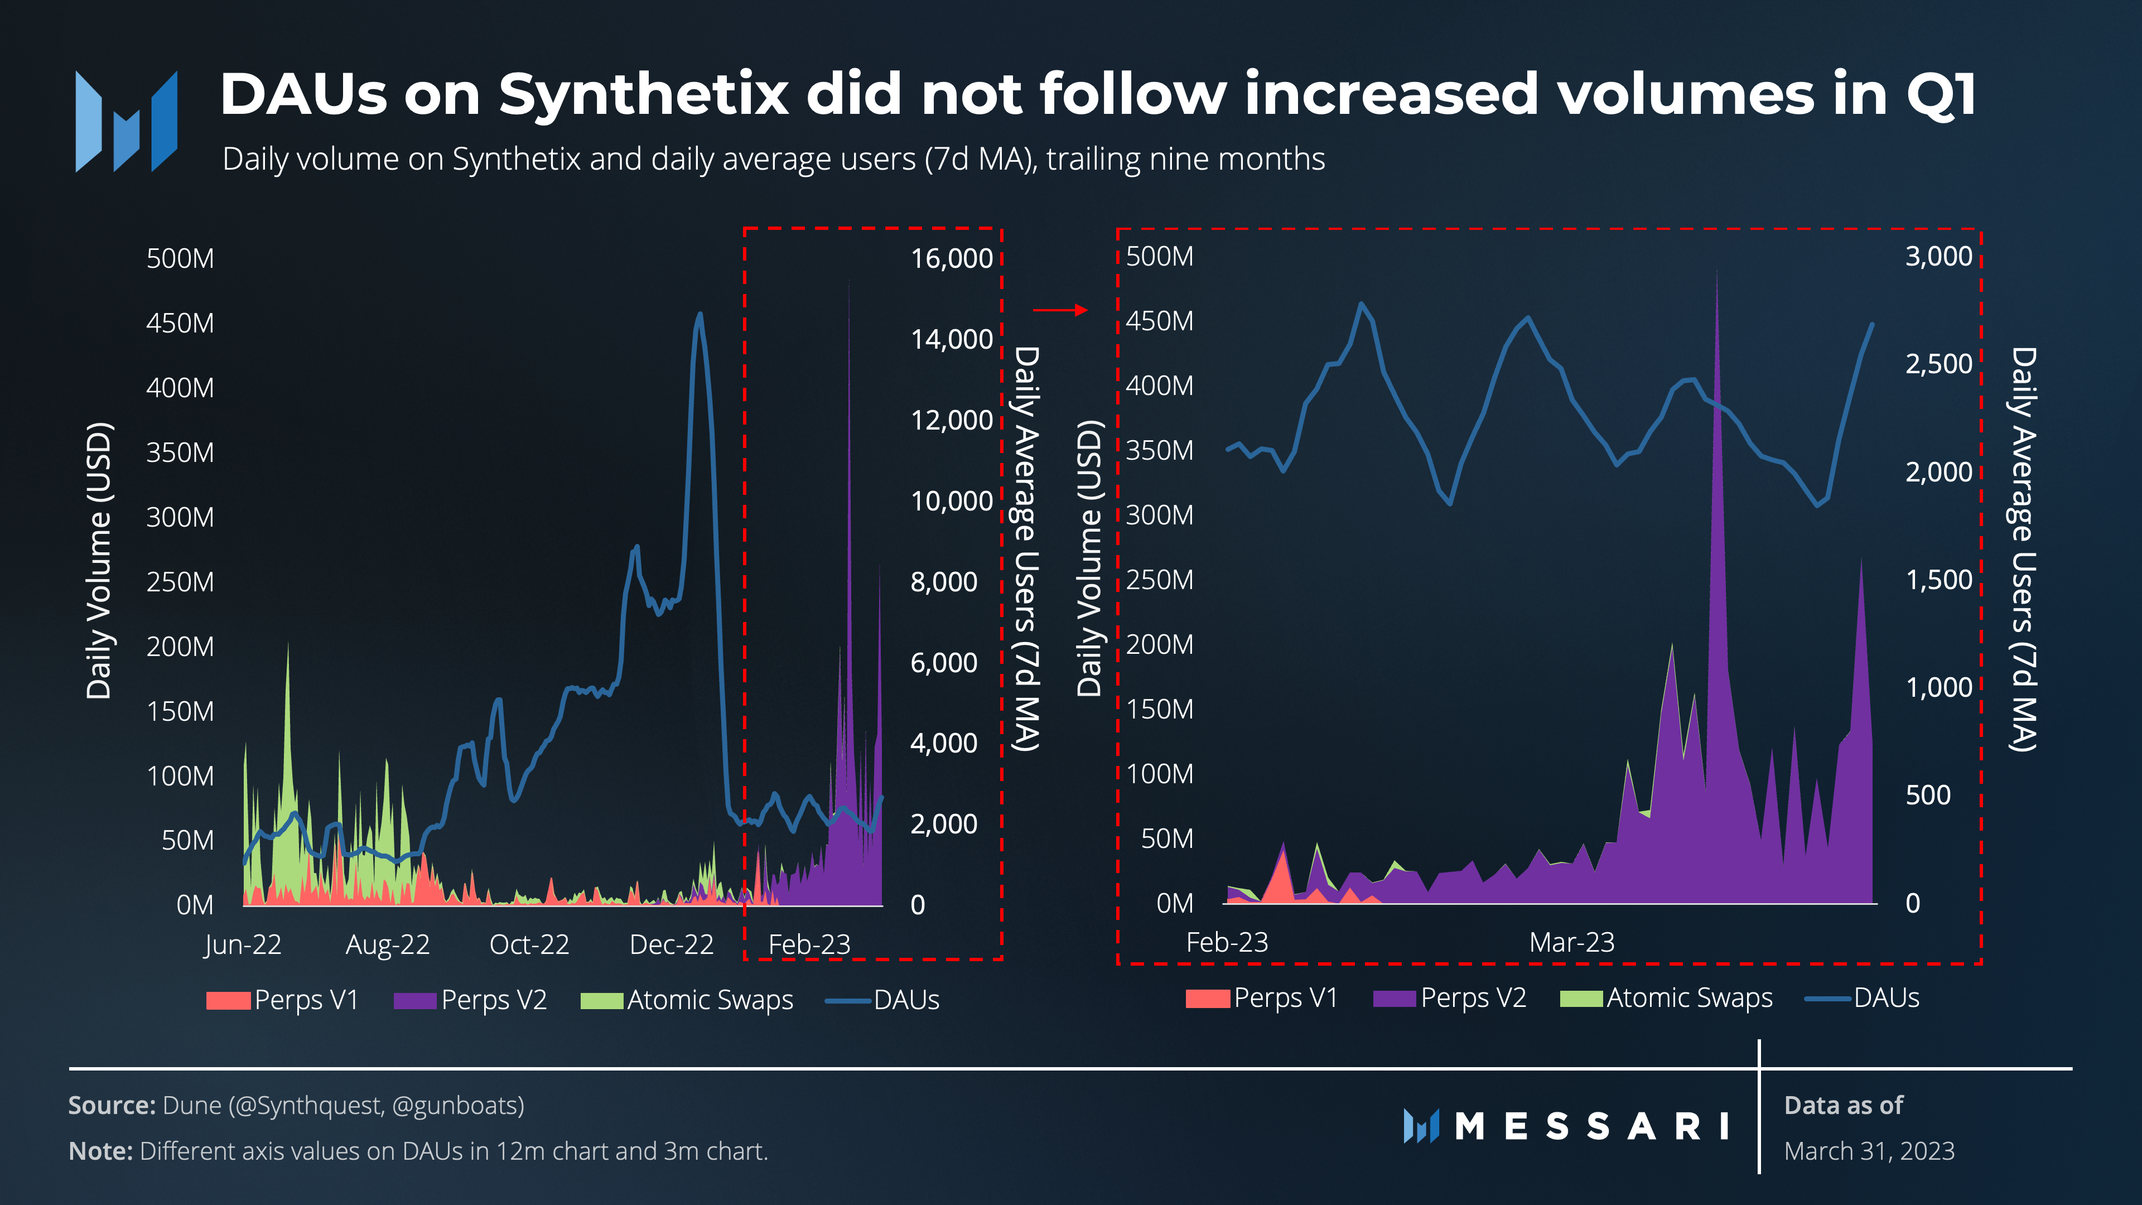
Daily average users on Synthetix leveled off around 2,500 in Q1, after ramping up in Q4’22 likely from Optimism Quest. The remaining users were significantly busier than rewards farmers. During OP quest, from September 20, 2022, to January 17, 2023, the daily average volume per user was ~$2,000, while from January 18, 2023, to March 31, 2023, the average volume per user was more than 12x at ~$25,000. Synthetix users are almost entirely on Optimism, where DAUs averaged 5.6x the participation of that on Ethereum Mainnet.
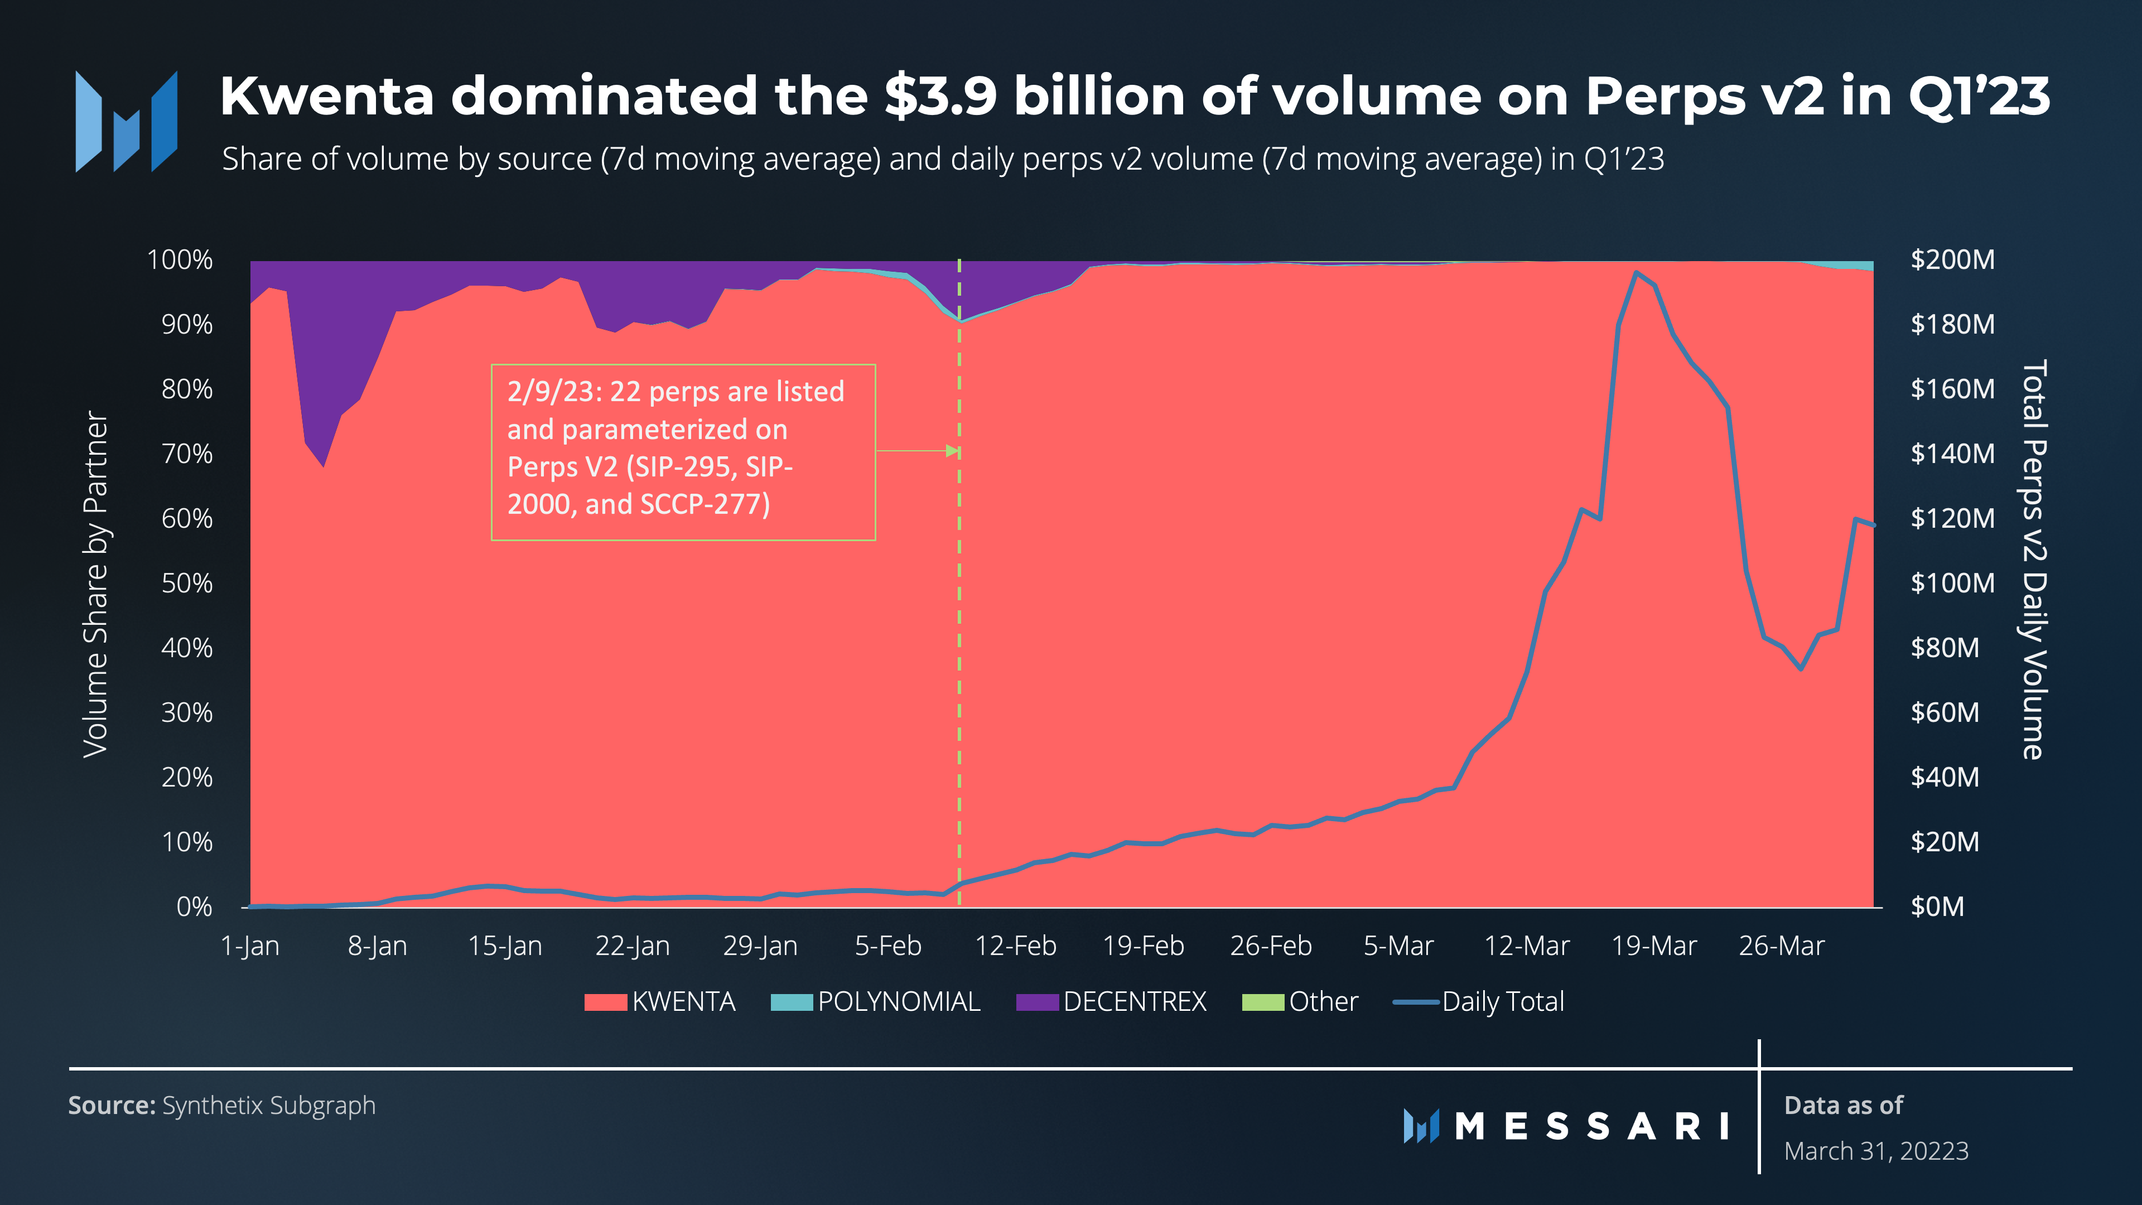
The launch of Synthetix Perps V2 has clearly been a catalyst to increased volumes. V2’s lower fees, dynamic funding rates, and price impact function create a mechanism similar to an order book that encourages arbitrageurs to neutralize staker exposure. These improvements led to nearly $4 billion in volume on Synthetix Perps in Q1’23. The consistent volume growth in the quarter can be attributed to three main factors: the general increase in market activity, the gradual increase in OI limits by Synthetix DAO, and the launch of new markets. The design seemed to be working well, based off the early experiences of stakers earning fees while taking little directional exposure.
Synthetix is now the backend for multiple perps front ends, with Kwenta being the dominant exchange in Q1. Kwenta originally offered incentives to just KWENTA stakers who trade on the platform, but it recently expanded the program to reward anyone who trades on the platform (though KWENTA stakers will still earn more). Polynomial and Decentrex are newer offerings that facilitated nearly $30 million in volumes in Q1.
SNX supply increased by less than 2% in Q1, ending the quarter with just under 316 million SNX outstanding. This was the smallest percentage increase since at least Q4’21. The drop in inflation was due to the 5% weekly decrease in SNX rewards to stakers, since the staking ratio is above the target of 65%. Inflation slowed in the last month of the quarter as SIP-294 was implemented, increasing the 6,000 SNX incentive reward for synths on Curve to 10,000. The inflation rate at the end of the quarter was 0.11% per week (342,000 SNX), or 5.79% annualized, and falling.
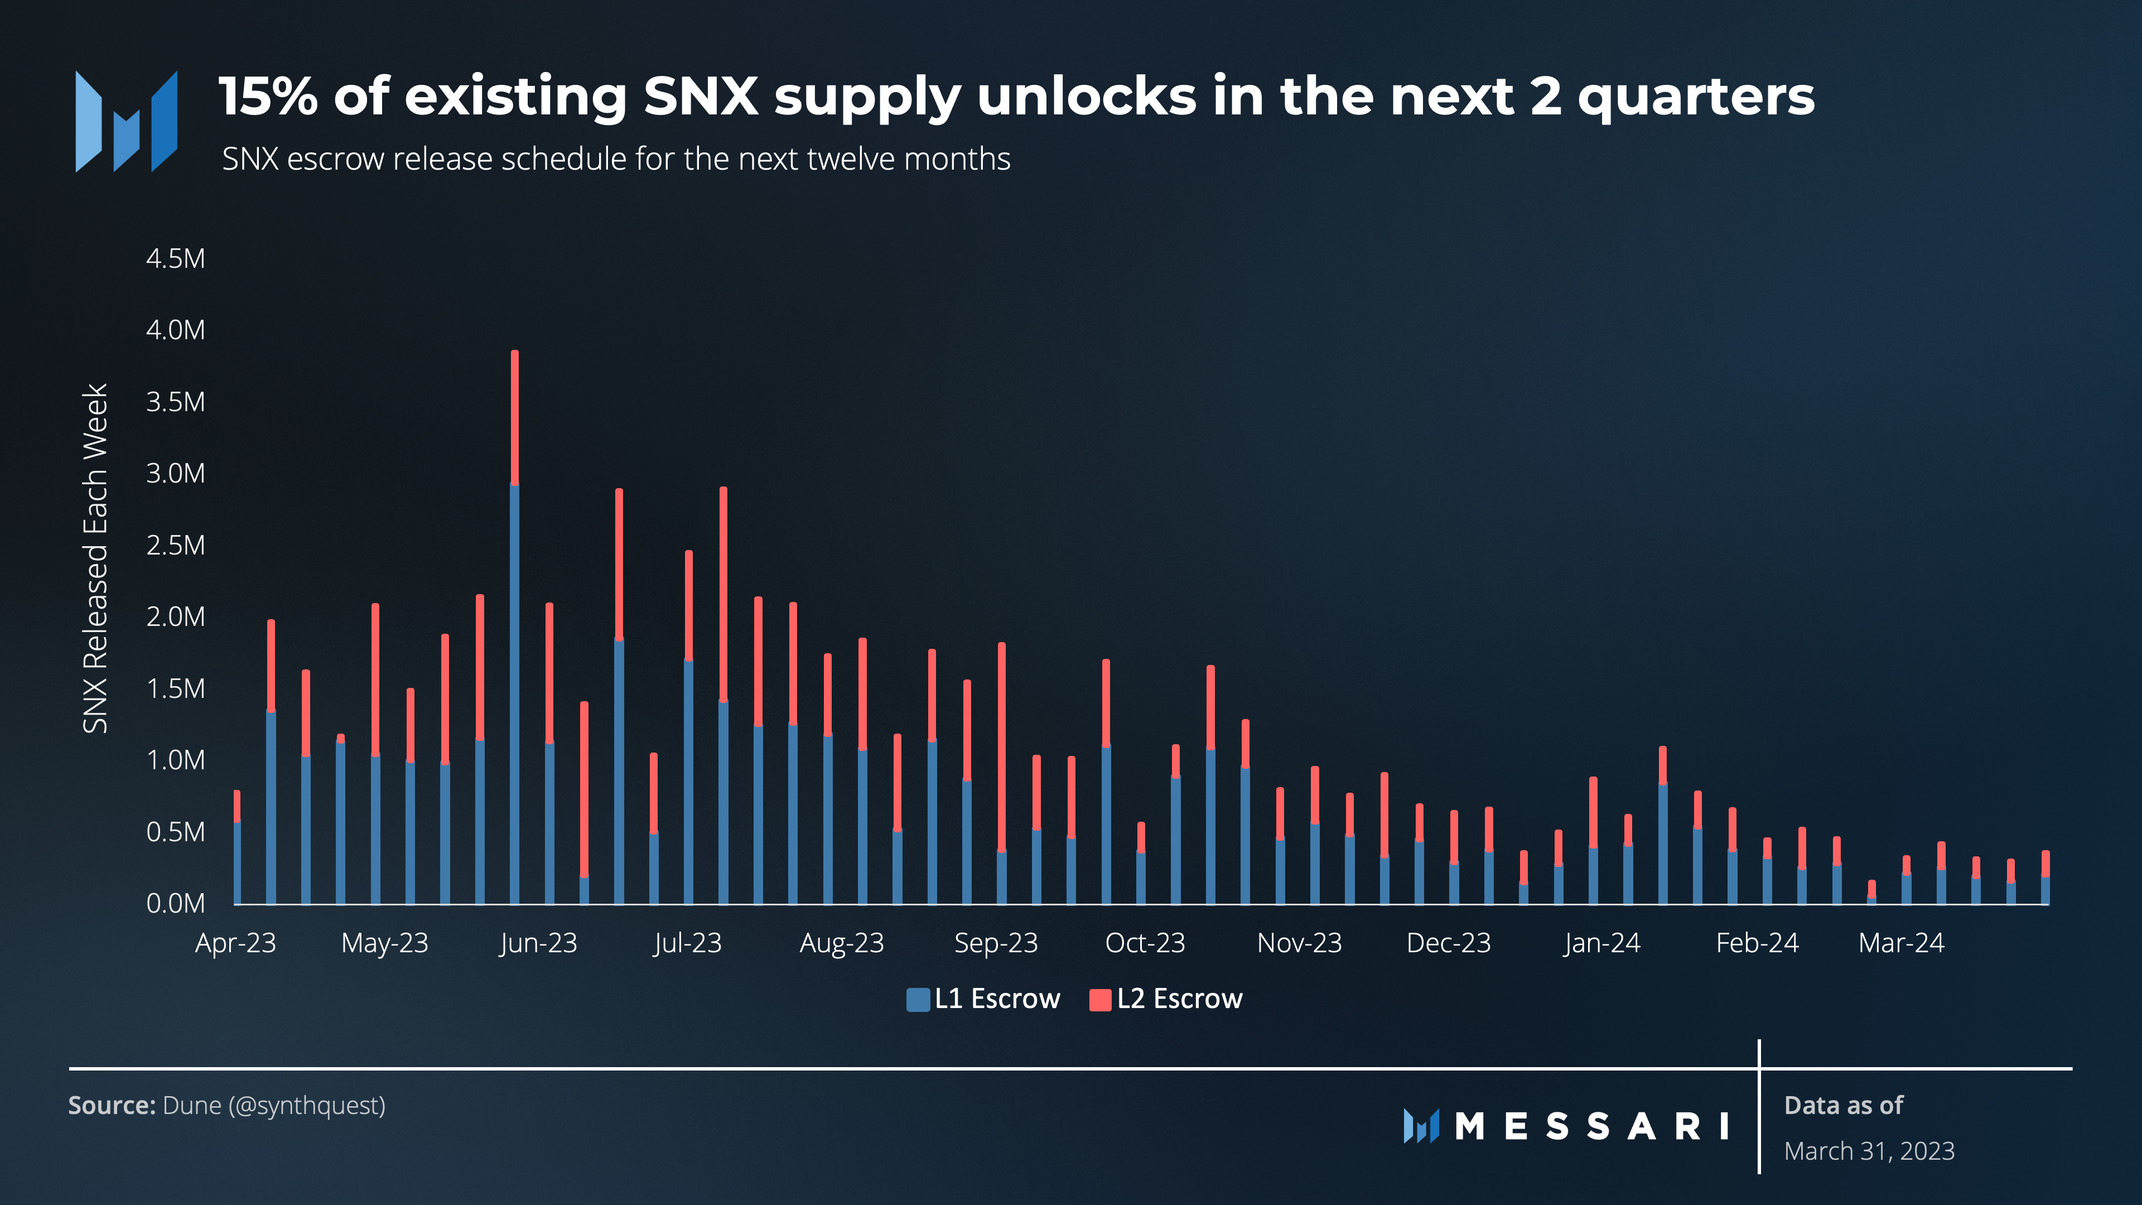
Synthetix stakers from the high inflation era are roughly halfway through the escrow period. With the inflation rate being significantly lower in the last two quarters, the hangover from earlier periods will not be as steep. Inflation escrow has two main lingering effects: First, it lowers the yield received by new stakers, because SNX rewards in escrow can be staked, thus reducing the share of the fees earned by new stakers. While that effect is unwound if the position is unstaked, which would improve the potential yield of new stakers, it could lead to the second effect: a large influx of supply coming on the market. Fortunately, stakers and investors can focus more on the stake rate and fee generation than the potential supply overhang after Q3.
Staker Perspective
Trading fees on Synthetix more than doubled from the fourth quarter, primarily on the Layer-2 instance driven by the release and expansion of Synthetix Perps V2. The product’s lower fees are a differentiating factor among decentralized perp exchanges that likely pushed Synthetix Perps volume dramatically higher. It also resulted in lower margins for stakers. Despite volumes on Synthetix being higher than any of the last five quarters, the amount of fees paid was less than half of Q2 and Q3 of 2022. To avoid bringing more risk to stakers due to the lower margins, the design also reduces the directional risk of stakers against the perp product by incentivizing market makers to flatten the directional skew of perp open positions. In the last month of the quarter, Synthetix stakers earned over $4.5 million in fees, a quarterly pace of over $13 million.
Yield for stakers was relatively flat quarter over quarter. The combination of SNX price appreciation and the reduction in inflation rewards helped offset tremendous growth in trading fees. The amount of fees paid more than doubled in Q1’23, which is the most sustainable and important source of revenue for stakers.
With the implementation of SIP-255, Synthetix changed how trading fees are paid to stakers. Instead of being distributed as rewards, trading fees (paid in sUSD) are now used to burn sUSD, the largest synth in the debt pool by USD value. This setup improves the health of the system by increasing the collateral ratio (no change in collateral but less debt) and still rewarding stakers who now owe less debt.
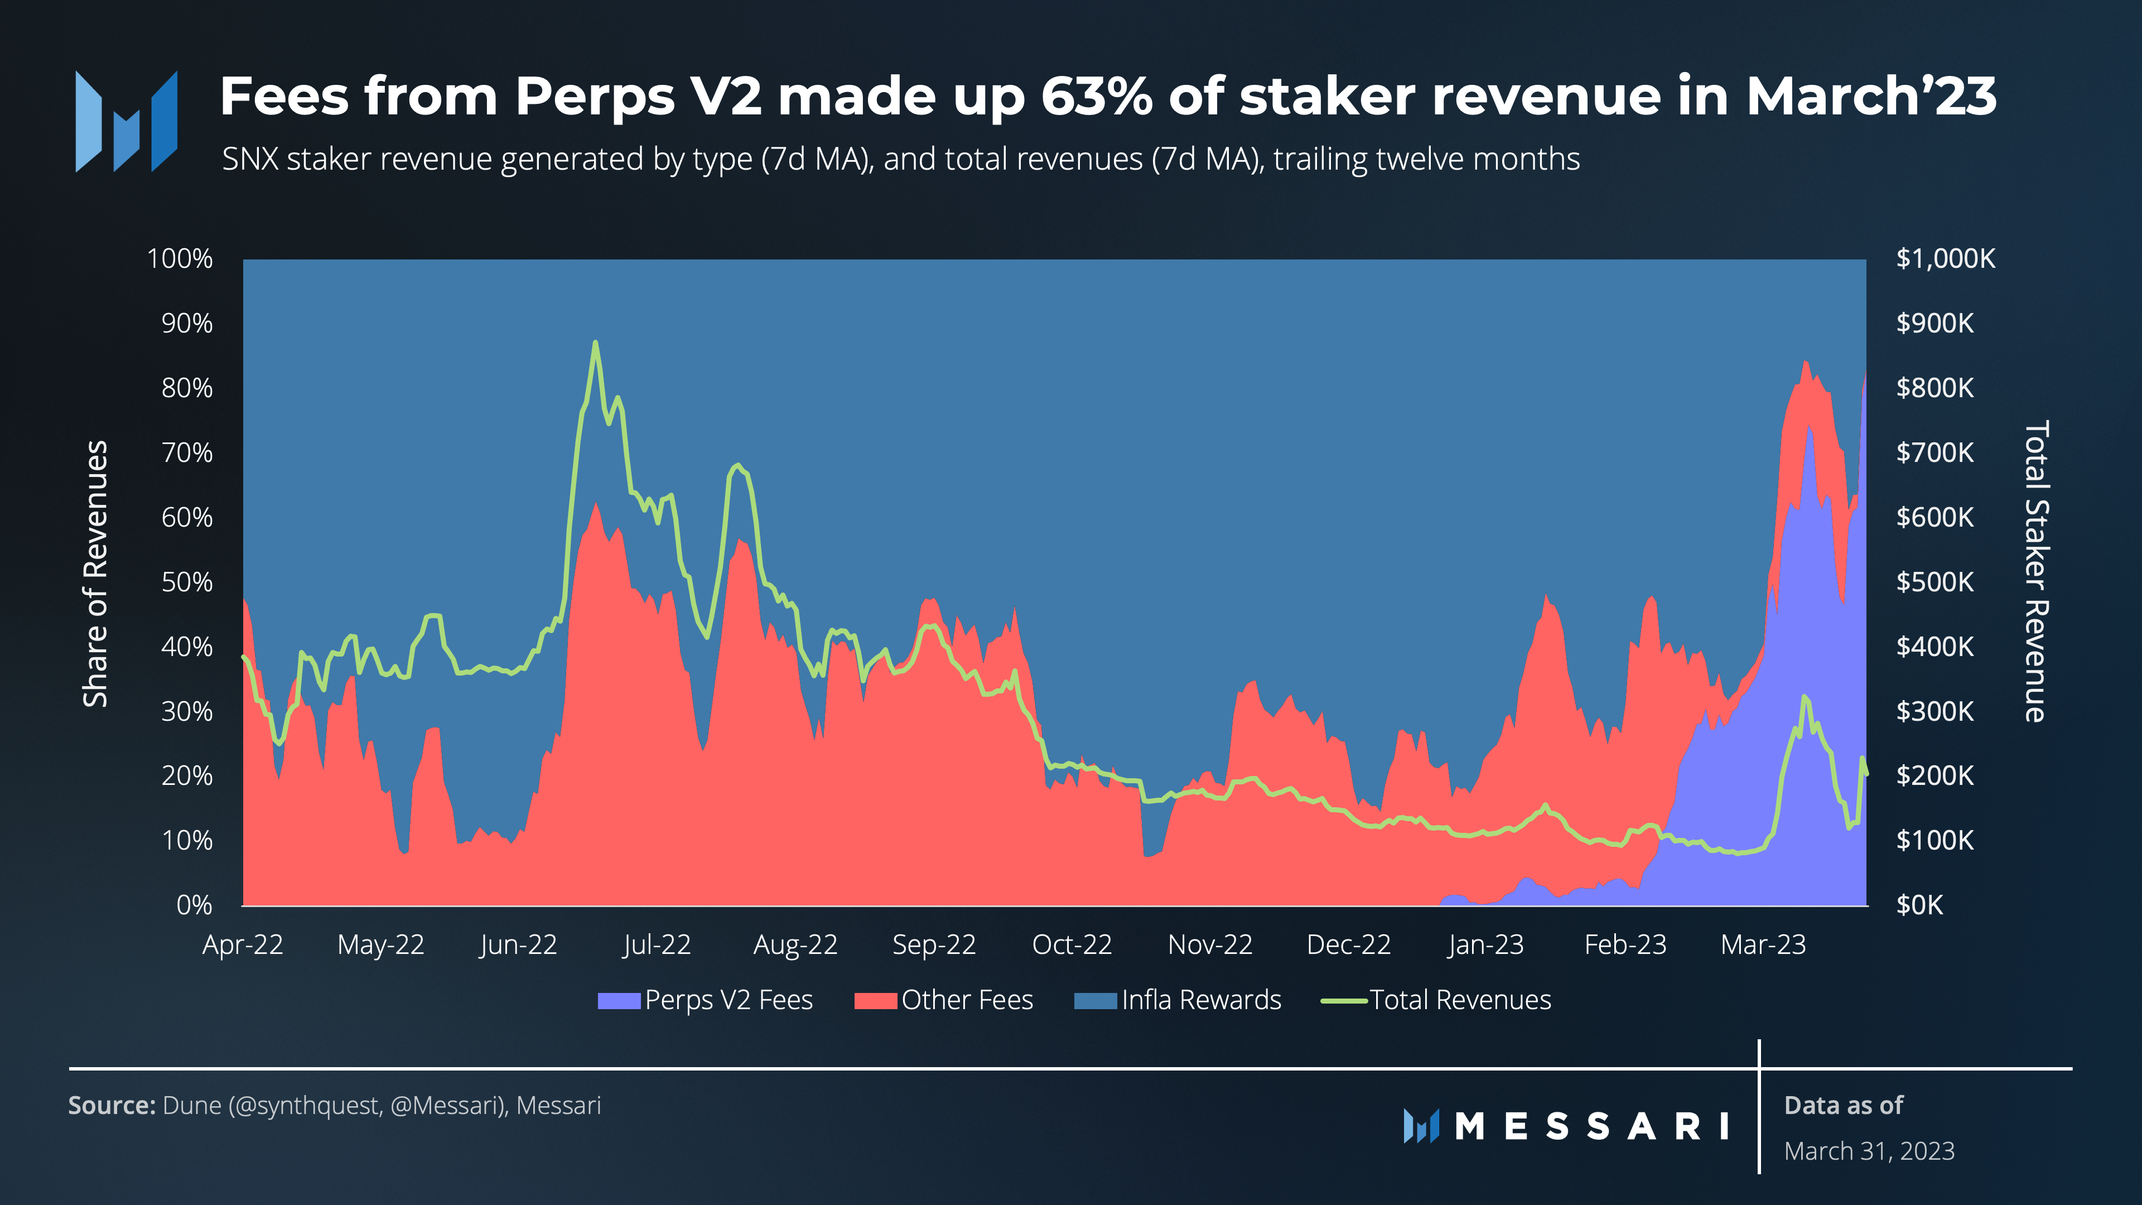
Understanding the mix of revenue generated helps assess the sustainability of the revenues and demand for the product. Stakers had their highest percentage of earnings from trading fees in Q1’23 compared to the last six quarters, with 56.3% of revenue coming from trading fees. The combination of inflation reduction and perps trading demand led to this new revenue mix. In the month of March, over 63% of staker revenue emanated from perps trading. As inflation continues to dwindle and the DAO adds trading pairs and increases open interest limits, the revenue source for stakers should continue to trend towards demand for the core product rather than inflationary rewards.
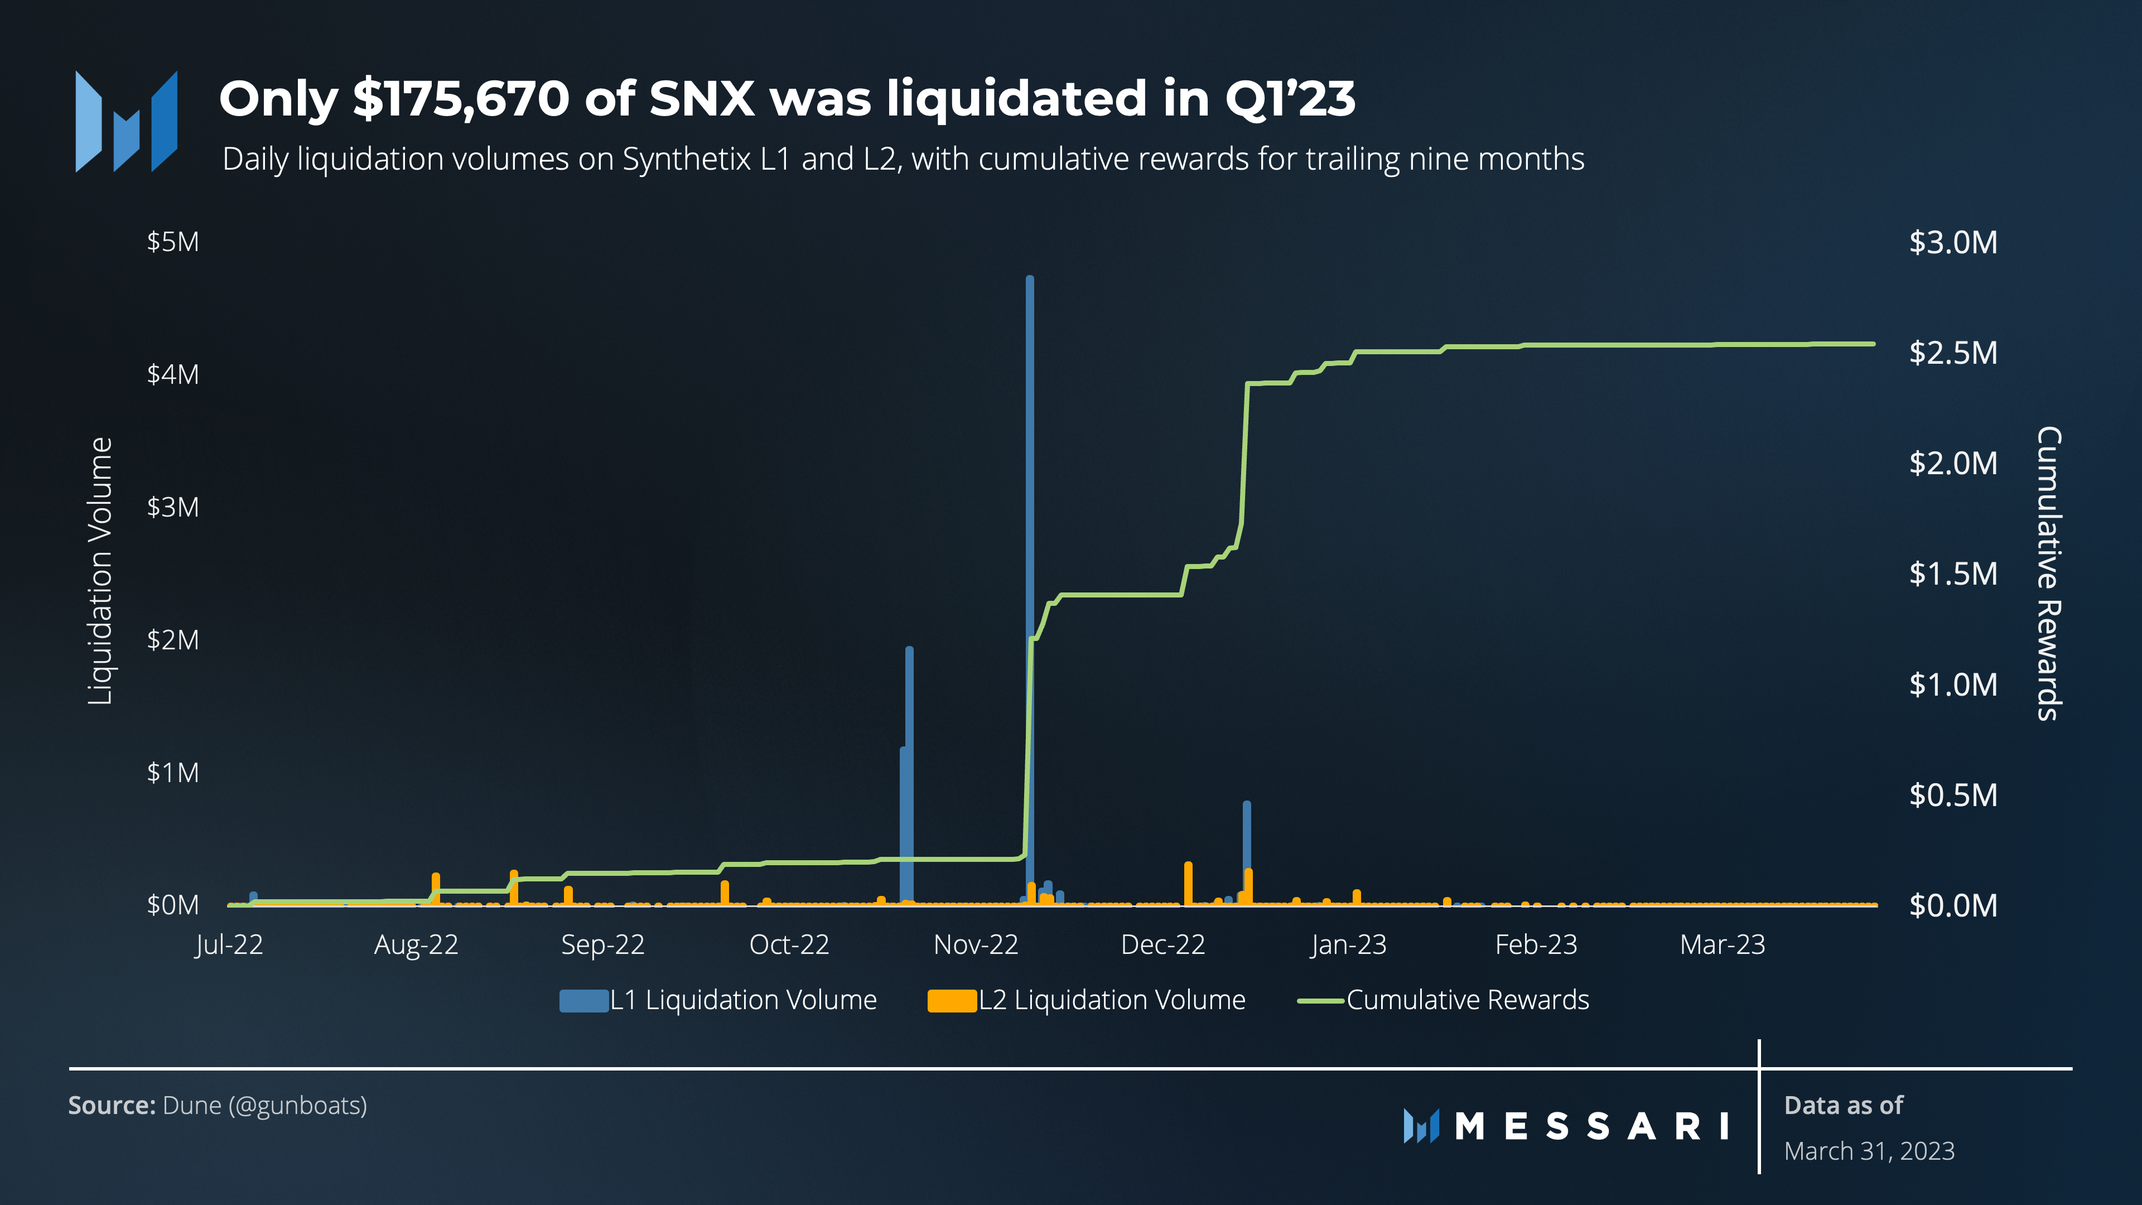
After large liquidations in previous quarters, the strength of SNX and the new fee burn mechanism helped reduce liquidations to under $200,000 in Q1. Liquidations can be very bad for Synthetix stakers because of their effect on a staker’s collateral ratio. Although we measure rewards to stakers, who collect a large discount on the collateral of liquidated peers, a healthy staker will see their collateral ratio fall as liquidations are socialized in the system. The DAO has increased penalties for liquidations in the past few quarters to further incentivize proactive and healthy stakers. The aforementioned fee change to pay stakers via burning debt should also help reduce liquidations.
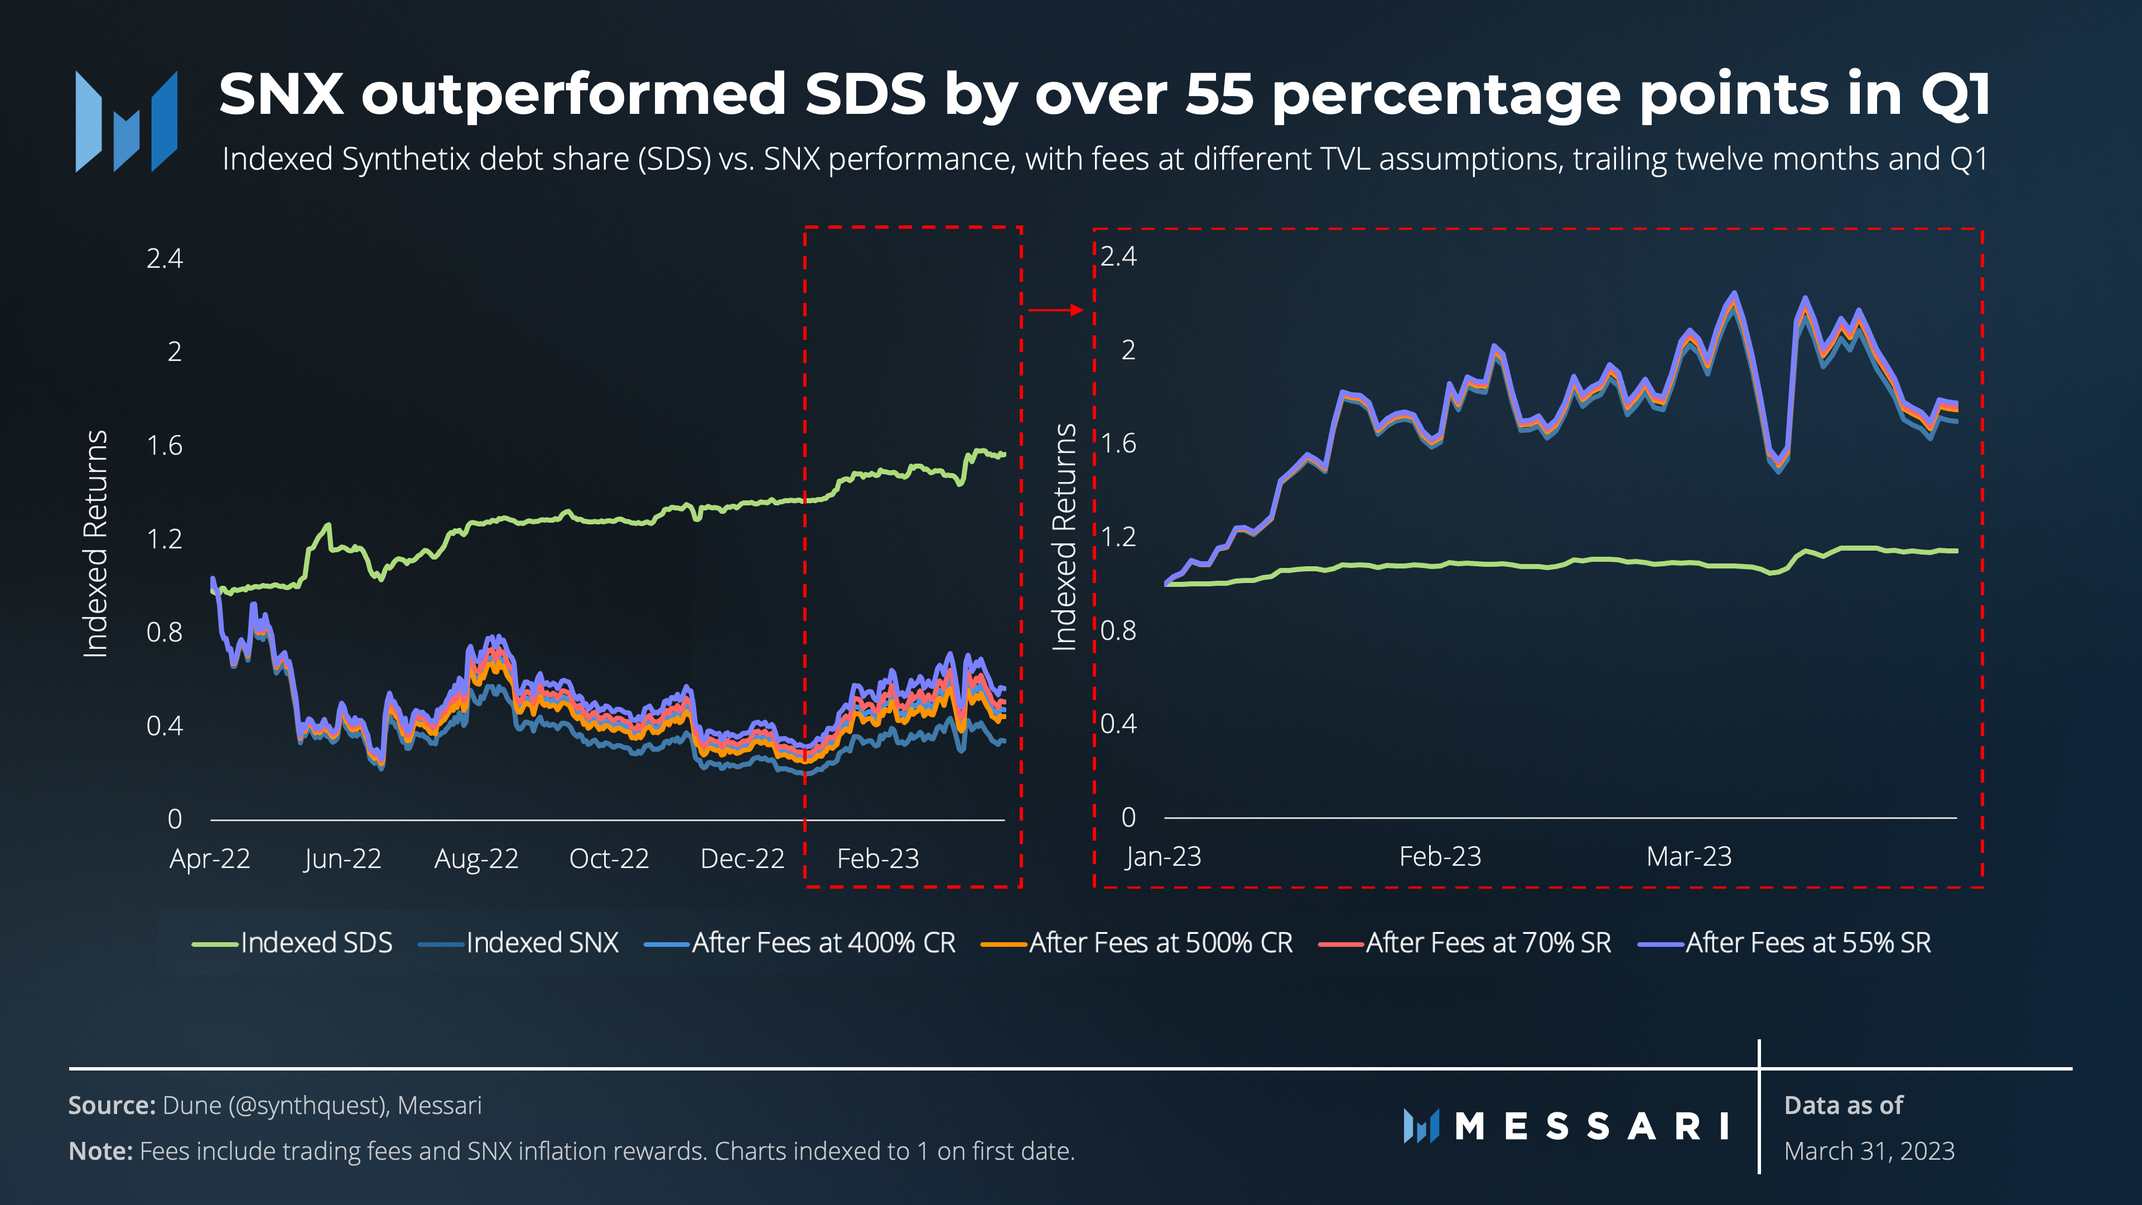
As fewer liquidations occurred and as SNX outperformed a stablecoin-heavy debt pool, the collateral pool (SNX) significantly outpaced the debt pool. Q1 demonstrated some of the positive effects of the reflexivity in the Synthetix system: an increase in trading leads to more fees and thus higher yields, which drives the SNX price higher and reduces risk in the system (because collateral is worth more). This, in turn, enables a large debt pool, which enables larger trades, and so on. The debt pool increased by ~15% in Q1 while SNX rose by more than 70%.
Qualitative Analysis
In June 2022, Synthetix launched a new governance structure, Synthetix V3GM. For more information on the governance process and many of the initiatives, please see our State of Synthetix Governance report.
Protecting Healthy Stakers
Two important changes, SIP-255 and SCCP-285, were implemented in Q1 that improved the health of the system.
With the Schedar release on February 15, the DAO changed the fee distribution mechanism from sending sUSD to a claim address for stakers to instead burning sUSD from the debt pool. The SIP primarily aimed to simplify fee payouts across chains, due to all the fees being generated on L1 from atomic swaps and being socialized across chains.
A positive externality from this change was the reduction in likelihood of a liquidation. Liquidations have pros and cons for stakers, who do typically earn a reward from excess collateral that gets liquidated, but the debt is also socialized among stakers, lowering each of their collateral ratios. By burning fees instead of leaving them to be collected, all else equal, the collateral ratio of the protocol will continue to improve as the debt pool shrinks from fee burns.
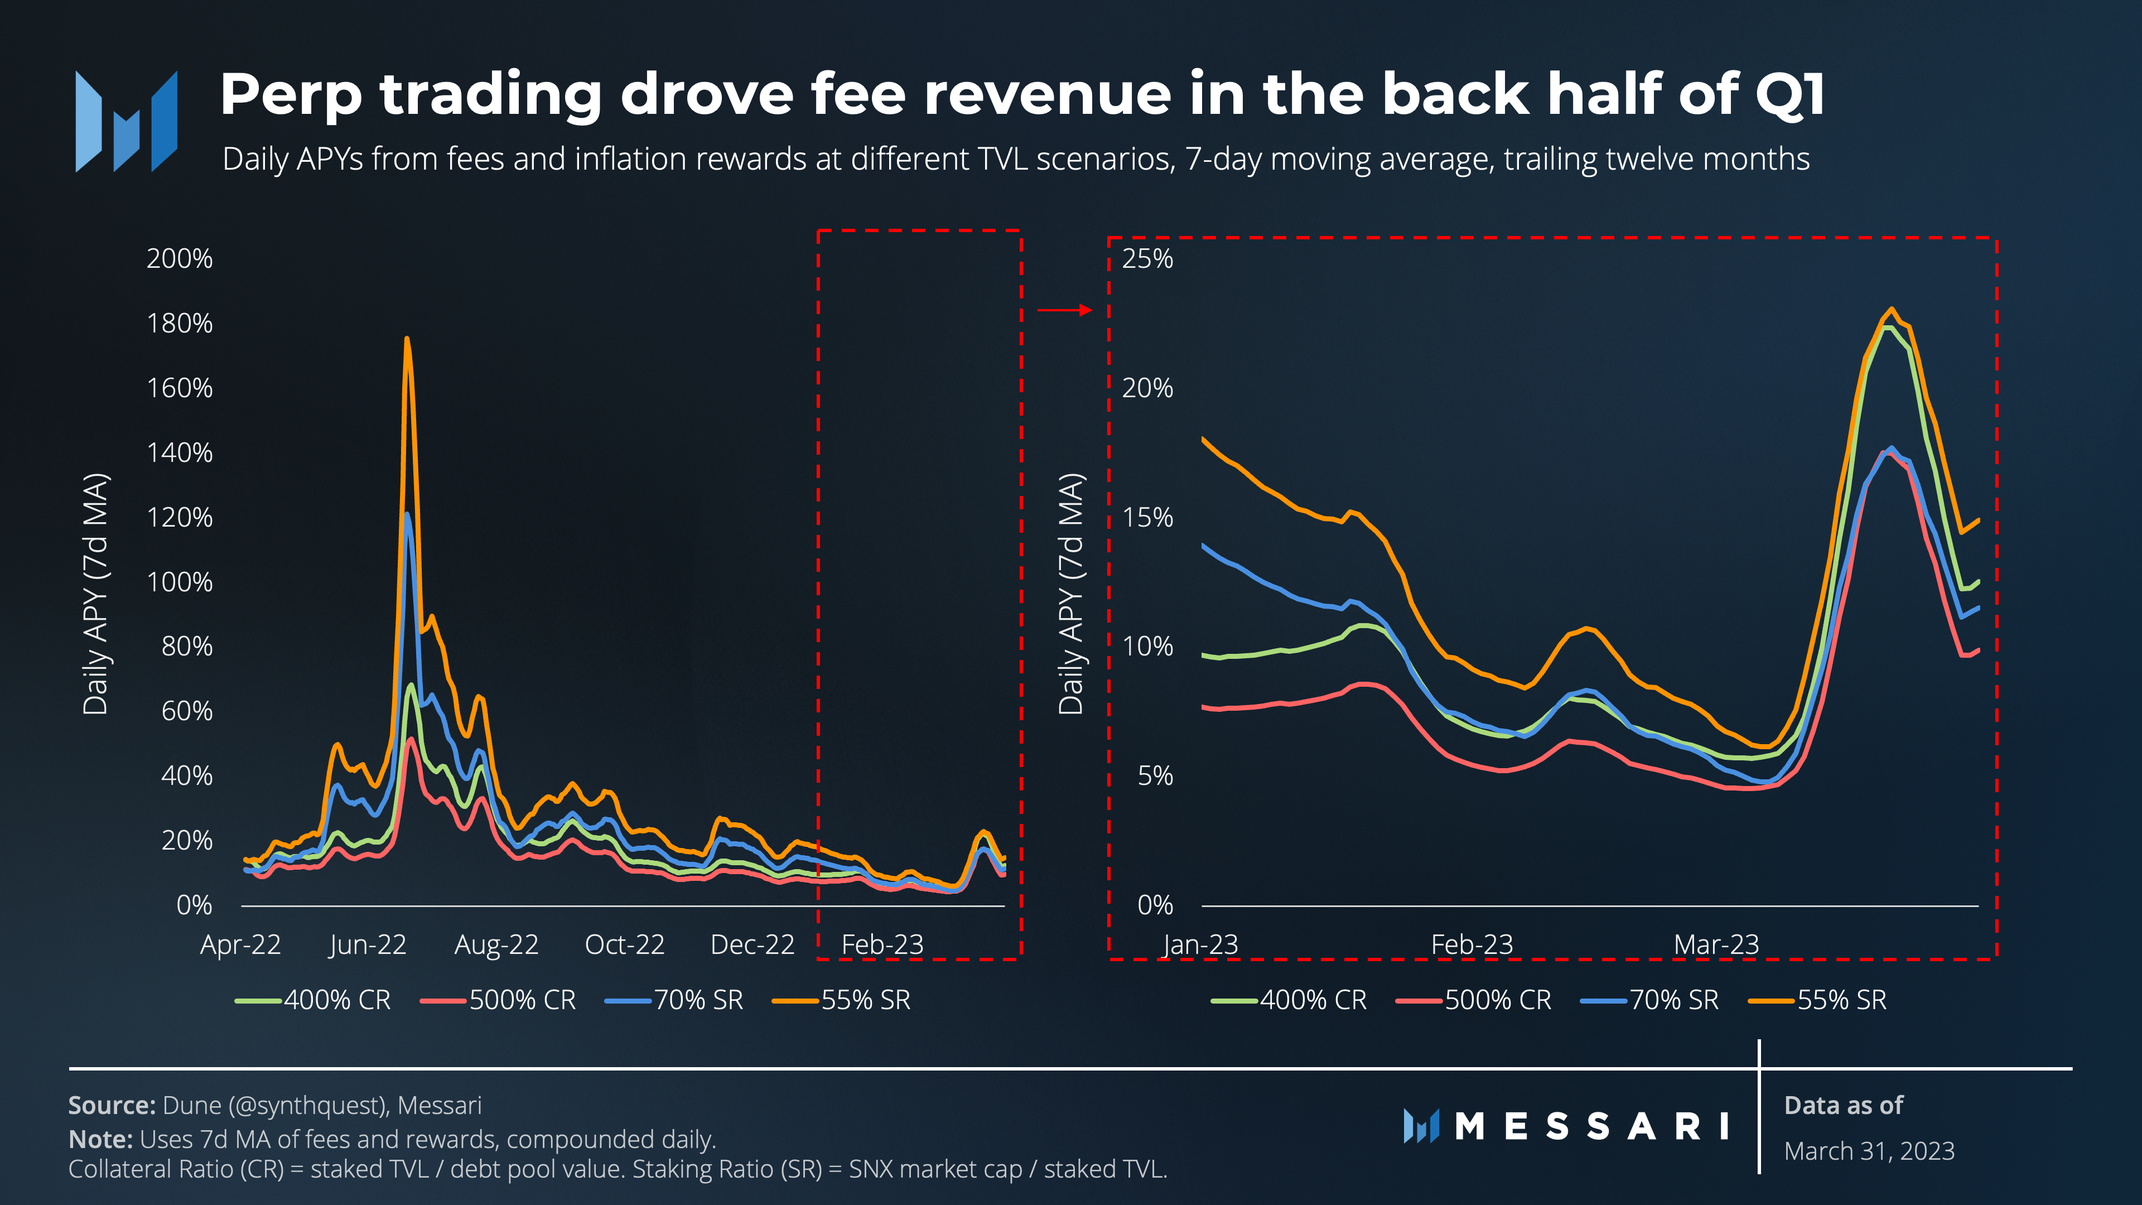
Another important change voted into effect in Q1’23 was the increase in the staking ratio from 400% to 500%. Although this change creates a healthier protocol with more backing, it also makes staking less efficient. To quantify its effect on efficiency, if the network collateral ratio was 400% in Q1’23, stakers would have earned a 10% annualized yield on their SNX. At a 500% collateral ratio, stakers would have earned less than 8%. While the change hasn’t driven out existing stakers, it may be slowing the growth of new stakers.
Synthetix V3 Update
Synthetix aims to provide on-chain liquidity collateralized by ERC-20 tokens, and it has recently released a major update called V3. The main goal of the update is to make Synthetix more modular, configurable, and composable, while keeping it as the permissionless backbone for the next generation of on-chain financial products.
In the DAO’s recent blog post, the primary achievements of V3 can be summarized as:
The Liquidity Layer for DeFi Derivatives: protocols can leverage the existing liquidity in the Synthetix protocol to create pools/vaults/markets, which also gives stakers more optionality on where to allocate their credit.
Power to Stakers with Multi-Collateral Staking: increased optionality for stakers to target debt exposure, hedging ability, collateral type, and credit type through combining Vaults into Pools connected to one or more Markets.
A Composable, Developer-Friendly System: to simplify and improve the developer experience by making the system cleaner and increasing the tools available to builders.
The Future is Cross-Chain: allows assets to be teleported cross-chain using the shared liquidity layer.
Overall, Synthetix's V3 update should make the protocol more flexible for stakers and protocols while also extending its reach across EVM deployments. The key features will likely be cross-chain functionality, multiple collateral types, developer tooling, and increased staker optionality. By enabling the creation of custom derivatives protocols, Synthetix hopes to be at the forefront of the next generation of on-chain financial products.
Ecosystem Update
As the developers of the DAO work on making the Synthetix protocol a permissionless liquidity layer, other contributors are focused on expanding the protocol’s reach through partnerships and new integrations.
As part of these efforts, SIP-294 increased the inflation spending of SNX rewards, from 6,000 SNX to 10,000 SNX weekly, to promote synth liquidity on Curve. Synthetix had four SCCPs in Q1 related to parameters and permissions for their partner 1inch to access atomic liquidity using Synthetix, but a common hurdle for the use case is synth liquidity. Thus, SIP-294 is intended to incentivize more liquidity on Curve to hopefully increase volumes of atomic swaps using 1inch and Curve.
The early success of Synthetix Perps has also driven a lot of ecosystem activity. Proposals were sent out for the governance of Lyra, an options protocol using Synthetix liquidity for delta hedging, to implement Synthetix Perps and similarly to Kwenta. Polynomial, formerly an options vault, launched a perps trading front end using Synthetix Perps in Q1. Mux, Nested, Unidex, and Conduit.lol are new Synthetix partners working on integrating Synthetix liquidity to their protocol solutions. In February, Synthetix passed SIP 2002 to incentivize and support partners who help generate fees for SNX stakers.
Closing Summary
Q1’23 was bullish for the market after a dogged 2022, and the timing of Synthetix Perps V2 added to the excitement. By the middle of Q1, 22 perps markets were available, and OI limits were gradually lifted. March saw Synthetix Perps dominate the usage of Synthetix, bringing consistently strong fee generation and large daily volumes to the product. The reduction in inflation has lowered rewards for stakers, but it will likely increase the sustainability of the protocol. SIP-255 changed the fee distribution for stakers to burn sUSD instead of distribute it, likely leading to a more resilient protocol. Lastly, V3 was finally launched, though its features will be released gradually as Synthetix strives to be the permissionless liquidity layer for on-chain financial derivatives.
This report was commissioned by Synthetix DAO. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Before joining Messari as a Senior Research Analyst, John worked in Equity Derivatives on the buy-side and sell-side for over five years. He studied macroeconomics and markets for almost a decade. Now, John spends time thinking about token design, DeFi protocols, and governance.
Before joining Messari as a Senior Research Analyst, John worked in Equity Derivatives on the buy-side and sell-side for over five years. He studied macroeconomics and markets for almost a decade. Now, John spends time thinking about token design, DeFi protocols, and governance.