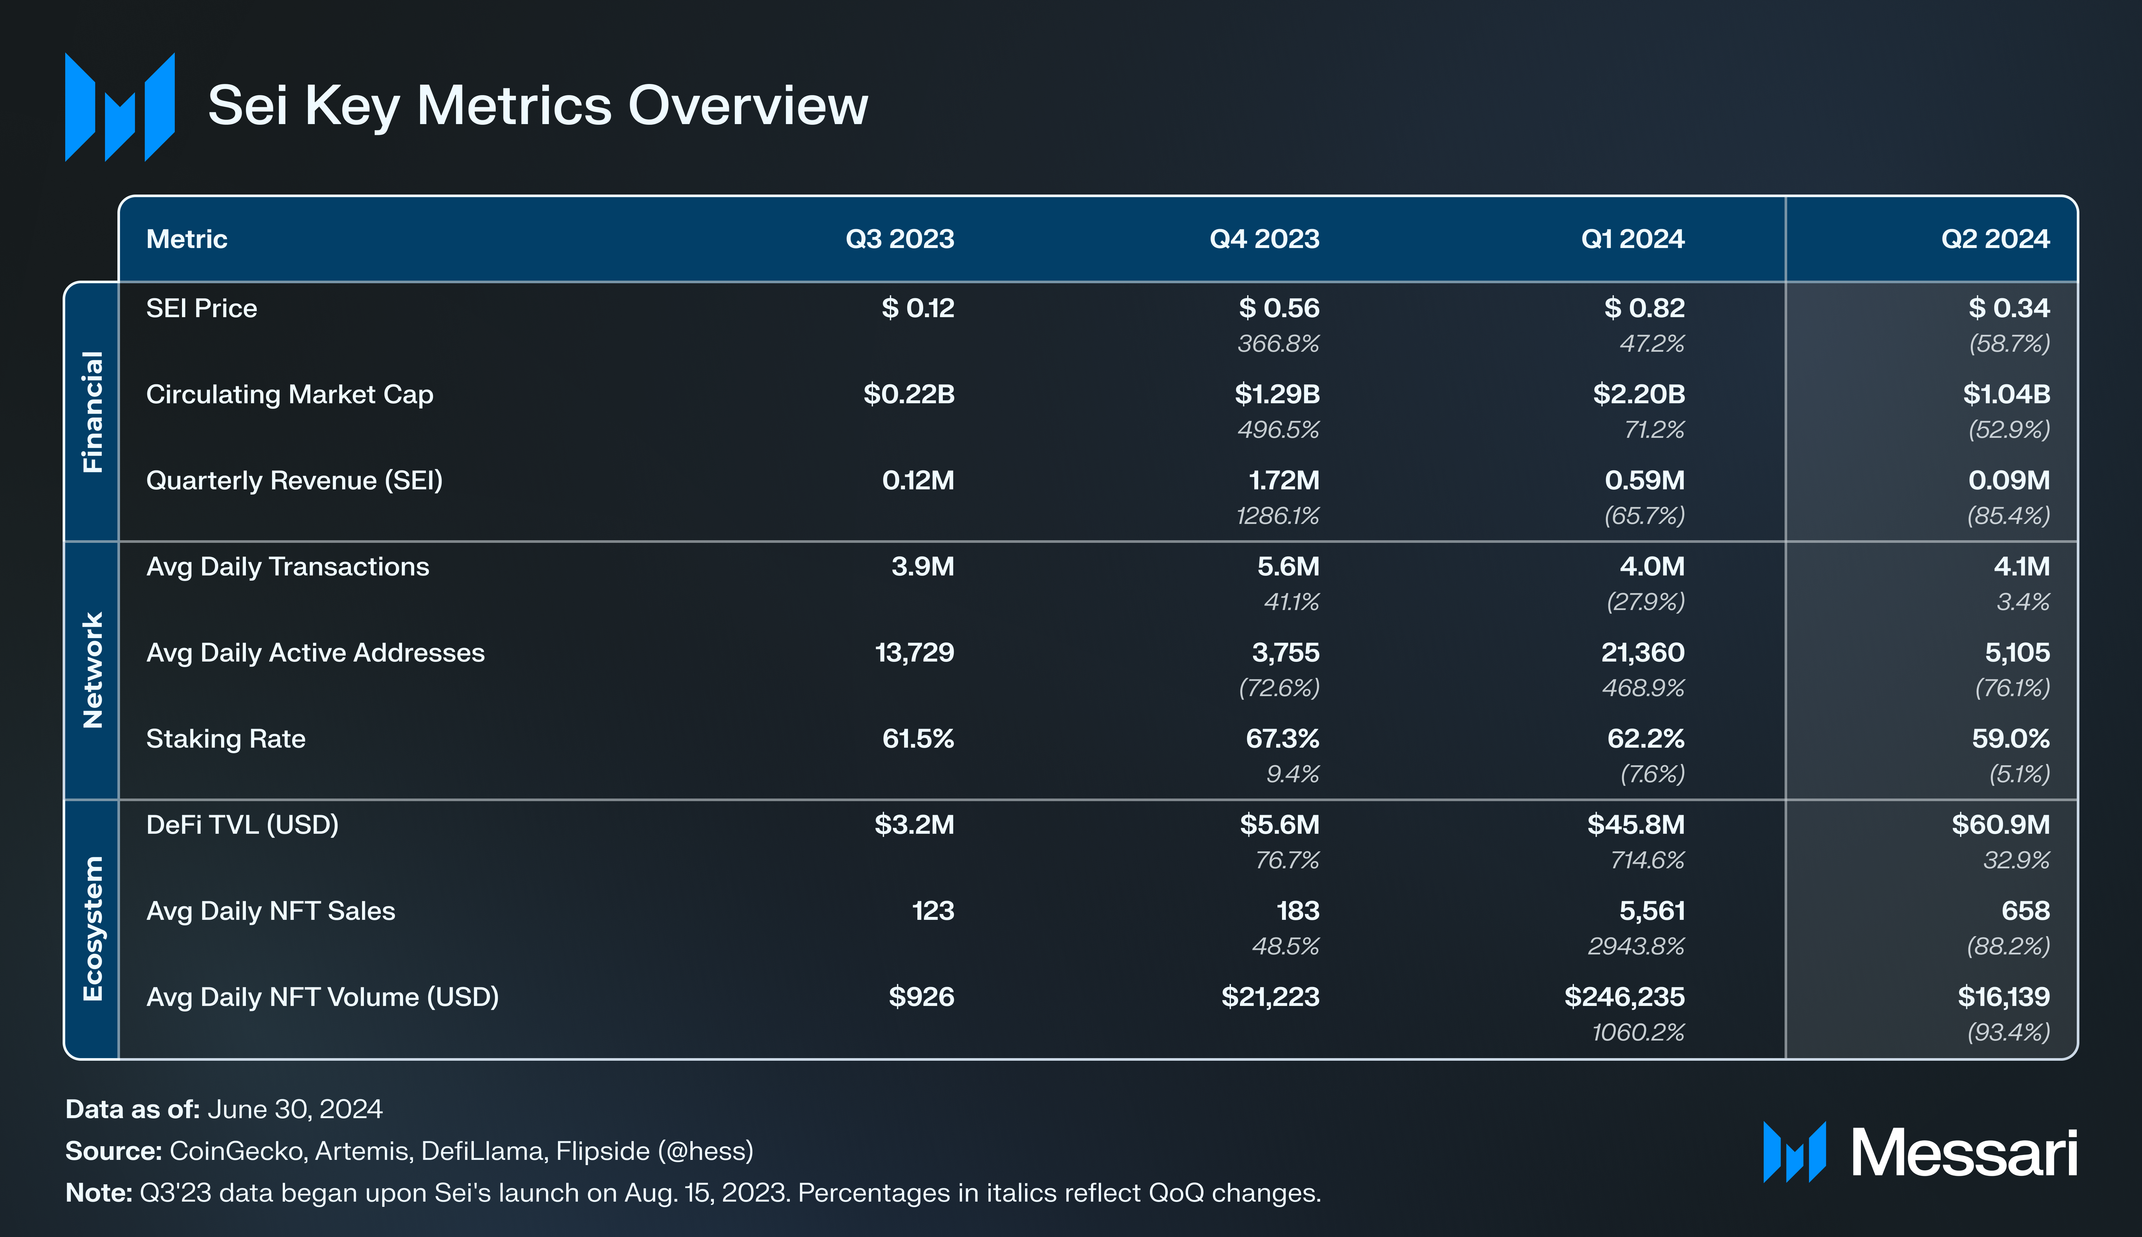
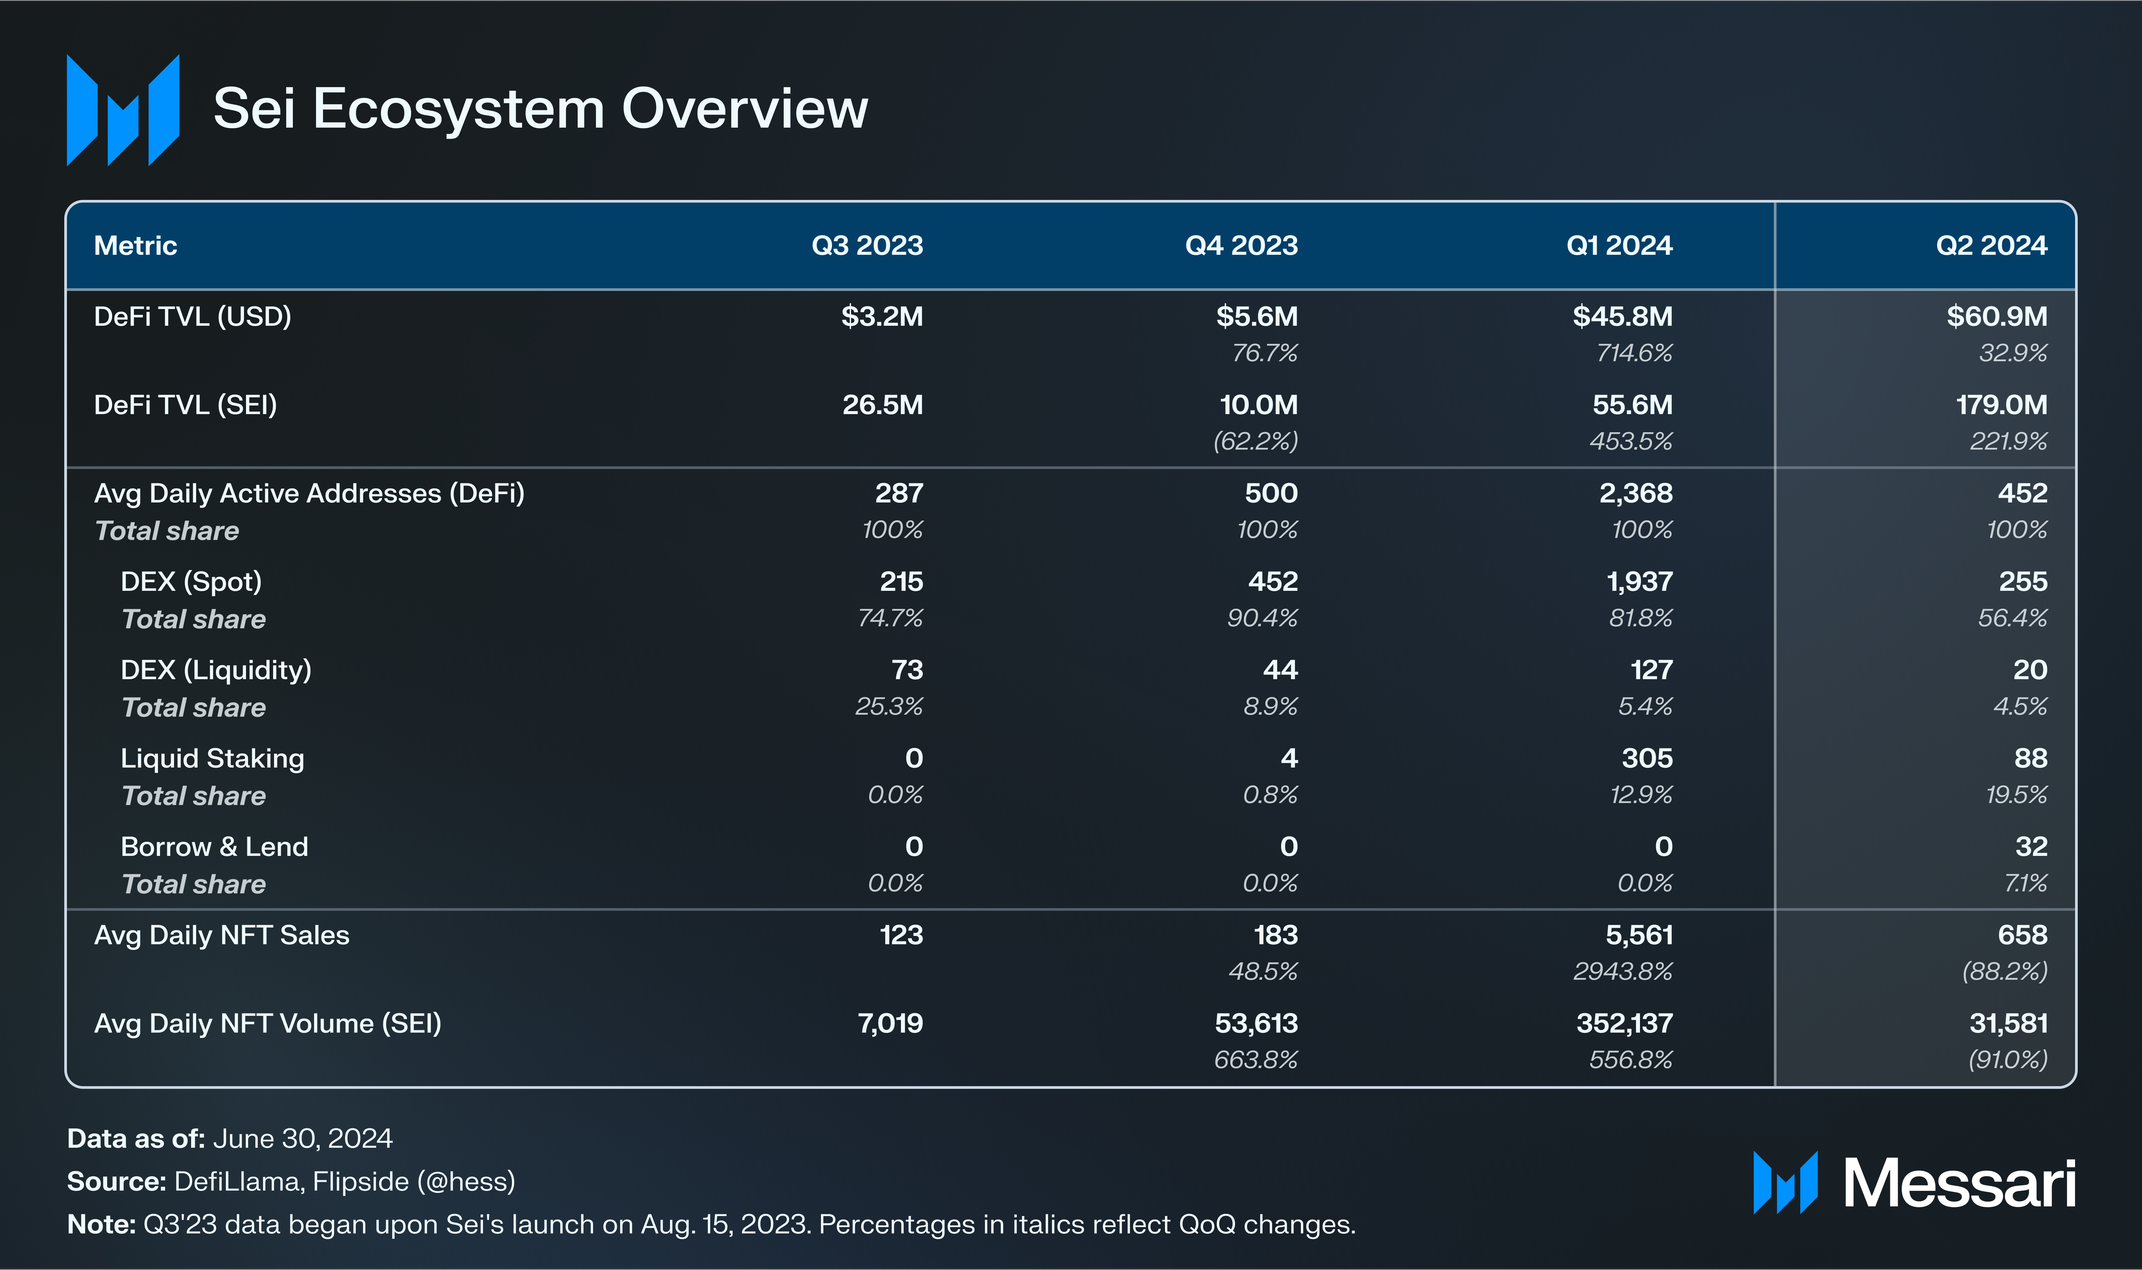
TVL (USD) increased 32.9% QoQ to $60.9 million. TVL on Yei Finance, Sei’s first borrowing and lending protocol, grew to $14.8 million.
The Sei V2 upgrade went live on May 27, 2024, introducing EVM compatibility and a host of new EVM-compatible protocols.
New DEXs like DragonSwap emerged, leading to drastic changes in the composition of TVL and DeFi activity on Sei. Astroport’s TVL fell by 92.7% QoQ, as its TVL dominance dropped from 98.9% to 5.5%.
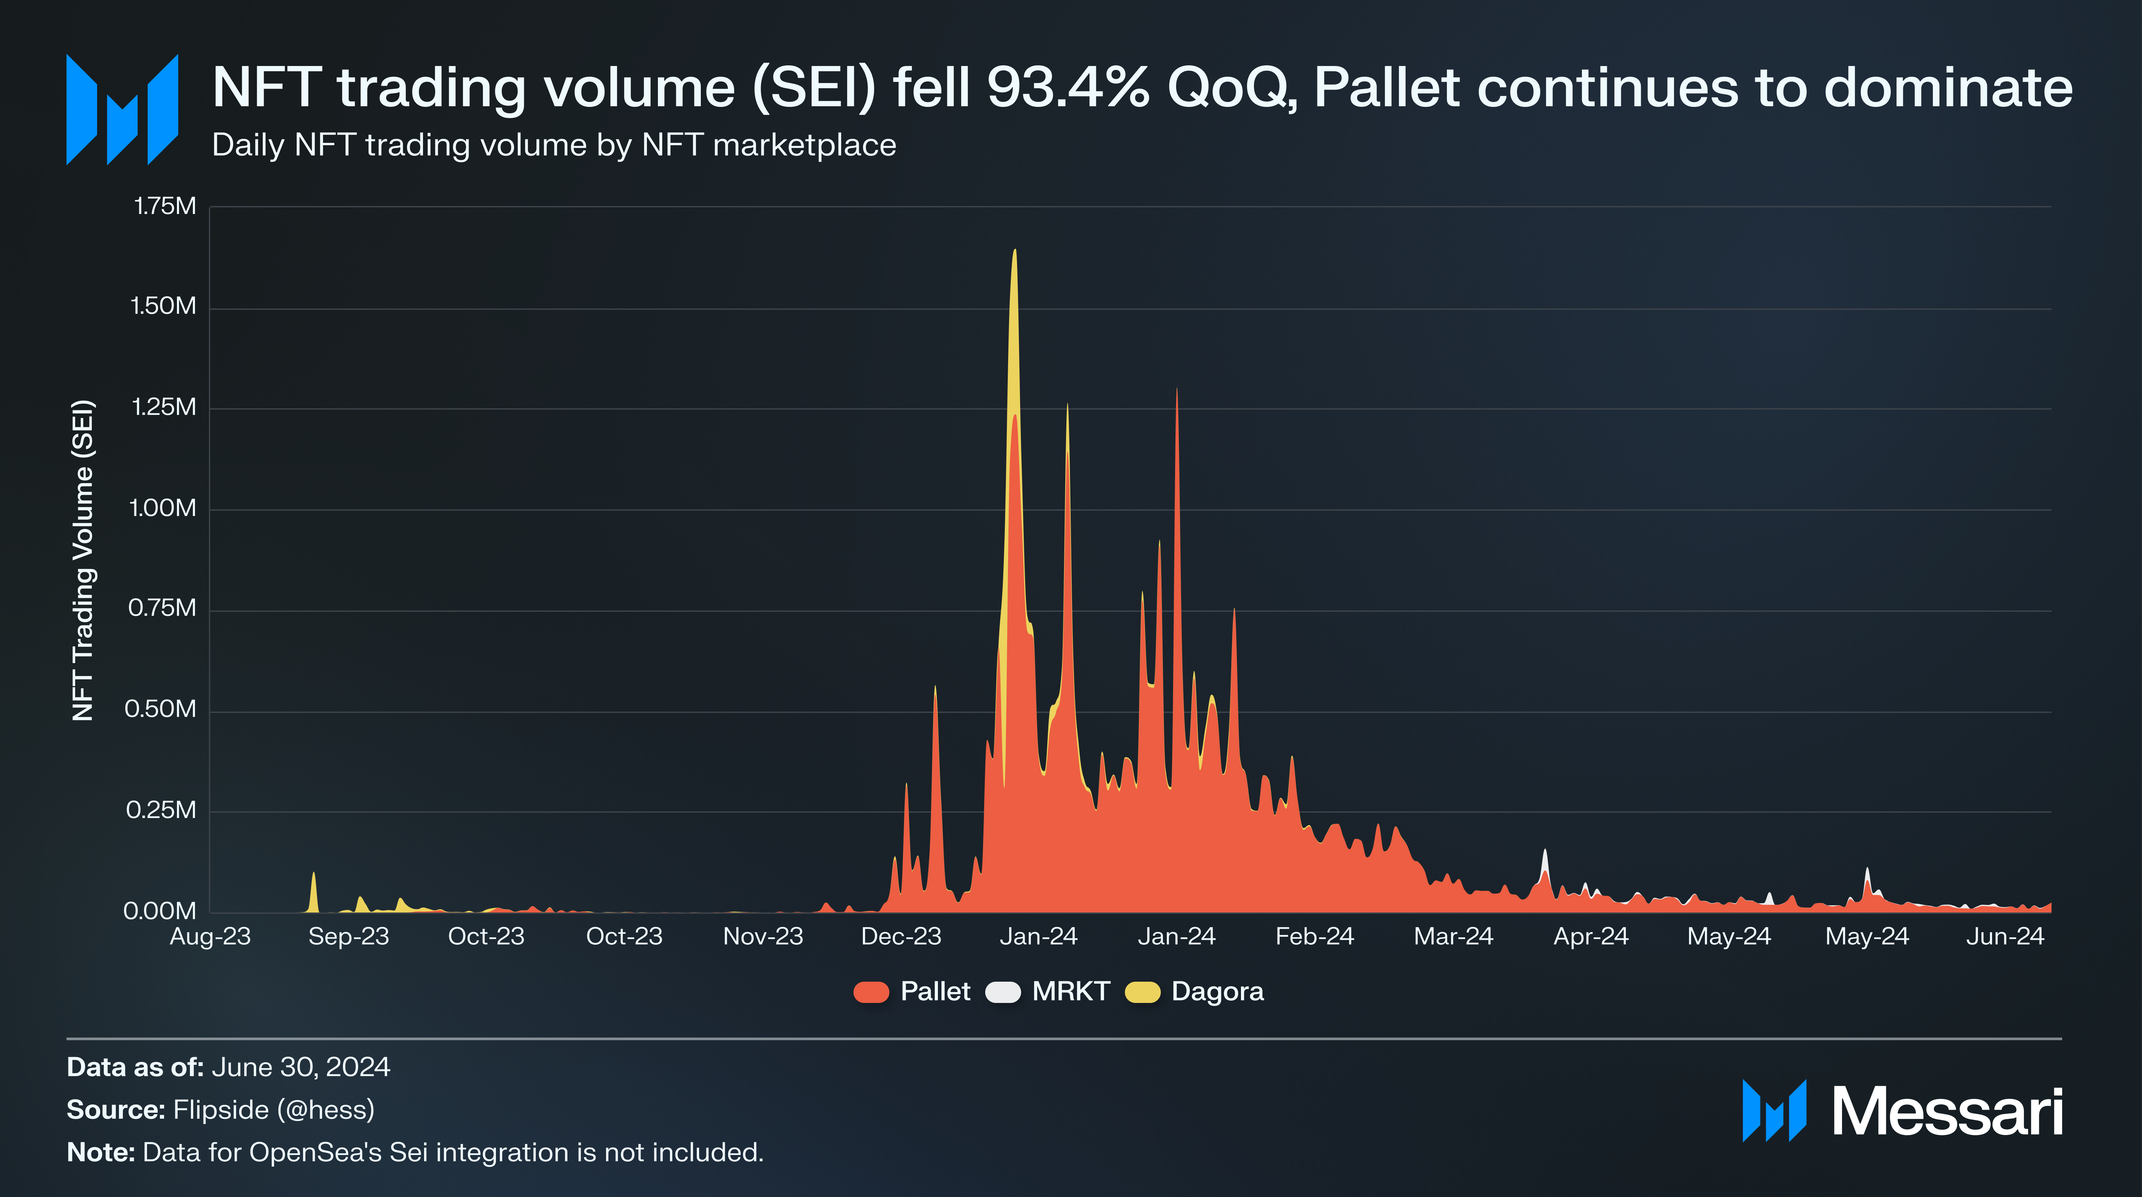
NFT sales, sellers, and buyers decreased 88.2%, 89.5%, and 85.6% QoQ, respectively. Pallet continued to dominate, accounting for 99.8% of NFT trading volume in Q2.
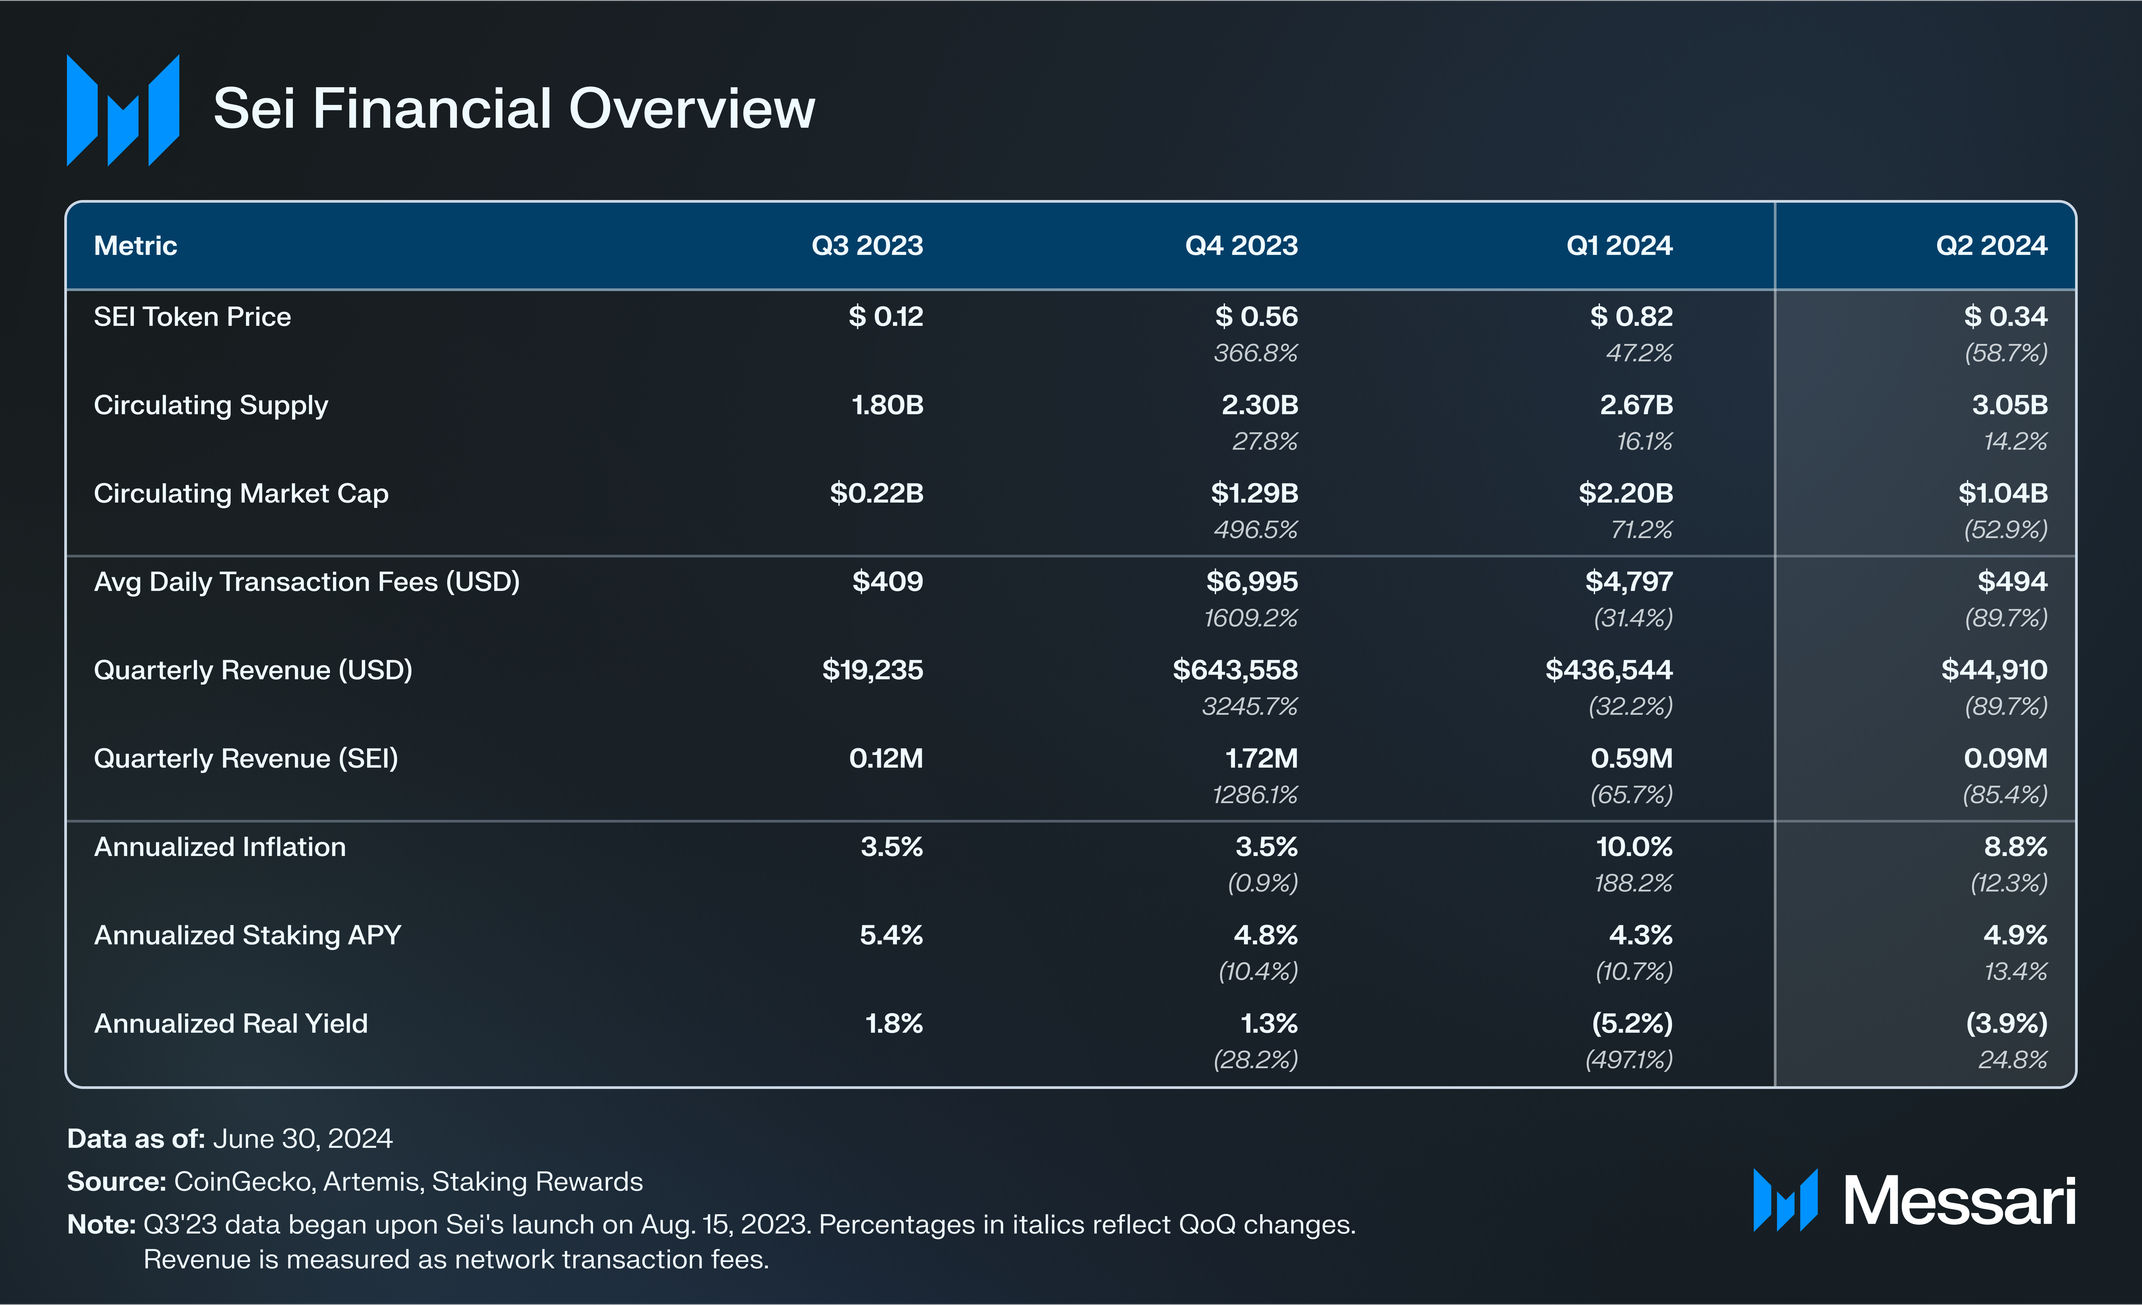
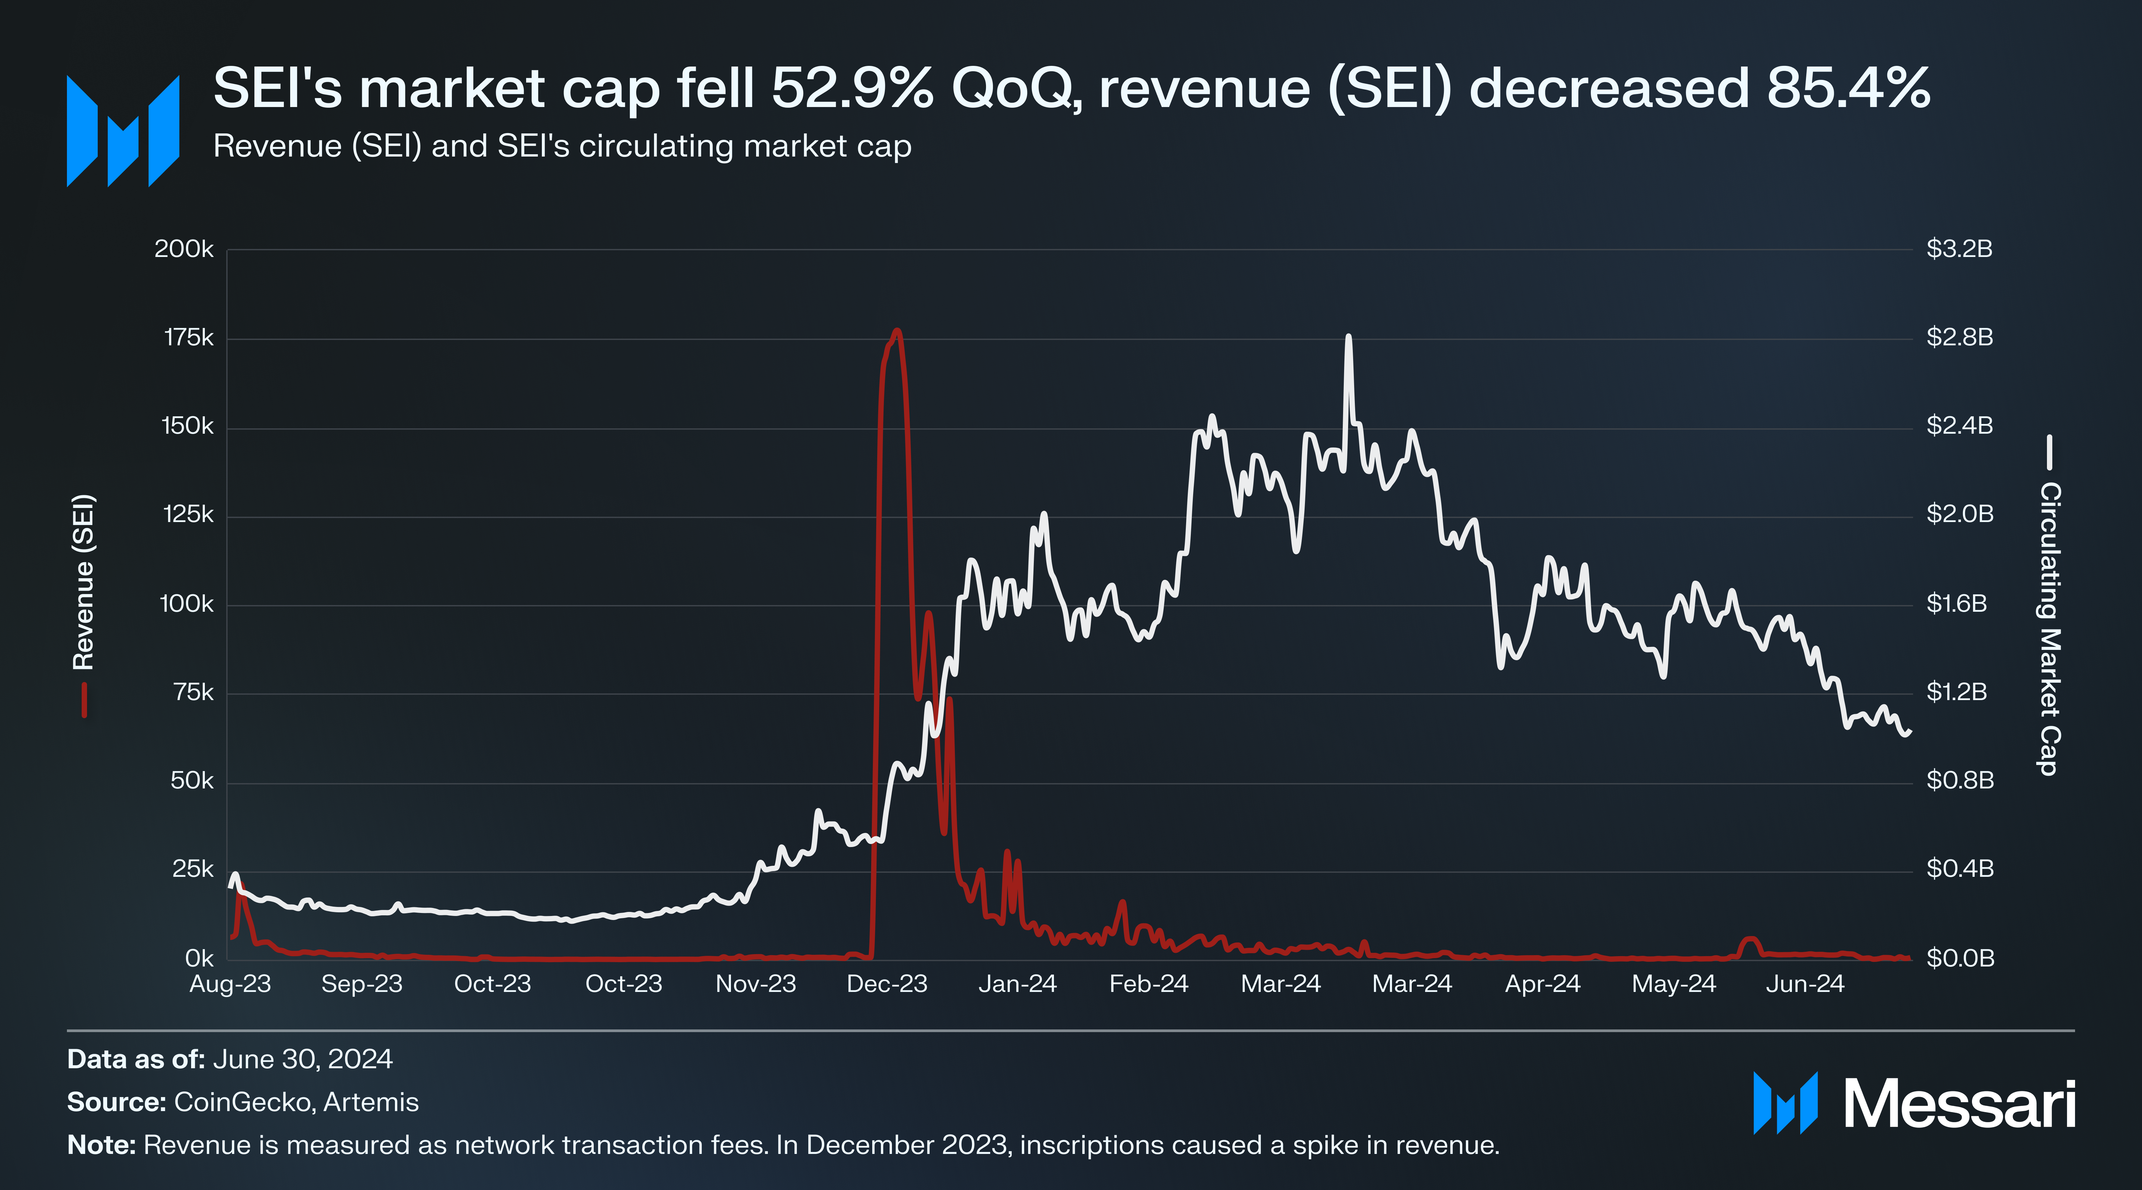
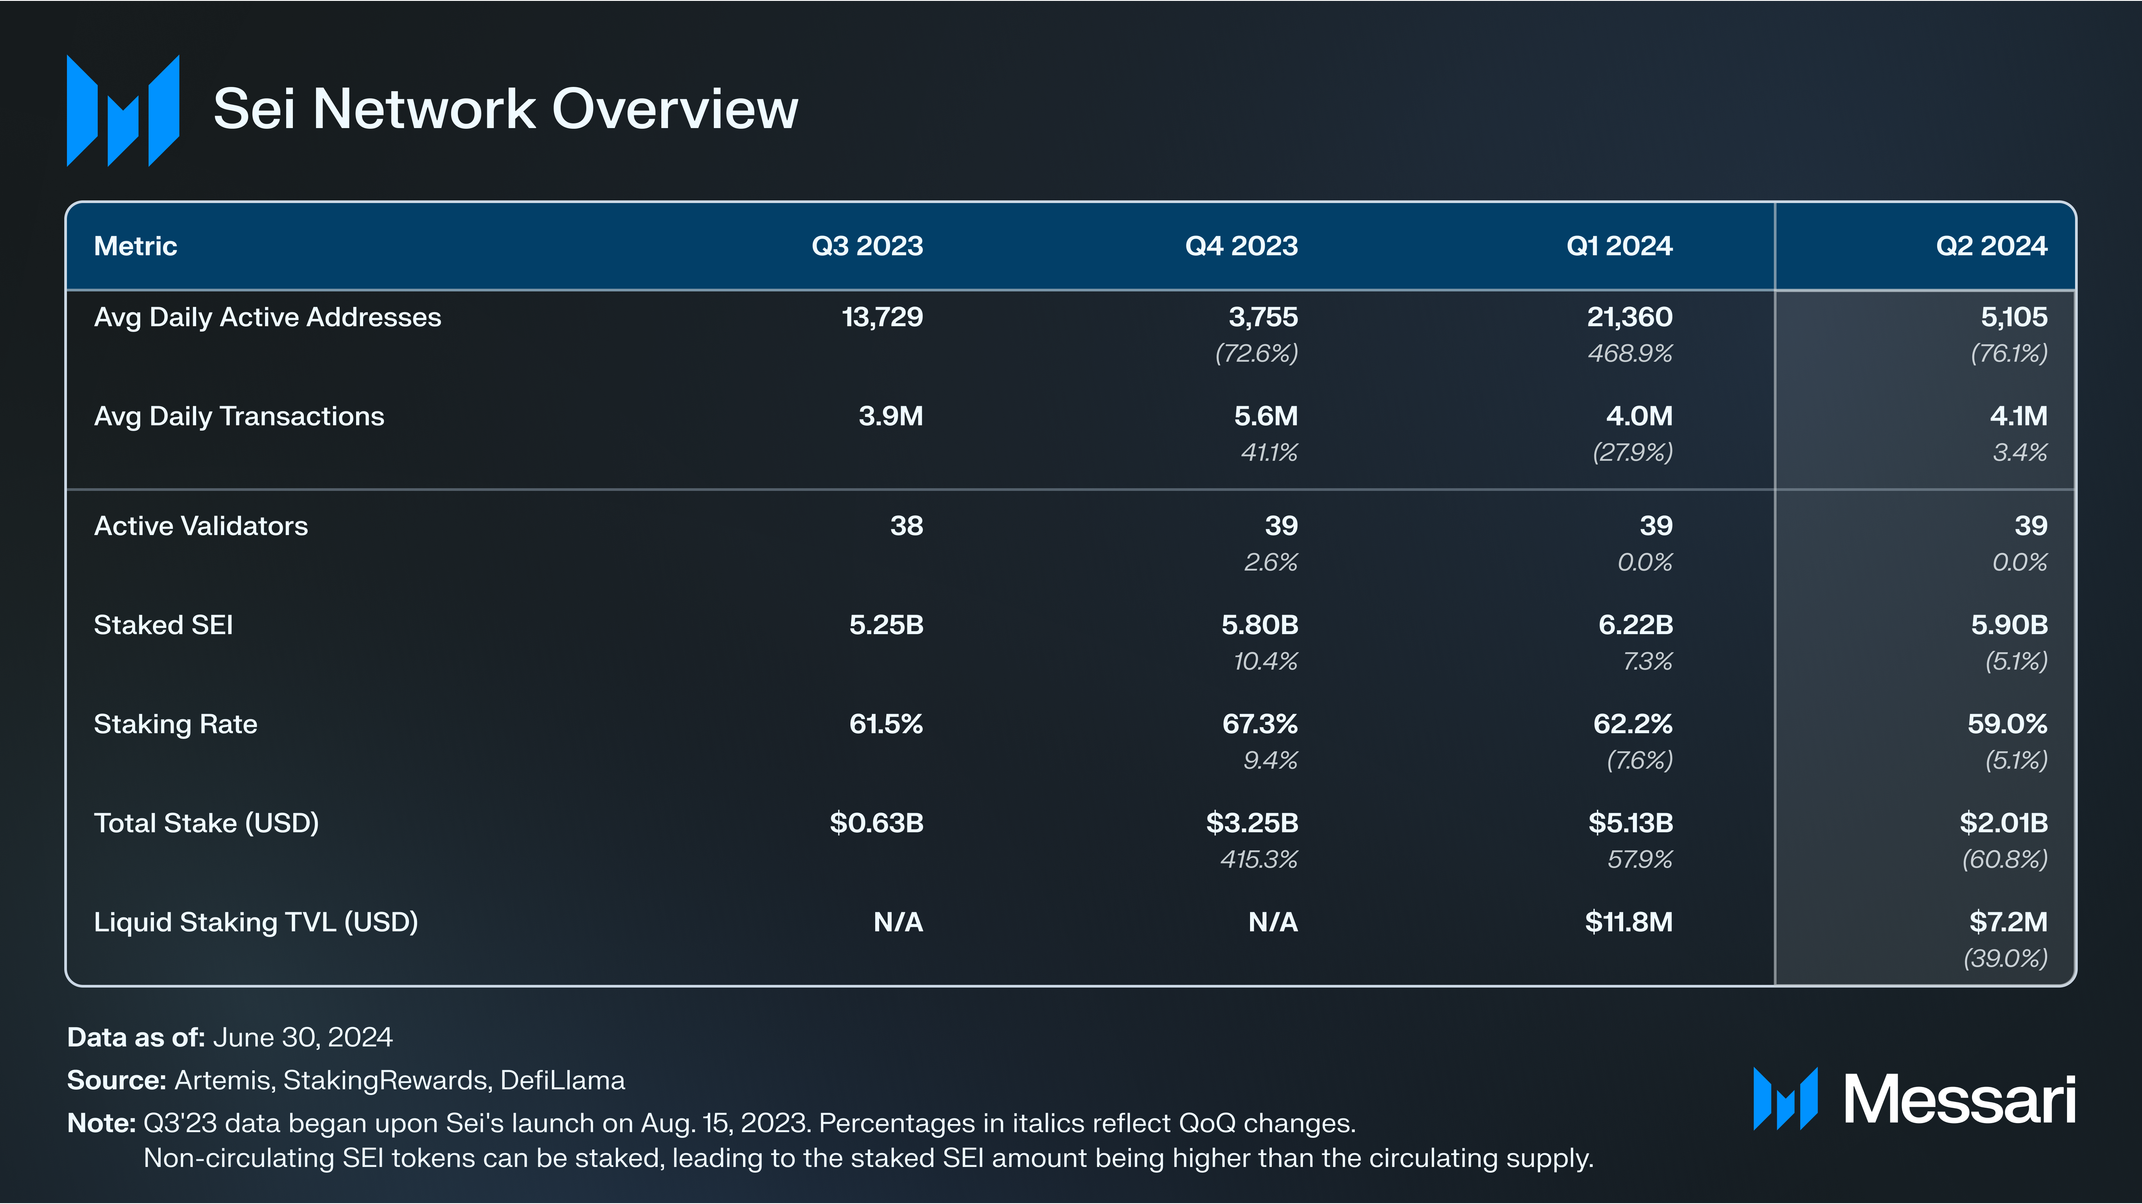
SEI’s price decreased 58.7% QoQ to $0.34, with its market cap rank falling from 59th to 69th. Meanwhile, total quarterly revenue denominated in SEI decreased 85.4% QoQ to 86,376.
The network's built-in features, such as Twin-Turbo Consensus and transaction parallelization, reduce latency and increase transaction throughput. The Sei V2 upgrade introduced three major upgrades to the network; (i) compatibility with Ethereum Virtual Machine (EVM) smart contracts written in Solidity, (ii) optimistic parallelization, and (iii) a re-architecture of the network’s storage interface with SeiDB. Sei’s upcoming open-source Parallel Stack will enable developers to launch modular Layer-2 networks that serve as EVM-compatible, parallelized execution layers built atop Sei. For a full primer on Sei, refer to our Initiation of Coverage report.
SEI’s price decreased 58.7% QoQ to $0.34. The token’s price had moments of volatility in Q2. However, these moments don’t appear to have been caused by Sei-specific catalysts. Rather, they aligned with the broader crypto market’s price action as SEI followed dips and gains in the price of majors such as Bitcoin.
Meanwhile, SEI’s circulating market cap decreased by 52.9% QoQ to $1.04 billion, as its circulating market cap rank fell from 59th to 69th. Sei’s quarterly revenue (SEI) decreased 85.4% QoQ to 86,376. Due to SEI’s price depreciation, quarterly revenue (USD) decreased by a larger 89.8% QoQ to $44,910.
Annualized inflation decreased 12.3% QoQ from 10% to 8.8%. Combined with a decrease in the amount of staked SEI, annualized staking APY increased 13.4% QoQ from 4.3% to 4.9%, resulting in an annualized real yield of -3.9% by the end of Q2.
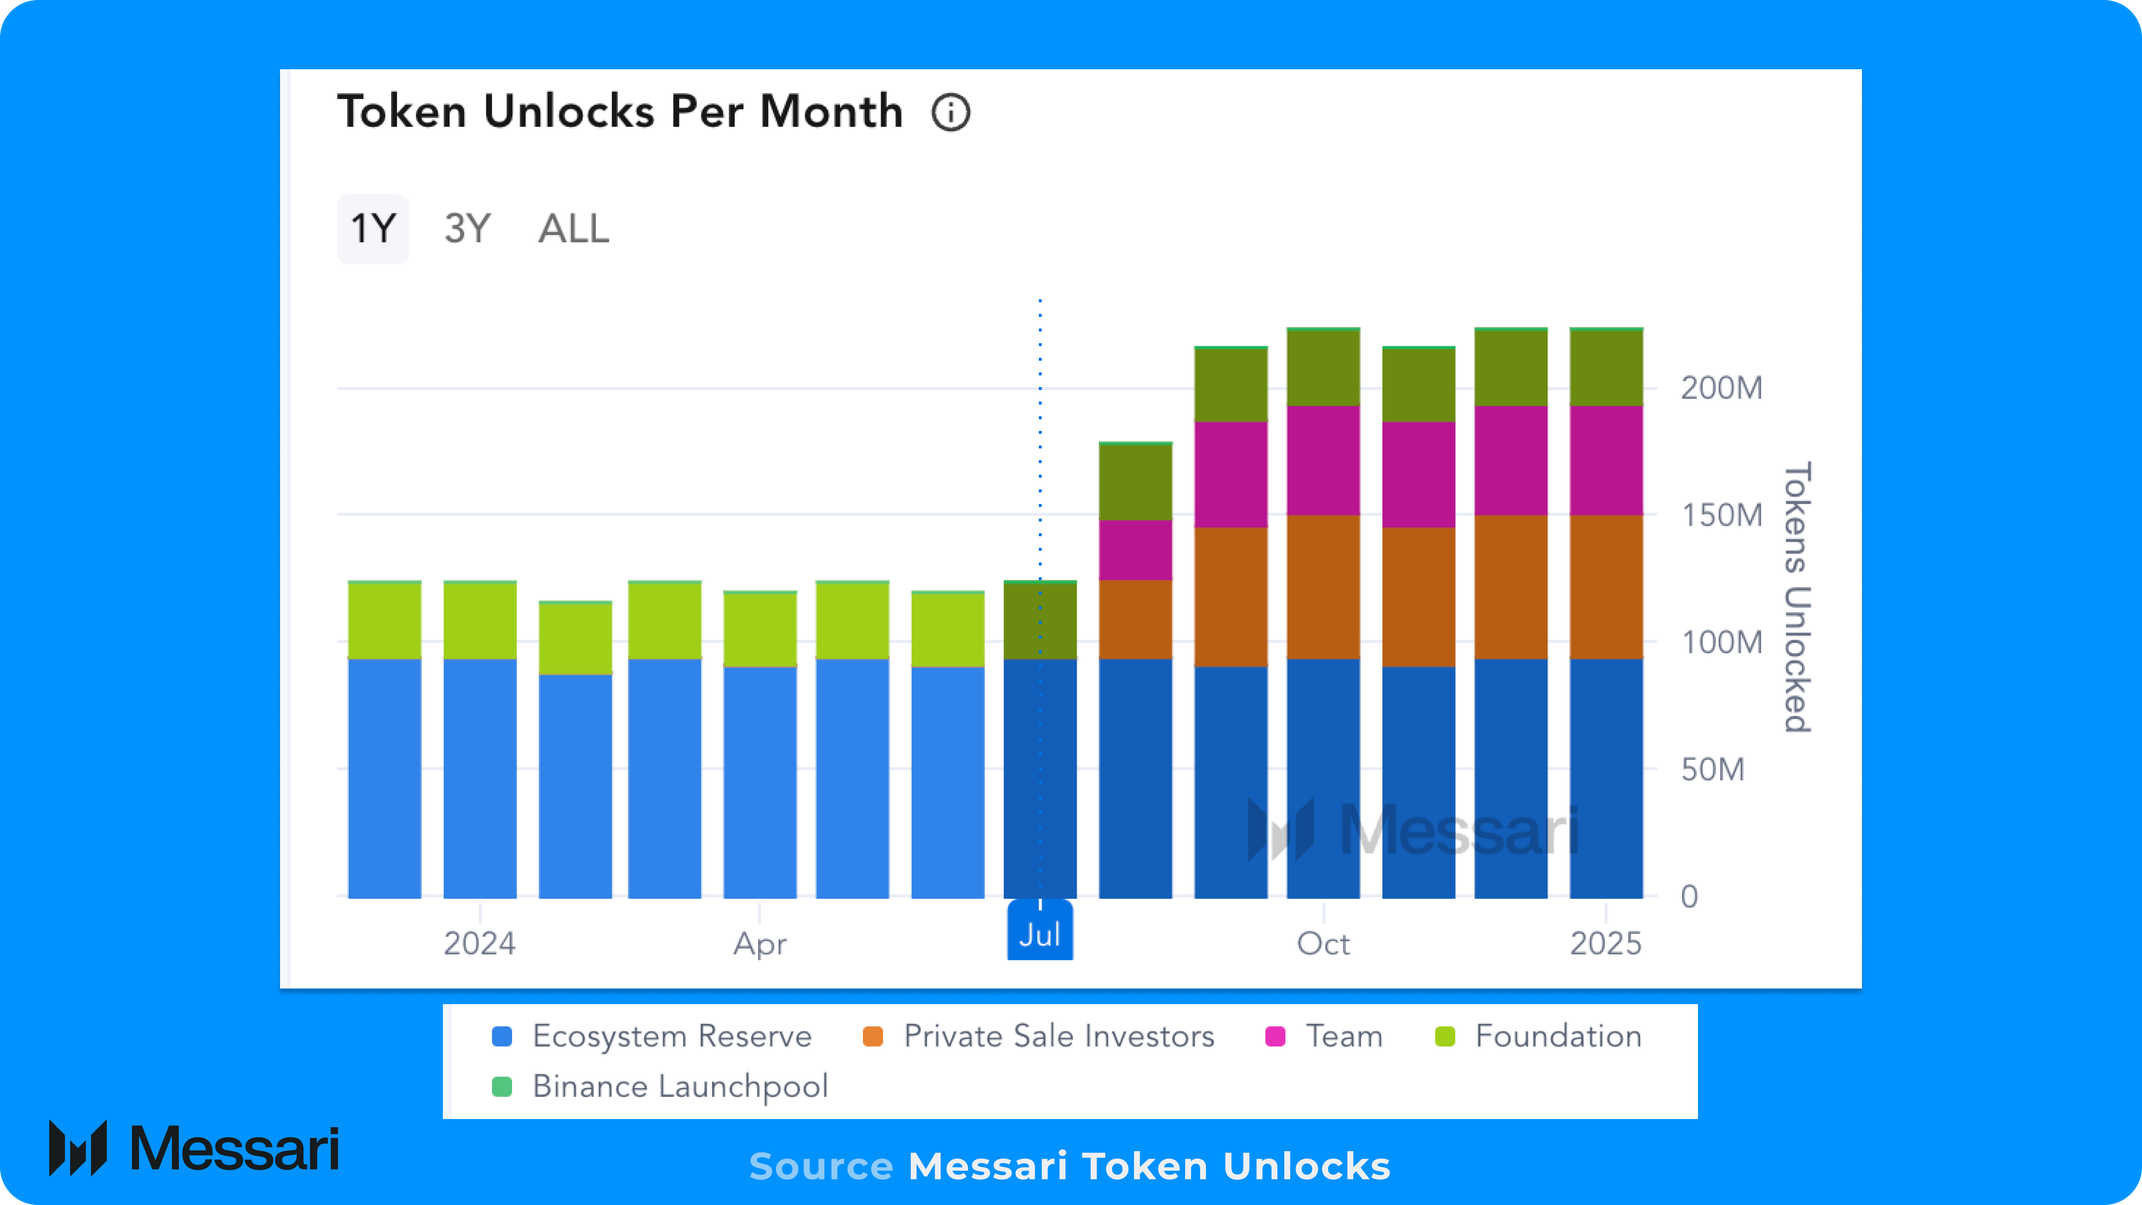
SEI Token Unlocks
SEI’s circulating supply increased 14.2% QoQ to 3.05 billion due to a mix of token unlocks and staking rewards. In Q2, 360.1 million locked SEI was unlocked at a daily rate of ~4 million SEI. This rate will increase starting in August 2024, when the investor and project team allocations begin vesting an additional ~3.2 million SEI per day. Ultimately, SEI tokens will continue to vest until August 15, 2032, with the 1.18 billion scheduled to vest by the end of 2024.
Sei Airdrop #2 was announced in May, rewarding a total of 34.4 million SEI to 44,445 addresses that staked SEI, liquid staked SEI, and/or held NFTs from top collections. Addresses earned between 200 and 6,000 SEI, depending on what activities they performed. The airdrop was distributed onchain on July 9, 2024.
Network Analysis
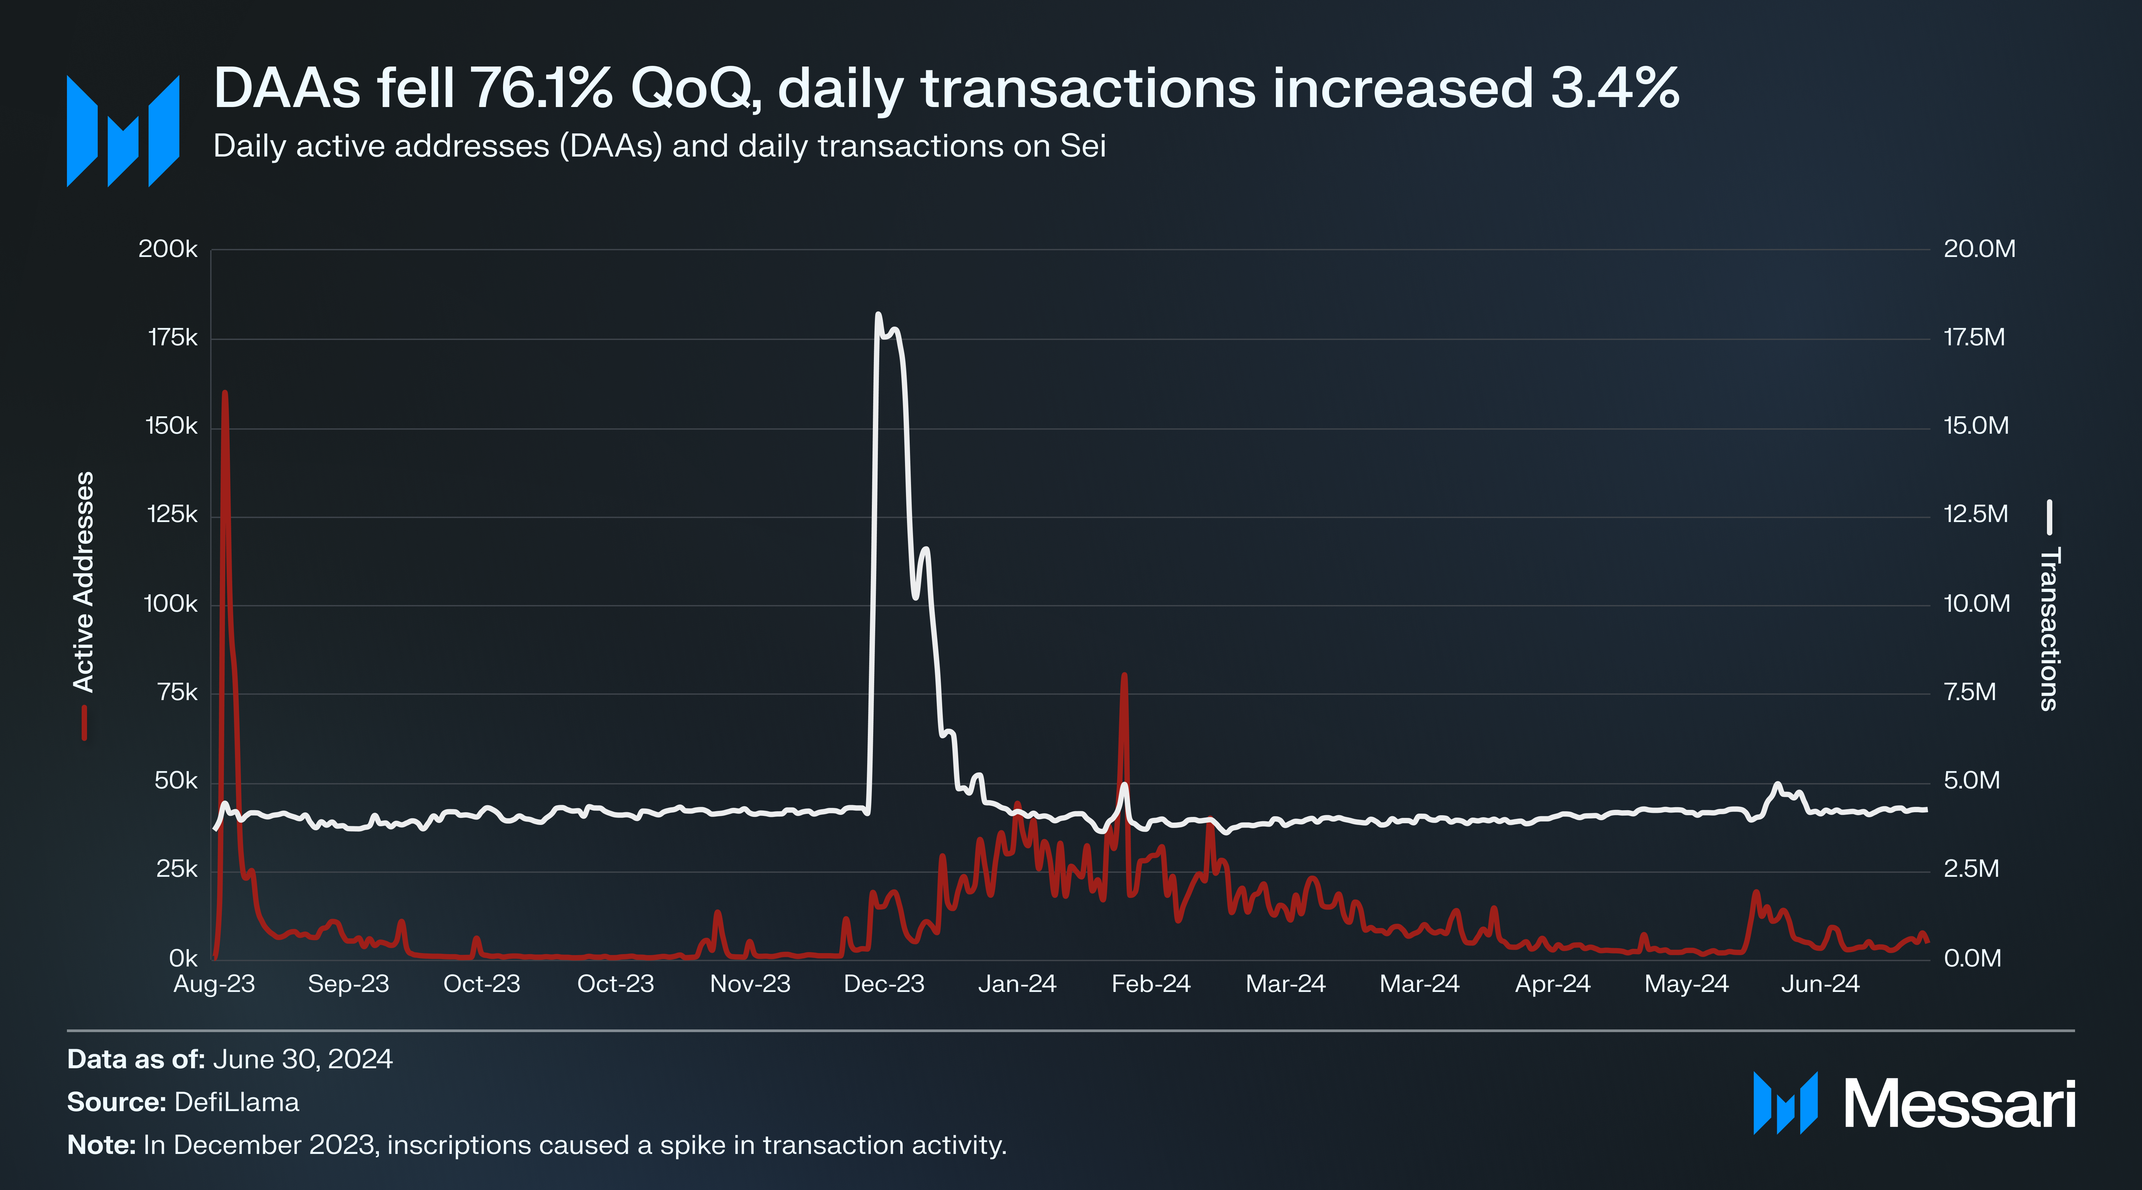
Average daily active addresses (DAAs) decreased 76.1% QoQ to 5,105, while daily transactions increased 3.4% QoQ to 4.1 million. The decline in average DAAs may have been a reversion to the mean for Sei’s mindshare and onchain activity after a well-received launch in H2’23 and a surge in activity in Q1’24.
Staking
Active validators remained unchanged in Q2 at 39. The total stake (SEI) decreased by 5.1% QoQ to 5.9 billion SEI. Combined with the aforementioned decrease in SEI’s price, the total stake (USD) decreased 60.8% QoQ to $2.01 billion. Notably, this metric includes unvested, locked SEI tokens that can be staked to earn liquid rewards.
Liquid Staking
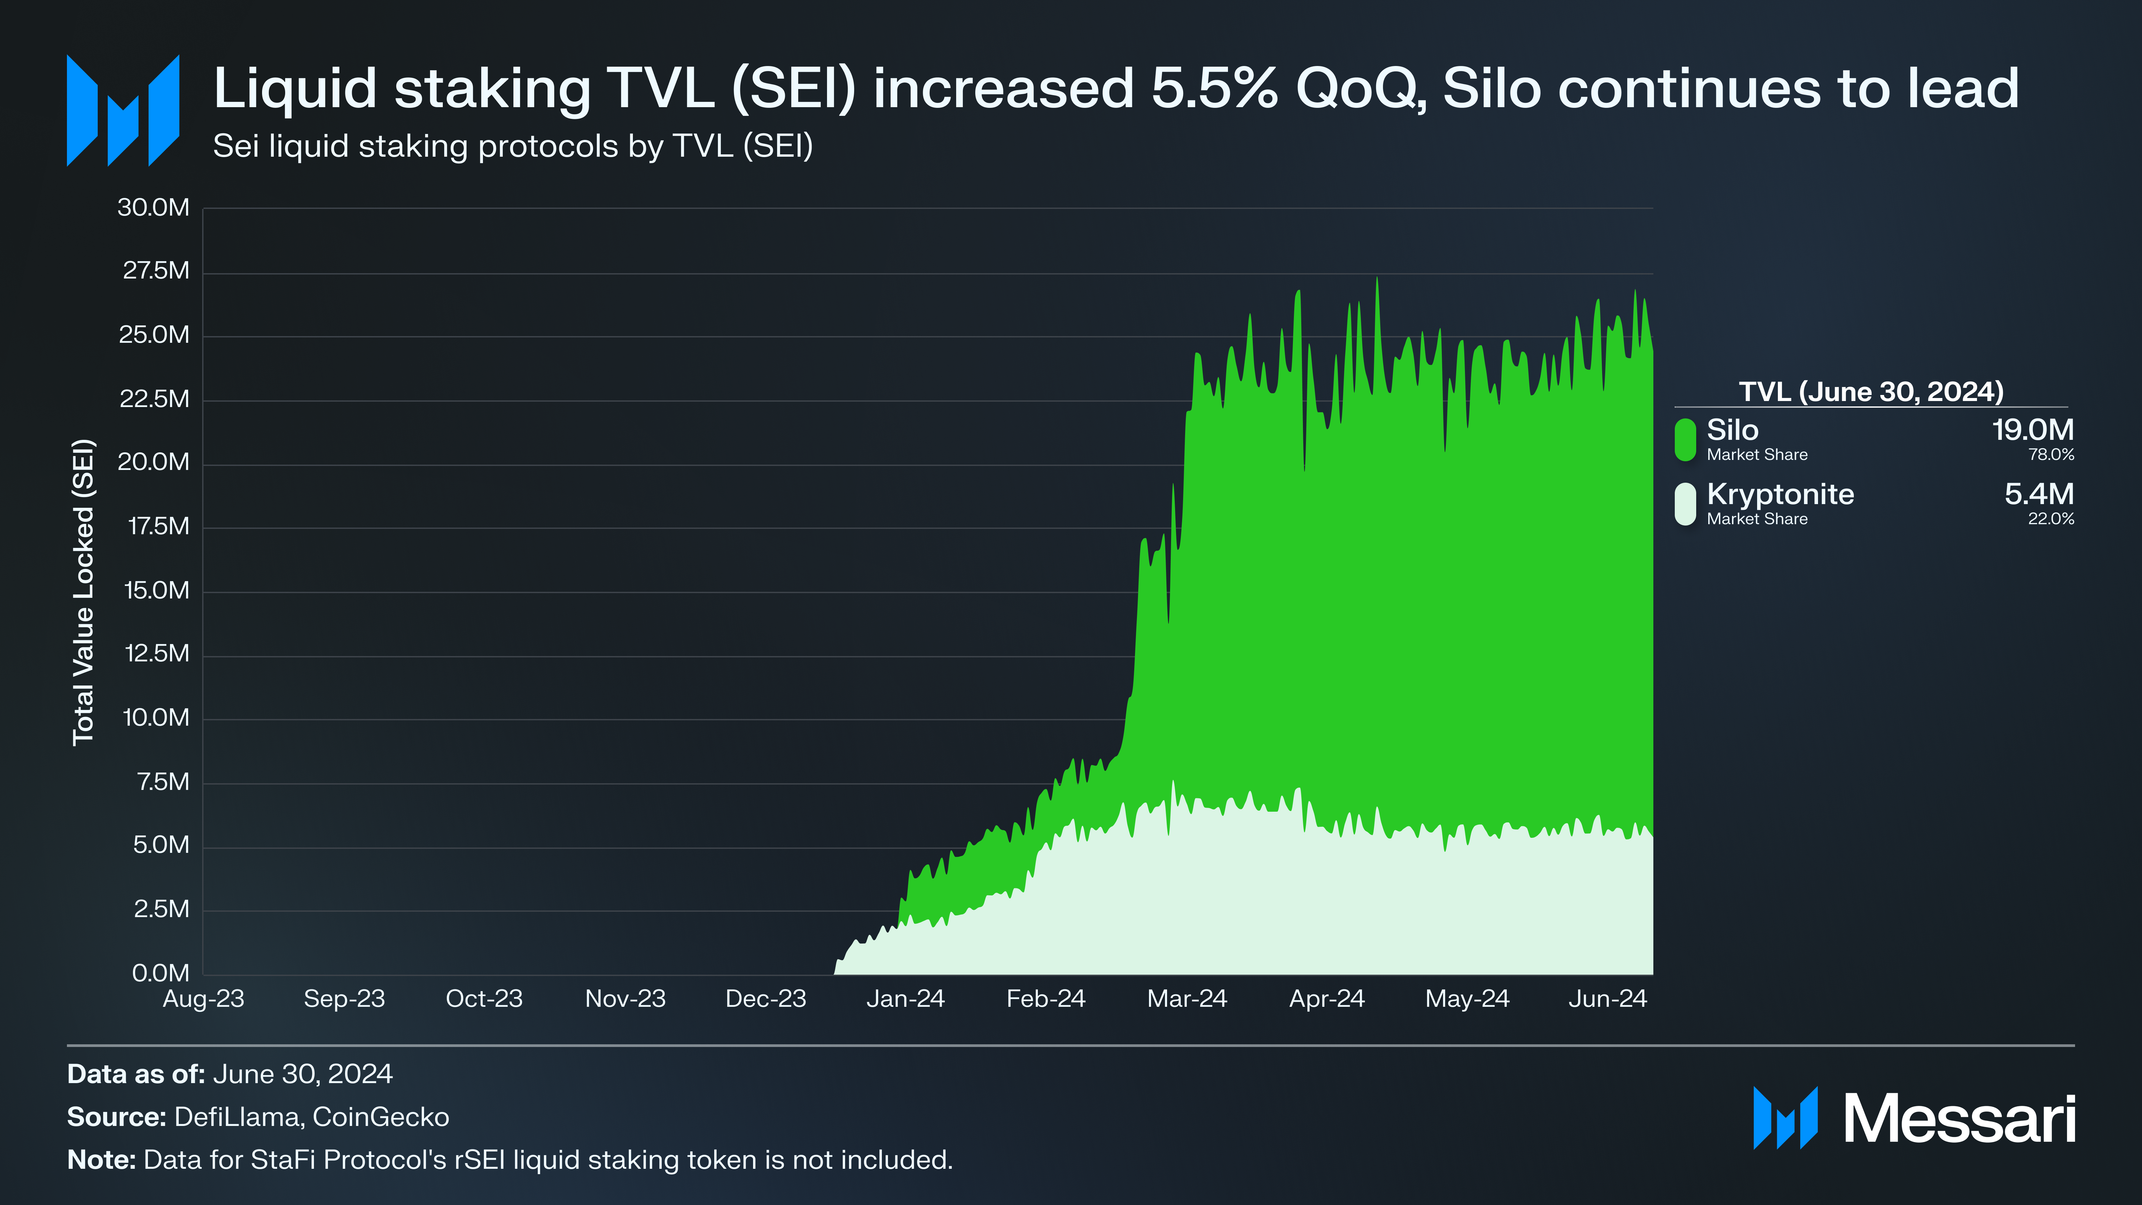
Liquid staking protocols Silo and Kryptonite launched around the beginning of 2024. These protocols allow users to stake SEI in return for their liquid staking tokens (Silo’s iSEI and Kryptonite’s stSEI). Both tokens can be unstaked to receive the underlying SEI after a 21-day unbonding period.
As of June 30, 2024, 24.4 million SEI had been liquid staked, a 5.1% QoQ increase from the 23.2 million SEI that had been liquid staked by the end of Q1’24. Compared to the total staked SEI, Sei ended Q2 with a liquid staking rate of 0.4%. Liquid staking TVL (SEI) on Silo increased by 13.6% QoQ, while Kryptonite decreased by 17%. Thus, Silo outperformed Kryptonite as its market share increased 8.1% QoQ from 72.1% to 78%, while Kryptonite’s market share fell 21% QoQ from 27.9% to 22%.
Notably, a new liquid staking protocol launched at the end of May, as StaFi Protocol entered the fold with its rSEI token. rSEI is an ERC-20 token compatible with Sei’s new EVM-compatible protocols. So far, rSEI adoption has been slow. The token is held by only eight addresses, with the top tokenholder holding 99.1% of the rSEI’s total supply of 145,171. Kryptonite and Silo continue to dominate with a combined share of ~99% of Sei’s liquid staking market.
Note: Data for StaFi Protocol’s rSEI token was not included in Sei’s total liquid staking TVL, which may cause it to be slightly understated in this report.
Sei V2 introduced compatibility for EVM smart contracts written in Solidity, including the ERC-20 and ERC-721 token standards. EVM smart contracts are backward compatible, meaning that smart contracts on Ethereum and its Layer-2 networks can be redeployed on Sei.
In effect, Sei simultaneously supports two execution environments. Each user’s EVM and Sei addresses are linked and share the same underlying account. EVM smart contracts and tokens are interoperable with existing Sei smart contracts and vice versa. The interoperability is enabled through the use of Precompiled Contracts and Pointer Contracts, many of which were approved by governance after the launch of Sei V2.
These contracts make tokens accessible in both environments without needing a wrapped version of the token. In essence, Pointer Contracts act as “translators” between the two execution environments. They allow users to signal what messages users want to send between either environment.
Optimistic Parallelization
Sei V2 introduced a change from pessimistic parallelization to optimistic parallelization. Under pessimistic parallelization, developers had to define the state (account balances, smart contracts, etc.) used by smart contracts to take advantage of Sei’s parallel transaction execution capabilities.
Under the new optimistic parallelization model, all transactions are assumed to be eligible for parallel processing. If dependencies between transactions exist (transactions interacting with the same part of Sei’s state), they are re-processed sequentially. This change improves the developer experience by not requiring dependency mappings to be defined. However, the approach could introduce additional latency to the network due to the need to re-execute transactions when dependencies exist.
Improved state read/write performance, leading to increased state sync times and decreased commit times for faster time to finality.
Decreased state bloat with less metadata needing to be stored.
Reduced hardware requirements for node operators.
Parallel Stack
In the future, Sei plans to launch its open-source Parallel Stack, which will enable developers to launch modular Layer-2 networks that serve as EVM-compatible, parallelized execution layers built atop Sei. These Layer-2s could use Sei’s validator set for sequencing services and customize their settlement and data availability (DA) layers.
Ecosystem Analysis
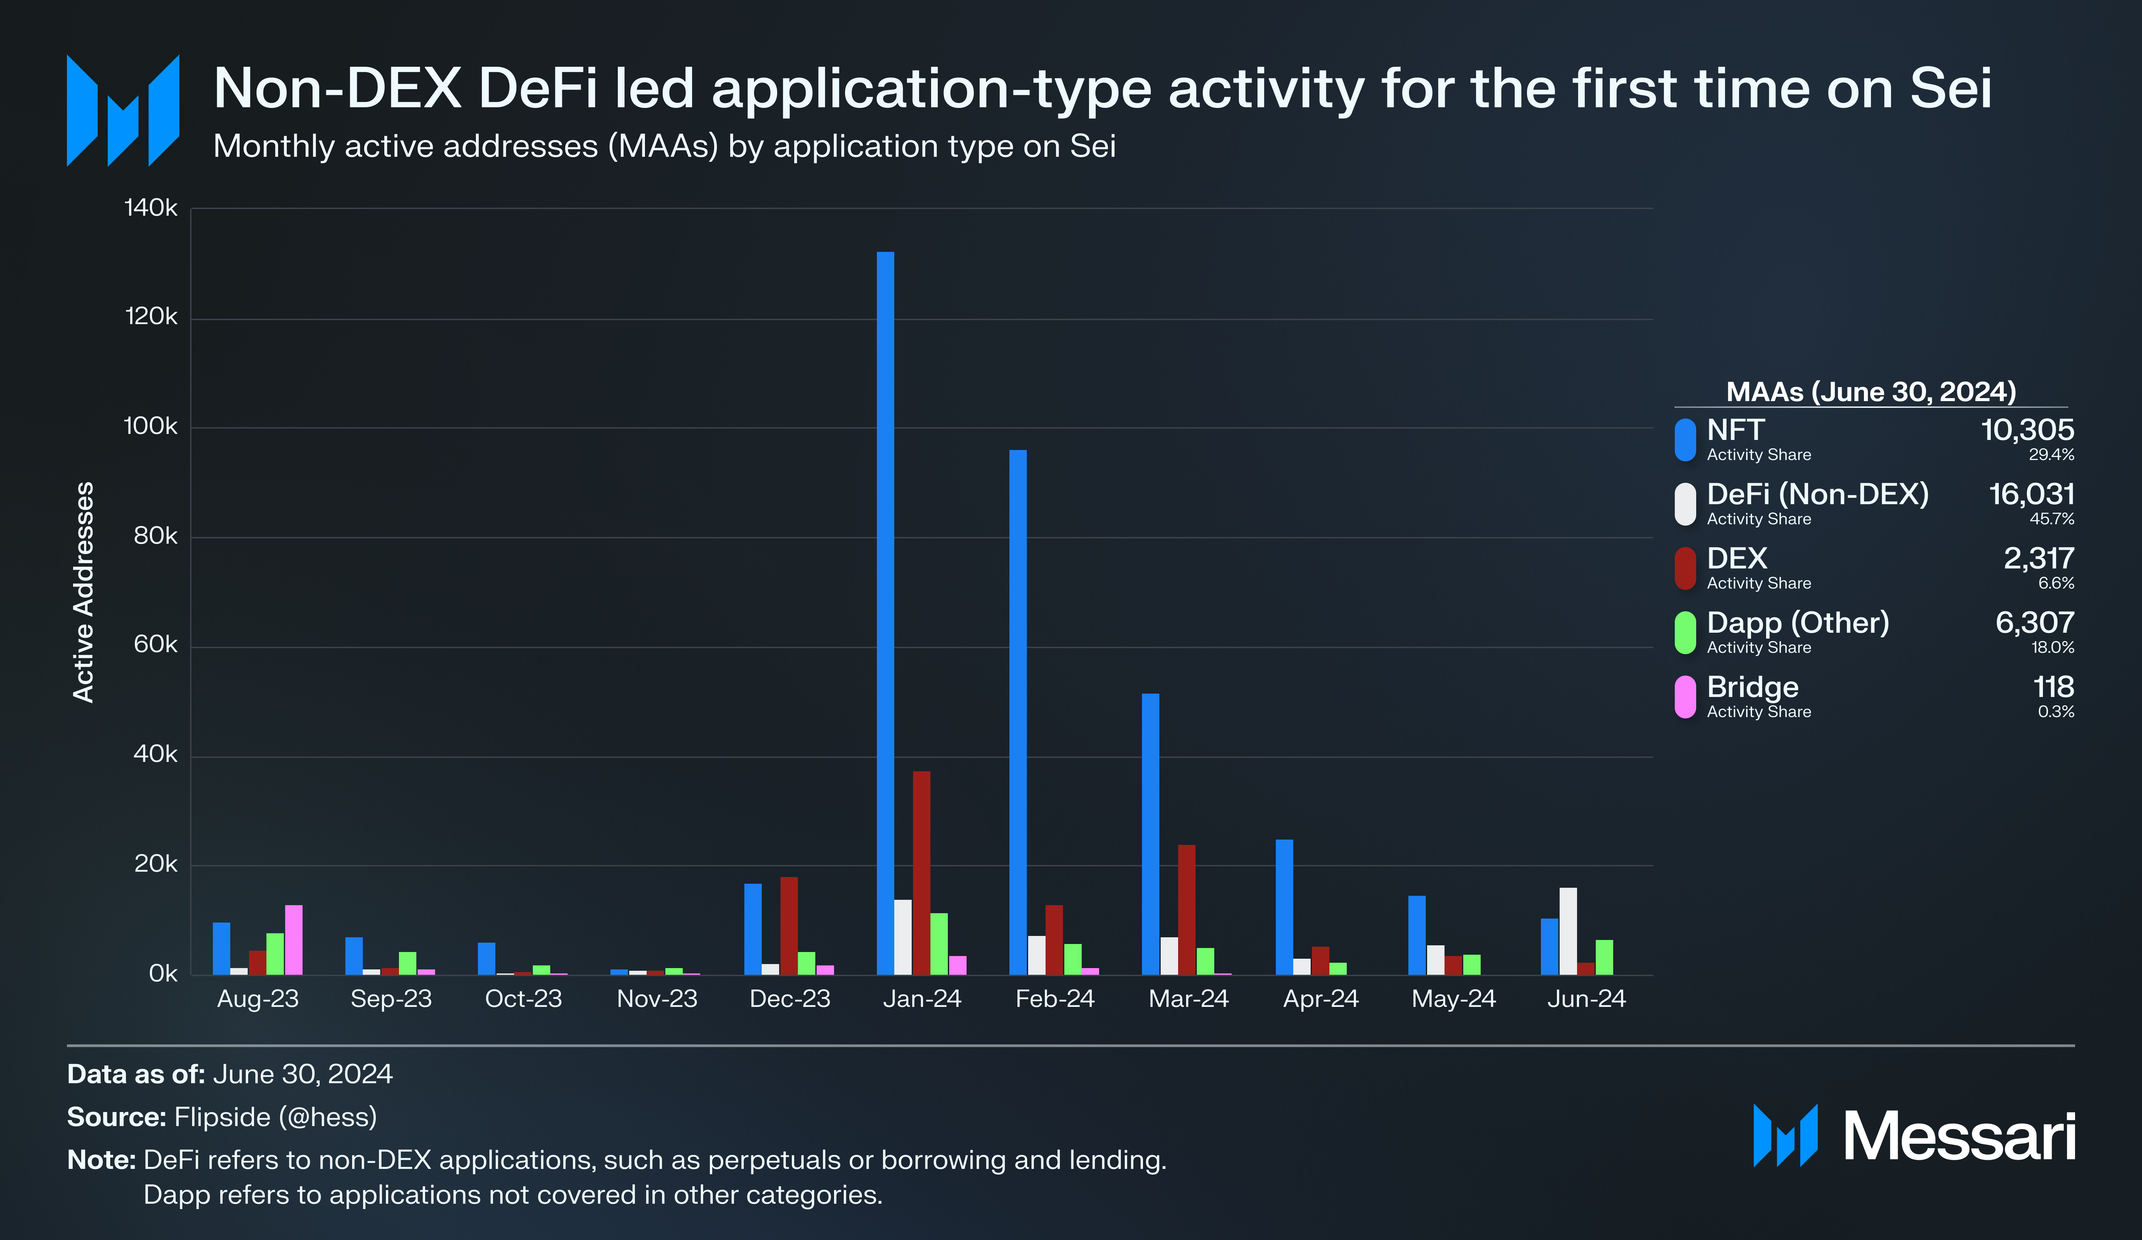
The NFT sector has decisively led ecosystem activity since Sei’s inception. However, the launch of Sei V2 bucked this trend in June, as active addresses in the DeFi sector led monthly ecosystem activity for the first time with a 45.7% share.
DeFi
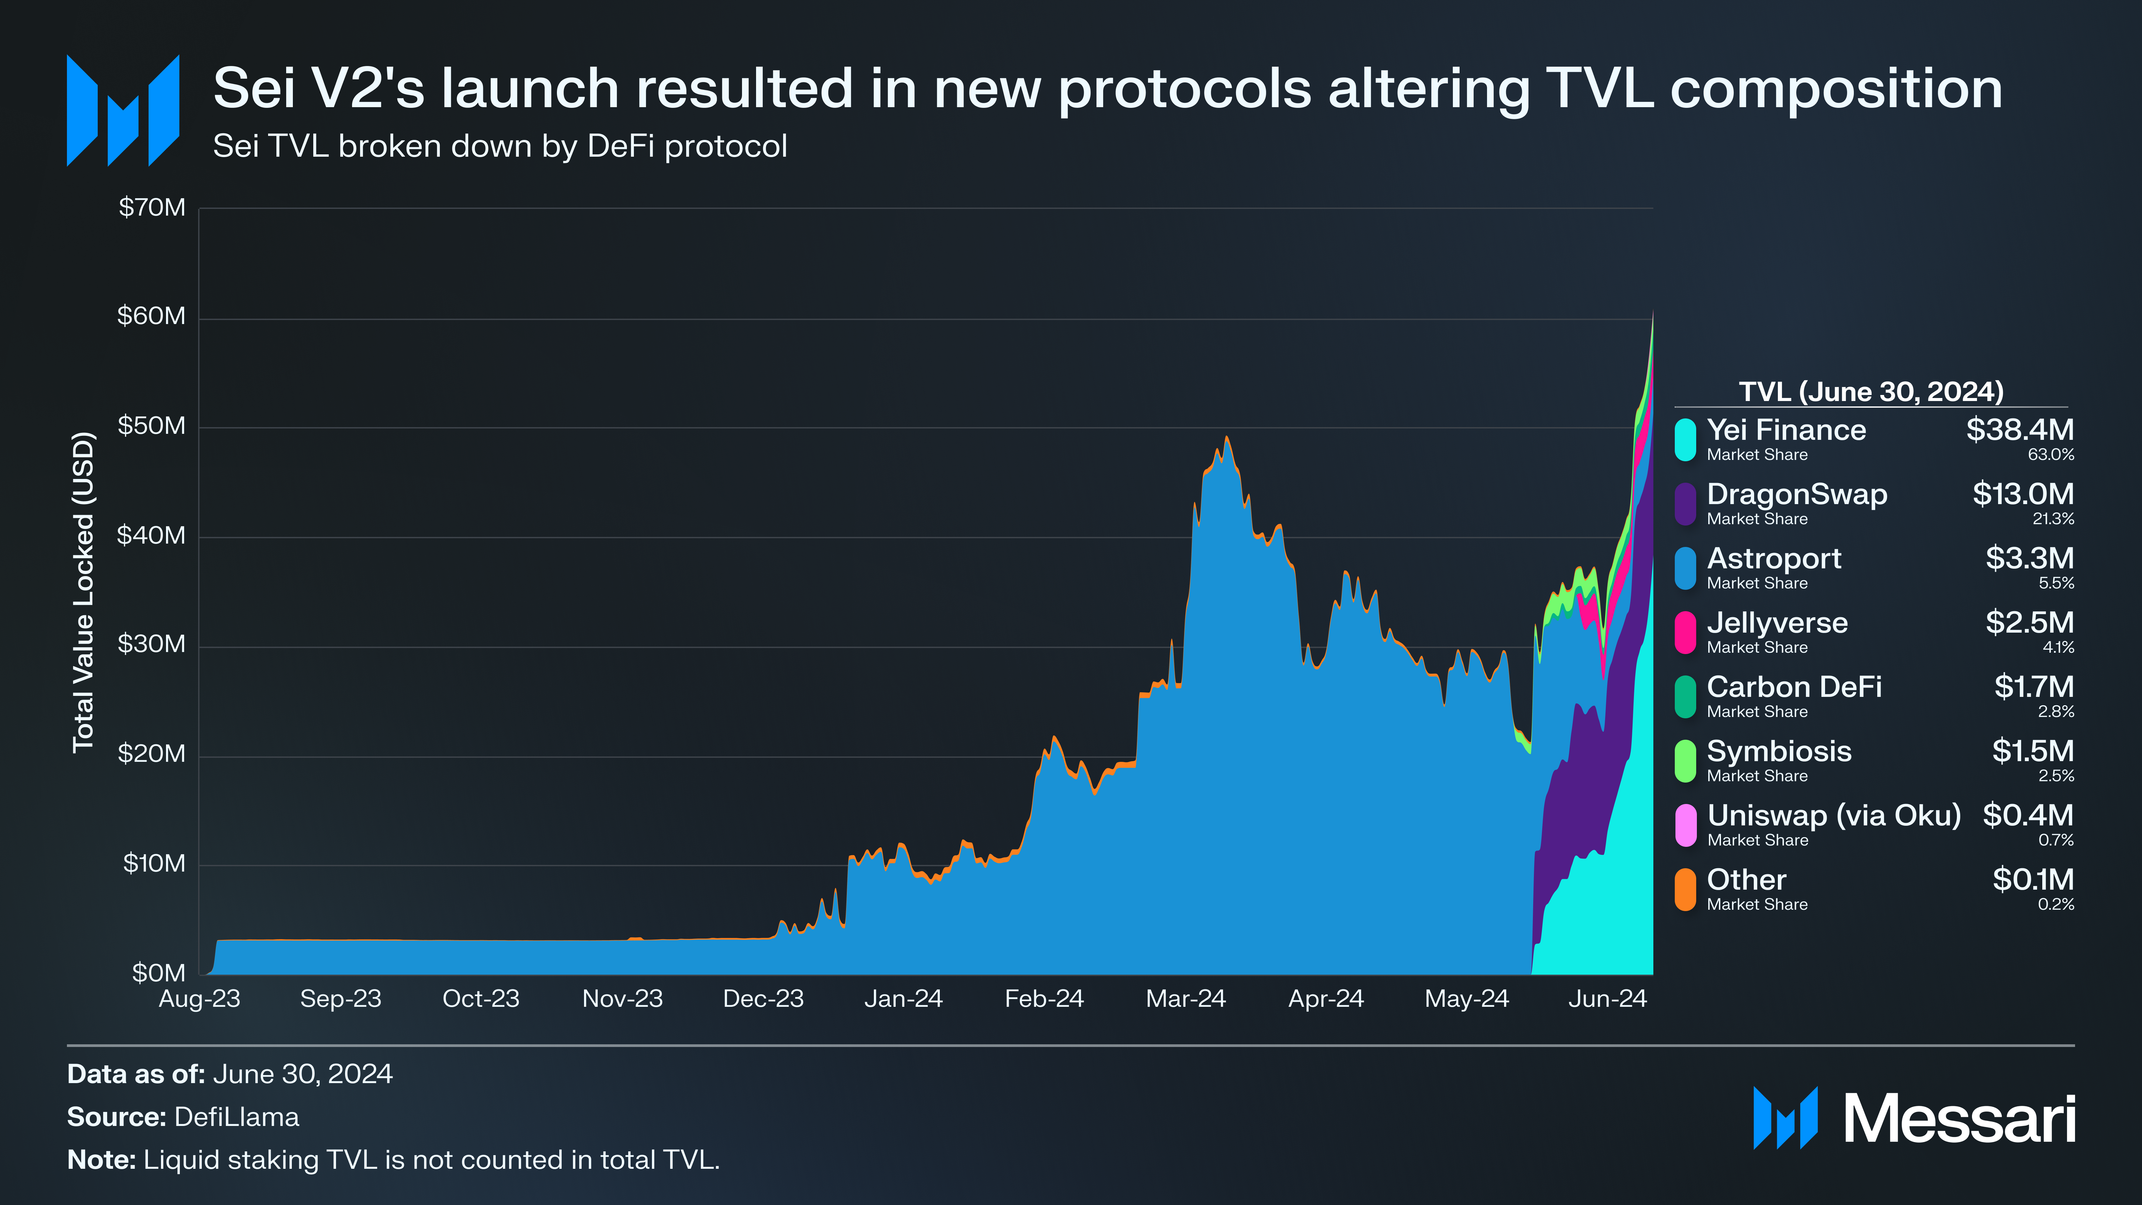
Sei’s TVL (USD) saw a 32.9% QoQ increase to $60.9 million. This increase is especially notable when considering SEI’s quarterly price decrease, as TVL (SEI) increased 221.9% QoQ to 179 million SEI. TVL growth was driven by the launch of Sei V2 and its introduction of EVM compatibility on May 27, 2024.
The Sei V2 upgrade unlocked new opportunities by expanding Sei’s developer ecosystem and enabling established EVM protocols to deploy on Sei. New EVM bridge integrations with Squid, Hyperlane, Symbiosis, LayerZero (via Stargate), and Wormhole enabled ERC-20 assets to be bridged to Sei, while Pyth Network, RedStone, and API3 integrations powered EVM data feeds. Ultimately, these developments kickstarted Sei’s TVL, which increased 271.6% in June alone.
Having only launched in Q3 2023, Sei hasn’t historically featured a large ecosystem of DeFi protocols. Before the launch of Sei V2, Sei had a DeFi Diversity score of 1 (i.e., the number of protocols making up 90% of a network’s TVL). With the launch of several new protocols post-Sei V2, the composition of Sei’s TVL changed and its DeFi Diversity score increased to 4.
Sei’s first EVM-compatible DEX, DragonSwap, quickly became Sei’s top DEX after its launch on May 29. The protocol launched a points program on June 25, 2024, ending the quarter with $13 million in TVL. Astroport was previously Sei’s top DEX, constituting 98.9% of Sei’s TVL at the start of Q2. Its TVL fell by 92.7% to $3.3 million by the end of Q2. As a result, Astroport’s TVL dominance fell to just 5.5%, while DragonSwap ended the quarter with 21.3%.
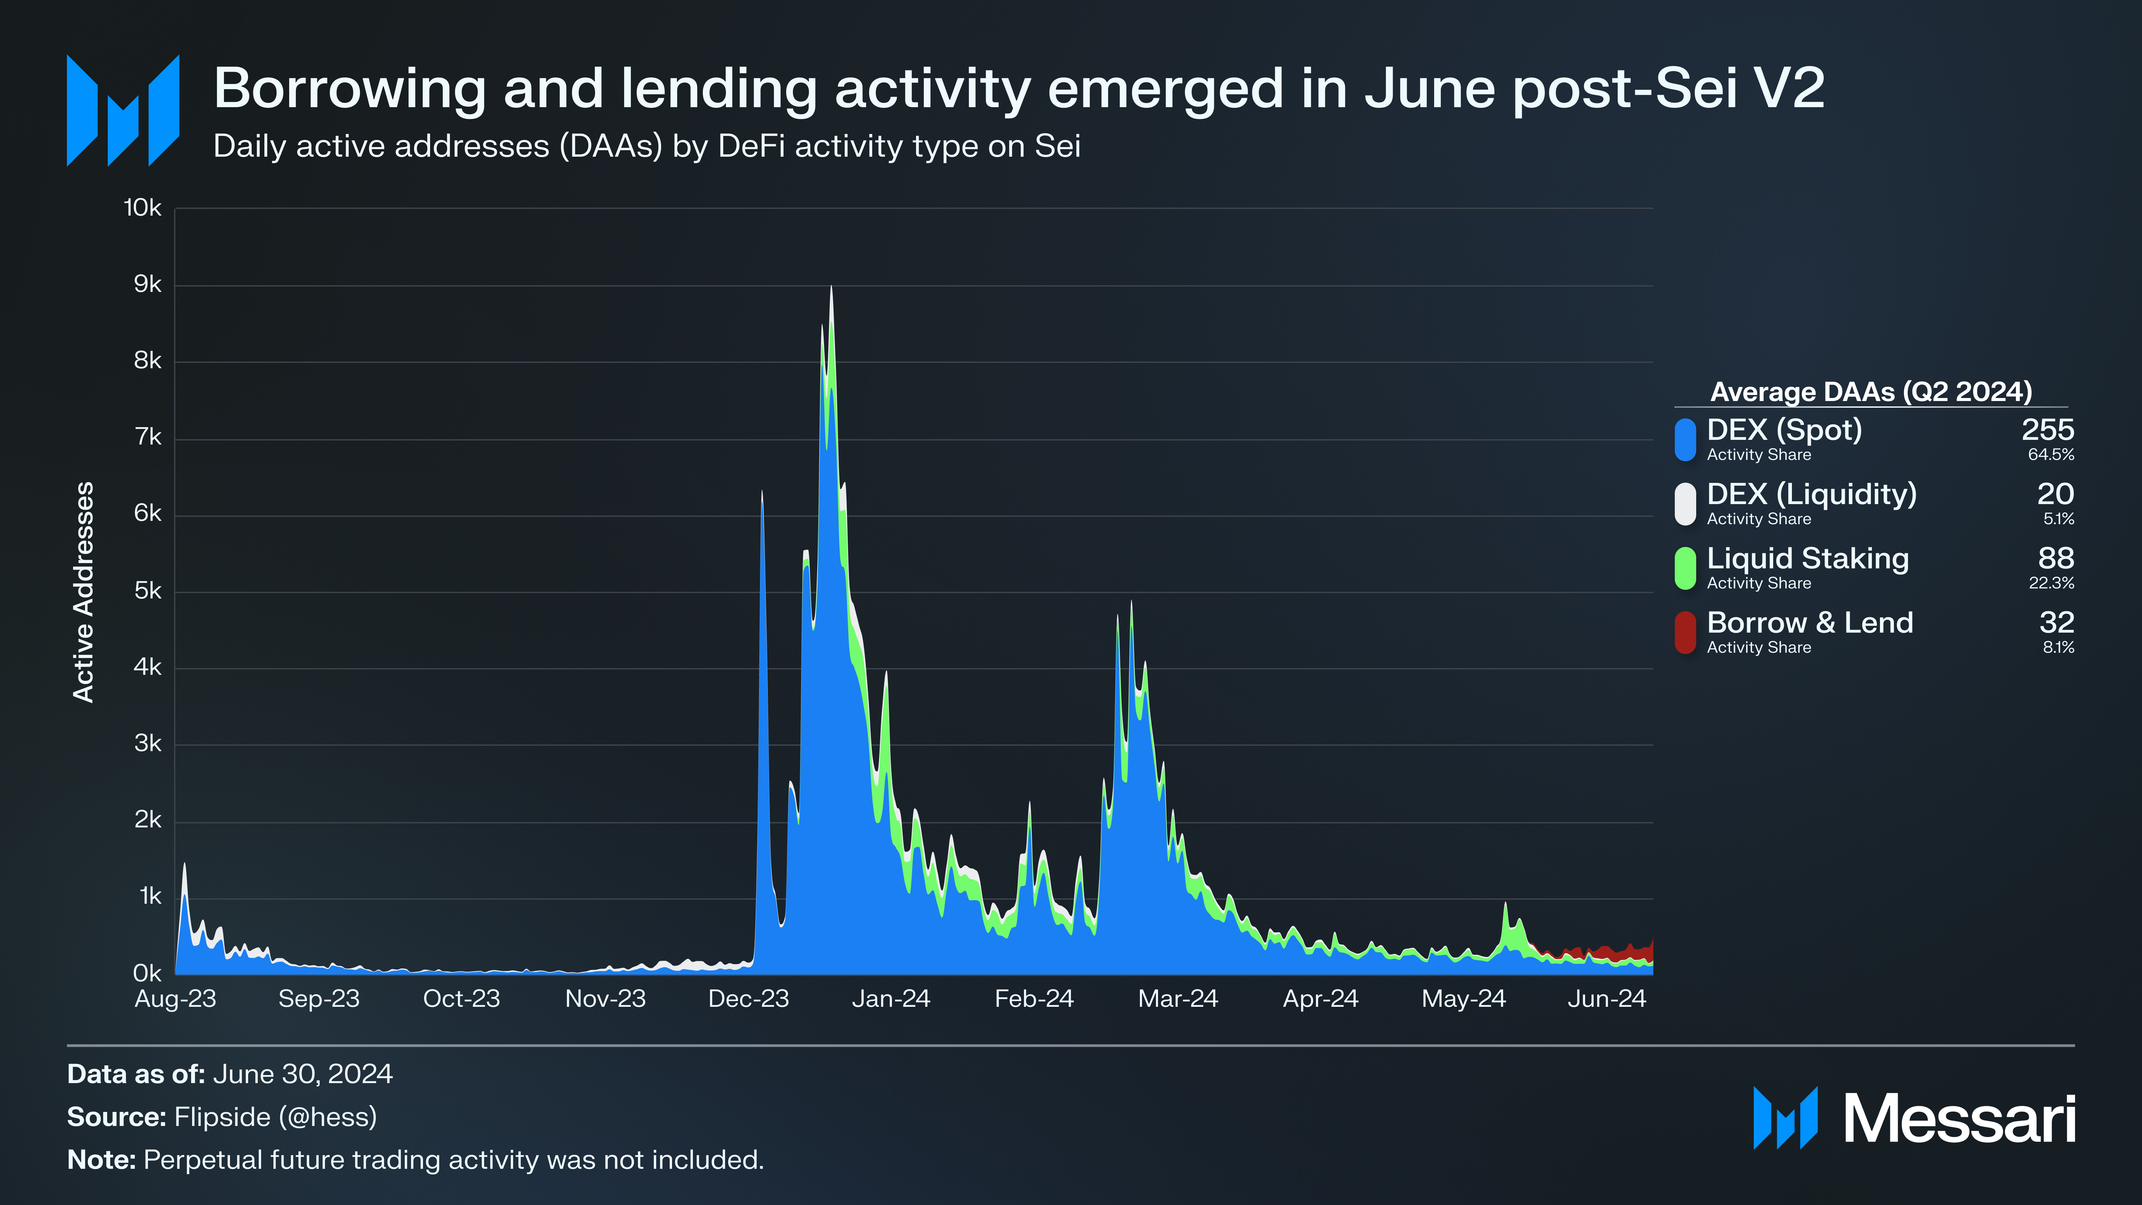
The launch of Sei V2 also resulted in a change in the composition of DeFi activity on the network. This change was led by another newcomer, Yei Finance, which became Sei’s first borrowing and lending protocol. The protocol is a fork of Aave V3 and features SEI, USDT, and USDC for borrowing and lending. Aside from being the first to market, Yei’s borrow and lend activity was further spurred by a points program that launched on June 17, 2024. At the end of Q2, Yei Finance commanded 63% of Sei’s TVL.
Other notable new protocols that emerged post-Sei V2 include (i) Uniswap, a friendly fork of Uniswap V3 on Sei via the Oku Trade front end, (ii) Jellyverse, a DEX that serves as Balancer’s friendly fork on Sei, and (iii) Carbon DeFi, a DEX that serves as the friendly fork of Bancor on Sei. The term “friendly fork” signifies that the underlying forked protocol has approved the forked deployment on another chain, in this case, Sei. Lastly, DEX aggregators like OpenOcean and Rubic Exchange have launched support for Sei and routing swaps through Sei’s growing DEX ecosystem.
NFTs
Sei’s NFT ecosystem has historically been one of the top sectors for the network, with over 30 million SEI in all-time total volume. However, NFT-related metrics saw major declines across the board after a booming Q1’24 for the sector.
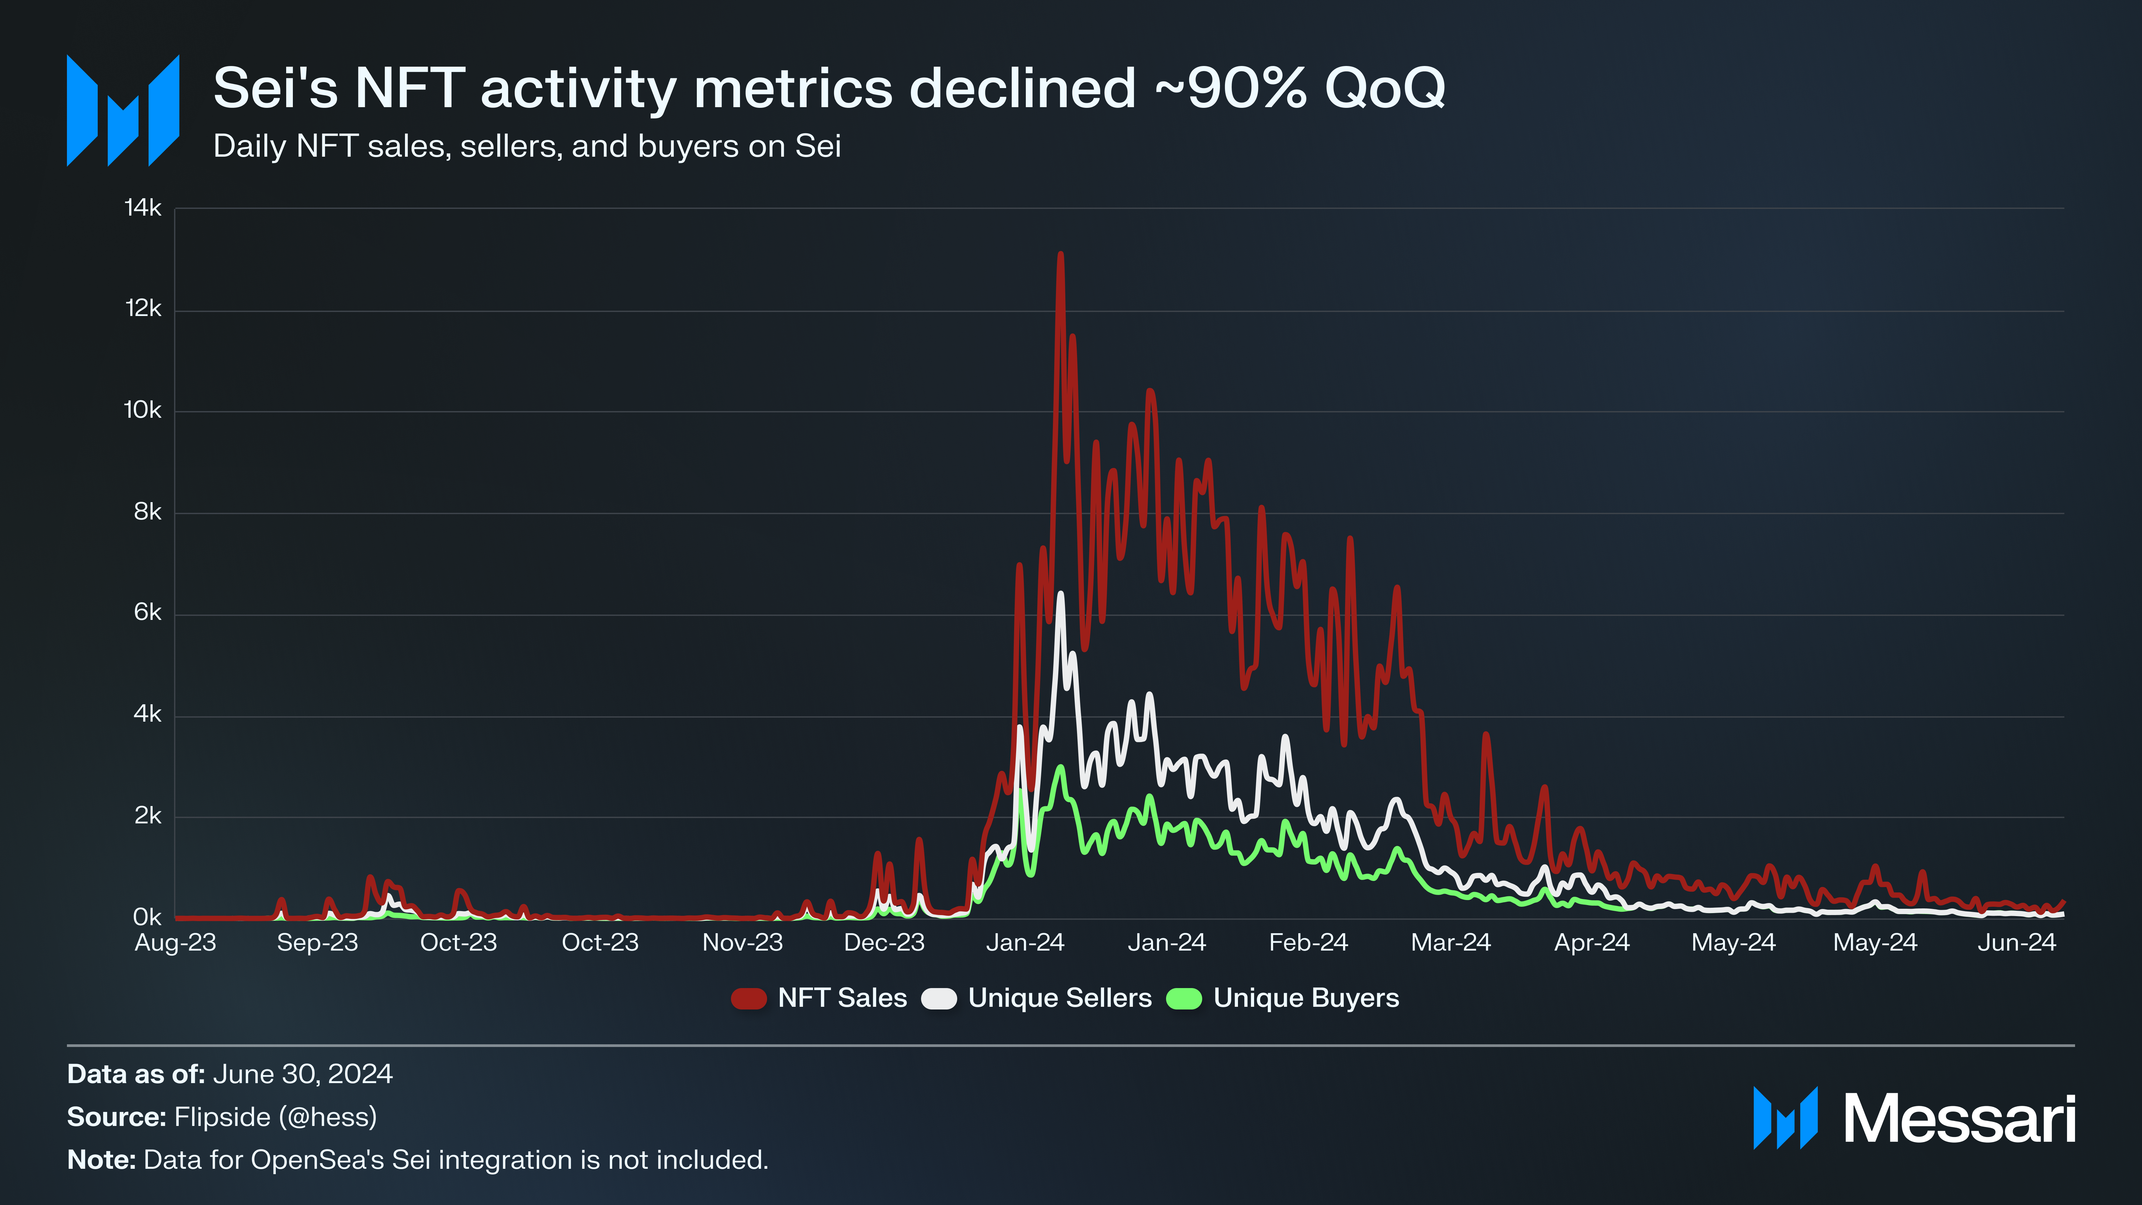
In Q2, Sei saw average daily NFT sales decrease 88.2% QoQ to 658, unique sellers decrease 89.5% QoQ to 243, and unique buyers decrease 85.6% QoQ to 186. Despite the recent decreases, the number of average daily NFT sales has grown in the medium term, with Q2’s average of 658 greatly exceeding the average of 183 in Q4’23.
Historically, the number of sellers has consistently exceeded the number of buyers. In June, however, the number of buyers and sellers converged and reached near parity, potentially marking an inflection point for NFT activity.
NFT trading volume (SEI) decreased 91% QoQ to 31,581. Sei-native NFT marketplaces, including Pallet, MRKT, and Dagora, continued to dominate. Pallet grew its market share in Q2, accounting for 99.8% of NFT trading volume, up from 94.4% in Q1’24. MRKT failed to eat into Pallet’s market share after launching in Q1’24, while Dagora’s activity continued to trend toward zero. Although not included in this section’s data, OpenSea launched support for Sei at the end of May.
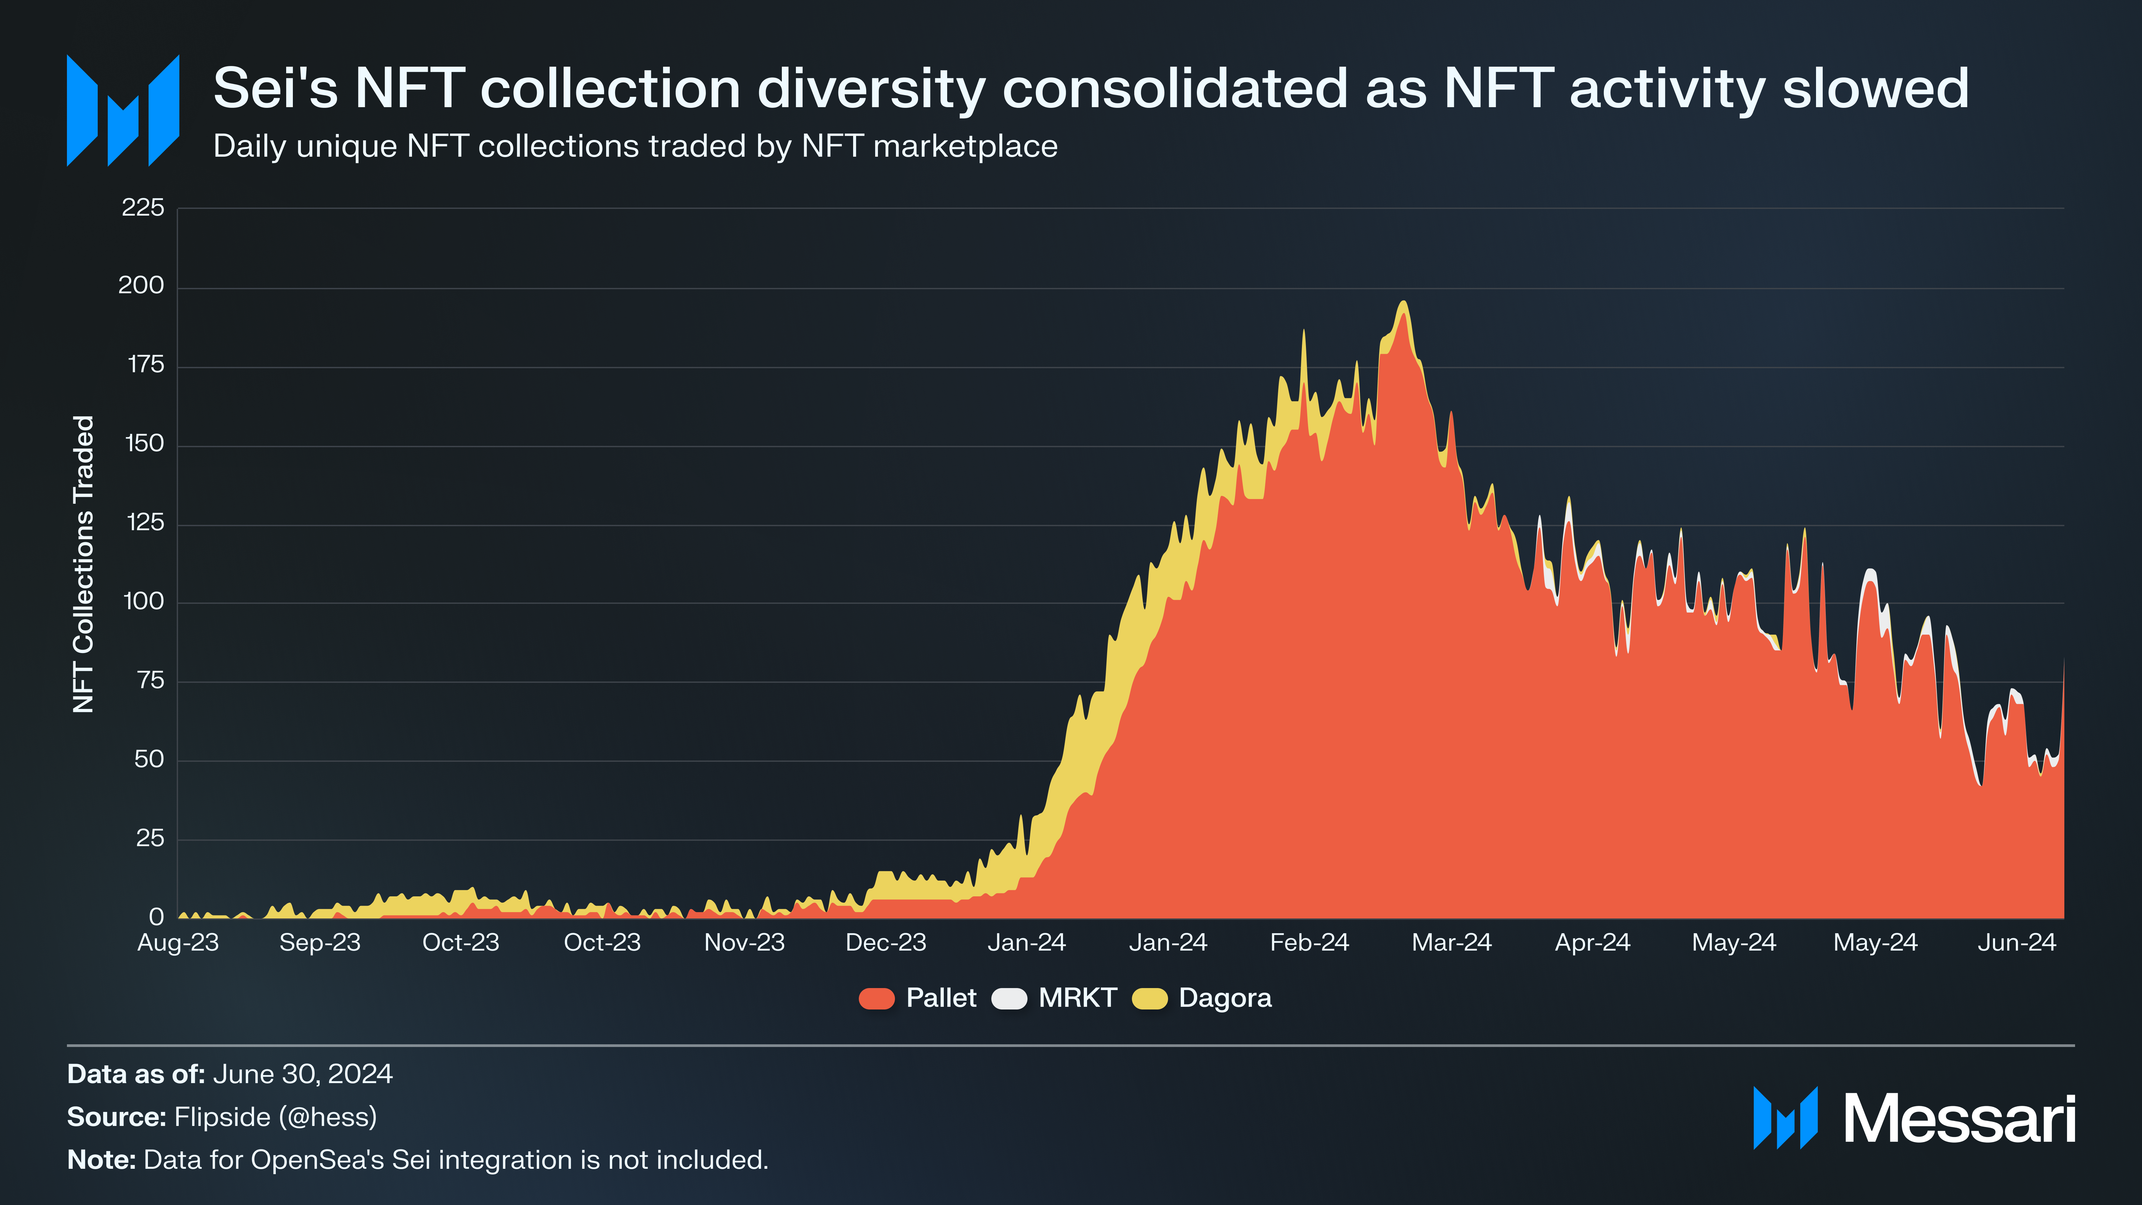
NFT sales peaked in December 2023, but the number of collections traded continually increased throughout Q1’24. This trend suggests that the NFT sector’s surge in trading volumes resulted in developers launching more NFT collections, leading to saturation of the sector. As NFT activity waned in Q2, the number of unique collections traded daily decreased 22.5% QoQ to 90.
Notably, Sei V2 introduced a variety of new NFT-related developments. Both Pallet and MRKT introduced support for ERC-721 non-fungible tokens (NFTs). WeBump, which offers a toolkit called Lighthouse, launched Lighthouse V2 and expanded support for ERC-721 tokens.
Grants
Sei Foundation announced two grant initiatives in April 2024:
A $10 million Sei Creator Fund to empower creators and builders across NFTs and social (content creation, in-real-life (IRL) events, etc.). Users could apply for funding directly from Sei Foundation. Later in June, Sei Foundation launched a $250,000 crowdfunding round in partnership with Gitcoin. Users could apply for funding, with voting on distribution slated to conclude in July.
An Entrepreneur in Residence (EIR) program to help bootstrap early-stage projects building on Sei. Developers can apply to receive a three-month stipend to develop a minimum viable product (MVP) alongside mentorship from Sei Foundation and Sei Labs.
Closing Summary
Sei experienced declines across various metrics in Q2 2024. Quarterly network revenue (SEI) fell 85.4% QoQ to 86,376 SEI, average daily active addresses fell 76.1% to 5,105, and various NFT-related metrics fell between 80% and 90% QoQ. SEI’s price decreased 58.7% QoQ to $0.34, with its market cap rank falling from 59th to 69th. However, DeFi TVL (SEI) increased 32.9% QoQ to $60.9 million.
Sei’s V2 upgrade went live at the end of May, introducing compatibility with EVM smart contracts, optimistic parallelization, and SeiDB. Various new EVM-compatible DeFi protocols launched, leading to a TVL (USD) increase of 271.6% in June. Two of the new protocols were Yei Finance and DragonSwap, which commanded 63% and 21.3% of TVL market share by the end of Q2, respectively.
Looking forward, the community can hope for further growth in activity as Sei looks to capitalize on the momentum spurred by Sei V2 in June. The momentum could continue into Q3 if incentive and points programs throughout Sei’s ecosystem effectively attract users and assets.
This report was commissioned by Gladiolus Labs Limited. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
During his 3.5-year tenure at Messari, Patryk contributed across Messari's Diligence, Protocol, and Enterprise research teams. As Research Manager, his primary focus was on Layer-1 and Layer-2 infrastructure and the DeFi ecosystems atop them.
During his 3.5-year tenure at Messari, Patryk contributed across Messari's Diligence, Protocol, and Enterprise research teams. As Research Manager, his primary focus was on Layer-1 and Layer-2 infrastructure and the DeFi ecosystems atop them.