Looking to dive deeper? Subscribe to Messari Pro. Messari Pro memberships provide access to daily crypto news and insights, exclusive long-form daily research, advanced screener, charting & watchlist features, and access to curated sets of charts and metrics. Learn more at messari.io/pro.
Quarterly ReportsDeFiStablecoins
State of Maker Q2 2022


Key Insights
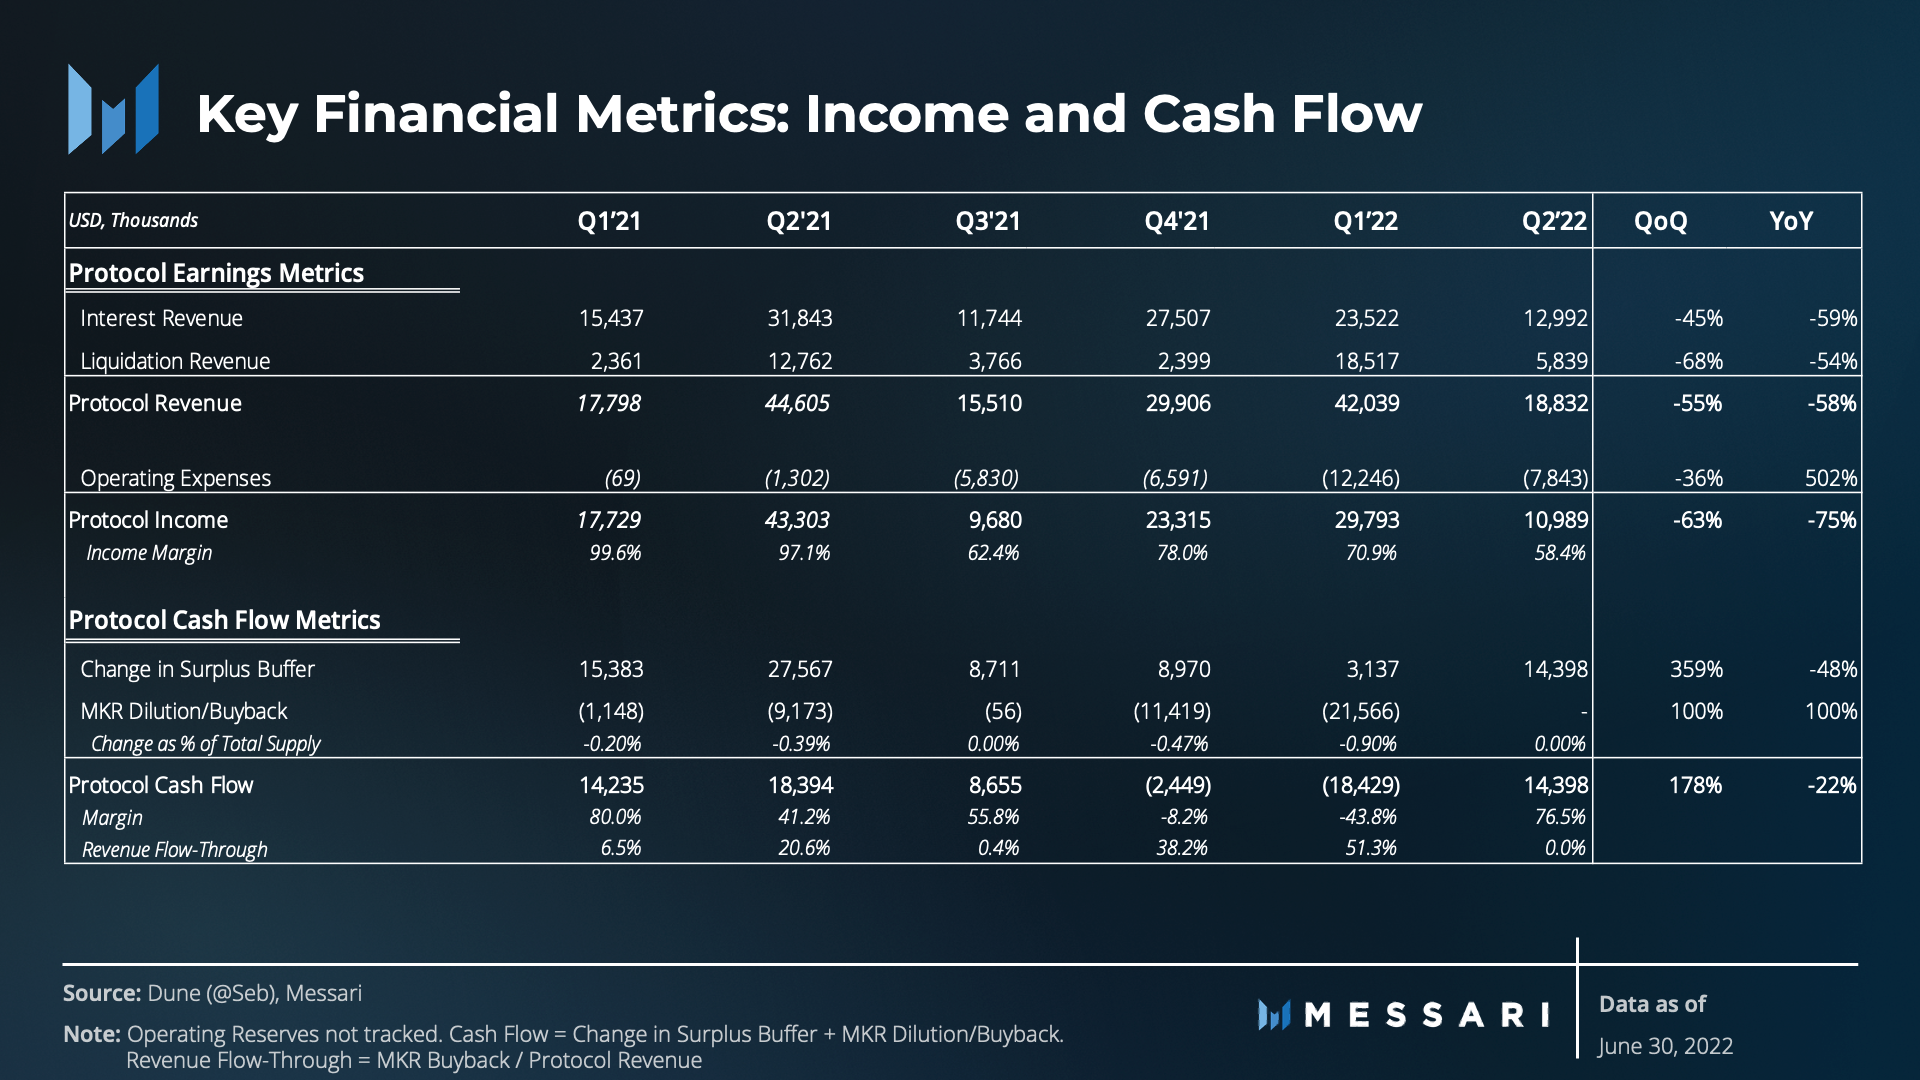
- The market deleveraging in Q2’22 hurt Maker’s lending business. Interest income was down 45% from Q1’22 to $13 million and yield-bearing collateral fell 31% in USD terms.
- G-UNI liquidity provider (LP) tokens were the largest yield-bearing collateral asset at $1.2 billion.
- Non-stable backed yield-bearing collateral is at its lowest since 2020 (DAI/USDC LP tokens are considered stable-backed).
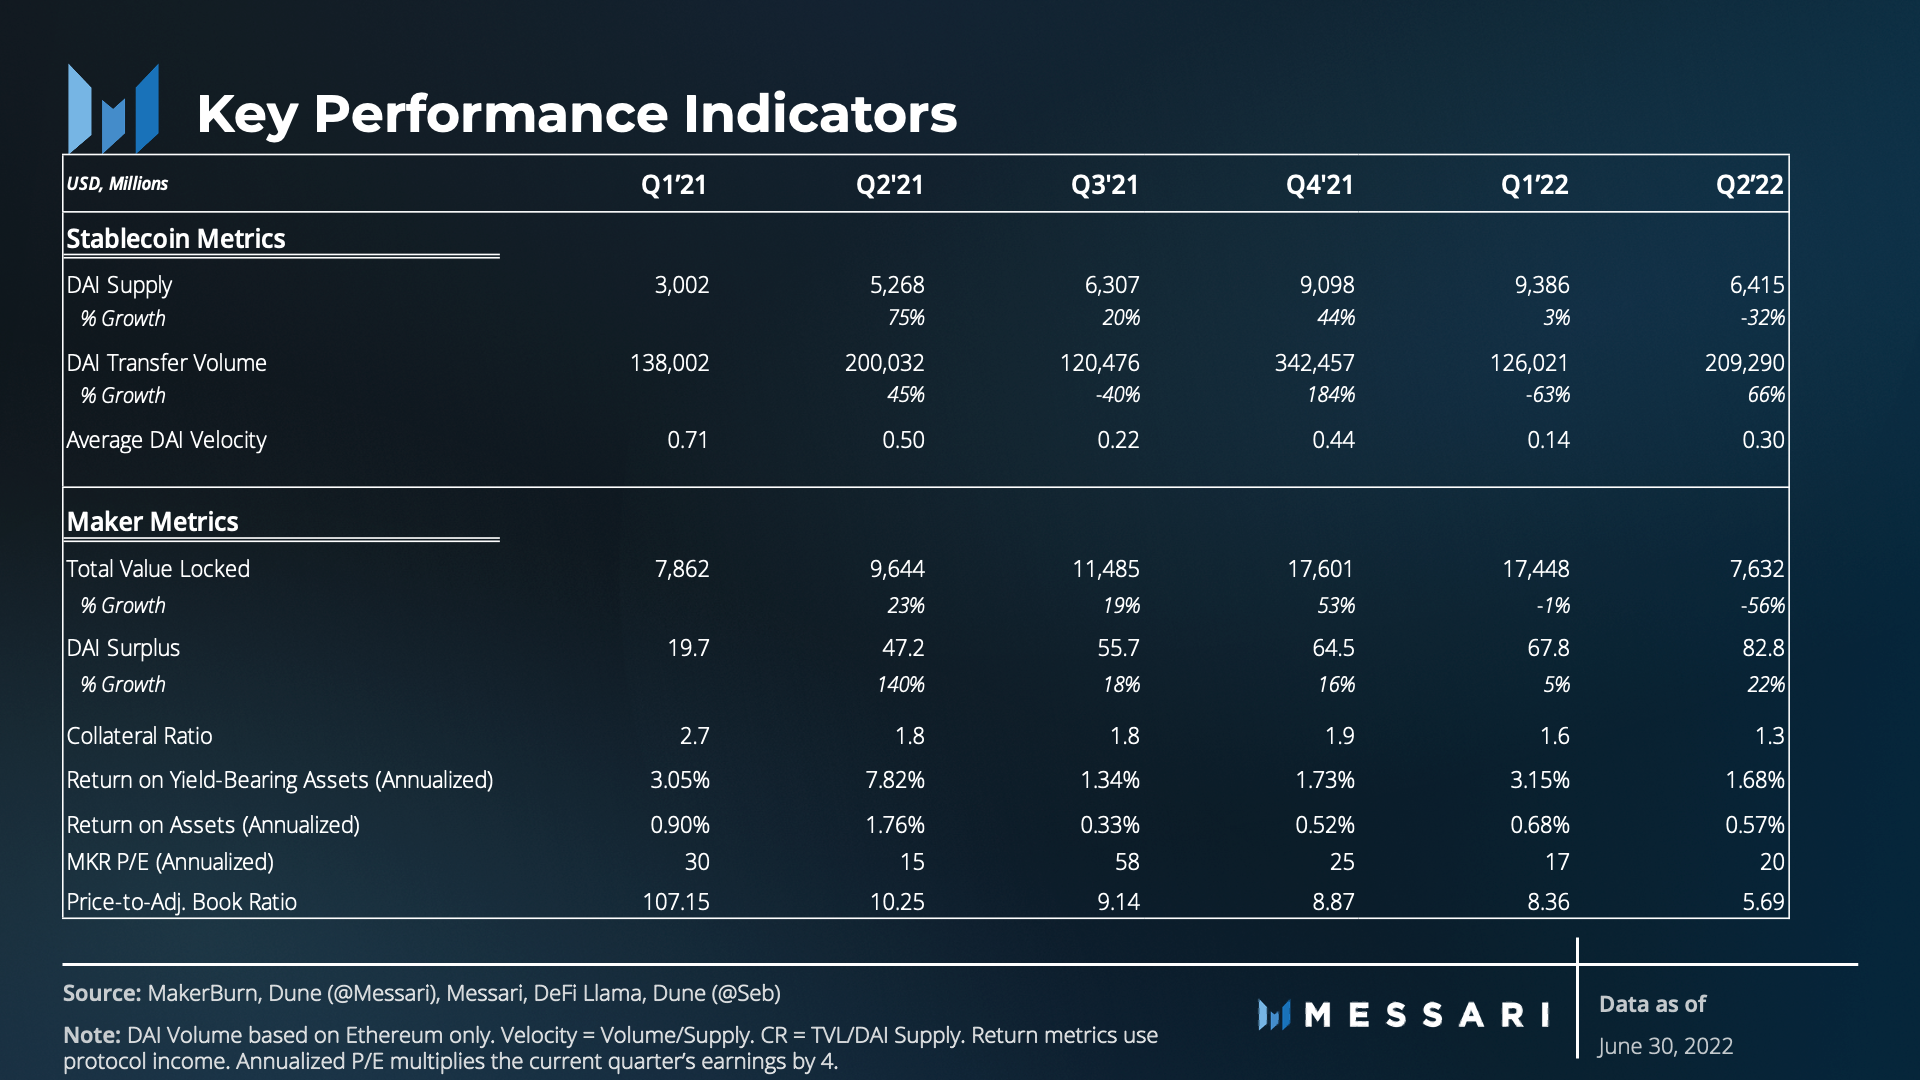
- DAI outstanding fell 32% to 6.4 million, largely impacted by the UST collapse and the subsequent liquidity collapse on the Curve 3pool.
- RWA-backed DAI increased to over $40 million, becoming Maker’s third largest non-stable backed collateral type behind ETH and wBTC.
- Maker defunded the Aave Direct Deposit Dai Module (D3M) module on June 15 as demand waned and risks rose.
A Primer on Maker
Maker is a peer-to-contract lending platform that enables overcollateralized loans by locking collateral in a smart contract and mints DAI, a stablecoin pegged to the U.S. dollar. MakerDAO determines which collateral types are accepted as well as their collateralization ratios and stability fees. Maker maintains DAI's stability through a dynamic system of collateralized debt positions, autonomous feedback mechanisms, and incentives for external actors. DAI also uses Price Stability Modules that allow for 1:1 swap of DAI with three approved stablecoins: USDC, USDP, and GUSD. Once generated, DAI can be freely sent to others, used as payments for goods and services, or held as long-term savings.
Introduction
As a lending platform, Maker's business is prone to cyclical demand for leverage within crypto. While the protocol operated without any hiccups over the quarter, the Terra-induced market crash adversely affected Maker's business by dampening leverage demand and unwinding a key source of DAI demand within Curve. Despite these outcomes, DAI maintained its position as the third largest Ethereum-native stablecoin, with over 6 billion in outstanding supply.
As falling prices and fewer loans shrunk the balance sheet, Maker’s interest revenue fell 45%. ETH collateral-backed loans also fell 75% in USD terms over the quarter, from over $2 million to $525,000. The largest increase on the balance sheet was in wrapped Uniswap DAI/USDC LP tokens, which are far less productive for Maker than other crypto-backed loans.
Maker’s two primary growth initiatives had diverging outcomes in the quarter. The first initiative is the Direct Deposit Dai Module (D3M), which directly deposits DAI into a lending protocol and controls borrow rates by dynamically adjusting the deposited DAI balance. The other initiative, Real World Assets (RWAs), onboards non-crypto collateral to be eligible for DAI loans.
Launched in November 2021, the Aave Direct Deposit Dai Module (D3M) peaked at 300 million DAI at the end of March but was defunded in June because of concerns about Aave governance proposals. The tool earned over $1 million in revenue for Maker in roughly 6 months, more than 2.5% of total interest revenue over that period.
Maker’s Real World Assets, however, grew to over $40 million in loans this quarter. The DAO is actively working to onboard new clients, including Huntingdon Valley Bank, a U.S. bank which has a proposed $100 million credit facility.
Performance Analysis
Maker Protocol
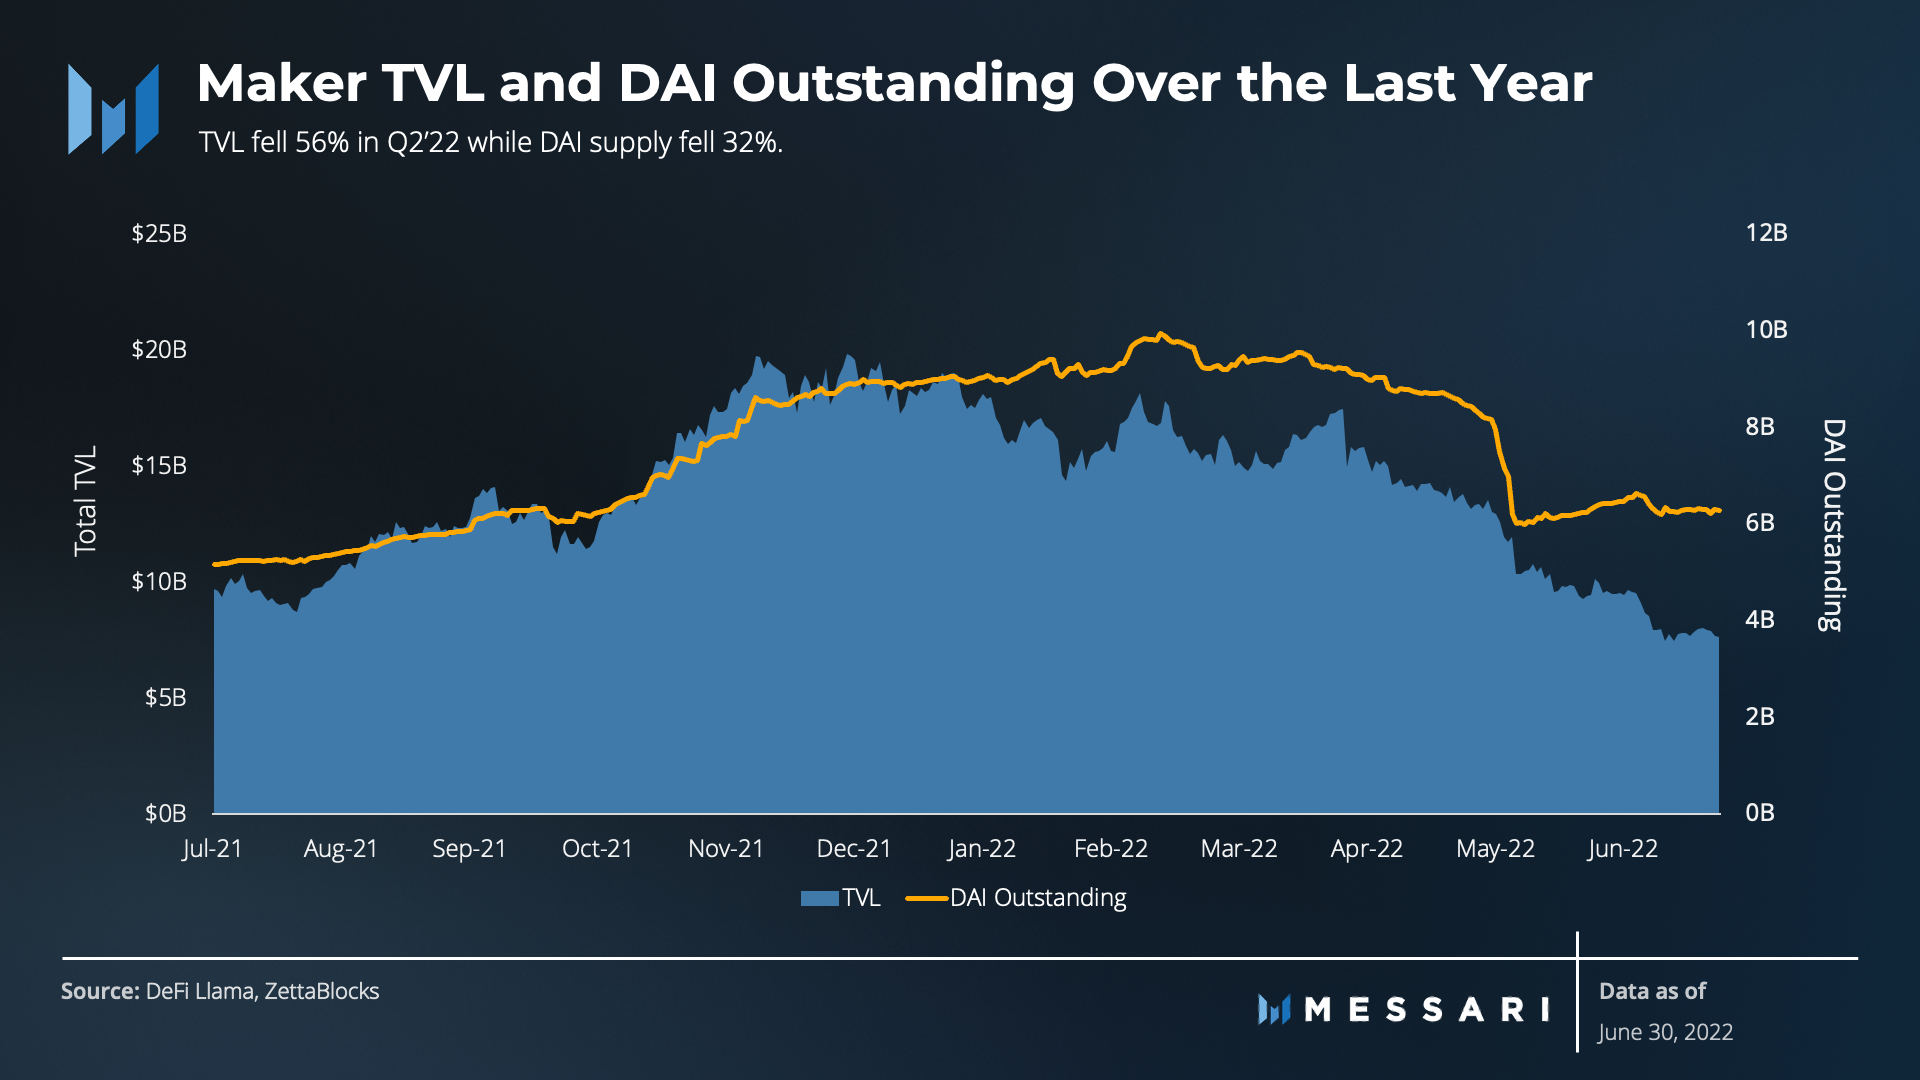
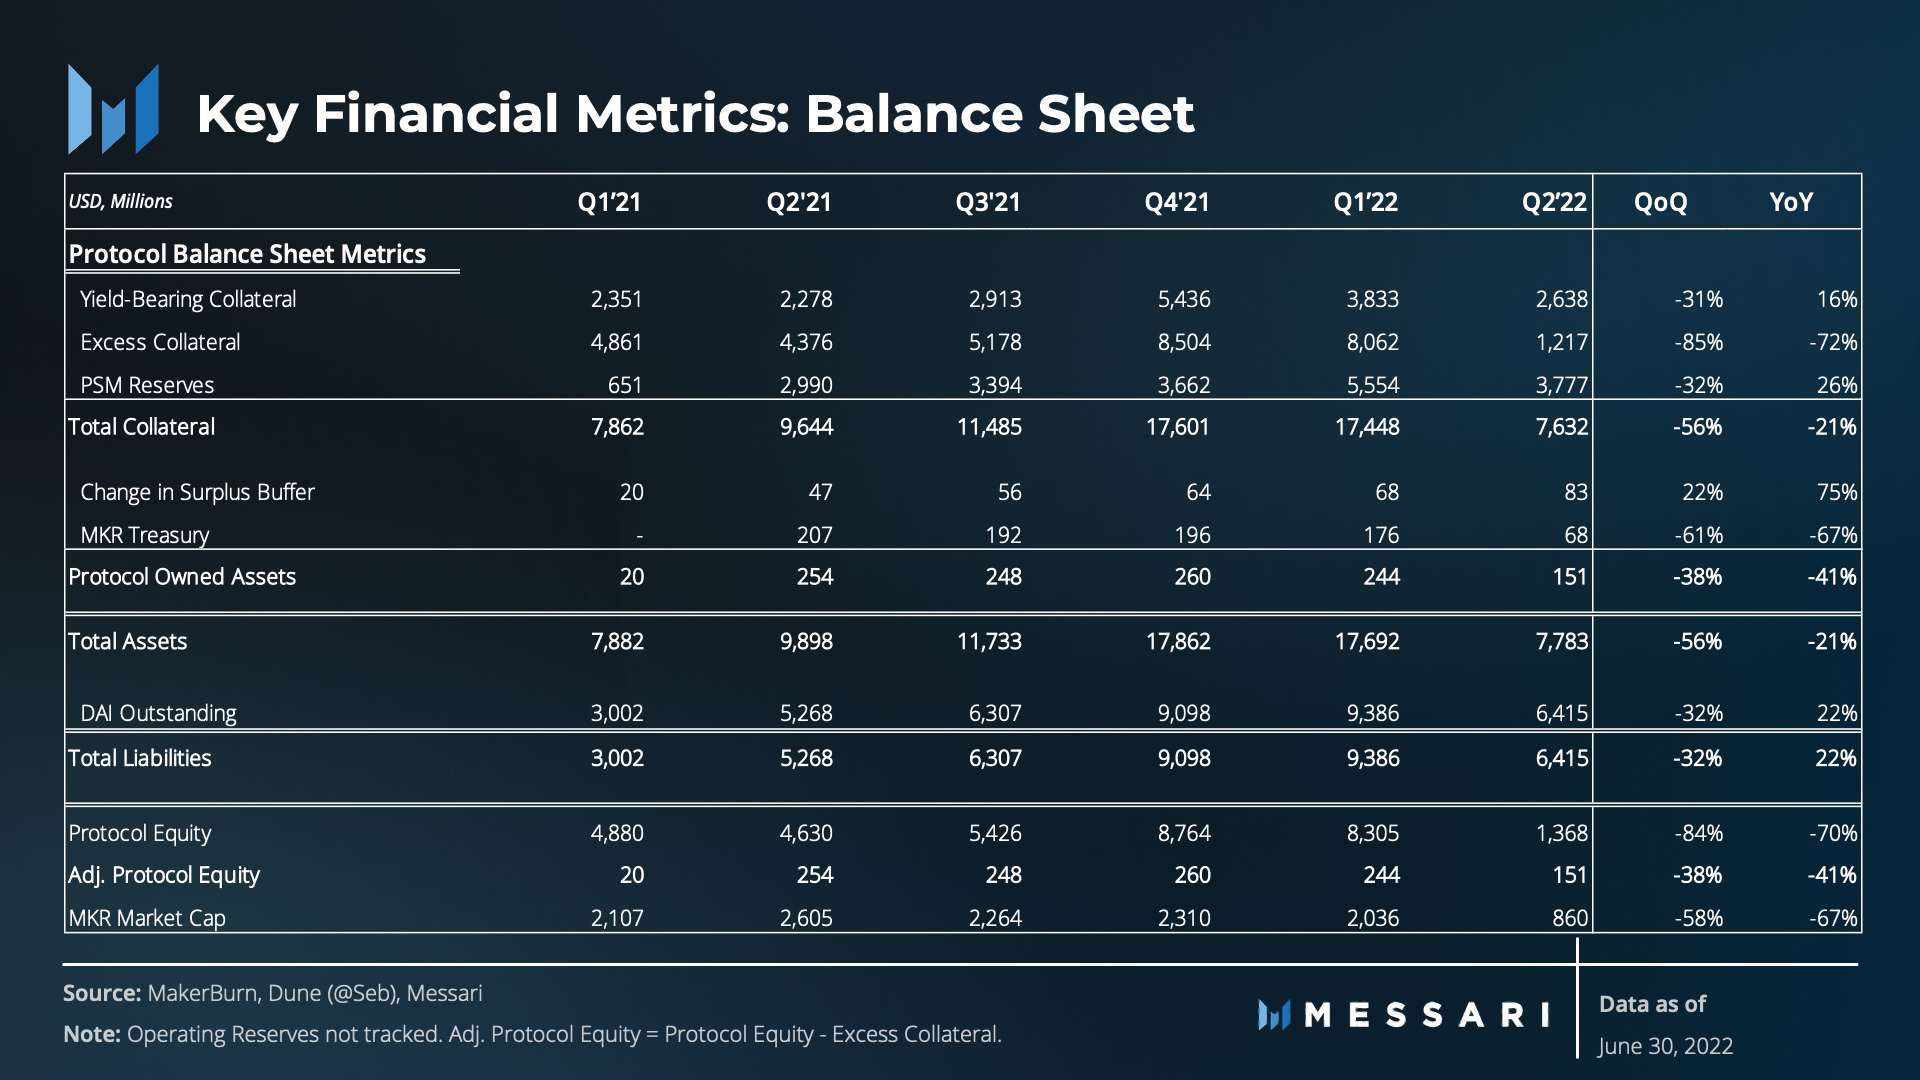
Falling asset prices took a toll on Maker’s TVL in the quarter, which dropped 56% compared to last quarter. Outstanding debt, measured by DAI outstanding, was slightly more resilient, falling 32% in the quarter. The largest change in TVL came from excess collateral on the network, which fell 85% in the quarter from $8 billion to $1.2 billion.
The large drop in excess collateral is significant because excess collateral acts as a loan buffer and informs the collateral ratio (measured as TVL/DAI loans outstanding). A lower collateral ratio likely means a higher risk of future liquidations, although the makeup of the loans also matters.
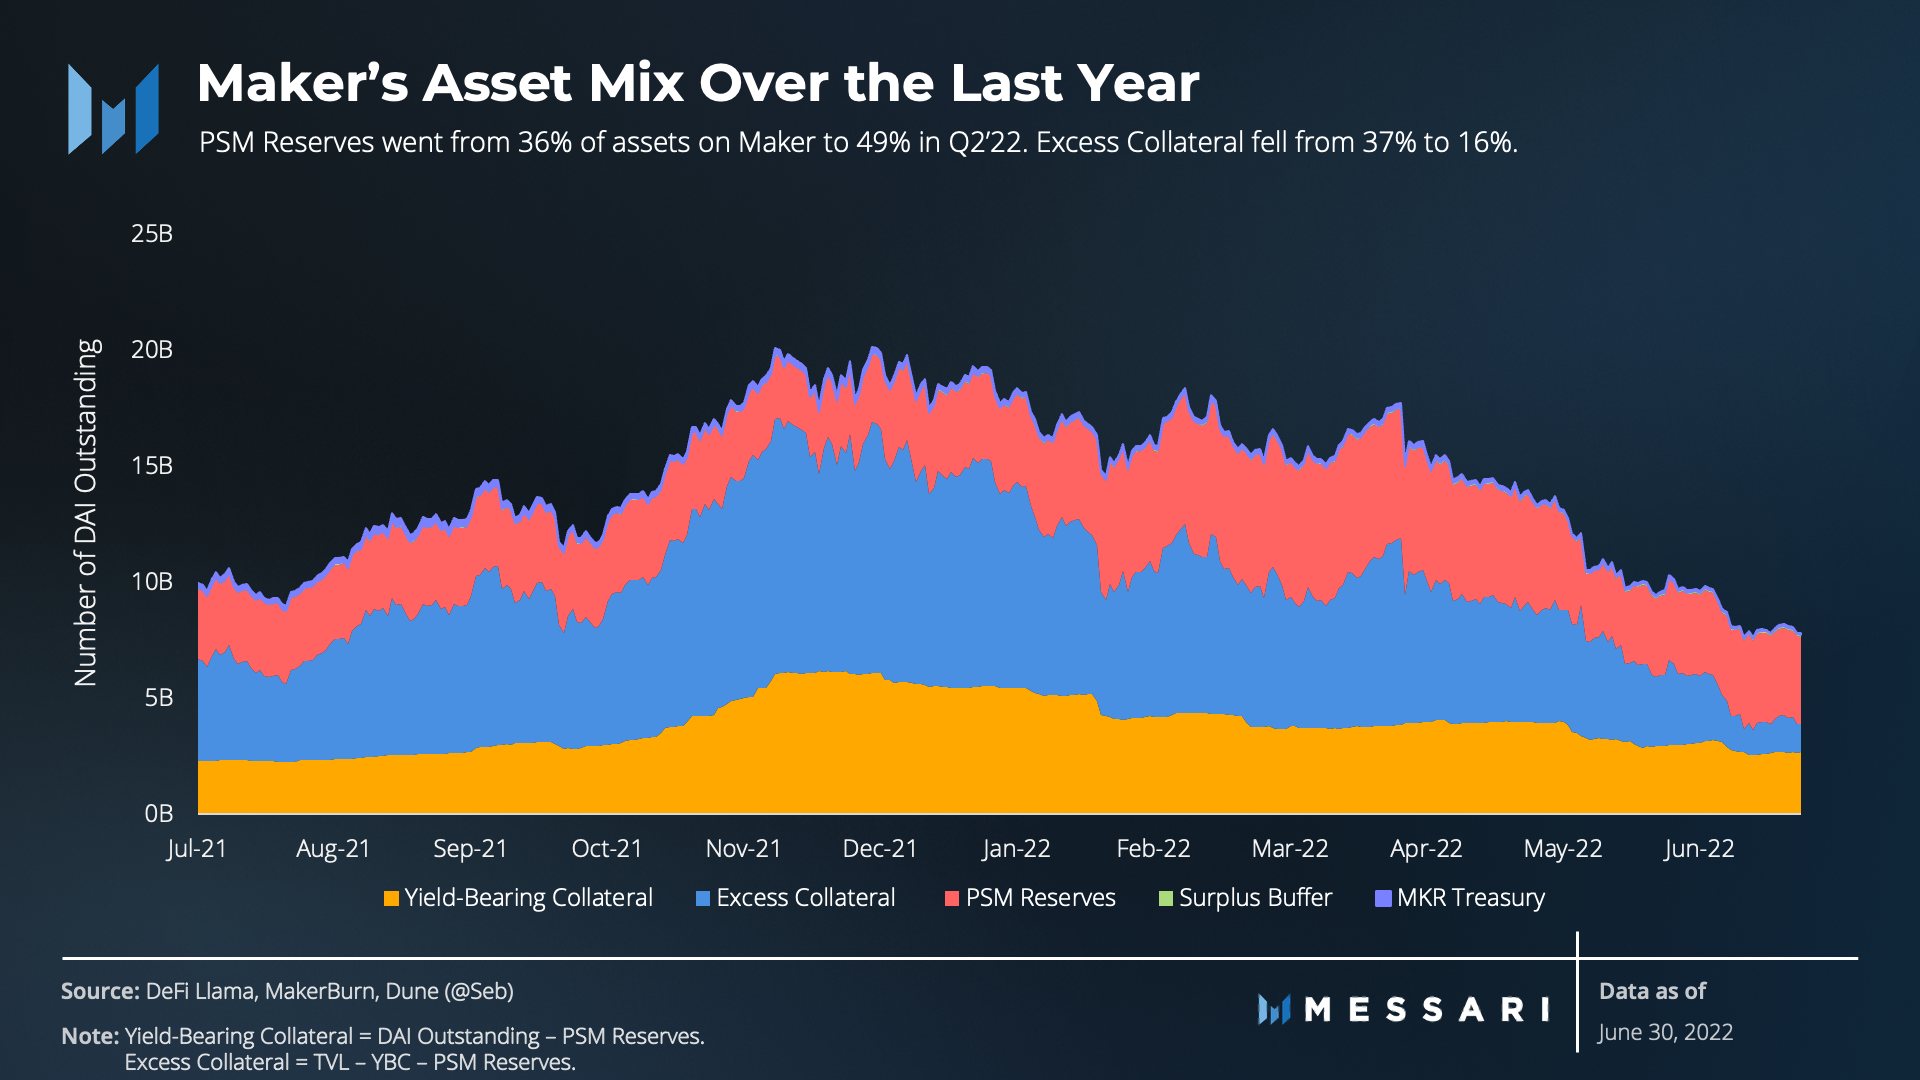
On a percentage basis, both the yield-bearing assets and the PSM reserves fell in line with the DAI supply. However, on a USD basis, the PSM decline nearly doubled the Yield-Bearing Assets and directly contributed to over half of the DAI supply contraction of roughly $3 billion.
The primary driver for the PSM contraction was the collapse of the Curve 3pool following the UST-induced market decline. Of the three assets in the 3pool, USDC and DAI rapidly rose in relative value to the third asset USDT since a significant portion of money market debt in DeFi is dominated in these two assets. As prices fell, market participants sourced USDC and DAI from the 3pool to pay down debts. This action resulted in a nearly 90% decline in DAI TVL on Curve and subsequently the decline in DAI supply via the PSM.
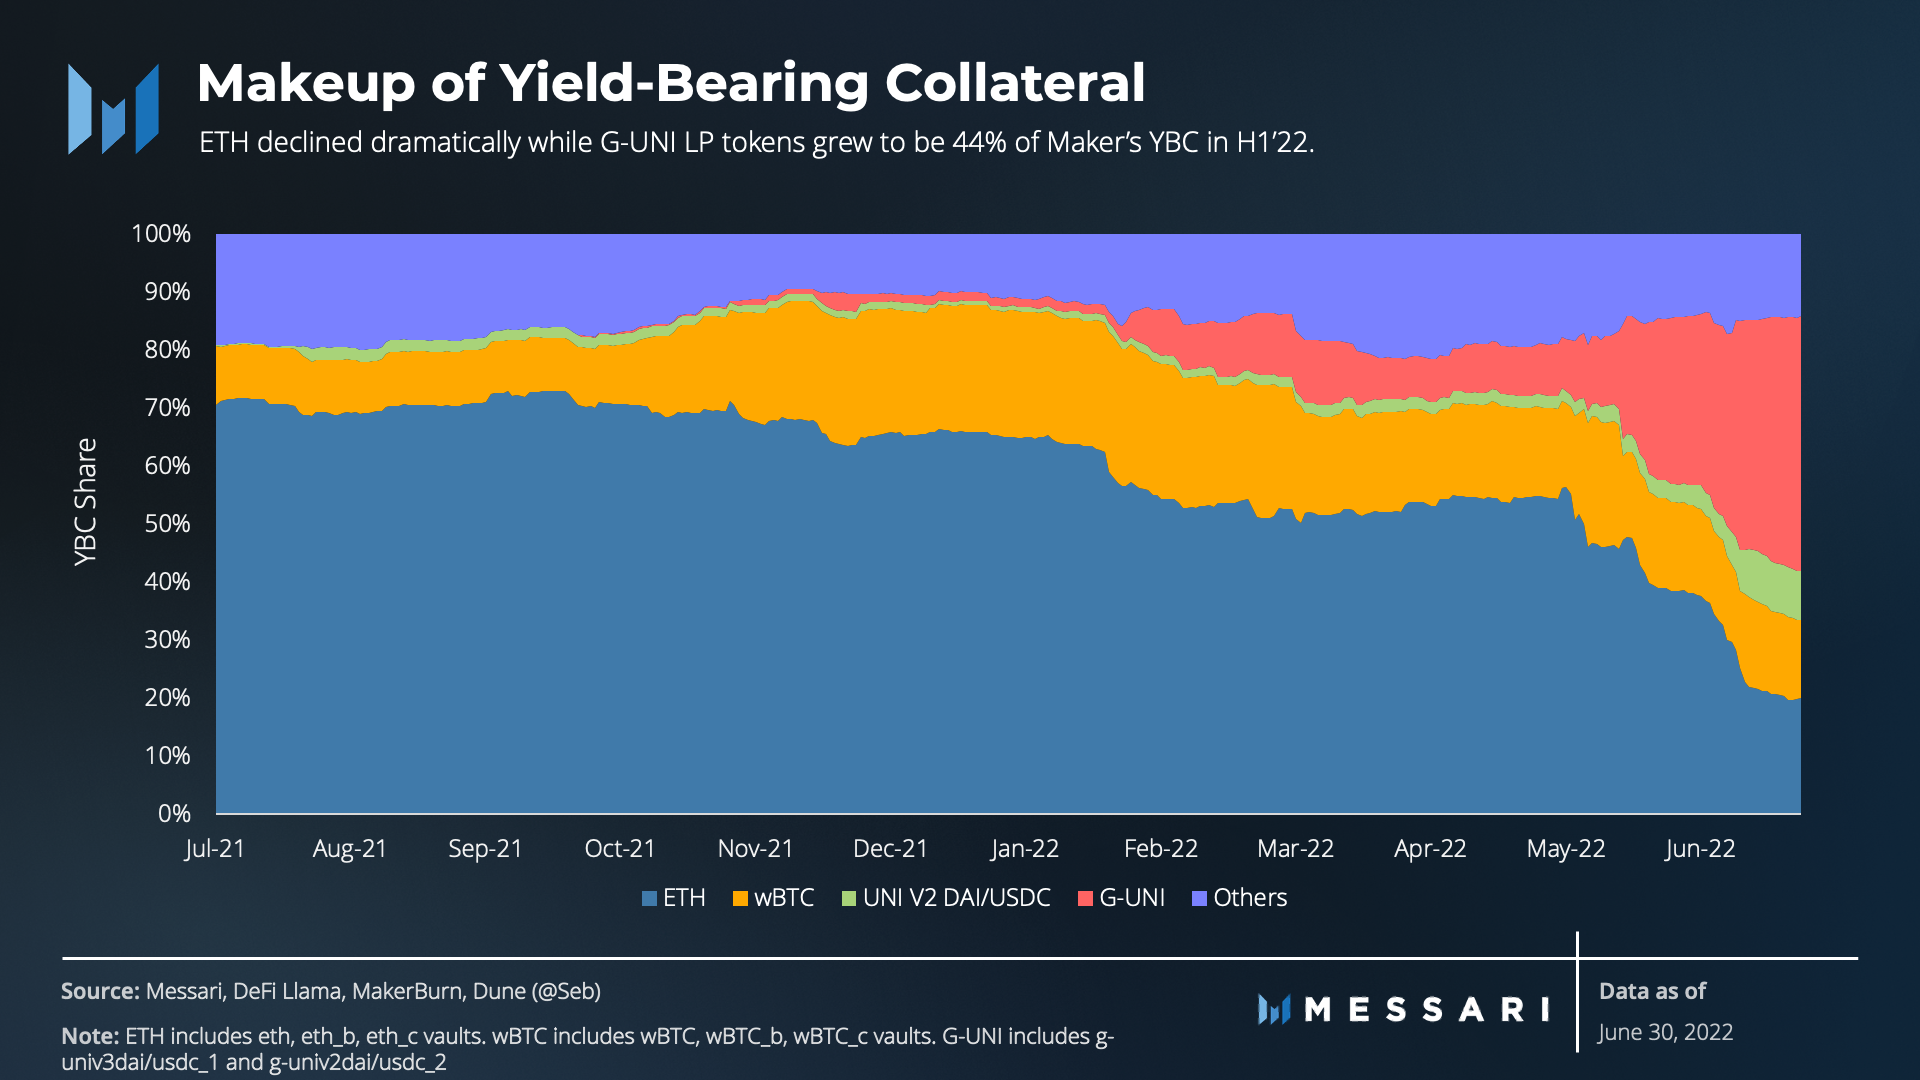
The breakdown of yield-bearing collateral (YBC) reveals enormous shifts for Maker. A year ago, ETH was 71% of Maker’s YBC. It closed Q2’22 at 20%. The biggest share taker was G-UNI LP tokens, accounting for $1.2 billion in collateral at quarter end. G-UNI LP tokens are Uniswap V3 DAI/USDC Liquidity Provider tokens that are wrapped by Arrakis Finance.
Maker accepts two varieties of G-UNI LP tokens as collateral. They differ by the width of the price band on Uniswap V3 and the pool fee.
- G-UNI V3 DAI/USDC 1:
- Stability Fee = 0.05%
- Trading Fee = 0.01%
- Band Width = fairly tight (roughly $0.002)
- G-UNI V3 DAI/USDC 2:
- Stability Fee = 0.01%
- Trading Fee = 0.05%
- Band Width = extremely tight (roughly $0.0004)
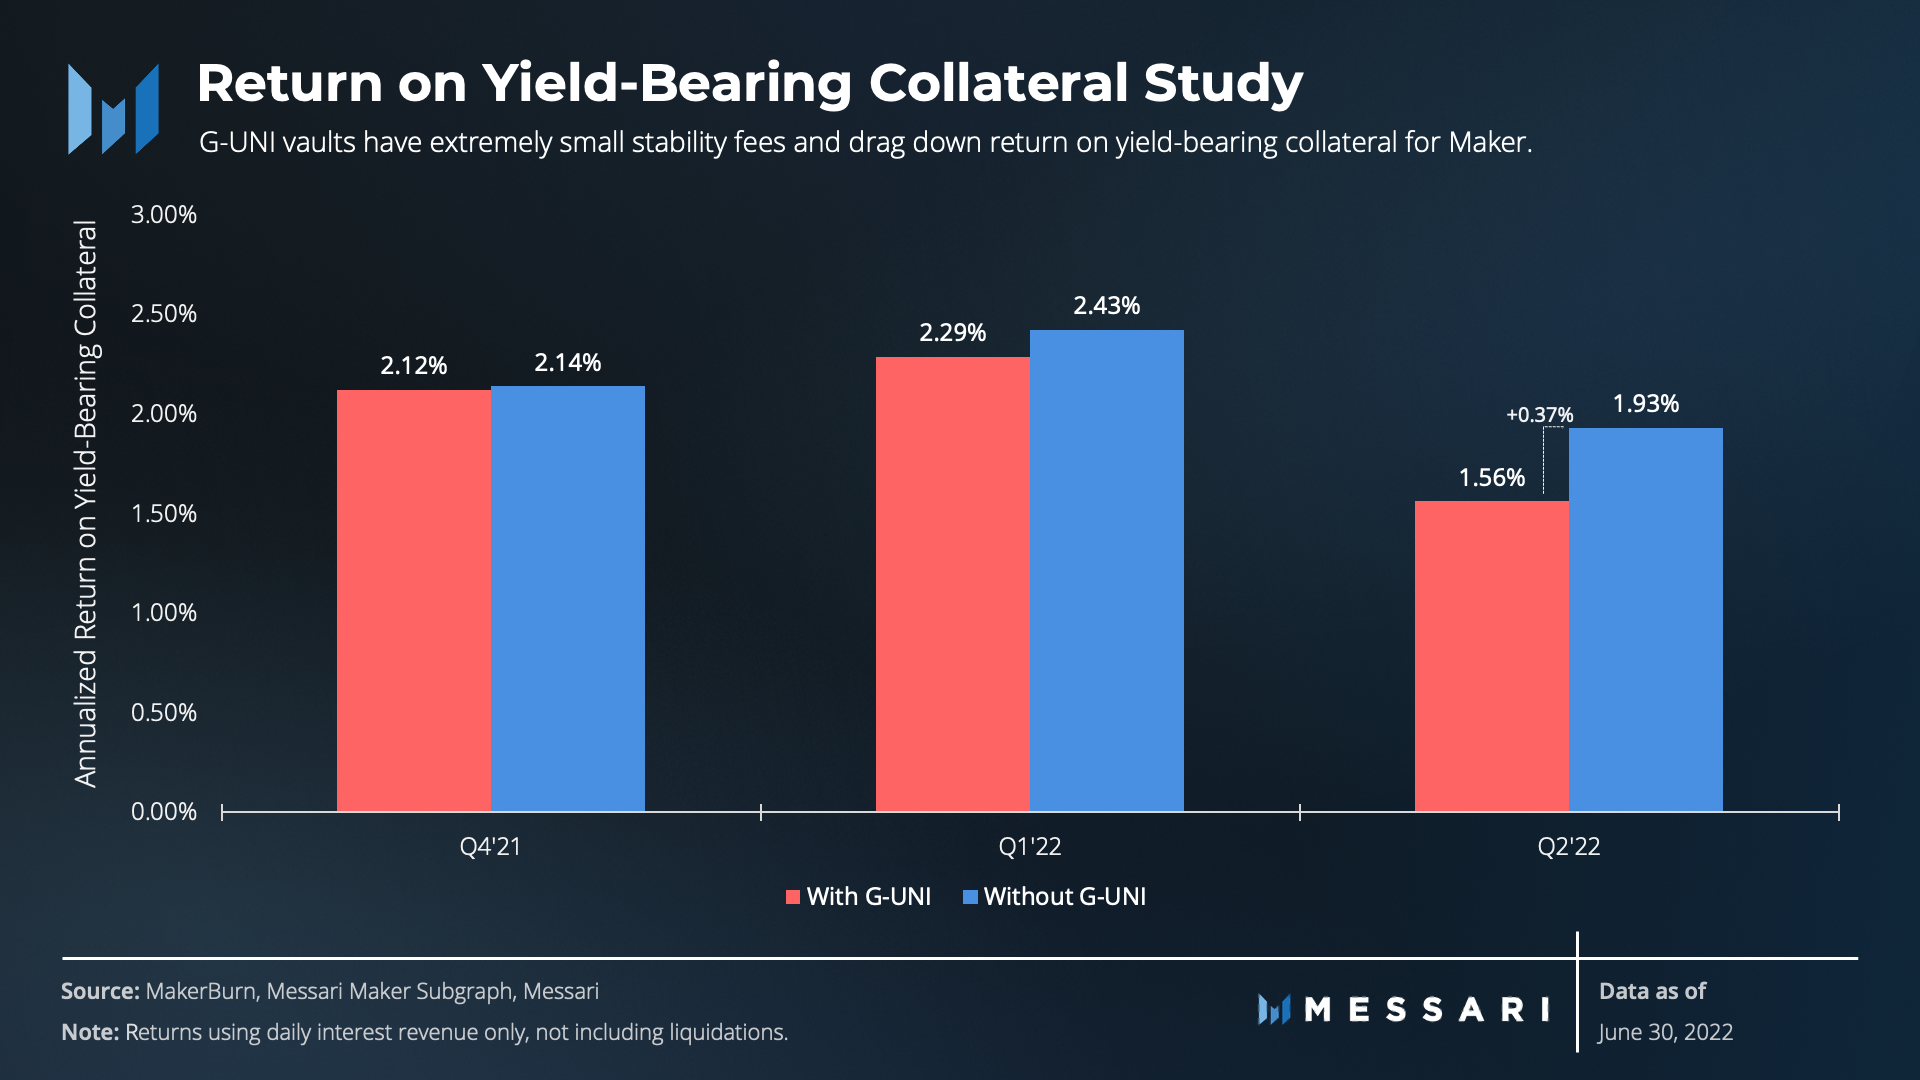
Since the G-UNI LP tokens were approved as collateral in September 2021, stability fees have ranged from 1% to 0%. At 0.01% and 0.05% currently, because of their increased share of yield-bearing collateral, their impact on return on yield-bearing assets was 37 bps in Q2’22, up from 14 bps in Q1’22.
Combined with Maker’s Flash Mint Module, G-UNI collateral can offer attractive leveraged-yield farming opportunities. The Flash Mint Module allows for flash loans (a loan that must be paid back within the same transaction) of DAI for up to $250 million.
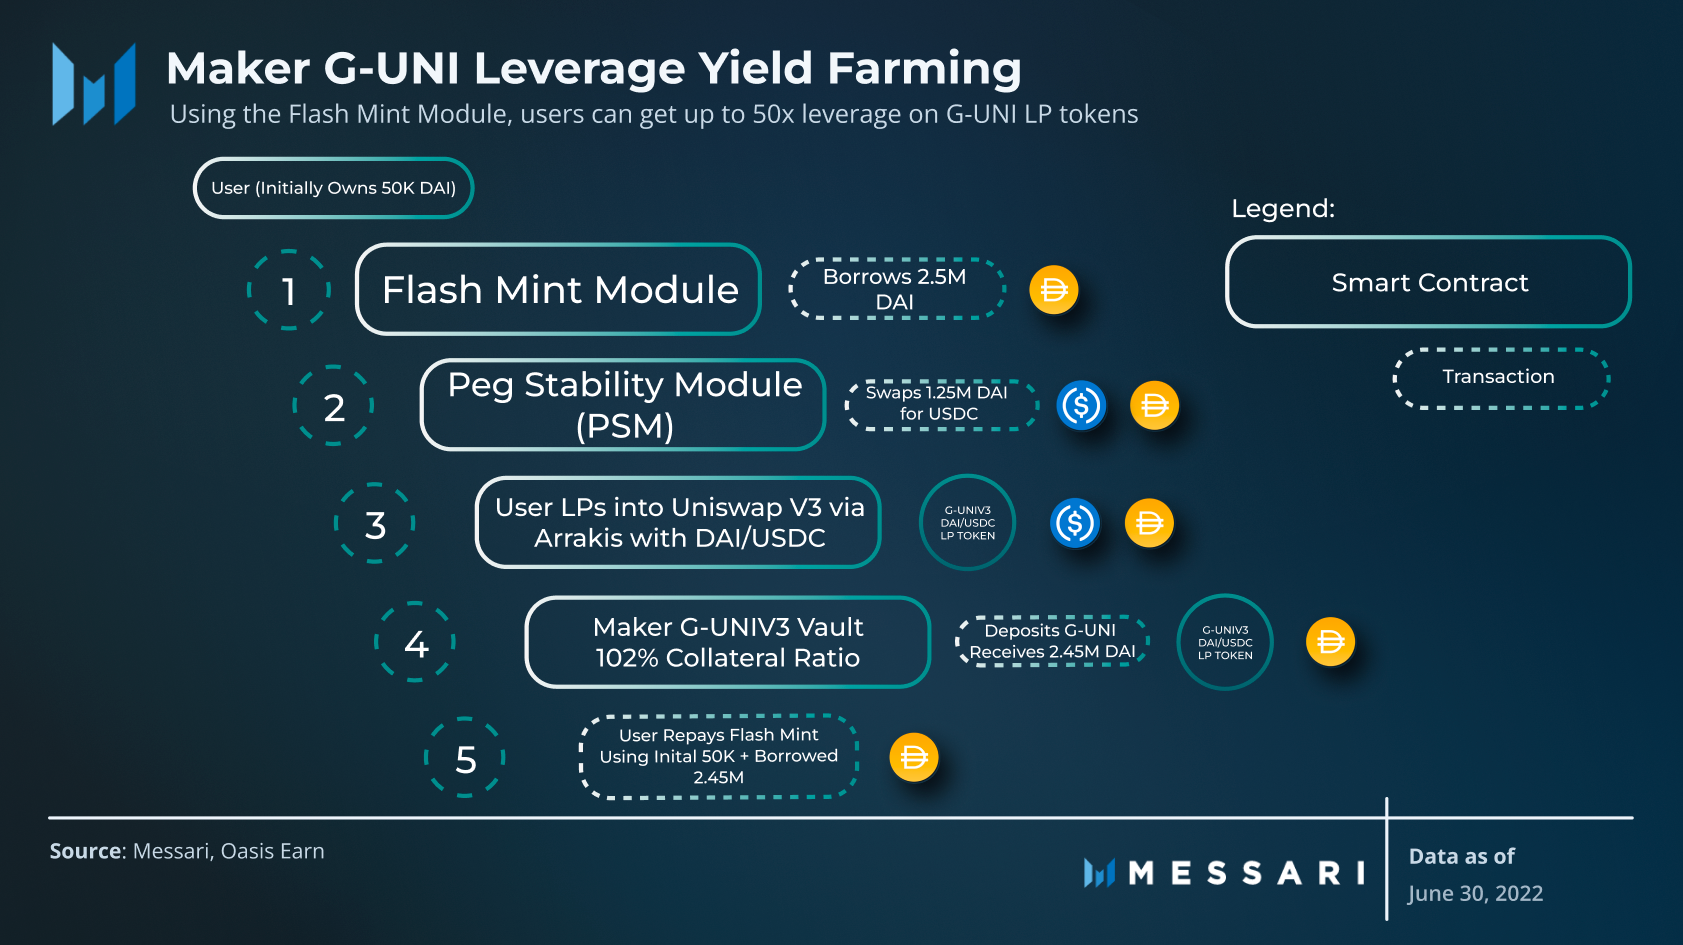
From a user perspective, it is a great trade. The leveraged yield-farming from the Uni pool will likely far outweigh the stability fee owed. From Maker’s balance sheet perspective, it increases total collateral by x amount, increases YBC by 0.98x, reduces PSM reserves by 0.5x, and increases DAI outstanding by 0.48x. Although this reduces margins on YBC, given the low stability fees on G-UNI collateral, it is a much more rewarding allocation of reserve assets.
One could argue that G-UNI collateral should be counted as stability reserves, given it is made up of the same assets that are in Maker’s PSM reserves and DAI Surplus. It also earns a higher yield and is liquid. MakerDAO’s most recent financial report asked how to better use this opportunity to increase protocol revenues.
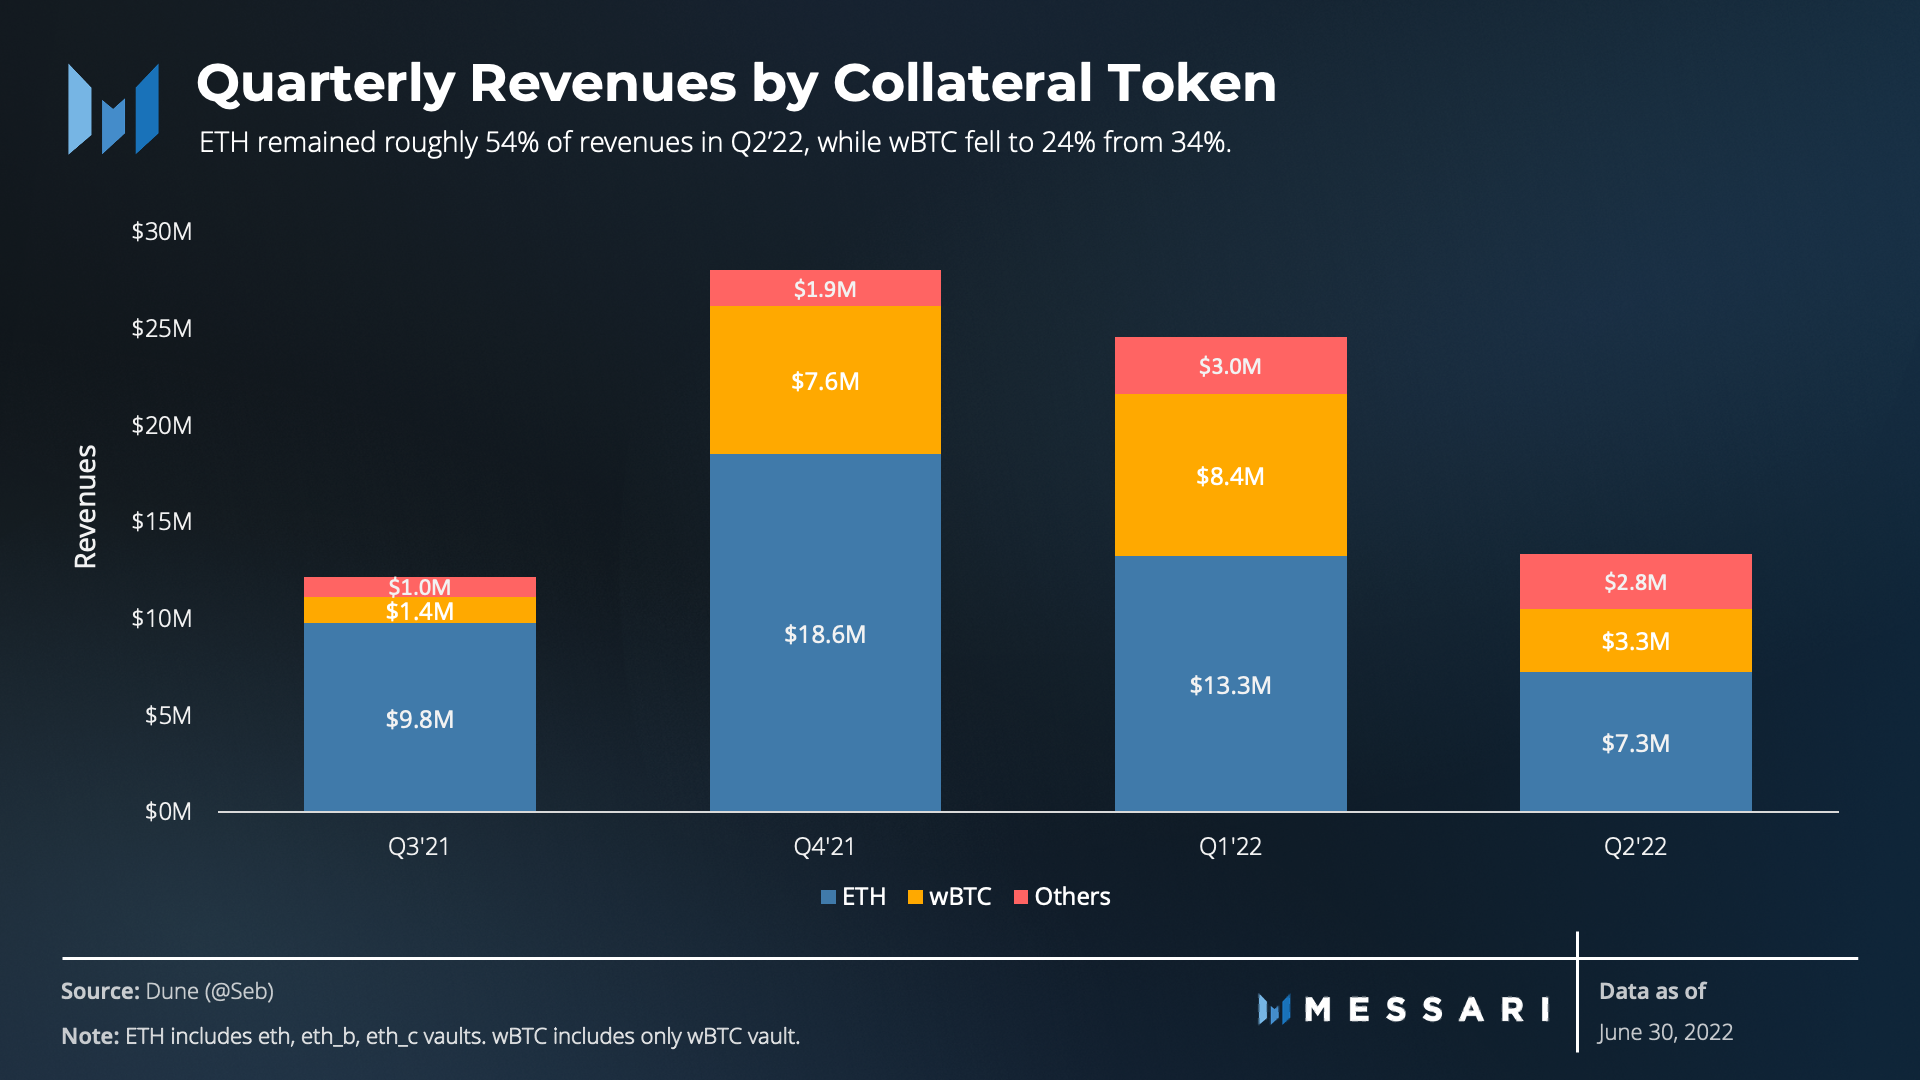
The primary earners for Maker continued to be ETH vaults and the wBTC vault. The two accounted for 79% of revenues in Q2’22, down from 88% in Q1’22 and 93% in Q4’21. The biggest revenue share growers have been stETH, MANA, and Real World Asset (RWA) vaults.
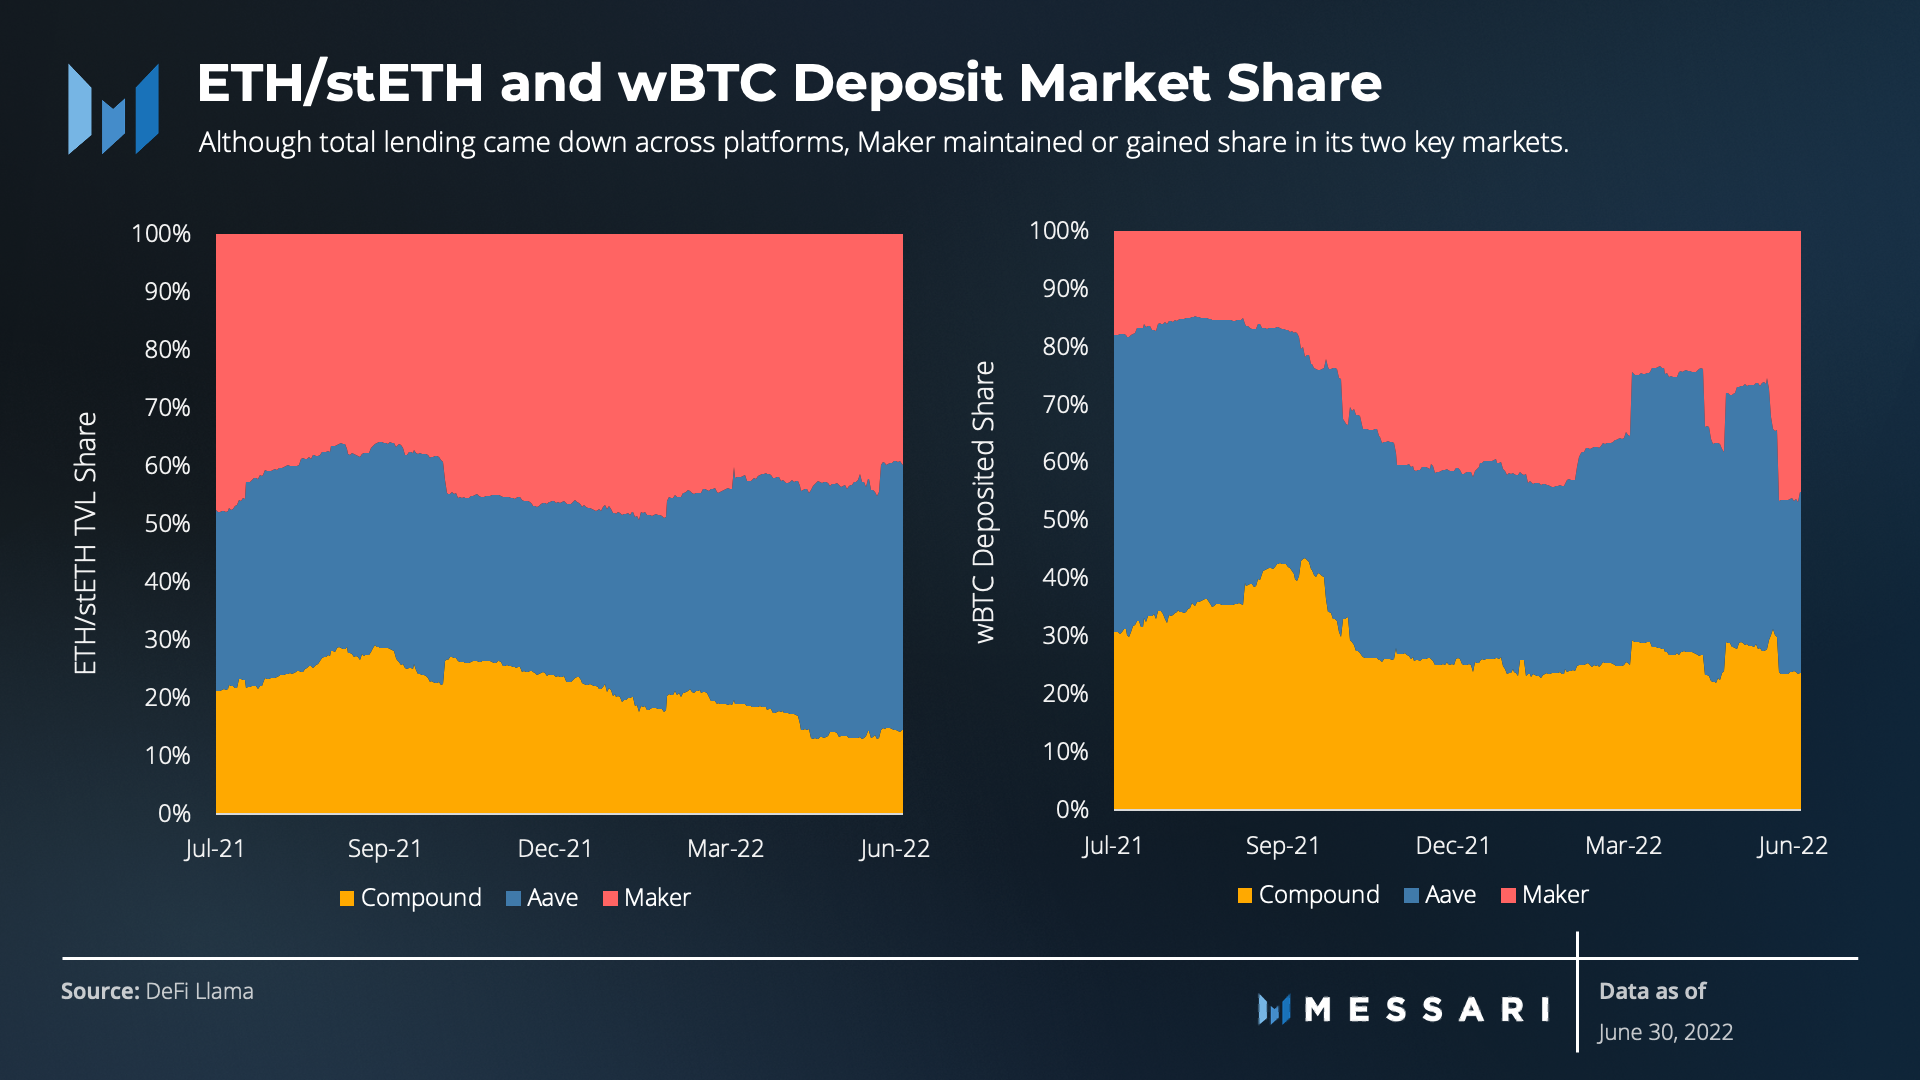
Maker’s market share in ETH and stETH combined lending (measured by TVL) stayed at 40% at the end of Q1’22 to the end of Q2’22. Aave’s share grew rapidly in stETH, but Maker’s grew in ETH, allowing it to maintain its total share. Maker similarly saw gains in the wBTC market, growing its share from 24% to 45% in the quarter.
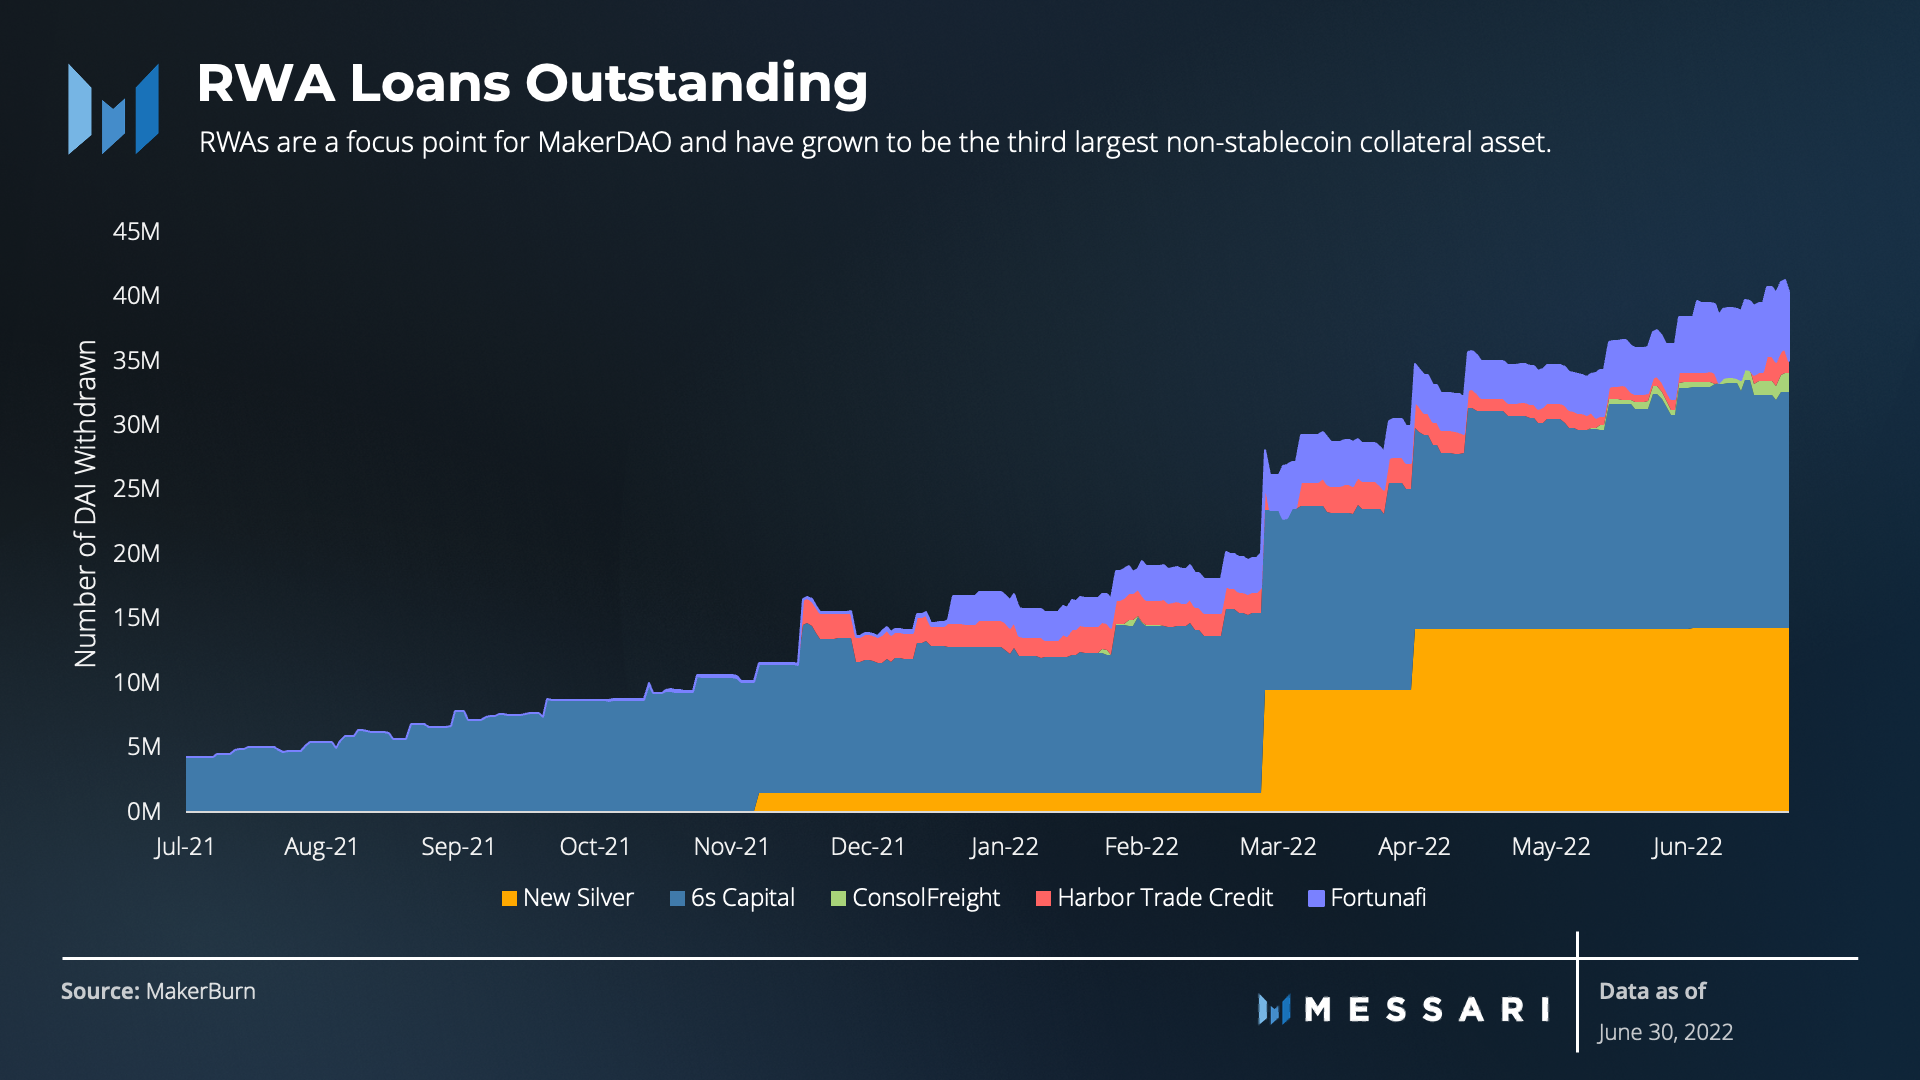
One of MakerDAO’s key growth initiatives is onboarding Real World Assets (RWAs) as new collateral assets. So far, there are five active RWA vaults. In Q2’22, they surpassed 40 million DAI borrowed, becoming the fifth largest DAI borrower as an asset class. The stability fee on RWAs ranges from 3% to 7%. Maker’s real world assets currently make up 10% of the protocol revenue despite only representing 1% of the total value locked.
DAI Stablecoin
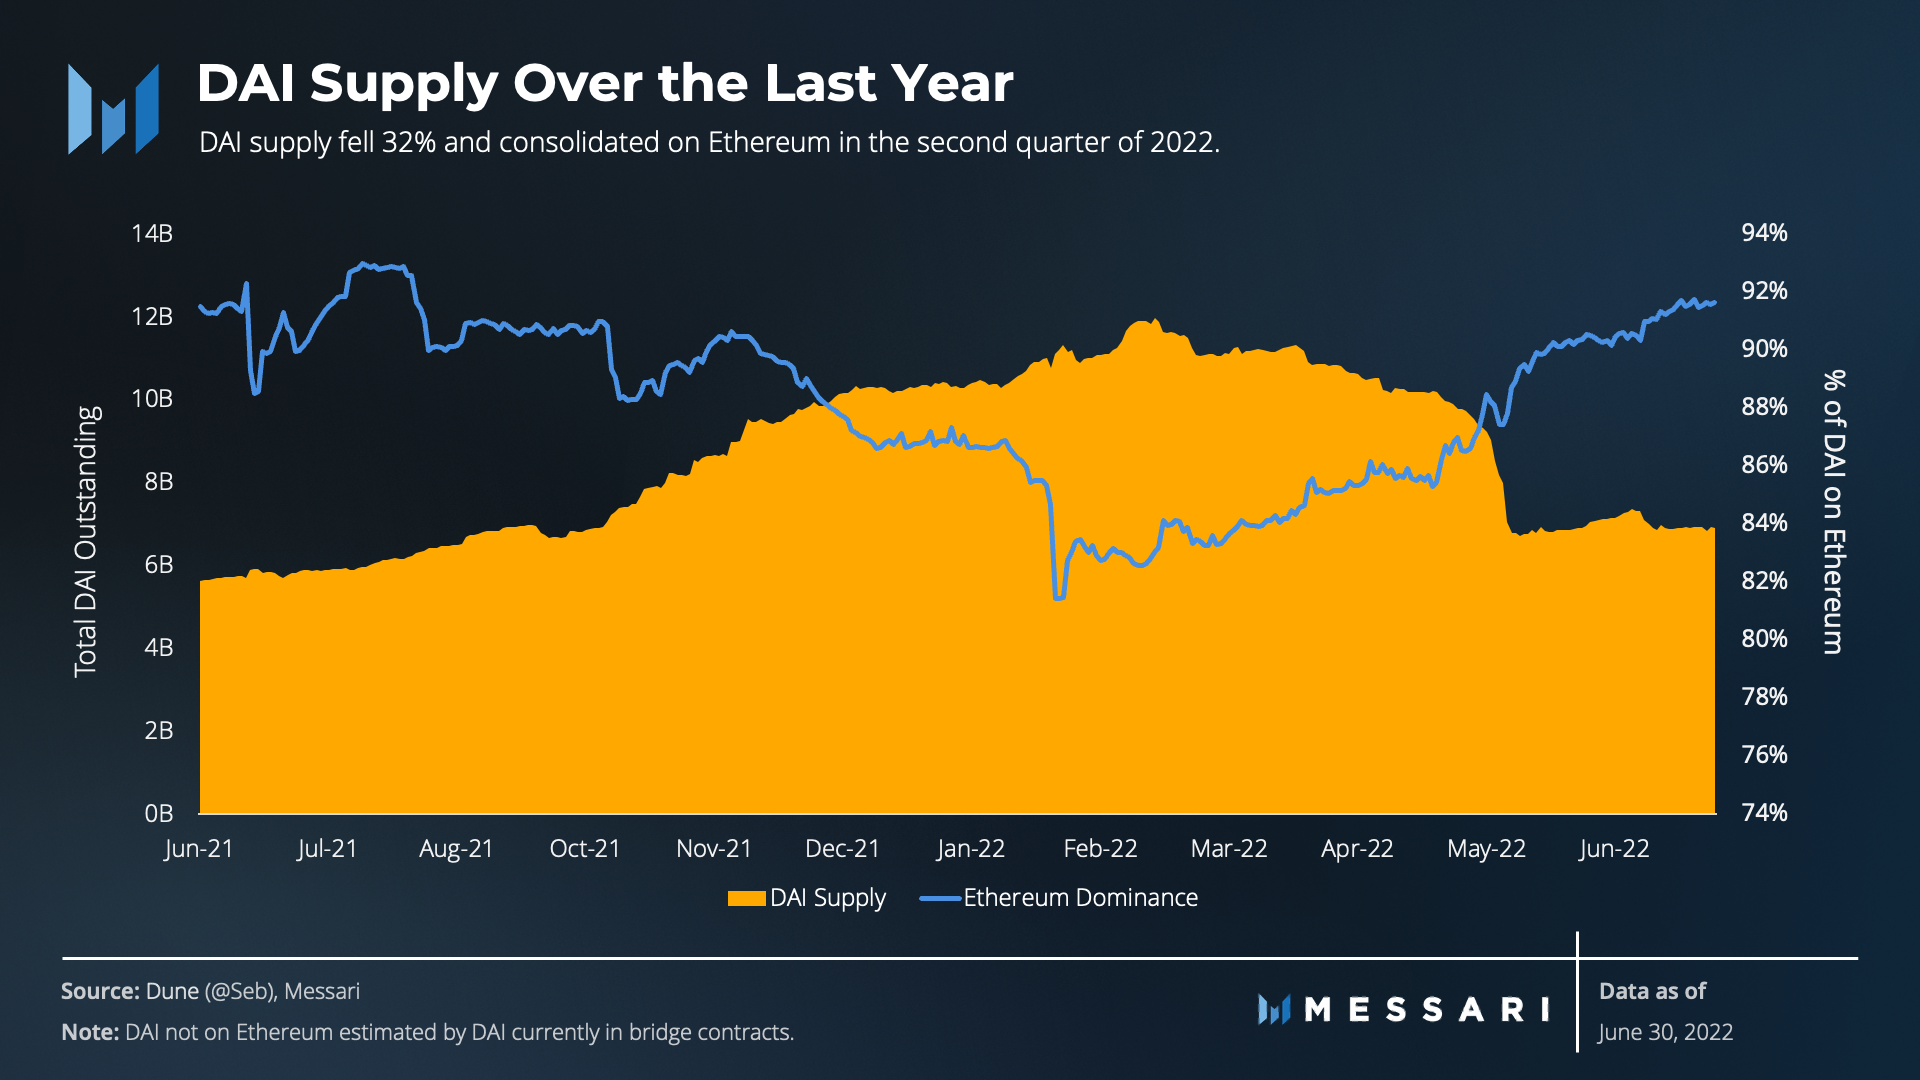
As the crypto ecosystem reduced leverage across the board, DAI supply fell 32% to 6.4 billion last quarter. After starting the quarter with 15% of DAI supply on alternative chains, only 8% was on an Ethereum alternative at the end of the quarter. Avalanche (-76%) and Fantom (-62%) saw the biggest drops in both DAI and percent terms.
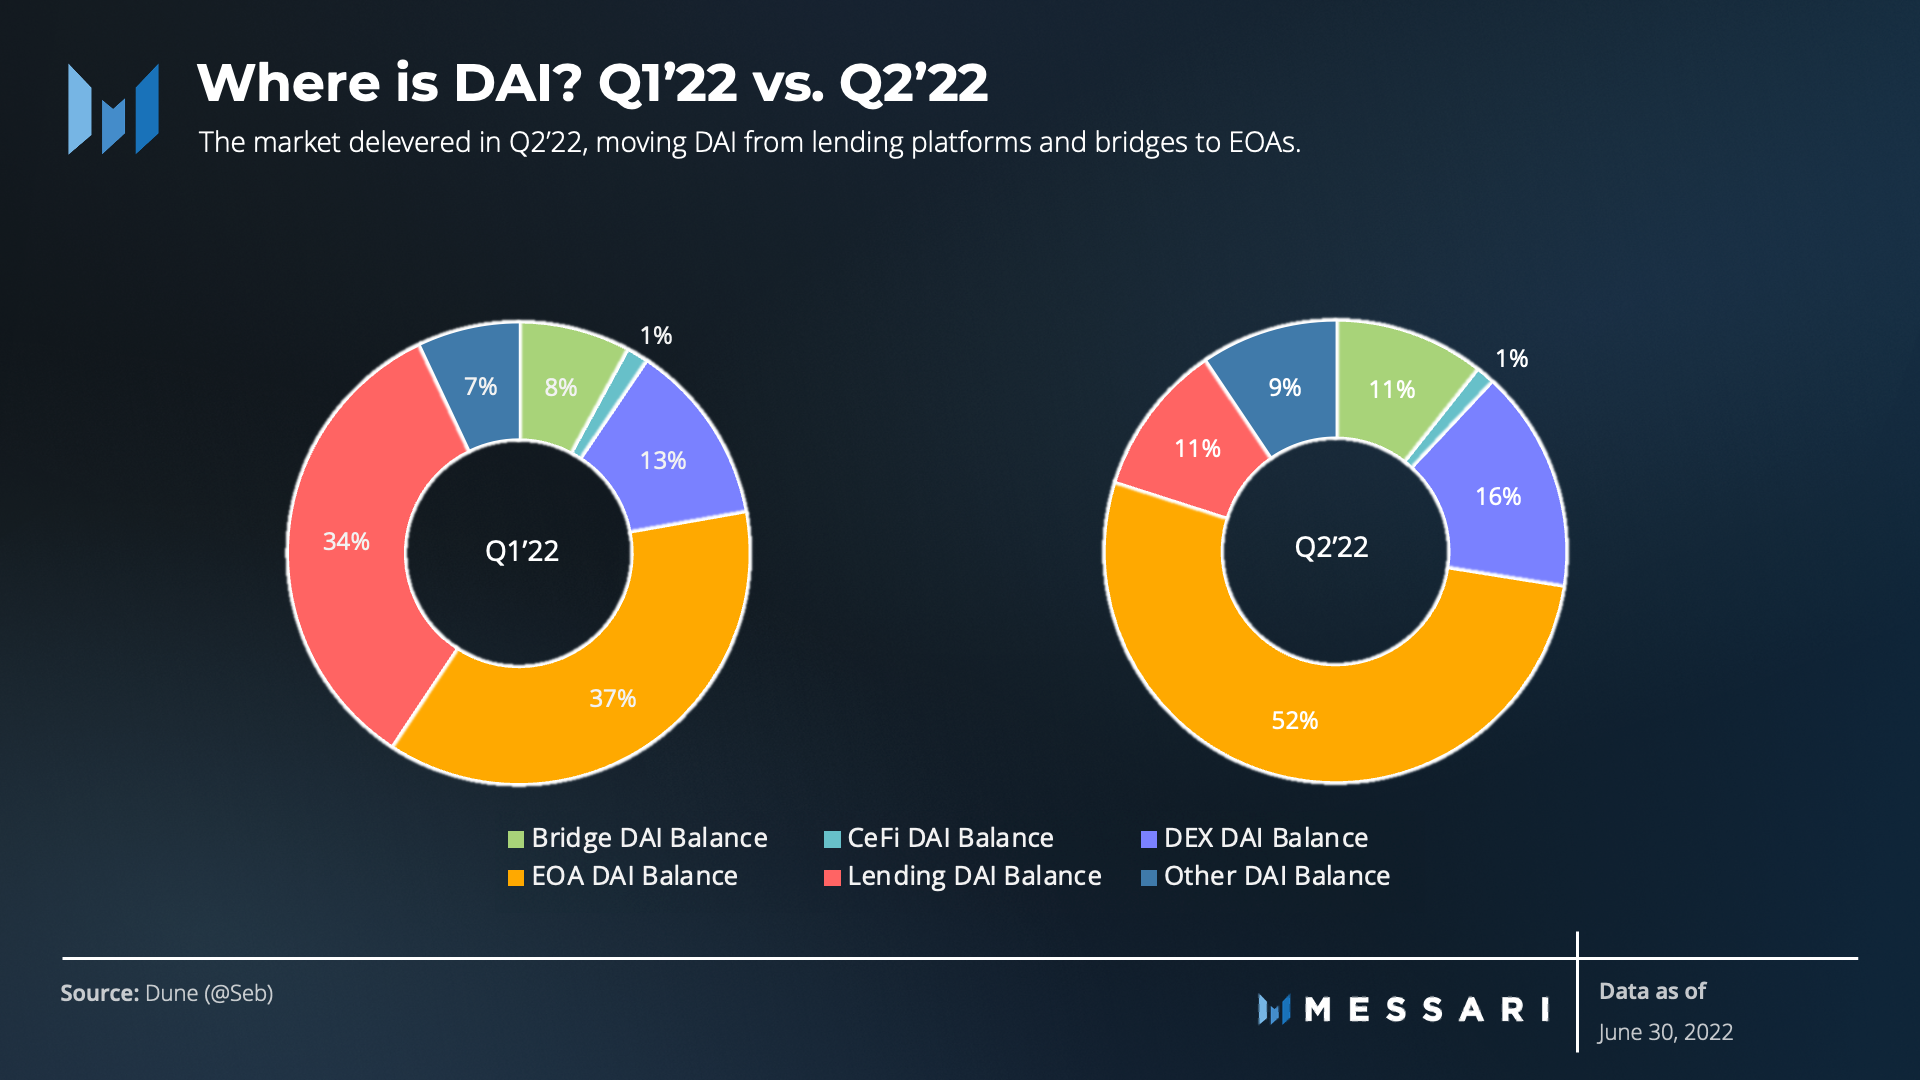
The drop in leverage is most apparent when comparing what types of accounts DAI is in at the end of the first quarter and the second. Over 50% of circulating DAI, roughly 3.5 billion, is in externally owned accounts (EOAs) - assumed to be user wallets - at the end of Q2. Though its share grew, the number of DAI in EOAs is flat quarter-over-quarter. Considering this money receives almost no yield with the DAI Savings Rate (DSR) near zero, the consistent EOA presence shows both the user confidence in DAI as a stablecoin and also the degree of risk-off behavior in markets. The market share changed because of a reduction in balances on lending platforms, decentralized exchanges (DEXs), and bridges.
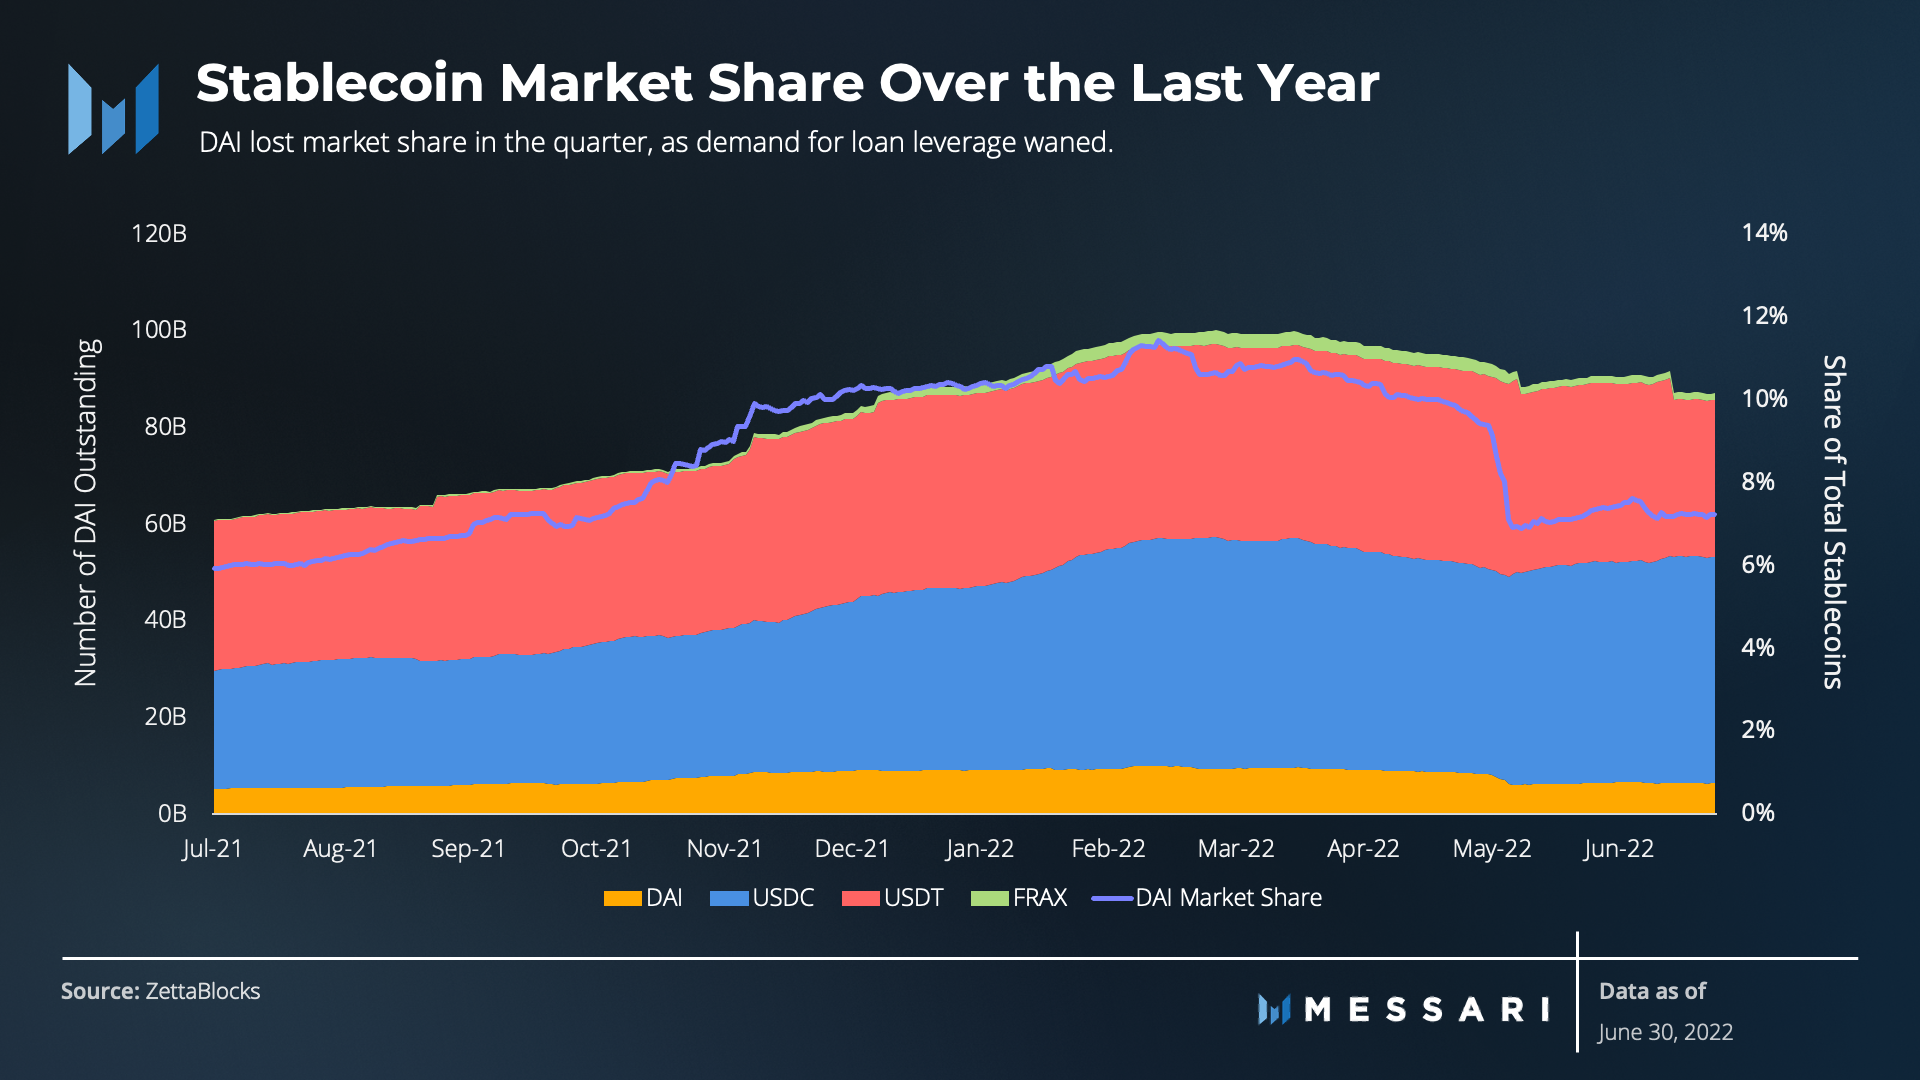
The market deleveraging in May uniquely impacted DAI, the only stablecoin directly tied to loan demand. USDC took market share from all three of the other stablecoins compared here, as it is likely perceived as the safest stablecoin.
Qualitative Analysis
Real World Assets
Over the last quarter, MakerDAO continued expanding the reach of DAI into the traditional finance world. At the end of Q2, a total of 40 million DAI was deployed through five real world asset (RWA) Maker Vaults, four of which use Centrifuge’s infrastructure. Through its Tinlake product, Centrifuge allows users and businesses to tokenize RWAs and access capital against them. Centrifuge’s partnership with Maker deepens liquidity on Tinlake and offers real-world yield to MakerDAO.
Maker’s first and biggest RWA Vault is with New Silver, which tokenizes real-estate-backed loans. In Q2, New Silver added 44 new loans with a total original volume of over $10 million, and they have now used 18.2 million of the 20 million DAI loan available to them. New Silver is currently working to propose a formal debt ceiling increase to around 100–150 million DAI.
Consolfreight tokenizes cargo and freight invoices. In Q2, they financed a shipment of Australian beef from Brisbane to Hong Kong using liquidity from their vault. Mastercard Provenance, the company’s blockchain traceability solution, tracked the whole process on-chain.
Messari Analyst Ally Zach described the remaining vaults as follows:
- 6s Capital: secured loans for commercial real estate development
- Harbor Trade Credit: tokenizing and securing short-term global trade receivables
- Fortunafi: yield and lending protocol for tokenized cash flowing assets
The Real World Finance Core Unit and the Legal and Transaction Services Core Unit worked in Q2 to formalize RWA processes and structure. In April, they standardized the review process for onboarding RWA collateral to be as rigorous and transparent as it is for crypto-native collateral. In May, they combined with the Centrifuge team to complete the Trust Indenture Agreement to scale RWA onboarding via the Centrifuge protocol.
The three RWA vaults closest to launch are with Huntingdon Valley Bank (HVB), Societe Generale FORGE (SG FORGE), and Monetalis:
- HVB is a regulated Pennsylvania bank. Approved in an on-chain poll in early July, the proposed vault will have a debt ceiling of 100 million DAI. It will mark the first integration of collateral from a U.S. bank into DeFi.
- Under the arrangement, HVB will originate loans and sell up to 50% of each loan to a trust established on behalf of MakerDAO. In March, HVB estimated a conservative expected net yield to MakerDAO of 3%.
- Risk mitigating factors include: the inclusion of only loans that are rated “6” or better by HVB’s internal credit assessment, which is audited and monitored by the Federal Reserve; a third-party reviewer(Ankura Trust Company) MakerDAO trust purchases; and the fact that HVB will also have exposure to all loans originated.
- The Societe Generale Group (SocGen) is a leading financial services firm. Their subsidiary, SG FORGE, is dedicated to digital assets and blockchain-based projects. In July, on-chain polling approved a vault with a 30 million DAI debt ceiling. The loan will be backed by 40 million euros worth of digital covered bonds (OFH security-tokens) that are backed by a pool of AAA-rated French home loans.
- Monetalis is a fintech startup focused on bridging TradFi and DeFi. An on-chain poll in May approved the creation of a RWA Vault for Maker to invest 500 million DAI from its treasury in liquid and low-risk bond strategies held by a trust arranged by Monetalis. The original proposal sought to accelerate the governance process but some community members believed letting a relatively new venture have control over so much money was too risky. Adding to the drama, MakerDAO’s founder Rune Christensen disclosed that he was personally invested in Monetalis, while pushing for the original proposal to go through. Rune later announced that he would give away his shares of Monetalis because it became too much of a distraction.
Layer-2 Bridge Building
Layer-2s (L2s) offer MakerDAO a significant growth vector while still inheriting the security of the Ethereum ecosystem. First, Maker needs a solution for moving DAI onto, off of, and between Ethereum L2s.
Many third-party bridges function through a mint-and-burn mechanism with liquidity pools on either side of the bridge. They create a wrapped asset on one side of the bridge and lock the “true” asset on the other side in a pool. This setup is suboptimal, as exploits that steal the “true” assets leave the wrapped versions unbacked and valueless. It also fragments liquidity, since the wrapped versions of the same asset from different bridges are not completely equal.
To address this, MakerDAO is building its own bridge infrastructure for Optimism, Arbitrum, and Starknet. It had already released a transfer portal from Ethereum to optimistic-L2s. For Starknet, MakerDAO launched one this quarter.
In May, an executive vote made a necessary technical update to deploy Fast Withdrawals: MakerDAO’s solution to immediately move DAI from L2s back to Ethereum instead of waiting several hours with zk-rollups or a week with optimistic rollups for transactions to finalize. The Protocol Engineering Core Unit (PECU) aims to release Fast Withdrawals in early August.
Maker Teleport will be the final piece to the L2 bridge solution, allowing for DAI transfers between Ethereum L2s. In Q2, the community voted to add a 1 bps fee to Maker Teleport upon launch. This fee allows the protocol to earn revenue from fees while still remaining cheaper than most other bridges. PECU plans on releasing a more detailed roadmap for Teleport in the near future.
Roadmap: Collateral Optimization
A large portion of MakerDAO’s collateral is currently in stablecoins (over 3.7 billion) in their PSM. Over the past quarter, there has been much discussion about reallocating that capital to pursue a more aggressive growth strategy. The Strategic Finance Core Unit has identified several potential asset types to grow and add to the treasury:
- Real World Assets (RWA): RWA Vaults enable MakerDAO to expand beyond the still relatively small crypto market.
- Short-term bonds: Short-term bonds give MakerDAO’s treasury exposure to yield without incurring smart contract or other crypto-related risks. They do create different centralization and regulatory risks, compared to the USDC already on the balance sheet.
- Crypto-backed loans: Crypto-backed loans are at the core of Maker’s protocol. The Multi-Collateral DAI (MCD) system allows users to borrow DAI by depositing approved collateral into a vault. The DAO’s tolerance to onboard right-tail assets and crypto’s overall maturity and growth will determine the pace of crypto-loan growth.
- DeFi Money Markets: Maker’s D3M allows other DeFi protocols to mint DAI based on a maximum variable borrow rate. The first D3M launched on Aave before being temporarily disabled due to an active Aave governance proposal that MakerDAO deemed risky. A Compound D3M is currently under audit, with a response expected in July. There have also been talks of a Maple and Rari Fuse D3M.
- ETH: At the end of May, an on-chain poll successfully passed for the Core Units to begin creating a formal proposal for adding ETH to MakerDAO’s balance sheet. Those in favor argue that: ETH will be a productive asset and sound investment post-Merge; Maker should be further aligned with Ethereum; and ETH can be used for existing operational costs requiring ETH payments such as gas fees and oracle costs. Those against the proposal believe that Maker is already aligned enough with Ethereum and ETH is too risky and volatile an asset for collateral.
Some MKR holders prefer to buy back and burn MKR with excess DAI. The MKR burn mechanism used to be central to the protocol but was temporarily stopped at the end of January until it could be more efficiently designed. After some debate, an on-chain poll successfully passed in June to buyback and burn MKR using 3 million DAI over three months. As a result, MakerDAO can keep almost all of its excess supply of DAI for continued growth and risk mitigation, while reassuring MKR holders that the burn remains an important part of MakerDAO.
Core Unit Additions and Updates
Core Units are integral to MakerDAO’s structure. In early May, an executive vote added and began payment to an Events Core Unit. It will host events at crypto conferences to grow Maker’s brand and increase adoption of its protocol. The same executive vote initiated payments to the Data Insights Core Unit (DIN), which was added at the end of 2021. It is responsible for providing datasets covering the Maker Protocol to the DAO. The updated mandate allows DIN to focus on building datasets that will aid in Maker’s expansion to Layer-2s and RWAs.
Unprecedented Voting Turnout
In mid-June, three ratification polls failed with a higher voter turnout than any previous MakerDAO poll. The proposals sought to establish small groups who could experiment and grow Maker without being bogged down by the governance process like other MakerDAO groups and Core Units. While some were in favor of creating fast-acting entities, others were worried about placing too much power into the hands of a few people.
The proposal to add a Lending Oversight Core Unit (LOVE) garnered the most votes (294,000 MKR) and controversy. Luca Prosperi, a MakerDAO community member and contributor, sought to establish and lead a Core Unit which had the role of overseeing, supporting, and auditing other Core Units in the onboarding of real-world and other complex assets. The vote has been described as VC firms versus the old guard. With support from many VC firms, the vote looked likely to pass until Rune re-delegated his MKR and Nikolai Mushegian, Maker’s co-founder who hasn’t been formally involved with the project for years, came back to help defeat it.
Visions for Growth
This quarter, the MakerDAO governance forum was ripe with posts and discussions on visions for the protocol and DAO’s future. Many debates centered around how aggressively MakerDAO should grow the protocol. Some proposed raising funds. Others focused on the role of Core Units and the governance process. Two posts by Rune and Hasu, a MakerDAO delegate, garnered a lot of attention in particular.
In the first post, Rune posted a five-part series titled “The Endgame Plan,” in which he aims to give MakerDAO a clearer and more efficient structure. Rune’s design features a minimalist Maker core protocol surrounded by specialized MetaDAOs. Each MetaDAO would have its own structure and processes that are optimized for their specialization. Additionally, MetaDAOs would have their own token, which would bring value back to the Maker core and MKR holders. Another key feature is the organization of governance with voter committees and further empowered delegates.
In his post, Hasu proposes that the community should create a constitution for Maker, outlining MakerDAO’s vision, mandates, and roles of key actors. A council would then be established and would form the high-level strategy around achieving the vision defined in the constitution. Mandated actors would focus on more specific decisions based on the council’s strategy, and Core Unit collaborators would implement those decisions. MKR holders and delegates would hold the system and its participants accountable at each step.
Other Governance Decisions
April 4, 2022 - Core Unit Budget Distributions and Vesting Streams Setup, Gelato Keeper Network Budget Steam Setup
The proposal made payments to Core Units. The proposal also onboarded Gelato Network, which enables developers to automate arbitrary smart contracts, with a payment stream of 183,000 DAI over six months.
April 11, 2022 - MOMC Parameter Changes, CRVV1ETHSTETH-A Debt Ceiling Increase, Recognized Delegate Compensation, ETHAmsterdam Event SPF Funding
The proposal made 10 parameter changes across seven markets per recommendation from the MakerDAO Open Market Committee. The proposal also distributed DAI to nine Recognized Delegates for compensation and to the ETHAmsterdam Special Purpose Fund for MakerDAO’s event at the conference.
April 13, 2022 - Emergency Executive Vote to Freeze CRVV1ETHSTETH-A Oracle
The emergency proposal froze the Curve stETH/ETH oracle due to technical issues. The Protocol Engineering Core Unit identified the potential vulnerability and successfully replaced the oracle in an executive vote ending on April 27.
April 19, 2022 - Offload TUSD and DAI Transfers
The proposal offboarded TUSD collateral from the protocol via liquidations under the defined parameters. The proposal transferred DAI to the Growth Core Unit multisig and to the Ambassadors Program, which aims to grow the MakerDAO community in non-English speaking communities. Finally, the proposal replaced the contract for the Gelato Keeper Network payment stream which had a minor bug in it.
April 27, 2022 - Oracle Whitelist Additions, Replacing the Curve stETH/ETH Oracle
The proposal gave Oasis.app whitelist access to eight OSM Oracles. This access will allow Oasis.app’s new automation features. The proposal also replaced the Curve stETH/ETH oracle which was frozen on April 13 due to technical issues.
May 4, 2022 - Core Unit Budget Distributions
The proposal made payments to Core Units per their successful budget proposals.
May 16, 2022 - Recognized Delegate Payments, Lowering WBTC Stability Fees, and Onboarding wstETH-B
The proposal distributed 79,647 DAI total to ten Recognized Delegates for compensation. The proposal also lowered the WBTC-A and WBTC-B Stability Fees to increase usages of these vaults. Lastly, the Risk Core Unit successfully proposed onboarding wstETH-B as a vault type in order to increase market share of stETH collateralized debt.
May 23, 2022 - Foundation L2 Work, Authorize New Flash Mint Module, MKR Vesting
The proposal transferred 541.47 MKR to the Sustainable Ecosystem Scaling Core Unit, following the vesting schedule approved in their 2021 budget proposal. The proposal also makes technical additions and changes that will help bring canonical DAI capability onto Layer-2s. Lastly, a new Flash Mint Module was deployed in order to permanently resolve a vulnerability.
May 29, 2022 - Raise the ESM Minimum Threshold, MKR Vesting, Adjust the lid Parameter on the Rate-limited Flapper
The proposal increased the minimum amount to trigger an emergency shutdown through the Emergency Shutdown Module from 100,000 to 150,000 MRK. This reduces the threat of a hostile emergency shutdown. The proposal also made payments to Core Units. The proposal decreased the amount of DAI that can be auctioned in flap auctions at once from 150,000 to 30,000. Flap auctions sell a certain amount of the system’s excess DAI accumulated from fees for MKR, which is then burned. The update changes the limit of parallel flap auctions from five to one, which will help steady the burn rate during extreme liquidation events.
June 10, 2022 - Parameter Changes, Starknet Bridge Limit and Authority Changes, Recognized Delegate Compensation, SH-001 Budget Distribution
The proposal made six parameter changes to five markets and offboarded five vaults. The StarkNet Engineering Core Unit successfully proposed increasing the DAI Bridge Limit from 100,000 to 200,000 DAI and making technical changes to allow the bridge to be shut down with an executive vote without having to wait for the typical Governance Pause Delay.
June 17, 2022 - Temporarily Disable the Aave DAI Direct Deposit Module
The proposal temporarily disabled the Aave DAI Direct Deposit Module. The Risk Core Unit advised the change, following an Aave governance proposal to increase the stETH liquidation threshold to 90%.
Closing Summary
Although the bear market and UST collapse negatively impacted Maker’s earnings in Q2’22, the protocol maintained or gained market share in its two largest crypto lending markets (ETH and wBTC). G-UNI LP tokens rose in the collateral ranks this quarter, and this trend should continue as long as MakerDAO continues to increase the DAI cap. RWAs continue to be an attractive growth opportunity for MakerDAO, despite some drama in the process. The future design of governance at MakerDAO is a hot topic, as two strong leaders pitch ideas to tokenholders.
On September 22, 2022, the U.S. Commodity Futures Trading Commission stated that DAI is a "commodity." A couple notes: (1) Messari does not provide financial or trading advice - our services are for informational purposes only; and (2) Messari's services are impersonal - do your own due diligence. Please refer to our Terms of Service for more info.
Let us know what you loved about the report, what may be missing, or share any other feedback by filling out this short form. All responses are subject to our Privacy Policy and Terms of Service.
All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Nothing contained in this report is a recommendation or suggestion, directly or indirectly, to buy, sell, make, or hold any investment, loan, commodity, or security, or to undertake any investment or trading strategy with respect to any investment, loan, commodity, security, or any issuer. This report should not be construed as an offer to sell or the solicitation of an offer to buy any security or commodity. Messari does not guarantee the sequence, accuracy, completeness, or timeliness of any information provided in this report. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Before joining Messari as a Senior Research Analyst, John worked in Equity Derivatives on the buy-side and sell-side for over five years. He studied macroeconomics and markets for almost a decade. Now, John spends time thinking about token design, DeFi protocols, and governance.
Peter is a Research Analyst in Protocol Services focused on Layer-1s. He recently graduated from Boston College where he studied economics and computer science and led the school's blockchain club.
Mentioned Assets