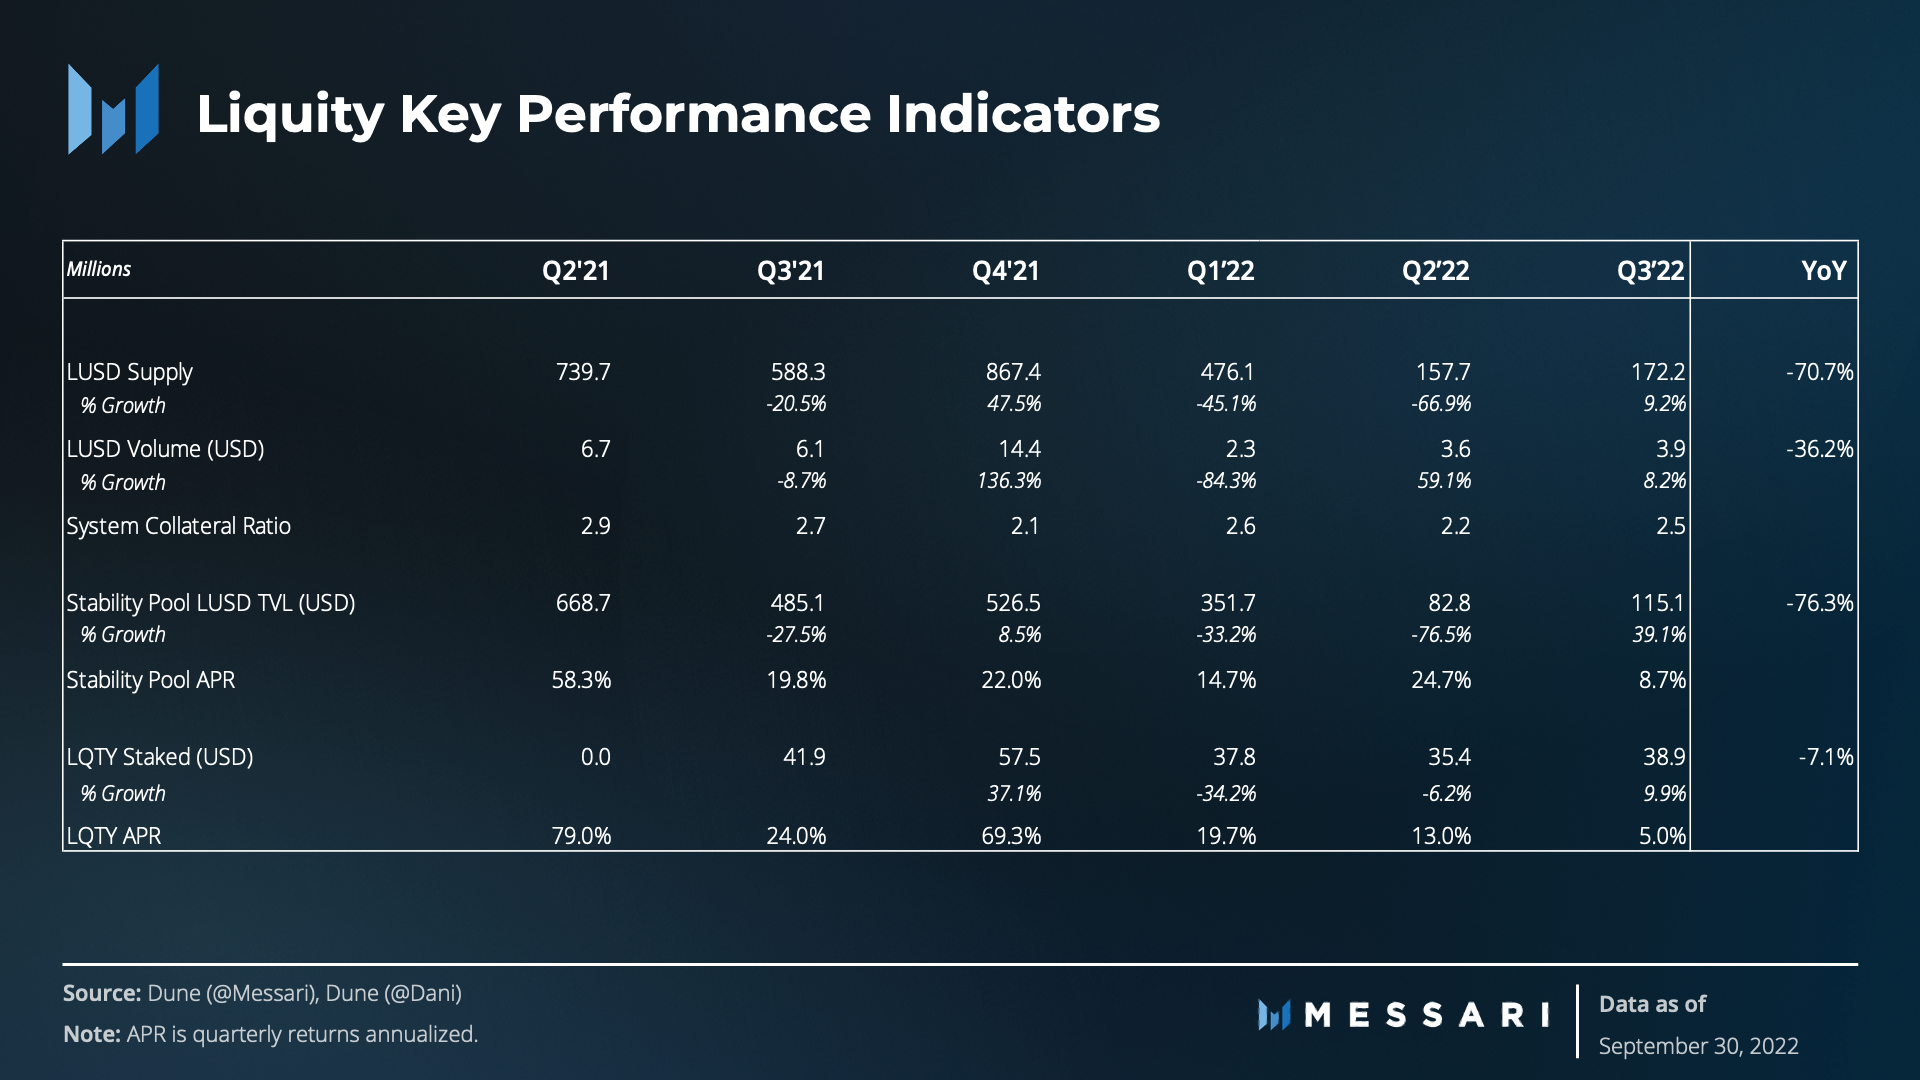
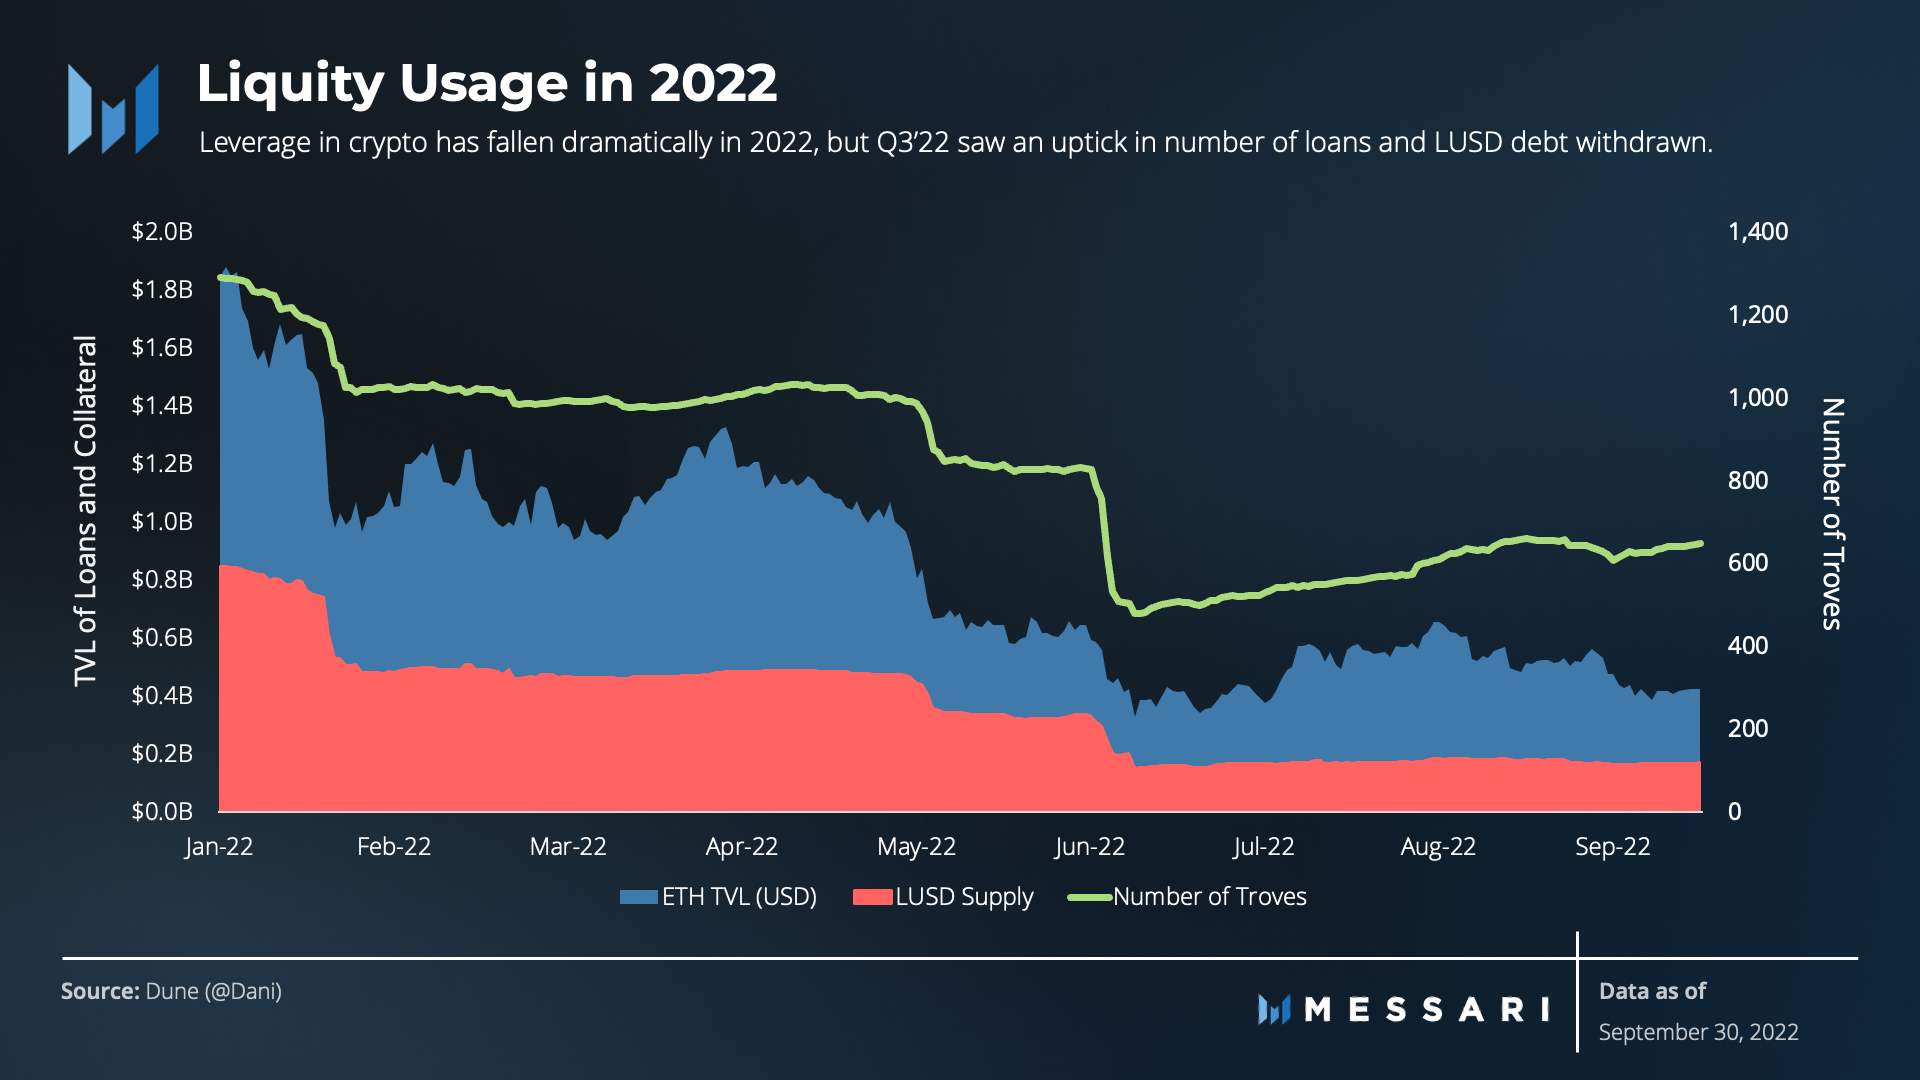
After the huge reduction in leverage in Q2, uncertain conditions did not incite much new borrowing in Q3. LUSD supply increased only 9% in the quarter.
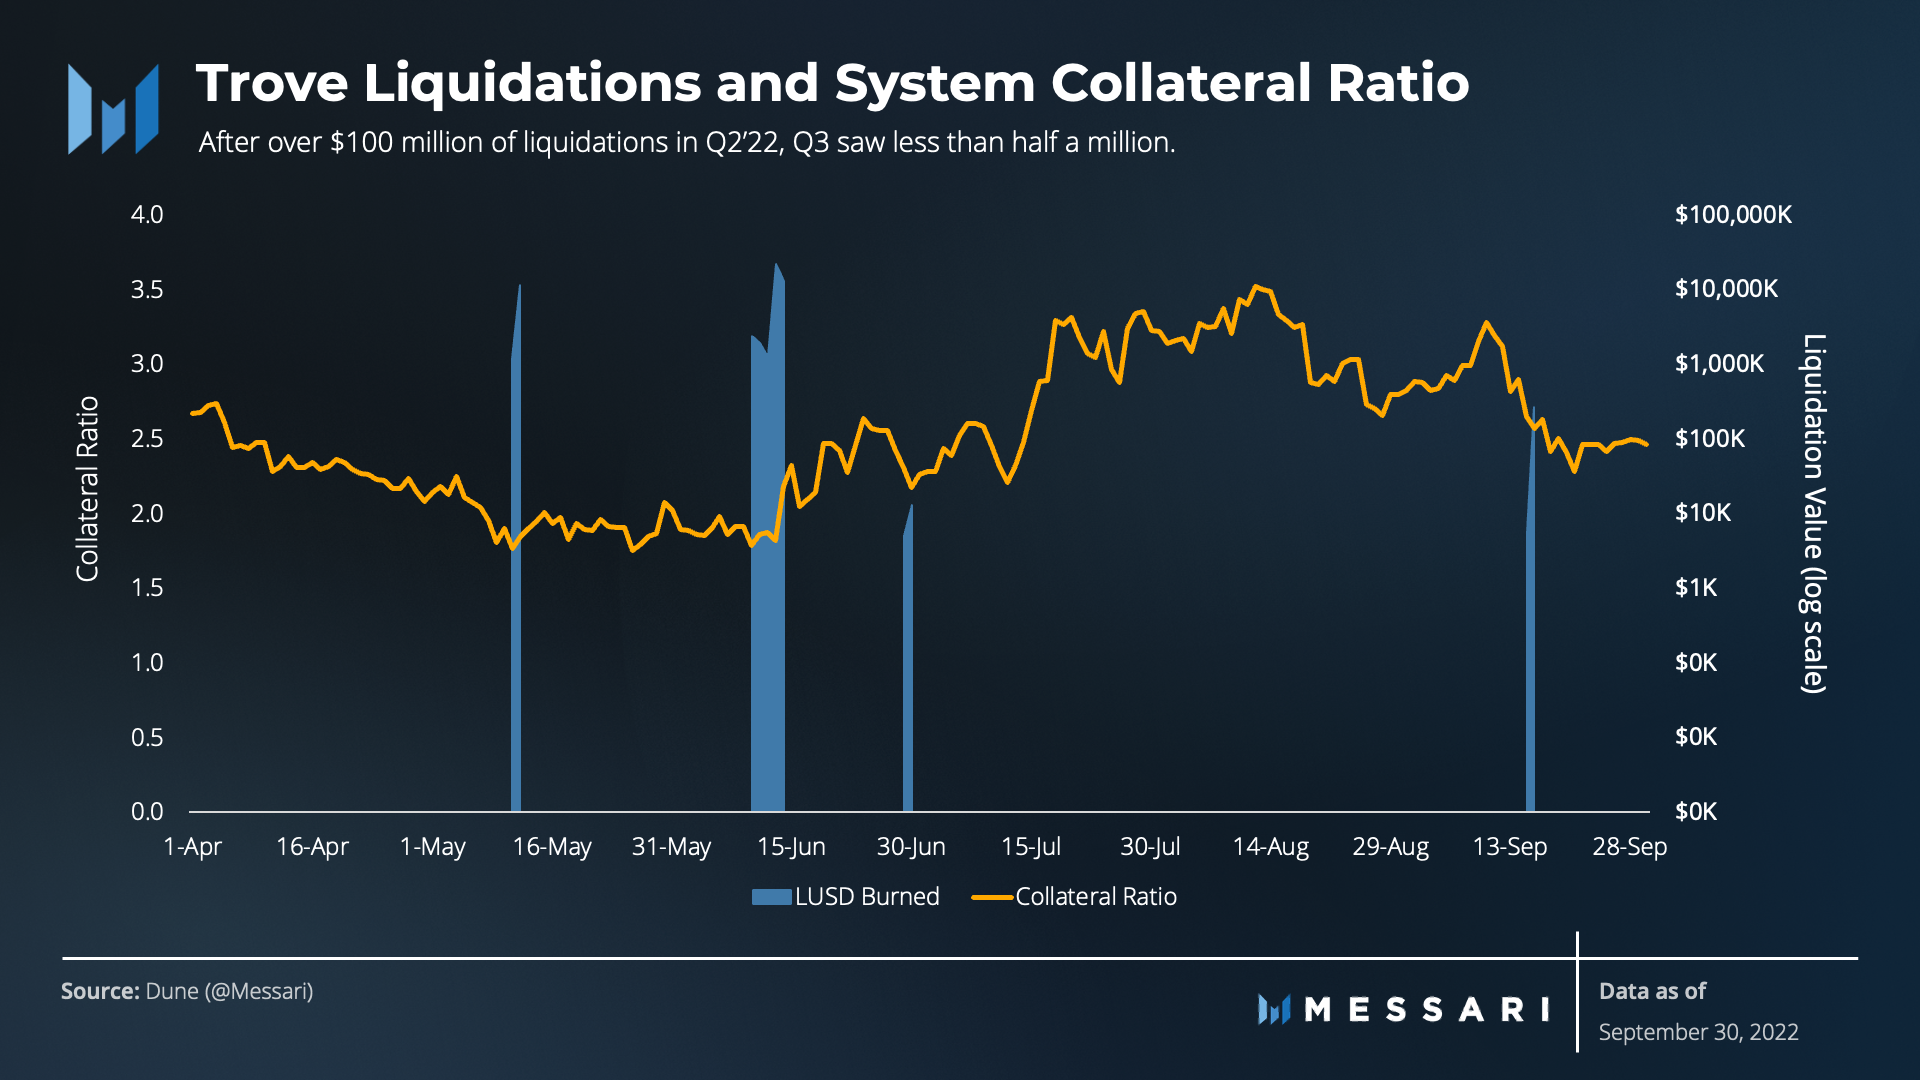
The system collateral ratio benefited from the rise in ETH, moving to 2.54 from 2.17. In ETH terms, borrowers continued to reduce exposure.
The big yields in Q2’22 attracted participants to the protocol in Q3. Unfortunately, a less volatile market led to the lowest yields for both LQTY stakers and Stability Pool Depositors since inception.
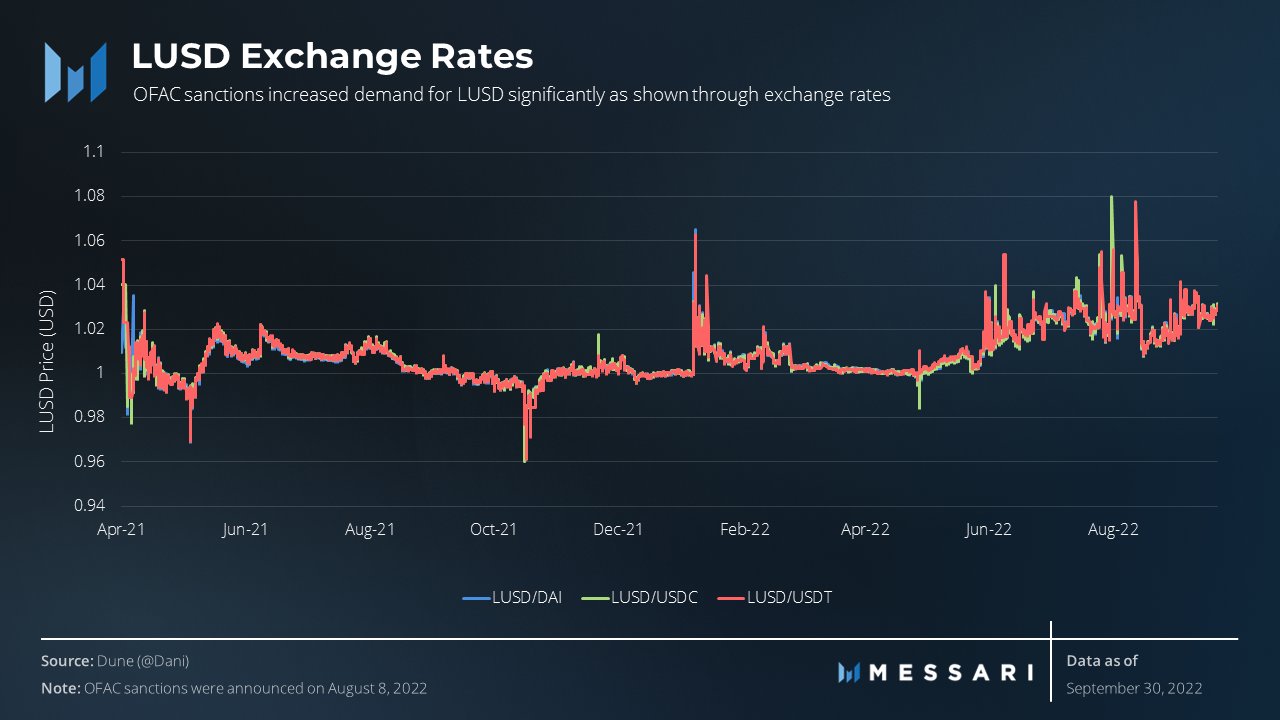
LUSD price was mostly trading above the $1 soft peg this quarter, as demand increased after OFAC sanctions brought decentralization to the forefront.
Chicken Bonds is the latest innovation from the team that launched Liquity. This tool helps protocols gain protocol owned liquidity without token emissions. A Liquity version launched in October, while a generalized primitive is expected in Q2’23.
Primer on Liquity
Liquity is a non-custodial, immutable, governance-free borrowing protocol. It charges users an issuance fee to take out an interest-free loan in USD stablecoin (LUSD) backed by ETH collateral. Loans can be liquidated if they fall below 110% collateral ratio. Liquidations are supported by a stability pool of deposited LUSD that will be used to pay back the loan in exchange for excess ETH. The protocol also has liquidation mechanisms should the stability pool be empty. Liquidators who initiate liquidations also receive 200 LUSD in gas compensation and 0.5% of the liquidated collateral. LUSD is hard-pegged between $1 and $1.10 through arbitrage opportunities, and soft-pegged to $1 using a Chainlink oracle. LQTY stakers earn the issuance fee in ETH as well as a redemption fee in LUSD when arbitrageurs swap LUSD to maintain the peg.
Introduction
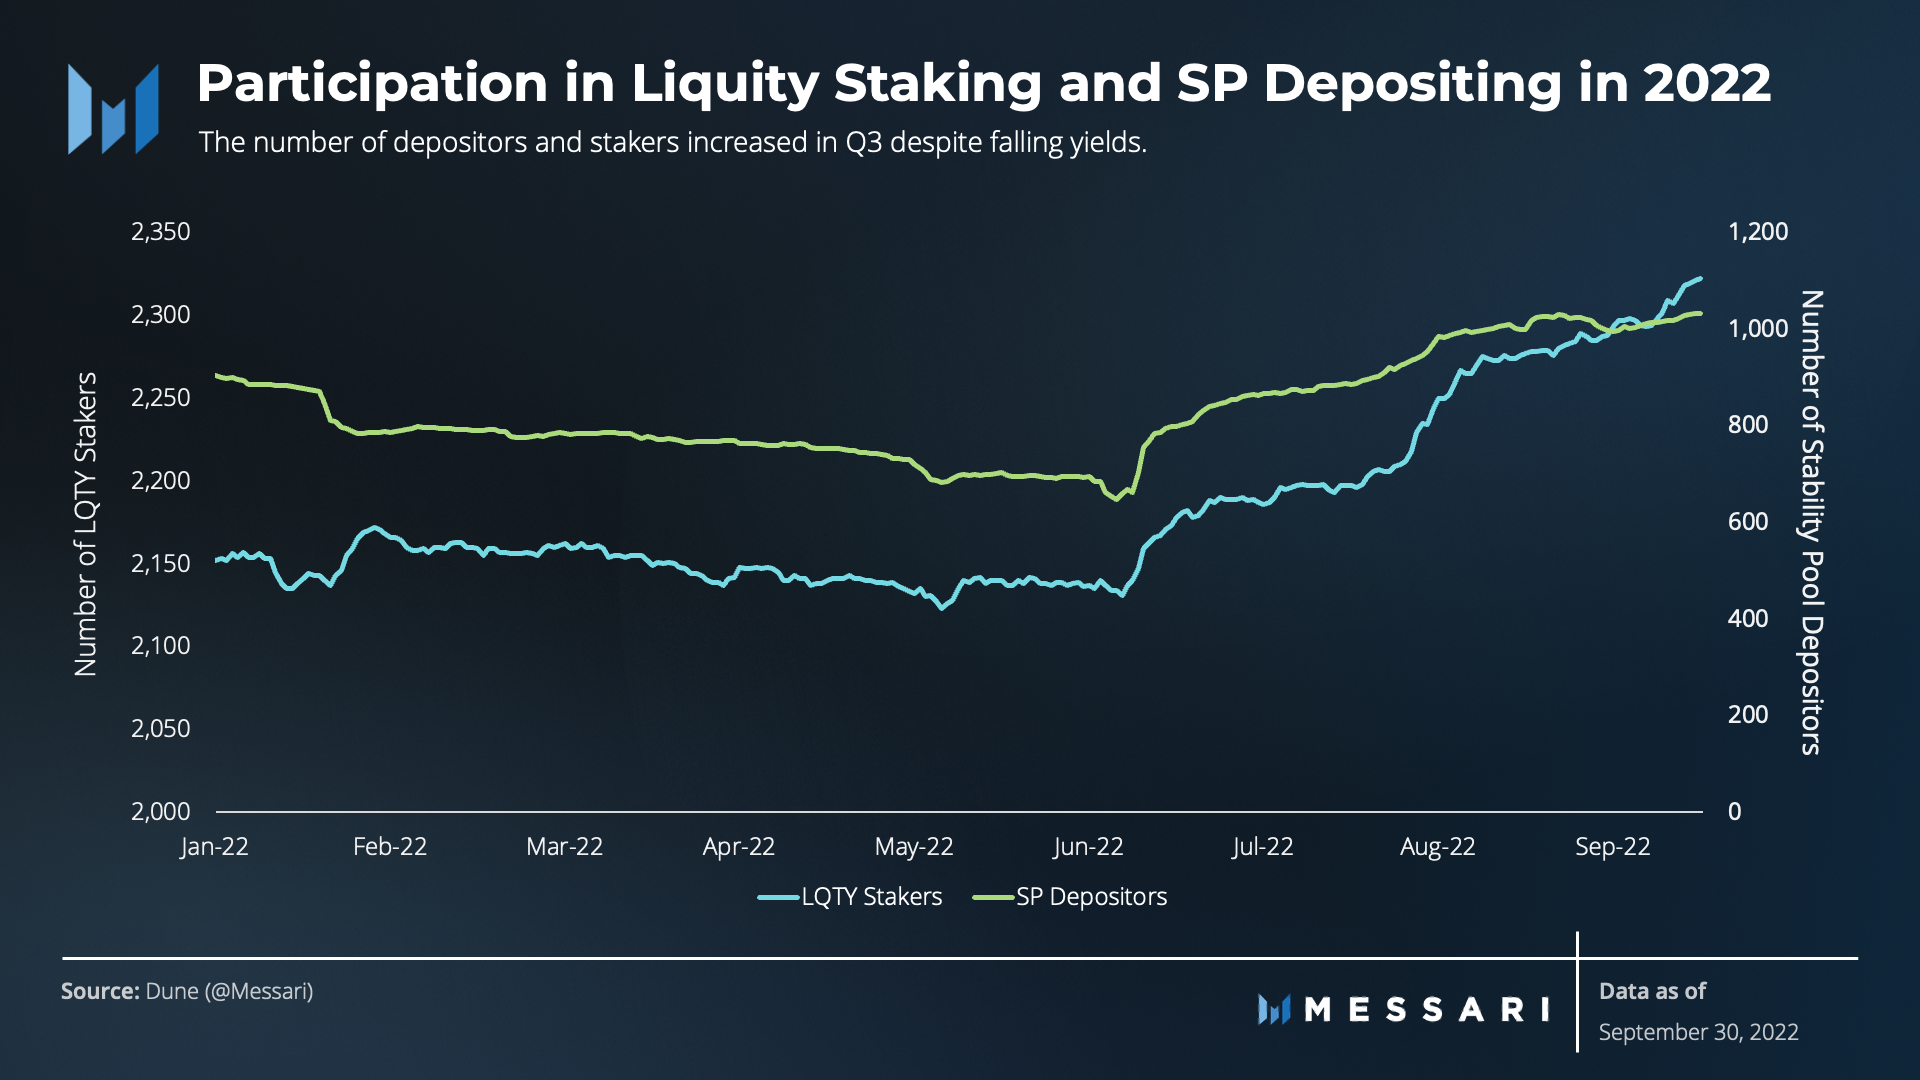
After a very profitable Q2, Liquity users and depositors had a much less eventful Q3’22. Yields for LQTY stakers and Stability Pool (SP) depositors fell to the lowest levels since inception. But users were undeterred, ending the quarter with the highest number of unique depositors and stakers this year.
The network’s health improved after the Q2 liquidations and a jump in ETH price in Q3. The stability pool also recovered some TVL. In August, LUSD became a hot topic as OFAC sanctions of Tornado Cash caused users to value the decentralization for their stablecoins.
In July, developers released a whitepaper for Chicken Bonds. Recently launched in the first week of Q4, Chicken Bonds will enable protocols to gain protocol-controlled equity (diversifying their treasury from just the native token) with a new primitive. Currently, the launch is only useful for LUSD holders, but a generalized version is expected to be launched in 2023.
Performance Analysis
Despite market anxiety over macro concerns, ETH rose 25% in the quarter. Even so, demand for leverage did not bounce back to the same degree. Though the number of loans (troves) outstanding increased by 29% in Q3, the amount of collateral staked fell by 4.3% in ETH terms.
Liquity's liquidation numbers reflected the leverage cleanout across the market. After $115 million of liquidations among the UST collapse and 3AC unwind, Liquity saw $476,497 of liquidations in Q3. Along those lines, liquidators made only $4,436 in Q3’22 after earning almost $700,000 in Q2. The system collateral ratio improved from 2.17 on June 30 to 2.47 by the end of September.
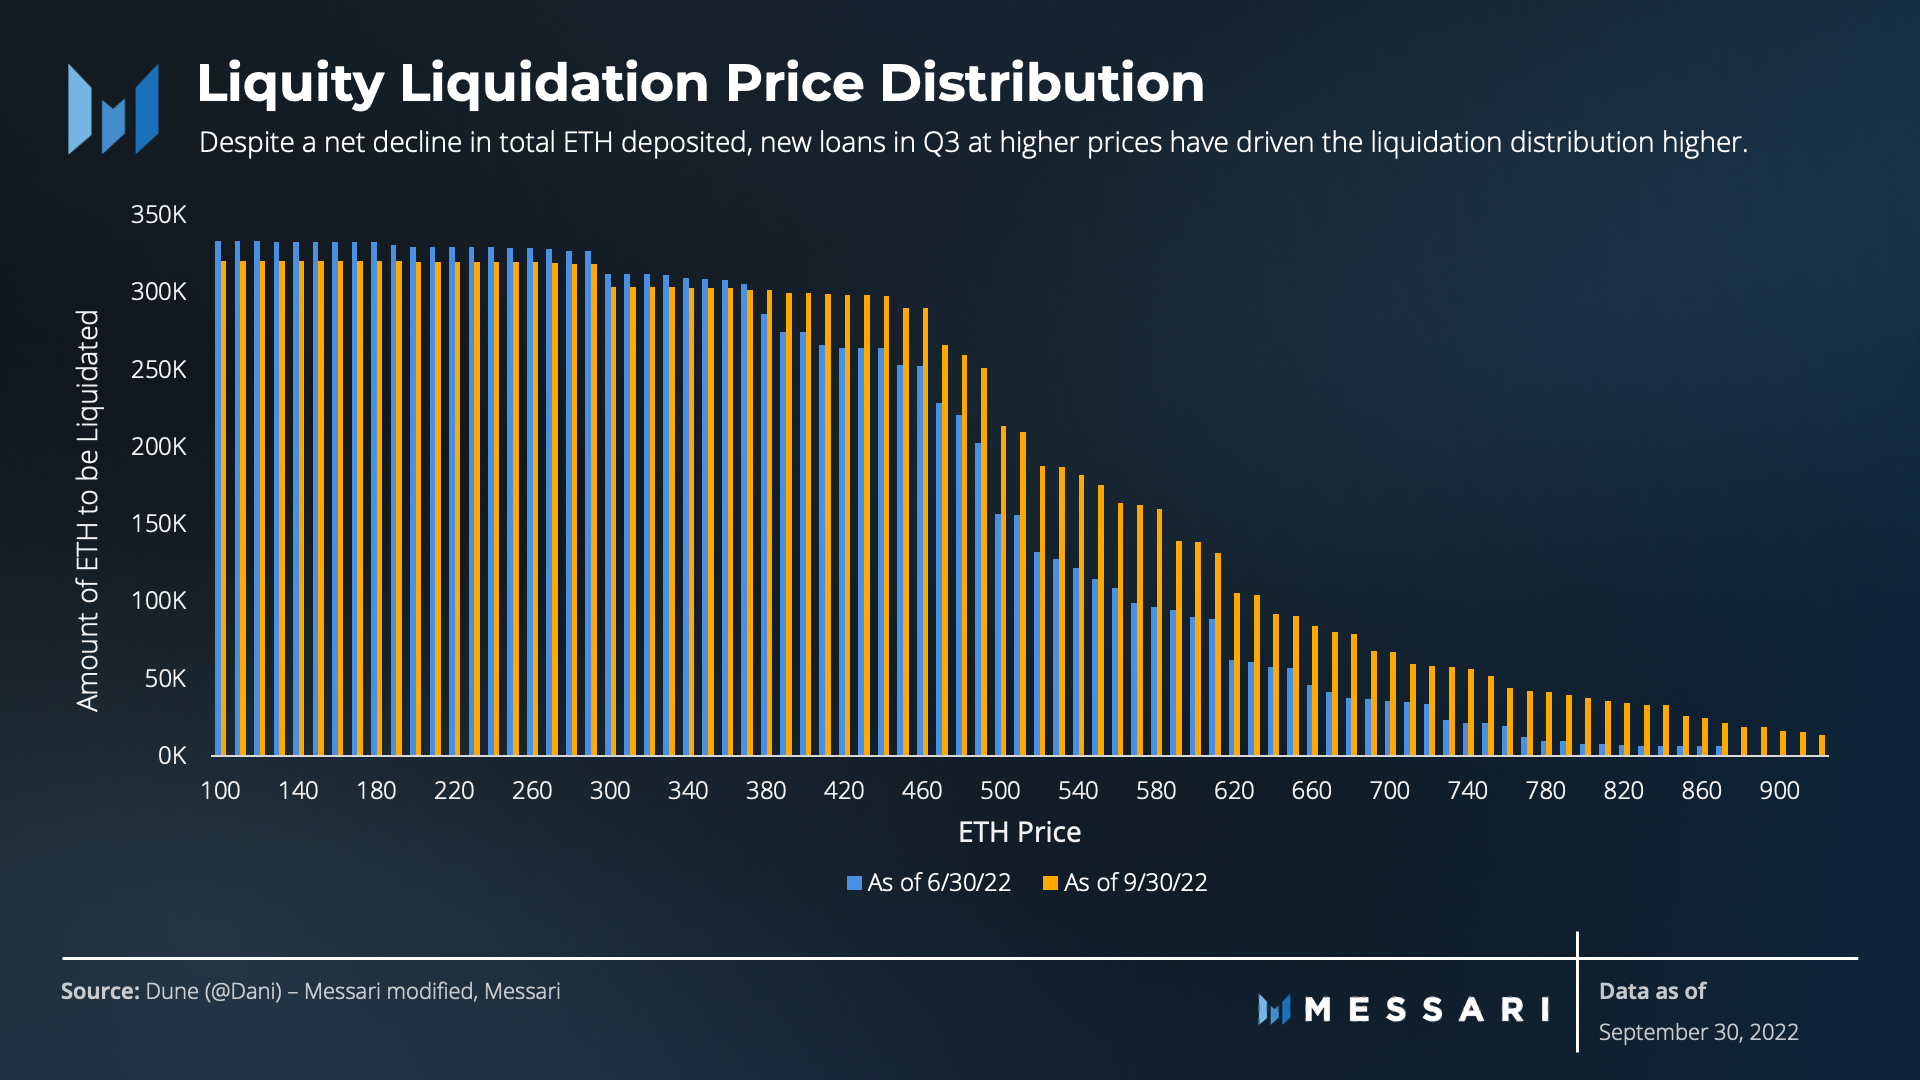
After the washout, there has been some renewal for loan activity. Even with a higher system collateral ratio, these new loans have pushed out the liquidation distribution as the price of ETH rose. Even so, if ETH were to drop back to Q2 lows below 900, it would only cause 5% of outstanding deposits to be liquidated.
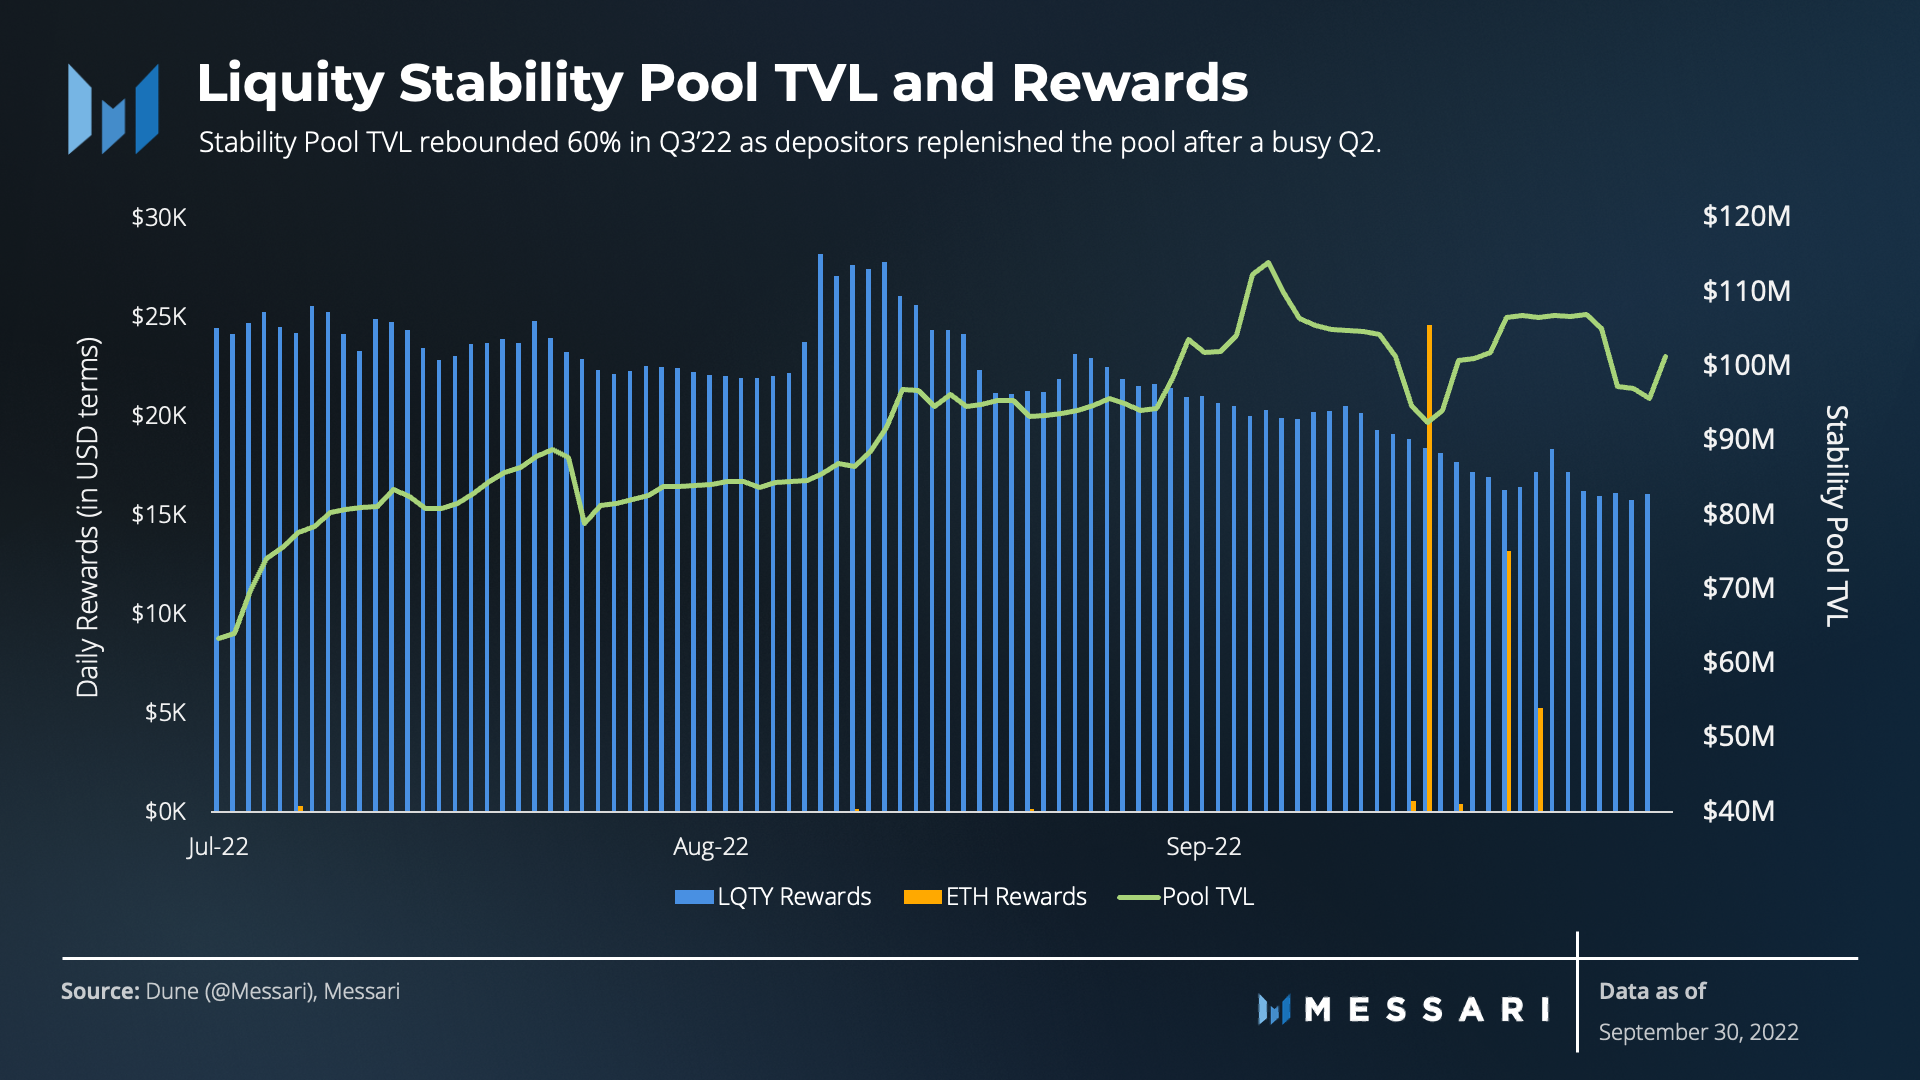
During the quieter Q3, the Stability Pool managed to regain some deposits. It increased its TVL by 60% in the quarter — a healthy response after the 83% depletion from liquidations in Q2. Rewards were almost entirely from LQTY incentives, with the USD value of rewards mostly fluctuating due to changing token price.
For the quarter, Stability Pool depositors earned just over $2 million in rewards, good for an 8.71% APR. The rewards were almost entirely from LQTY liquidity mining, with only $44,665 coming from ETH.
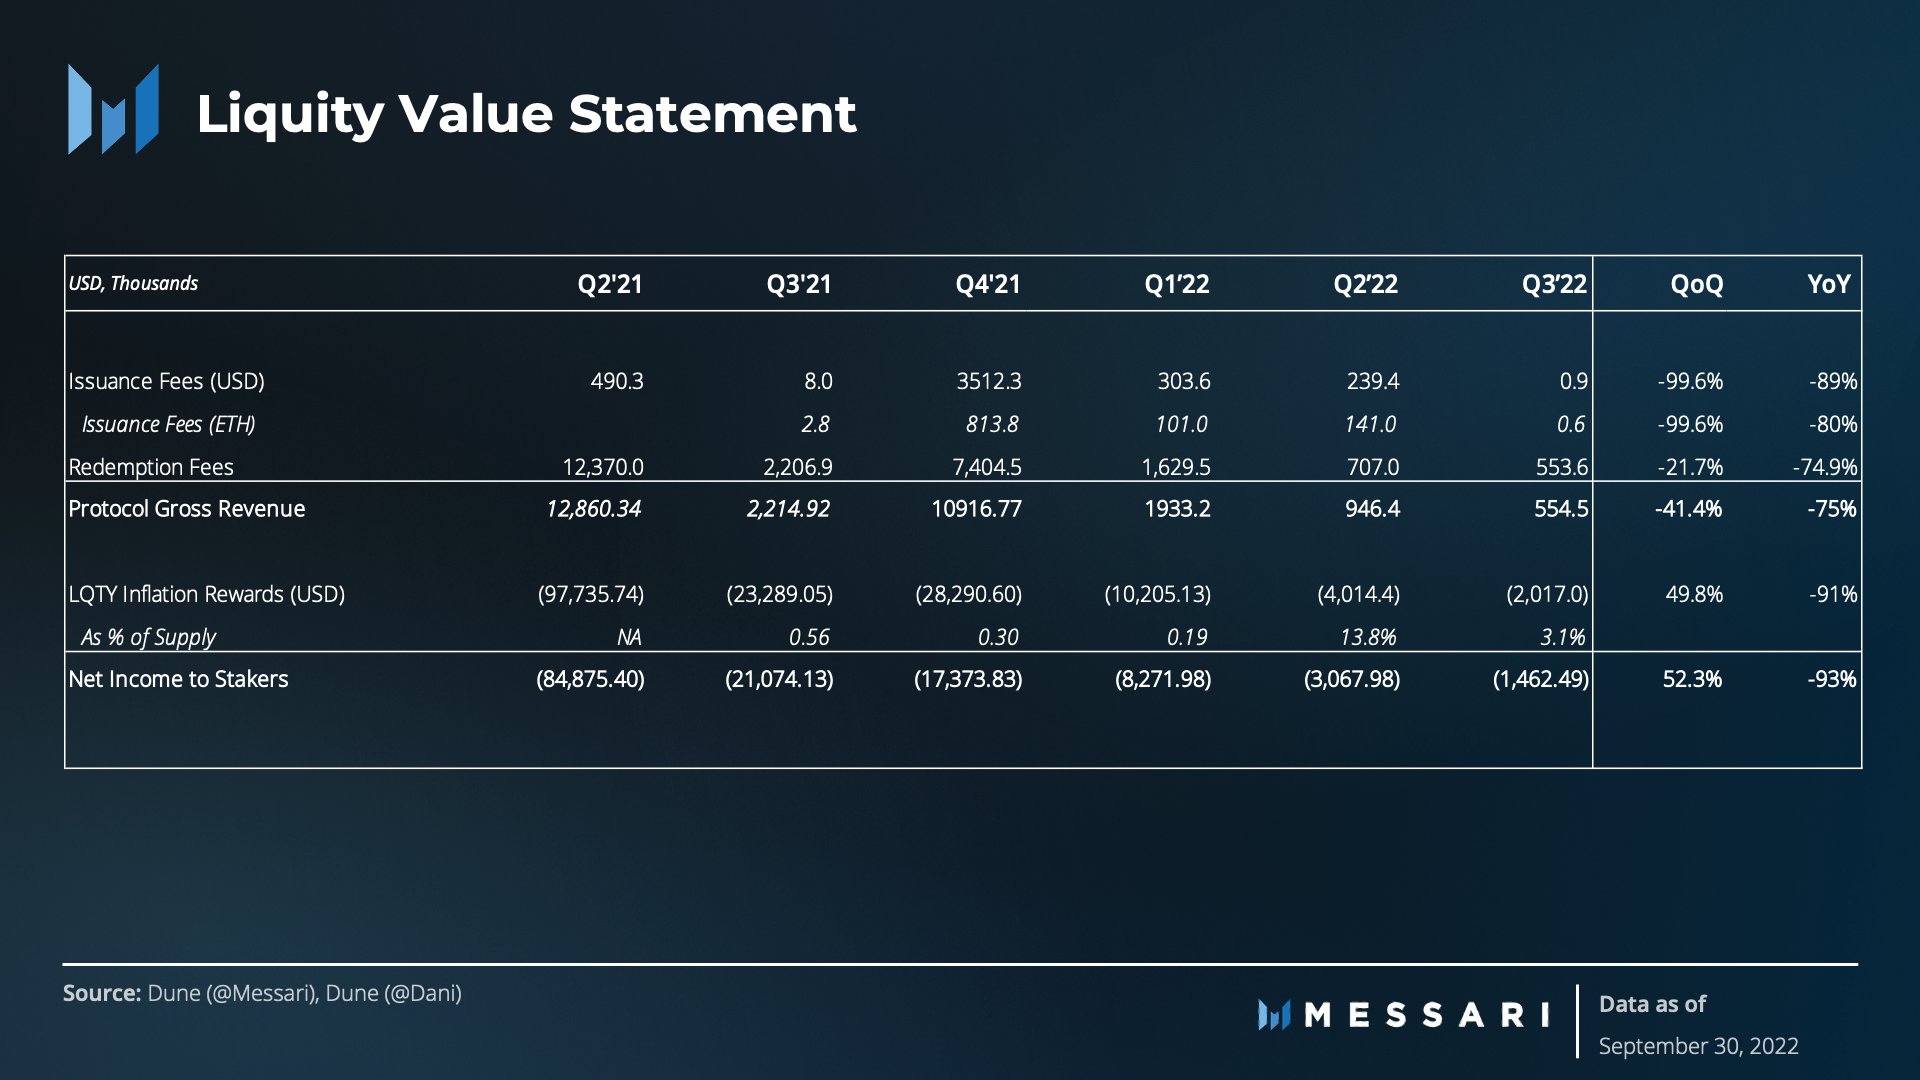
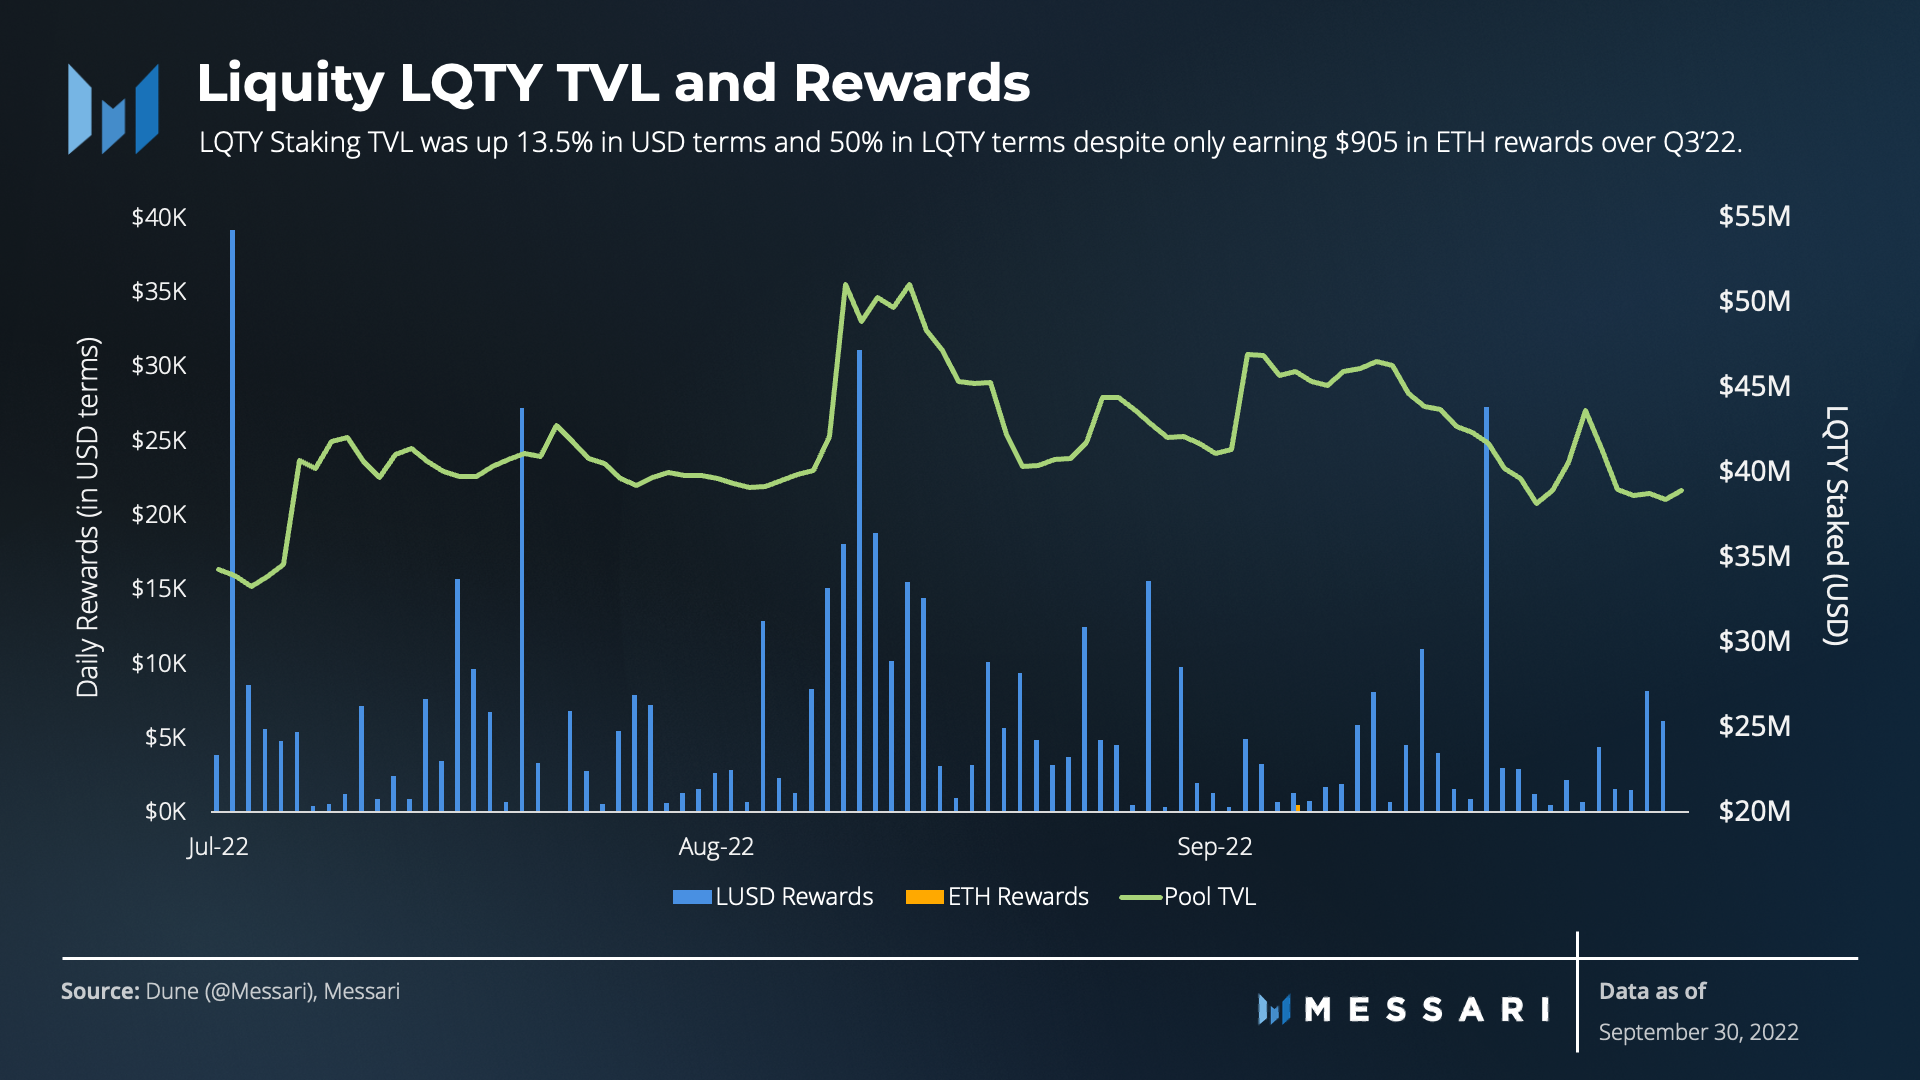
The lack of new loan demand hurt LQTY stakers the most, yielding under $1,000 in issuance fees in the quarter. Stakers still earned a 5% APR from LUSD rewards from redemptions. LQTY price fell 24% in Q3, turning a 50% increase in native tokens into a 13.5% increase in TVL. In total, stakers earned $554,519 in the quarter.
Despite a significantly worse quarter for earnings, Liquity drew many participants to stake and deposit in the Stability Pool. The previous quarter, along with the perception of continued market volatility, likely caused users to add stablecoin exposure while utilizing liquidations to buy dips in ETH. The number of depositors climbed by 25% in Q3’22. The number of LQTY stakers only increased 6.6% QoQ, likely balanced by the factors of a falling token and the perception of less loan demand.
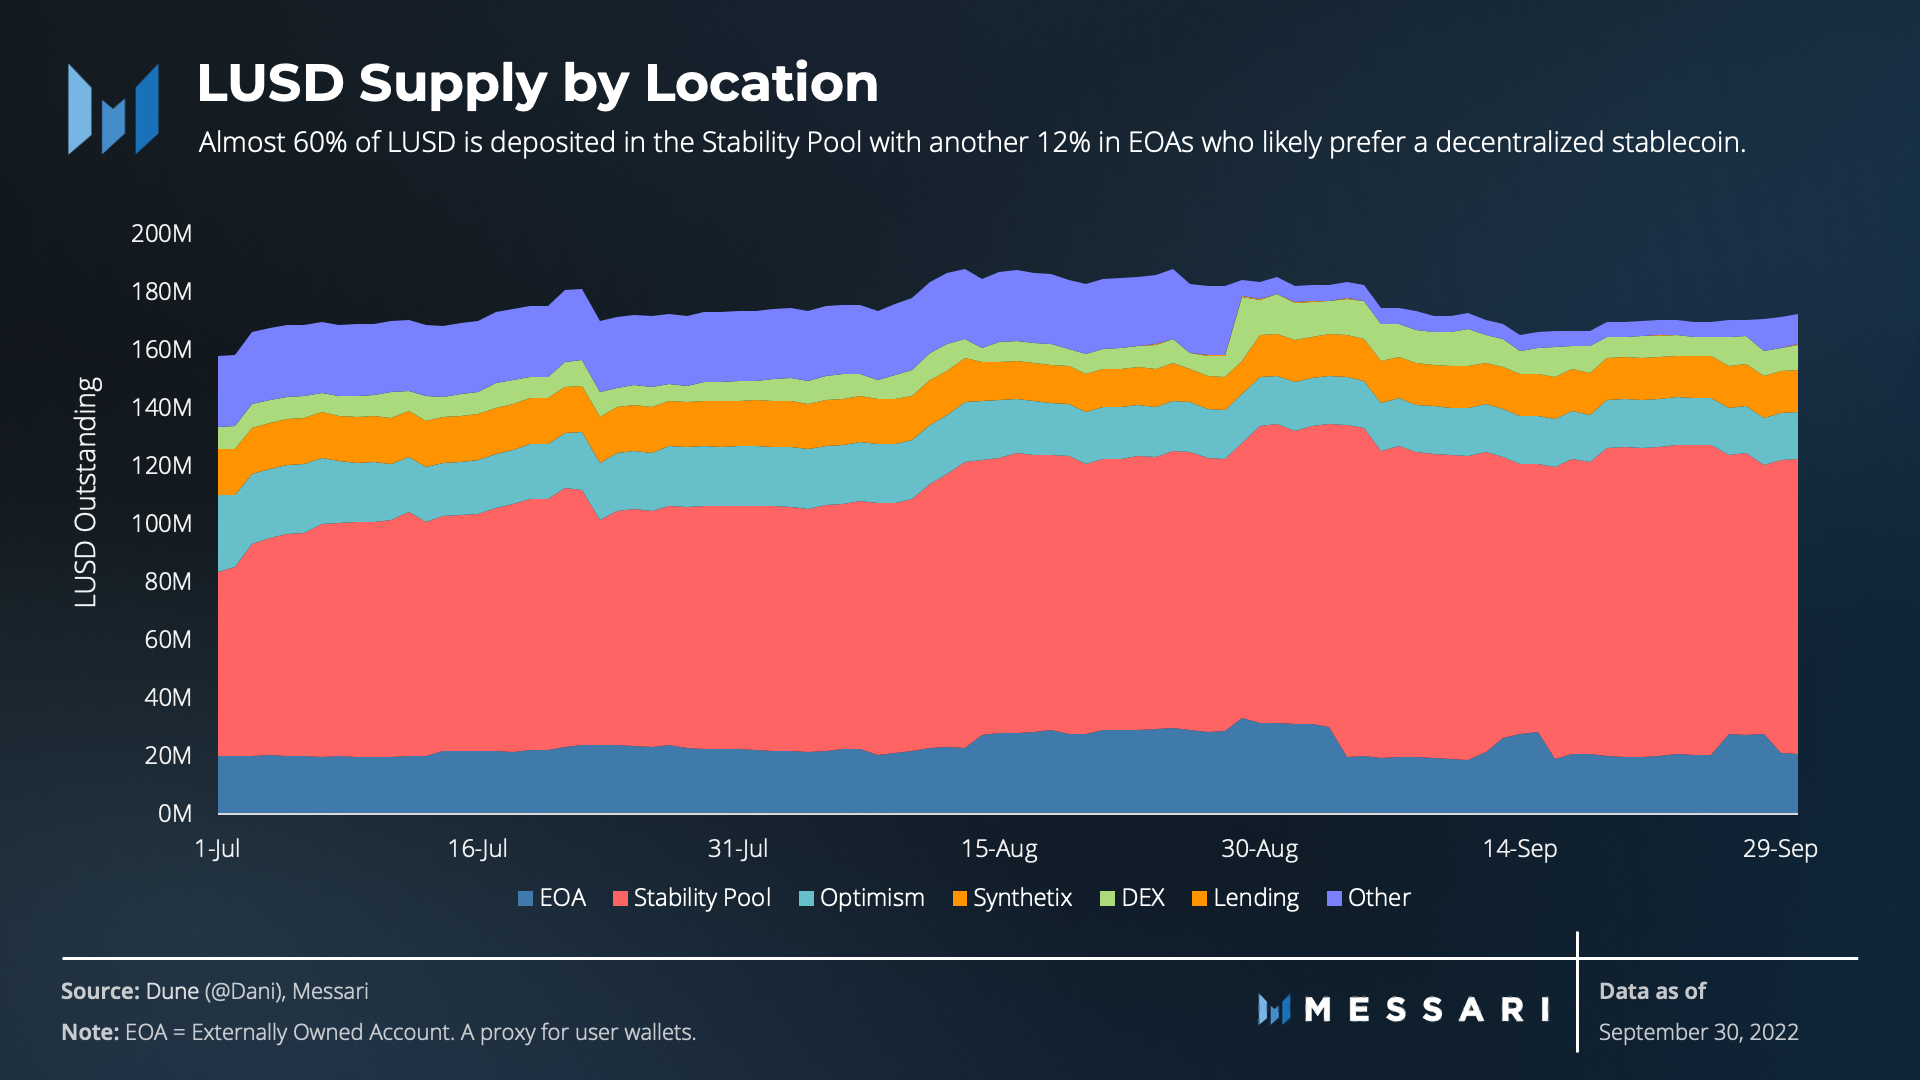
Unlike most other stablecoins, LUSD has a primary use case, which is to support the protocol in the stability pool. Further, it is by far the most decentralized stablecoin and has found a second use case, which is to be held in EOAs (Externally Owned Accounts, typically user wallets). Lastly, LUSD has continued to grow on the Optimism L2 network, increasing supply 9.4% in Q3. This goes hand-in-hand with its 8.4% increase on Synthetix, which offers an LUSD-sUSD wrapper to exchange the two currencies one-for-one on Optimism.
Qualitative Analysis
Chicken Bonds
Chicken Bonds are tools for protocols to build protocol-owned liquidity without requiring expensive token emissions. Increasing the liquidity for a protocol’s native token reduces the slippage incurred by traders and ultimately lessens the token’s price volatility. Chicken Bonds offer a unique solution to this liquidity problem by providing protocols with the ability to offer their users an amplified yield on their deposits, while still generating protocol-owned liquidity.
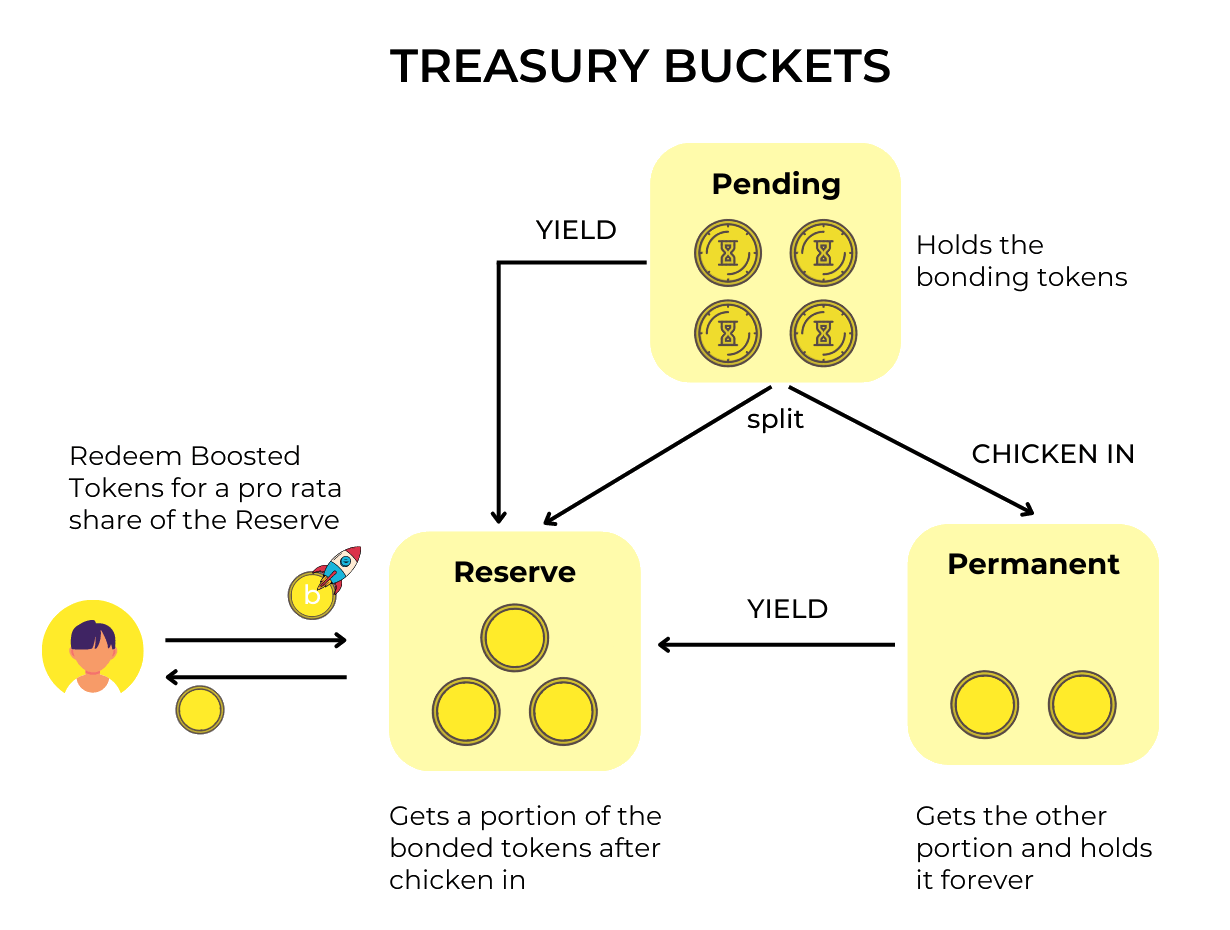
Chicken Bonds require token holders to forgo yield in the short-term to gain access to amplified yield in the long term. Users bond tokens into the "Pending Bucket'' where they accrue Boosted Tokens but no yield. Boosted Tokens represent a share in the “Reserve Bucket,” which is where the yield amplification magic happens. Yield from tokens in the Pending Bucket, Boosted Tokens in the Reserve Bucket, and Tokens in the Permanent Bucket all accrue to the Boosted Tokens. The graphic below shows the flows of user deposits within the three buckets.
Pending Bucket: Where bonding tokens go. Users can "Chicken Out" at any point and get their tokens back. While in the Pending Bucket, users earn boosted tokens on a bonding curve but no yield.
Permanent Bucket: If users "Chicken In," they exchange their bonded tokens for Boosted Tokens. The bonded tokens get split — most going to the Reserve Bucket and the rest to the Permanent Bucket. There, they will continue to earn yield for the Reserve Bucket in perpetuity.
Reserve Bucket: Boosted Tokens represent a pro-rata share of this bucket. The tokens receive a boosted yield and are redeemable at any time for the holder's pro-rata share of the bucket.
Chicken Bonds will collaborate with Liquity by allowing depositors in the stability pool to earn a higher yield from holding the bonded LUSD (bLUSD) token. Through bonding LUSD, users will earn a higher, automatically compounded yield.
To begin the bonding process, users first deposit their LUSD into the Pending Bucket. While deposited, users begin to earn bLUSD over time, and their deposits are represented as NFTs. This setup allows users to sell the NFT to capture the time value of their deposit. They could also choose to withdraw their principal without any penalties. Exiting like this is referred to as Chickening Out, and it is how the bonds offer principal protection.
Based on current simulations done by the Liquity team, the breakeven point for the bonding process is around 30 days. If users wait for their bLUSD position to reach the breakeven point, they can choose to Chicken In and move their deposit into the Reserve Bucket and the Permanent Bucket.
The Reserve Bucket maintains the majority of the LUSD deposited in the system to back the bLUSD supply, while earning yield in the Stability Pool. Additionally, users in the Reserve Bucket can redeem their bLUSD for the underlying LUSD at any time. They could also sell their bLUSD on the open market, once again providing users an opportunity to Chicken Out. The remaining LUSD is sent to the Permanent Bucket and deposited into the LUSD:3CRV liquidity pool providing protocol-owned liquidity.
Chicken Bonds for LUSD went live on October 4. Following this release, Liquity will provide protocols and DAOs a generalized version to use in Q1 2023. For LQTY holders, the generalized version of Chicken Bonds could become a way for Liquity to charge a fee for other protocols to use Chicken Bonds and direct these fees to LQTY stakers.
DeFi’s Decentralized Stablecoin
Liquity is one of the few protocols that truly adheres to the principles of decentralization and autonomy. Since its launch, Liquity has operated without a governance system in place. The protocol’s parameters are the same today as they were in April 2021 when Liquity launched: the protocol is entirely automated by immutable smart contracts.
The importance of Liquity’s decentralized design became apparent on August 8 following the sanctions by OFAC on the popular cryptocurrency mixer Tornado Cash. Circle, the issuer of USDC, was forced to comply with these sanctions. It blacklisted any assets that had interacted with Tornado Cash, rendering the assets non-transferrable. Users who had interacted with Tornado Cash at any point quickly learned their lesson. Holding centralized stablecoins like USDC and USDT directly exposes them to the risk of having their assets frozen, even if they weren’t acting nefariously.
The newfound value of a truly decentralized stablecoin can be shown through the LUSD exchange rate. The day prior to the sanctions, LUSD was trading at $1.02, and just hours after the sanctions went public, LUSD began trading at $1.048. A few days later on August 14, LUSD peaked at $1.079.
The decentralization of Liquity lies not only in the protocol parameters but also in the utilization of third parties to run decentralized front ends to access the protocol. This ensures that there is no single point of failure for end users in interacting with the protocol. By providing a front-end launch kit with SDKs and LQTY rewards, third parties are incentivized to easily set up a front end and get paid in LQTY rewards when end users interact with their front end. Users should note, when interacting with a front-end it is their responsibility to conduct the proper due diligence to determine whether it is malicious. Currently, there are 29 different front ends that end users can interact with in the protocol.
Continued Integrations
Liquity's value proposition of being the most decentralized stablecoin is not going unnoticed by the DeFi community. Existing integrations with Synthetix, Saddle, and Protocol B are largely because of their communities’ focus on decentralization. As protocols begin valuing censorship resistance more, LUSD stands to gain from further integrations.
As seen in Q3, three proposals passed to integrate LUSD on the following protocols: Aave V2, Angle, and Mimo. Each of these communities overwhelmingly supported integrating LUSD, citing the resiliency of the stablecoin. Monitoring the TVL of LUSD on these protocols and future integrations will be an important metric to gauge the success of Liquity moving forward.
Closing Summary
As a result of a less volatile market, yields for LQTY stakers and Stability Pool Depositors were the lowest they have been since Liquity's launch. Although yields have cooled down from a volatile Q2, the system benefited in Q3 from the LUSD supply increasing by 9% and the system’s collateral increasing to 2.54.The potential regulatory risks for stablecoins highlighted the need for a truly decentralized stablecoin, as confirmed by the number of protocols integrating LUSD in Q3. Chicken Bonds launched for LUSD, with a generalized version for use by other protocols expected in Q1 2023. With this novel bonding mechanism, Liquity hopes to gain deeper liquidity for LUSD and another potential revenue stream for LQTY stakers via the generalized versions.
All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Nothing contained in this report is a recommendation or suggestion, directly or indirectly, to buy, sell, make, or hold any investment, loan, commodity, or security, or to undertake any investment or trading strategy with respect to any investment, loan, commodity, security, or any issuer. This report should not be construed as an offer to sell or the solicitation of an offer to buy any security or commodity. Messari does not guarantee the sequence, accuracy, completeness, or timeliness of any information provided in this report. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Before joining Messari as a Senior Research Analyst, John worked in Equity Derivatives on the buy-side and sell-side for over five years. He studied macroeconomics and markets for almost a decade. Now, John spends time thinking about token design, DeFi protocols, and governance.
Ryan is a research analyst in the protocol reporting division with a focus on DeFi. He graduated from Clark University with his MBA and previously worked in Real Estate. Ryan's true passion has been in crypto and he now focuses on understanding DeFi protocol design, governance and tokenomics.