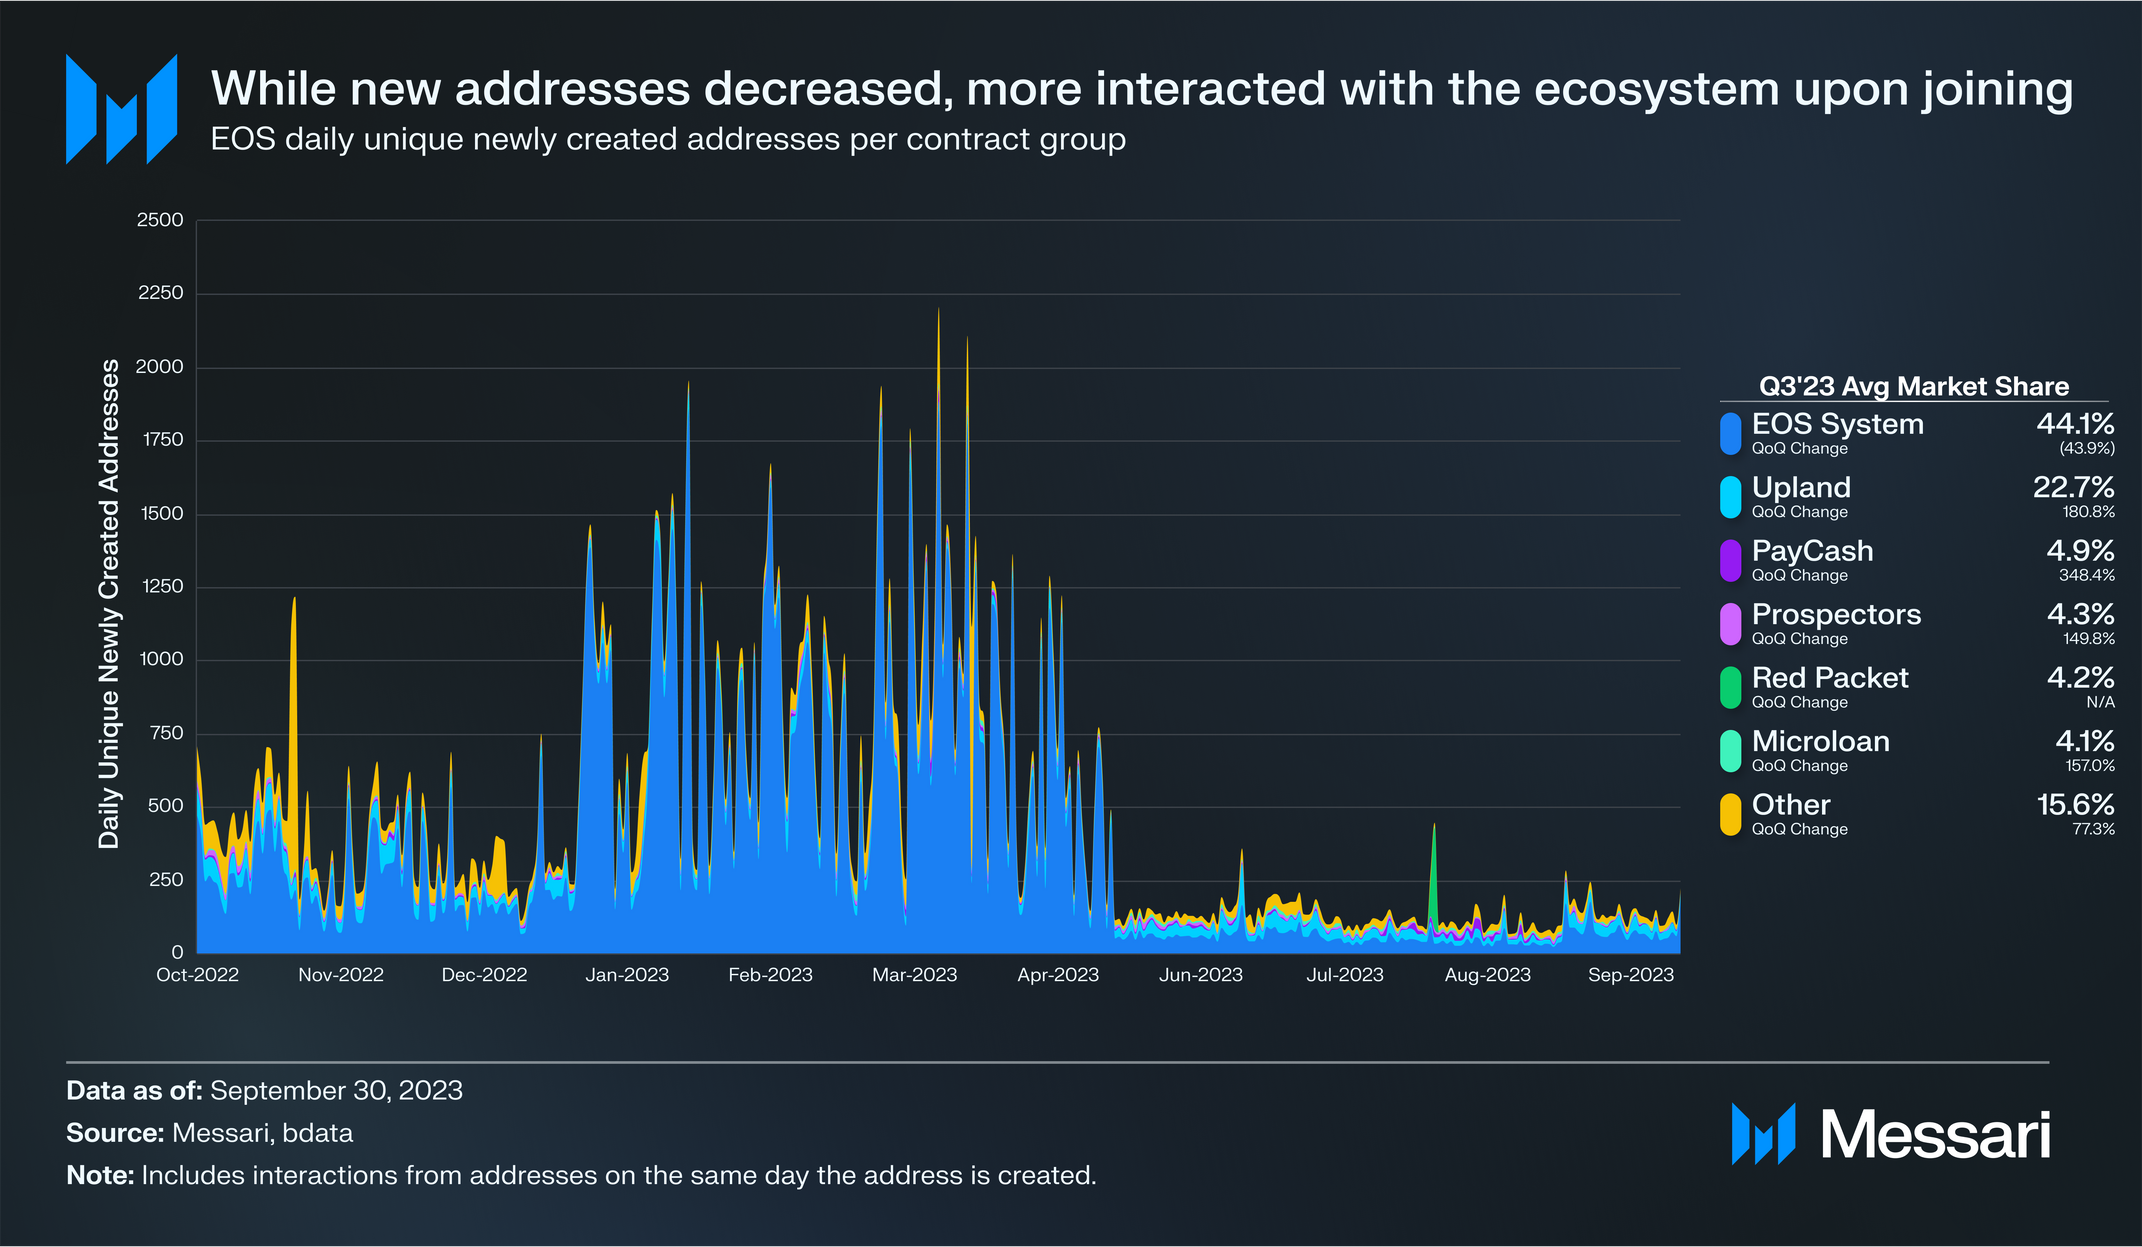
Average daily new addresses fell 50% QoQ to 652, but these addresses participated in the ecosystem upon joining at a higher rate. The EOS System’s market share of activity from newly created addresses decreased from 79% to 44% QoQ.
EOS Labs was founded in August, joining the ENF and ENV as independent third parties furthering EOS development and growth. EOS Labs will fulfill incubator and builder roles, focused on the application layer.
$EOS received regulatory approval from the Japan Virtual and Crypto Asset Exchange Association (JVCEA). $EOS began trading on licensed marketplace BitTrade on September 13.
The ENF unveiled a developer onboarding strategy, including SDKs, enhanced documentation, and more. In Q3, the Wharf Session Kit and Web IDE were released.
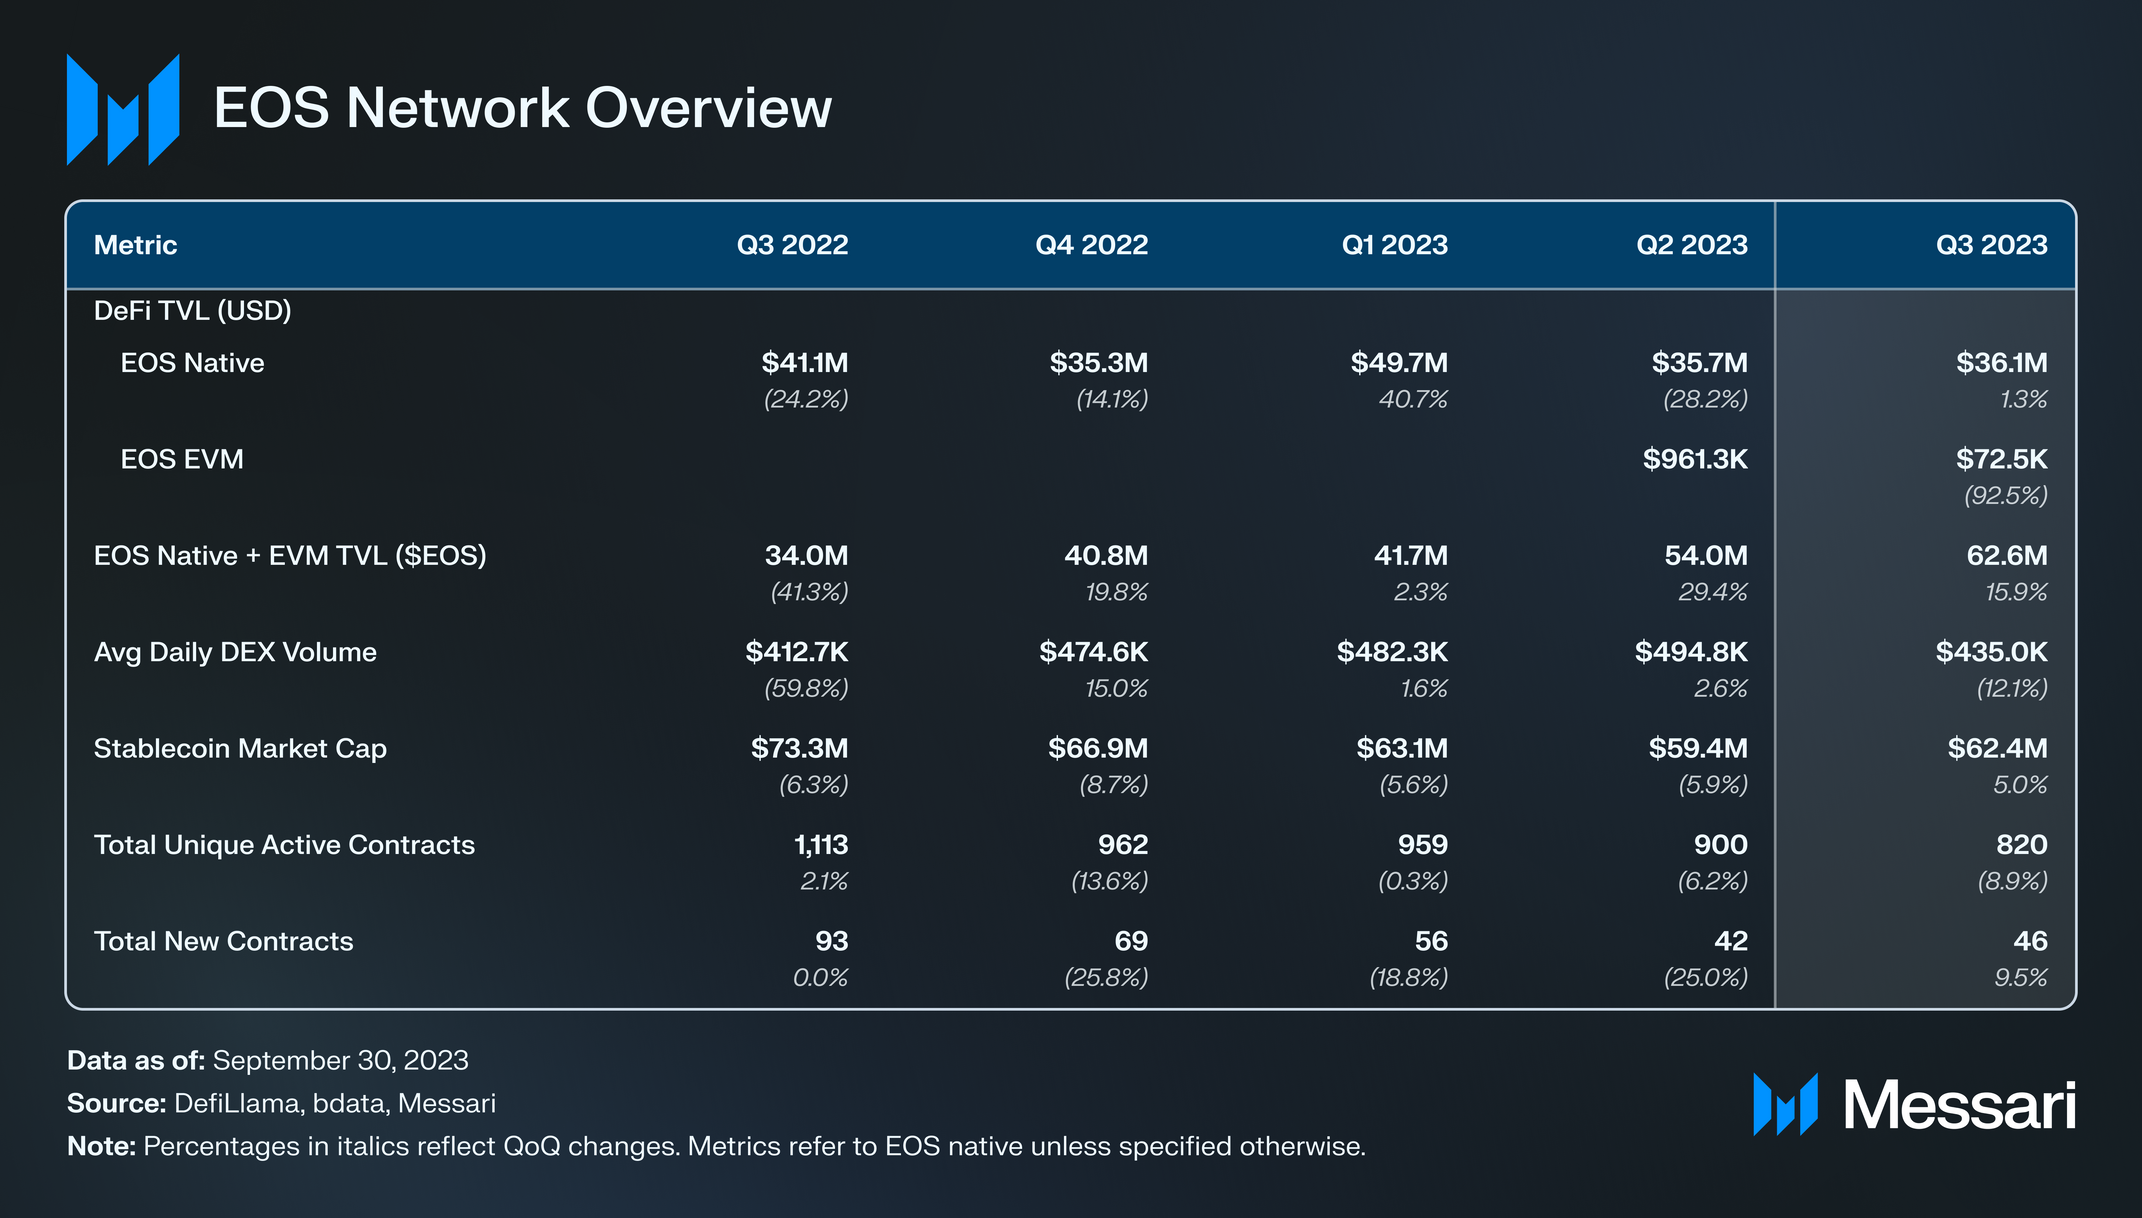
DeFi TVL on the EOS EVM decreased 92% QoQ to $72,000. The drop occurred when two addresses (which were likely the same user) withdrew $760,000 from DEX Noah Swap.
Primer on EOS
EOS is a Delegated Proof-of-Stake (DPoS) Layer-1 blockchain built using the open-source Antelope protocol. EOS’s founding team Block.one raised around $4.1 billion in a 2017-18 ICO but slowly stopped supporting the network through core development and ecosystem funding. A community-led effort driven by the non-profit EOS Network Foundation (ENF) ensued to take over ownership of the project to prevent further decay of the protocol codebase and the EOS ecosystem.
The grassroots effort has driven several technical upgrades, including an inter-blockchain communication (IBC) protocol connecting all Antelope networks, an EVM solution deployed as a smart contract on the original EOS network (“EOS Native”), and a new consensus mechanism based on HotStuff (estimated Q4’23 launch). Beyond the ENF, EOS protocol and ecosystem development is furthered by EOS Network Ventures (ENV) and EOS Labs, which was founded in August 2023. For a full primer on EOS, refer to our Initiation of Coverage report.
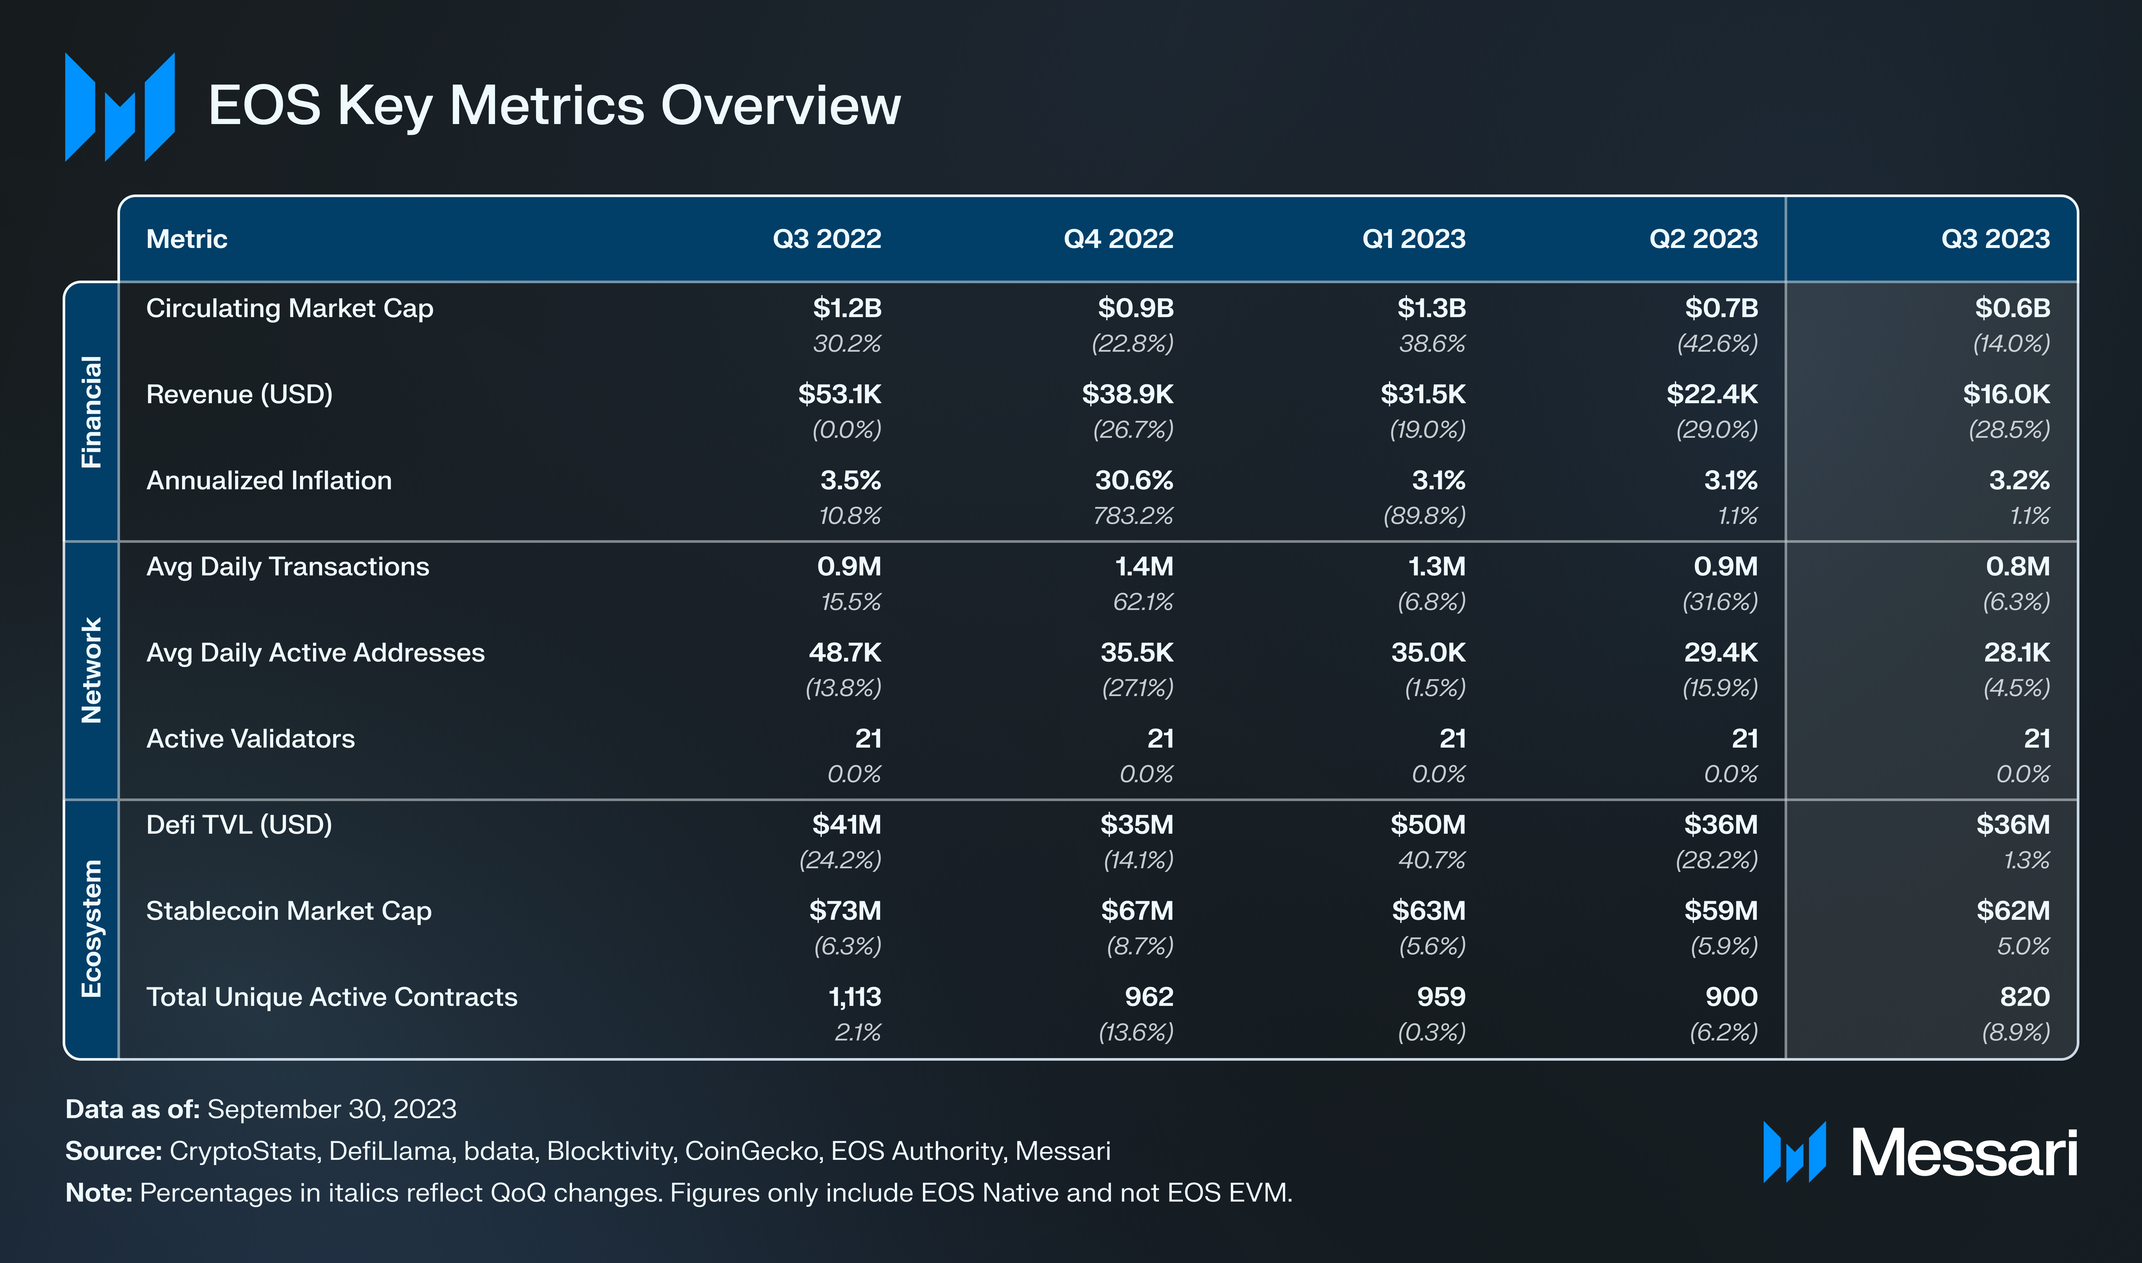
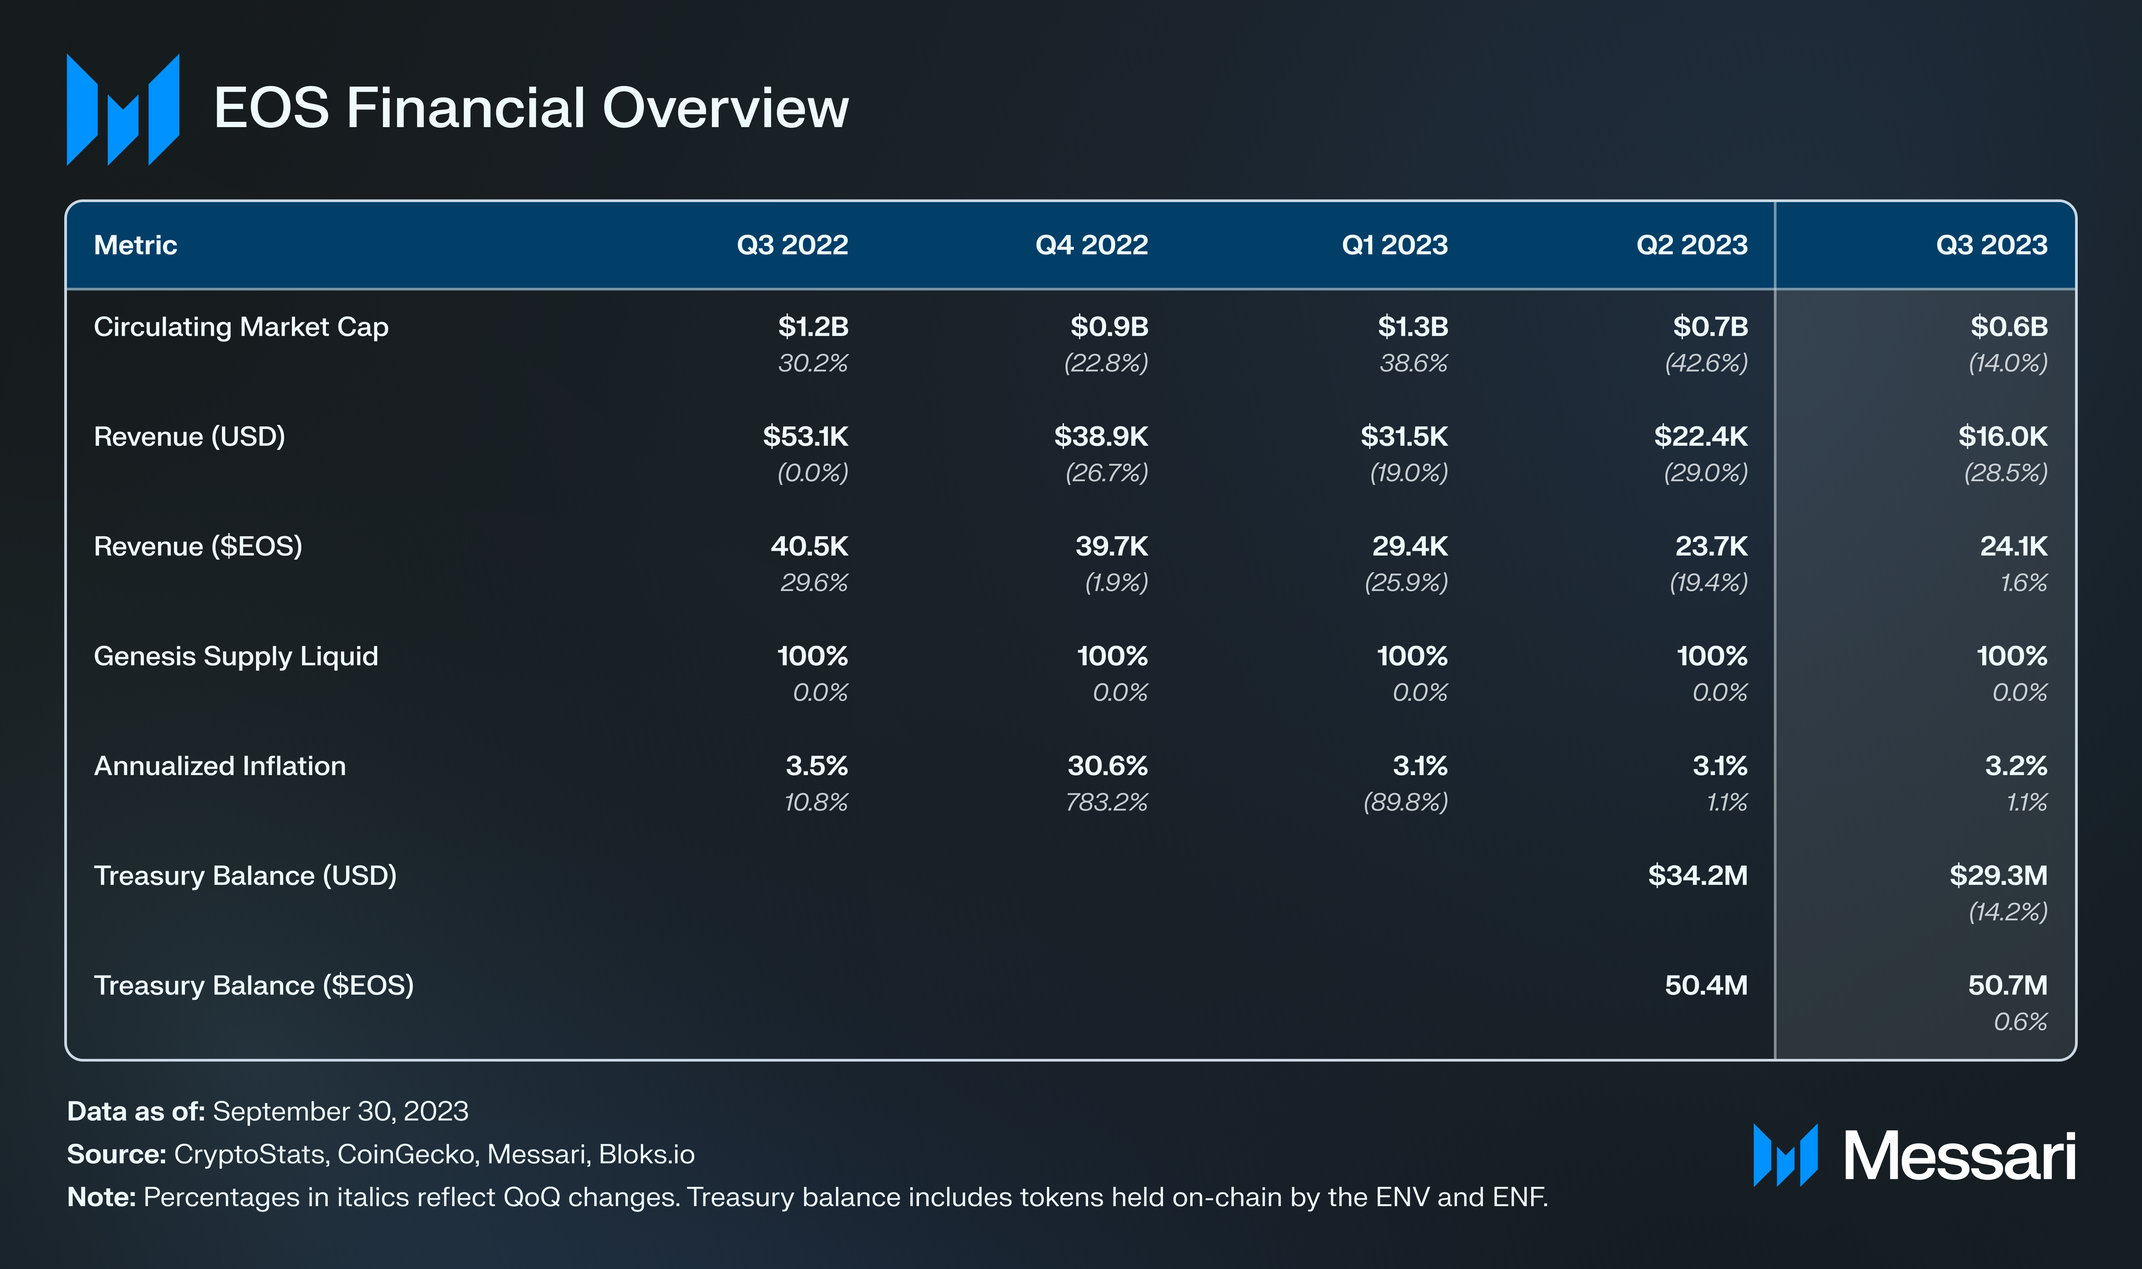
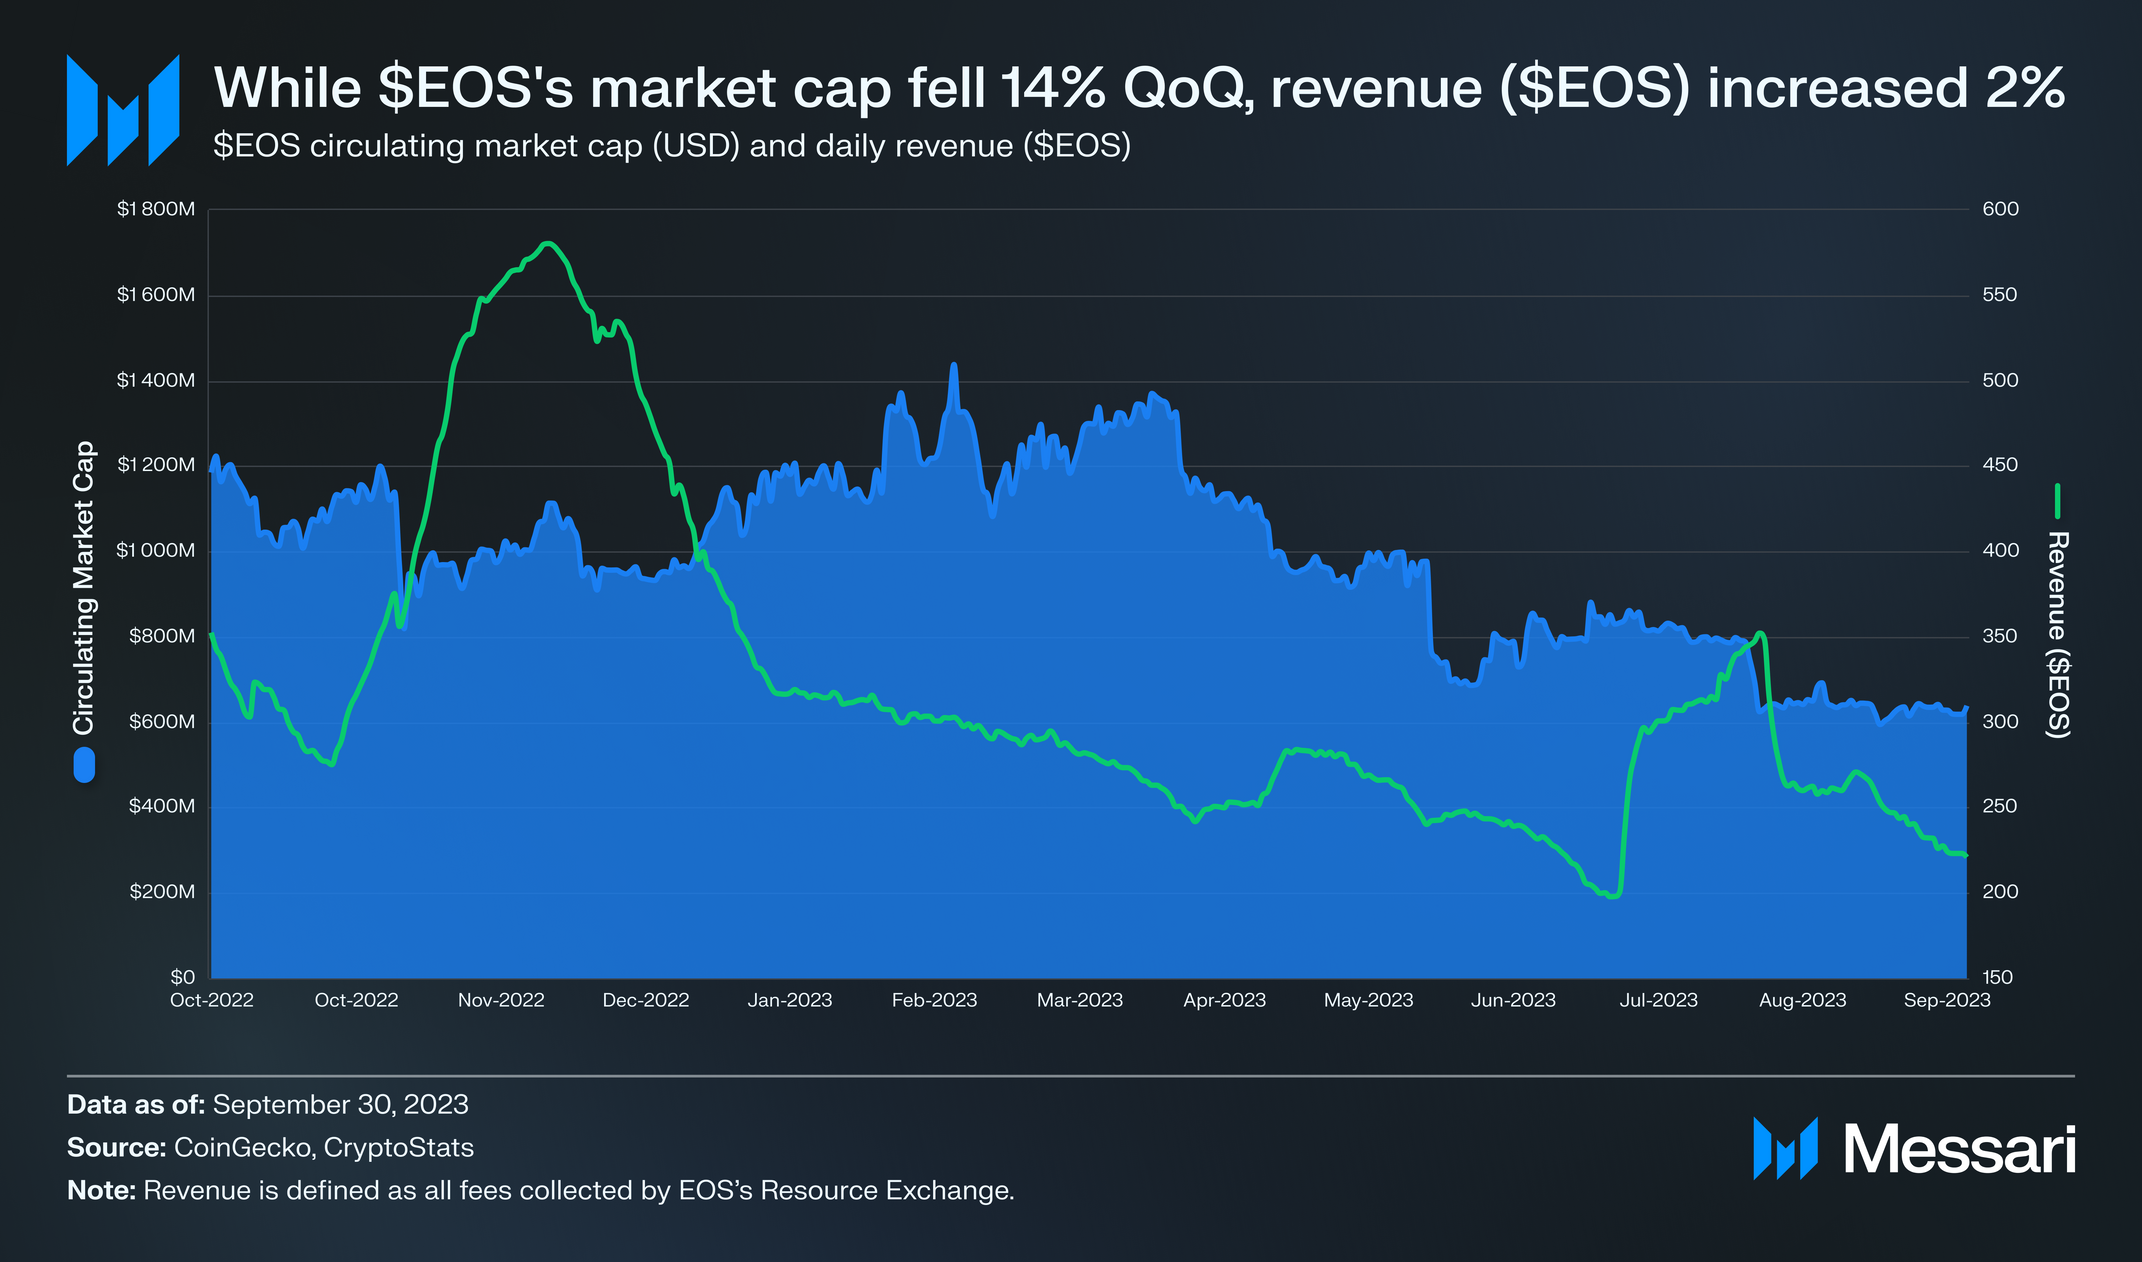
Q3’23 featured a largely quiet, sideways trading overall crypto market. The one major exception was a large selloff in mid-August. $EOS followed this trend: its circulating market cap decreased 14% QoQ to $640 million, with the drop largely occurring from August 16-18. EOS’s market cap rank among all cryptocurrencies fell slightly QoQ from 51 to 56. Right after the market downturn, activity similarly fell on EOS which reversed the upward trend in revenue (denominated in $EOS). Nevertheless, total quarterly revenue still increased QoQ, up 2% QoQ to 24,000 $EOS ($16,000).
EOS revenue is defined as the fees collected by EOS’s Resource Exchange (REX). EOS’s unique resource model separates bandwidth and storage costs into two transaction fees. Other networks typically bundle these costs into one transaction fee. Through REX, users can pay a fee to boost their available bandwidth for 24 hours and trade the storage resource. REX then distributes these fees to EOS stakers.
The EOS protocol mints the $EOS token at around a 3% annual inflation rate, which it distributes to validators (1%) and the EOS Network Foundation (2%). In Q4’22, the inflation rate spiked to 30% due to the funding of the newly created EOS Network Ventures with roughly 68 million EOS — the amount that had previously been burned in two portions in 2019 and 2020. Together, the EOS Network Foundation (ENF) and EOS Network Ventures (ENV) have $29 million of $EOS in theironchainaccounts.
In mid-August, a third independent entity, EOS Labs, was founded. The ENF pledged to reallocate a quarter of its $EOS allocation from inflation to EOS Labs. EOS Labs plans to support developers through financing and building infrastructure, as well as developing its own products and tools. The various growth initiatives of all three organizations are covered in more detail in the Ecosystem Growth section.
At the beginning of Q2’23, the EOS EVM launched, adding another element to $EOS’s tokenomics. EOS EVM is an EVM execution environment deployed as a smart contract on EOS native, similar to Aurora on NEAR. EOS EVM uses $EOS as its gas token. Permissionless relayers (dubbed “miners”) are responsible for accepting valid EOS EVM transactions, wrapping them into EOS native transactions, and submitting them to the EOS native ledger.
Relayers currently receive 10% of the EOS EVM transaction fee, with the remaining 90% accruing in the eosio.evm contract. Through governance, the funds accrued in the eosio.evm contract can be used for operational costs, token burns, or other uses. At the moment, both the ENF and Noah, a decentralized exchange (DEX) on the EOS EVM, are running miners. The ENF has committed to burning any profits made through running its miner, and in the future, the 10% allocation of fees to miners could be increased to incentivize more miners.
The EOS EVM will likely become the primary driver of value for $EOS if activity increases on the network. Not only could it overtake EOS native in terms of fees generated, but almost all of its fees could also be burned, subject to governance.
At the end of August, the ENF announced that $EOS received regulatory approval from the Japan Virtual and Crypto Asset Exchange Association (JVCEA). This allows $EOS to be traded against the Japanese yen on regulated crypto exchanges in Japan. $EOS became available to trade on licensed marketplace BitTrade in mid-September. To celebrate the launch, there are no trading fees on the $EOS/JPY pair until October 11.
Network Overview
Usage
EOS Native
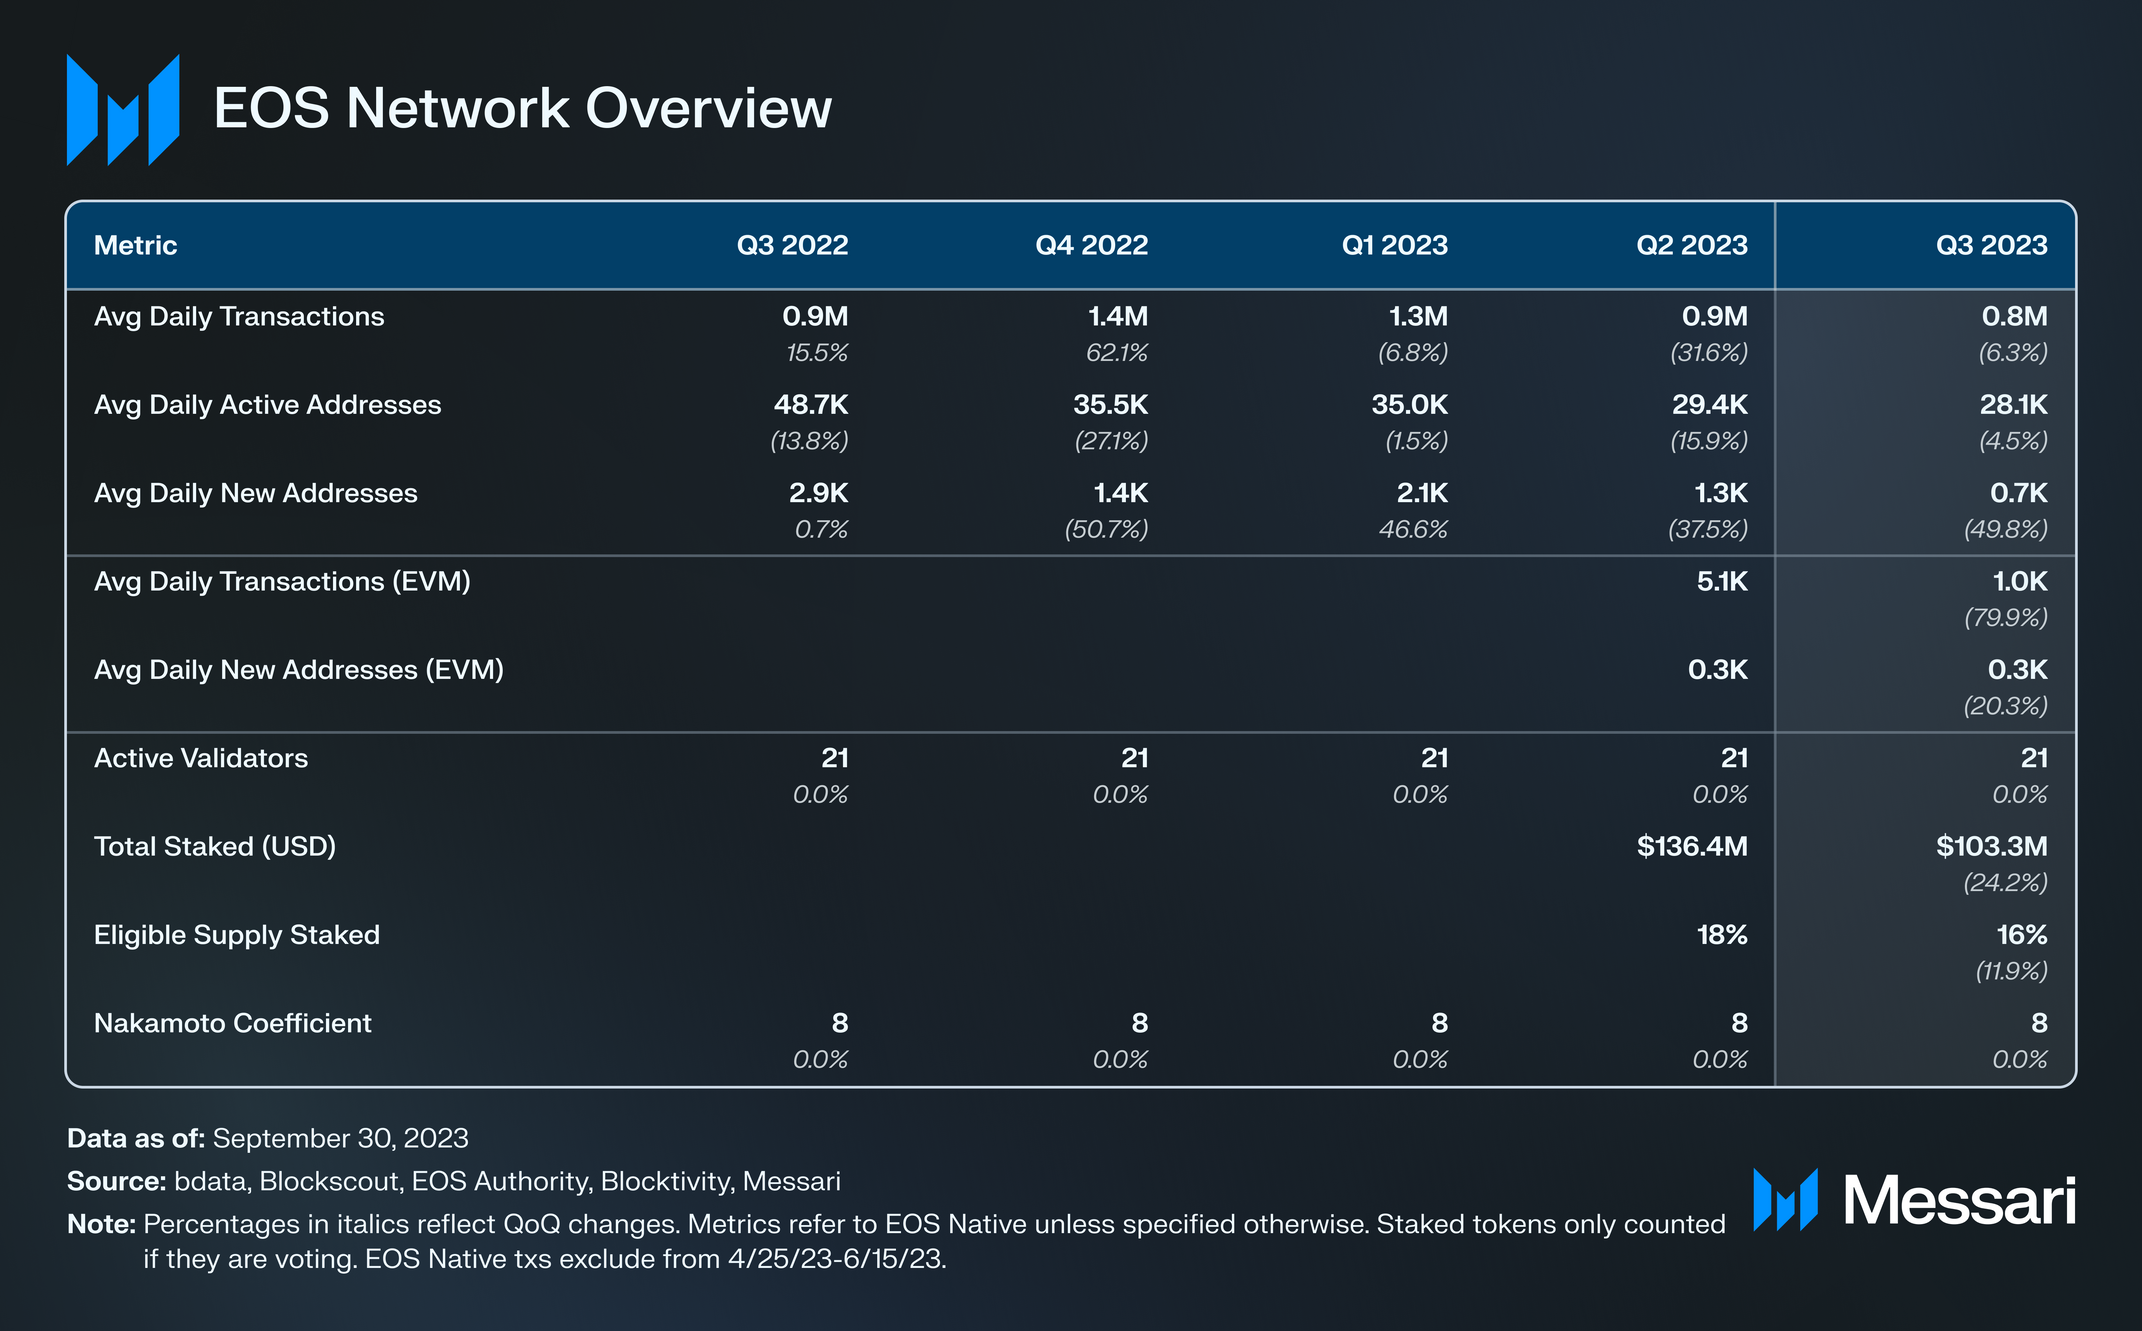
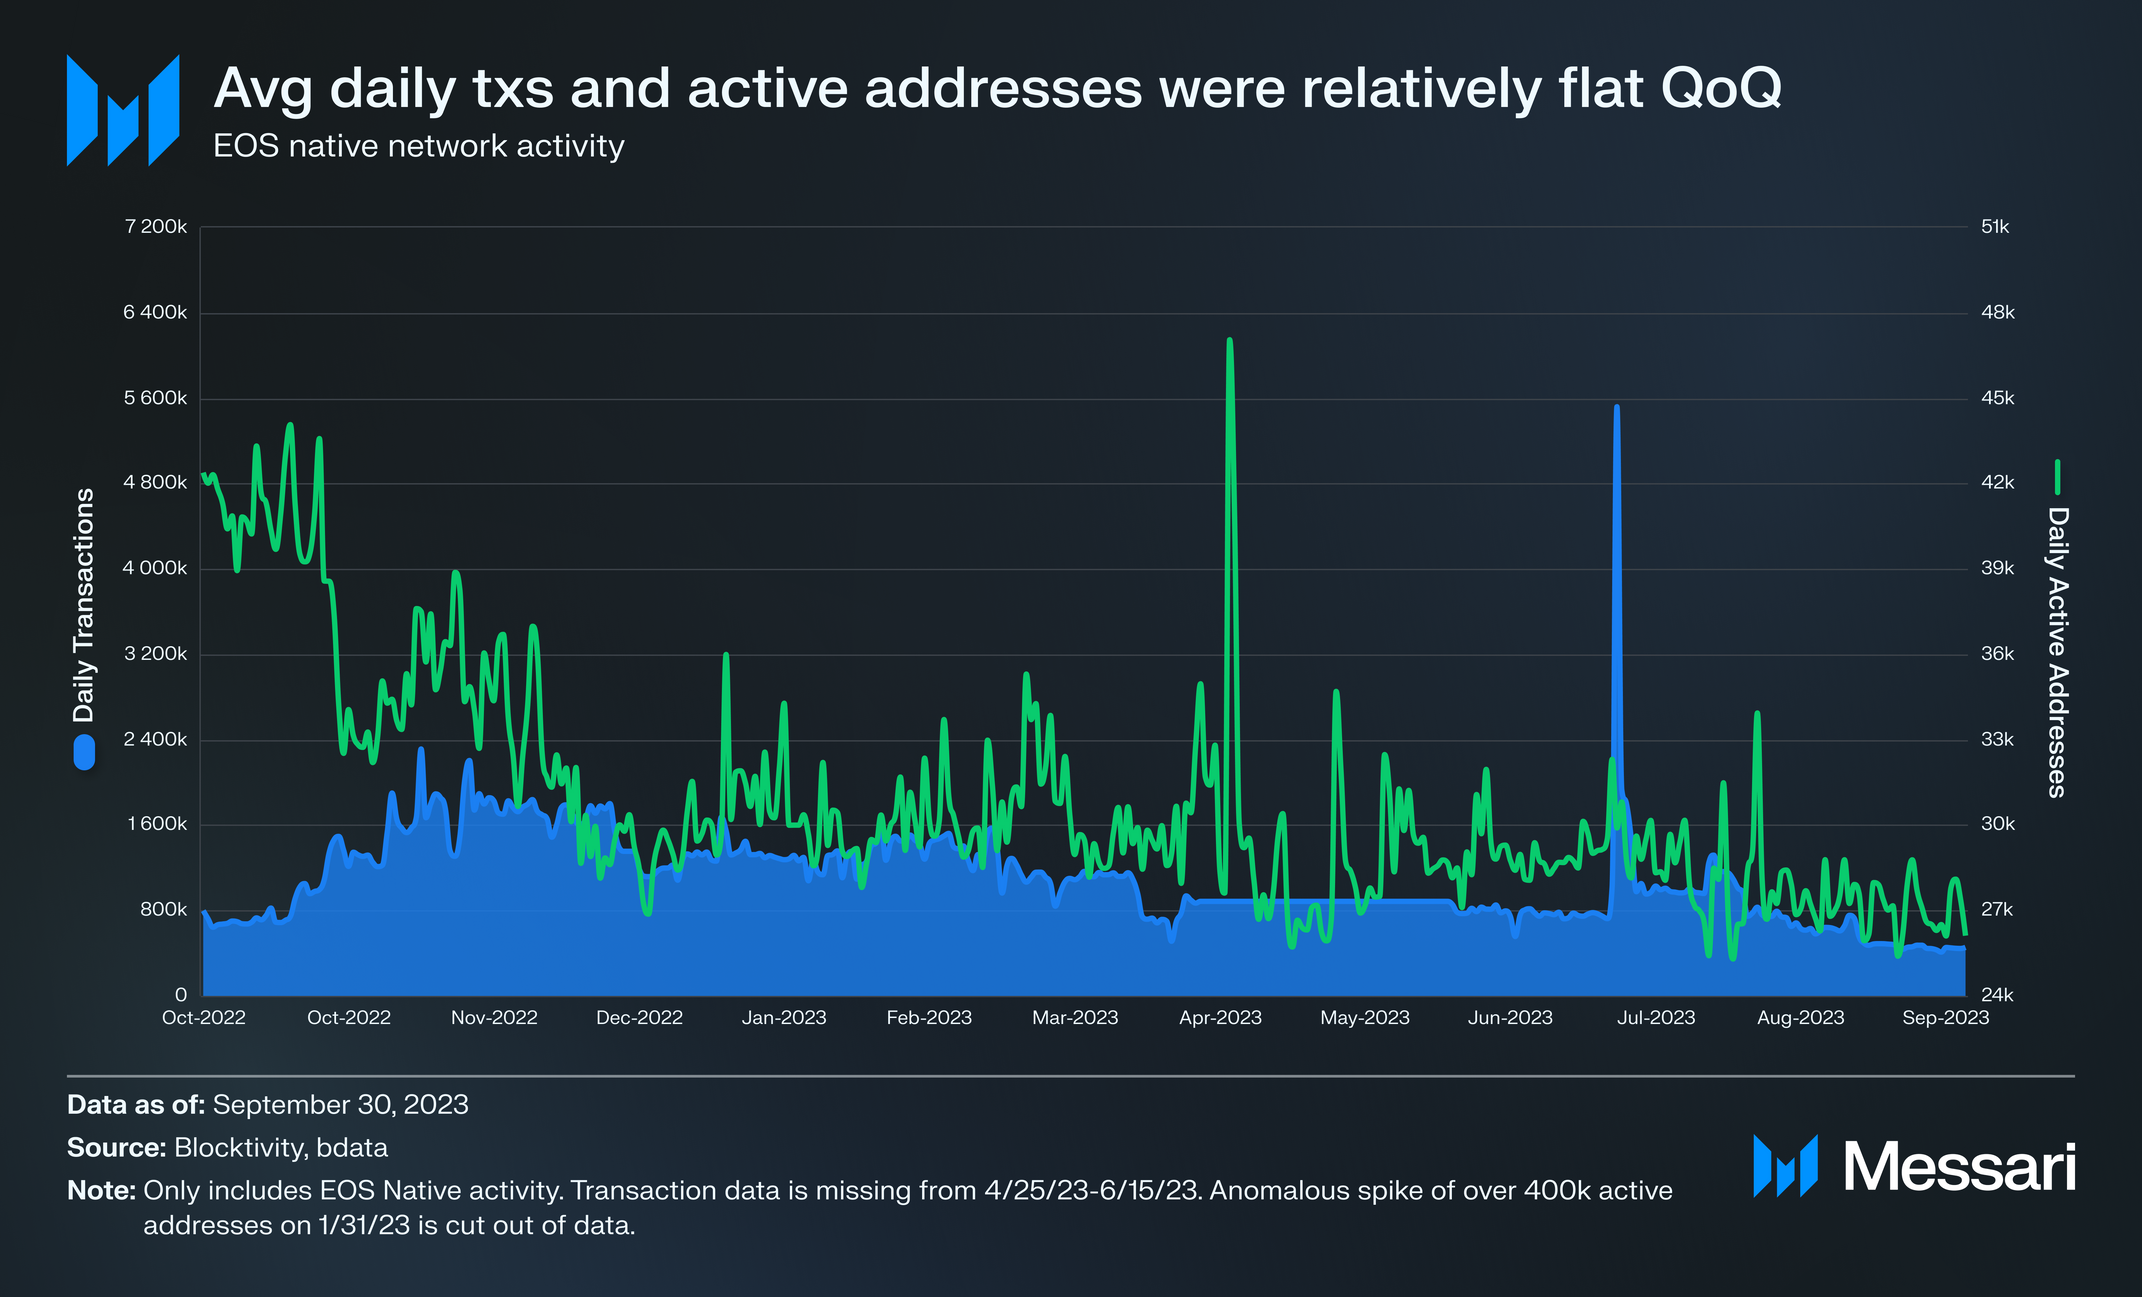
Average daily transactions and active addresses were relatively constant QoQ, decreasing by 6% and 5%, respectively. Daily transactions spiked to over 5.5 million on July 20, over double the previous yearly high. It’s unclear exactly what drove this spike, but it was likely anomalous since active addresses did not follow the spike. The chart excludes a spike in daily active addresses of over 436,000 on January 31, 2023. It’s also unclear what exactly caused the spike — but almost all of the spike was users just interacting with the EOS system contract and not with a particular dapp.
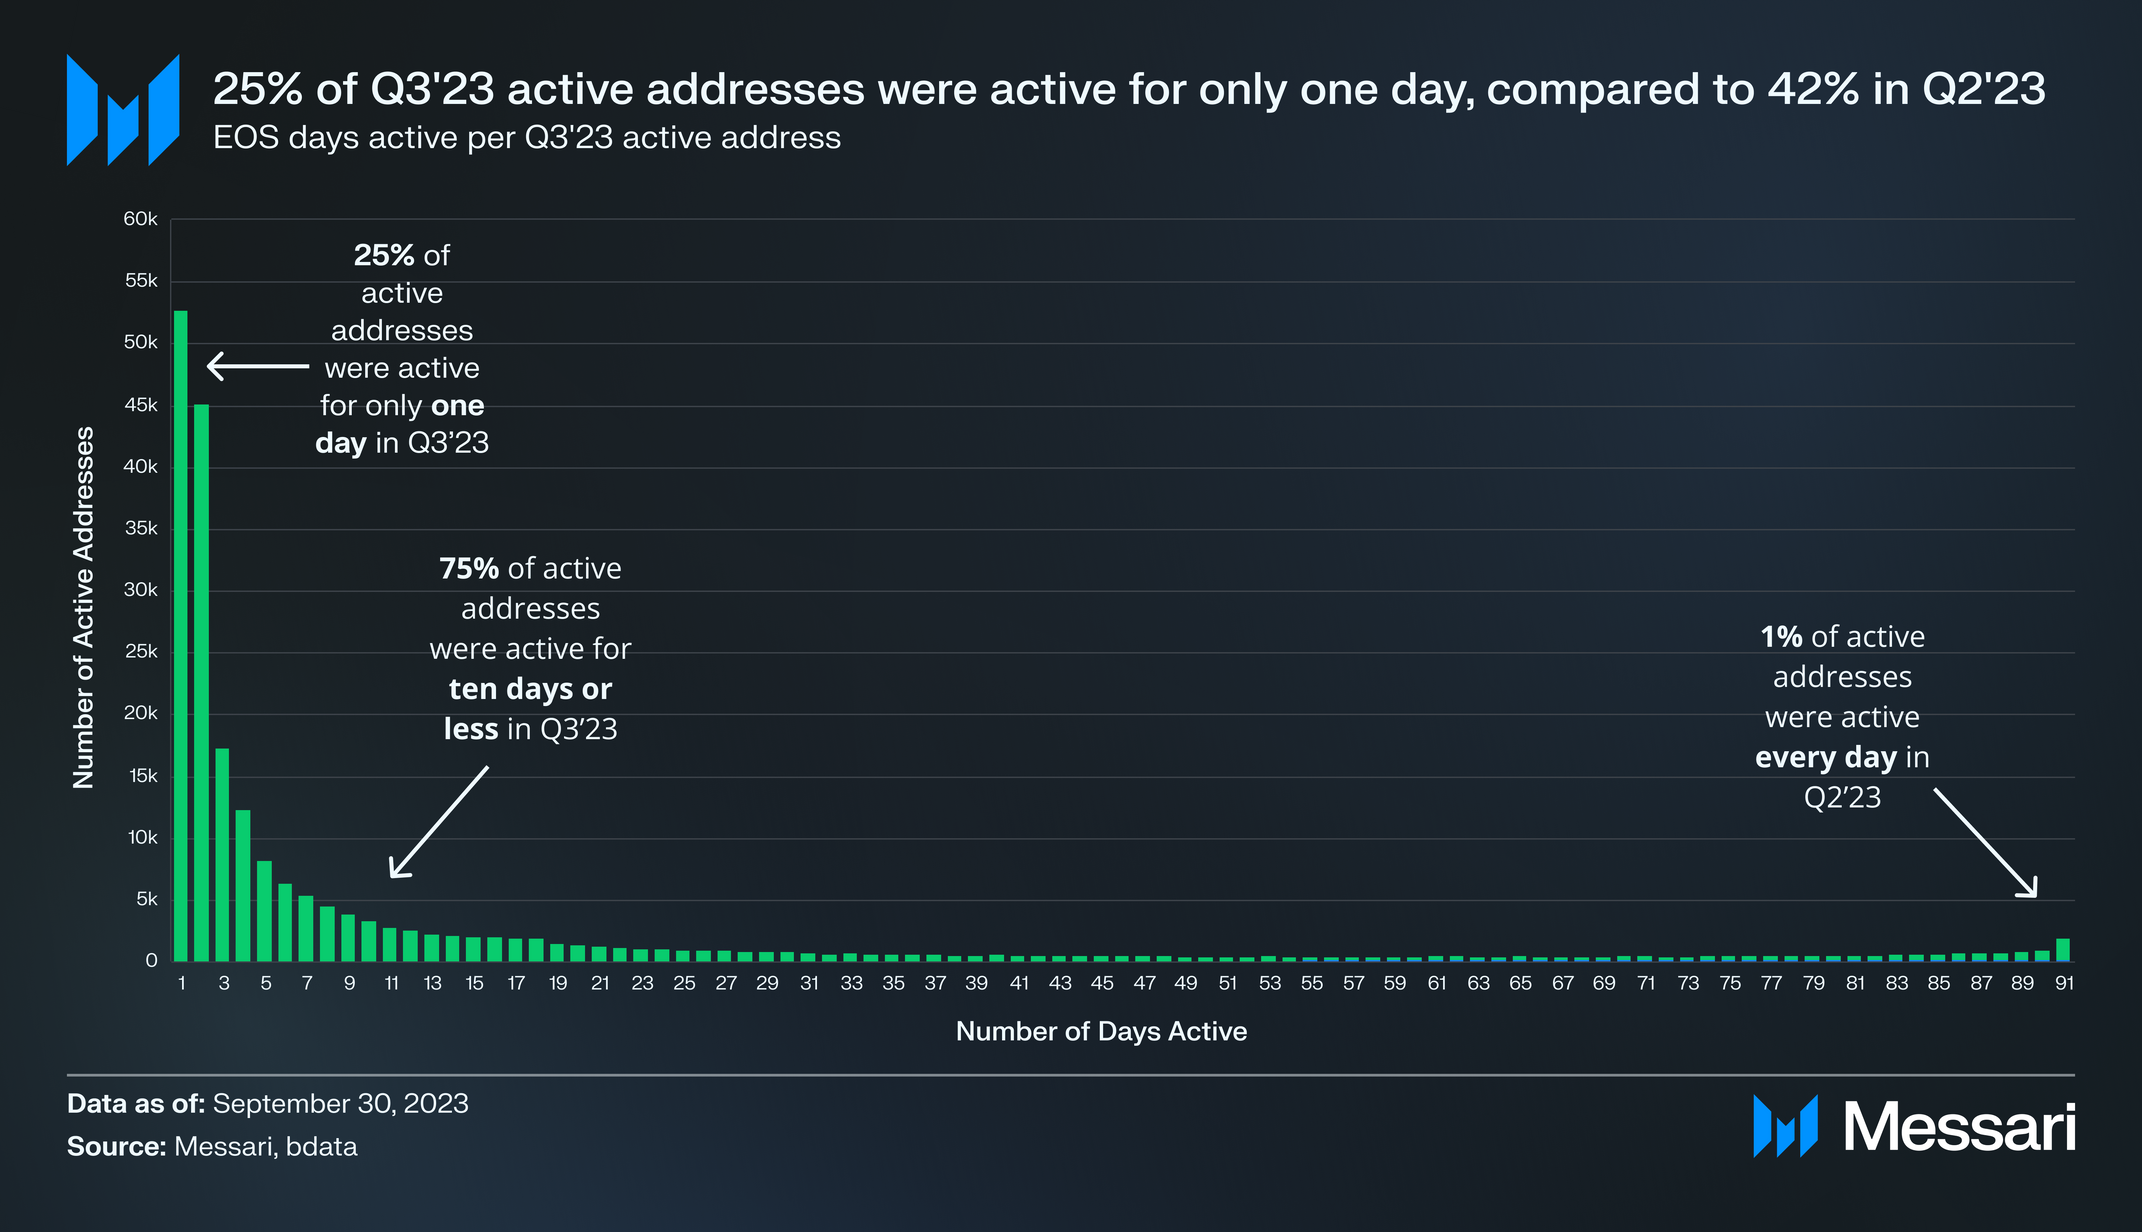
There were 212,000 total unique active addresses in Q3’23, a 39% QoQ decrease. However, the active addresses in Q3’23 were generally more active than those in Q2’23, measured by the number of days each address was active. In Q3’23, 25% of active addresses were active for only one day, compared to 42% in Q2’23. Similarly, 75% of active addresses were active for ten days or less in Q3’23, compared to four days or less in Q2’23.
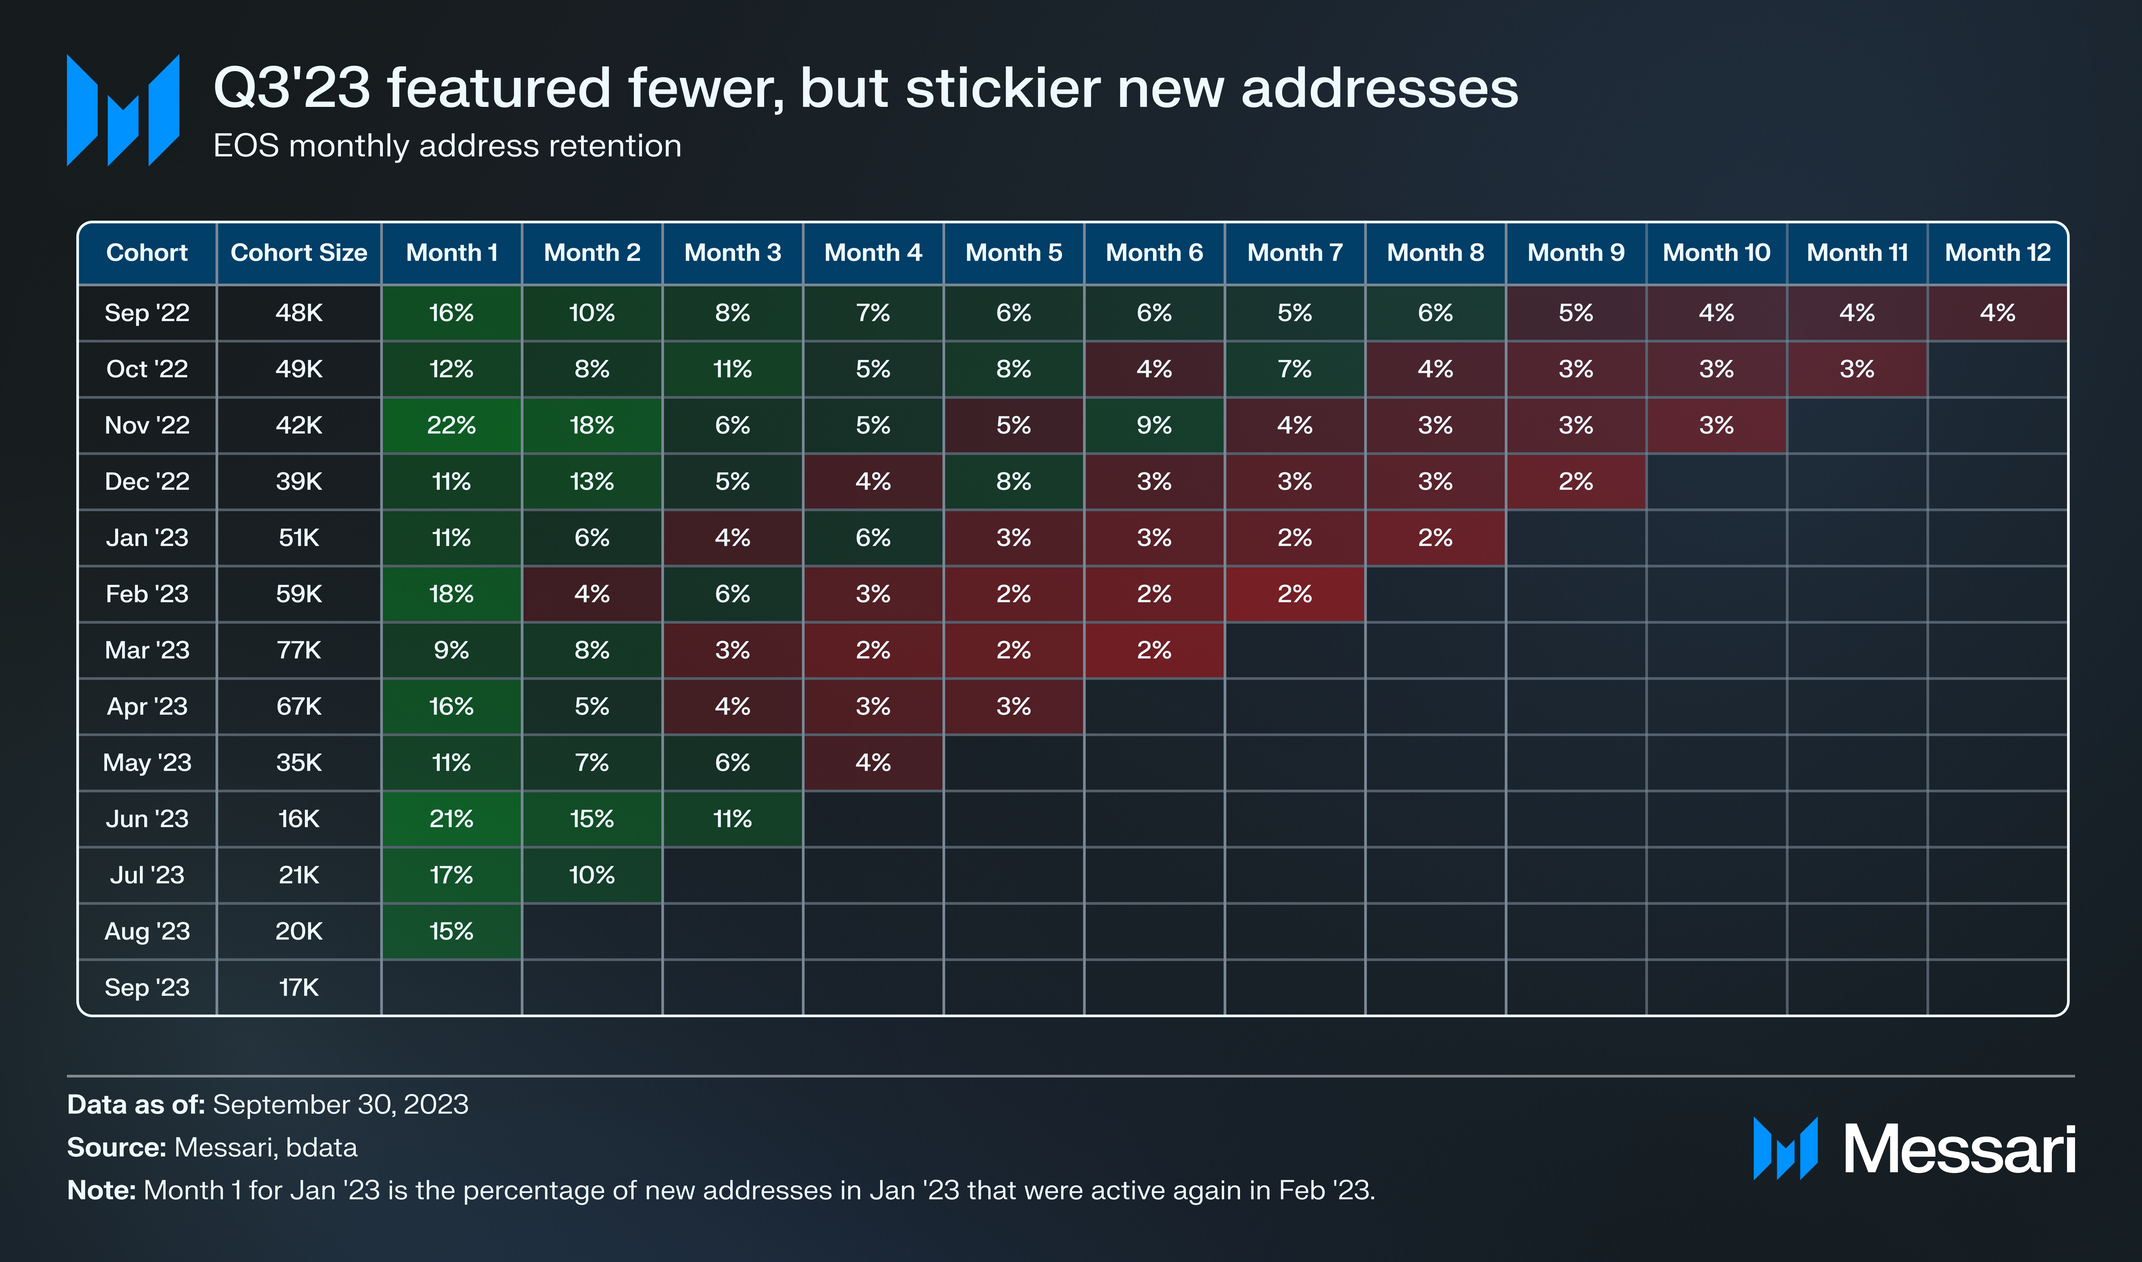
New addresses decreased by 50% QoQ to an average daily figure of 652. Although there have been fewer new addresses, they have tended to be stickier in recent months. The June 2023 - August 2023 cohorts averaged a 17% first-month retention rate, compared to 14% for the September 2022 - May 2023 cohorts.
EOS EVM
Activity on the EOS EVM has remained relatively low since its launch on April 13. In Q3’23, there were 1,000 average daily transactions and 252 average daily active addresses, QoQ decreases of 80% and 20%, respectively. However, daily transaction figures began picking back up in mid-September, sustaining over 1,000 daily transactions from September 13 to the end of the quarter except for one day.
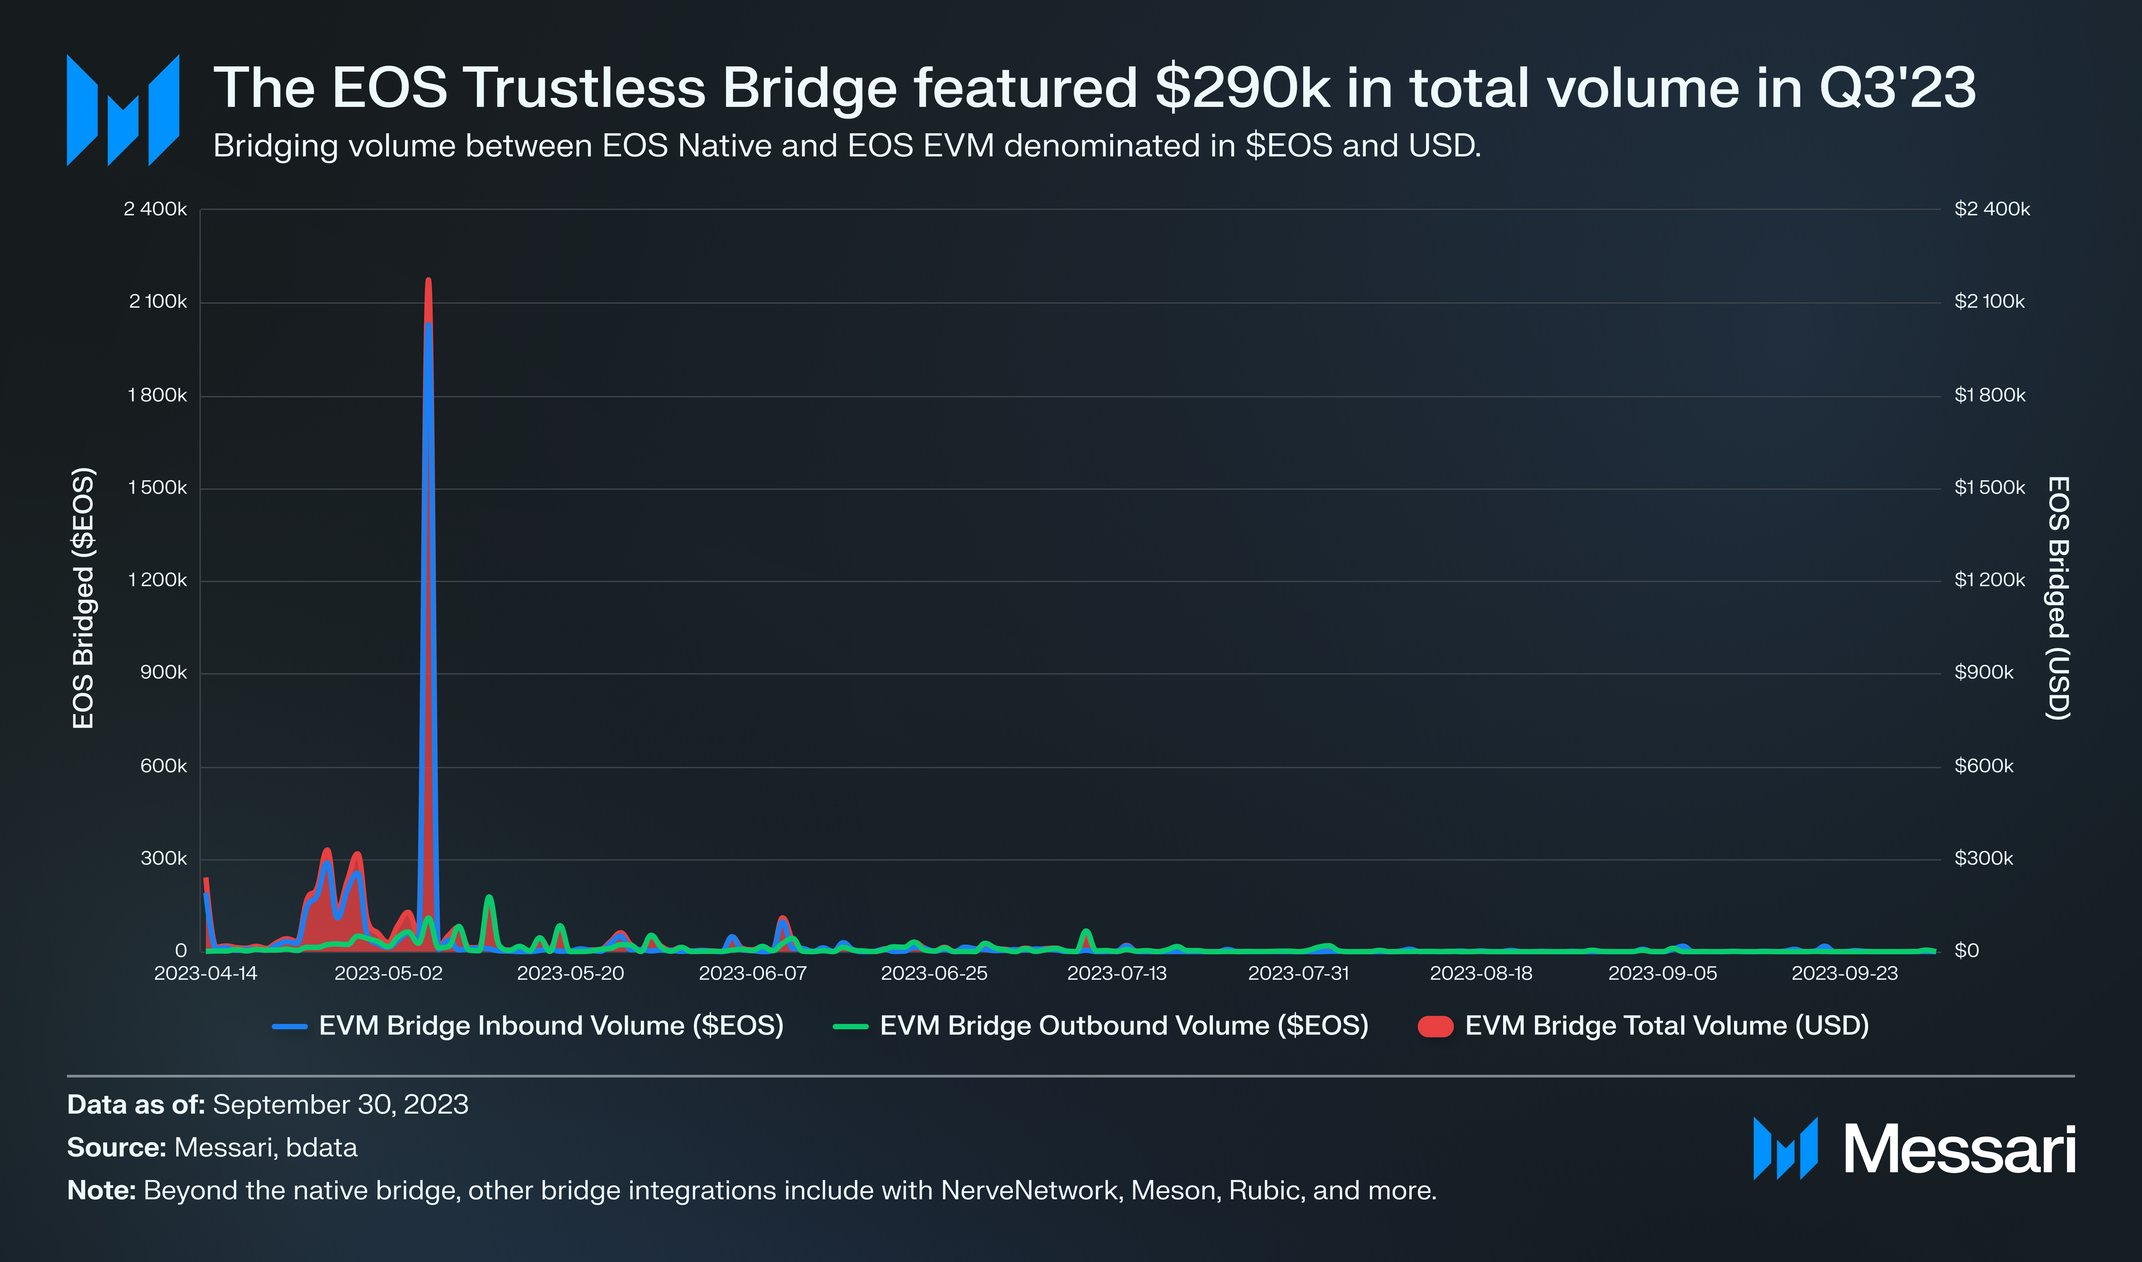
Users can bridge to the EVM either through the trustless EOS native <> EVM bridge or through third-party bridges connecting the EVM to other networks. The trustless EOS native <> EVM bridge only supports transfers of $EOS to externally owned accounts (not smart contracts). At the end of August, the ENF launched a trustless bridge front end, allowing users to deposit from and withdraw to their EOS account or centralized exchange, starting with OKX. The EOS EVM V0.6.0 upgrade, currently on testnet, will add USDT support to the trustless bridge.
Activity through the trustless bridged decreased substantially this quarter. $EOS bridged from EOS native to EOS EVM decreased from over 4.2 million to 0.17 million. The Q2 figures are driven up by when the exploiter of DeFi protocol PayCash bridged almost 2 million $EOS to the EVM, transferring the stolen funds to thousands of addresses on the EVM in portions of a few hundred $EOS.
Users can also bridge to EOS EVM from other EVMs and centralized exchanges. Soon after launch, the ENF partnered with Multichain to connect the EOS EVM with Multichain’s supported networks through its token bridge. At the end of July, the ENF announced that around $400,000 worth of funds were locked in the bridge after the bridge ceased operations in mid-July.
At the beginning of July, bridging protocol NerveNetwork integrated on the EOS EVM. Other cross-chain protocols connected to EOS EVM include Meson and Rubic.
Security and Decentralization
EOS validators earn block rewards funded by 1% annual inflation. Of this 1%:
25% is allocated to validators in proportion to the number of blocks they produce.
75% is allocated to validators in proportion to the number of votes they receive from $EOS holders.
Only the top 21 validators (“active block producers”) with the most voting power participate in consensus in a given round. Thus, the 25% of the 1% inflation only rewards active BPs. However, validators outside the top 21 (“standby BPs”) are still rewarded from the 75% portion of the 1% inflation if they meet certain criteria. At the end of Q3’23, there were 63 validators earning validator rewards.
At the end of the quarter, there was over 179 million $EOS ($103 million) staked and voting for validators, a 11% QoQ decrease. This represented around 16% of the circulating supply. Note that the same staking contract is used for voting for validators and acquiring network resources. An additional 107 million $EOS was staked but not voting for validators. Around two-thirds of this comes from tokens that were yet to vest to the original EOS contributor Block.one (B1). Block producers froze the vesting contract due to B1’s lack of contribution back to EOS. There are currently no plans to unfreeze, burn, or do anything else with these tokens.
In EOS’s Delegated Proof-of-Stake (DPoS) model, a tokenholder does not delegate tokens toward one validator; instead, they stake their tokens and then can vote for up to 30 validators. Each validator would then receive that tokenholder’s full amount as voting power. For example, if a tokenholder had 1 million voting power and voted for 30 validators, each validator would have 1 million voting power. Due to this system, it is impossible to precisely measure how much stake is delegated to all validators versus the top 21 (active BPs).
In order to take over the network through a two-thirds attack, a malicious actor would need to control 15 validators. Because of the abovementioned voting power system, a malicious actor would need enough stake to control the seventh highest validator by voting power. At the end of the quarter, this threshold was 129 million $EOS ($75 million).
Geographic diversity is also an important factor in the resiliency of a validator network. Of the active BPs at the end of the quarter, the Cayman Islands was the most popular hosting location, with four validators, followed by Hong Kong with three. Asia was the most popular region with 10 validators.
Upgrades and Roadmap
The EOS Network Foundation continues to further development on both EOS native and EOS EVM. The most notable development is the upcoming upgrade to Antelope Leap 5.0, planned for Q4’23. The milestone upgrade will implement a modified variant of HotStuff, a BFT-based protocol developed by the Facebook team working on Libra. The upgrade will bring several improvements including expanding the validator count beyond 21 and bringing near-instant finality. Additionally, it will separate the responsibilities of a validator within the consensus mechanism into three roles:
Block Proposer: responsible for ordering transactions into a block.
Block Finalizers: responsible for sending signatures on block proposals to the Consensus Leader.
Consensus Leader: responsible for collecting signatures from Block Finalizers and generating a Quorum Certificate.
At the launch of Antelope Leap 5.0, active BPs will fulfill all three roles. But in the future, the different roles can be fulfilled by different parties. For example, block proposers could continue being limited to around 21 nodes, but block finalizers could be opened up to significantly more validators. This would improve security and decentralization by having more voting validators without meaningfully reducing performance by keeping block proposers to high-performance nodes.
The ENF’s September program and operations report listed an estimated launch date of November 28, 2023, for the upgraded consensus mechanism.
Aside from addressing Antelope’s three-minute transaction process, instant finality will also complement Antelope IBC and allow for near-instant cross-chain messaging. Since its launch in January, Antelope IBC has had relatively low use on EOS, though its activity increased in Q3’23. In the quarter, there was an average of 277 daily calls of EOS IBC-related contracts from an average of 31 daily unique addresses, a 40% and 23% QoQ increase, respectively.
At the beginning of September, the ENF published the EOS EVM roadmap, outlining upcoming upgrades and features. Later in September, EOS EVM V0.6.0 went live on testnet. The upgrade includes support for USDT on the trustless bridge, a Pyth Network oracle integration, and more. Future upgrades outlined in the roadmap include supporting all EOS native tokens on the trustless bridge, EIP compatibility starting with EIP-1559 and EIP-4337, trustless bridge front-end refresh, RPC scalability enhancements, and more.
The ENF also announced at the beginning of Q3’23 that BlockSec is conducting a full code audit of the EOS EVM, which previously underwent an audit from Sentnl before launch.
Ecosystem Overview
Popular Contracts
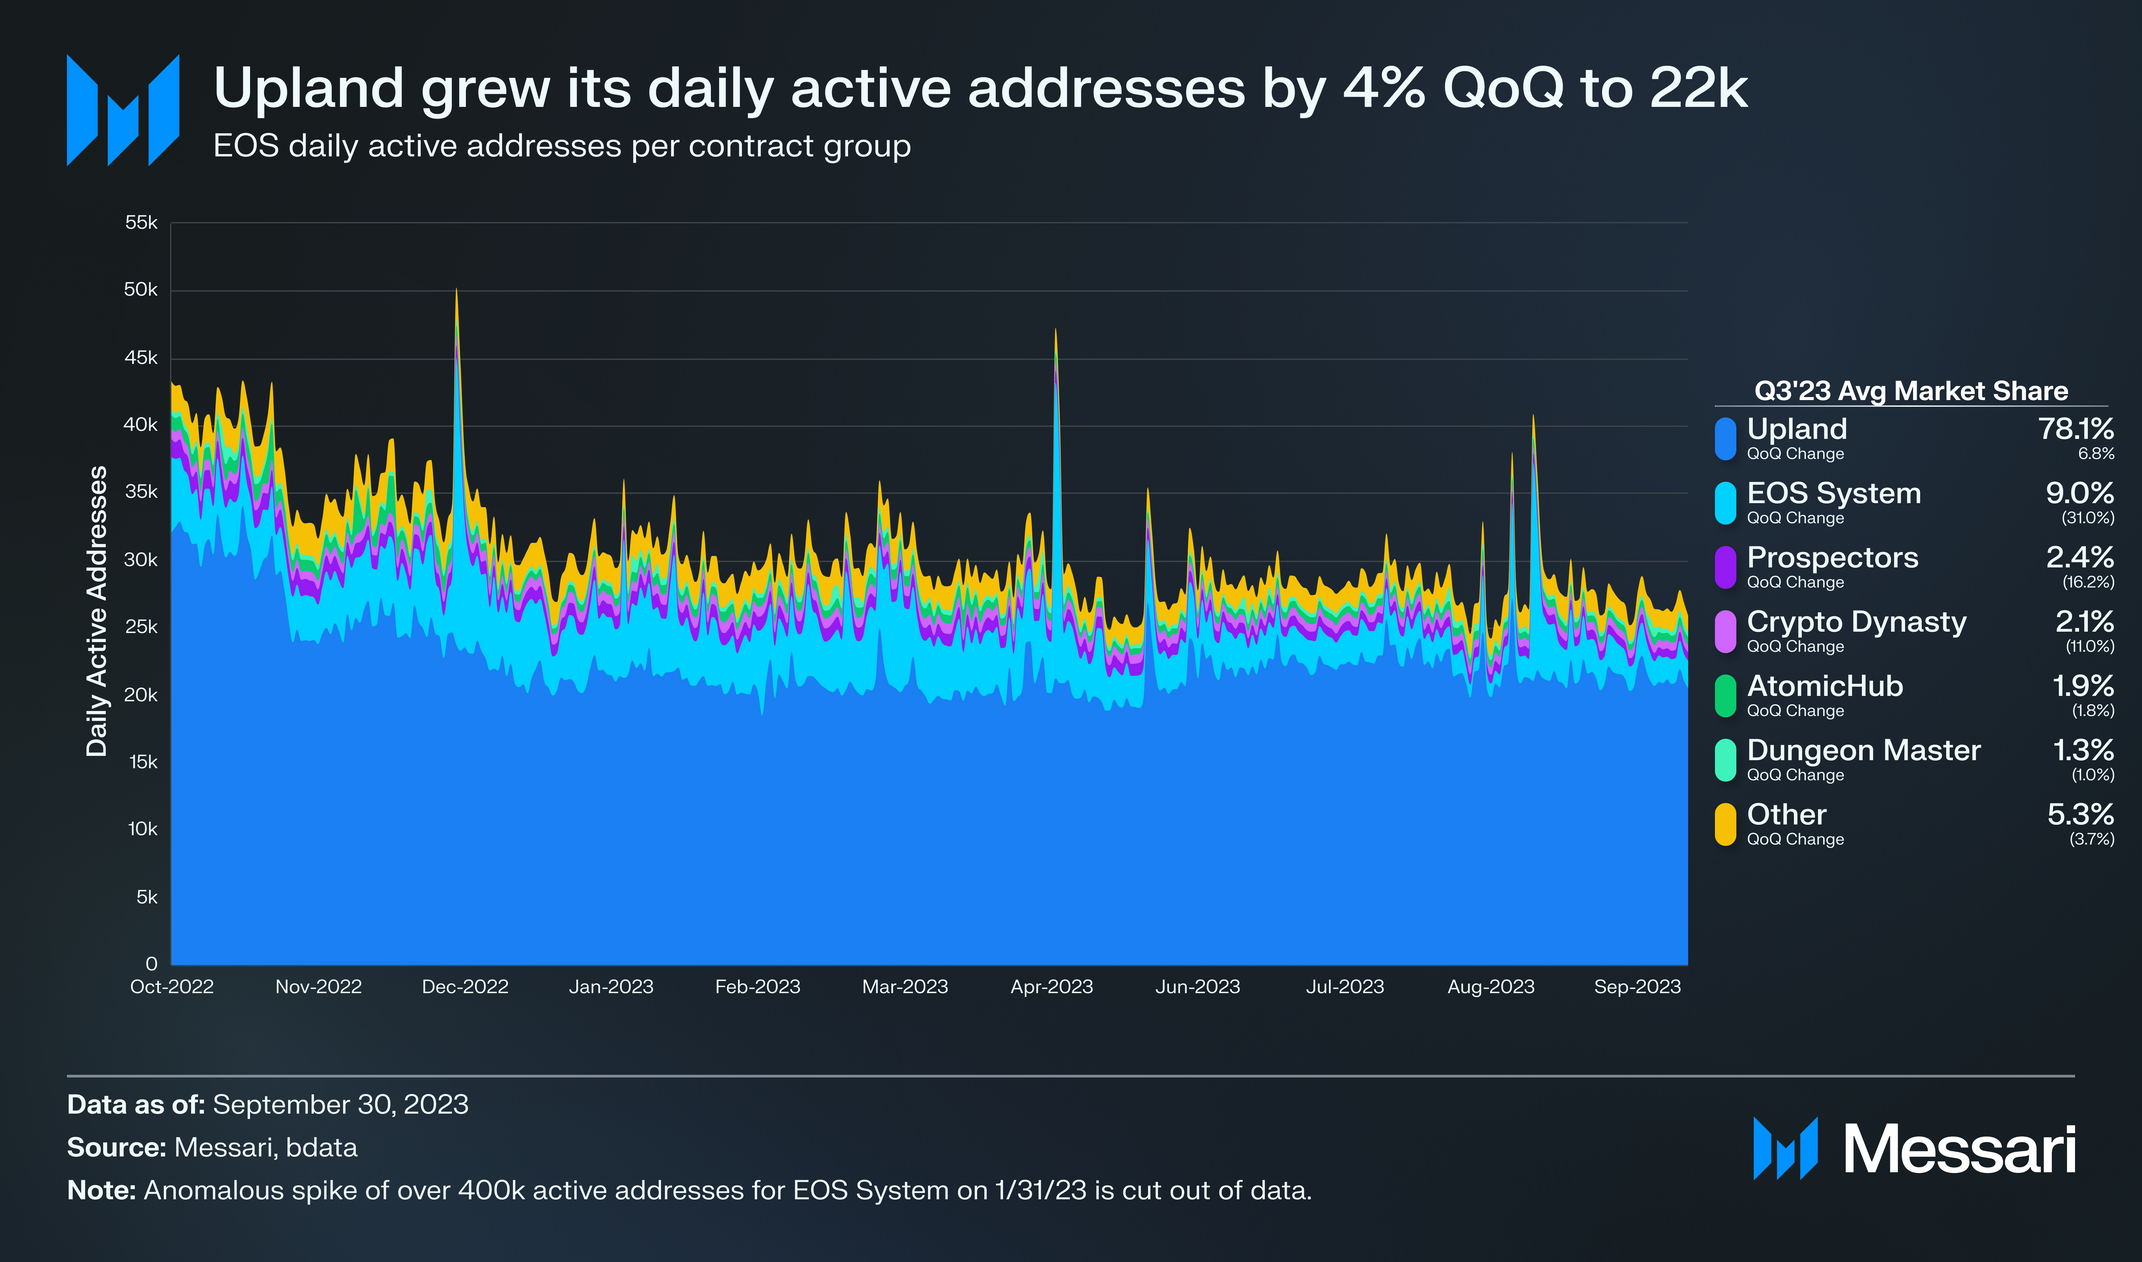
Virtual property game Upland is the most popular EOS contract group by daily active addresses. In Q2’23, Upland averaged 22,000 daily active addresses, a 4% QoQ increase. The EOS System contract, which handles functions such as delegation and resource management, was the second most popular contract group. It averaged 2,500 daily active addresses in the quarter, a 33% QoQ decrease.
Rounding out the top six contract groups by daily active addresses were MMO strategy game Prospectors, NFT marketplace AtomicHub, RPG game Crypto Dynasty, and NFT staking game Wombat Dungeon Master. Each of these contract groups experienced a slight QoQ decrease in average daily active addresses.
Upland was the only major contract group to grow its average daily active address count. Its market share grew from 73% last quarter to 78% this quarter.
This chart includes only contract calls from addresses on the same day that the address is created (“newly created addresses”). It highlights what addresses do when they join the network, revealing several noticeable differences from the above analysis on contract calls from all addresses.
EOS contract groups experienced a reduction in daily unique newly created addresses across the board. The EOS System had the most significant decrease among top contract groups, down 85% QoQ to an average daily figure of 54. Its market share also decreased from 79% to 44%. This indicates that new addresses are participating in the ecosystem at a higher rate.
Upland’s average share of newly created addresses was 23%, significantly less than its 78% average share of all addresses. While this discrepancy indicates that Upland’s activity is driven by existing users, Upland still makes up a notable share of newly created addresses.
PayCash was an exception among other top contract groups, increasing its daily unique newly created addresses by 19% QoQ to 6. PayCash is a DeFi protocol that offers swapping and fiat-to-crypto on-ramping features.
Along with PayCash, Red Packet was a new entrant into the top six contract groups, averaging 5 daily unique newly created addresses. Red Packet is an implementation of the WeChat red envelope application, allowing users and projects to gift tokens to each other. Red Packet raised over $2,000 on public goods funding platform Pomelo.
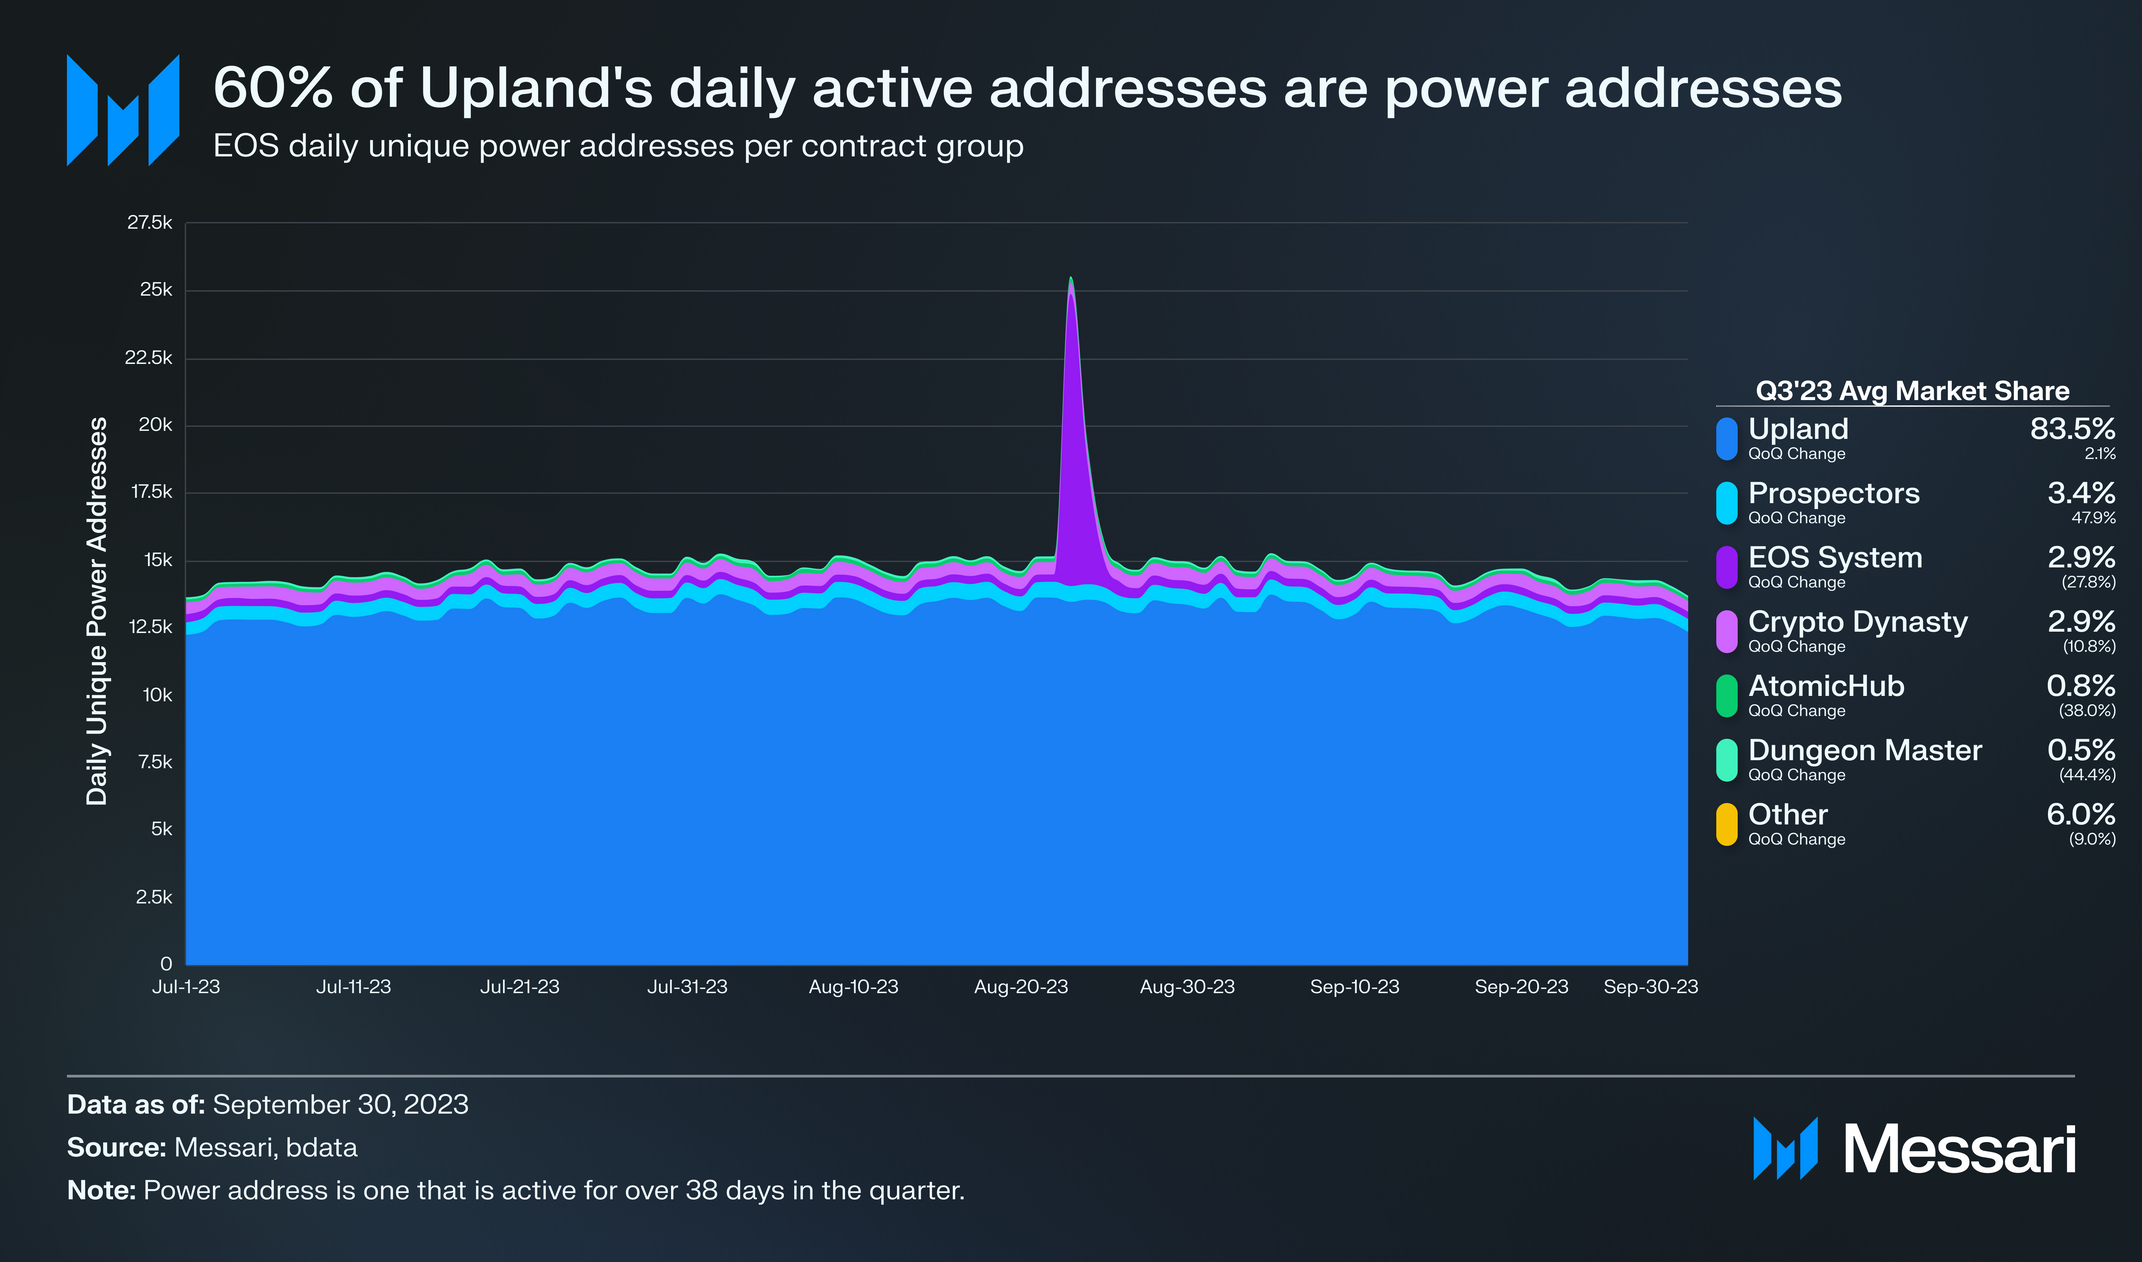
This chart again only looks at contract calls from a subset of addresses; here, power addresses. A power address is defined as one that is active for over 38 days in the quarter, which was the cut-off for the 90th percentile of addresses by number of days active.
Throughout the quarter, Upland had an average 84% share of power addresses among contract groups. Of its 22,000 average daily active addresses, over 13,000 were power addresses (60%). A large percentage of the average daily active addresses of Prospectors and Crypto Dynasty similarly turned out to be power addresses.
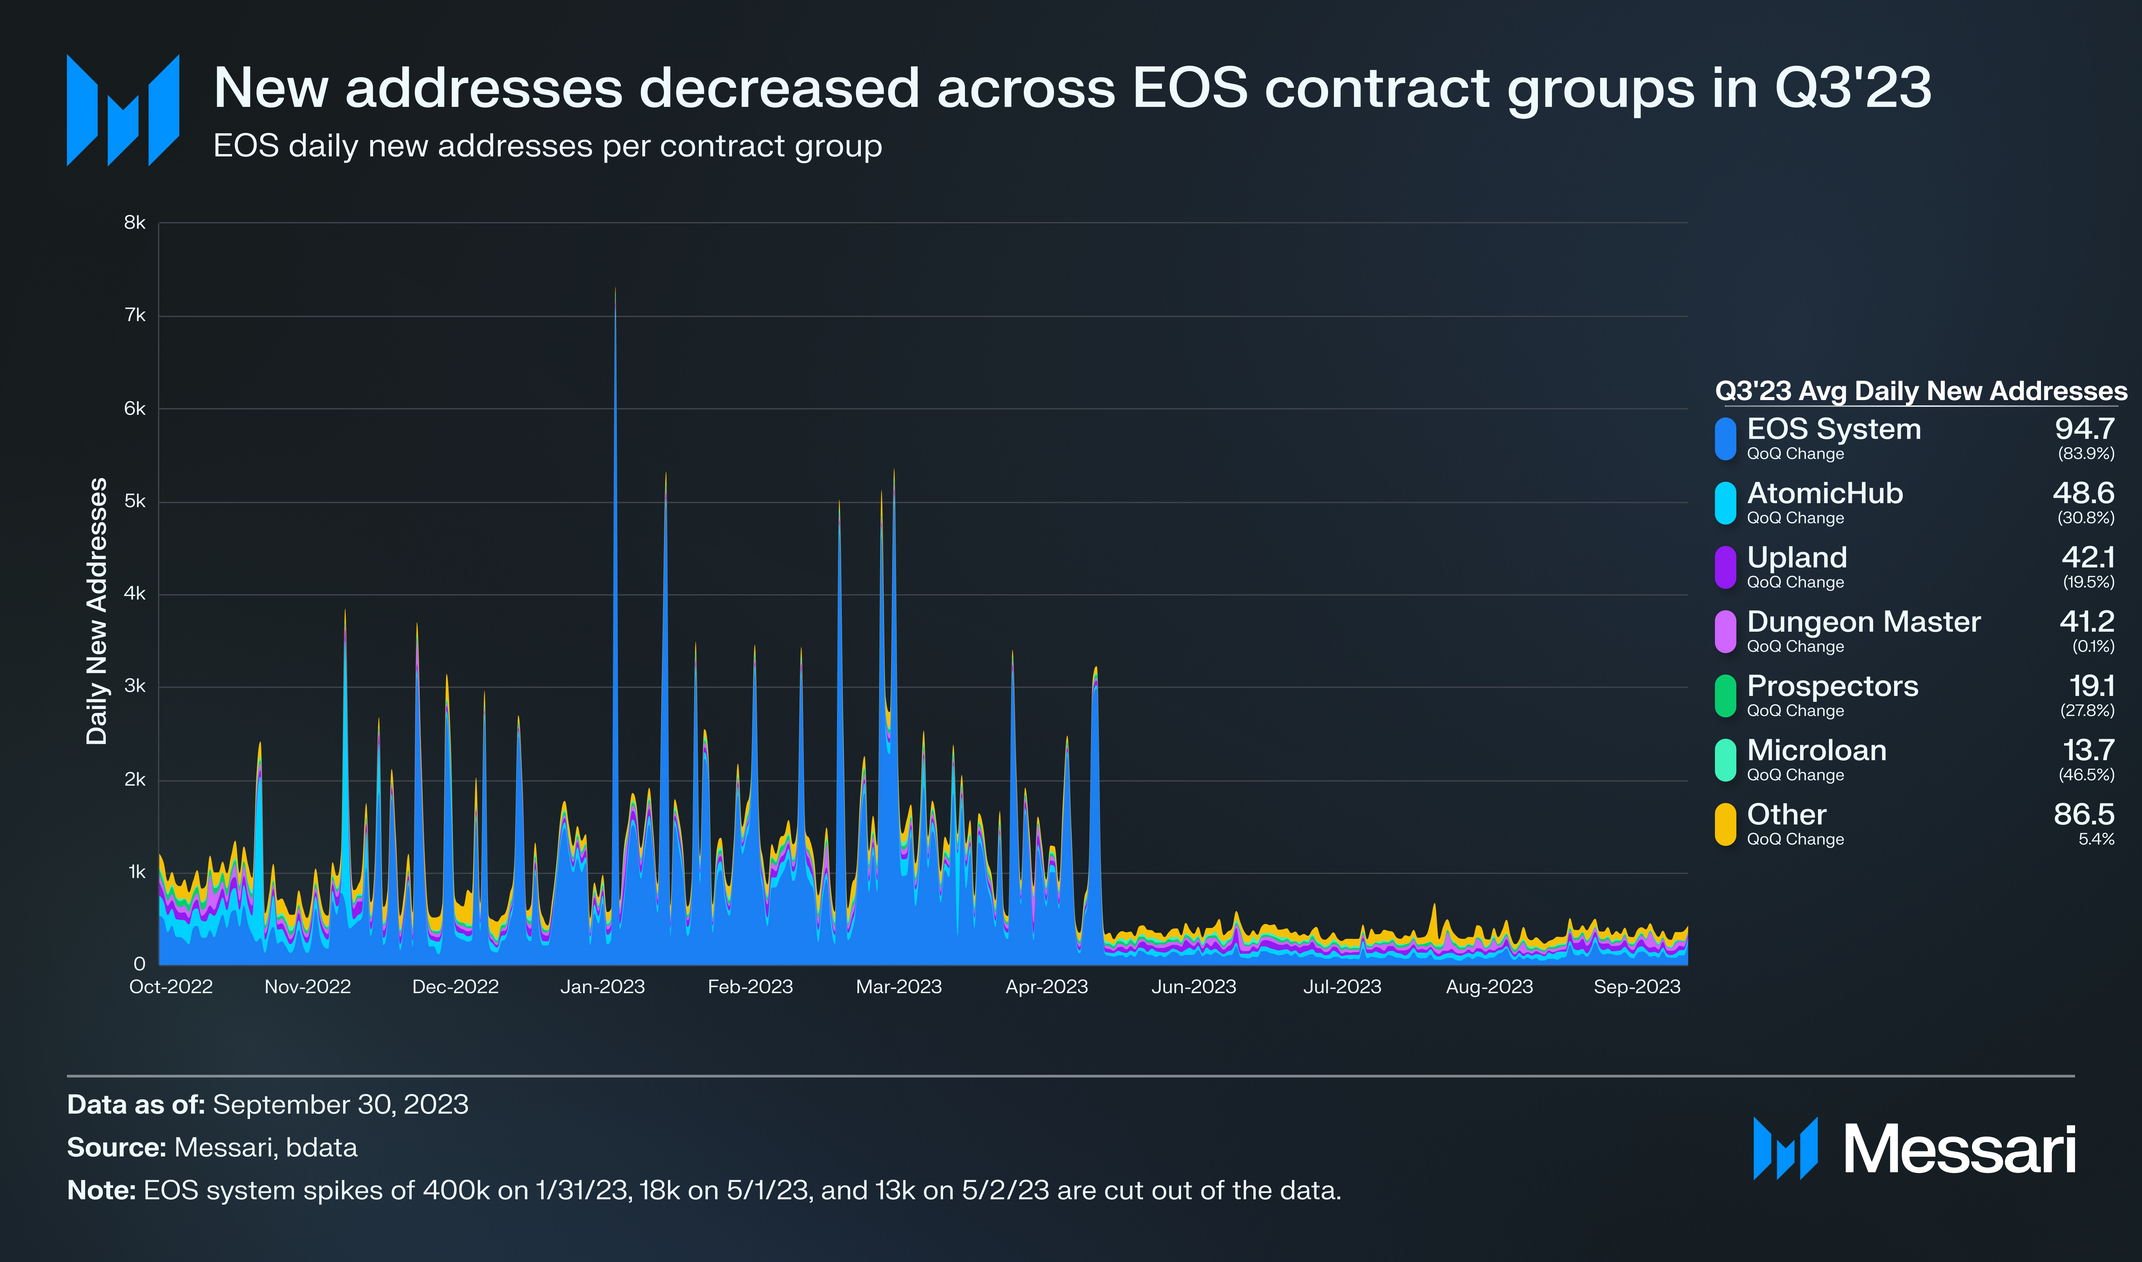
This chart re-examines all addresses (rather than just newly created or power addresses), but it counts an address’s first interaction with a contract group. This analysis reveals the number of daily new addresses for each contract group.
The QoQ decrease in average daily new addresses was felt across contract groups. Despite an 84% QoQ decrease in average daily new addresses, the EOS System is still the fastest-growing contract group at 95 daily new addresses. The EOS System will likely always have the highest number of new addresses since most new EOS addresses need to interact with it upon joining the network. Dapps in the EOS ecosystem with the highest growth rates include AtomicHub, Upland, and Dungeon Master.
DeFi
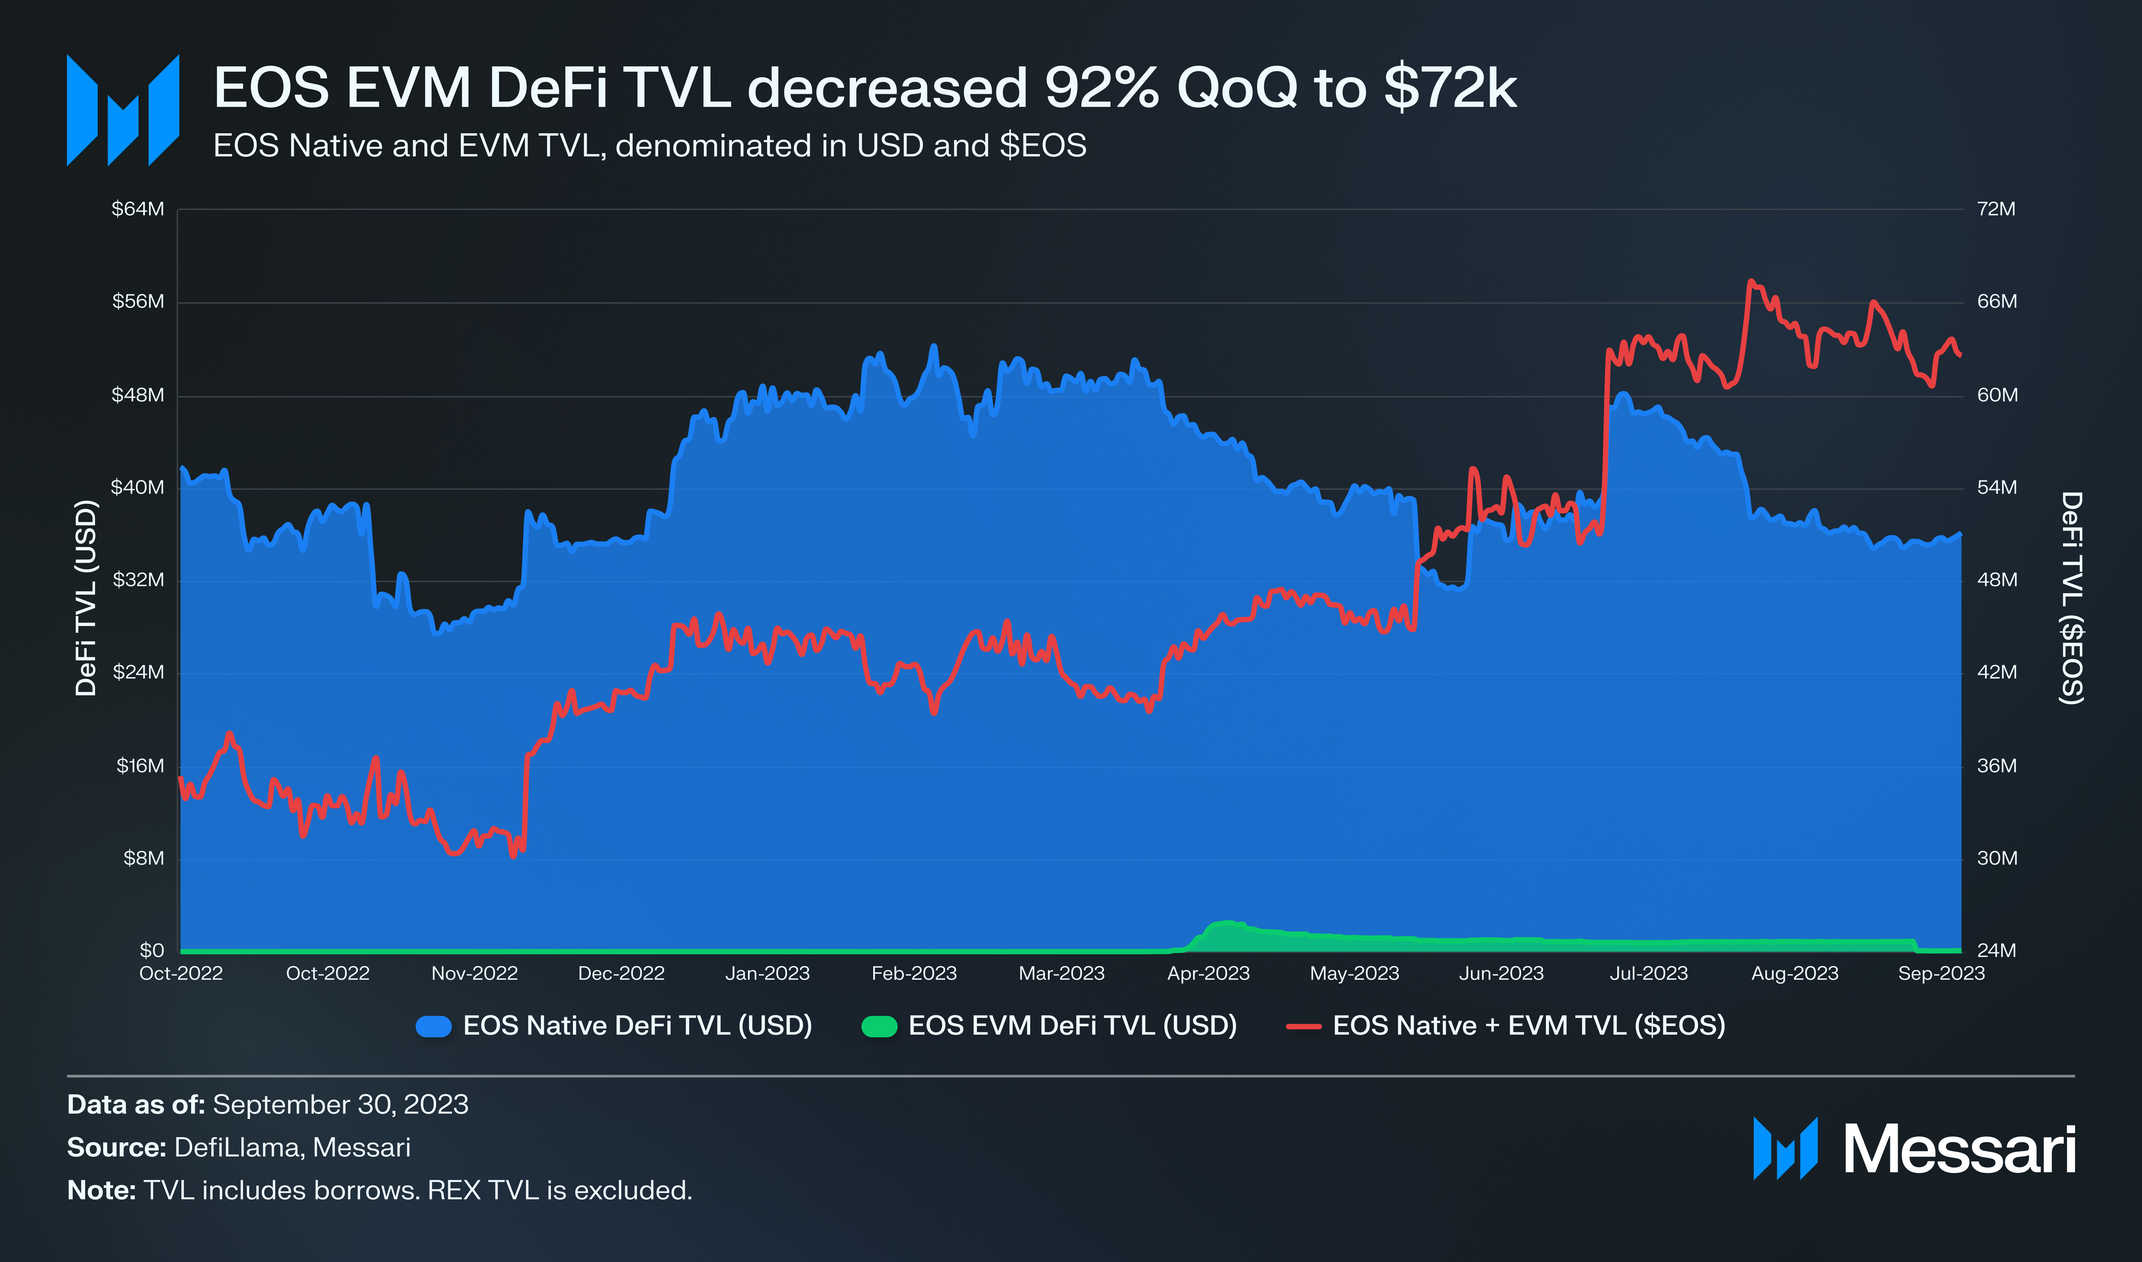
TVL on the EOS native chain increased by 1% QoQ to $36 million, ranking the network around 41st among all chains. Around half of that TVL was from Defibox, a platform featuring swapping and lending capabilities. Defibox’s market share decreased from around 65% to 61%. After suffering from an exploit in early May, PayCash’s TVL increased QoQ from $7 million to $12 million. The increase largely came from July 18-20, when TVL grew $8 million. On July 19, PayCash’s DEX volume spiked to $11 million. It’s unclear what exactly drove these events.
EOS EVM’s DeFi TVL decreased 92% QoQ to $72,000. The significant drop came from two addresses (which are likely the same user) eachwithdrawing around $380,000 in liquidity from AMM Noah Swap on September 20. Noah Swap remained the top EOS EVM protocol by TVL at $63,000.
EOS EVM’s DeFi ecosystem stands to benefit from the EVM V0.6.0 upgrade, enabling USDT transfers in the trustless bridge. To this point, the EVM has not had access to any native stablecoins, instead relying on wrapped stablecoins bridged through third parties. These coins can carry additional risk, as occurred with the Multichain incident. Since EOS Native’s USDT is a native integration, USDT transferred through the trustless bridge to the EVM is much more secure than wrapped USDT from other bridges. Many DeFi protocols have been waiting for this upgrade before conducting liquidity incentive programs.
In mid-September oracle Pyth Network integrated its pull oracle on EOS EVM, allowing EOS EVM developers to access its over 300 price feeds for cryptoassets, equities, FX pairs, and more. Previously in the quarter, Pyth added a price feed for the EOS/USD pair across its supported networks.
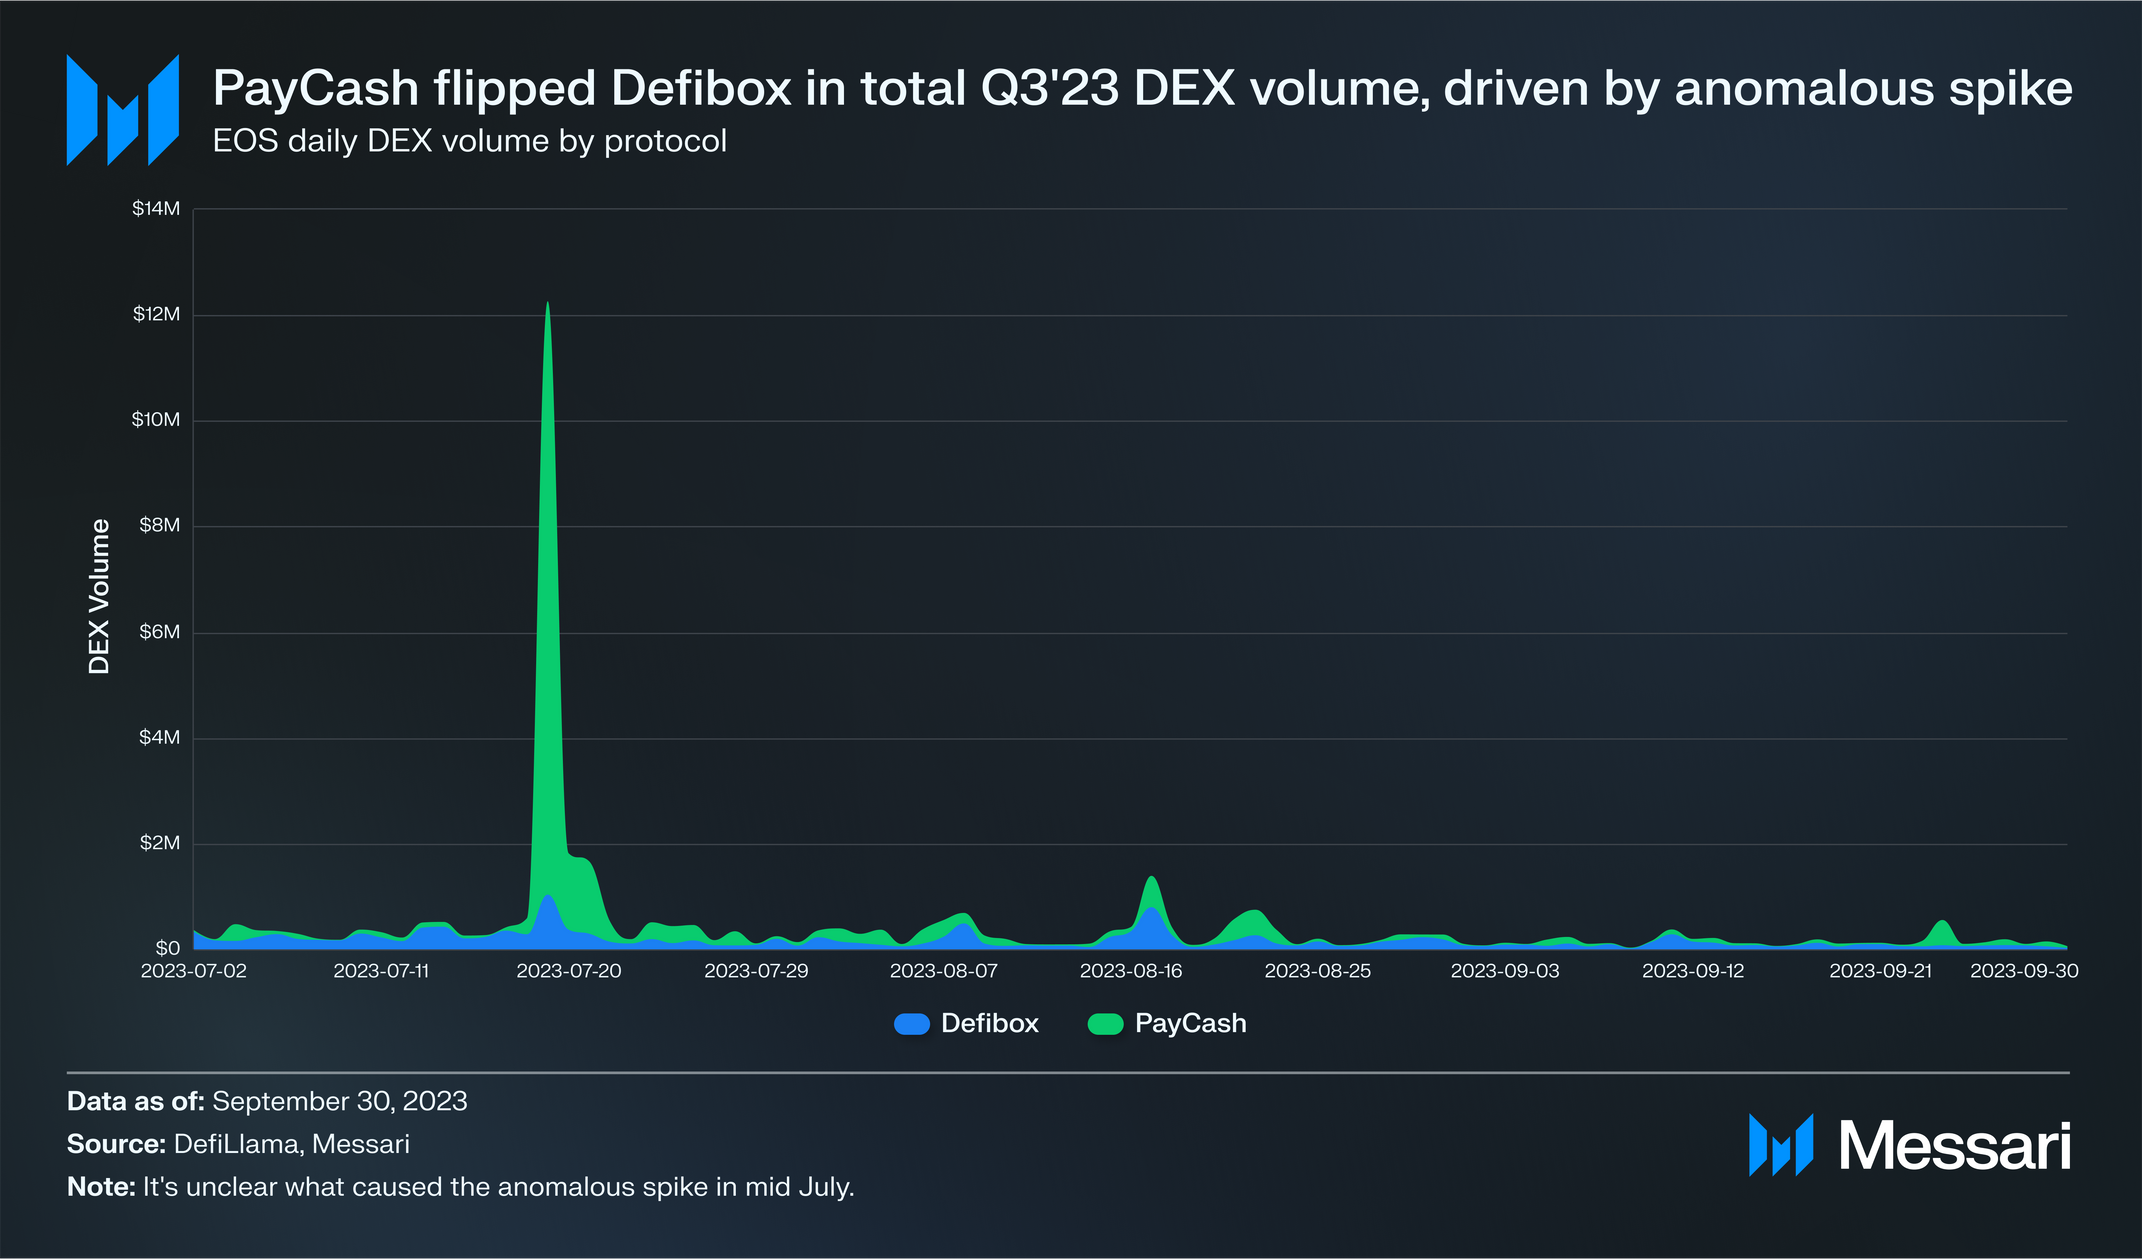
Average daily DEX volume on EOS native decreased by 12% QoQ to $435,000. As noted above, PayCash DEX volume spiked to over $11 million on July 19. PayCash flipped Defibox in total DEX volume this quarter. But if the July 19 spike is excluded, Defibox remained ahead.
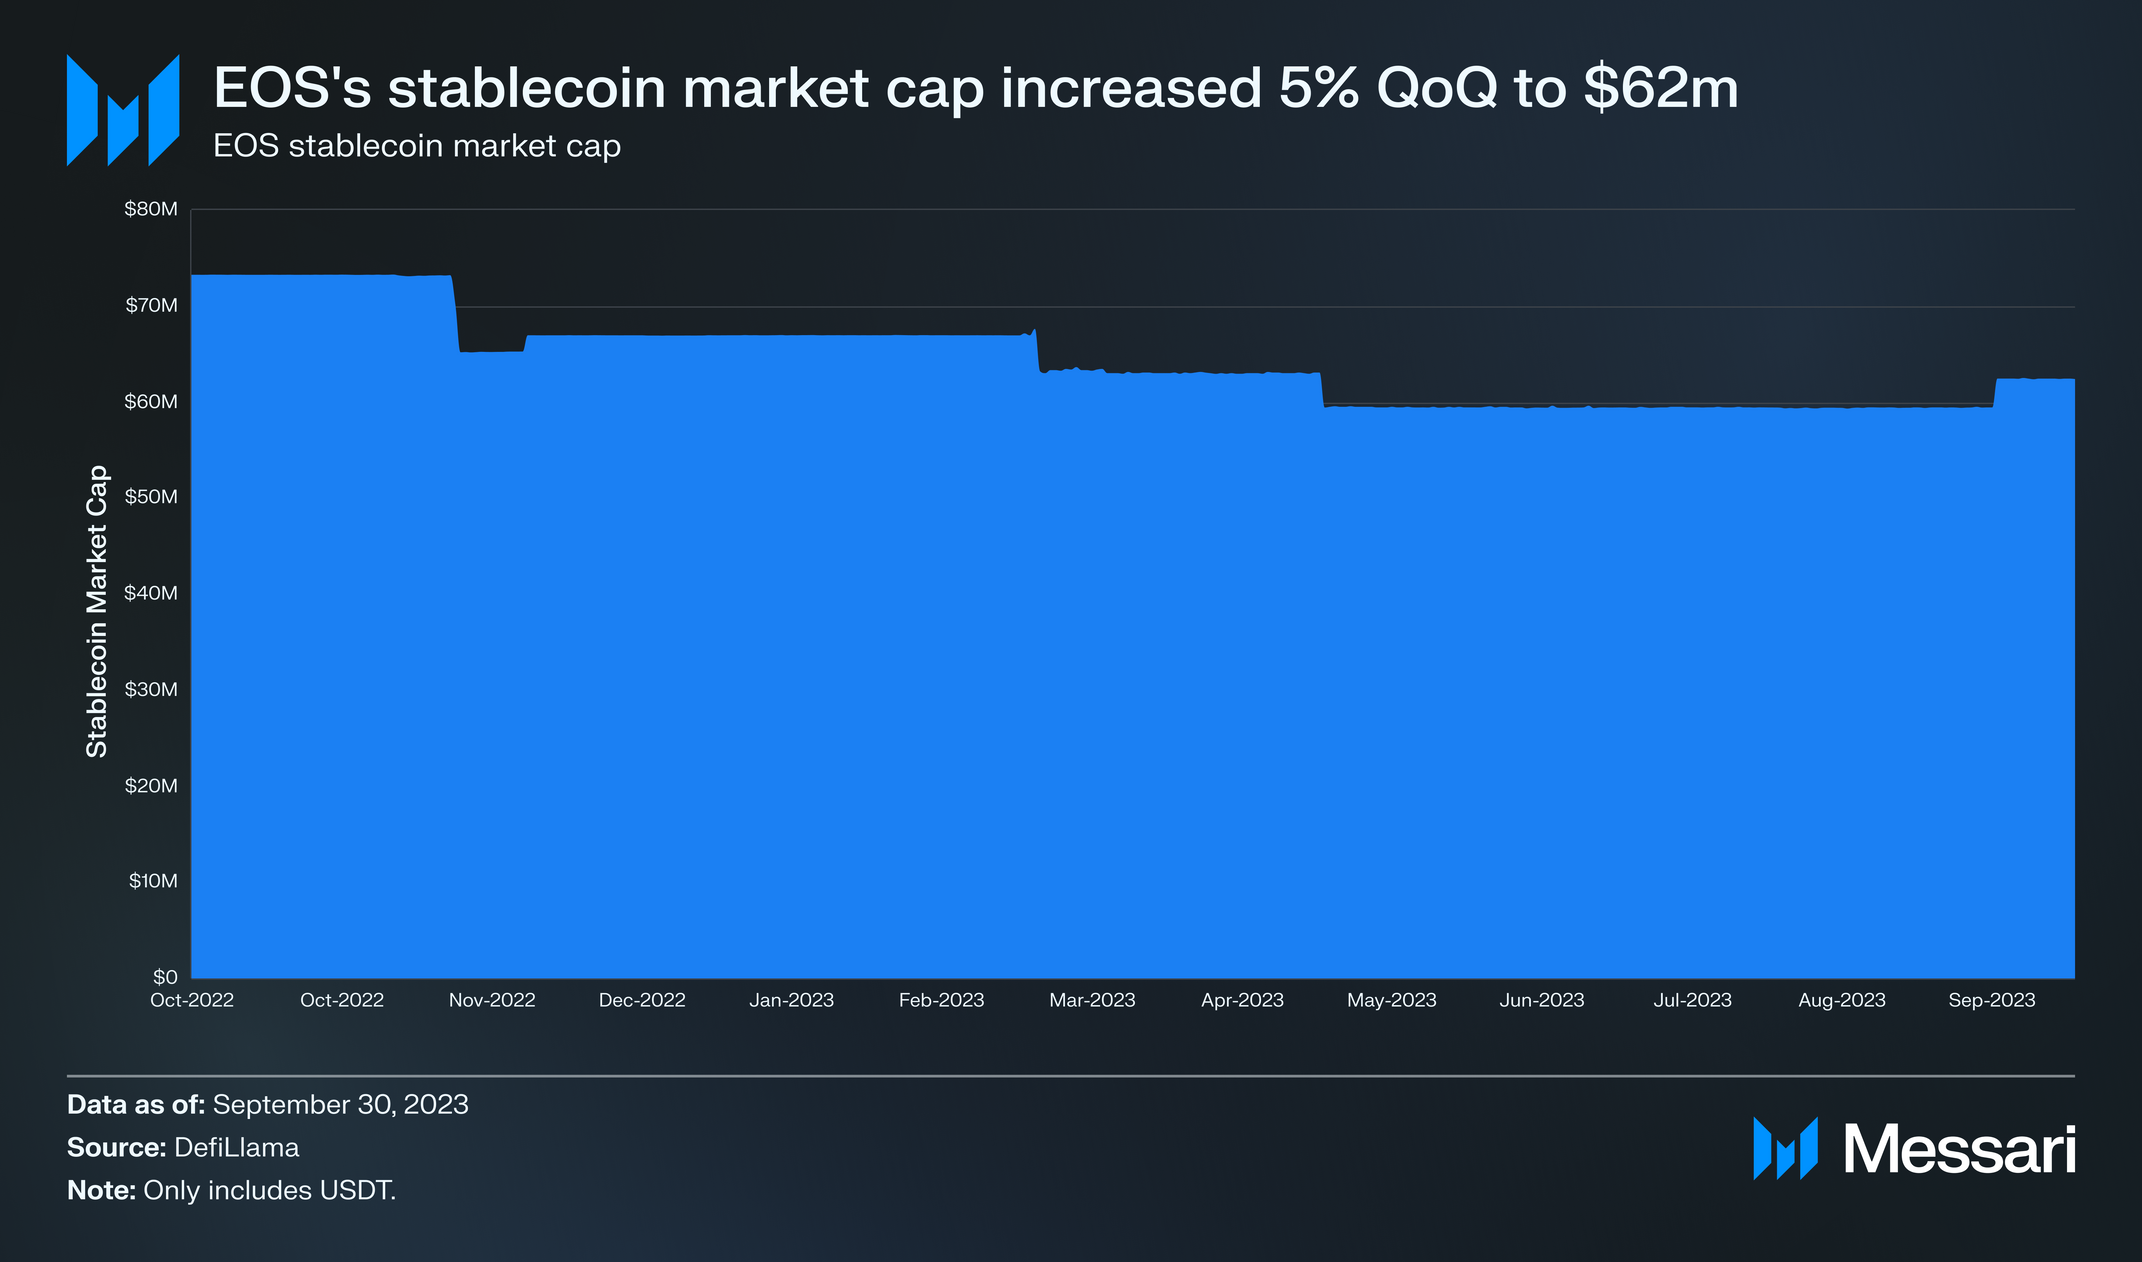
EOS native’s stablecoin market cap increased 5% QoQ to $62 million, ranking it 20th among all networks. The increase was the first increase of over $1 million since early December 2022. This figure is entirely composed of USDT. EOS is one of fourteen networks natively supported by Tether. There are also some EOS native stablecoins, namely USN, which are not included in this data. USN is an overcollateralized stablecoin generated through staking various tokens on Defibox. At the end of the quarter, USN’s market cap was around $820,000.
NFTs, Gaming, and Other
The most popular dapps by address activity on EOS are gaming-related, including Upland, Prospectors, Crypto Dynasty, and Dungeon Master.
In Q3’23, much of the new NFT and gaming-related activity occurred on the EOS EVM.
At the beginning of July, multichain NFT toolkit Collectify launched on the EVM. Collectify allows NFT creators and projects to easily create their own marketplace, minting smart contract, whitelists, and more.
In mid-July, gaming studio and NFT marketplace OpenBiSea launched on the EOS EVM. The integration brings OpenBiSea’s multichain NFT marketplace and motorcycling play-to-earn game MotoDEX to the EVM.
In mid-September, PlayZap launched on the EVM. PlayZap is a multichain arcade game platform with play-to-earn mechanics. It has over 100,000 downloads on the Google Play store. Its in-game token PZP was listed on Noah Swap soon after its integration.
The EVM Name Service (EVMNS), one of the top recipients of the Pomelo Season 6 EOS EVM pool, launched in mid-September. The project allows users to register “.evm” names to link to their address, similar to ENS on Ethereum. Over 2,000 addresses have claimed a name so far.
Development
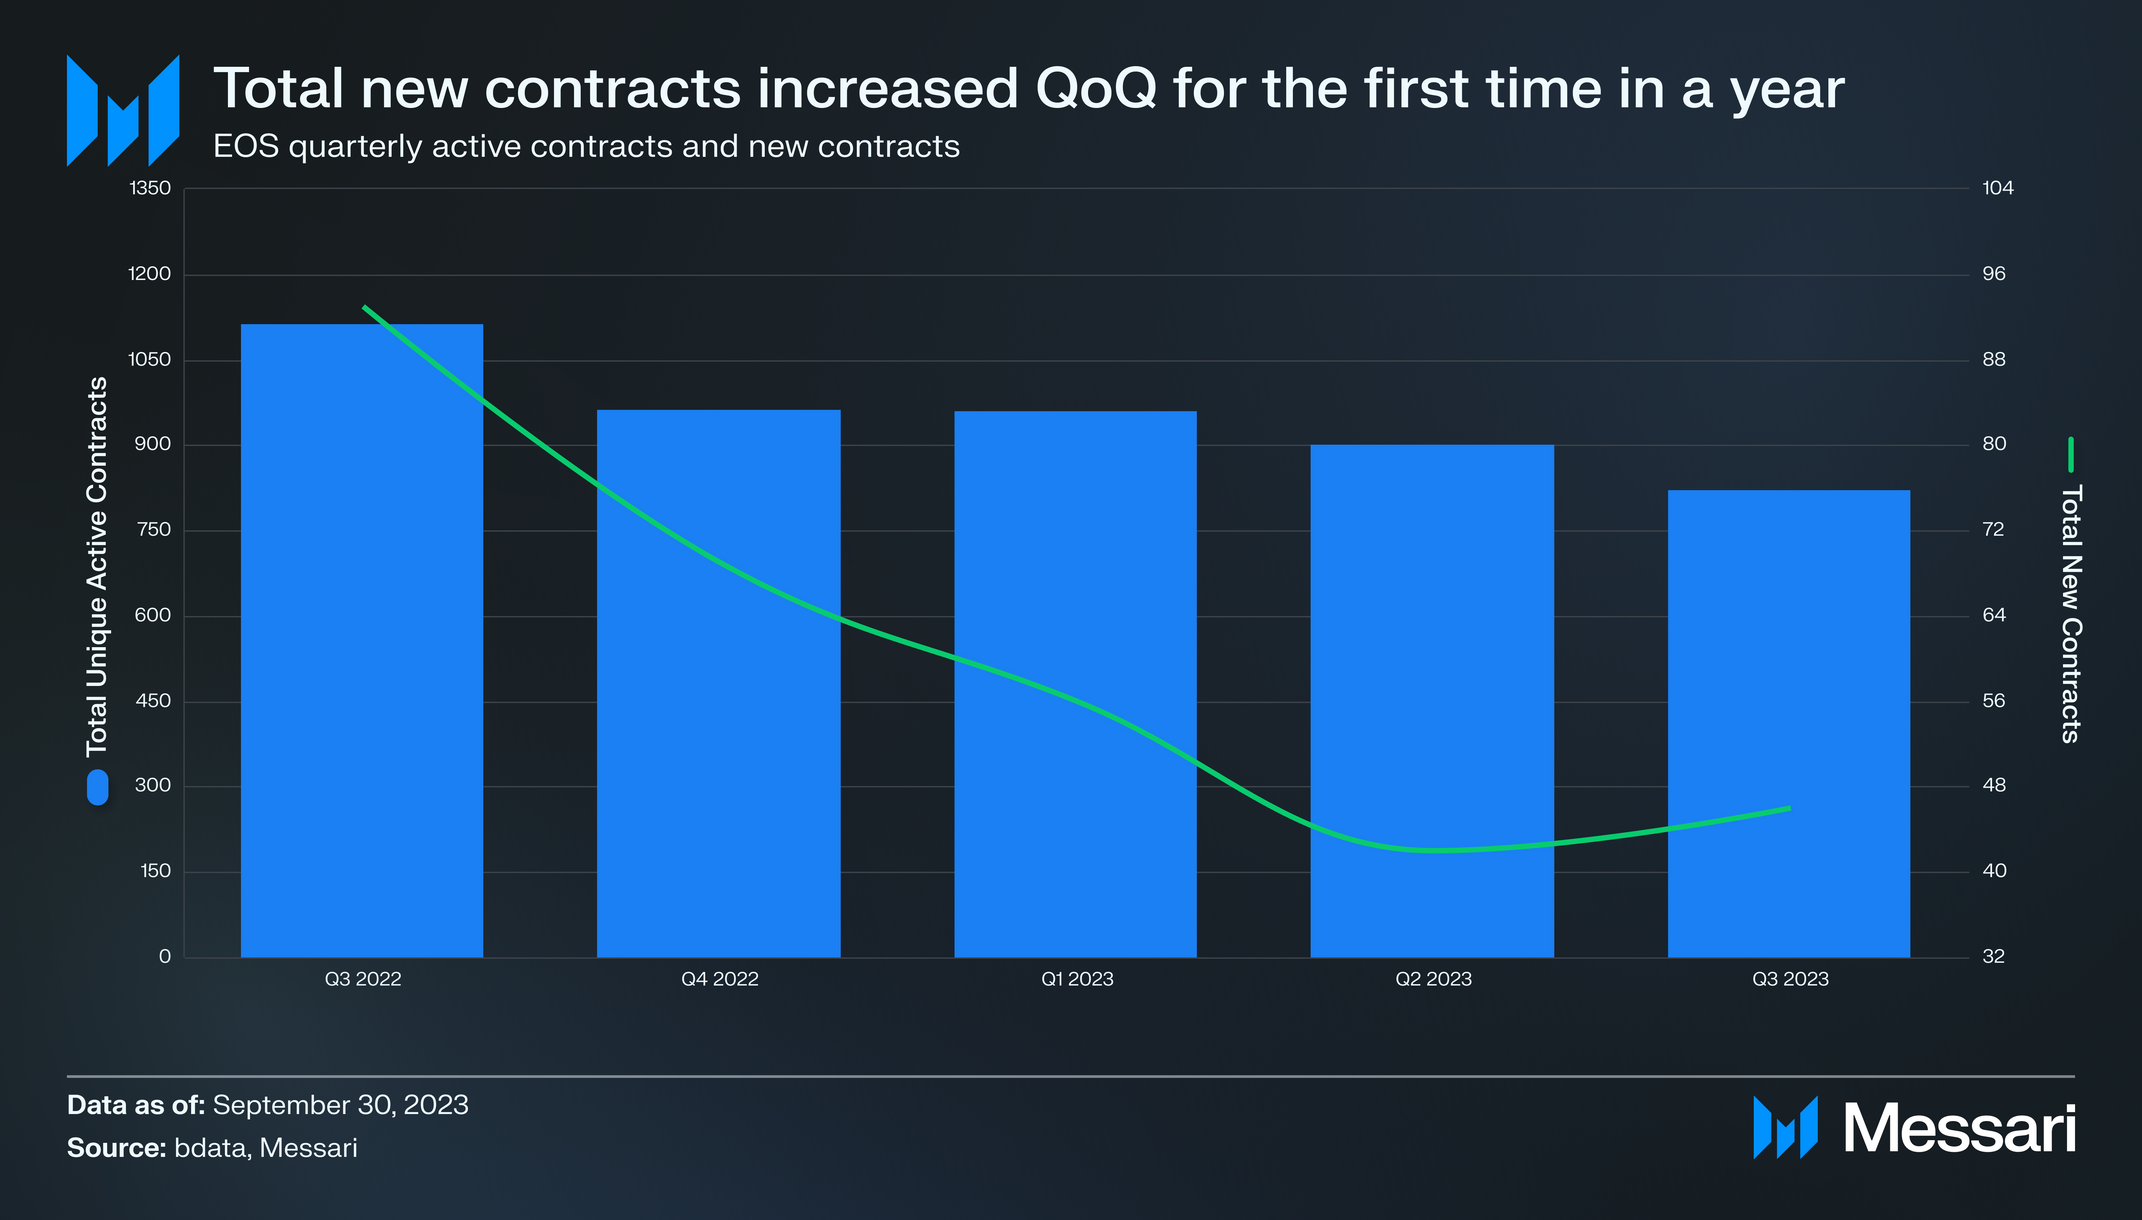
Ecosystem development, measured via the number of unique contracts called and new contracts, has gradually decreased in the past year. The number of unique contracts called throughout the quarter decreased by 9% QoQ to 820. The number of new contracts called in the quarter increased for the first time in the past year, up 10% QoQ to 46.
Several tools to improve smart contract developer experience were launched in Q3’23, including the Wharf Session Kit and the Web IDE. Wharf, an open-source project sponsored by the Antelope Coalition, launched its V1.0 Session Kit in early August. The Session Kit is the first of Wharf’s three planned SDKs, with the Account and Contract Kits in progress. The Session Kit allows developers to easily enable users to connect to a web app with their wallet, establish a session on the blockchain, and other features.
A day later, the ENF launched the Web IDE, an integrated development environment to ease smart contract development. The ENF also spun out a separate Twitter account specifically for developer relations.
In mid-August, the ENF unveiled its overall developer onboarding strategy. Beyond the Wharf SDKs and Web IDE, the strategy includes enhanced developer documentation with multilanguage support, a developer learn-and-earn portal, and attending and hosting IRL and online events.
Growth
The ecosystem growth strategy shifted significantly this quarter with the introduction of EOS Labs. EOS Labs is a new independent entity led by community member Huaqiang Wen. EOS Labs will fulfill both incubator and builder roles: it will offer financing and infrastructure to assist developers, while also developing its own set of products and tools to aid the ecosystem.
The ENF pledged to allocate a quarter of the 2% annual inflation it receives from the network to EOS Labs. As a result, the ENF is sunsetting three of its growth initiatives: Yield+, a liquidity incentive program that distributes $EOS to DeFi protocols for them to use as additional rewards; the Direct Grant Framework, a milestone-driven grant system administered by the ENF; and Pomelo, an open-source public good crowdfunding platform. As open-source software, Pomelo could continue in the future, but the ENF no longer plans to provide matching bonuses. The ENF noted that existing grants from the Direct Grant Framework will continue to be honored.
As for the reason behind the switch, the ENF explained that the operational cost associated with these programs was no longer worth their benefit and that EOS Labs would provide a better, more focused use of these funds. The ENF will revert most of its attention back to the protocol layer, with EOS Labs’s attention on the application layer.
Pomelo’s seventh and last season began receiving applications on September 20. The ENF contributed $150,000 combined to two matching pools: half to a pool for EOS Native public goods and half to a pool for EOS EVM public goods. See here for an analysis of Pomelo Season 6.
At the beginning of the quarter, the ENF launched the EOS EVM Incentive Program, offering up to $50,000 per qualifying EOS EVM project. The Program offers marketing and development support on top of the grant. EOS EVM AMM and launchpad Neutroswap was a recipient of the grant system.
Beyond EOS Labs and the ENF, EOS Network Ventures (ENV) will continue to invest in ecosystem projects. At the end of Q1’23, the ENV committed to investing $20 million into EVM projects and GameFi projects (across both EOS native and EVM).
Closing Summary
Following the overall market trend, Q3 featured largely sideways and reduced activity on the EOS blockchain, with most key metrics falling slightly QoQ. After its launch last quarter, the EOS EVM saw significantly less address activity this quarter, with average daily transactions and new addresses falling 80% QoQ and 20% QoQ, respectively. DeFi TVL on the EVM also dropped 92% to $72,000.
The EOS EVM Incentive Program, launched by the ENF at the beginning of Q3, will look to reverse these trends by attracting more developers, and thereby users, to the EVM by offering up to $50,000 in grants per qualifying project. Beyond the ENF and ENV, there’s now a third independent entity driving growth in the EOS ecosystem - EOS Labs. EOS Labs will fulfill incubator and builder roles, mainly focusing on the application layer.
A lot of the ENF’s growth efforts have been focused in Asia. On September 13, $EOS began trading on licensed marketplace BitTrade after receiving regulatory approval from Japan Virtual and Crypto Asset Exchange Association (JVCEA). Q4 is expected to feature a milestone upgrade to Antelope Leap 5.0, which will bring near-instant finality and other improvements to EOS Native. Its successful deployment, along with the continued growth efforts of the three entities, will be key to EOS building out of the bear market.
This report was commissioned by EOS Network Foundation. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Looking to dive deeper? Subscribe to Messari Pro. Messari Pro memberships provide access to daily crypto news and insights, exclusive long-form daily research, advanced screener, charting & watchlist features, and access to curated sets of charts and metrics. Learn more at messari.io/pro.
Peter is a Research Analyst in Protocol Services focused on Layer-1s. He recently graduated from Boston College where he studied economics and computer science and led the school's blockchain club.
Peter is a Research Analyst in Protocol Services focused on Layer-1s. He recently graduated from Boston College where he studied economics and computer science and led the school's blockchain club.