Looking to dive deeper? Subscribe to Messari Pro. Messari Pro memberships provide access to daily crypto news and insights, exclusive long-form daily research, advanced screener, charting & watchlist features, and access to curated sets of charts and metrics. Learn more at messari.io/pro.
Layer-1Quarterly Reports
State of EOS Q2 2023

Key Insights
- EOS EVM, an EVM execution environment deployed as a smart contract on EOS native, launched in mid-April. So far, the network has accumulated over $1 million in TVL and averaged 5,100 daily transactions.
- $EOS’s market cap decreased 43% QoQ to $740 million. Its market cap rank dropped from 42nd to 49th.
- Virtual property game Upland was by far the most popular dapp by active addresses. In May, Upland partnered with the EOS Network Foundation (ENF) to host a hackathon with up to $10,000 in prizes.
- Ecosystem growth initiatives have been targeting GameFi and EVM-based projects. In Q2’23, EOS Network Ventures (ENV) deployed $5.4 million of its $20 million fund, and the ENF committed $158,000 to Pomelo match contributions to projects in those categories.
- The ENF announced that the EOS native consensus upgrade bringing near-instant finality is estimated to launch in Q4’23. Among other network and decentralization improvements, near-instant finality will fully unlock the potential use cases of Antelope IBC, a cross-chain protocol that launched in Q1’23.
Primer on EOS
EOS is a Delegated Proof-of-Stake (DPoS) Layer-1 blockchain built using the open-source Antelope protocol. EOS’s founding team Block.one raised around $4.1 billion in a 2017-18 ICO but slowly stopped supporting the network through core development and ecosystem funding. A community-led effort driven by the non-profit EOS Network Foundation ensued to take over ownership of the project to prevent further decay of the protocol codebase and the EOS ecosystem. The grassroots effort has driven several technical upgrades, including an IBC implementation, EVM solution, and new consensus mechanism (estimated Q4’23 launch). For a full primer on EOS, refer to our Initiation of Coverage report.
Key Metrics
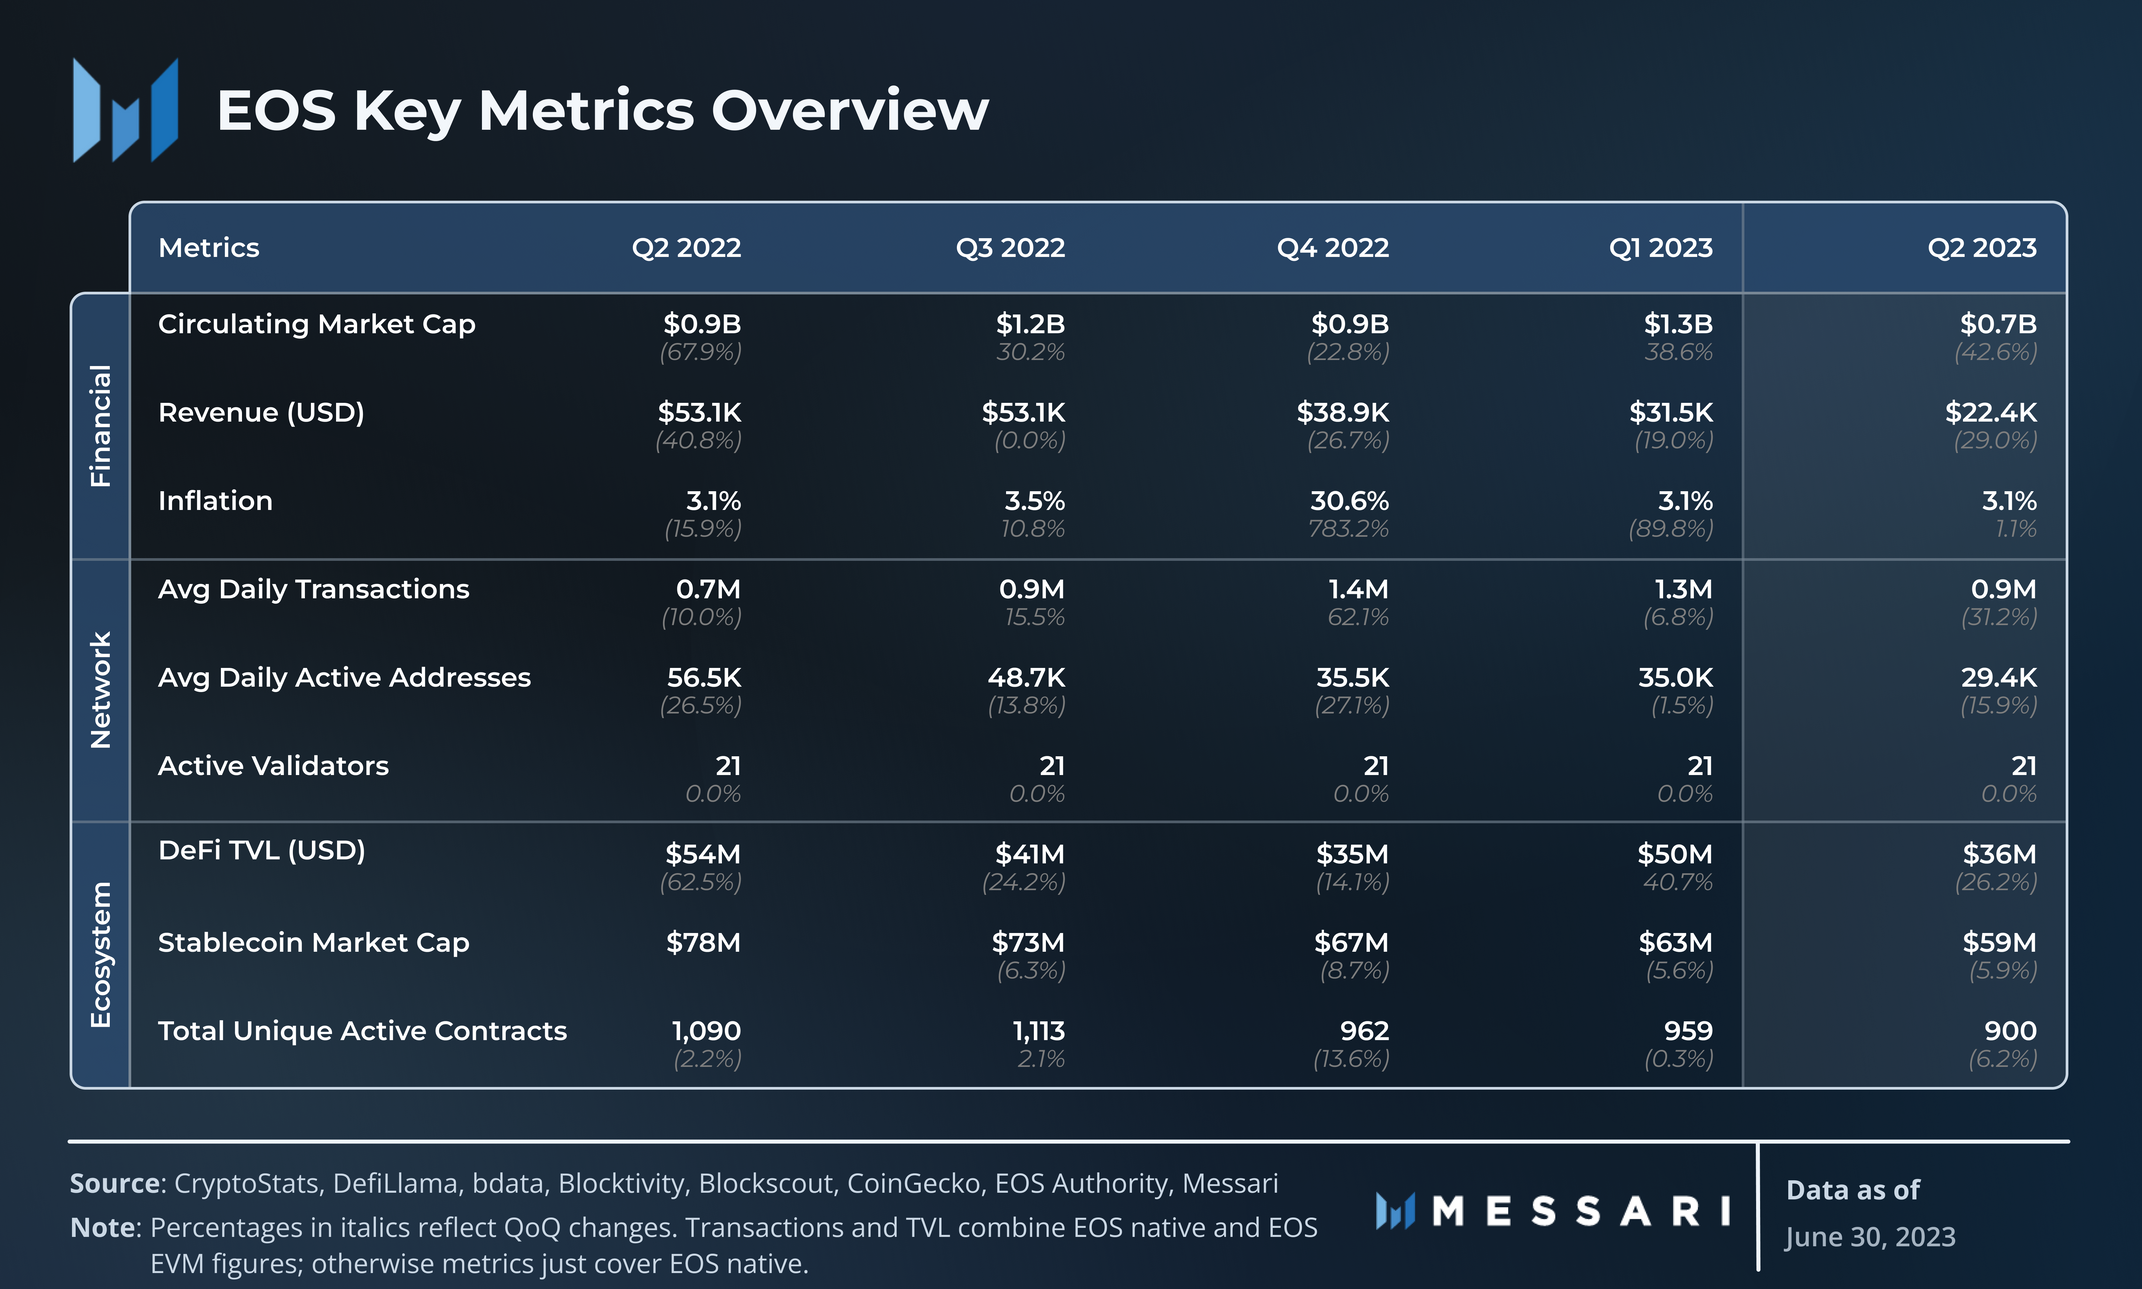
Note: The quantitative data in this report pertains to the original EOS network (“EOS native”) unless stated otherwise. The EOS EVM network lacks viable data in many areas as it has only recently been deployed.
Financial Overview
Q2’23 was an up-and-down quarter for the overall crypto market. In the first half of the quarter, a meme coin craze drove up on-chain activity and prices. After a brief period of relative calm, the market dropped due to several U.S. regulatory events, including enforcement actions against Coinbase and Binance. Among other claims, these enforcement actions labeled several Layer-1 tokens as securities. BTC and ETH were not part of these allegations; thus, alt-L1 tokens generally experienced more negative price action.
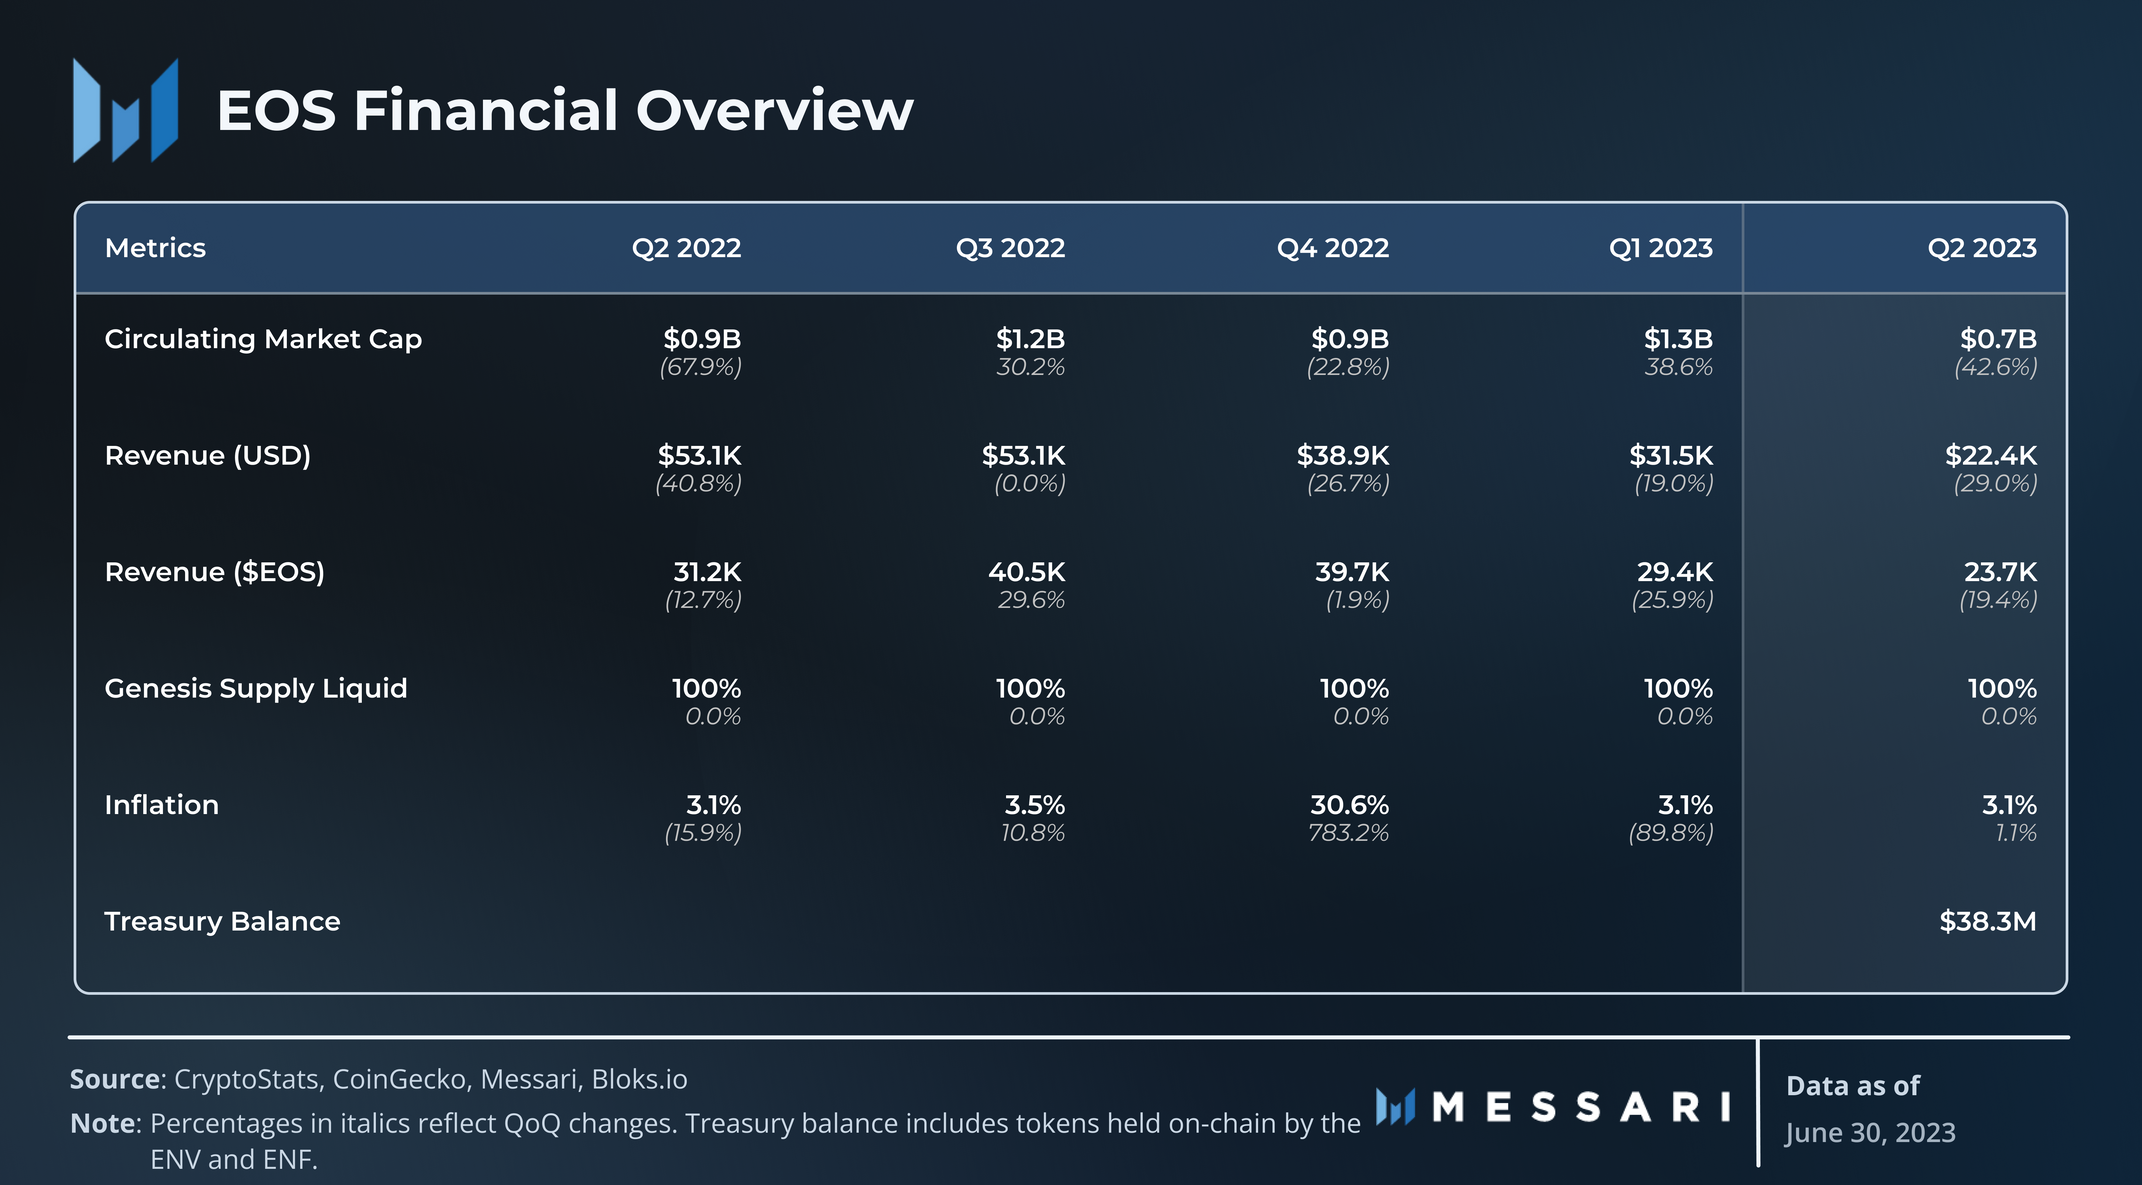
Although $EOS was not named in any of the claims, it still suffered from the market downturn. $EOS’s market cap decreased 43% QoQ to $740 million. Furthermore, $EOS decreased more than tokens with a similar market cap, as its market cap rank fell from 42nd to 49th.
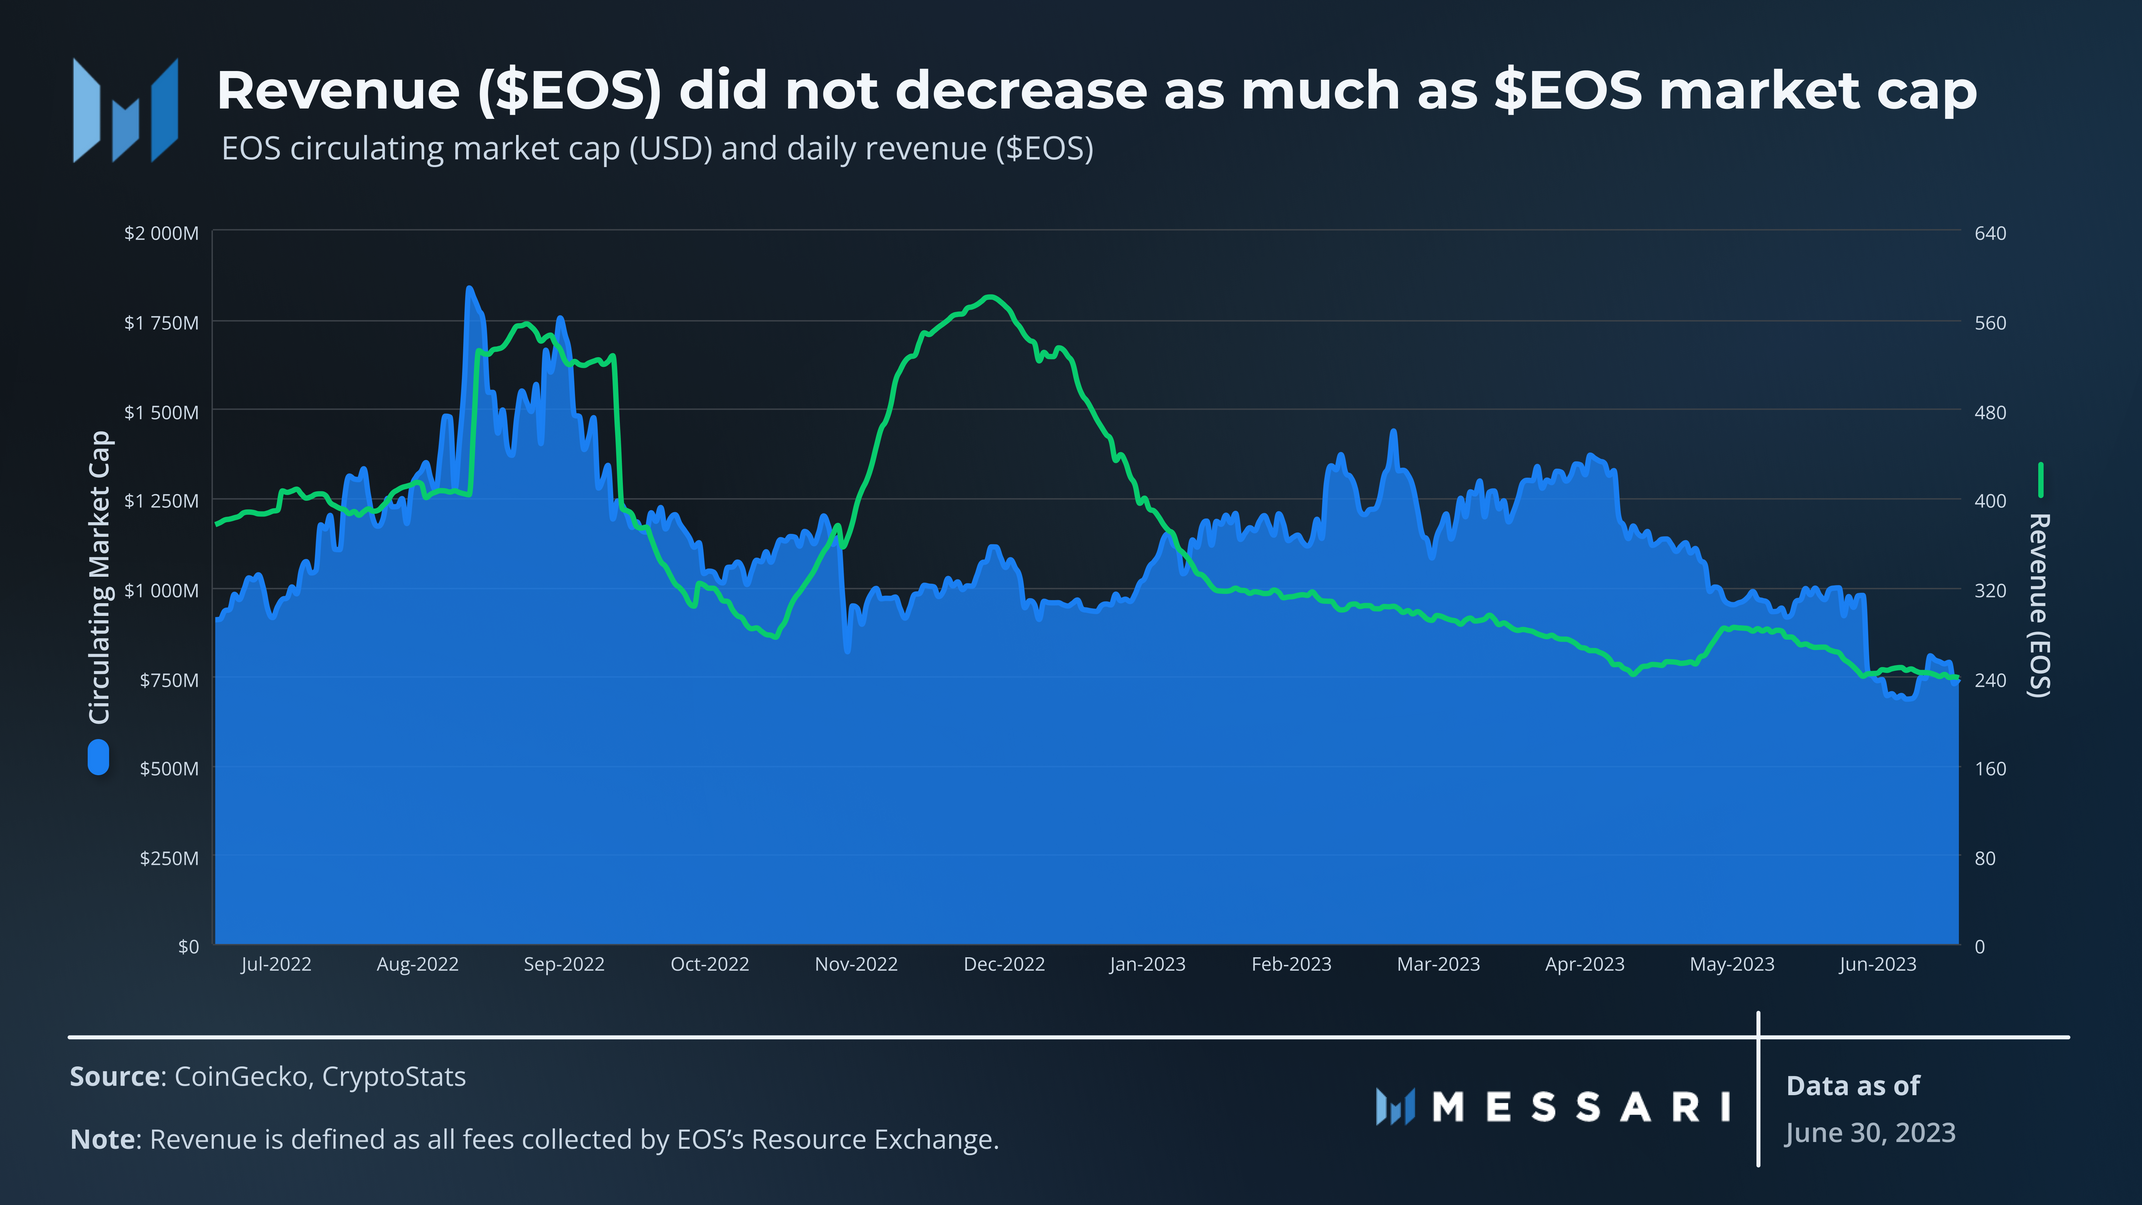
EOS revenue (denominated in $EOS) decreased 19% QoQ. Due to $EOS’s price depreciation, revenue (denominated in USD) decreased even more, by 29% QoQ. Revenue did not decrease as much as market cap, indicating that $EOS’s price depreciation was driven more by external market events than EOS fundamentals.
EOS revenue is defined as the fees collected by EOS’s Resource Exchange (REX). EOS’s unique resource model separates bandwidth and storage costs into two transaction fees. Other networks typically bundle these costs into one transaction fee. Through REX, users can pay a fee to boost their available bandwidth for 24 hours and trade the storage resource (for a more in-depth explanation, refer to the EOS Initiation of Coverage report). REX then distributes these fees to EOS stakers.
The EOS protocol mints the $EOS token at around a 3% annual inflation rate, which it distributes to validators (1%) and the EOS Network Foundation (2%). In Q4’22, the inflation rate spiked to 30% due to the funding of the newly created EOS Network Ventures with roughly 68 million EOS — the amount that had previously been burned in two portions in 2019 and 2020.
Together, the EOS Network Foundation (ENF) and EOS Network Ventures (ENV) have $38.3 million in $EOS in their on-chain accounts. The various growth initiatives of both organizations will be covered in the Network and Ecosystem sections below.
On April 13, the EOS EVM launched, adding another element to $EOS’s tokenomics. EOS EVM is an EVM execution environment deployed as a smart contract on EOS native, similar to Aurora on NEAR. EOS EVM uses $EOS as its gas token. Permissionless relayers (dubbed “miners”) are responsible for accepting valid EOS EVM transactions, wrapping them into EOS native transactions, and submitting them to the EOS native ledger.
Relayers currently receive 10% of the EOS EVM transaction fee, with the remaining 90% accruing in the eosio.evm contract. Through governance, the funds accrued in the eosio.evm contract can be used for operational costs, token burns, or other uses. At the moment, both the ENF and Noah, a decentralized exchange (DEX) on the EOS EVM, are running miners. The ENF has committed to burning any profits made through running its miner, and in the future, the 10% allocation of fees to miners could be increased to incentivize more miners.
The EOS EVM will likely become the primary driver of value for $EOS if activity increases on the network. Not only could it overtake EOS native in terms of fees generated, but almost all of its fees could also be burned, subject to governance.
Network Overview
Usage
EOS Native
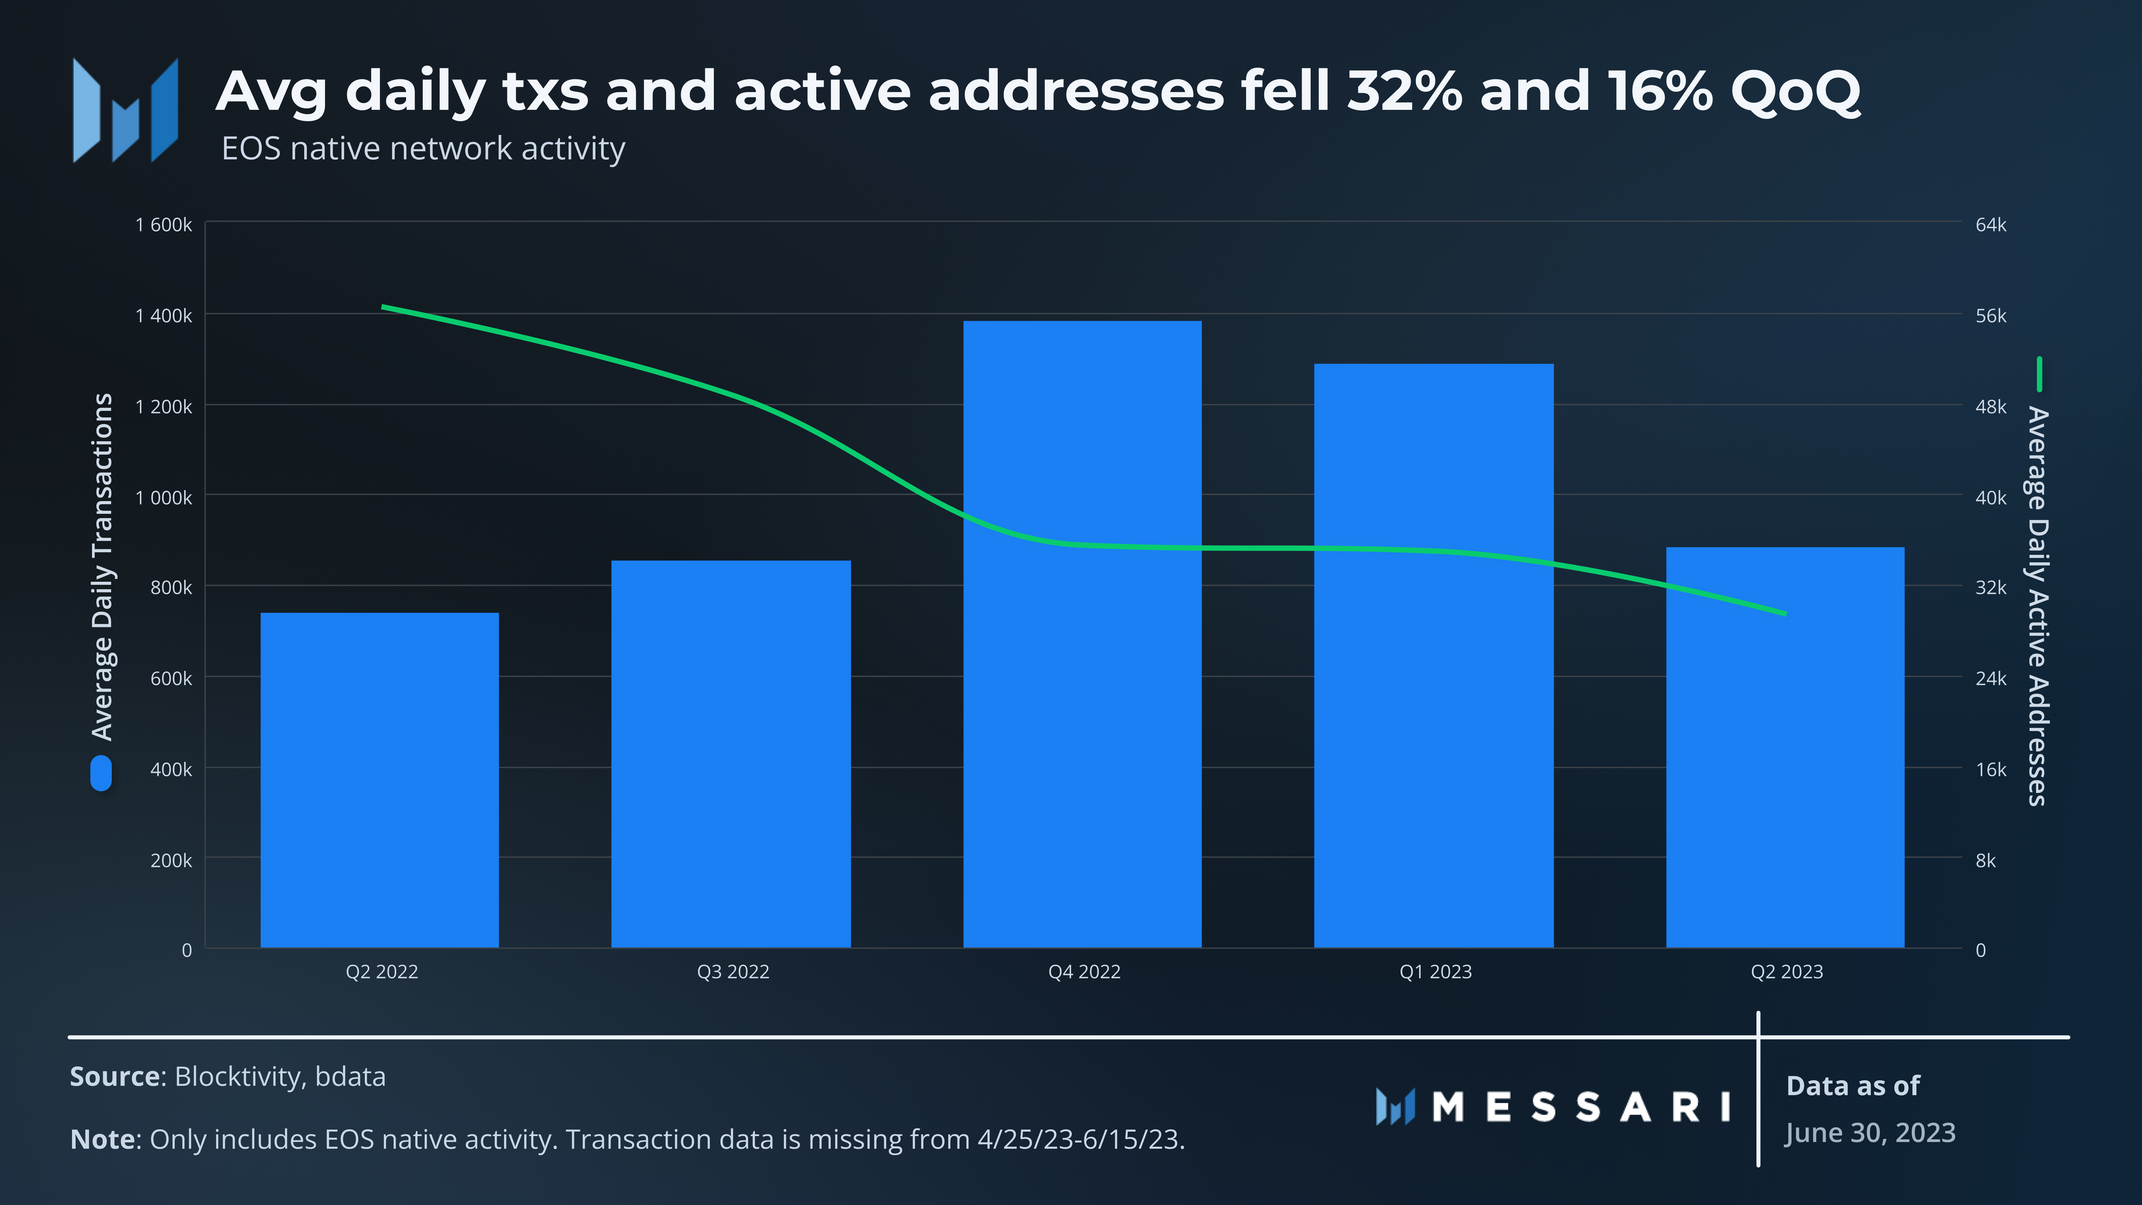
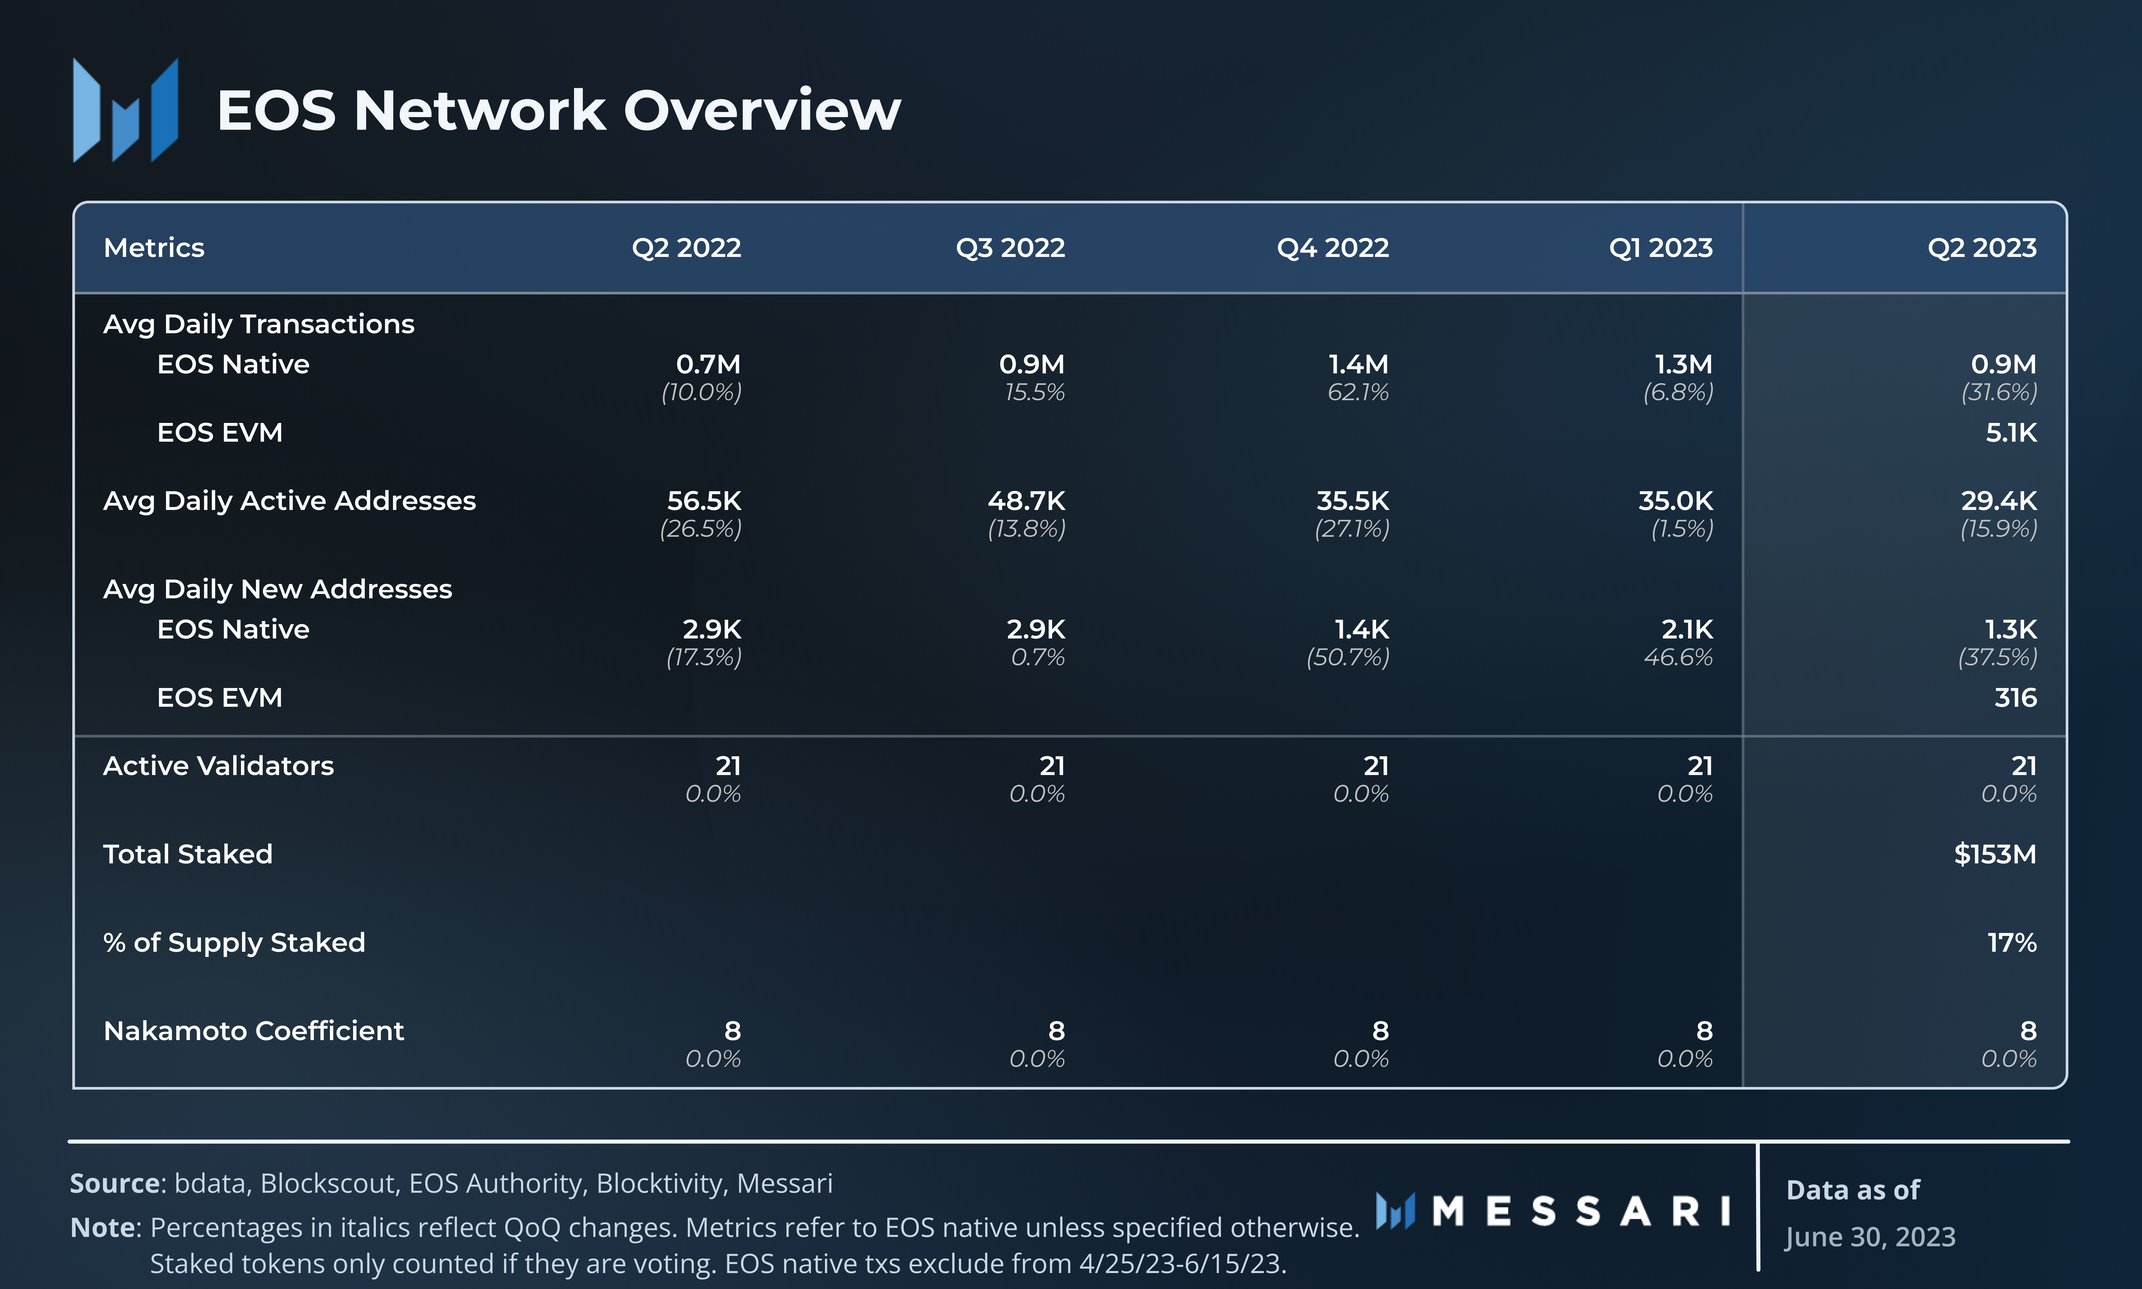
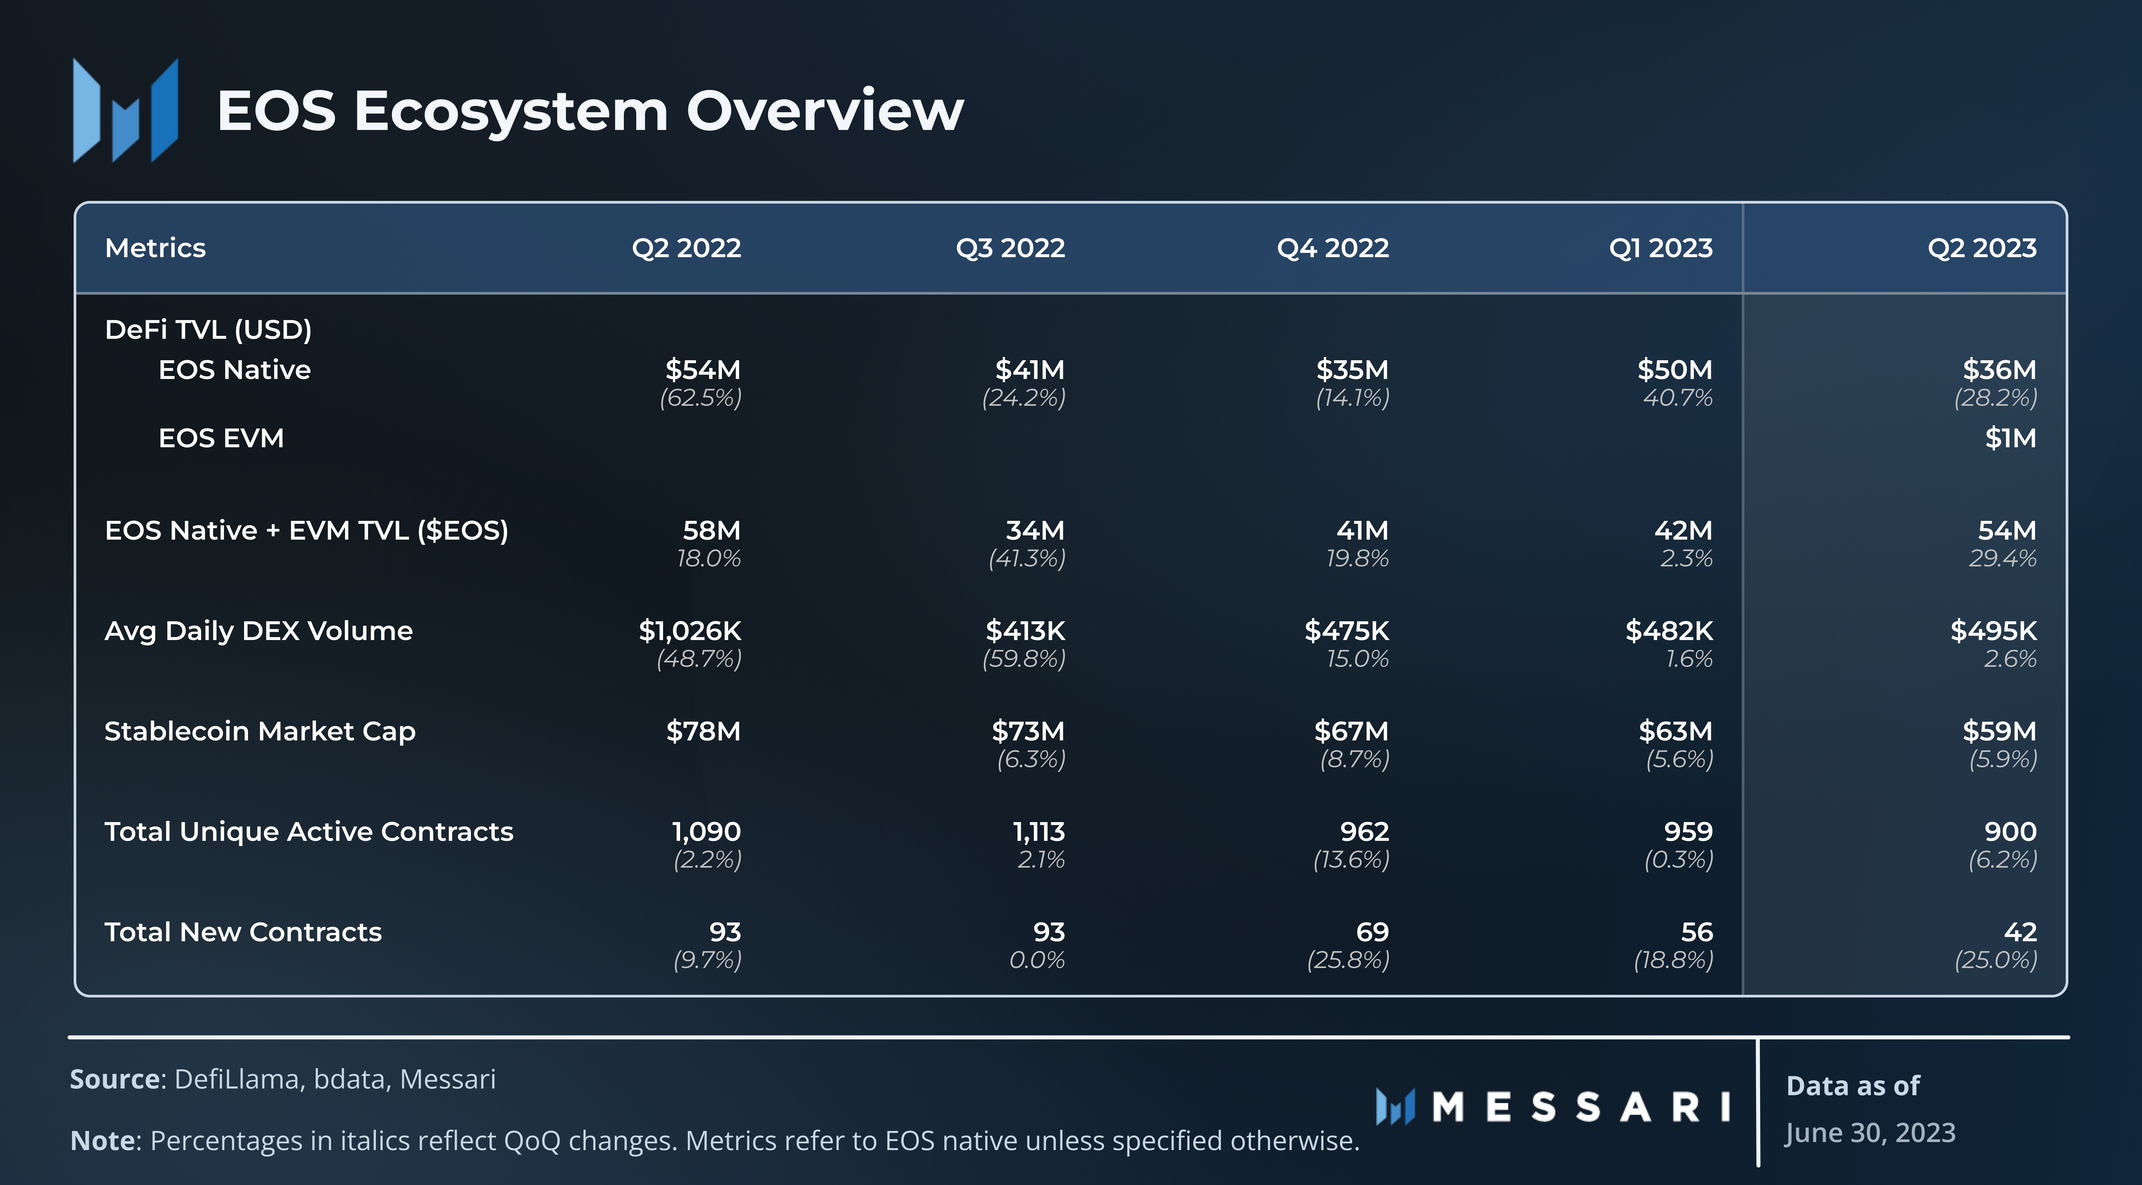
Average daily transactions decreased 32% QoQ to below 1 million. Average daily active addresses decreased less significantly QoQ, down 16%. Much of the Q2’23 decrease can be attributed to an anomalous spike of over 436,000 daily active addresses on January 31, 2023. It’s unclear exactly what caused the spike - but almost all of the spike was users just interacting with the EOS system contract and not with a particular dapp. Excluding this spike in Q1’s average, the average daily active addresses only decreased 3% QoQ.
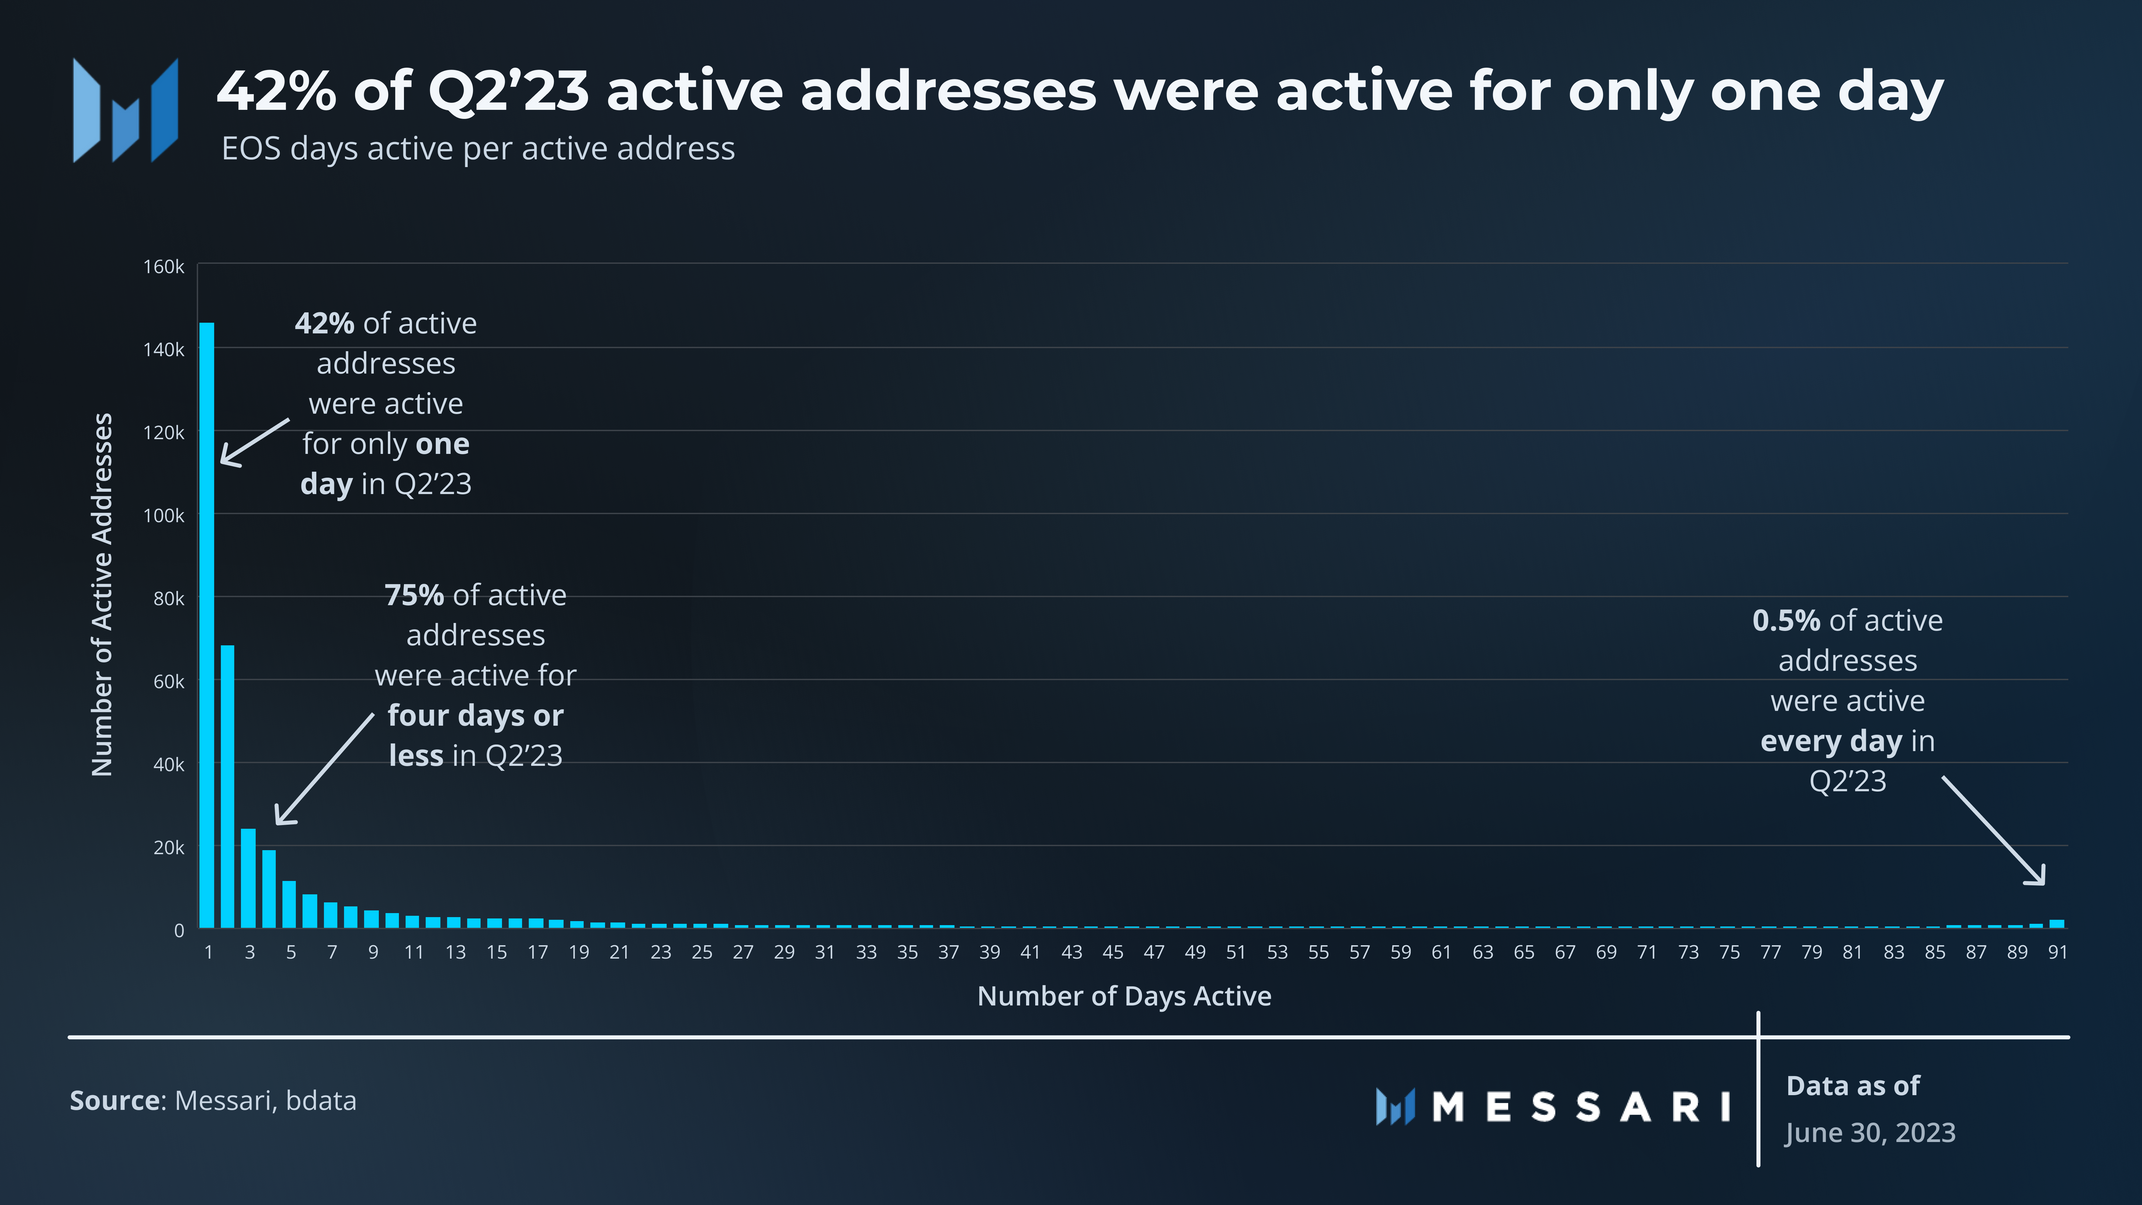
The number of total addresses active in Q2’23 decreased 57% QoQ to 350,000. Of these Q2’23 active addresses, 42% were active for only one day in the quarter, and 75% were active for four days or less.
New addresses decreased 38% QoQ to an average daily figure of 1,300. Daily new addresses dropped rather suddenly from May 13 to May 14. From the start of the quarter through May 13, there was an average of 2,100 daily new addresses. From May 14 to the end of the quarter, the figure decreased to 580. It’s unclear exactly what drove this sharp decrease in address growth.
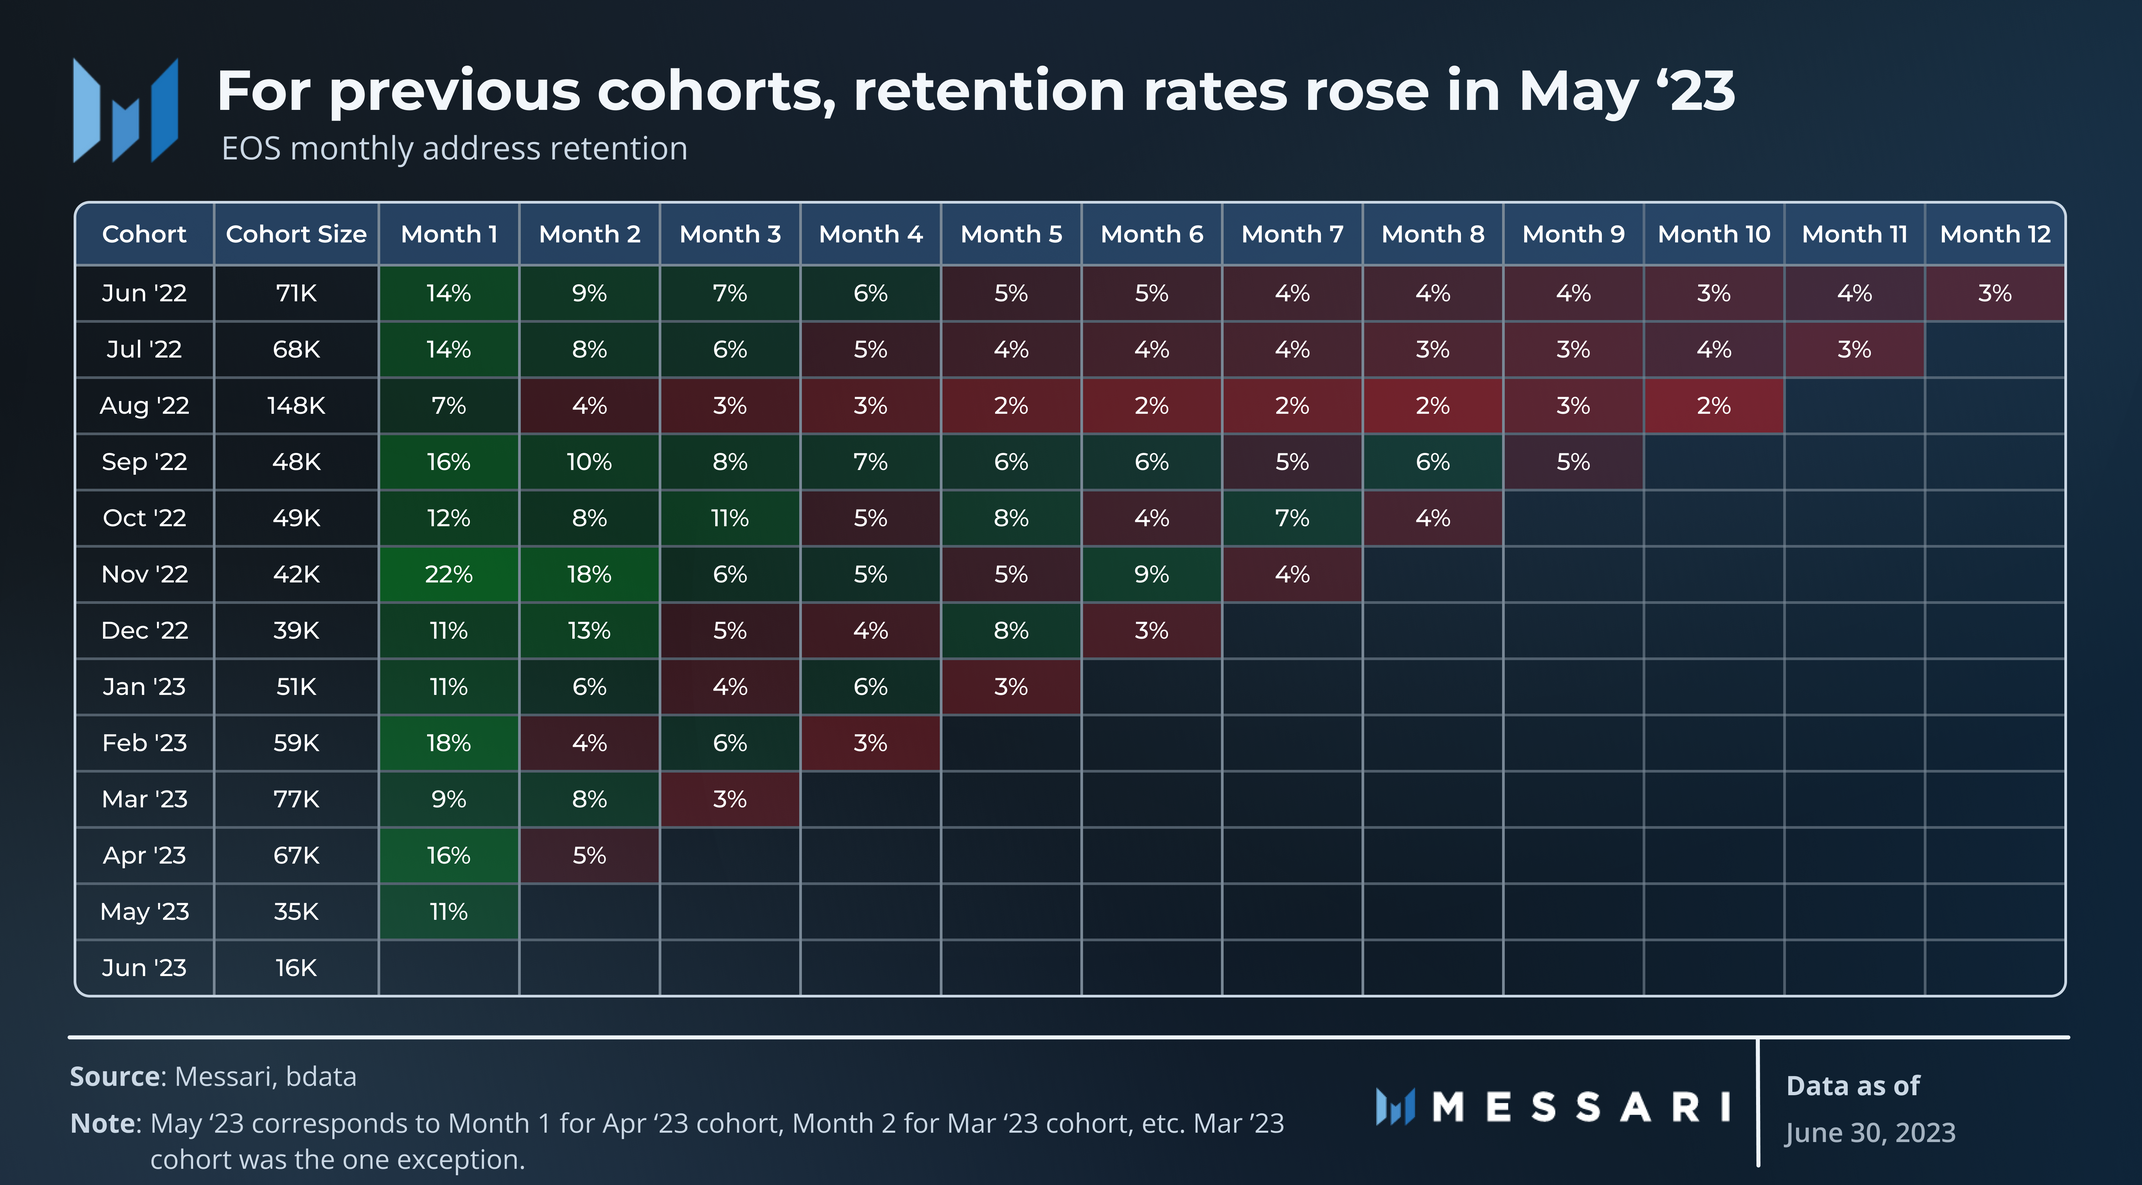
Between the April and May 2023 cohorts of new addresses, an average of 14% returned the following month. This is largely in line with EOS’s historical one-month retention rate.
May 2023 attracted back existing users who had not interacted with EOS in at least a month. For a given cohort, retention rates are generally expected to decrease as time goes on (i.e., going left to right on the above table). For all of EOS’s monthly cohorts except March 2023, this pattern is broken for the month corresponding to May 2023 (i.e., Month 3 for Feb ‘23 cohort, Month 4 for Jan ‘23 cohort, etc.).
EOS EVM
The architecture of the EOS EVM network includes:
- An execution layer built using Silkworm, the C++ implementation of the Erigon Ethereum client.
- Support for cryptographic primitives, enabling functionality for zk-SNARKs.
- 1 second block times.
- Full Ethereum RPC compatibility.
As mentioned above, activity on the EOS EVM has been relatively low since launch on April 13. So far, there have been 5,100 average daily transactions and 316 average daily new addresses.
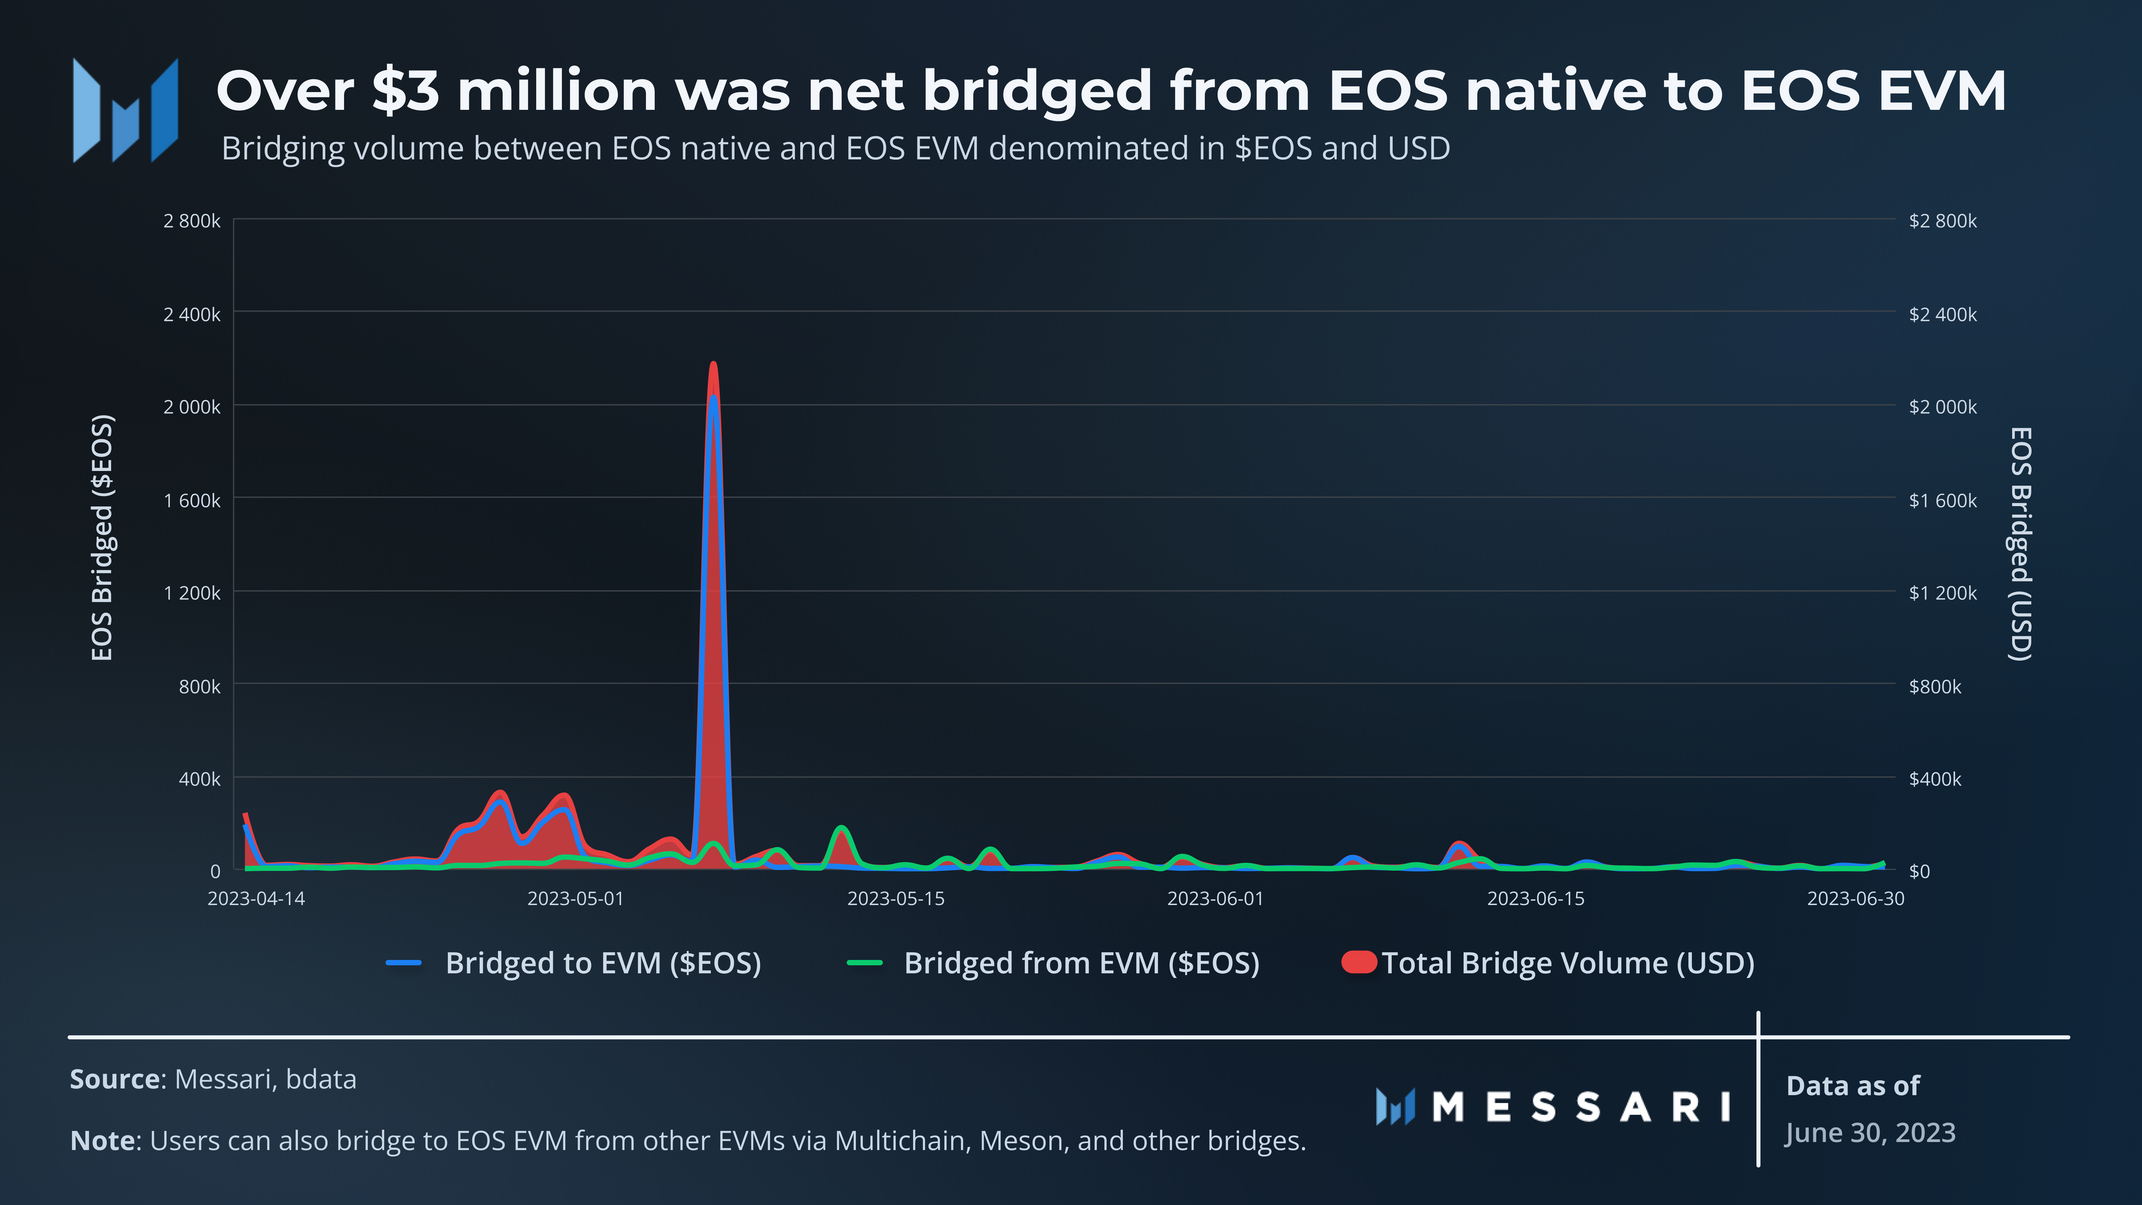
Users can bridge to the EVM either through the trustless EOS native <> EVM bridge or through third-party bridges connecting the EVM to other networks. The trustless EOS native <> EVM bridge only supports transfers of $EOS to externally owned accounts (not smart contracts).
Since launch, 4.3 million $EOS was bridged to the EVM by 616 unique addresses. Only 1.4 million $EOS was bridged back from the EVM, indicating a net inflow of almost 3 million $EOS via the EOS native <> EVM bridge. In USD terms, the EVM had a net inflow from EOS native of over $3 million. However, almost 2 million of the $EOS bridged to the EVM came from one address on May 5. This address exploited DeFi protocol PayCash before transferring stolen funds to thousands of addresses on the EVM in portions of a few hundred $EOS. PayCash’s contract was neither open-source nor audited.
Near the end of March, the ENF partnered with Multichain to connect the EOS EVM with Multichain’s supported networks through its token bridge. The ENF also announced an “AirDrip” campaign, where they send a small amount of $EOS to new users entering through Multichain to cover gas costs for initial transactions. The total bridging volume via Multichain was $2.2 million. In late May, the Multichain team announced protocol issues causing service outages for some of the cross-chain routes. However, on June 7, the ENF announced that Multichain’s EOS EVM router was performant again.
In early May, the ENF furthered its partnership with Multichain, announcing it was one of Multichain’s partners for Multichain’s $100 million ecosystem fund. The fund, dubbed MultichainVerse, will invest in and support multichain projects at any development stage across various networks.
EOS EVM is also connected to other networks via cross-chain protocols Meson and Rubic.
Security and Decentralization
EOS validators earn block rewards funded by 1% annual inflation. Of this 1%:
- 25% is allocated to validators in proportion to the number of blocks they produce.
- 75% is allocated to validators in proportion to the number of votes they receive from $EOS holders.
Only the top 21 validators (“active block producers”) with the most voting power participate in consensus in a given round. Thus, the 25% of the 1% inflation only rewards active BPs. However, validators outside the top 21 (“standby BPs”) are still rewarded from the 75% portion of the 1% inflation if they meet certain criteria. At the end of Q2’23, there were 61 validators earning validator rewards.
At the end of the quarter, there was over 201 million $EOS ($153 million) staked and voting for validators. This represented around 17% of the circulating supply. Note that staking for validator delegation/voting and acquiring network resources happen in the same contract. An additional 107 million $EOS was staked but not voting for validators. Around two-thirds of the additional $EOS came from tokens that were yet to vest to the original EOS contributor Block.one (B1). However, block producers froze the vesting contract due to B1’s lack of contribution back to EOS. There are currently no plans to unfreeze, burn, or do anything else with these tokens.
In EOS’s Delegated Proof-of-Stake (DPoS) model, a tokenholder does not delegate tokens toward one validator; instead, they stake their tokens and then can vote for up to 30 validators. Each validator would then receive that tokenholder’s full amount as voting power. For example, if a tokenholder had 1 million voting power and voted for 30 validators, each validator would have 1 million voting power. Due to this system, it is impossible to precisely measure how much stake is delegated to all validators versus the top 21 (active BPs).
In order to take over the network through a two-thirds attack, a malicious actor would need to control 15 validators. Because of the abovementioned voting power system, a malicious actor would also need enough stake to control the seventh highest validator by voting power. At the end of the quarter, this threshold was almost 143 million $EOS ($109 million).
Geographic diversity is also an important factor to the resiliency of a validator network. Of the active BPs at the end of the quarter, Hong Kong and the Cayman Islands were the most popular hosting locations, with four validators each. Asia was the most popular region with 10 validators.
Upgrades and Roadmap
The EOS Network Foundation continues to further development on both EOS native and EOS EVM. Antelope Leap, the open-source protocol powering EOS, was upgraded four times throughout the quarter. Most notably, the ENF announced the release of Antelope Leap 4.0.0 at the end of April. The released version includes several improvements: It optimizes node performance, improves block propagation, schedules future snapshots, adds read-only transactions, and improves the performance of EVM-related functions.
Near the end of June, the first upgrade to EOS EVM, version 0.5.0, launched. The update included general bug fixes and added support for read-only transaction execution. It also enabled Yield+ on the EVM (see the DeFi section below for more details), among other updates
After launching Antelope IBC in January and EOS EVM in April, the next major feature to be added to EOS will be a new consensus mechanism. In mid-2022 teams of the EOS, WAX, and Telos networks agreed to give a 24-month, milestone-based grant worth $3.8 million in their native tokens to UX Network development team 0rigin for developing the new consensus mechanism along with Antelope IBC.
The teams have been working to implement a modified variant of HotStuff, BFT-based protocol developed by the Facebook team working on Libra. The upgrade will bring several improvements including expanding the validator count beyond 21 and bringing near-instant finality.
Aside from addressing Antelope’s three-minute transaction process, instant finality will also complement Antelope IBC and allow for near-instant cross-chain messaging. Since launch in January, Antelope IBC has had relatively low use on EOS. In Q2’23, there was an average of 198 daily calls of EOS IBC-related contracts from an average of 26 daily addresses.
ENF’s June program and operations report listed an estimated launch date of November 28, 2023, for the upgraded consensus mechanism.
Ecosystem Overview
Popular Contracts
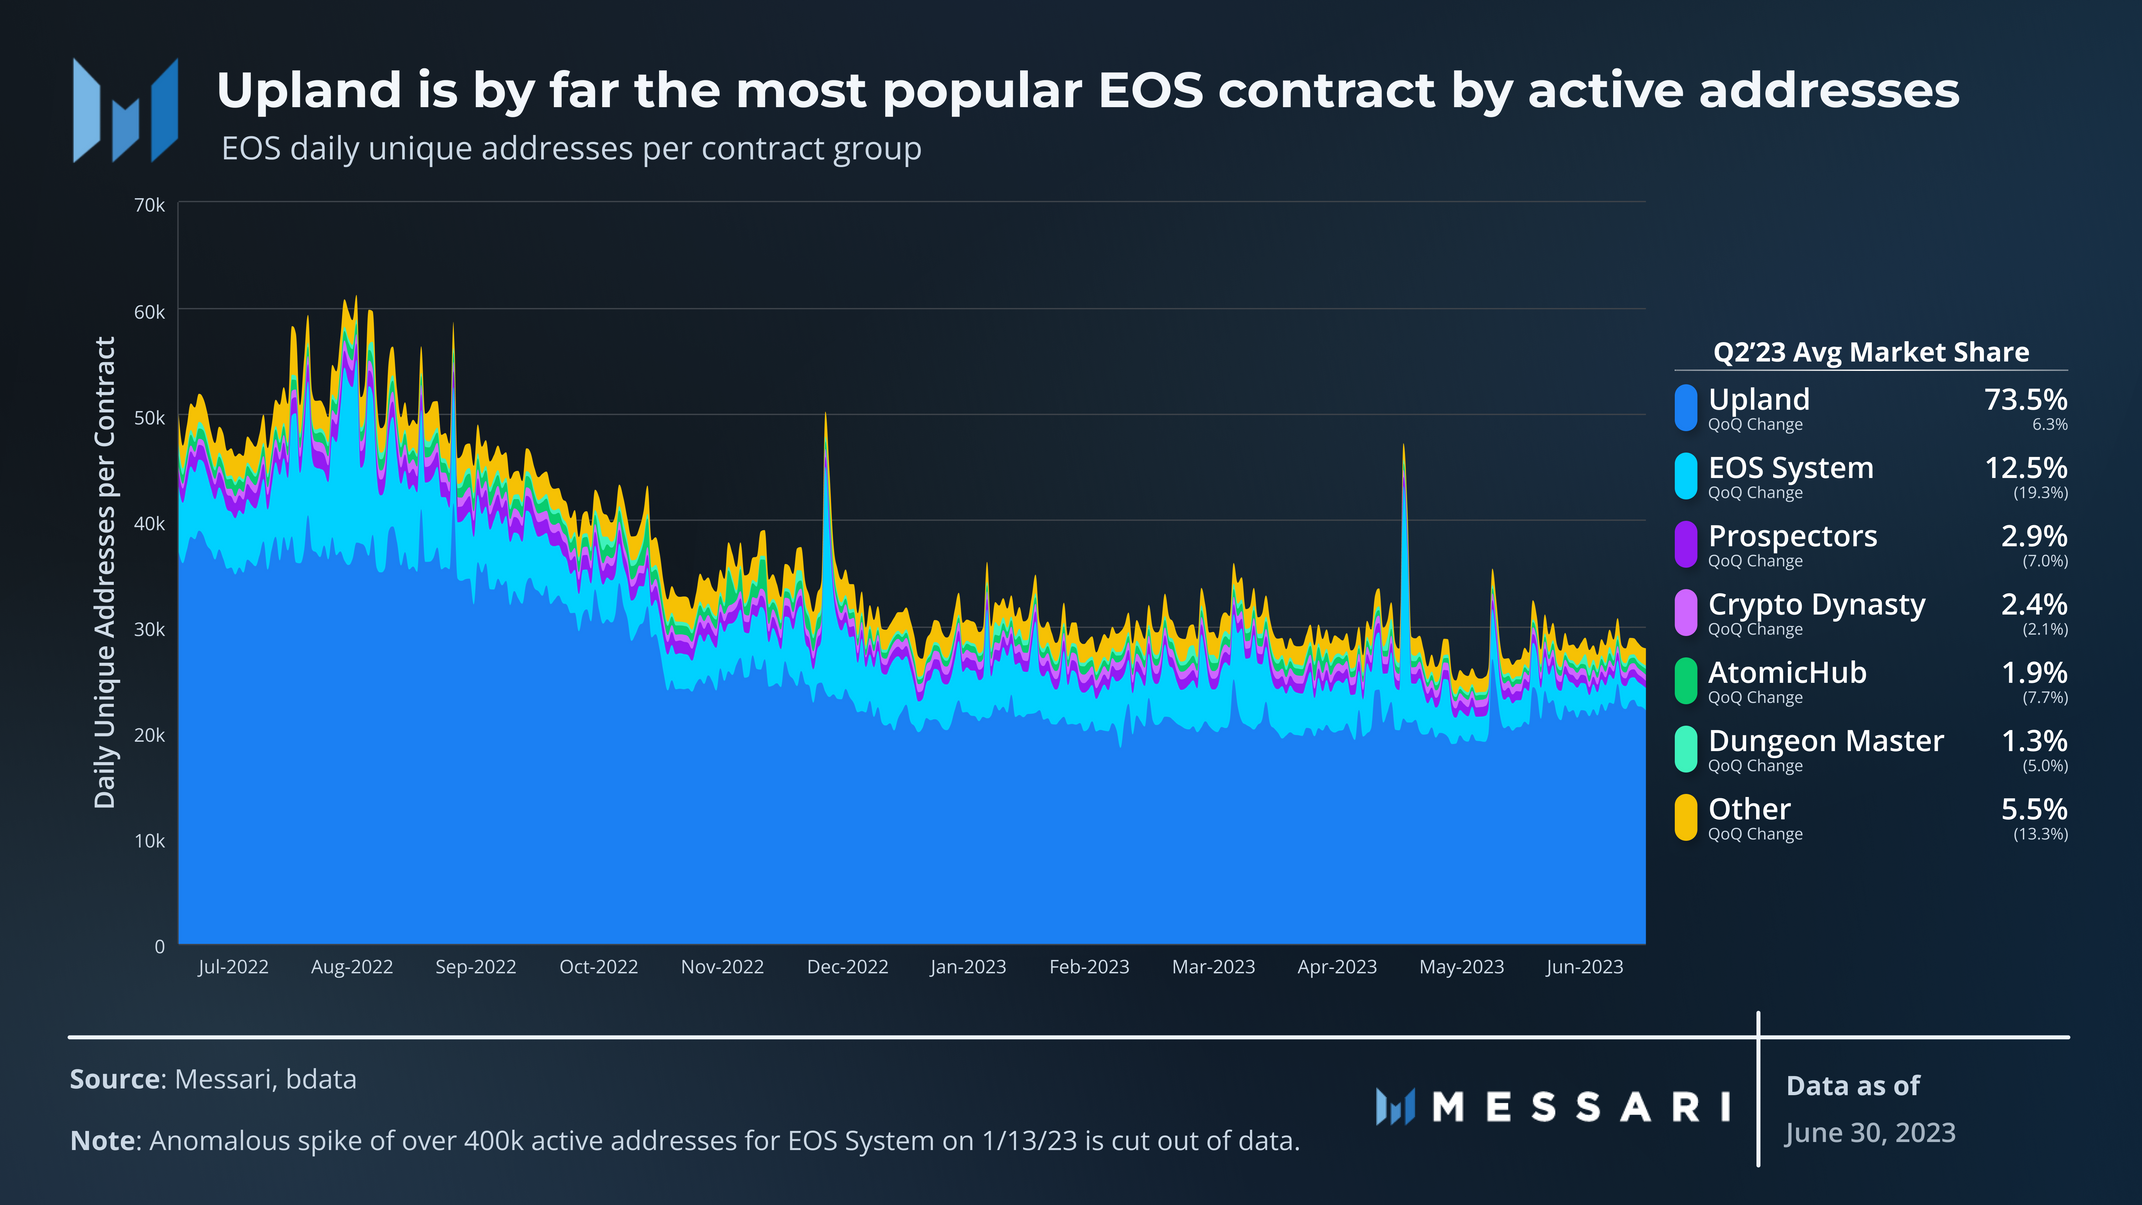
Virtual property game Upland is the most popular EOS contract group by daily active addresses. In Q2’23, Upland averaged 21,000 daily active addresses, giving it a 74% average market share among other contract groups. The EOS System contract, which handles functions such as delegation and resource management, was the second most popular contract group. It averaged almost 4,000 daily active addresses in the quarter. Upland and the EOS System combined for an average market share of 86%.
Rounding out the top six contract groups by daily active addresses were MMO strategy game Prospectors, RPG game Crypto Dynasty, NFT marketplace AtomicHub, and NFT staking game Wombat Dungeon Master.
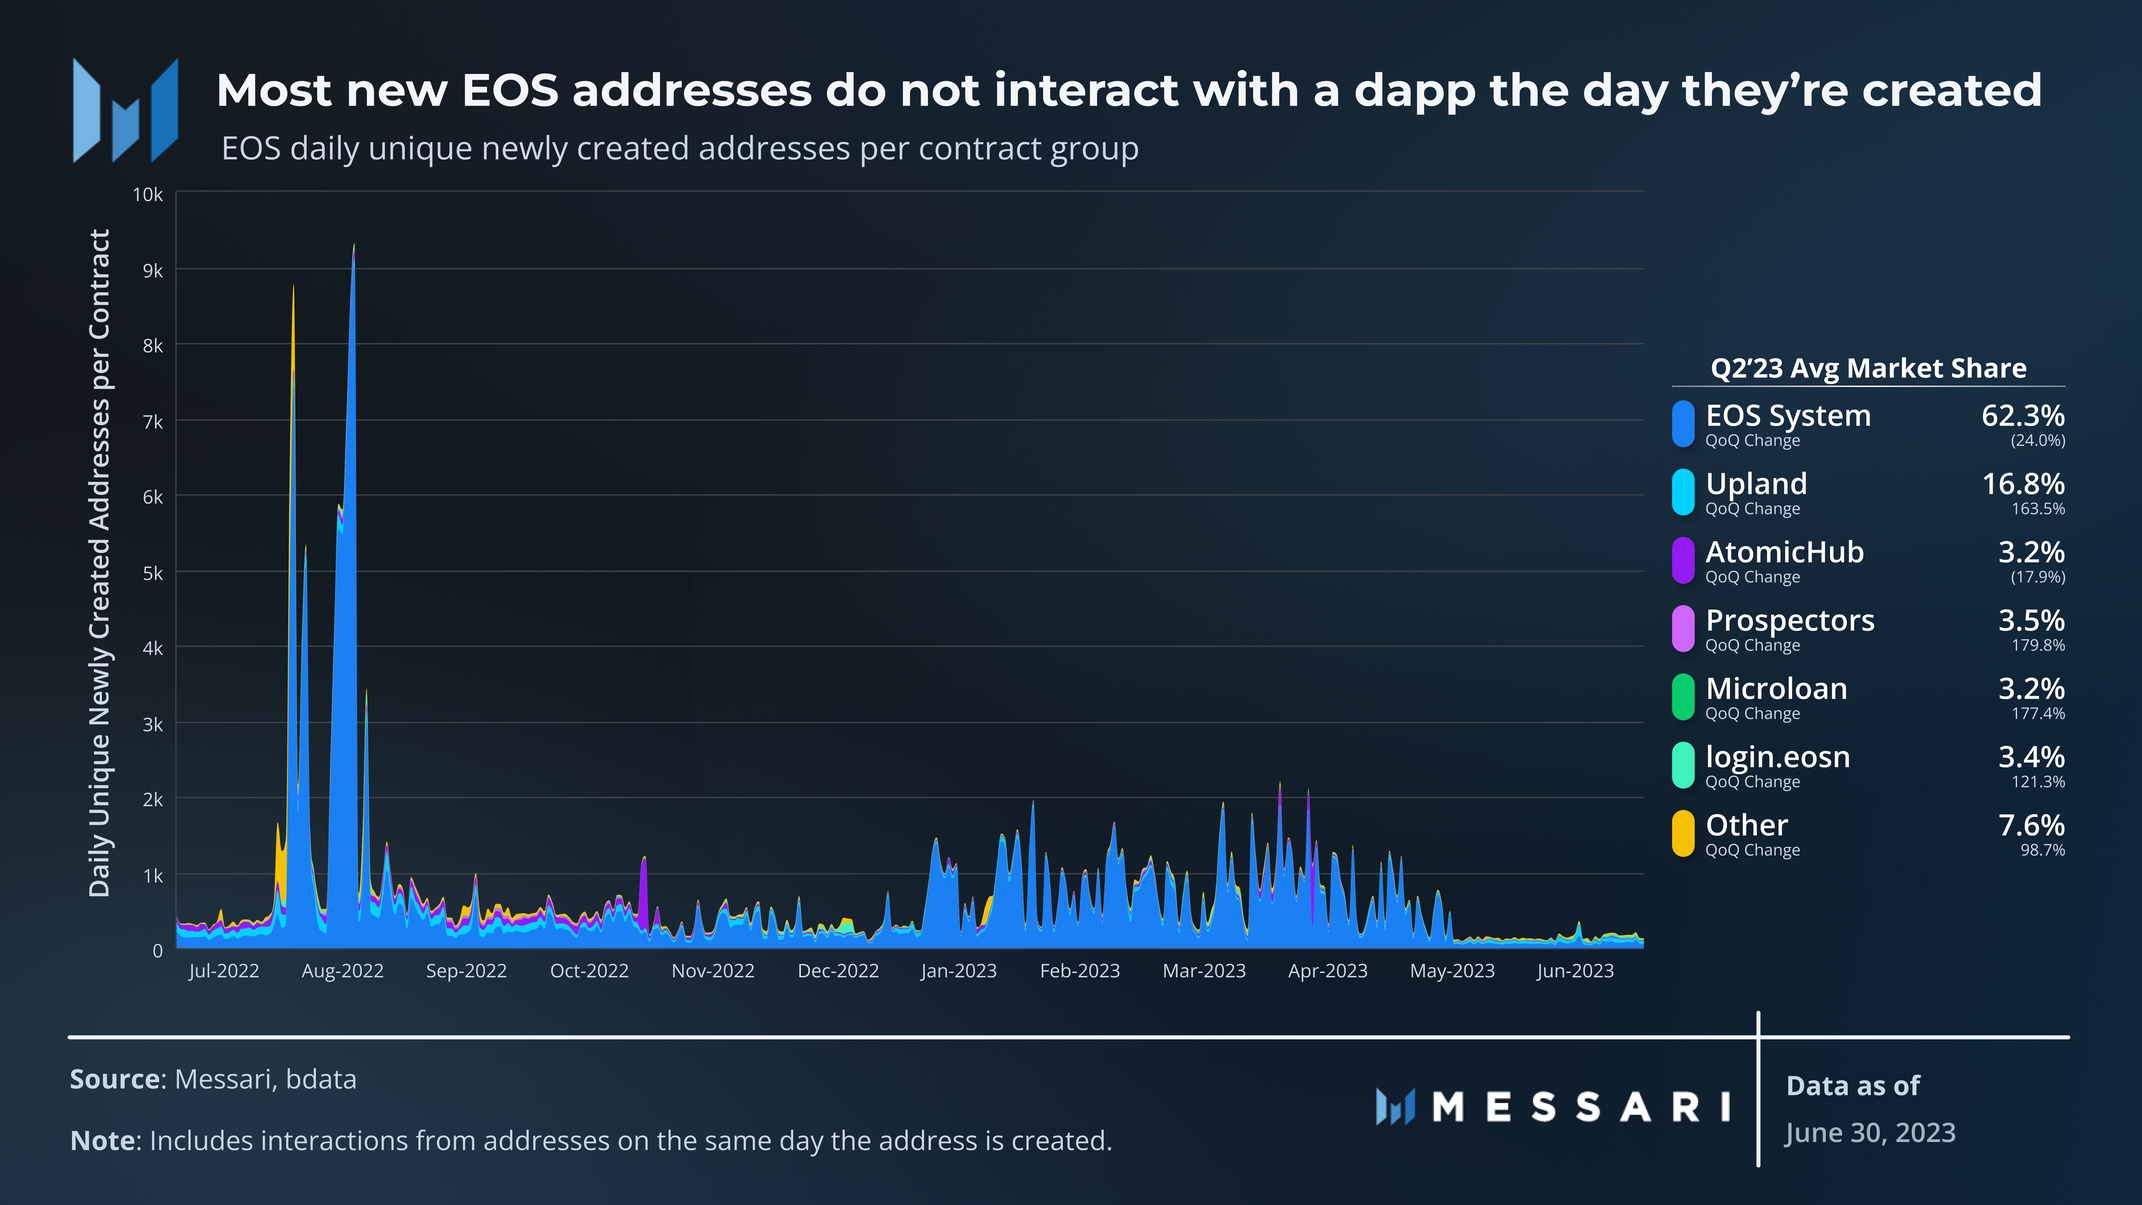
This chart includes only contract calls from addresses on the same day that the address is created (“newly created addresses”). It highlights what addresses do when they join the network, revealing several noticeable differences from the above analysis on contract calls from all addresses.
The most popular contract for newly created addresses is the EOS System. Over the quarter, the WAX System had a 62% average share of newly created address interactions. In other words, many addresses join the network just to stake their $EOS rather than for a specific ecosystem use case. Upland’s average share of newly created addresses was 17%, significantly less than its 74% average share of all addresses. While this discrepancy indicates that Upland’s activity is driven by existing users, it still makes up a notable share of newly created addresses.
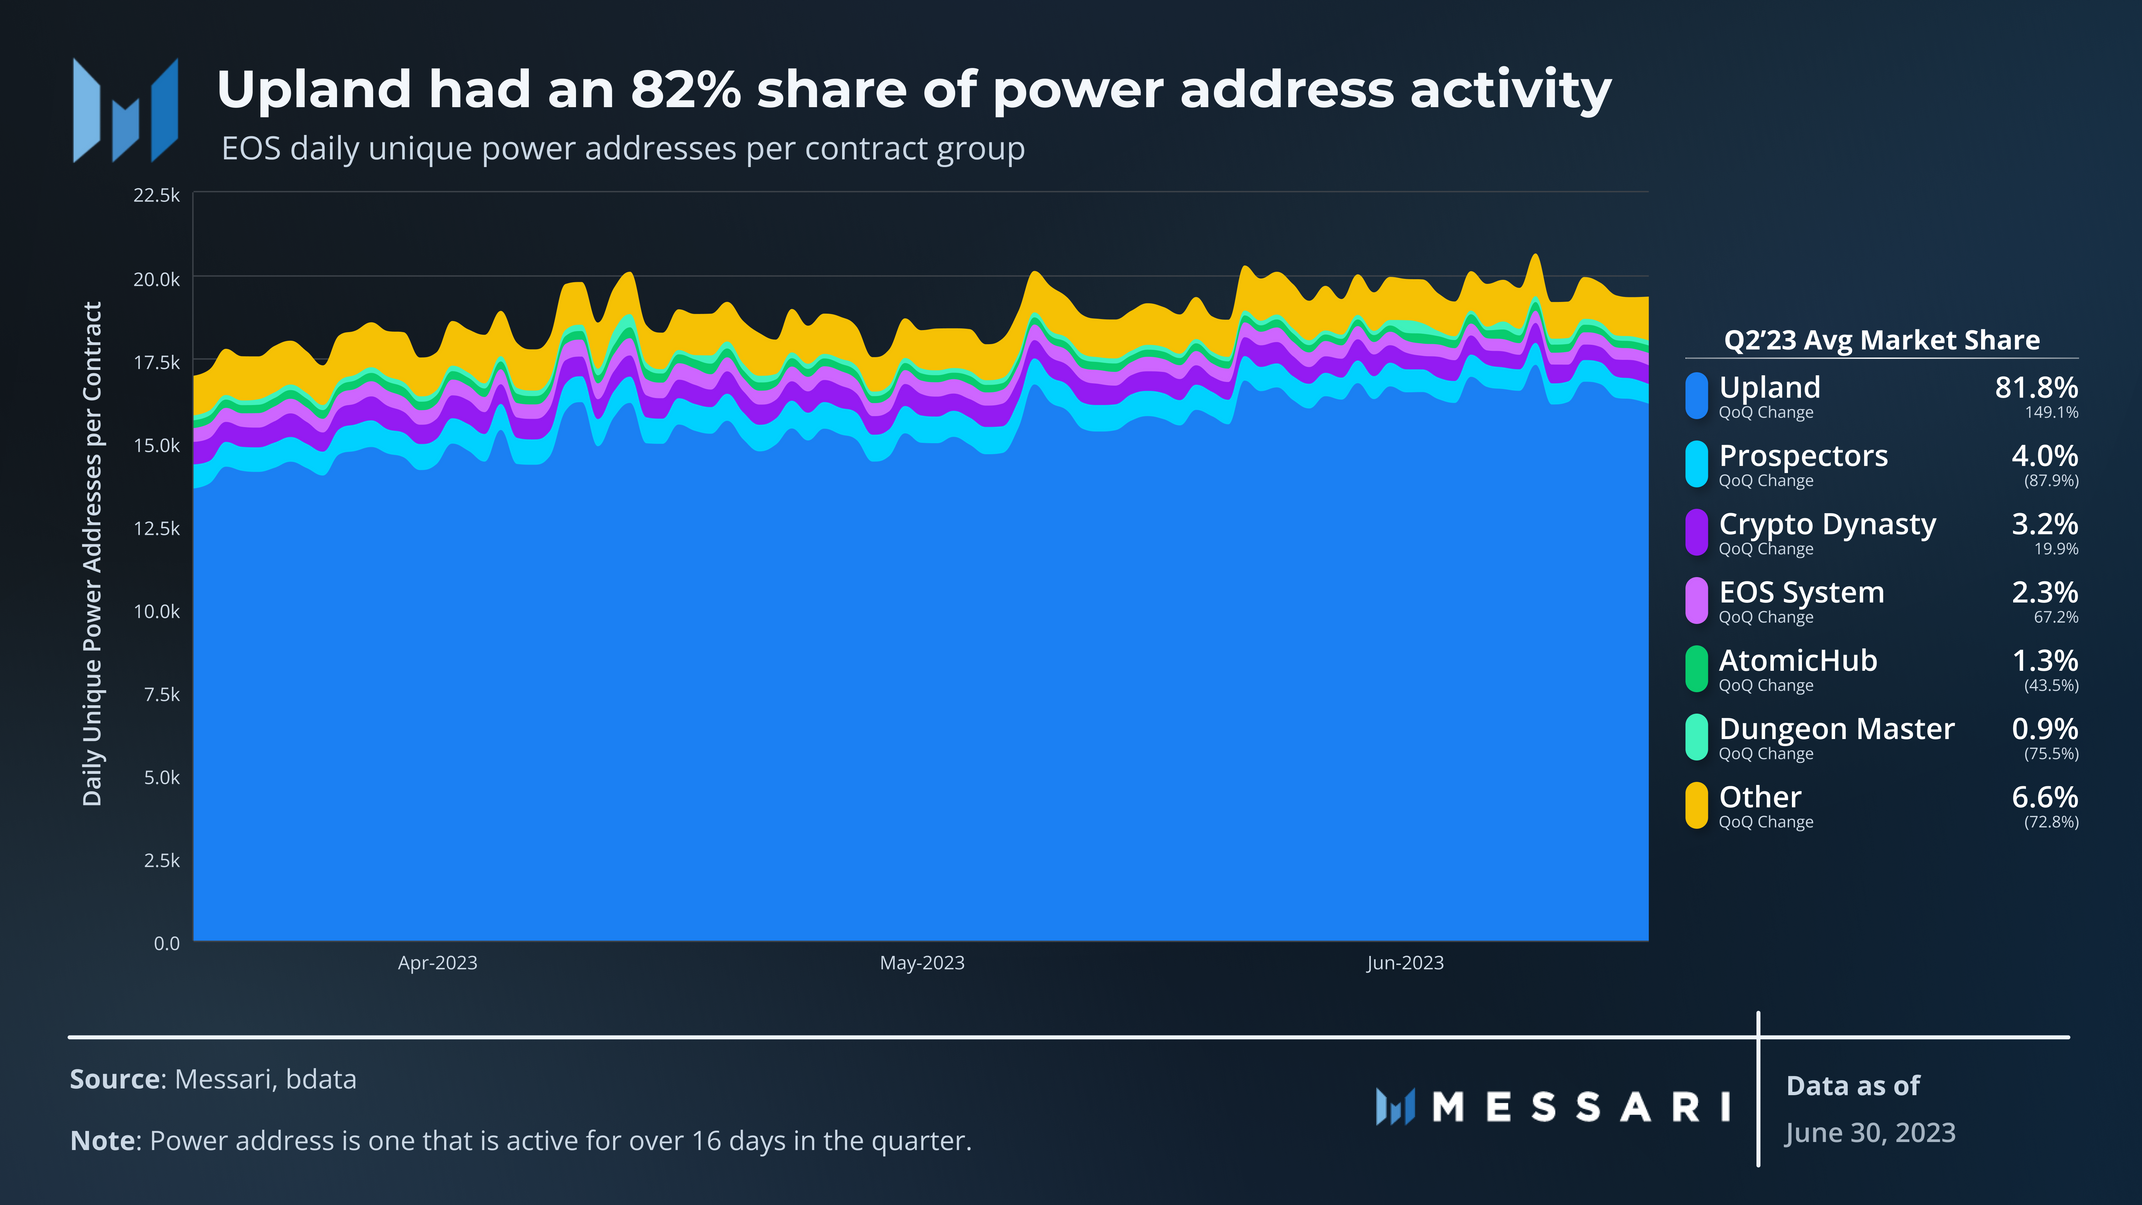
This chart again only looks at contract calls from a subset of addresses; here, power addresses. A power address is defined as one that is active for over 16 days in the quarter, which was the cut-off for the 90th percentile of addresses by the number of days active.
Throughout the quarter, Upland had an average 82% share of power addresses among contract groups. Of its 21,000 average daily active addresses, over 15,000 were power addresses (73%). A large percentage of the average daily active addresses of Prospectors and Crypto Dynasty turned out to be power addresses.
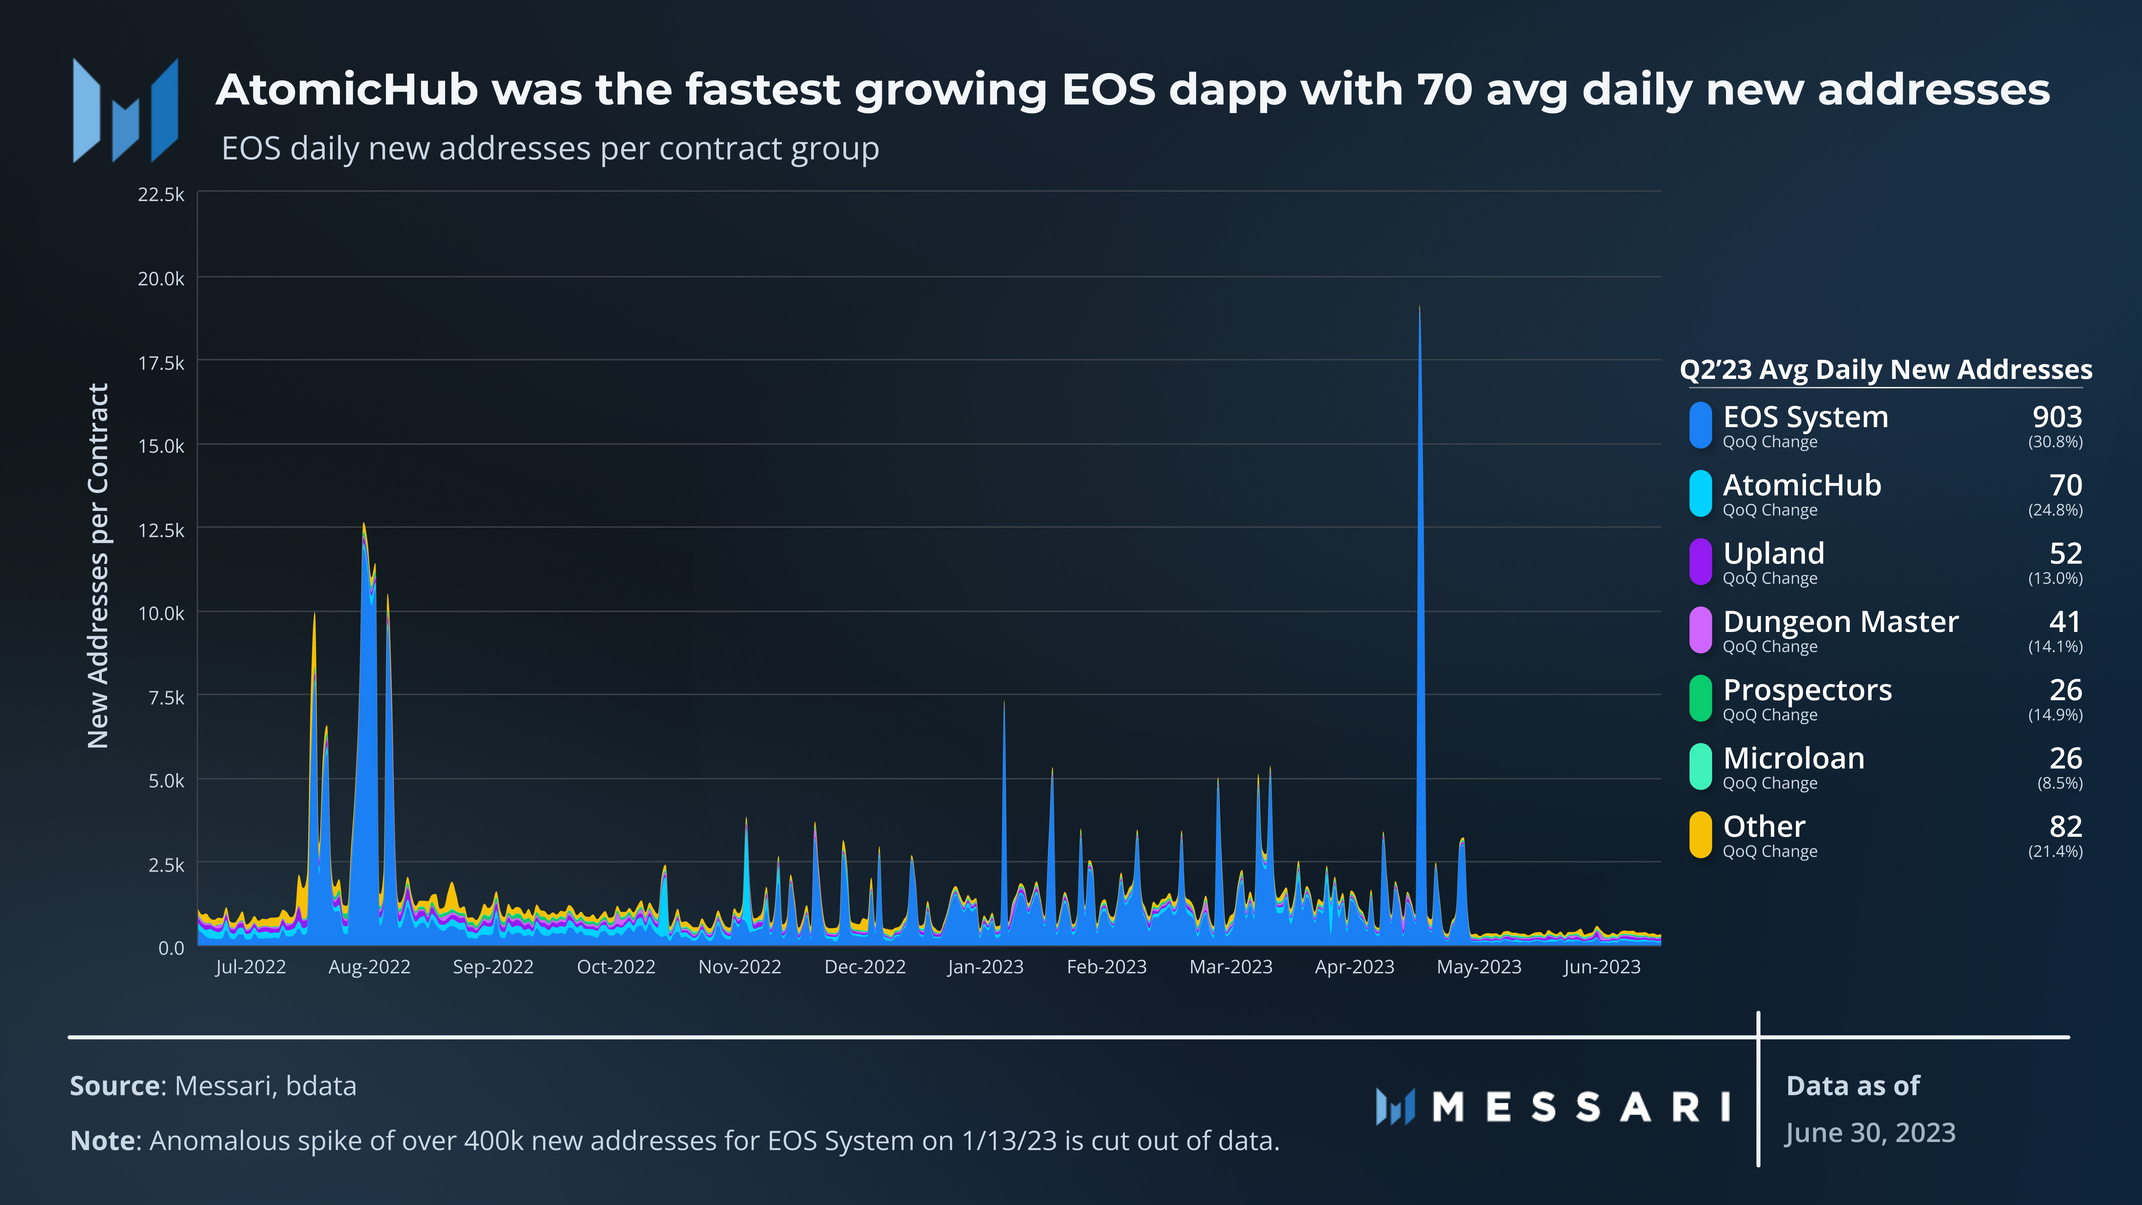
This chart re-examines all addresses (rather than just newly created or power addresses), but it counts an address’s first interaction with a contract group. This analysis reveals the number of daily new addresses for each contract group.
The QoQ decrease in average daily new addresses was felt across contract groups. The EOS System is the highest growing contract group, given that most new EOS addresses need to interact with it upon joining the network. After that, there is a large drop off in the growth rate of dapps in EOS’s ecosystem. AtomicHub was the second-fastest growing contract group with an average of 70 daily new addresses in the quarter, followed by Upland (52) and Dungeon Master (41).
DeFi
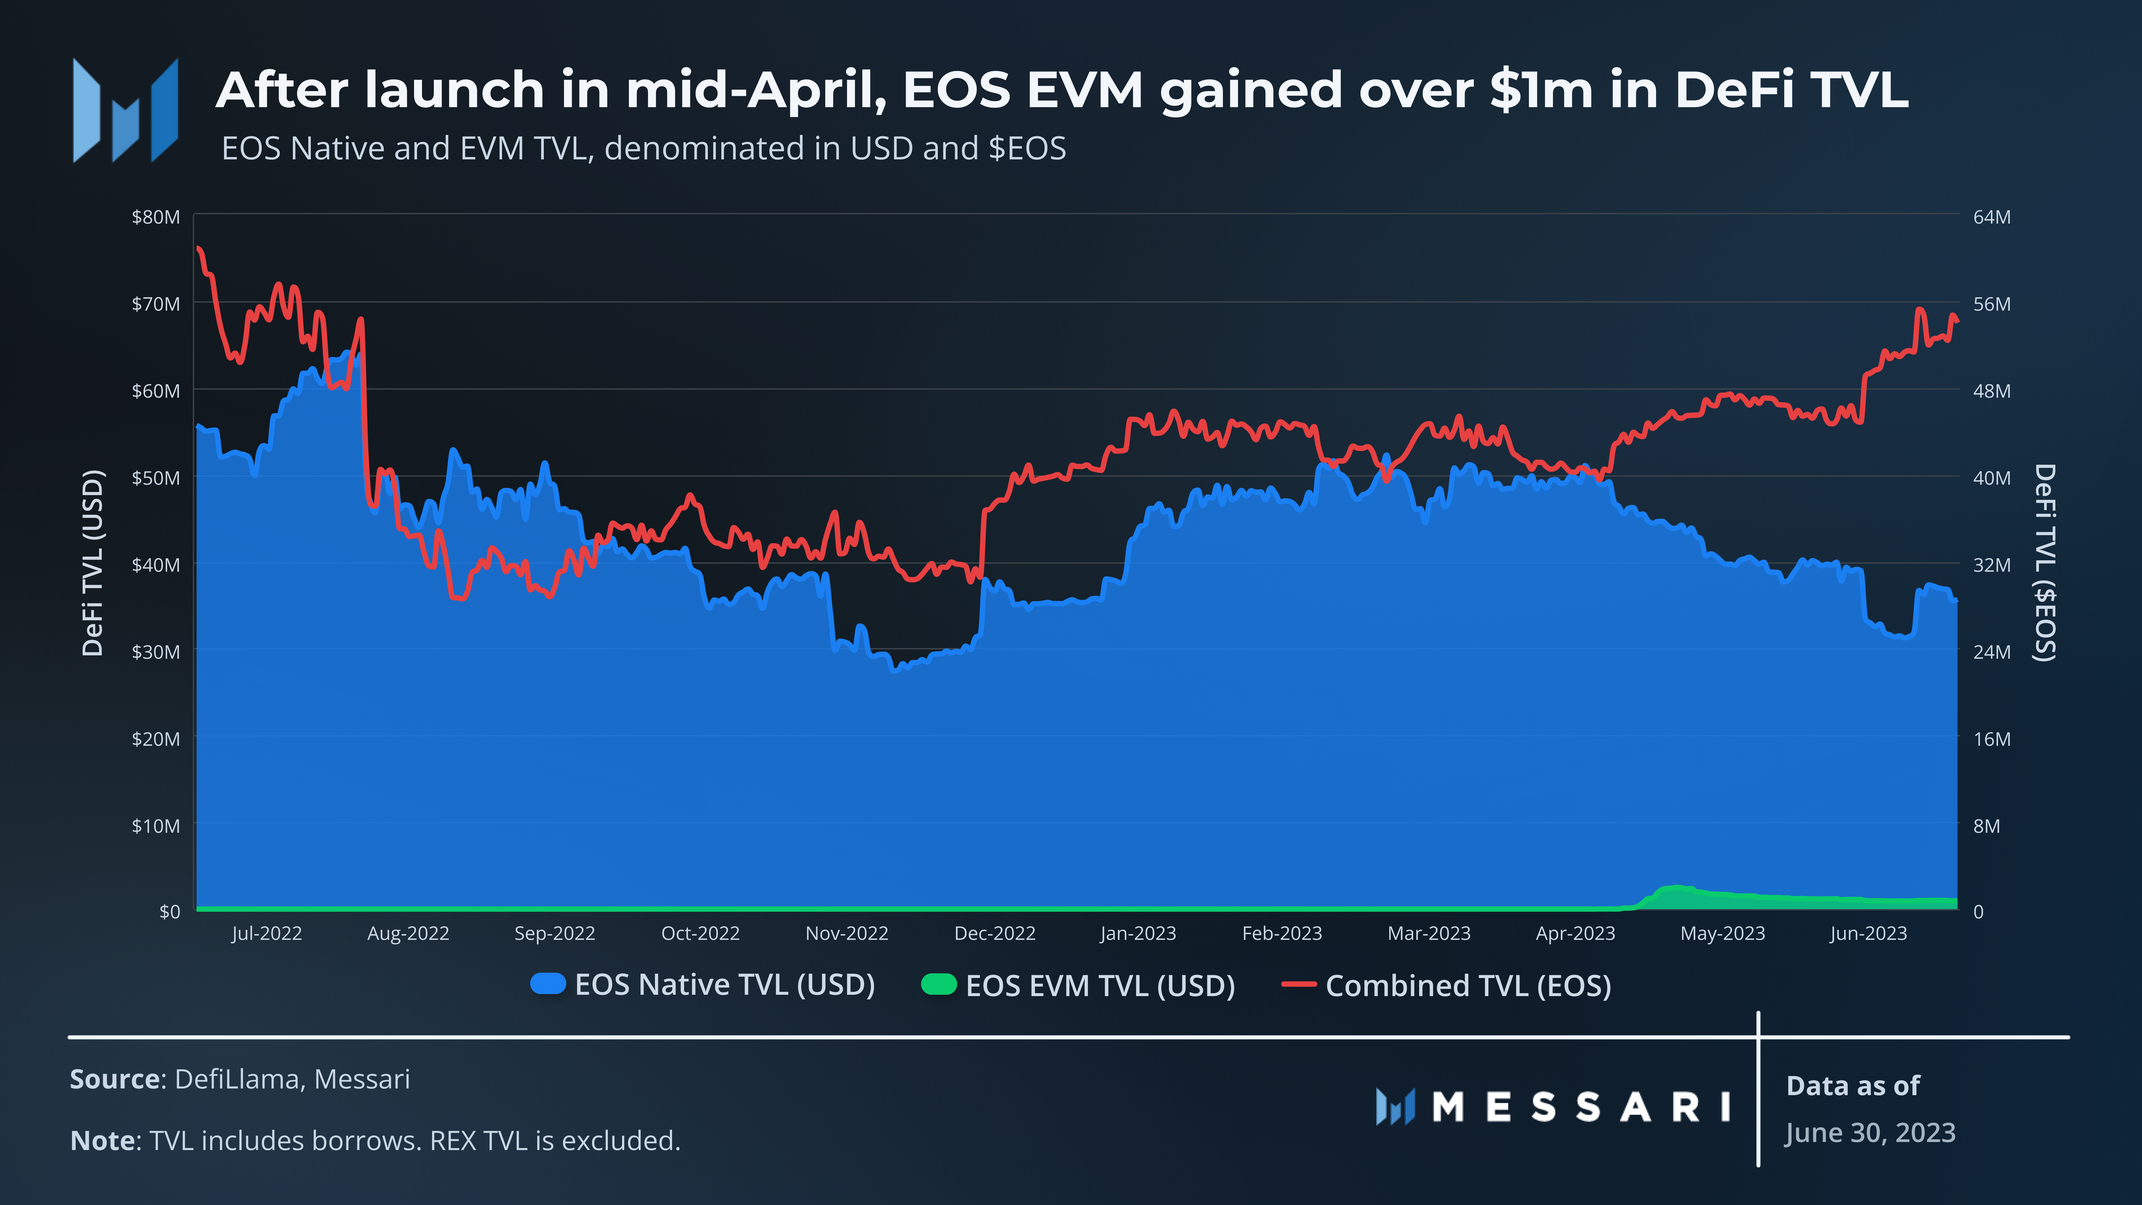
TVL on the EOS native chain decreased 28% QoQ to $36 million, ranking the network around 38th among all blockchains. Around 65% of that TVL was from Defibox, a platform featuring swapping and lending capabilities. The second most popular DeFi protocol by TVL was PayCash with over $7 million TVL. PayCash offers swapping and fiat-to-crypto on-ramping features. As noted above, PayCash suffered from an exploit in early May.
After launching in April, the EOS EVM ended the quarter with over $1 million in TVL. AMM Noah Swap has so far been the most popular protocol, with almost $800,000 TVL. Since launch, Noah Swap has been conducting an airdrop for its token NOAH, rewarding traders and liquidity providers. NOAH ended the quarter with a circulating market cap of $141,000. As noted above, the Noah team also runs an EVM miner. Other EOS EVM DeFi protocols include DEXs Neutroswap and Frogge.Finance.
The ENF created two programs to bolster EOS’s DeFi ecosystem: Yield+ and Recover+. Yield+ is a liquidity incentive program that distributes $EOS to DeFi protocols for them to offer as additional rewards. To participate, protocols need to meet certain criteria, including a minimum TVL threshold, passing a KYC check, and passing a smart contract audit. As mentioned above, the EOS EVM 0.5.0 upgrade enabled Yield+ on the EVM. Recover+ is an insurance program for the same protocols participating in Yield+. It offers funding and consulting to help prevent exploits and respond to them if they do happen. Notably, PayCash is not a member of the program.
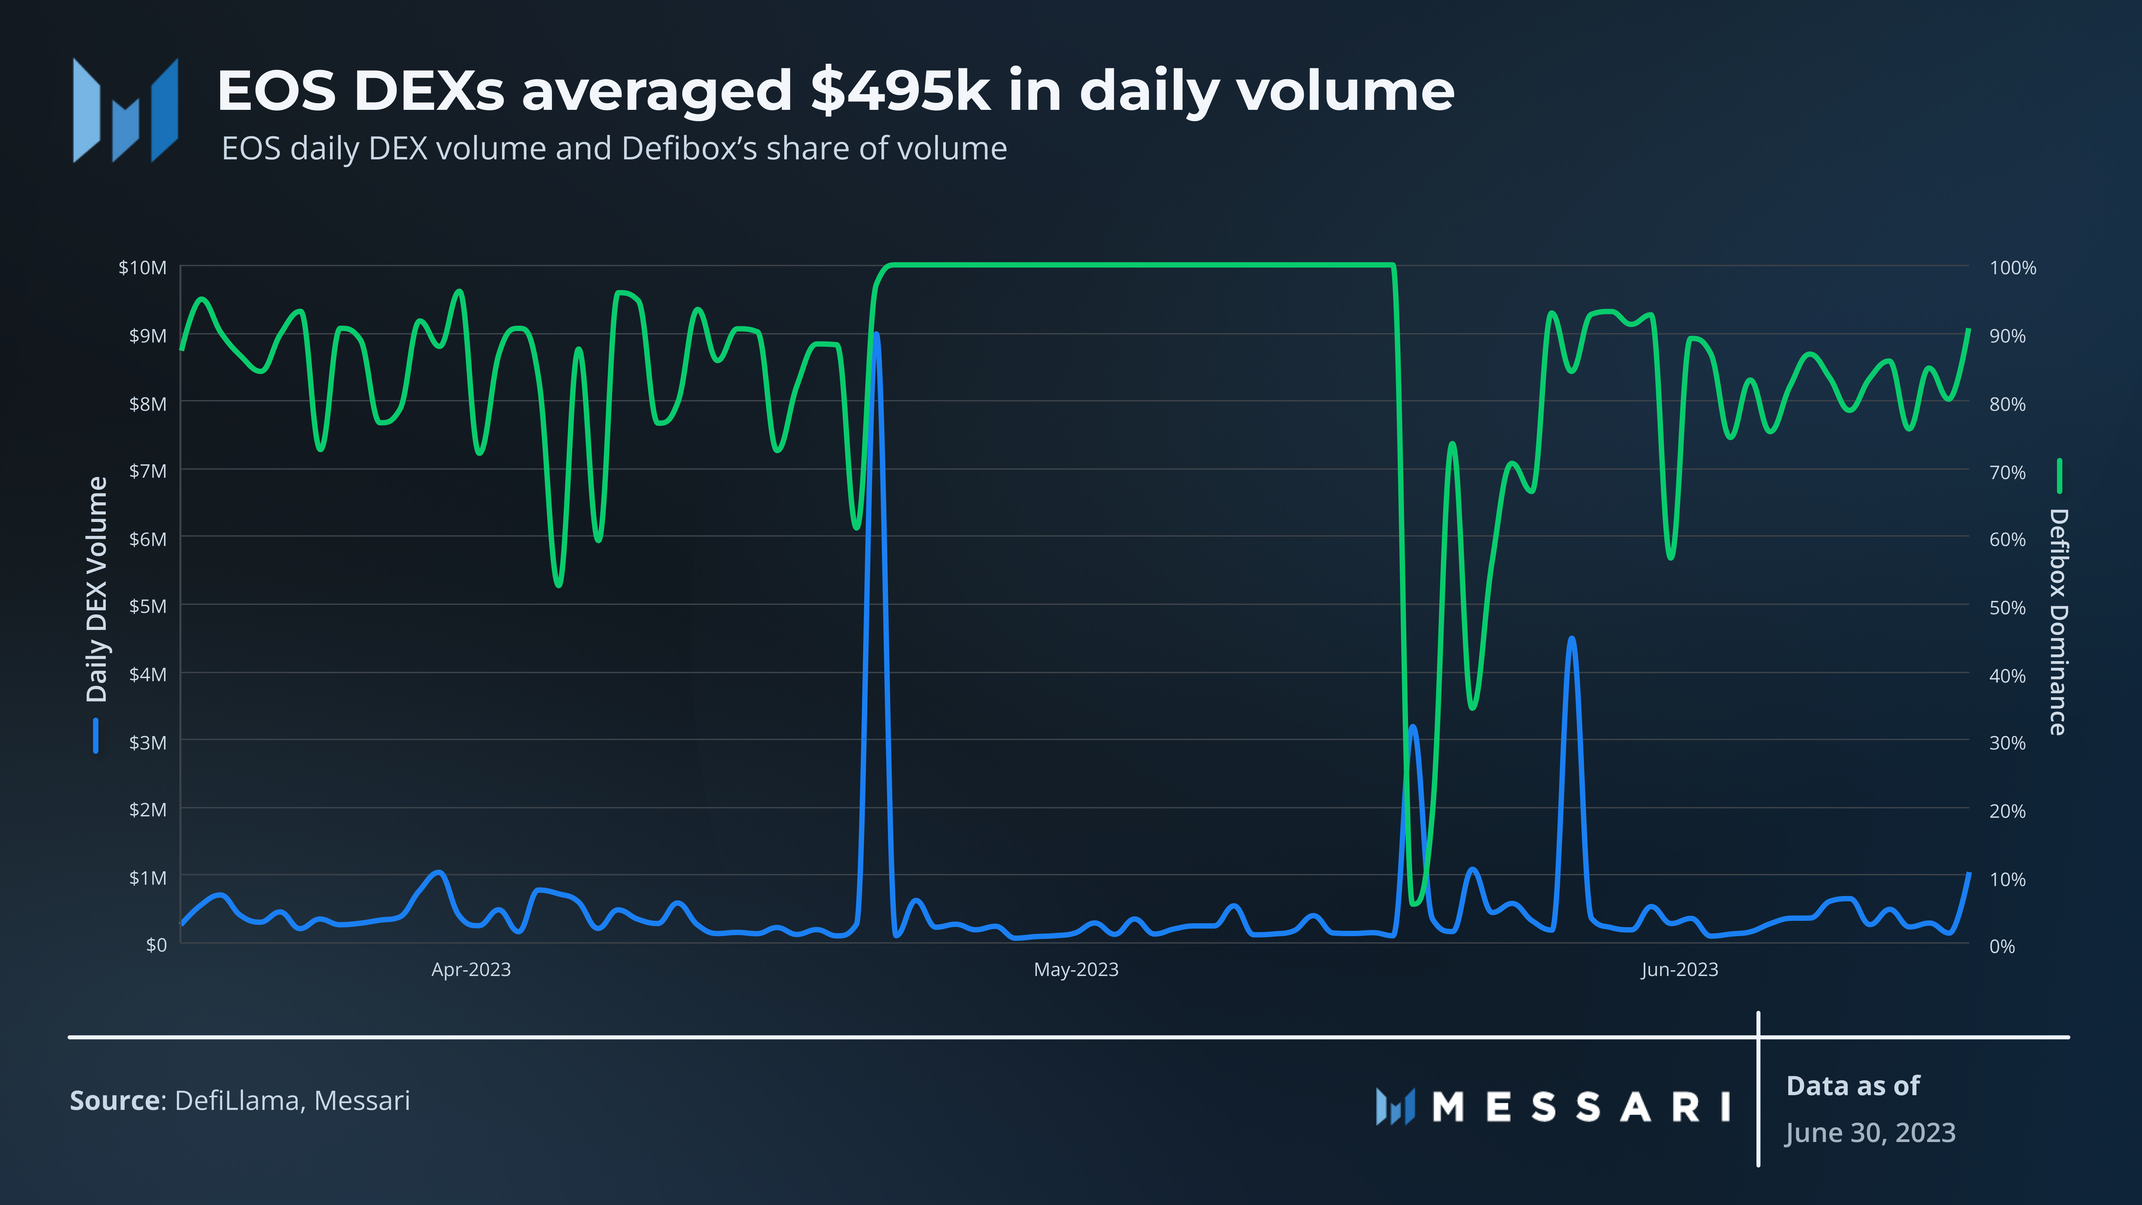
The average daily DEX volume on EOS native increased 3% QoQ to $495,000. There was a spike of almost $9 million in DEX volume on May 6, likely relating to the PayCash exploit.
As with TVL, Defibox has been home to most DEX volume, accounting for over 80% of the quarterly volume.
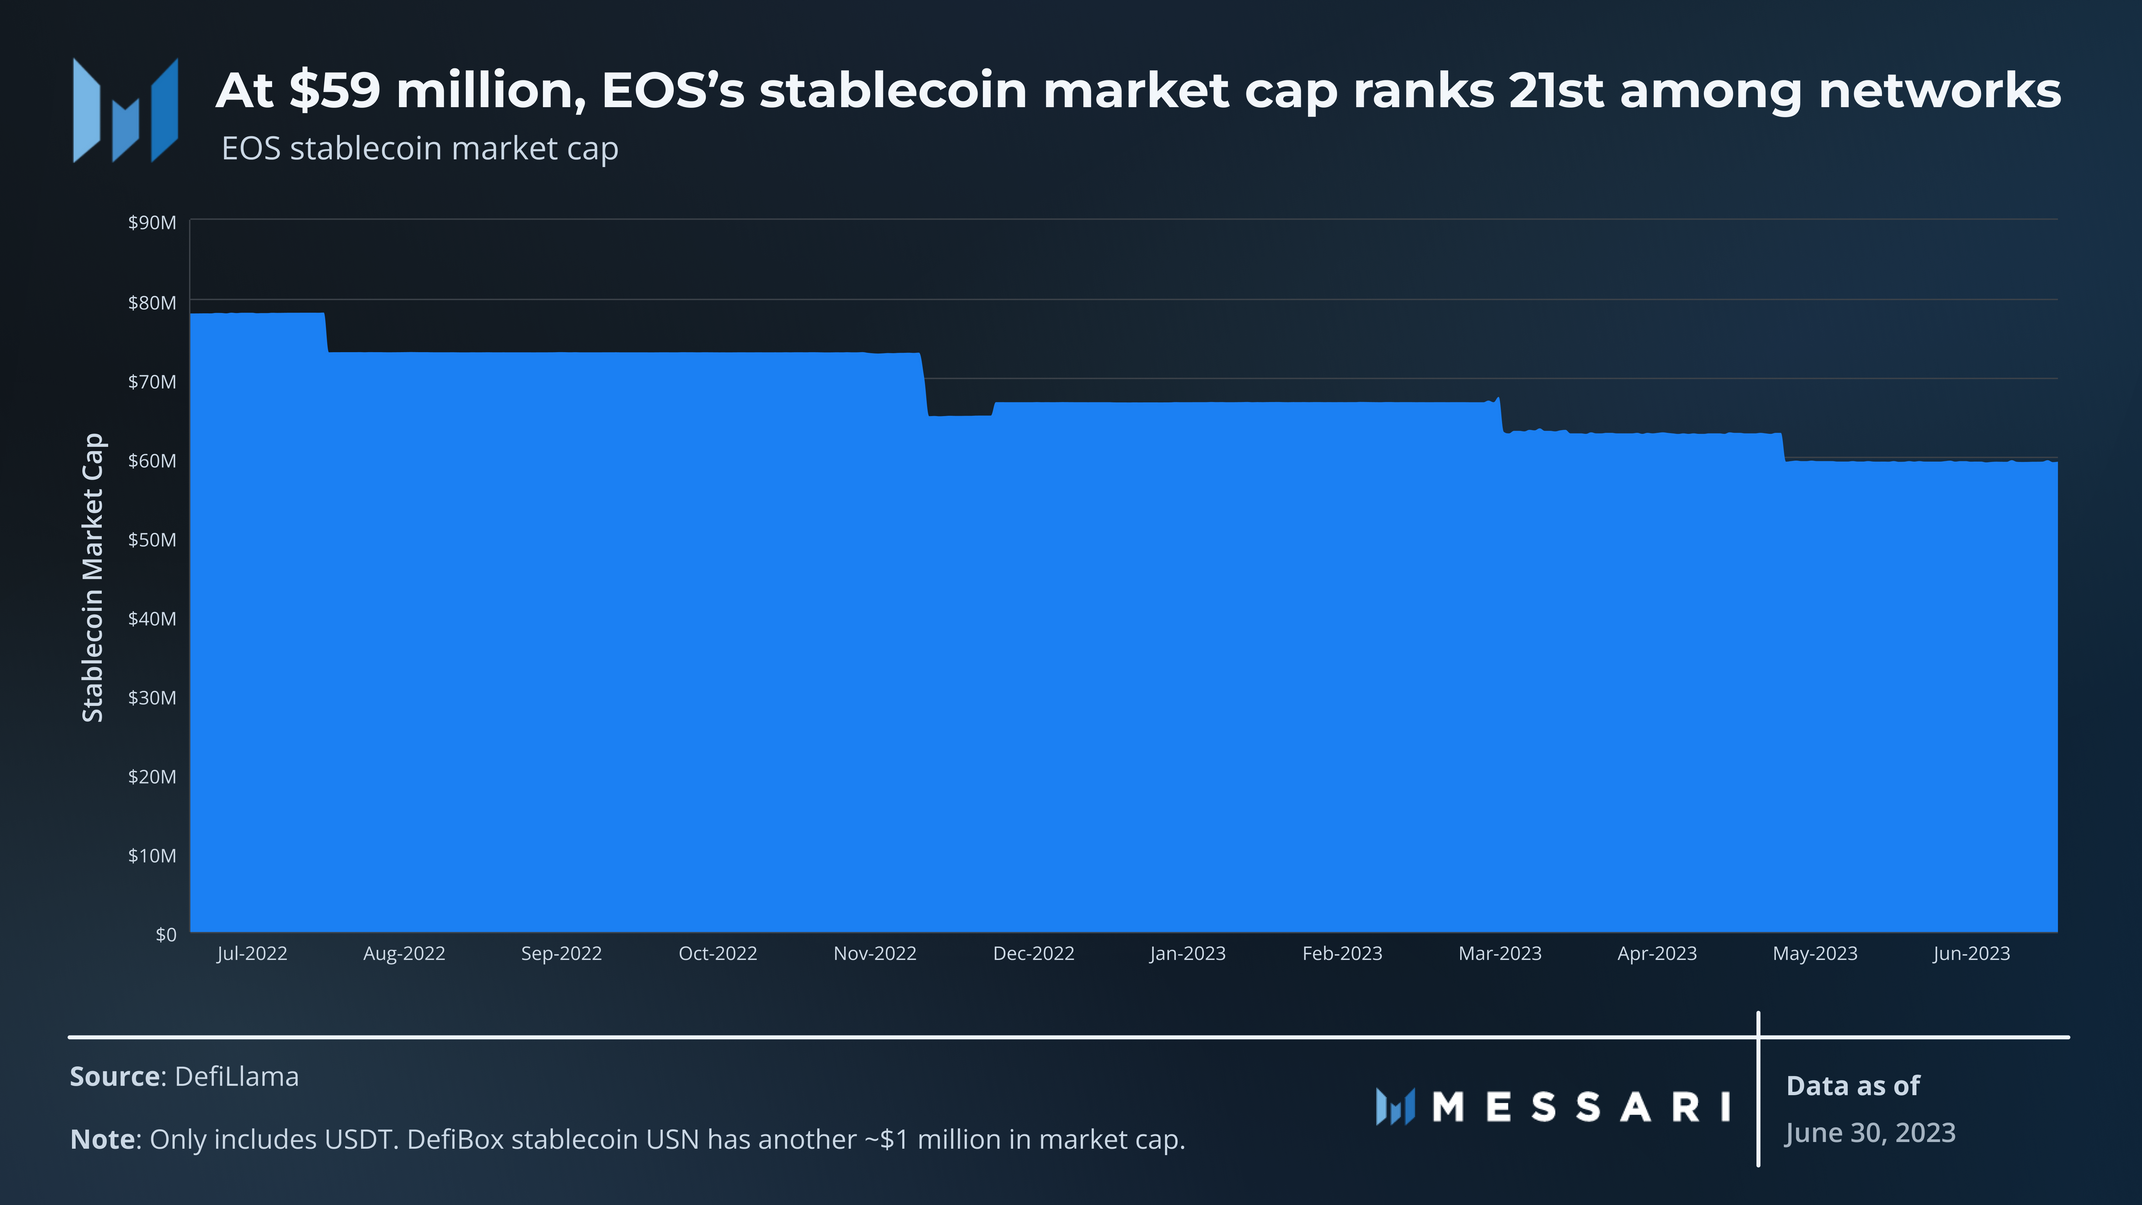
EOS native’s stablecoin market cap has gradually decreased over the past year; however, it still ranks 21st among all chains at $59 million. This figure is entirely composed of USDT. EOS is one of thirteen networks natively supported by Tether. There are also some EOS native stablecoins, namely USN, which are not included in this data. USN is an overcollateralized stablecoin generated through staking various tokens on Defibox. At the end of the quarter, USN’s market cap was just over $1 million.
NFTs, Gaming, and DAOs
The most popular dapps by address activity on EOS are gaming related, including Upland, Prospectors, Crypto Dynasty, and Dungeon Master.
Upland is a Play-to-Earn digital real-estate and metaverse game. In May, Upland held a hackathon, partnering with the ENF to offer $10,000 in prizes to winners.
Dungeon Master is an NFT-based game created by Wombat. Wombat is a gaming platform that includes its own native wallet. In May, Wombat announced its accelerator program Wombat X with several founding partners including the ENF. The program aims to help early-stage games develop their infrastructure and build their audience.
All of the above-listed games are several years old, with most of them launching around 2019. To attract new games, the ENV launched a $20 million fund dedicated to GameFi and EVM projects.
AtomicHub is the network’s primary NFT marketplace with over 5,000 collections listed. On the last day of the quarter, AtomicHub facilitated around $900 in volume between 1,200 sales.
Hypha is a DAO tooling platform with features including decentralized governance frameworks, multi-sig wallets, and more. After receiving an $850,000 grant from the ENF in September 2022, Hypha launched its beta program at the beginning of Q2’23 and started a waitlist that organizations can join.
Development
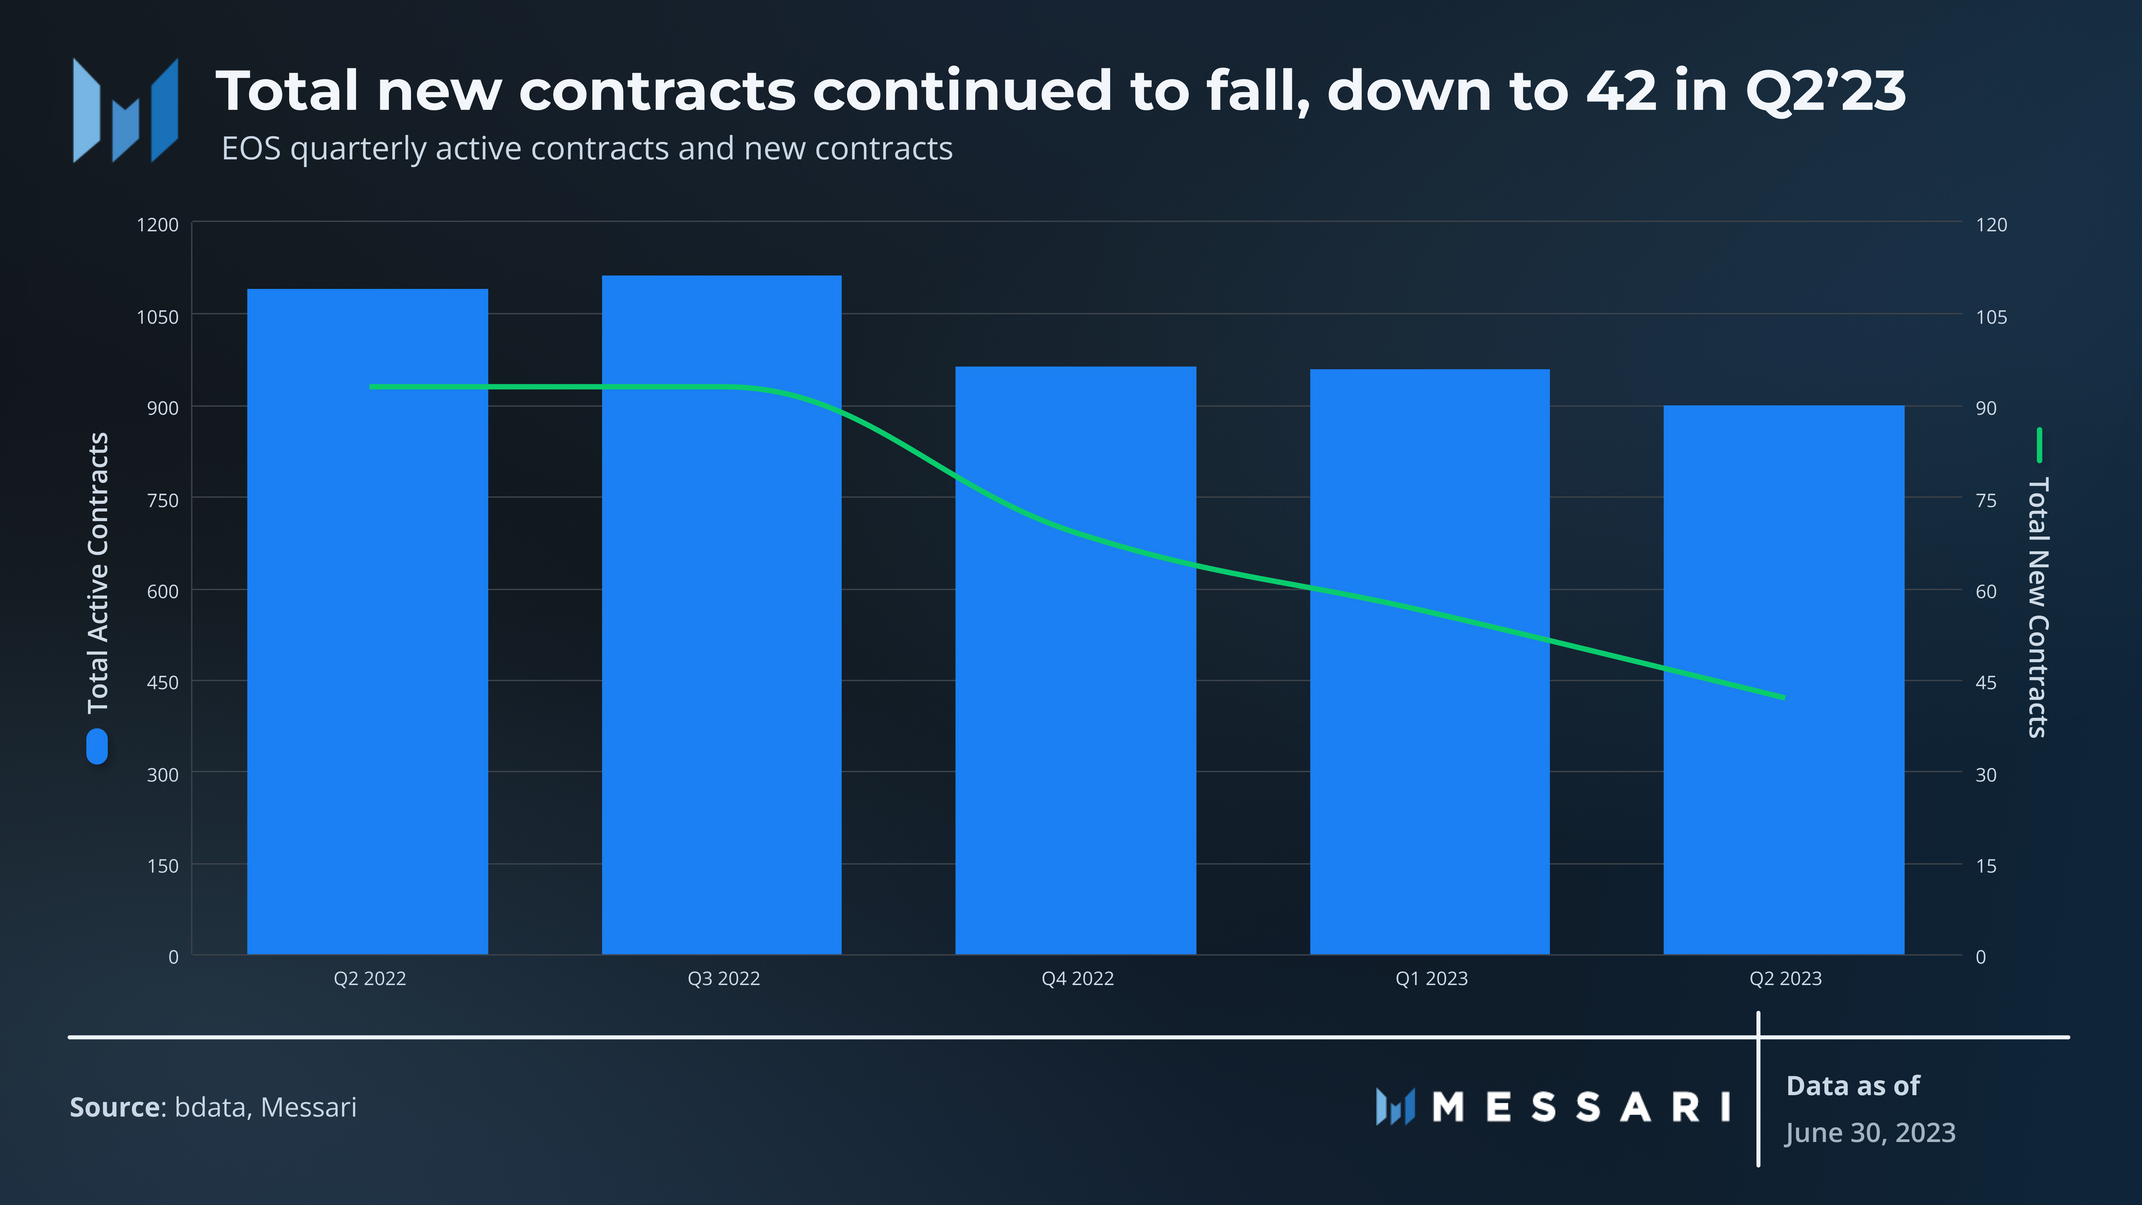
Ecosystem development, measured via the number of unique contracts called and new contracts, has gradually decreased in the past year. The number of quarterly unique contracts called decreased 6% QoQ and 17% YoY to 900. Quarterly new contracts fell more substantially, down 25% QoQ and 55% YoY to 42.
Several tools to improve smart contract developer experience featured upgrades in Q2’23. Docker Utilities for Node Execution (DUNE) is a tool that helps perform several core functions involved in smart contract development, including node management, smart contract compiling, and running tests. DUNE upgraded twice in the quarter to improve backwards compatibility, port forwarding, and reference-contract upgrades. Contract Development Toolkit (CDT) is another tool helping developers write C/C++ smart contracts for Antelope chains. Released in May, V4.0.0 introduces a new project manager, adds support for additional crypto primitives, and fixes several bugs.
Growth
Ecosystem growth is driven by several programs and groups including Pomelo, the ENF Direct Grant Framework, and EOS Network Ventures.
Pomelo is an open-source public good crowdfunding platform modeled after Gitcoin. Like Gitcoin, Pomelo features a quadratic funding mechanism, which uses a matching pool funded by partners to boost individual donations. Pomelo’s sixth round occurred in the month of June. The ENF contributed $158,000 across three matching pools:
- $65,000 to the GameFi pool. Top recipients included Pink Cat Eating Papaya, a play-to-earn game where players take care of their cat; NFT Game Stats, an analytics platform for EOS NFTs and games; and NewChat, a messaging protocol that can be integrated into games.
- $65,000 to the EOS EVM pool. Top recipients included Noah Swap; EVMNS, an EOS EVM name service; and Metahub, a web wallet with integration for both EOS EVM and EOS native, removing the need for users to switch between wallets to access both networks.
- $28,000 to a general EOS pool. Top recipients included EOS Ecosystem Dashboard, a dashboard that aggregates and reviews EOS projects; DAOBOX, an open-source governance tool; and Recover+, which plans to build a vault monitor into its insurance program offerings.
Through the Direct Grant Framework, the ENF gives out milestone-driven grants to teams. Applications are assessed by a committee of senior EOS community members, including some with technical expertise. The ENF announced four grant recipients in Q2’23:
- Alphaday received a $3,000 grant to build an EOS dashboard aggregating news, podcasts, ecosystem projects, protocol information, and more.
- FACINGS reached stage two of its grant, unlocking an additional $40,000 to continue developing its NFT creator and marketplace.
- Antelope Firewall received a $50,000 grant to build a proxy to be used in Antelope node operator infrastructure, making it easier for operators to run nodes and offer public endpoints.
- EOS Vision received a $10,000 grant to promote EOS through content across social media platforms.
In Q4’22, EOS block producers passed a proposal to mint around 68 million $EOS for an ecosystem fund managed by ENV. At the end of Q1’23, the ENV made a commitment to invest $20 million into EVM projects and GameFi projects (across both EOS native and EVM). The first round of investments totaled $5.4 million, with the recipients to be announced shortly.
On the same day as the EVM launch, the ENF announced a partnership between DWF Labs and ENV. The partnership includes a $45 million token purchase agreement and a $15 million commitment to invest in EOS projects. Some industry members voiced concerns over DWF’s operations, but the firm defended its investment strategy.
In general, the ENF has been focused on expanding within the Asian market. ENF CEO Yves La Rose shared that business development efforts in Asia include: applying for a residency in Hong Kong; working with a regulatory body to make EOS available in a new, to-be-announced location; and meeting with government officials, businesses, and other potential partners in Hong Kong and Asia in general.
Closing Summary
Q2’23 featured a milestone product launch for EOS with EOS EVM going live. The network has EVM amassed over $1 million in TVL and averaged 5,100 in daily transactions. Growth initiatives, including ENV’s $20 million fund and contribution from ENF through Pomelo and its Direct Grant Framework, continue to target EVM as well as GameFi projects.
As the crypto market was driven down by negative U.S. regulatory actions, $EOS’s market cap decreased 43% to $740 million, ranking it 49th among all tokens. Several metrics related to activity and development, including daily transactions, active addresses, new addresses, and new contracts called, also fell QoQ. The above growth initiatives aim to reverse these downward trends and improve the strength and diversity of EOS’s network and ecosystem. Additionally, the consensus upgrade planned to launch in Q4’23 will improve network decentralization and user experience.
Let us know what you loved about the report, what may be missing, or share any other feedback by filling out this short form. All responses are subject to our Privacy Policy and Terms of Service.
This report was commissioned by the EOS Network Foundation. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.

Peter is a Research Analyst in Protocol Services focused on Layer-1s. He recently graduated from Boston College where he studied economics and computer science and led the school's blockchain club.
Mentioned Assets