On Wednesday, February 2nd, Ryan Selkis, Chase Devens, and James Trautman went live with the Ava Labs team to have a more in-depth conversation about the current state of Avalanche and their roadmap for the future. View the full recording now or read the transcript of the call here.
Key Takeaways
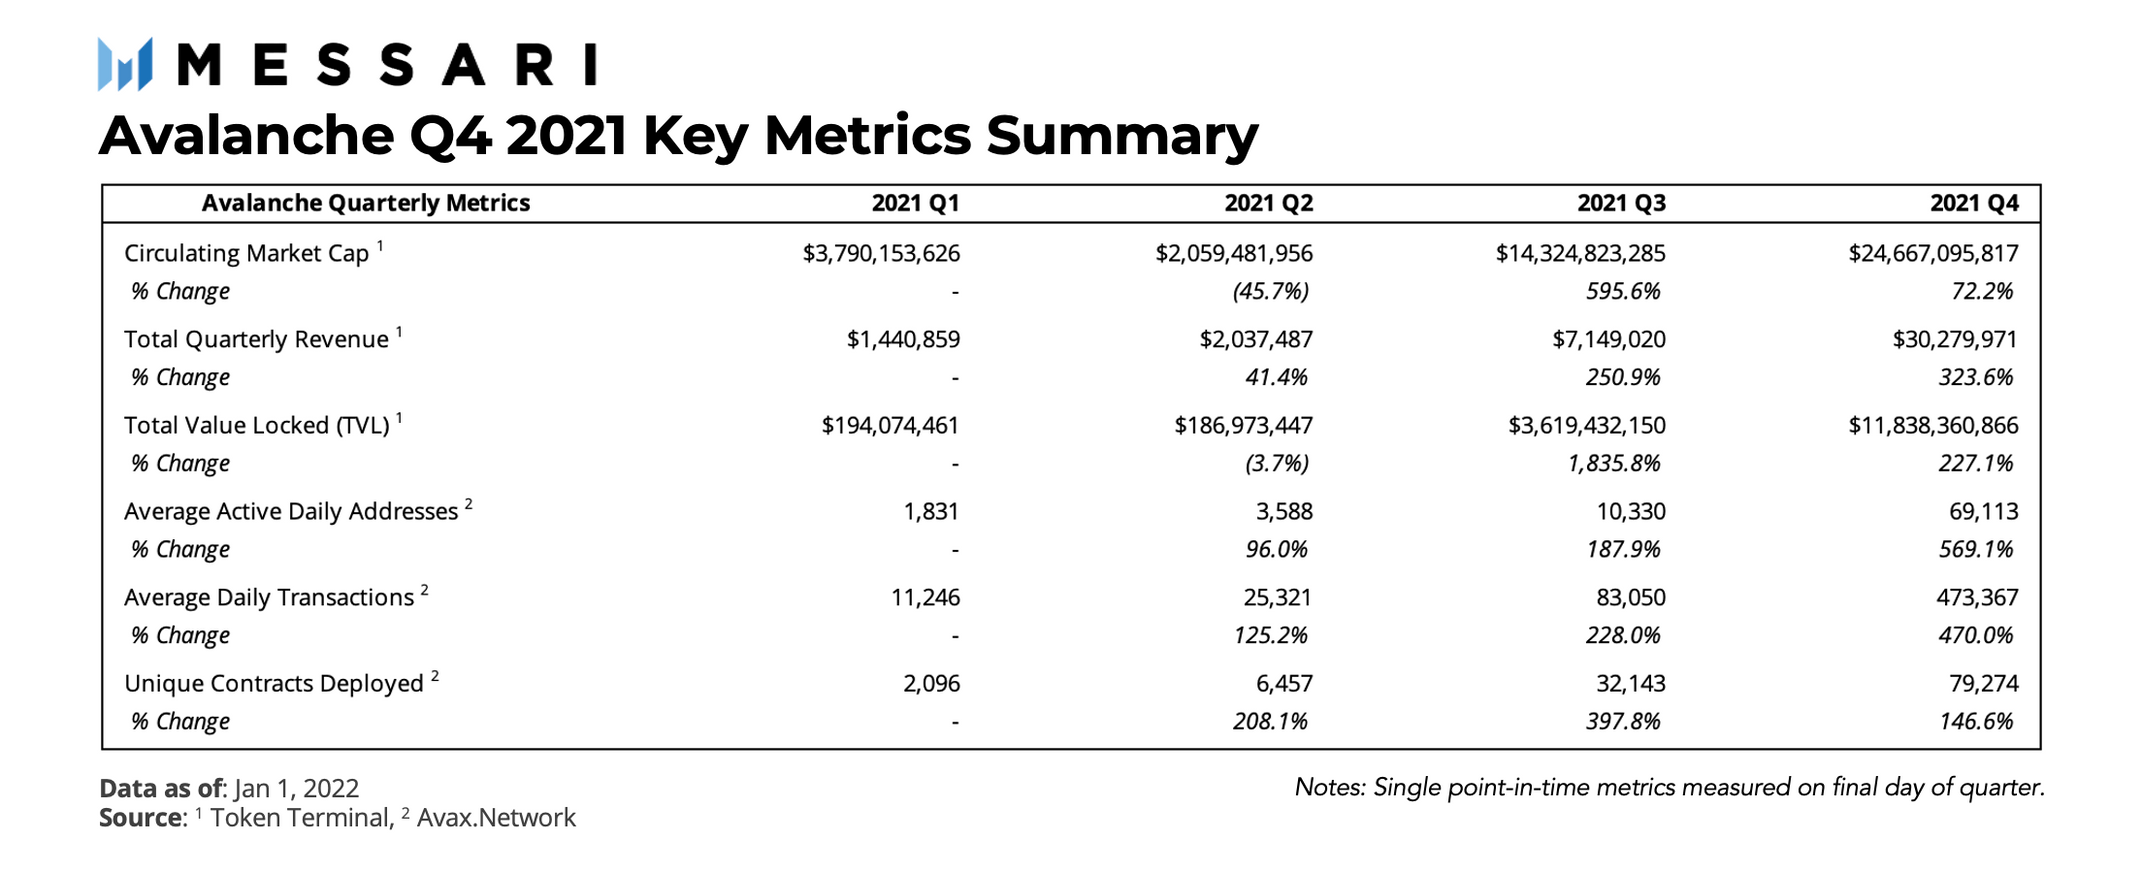
Avalanche recorded all-time highs in active addresses, transactions, TVL, and market capitalization during Q4 fueled by incentive campaigns and network partnerships.
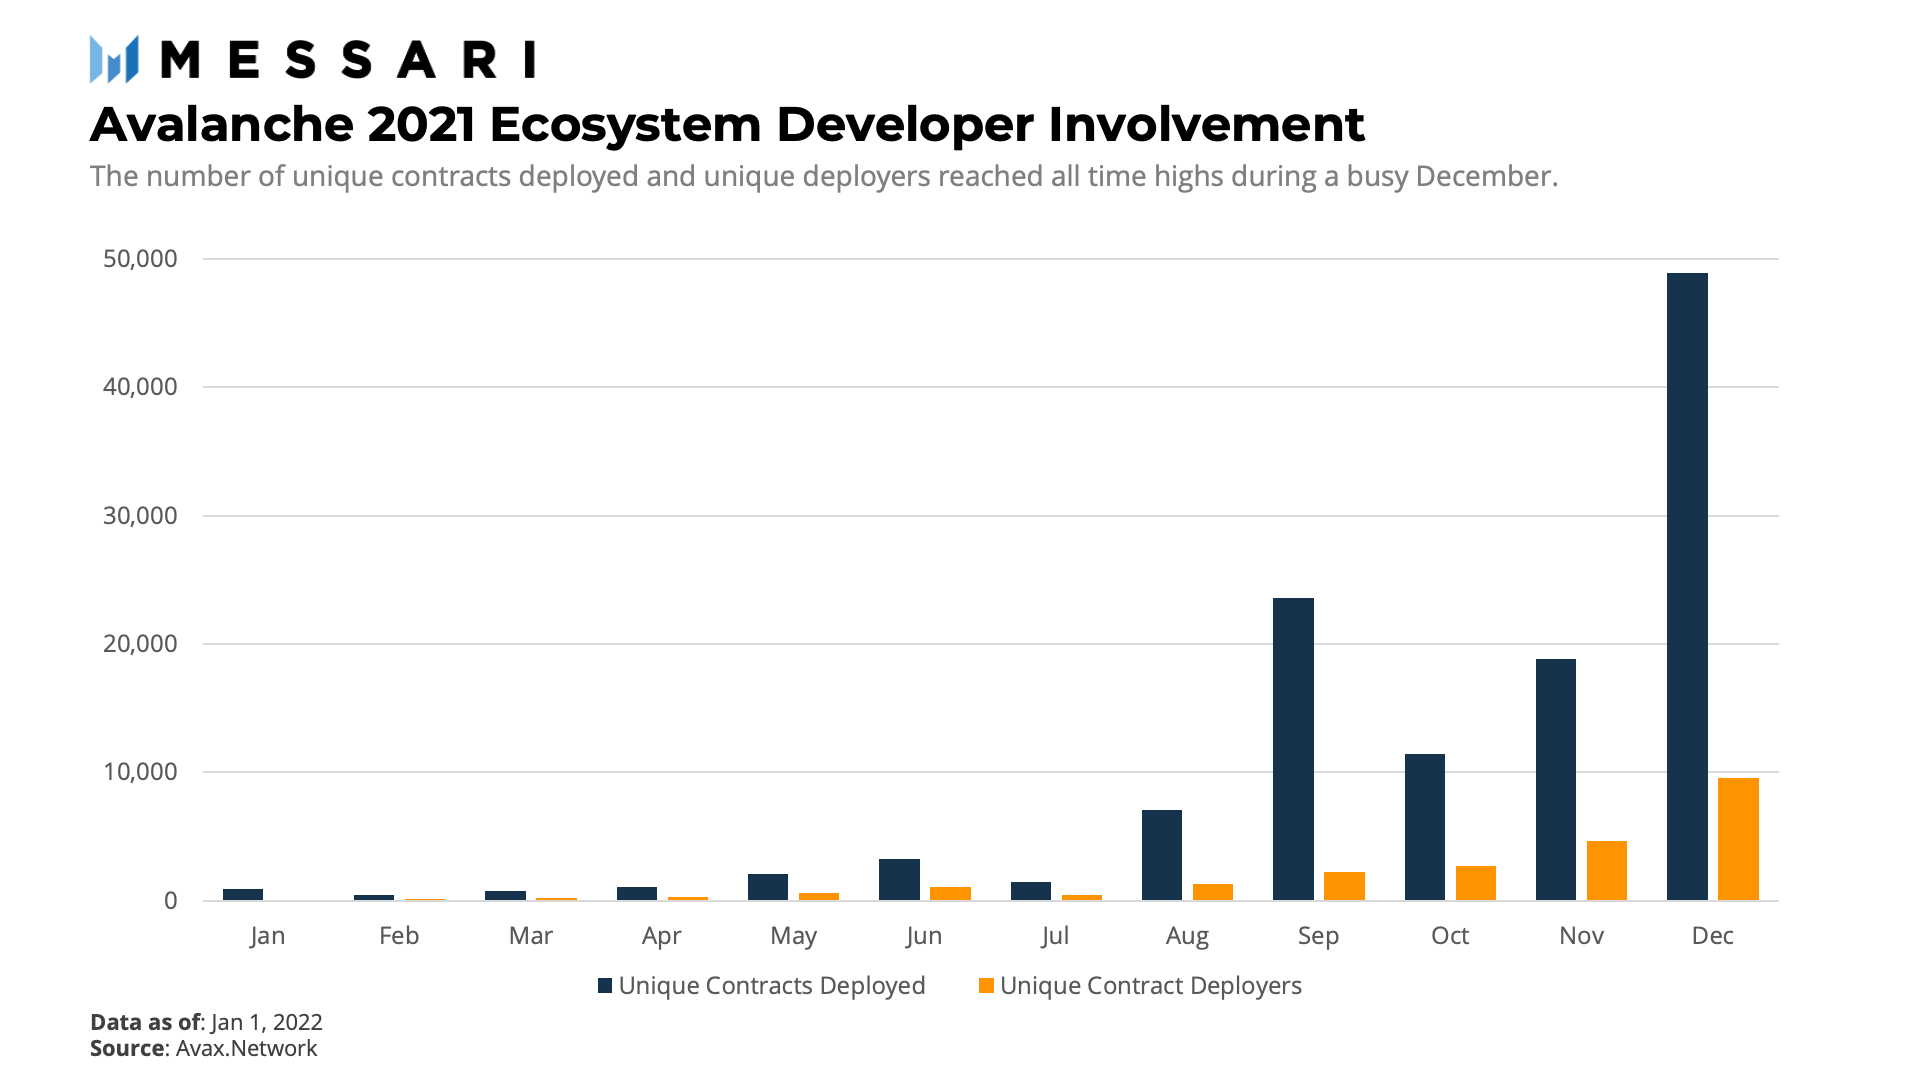
The arrival of Aave and Curve sparked a network-wide DeFi boom; the number of contracts deployed and unique contract deployers to the network both reached an all-time high in December.
Several patches were introduced at the network level to combat spiking transaction fees.
Introduction to Avalanche
The Avalanche network is a Proof-of-Stake (PoS) smart contract platform for decentralized applications. Whereas most competitors use consensus mechanisms in the Classical or Nakamoto families, Avalanche differentiates itself through its creation and implementation of a new consensus family known as “Avalanche consensus.” Following years of research, the Avalanche mainnet was launched in September 2020 and featured the release of all three Avalanche chains (the P, X, and C chains). As the first edition of quarterly coverage on Avalanche, this report will highlight important developments since the launch of Avalanche’s mainnet in addition to standard evaluation of the network’s most recent quarterly performance. A full appendix of quarterly events and data are available at the end of the report.
Network Overview
One of the defining narratives of 2021 was the rise of alternative Layer-1 smart contract platforms that began eating away market share from the industry leader, Ethereum. Due to congestion on the Ethereum network and slow rollout of Layer-2 scaling solutions, newer Layer-1 platforms were able to offer better support for marginal users. After its late 2020 mainnet launch, the Avalanche network found itself in the right place at the right time to welcome new participants into its economy.
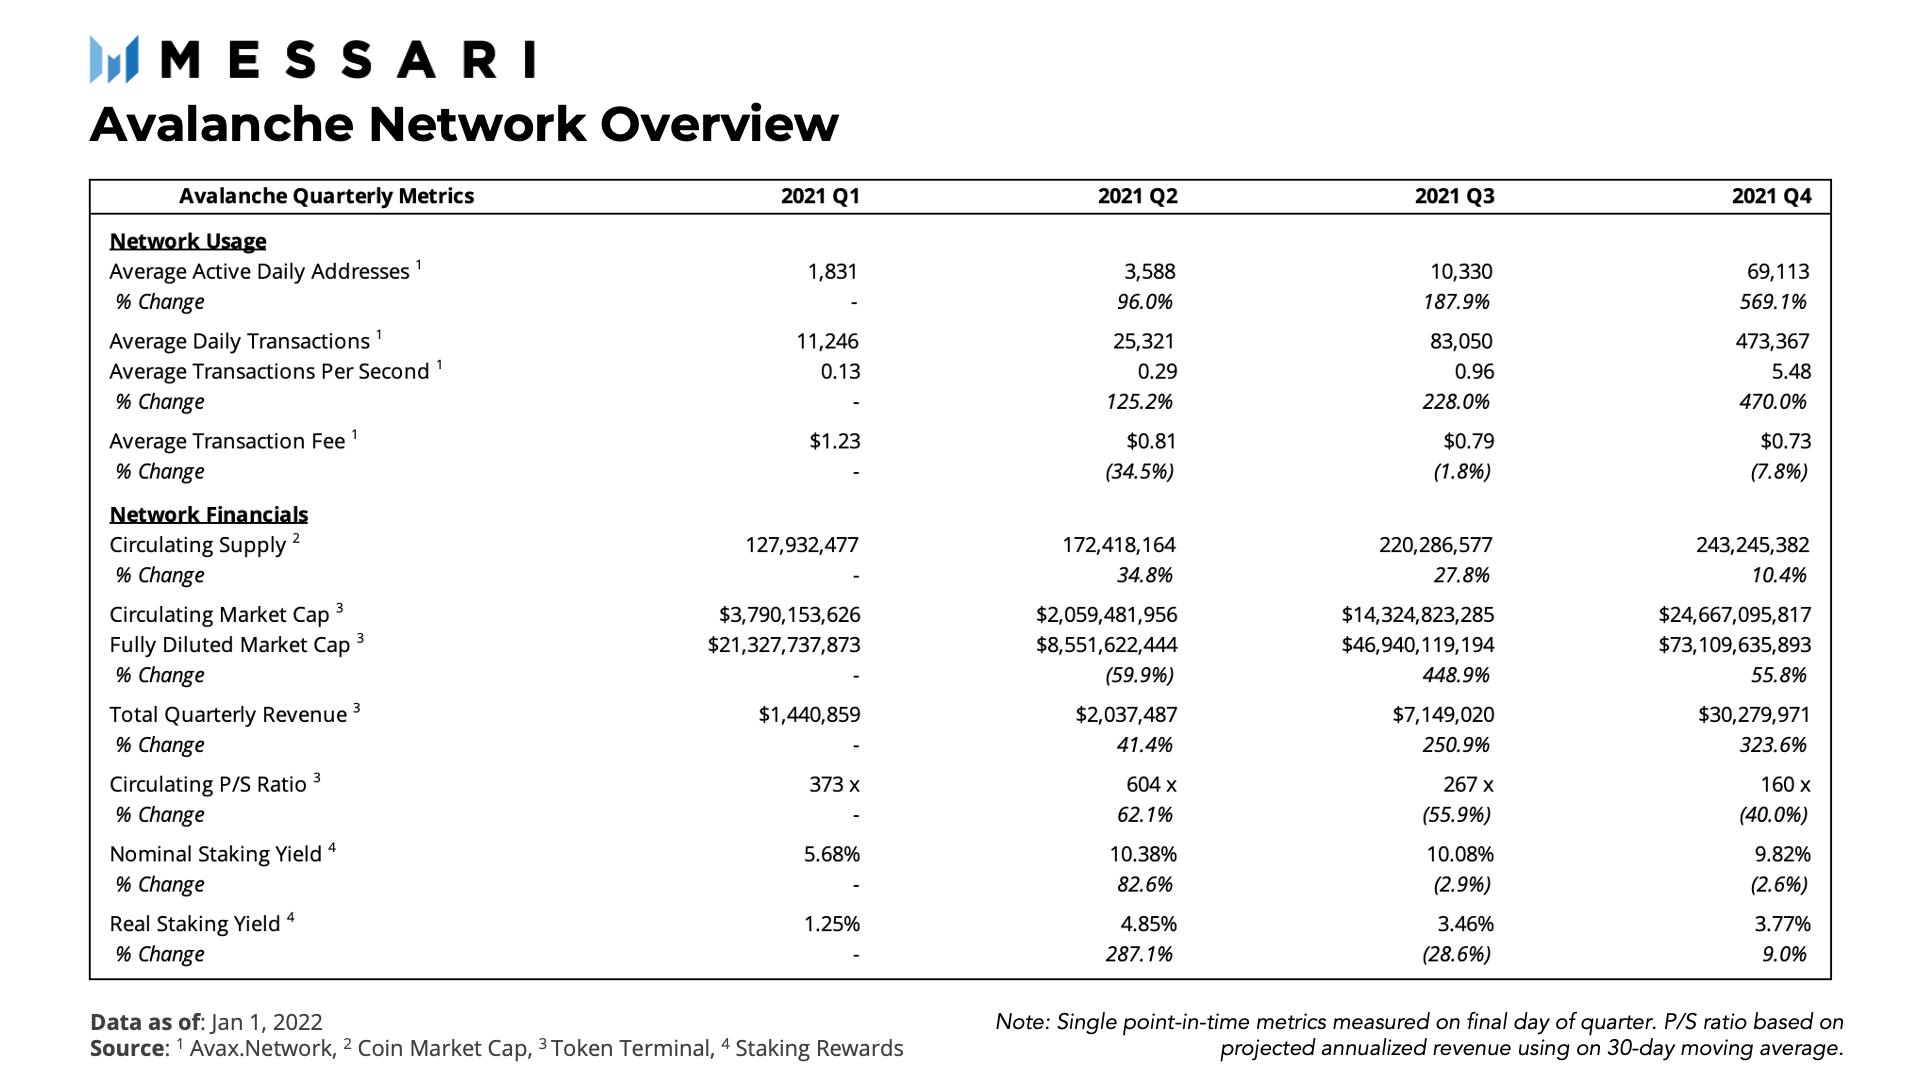
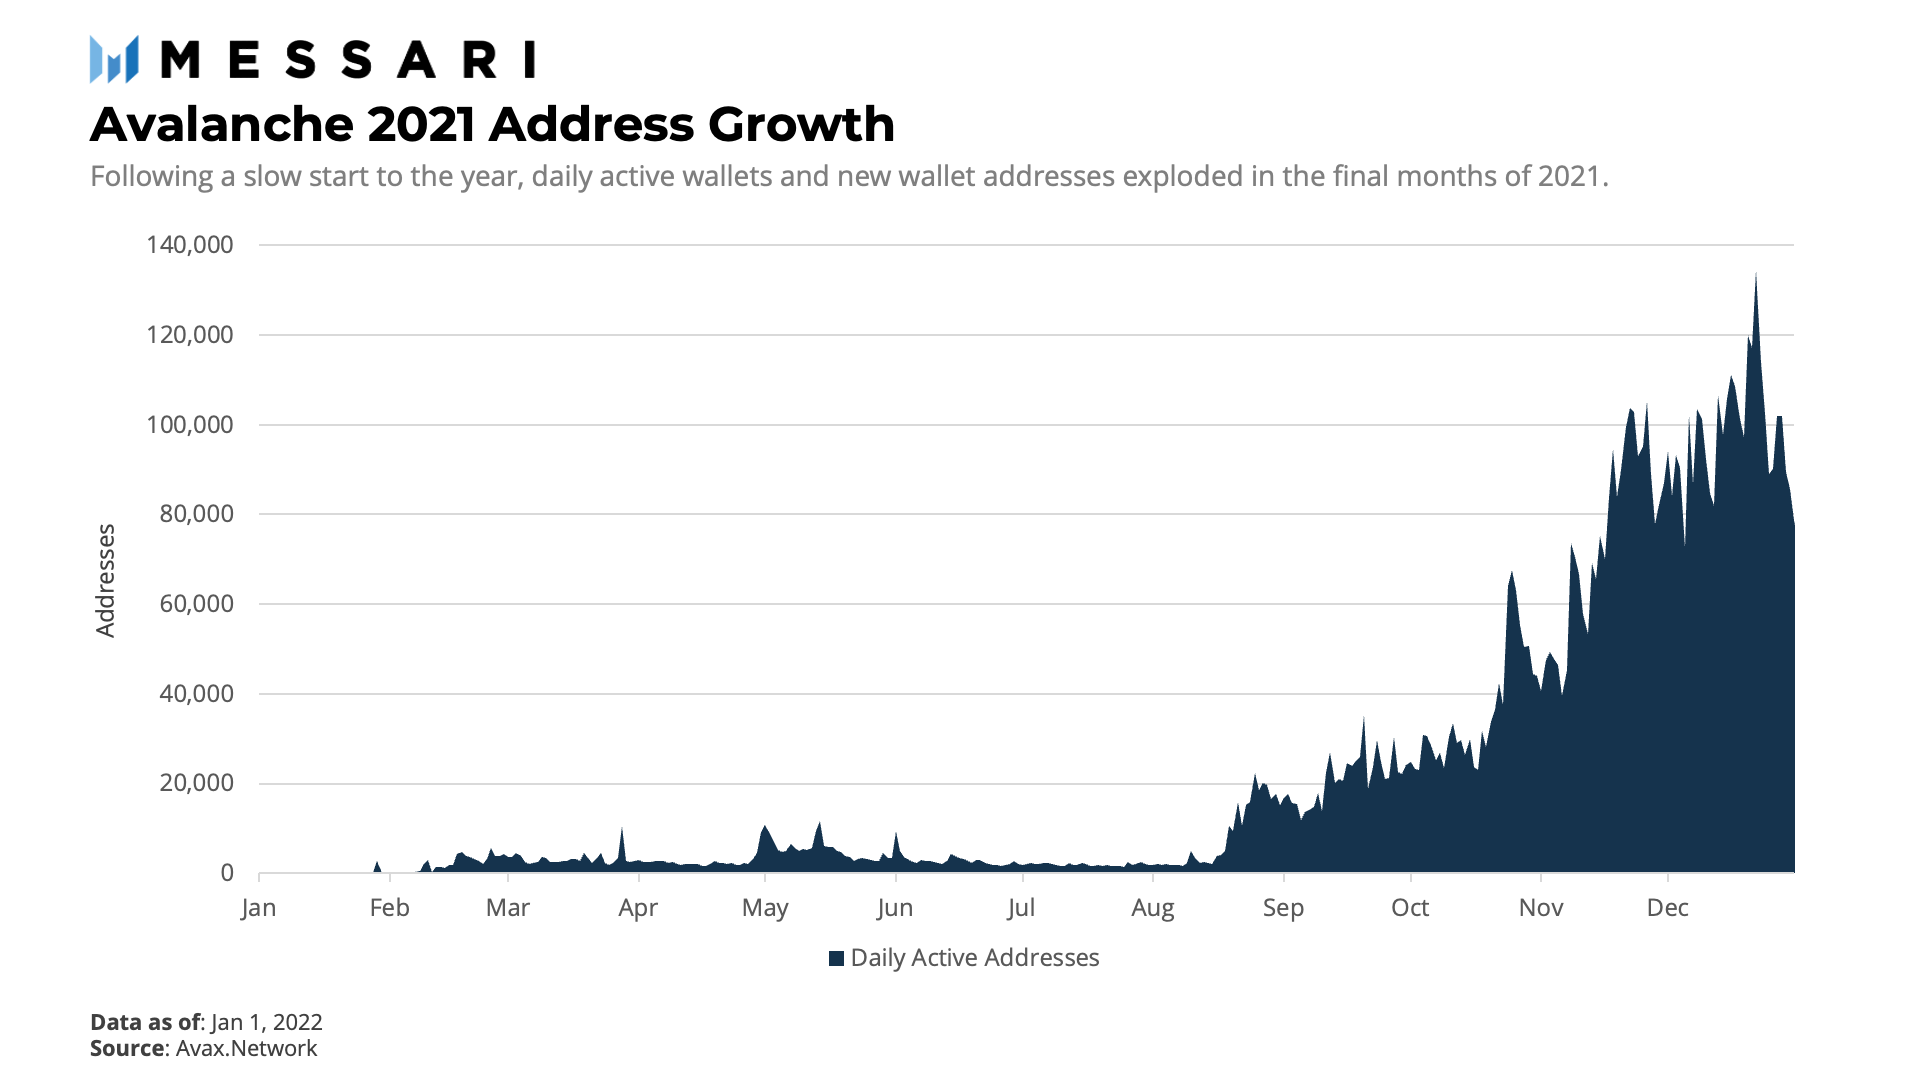
The launch of the official Avalanche-Ethereum bridge in February 2021 saw the first small group of users trickle into the network. However, these early adopters would be forced to wait until Q3 for more company in this uncharted ecosystem. Material network growth began in the second half of August following the release of an upgraded bridge and the announcement of liquidity mining incentive programs. Avalanche averaged around 10,000 daily active addresses during Q3 before experiencing exponential growth throughout Q4 and averaging roughly 70,000 active addresses per day. Whether this can be attributed to long-term network effects or temporary incentives will be an area to monitor going forward.
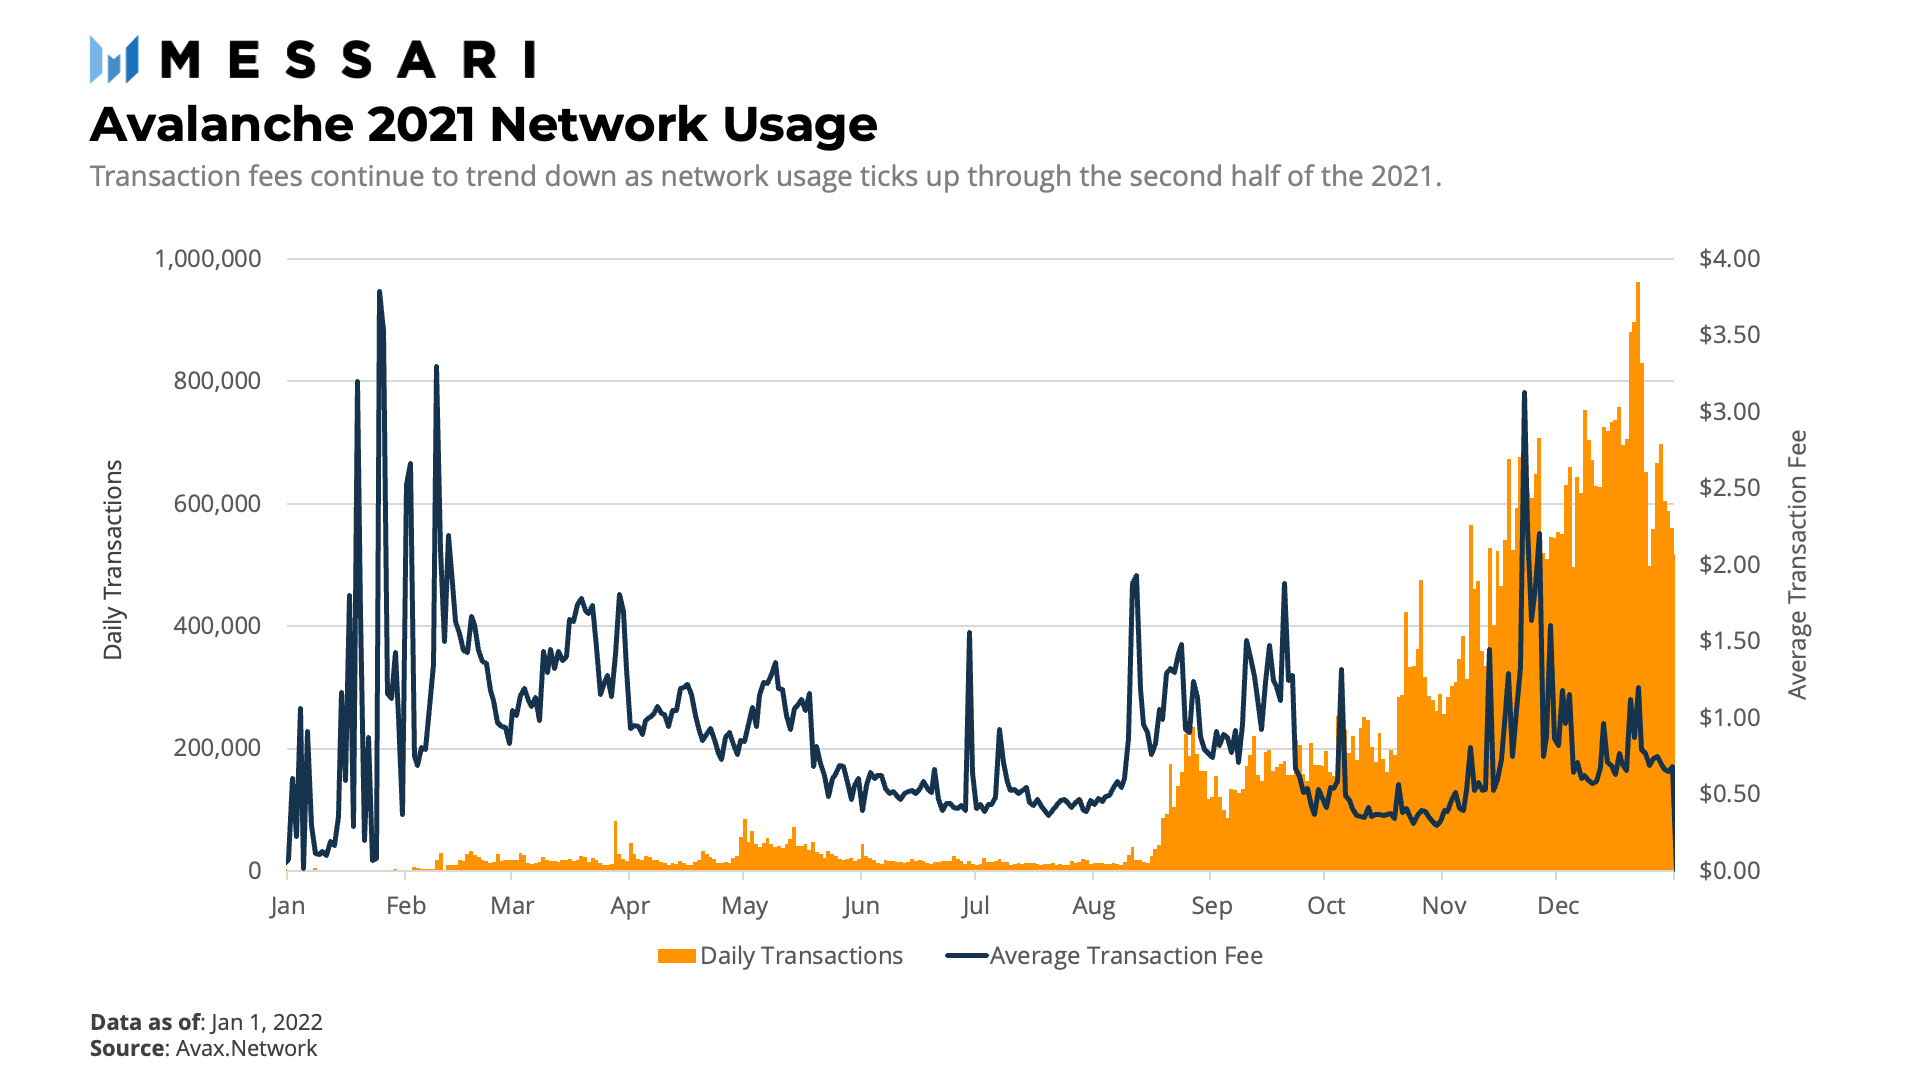
Not surprisingly, transaction activity on the network followed a nearly identical pattern to that of address growth. The mid-October spike in transactions can be partially attributed to the launch of Aave and Curve on the network as part of the $180 million Avalanche Rush liquidity mining program. It should be noted that the dollar value for the Avalanche Rush campaign announcement was quoted when AVAX was trading at around $20.
On aggregate, Avalanche finished Q4 averaging about 475k transactions per day, a number that is almost 40% of Ethereum’s roughly 1.25 million average transactions per day. Given this rapid adoption, Avalanche is becoming an enticing platform for upcoming projects that want to maintain EVM compatibility while attracting fee-sensitive users. While gas fees were trending up in tandem with transaction volume on Ethereum, Avalanche’s daily average transaction fees remained relatively stable despite an increase in transaction volume. Q4 witnessed a few notable spikes in transaction fees, but at its peak, users were only forced to pay an average of $3 for their requests, still a fraction of Ethereum’s Q4 daily high of $62 per transaction.
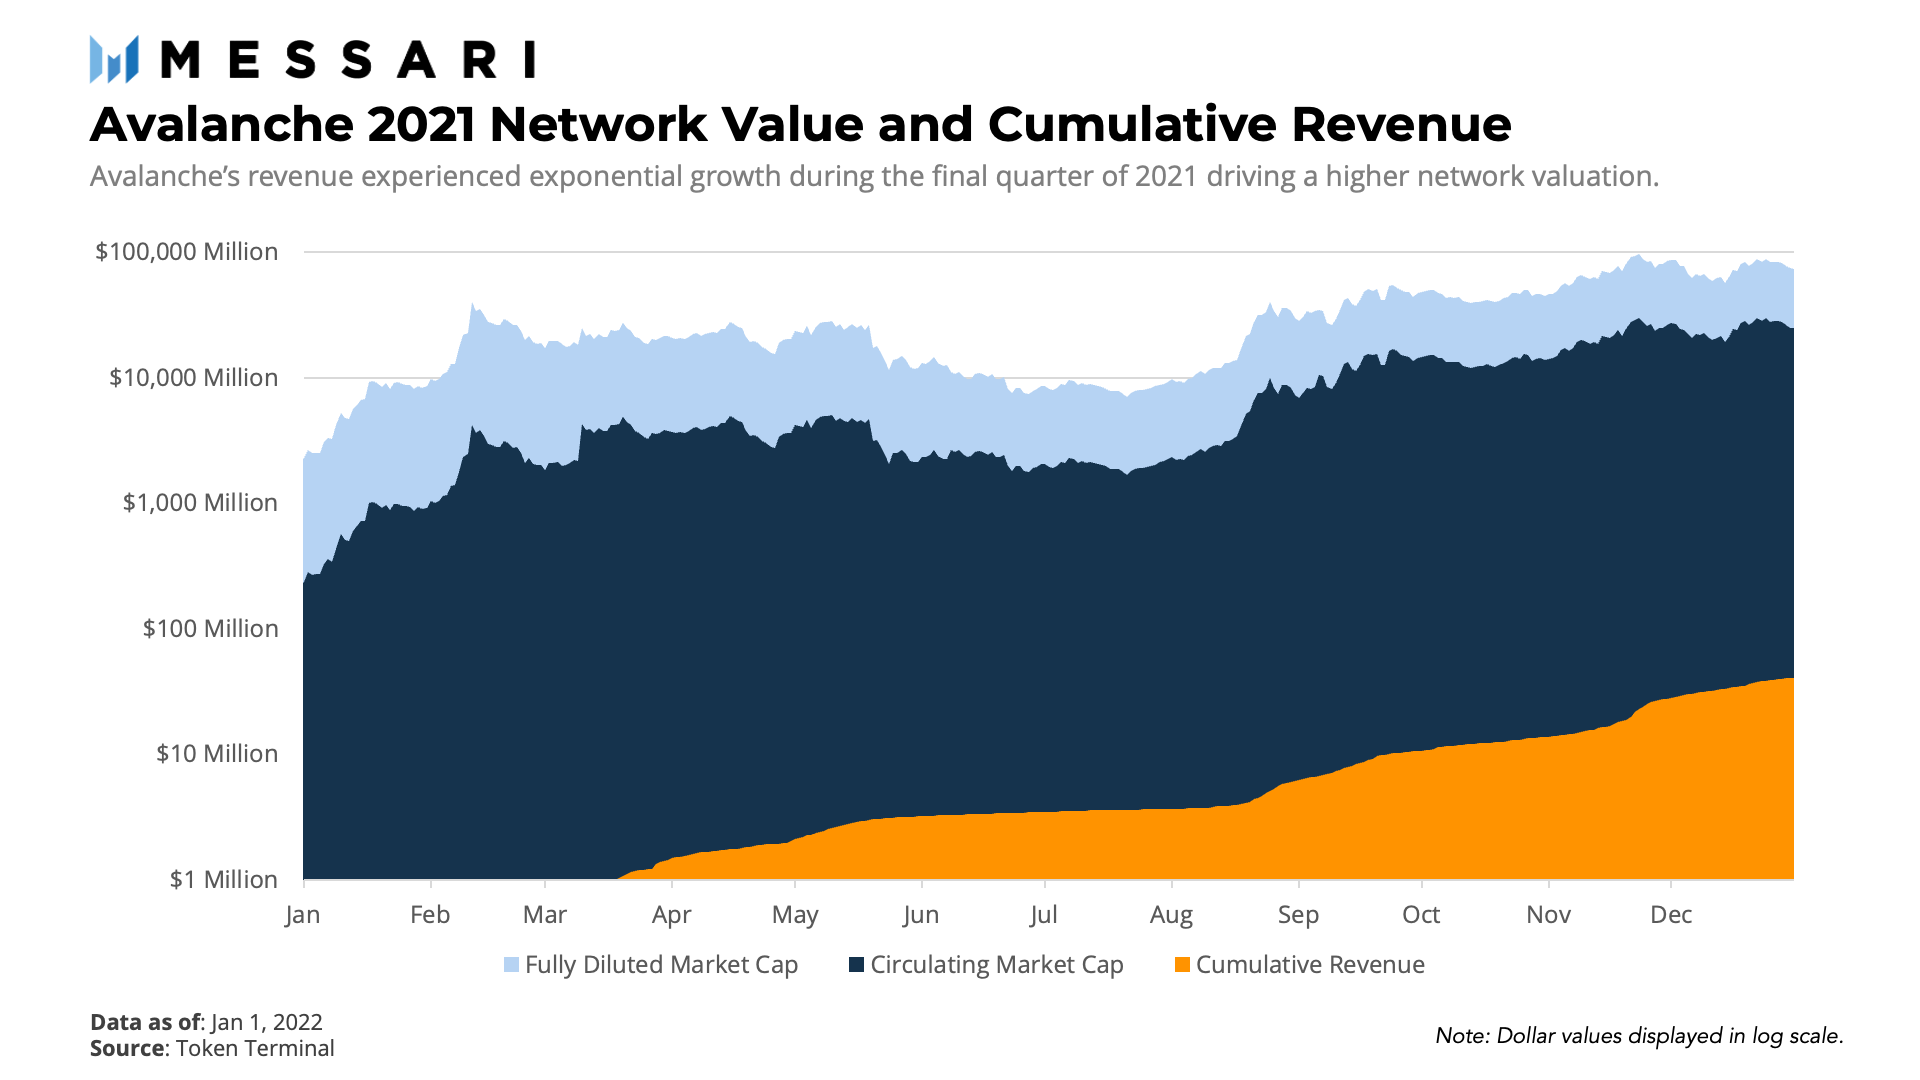
Avalanche recorded its highest quarterly relative valuation growth in Q1 2021. Given that the network supported less than 2,000 average active addresses and only generated an average of 11,000 transactions per day, it appears the 917% quarterly market cap growth was driven primarily by speculation. This resulted in a 373x price-to-sales (P/S) ratio. Fundamentals began catching up to the forward-looking valuation in Q3. The distribution of Avalanche’s network revenue (transaction fees) is atypical for smart contract platforms; rather than distributing transaction fees to validators, 100% of fees are burned from the network’s circulating supply. This drives value to all token holders in the form of increased scarcity rather than compounding the balances of validators and delegators. Q3 transaction volume grew 228% from Q2 while transaction costs remained relatively stagnant, allowing the network to produce just over $7 million worth of revenue and bringing its P/S ratio down to 267x - a 56% decrease from its quarter-ending high of 604x in Q2.
As the market's valuations cooled off in Q4, Avalanche's revenue continued to grow at an exponential rate in tandem with its transaction growth. The network produced $30 million in revenue during the quarter and saw its P/S ratio nearly half again to 160x. Comparing this Q4 P/S ratio with its PoS competitors, Avalanche comes in behind Binance Smart Chain (58x) but ahead of Fantom (228x), Polygon (424x), Solana (676x), Near (2,784x), Terra (5442x), and Cosmos (11,953x).
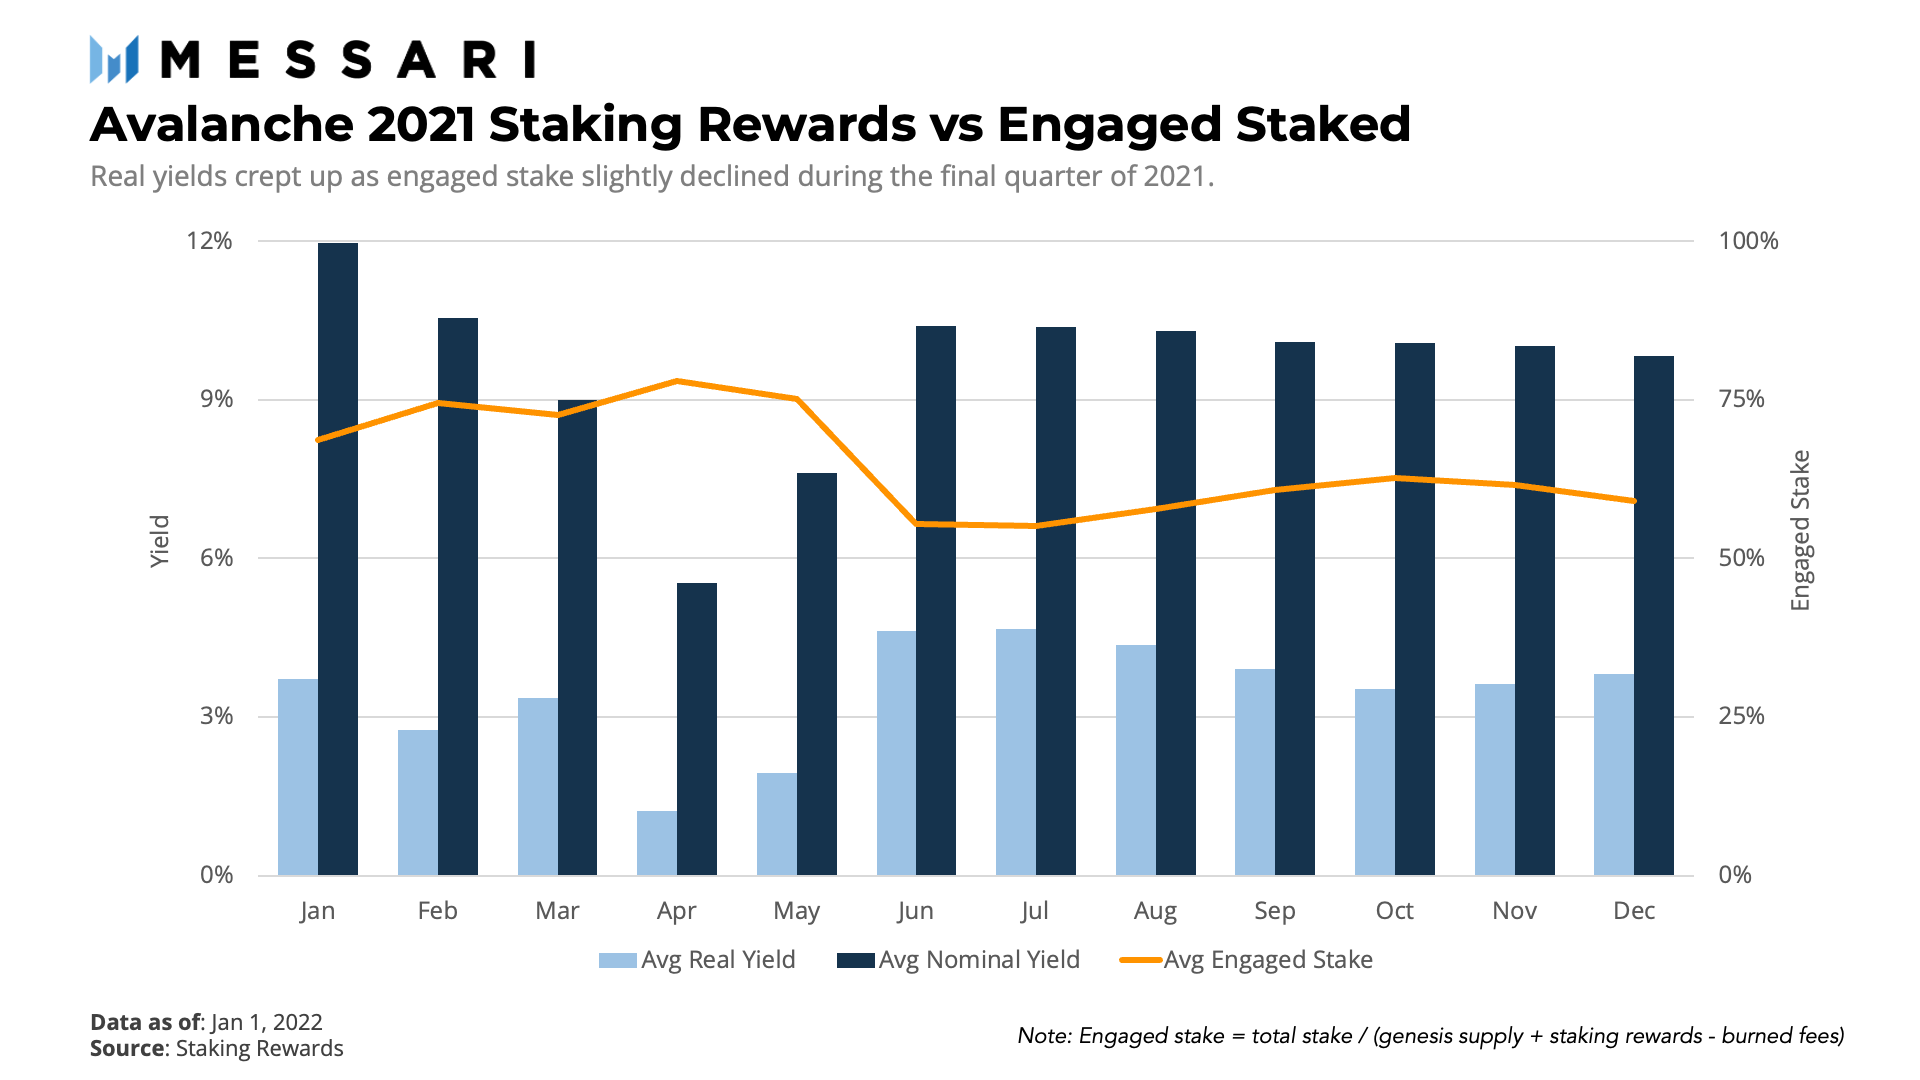
Because all transaction fees are burned, Avalanche staking rewards consist solely of new token issuance. Given the early state of the network, Avalanche’s staking rewards were highly inflationary during 2021. Most months hovered near double-digit nominal yields. A key feature of AVAX staking is that the vesting supply can still be staked. This resulted in a higher percentage of engaged stake and significantly lower real yields early in the year. Yields between March and May were volatile due to network upgrades and short periods of offline validators. A supply unlock coincided with a decrease in engaged staking rate in June before yield and engaged stake volatility declined. In Q4, engaged stake saw a slight decline which coincided with a small rise in real yield. This could be attributed to smaller stakers exiting to take advantage of Avalanche Rush incentives within DeFi.
Ecosystem & Development Overview
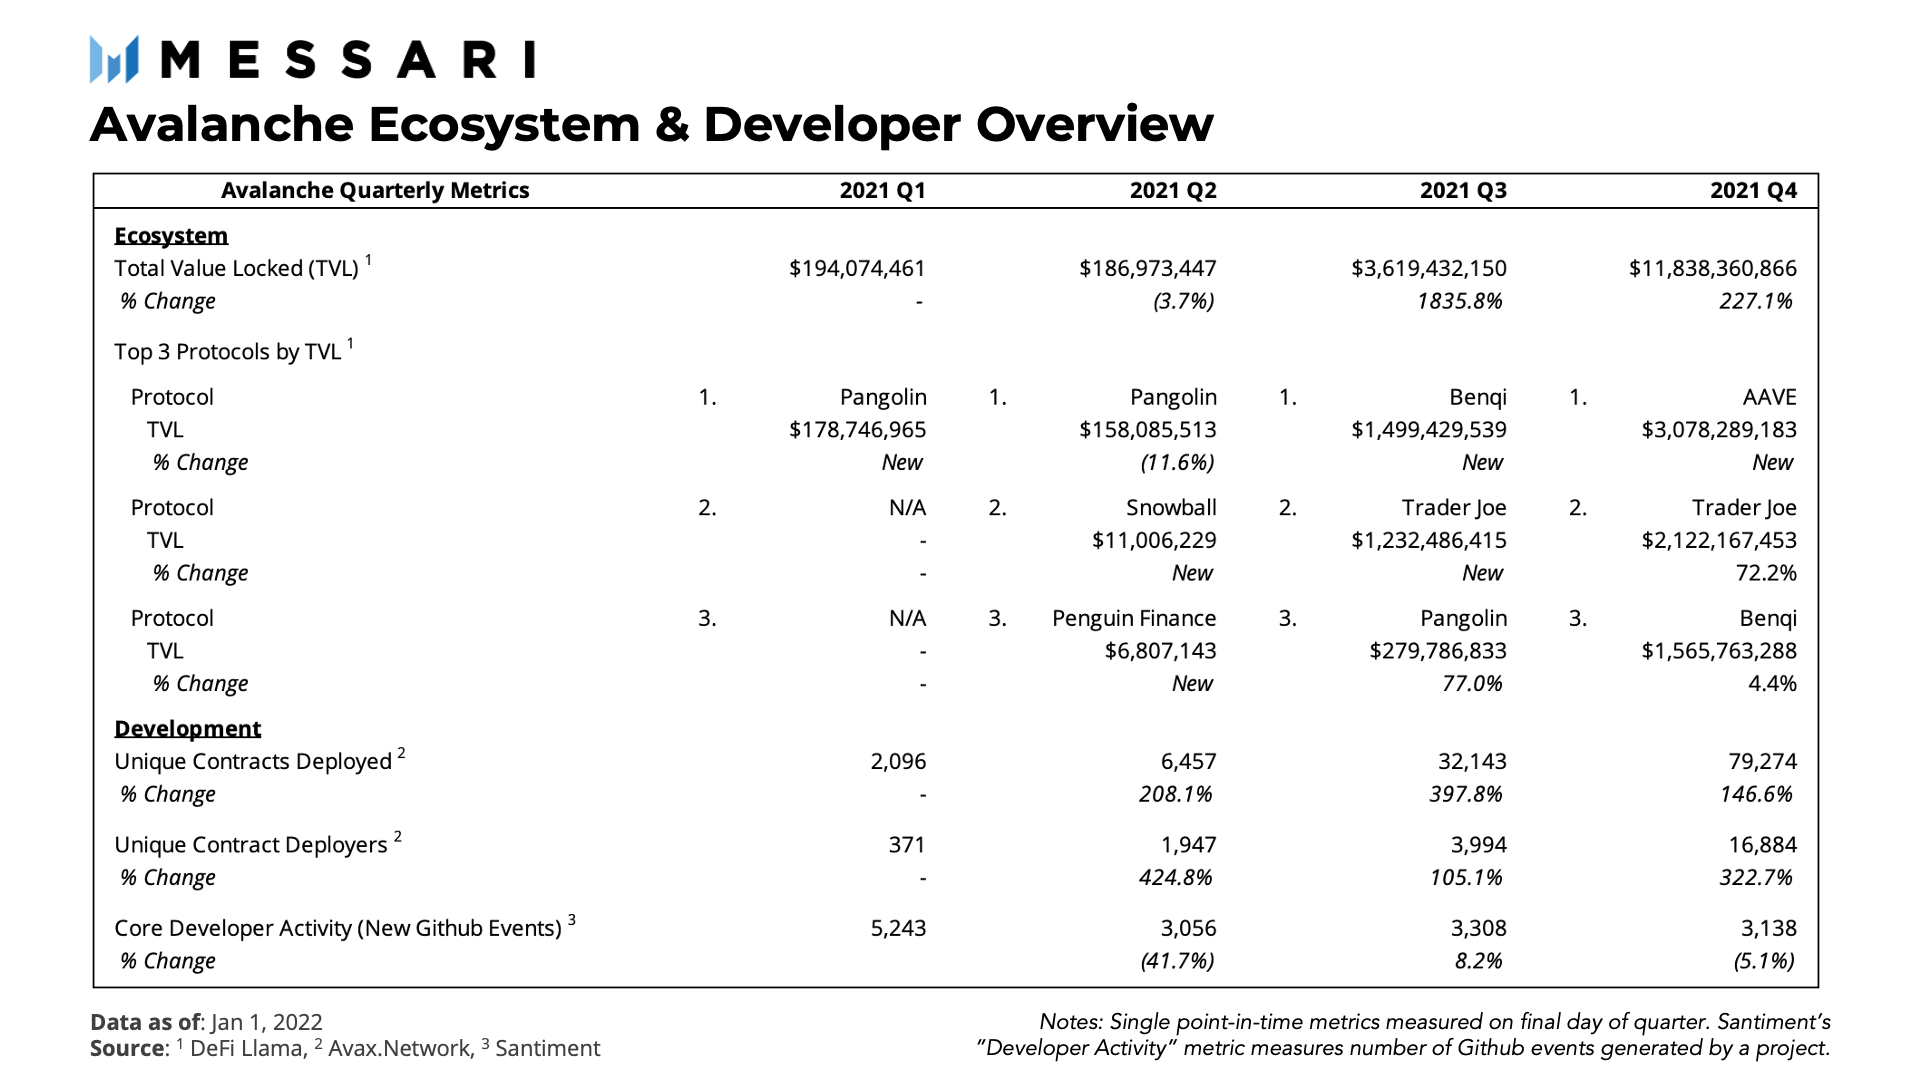
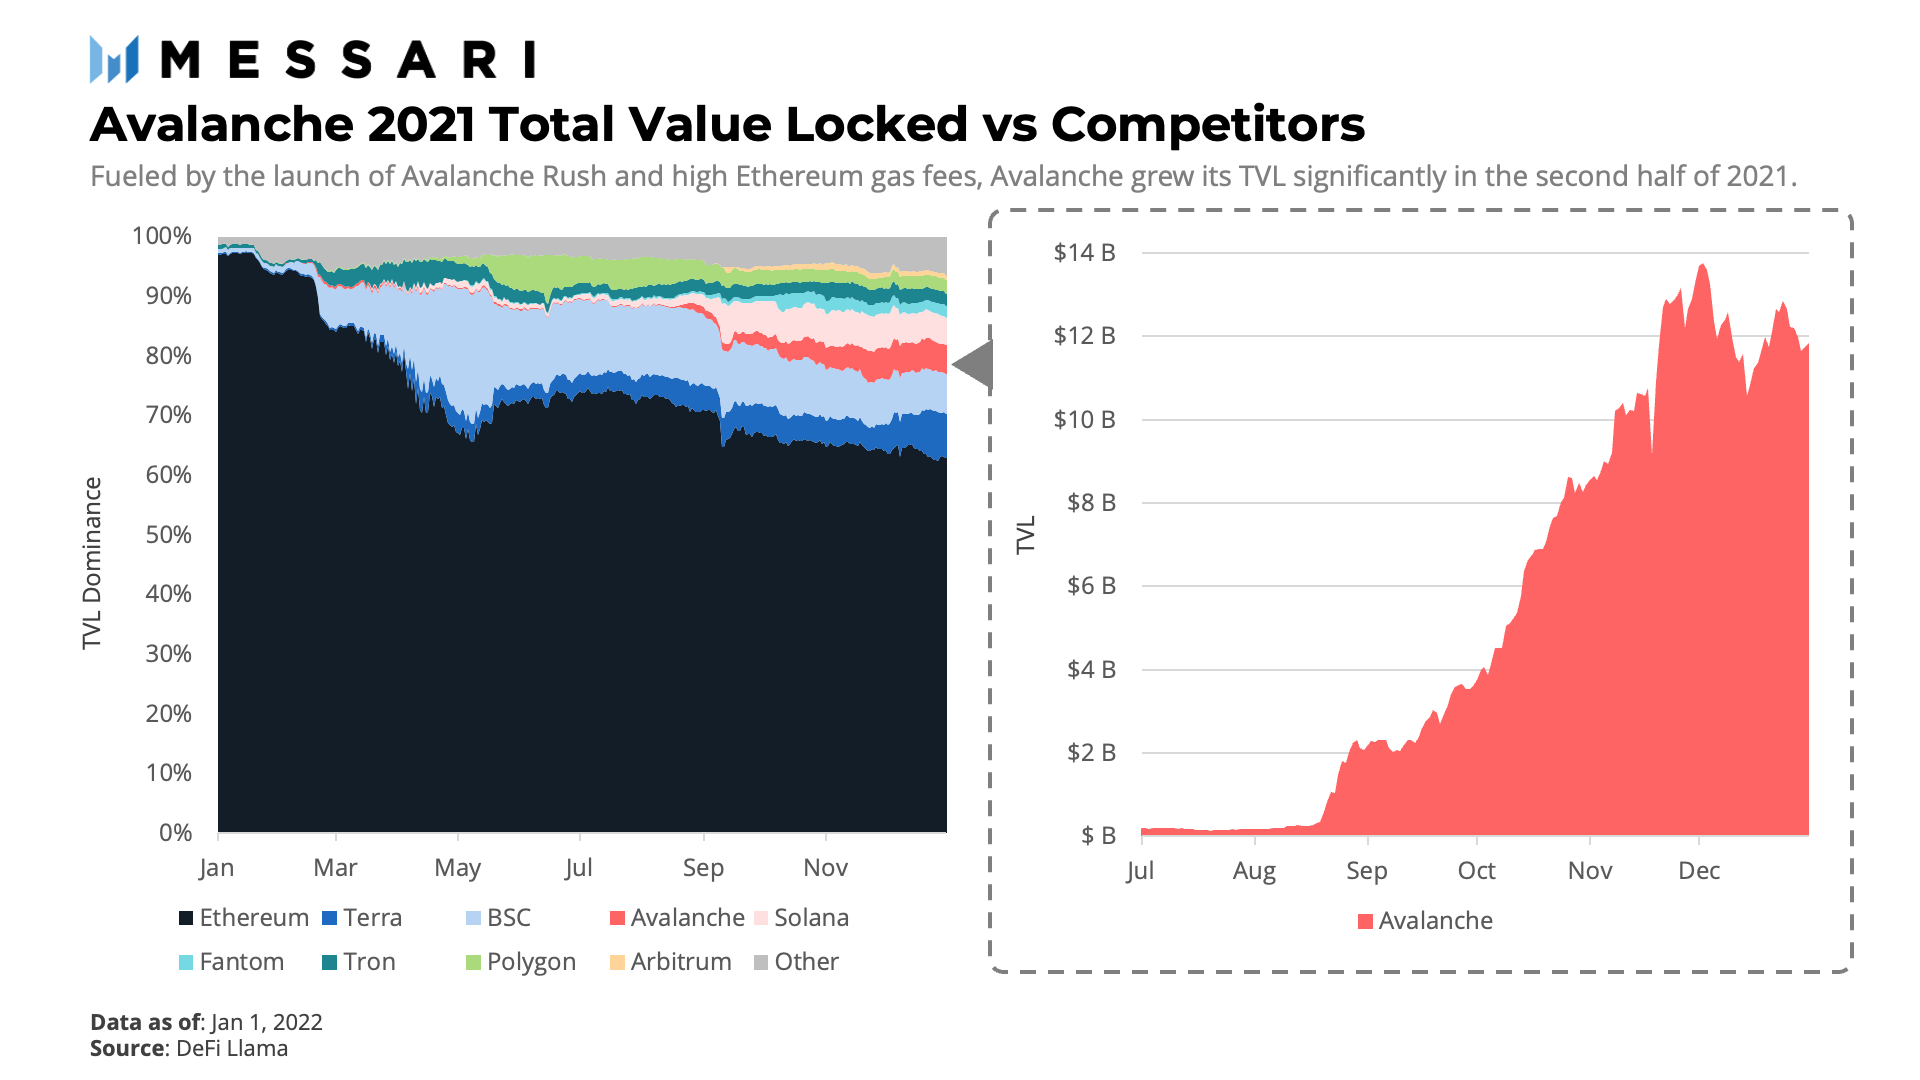
As highlighted in the section above, network usage soared over the final four months of 2021. This can be primarily attributed to the growth of familiar DeFi services on the network (decentralized trading via Pangolin and Trader Joe, borrowing and lending via Benqi) along with the expansion of leading Ethereum protocols (Aave and Curve) into the Avalanche ecosystem. Although the rate of AVAX market cap growth slowed during Q4 to a 56% relative rate, its TVL exploded 714%. While correlation doesn’t imply causation, it appears that users wanted exposure to the Avalanche Rush incentive program that was boosted by the arrival of Aave and Curve in October.
Q4 was an expansionary quarter for the crypto market as a whole with aggregate TVL increasing 40% to $240 billion. Avalanche’s TVL grew at the fastest rate among its competitors within the Layer-1 and Layer-2 network categories (+2.75% TVL dominance). The Terra ecosystem (+2.48% TVL dominance) was a close second. It appears that a significant portion of Avalanche growth came not only at the expense of Ethereum (-4.31% TVL dominance) but also Binance Smart Chain (BSC) (-2.94% TVL change). It makes sense to see Avalanche grow against Ethereum considering the native Avalanche bridge only supports a path between these two networks and has been one of the most widely used solutions to emigrate away from Ethereum in Q4. The growth against BSC is less clear, but we can speculate that it may be related to BSC’s EVM compatibility and similar low-fee environment.
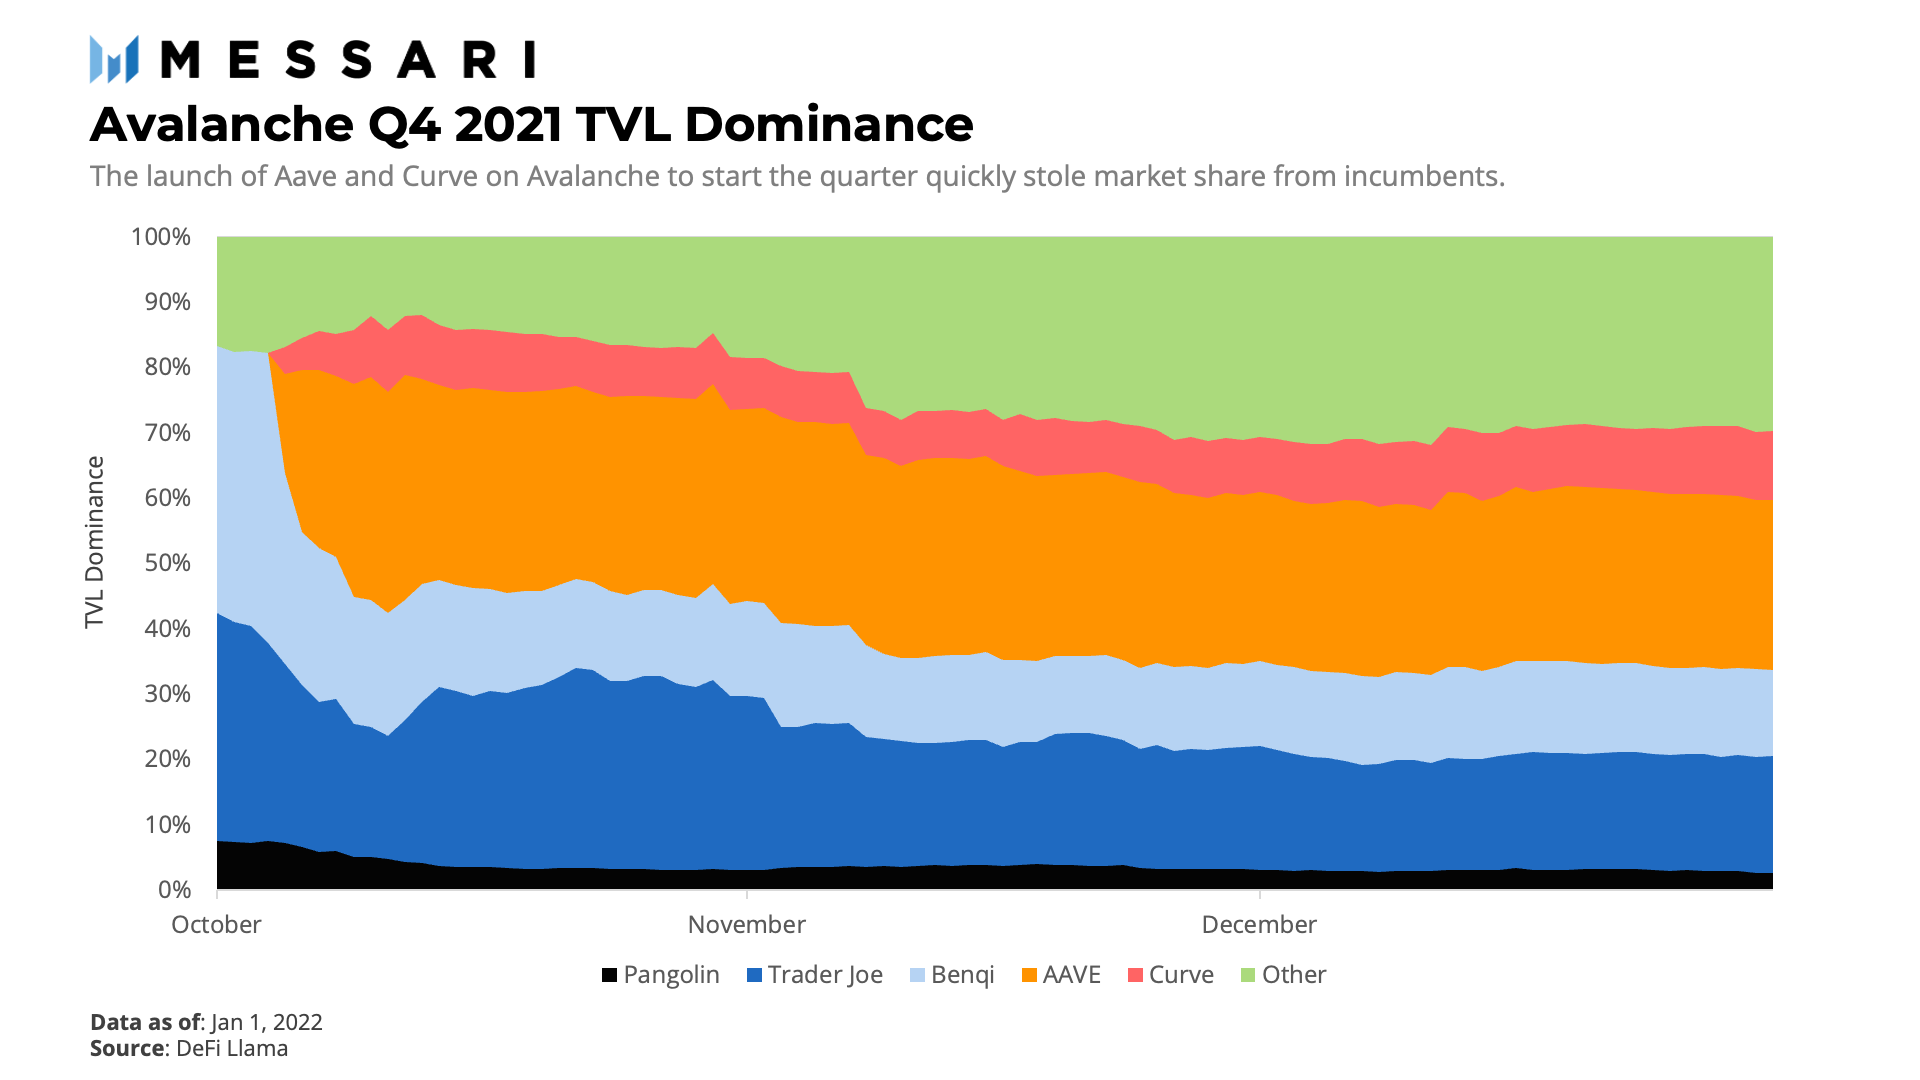
Zooming into the relative TVL share of applications on Avalanche during Q4, we clearly see the effect of Aave and Curve’s arrival on the rest of the Avalanche DeFi ecosystem. Pangolin was already unseated as the market-leading DEX when Trader Joe went live and took over in Q3, but Benqi still sat atop the DeFi throne heading into Q4 with a monopoly in the borrowing and lending markets. Benqi’s moat dried up nearly instantly and Aave, Ethereum’s leading borrowing and lending market, steamrolled the competition thanks in part to its liquidity mining partnership through Avalanche Rush. Aave would finish Q4 as the ecosystem leader with over $3 billion TVL.
The other notable TVL trend across Q4 was the growth of the long tail DeFi protocols on Avalanche. Entering Q4, only 29 protocols had amassed $1 million TVL, but 60 protocols would reach that mark by the end of Q4. This emergence of new players is also supported in the developer metrics for Q4.
Q4 developer activity in the Avalanche ecosystem aligns closely with the network’s overall TVL growth. The number of unique contracts and the number of unique deployers of these contracts grew an order of magnitude during the final quarter of 2021. We can see that a significant spike in contracts deployed in September preceded the growth of Avalanche’s long-tail DeFi TVL growth. It wouldn’t be surprising to see December’s surge in contract deployments contribute to continued adoption of the network’s long-tail protocols in Q1 2022.
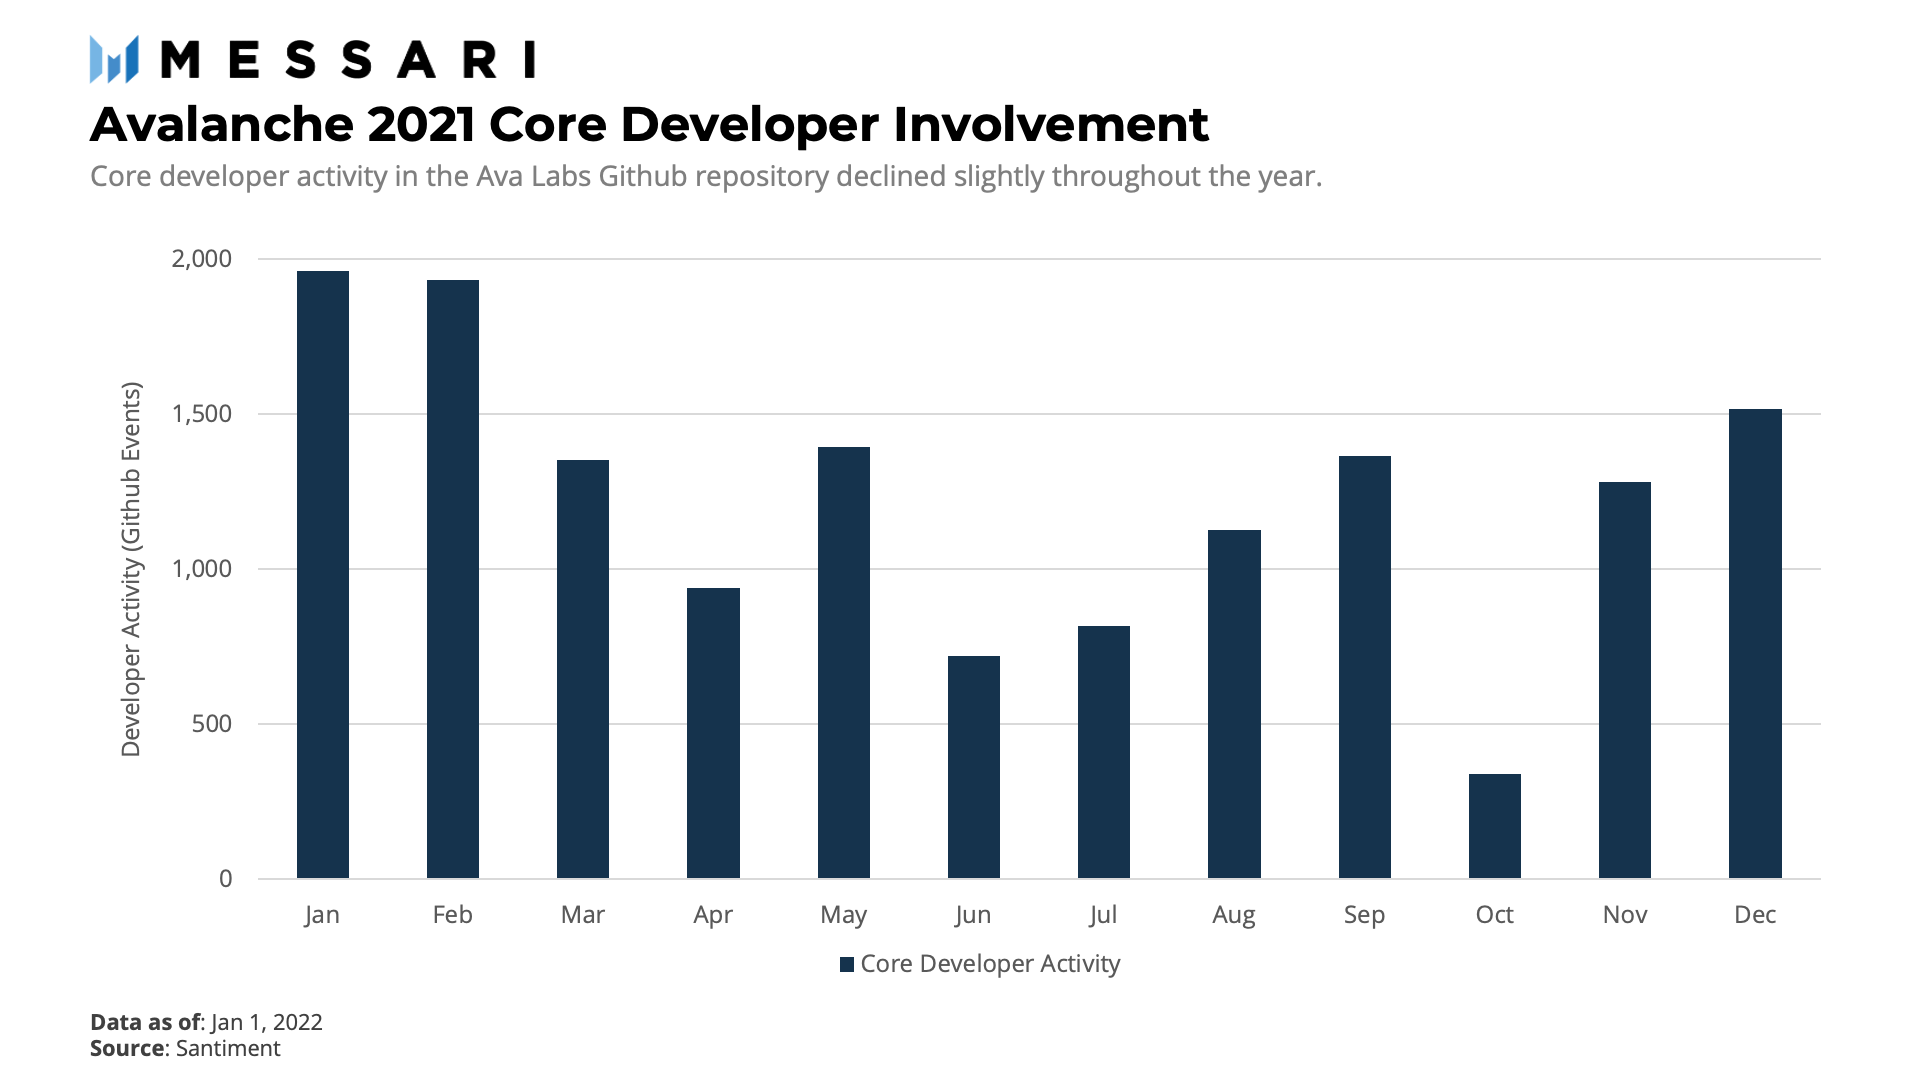
The growth rate of events in the Ava Lab’s Github repository declined slightly throughout 2021. While the rate declined, the number of events still indicates a consistent buildout of the network’s infrastructure from its core team.
Staking and Decentralization
The security of PoS networks requires users to lock up the network’s native tokens and participate in validation duties. A distributed network of validators and active participants can help ensure the network functions as intended.
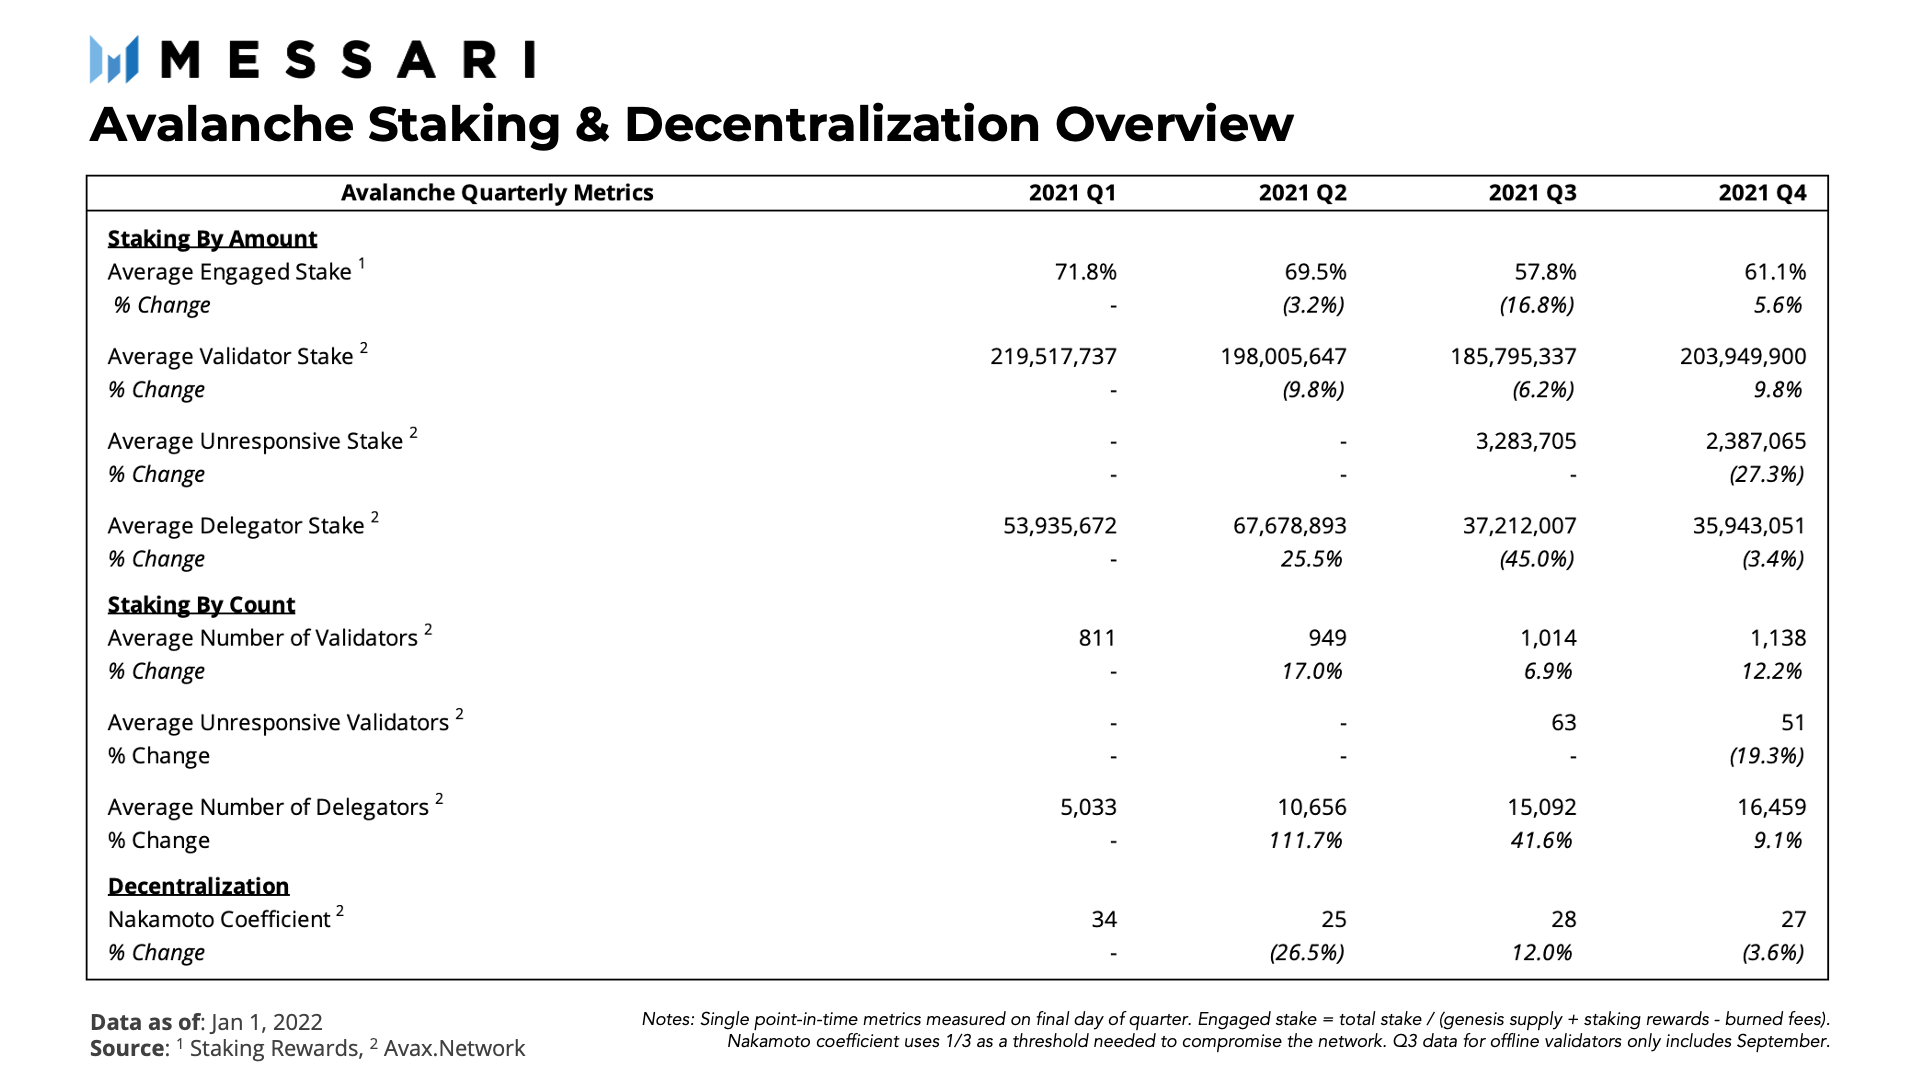
As discussed above, engaged stake trended down throughout the year before finding an equilibrium around 60% at the end of 2021.
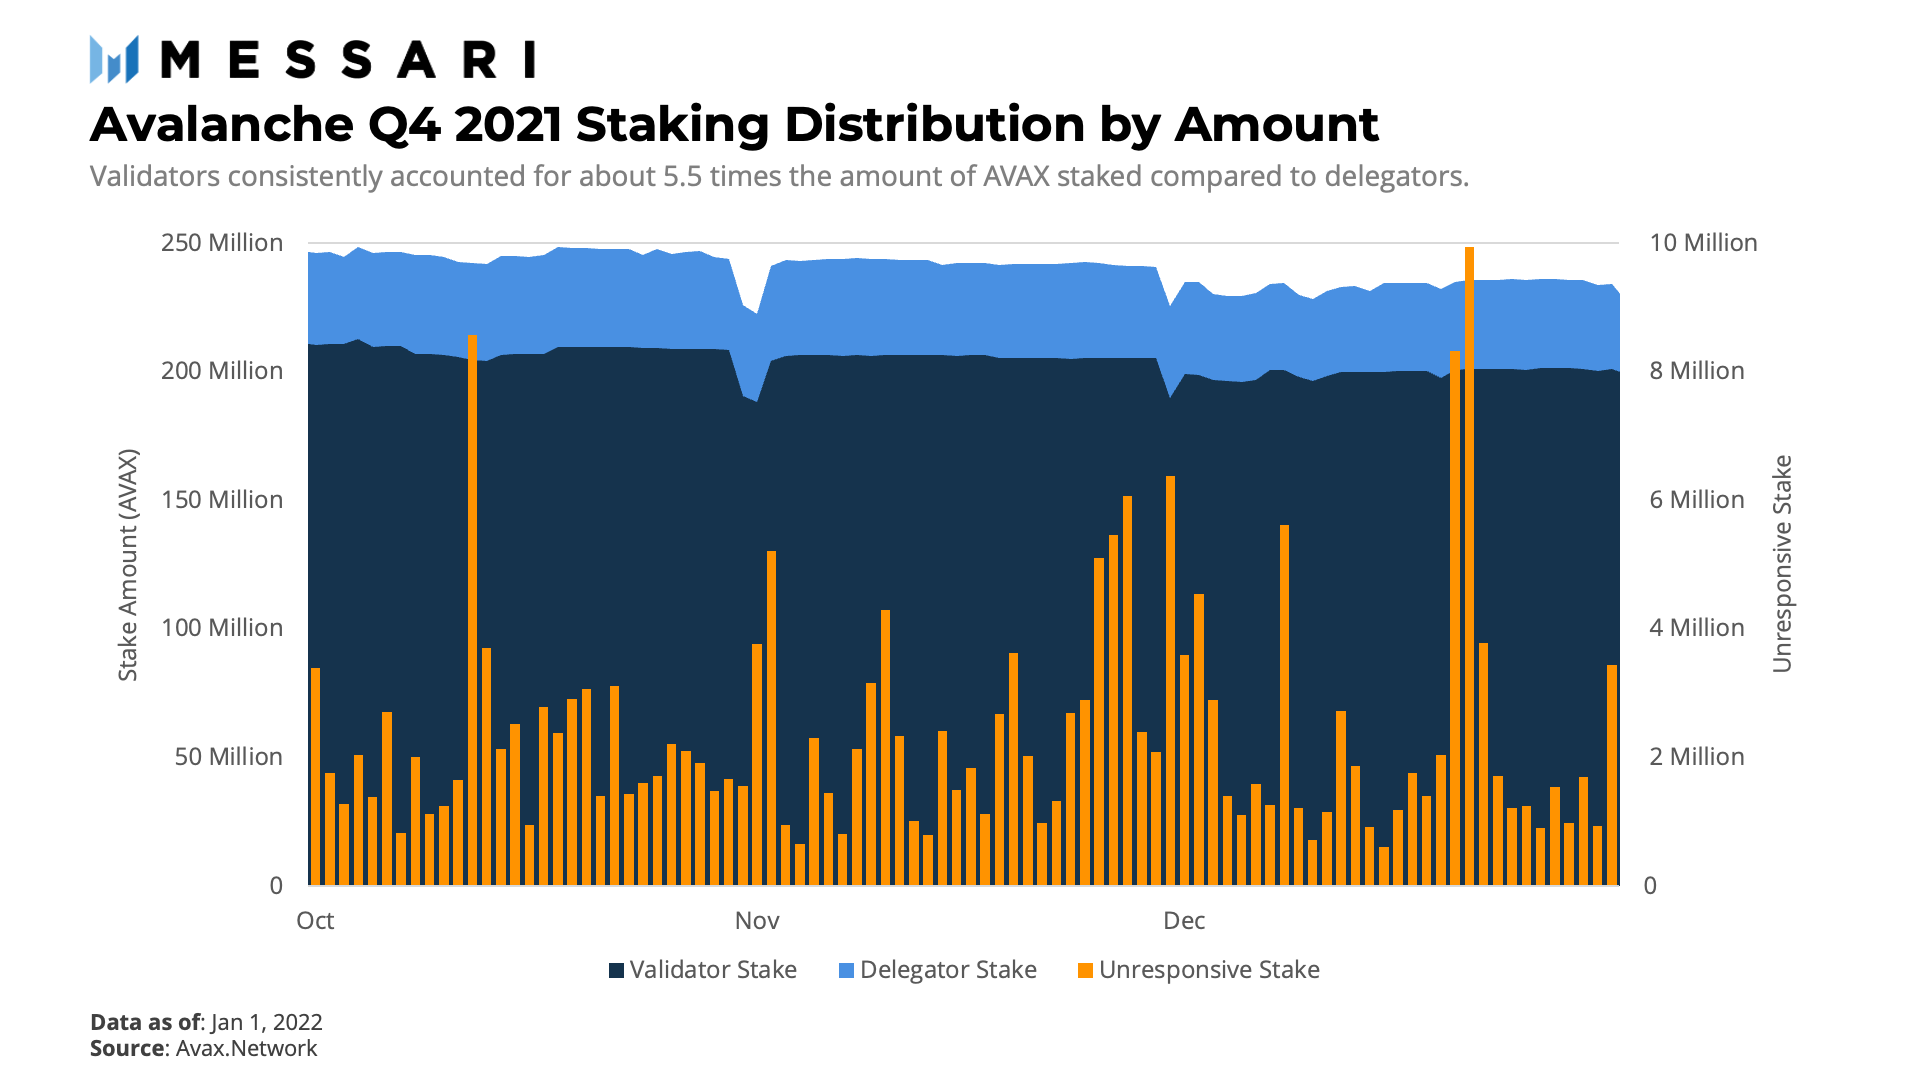
Staking activity during Q4 was rather uneventful. Such predictability and lack of volatility is generally good for network health. Validator stake was consistently about 5.5 times greater than the amount of delegated stake for the quarter. A few days witnessed higher than normal amounts of unresponsive validator stake but the total amount of offline stake never came close to levels that could compromise the network.
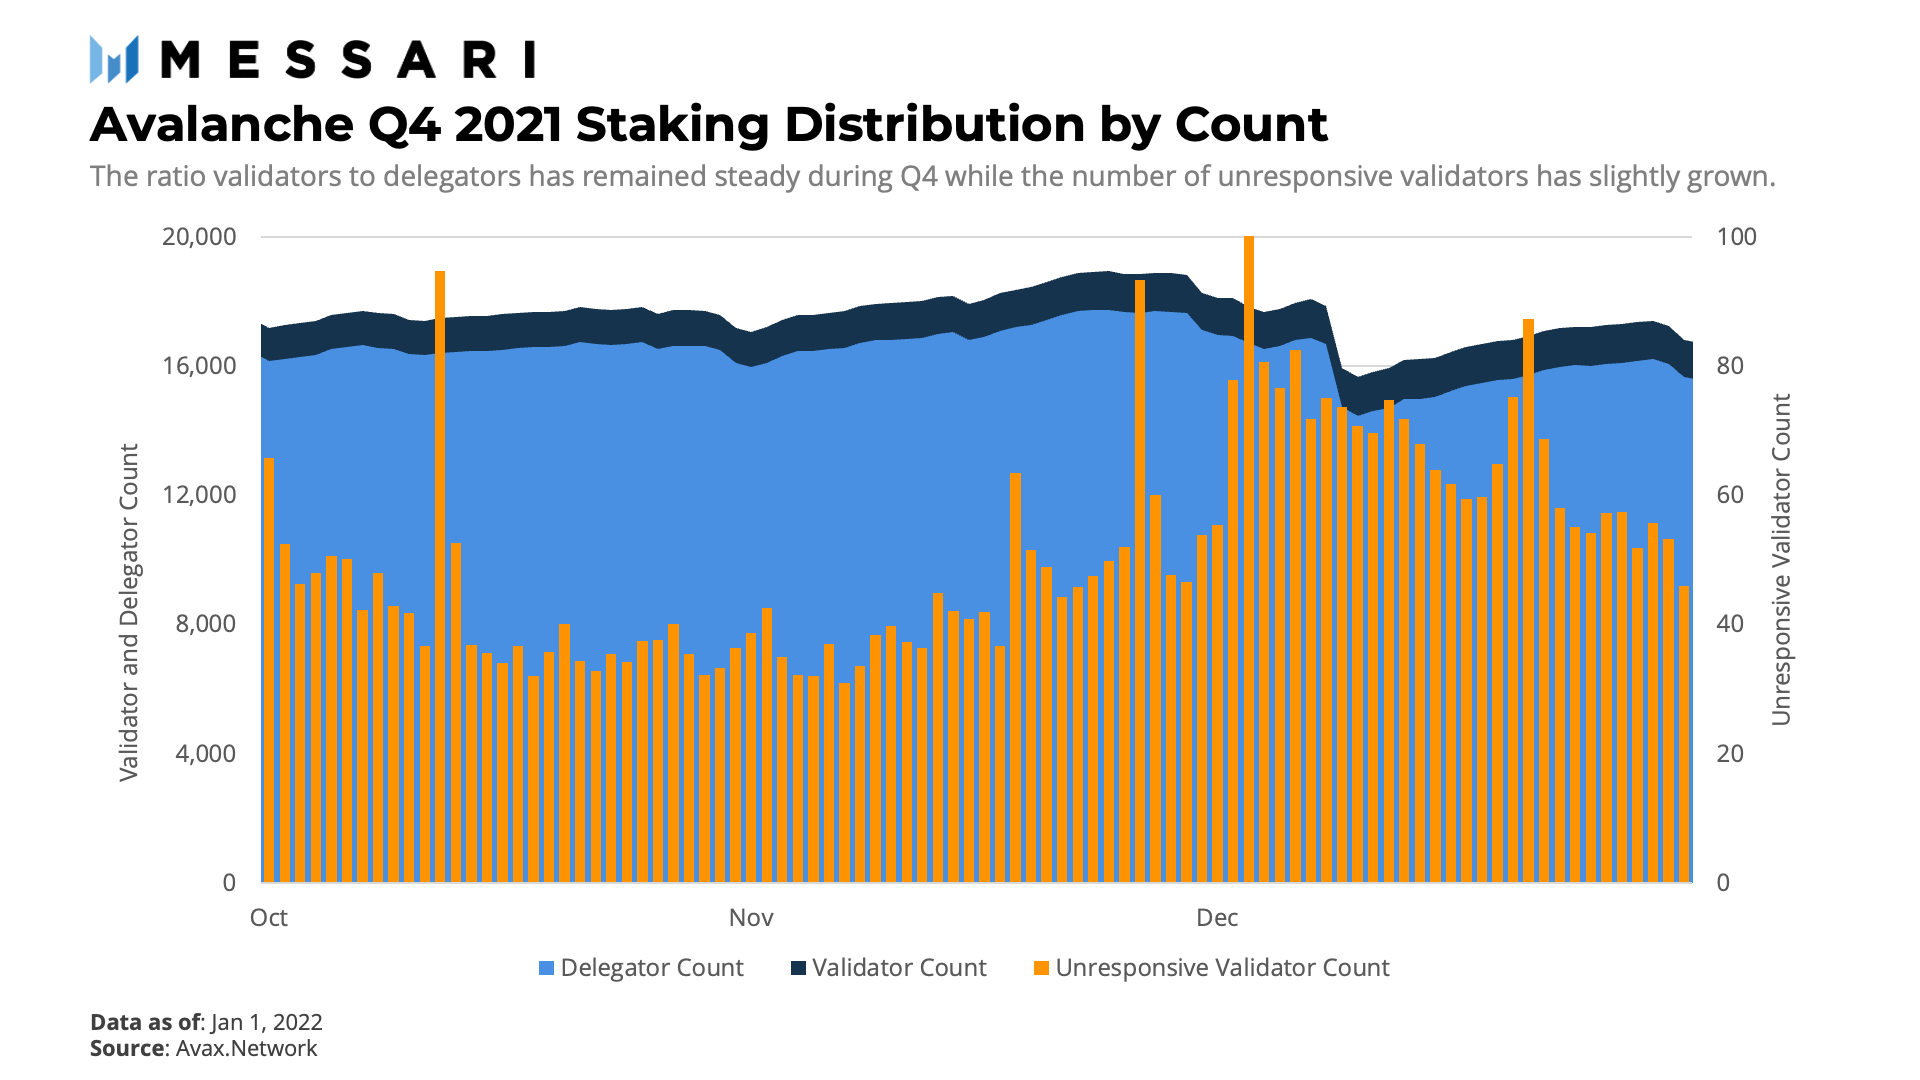
There was a similar lack of events in the staking data by entity. The number of delegators consistently outnumbered the number of validators, a pattern consistent with other PoS networks that support native delegation. The number of offline validators increased slightly during December but returned to its three-month average by the end of the month. Finally, the number of delegators decreased sharply in early December but recovered to close the quarter.
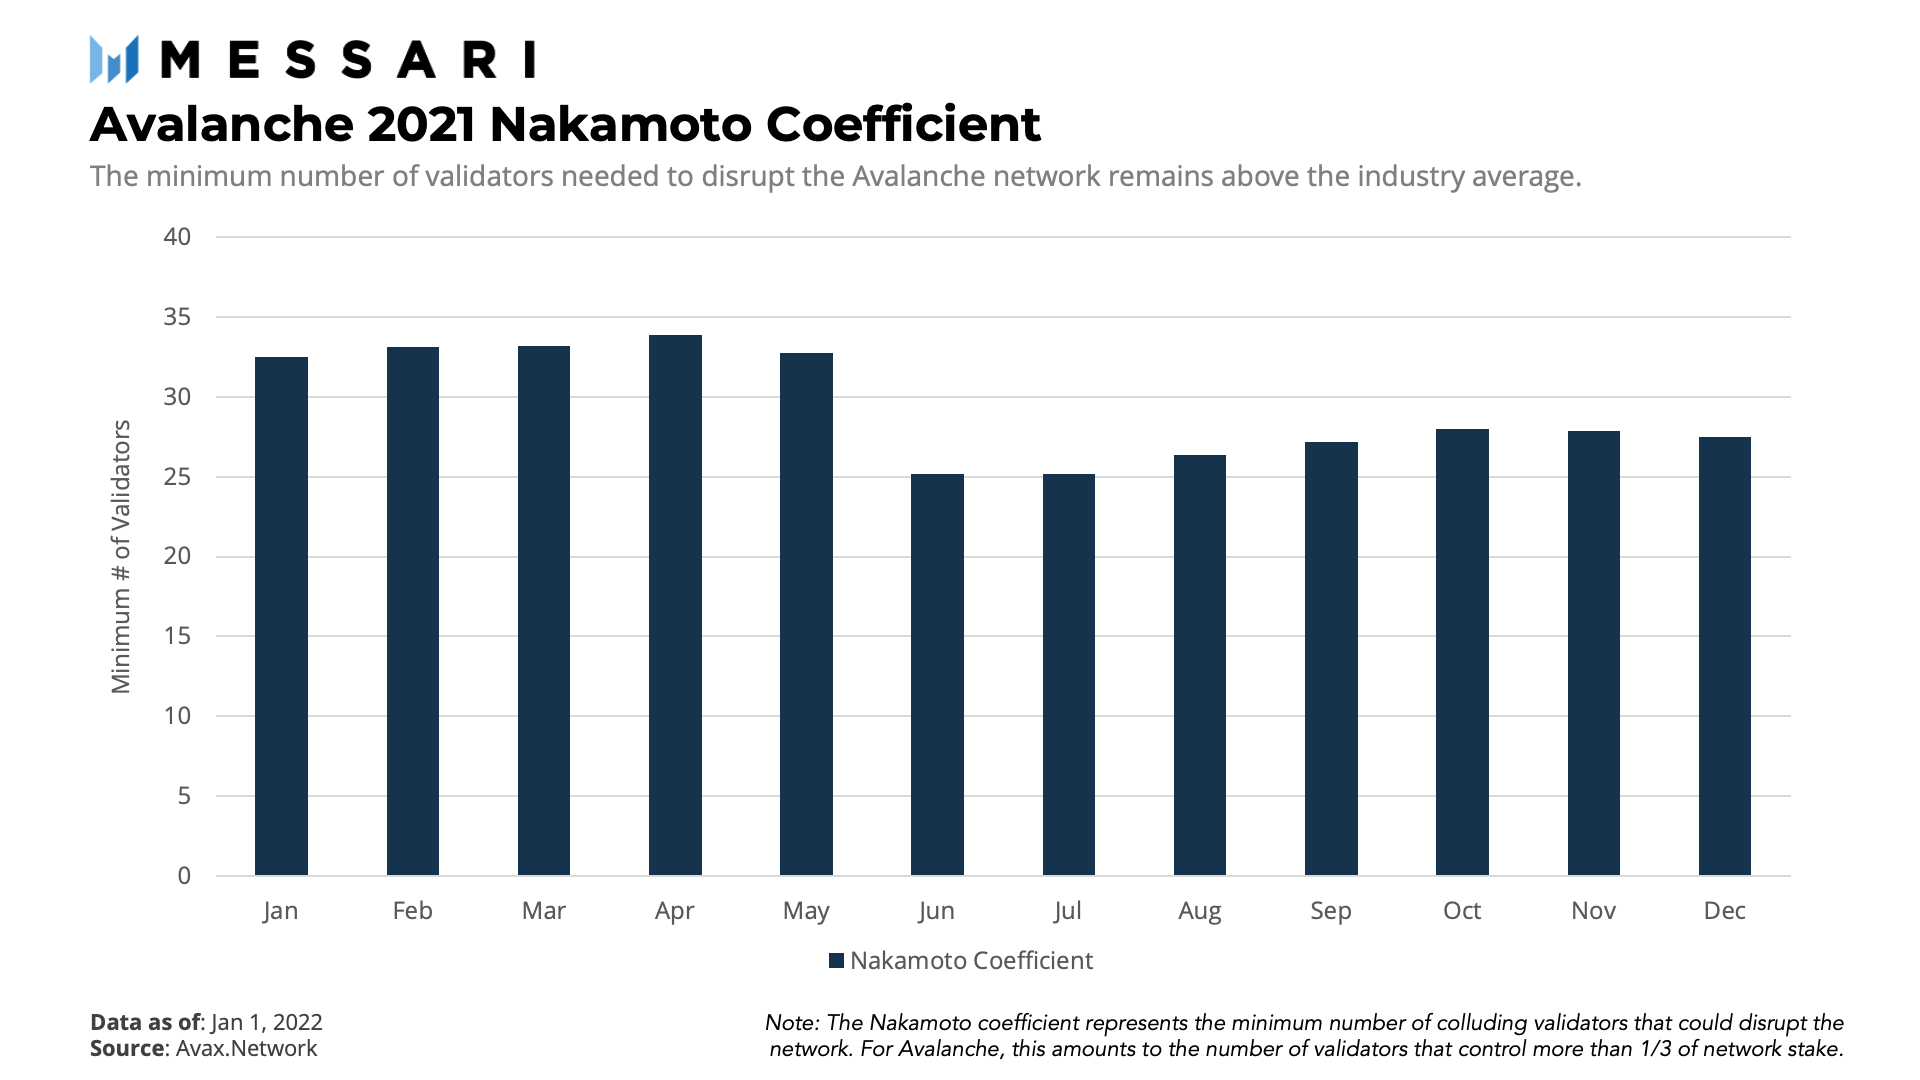
The Nakamoto coefficient is a metric first introduced by Balaji Srinivasan to quantify the decentralization of blockchain networks. The number itself represents the minimum number of actors who can collude to disrupt the network. For Avalanche, the Nakamoto coefficient is equal to the number of validators that control ⅓ of the network’s stake. Avalanche’s Nakamoto coefficient hovered in the low 30s to begin 2021 but fell to 25 in June. Since this decline, the coefficient has remained relatively stable in the upper 20s, putting Avalanche above the industry average for other Layer-1 networks.
Key Events and Catalysts
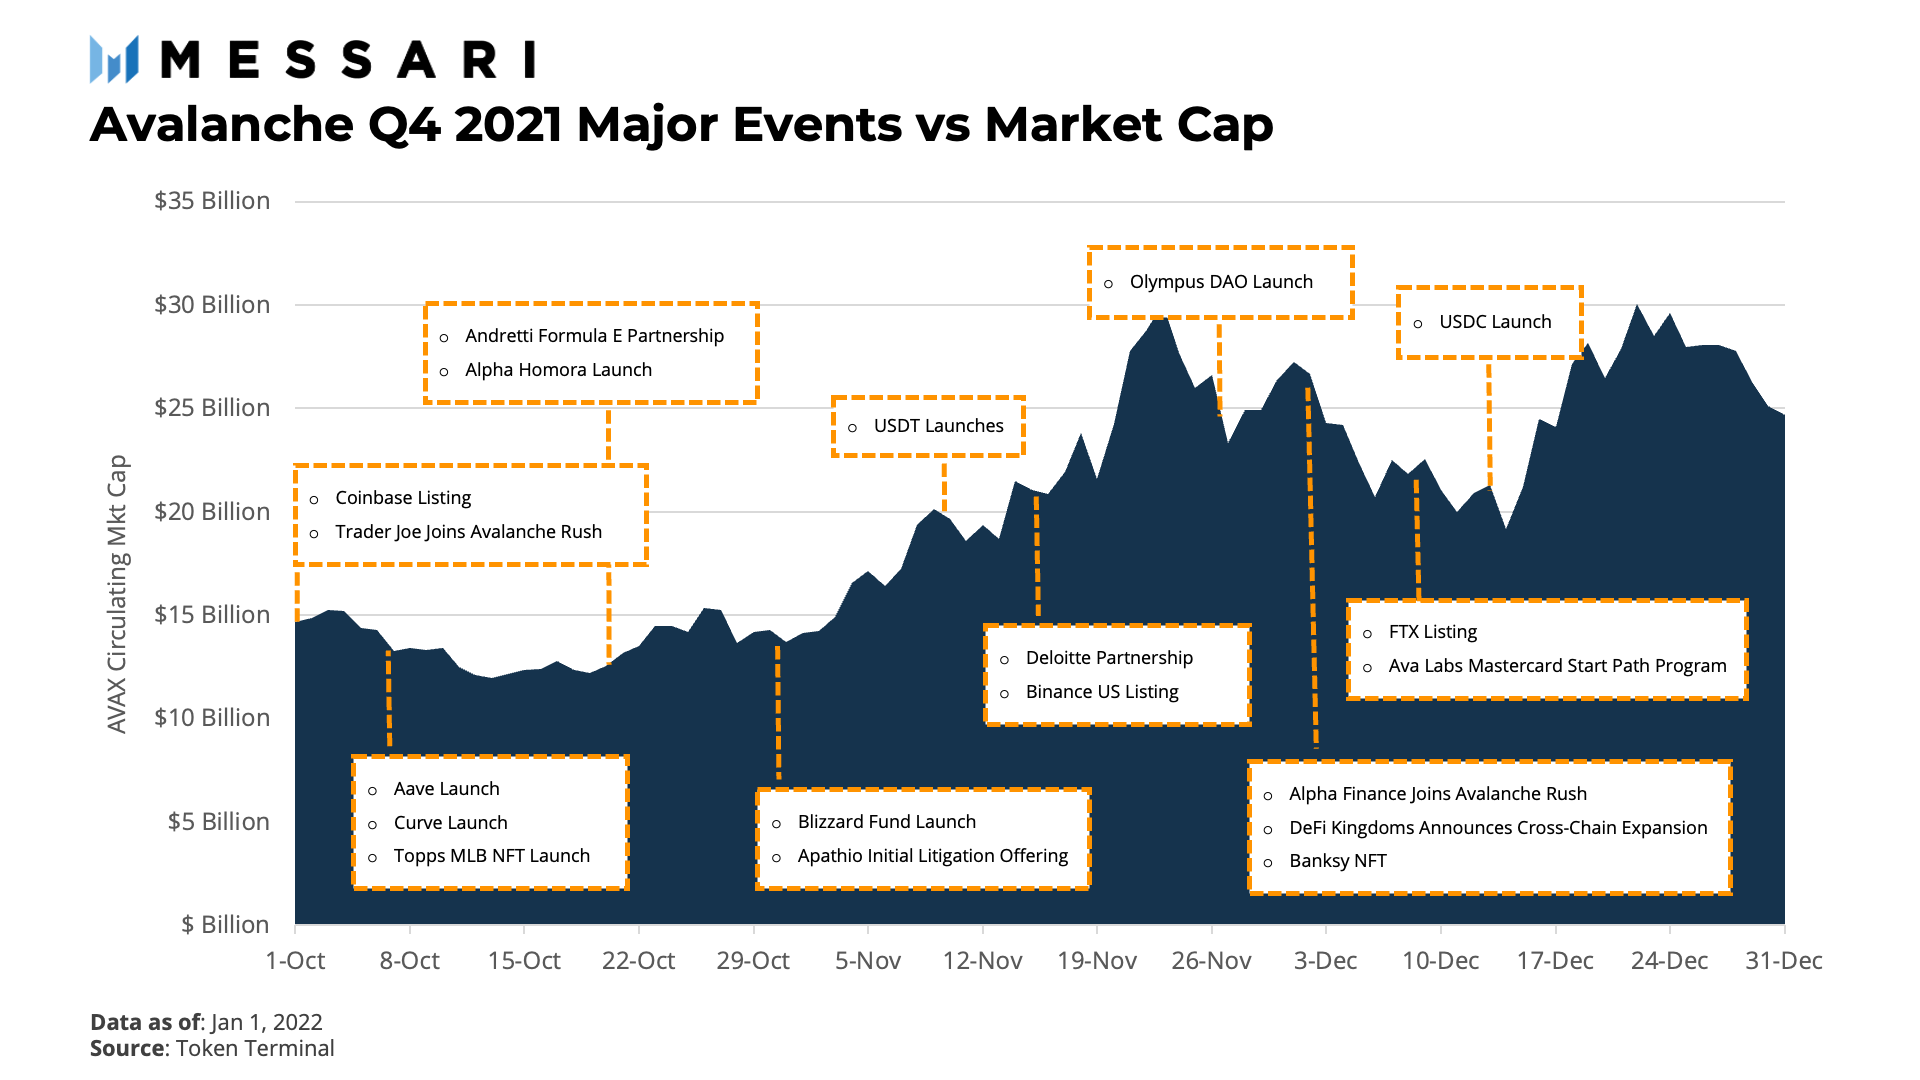
Q4 of 2021 proved to be pivotal for the Avalanche ecosystem. Indeed, a flurry of activity contributed to Avalanche's ecosystem growth, as evidenced by the data presented in the previous sections of this report. But what were the key events and drivers of growth? Outside of the many Initial DEX Offerings (IDOs), DeFi, and NFT launches, the theme of Q4 was primarily centered around major exchange listings, high-profile partnerships, and the continued deployment of the Avalanche Rush liquidity mining program.
October 2021
Avalanche's Q4 began with arguably one of the most sought-after landmarks for any crypto project – the ever-desired Coinbase and Coinbase Pro exchange listings. The listings were announced on September 29th, and by the first day of Q4, AVAX volume was off and running on Coinbase. The Avalanche Rush liquidity mining program expanded its reach in that same week when it added Trader Joe (JOE), the largest native DEX on Avalanche. Announced on September 30th, $20 million of rewards in AVAX and JOE were set to be paid out over the following three months. Furthermore, BenQI (QI), an algorithmic liquidity market protocol, announced on October 4th, phase two of its liquidity mining program, with $4 million in AVAX to be paid out over the following 45 days. Likewise, on October 4th, Aave (AAVE) went live on Avalanche with $20 million in AVAX liquidity mining incentives to be paid out over an unknown period. As highlighted above, these three DeFi protocols ended the quarter as the largest protocols in terms of TVL.
Following an action-packed first week of Q4, Curve (CRV) was deployed to Avalanche bringing its famous like-asset trading to the network. Curve, a participant in the Avalanche Rush incentive program, became the fourth largest DeFi protocol on Avalanche by the end of the year, growing from $175 million in TVL to over $1 billion.
By week three, the attention shifted from exchange listings and the Avalanche Rush program to the NFT marketplace and high-profile partnerships. One of the oldest collectible companies in the US, Topps, launched the 2021 MLB Series 2 Baseball NFT collection. The launch featured a brand-new baseball card-inspired release in conjunction with Major League Baseball and MLB Players, Inc. Further, renowned visual artist Jason M. Peterson launched a 1-of-1 NFT for the collective ownership of his newly created mural of Kanye West in Chicago.
October concluded with another high-profile partnership, additional project launches, and Avalanche Rush participants. On October 20th, a partnership with Andretti Formula E Autosports was announced. The multi-year agreement marked the first title sponsorship from a blockchain company with a Formula E team with a natural alignment between organizations committed to sustainability. On October 21st, Alpha Finance Lab deployed Alpha Homora V2 on Avalanche while Penguin Finance (PeFi) joined Avalanche Rush with $2.5 million in incentives.
November 2021
November was a continuation of October’s blitz of new project launches and partnerships. On November 1st the Avalanche Foundation launched Blizzard, a $200 million fund dedicated to accelerating development, growth, and innovation across the Avalanche ecosystem. The fund came into existence through financial contributions from the Avalanche Foundation, Ava Labs, Polychain Capital, Three Arrows Capital, Dragonfly Capital, and several others. In addition to Blizzard, one of Avalanche's early and much-anticipated use cases, Initial Litigation Offerings (ILOs), became a reality with the launch of the Apothio Initial Litigation Offering, the first tokenized litigation funding for one of the largest US crop destructions in US history.
By the middle of November, the Avalanche ecosystem welcomed the native launch of Tether (USDT), the largest stablecoin by market capitalization, and announced another high-profile partnership with Big Four accounting firm Deloitte. The strategic alliance with Deloitte was formed to enable a new disaster recovery platform that uses Avalanche to help state and local governments easily demonstrate their eligibility for federal emergency funding.
November was capped off with another exchange listing and partnership. On November 17th, Binance.US announced the listing of AVAX and opened trading on AVAX/USD and AVAX/USDT pairs. Two days later, Orange Comet, an NFT and blockchain experience company built on Avalanche, announced its multi-year partnership with the New York Islanders hockey team and UBS Arena to produce and sell NFTs on the Orange Comet Marketplace.
December 2021
Down the final stretch of Q4, the Avalanche ecosystem continued full steam ahead with more project launches, incentives, exchange listings, and partnerships. On December 2nd, DeFi Kingdoms, a popular play-to-earn game built on Harmony, announced their first cross-chain expansion to Avalanche with the launch of a new realm, DeFi Kingdoms: Crystalvale. Near the same time as DeFi Kingdom's expansion, one of 2021's fastest-growing DAOs, Olympus DAO, expanded to Avalanche. Early December also marked when Alpha Finance Lab joined Avalanche Rush with a $6 million allocation, bringing incentives to its ecosystem of cross-chain DeFi products that launched on Avalanche in October. By the end of the first week of December, one of renowned street artist Banksy's most iconic pieces, Love is in the Air, became a fractionalized NFT on Avalanche. The NFT was made possible by Particle, which partnered with Avalanche to bring fine art on-chain in November.
Before Q4 and the broader year came to an end, AVAX was listed on FTX and Kraken, two of the top five exchanges by trading volume. To celebrate FTX integrating AVAX C-Chain, FTX teamed up with the Avalanche team to give away up to $800,000 worth of AVAX. On the same day the FTX listing was announced, Ava Labs was selected for the Mastercard Start Path Program. The program will enable Ava Labs to connect with Mastercard's ecosystem of partners to support innovation. Together, their mission will be exploring and solving how blockchain technology can democratize use cases for all users. Finally, the second-largest stablecoin by market capitalization, USDC, launched on Avalanche to close out December.
Ecosystem Challenges
Q4 represented a major period of growth for Avalanche, but it didn't come without growing pains. As the Avalanche C-chain recorded new highs for daily transactions and witnessed the number of unique developers in its ecosystem double, the network temporarily experienced higher than usual transaction fees. The Avalanche community quickly responded, a unique mechanism around gas caps limiting block space and Metamask struggling to estimate fees due to the mechanism.
The anticipated solutions to scaling include governance, pruning, and subnet development, which will involve removing the gas limit mechanism, among other optimizations. The higher fees may have been a signal that the network wasn’t quite ready for the growth it experienced over Q4; however, the proposed solutions are top of mind as the Avalanche team and community look ahead into 2022.
The Road Ahead
Currently, Avalanche does not maintain an updated public-facing roadmap, so the protocol developments are not prescribed. However, it is expected that Avalanche Rush will continue to accumulate participants as the $180 million liquidity mining program has not been exhausted.
It is also anticipated that core platform upgrades will continue. Significant upgrades, known as Apricot, are being implemented in phases, in which phase five of six was implemented successfully during Q4. As part of phase five, several patches were implemented aimed at P<>C chain atomic transfers and C-chain fee algorithm optimizations. All phases of Apricot broadly represent one of the solutions (pruning) to the high transaction fees experienced during Q4.
Another area of focus is expected to be the development of subnets. Avalanche will continue to pursue developing flexible and customizable subnets with the aim of enabling individuals and institutions to create custom blockchains tailored to their needs and go to market more efficiently. A major milestone was reached in December with the launch of Subnet-Ethereum Virtual Machine (EVM), which is a custom VM that enables users to create their own EVM-compatible blockchain. Ultimately, further development in this area is expected and, if successful, could serve as another catalyst for further ecosystem growth.
Avalanche on-chain governance is also still in development. AVAX will at some point be used to provide on-chain governance for critical network parameters where participants can vote on changes to the network and settle network upgrade decisions democratically. Parameters will include factors such as the minimum staking amount, minting rate, and transaction fees.
While Avalanche Rush may continue to serve as a catalyst for ecosystem growth and garner more project launches and partnerships, significant technological advancements are on the horizon for the teams developing the Avalanche core platform and are critical to the network's ability to sustain further growth.
Closing Summary
Intuitively, due to congestion on the Ethereum network and the slow rollout of Layer-2 scaling solutions, newer Layer-1 platforms offered better support for marginal users. With the combination of the Ethereum-Avalanche bridge and Avalanche Rush, Avalanche found itself in a position to grow its user base and welcome new participants into its economy. As individuals and institutions piled in, Avalanche recorded all-time quarterly highs of active addresses, transactions, TVL, and market capitalization.
The arrival of high-profile partnerships and project launches like Aave and Curve triggered network-wide DeFi growth and the number of contracts deployed. Unique contract deployers to the network also reached all-time highs during the quarter.
Although Q4 of 2021 proved to be pivotal for the Avalanche ecosystem, it also surfaced intermittent scaling issues as evidenced by temporarily increased transaction fees. This issue is not unfamiliar, and solutions are in motion and at the forefront for the teams developing the core platform. Tracking the growth of the network and its progress towards core platform optimization will be top of mind looking ahead into 2022.
This report was commissioned by Ava Labs, a member of Messari Hub. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. Paid membership in the Hub does not influence editorial decision or content. Author(s) may hold cryptocurrencies named in this report.
Crypto projects can commission independent research through Messari Hub. For more details or to join the program, contact hub@messari.io
This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research, and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our terms of use for more information.
This report was commissioned by Ava Labs. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
James was a Research Analyst at Messari, focusing on Layer-1 protocols, with prior experience in traditional finance at Northwestern Mutual and U.S. Bank.
James was a Research Analyst at Messari, focusing on Layer-1 protocols, with prior experience in traditional finance at Northwestern Mutual and U.S. Bank.