Solana October 2025 Update

Institutional Flows: DATCOs and ETFs
The pace of purchases from Solana DATCOs slowed considerably, with 1.92 million SOL ($359 million) purchased in October vs. 9.84 million SOL ($1.8 billion) in September. As we noted back in August, the ability of these DATCOs to conduct purchases beyond their initial raise figures would depend on market NAV (mNAV) premium.
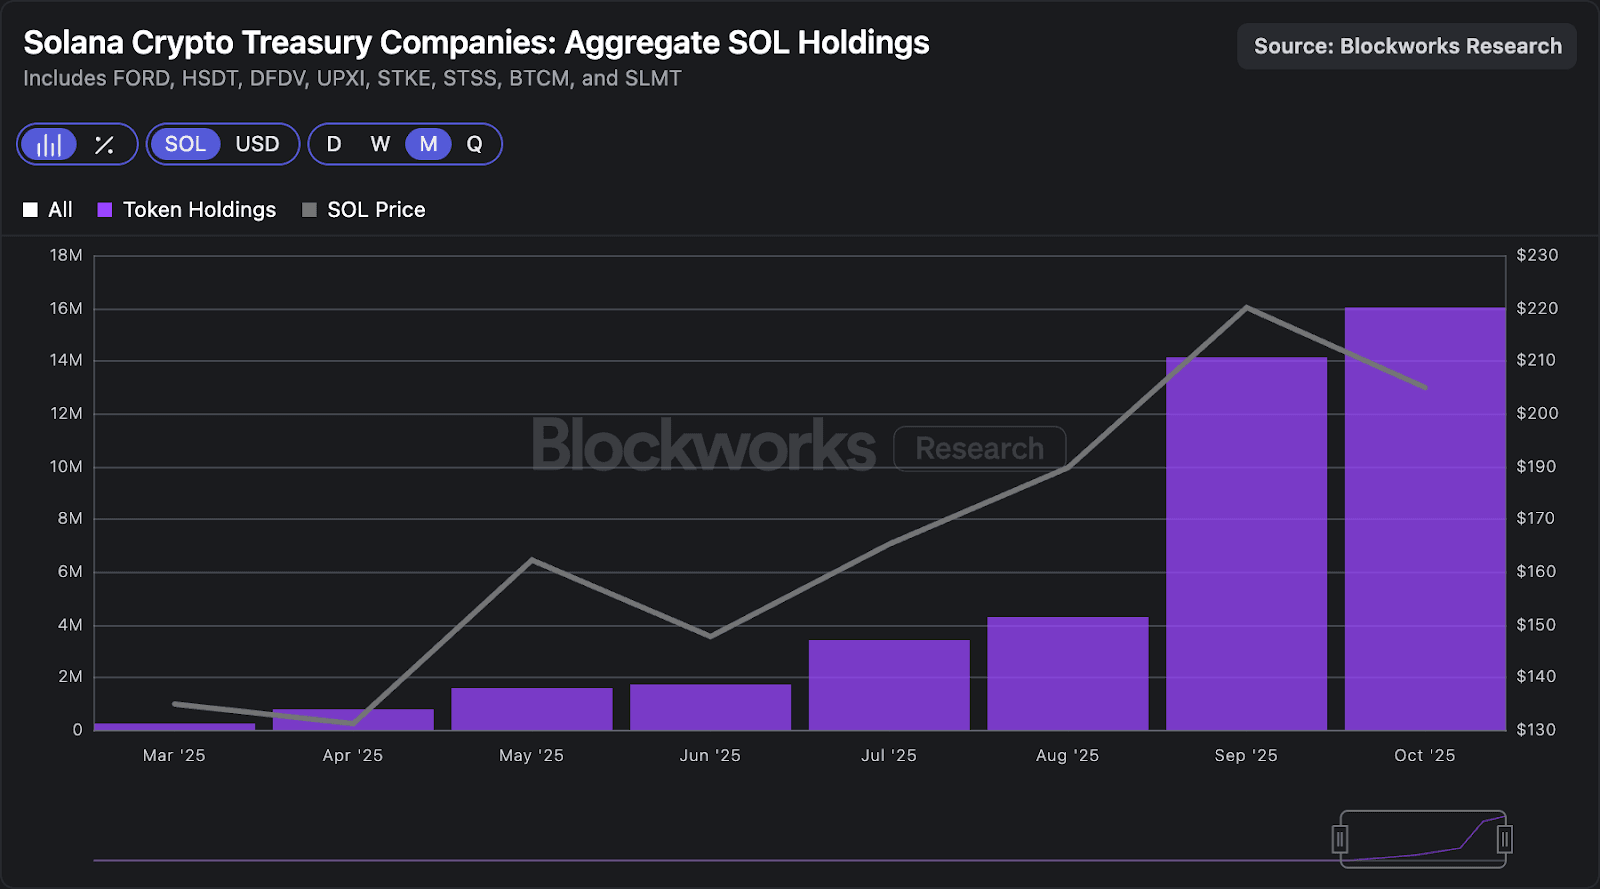
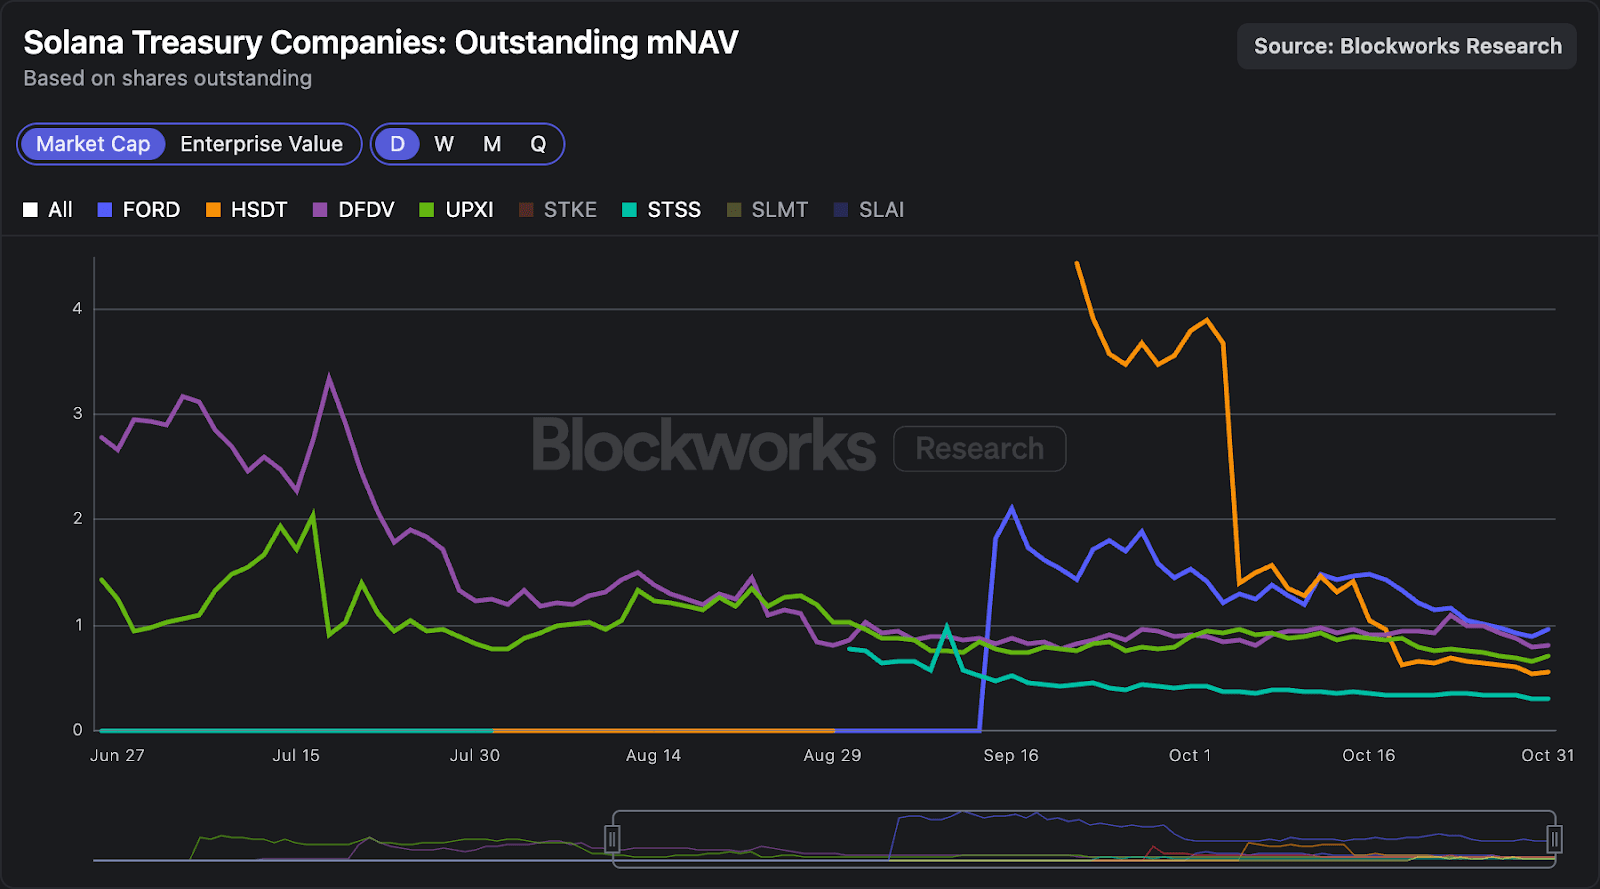
The chart below shows that the five largest SOL DATCOs are all trading at a discount to outstanding mNAV as of October 31st, significantly tightening their financing conditions. FORD, the largest SOL DATCO with 6.28 million in token holdings ($1.28 billion), is trading at a slight discount to mNAV (0.96x). However, peers are trading at mNAV ratios between 0.3x and 0.8x, introducing the risk that some of these DATCOs pursue a similar strategy to the one employed by ETHZilla, which sold approximately $40 million of its ETH treasury holdings to repurchase shares until its discount to mNAV is normalized.
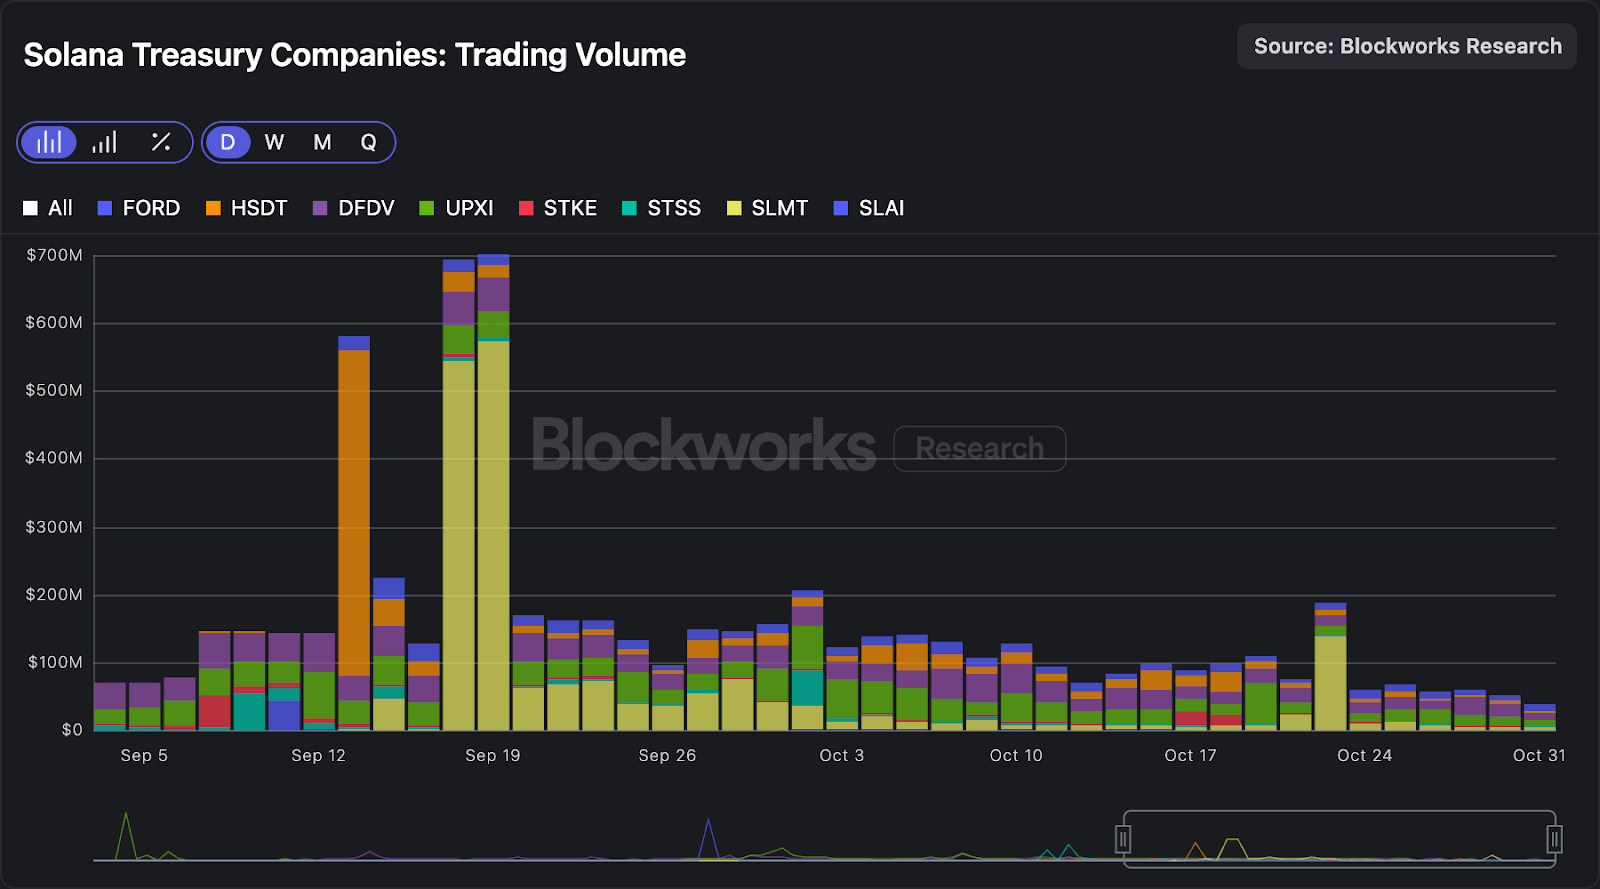
As a final note on this front, Solana DATCOs have also struggled with limited secondary market activity, with trading volumes declining sharply since mid-September. This dynamic has direct implications for capital-raising capacity. DATCOs have relied heavily on at-the-market (ATM) equity offerings to fund the accumulation of cryptoassets. However, this strategy becomes increasingly constrained when trading volumes are thin.

Carlos leads coverage on Solana and spends his time on DeFi applications. Previously held a research role at 21Shares.