Solana May 2026 Update

Institutional Flows: ETFs and DATCOs
SOL ETP inflows total $110.6M in May, accelerating sharply from $17.8M in April. April’s ETP inflows were by far the lowest since SOL ETFs were approved in the US by the SEC in July 2025. The sharp inflow bounce from this local bottom may signal renewed appetite by institutions for Solana exposure. By contrast, Solana DATCO holdings were largely unchanged for an eighth consecutive month, constrained by limited secondary liquidity and persistent mNAV discounts. DATCOs trimmed about 150k SOL tokens from April to May.
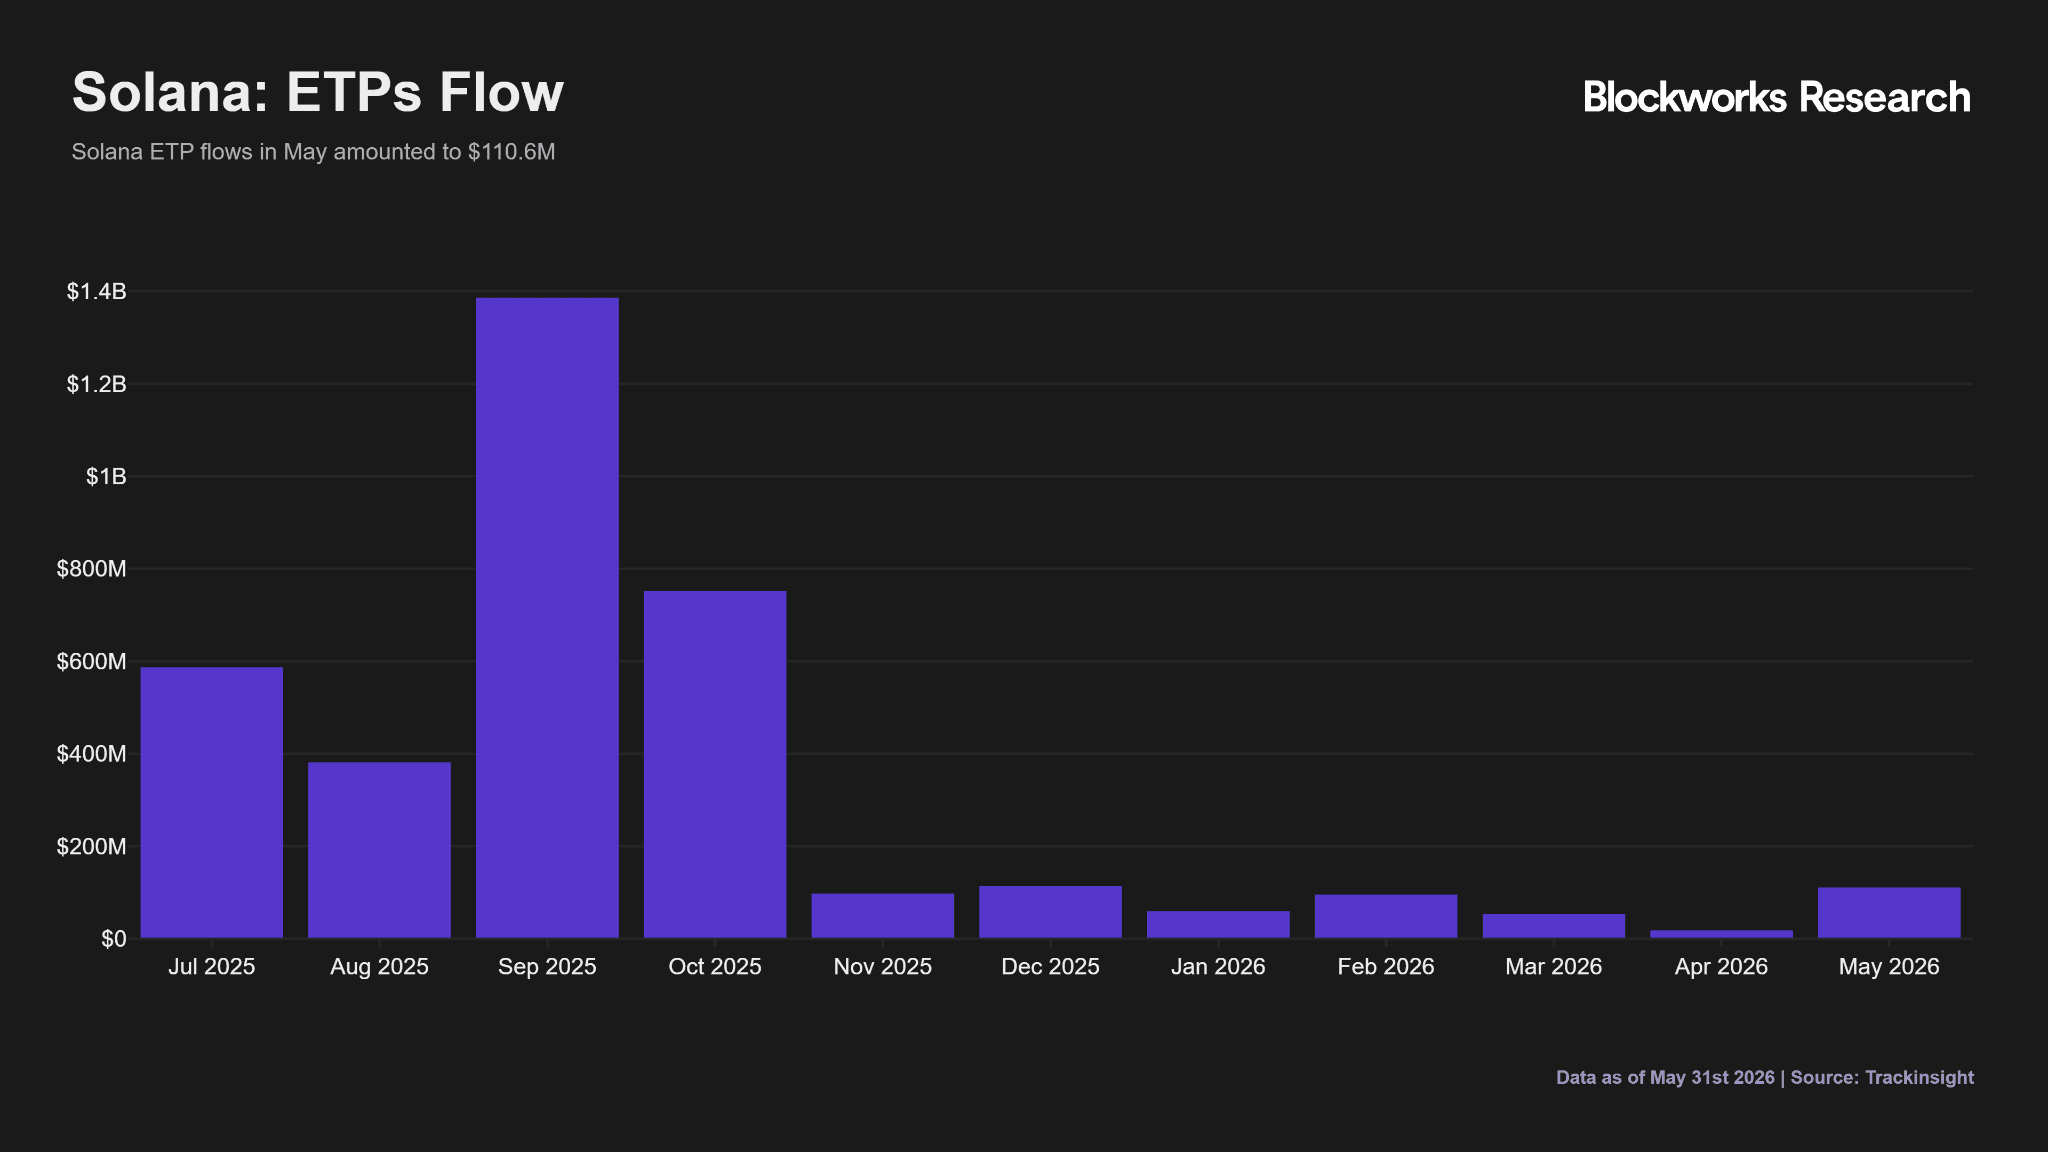
On a market cap adjusted basis, May SOL ETP inflows amounted to 0.25% of SOL’s market cap. Following a market cap adjusted inflow of 0.05% in April, May inflows represent a meaningful reversion, far above the usual 0.12% market cap adjusted inflow.
Network Health
SOL Inflation Discussions Reignite
SIMD 547, proposed by Temporal’s Cavey, has revived the SOL value accrual discussion by targeting the burn side of net emissions. SIMD 547 introduces a fully burned, resource-based fee charged on CU requests. Following SIMD 96, which redirected all priority fees to block producers, all meaningful sources of SOL burn have disappeared.
