Shifting Attention: Base and Hyperliquid

Firstly, this is not a short or underweight Solana piece. In contrast, we believe that Solana’s DEX volumes likely continue to dominate, given the ease of transactions, its monolithic nature and UX, and its strong fundamentals. Similarly, there may continue to be winners on the chain, specifically for DeFi products, such as Jupiter, Jito and others. The chain continues to dominate the market, volumes and fees, and has an easy onboarding process. It’s likely that teams will continue to launch their tokens primarily on Solana, as exhibited recently by Pudgy Penguin’s decision to launch their native token, PENGU, on Solana, as opposed to Abstract chain.
Instead, we believe that other networks and L1s may take market share away from Solana, and that it may make more sense to focus on the protocols and tokens of those networks. More specifically, we believe that it makes sense to focus on the ecosystems of Base and Hyperliquid, as well as Monad, Abstract and MegaETH.
Base
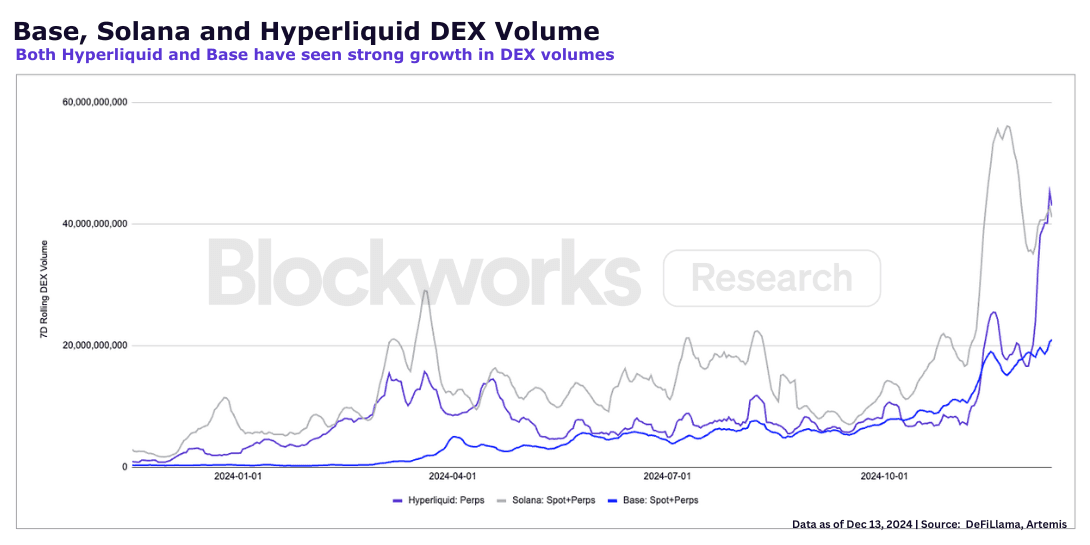
Base is currently the only L2 that can be credibly said to be competing with Solana and with Ethereum. The Base team’s decision to continuously optimize the chain by increasing gas targets gradually (with the latest gas target being 18 Mgas/s with 2-second block times, enabling 36M gas per block), is distinctly different from the strategy employed by L2 competitors such as Arbitrum and Optimism, who have instead chosen to scale horizontally.
Base also boasts strong distribution through its relation to Coinbase, and has clearly commanded a lot of attention from both users and developers. Base saw $46B in DEX volumes in November, while Arbitrum had $34B and OP Mainnet had only $5B. Users have also consistently been paying more fees on Base compared to other L2s since March of 2024. In November, Base saw $10.7M in fee revenues, while Arbitrum had only $1.6M and OP Mainnet had only $766.5K. It’s clear that Base is currently at the center of the Ethereum ecosystem, and its distribution advantage and deepening liquidity likely accelerate the gravitational pull of ETH-based capital from competing ecosystems.
We’ve also seen more experimentation from teams on Base than any other L2. While Arbitrum, OP Mainnet and Ethereum all saw limited AI Agent activity, Base had Virtuals, Spec and others. Native Base DeFi protocols have also been performing well, with Aerodrome and Moonwell leading the way.

Boccaccio leads coverage on gaming, consumer apps, alt-L1s and modular ecosystems.