Many market participants still view Ronin as synonymous with the rise and fall of Axie Infinity, causing them to overlook its accelerating growth.
As Web3 gaming fundamentals strengthen, Ronin is positioning itself in three key areas with high growth potential.
With a vertically integrated ecosystem that generates revenue across every layer, Ronin can continuously fund a multi-pronged developer acquisition strategy to attract and retain top talent.
Ronin’s recent all-time high in daily active users (“DAUs”) and growing share of total gaming DAUs suggest its current growth trajectory could position it as the sector leader in Web3 gaming.
Introduction
In 2021, Ronin’s flagship game, Axie Infinity, propelled Web3 gaming into the global spotlight, growing from ~3,000 daily active users in early May to a peak of ~750,000 in November, while its marketplace continously generated tens of millions of dollars in daily trading volume. By August 2021, the game garnered so much interest in the Philippines that it prompted a public statement from the Philippine Department of Finance.
The success of Axie Infinity paved the way for future gaming innovations by introducing gamers to onchain asset ownership and financial mechanisms within gaming. However, when the market crashed in 2022, Axie’s highly inflationary tokenomics model proved to be unsustainable, resulting in a mass exodus of players from the game.
As Web3 gaming progresses into a new era, many market participants still perceive Ronin as synonymous with the parabolic rise and subsequent fall of Axie Infinity, causing them to overlook its accelerating growth. This current misperception around Ronin is reminiscent of the negative sentiment towards Solana following the collapse of FTX, which left many investors sidelined during Solana’s sharp rerating in the second half of 2023. A closer look at the fundamentals driving Ronin’s growth suggests a compelling case for history to repeat itself.
In this report, we’ll provide a brief overview of the current state of Web3 gaming, highlight key areas of growth opportunity, explore how Ronin is positioning itself in these areas, examine Ronin’s strategic approach to ecosystem development, review current adoption metrics, and discuss potential risks to its future market dominance.
Note: Our Protocol Services report provides a comprehensive overview of Ronin Network’s technical architecture, tokenomics, history, and network growth as of July 2024.
Where We Are and How We Got Here
Sky Mavis, the team behind Ronin, began developing Axie Infinity on Ethereum in early 2018. However, when Ethereum gas fees surged in early 2021, the team quickly recognized that scaling on Ethereum would prove unsustainable. In response, Sky Mavis launched their own chain, Ronin Network, in April 2021.
The massive surge in Web3 gaming during the second half of 2021, driven by a ~5,700% increase in the price of Axie Infinity’s native token (AXS) from June to November 2021, sparked a frenzy of investment in the sector. H2 2021 raises saw enormous individual rounds, such as Sorare’s $680 million Series B and Sky Mavis’ $152 million Series B. This momentum carried into 2022, with a combined $2.3 billion invested in Web3 gaming-focused fundraising rounds in the first half of the year.
While investment has since cooled, with a cumulative $575 million raised in the first half of 2024, sector fundamentals are arguably stronger than ever:
2024 has witnessed a surge in adoption, with gaming onchain daily active users (DAUs) reaching an all-time high of 5.21 million on September 13, 2024—a 147% increase from the previous peak of 2.11 million in November 2021.
According to FootPrint Analytics, the total number of Web3 games has grown by 139% since January 2022, with over 1,995 new games launched.
Telegram mini-games on the TON network have attracted hundreds of millions of users - though only a fraction are onchain - and generated tens of millions in revenue.
Additionally, Pixels, one of the top games of 2024, reached over 1 million onchain daily active users (DAUs) on May 12, 2024.
Of course, distinguishing bot activity from real users is challenging, and unique active wallets are an imperfect metric for measuring adoption. Still, these metrics point to a disconnect between market interest and fundamental growth.
Alongside positive crypto-native metrics, we’re seeing increased adoption from Web2 companies. Major Web2 intellectual property has entered the Web3 gaming space, with Ragnarok debuting its first venture on Ronin and EVElaunching a new survival MMO on Redstone. Additionally, there are early signs of adoption from leading global enterprises, with Sony announcing its Layer 2 blockchain, Soneium, in August 2024.
While Web3 gaming still has a long road ahead, these current trends indicate the sector is heading in the right direction.
Targeting Areas of High Growth
While it’s still too early to say which specific growth strategies will ultimately send us to the promised land of “mass adoption,” trends in both Web2 and Web3 gaming point to several key areas with the potential for outsized growth.
Over the course of its history, Ronin has positioned itself in three of these areas:
Independent Game Developers
Mobile Gaming
Asian Demographic
Independent Game Developers
One of the prevailing theses behind 2021’s capital-intensive fundraising rounds was the need for a high-quality, breakout AAA game to onboard Web2 gamers. For some in the Web3 community, this remains the leading strategy; however, data from Web3 gaming adoption and trends in Web2 suggest that independent games may offer a more promising path.
Challenges of AAA Games
Producing AAA games in Web2 typically requires tens to hundreds of millions in capital, at least four years of development, and global distribution across multiple platforms. Despite these resources, AAA games can still fall flat. As with major productions in any form of entertainment, sinking vast amounts of capital into a single project is always a gamble.
For Web3 games, onboarding enough players to justify the expense becomes increasingly difficult due to several factors:
Low awareness
According to a recent poll conducted by OnePoll on behalf of Unstoppable Games, over 50% of gamers have never heard of a blockchain game.
Stigma against NFTs and crypto
According to the Ultra PC Gaming Report, only 18% of gamers are interested in earning cryptocurrency, and 19% in earning NFTs.
There is evidence to suggest that this aversion is driven primarily by stigma and semantics, as 33% of participants expressed interest in earning both “real money” and “limited edition items.”
Distribution bottlenecks
While there are Web3 games employing creative workarounds, Steam’s 2021 ban of NFTs, crypto, and blockchain, as well as Apple’s app store regulations, block off valuable distribution channels.
In contrast, indie games typically require between $10,000 and $1 million in capital, as little as six months of development, and less extensive distribution. Furthermore, beyond the large differential in resource expenditure, trends in traditional gaming indicate a growing preference for independent games.
Trends in Web2 Gaming
Platform metrics and individual game performance indicate that, over the past two years, indie games have become serious competitors to major AAA releases:
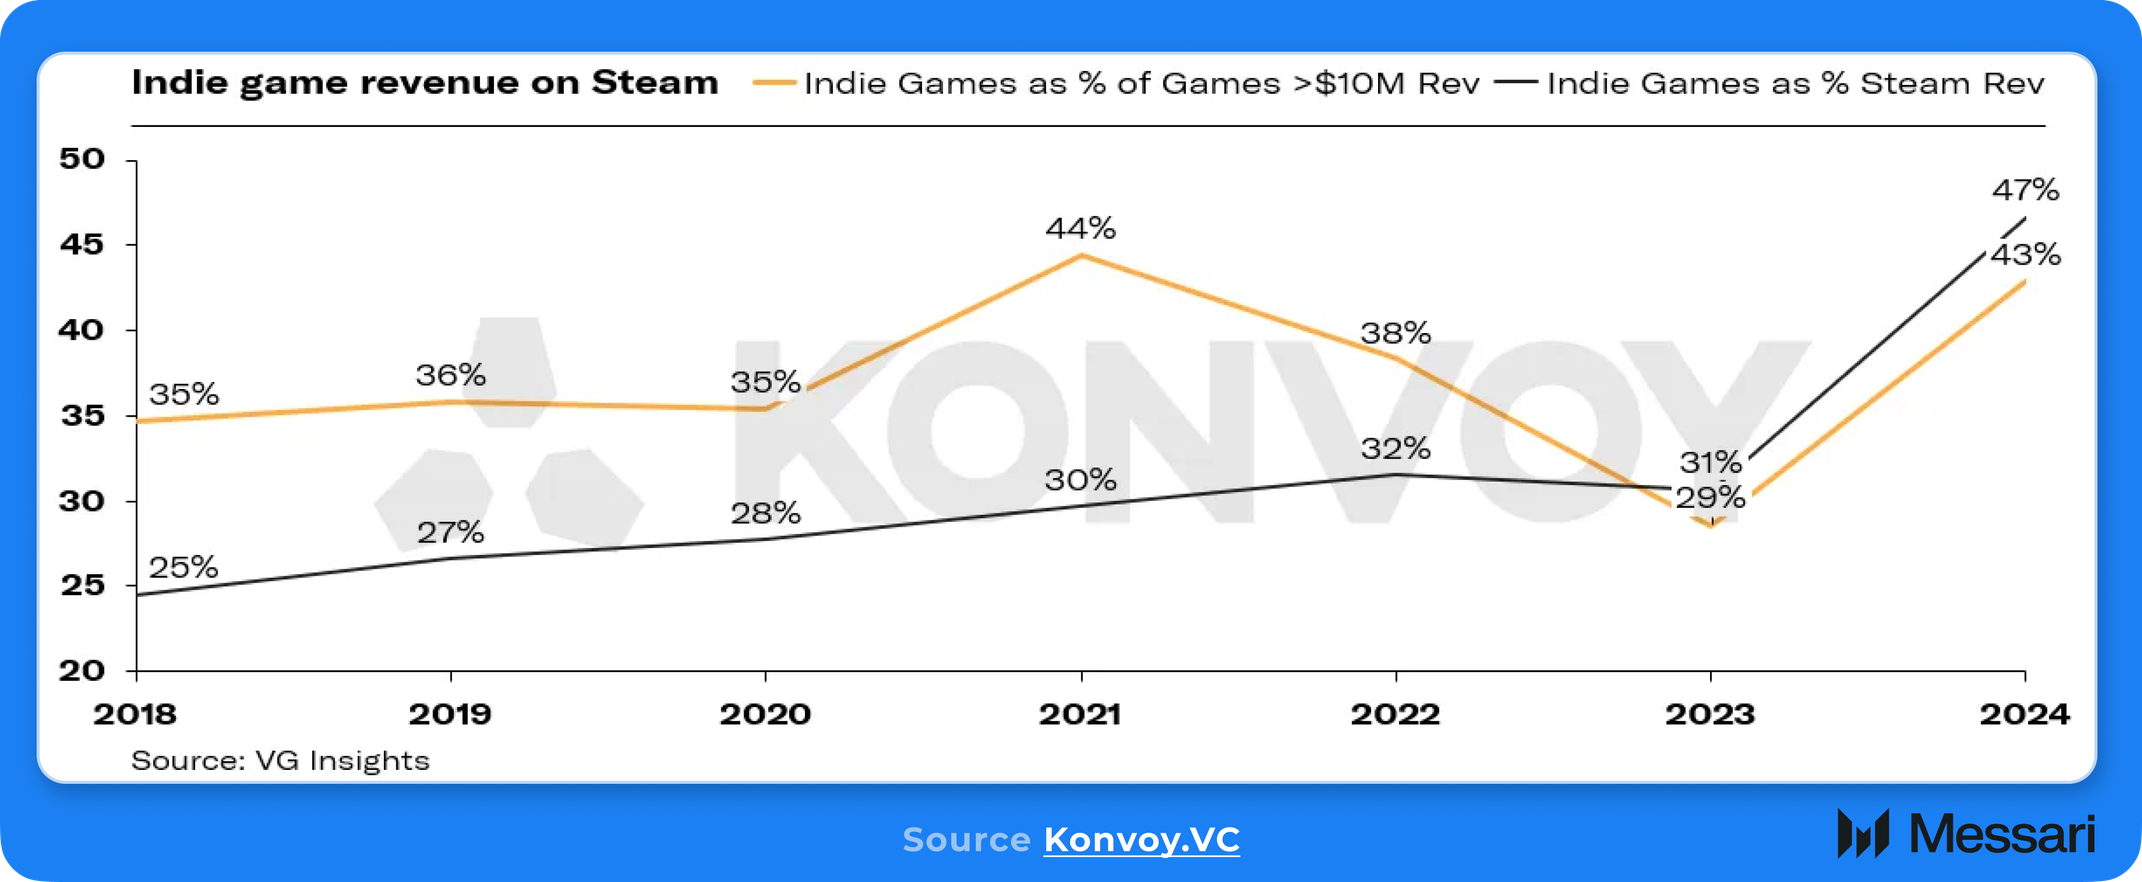
In 2023, indie games accounted for 31% of all Steam revenue, up from 25% in 2018.
The average Steam rating for indie and AAA games has nearly converged, at 72% and 74%, respectively, compared to 67% and 78% in 2018.
Indie game Palworldgenerated over $442 million in gross revenue from January to March 2024, reaching the second-highest concurrent player count for paid games ever recorded in Steam’s history.
In April 2024, Manor Lords, a city builder developed by a single creator, sold over 1 million copies on its first day and reached a peak concurrent player count of 170k—the highest ever for its genre.
This broader shift toward independent games is driven by both technical advancements and gamer sentiment around recent AAA productions. Developer tools like Unity and Unreal Engine allow indie developers to produce games that rival AAA titles in production quality, and with the growing use of AI in game development, this gap is likely to narrow even further. Additionally, many gamers are voicing frustration with the lack of innovation in AAA titles, as many major studios fall back on 'proven' game models rather than taking creative risks.
Web3 Adoption Metrics
2024 saw the release of several 'AAA' games that raised massive capital through both private investments and public NFT sales. However, their adoption metrics have so far lagged well behind those of leading indie games:
Illuvium: Raised $60 million in private funding and $72 million from land sales; its estimated DAU is fewer than 5,000.
Big Time: Raised $21 million in private funding and over $100 million from NFT sales; the most recent season's leaderboard shows 41,459 total players.
In comparison, Pixelsraised only $7.2 million and, as of September 18, 2024, had 550,000+ DAU. Between its initial $2.4 million raise on February 3, 2022, and its second round of $4.8 million on February 9, 2024, Pixels scaled to approximately 200,000 daily active wallets. At its peak, Pixels surpassed 1 million DAU, making it the highest-ranked game by DAU in 2024.
According to a Blockchain Gamerarticle published on April 11, 2024, Pixels' monthly recurring revenue (MRR) from its VIP program reached $1.6 million. As opposed to the unreliable speculative revenue generated from NFT sales, this revenue is driven by real player demand.
Of course, the number of playable 'AAA' Web3 games remains limited, and for every Pixels, there are many indie games that struggle to gain significant adoption. Still, these early trends suggest a path forward that prioritizes less resource-intensive games over a path that hinges on producing a singular 'breakout' title.
Ronin's Approach to Independent Developers
Ronin’s ecosystem is largely composed of games developed by independent teams that prioritize gameplay mechanics over the high-fidelity graphics seen in AAA titles. Games like Pixels and Forgotten Runiverse embrace low-fidelity, pixelated art, while titles like Wild Forest deliver simple yet addictive PVP mobile gameplay. Although 69% of the 13 current games within the Ronin ecosystem have secured investor funding, the largest disclosed round is Apeiron’s $10 million seed round in 2022.
This indie-centric approach is also evident in Ronin’s native developer acquisition strategy. Through its builder program, Ronin Forge, the company intentionally targets indie game developers, specifically seeking applications from 'scrappy, experimental teams.'
Later in this report, we’ll cover Ronin’s multi-pronged developer acquisition strategy and ecosystem curation in greater detail.
Mobile Gaming
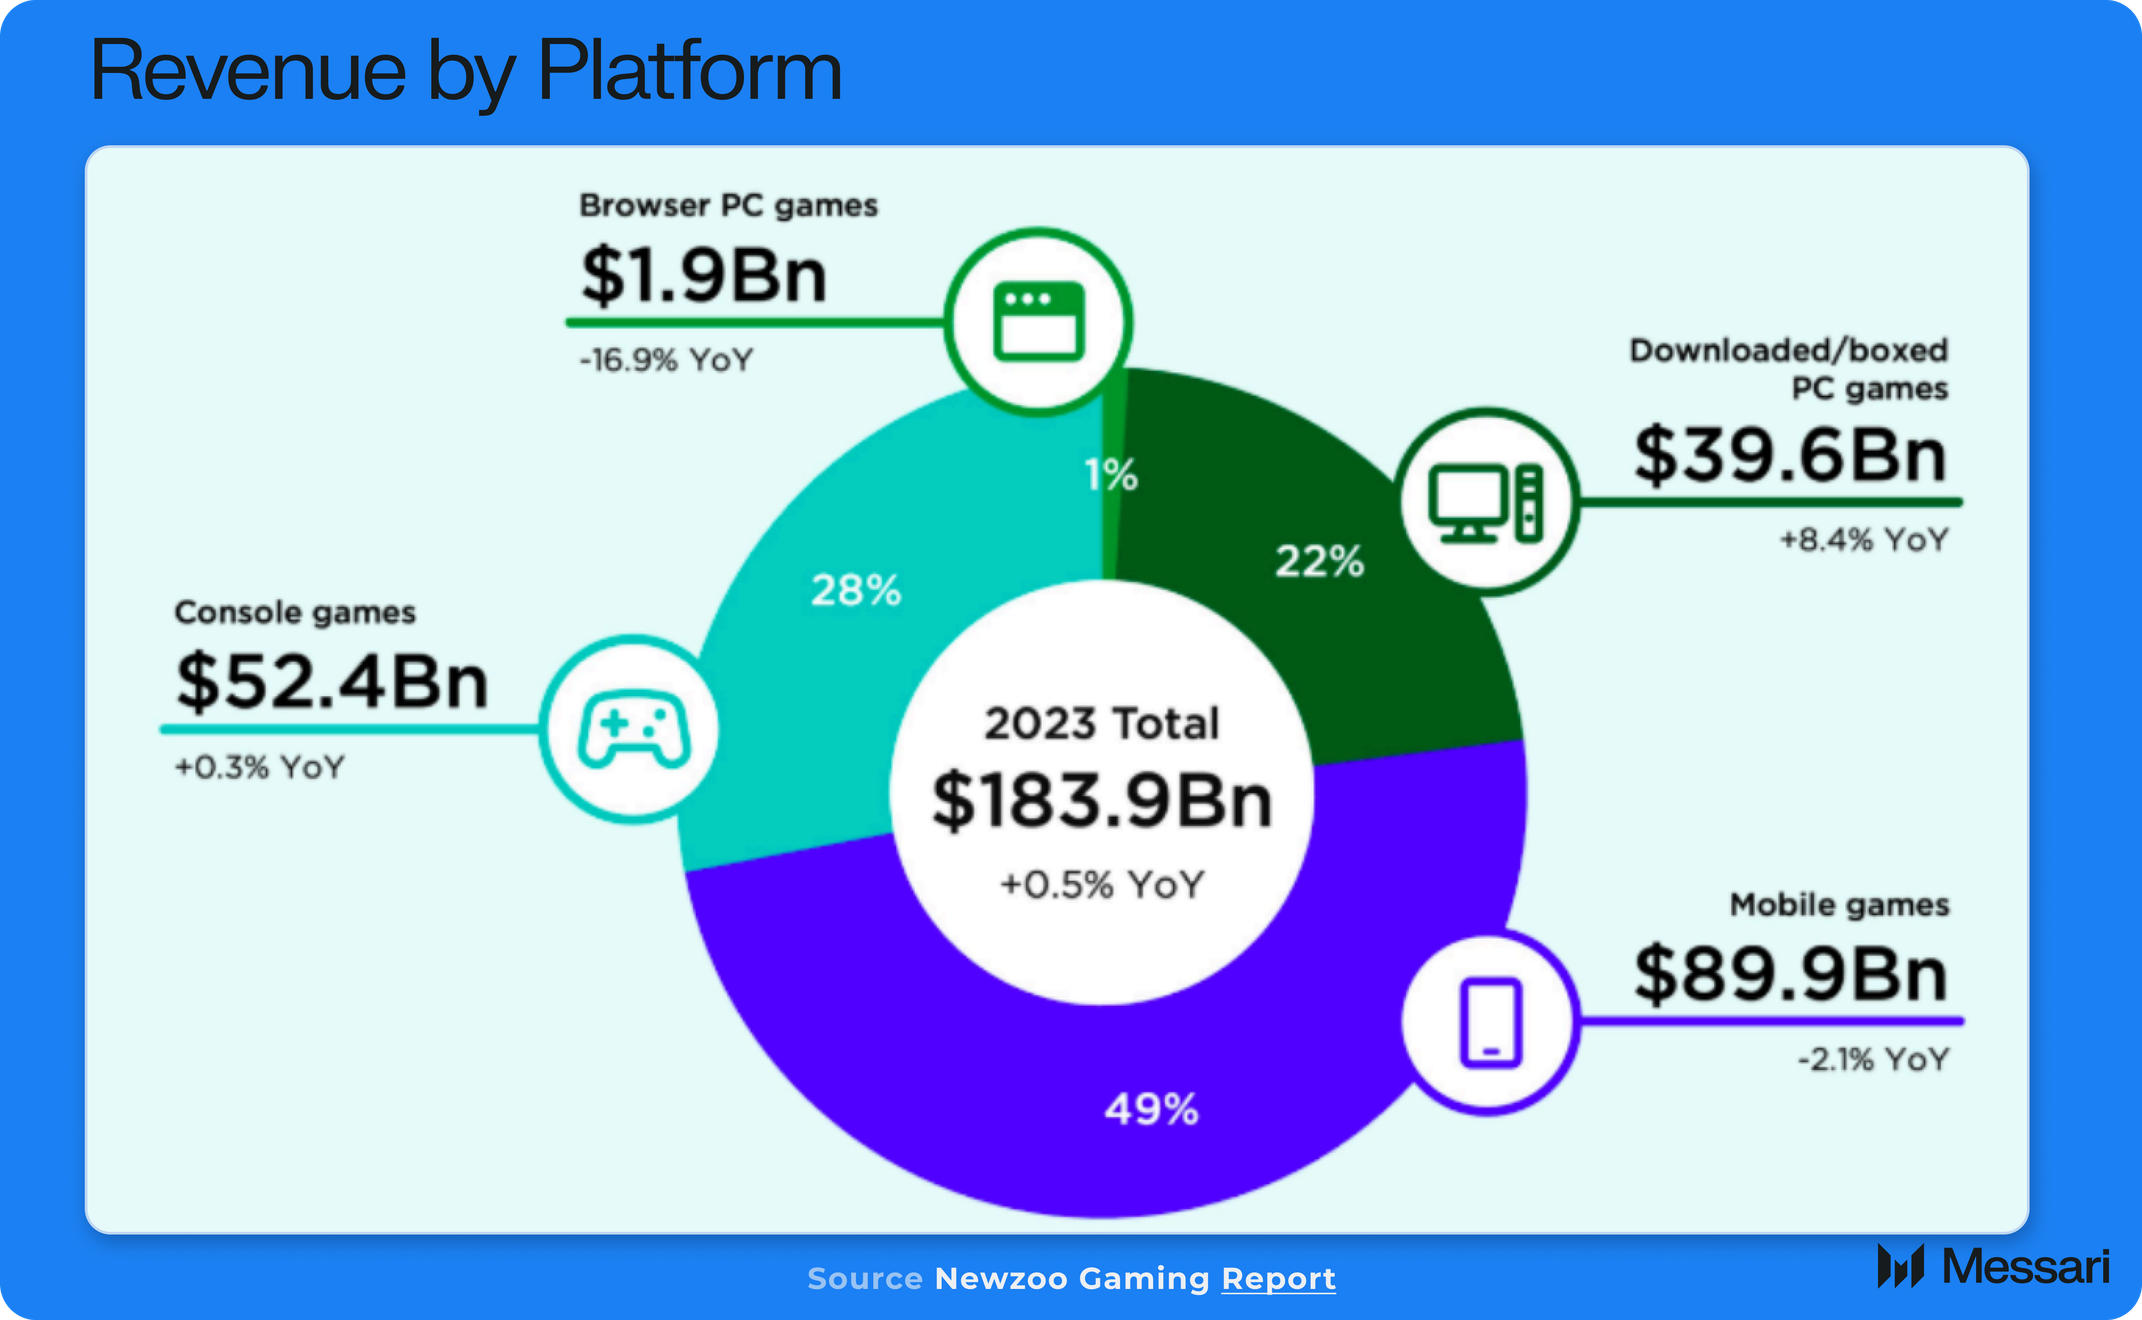
According to the 2023 Newzoo Gaming Report, 49% of total gaming revenue came from mobile in 2023, with 79% of gamers playing mobile games. However, of the 490 Web3 games listed on gam3s.gg, only 157 (32%) are available for mobile.
One key reason for the shortage of mobile games in crypto is the restrictive policies imposed by app stores. Historically, app stores have been less than welcoming to crypto gaming. However, we’re now beginning to see a shift in this trend.
In July 2023, Google Play announced a significant policy update, allowing developers to integrate digital assets like NFTs into their games and apps. However, Apple still lags in this regard, restricting auctions or variable offers on NFTs and requiring that all purchases be made with fiat through Apple’s payment rails.
Despite lingering restrictions, Web3 games continue developing creative workarounds. A recent notable example is TON Network’s introduction of “stars,” an in-app currency on Telegram acquired through Apple’s payment rails that can later be converted into $TON. Conversely, games like Axie Infinity and NFL Rivals have released mobile apps through the Apple app store while siloing trading activity to browser-based marketplaces.
Ronin’s Approach to Mobile
Ronin tackles mobile gaming through multiple distribution channels, including traditional app store releases, Telegram mini-games, and an aggregated 'mini app store' embedded within its mobile wallet.
Traditional Mobile Apps: 46% of games in the Ronin ecosystem are accessible through mobile apps, 14% higher than the overall percentage of mobile crypto games.
Telegram Mini-Games: Ronin has recently ventured into the Telegram gaming ecosystem with titles like Lumina Hunt by Tatsumeeko.
Native Wallet App Store Model: For browser-based games optimized for mobile, such as Pixels, Ronin offers an aggregated hub within its wallet, allowing users to play these games directly from the wallet’s browser.
Later in the report, we’ll explore how Ronin’s mobile app store model enables streamlined distribution for projects within the Ronin ecosystem.
Asian Demographic
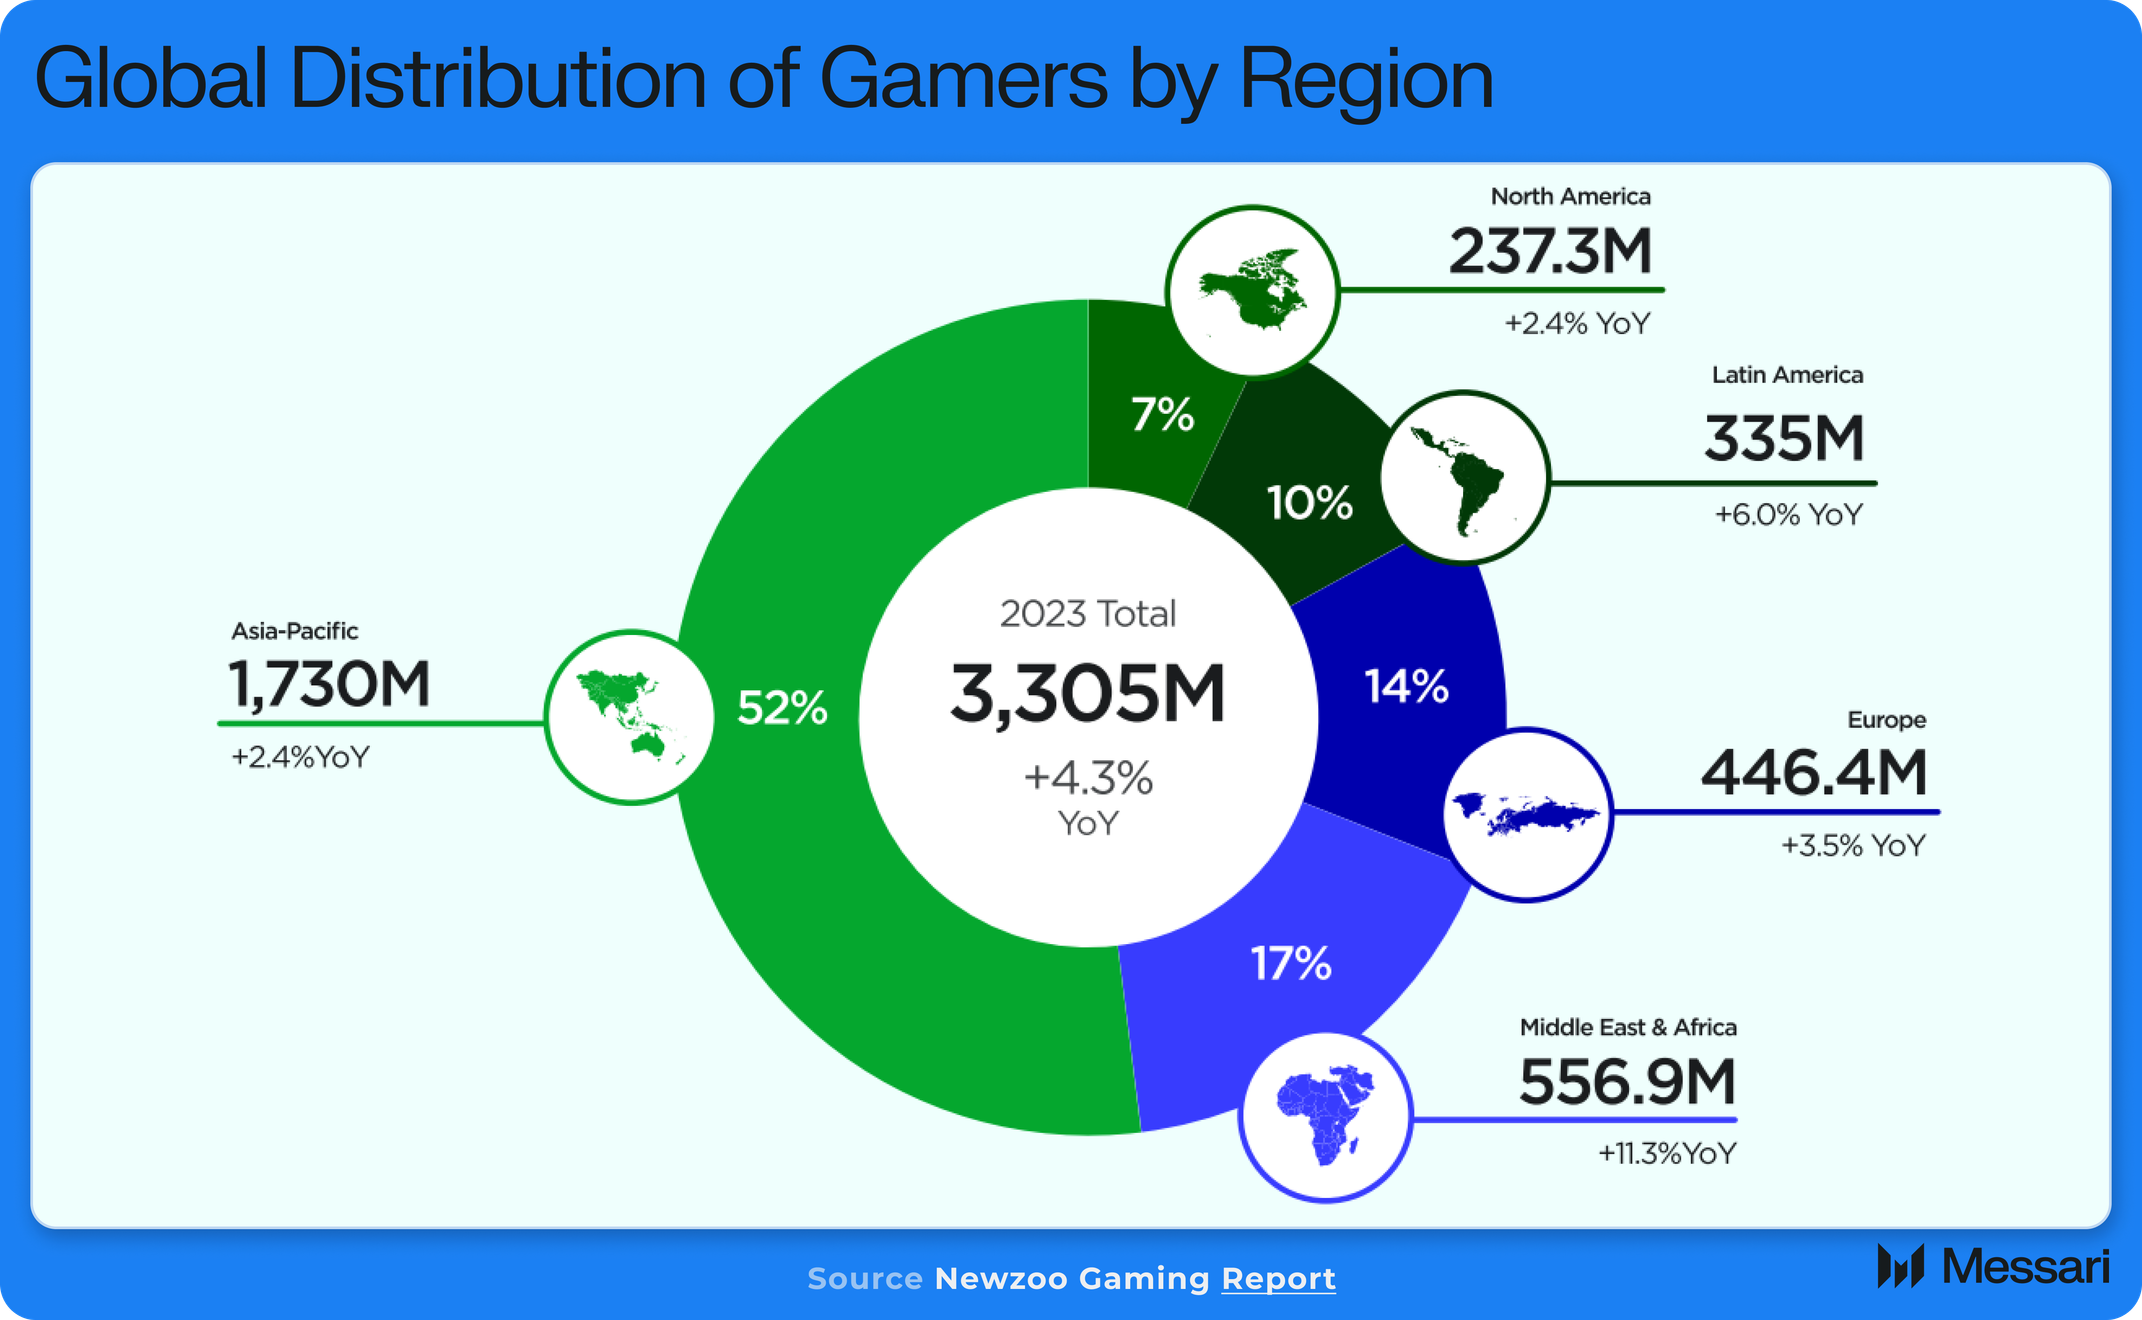
According to Newzoo’s previously mentioned report, global player numbers are projected to grow at a CAGR of 3.7% from 2021 to 2026, reaching 3.68 billion players by the end of 2026. Driven by massive developing markets like India and China, as well as gaming-centric countries such as Japan and South Korea, over 50% of the global gaming population is now based in Asia.
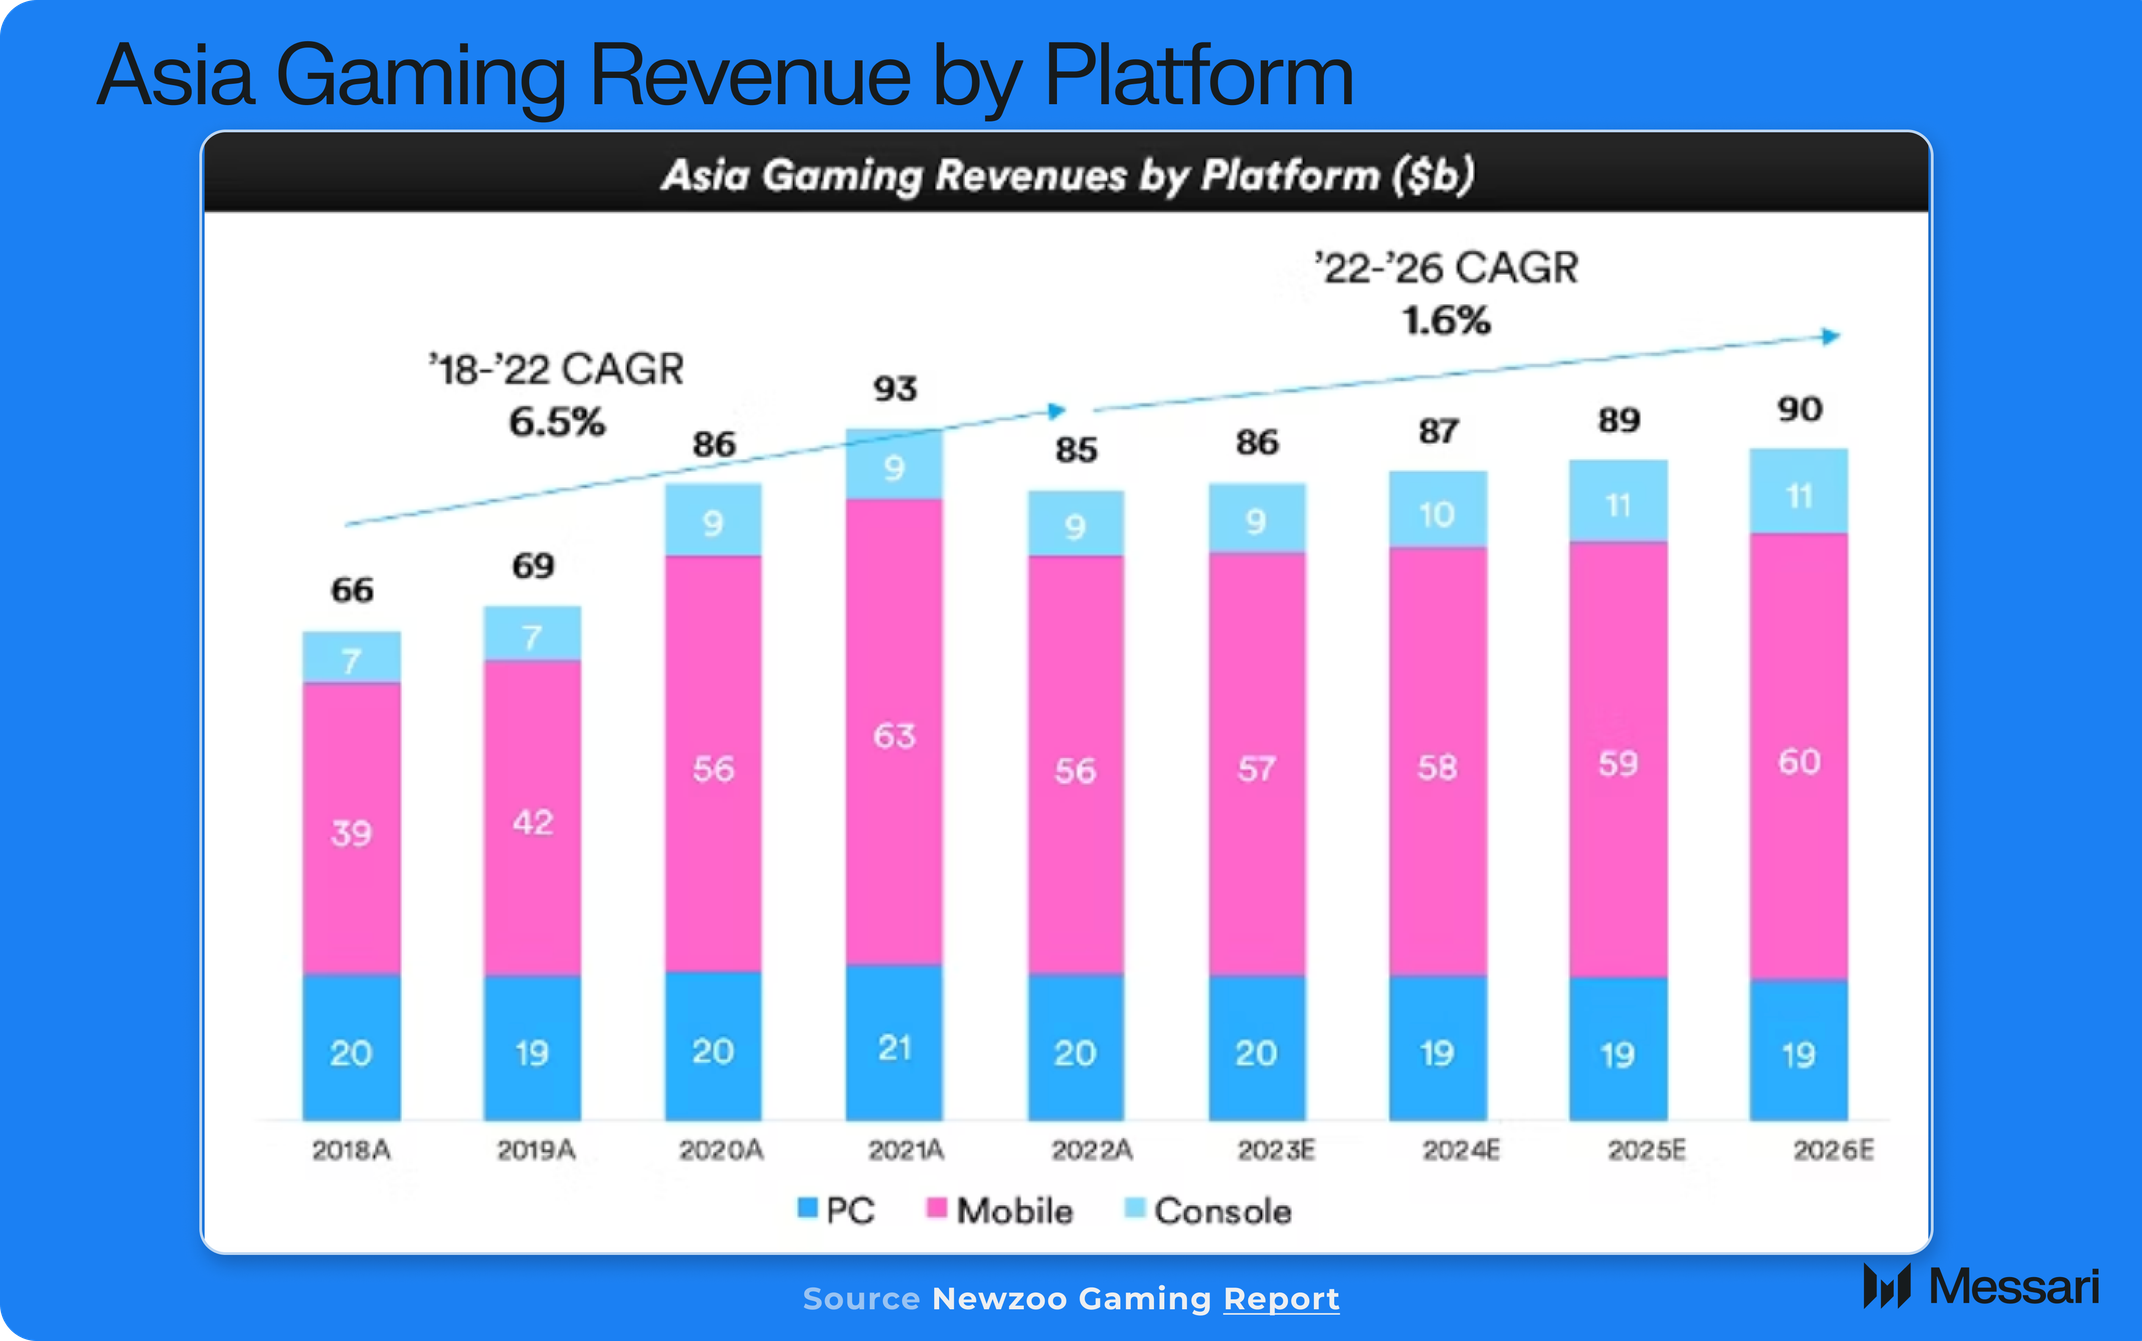
Asia presents a natural synergy with a mobile-focused strategy. In the four-year period from 2018-2022, mobile gaming revenue in Asia had a compound annual growth rate (CAGR) of 12.7%, growing from $39 billion to $63 billion. In comparison, PC revenue remained relatively flat, inching up from $20 billion to $21 billion. Console revenue grew from $7 billion to $9 billion—better than PC, but still significantly lagging mobile.
This trend is also evident in Web3 fundraising, where approximately 55% of the capital raised in Web3 gaming since 2019 has come from Asian VCs and entities such as Animoca Brands and Binance Labs. With this growing influx of capital, Asia is positioned to be a dominant force in the adoption of Web3 gaming.
Ronin’s Approach to Asia
Since its inception, Sky Mavis, the company behind Axie Infinity and the Ronin Network, has had deep ties to Asia. Founded in Vietnam, Sky Mavis initially gained traction for Axie Infinity in the Asia-Pacific region, particularly in the Philippines. Additionally, Sky Mavis has consistently attracted capital from prominent Asian VCs, with Animoca Brands participating in four of their five fundraising rounds, including leading their $1.46 million seed round in 2019.
This past year, Ronin made significant strides to strengthen its momentum in Asia. In April 2024, Ronin onboarded the RagnarokIP, one of South Korea’s earliest commercially successful Web2 gaming IPs, for its Web3 debut with Ragnarok: Monster World. Additionally, building on its support in the Philippines, Ronin was chosen to debut the first Filipino stablecoin, PHPC. As Ronin continues to scale its presence in the region, it’s likely to become an increasingly attractive distribution channel for game developers targeting the Asian market.
Building the Ronin Empire
To drive growth in these areas of opportunity, Ronin has built a vertically integrated ecosystem that allows for greater control over its development, supported by a multi-pronged game developer acquisition strategy.
Vertical Integration
One of the major decisions a network makes in its early stages is how opinionated it will be in ecosystem development. General-purpose chains, like Ethereum and Solana, often take an unopinionated approach, building only the network and giving developers the freedom to build foundational applications on top of it. Chains developed with specific use cases in mind, like Hyperliquid or ImmutableX, often opt to build foundational applications like exchanges or marketplaces in-house.
Ronin takes a highly opinionated approach, developing all core components of its ecosystem in-house and requiring developers to obtain permission from Sky Mavis before launching on mainnet. While this approach is less decentralized, blockchain gaming’s core value lies in the ownership of in-game assets. The permissions around who can build on the chain doesn’t impact this feature. Additionally, Ronin’s approach offers distinct benefits for each player in the ecosystem:
Gamers: A curated ecosystem eliminates the need for decision-making around non-gaming applications, improving UX for both crypto-native and traditional gamers.
Developers: With streamlined distribution channels and infrastructure compatibility, developers can focus entirely on game development and community building.
Ronin: Instead of third-party applications capturing fees from foundational products, Ronin captures value from each core gaming-adjacent application within its ecosystem.
With this in mind, we’ll explore Ronin’s vertically integrated structure through three primary value propositions:
Streamlined distribution for game developers
Unified Web3 experience for gamers
Full stack value capture back to Ronin
Streamlined Distribution
According to data from Footprint Analytics, the total number of Web3 games has increased by 402% since January 2021, rising from 680 to 3,414. This continuous proliferation of new games, with varying levels of quality, results in gamers spending more time searching for high-quality titles and developers spending more money on capturing player attention.
For games that choose to build on Ronin, discoverability becomes less of a challenge. In addition to a standard ecosystem tab on their website, Ronin employs an app store model with two distinct distribution channels: desktop games that require installation are available through Mavis Hub, while mobile-compatible browser games can be accessed directly via the Ronin mobile wallet.
The benefits of aggregated distribution are evident from the Cambrian explosion of mini-games and the subsequent parabolic rise in onchain activity following the release of Telegram’s Apps Center. By joining the network, developers are handed a built-in top-of-funnel pipeline with unified player liquidity. As Ronin expands further into mobile gaming, this mobile app store model will become an increasingly valuable differentiator for developer acquisition.
Unified Web3 Experience
Seamlessly onboarding traditional gamers to Web3 requires narrowing the gap between familiar Web2 gaming experiences and the complexities of interacting with the Web3 stack. While handling these complexities becomes second nature to crypto natives, learning to set up a wallet, bridge assets, swap on decentralized exchanges, and trade NFTs still presents a steep learning curve for many first-time users. By developing core gaming-adjacent applications in-house, Ronin is able to:
Remove the decision-making process around which applications to use.
Maintain control over application quality.
Aggregate assets within a unified marketplace.
Paired with aggregated distribution, this approach has a massive positive impact on user experience. The Ronin mobile wallet enables direct access to these ecosystem applications. From within the wallet, players can:
The value derived from this combination cannot be overstated. By providing a central hub where gamers can access every aspect of the Web3 gaming experience, Ronin retains full attention within its ecosystem, enabling a seamless transition between gaming and Web3 actions like token swaps and NFT trading.
Full Stack Value Capture
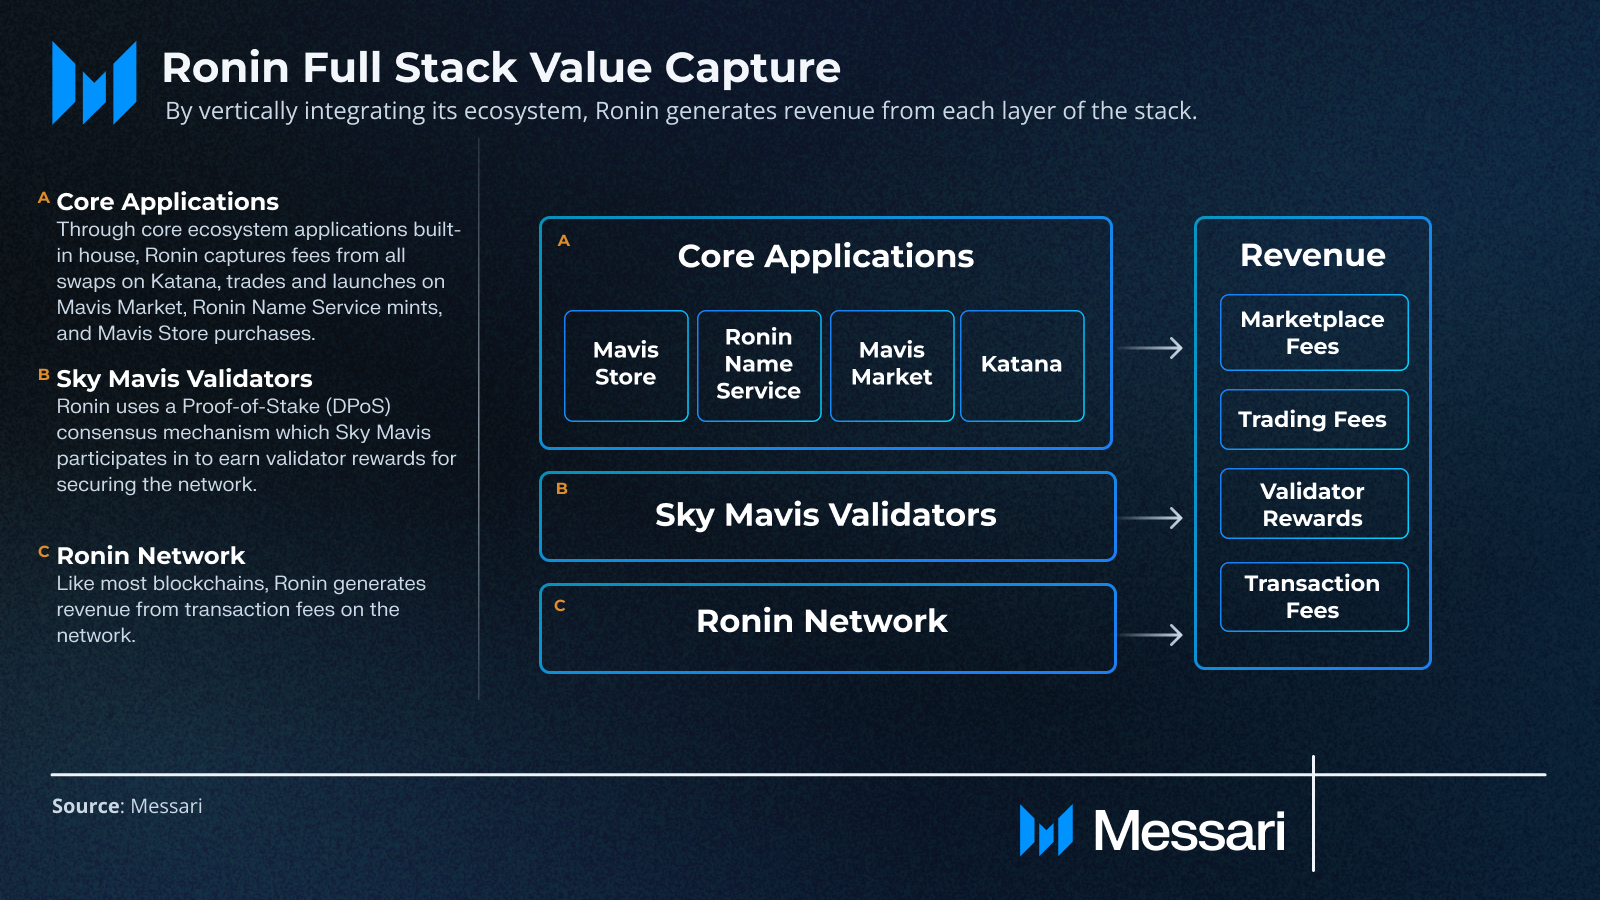
Beyond providing a better user experience, building core applications in-house enables Ronin to capture value at every layer of the stack.
In-House Revenue Engines:
Mavis Market: Ronin’s NFT marketplace and launchpad.
Sky Mavis Fee: A fixed 2% fee charged by Sky Mavis.
Ronin Fee: A fixed 0.5% fee goes directly to the Ronin Treasury.
Mavis Store: Ronin’s marketplace for in-game purchases.
Sky Mavis Fee: A fixed 5% fee charged by Mavis Store for building and maintaining the marketplace.
Sky Mavis receives rewards by running governing validators on the network.
By owning the entire stack, Ronin generates a continuous stream of revenue that helps fund its treasury and investments in ecosystem development initiatives like Ronin Forge. Additionally, as the network scales and more games depend on these applications, so does Ronin’s pricing power.
Growth Strategies
While the continuous release of new Web3 games is undoubtedly a positive sign of sector growth, this influx of titles brings its own challenges. As more Web3 games enter the market, gaming ecosystems must focus on:
Striking the right balance between game supply and player demand.
Establishing quality thresholds to ensure players are exposed to enjoyable games.
Building robust acquisition pipelines to capture high-quality titles.
Permissioned Approach
The Sky Mavis team currently takes a high-touch approach, curating which games are launched on the network through a variety of acquisition channels. This approach provides greater control over supply, demand, and release cadence, along with full oversight of quality. As the ecosystem evolves, Ronin can selectively introduce games with specific characteristics that algin with community preferences and player acquisition strategies.
In March 2023, Ronin began onboarding games from third-party developers. After announcing its first five titles on the same day, Ronin has maintained a relatively steady release cadence, with ten titles announced between August 2023 and July 2024. During this period, games were added to the network individually, with no more than two releases per month.
However, recently Ronin increased its release cadence, announcing eight new titles in September 2024. Of these, seven were developed through Ronin’s in-house builder program, Ronin Forge. While this influx of releases will have varying effects on the balance of game supply and player demand, as we’ll explore later, it also presents opportunities to drive revenue growth.
Game Developer Acquisition
As the Web3 gaming sector continues to grow, acquiring both Web3 and Web2 game developer talent has become increasingly competitive. In June 2024, ArbitrumDAO finalized its Gaming Catalyst Program proposal, deploying $215 million from its treasury to accelerate game developer acquisition and support ecosystem builders. Despite this massive injection of capital, TreasureDAO, a longstanding project in Arbitrum’s gaming ecosystem, recently passed a proposal to build their L2 within the ZkSync ecosystem following conversations with the ZkSync team. Events like this highlight the need for gaming ecosystems to develop acquisition strategies that not only attract talent but also retain it.
Ronin takes a multi-pronged approach to game developer acquisition:
High-touch, in-house builder programs
Ronin Forge provides builders with a $50,000 grant, access to Ronin infrastructure, and hands-on support from the Ronin team.
Axie Infinity Builders Program is a program directed by Sky Mavis that aims to expand Axie’s IP. Builders receive a minimum $10,000 grant in AXS, access to Ronin infrastructure, and hands-on support from the Sky Mavis team.
Acquisitions from competing gaming ecosystems.
In Q4 2023, Ronin onboarded Pixels and Apeiron, both of which migrated from Polygon.
According to DappRadar, As of September 24, 2024, these two games account for 39.4% of Ronin’s 1.75 million daily active wallets.
Partnerships with Web2 and Web3 intellectual property.
Forgotten Runiverse is the flagship game of the NFT project Forgotten Runes Wizard Cult. The game has already achieved over 967,000 Unique Active Wallets in its open beta playtest.
Ragnarok Monster World marks the entry of the popular Web2 game Ragnarok into the Web3 space. Their first mint on the Ronin Launchpad in May 2024 generated $604,398 in volume.
Game studio partnerships for new ventures.
Ronin onboards a mix of established game studios like Zillion Whales and new entrants like GMonsters.
This diversification across internal and external acquisition channels allows Ronin to capture talent from outside its ecosystem while reducing flight risk through builder programs that foster games with strong ties to the network.
Ronin Growth Metrics
User Metrics
In Q4 2021, Axie Infinity drove daily active users to record highs, peaking at 1.1 million DAUs on November 19, 2021. However, as interest in the game died and the market continued to decline, DAUs plummeted by over 99%, hitting a low of 10,280 on December 24, 2022. Over the past few years, the release of new games on the network has fueled growth beyond its 2021 peak. Since December’s local low, DAUs have surged by over 26,000%, reaching a new all-time high of 2.27 million on August 1, 2024.
While many games on Ronin have gained popularity over the course of this revival, the lion’s share of growth has been driven by a select few releases:
Pixels
Pixels launched on Ronin on October 30, 2023, and by January 1, 2024, had amassed 127,000 DAU.
At its all-time high on May 12, 2024, Pixels reached 1.03 million DAU, marking a 711% increase since the start of the year.
As of September 24, 2024, Pixels has 630,000 DAU, showing a strong recovery from its 2024 low of 250,000 DAU in June.
Apeiron
Apeiron launched on Ronin on December 18, 2023, and by January 1, 2024, had captured 7,900 DAU.
On September 21, 2024, Apeiron hit an all-time high of 153,000 DAU, a 1,800% increase from the start of the year.
Wild Forest
Wild Forest debuted on Mavis Hub on May 14, 2024, but struggled to gain any traction until late June.
Since then, the game has seen a meteoric rise, reaching an all-time high of 154,000 DAU on September 8, 2024.
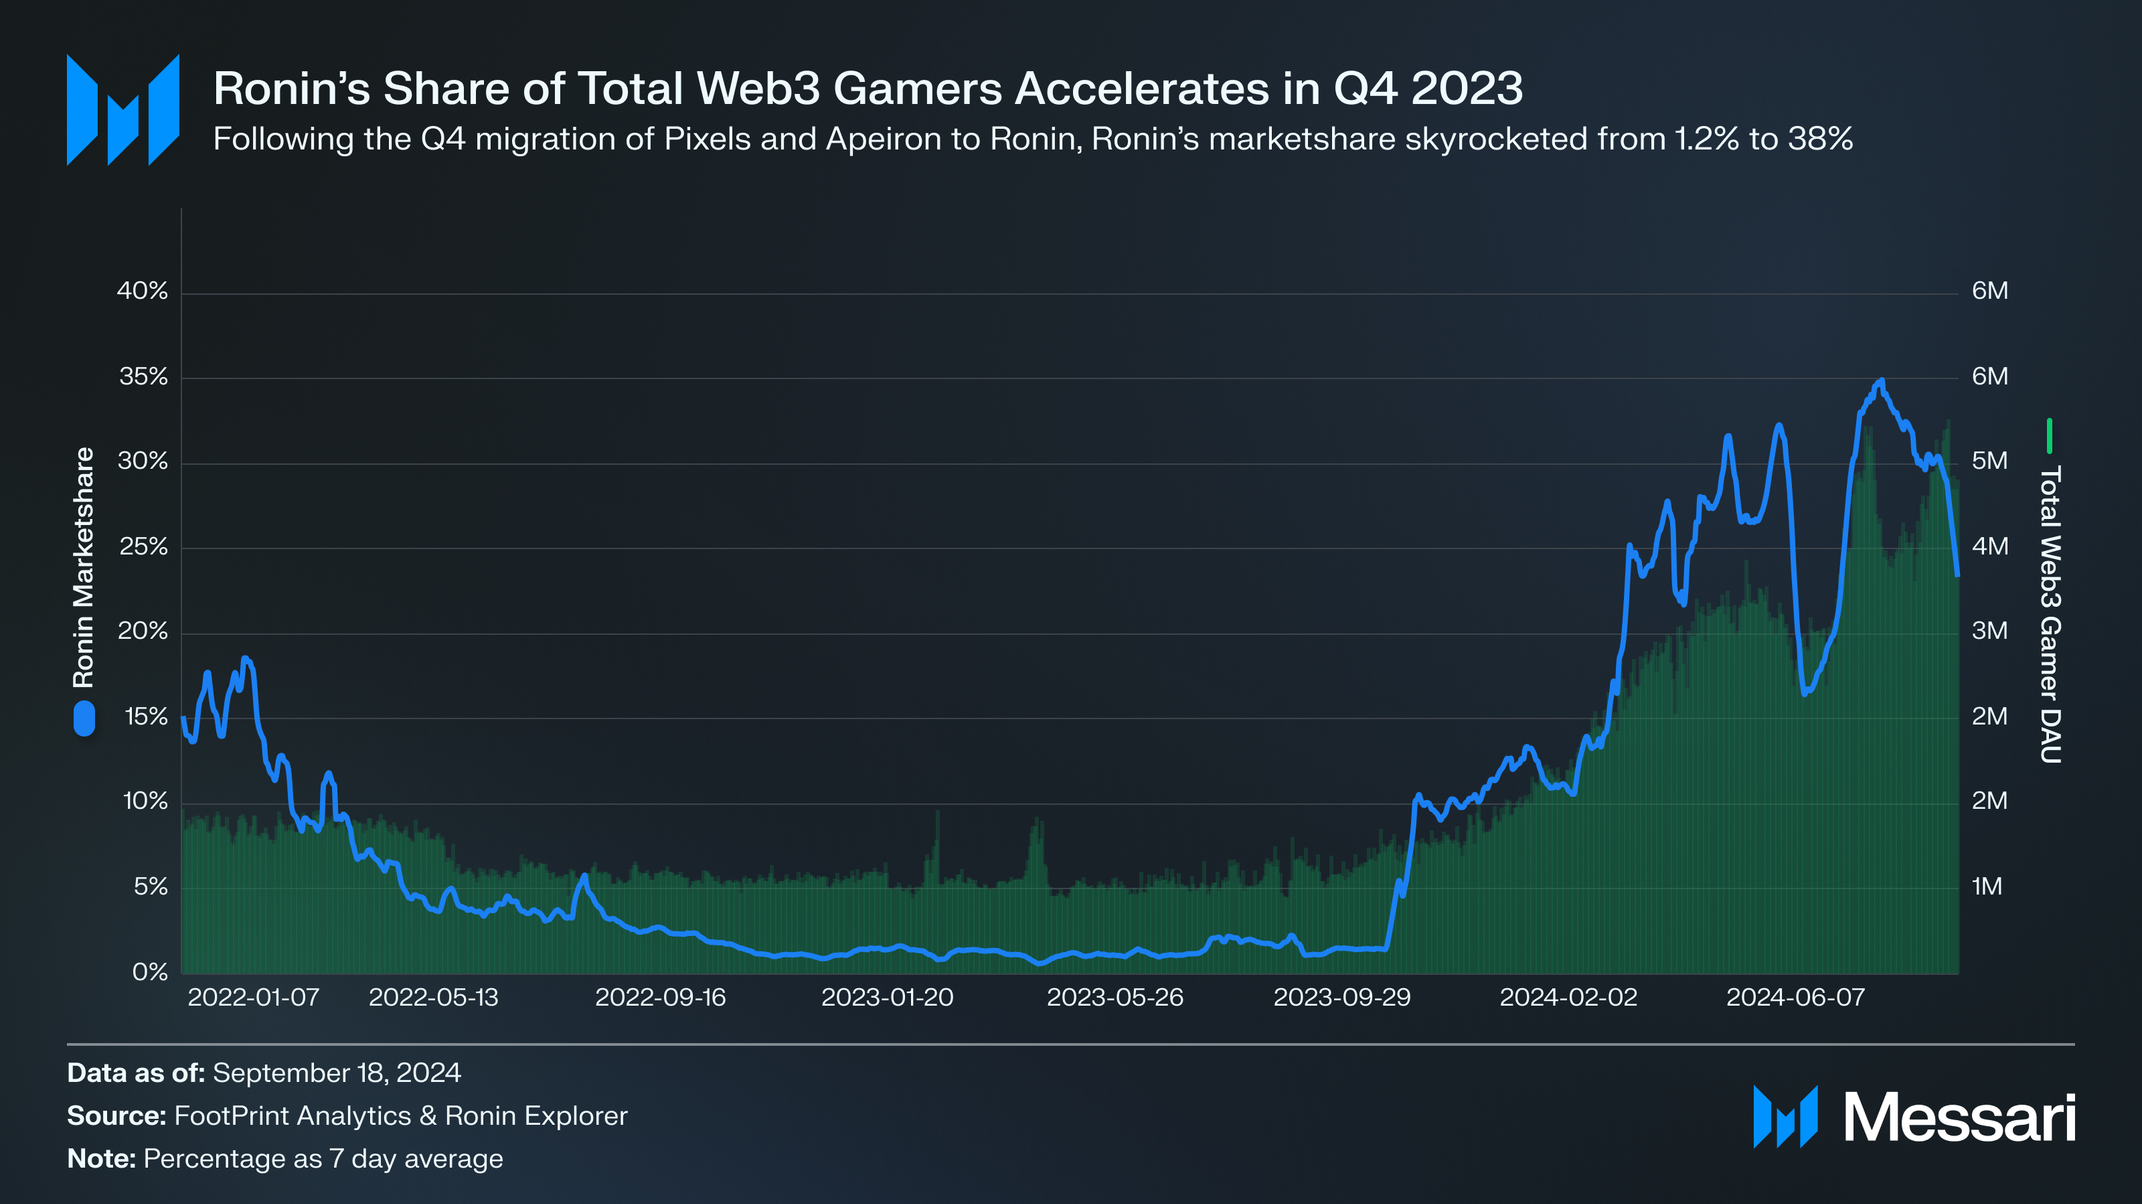
The outsized growth of these projects drove Ronin’s market share from just 1.2% of the total onchain gaming DAU at the start of Q4 2023 to a peak of 38% in August 2024. However, since August, Ronin has lost some of its market share to popular releases on opBNB, such as Seraph: Enter the Darkness, which grew from 182,000 DAU on August 1 to over 500,000 by late September. As of late September, Ronin's market share stands at around 21% of total gaming DAU.
Core Application Revenue Generators
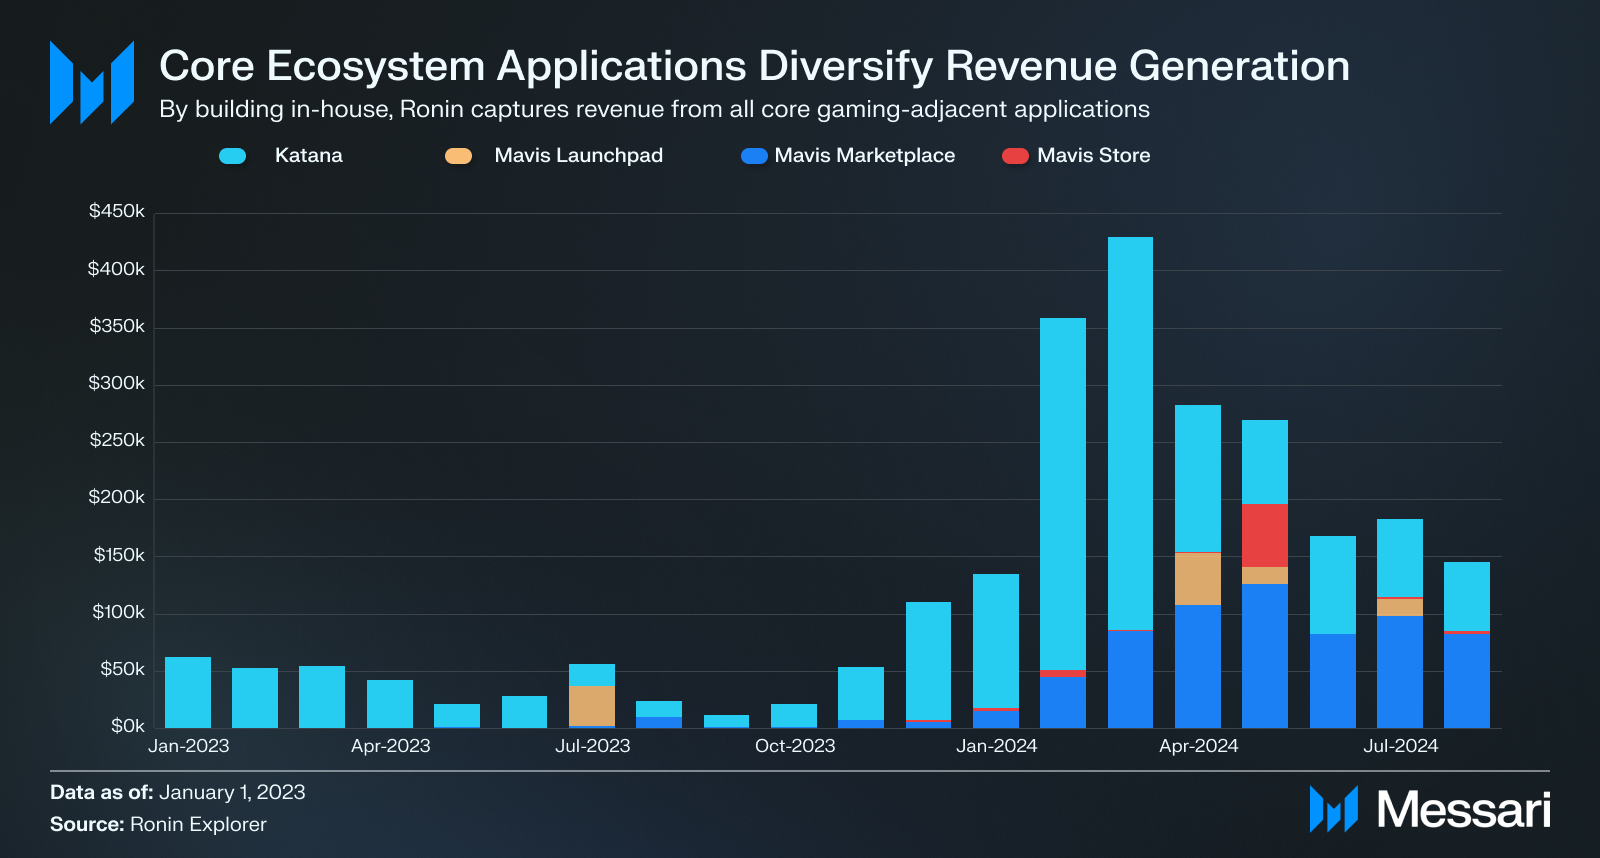
As mentioned earlier, in addition to transaction fees, Ronin generates revenue from multiple core ecosystem applications. Ronin’s monthly revenue from these applications rose from $61,677 on January 1, 2023, to a peak of $428,937 in March 2024, representing a compound monthly growth rate (CMGR) of 14.86%. Although revenue has since declined, due primarily to a lack of new token listings on Katana, as early-stage ecosystem games progress in their development, the launch of new tokens and NFTs on these platforms is likely to drive more volume.
Katana
A primary driver of this revenue growth is Katana, Ronin’s native decentralized exchange. As evidenced by Katana’s Q1 2024 volume fluctuations, activity tends to correlate with new token listings. Between February and March 2024, Katana listed four tokens—$APRS, $BANANA, $YGG, and $PIXEL. These tokens vary in utility, with tokens like $PIXELS required for minting in-game NFTs and participating in guild, and tokens like $YGG required to participate in DAO governance. These listings, combined with $RON’s listing on Binance, drove monthly revenue from $117,569 in January to $307,319 in February and $343,601 in March.
With no new listings in April, revenue dropped by 62.7% and has continued to decline, reaching $60,608 in August 2024. However, with Ronin adding eight new games to its roster in September and other titles emerging from beta, its likely we will see a resurgence in volume once these games launch their tokens.
Mavis Marketplace
Katana's volume drop in April was cushioned by $107,358 in revenue from Ronin's NFT marketplace, Mavis Marketplace. Since its inception, Mavis Marketplace has grown its monthly revenue at a CMGR of 36.82%, increasing from $749 in May 2023 to $82,589 in August 2024, with cumulative revenue reaching $664,963.
Marketplace volume is primarily driven by the popularity of ecosystem games, along with significant one-off events. While volume isn’t entirely dependent on these events, they can lead to spikes in daily revenue, such as the Kaidro Spark Suit mint, which generated $19,585 on April 9, 2024. Additionally, as shown by Axie Marketplace’s $4.5 billion in total volume, even a single game that captures a large market share has the potential to transform Mavis Marketplace into a major revenue engine for Ronin.
Ronin Launchpad
While launchpad revenue relies on infrequent, singular events, these events have shown the ability to attract substantial capital. To date, five projects have launched NFTs through the platform, generating a cumulative $110,476 in revenue. If the platform continues to attract capital for successful launches, it's likely that new projects will see the launchpad as an ideal venue for debuting their collections.
Mavis Store
Since its launch in December 2023, the Mavis Store has generated a cumulative $71,513 in revenue. Typically, the store has driven between $500 and $6,000 in monthly revenue, with May 2024 as an outlier, generating $54,954 from the Wild Forest Pre-Global Release NFT Sale. While it's unlikely that the Mavis Store will become a primary revenue driver in the near term, significant one-off events could provide occasional revenue boosts. Additionally, if Ronin eventually expands to hundreds or even thousands of games, the combined listings of in-game purchases could lead to substantial growth for the store.
Risks
Stifled Organic Growth
While a permissioned approach to growth offers certain benefits, it also limits Ronin's ability to capitalize on organic growth driven by permissionless innovation. Web3 gaming is still in its early stages, but as the sector matures and higher-quality teams enter the space, gating access presents a greater risk of missing out on games with breakout potential. Jeff Zirlin, co-founder of Sky Mavis, acknowledges this and has indicated that Ronin has plans to open its ecosystem to all developers in the future.
AAA Strategy Succeeds
Although there are many reasons to believe that independent games could drive greater Web3 adoption, it’s still early in the sector’s development, and producing AAA games could ultimately prove to be a more effective strategy for acquiring Web2 gamers. With onchain AAA titles like Off the Grid set to release this year, a hit game in this space could lead to increased investor capital flowing toward AAA projects. Given that Ronin’s ecosystem primarily supports indie games, it’s unlikely that a breakout AAA game would emerge from within Ronin.
Increased competition from Web2 enterprises
The entry of Web2 enterprises and intellectual property into Web3 gaming is a positive development for the sector overall but could present a risk to Ronin's growth. Ideally, these new entrants would expand the Web3 player base by introducing Web2 gamers. However, if Web2 gamers continue to resist Web3, these entrants may end up siphoning users from chains like Ronin rather than onboarding new players.
Conclusion
While the exact timeline for when Web3 gaming will reach widespread adoption remains uncertain, the sector's fundamental growth is undeniable. As we climb out of the valley of despair and progress further along the road to mass adoption, Ronin’s curated growth strategy and full-stack value capture uniquely position it to emerge as the sector leader, capitalizing on the trends propelling the broader onchain gaming industry forward. While the market's gaze is elsewhere, the quiet revival of Ronin’s empire offers an opportunity. If sector evangelists are right and Web3 gaming is truly inevitable, it’s best to be prepared ahead of time.
All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Nothing contained in this report is a recommendation or suggestion, directly or indirectly, to buy, sell, make, or hold any investment, loan, commodity, or security, or to undertake any investment or trading strategy with respect to any investment, loan, commodity, security, or any issuer. This report should not be construed as an offer to sell or the solicitation of an offer to buy any security or commodity. Messari does not guarantee the sequence, accuracy, completeness, or timeliness of any information provided in this report. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Prior to joining Messari, Chris was the Growth Lead at a Paradigm and a16z-backed gaming startup called LootRush. His primary focus is Consumer Products, Music x Crypto, Gaming, Digital Art, and market buying local tops.
Prior to joining Messari, Chris was the Growth Lead at a Paradigm and a16z-backed gaming startup called LootRush. His primary focus is Consumer Products, Music x Crypto, Gaming, Digital Art, and market buying local tops.