The following report was written by Messari Hub Analyst(s) and commissioned by Anchor Protocol, a member of Messari Hub. For additional information, please see the disclaimers following the article.
In the years following the financial crisis of 1907, a secret gathering took place on Jekyll Island off the coast of Georgia to plan the reform of the US banking system. This conclave was concerned about flaws in the financial system the crisis exposed - a wave of bank runs and bankruptcies caused by a loss of depositor confidence and exhaustion of banks’ liquidity. It was there that the foundations for the Federal Reserve System were laid out - and over a century later the creature from Jekyll Island continues to set the interest rates that prices the world’s financial assets.
Birthed from the clandestine halls of Terra Form Labs (TFL), the original Anchor whitepaper describes its ambitious goal of disrupting central banks by providing a decentralized central bank target rate which will become a reference rate for the broader DeFi ecosystem. The aspiring benchmark in question is the Anchor Rate, which this protocol is built around. Unlike lending rates in generic DeFi protocols, which vary per block depending on borrowing demand, the intention is that the Anchor Rate will depend on staking rewards from a diversified set of Proof-of-Stake (PoS) blockchains, which Anchor views as the true source of yield on-chain. This carries with it a number of properties that improve stability: 1) most PoS blockchains have a relatively fixed monetary policy, 2) the Anchor rate is not driven by the volatility of DeFi leverage cycles in the same way as generic DeFi lending rates.
Establishing a crypto-native “natural rate of interest” as a foundation for future crypto fixed income markets is a grandiose ambition - and the eyebrow raising fixed 20% stablecoin yield on deposits will set off the “Ponzi alarm bells” in the head of any self-respecting investor. But stranger things have happened in crypto… and after unpacking the mechanics, you might conclude that Anchor just might stand a chance of living up to its lofty aspirations.
How this economic machine works
Anchor only accepts a very specific type of collateral from borrowers in the form of bonded assets (bAssets) - liquid staking derivatives (via Lido Finance) on an underlying PoS token, such as bLUNA, which is backed by staked LUNA. These bAssets are fungible, and can be converted 1:1 to the underlying, excluding any slashing events that occur for the delegated validators on Lido’s whitelist (slashing risks are shared across all bAsset holders, reducing the idiosyncratic risks).
The Anchor Rate
The underlying PoS staking rewards for these tokens are converted to UST, which is then distributed to depositors depending on the amount of yield relative to the Anchor Rate. The Anchor Rate is the target deposit APY in the protocol. This was initialised as an arbitrary figure but will transition to a more precise calculation in future: the 12 month rolling weighted average of staking yields across the bAsset collateral deposited in the Anchor protocol, where each yield is scaled by the maximum loan-to-value (Max LTV) of the corresponding collateral type. Max LTV is the value assigned to each collateral type that determines the maximum one can borrow for every unit of collateral posted (set by governance, depending on the perceived stability and liquidity of that collateral).
The overcollateralization of loans effectively boosts the PoS yield available to lenders - for example, at genesis bLUNA had a Max LTV of 0.5, meaning a UST100 loan must be collateralized by UST200 of bLUNA. Therefore, were LUNA to yield 10% in PoS staking rewards, the example loan above effectively yields 20%.
Due to lack of diversification in eligible PoS assets at launch (only bLUNA was available), the Anchor Rate was first set at an arbitrary 20% and is currently a governance controlled parameter in the protocol as opposed to market determined via on-chain PoS rewards.Anchor aims to implement a market determined Anchor Rate when the protocol matures with sufficient deposit liquidity and PoS assets available. Borrowers are incentivized via ANC token rewards, as discussed later.
Open Market Operations
Anchor also defines a “threshold deposit rate”, which is the minimum effective deposit rate the protocol aims to keep when yields are below the target. Keeping the realised fixed deposit rate close to target Anchor Rate, as well as at or above the threshold rate is the main function of the protocol - it is supposed to function like an interest rate swap, converting floating rate cashflows into a stable fixed rate.
When the realised deposit rate is below the target rate, the deposit rate is subsidized via Anchor’s Yield Reserve and borrowing is incentivised through ANC token rewards.
In periods where the deposit rate realises above the target rate, excess yield accrues to the yield reserve and ANC incentives to borrowers decrease.
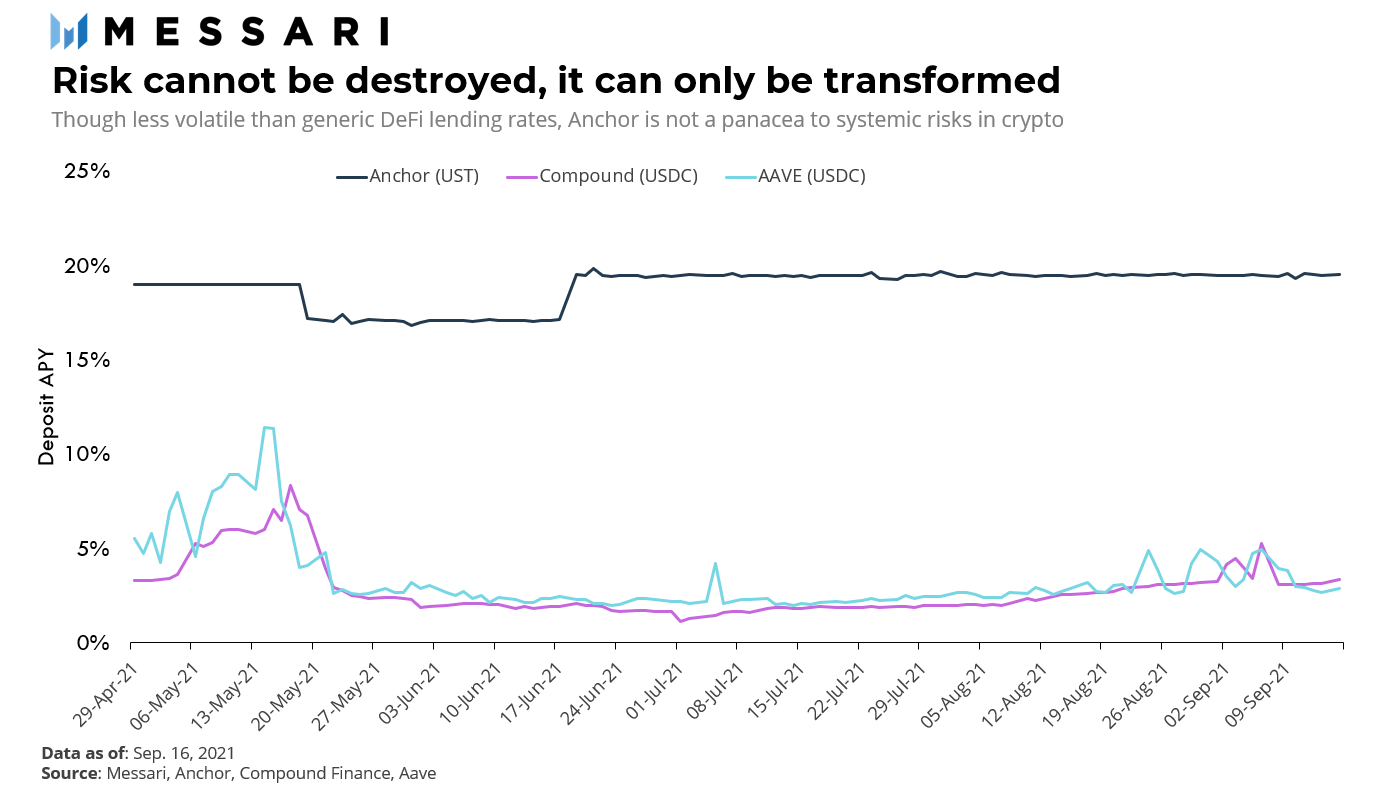
So far Anchor has managed to maintain a relatively stable deposit yield on UST. But although the rate has been far less volatile than stablecoin supply rates in traditional DeFi, it hasn’t been constant. The step change in the deposit rate following the flash crash in May highlights an immutable fact in finance - risk cannot be destroyed, it can only be transformed. And whilst traditional DeFi have variable rates as a release valve for the inherent volatility in collateral, Anchor is absorbing the volatility behind the scenes, releasing in a more abrupt manner when its shock absorbing capacity is breached.
Liquidations to backstop collateral values
Given the risks of accepting volatile crypto assets as loan collateral, liquidations play a key role in backstopping the protocol. When a loan becomes undercollateralized (when the asset price falls enough that the LTV rises above the maximum), liquidators are free to bid to exchange UST for the posted bAsset collateral at a discount to the oracle price (successful bids are executed over the counter). This protects depositors from defaults, and provides stablecoin liquidity to the protocol whilst derisking the loan book during periods of stress. Liquidation contracts enforce lengthy withdrawal periods to increase predictability of liquidation demand, an advantage over a traditional keeper system which relies on going to the market for bids on the collateral.
Anchor protocol is necessarily complex given its lofty goals, and its codebase has wisely been through audits by Cryptonics. However, there is no better test for a protocol than real time market crises.
Testing in prod
The system went through a live stress test during the flash crash in mid May 2021. The price of the LUNA token, which functions as a “seigniorage share” in maintaining the peg of Terra’s algorithmic stablecoin UST, saw a rapid decline over the course of May 19th. LUNA not only faced downward pressure from arbitrageurs looking to buy UST at a discount, but its decline also led to liquidations for leveraged borrowers on Anchor as their bLUNA collateral fell (leading to breaches of LTV limits). The negative feedback loop from this archetypal liquidation cascade not only caused a depegging of UST from 1 dollar but also saw the LUNA/bLUNA rates on Terraswap fall below 1 as liquidators looked to redeem their newly acquired bLUNA. This highlighted the nature of the risk in the protocol - economic relationships break down during periods of stress, when elevated trading frictions and congestion widen the limits to arbitrage. The more layers of complexity a protocol relies on in order to function properly, the more potential points of failure during black swan events.
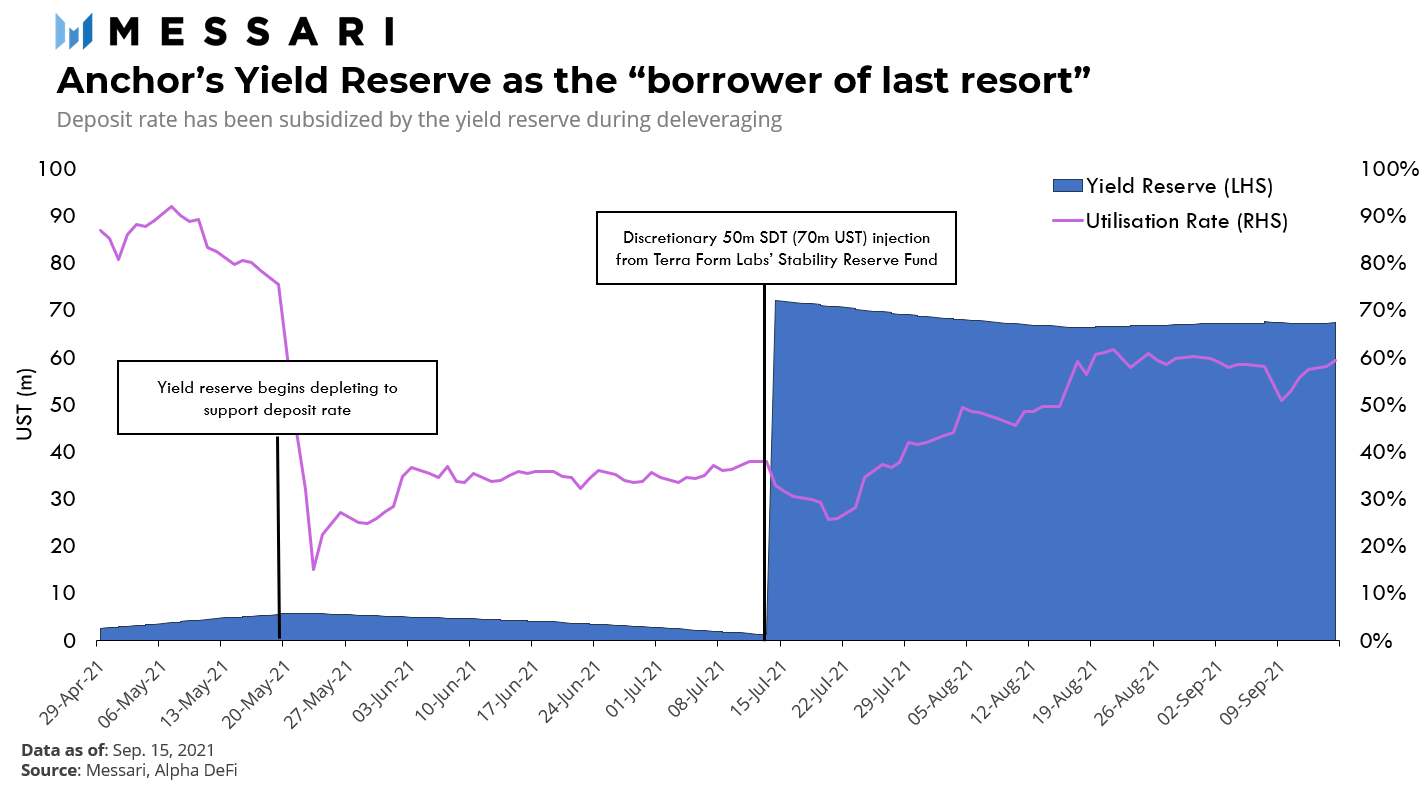
Despite the extreme circumstances in May 2021, Anchor’s deposit rate itself largely behaved as it was designed. As the utilisation rate fell with the collapse in demand for borrowing, so did the “organic” yield made from borrowers collateral, leaving less available to distribute to lenders. Once the deposit rate fell to the threshold level, Anchor began subsidizing the difference via its yield reserve. This continued to maintain a stable deposit rate whilst borrowing demand was subdued - the yield reserve fell from 5.5m+ UST after May 19th down to the 1.1m UST level by the beginning of July 2021. On July 7th, Terra Form Labs announced they would step in to capitalize the yield reserve with 50 million SDT (~70m UST) from their $1bn+ Stability Reserve Fund, which emphasized the importance of Anchor in the Terra ecosystem and TFL’s commitment to the protocol. They estimated this would be a one-off intervention which would provide the runway for Anchor to introduce upgrades that would make it more self-sustainable. Though subsidies to the deposit rate from the yield reserve continued into July, borrowing demand began to pick up again and August saw the utilisation rate rise from the 35% level to 60%, at which point excess yield from borrowing began to replenish the yield reserve organically.
Roadmap
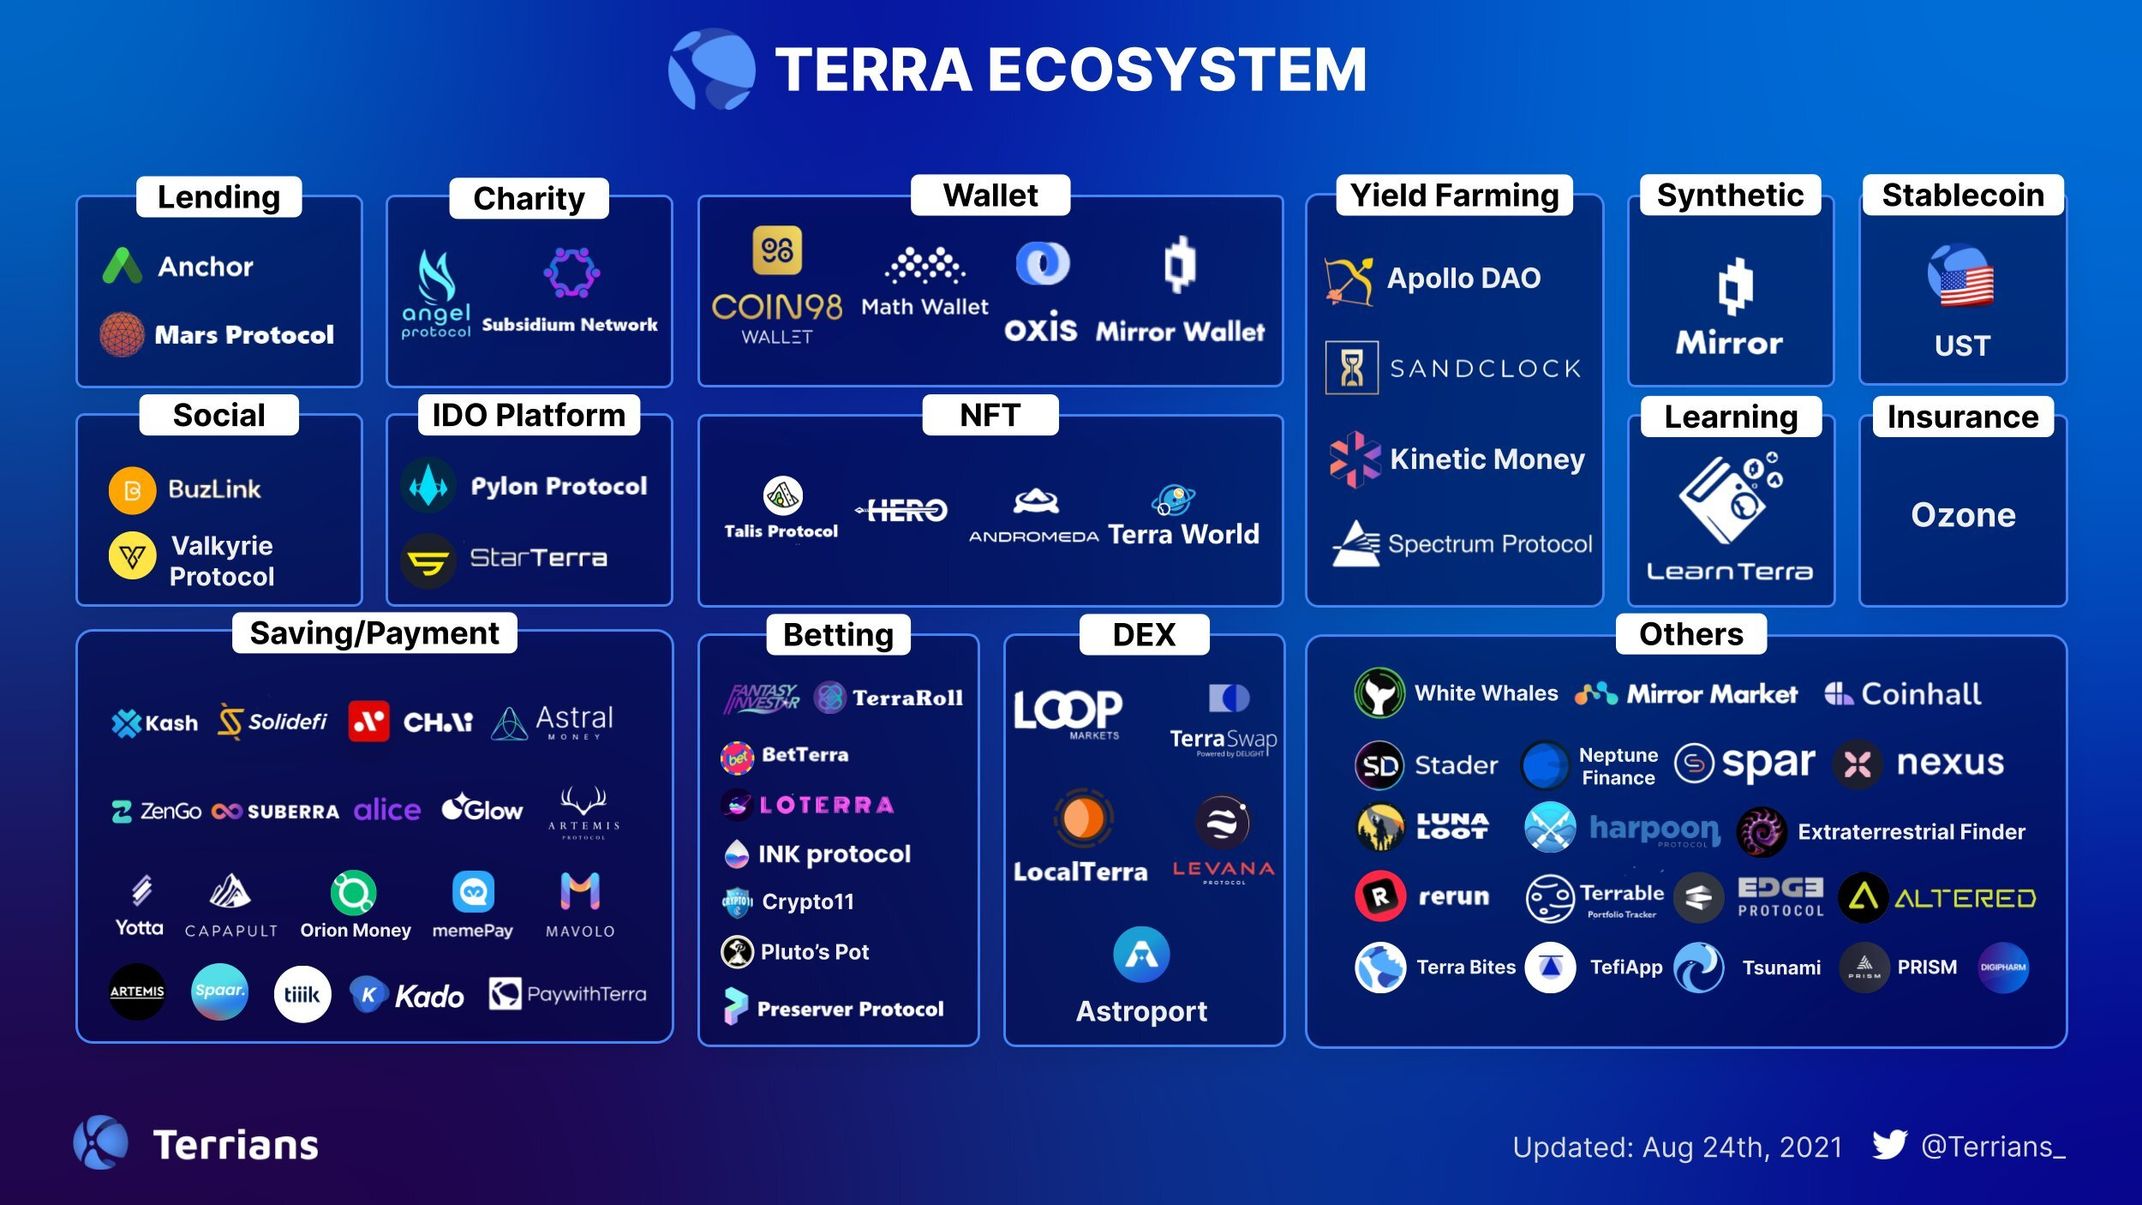
TFL have made no secret of their desire to create use cases for UST, specifically across savings, payments, and investments. Following Mirror Protocol’s launch earlier in 2021 to address the investment options within the Terra ecosystem, Anchor is the next step by providing a savings protocol for the #LUNAtics community.
For the Anchor Rate to reach its goal of becoming the benchmark on-chain interest rate, its collateral base must be representative of available blockchain staking rewards. Its first step in diversifying eligible collateral was deploying bETH on Anchor at the beginning of August - a Lido staking derivative backed by ETH 2.0. Not only does this diversify the collateral base but it also unlocks cross-chain borrowing demand, something which Anchor looks to further bolster via the inclusion of bATOM, bSOL, and bDOT going forward.
The events in May also inspired a number of other tweaks, including:
a new liquidation queuing mechanism designed to incentivize more competitive bids for liquidations (reducing discounts at which collateral is procured during distress).
a change in a number of governance parameters including Max LTV and the maximum liquidation discount (which should reduce downward pressure on bAsset prices following liquidation).
improved notifications for at risk loans to enable more timely reduction of LTV for borrowers (e.g. Telegram, mobile functionality).
the flexibility to deploy unutilized deposits into other yield generating protocols such as mars protocol and mirror protocol.
the transition of the Anchor Rate from its initial form as a fixed governance-set parameter to a floating rate, adjusting algorithmically every 6-months based on related on-chain metrics.
Oracles will be prioritised in the mempool following Terra’s Columbus-5 upgrade which will prevent stale pricing issues during periods of congestion.
ANC tokenomics
The ANC token is designed to capture a proportion of the yield available and to scale with the assets under management in the protocol. 10% of the flow into the Anchor Yield Reserve from protocol fees paid in UST are used for ANC token value accrual. Sources of fees include: a portion of rewards from deposited bAssets, excess yield above the target deposit rate, collateral liquidation fees, and ANC deposits from governance polls which fail to reach quorum. UST is swapped for ANC in the open market which is then redistributed pro rata to ANC stakers.
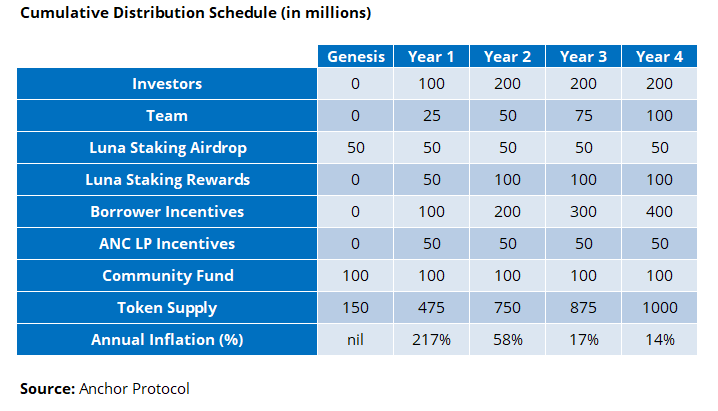
ANC is also used as borrower incentives (100m per year) as well as rewards within ANC liquidity pools. ANC token supply is capped at 1 billion, to be distributed over 4 years since genesis of the protocol in April 2021 via the below schedule:
Competition
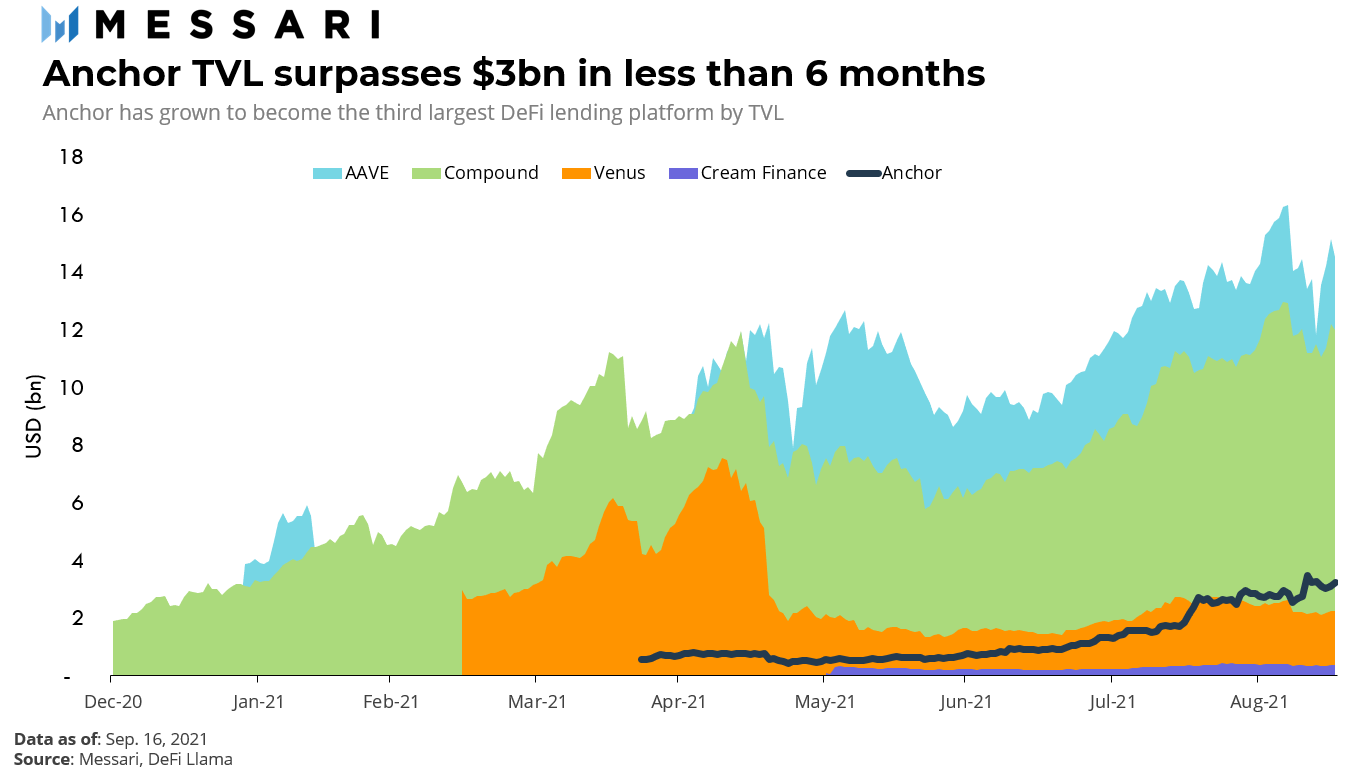
Driven by Anchor’s high headline fixed deposit rate, Terra’s comparatively low costs versus Ethereum mainnet, as well as the strong run up in LUNA’s price, TVL has continued to increase since launch and in August it surpassed Cream Finance and Venus protocol to become the third largest lending platform behind Compound and Aave.
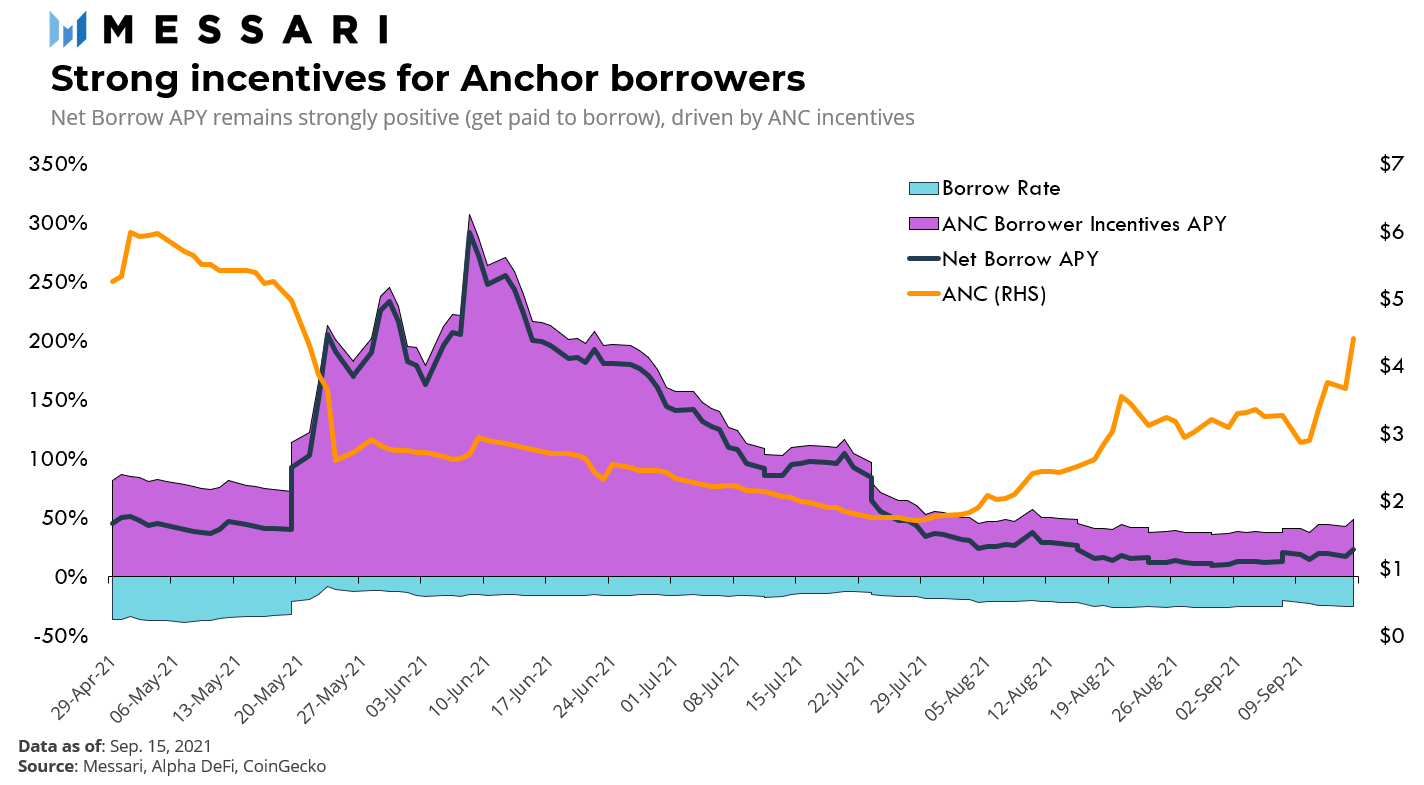
However, the true litmus test for Anchor’s long term viability is building a sustainable loan book, which ideally involves long term borrowers with stable cash flows that are independent of the token prices of underlying bAsset collateral. At this early stage, the majority of demand for borrowing on Anchor is still for speculative purposes (as with most other DeFi lending projects), so over the long term the protocol needs to continue working towards separating itself from the vulnerabilities of crypto leverage cycles in order to remove reliance on their yield reserve for defending their fixed deposit rate. Whilst Anchor’s headline yield has unarguably been competitive, it is unclear that borrowers are better served through this protocol than other sources - standalone borrow rates are still relatively high. Though this has so far been offset by ANC incentives - Net Borrow APY after ANC rewards has been strongly positive to the extent you could have got a higher yield from borrowing on Anchor than as a depositor - this is not a long term solution that will lead to sustainable loan growth from “the right kind of borrowers”.
There are a number of additional routes for Anchor to gain traction. Their JavaScript SDK allows financial institutions to integrate Anchor Protocol “with 7 lines of code or less”, which has already led to FinTech firms using it for “plug-and-play-savings” (including Y Combinator’s Yotta Savings). Interoperability across blockchains was initiated via Orion Money in the summer, which gave stablecoins outside of Terra access to Anchor. Terra’s imminent Columbus-5 upgrade will open it up to the Cosmos ecosystem via its Internet of Blockchains (IBC), and multichain accessibility for UST is expected to increase further via Wormhole V2. These are a sample of the opportunities for Anchor to capture market share.
Conclusion and key takeaways
The ambitions of the Anchor project are wide-ranging, with the potential to have deep and meaningful implications for the future of DeFi and its role in the broader financial world. With TFL’s commitment to Anchor as a cornerstone of their grand plans for the Terra ecosystem, the formidable early traction looks set to continue. But Terra founder Do Kwon has been vocal about TFL’s role as a “transient aberration” - their medium term goal is to step back and let the community run the ecosystem in a decentralized manner. The real tests for Anchor lie beyond this honeymoon period of TFL recapitalizations of the yield reserve, bootstrapping borrower incentives, an arbitrarily determined Anchor Rate, and pre their diversification of collateral. The crypto community, Wall Street, and Main Street will all be watching its progress with great interest.
Disclaimer: On Feb. 16, 2023, the SEC stated that LUNA and UST are "securities". A couple notes: (1) Messari does not provide financial or trading advice - our services are for informational purposes only; and (2) Messari's services are impersonal - do your own due diligence. Please refer to ourTerms of Usefor more info.
On March 9, 2023, the State of New York alleged that LUNA and UST are "securities". A couple notes: (1) Messari does not provide financial or trading advice - our services are for informational purposes only; and (2) Messari's services are impersonal - do your own due diligence. Please refer to ourTerms of Usefor more info.
This report was commissioned by Anchor Protocol. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.