Radiant Capital: A Novel Approach to the Lending Market

Update: on January 2, 2024, Radiant Capital's USDC market deployment on Arbitrum was exploited, resulting in a loss of ~1.9K ETH.
Radiant Capital is an omnichain money market protocol, enabling users to borrow and lend assets on Arbitrum and BNB Chain. The project implemented its v2 upgrade and associated mechanism changes in Q1 2023. Together with accelerated interest from crypto Twitter at the time and major CEX listings in March, TVL increased notably from ~$100M at the beginning of 2023 to ~$670M at the end of April. Accordingly, the price of the native token, RDNT, also increased by ~10x, with the project reaching an FDV of ~$470M in the middle of April. However, the trend reversed, and the price has steadily moved in a downward direction. RDNT is priced at ~$0.23 as of October 3, which values the token at a market cap of ~$79M and an FDV of ~$240M. Interestingly, the project’s value metrics, such as revenue and utilization, have been relatively stable, although the price of RDNT has decreased. This implies that a change in fundamentals didn’t mainly drive the price change but could signal that the token was overpriced following the increased attention the project received.
Protocol Performance
In short, Radiant Capital allows users to deposit assets to be borrowed as well as borrowing collateral on either Arbitrum or BNB chain. A borrower can then use their collateral to borrow assets on any EVM chains that are supported by Stargate Finance. Radiant’s native token is constructed on top of LayerZero’s interoperability standard, and the protocol leverages Stargate’s Stable Router. This means that tokens transferred across chains are native, and Radiant doesn’t have to rely on third-party bridges. For an in-depth analysis of Stargate and its v2 upgrade, see this report we recently published.
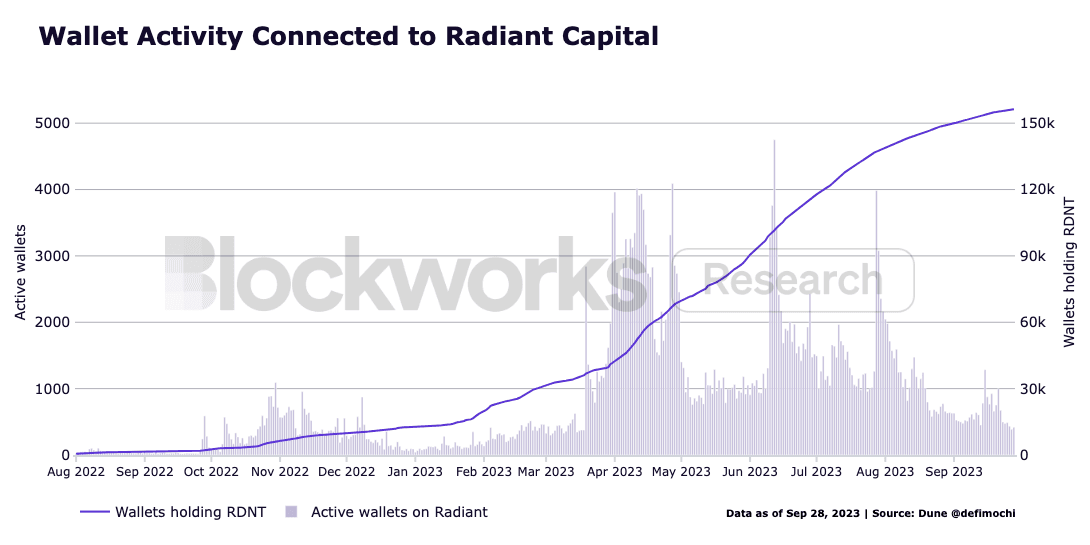
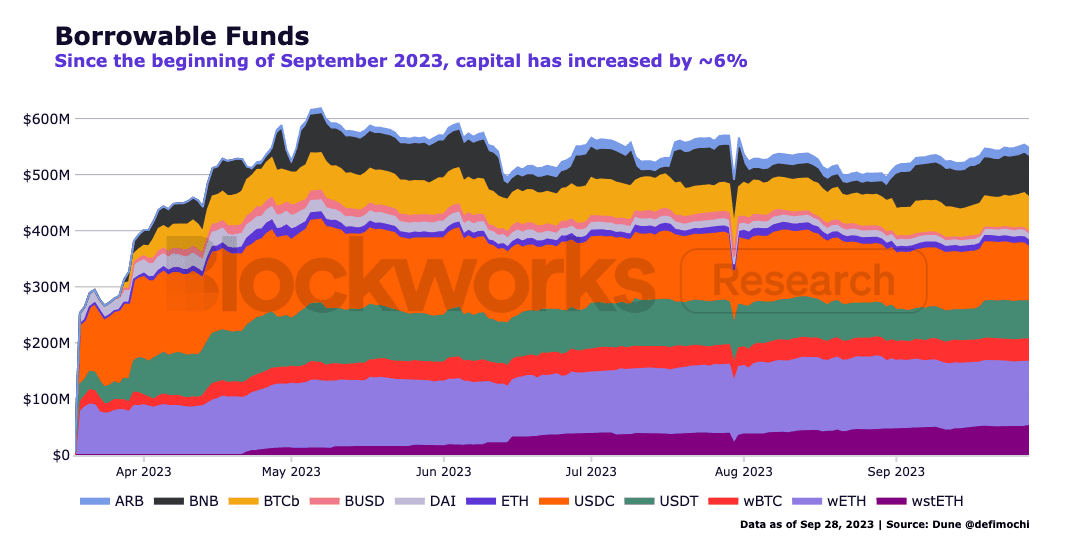
As mentioned earlier, Radiant received vast visibility on crypto Twitter at the beginning of the year and was listed on several major CEXs in March 2023. This led to the number of active addresses rapidly increasing at the end of Q1 2023 and the beginning of Q2 2023, but the platform hasn’t retained similar figures since then. More alarmingly, the number of addresses has somewhat dropped since the end of August 2023 to levels not seen since the middle of March 2023. Despite this, the value of borrowable assets deposited at Radiant has remained relatively stable, although down from the top of ~$620M at the beginning of May to ~$550M. This implies that capital on the platform is sticky, likely as a result of Radiant’s tokenomics structure, which incentivizes users to become token holders as well as long-term alignment between token holders and the protocol.

Brick leads coverage on Aevo, Chainlink, and MakerDAO. Previously he worked in investment banking as a sector-agnostic M&A and ECM advisor.