Q3 Protocol Outlooks


Our final Q2 report focuses on the evolution of DeFi assets during a bear market and explores the upcoming developments of major protocols.
It’s been a long struggle for DeFi from the days of Maker dominance, through DeFi summer led by Synthetix and Compound, during the false hope of “DeFi 2.0” and unstable stablecoins, and now the revival of the OGs primitives. Throughout that time TVL was used as the best measure of success.
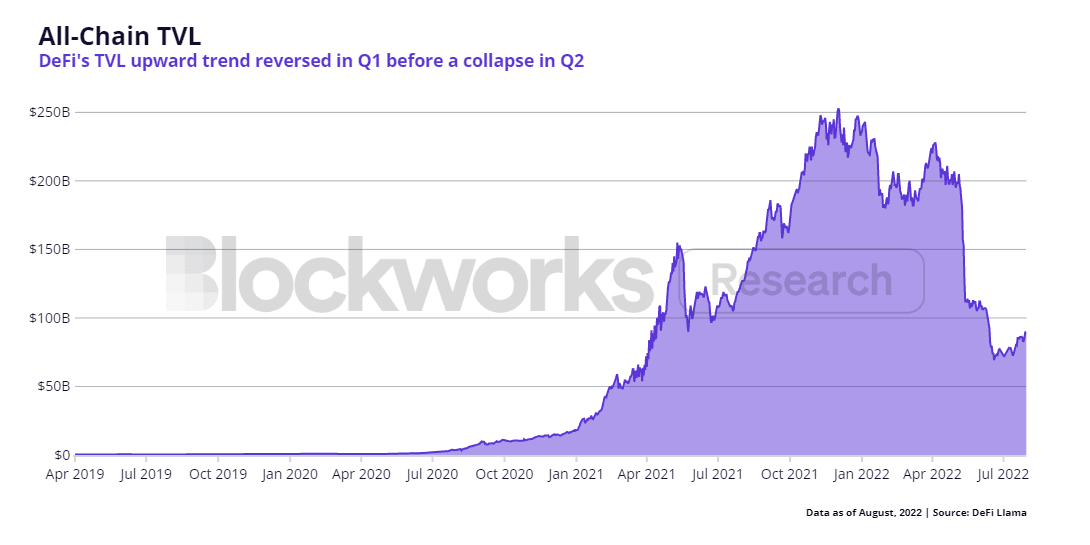
As users were attracted through unsustainable inflationary native token rewards, TVL lost its usefulness as an indicator of product market fit (PMF). Users aped into projects to farm and dump their earnings. Once the rewards slowed or ceased, users left. Falling token prices meant that the promised APYs became unrealizable. TVL in Q2 plummeted.
One project paid out 14.7 times the original allocation within the first five months of launch, driving TVL to an all-time high by YE 2021. As the emissions rate fell to double-digit annualized inflation, TVL fled. Monthly rewards fell 99% from a high of $20 million per month to $200,000 by the end of Q2.
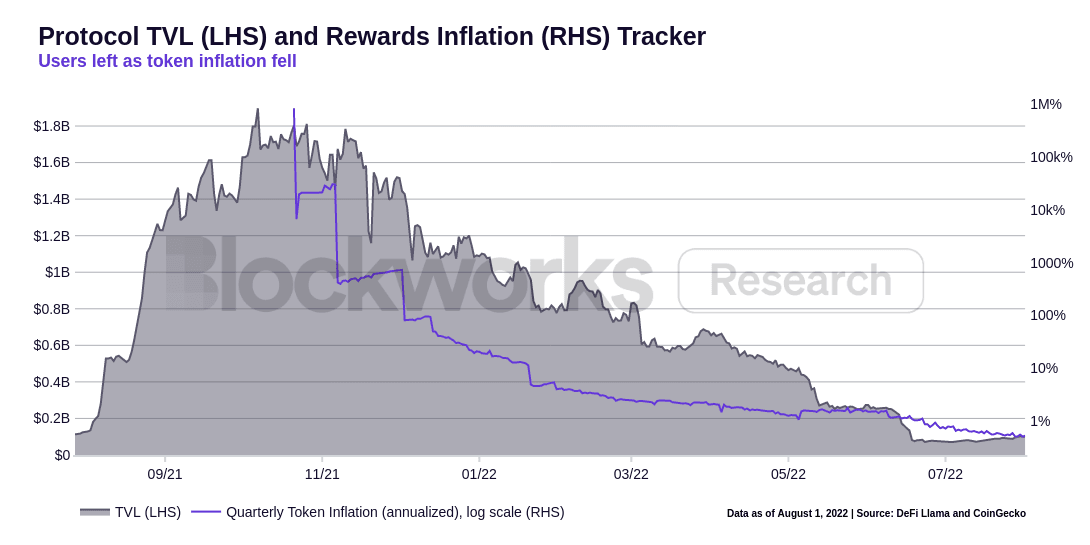
PMF can be better measured by how much users are willing to pay for the services. Temporary rewards can help with customer acquisition costs, but protocols need users to remain once incentives end.
Westie leads coverage on Ethereum, L2s, and Synthetix. Previously he worked in public sector technology Consulting at Guidehouse.
Pibblez leads coverage on emerging L1s, infrastructure, and stablecoins. Previously worked as a Research Analyst at Kraken.
Matt leads coverage on DEXs, derivatives, governance, and the Avalanche ecosystem. Previously he worked as an Analyst at Ikigai Asset Management and Teller Finance.