Q2 Report Part 2: Network Coverage, Layer 1s and 2s


In spite of the macro headwinds and abysmal price action, layer 1 (L1) blockchains continued development throughout the second quarter. The Blockworks Research Q2 Network Coverage Report discusses both the hardships and innovations from each network covered by our team.
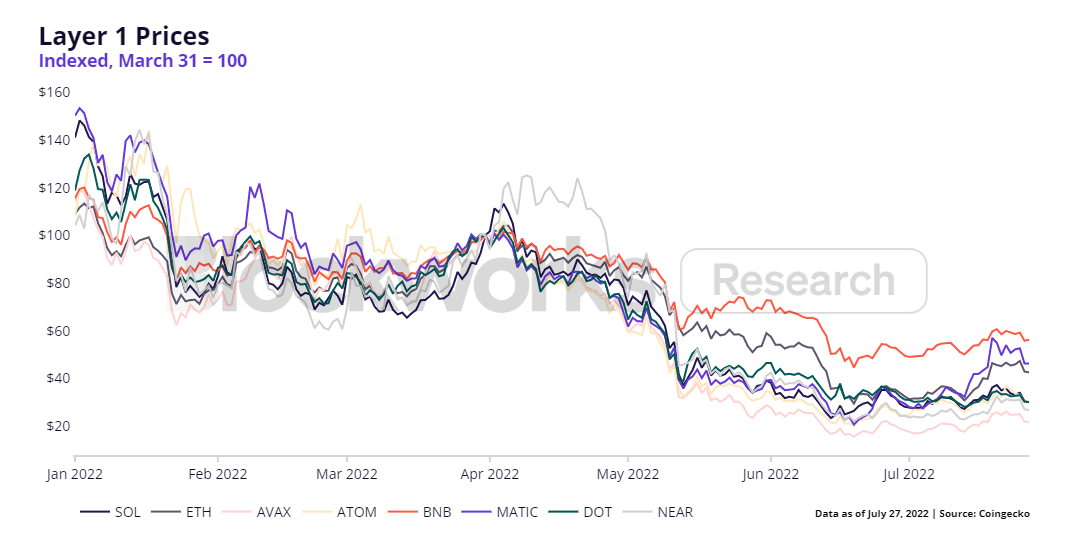
Layer 1 and 2 (L2) token prices fell more than Bitcoin in Q2, continuing Q1’s bear market. While most of the native tokens were directly correlated, AVAX took the hardest hit overall as its ecosystem TVL dropped immensely and the C-Chain’s primary application, Crabada, moved to its own subnet. NEAR was able to outperform in the small market rally in April as a result of DeFi protocol launches but was unable to sustain as prices drove lower. At the beginning of Q3 we finally saw an uptick in prices, with MATIC leading the way as a result of their partnership with Disney and their zkEVM announcement. We will see if this rally continues in the face of continued macro headwinds.
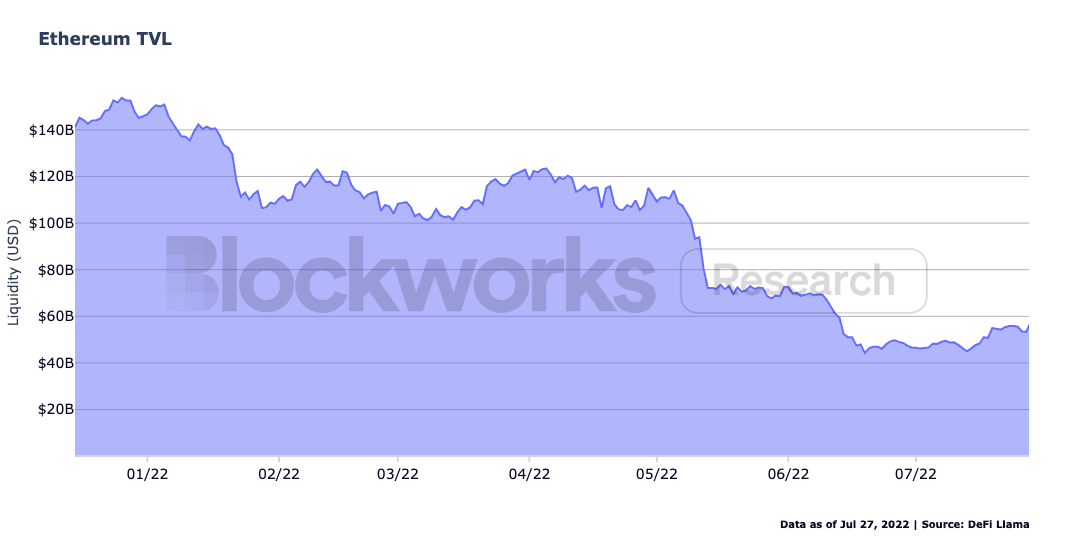
Ethereum TVL declined nearly 63% since the start of the year. On the other hand, TVL denominated in ETH hardly budged on the quarter and ETH TVL dominance remained high with 60-64% market share, demonstrating that Ethereum is holding its own against the challengers.
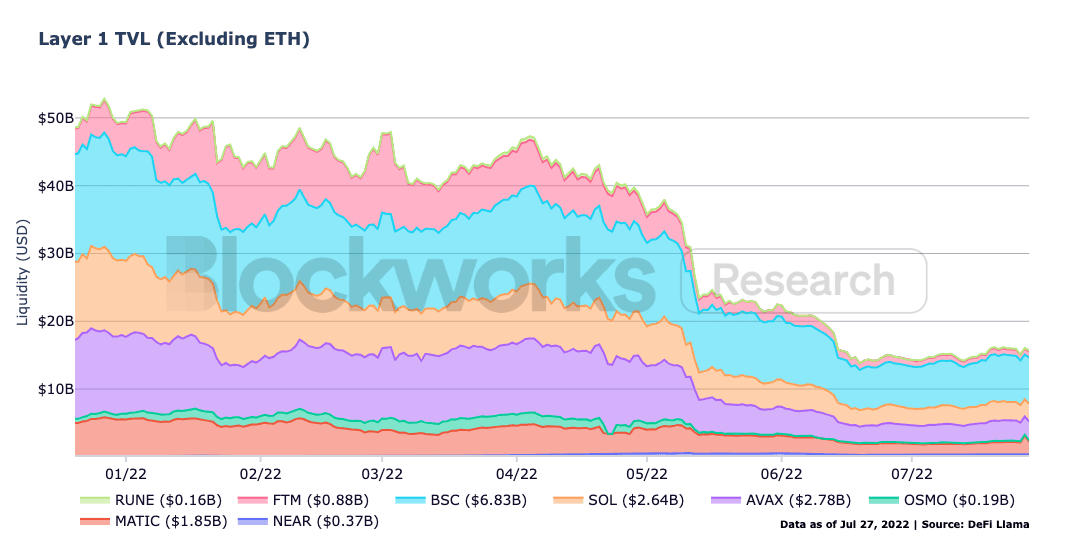
The venture capital “Ethereum killer” L1 networks, such as Avalanche, Solana, and NEAR, experienced their own brutal drawdowns, with most networks losing around half of their TVL. Nothing performed as poorly as Terra, which lost $32 billion in TVL from April’s high as UST and the LUNA token collapsed to near zero.
Pibblez leads coverage on emerging L1s, infrastructure, and stablecoins. Previously worked as a Research Analyst at Kraken.
Sam leads coverage on Ethereum, L2s, Aave, Compound, as well as NFTs and gaming. Previously worked on a hedge desk at UGC.
Dan leads the build out of the Analytics product, spending most of his time with onchain data.
Matt leads coverage on DEXs, derivatives, governance, and the Avalanche ecosystem. Previously he worked as an Analyst at Ikigai Asset Management and Teller Finance.