The following report was written by Messari Hub Analyst(s) and commissioned by the Perpetual Protocol, a member ofMessari Hub. For additional information, please see the disclaimers following the article
Since the first account of a derivative contract was recorded by Aristotle in 300s BC, financiers have created thousands of financial instruments to serve a common purpose: to allow speculators to obtain higher returns and businesses to protect their bottom lines. This important counterplay has resulted in an astounding $560 trillion market today.
In 1992, American economist Robert Shiller introduced a completely new derivative: perpetual futures. However, his idea only came into fruition when cryptocurrency exchange BitMEX developed the instrument for cryptoassets in 2016. A perpetual futures contract is a standardized agreement to buy or sell an underlying asset. The key difference with traditional futures is that there is no settlement date. Instead, perpetuals do not expire and remain effective until the trader closes their position. This allows traders to speculate on the future price without having to own the underlying asset. And by using leverage, traders can get exposure to the underlying with only a part of the total value in collateral or margin.
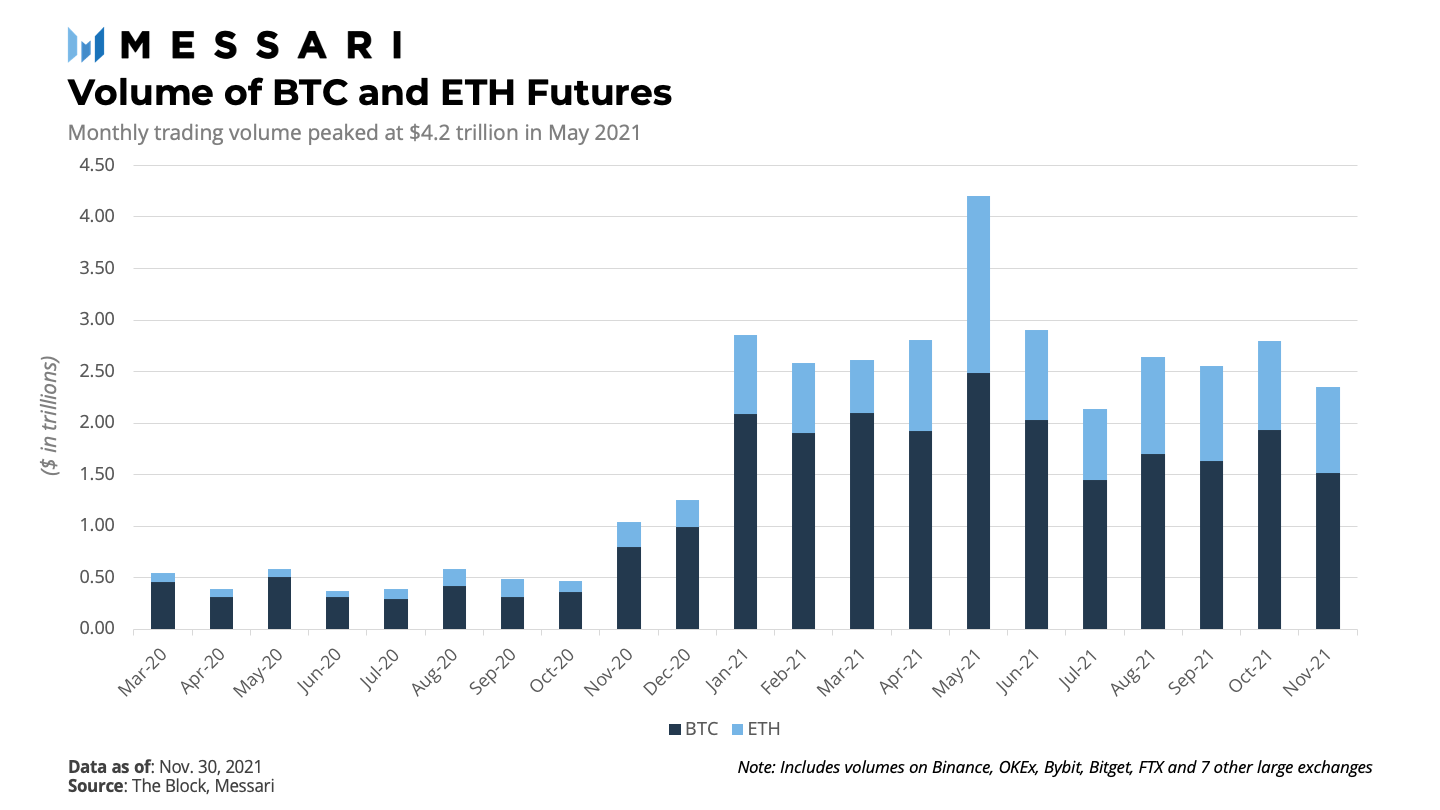
Thanks to its benefits over traditional products, perpetual futures have become one of the most popular financial instruments in the industry today. This is clear when we look at the evolution in trading volumes. Monthly volume of BTC and ETH futures across major centralized exchanges reached its peak at $4.2 trillion in May 2021. After markets calmed down, volumes have remained steady around the $2.5 trillion level.
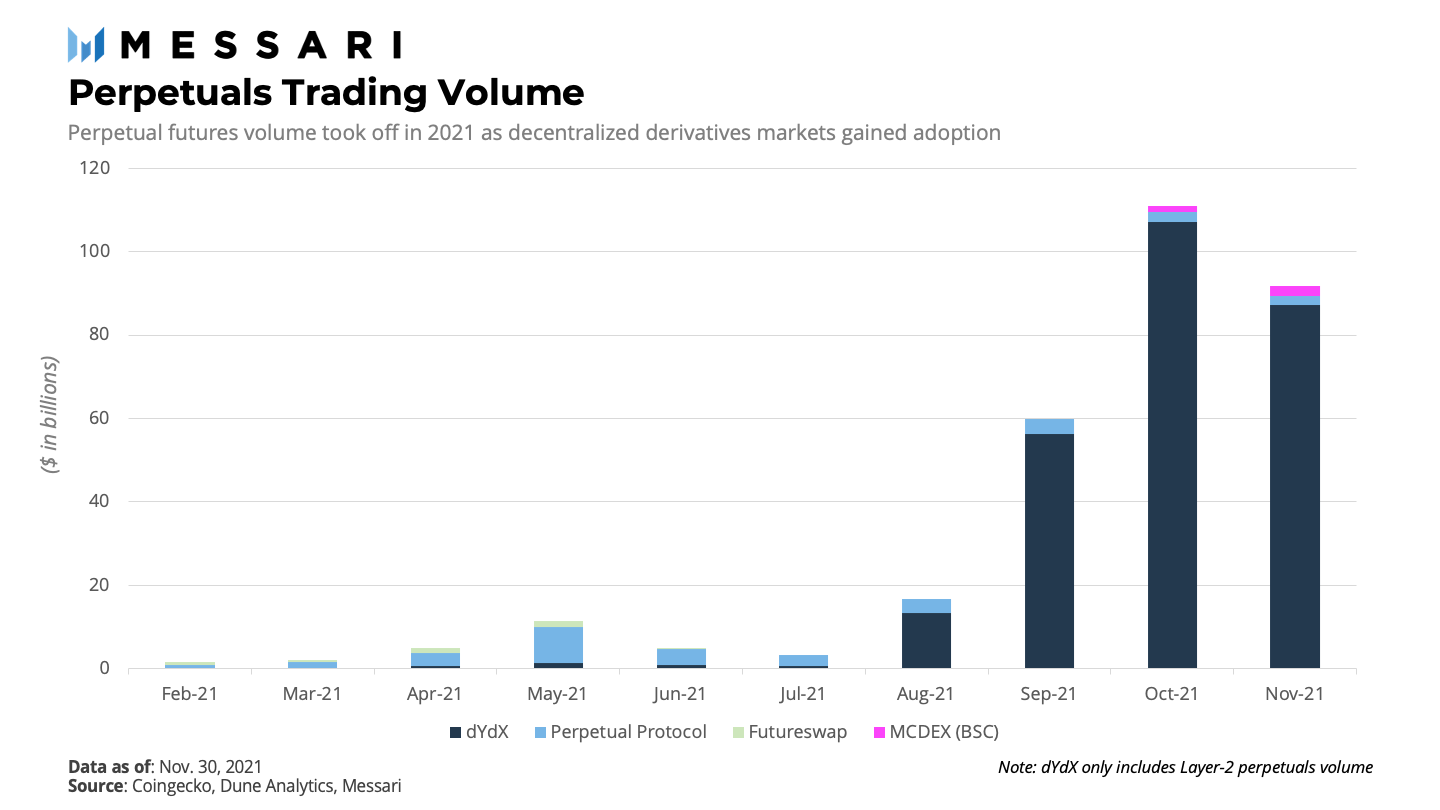
Turning to decentralized finance, we find a similar trend. Decentralized perpetuals reached nearly $11 billion in volumes in May 2021. That is almost a 2.5 times increase month-over-month and more than a 60 times increase from November 2020. Despite the increasing adoption, decentralized perpetuals represent only 1.3% of derivatives volume compared to its centralized peers at the time of writing. On the flip side, this also means there is still significant upside for the segment. Will Perpetual Protocol be able to capture this opportunity?
What is Perpetual Protocol?
Launched on the xDai chain in December 2020, Perpetual Protocol quickly became one of the leading decentralized perpetuals markets. The protocol supports up to 10x leverage and allows users to trade across 15+ markets. In less than a year, over $32 billion in volume has been traded on the platform. This ranks the protocol second in terms of trading volume in its category after market leader dYdX at $278 billion. And with $32 million in fees generated, the protocol is 15th in terms of cumulative revenue across top dApps and blockchains. To fund all this growth, the team raised a $1.8 million seed round led by Multicoin Capital in August 2020. Prior to the seed round, Binance Labs invested in the early stages of the project.
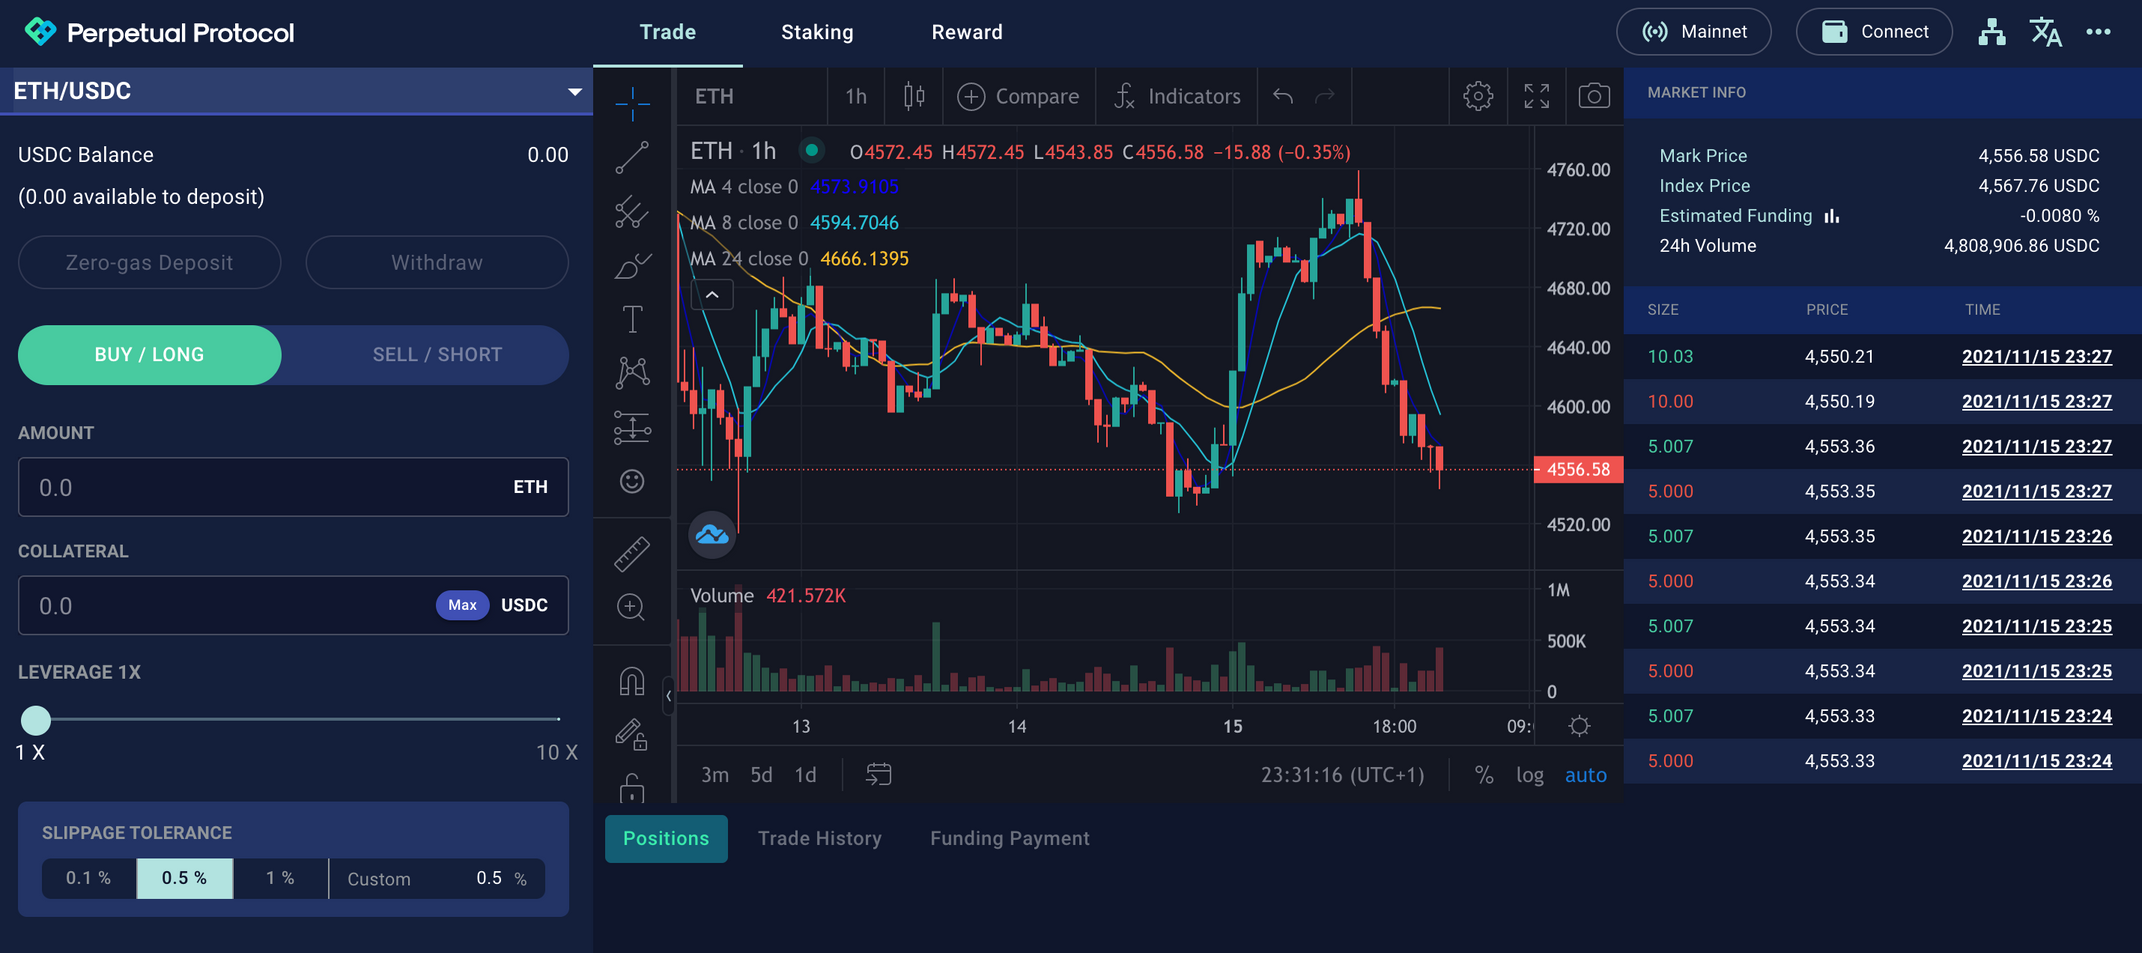
One of the key success factors for Perpetual Protocol was pioneering as the first derivatives platform launched on a sidechain. Betting on Layer-2 solution xDai, Perpetual Protocol could initially offer much lower gas fees and higher transaction speed than its peers. With the large adoption of scaling solutions this year, we all know how this bet ended up. In addition, its intuitive interface and robust trading tools are designed to attract seasoned traders, which represents the most important segment of the project’s user base.
To facilitate trading in the DeFi space, Automated Market Makers or AMMs are often used. The most famous example is Uniswap, which utilizes the constant function x*y=k to determine the price of the asset and facilitate the swap. Despite the sheer amount of innovation in this space, AMM models are focused on serving spot trading and cannot easily be applied to derivatives. The reason for this is that derivatives products typically involve short selling and leverage. While it is possible to make AMMs compatible with derivatives by allowing traders to borrow from liquidity providers, this exposes the market makers to high impermanent loss. Another shortcoming is that the open interest will be bound by the pool size when incorporating leverage on traditional AMMs.
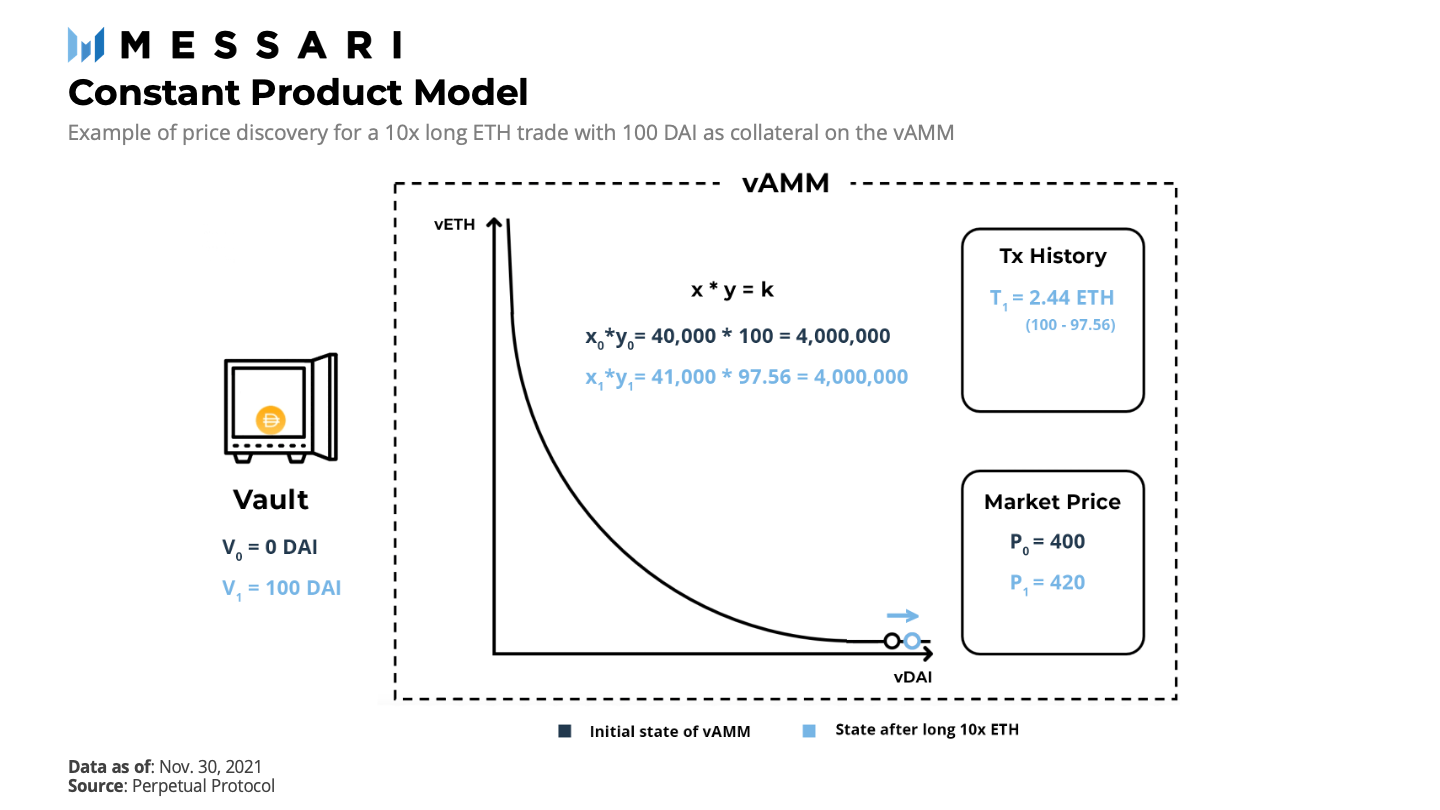
To solve these issues, Perpetual Protocol introduced an entirely new model called the Virtual Automated Market Maker or vAMM. This model uses the same constant product formula as Uniswap, but no real assets are stored inside the vAMM itself. Instead, the tokens are sent to a clearing house, which stores the collateral in a smart contract vault and uses the vAAM solely for price discovery. The amount of ETH/DAI and DAI set in the vAMM, for example, are therefore not real tokens. These virtual tokens are just used as the variables in the constant product formula to calculate the price of the derivative. This allows the use of leverage and removes the need for liquidity providers.
As prices are determined by the vAMM, the price on Perpetual Protocol, or the mark price, and the average price from major exchanges, or the index price, are not the same. A time-weighted average price or TWAP is taken for both prices. The index price is derived from Chainlink, which the team believes is the most battle-tested oracle. To converge the two prices, funding payments are used to incentivize traders to take long or short positions. When the mark price exceeds the index price, the funding rate is positive and long traders pay short traders. The opposite happens when the index price exceeds the mark price. Funding payments are calculated and exchanged amongst traders hourly on Perpetual Protocol.
Another key part of leveraged trading is liquidation. When you trade on leverage, you are essentially using collateral to borrow money from the exchange to purchase an asset. If the value of that asset falls, your losses begin to approach the value of your margin and this puts the exchange at risk. To prevent your position from being under-collateralized, the exchange will proactively liquidate your position. On Perpetual Protocol, partial liquidations are used. As long as the ratio between the asset value and the margin is above 2.5%, only a quarter of your position will be liquidated. Once the margin ratio falls to 6.25%, the total position is liquidated. These liquidations are triggered by keeper bots, who earn 1.25% of the remaining position.
To protect their protocols against unexpected events, perpetual platforms typically set up insurance funds. Perpetual Protocol stores half of the revenue generated from trading fees in its fund. There are two distinct situations when the insurance fund has to step in: (1) to cover a loss from a bankrupt position that was not liquidated in time and (2) to pay the funding payments that could not be met by one side of the trade. The second can happen when there are more participants on one side of the trade than the other and the open interest becomes skewed. If markets are bullish and the shorts have to pay the longs, for example, the small short side cannot make the funding payment to the large long side. In this case, the insurance fund has to step in to make the funding payment. Conversely, if the longs have to pay the shorts in bullish markets, the insurance fund receives the extra funding payments.
Tokenomics
The PERP token acts as the utility token for the Perpetual Protocol ecosystem. Issued by the Perpetual DAO, the ERC-20 token is designed to facilitate and incentivize the decentralized governance of the protocol. The token has three key use cases:
Governance: Holders can stake their PERP tokens to vote on or propose new ideas to improve Perpetual Protocol. Community proposals will be high-level at first and are implemented by the Perpetual Protocol team once passed.
Staking: PERP holders can lock up their PERP for a fixed amount of time in the staking pool. The staked tokens can be sold by protocol if the insurance fund becomes depleted in extreme market conditions. In return for locking up tokens and bearing this risk, stakers receive rewards each week.
Backstop: The native token acts as an ultimate backstop of the system in extreme market conditions. If the insurance fund is unable to cover unexpected losses, the protocol will mint new PERP tokens and immediately sell them for collateral to keep the system solvent.
To incentivize governance participation and create an ecosystem surrounding the protocol, the following incentive structure has been designed:
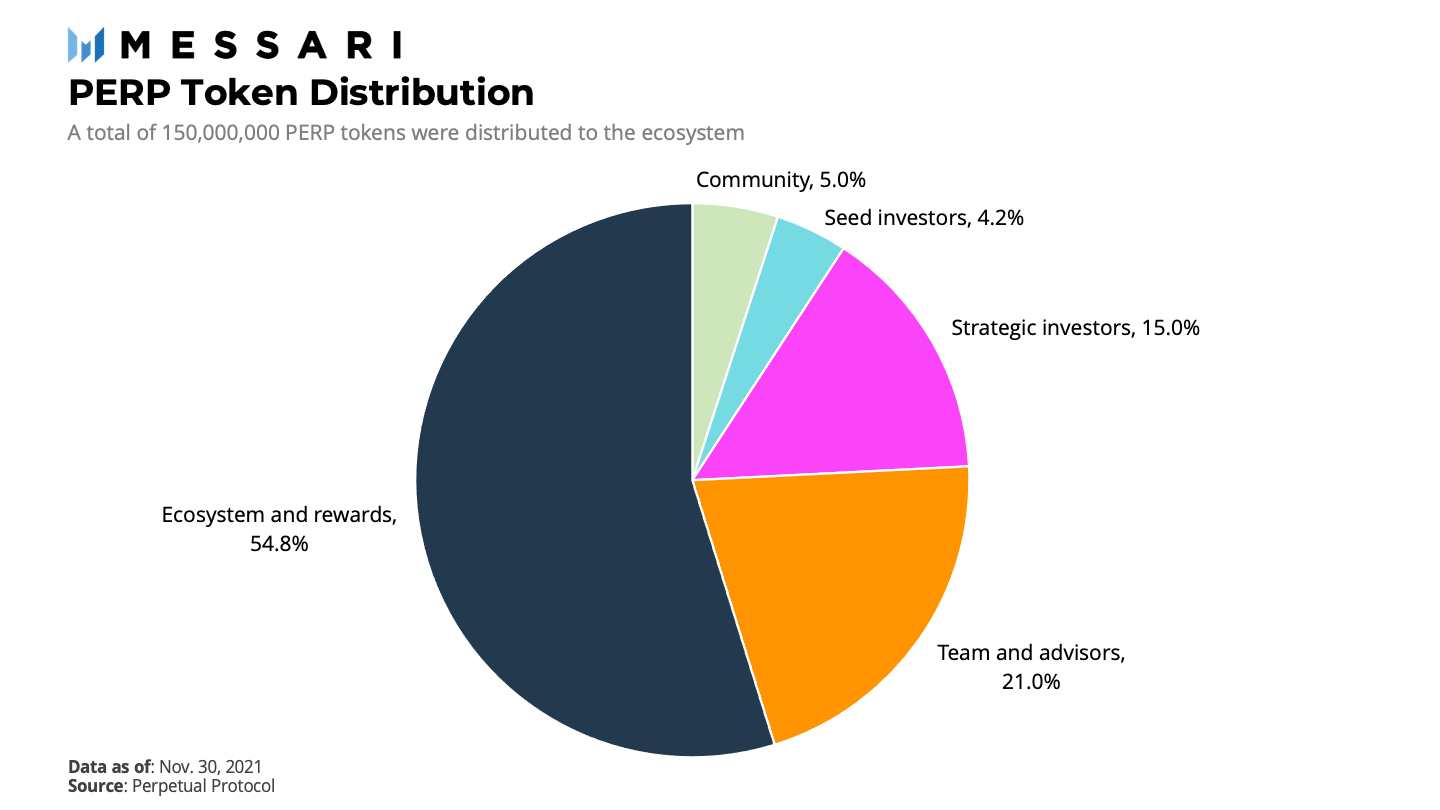
A total of 150,000,000 PERP tokens were distributed at genesis to the community, the investors, the team, the advisors, and the ecosystem. The community got access to PERP through the Balance Liquidity Bootstrapping Pool held in September 2020. The initial distribution was as follows:
Perpetual Protocol v2: Curie
Taking over the decentralized perpetuals market by storm in the past half-year, Perpetual Protocol announced its first major update “Curie” - named after the renowned scientist. Marie Curie was the first woman to win the Nobel Prize and the only person ever to win the esteemed prize twice. Similar to how her work impacted the fields of science, the team seeks to lay the foundations for DeFi with Perpetual Protocol v2.
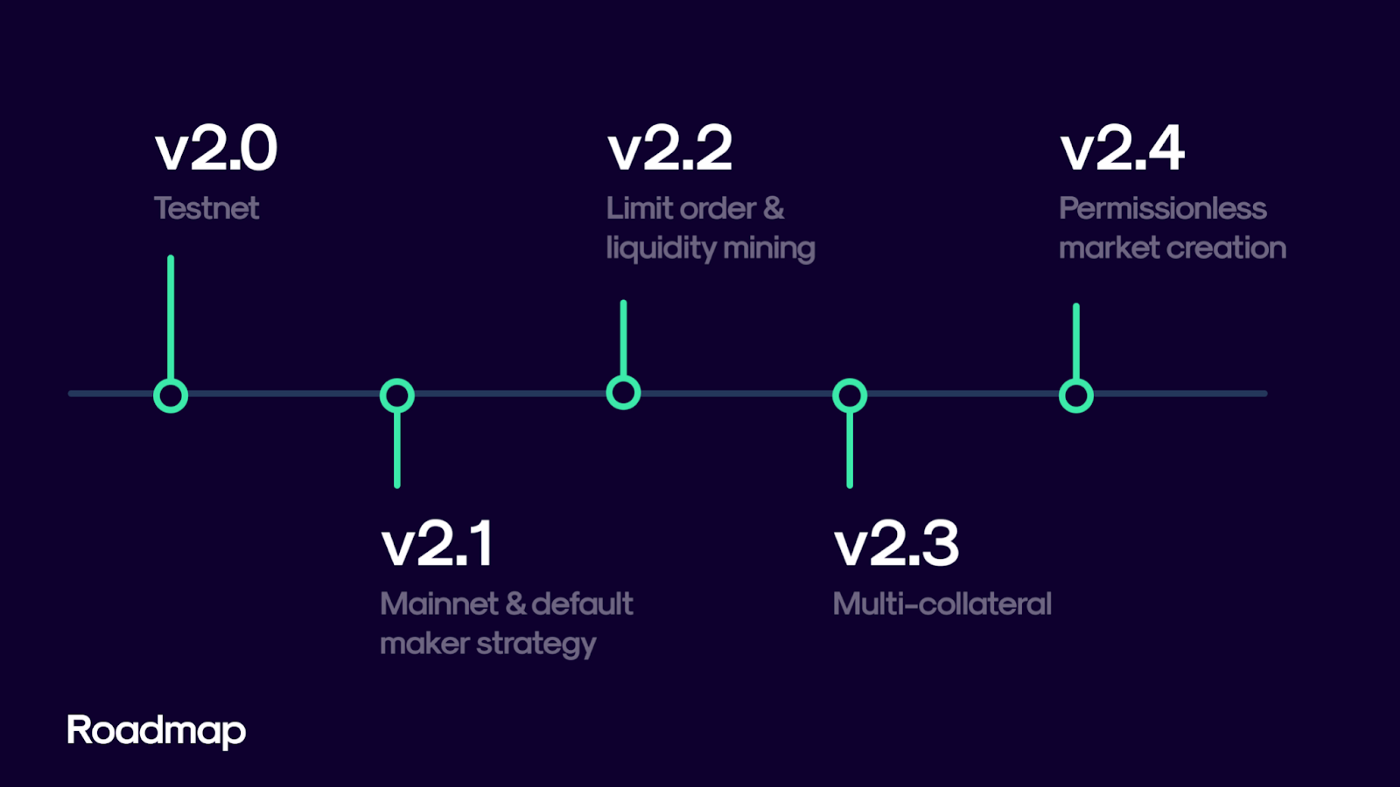
Launched on Optimism last month, Curie introduces concentrated liquidity, permissionless market creation, cross-margin and multi-collateral assets, and revamped tokenomics. At the same time, the project is launching a developer grants program to further drive adoption in its ecosystem. With these modifications, the team wants to stack up to established competitors such as FTX and leverage the composability of blockchain technology. The v2 Mainnet was launched on November 30 and the remainder of the upgrade will be rolled out as follows:
In the first version, Perpetual Protocol pioneered the vAMM model which combined virtual tokens with the popular constant product model. As we have seen, this enabled the use of leverage and removed the need for liquidity providers. While this innovative model is one the project’s key success factors, there are risks involved to the approach: (1) the protocol is reliant on the insurance fund in case of skewed open interest and (2) the traders are exposed to high degrees of slippage.
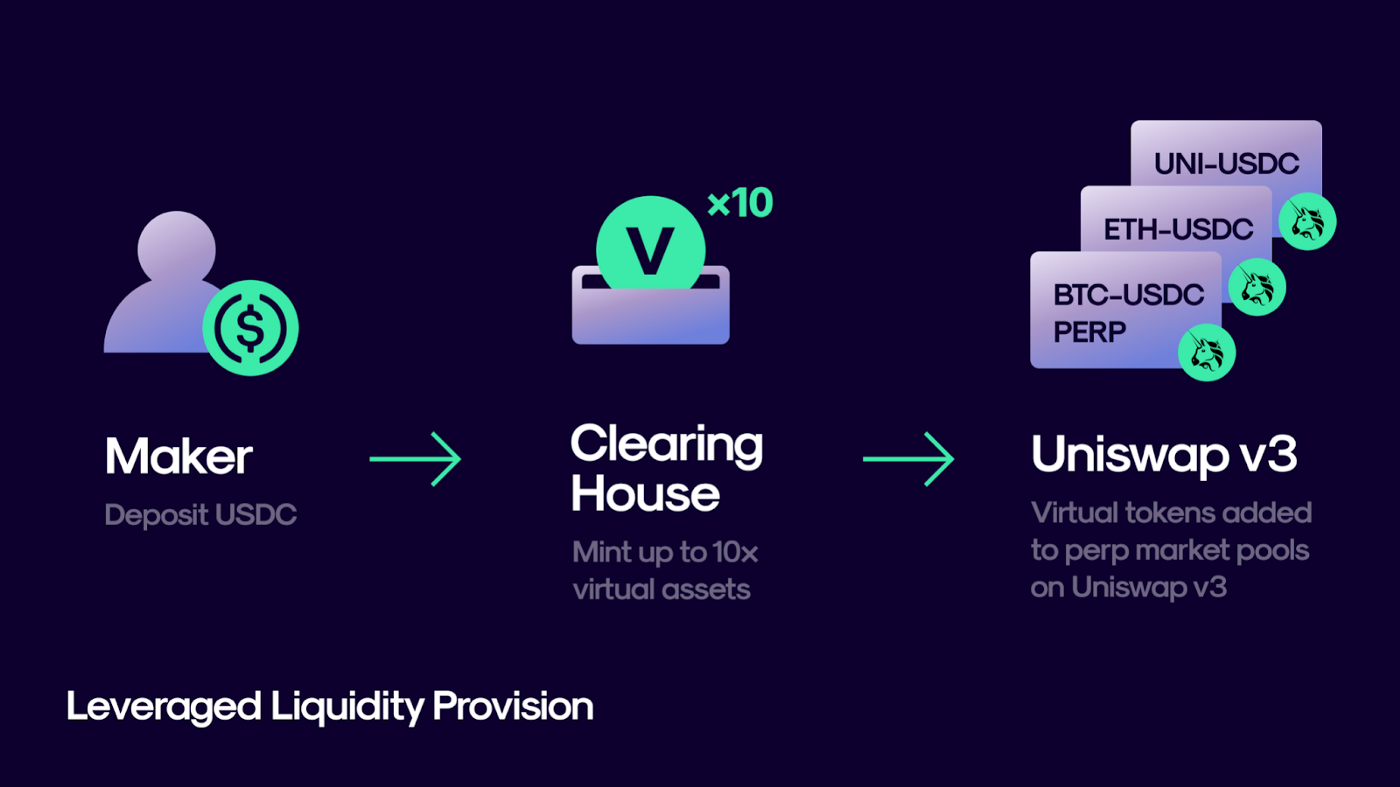
To tackle the former risk, Curie combines Perpetual Protocol’s vAMM model with Uniswap v3 as the execution layer. By introducing liquidity providers, every trade will occur between two counterparties. For makers, the updated vAMM will mint virtual tokens that are placed in Uniswap v3 liquidity pools. For traders, it will mint virtual tokens that are used for buying and selling. The result is that the funding payments pass between the counterparties via liquidity pools. This reduces the insurance fund’s involvement in skewed markets and makes the protocol more secure.
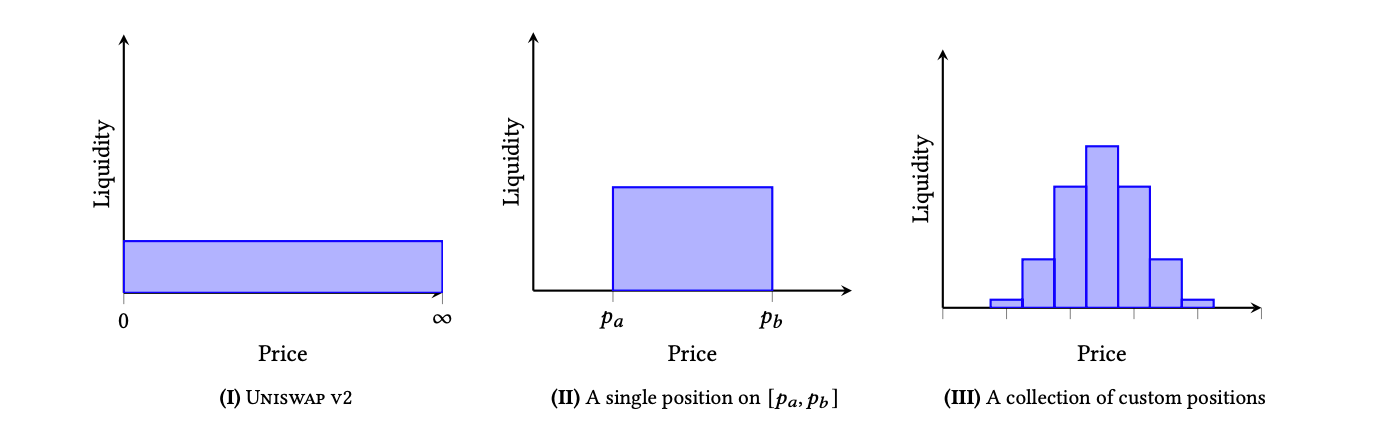
The second risk lies in the price discovery method. As the x*y=k model spreads liquidity uniformly across all price ranges, this causes high slippage for large trades. That’s because the trade is more likely to move the price as the trade size approaches the vAMM balance. Uniswap v3 tackles this by introducing concentrated liquidity, which allows liquidity providers to concentrate their capital within custom price ranges. Individual positions are then aggregated together into a single pool, forming one combined curve for users to trade against. Traders experience less slippage because large trades are spread across multiple positions rather than a single point on the price curve. The result: slippage is reduced by up to 930% on Curie.
Besides reducing slippage, concentrated liquidity also greatly improves capital efficiency. On earlier iterations of Uniswap, the majority of liquidity is never put to use. For example, the stablecoin pair DAI/USDC reserves only 0.50% of capital between $0.99 and $1.01 - the price range in which you expect to see the most volume. Liquidity providers thus only earn fees on a small portion of their capital in Uniswap v2. With concentrated liquidity, makers can construct their own price curves and set up sophisticated strategies to increase fee revenue.
Using virtual tokens, Curie also introduces leveraged liquidity provision for the first time. In addition to earning fees, makers can apply leverage to their liquidity to increase profits. As shown in the figure, makers deposit USDC and can mint virtual tokens at their preferred leverage. This opens the door to a whole range of new liquidity provision strategies. The protocol will initially allow up to 10x leverage, but this can be increased via the governance system.
Finally, the integration with Uniswap v3 also opens the door for further ecosystem integrations thanks to the high degree of composability. For example, any third-party market making strategy provider will be able to run smart contracts on Curie.
Permissionless Market Creation
Prior to Curie, new markets could only be created after passing a governance proposal. The problem is that it takes a lot of time to pass and implement a new market using this approach. In addition, since the insurance fund is shared across all markets in Perpetual Protocol v1, there are security concerns when you introduce a new asset - you don’t want a new asset to crash and wipe out the entire insurance fund. By setting up a separate insurance fund for each market, this is no longer an issue on Curie.
One of the key advantages of decentralized exchanges is that they can enable permissionless markets. Curie will empower its users to create perpetual markets using Uniswap and an oracle provider such as Chainlink. If an asset has a price feed on one of these platforms, anyone can create a perpetual market for that asset in a few simple clicks. As such, Curie users can gain access to perpetuals for the long tail of assets that are typically not available on popular platforms. Note that the protocol will also no longer be limited to crypto assets following the update. On Curie, users can trade anything they like - from forex, to gold, or even coffee beans.
Cross-Margin & Multi-Collateral
While Perpetual Protocol is one of the top derivatives platforms today, it is still a relatively young project. In the midst of the rapid growth, the team has not had the time to build out all the features traders are used to on established exchanges. This is going to change with the new upgrade. Curie introduces cross-margin and multi-asset collateral:
Cross-margin allows traders to open multiple positions using their account balance as a common pool of collateral. This means that a trader’s available margin increases as their position becomes more profitable. As such, cross-margin improves capital efficiency for traders and reduces risk for the protocol.
Multi-collateral allows traders to use multiple types of assets besides USDC. For instance, a trader can use wBTC as the collateral to open a long position on ETH-USDC. This design gives traders more flexibility and greatly improves the user experience - something the team wants to put a lot more focus on with Curie.
Tokenomics Update
The update also brings changes to the tokenomics. With the arrival of Curie, fees will be generated from three different sources:
Transaction fees from public markets
Transaction fees from private markets created by users
Rehypothecation: Funds in the insurance fund can be utilised in low-risk protocols to increase returns
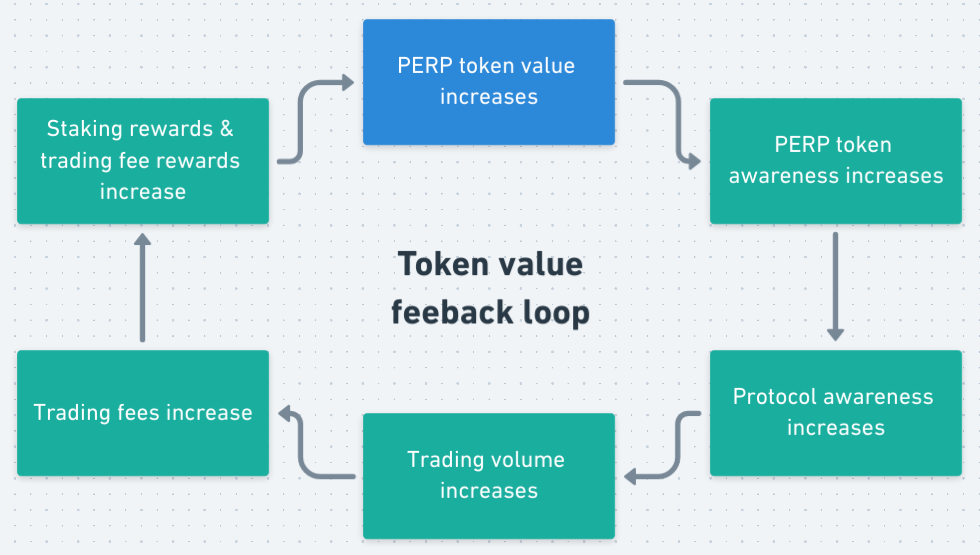
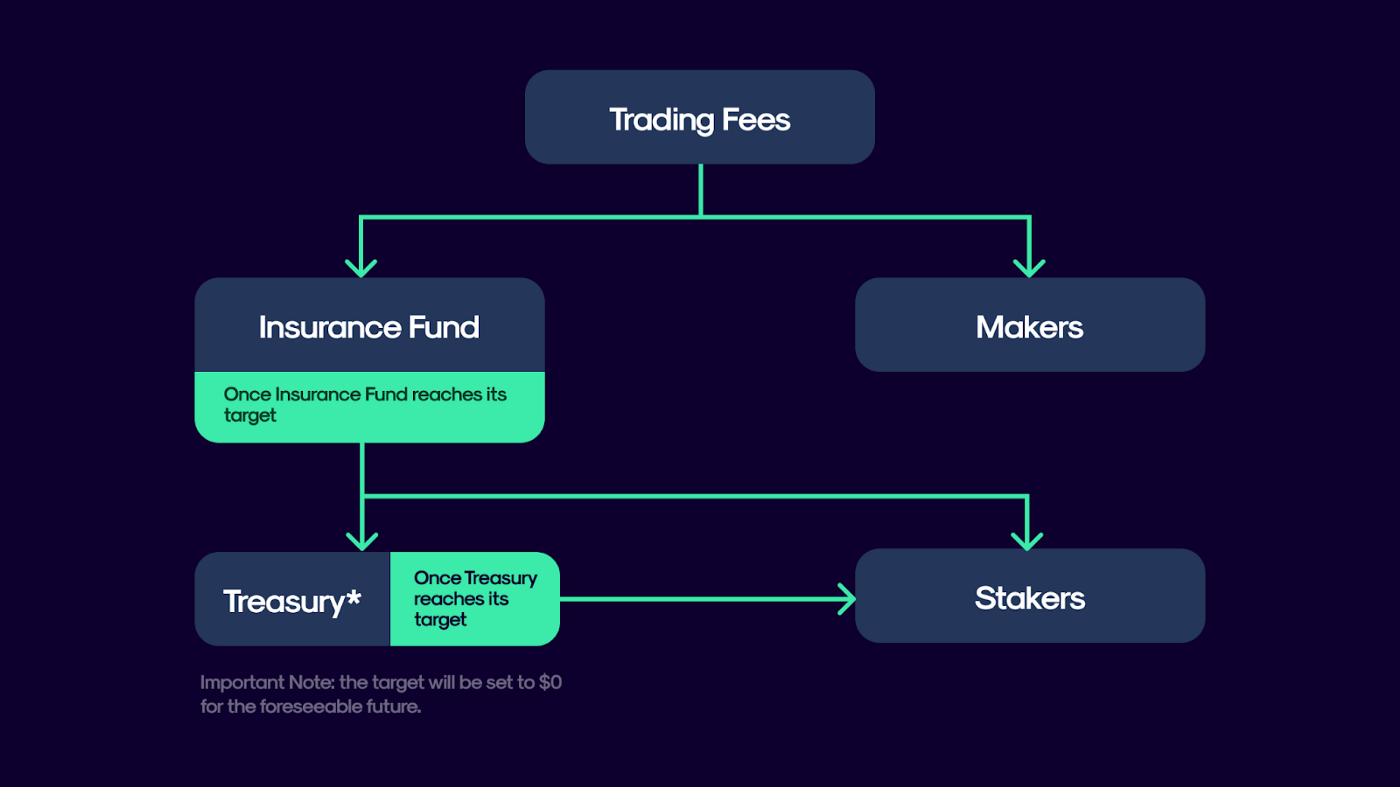
As more markets are added and more trading volume passes through the protocol, each of these revenue sources is expected to grow. Combining this leveraged liquidity provision, total fees generated on Curie should be much higher than what Perpetual Protocol v1 could ever achieve. Besides adding revenue streams, the flow of trading fees will also change on Curie. Instead of paying out half of the trading fees to stakers, makers now also need to receive their share. The new flow of trading fees is as follows:
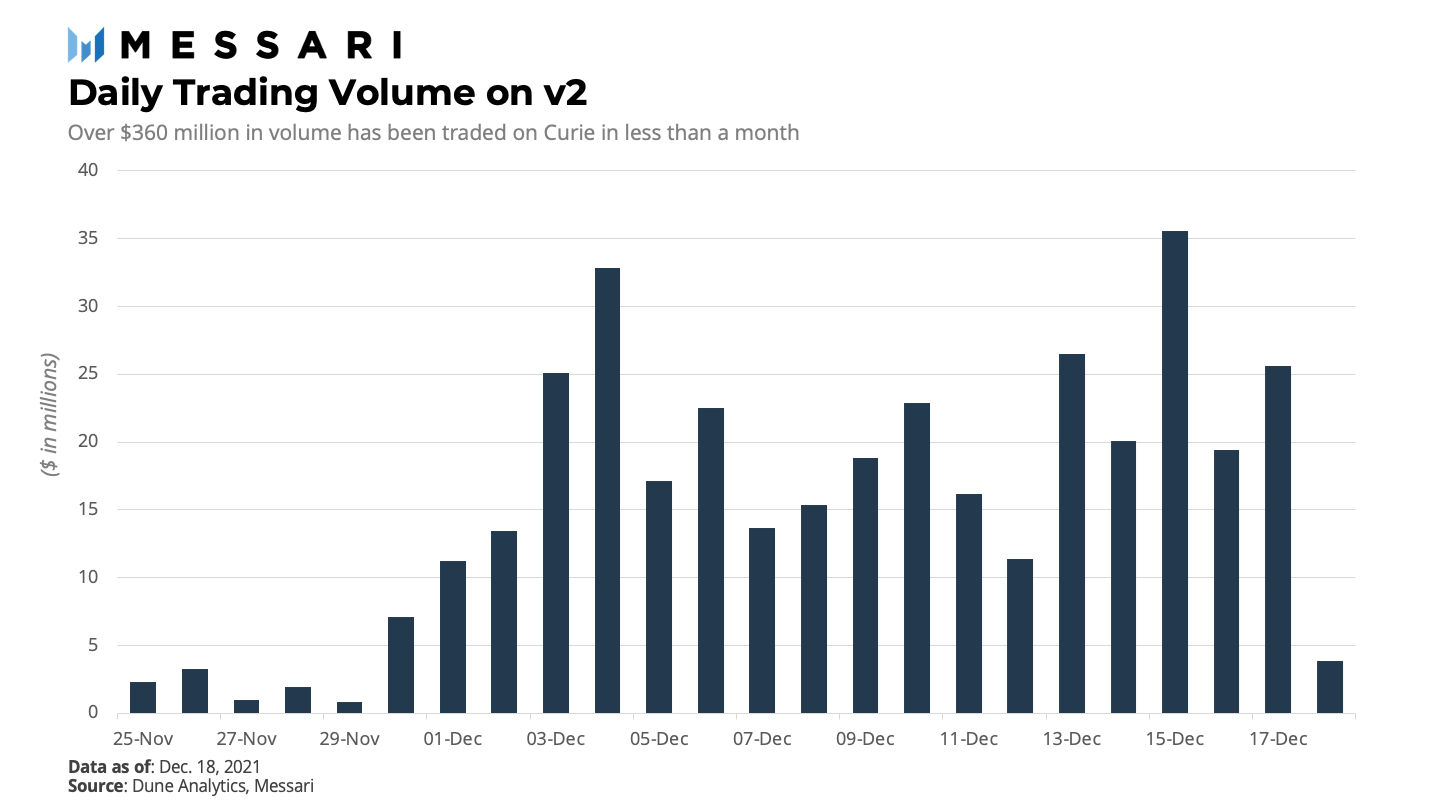
Since its launch one month ago, over $360 million in volumes has been traded on Curie. Daily trading volume averaged $15.3 million and peaked at $35.5 million on December 15. While those are impressive numbers for any protocol’s first month, it is still miles away from the $2.3 billion traded on Perpetual Protocol v1 over the same period. There is clearly still a lot of on-boarding to do - something the team is tackling with its liquidity mining and gas rebate programs.
Looking at fees and transactions, we find a similar picture. A total of $330 thousand in fees has been generated on the platform and there is no sign of slowing down. On average, 900 transactions are executed every day. Transactions are naturally larger on weekdays - even crypto traders take a break on the weekends. It remains to be seen how much the new tokenomics will impact protocol revenue.
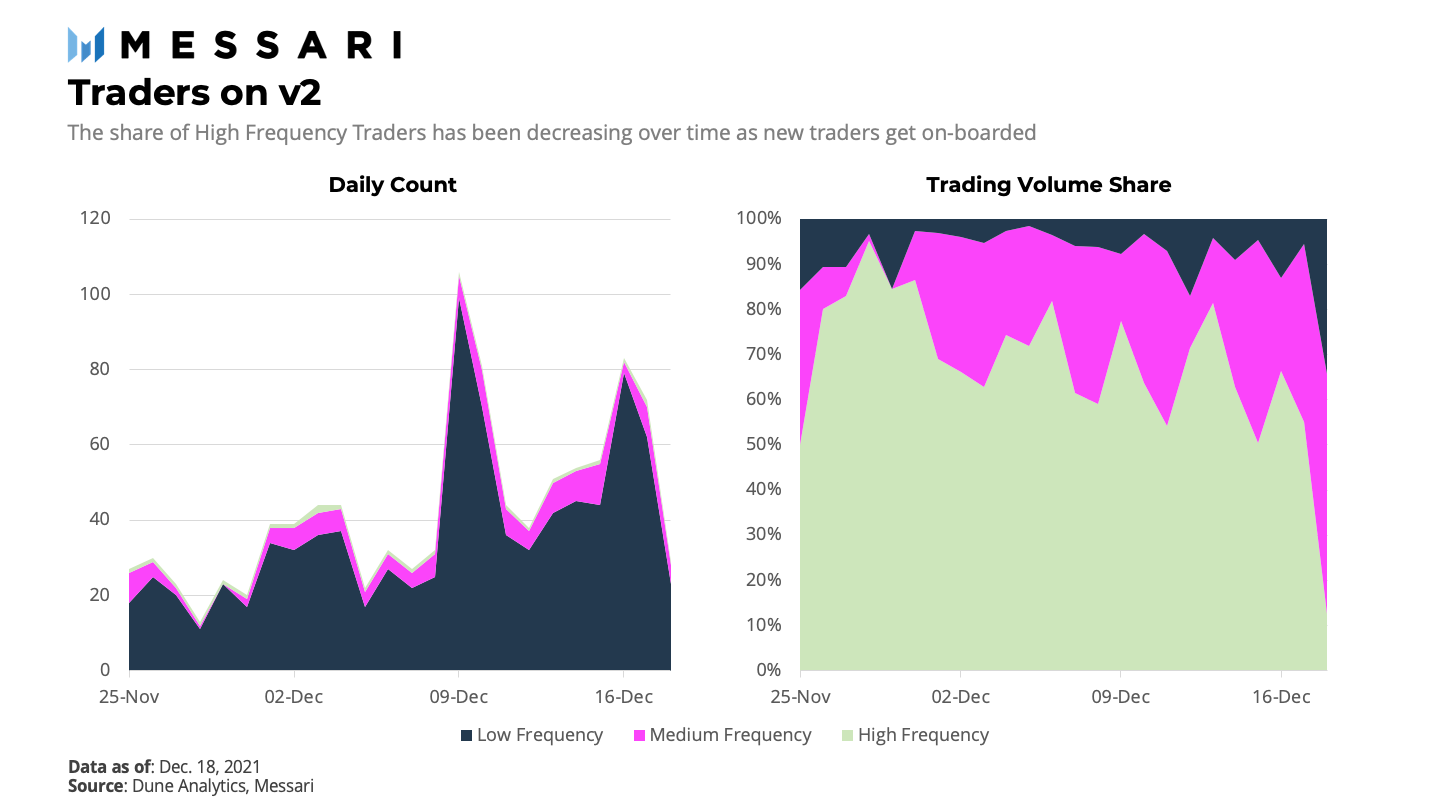
Finally, who’s actually using the platform? We find that the largest share of volume is transacted by the smallest group of traders: High Frequency Traders. This is not unexpected as it is this type of trader’s business to come in early and leverage powerful technology to outspeed others. Nonetheless, the share of High Frequency Traders has decreased as smaller traders came onto the platform throughout the month. A total of 440 unique users have registered so far. This number is likely to continue to rise with the new on-boarding efforts.
Grants Program
To foster innovation in its ecosystem, Perpetual Protocol launched a developer grants program in August 2021. The grants committee currently consists of four community members and one investor. This diverse committee should make sure the funds are used in the best interest of the protocol. A total of 500 thousand PERP is set aside to provide financial support to teams that want to:
Develop on-chain strategies using the protocol
Build projects that benefit the ecosystem
Create content to increase brand awareness for Perpetual Protocol
Teams that wish to participate can apply through a Request for Proposal and three deals have been approved to date. The team believes composability is key to build out an ecosystem surrounding the protocol and the grants program is one of the key actions to achieve this objective.
Competition
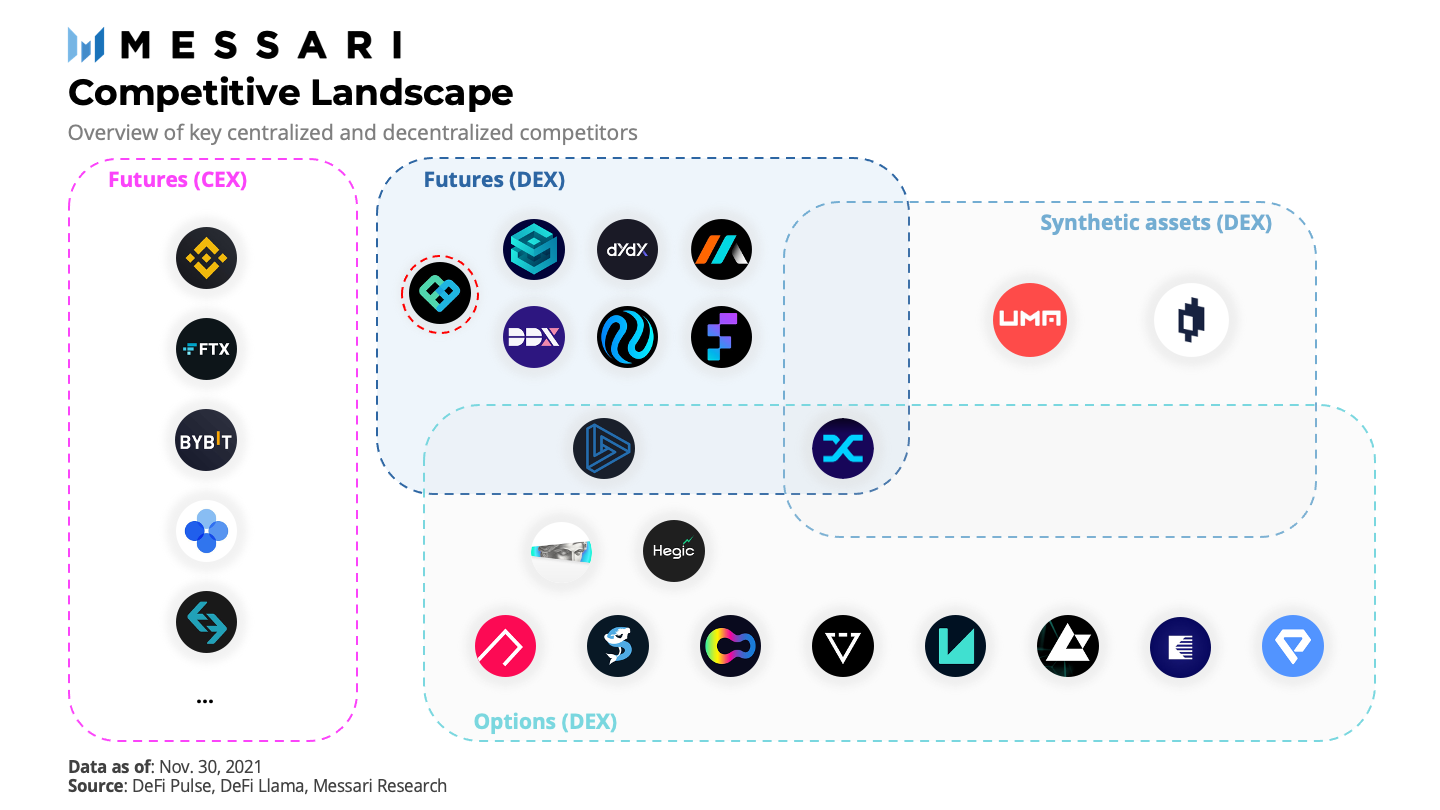
As mentioned above, the crypto derivatives market has seen some remarkable growth in the past years. Amidst this growth, perpetual swaps have won the race as the most popular financial instrument. Perpetual Protocol pioneered Layer-2 perpetuals and this contributed to its rapid growth in the decentralized perpetuals market. Today, the project is battling against its decentralized peers (DEXes) as well as established centralized exchanges (CEXes) that are looking to capture a part of this prosperous market. While the team has expressed no short-term plans to offer other types of derivatives products, decentralized synthetics and options platforms also compete with Perpetual Protocol for trading volume.
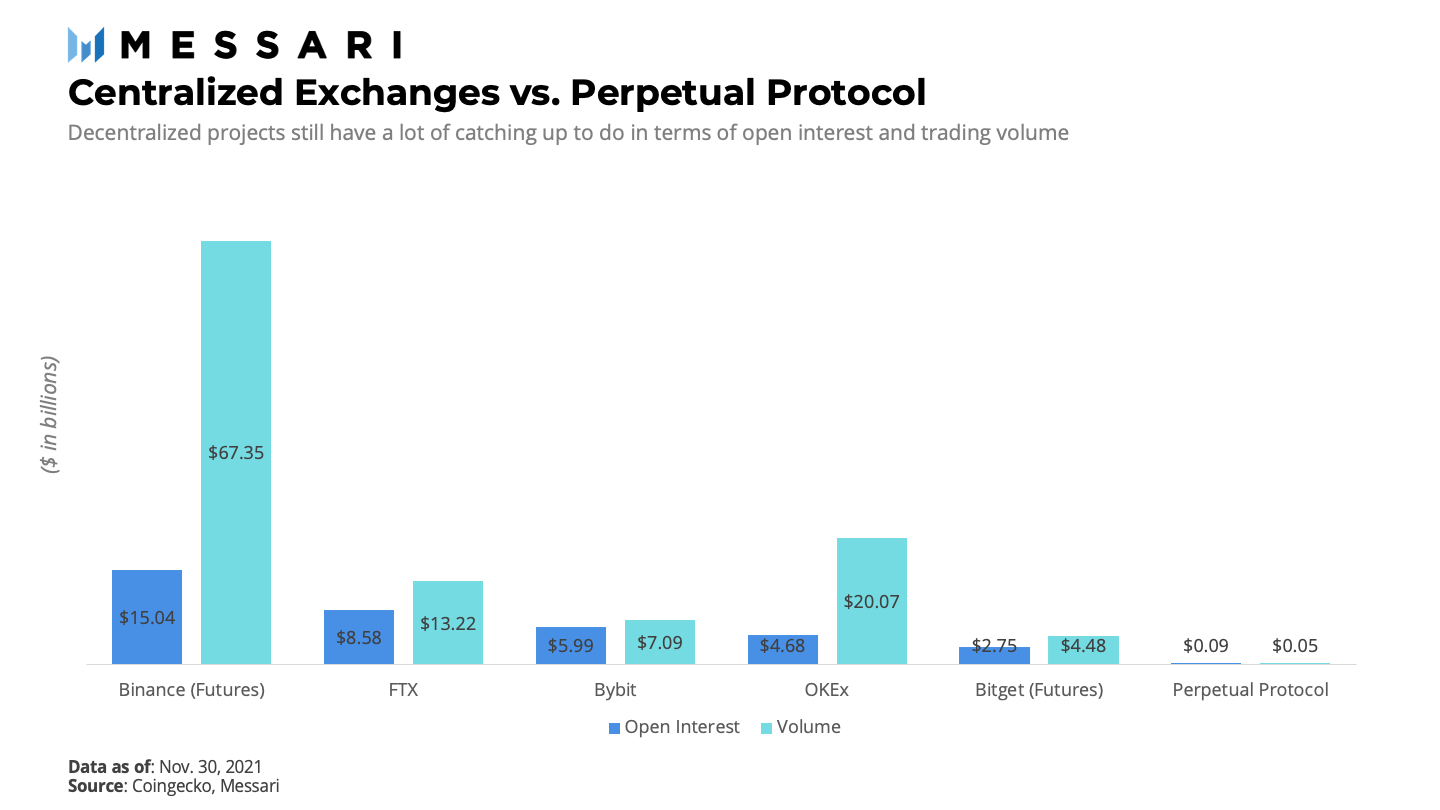
Naturally, centralized players were the first to offer crypto derivatives at scale. Today, crypto startups such Binance, FTX and Bybit still retain the largest share of the market.Comparing trading activity of CEXes with that of Perpetual Protocol gives a clear picture of the market share decentralized projects can dig into. Evidently, there is still quite some room to grow:
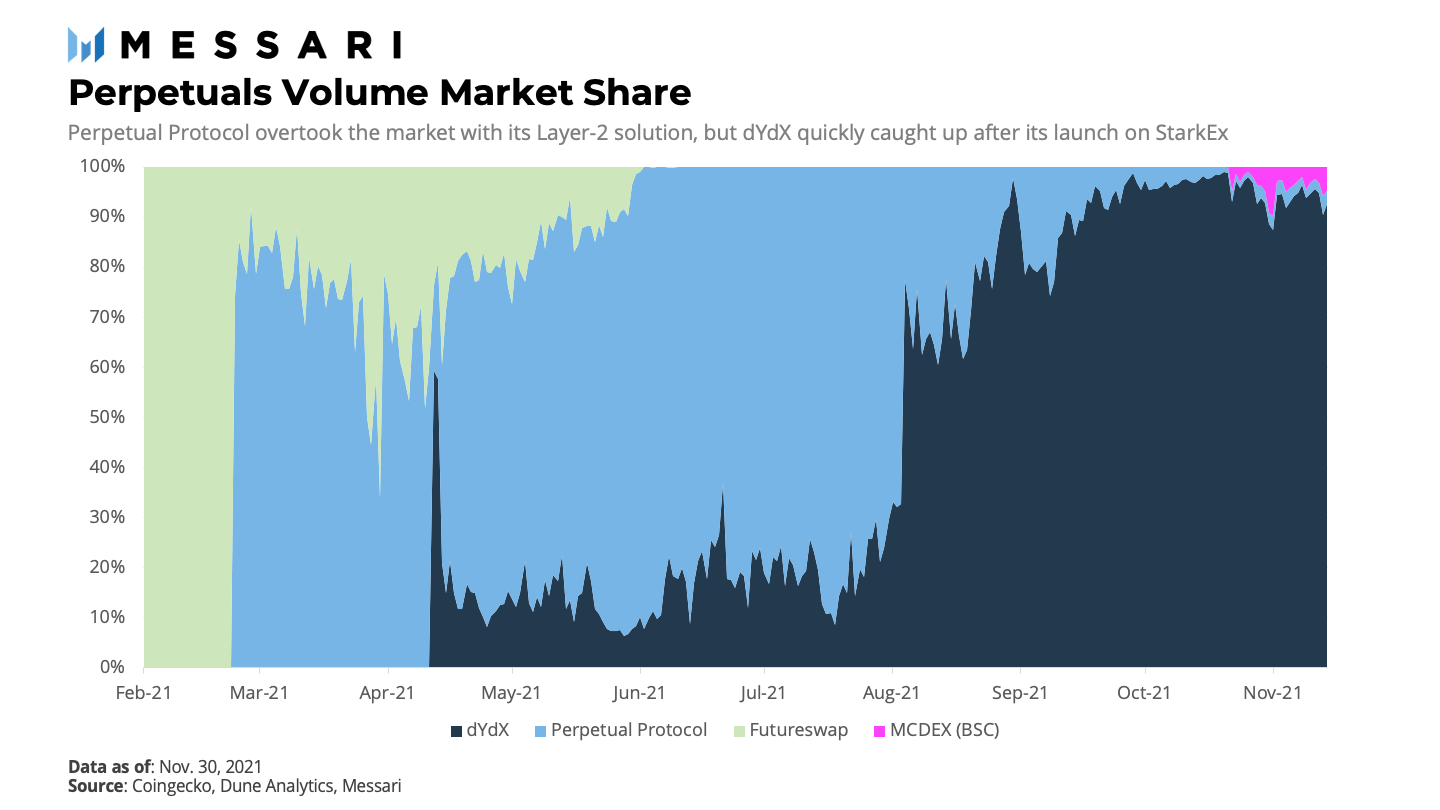
Pioneering Layer-2 perpetuals, we know Perpetual Protocol overtook the market at unparalleled speed in the beginning of the year. However, as its competitors transitioned to Layer-2 solutions, its market share decreased alongside its competitive edge. Today, established player dYdX has reascended the throne as market leader in the DeFi space. With Curie, we may just see another disruption as the protocol deploys on the Optimism scaling solution, and potentially other networks in the future. A similar thing happened back in the beginning of the year after all - and look how that turned out …
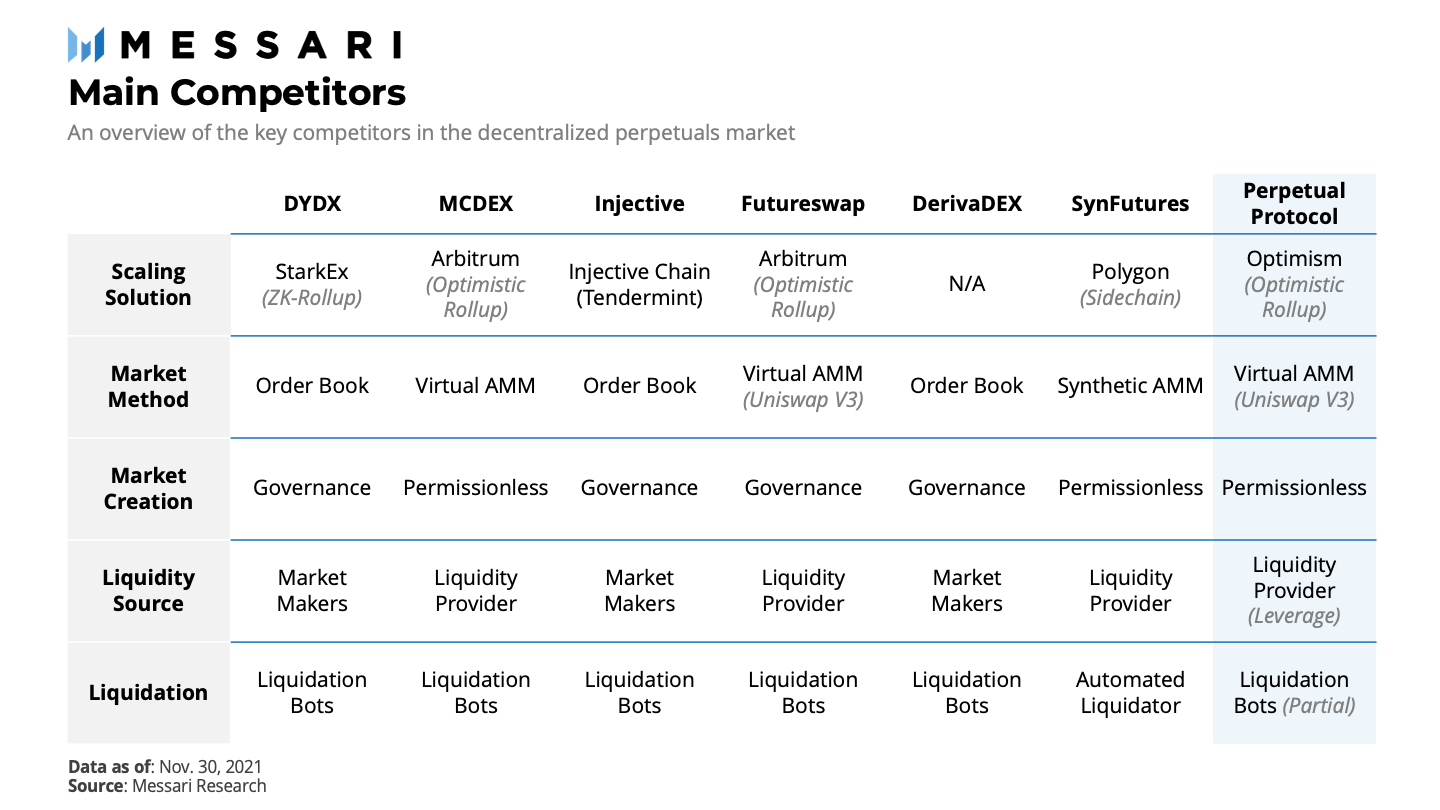
Finally, let’s take a closer look at the key competitors. There are six established players besides Perpetual Protocol. As we have seen, dYdX and Perpetual Protocol are by far the largest players. Note that DerivaDEX and SynFutures are still in the development phase. The projects are all gunning to become the reference decentralized market and seek to differentiate themselves in terms of the scaling solution, how markets are made and new markets are created, the liquidity source, and the way positions are liquidated:
Similar to how Perpetual Protocol disrupted the market, one of the main risks for the project is that a newcomer could come along with a better solution. It may also be difficult to attract liquidity providers as Perpetual Protocol transitions to concentrated liquidity - they might just prefer the current solutions. Nevertheless, the team believes the new design will allow the protocol to scale better than ever and will only improve its position in the market.
Conclusion
With the tremendous amount of potential left for decentralized derivatives relative to the traditional market, a ton of innovation is going on in the space. As a result, new and innovative protocols are popping up left and right to seize this opportunity. With Curie, Perpetual Protocol seeks to correct the weaknesses of its first iteration and strengthen its position.
The update is designed to increase volume and revenue, while reducing slippage and overreliance on the insurance fund. By introducing liquidity providers and improving the user experience on Optimism, the team is convinced Curie will become the go-to tool for derivatives traders. And by incorporating Uniswap v3 as the execution layer, enabling the creation of private markets, and launching its developer grants program, Perpetual Protocol is leveraging composability to build out its ecosystem. This is a step in the right direction towards its goal of becoming a foundational tool in the DeFi ecosystem. Be that as it may, the future of decentralized finance remains difficult to predict. Throw in complex derivatives and you have a volatile cocktail that can make anything happen. Only time will tell, but Perpetual Protocol is without a doubt a project to keep on your radar.
This report was commissioned by Perpetual Protocol. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.