Pendle's Pricing Power

Pendle dominates the market in which it operates. As such, it is exercising its pricing power and cementing its moat against competitors. With a 66% increase on the YT take rate, Aave supporting PTs as collateral, permissionless listings, and the pending Boros launch, tailwinds are in place for growing Pendle’s utilization, distribution, and revenue.
Currently, 38% of the PENDLE supply is staked as vePENDLE, earning the revenue as yield. This puts the vePENDLE market capitalization at $195M. Pendle’s last month earnings, annualized, came in at $25M, falling from its peak annualized earnings rate this year of $34M. Historically, Pendle’s monthly annualized earnings rate has fluctuated between $8.4M and $48.4M, which can inform a bear case and a bull case assuming 30% growth in revenue with the increased YT take rate.
| Annual Earnings | FDV/ Earnings | vePENDLE MC/ Earnings | |
| Bear Case | $10,920,000 | 80.9 | 17.7 |
| Bull Case | $62,868,000 | 14.0 | 3.1 |
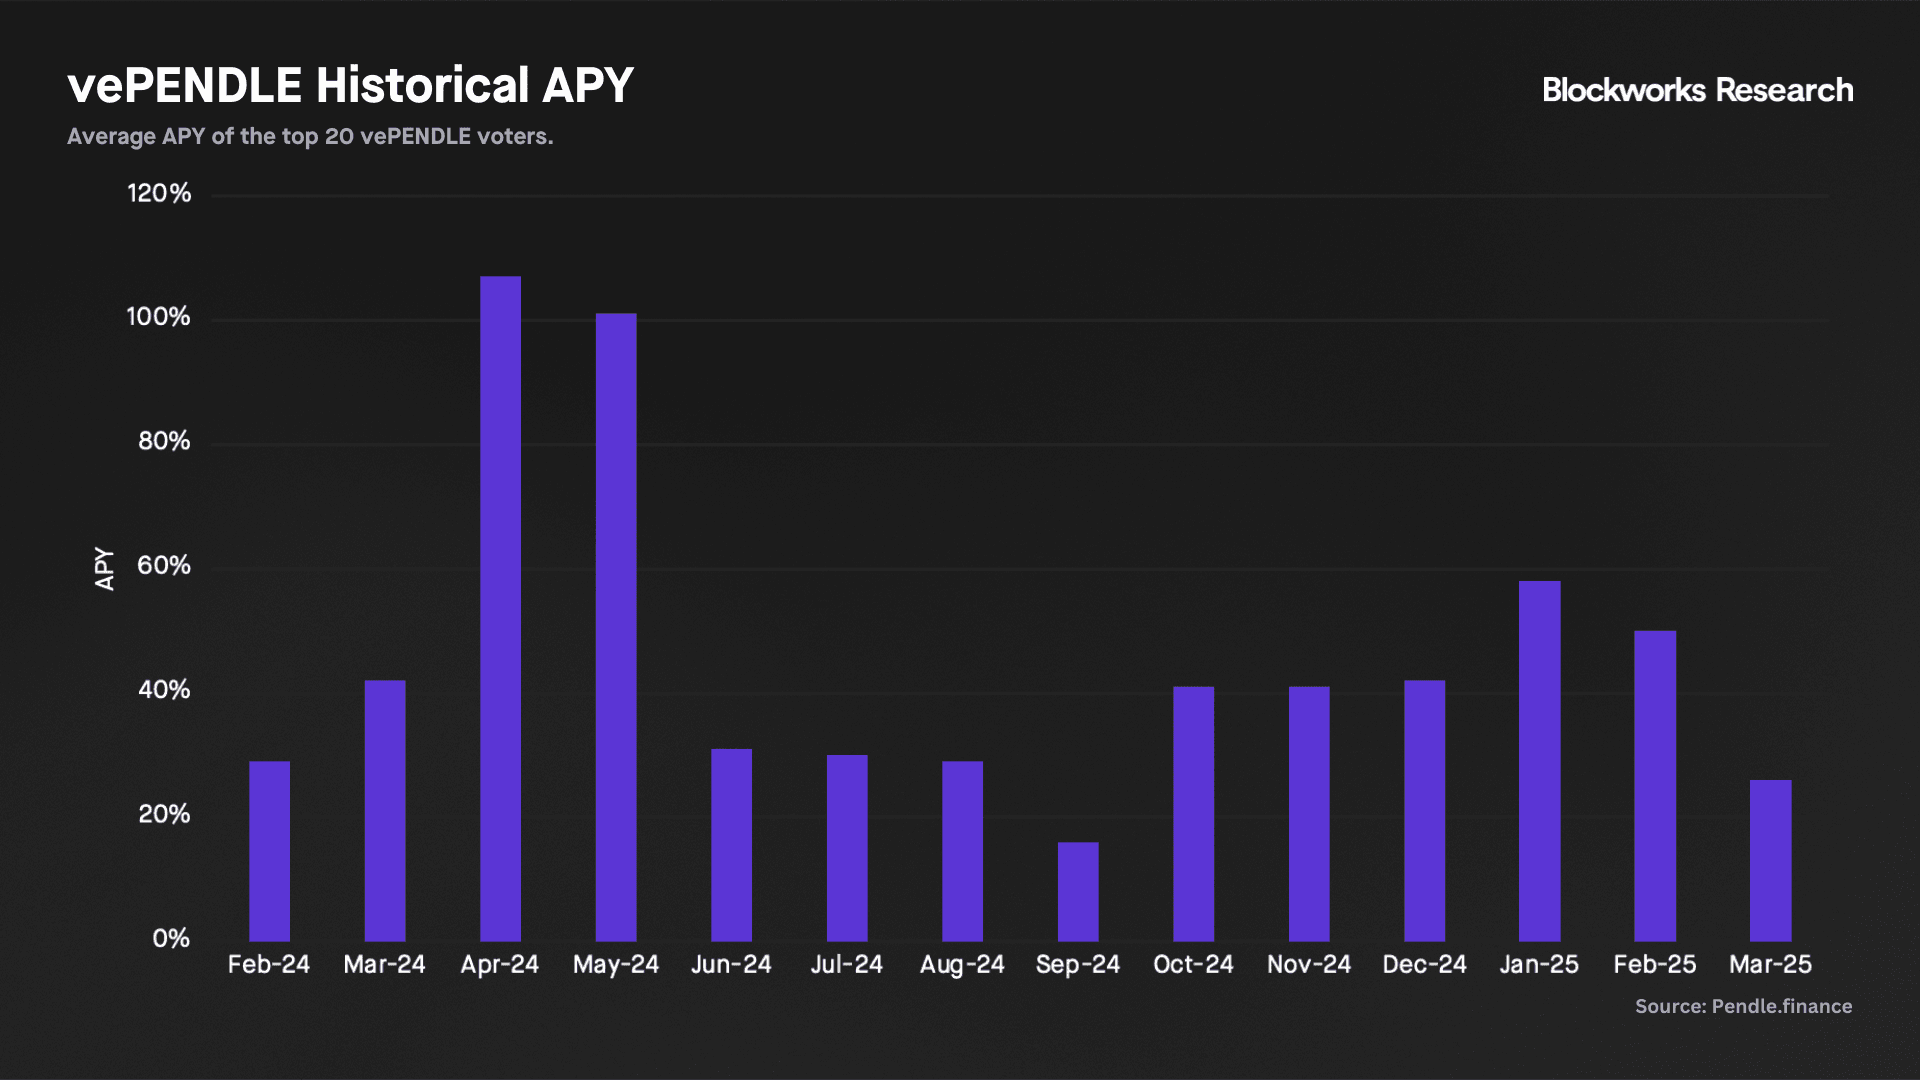
A vePENDLE position, which carries duration risk and illiquidity, has historically paid a median APY of 41% (measured from the average of the top 20 vePENDLE voters).
Boros will open up an entirely new vertical and revenue stream for Pendle. Beginning with perpetual futures funding rates, this market will offer a venue for hedging and speculating on a market that settles trillions in annual volume, holds hundreds of billions in open interest, and pays tens of billions in funding fees. The addressable market for Boros is large, and much larger than the market for YBAs that Pendle V2 currently serves.
It is highly indeterminate how successful this new market will be, or its parameters to monetize utilization, but it can be expected that it will capture fees from volume, liquidations, and perhaps a take rate on the fixed and variable rates paid by users. While the perpetual futures market is not the most precise comparison for the market in which Boros will enter, incredibly small penetration into this market could have the capacity to generate large revenues. Notably, funding rates will not be the only market that Boros can service, as it has the capacity to service any offchain or onchain yield that can be measured with an oracle. The launch of Boros will likely add additional revenue streams that are diversified from its current reliance on elevated onchain yields, new inventory of YBAs coming to market, and airdrop campaigns.

Luke leads coverage on money markets, stablecoins, real world assets, interoperability, and intents-based infrastructure. Previously worked in market research and product at a startup incubator.