Opportunities and Risks for Crypto Interest Accounts

“Only when the tide goes out do you discover who's been swimming naked” - Warren Buffet
In the fiat world, central banks dictate risk-free rates and serve as lenders of last resort. On the other end of the spectrum, crypto does not have any central authority backstopping the system, and yields don’t come for free.
As the digital assets industry matures, customers will want the services that come with greater financialization, such as compounded interest and borrowing. However, functionally limited protocols such as Bitcoin were not designed to permit lending on the blockchain. As such, lending has not been achieved in a trustless manner. Within centralized intermediaries, lending has been off-chain and settled in traditional infrastructure. With greater financialization, we can expect teething problems as “too good to be true” interest doesn’t come for free.
A Warning from Cred
If you haven’t had a chance to follow Cred’s bankruptcy filings, below is their reported balance sheet as of November 7, 2020. We also adjusted the balance sheet based on reports here, here, and here.
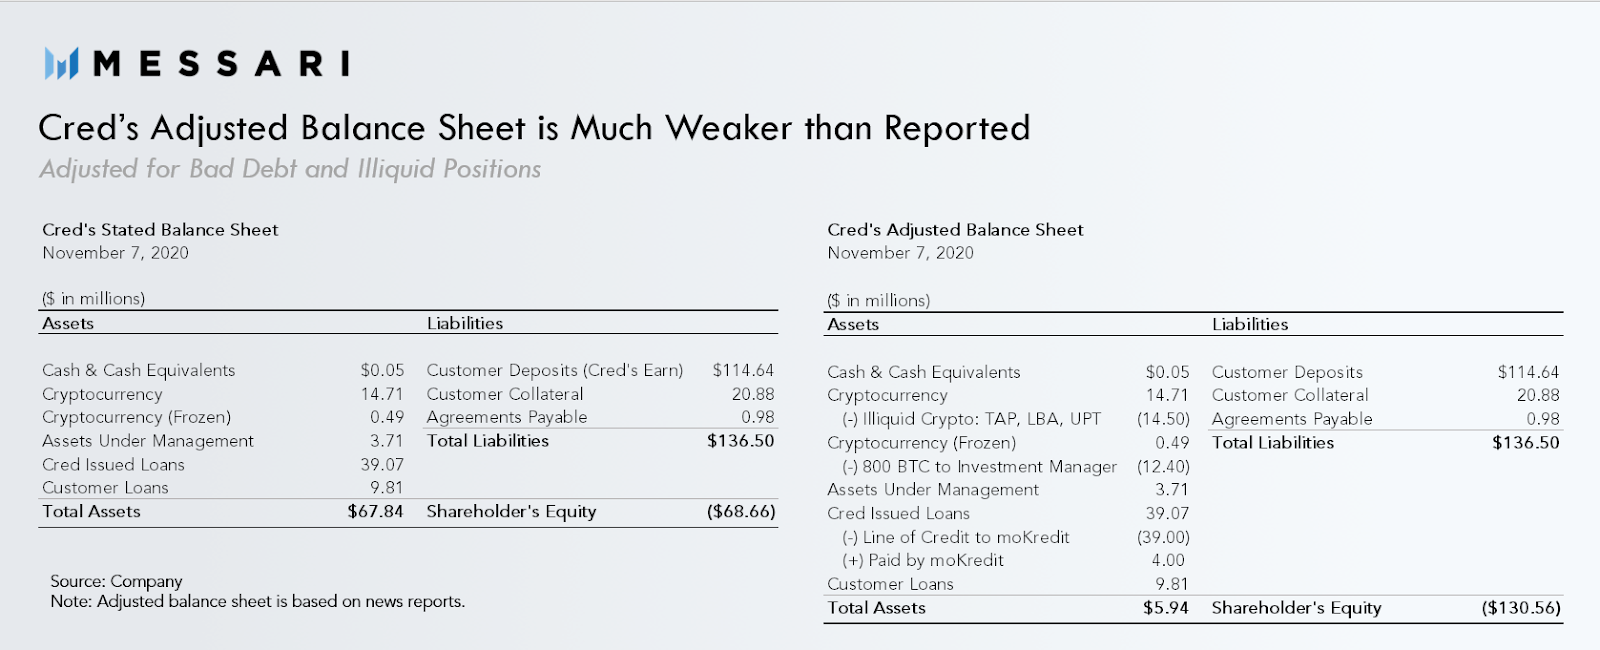
Through a series of events, Cred – a U.S. licensed cryptocurrency lender – was insolvent months before they publicly declared bankruptcy. Reportedly poor business practices such as a conflict of interest where Cred allegedly allocated $39 million of capital to moKredit, a Chinese lender led by the co-founder of Cred. However, most of what we see on its financials is a compilation of poor liabilities, risk, and liquidity management.

Mira was a Senior Research Analyst at Messari. Prior to joining Messari, Mira was a Senior Portfolio Manager for a US$6 billion Asia Pacific equities fund at APG Asset Management. Mira received a BA in Economics and Mathematical Methods in the Social Sciences from Northwestern University.