Neutrl issues NUSD, a synthetic U.S. dollar that packages institutional market-neutral strategies (discounted OTC token purchases, basis/funding arbitrage, and staking yield on hedged collateral) into a single fully backed asset.
The protocol separates stability and yield: NUSD is a non-yielding, fully backed synthetic dollar, while sNUSD is a non-rebasing, yield-bearing claim on protocol revenues.
Neutrl’s core edge is access to illiquid over-the-counter (OTC) altcoin deal flow at steep discounts, combined with systematic hedging via perpetual futures to lock in dollar-denominated returns independent of market direction.
Neutrl’s portfolio structure and duration-matching framework are designed to align asset maturities with redemption liabilities, reducing forced selling risk and allowing more capital to be deployed into longer-tenor trades.
Early traction suggests demand for this form of “real yield,” but long-term sustainability depends on continued access to high-quality OTC supply and disciplined risk management.
Background
Over the last several DeFi cycles, demand for stablecoin yield has pushed protocols into increasingly crowded trades and incentive-driven designs. Basis trades on BTC and ETH perpetual futures, conservative money-market lending, and short-dated liquidity mining have all contributed to yield compression. Attractive spreads are quickly arbitraged away, and remaining yields are either low or propped up by inflationary token emissions rather than sustainable economic returns. As more protocols pursue the same narrow set of opportunities, the marginal dollar of stablecoin liquidity has fewer productive places to go, and “yield” increasingly reflects redistribution rather than value creation. The rise of exogenous incentives (points, emissions, and synthetic APY bootstrapping) has accelerated this trend, masking the fact that organic yield opportunities have not grown in proportion to onchain capital.
At the same time, crypto’s private markets have expanded in scale, complexity, and fragmentation. Large allocations of tokens sit under multi-year vesting schedules, leaving early investors, foundations, and funds with substantial illiquid exposure. When liquidity needs arise, these holders often sell locked tokens at steep discounts via OTC (over-the-counter) channels. Yet the OTC landscape is highly fragmented, dominated by bespoke bilateral agreements, variable custodial requirements, inconsistent legal documentation, and significant counterparty risk. These frictions create wide, persistent illiquidity discounts that retail users and most DeFi systems cannot access due to the absence of standardized onchain settlement, KYC-gated workflows, and reliable hedging rails.
The result is a structural imbalance: DeFi has an abundance of capital seeking yield but limited access to the types of structural, real-economy inefficiencies that generate durable, non-incentive-based returns, while private markets hold persistent illiquidity premia that few participants can systematically capture. Onchain stablecoin supply has grown by tens of billions, yet DeFi-native credit markets have stagnated, in part because they cannot originate differentiated yield without assuming directional or credit risk. Meanwhile, locked-token positions have ballooned in parallel, and OTC volumes remain deep but operationally siloed. The infrastructure required to bridge these two domains remains underdeveloped.
This mismatch has pushed protocols toward synthetic-yield mechanisms, escalating ARR competition, and funding- and volatility-dependent strategies whose returns collapse when leverage demand and basis premia compress (often to levels that are no longer profitable, on a risk-adjusted basis, given the exchange, margin, and smart-contract risk embedded in the trade).
It has also driven the recent wave of synthetic dollars and basis stablecoins, which attempt to rebuild yield around perps funding but remain constrained by the same market saturation. What is missing is a scalable and transparent way to turn the structural frictions of private markets into accessible, market-neutral yield.
Introduction
Neutrl enters this landscape with a simple premise: the most durable yield in crypto comes not from incentives or leverage, but from structural spread capture. Rather than competing for the saturated funding markets or emission-driven yield, Neutrl is built around opportunities whose economics originate outside of DeFi entirely. The protocol utilizes illiquidity, vesting asymmetry, and derivatives term structure as sources of systematic return that can be isolated, hedged, and delivered onchain.
At its core, Neutrl is a synthetic-dollar protocol that transforms altcoin OTC discounts and derivatives basis spreads into fully backed, market-neutral yield streams. It pairs discounted acquisition of locked-token exposure with delta-neutral hedges in perpetual futures, converting vesting-related price differentials into returns that are fixed once the discount and hedge are set. Complementary returns are sourced from a diversified funding-rate book and conservative cash-equivalent allocations, giving the system multiple orthogonal yield drivers without relying on bullish market conditions or cycles of escalating APY incentives. Neutrl’s design emphasizes neutrality rather than directionality. Its mechanisms aim to preserve solvency and backing under both expansionary and contractionary market regimes.
NUSD functions as a fully backed synthetic dollar, while sNUSD represents staked NUSD whose redemption value relativetoNUSD increases as the protocol accumulates revenue. By separating stability from yield, Neutrl avoids the liquidity–duration mismatch that has undermined prior attempts at yield-bearing stablecoins. The system’s architecture is built to handle long-dated OTC maturities, manage rolling hedges across many venues, and maintain continuous auditability through cryptographic attestations rather than opaque internal reporting.
Built by a team with backgrounds in OTC trading, quantitative derivatives, and institutional market infrastructure, Neutrl recently closed a $5 million seed round with investors such as STIX and Accomplice. Following the launch of its public phase on November 2025, circulating NUSD supply expanded 54.5% month-over-month, from approximately 120.7 million in November to 186.4 million in December, reflecting accelerated user inflows during the protocol’s expansion phase.
Architecture Overview
Neutrl uses a dual-token model that cleanly separates stability from yield. NUSD is the base synthetic dollar, minted permissionlessly at a 1:1 ratio against supported stablecoins (USDC, USDT, USDe). Minted assets flow into a reserve pool backing all NUSD in circulation. Unlike stablecoins backed exclusively by fiat reserve stablecoins collateralized only by cash and treasuries in traditional custody, NUSD is backed not only by liquid stablecoins but also by delta-neutral crypto exposures, such as hedged locked-token positions and short-perpetual hedges.
sNUSD represents staked NUSD. When users stake, they receive sNUSD at a ratio that increases over time as strategy revenue accrues to the NUSD reserves of the staking vault. sNUSD supply stays fixed, so the exchange rate appreciates, mirroring the standard “rebasing via exchange rate” mechanism: balances remain constant, but underlying value increases.
Unstaking is subject to a mandatory 10-day cooldown. This delay is central to Neutrl’s duration management, giving the system time to unwind positions or wait for liquidity from maturing OTC trades. After the cooldown, users withdraw NUSD at the then-current exchange rate.
Redemptions of NUSD back into stablecoins are subject to KYC/KYB verification. Redemptions may also be limited by jurisdictional constraints, including restrictions on users from regions sanctioned by the U.S. Office of Foreign Assets Control (OFAC) or locations where the protocol cannot legally offer service. Small redemptions ( those within the liquid buffer, enabling same-block settlement without touching longer-duration positions or affecting the hedged book) draw from an immediate liquidity buffer, while larger ones (those that exceed the protocol’s liquid buffer) pull from the Neutrl AssetReserve and may enter a redemption queue targeted for clearance within 48 hours. This structure strikes a balance between permissionless minting and regulatory and liquidity requirements.
This structure strikes a balance between permissionless minting and the regulatory/liquidity constraints the protocol must operate under: permissionless inflows do not trigger regulated redemption obligations, while redemptions ensure compliance with AML requirements and prevent forced unwinds of longer-dated hedged positions.
A significant share of private-market token exposure sits under vesting contracts (SAFTs and similar instruments) that entitle holders to future allocations but cannot be freely traded. Early investors, foundations, and funds often seek to monetize these positions before unlock and are willing to sell at steep discounts, typically around 50% for large-caps (those with market capitalizations generally in the multi-billion-dollar range, exhibiting stable liquidity and lower idiosyncratic volatility relative to smaller assets) and up to 70–80% for smaller, illiquid assets. Neutrl positions itself as a systematic buyer of this flow, sourcing deals through platforms like STIX and direct relationships with foundations and professional investors.
Sellers undergo KYC/KYB checks, verify ownership and vesting schedules, and transact via regulated custodians or onchain escrows. Once rights to the vested tokens are secured, Neutrl opens a matching short perp position to hedge price exposure. Upon vesting, it receives the tokens, closes the hedge, and captures the spread between the discounted purchase price and the market price at hedge entry, net of funding and execution costs. In select cases, locked collateral may also be staked while hedged, adding incremental yield.
Neutrl’s second major yield component comes from systematically capturing basis spreads and funding-rate differentials in perpetual futures markets. Crypto perpetual futures often trade at a premium to spot, reflecting persistent speculative demand for leveraged long exposure. To maintain price convergence with spot markets, funding payments are transferred from long positions to short positions.
Neutrl runs the basis trade at scale across venues such as Binance, Bybit, and Hyperliquid. It expands beyond BTC and ETH into hundreds of altcoin markets, where funding behavior differs and historically skews positive. Over the past year, altcoin perps exhibited positive funding on roughly 77.5% of days, with mid-single-digit annualized returns even in difficult conditions. Diversification and conservative leverage improve reliability and reduce idiosyncratic risk.
The third component is stablecoin and cash-equivalent yield. Part of Neutrl’s reserves remain in liquid stablecoins such as USDEe and sUSDS. These positions provide low-risk yield, anchor overall returns, and supply immediate liquidity for redemptions and margin needs. When funding compresses or OTC opportunities dwindle, capital can shift toward this sleeve without impairing solvency.
In bull markets with strong demand for leverage, funding-rate and basis trades may be most attractive. In bear markets, when leveraged activity contracts but unlock-driven selling increases, OTC discounts widen and become more desirable. Stablecoin yield remains the baseline in all conditions, providing a steady floor for the system.
Valuation Methodology
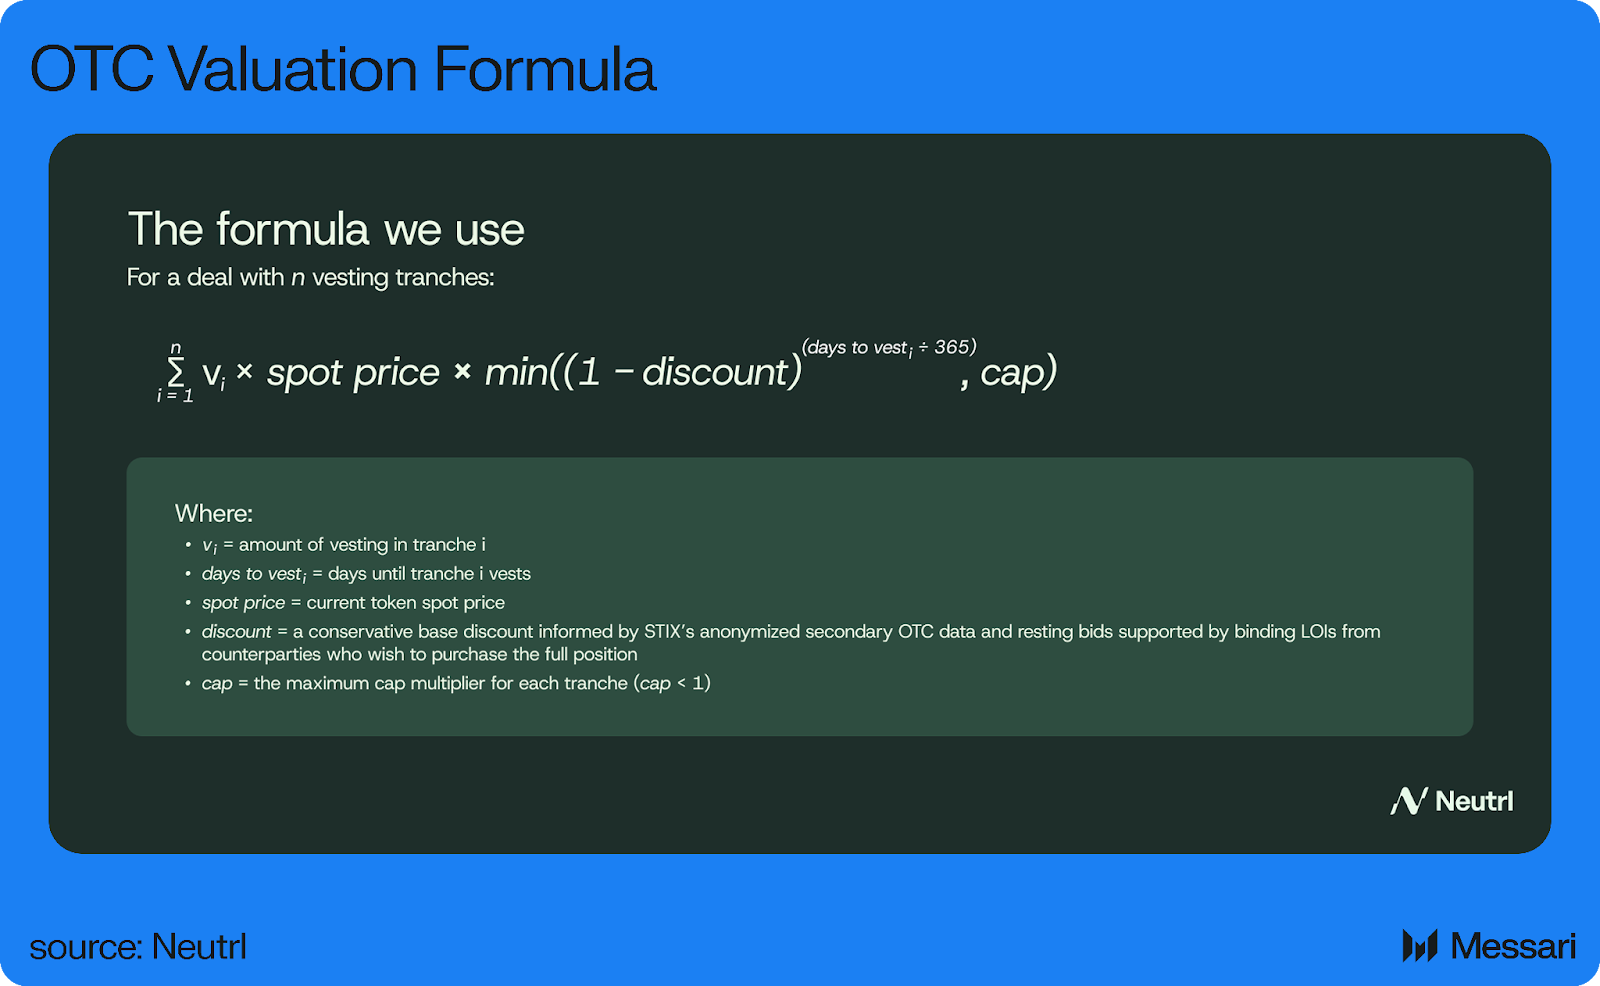
Neutrl values illiquid OTC positions using a conservative, time-weighted discount framework rather than spot marks or flat haircuts. Longer vesting horizons receive deeper reductions to reflect transfer restrictions, price uncertainty, and liquidation frictions, while even near-vesting tranches remain capped below spot to avoid overstating collateral value. Discount inputs are drawn from the conservative end of anonymized OTC datasets such as STIX, mirroring traditional asset-management practices for restricted securities and ensuring reserve strength is never overstated. This downward bias protects sNUSD holders from over-distribution and preserves a realistic view of liquidation outcomes under stress.
Transparency and risk management reinforce this conservatism. Neutrl uses zero-knowledge reserve attestations via Accountable, which verifies custodied balances, hedges, and valuation rules without revealing individual positions. Operationally, the protocol relies on institutional OTC channels, legal contracts, custodial settlement, and off-exchange trading to minimize counterparty and exchange risk. Leverage remains low with continuous margin monitoring, automated top-ups, and a globally distributed trading team for volatile periods. Funding rate, liquidity, and duration risks are mitigated through diversification, the ability to rotate into stablecoin yield when conditions worsen, and mechanisms such as laddered maturities, redemption queues, and cooldowns.
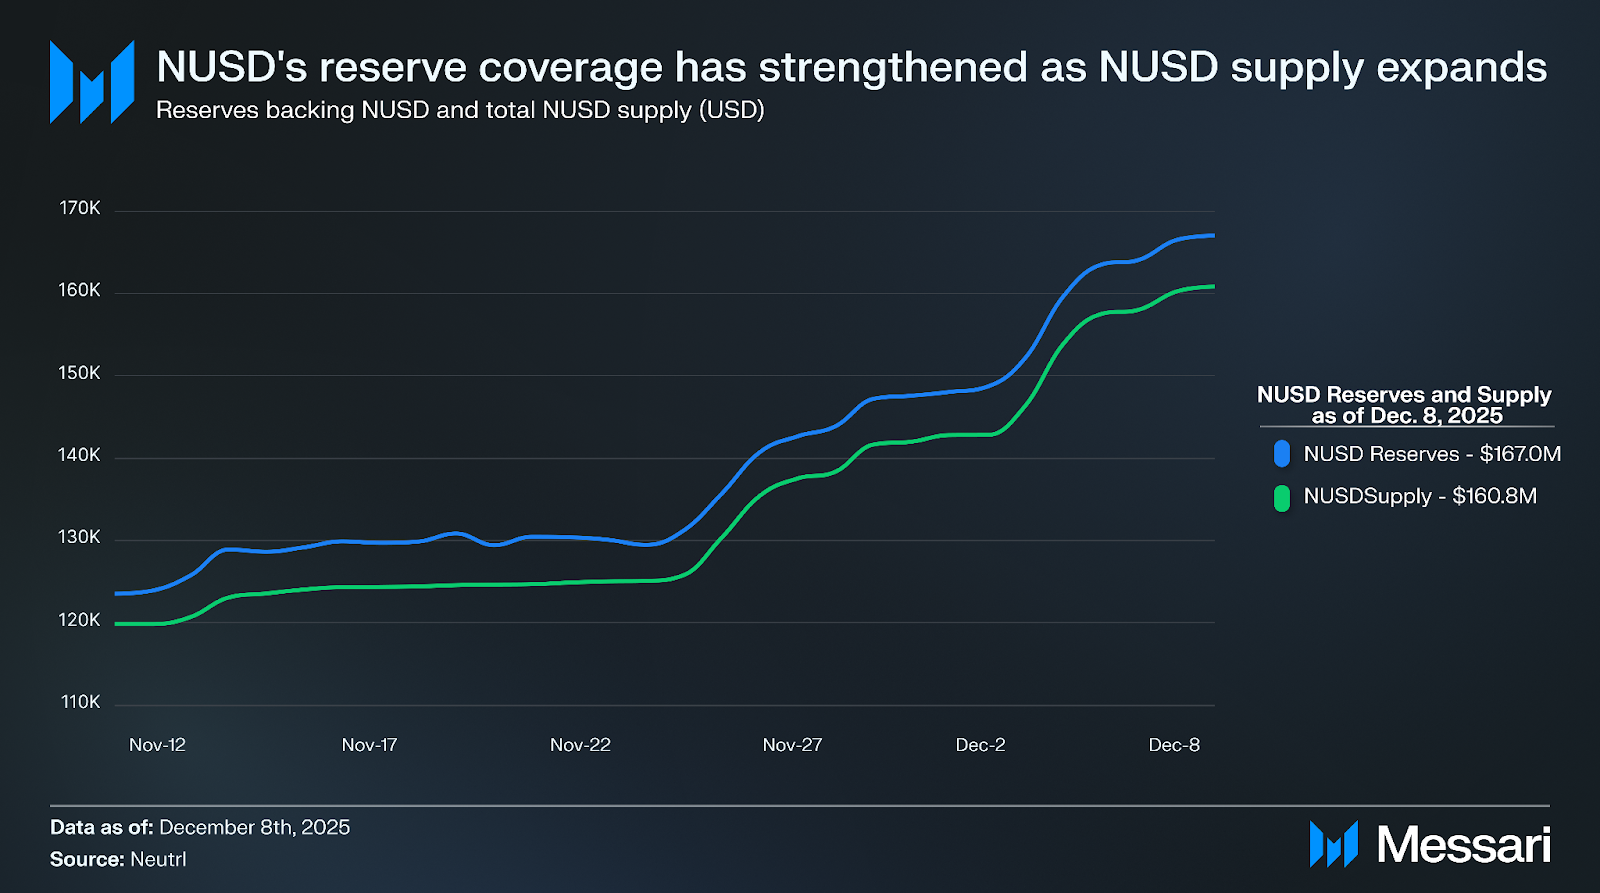
The relationship between circulating NUSD supply and the reserve assets backing it is the primary measure of solvency for synthetic-dollar protocols. Throughout Neutrl’s expansion phase, reserves remained consistently above supply, with the buffer widening as OTC tranches vested and derivatives hedges accrued funding. As of December 8, 2025, reserves exceeded circulating NUSD by 3.9%, consistent with Neutrl’s conservative valuation framework, which intentionally understates the value of locked-token positions and limits the contribution of illiquid assets near unlock.
Tokenomics
All protocol revenue accrues to sNUSD holders through increases in the sNUSD:NUSD exchange rate, with yield periodically swept into the staking contract and amortized over a seven-day period. NUSD itself remains a non-yielding, fully backed synthetic dollar, while sNUSD holders absorb losses only after the protocol’s insurance fund is exhausted, placing sNUSD in a defined second-loss position. Users seeking stability hold NUSD, while those seeking yield accept staking lockups and strategy risk.
As Neutrl realizes profit from OTC discounts, basis trades, and stablecoin yield, these gains flow into the NUSD reserves. Since sNUSD supply is fixed, the exchange rate rises continuously for liquid strategies and in larger increments when OTC positions mature. For example, if 5.0 million sNUSD are outstanding and $1.0 million in net revenue is earned, the ratio may rise from 1.0 to 1.2, delivering a 20.0% return to stakers.
Growth
Neutrl’s growth relies on a feedback loop between total-value-locked (TVL), lock duration, and yield. New deposits initially dilute yield. Yield-sensitive users respond by staking or extending lockups, which gives Neutrl more predictable liabilities and allows for allocation into higher yielding OTC and basis opportunities. Higher deployment into more profitable trades increases protocol revenue, accelerates the rise of the sNUSD exchange rate and headline APRs, which in turn attract more deposits. The flywheel moderates once market conditions tighten, with no higher-yielding strategies available.
The system is built to adapt across regimes. When OTC opportunities tighten, funding premia often rise alongside increased demand for leveraged longs, improving the relative appeal of derivatives strategies. When funding compresses and sentiment weakens, OTC discounts typically widen. Neutrl can shift across these modes rather than relying on a single source of yield.
The market opportunity is substantial. Many major tokens have large unvested supplies, and billions of dollars in unlocks occur monthly. Historical OTC volume exceeds $10 billion, with monthly flows in the $200–$400 million range. Neutrl only needs a fraction of this to scale meaningfully. Early traction supports this thesis. The private beta attracted ~$50 to 52 million with indicative APRs near 29–30%, and integrations with Pendle, Morpho, and Euler embedding NUSD and sNUSD into the broader DeFi ecosystem.
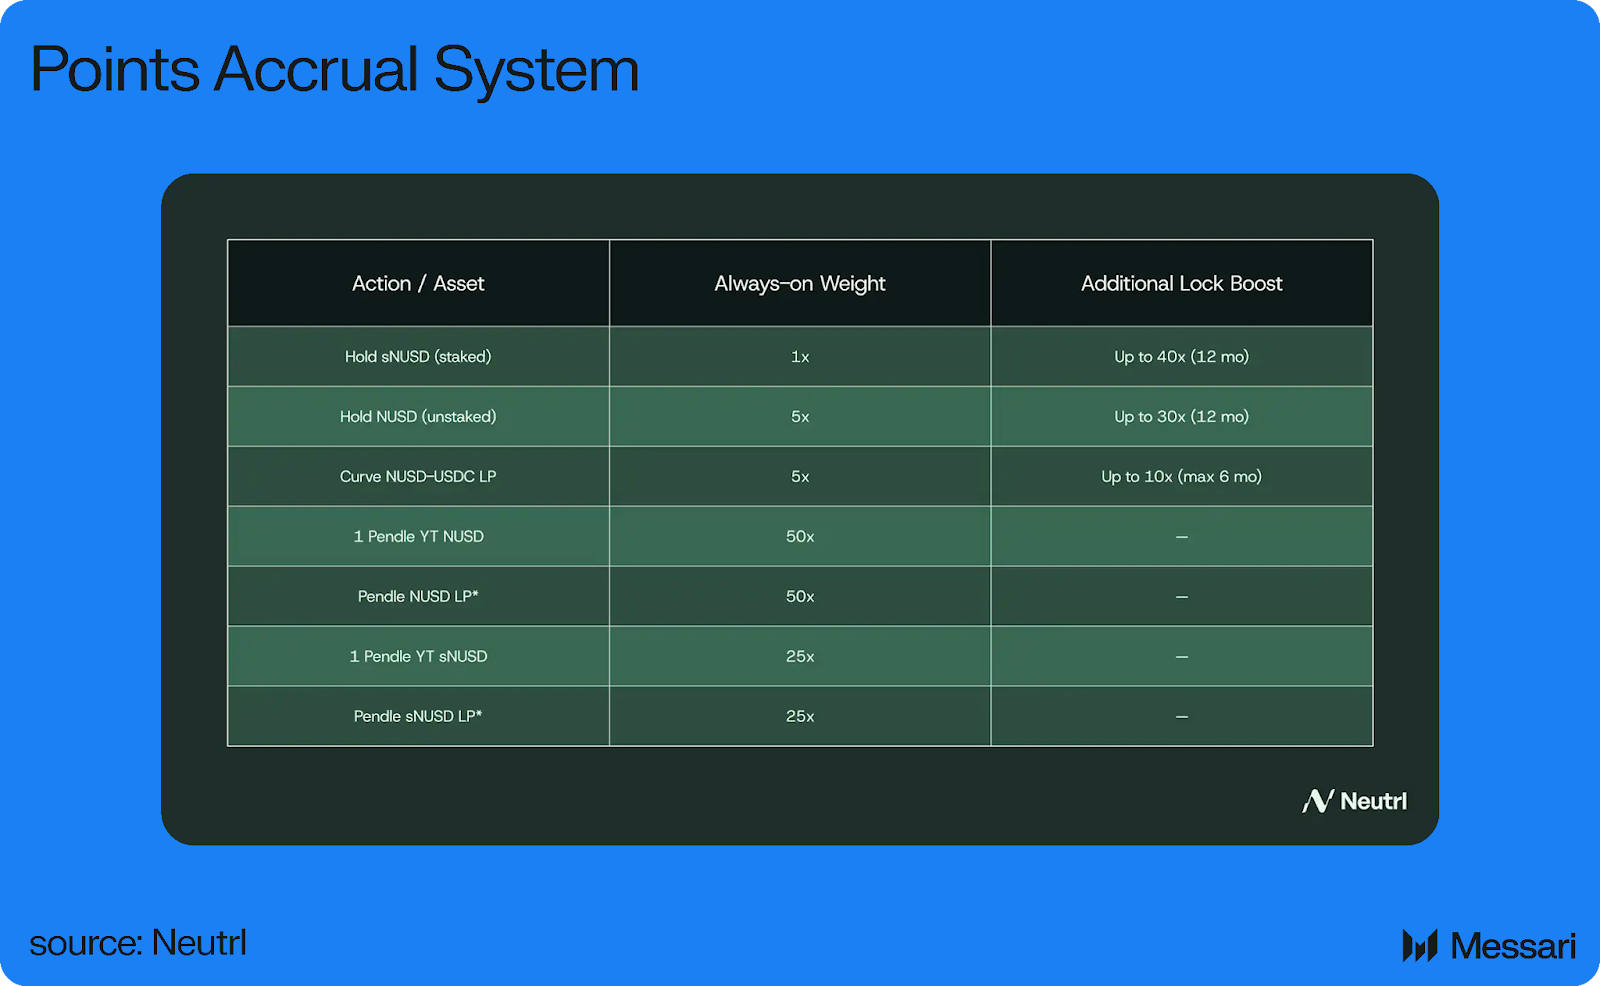
A complementary element of Neutrl’s growth model is the Points framework, which aligns user behavior with the protocol’s balance-sheet needs. Different actions receive distinct base weights. Longer lockups, such as twelve-month sNUSD commitments, provide the highest multipliers because they extend liability duration and support larger, longer-dated OTC deployments, while liquid positions earn lower weights but still improve secondary-market depth and redemption stability.
By linking multipliers to position type and time horizon, the framework shapes the system’s overall maturity profile in a predictable way. Pre-deposit participants, already accruing Points, form the initial base of longer-duration capital. As Neutrl scales, Points function less as an incentive program and more as a coordination mechanism, helping align user commitments with portfolio duration and enabling deeper deployment into market-neutral strategies without elevating liquidity or redemption risk.
Governance
Neutrl’s governance framework is expected to evolve as the protocol scales. While the current design prioritizes operational reliability and risk management, Neutrl Labs anticipates transitioning toward a more formalized governance structure over time. Planned developments include establishing defined procedures for proposing and evaluating changes to key system parameters, documenting all governance processes publicly, and expanding independent oversight as the protocol matures.
At present, protocol control resides with contributors at Neutrl Labs, who can execute emergency actions such as initiating system pauses or rebalancing positions in order to protect users. These interventions require multisign approvals and are disclosed through official communication channels. Routine parameter adjustments or architectural changes are announced in advance to maintain transparency.
Neutrl Labs is also evaluating the creation of an independent Risk Committee responsible for reviewing reserve management, margin practices, and major incidents. This body would formalize oversight, enhance accountability, and strengthen the protocol’s long-term governance and risk framework.
Conclusion
Neutrl generalizes and extends the synthetic-dollar model beyond the now-standard basis-trade wrapper. By combining discounted locked-token purchases, systematic hedging via perps, diversified basis and funding strategies, and yield-bearing stablecoins, it seeks to create a synthetic dollar whose yield is rooted in structural inefficiencies in both private and public crypto markets. Its architecture separates stability and yield through NUSD and sNUSD, applies conservative valuation standards to illiquid positions, and relies on duration matching and dynamic allocation to maintain solvency and user trust.
In doing so, Neutrl tackles several of the major challenges facing yield-bearing stablecoins today: yield compression from crowded trades, fragility in the face of funding-rate reversals, opacity around backing, and the misalignment between short-term liquidity demands and long-dated asset exposures. The protocol’s reliance on the evolving OTC market for locked tokens and on funding spreads in derivatives markets means that its performance will be sensitive to macro-cycle dynamics, competition, and the continued presence of counterparties willing to sell at discounts. Its success will hinge on execution quality, risk discipline, and the ability to maintain conservative practices as capital scales.
This report was commissioned by Neutrl. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
FaustianCreek is a Research Analyst for Messari. His main interests are in AI Infra, DePIN, and DeFi. FaustianCreek was a former consultant at a number of asset management firms in addition to prior experience at a DePIN protocol.
FaustianCreek is a Research Analyst for Messari. His main interests are in AI Infra, DePIN, and DeFi. FaustianCreek was a former consultant at a number of asset management firms in addition to prior experience at a DePIN protocol.