This report was commissioned by Native. By providing this disclosure, we aim to ensure that the research reported in this document is conducted with objectivity and transparency. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Blockworks. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Blockworks maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) submit financial conflict of interest (FCOI) disclosures on a monthly basis that are reviewed by appropriate internal parties and may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
Native: Scaling Tokenized Equity Markets

Key Takeaways
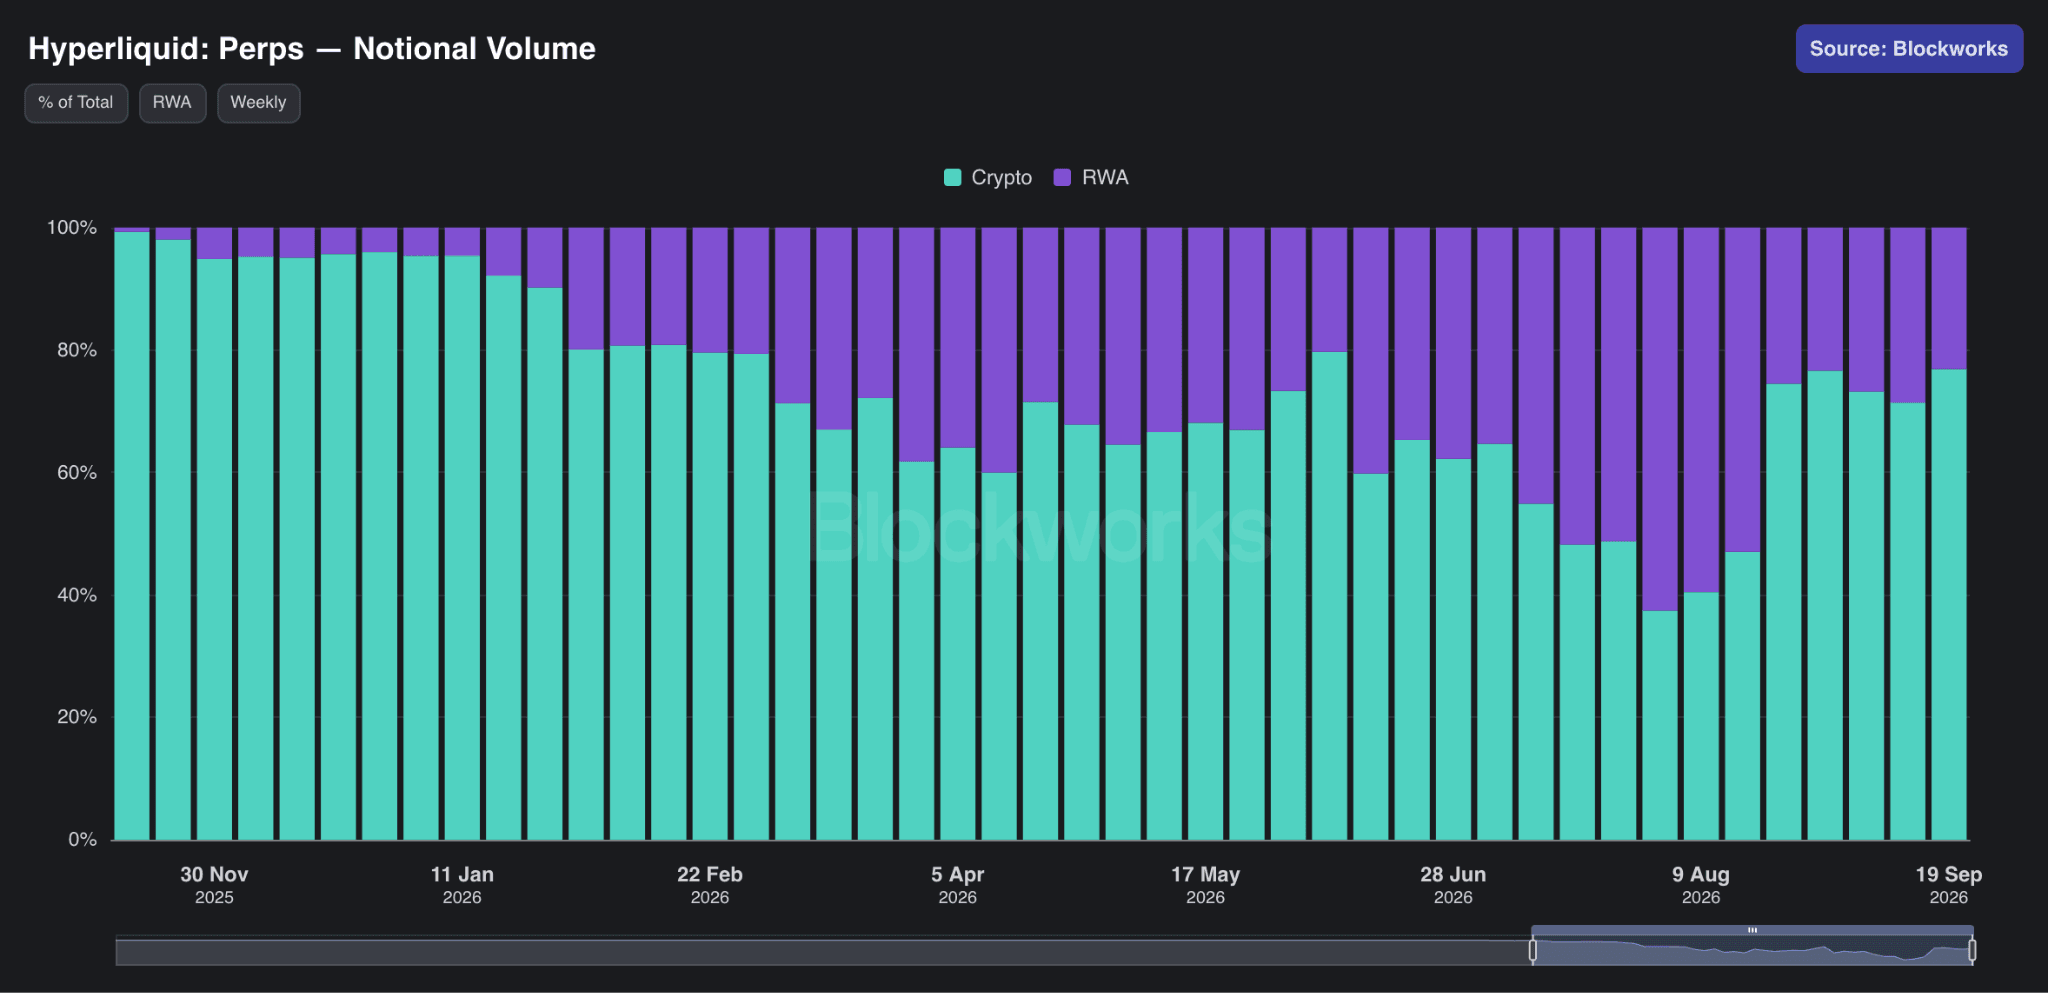
- Onchain markets are expanding beyond crypto-native assets. RWAs reached more than 60% of Hyperliquid’s weekly perpetual volume at their early-August peak, while spot tokenized equity volume increased over 100x in six months and briefly approached 20% of total spot DEX volume.
- Passive AMMs remain valuable for long-tail and correlated pairs. However, most tokenized equities trade against stablecoins and track efficient external markets, making active pricing, reliable quotes and deterministic execution crucial for scaling this market.
- The shift is already visible on Solana, where propAMMs overtook passive AMMs in September 2025 and now dominate SOL-USD trading. Active venues also gained tokenized equity share as volumes increased, although incentives and aggregator routing make market share an imperfect measure of execution quality.
- Native is building toward a shared liquidity layer that combines active pricing, onchain price discovery and external LP capital. Native Relay is its established RFQ and distribution engine, while Native Core entered public beta in late August. The bStocks volume analyzed in this report was executed through Relay rather than Core.
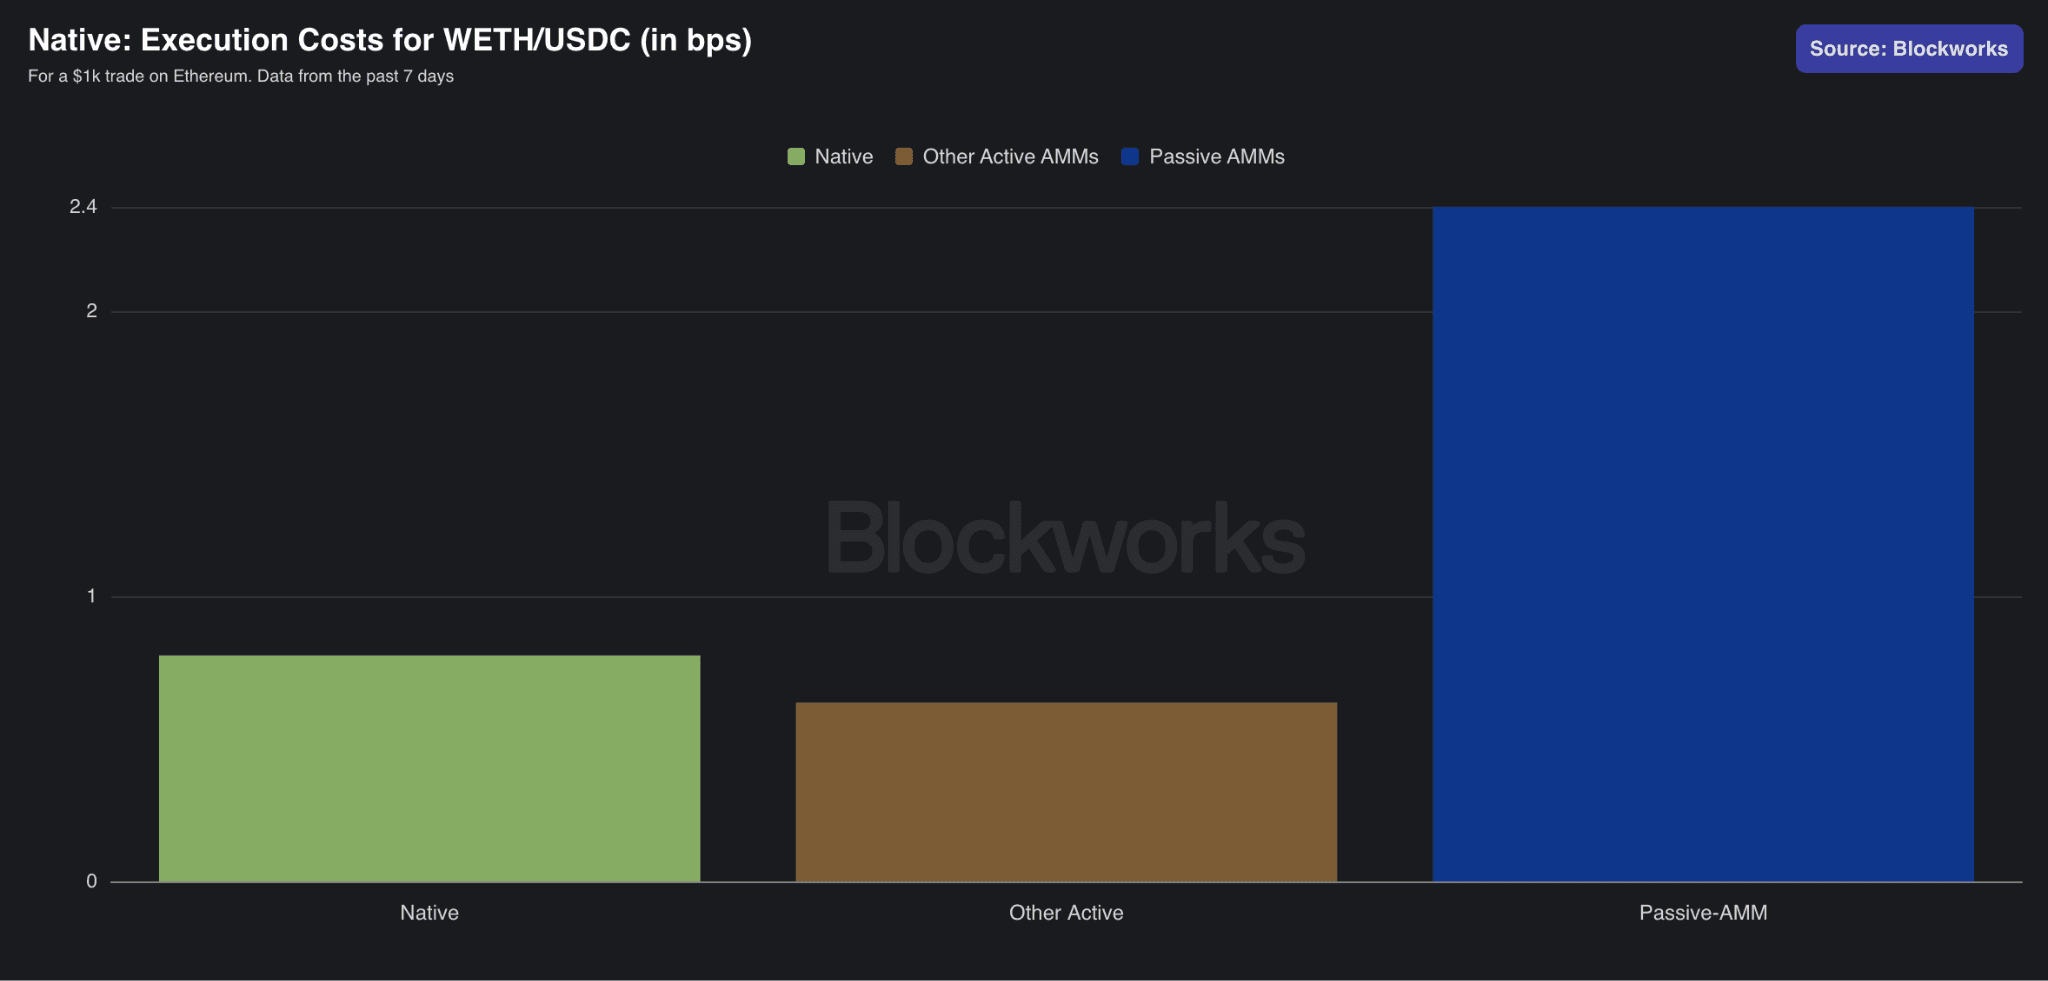
- Native processed $9.3B of tokenized equity volume on BNB Chain between July 15 and August 31, accounting for 50% of the chain’s tokenized equity spot DEX volume. During the 30 days ending August 31, the platform also generated $548K in trading fees, while its measured execution cost for a $1,000 WETH-USDC trade was 66% below passive AMMs.
Introduction: The Rise of Tokenized Equities
Onchain finance is expanding into a 24/7 market for equities, commodities, foreign exchange and other real-world assets (RWAs).
Perpetual futures already show how quickly this shift can happen once the right market structure is in place. Hyperliquid’s onchain order book allowed HIP-3 markets to reach meaningful scale. By mid-July, RWA markets had overtaken crypto-native markets in notional volume, with their share of Hyperliquid’s weekly volume peaking above 60% in early August, up from effectively zero a year earlier.
Centralized exchanges are moving in the same direction. Binance listed its first equity perpetuals in March 2026 and brought tokenized equities to spot markets in June with the launch of bStocks. Between June 11 and August 11, it added roughly 50 tokenized equities but only two new crypto spot listings. For a venue built around crypto-native assets, that change shows how quickly real-world markets are becoming part of the industry's core product offering.
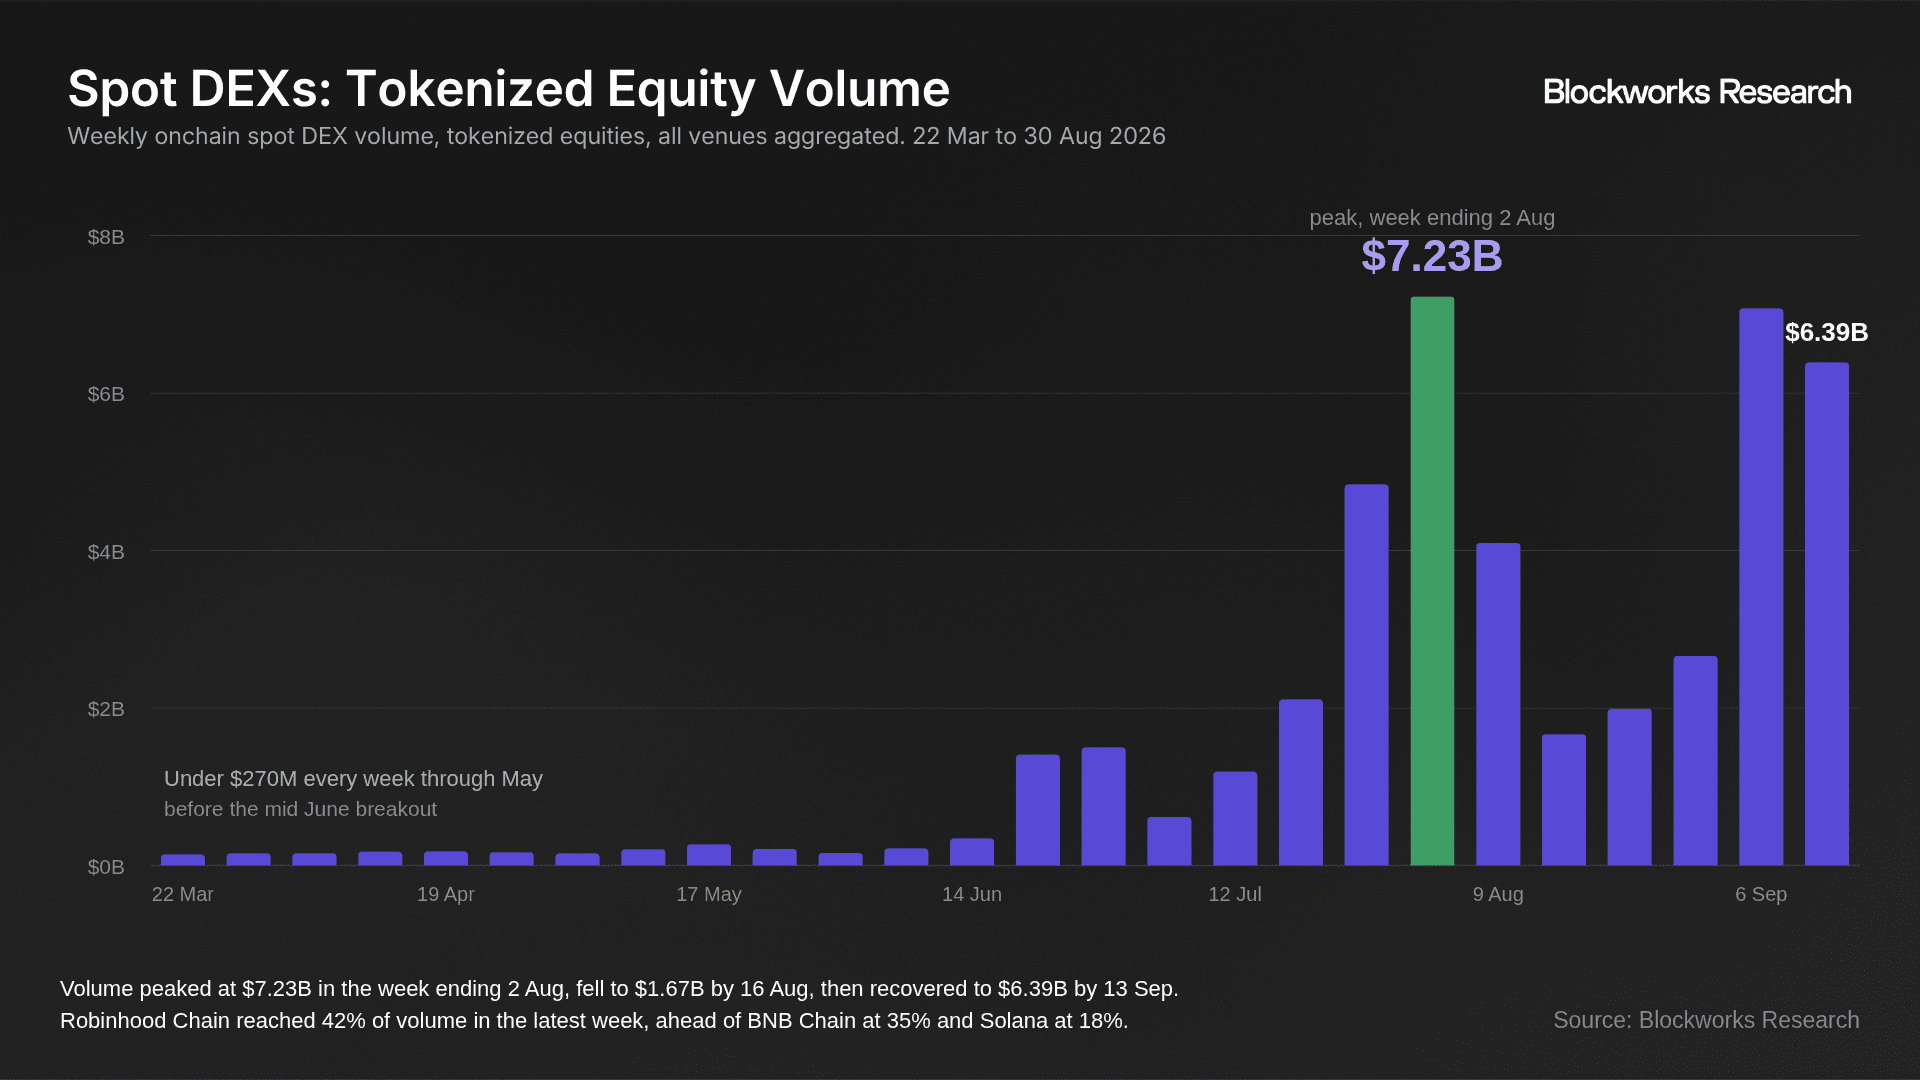
Spot DEXs are now seeing a similar expansion. Aggregate tokenized equity volume increased more than 100x in less than six months, from approximately $50M in early February to a weekly peak of $7.23B in late July. Tokenized equities remain small relative to their addressable market, but their share of spot DEX volume rose from a rounding error to nearly 20% during the final week of July.
The market structure underneath that growth remains immature. Tokenized equities require reliable quotes and execution against external reference prices that are already highly efficient. This report examines whether existing onchain liquidity models can meet that standard and uses Native as a case study in combining active pricing, transparent matching and permissionless capital provision.
1. The Problem: An Immature Spot Market Structure
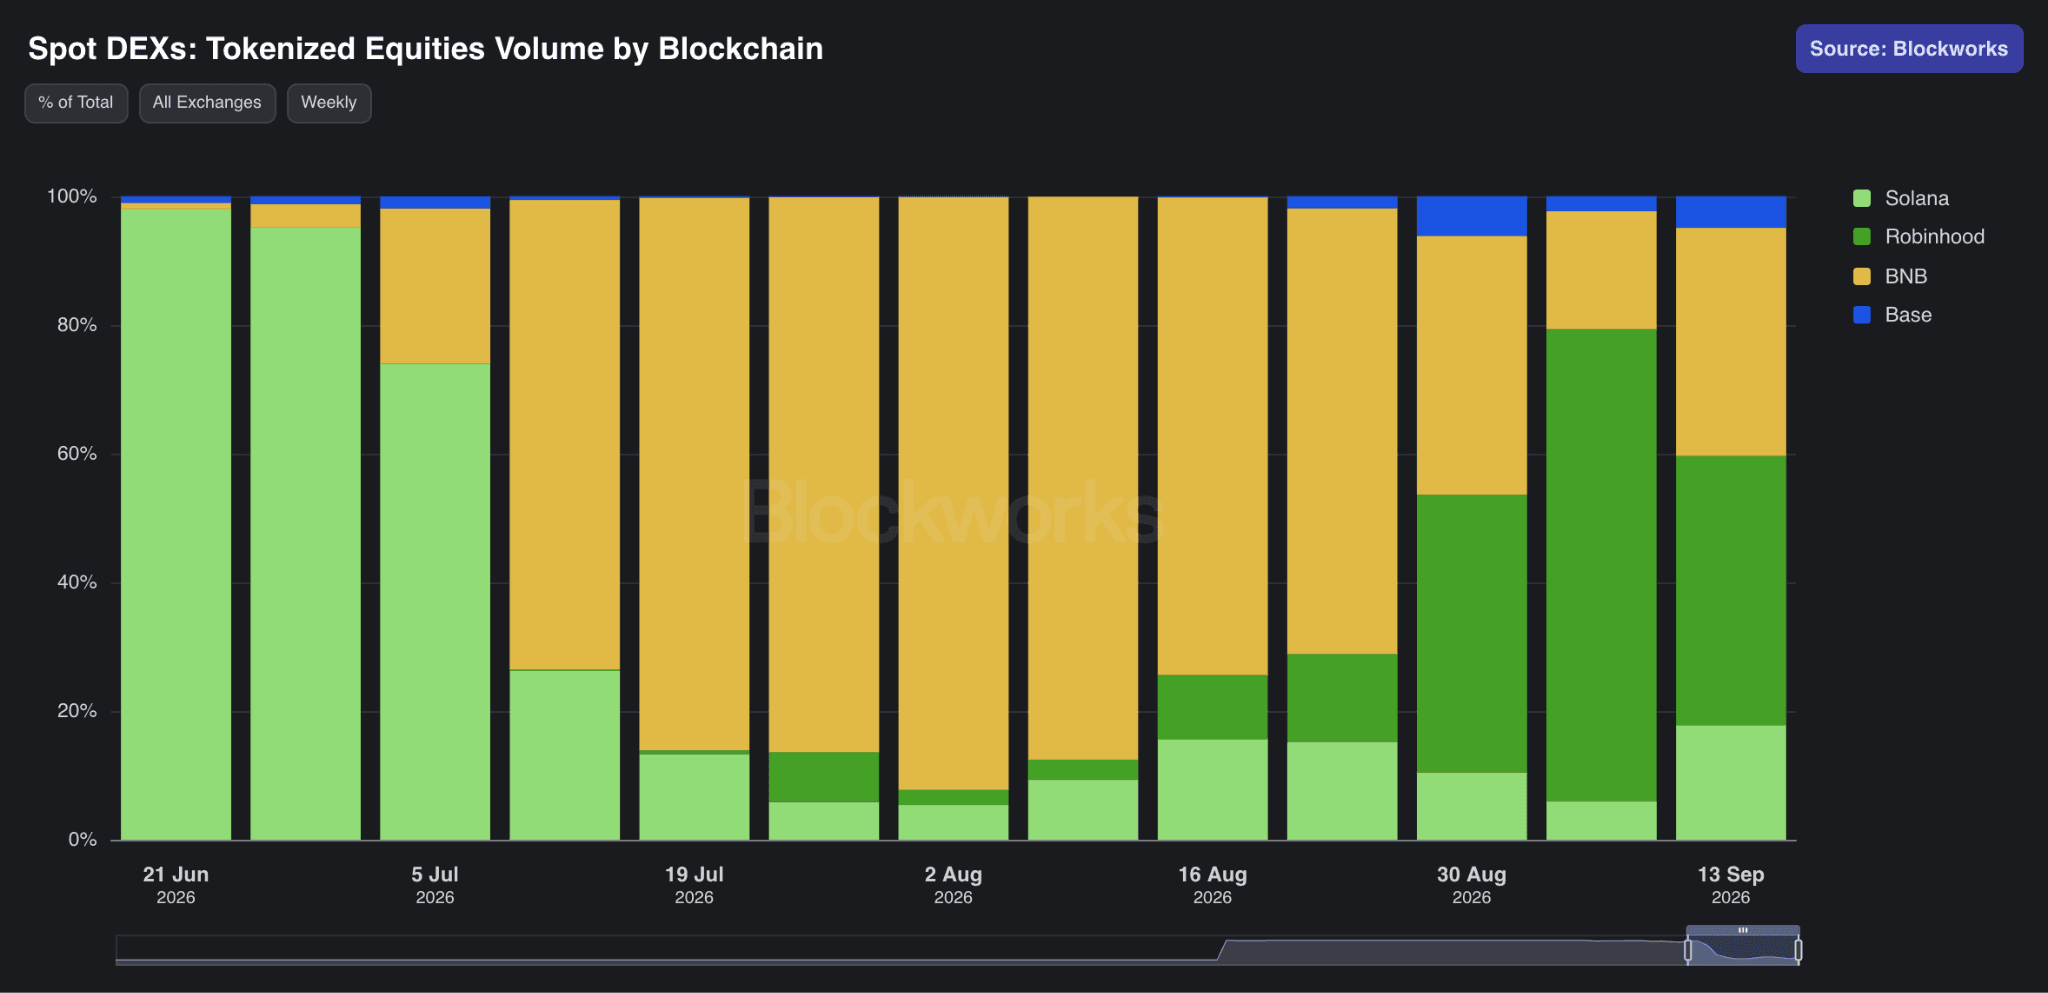
Tokenized equity activity has concentrated on Solana, BNB Chain and, more recently, Robinhood Chain. Solana led through the first half of 2026 before BNB Chain surpassed $1B in daily volume in late July. BNB Chain still led weekly volume at the end of August with a 43% share, compared with Robinhood Chain’s 36%.
Robinhood Chain then took the daily lead in early September, reaching a peak of nearly $1.5B in tokenized equity volume on September 4. Unlike Solana and BNB Chain, where activity initially centered on equity-stablecoin pairs, Robinhood Chain’s growth has been driven by memecoin-equity pairs, though the durability of that activity remains uncertain.
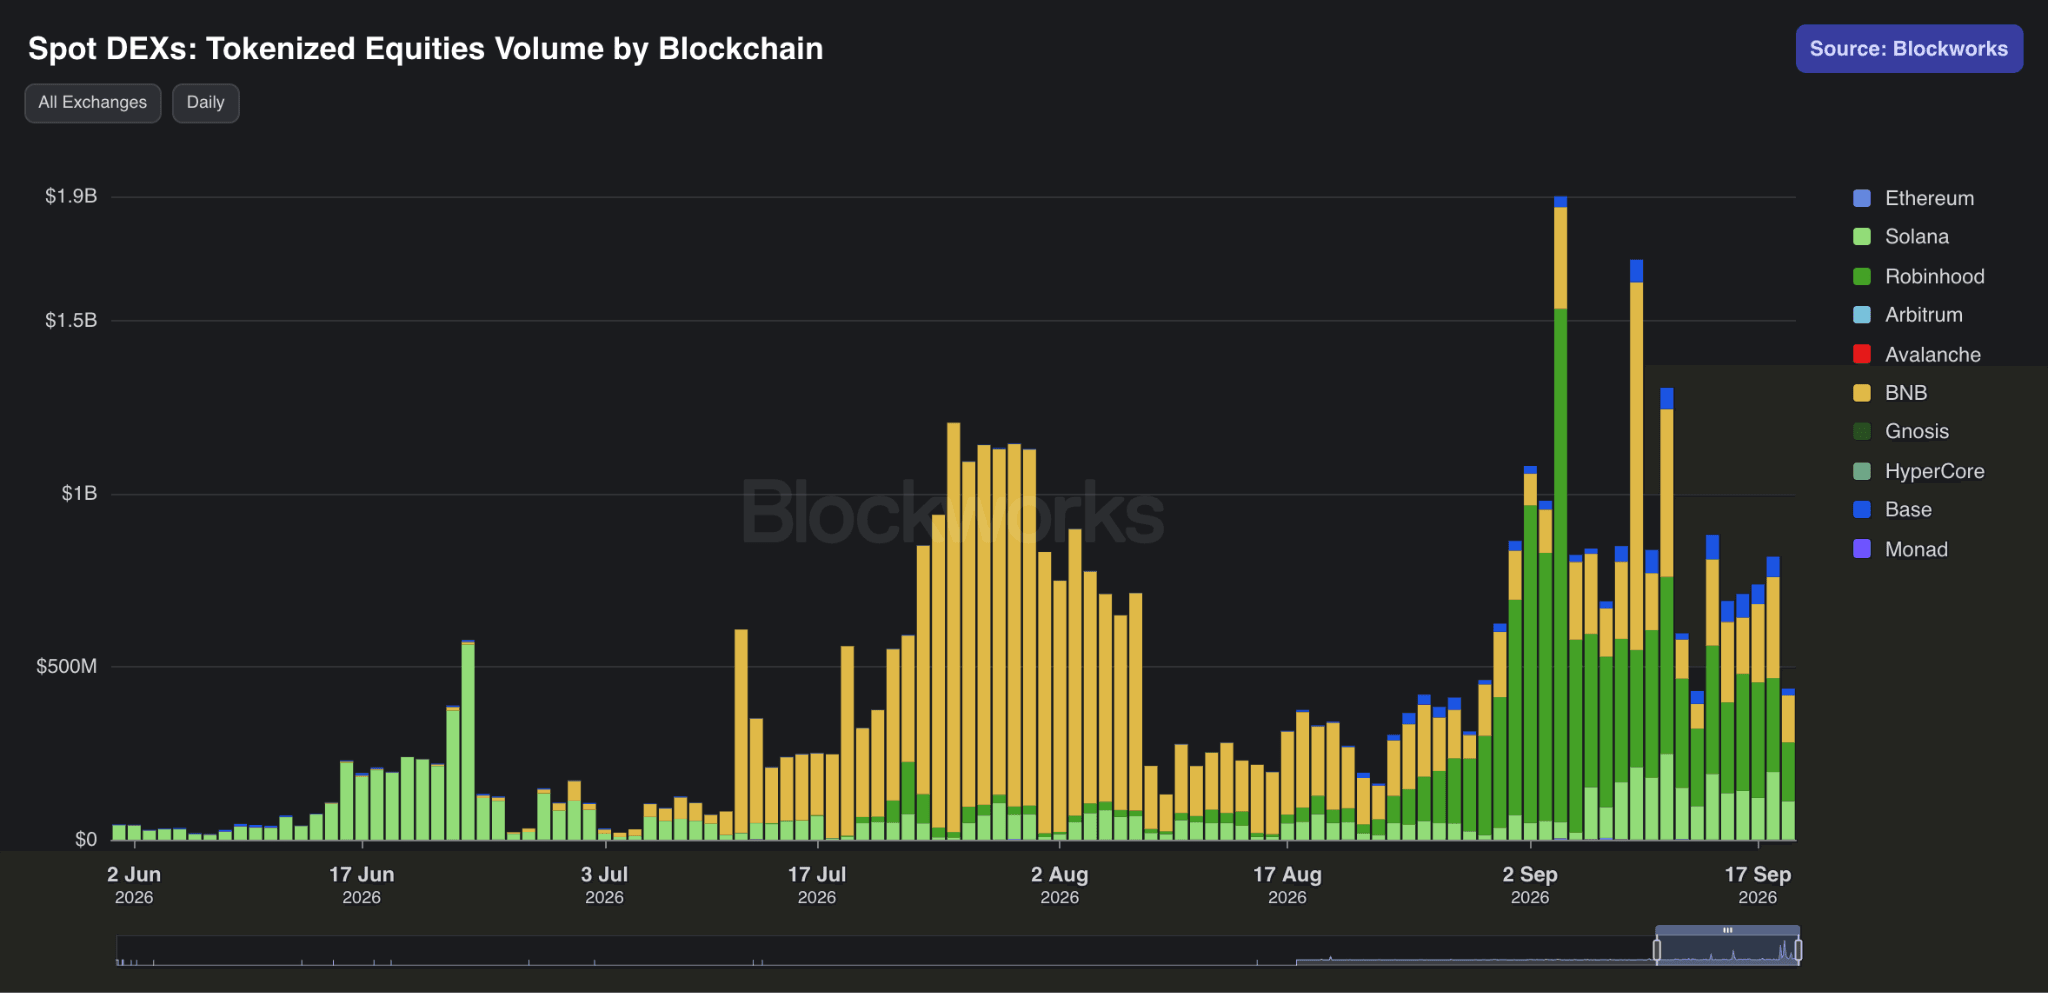
BNB Chain accounted for about 92% of tokenized equity spot DEX volume during the final week of July, but its rise coincided with Binance Alpha incentives that awarded amplified points for purchases of QQQB and several other tokenized equities. Near-zero trading fees also made repeated turnover inexpensive. The resulting activity demonstrates distribution and execution capacity, but headline volume is a noisy measure of demand that may not persist after incentives fade.
Beneath these volumes, three liquidity models matter:
- Passive AMMs allow anyone to supply liquidity against a predefined curve. They are permissionless and continuously available, but execution depends on the pool's state when a transaction lands. When an asset has a fast-moving external price, pools can remain mispriced until arbitrageurs update them, exposing LPs to adverse selection.
- PropAMMs and RFQ networks use professional market makers to update quotes continuously. They offer more responsive and deterministic pricing, but generally lack a transparent pre-trade order book. Their liquidity is also constrained by the capital and risk appetite of participating market makers.
- Onchain order books expose bids, asks and available depth before execution. Historically, continuous order placement, cancellation and matching have been difficult to support onchain at competitive latency. Hyperliquid has shown that the model can scale in perps, although spot introduces additional inventory and cross-chain settlement requirements.
The best model depends on the pair. Passive AMMs are valuable for long-tail assets that cannot attract professional market makers and can compete in correlated pairs where relative-price risk is low. Active quoting matters most when prices move quickly and a liquid external reference market exists.
Tokenized equities favor active liquidity. Most trade against stablecoins, although memecoin-equity pairs have gained traction on Robinhood Chain and, most recently, Solana. In both cases, the equity leg tracks an efficient offchain reference price, while memecoin pairs add a second volatile asset. If onchain venues are to compete with traditional exchanges, they must update prices continuously and offer tight, reliable quotes.
Evidence from Solana and BNB Chain
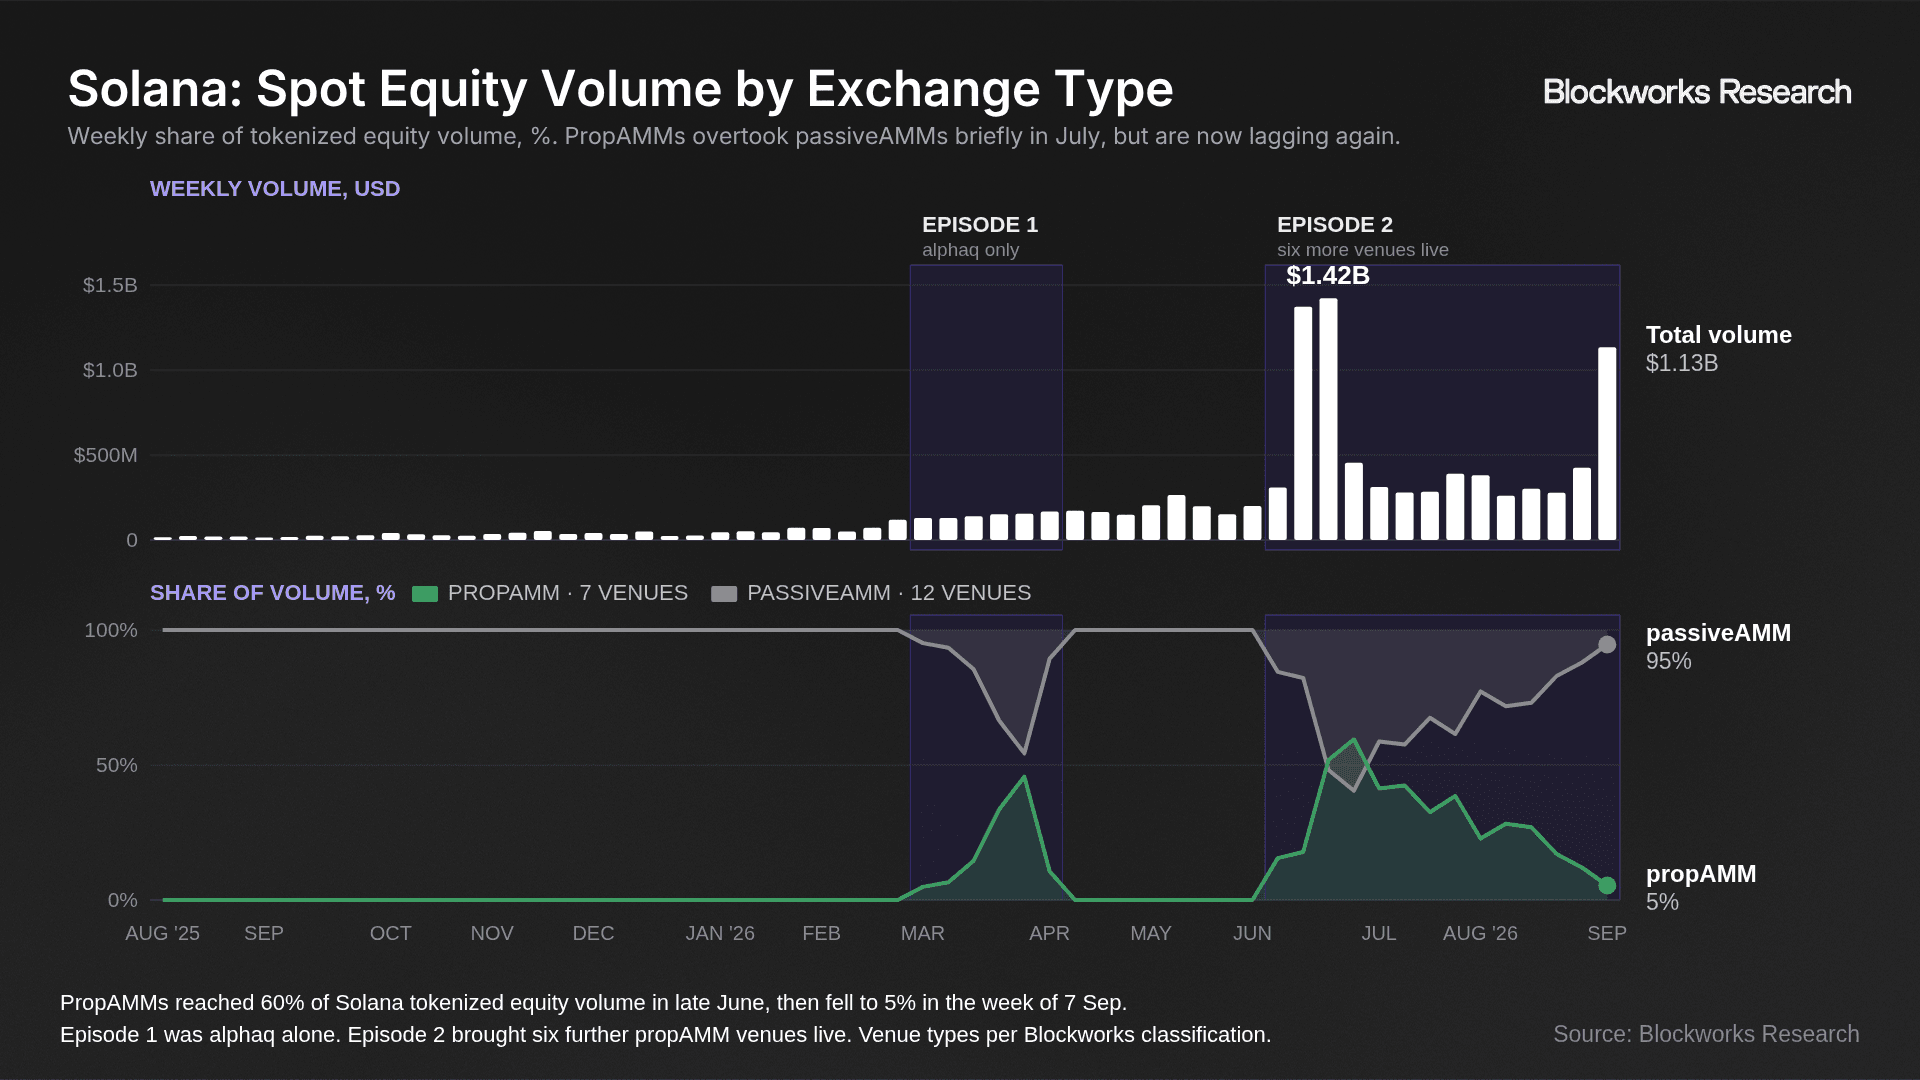
Solana’s broader spot market illustrates the advantage of active pricing in volatile pairs. PropAMMs overtook passive AMMs in overall DEX volume in September 2025 and now dominate SOL-USD trading. Tokenized equities initially followed the same pattern, with propAMMs capturing more than 50% of volume as activity accelerated in July. However, their share has since fallen to 5% as memecoin-equity pairs gained traction, with Raydium capturing most of that activity.
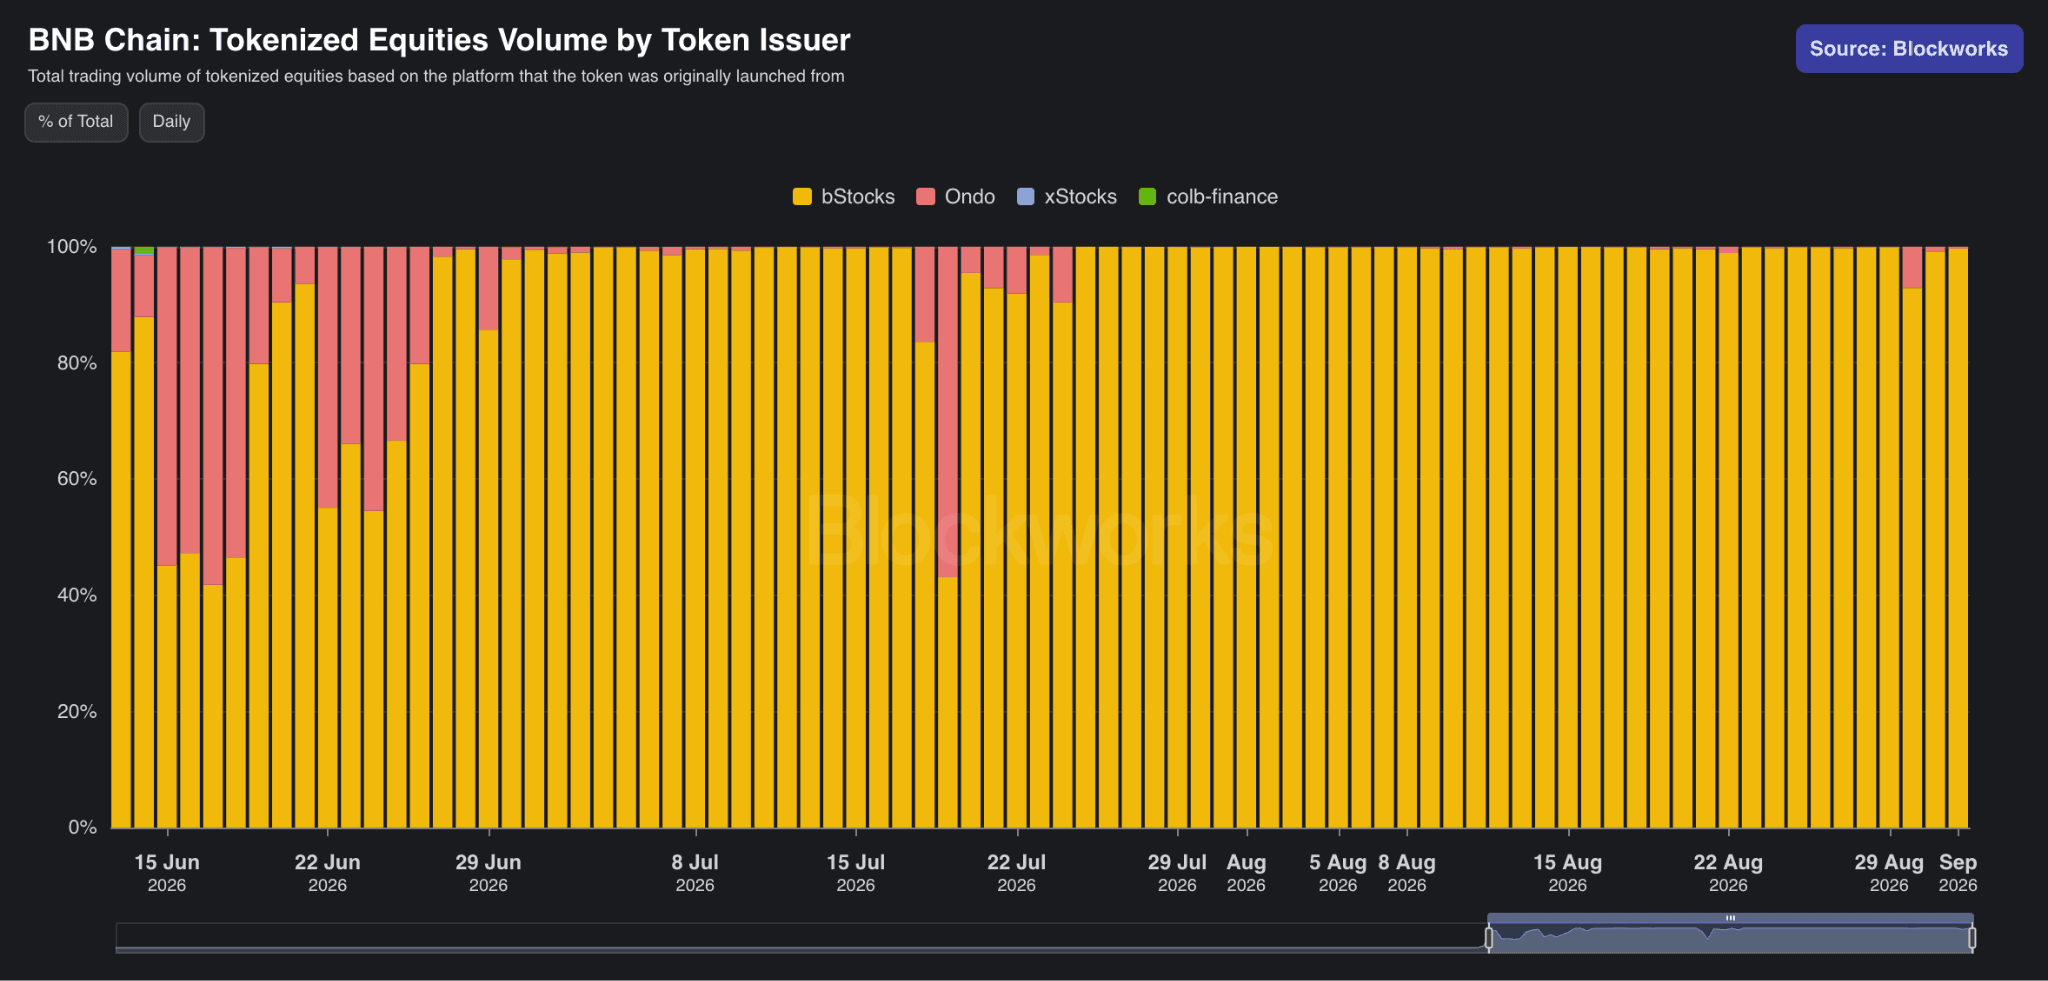
BNB Chain offers a more concentrated case. Although Ondo and xStocks were already available on the network, recent activity has centered on bStocks, the tokenized equities introduced through Binance in June.
Binance supplied distribution, while Native, Tessera, PancakeSwap, Uniswap and other venues provided onchain execution. Native and Tessera captured much of the initial increase in volume. As activity declined, passive venues such as PancakeSwap and Uniswap regained share.
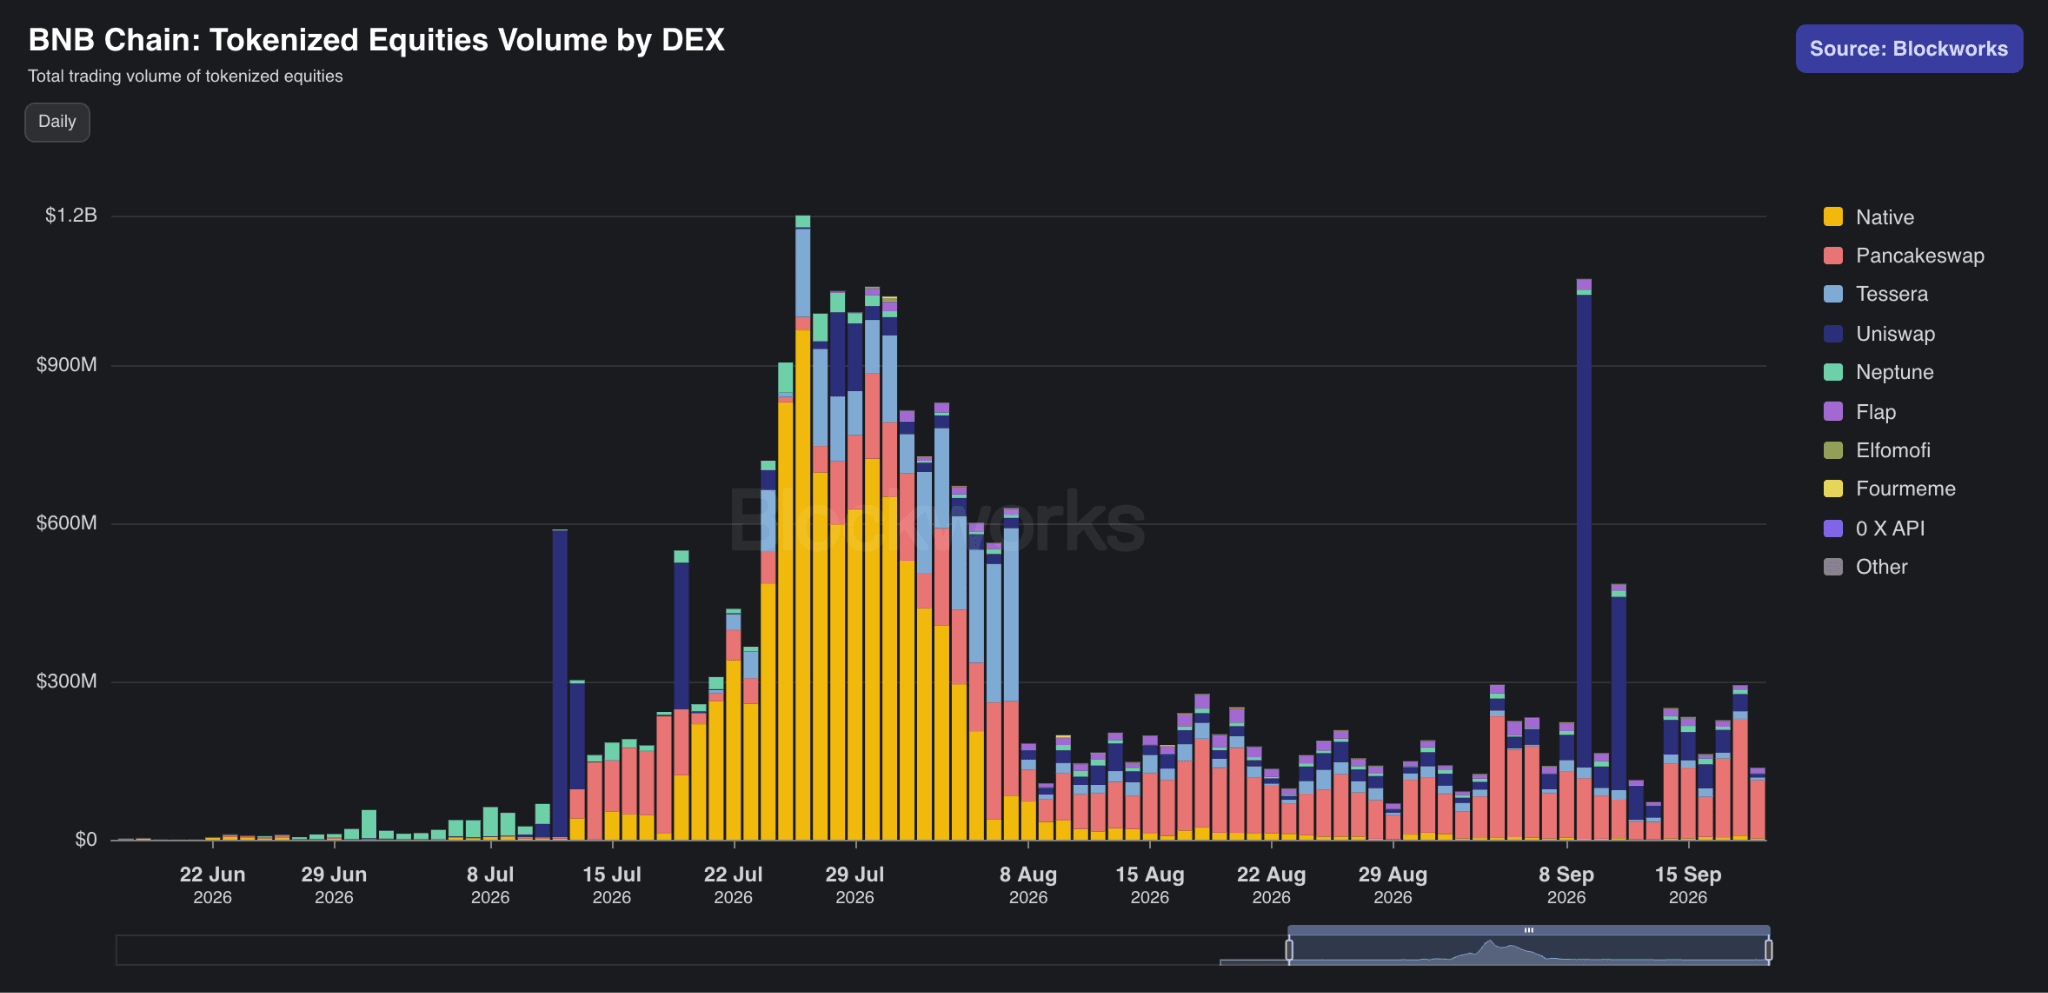
DEX share alone does not prove better execution. Incentives, asset coverage and aggregator routing all affect where trades land. Still, both ecosystems suggest a similar division of labor: passive AMMs provide baseline liquidity, while active venues become more competitive when flow is larger and more price-sensitive.
2. The Comparative Landscape
The principal liquidity models differ across pricing certainty, capital access, pre-trade transparency, LP risk and suitability for RWAs.
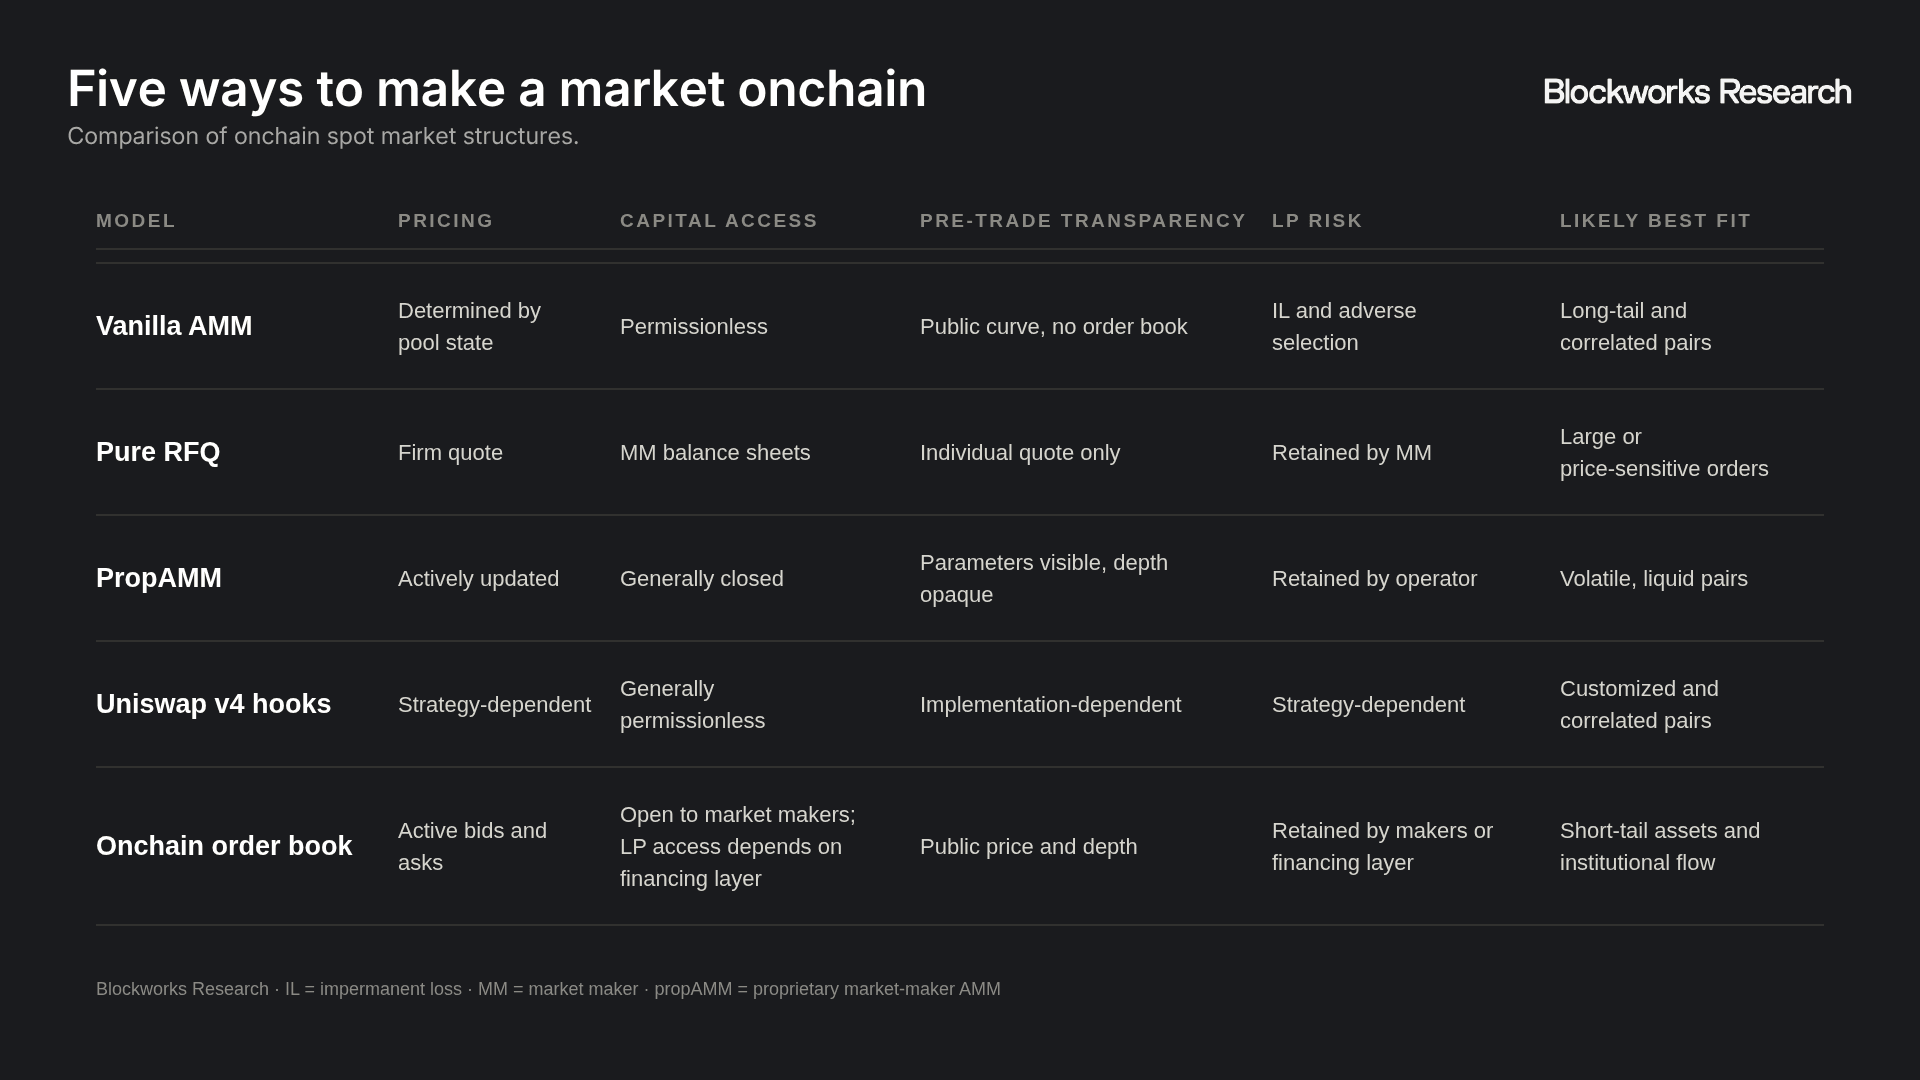
- Vanilla AMMs are permissionless, battle-tested and effective at creating markets without professional intermediaries. Their weakness is adverse selection when external prices move faster than their curves update.
- Pure RFQ networks provide firm quotes and can execute larger orders efficiently, but reveal no public depth and rely on the balance sheets of participating market makers.
- PropAMMs combine AMM-compatible settlement with actively managed pricing. They are capital-efficient, but are usually controlled and financed by a single operator, preventing outside LPs from expanding quoting capacity.
- Uniswap v4 hooks enable dynamic fees, custom curves and other programmable strategies. They may improve passive liquidity, particularly for correlated assets, but execution still depends on pool state and the design of each hook.
- Fully onchain order books display bids, asks and depth, allowing multiple market makers to compete in public. Their historical constraint has been the latency and throughput required for continuous quoting.
No model dominates every market. Passive liquidity remains important where open access and low capital costs outweigh the value of constant repricing. For liquid assets tied to external markets, however, active quotes and deterministic execution become harder to avoid.
3. Convergence: Toward an Open Order Book
The boundaries between these models are already beginning to blur. PropAMMs resemble two-sided order books compressed into a small set of parameters, primarily spread and depth. RFQ networks provide firm quotes without displaying the market behind them. Uniswap v4 hooks allow AMMs to adjust fees and pricing logic dynamically. Each model is moving away from static liquidity and toward more active, quote-driven pricing.
PropAMMs have already displaced passive curves across price-sensitive markets on Solana such as SOL-stablecoin pairs. However, propAMMs stop short of becoming open market infrastructure. Each venue is controlled and financed by a single market maker, exposes little pre-trade depth, and can withdraw liquidity at any time. Aggregators reduce this fragmentation for traders, but they do not open the underlying supply of liquidity or capital.
Native’s architecture is designed to combine active pricing and transparent price discovery with outside capital across four components:
- Native Core is the onchain price-discovery and matching layer, which Native describes as a central limit order book operating with 50-millisecond block times. Core entered public beta in late August 2026 with permissionless deposits and withdrawals.
- Native Pool consists of smart contracts deployed across EVM chains, including BNB Chain, Ethereum, Arbitrum and Base. These contracts custody assets and enforce settlement. LPs supply assets on a single-sided basis, which collateralized market makers can elect to access through a credit system.
- Native Pro provides institutions and professional market makers with exchange-grade API and SDK access.
- **Native Relay **is Native’s established RFQ and distribution engine. It streams prices to wallets and aggregators and routes their order flow to professional market makers. According to Native, the bStocks activity was executed entirely through Native Relay’s RFQ engine rather than Native Core.
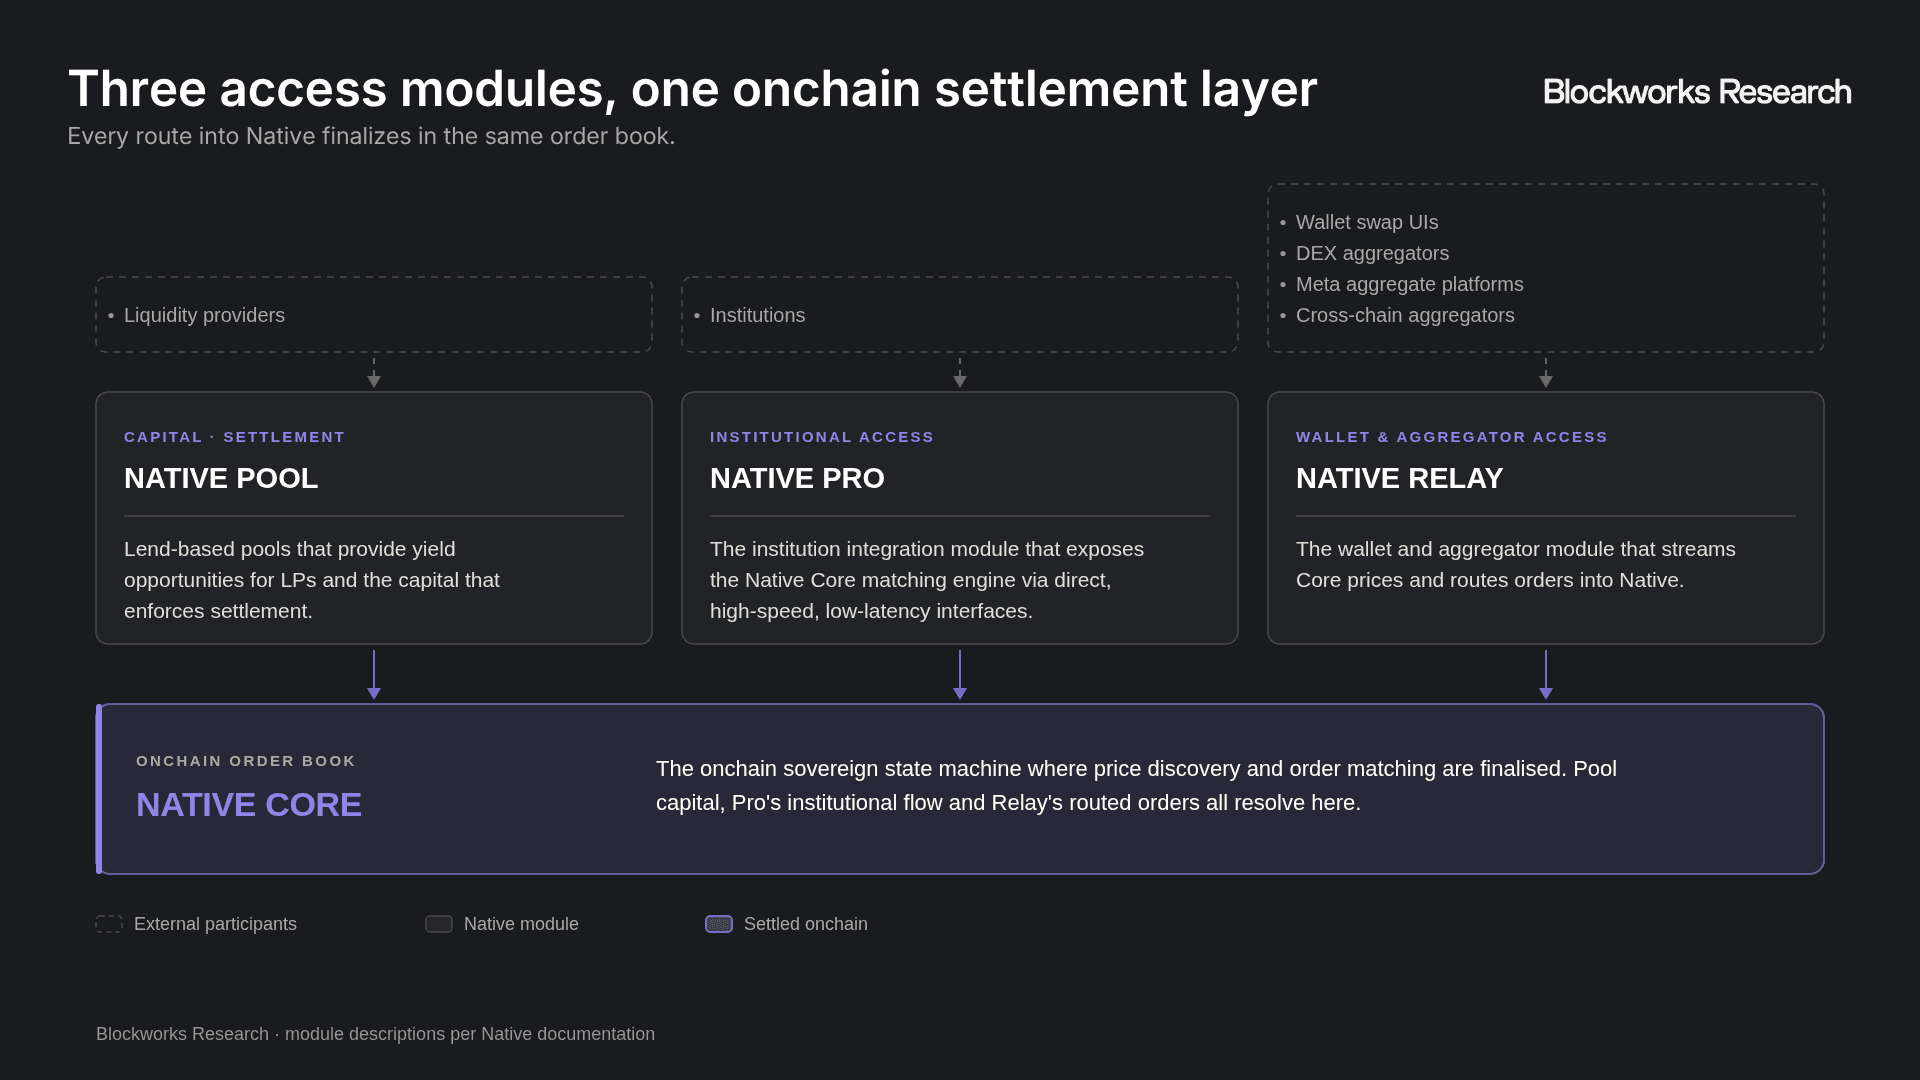
The key distinction in Native’s model is that outside capital can provide inventory without determining prices. LPs deposit assets on a single-sided basis into Native Pool, while professional market makers remain responsible for quoting. When a market maker elects to use Pool liquidity, the Pool supplies the asset sold to the trader and records the resulting position against the market maker’s collateral and credit limit. The market maker later settles that position by returning the borrowed asset and claiming the inventory received from the trade. This reduces the amount of inventory market makers must hold on their own balance sheets, while LPs avoid the conventional impermanent-loss exposure of a paired AMM position.
Importantly, this convergence does not mean passive AMMs will disappear. They remain well suited to long-tail assets and correlated pairs, where their lower cost of capital can offset less responsive pricing. But most tokenized equities trade against stablecoins, creating volatile pairs with highly efficient external reference markets. These markets are better suited to active, order-book-based liquidity.
The likely end state therefore combines three features that no existing model has fully delivered: reliable active pricing, transparent onchain price discovery, and outside capital financing market makers. Native is attempting to bring those features into a shared liquidity layer.
4. Case Study: Native
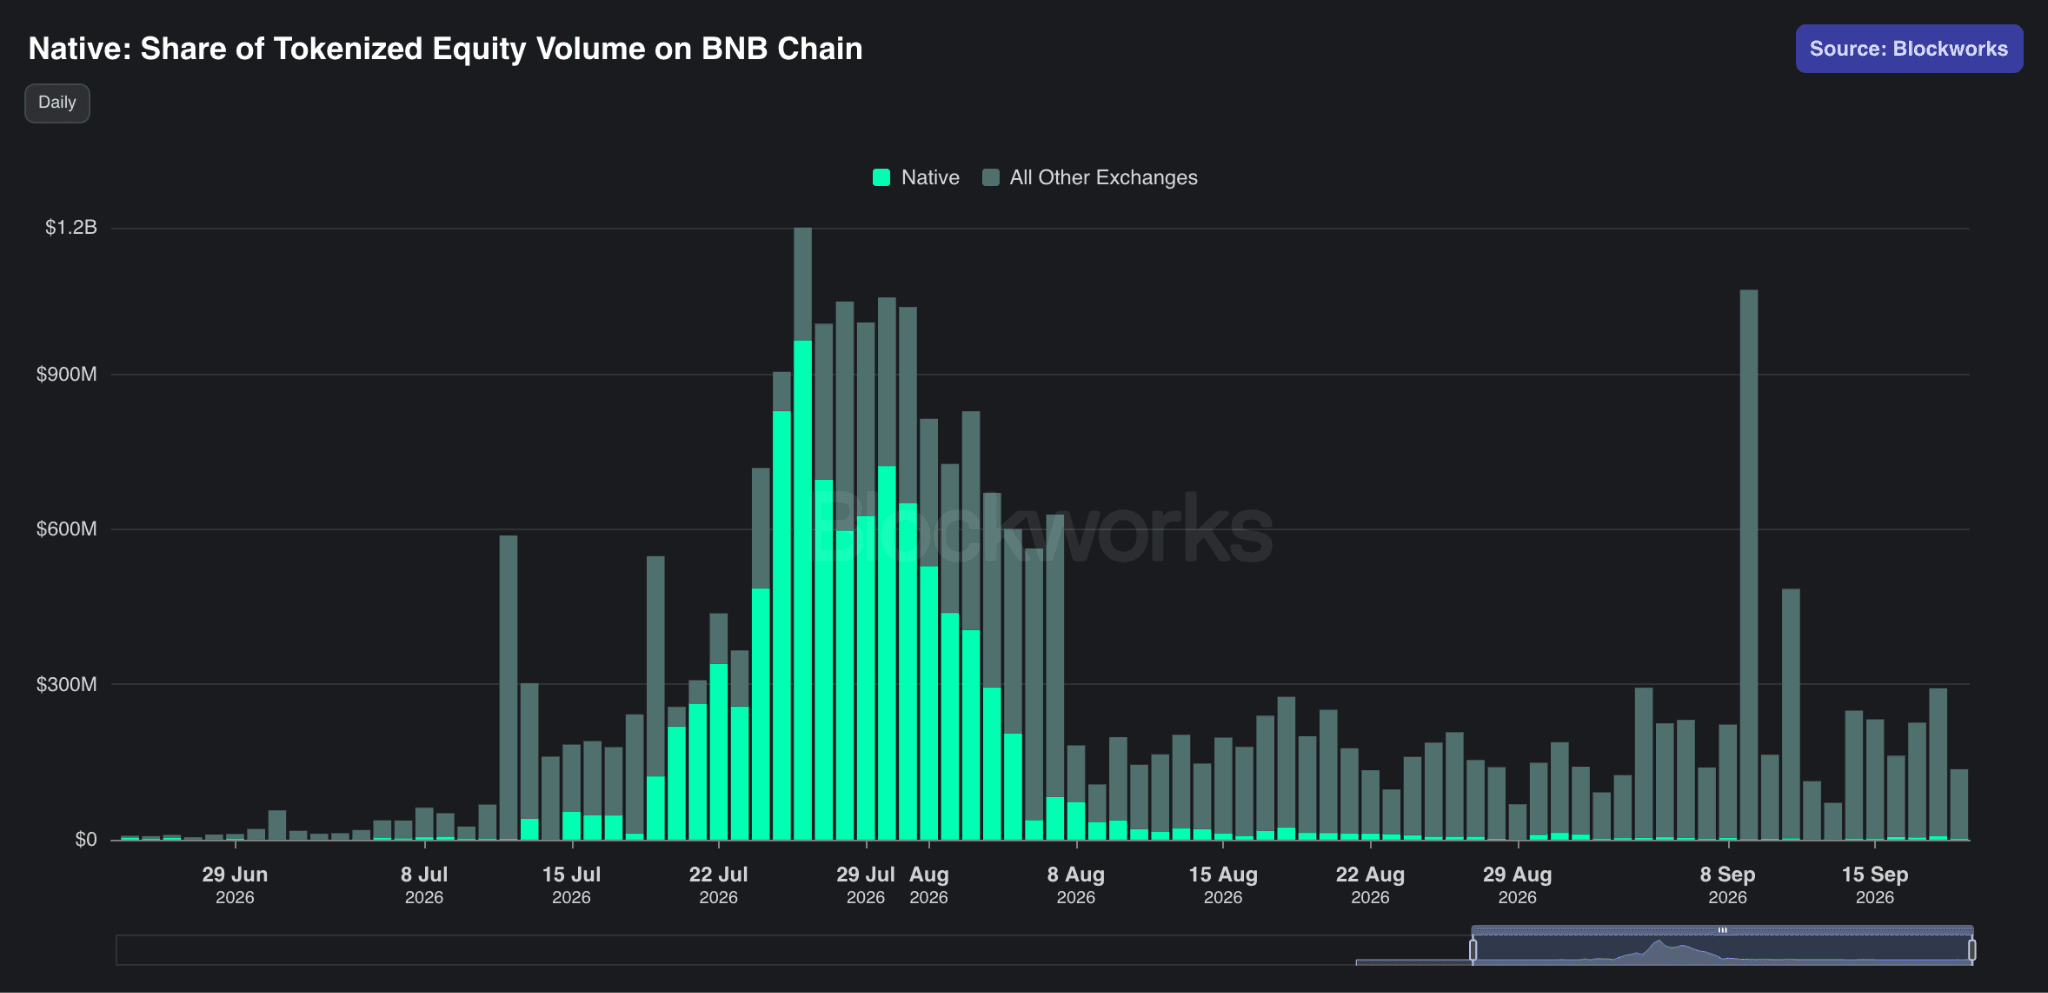
Native’s first meaningful test came from tokenized equities, particularly bStocks on BNB Chain. Activity was negligible through June before accelerating alongside the Binance Alpha incentives discussed earlier. Between July 15 and August 31, Native processed $9.3B of tokenized equity volume on BNB Chain, accounting for 50.5% of the chain’s tokenized equity spot DEX volume. According to Native, the bStocks activity was executed entirely through Native Relay’s RFQ engine rather than Native Core.
Activity peaked in late July. Native processed $965M on July 26 alone and captured 78% of BNB Chain’s tokenized equity DEX volume between July 21 and July 27. On July 26, its share reached 81.6%.
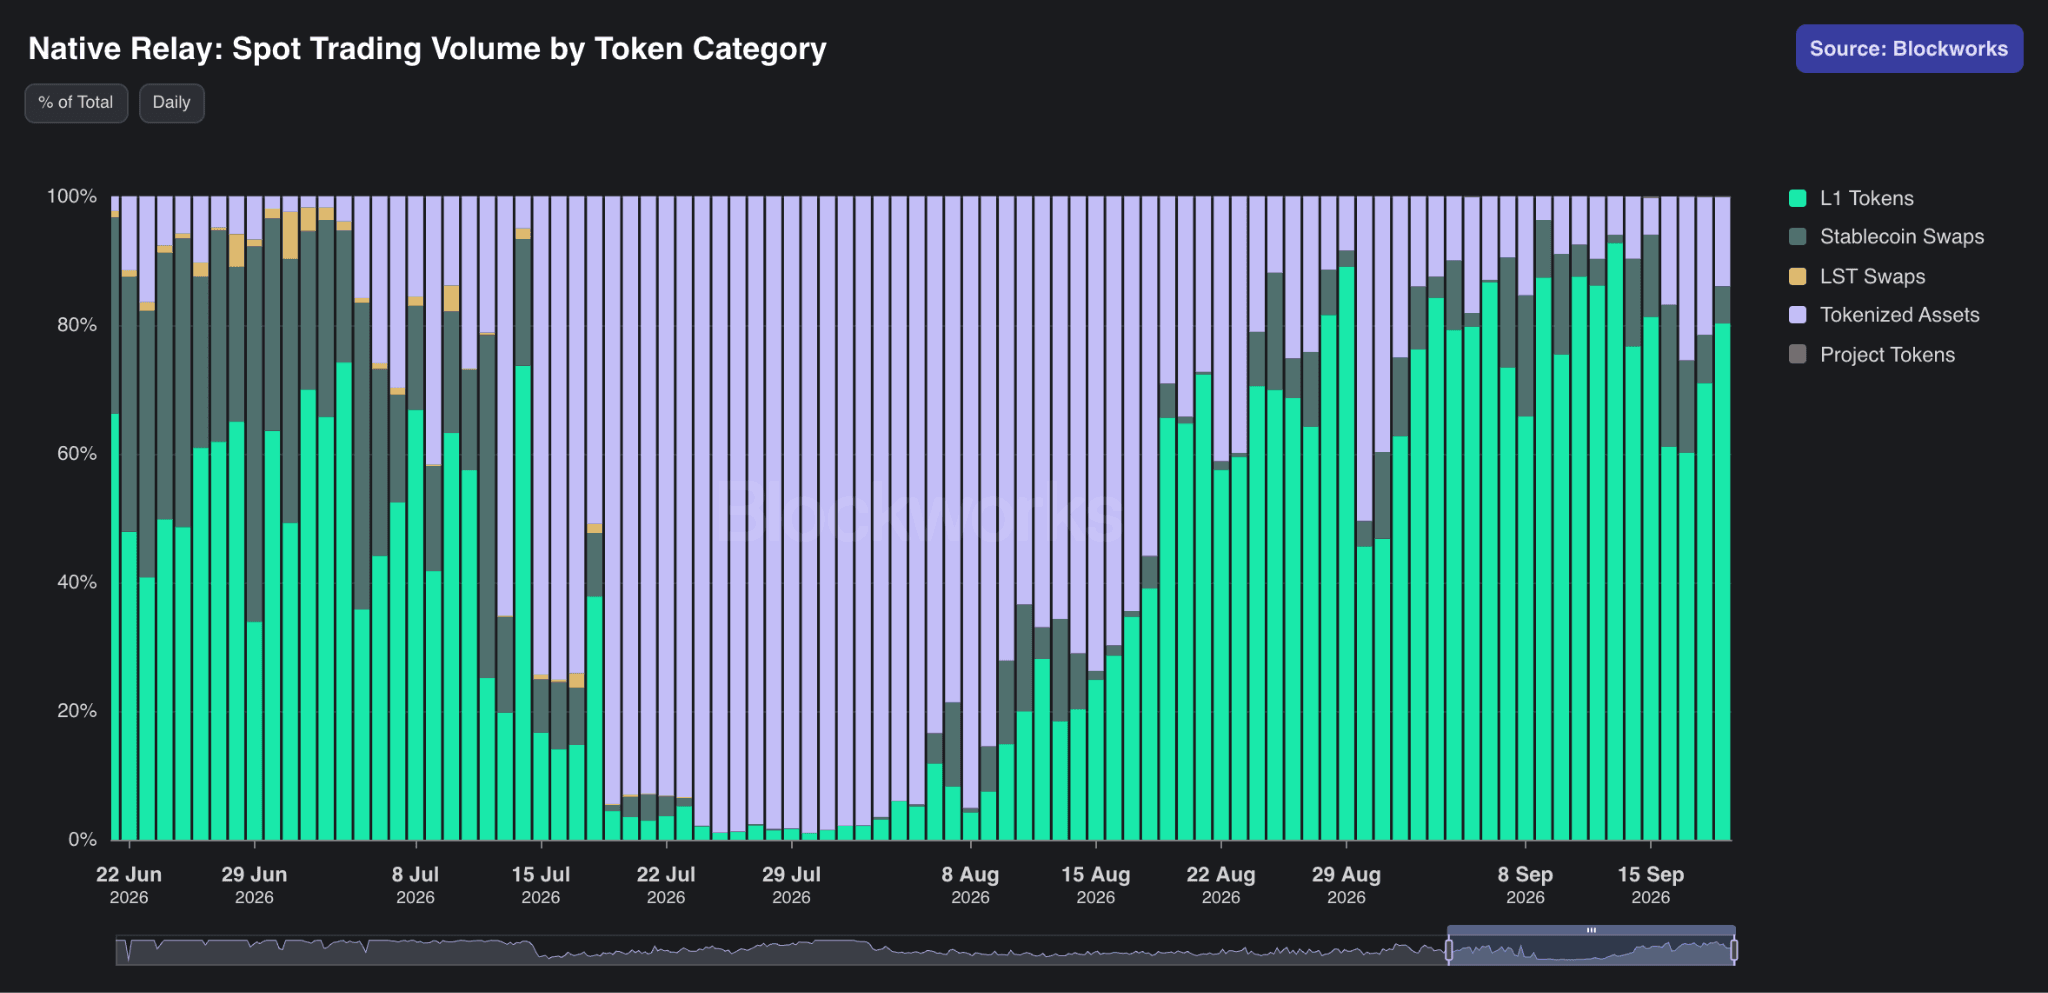
Looking across all asset categories, Native processed $2.36B in total spot trading volume during the 30 days ending August 31. Tokenized equities accounted for $1.84B (78.2% of the total), followed by crypto-native pairs (18.1%), stablecoin swaps (3.2%) and tokenized commodities (0.5%).
QQQB-USDT alone generated 72.6% of total volume, while the five largest pairs accounted for 91.7%. Native nevertheless supported 31 active tokenized-asset markets on August 31, indicating that its asset coverage was considerably broader than its volume distribution.
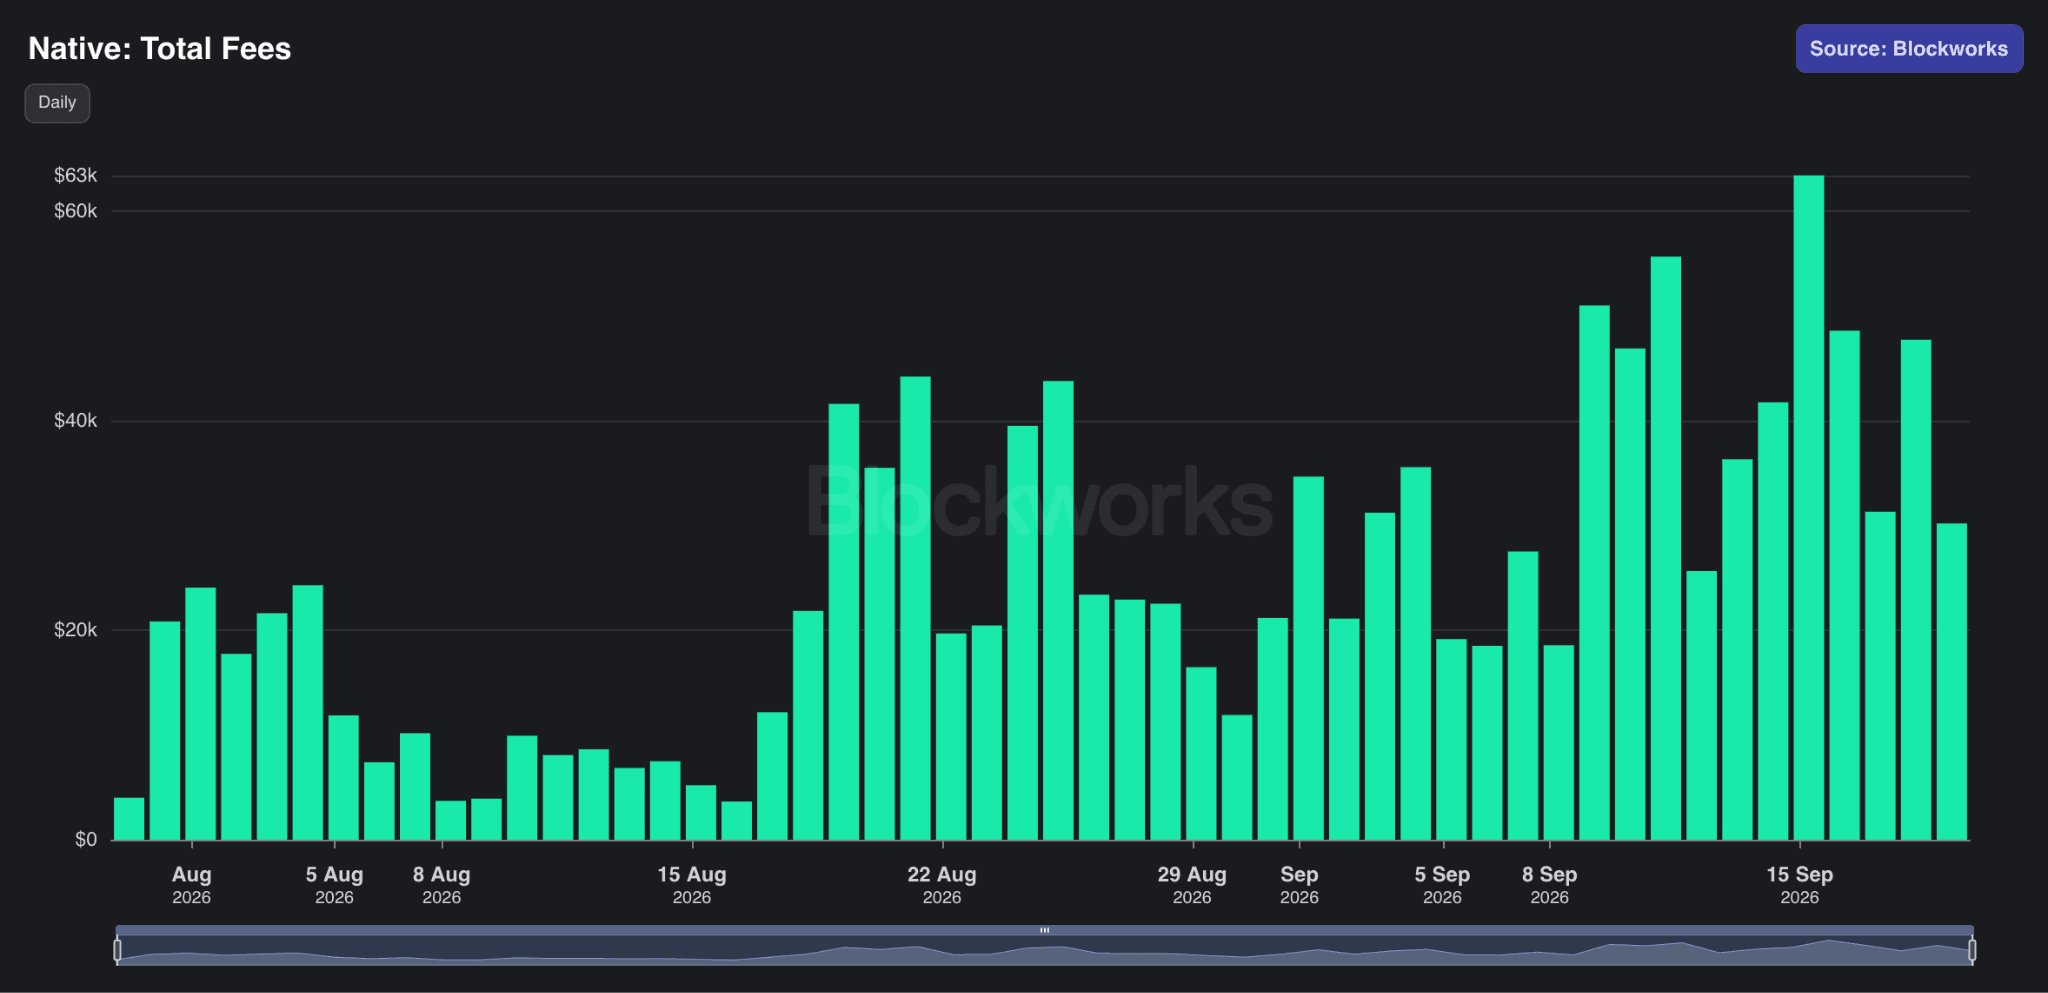
Over the same 30-day period, Native generated $548K in trading fees, equivalent to 2.3 basis points of spot volume. Taker fees accounted for 84% of the total, with maker fees contributing the remaining 16%. Fee generation accelerated in September, averaging $36.1K per day between September 1 and September 19, 95% above the August average of $18.4K.
Execution quality provides a more direct test of Native’s model than volume alone. For a $1,000 WETH-USDC trade on Ethereum, Native’s measured execution cost was 0.79 basis points, 66% below the 2.37 basis points recorded on passive AMMs, though above the 0.63 basis points offered by other active venues.
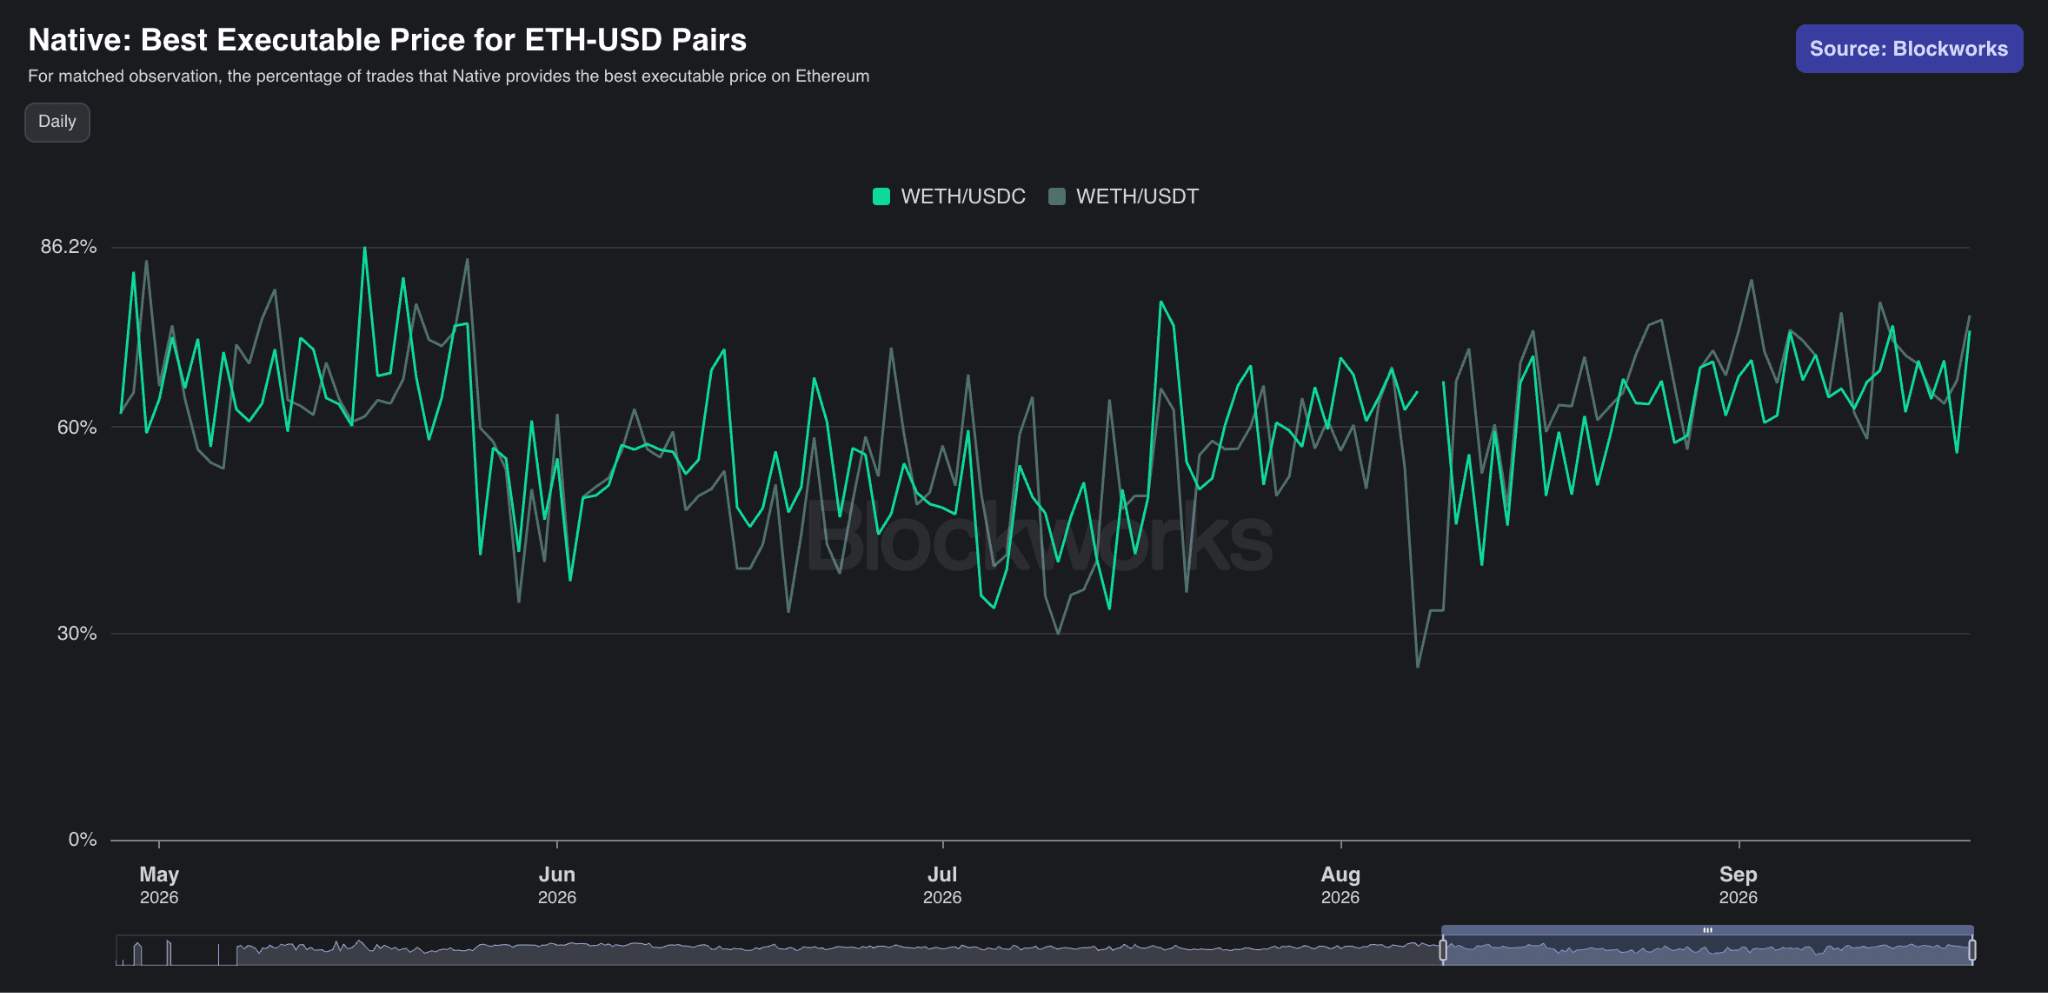
Native provided the best executable price in 60.6% of WETH-USDC observations and 60.8% of WETH-USDT observations on an average day in August. These figures increased to 63.8% and 68.7%, respectively, during the final week of the month, suggesting that Native remained competitive in major crypto markets even as its tokenized equity activity declined.
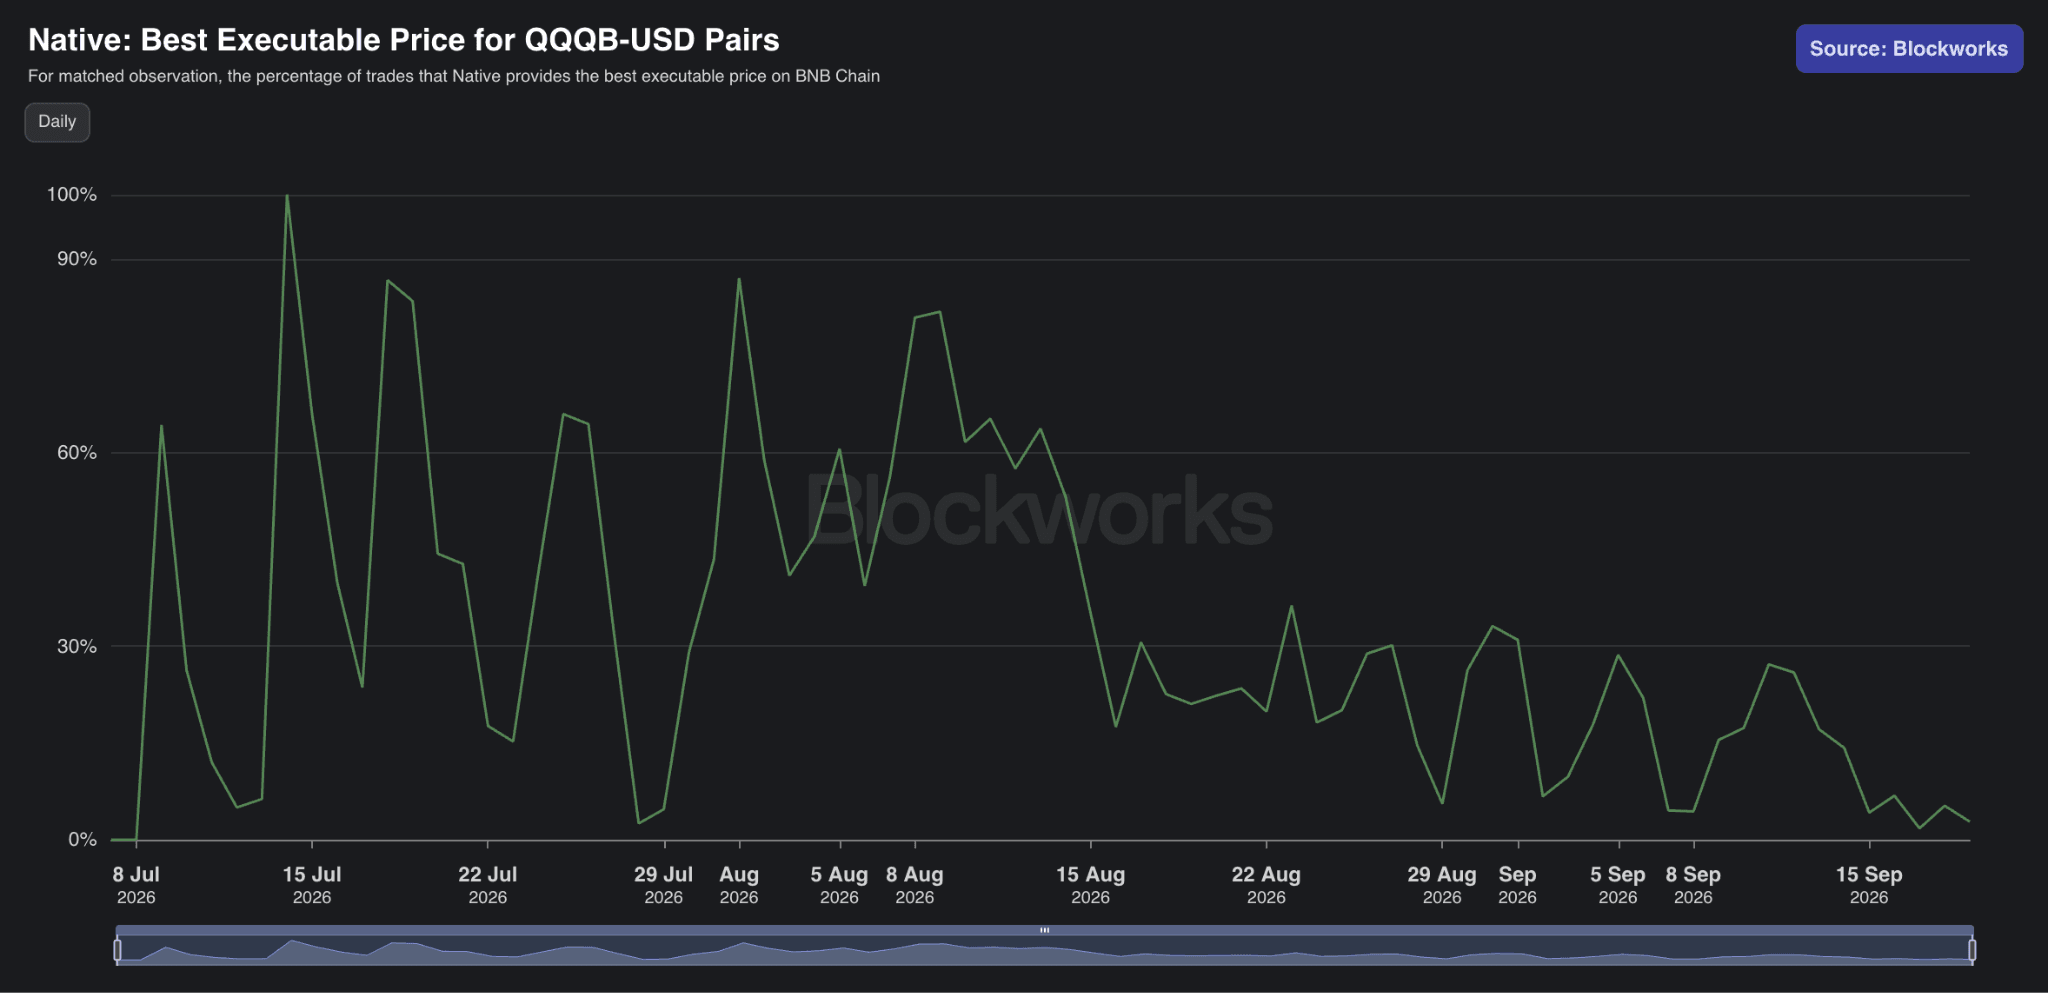
Native also demonstrated competitive execution during the bStocks surge. It offered the best executable QQQB-USDT price in 40% of daily observations during the week it captured 78% of BNB Chain’s tokenized equity volume, rising to 66.7% between August 7 and August 13. Although this frequency moderated later in the month, the early data indicate that Native Relay remained price competitive during periods of elevated activity.
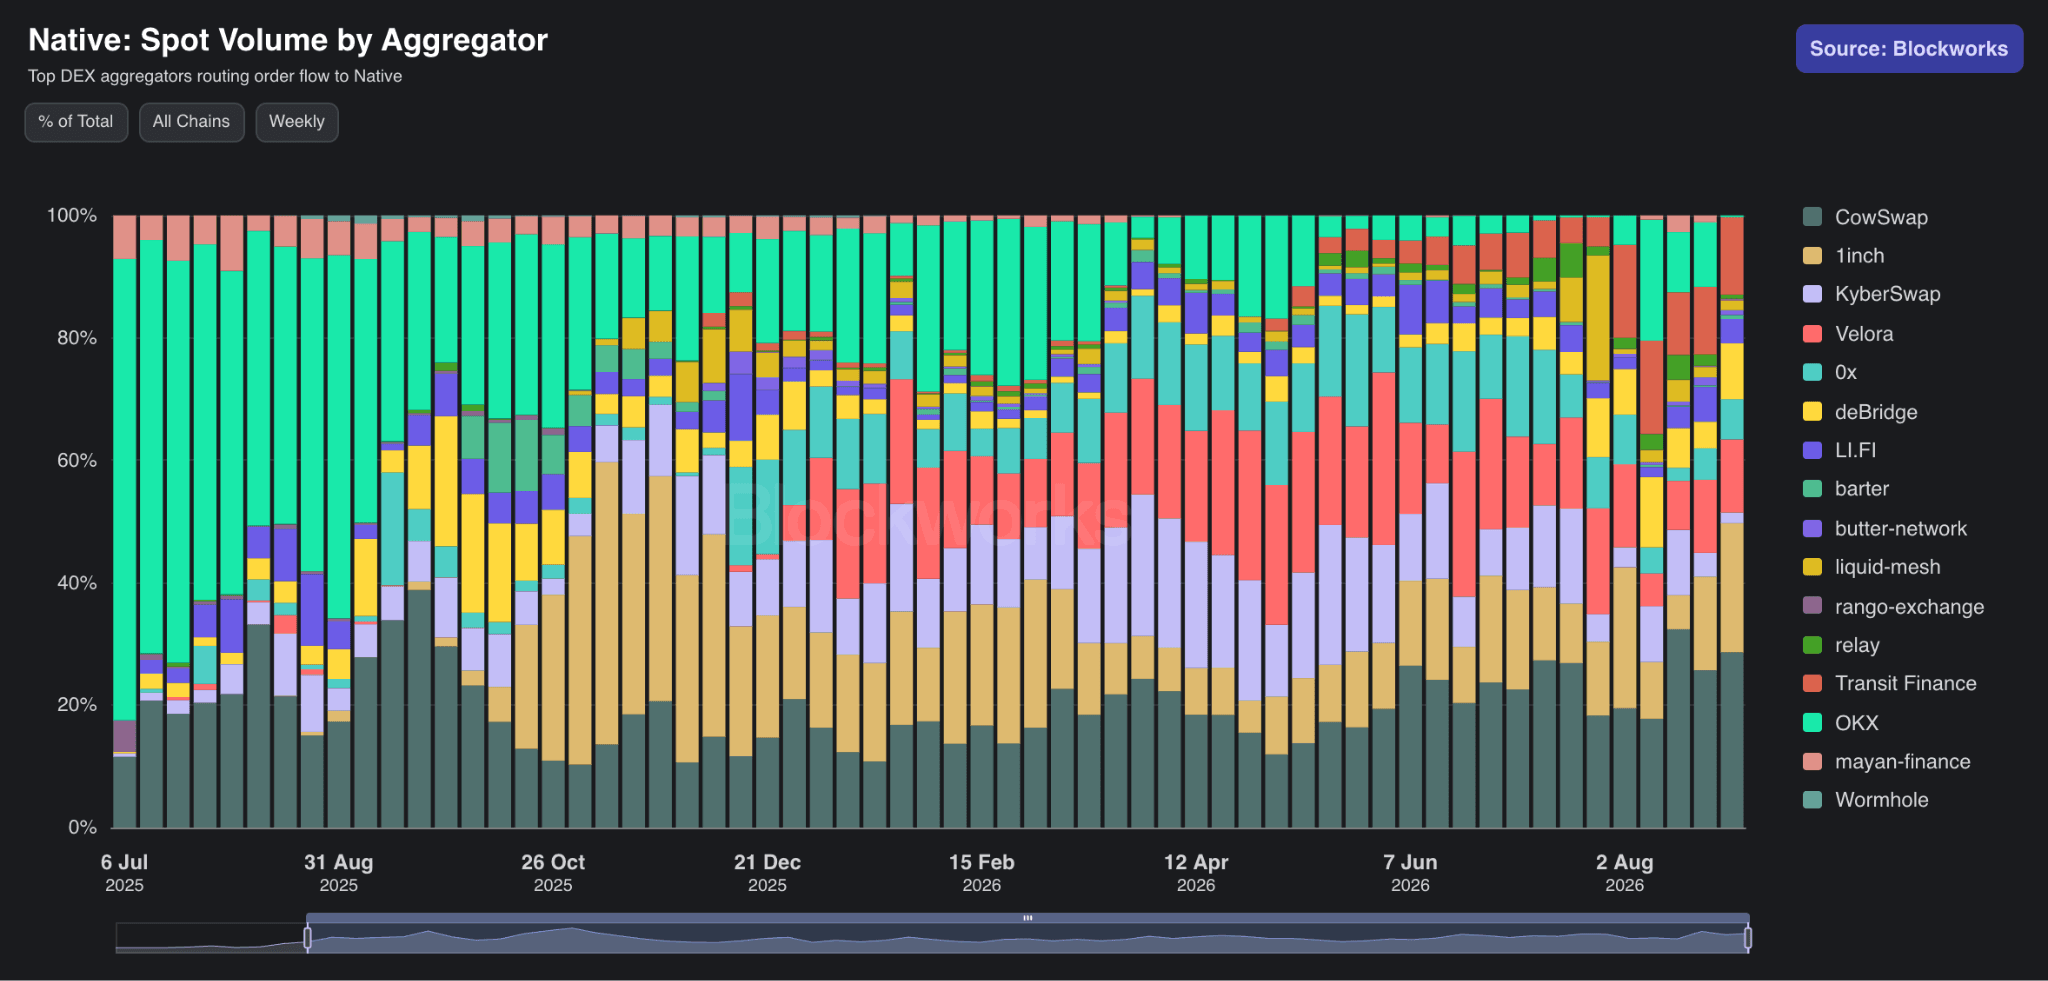
Distribution is another important part of Native’s model. Fifteen named aggregators routed $260M through Native during the four weeks ending August 30. CoW Swap, 1inch and Transit Finance accounted for 53.5% of identified aggregator flow, demonstrating broad distribution while leaving some concentration among the largest integrations.
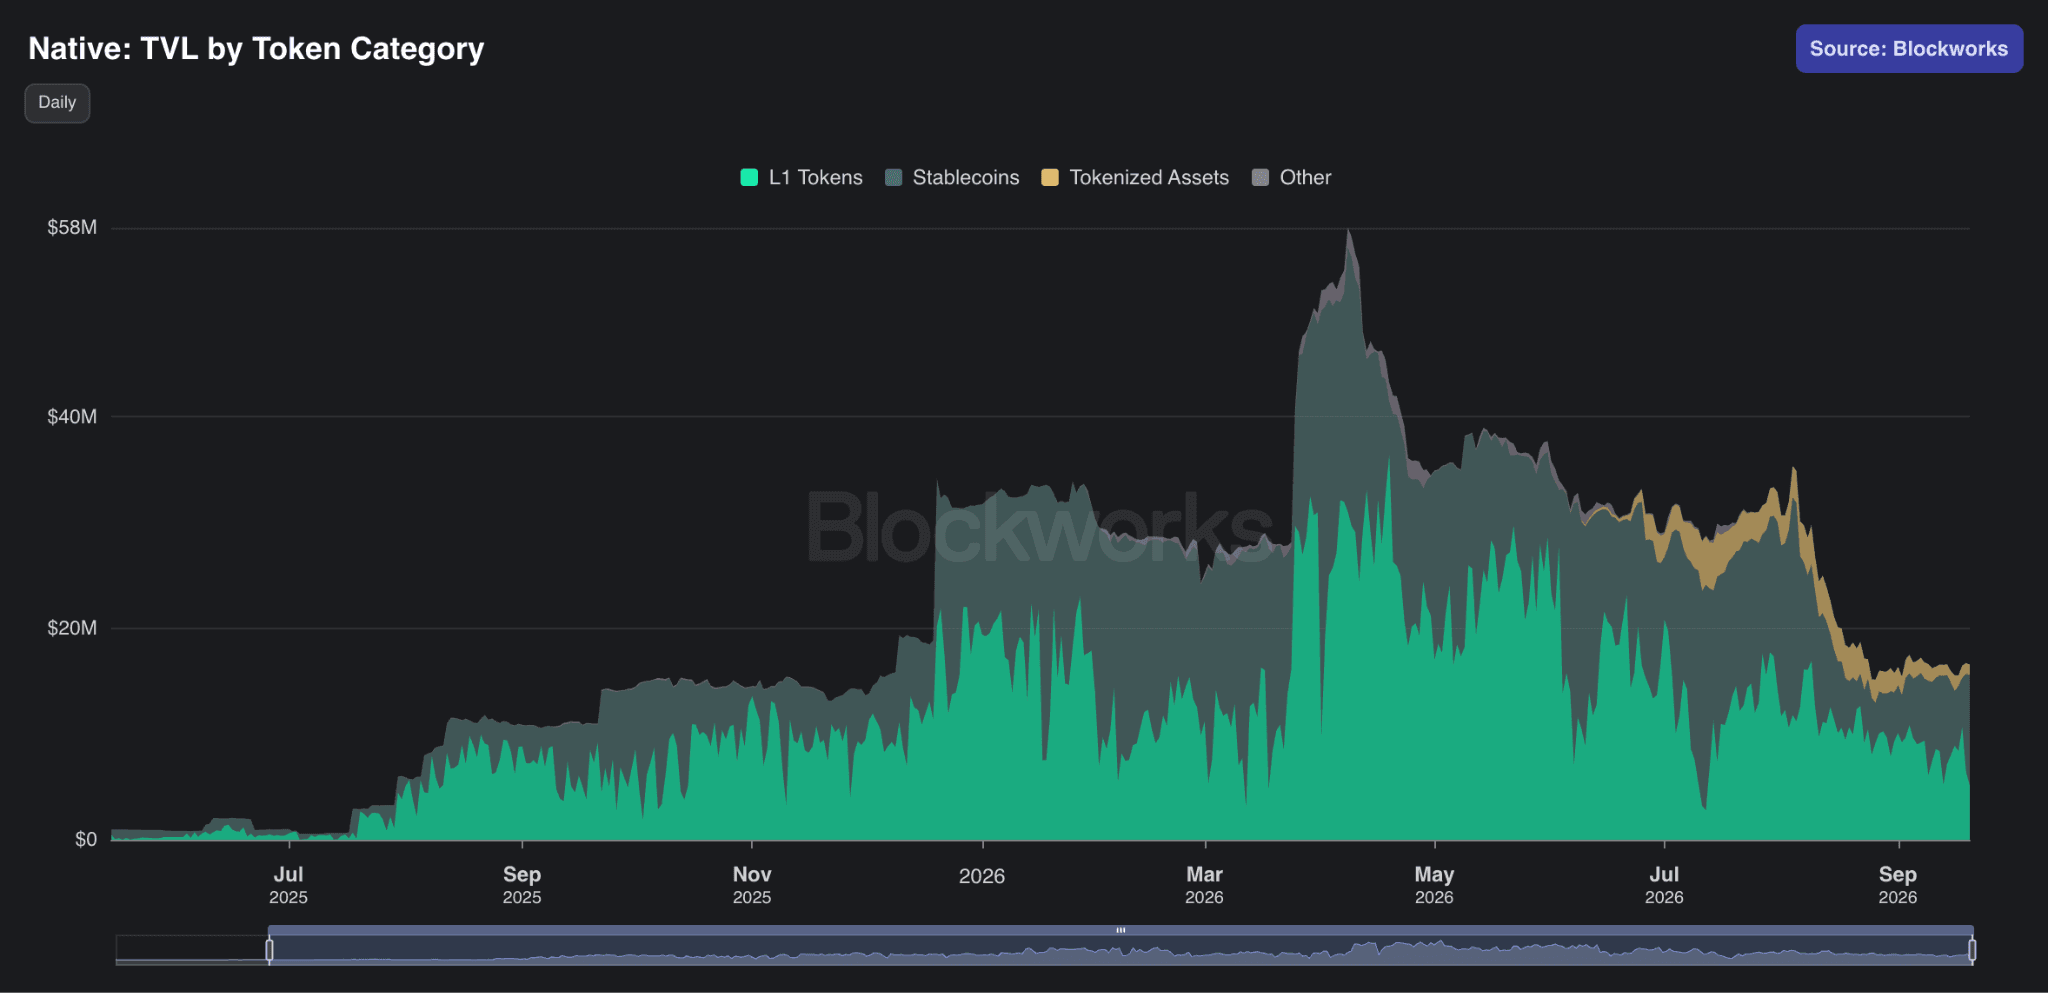
Native Pool held $16.5M of liquidity on September 20, consisting of 63% stablecoins, 31% L1 tokens and 6% tokenized assets. Because the bStocks activity discussed above ran through Relay rather than Core, these figures do not yet show how effectively Pool liquidity translates into trading capacity.
5. Risks and Open Questions
Native’s early traction is encouraging, but several questions remain unresolved.
Volume durability. There is no publicly documented Native trading-rewards program, but its volume can still be indirectly subsidized by incentives offered by issuers, wallets or distributors. The bStocks surge coincided with Binance Alpha rewards, making it difficult to separate Native’s execution advantage from the broader increase in incentivized turnover. Issuer-funded rewards within Native Pool could similarly inflate liquidity or LP returns. Native’s share and best-price frequency both declined sharply as bStocks activity cooled, making performance outside incentive-heavy markets the clearest test.
Core adoption and concentration. Native’s reported bStocks history was generated through Relay rather than Core, which only entered public beta in late August. Core must still demonstrate that it can attract multiple market makers and meaningful order flow while maintaining transparent depth. Concentration also remains high across the existing business: QQQB-USDT accounted for 72.6% of 30-day volume, while the three largest named aggregators generated 53.5% of identified aggregator flow. If quoting remains concentrated among a small number of firms, Native risks reproducing the same dependency as a propAMM within a nominally open order book.
Credit and settlement risk. Native’s single-sided model avoids conventional AMM-style impermanent loss, but it does not eliminate risk. LPs remain exposed to smart contract, collateral, oracle, liquidation and market-maker credit risk. These risks may become most visible during periods of extreme volatility or when tokenized assets continue trading while their underlying markets are closed. Capital efficiency should therefore be evaluated alongside collateralization and realized losses, not in isolation.
Competition and vertical integration. PropAMMs have already shown that closed systems can provide competitive execution, while aggregators reduce the inconvenience of their fragmented liquidity. Native must demonstrate that opening capital and price discovery produces meaningfully better depth or pricing. At the same time, tokenized asset issuers and distributors may vertically integrate liquidity into their own exchanges, as Backpack has done with tokenized stocks. Native’s position as a neutral liquidity layer is more valuable if issuers and order flow providers prefer shared infrastructure over controlling the entire stack themselves.
6. Conclusion
Onchain spot markets are unlikely to converge on a single model. Passive AMMs should retain an important role in long-tail and correlated pairs, where permissionless access and low-cost capital matter most. However, volatile assets with efficient external reference prices require more responsive liquidity. The rise of propAMMs on Solana already shows that active quoting wins when execution quality matters.
Native is attempting to extend that model by combining active pricing with transparent onchain price discovery and permissionless capital provision. The platform’s $9.3B in tokenized equity volume was driven primarily by bStocks activity processed through Relay, demonstrating distribution and throughput without yet validating Core or the role of outside LP capital.
Native’s progress will ultimately be measured through execution quality rather than headline volume. If Core can attract competing market makers, maintain tight and reliable quotes, and turn outside capital into persistent depth across a broader set of markets, Native offers a credible model for bringing tokenized equities and other price-sensitive assets onchain.

Carlos leads coverage on Solana and spends his time on DeFi applications. Previously held a research role at 21Shares.