[Messari Research] Ray Dalio and Bitcoin
Written by Qiao Wang - July 18th
I’ve always believed that, when it comes to understanding macroeconomics, the only people worth listening to are successful macro traders. Not central bankers, media, or armchair economists on Twitter.
The macro trader’s incentive is to maximize their P&L. They have gained real insights after getting #rekt time and time again. The academic or hobbyist’s incentive is often to cherry-pick data to support a preferred narrative. They are only there to entertain.
That’s why I can’t recommend enough this monster piece by hedge fund titan Ray Dalio, where he discusses what the coming macro paradigm shift will look like.
It’s long, so let me summarize (and apply it) for you.
Paradigms
Paradigms are long periods of time, usually about ten years, in which certain market dynamics tend to persist.
For instance, central banks’ efforts to revive the economy from the 2008 financial crisis marked the beginning of the most recent paradigm shift towards easy money policies. Even though growth has been relatively slow since the financial crisis, equities have experienced one of the longest bull markets in history. As inflation remained low, commodities underperformed the previous decade. Meanwhile, widening wealth and income gaps contributed to the global rise of populism.
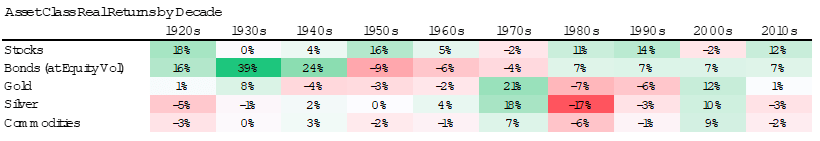
Those are symptoms, not underlying forces, of the current paradigm. And symptoms will often persist long enough for people to believe they will never end. The driving forces, though, tend to be unsustainable. It’s merely a matter of time before each paradigm ends.
Driving Forces of the Current paradigm
As such, forecasting a paradigm shift boils down to identifying driving forces of the paradigm and examining why they are unsustainable.
Dalio believes that we are near the end of the current paradigm, as the following driving forces are no longer sustainable.
- 1a) Rate cuts and quantitative easing lead to cheap credit and an enormous amount of cash in the economy. That pushes up equities and debts and drive down their expected future returns. But rates can only go so low and quantitative easing has diminishing returns the more it is employed as a strategy.
- 1b) Corporate tax cuts boost stock prices and shrink expected future returns even further. Such cuts are (probably) not sustainable and will likely be reversed if Democrats gain more power in the U.S.
- 2a) Technological automation causes an increased share of the pie going to capitalists and a decreased share of the pie going to workers, inevitably leading to conflicts between the two groups.
- 2b) Asset bubbles benefit those who own assets, i.e., the capitalists, at the detriment of those who don’t, i.e., the workers. This widening wealth gap leads to further conflicts.
Coincidentally, I touched on both macro trends in a recent tweetstorm.
Catalysts of the Next paradigm
As such, the current paradigm will likely end when expected future returns of productive assets like equities and debts cannot decrease any further, and when local and global conflicts reach a boiling point.
More precisely, a new paradigm can be triggered by a combination of the following catalysts.
- Conflicts hurt equities and debts, causing money to flow into safe-haven assets.
- As expected future returns approach zero, investors won’t want to hold equities and debts anymore and will move to other asset classes.
- During an economic downturn, central banks will no longer be able to rely on traditional rate cuts to stimulate markets, but only on the radical quantitative easing, aka “money printing”.
- Enormous amounts of liabilities (e.g., treasury bonds, pension, and healthcare) will increasingly be coming due. They won’t be able to be funded with those low-return assets, but instead with currency depreciations.
How is this related to crypto?
There’s zero mention of the word “Bitcoin” or “crypto” in Ray Dalio’s piece. In the grand scheme of things, crypto simply does not have enough liquidity capacity to be considered by a $100B hedge fund.
Yet, the entire piece screams “buy Bitcoin”. If Ray Dalio’s predictions are correct, Bitcoin and gold will likely be the best performing assets during the next decade. Traditionally, gold thrives in inflationary environments and geopolitical conflicts.
The intersubjective belief of Bitcoin as digital gold is gaining momentum day by day. Earlier this week, Fed chairman Jerome Powell even said “Bitcoin is a store of value, like gold”. In a recent post, I wrote about my belief that the first half of this year’s Bitcoin rally was due to Yuan depreciations. I certainly did not hold this belief during the Cyprus crisis in 2013 and Brexit in 2016, even though Bitcoin rose on both occasions.
What about other cryptoassets? In the short-term (hours to days), they will likely continue to be correlated with Bitcoin. If Bitcoin rallies due to inflation or conflicts, they will also rise. In the long-term (months to years), however, my hunch is that they will only be driven by endogenous factors such as technological upgrades, but not by exogenous factors as macroeconomic conditions.
Concluding with two beautiful quotes from Ray Dalio’s piece…
On recency bias: “The consensus view is typically more heavily influenced by what has happened relatively recently (i.e., over the past few years) than it is by what is most likely.”
On money printing addictions: “History has shown us and logic tells us that there is no limit to the ability of central banks to hold nominal and real interest rates down via their purchases by flooding the world with more money.”