Inverse relationship between market capitalization and volatility
It is well known that in the stock market, market capitalization is inversely correlated with the volatility. There are a couple of theories behind this. First, large caps are more resilient to market-moving news. Second, they are less prone to irrational speculation as their trading volume is dominated by rather sophisticated investors.
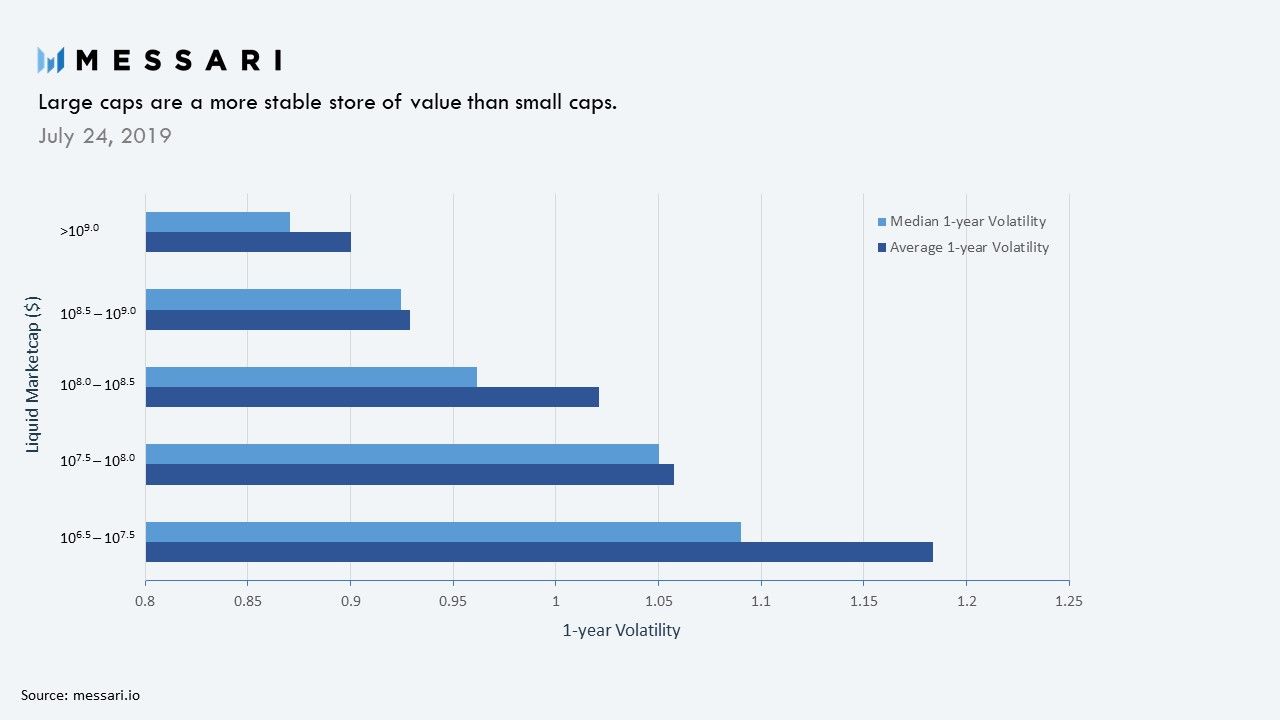
We are seeing a similar pattern with cryptoassets. According to our research, the volatility, which is defined as the average annualized standard deviation of daily returns over the last 365 days, of large caps is 90%. This number increases steadily as marketcap decreases.
For context, the volatility of the S&P500 is normally between 10% and 20%.
Let us know what you loved about the report, what may be missing, or share any other feedback by filling out this short form. All responses are subject to our Privacy Policy and Terms of Service.