Maker TVL quietly approaches $2 billion after a surge in USDC collateral

While everyone was distracted by the onslaught of new governance tokens and sky-high APYs available through yield farming, Maker has steadily grown to nearly $2 billion in value locked.
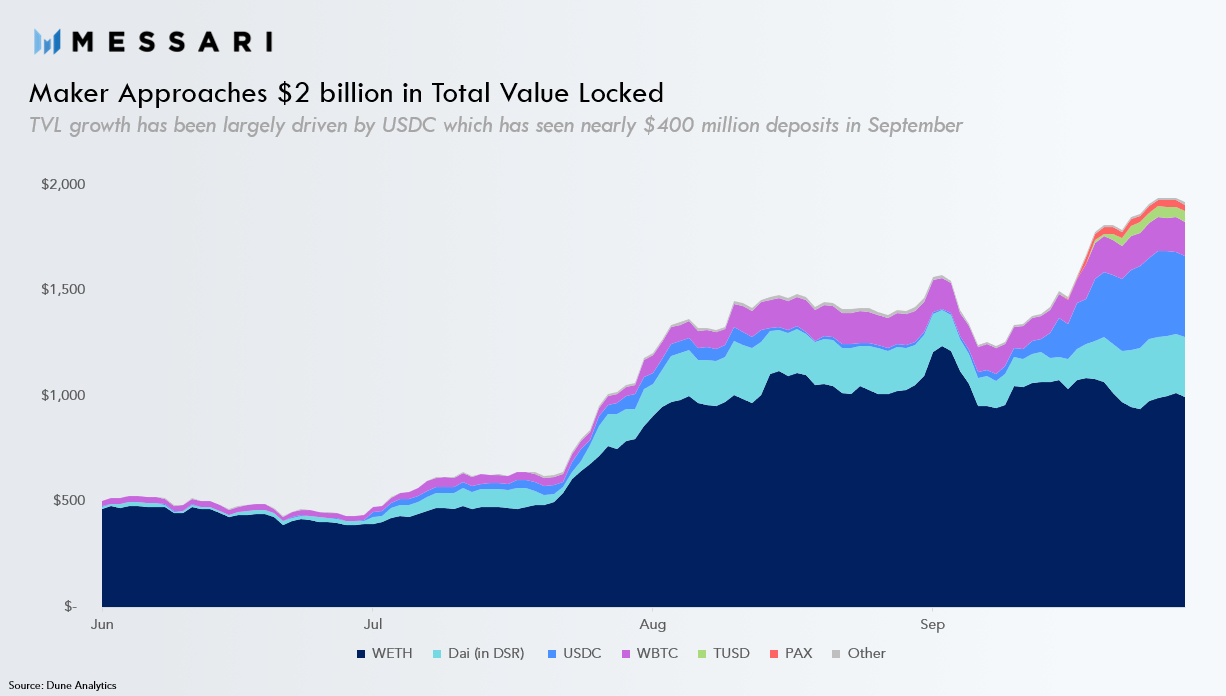
Almost all of the recent growth has been a result of USDC deposits which comprised a mere 0.6% of TVL at the start of September but has quickly reached 20% as around $400 million has been deposited. This is a result of a concerted effort by Maker governance to restore the Dai peg which has meant incentivizing stablecoin-collateralized debt with higher debt ceilings and lower liquidation ratios. By making debt creation less capital intensive, it becomes more attractive to mint Dai, increasing the supply and putting downward pressure on the price.
Despite not having any native yield farming, Maker has still been materially impacted by the craze. When new liquidity mining programs are launched requiring Dai to be locked up, it causes a rush to acquire Dai which pushes it further from its peg. This began with the COMP token distribution which created an incentive to lock up Dai in Compound. The outstanding supply more than doubled in the span of a few weeks as the peg began to break.
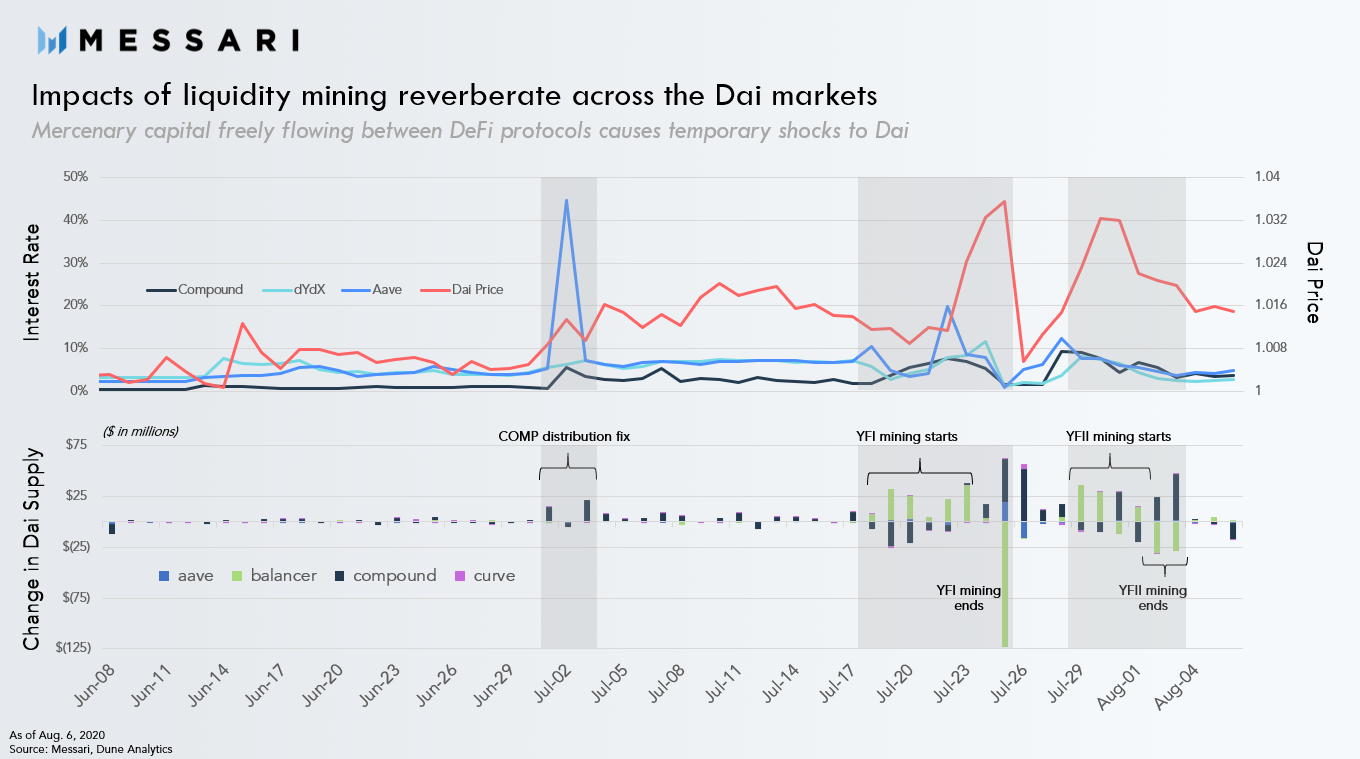
As the increased demand for Dai made it more expensive to both purchase or borrow, users elected to mint it instead to participate in these yield farms. This has the effect of increasing total collateral locked as well as Dai outstanding. Another way to produce the same effect is by directly integrating Maker into yield farming strategies. We’ve seen this with yearn’s ETH vault strategy which enables holders to earn a return by depositing ETH that is then collateralized to take out a loan with Maker and subsequently disperses Dai into yearn’s Dai vaults (which are then used to farm CRV). This vault received so much interest, a cap was quickly put on it to prevent more deposits. As it stands $37 million is deposited which accounts for almost 4% of all ETH collateral in Maker.
Dai remains one of the most used stablecoins across DeFi. As the industry continues to grow at this rapid clip, it's only natural that Dai will continue to grow with it given its entrenched network effects. Yet despite growing from $70 million in outstanding debt to $900 million, massively increasing the system’s potential earnings, MKR has not received the same increased investment as the rest of DeFi. In fact, MKR is up a meager 18% on the year, dwarfed by the triple-digit returns of almost every other major DeFi asset.
