MakerDAO's 12M Financial Outlook & Valuation: Balancing Growth Against Costs

We recommend reading our precursor report on MakerDAO, covering Endgame and the project’s business model in more detail.
MakerDAO’s MKR token has had a notable price increase since mid-June, having reached ~$1,340 at the beginning of August, a ~115% increase from the previous 90 days. However, the project recently made the decision to increase its DAI Savings Rate (“DSR”) through the Enhanced DSR (“EDSR”), which boosted the rate from 3.2% to 8.0%. The rate increase was originally intended to grow the project’s userbase, but it quickly became apparent that the rate was going to be taken advantage of by large whales and funds while also bringing about a significant cost onto MakerDAO’s income statement, thus decreasing the run rate free cash flow that was a key driver for MKR’s strong recent price performance. Consequently, the EDSR was capped at 5%, and stability fees for most crypto vaults were expanded to be in line with the accelerated interest rate such that arbitraging the EDSR wouldn’t be as profitable. All of this initially added ~1.2B DAI into the DSR vault and expanded the annualized DSR cost from ~$9.2M to over $70M. At least currently, the cost has yielded some results since, within a month, the DAI supply has also expanded from ~4.6B tokens to ~5.1B. Be that as it may, the supply was as high as ~5.5B on August 20, and therefore, the sustainability of this growth should be closely followed going forward.
Although the DAI supply has increased meaningfully from a month ago, the market hasn’t reacted well to the higher DSR cost and recent ~400M DAI supply shrinkage, as shown by MKR trading at ~$1,100 as of August 20, down ~9% in the past seven days. To offset the DSR costs, MakerDAO still has assets on its balance sheet that it can deploy into RWAs, but the project will also have to continue expanding its stablecoin supply to reach a similar free cash flow level that it maintained in June 2023.
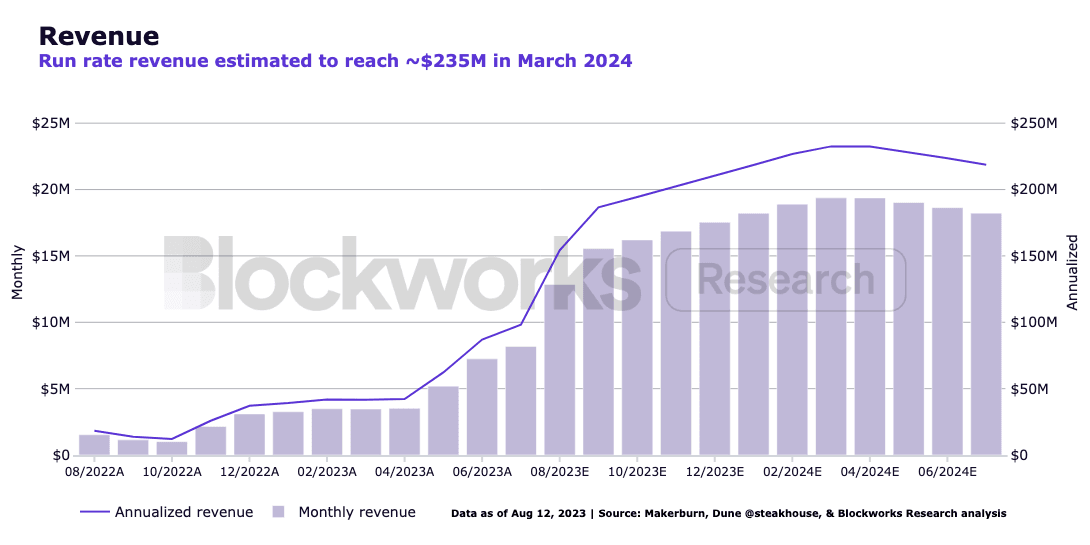
As described in our earlier report, MKR’s price appears to be attributed to the short-term value that is channeled to token holders. Accordingly, we’ve granularly modeled MakerDAO’s financials for the next 12 months, which are introduced below.
The full model can be found here.
Revenue

Brick leads coverage on Aevo, Chainlink, and MakerDAO. Previously he worked in investment banking as a sector-agnostic M&A and ECM advisor.