The following report was written by Messari Hub Analyst(s) and commissioned by Integral, a member of Messari Hub. For additional information, please see the disclaimers following the article
Decentralized exchanges (DEXs) have grown significantly as crypto has bloomed. Uniswap is the most valuable DeFi protocol by market cap. The entire DEX volume has exceeded $78 billion per month for the last two full months and topped out at $163 billion in the month of May. DEXs now average 7-10% of aggregate CEX spot volumes on a monthly basis.
DEXs created this success from the now famous yet simple x*y=k price curve which is responsible for balancing pool liquidity across all price ranges. Uniswap was the pioneer. And such opened up the door for permissionless trading. Any asset for any trader. Small market cap, small trader? Doesn’t matter. Permissionless pools enable anyone to supply liquidity to any asset.
But not all DEX orders are the same.
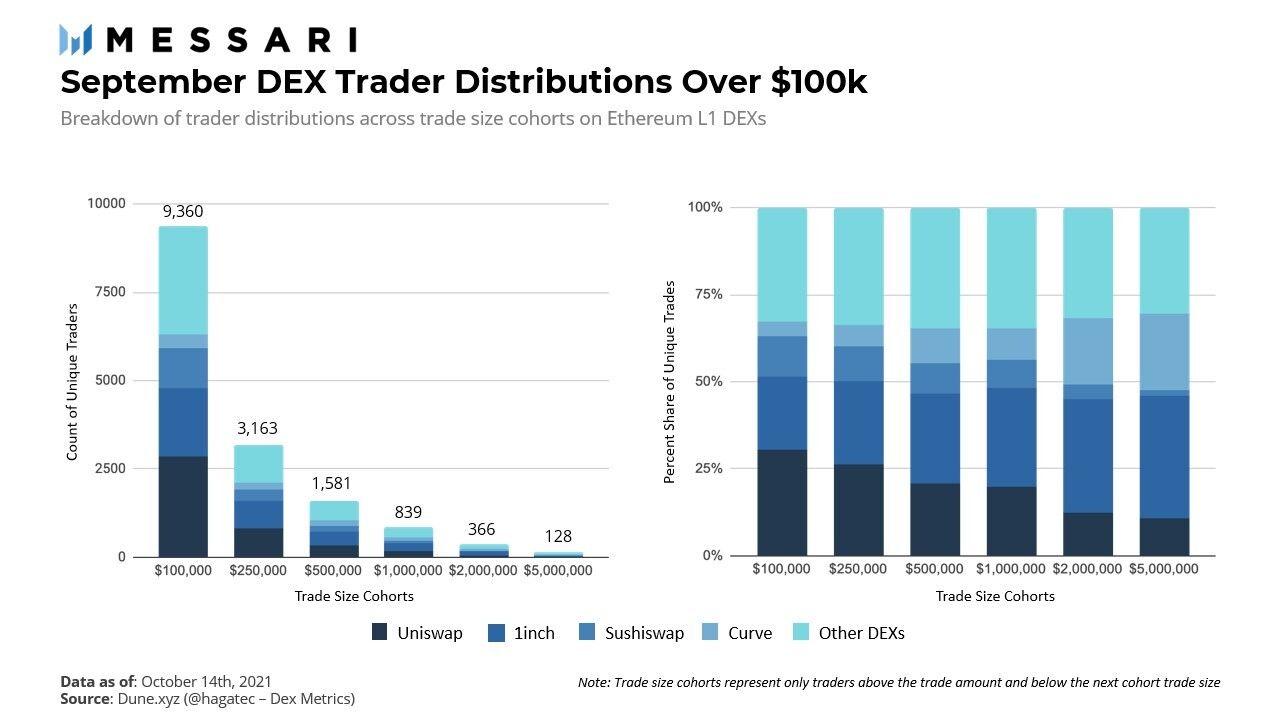
There are large trades and small. Larger the trade, the more liquidity is required in the DEX to efficiently execute the trade with low slippage. Naturally as crypto has grown, we have started to see more frequent large trades. In March of this year, DEXs saw 1,215 unique traders execute trades over $500k which all totaled to $9 billion in volume. Those figures more than doubled in 6 months. September saw 2,914 unique traders executing trades larger than $500k on DEXs and these trades totals over $19 billion in volume. 140% and 112% increases in each figure respectively.
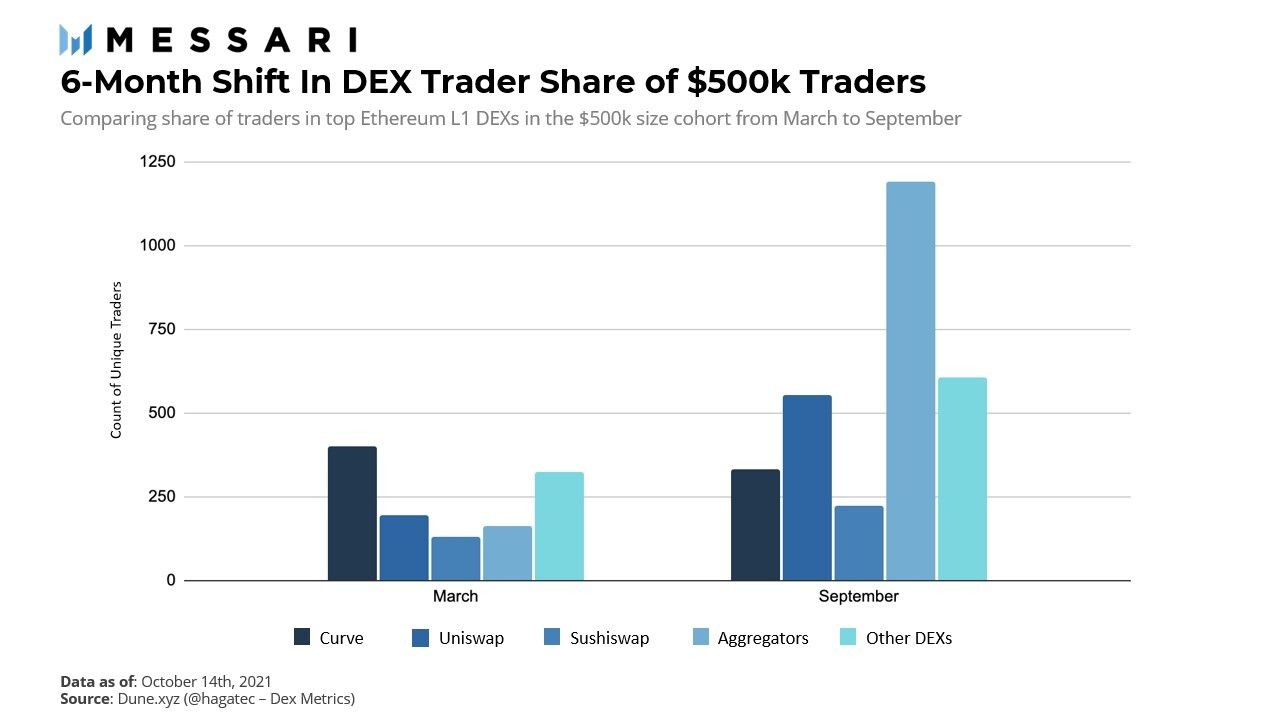
Protocols servicing this market segment of $500k plus trades shifted as well. Curve served the bulk of the traders (33%) back in March. Now in September, DEX aggregators and Uniswap account for just over two thirds (67%) of all DEX trades over $500k. Curve accounts for just 11%. This suggests the nature of the swaps or the intention of the traders shifted dramatically. Curve’s DEX is used for trading assets that stay pegged to each other in value so essentially swaps there are trading one asset for a similar asset - no speculative trading or taking positions in price performant assets. Of course, Uniswap is different. Here traders tend to swap from one asset into a different, dissimilar asset in hopes of outperforming the swapped asset. So not only has the market size for large $500k plus DEX trades more than doubled in the last 6 months but the growth has been overwhelmingly in traders swapping speculative assets.
DEX protocols themselves have begun to change to more efficiently accommodate larger transactions. Uniswap’s V3 and Sushi’s Trident have implemented concentrated liquidity models to improve upon the x*y = k model. DEX routers have grown to attract significant volume - especially in the large-order market where large trades are efficiently broken up among various DEXs. Now most protocols in the DEX sector are pushing to solve for liquidity efficiencies and efficient execution of larger orders to both utilize ecosystem capital efficiently as well as to handle larger transactions that come with maturity.
One of the newer protocols tackling this large-order niche of the DEX market is Integral Protocol.
Enter Integral
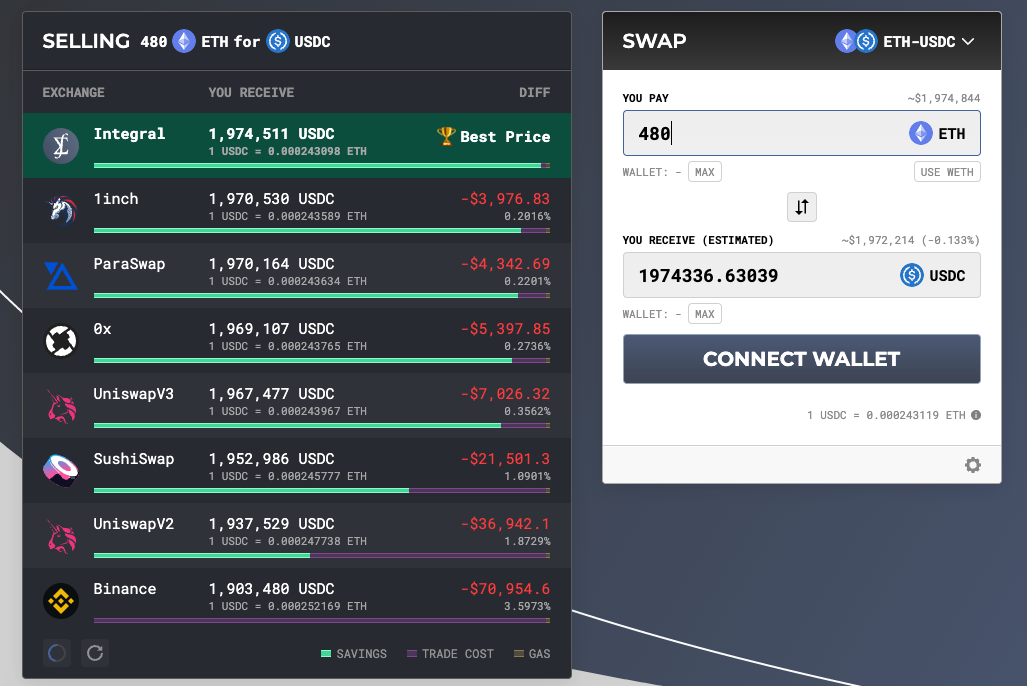
Integral launched its DEX in March 2021 on Ethereum and subsequently raised $31 million in April’s fair-launch token event. The protocol’s objective is to be ‘the last exchange’ and aims to accomplish this by mirroring other top exchanges’ liquidity on to its DEX. Having the equivalent liquidity of top exchanges enables the protocol to offer low-slippage trades even on large orders. There are a few distinct design choices in the DEX that differ from the classic AMM DEX that enables the protocol to execute their vision.
Liquidity Model
Integral separates the capital used to execute trades and the depth of the order book or price curve. In the classic AMM employed at Uniswap, LPs deposit assets that make up the trading pool - these funds both define the depth (slippage) on trades and supplies the tokens for the other side of the trade. For Integral, the depth is defined by other top exchanges. All that is needed is an oracle in order to effectively mirror the depth of other top exchanges like Binance and Uniswap.
Currently, the protocol mirrors greater than 3x of Binance’s spot liquidity or 1x of Uniswap’s liquidity. This acts as implied liquidity for Integral and its traders who can execute against top-tier liquidity depth on a decentralized protocol resulting in low-slippage trades.
The question is now, how does the protocol fund the other side of the trade if the liquidity depth is mirrored from other exchanges? A leveraged AMM model is used which in effect concentrates the protocol’s liquidity. LP provided funds are placed into a pool and are the source of capital used to execute trades. As a result, significantly less capital is required to provide comparable execution. In the same vein, LPs earn significantly more fee income per unit of liquidity due to the concentrated liquidity.
Risk however is introduced to the protocol with this model. Integral’s smaller pool of capital may be 100% misbalanced by traders if many take one side of a trade. For example, assume there is $10 million of LP capital in Integral acting as execution capital against an implied $200 million Binance liquidity. If enough volume is executed on Integral, the pool of say ETH/USDC could become 100% of only one asset resulting in an untradeable pool.
Trade Execution
Integral introduces a concept of time-delayed execution meaning that trades are executed after a wait period. Uniswap’s 5-minute TWAP oracle is used to provide price feeds every five minutes to execute trades against. Trades sit in a waiting period until the period is up and then it is executed.
The trade delay is implemented to protect LPs from impermanent loss. Impermanent loss occurs when arbitrageurs with known price data execute against the trading pool. Implementing the 5-minute delay forces the arbitrageur to take a 5-minute price-directional position in the asset. Something arbitrageurs don’t like to do. So in a game theoretic sense, this mechanism persuades arbitrageurs to utilize the numerous other DEXs where they are not exposed to price risk.
Markets
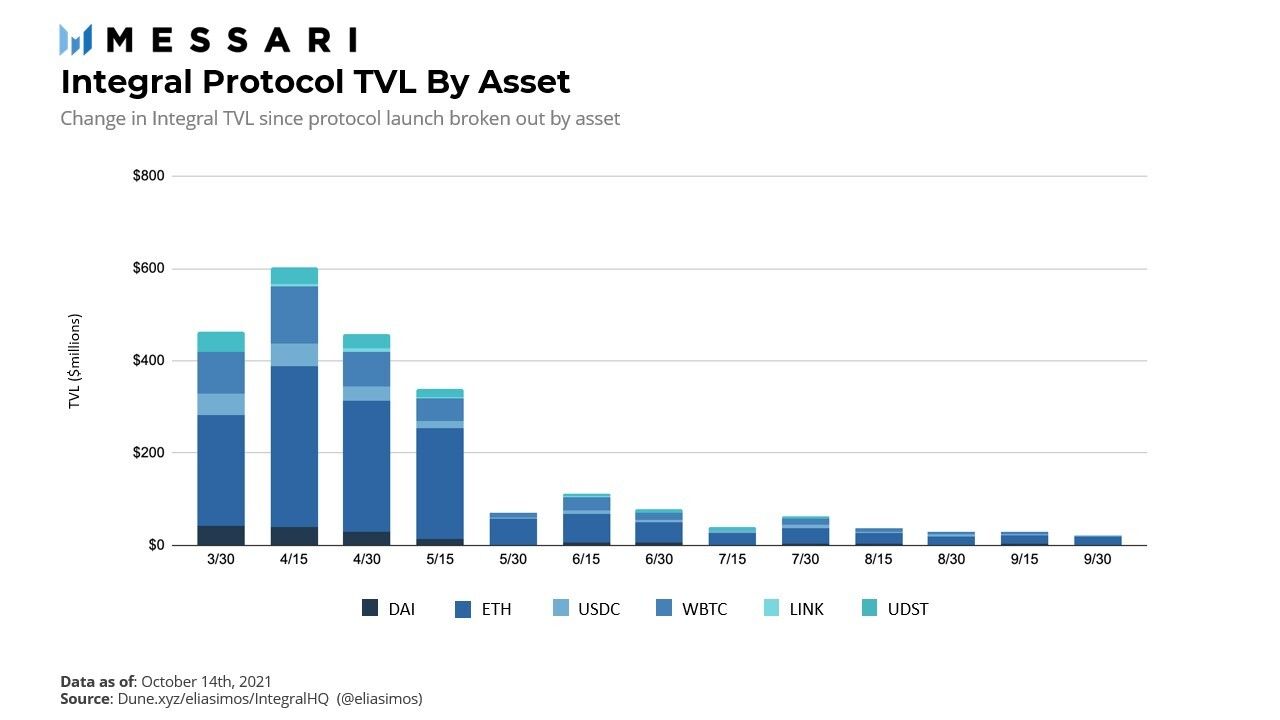
Integral currently offers trading in three non-stable markets; ETH, WBTC, and LINK along with the usual Ethereum stablecoins; USDC, DAI, USDT. The protocol currently has $28 million in executable liquidity. The majority of this sits in the ETH-USDC and ETH-WBTC pools. Each with approximately $10 million liquidity each. However, the bulk of the balance resides in ETH. Almost 67% of the entire protocol’s liquidity is in ETH due to the current imbalance in the trading pools.
TVL has dropped 96% from April’s all-time highs of $733 million, however, TVL in Integral is strictly for sourcing inventory to fund the other side of trades. The protocol made the decision to reduce the farming rewards in order to dampen the ITGR emission rate, which likely contributed to the noted drop in TVL. Despite the low liquidity of less than $30 million, the protocol is still able to execute large orders due to its implied liquidity mirrored from Binance and Uniswap.
In September, Integral did $7.4 million in monthly trading volume. 66% of Integral’s volume was generated from traders trading above $100k in the transaction. Compared to the rest of the DEX market, only 60% of the September volume was attributable to trades over 100k. Looking at unique traders executing swaps above $100k further highlight’s Integral’s affinity with this cohort. 21 of Integral’s 156 traders in September did large trades which is 13% of their monthly user base. Meanwhile, the rest of the DEX market had just over 2% of its monthly users execute orders over $100k. An upward deviation here makes sense given Integral currently caters to large-swap orders due to its mirrored depth and delayed execution methodology (only large trades can net a favorable price compared to other DEXs due to the delay mechanism requiring multiple gas-expensive transactions).
ITGR Supply and Tokenomics
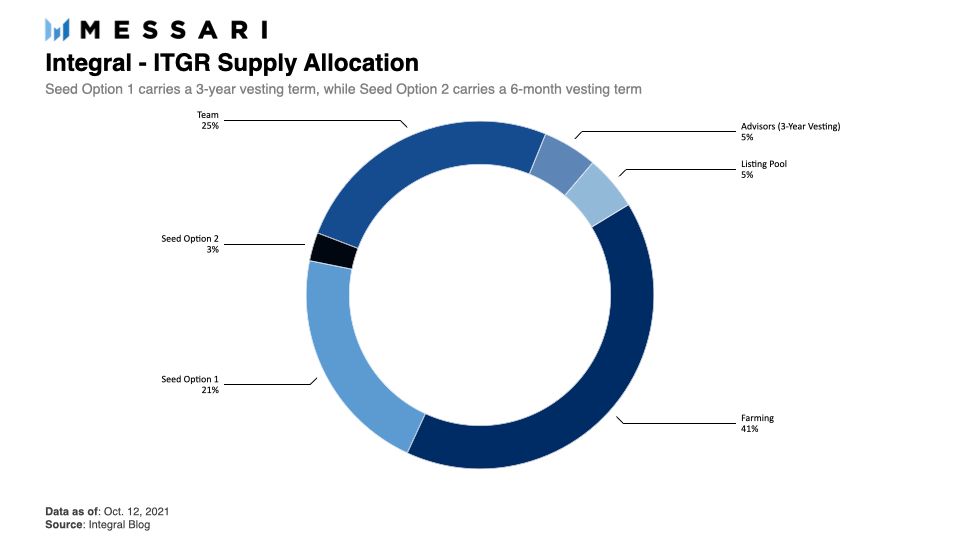
The native token of Integral, ITGR, functions as the protocol's governance token. The ITGR token has a fixed supply of 300 million, and the allocation data is shown below.
Holders of ITGR receive an additional benefit as all trading fees, currently set at 1bps for stablecoin pools and 5bps for all others, accrue to the ITGR token.
Integral completed a public seed round as of April 28 this year, which allowed the project to raise ~$32 million. The token sale included two options as shown in the supply allocation chart. The first option, which has a three-year vest compared to the six-month vest option, accounted for nearly 80% of the total raised amount. On September 15 the ITGR token officially became available for trading on Uniswap.
The project has a liquidity mining program, which allows liquidity providers to earn ITGR tokens. The LP rewards are designed such that only providers to pools that are out of weight or are larger than $2 million in TVL receive ITGR rewards. The earned ITGR tokens also linearly vests over a 6-month period.
A staking function has also been developed for the ITGR token. Holders of vested tokens can choose to stake these and earn additional ITGR tokens. The protocol offers 45% APY for a three-year lockup, and 10% APY for a six-month lockup period. Currently, over 900,000 ITGR has been staked, which accounts for ~15% of the circulating supply.
Road Ahead
As the crypto ecosystem continues to rapidly expand, it’s expected that the volume and magnitude of large trades should increase as well. Currently, Integral offers a unique solution for traders in this market via its trade delay mechanism and its implementation of a concentrated liquidity design. But, to create or maintain any edge in this space, continuous product improvement and integrations have proven to be vital.
Integral has announced its intention to build out a new product, an on-chain OTC protocol. The OTC product is set to launch in November, and interested users can sign up on the waitlist. To drive user adoption of its current product set and any future additions, integrations will be pivotal, as this strategy can (implicitly) bring the protocol to users. Integrations with DEX aggregators could increase volume flowing to the protocol without requiring users to directly interface with it. Due to its unique mechanism design, it may be technically challenging for Integral to successfully develop these integrations.
While Integral looks to build out these new products and integrations, the competitive landscape around this sector of the market will also evolve. Uniswap and aggregators like 1inch have already developed a significant level of brand recognition, giving them a competitive advantage without necessarily focusing on this particular market segment. Competition will of course not only come from decentralized exchanges and aggregators, but also from centralized entities.
As the market for large orders continues to grow, Integral will look to successfully develop innovative products and build out partnerships and integrations to serve this niche market. Facing strong competition from established centralized and decentralized competitors, Integral will continue building out a strong, unique product set in hopes of ultimately finding success.
This report was commissioned by Integral. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.