Grvt is a perp DEX where users can earn up to 11% APY interest on margin deposited to trade. Interest currently comes from protocol trading fees, with rehypothecation of most user deposits to external DeFi protocols coming soon as a second source of interest. Grvt announced Aave will be its first external yield source in February.
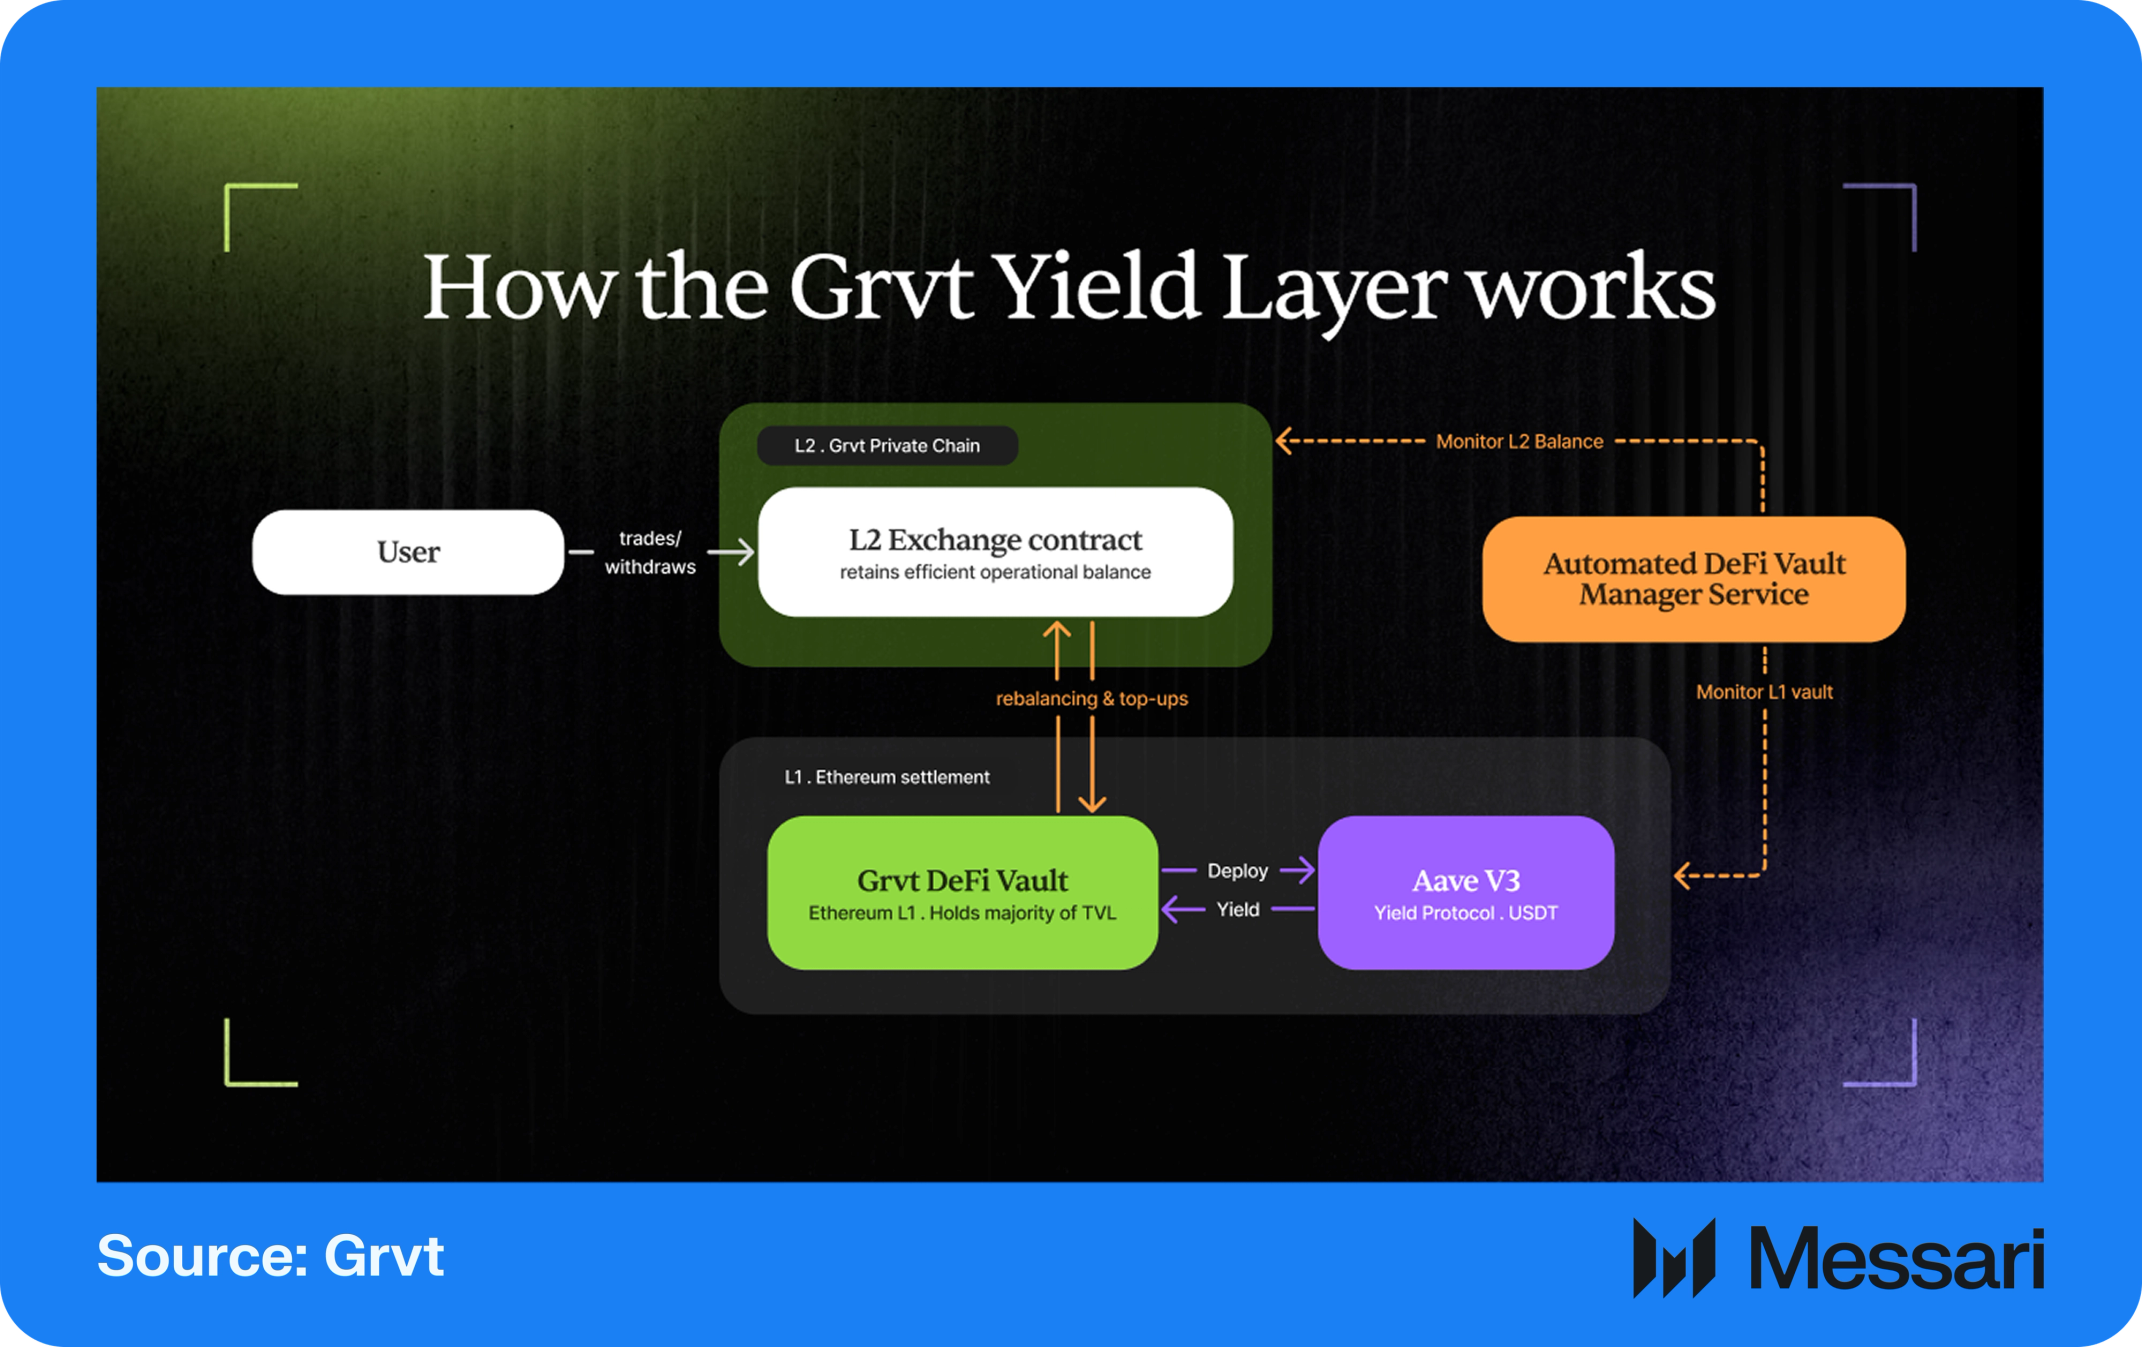
Grvt's Yield Layer is the earn infrastructure built on top of Grvt's unified margin system, routing idle collateral into onchain yield integrations such as Aave, so that the same balance backing a trader's open positions is simultaneously generating yield.
Grvt decouples where collateral deposited earns yield (Ethereum L1) from where user activity is tracked (Grvt private L2), ensuring composability with external DeFi without compromising the privacy guarantees of its Validium-based appchain.
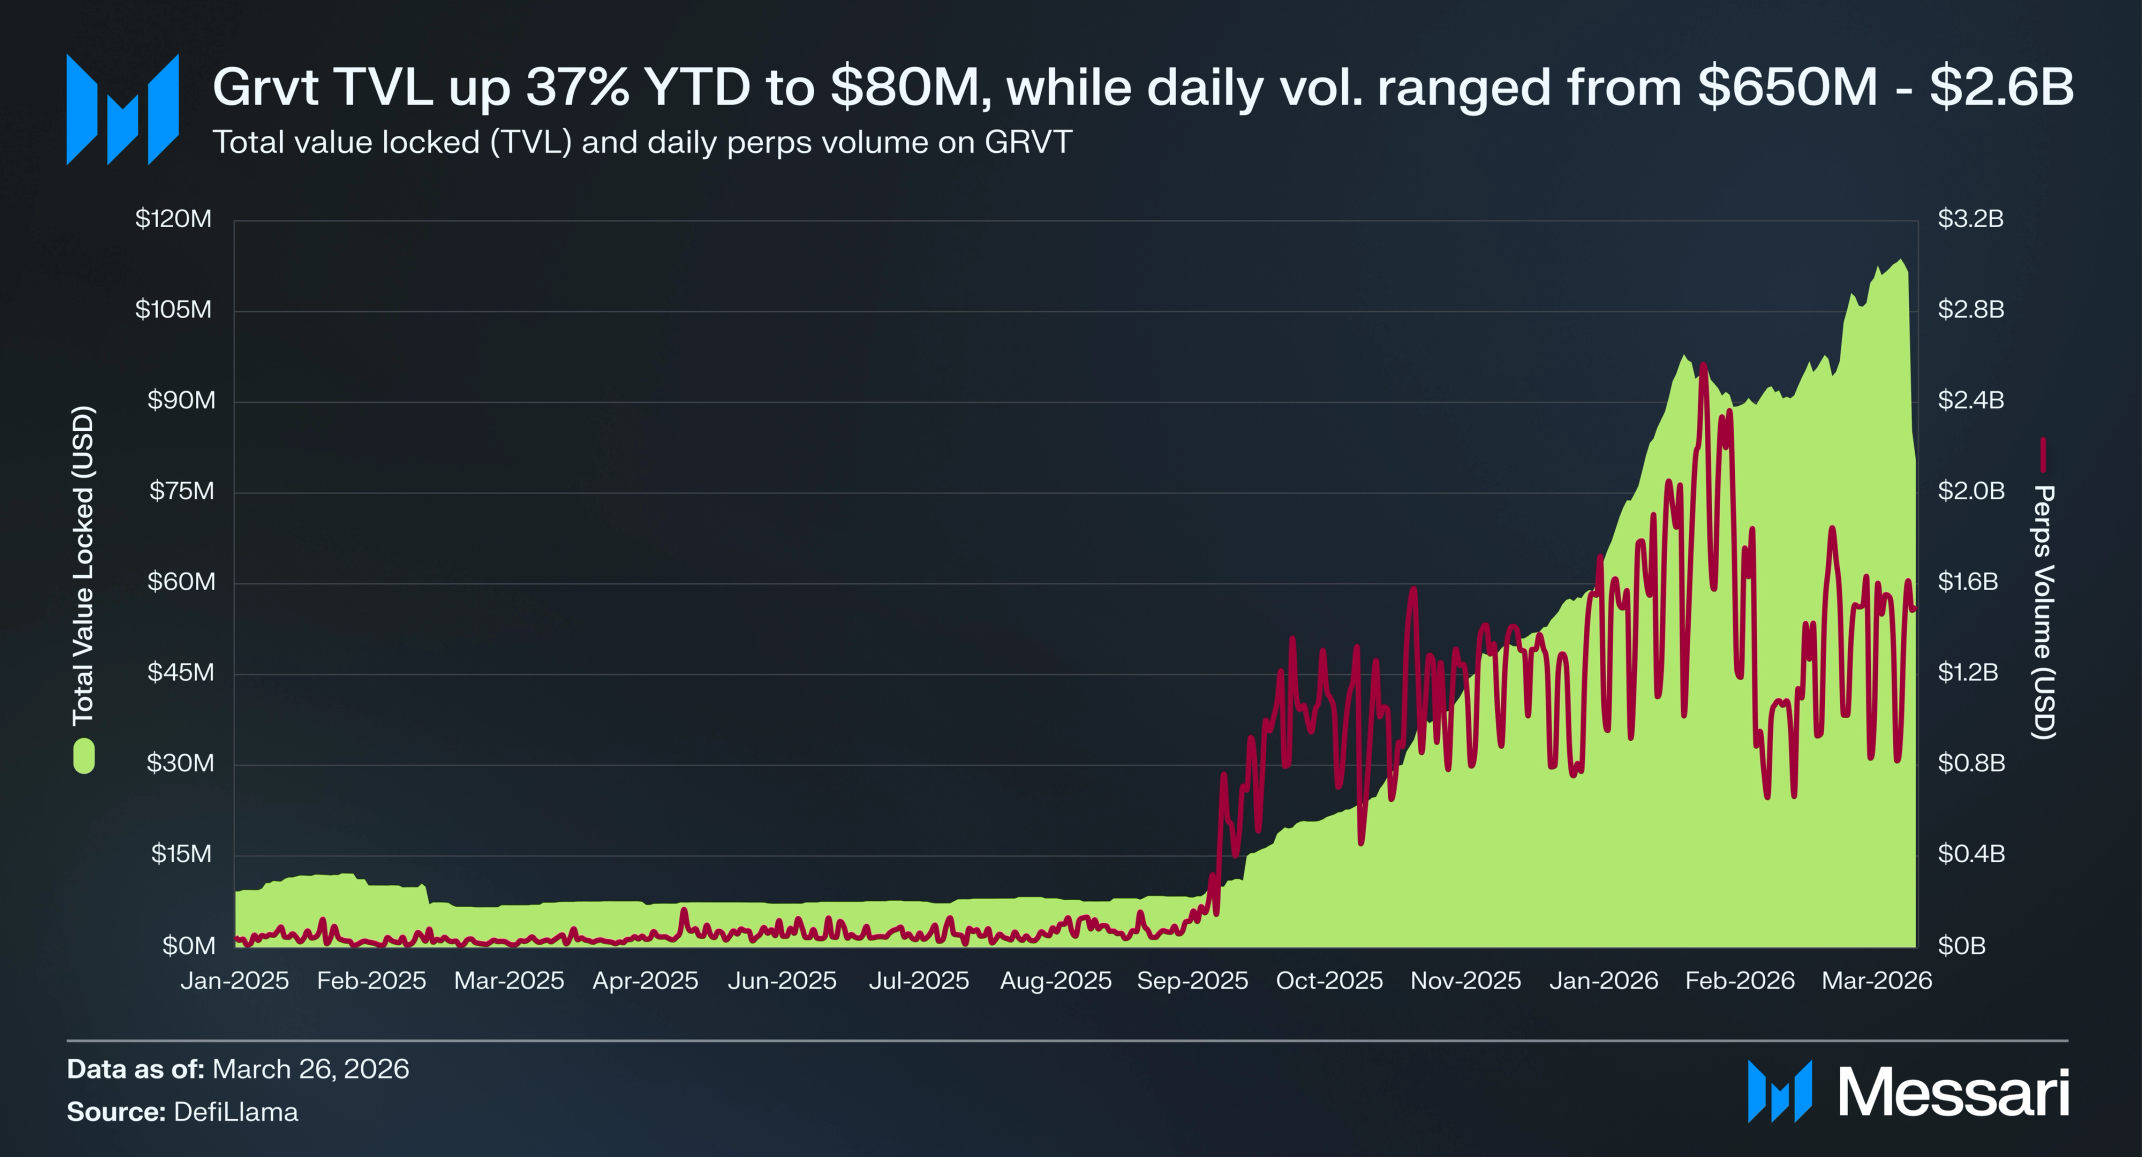
Grvt total value locked (TVL) has increased 36.8% year-to-date (YTD) from $58.8 million to $80.4 million, while open interest has increased 53.4% to $451 million, as of March 23, 2026. Daily perp volume has held steady thus far in 2026, ranging from $650 million to $2.6 billion ($1.5 billion on March 26).
GRVT, the protocol’s upcoming token, will provide benefits to stakers, including reduced trading fees, higher GLP vault allocation and APY on margin, lockup rewards, principal insurance, better foreign exchange and on/off ramp fees, and cashback in GRVT on payments with Grvt card. TGE is intended for the end of June 2026.
Primer
Grvt (pronounced "gravity") is a hybrid exchange that blends the efficiency of a centralized exchange (CEX) with the transparency of a decentralized exchange (DEX). Grvt currently offers perpetual futures, with plans to expand into spot and option markets in the future. Unlike typical DEXs that rely on Automated Market Makers (AMMs), Grvt utilizes a Central Limit Order Book (CLOB) model. This allows it to deliver a trading experience comparable to centralized exchanges (CEXs), featuring high throughput and low latency, while ensuring users retain full ownership of their assets. Grvt’s mission is to build an onchain Grvt's mission is to build an onchain finance platform that maximizes capital productivity, democratizing access to institutional-grade financial products in a self-custodial environment.
The platform’s infrastructure is built on ZKsync, a Layer 2 (L2) Ethereum scaling solution. Grvt was the first dedicated appchain launched on the ZK Stack, a modular framework that enables developers to deploy custom, interoperable blockchains known as ZK Chains. By integrating into the Elastic Chain, an ecosystem of ZK chains that share liquidity and users, Grvt can seamlessly interact with other ZK chains while maintaining its own sovereign execution environment.
ZKsync’s Atlas upgrade is foundational to Grvt’s mission. By leveraging the Elastic Chain’s one-second finality and shared bridge, Atlas allows users to seamlessly interact with assets across Ethereum and other ZK chains as margin within a single unified account. This eliminates liquidity fragmentation, enabling the institutional-grade performance and capital efficiency required for a comprehensive, self-custodial onchain finance platform. Grvt raised $34 million in 2025, with $19 million raised in a Series A funding round in September co-led by the ZKsync Foundation, Further Ventures, EigenCloud, and 500 Global. For a full primer on Grvt’s technical design, refer to our prior Pulse Report.
Perp DEXs were the breakout growth story in crypto in 2025, led by Hyperliquid the market leader. As the leading Perp DEX, Hyperliquid benefits from strong liquidity and network effects, as all else equal Perp DEXs are a winner-take-most market where liquidity begets liquidity in a self-reinforcing flywheel. But all else is not equal. A large portion of Perp DEX volume comes from mercenary capital farming airdrops and points on Perp DEX protocols that have yet to launch a token. Grvt fits into this category as its token generation event (TGE) is intended to take place at the end of June 2026, and Season 2 points are live, with 18% of the token supply allocated to it. Attributing the percentage of Grvt open interest and trading volume to fundamental adoption versus points farming is beyond the scope of this report. Regardless, in the last year, growth of Grvt’s open interest and daily trading volume has far outpaced the total Perp DEX market, which includes many competitors that have yet to launch tokens, broadly showing outsized adoption of Grvt.
Grvt Outperformance
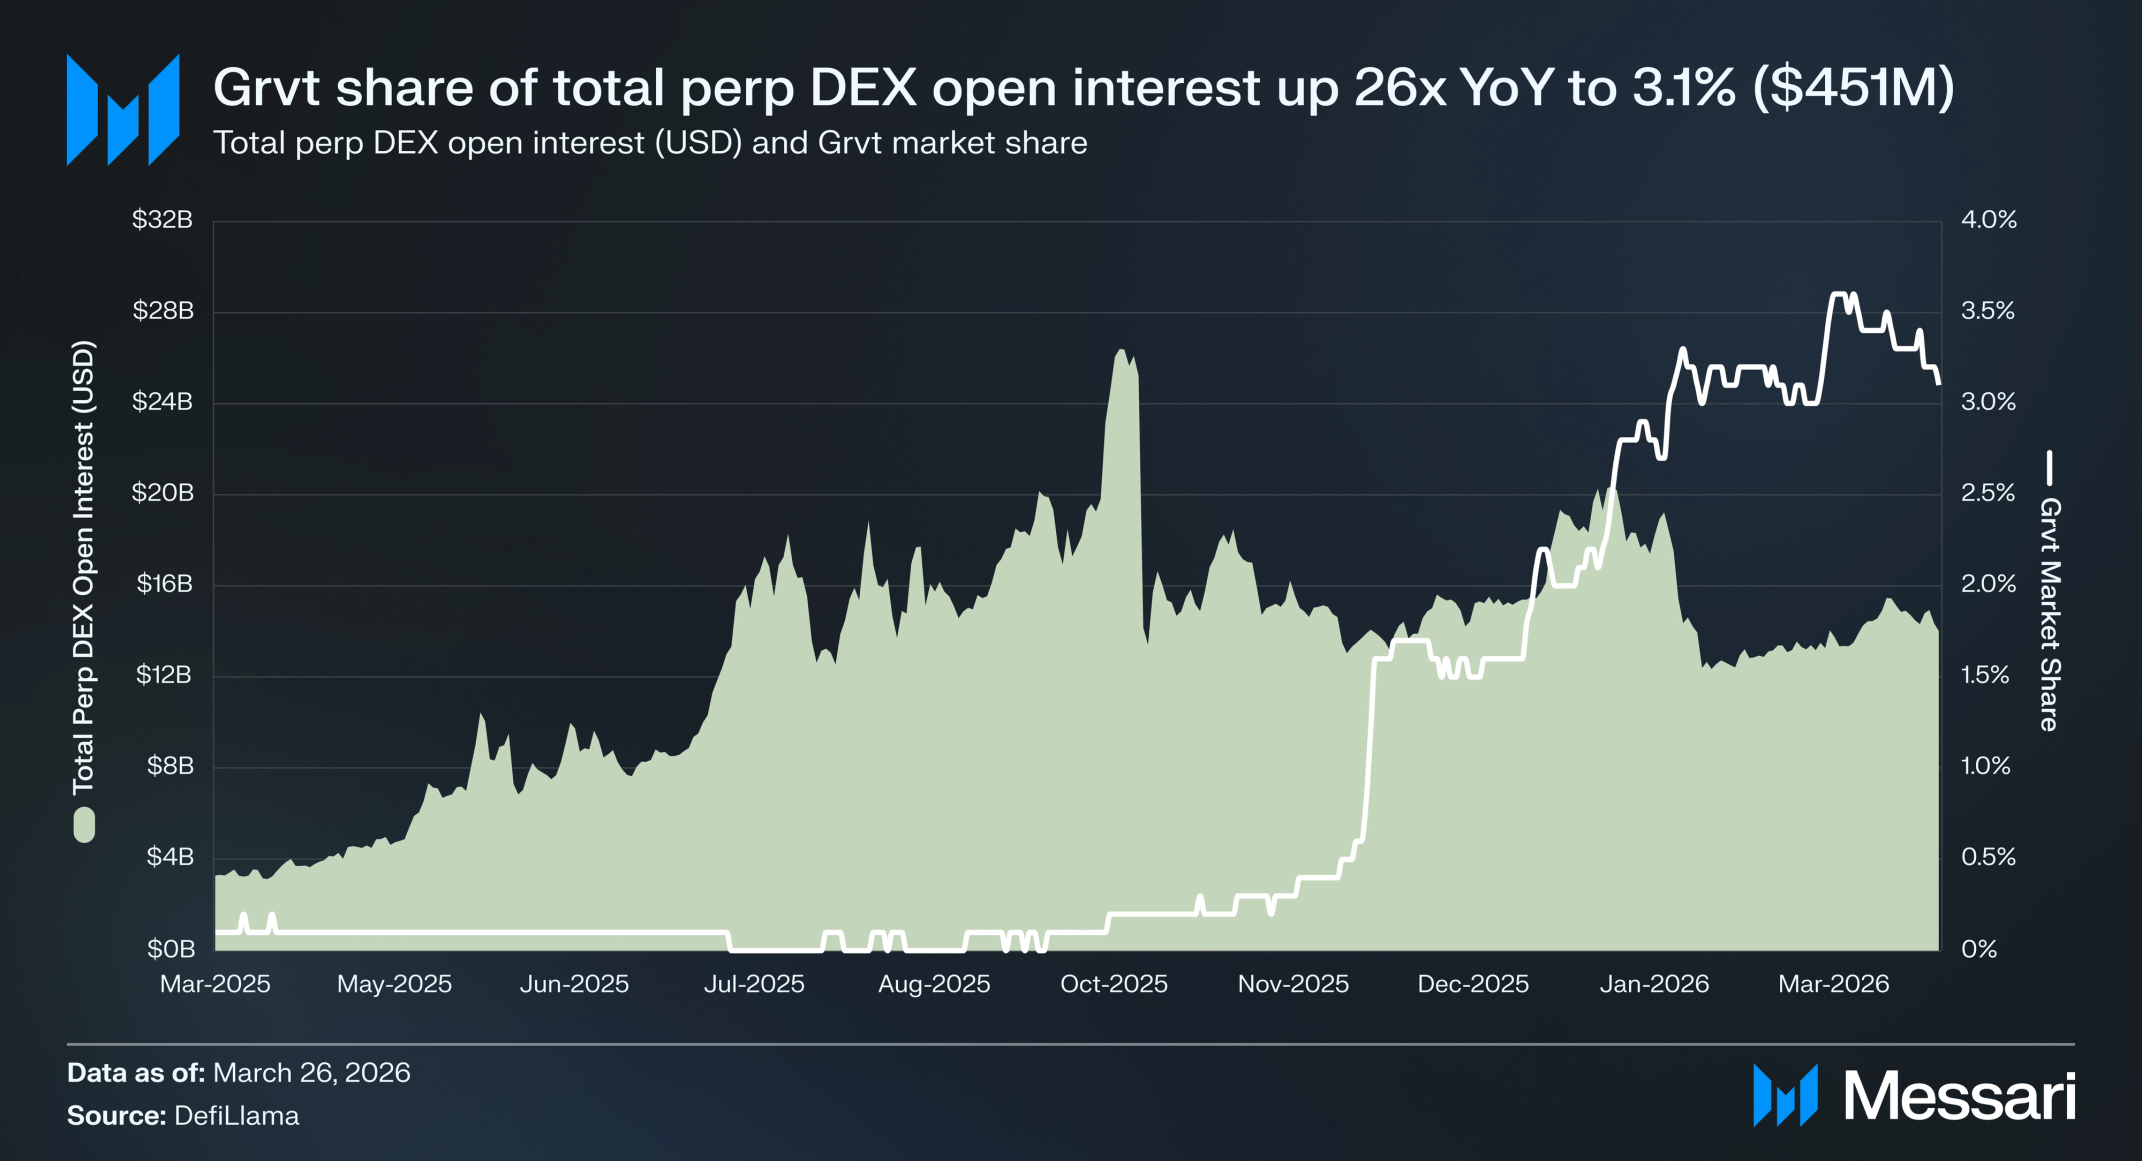
Grvt’s share of total Perp DEX open interest has increased 26x year-over-year (YoY) to 3.1%, far outpacing the 4x increase in total Perp DEX open interest from $3.3 billion to $14 billion over the same time period.
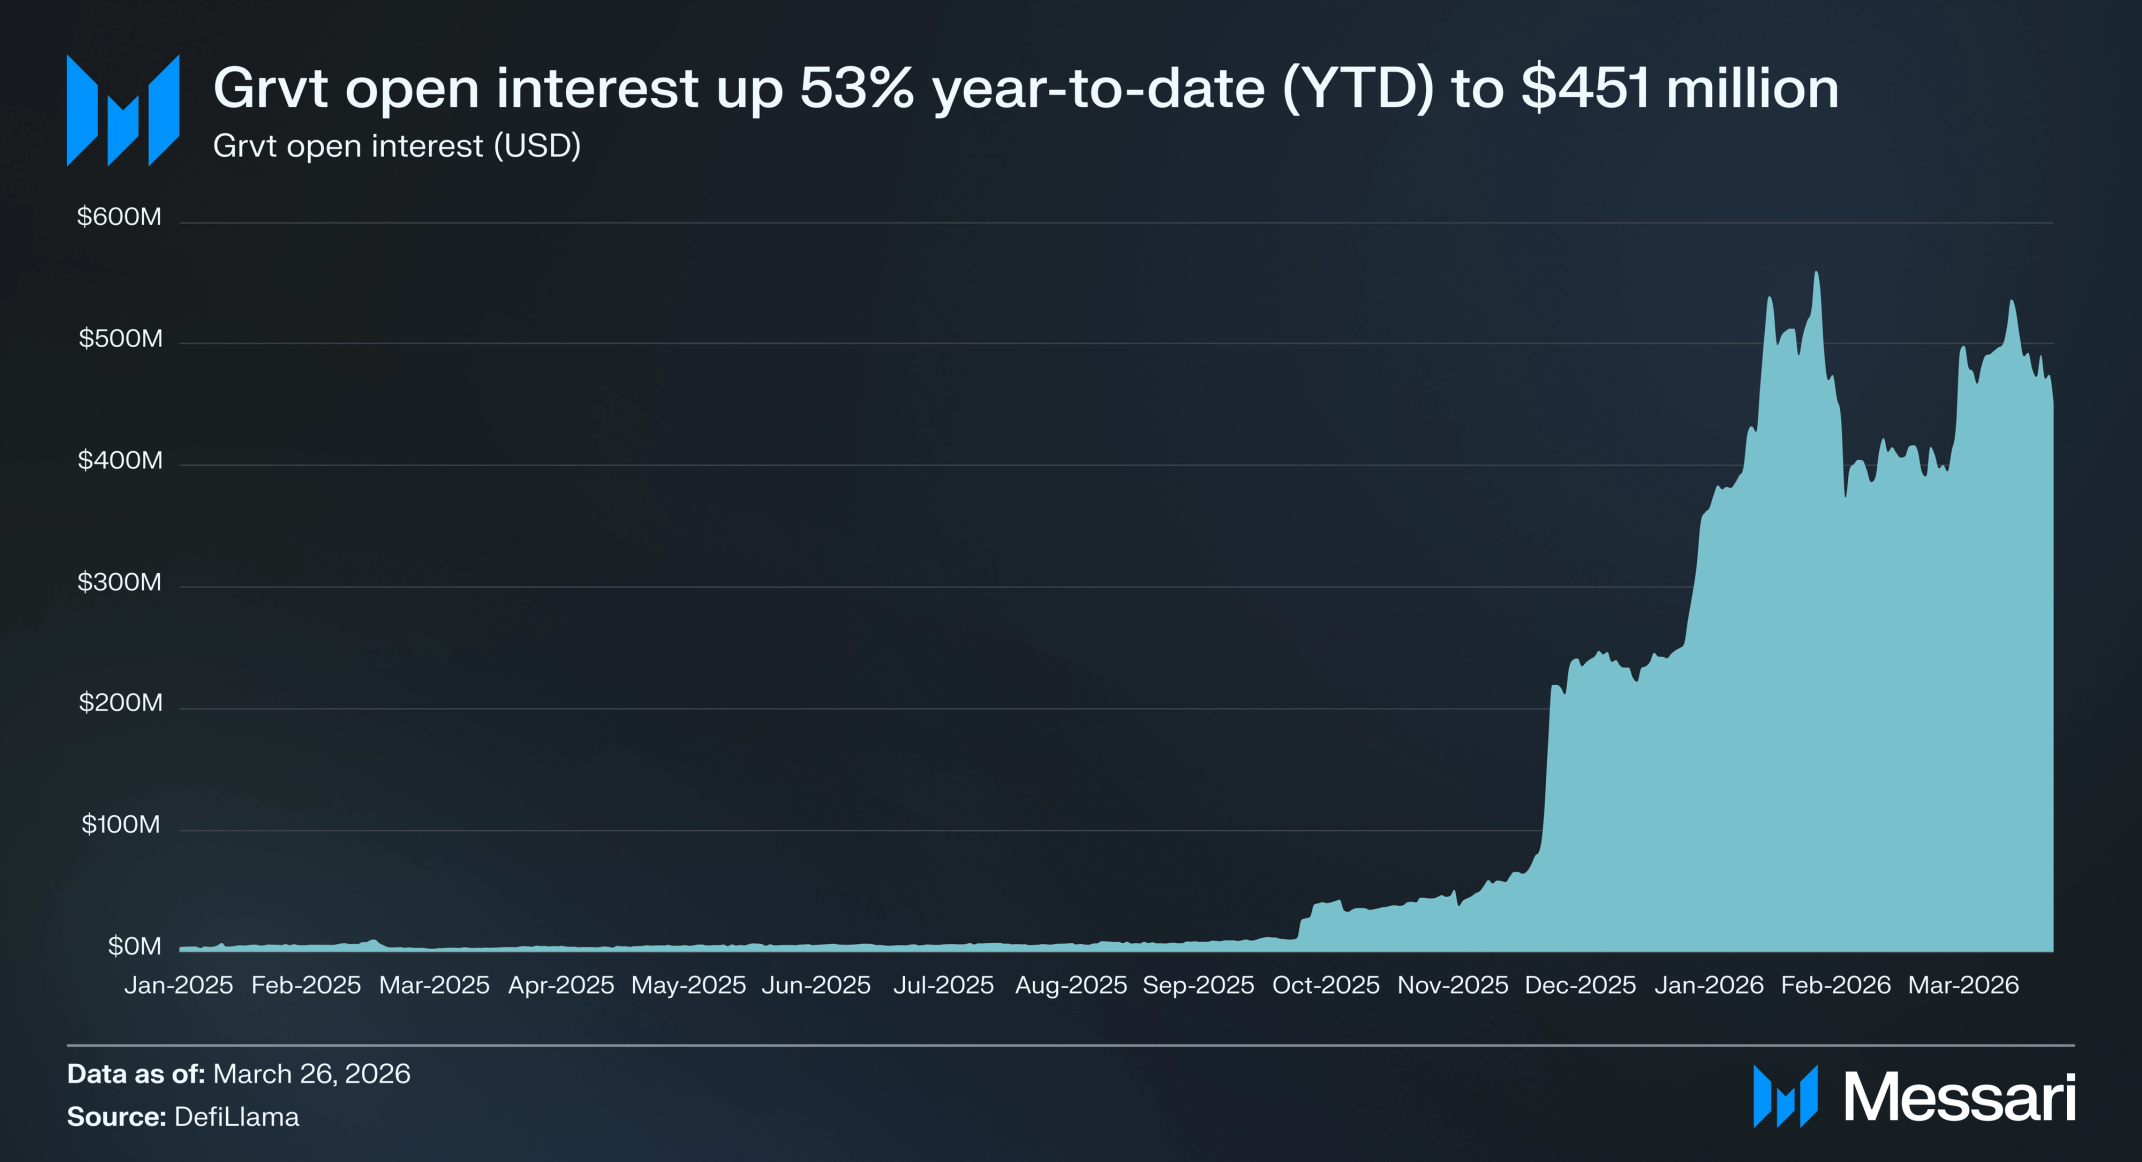
Open interest has increased 53% year-to-date (YTD) to $451 million, ranging between $317.6 million and $560 million since the start of 2026. Prior to 2026, open interest grew 11x QoQ from $26.1 million at Q3-end to $294 million at Q4-end, due to a number of catalysts:
Points program: Grvt’s points program allocated 15% of points to open interest, creating a strong incentive for users to maintain position and farm points through sustained OI rather than short-term volume alone.
Trading competitions: Grvt ran eight trading competitions in November 2025 alone, driving a significant increase in user acquisition and trading activity.
10% APY on idle USDT deposits: Grvt previously offered 10% APY on idle USDT deposits.
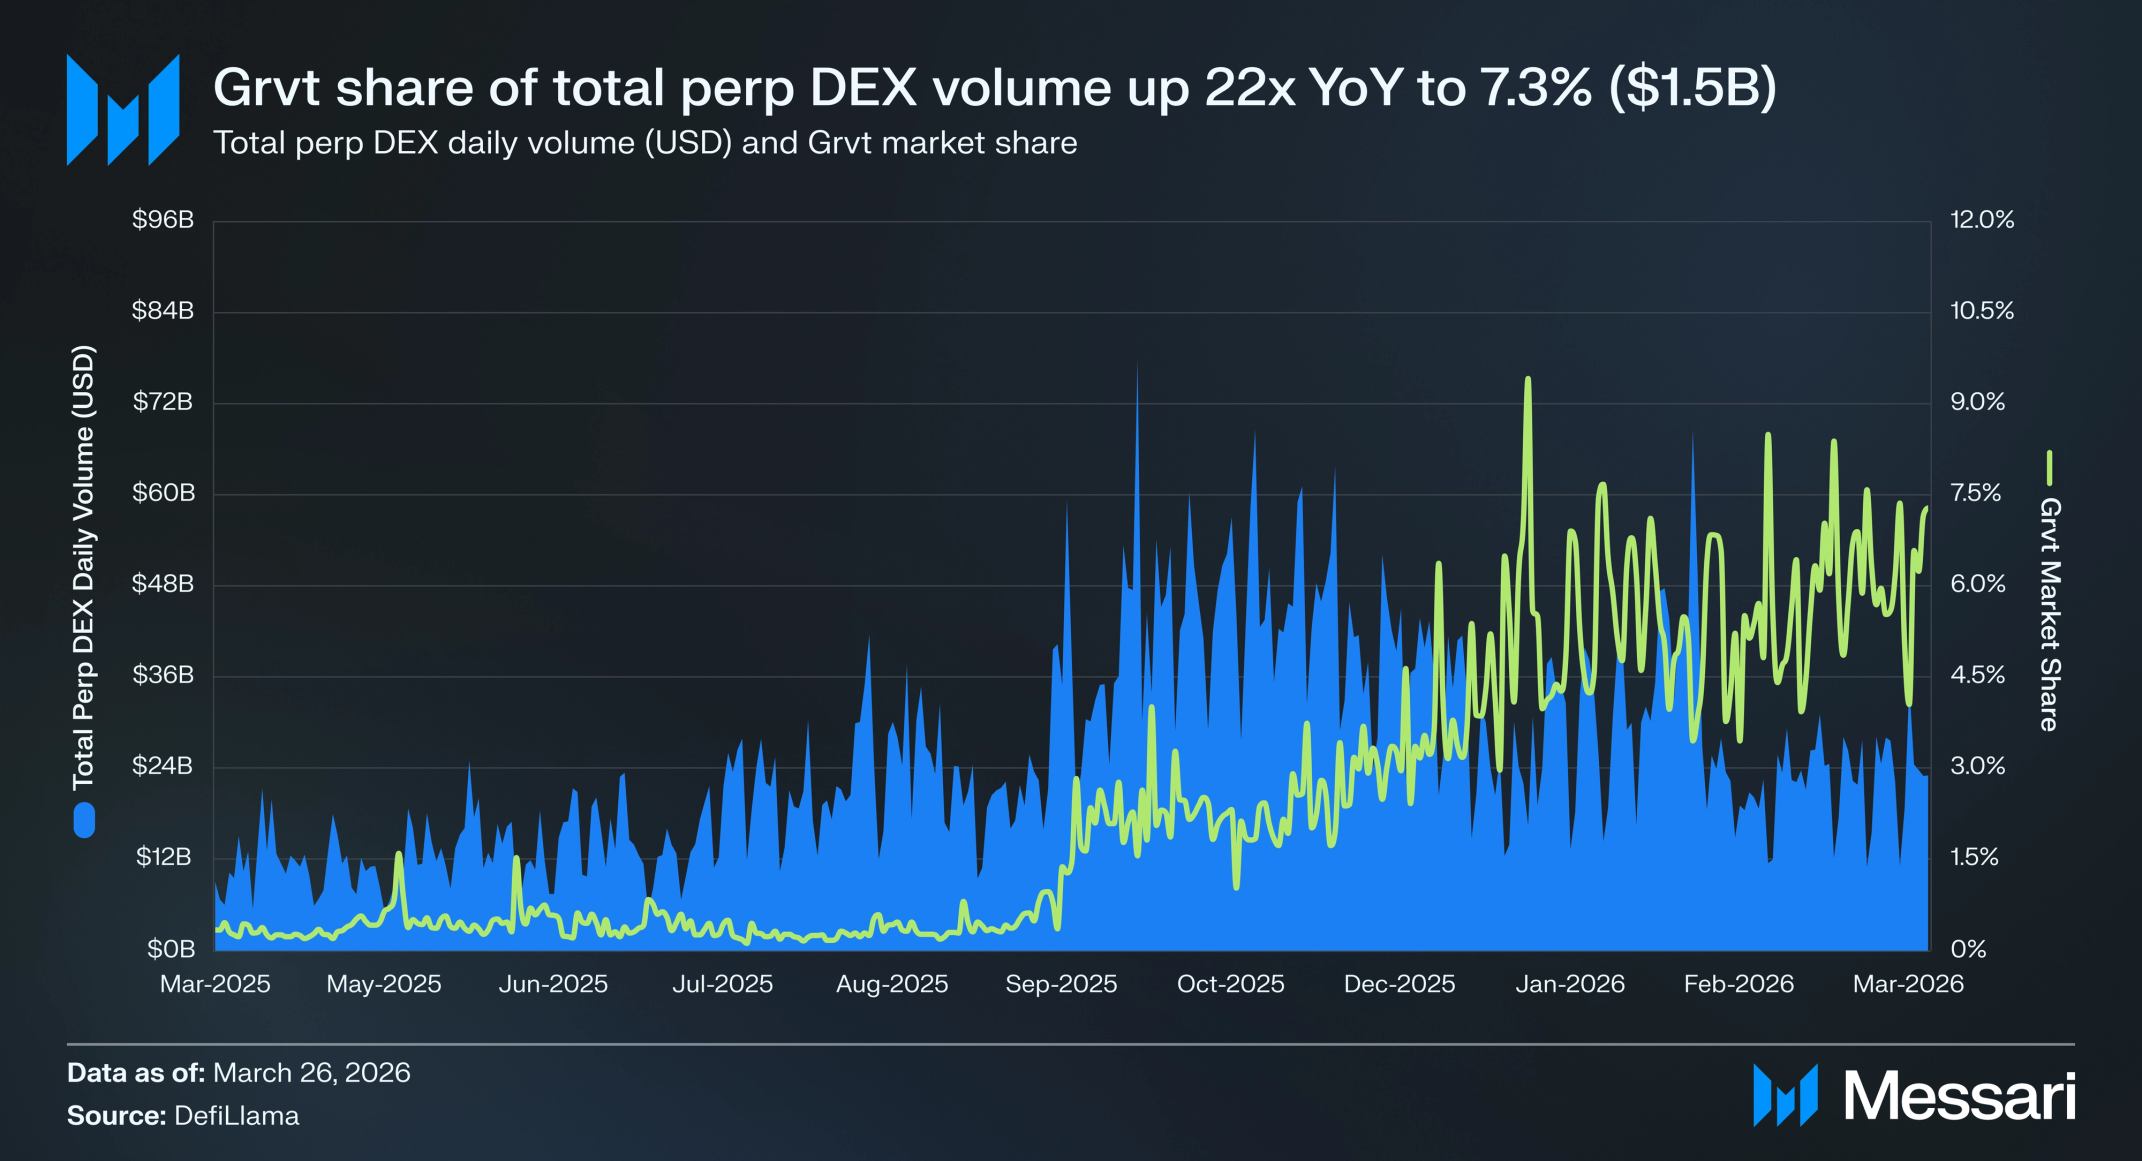
Like with open interest, Grvt’s share of total Perp DEX volume has increased 22x YoY to 7.3%, far outpacing the 2.5x increase in total Perp DEX daily volume from $9.1 billion to $23.1 billion over the same time period.
Daily perp volume has held steady thus far in 2026, ranging from $650 million to $2.6 billion ($1.5 billion on March 26). Grvt total value locked (TVL) has increased 36.8% year-to-date (YTD) from $58.8 million to $80.4 million.
Yield on Margin as the Separator
Earning up to 11% APY interest on all deposits used for trading is the defining feature of Grvt. Introduced in October 2025, interest comes from protocol trading fees and rehypothecation of most user deposits to external DeFi protocols to earn real yield. While some competitors offer the ability to earn yield on deposits, either the scope, percentage earned, or both, are limited compared to Grvt.
Limited Scope: Hyperliquid’s portfolio margin automatically generates yield on borrowable assets not being used as collateral to trade.
Lower Yield: Platforms such as Synthetix support the deposit of yield-bearing liquid staking tokens such as sUSDe and wstETH as collateral to trade. Crypto native LSTs like wstETH typically yield low, single-digit APY, while stablecoins can yield higher with the tradeoff of increased counterparty risk. For example, sUSDe yield has ranged between 2-11% APY in the last year.
Along with distributing protocol trading fees, unified margin and rehypothecation of deposits are Grvt’s two key design choices that enable yield on all collateral used for trading.
Unified Margin
On Grvt, all trader collateral is treated as a single balance under One Balance design, the protocol’s yield and collateral orchestration system. This design choice to operate via unified margin maximizes capital efficiency compared to Perp DEXs that operate under isolated margin, whereby each market requires its own collateral pool. Under isolated margin, collateral must be preallocated to each position or market, so excess buffer on one trade cannot be used to support another, often forcing traders to overfund multiple accounts and leaving capital idle. Unified margin instead lets every dollar of collateral simultaneously support all positions in the portfolio, recognize natural hedges (for example, long BTC vs. short ETH), and be routed into yield strategies to a level defined by the protocol.
Grvt's Yield Layer is the infrastructure that operationalizes this, routing idle collateral into on-chain yield integrations such as Aave, so that the same balance backing a trader's open positions is simultaneously generating yield. This is only possible under unified margin; under isolated margin, collateral is locked per-position and cannot be redirected productively. While most platforms lock isolated margin collateral per-position with no productive use, Grvt extends yield generation to isolated and cross margin as well, making Earn on Equity a platform-wide feature.
The challenge in implementing unified margin is that the risk engine underpinning it must continuously price a portfolio of heterogeneous assets, model the correlations between them, stress-test the combined position against adverse market scenarios, and trigger liquidations accurately and instantly when thresholds are breached. If not, there is a risk of systemic losses and failure. Because unified margin concentrates risk at the account level, severe losses in one position can consume shared collateral and jeopardize otherwise healthy trades, whereas isolated margin physically walls off collateral per position but at the cost of much lower capital efficiency.
Ultimately, the sustainability of a Perp DEX built on unified margin is determined by the efficacy of the risk engine, underpinned by an optimal technical architecture. Grvt is architected as a hybrid exchange leveraging zero-knowledge proofs (ZKPs) to ensure privacy. Trade orders are matched offchain on Grvt’s own servers, while every step involving asset movement and settlement is completed inside a ZKP system called Validium, a secure vault built on ZKSync technology, to ensure privacy.
To date, USDT is the only accepted form of collateral on Grvt, though support for BTC, ETH, and yield-bearing RWAs is intended.
Rehypothecation
Grvt rehypothecates most user deposits to external DeFi protocols to earn real yield, while the L2 trading contract retains enough for day-to-day user withdrawals. In February 2026, Grvt announced it will integrate overcollateralized lending and borrowing protocol Aave as its first external yield source. The integration is enabled by Aave ecosystem service provider and financial architect TokenLogic. Integrations with other DeFi protocols such as Aave’s V4 and Horizon (RWAs) instances, Morpho, Pendle, Ethena, and major stablecoin issuers are intended in the coming months.
By decoupling where collateral deposited earns yield (Ethereum L1) from where user activity is tracked (Grvt private L2), Grvt ensures the privacy guarantees of its Validium-based appchain, while remaining composable with external DeFi.
Earn on Equity Terms, Negative Maker Fees, and Tradable Assets
Up to 11% APY can be earned on up to $100,000 deposited to a Grvt user’s trading account as follows.
3.5% APY: Complete five trades in a four-week cycle.
Additional 1% APY: Onboard at least one referral who deposits at least $1,000 USDT and completes five trades before the four-week cycle ends (can also be completed as the invitee).
Additional 1%- 6.5% APY: In a given four-week cycle, earn a 1% APY boost for having $50,000 in trading volume and an additional 1% boost for each of the following volume milestones: $300,000, $750,000, $1.5 million, $2.5 million, and another 1.5% for reaching $5 million in volume.
Maker fees on Grvt are negative across all nine fee tiers, ranging from -0.0001% to -0.003%, with users receiving a USDT rebate immediately to their trading account on each executed trade. As such, users trading as makers do not face additional hidden fees to reach the maximum APY.
The exchange supports perpetual futures trading for major assets, including:
Crypto assets: BTC, ETH, SOL, BNB, XRP, HYPE, etc.
Equities: GOOGL, CRCL, COIN, PLTR, NVDA, META, PYPL, etc.
ETFs: EWJ, EWY, SPY, QQQ
GRVT Functionality and TGE
On March 12, 2026, Grvt introduced the GRVT token, which will provide benefits to GRVT stakers, including reduced trading fees, higher GLP vault allocation and APY on margin, lockup rewards, principal insurance, better foreign exchange and on/off ramp fees, and cashback in GRVT on payments with Grvt card. Membership tiers for these benefits will be released at a later date and determined by the amount and length of Grvt staked. The GRVT token generation event (TGE) is intended for the end of June 2026.
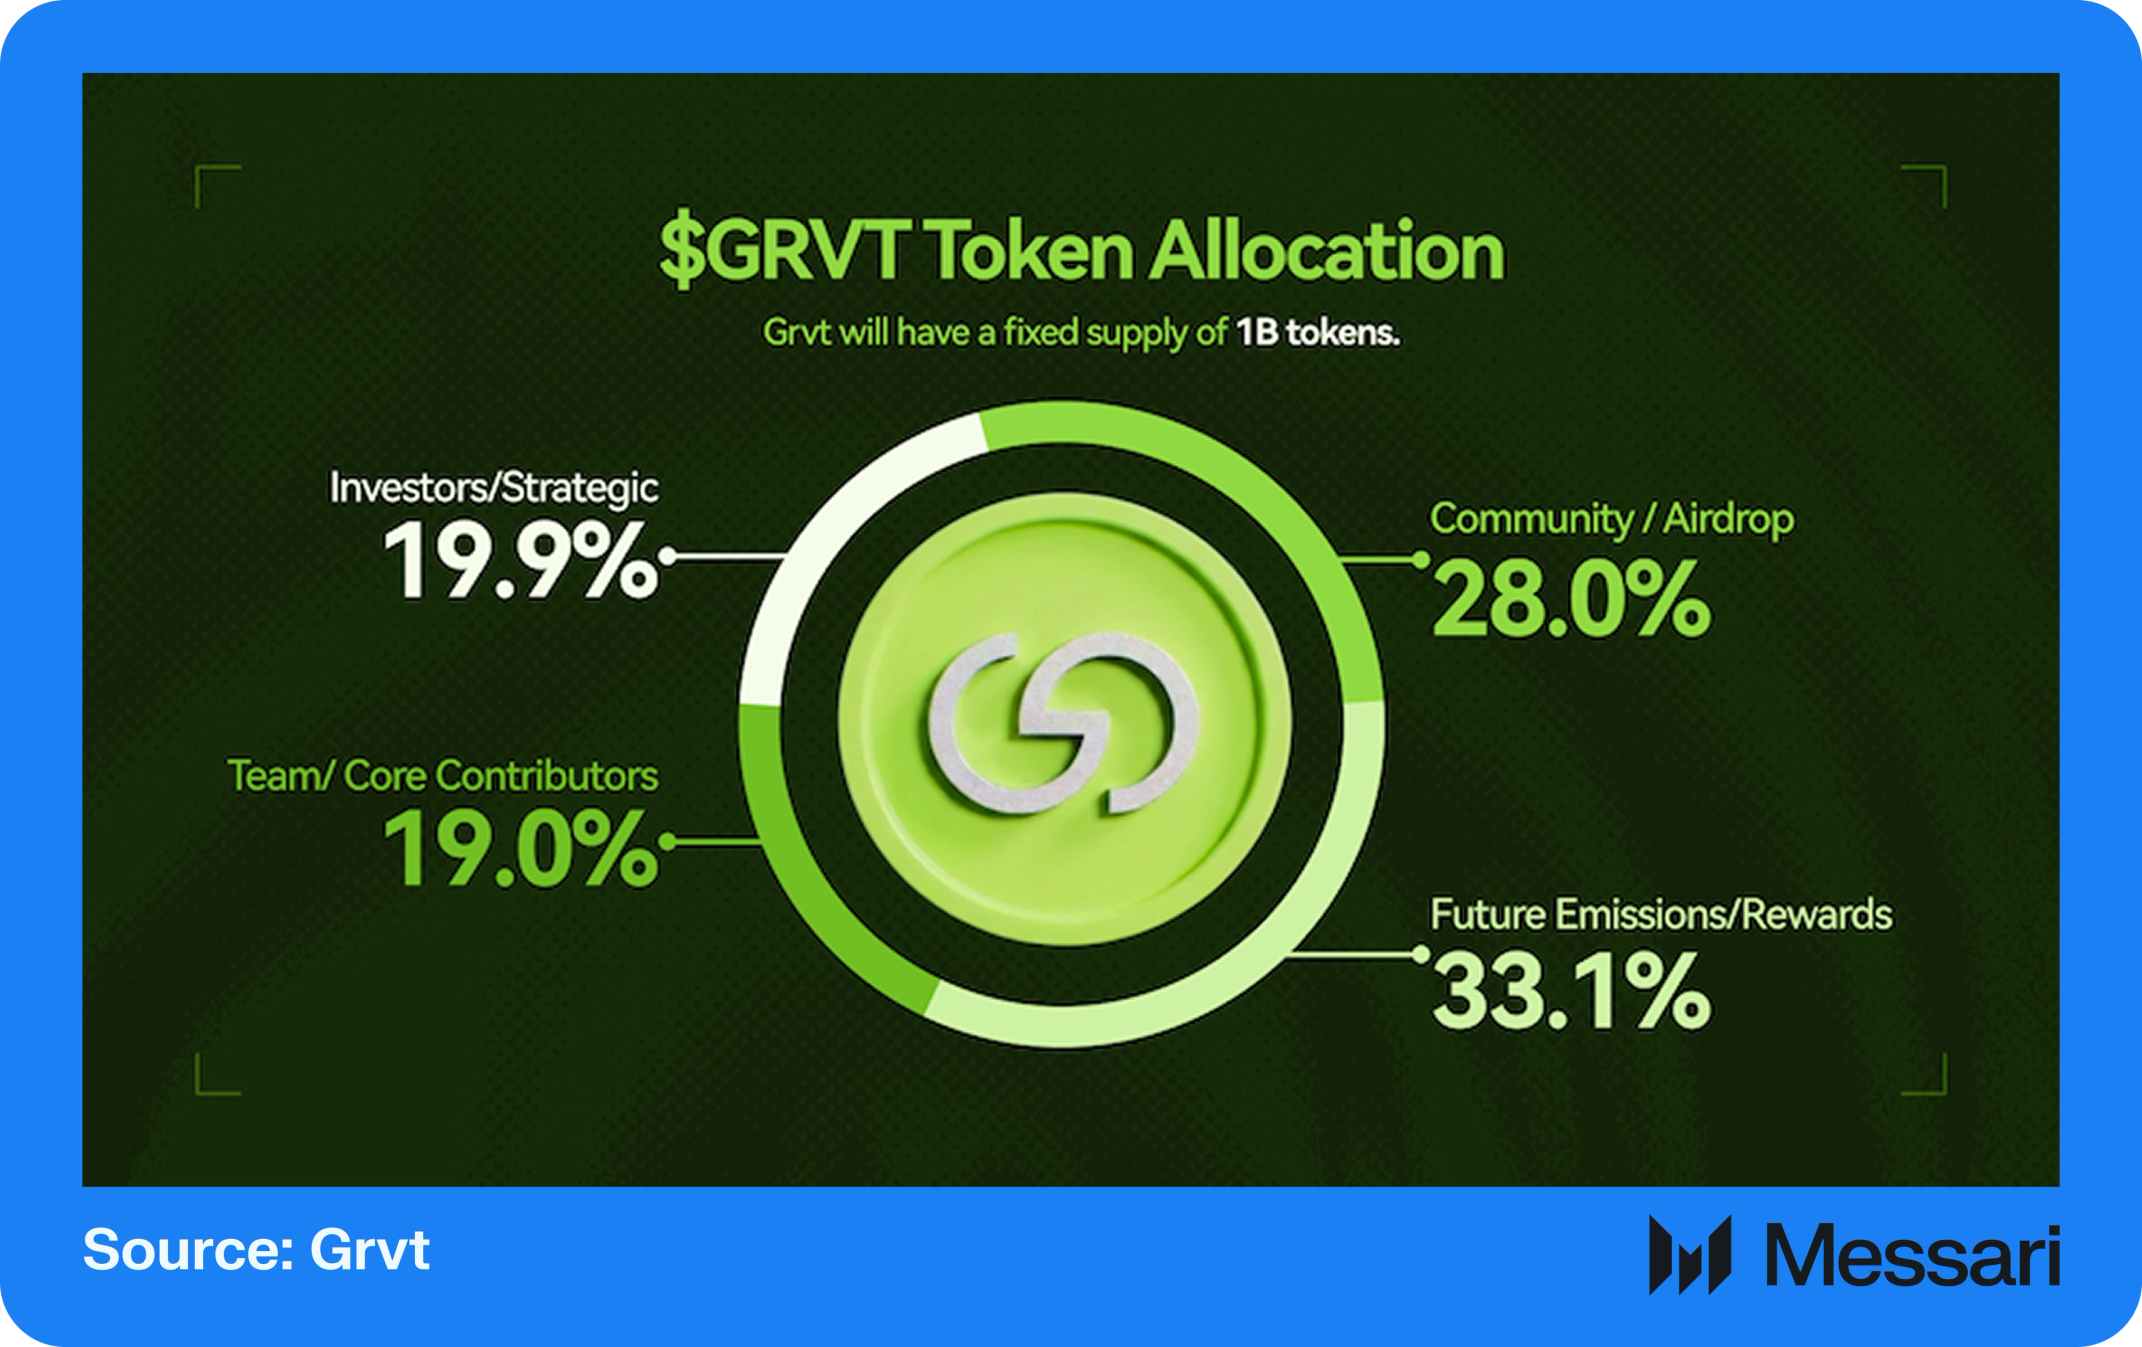
GRVT will have a maximum supply of 1 billion, as follows:
Future Emissions/Rewards: 33.1%
Community/Airdrop: 28.0% (10% to Season 1 points and 18% to Season 2)
Investors/Strategic: 19.9%
Team/Core Contributors: 19.0%
The Grvt team also intends to implement a systematic buyback program of GRVT, raise capital from institutional investors to secure “Day 1 anchor buyers,” and have GRVT be listed on multiple tier 1 exchanges.
Other Key Updates
GLP Capacity Increase (March 20): Capacity was raised to $30 million for the Grvt Liquidity Provider (GLP), Grvt’s delta-neutral market-making strategy.
Grvt x CCXT (March 19): Grvt has partnered with CCXT, a crypto exchange trading library, which joined its Builder Codes program.
New Fee Structure (March 19): Grvt updated its trading fee structure, raising the trading volume required to reach each of the fee tiers after Level 1.
Split Take Profit and Stop Loss (March 19): Split take profit and stop loss were made available, allowing partial closes of positions at specified levels.
Bug Bounty Program Complete (March 17): Grvt concluded its bug bounty program, with ZK token rewards distributed for the highest impact submissions.
Season 2 Points Program (March 15): Changes to Points Multipliers for Grvt Season 2 Points were announced. These include the Altcoin multiplier being reduced from 5x to 2x and RWAs having a 3x multiplier.
Grvt x Arbital (March 2): Grvt integrated institutional market-making protocol Arbital, so that its users can run market-making strategies with zero code required.
Grvt x Planemo Trading Strategies (Feb. 16): Planemo Trading went live on Grvt, allowing users to automate trading strategies.
Grvt x Fraction AI (Feb. 13): Fraction AI partnered with Grvt to integrate AI agents to Grvt.
Scale Orders (Feb. 12): Grvt released scale orders, allowing users to spread limit orders across a price range to scale in and out positions automatically.
Closing Summary
Earning up to 11% APY interest on all deposits used for trading is the defining feature of Grvt. Interest comes from protocol trading fees and rehypothecation of most user deposits to external DeFi protocols to earn real yield. Grvt started to integrate Aave V3 as its first external yield source in February, with other DeFi protocols such as Aave’s V4 and Horizon (RWAs) instances, Morpho, Pendle, Ethena, and major stablecoin issuers expected in the coming months. By decoupling where collateral deposited earns yield (Ethereum L1) from where user activity is tracked (Grvt private L2), Grvt ensures the privacy guarantees of its Validium-based appchain, while remaining composable with external DeFi.
Unified margin is the other key design choice that unlocks yield for Grvt traders. Treating all trader collateral on Grvt as a single balance maximizes capital efficiency compared to Perp DEXs that operate under isolated margin, whereby each market requires its own collateral pool.
The growth of open interest and daily trading volume on Grvt suggests merit in these design choices. Open interest has increased 53% year-to-date (YTD) to $451 million, ranging between $317.6 million and $560 million since the start of 2026, while daily perp volume has held steady thus far in 2026, ranging from $650 million to $2.6 billion ($1.5 billion on March 26).
With BTC, ETH, and yield-bearing RWA collateral on the horizon, Grvt is primed to further the capital productivity of user assets, as preparation is made for the intended TGE of GRVT in late June.
This report was commissioned by Grvt Technologies Pte Ltd. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Matt is a Research Manager at Messari for the Protocol Reporting team. A generalist at heart, who's curious about anything and everything, and ultimately, on an adventure to find out what's true. He was an investigative reporter and multifamily/senior housing development associate before joining Messari in 2022.
Matt is a Research Manager at Messari for the Protocol Reporting team. A generalist at heart, who's curious about anything and everything, and ultimately, on an adventure to find out what's true. He was an investigative reporter and multifamily/senior housing development associate before joining Messari in 2022.