Ethereum September 2025 Update

Fundamentals
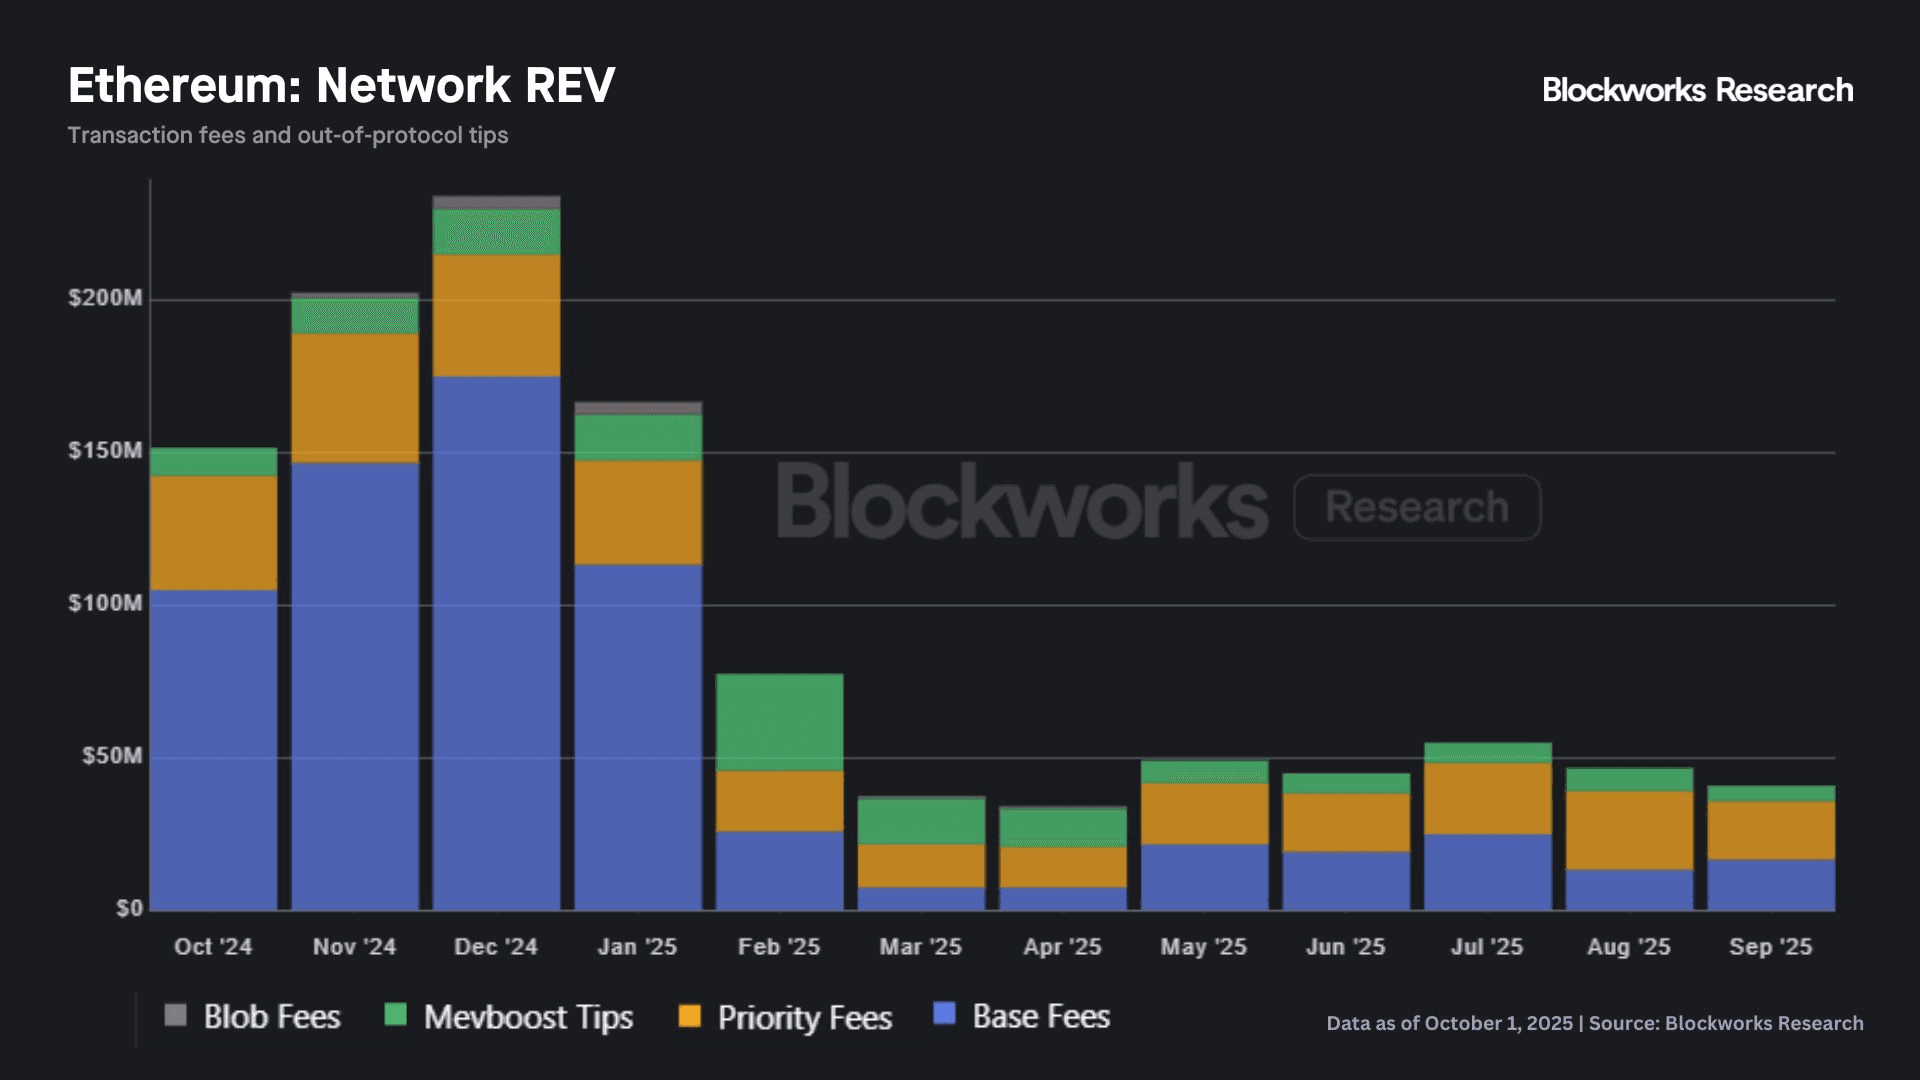
In September 2025, Ethereum’s Real Economic Value (REV) continued to soften, falling ~9% MoM to ~$41.4M from ~$46.5M in August. The decline was broad-based across base fees, priority fees, and MEV-boost tips, reflecting a moderation in demand for blockspace despite elevated stablecoin supply and relatively strong trading activity earlier in the quarter. September marked one of the weakest revenue months of the past year, underscoring the disconnect between network usage metrics and fee generation as scaling solutions and more efficient transaction routing reduce onchain cost burdens.
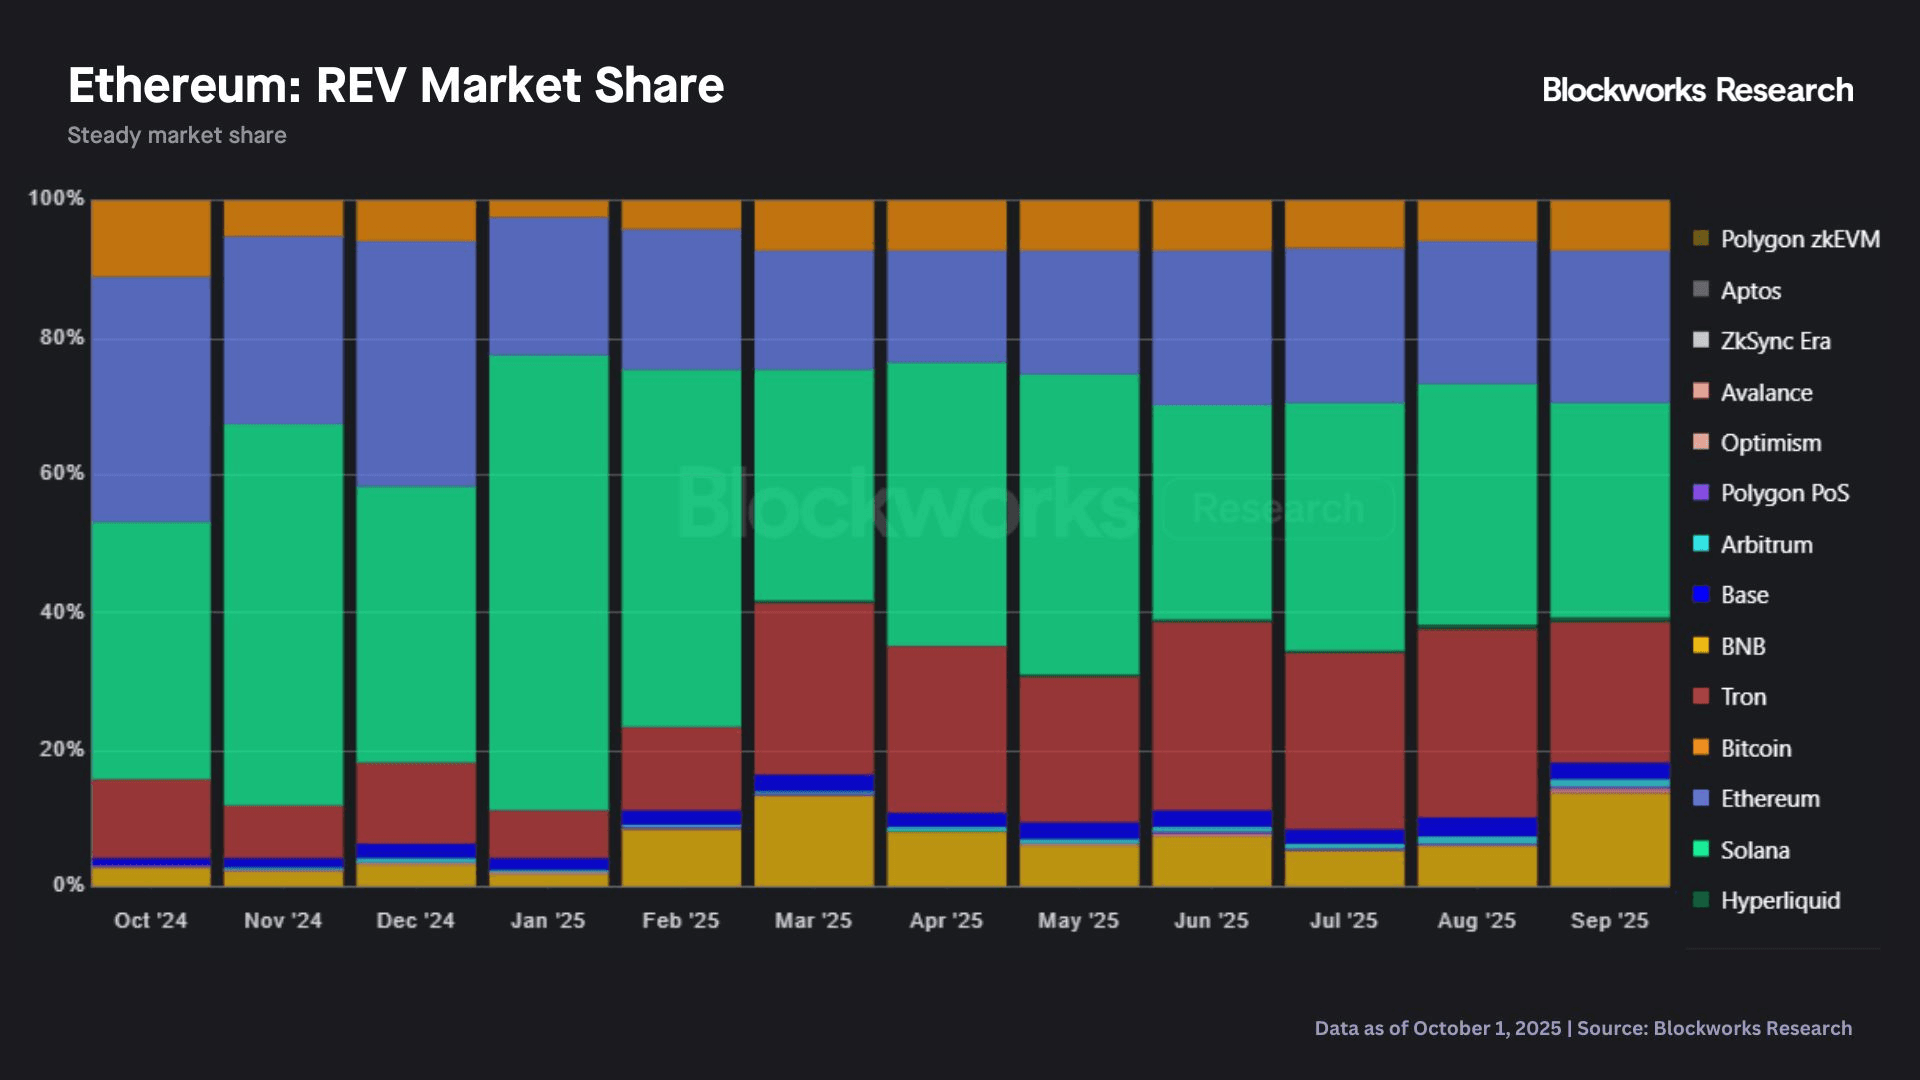
Ethereum’s share of industry Real Economic Value (REV) held steady in September at ~22%, as little changed from August at ~21% despite a 9% decline in absolute terms. The stability in share reflects broad-based weakness across networks rather than idiosyncratic Ethereum underperformance. Only Solana (31%) continued to command a higher monthly REV. The chart below illustrates the evolution of Ethereum’s REV share relative to other chains over the past year.
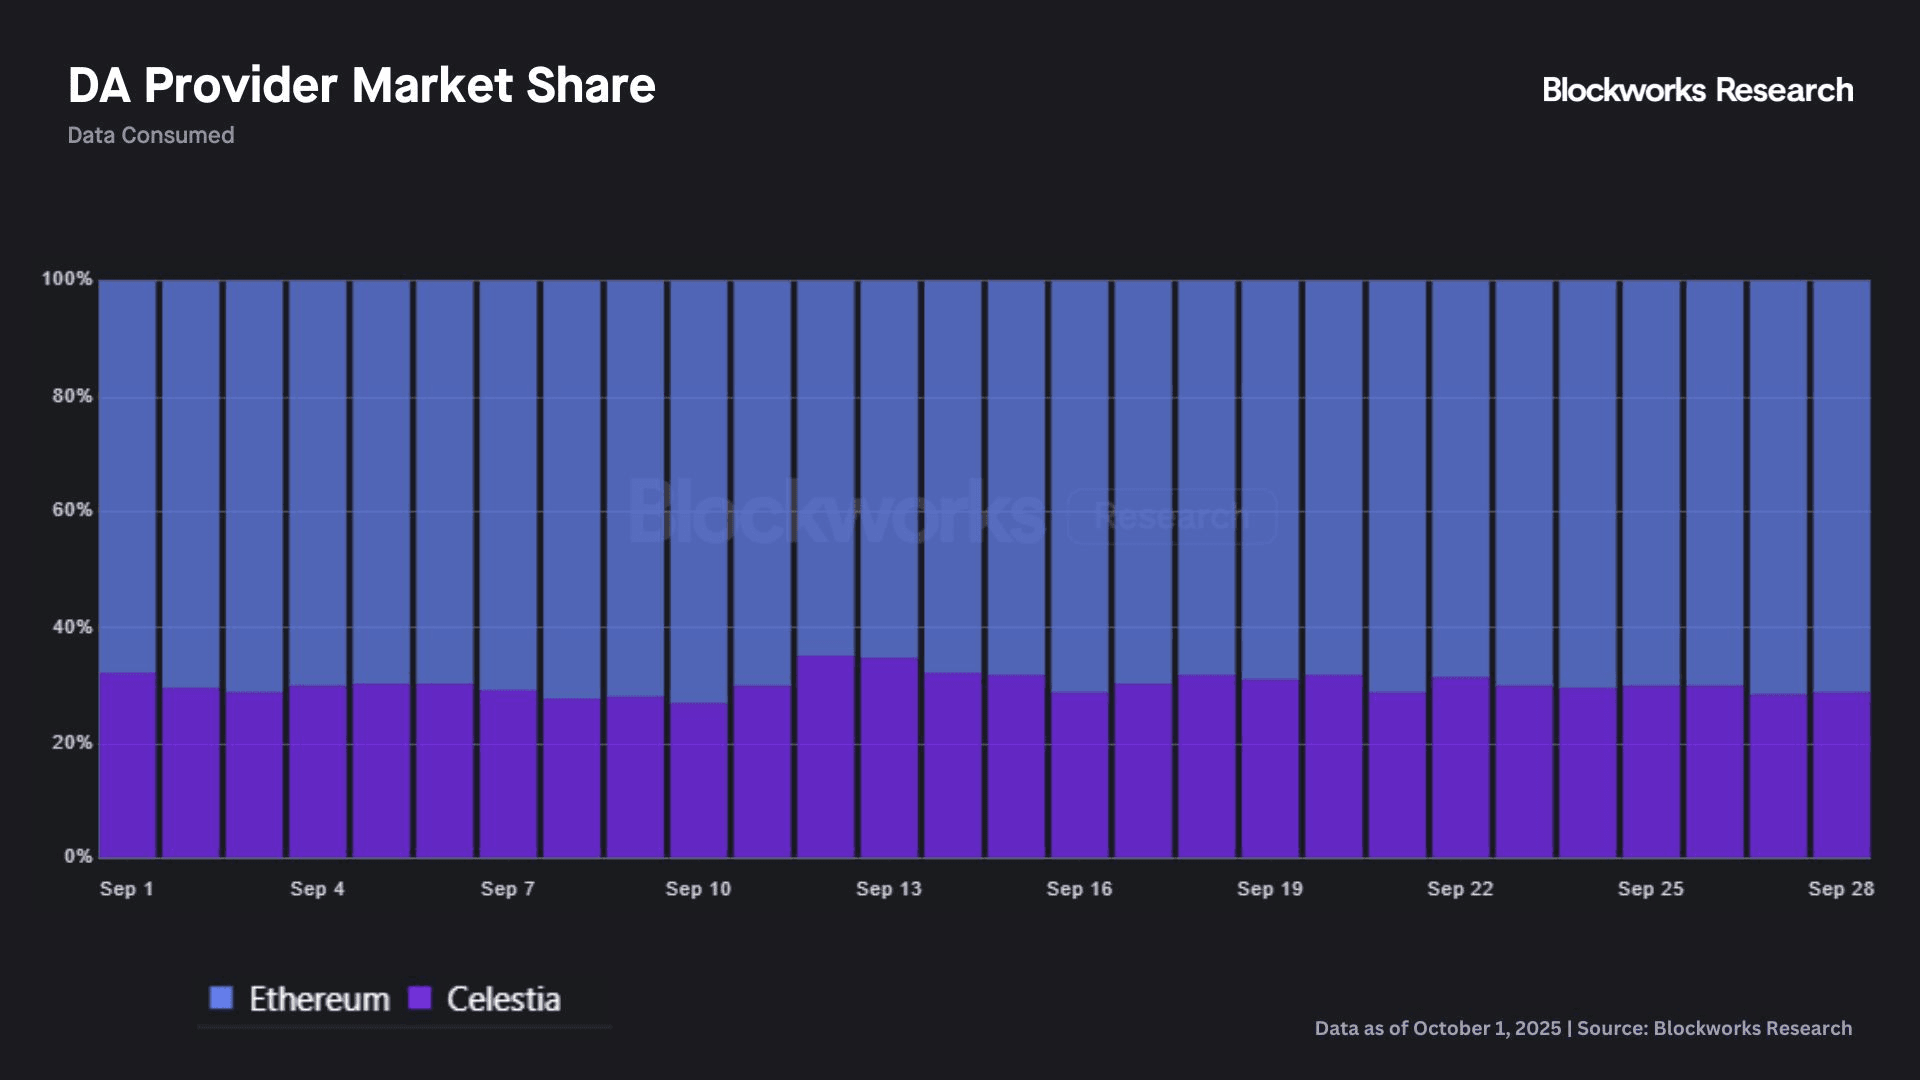
Ethereum maintained its leading position in the data availability (DA) market through September, holding roughly two-thirds of total consumption. This represents a continuation of gains made since May, when Celestia briefly captured incremental share on the back of Eclipse-related activity. However, with data posted to Celestia down sharply in recent months, Ethereum has reclaimed ground and stabilized its dominance. The dynamic underscores Ethereum’s resiliency as the default DA layer, even as alternative providers seek to compete on cost and modularity. The chart below illustrates the evolving DA market share between Ethereum and Celestia throughout September.

Marc covers Ethereum, Bitcoin and their L2s. Previously led Ethereum and DeFi research at CoinShares.