Ethereum August 2025 Update

Fundamentals
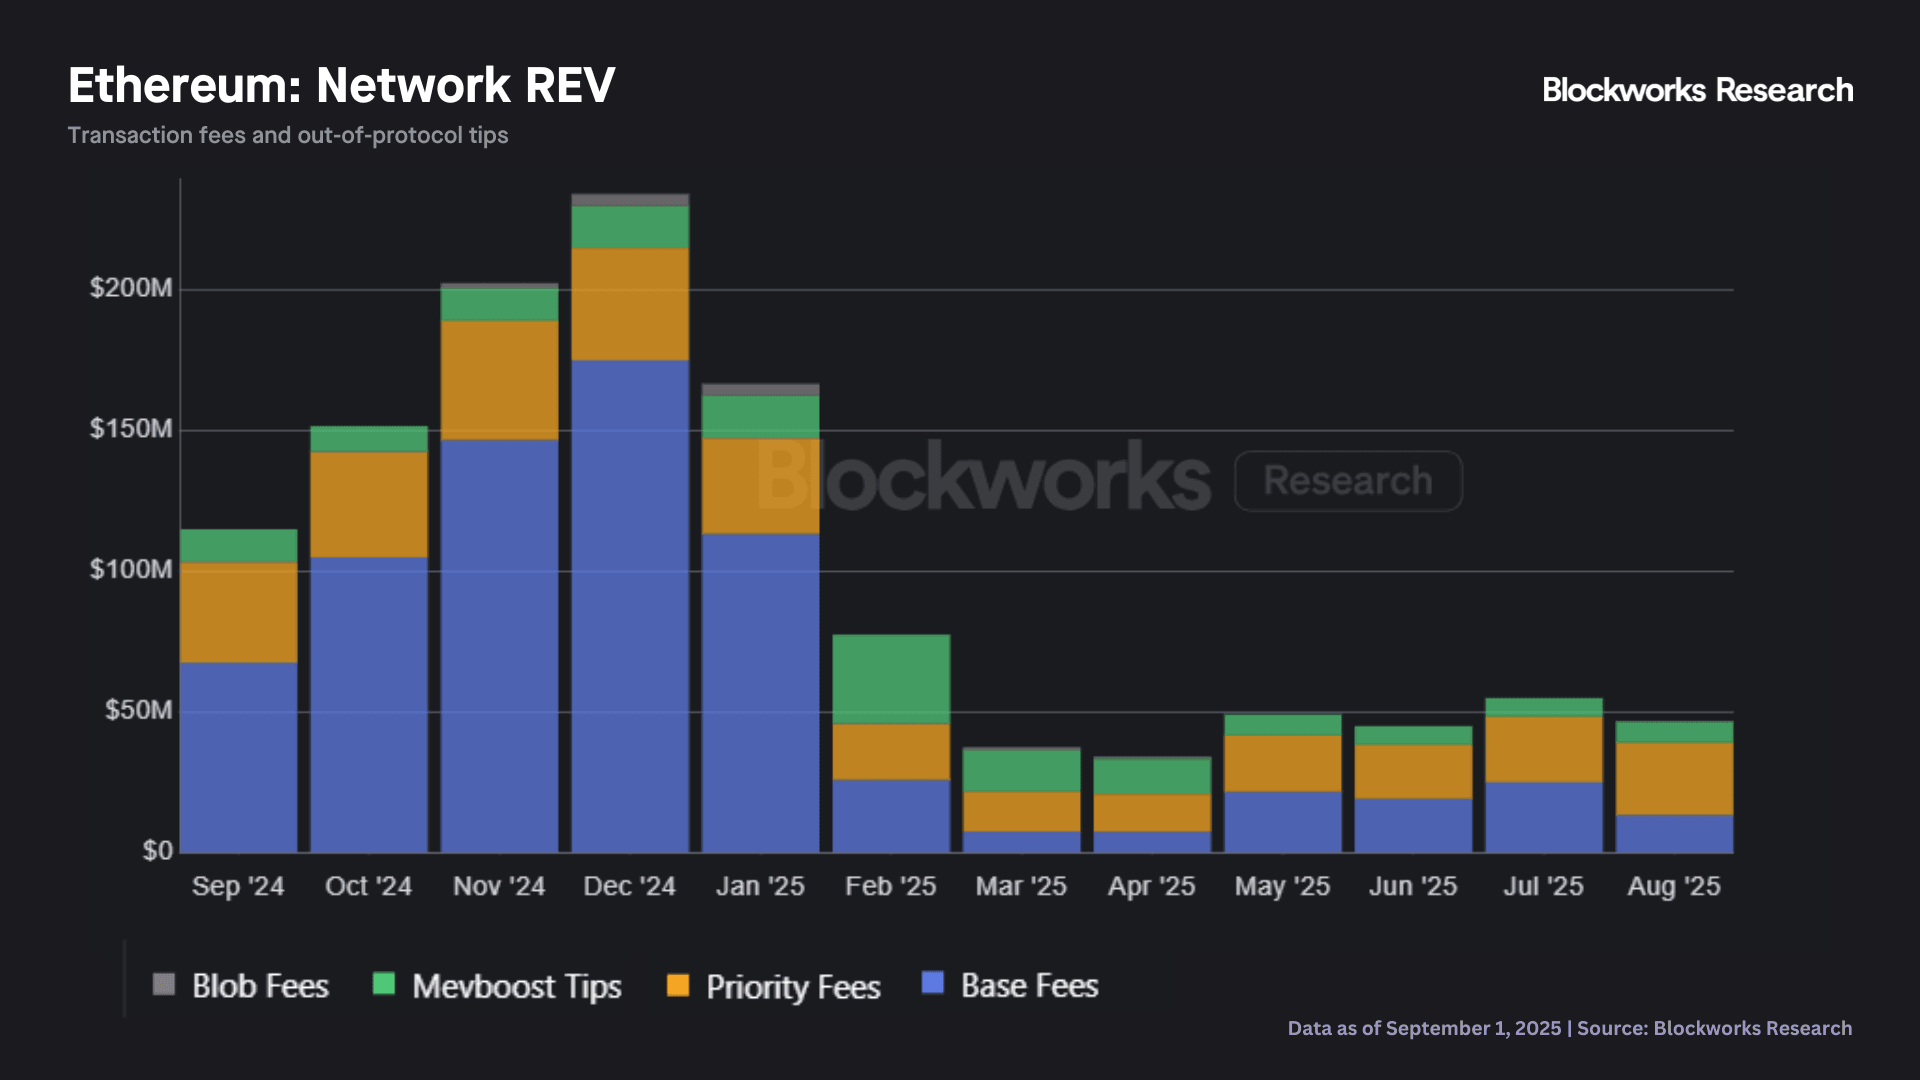
Furthermore, despite the ~19% price increase, Ethereum’s Real Economic Value (REV), which combines transaction fees and tips paid for transaction execution, decreased by ~16% to $46.5M (vs $55M in July). August was the third-lowest REV-generating month in the last year, but it mattered little thanks to the aforementioned flows. Below we show Ethereum’s monthly REV over the last year.
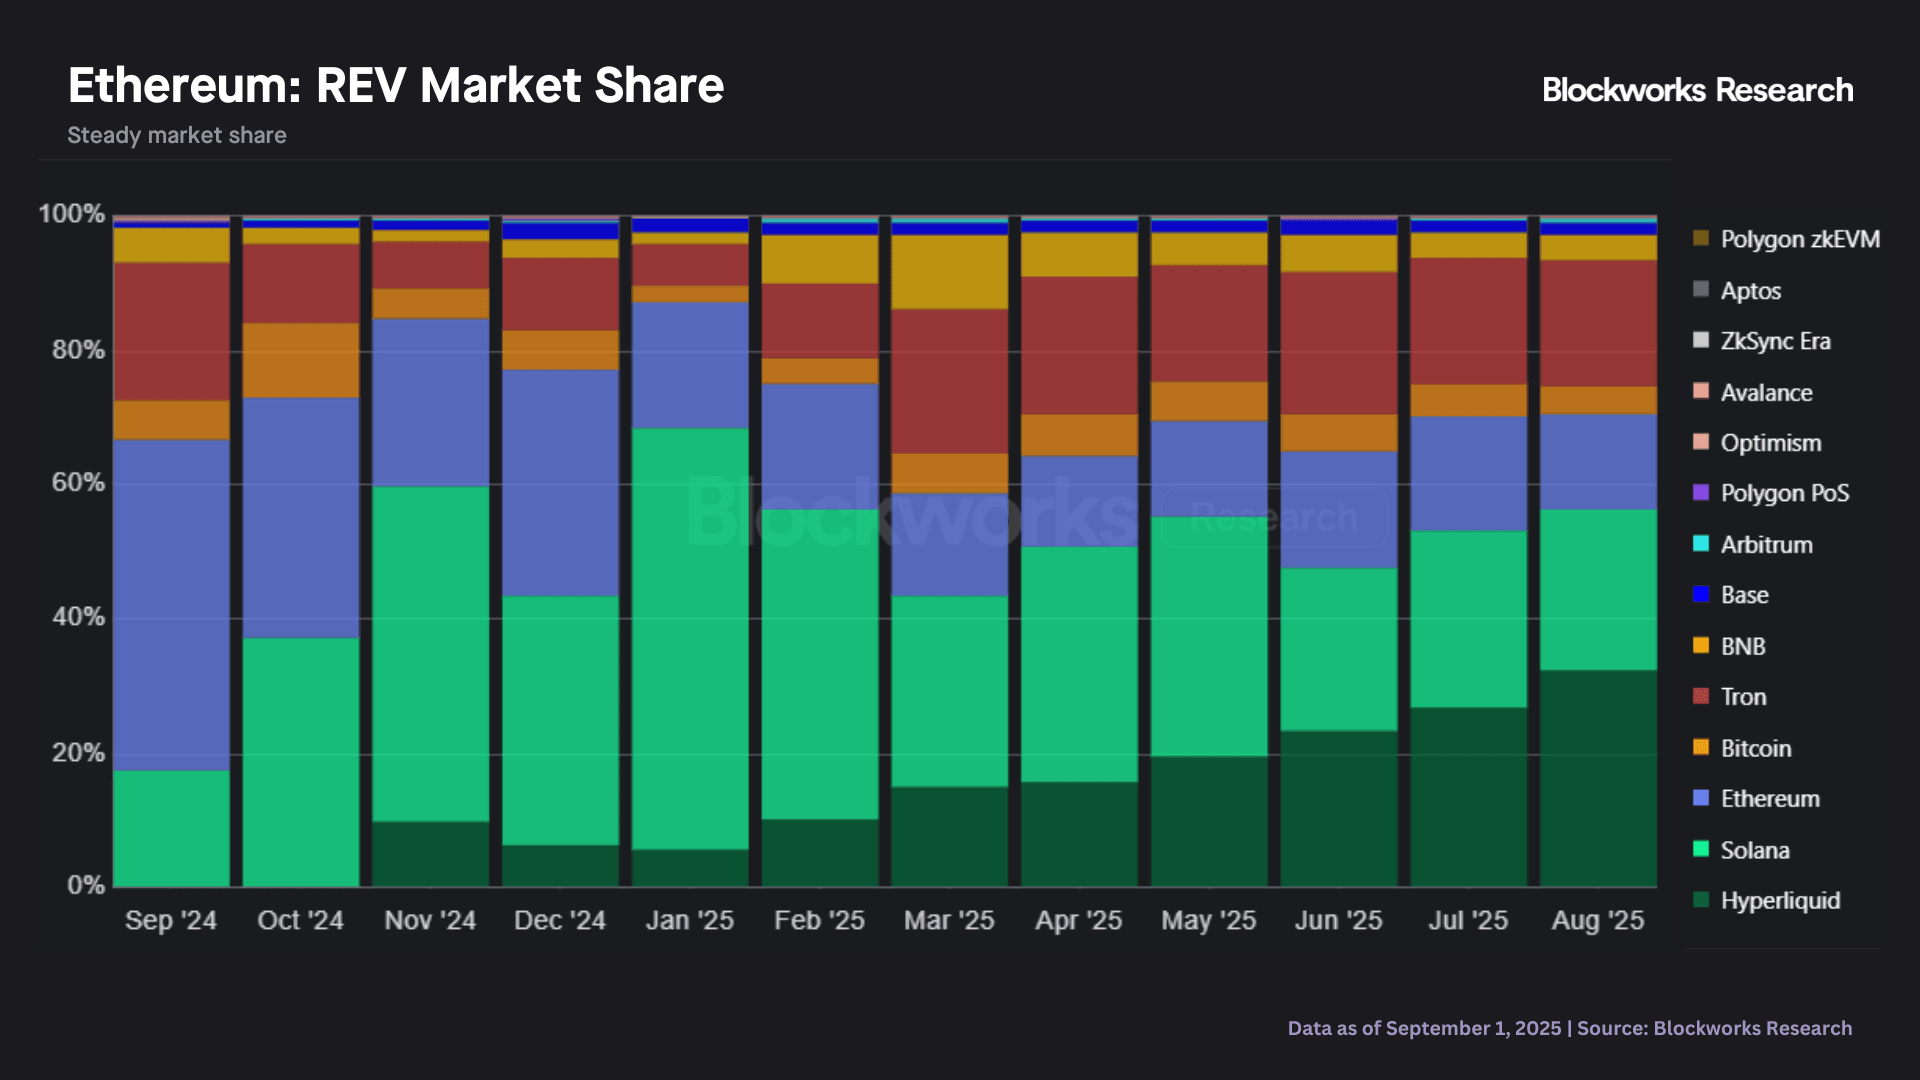
Despite the ~19% price increase, Ethereum’s Real Economic Value (REV) fell ~16% to $46.5M (vs. $55M in July). Even so, ETH’s share of industry REV was roughly flat (~15% in July vs ~14% in August). In August, three chains recorded higher REV shares: Hyperliquid (32%), Solana (24%), and Tron (19%). Below we show Ethereum’s monthly REV share over the last twelve months.
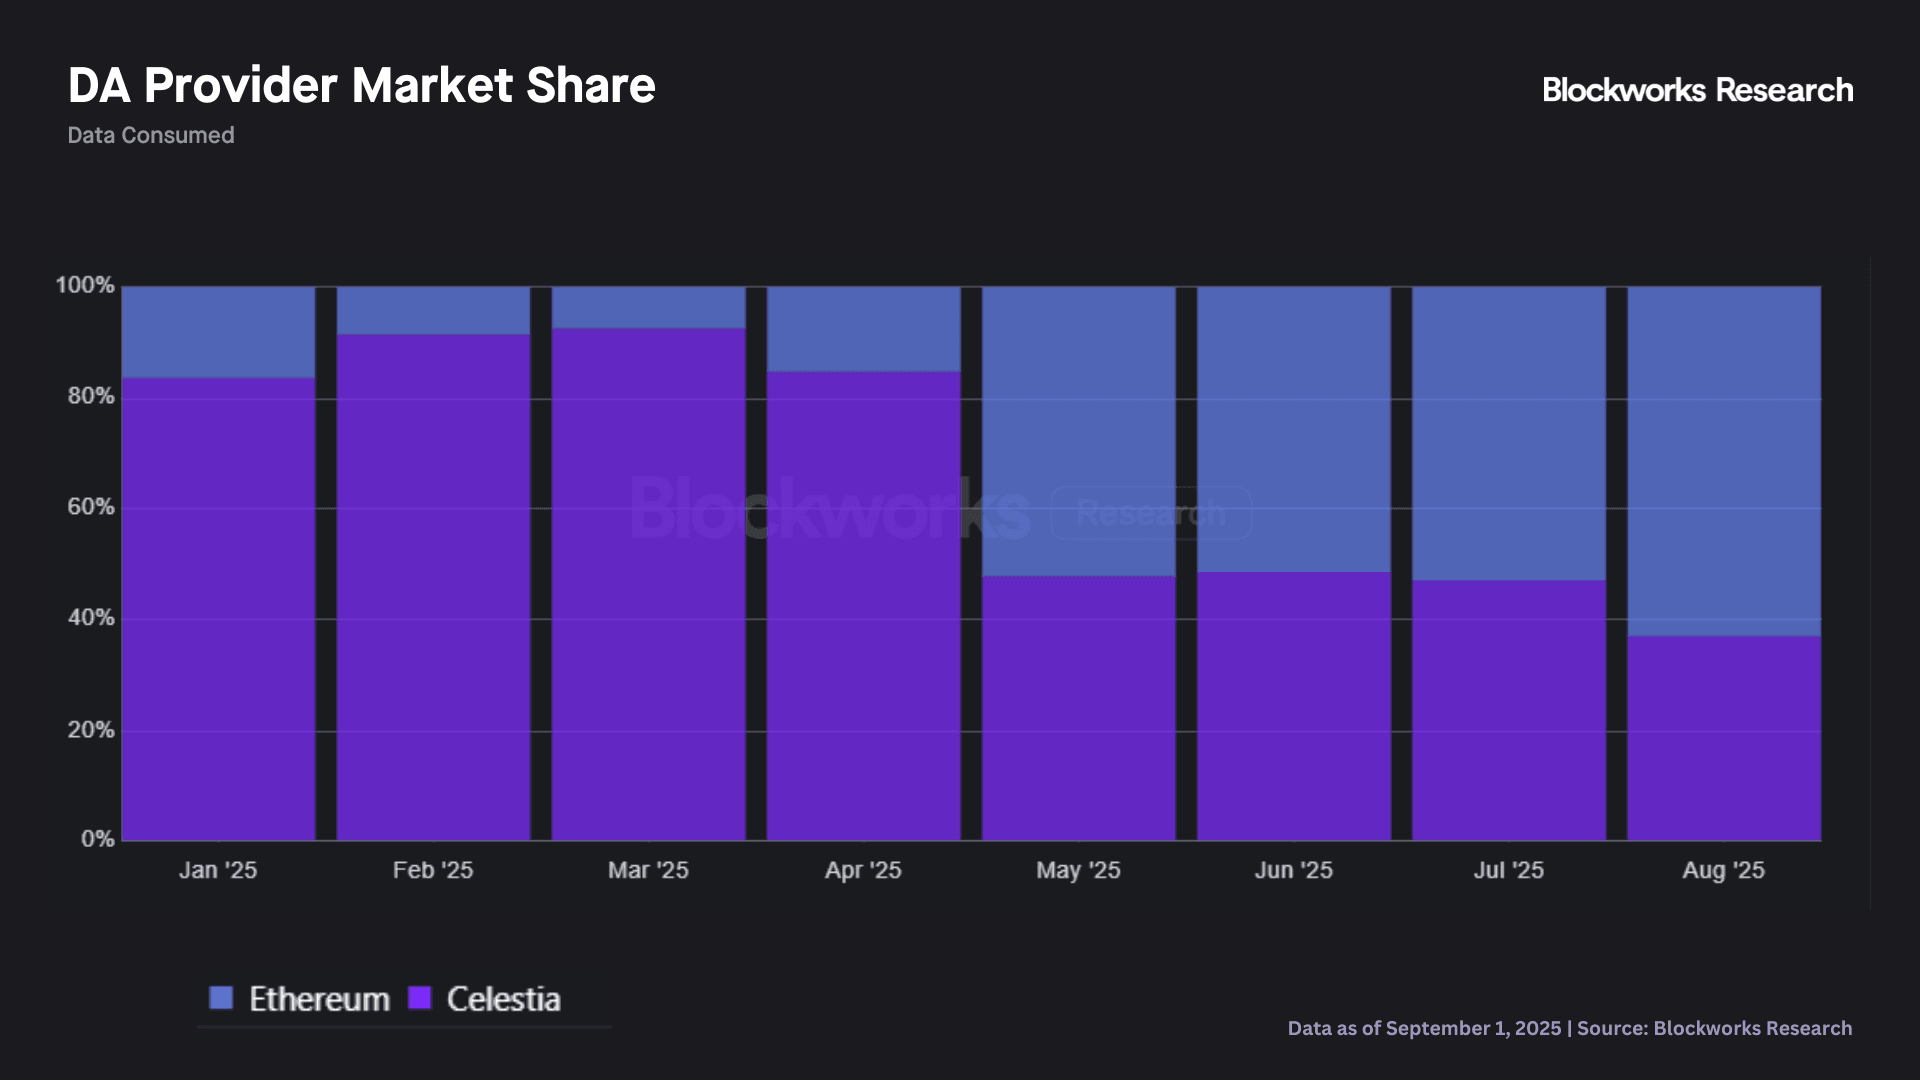
Ethereum also managed to grow its position in the data availability market, with its market share increasing from ~53% in July to 63% in August. The recent reclaim of DA market share since May has primarily been driven by a sharp 95% decline in data posted to Celestia by Eclipse. Below we show the DA providers’ market share over the last twelve months.

Marc covers Ethereum, Bitcoin and their L2s. Previously led Ethereum and DeFi research at CoinShares.