This research report was produced independently by Blockworks. No third party commissioned, funded, or had input on its content. All analysis and conclusions are the author(s)' own. All published Blockworks research is reviewed internally to ensure accuracy and objectivity. Researchers submit financial conflict of interest (FCOI) disclosures on a monthly basis, which are reviewed by appropriate internal parties. The author(s) of this report may hold positions in the assets discussed. This report is for informational purposes only and does not constitute investment advice. Readers should conduct their own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results.
EIP-8363: Tapered Issuance Burn


Key Takeaways
- EIP-8363 would progressively burn validator rewards as the staking ratio rises, reaching a 0% staking yield above a 50% staking ratio, limiting issuance-driven stake growth while preserving incentives for validators to perform their duties.
- Supporters argue that lower issuance would reduce unnecessary dilution, strengthen ETH’s monetary premium and maintain a large unstaked constituency capable of resisting validator capture.
- Critics contend that the modest inflation reduction may not justify the risks to staking products, institutional demand and the LST-based DeFi economy. Its equilibrium and prospects for adoption remain highly uncertain.
- Like SIMD-228, EIP-8363 is unlikely to pass because of its complexity and potential disruption to staking and DeFi. It would likely reduce staking without threatening security, although the eventual equilibrium is uncertain.
- Unlike SIMD-228, which addressed Solana’s materially high inflation, EIP-8363 is largely a solution in search of a problem. Ethereum’s resources would be better directed toward strengthening demand for ETH by expanding L1 capacity and reconsidering the blobspace and rent charged to L2s.
Technical Summary
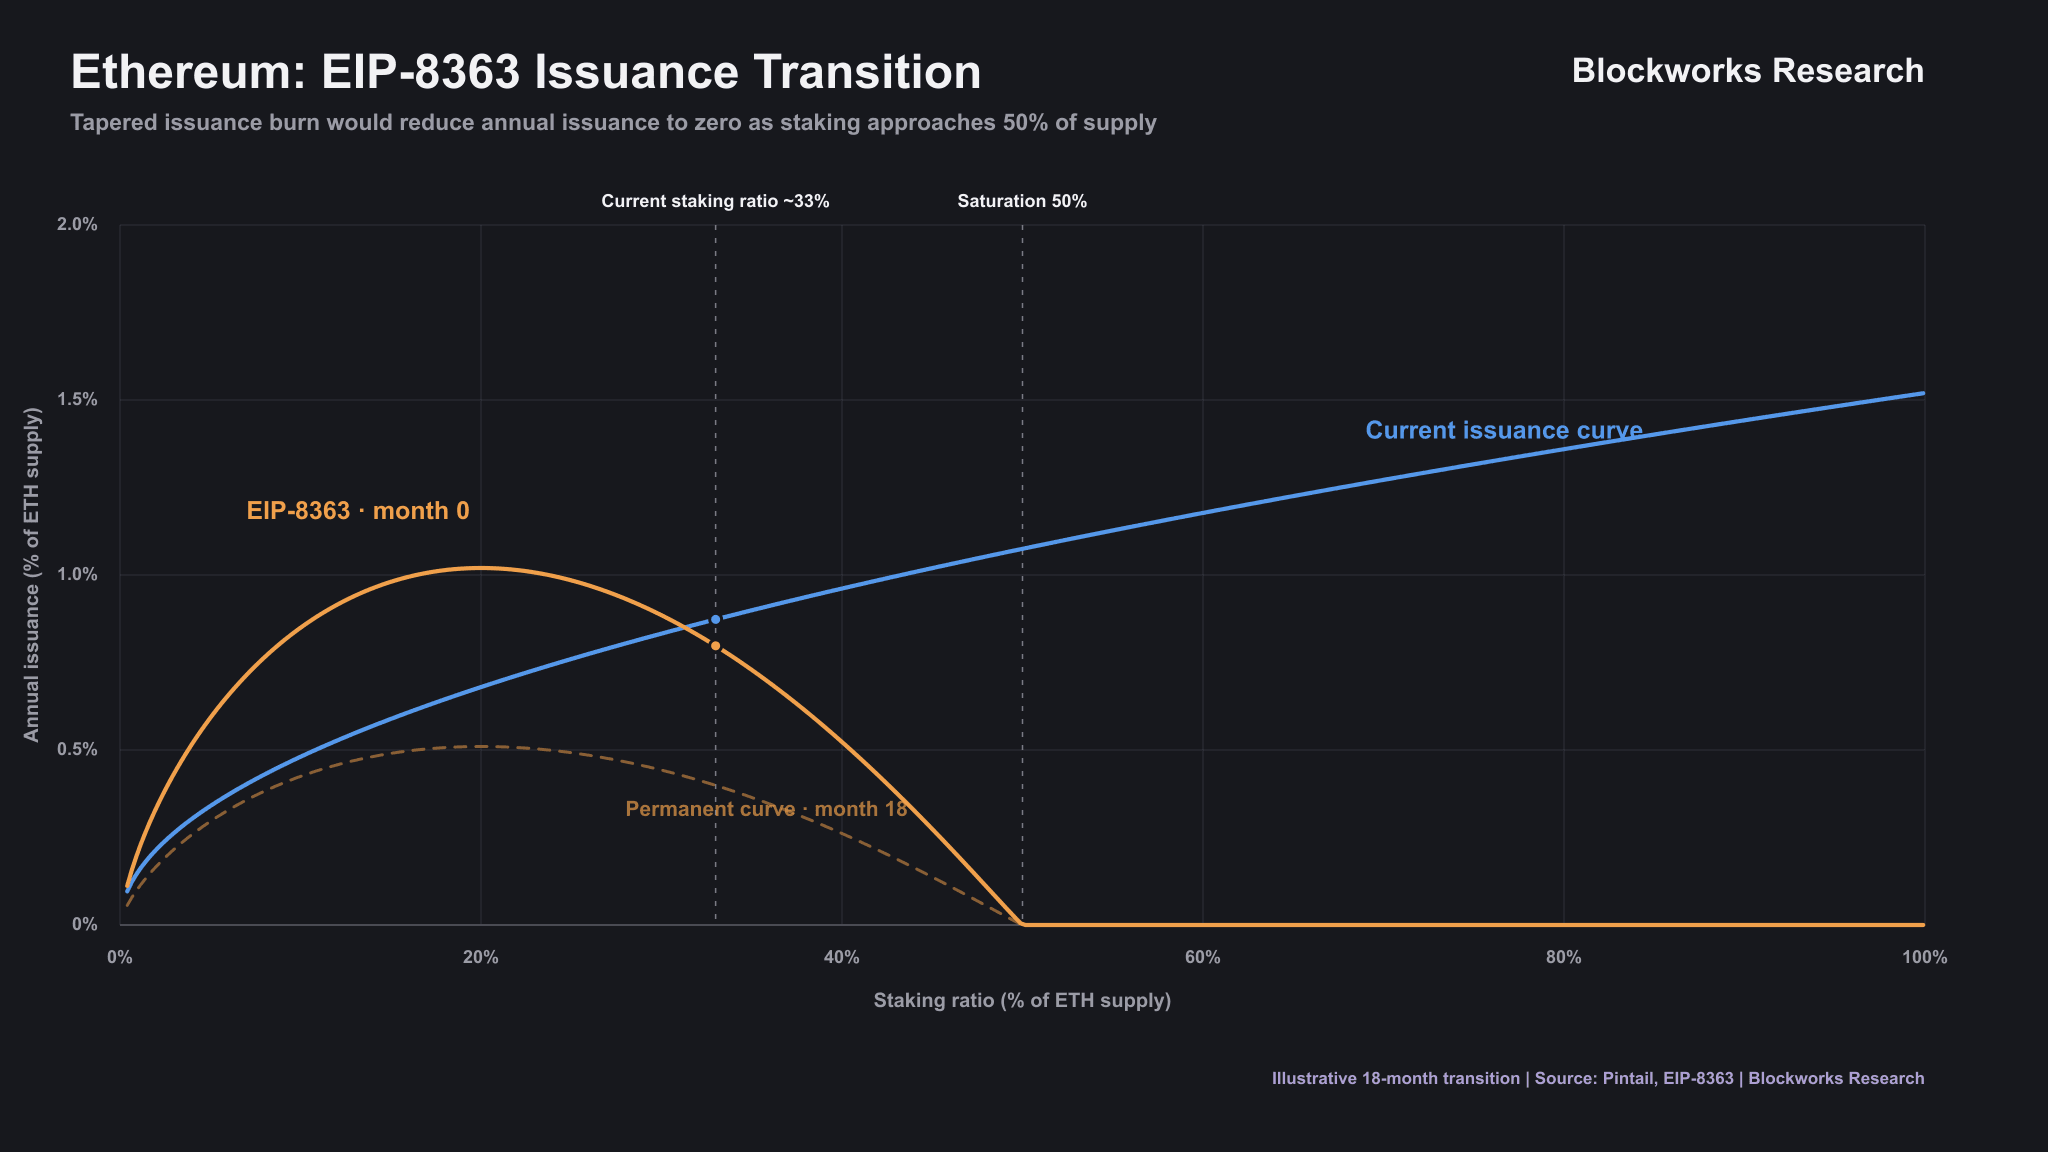
EIP-8363 is a new draft proposal, not an adopted Ethereum policy. It would keep the present consensus rewards and penalties, then burn a fraction of each validator’s rewards for an assigned duty. The fraction rises as more ETH is staked and reaches 100% burn at 60.25 million ETH (~50% of the supply). The proposal phases the reduction over 18 months. As of 7th August 2026, its pull request remains open. The proposal aims to stop consensus issuance from encouraging stake growth indefinitely while retaining strong incentives to perform validator duties. This report aims to provide a balanced take on the benefits and drawbacks of this proposal.
Benefits
1) Overpaying for Security
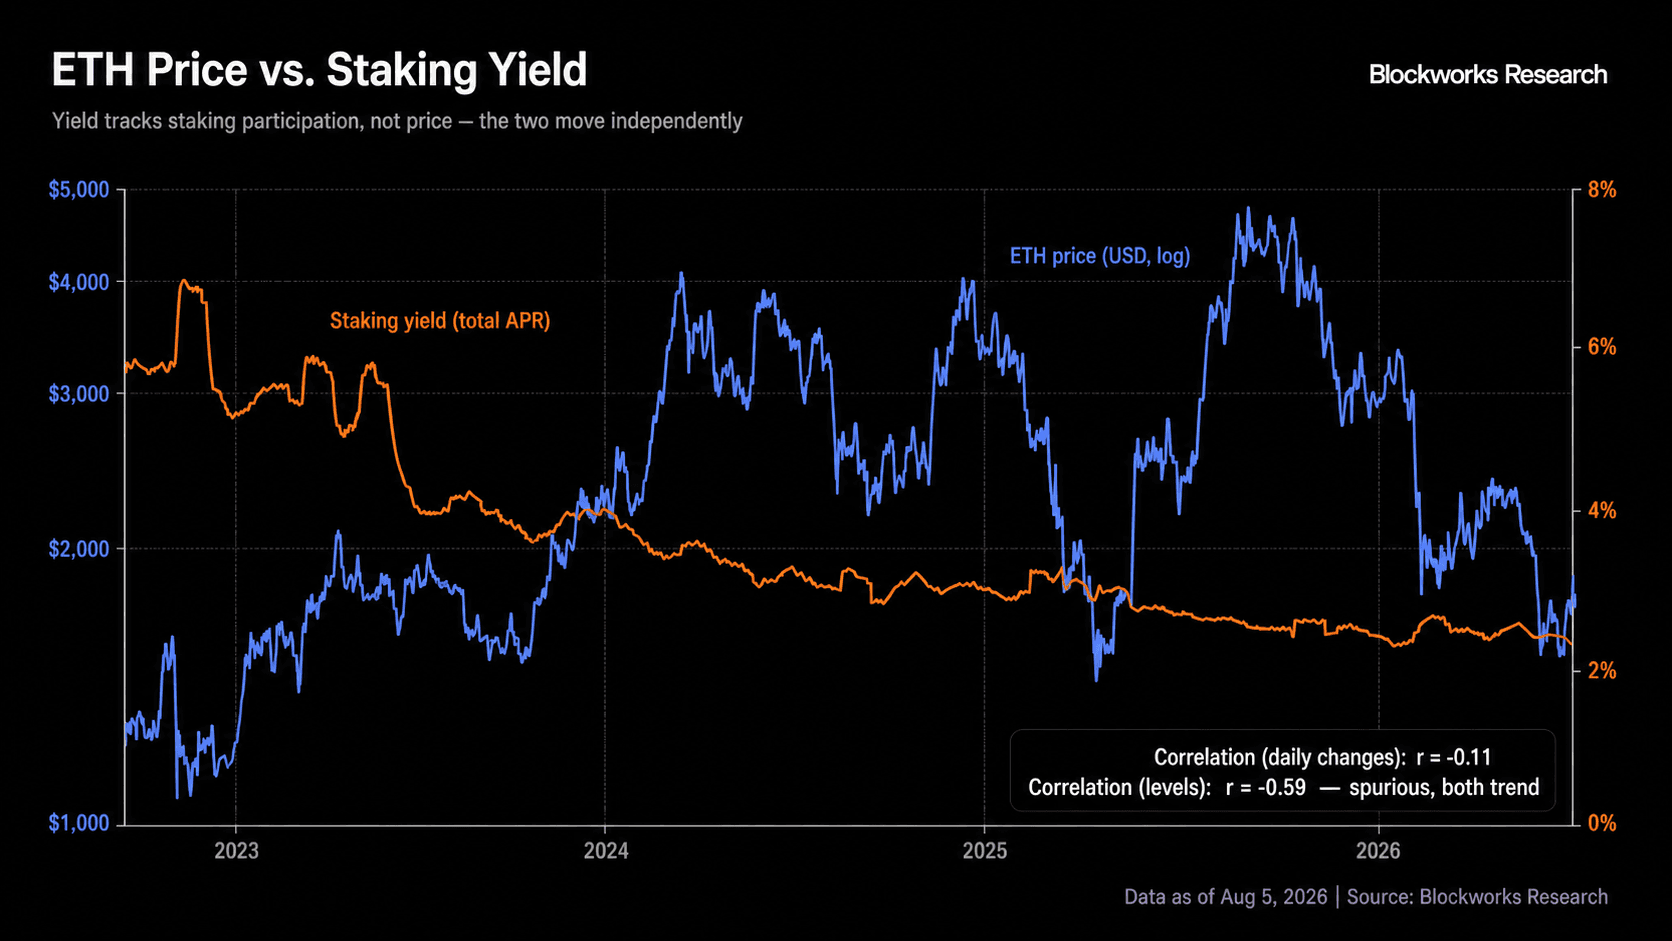
It places a ceiling on issuance-driven stake growth. The present curve has no off-switch and staking is becoming cheaper through better tooling, custody, liquid staking and ETPs. The marginal staker’s required premium continues to fall below the curve’s residual yield. This is evidenced by the fact that the staking ratio has only increased since the switch to PoS with no signs of stopping despite a falling yield (as shown below). Every successful chain from BTC to SOL reduces issuance over time as the need to bootstrap/incentivize diminishes. This is a smoother constraint than a validator cap, which could create scarce “staking licences”, and less manipulable than a rapidly adjusting target ratio.
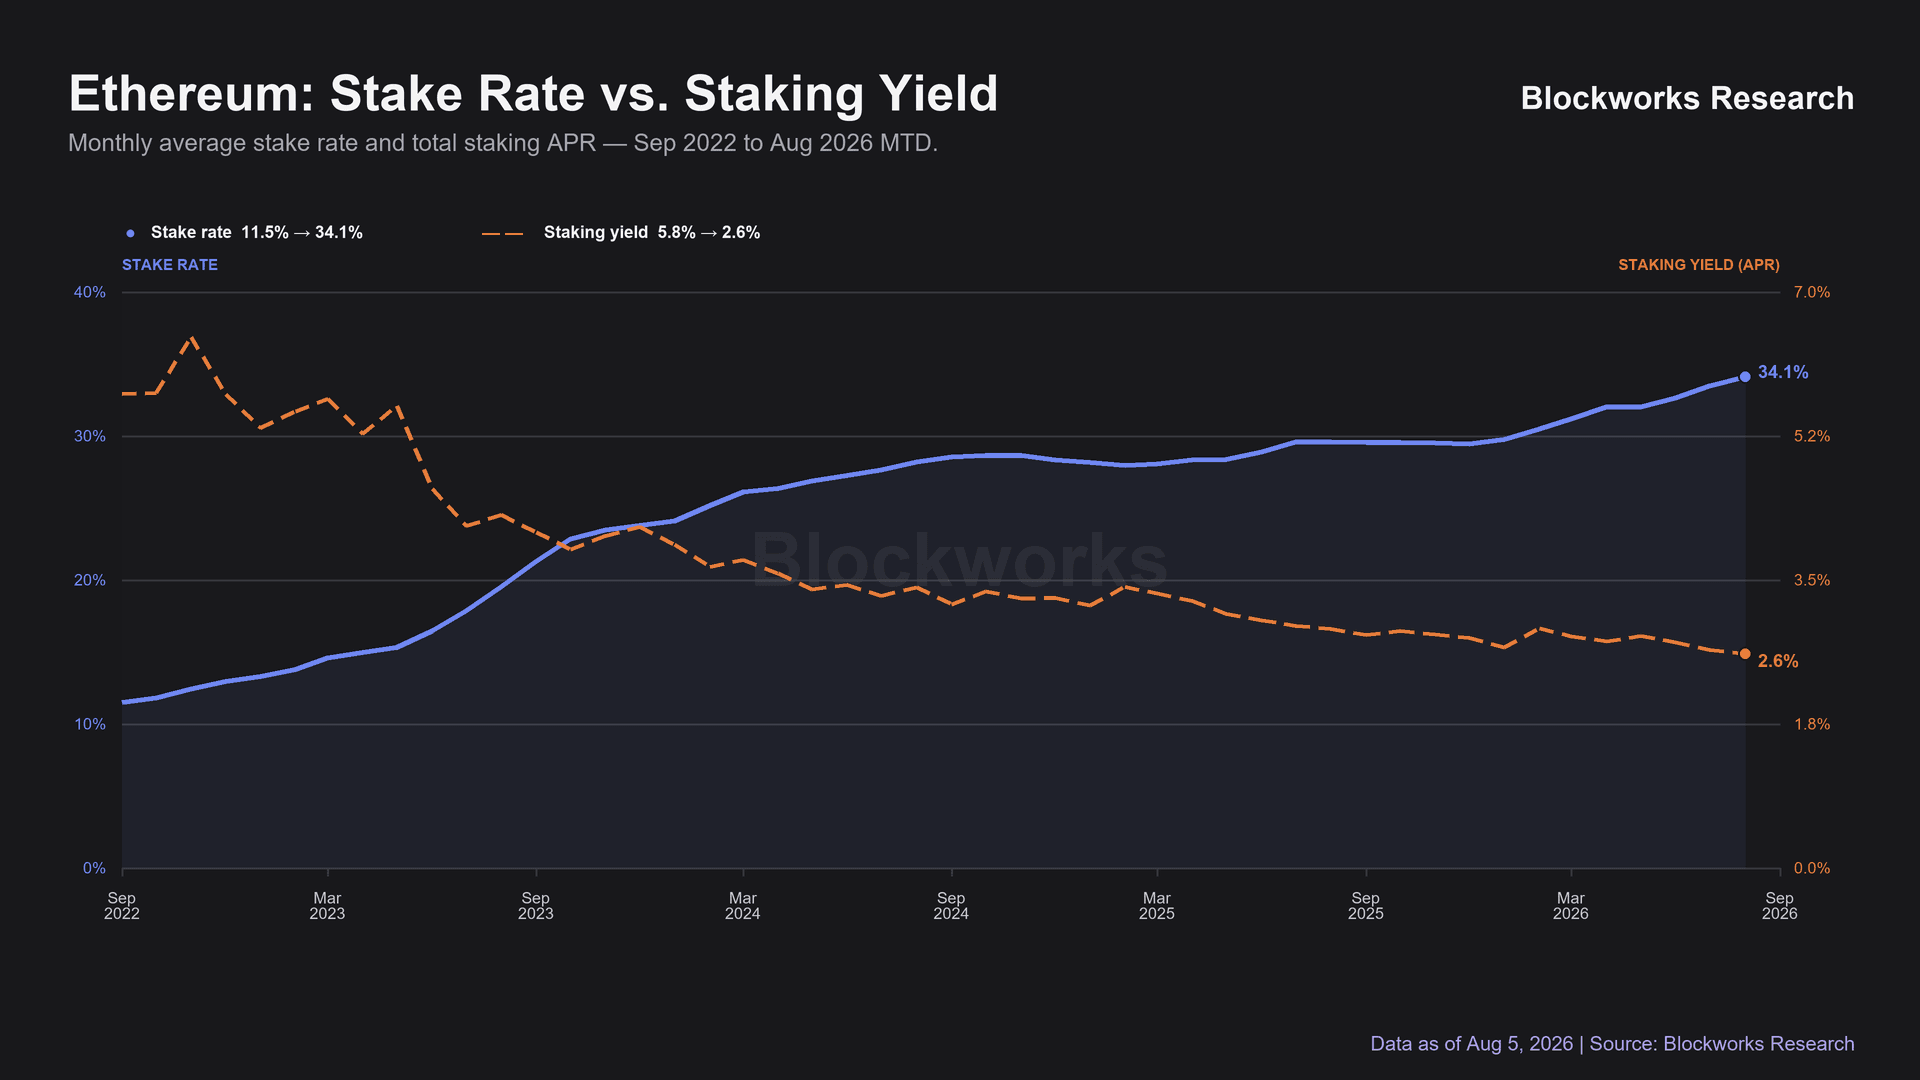
Counter: This is the same argument as SIMD-228. Ethereum issuance is already low (~0.85%/yr) and not widely considered a top 5 problem that the network has.
2) Monetary Premium
A lower issuance could strengthen ETH’s store-of-value properties and its broader monetary role. Deflationary economics can attract capital by making scarcity easier to understand and valuation less dependent on nominal staking yield. Institutional investors are familiar with real yield and buybacks and often respond positively to mechanisms that reduce an asset’s supply.
Greater demand for ETH as a SoV could support onchain activity, including DEX volumes, new users and new applications, which would generate additional fee burn and create a potentially sustainable flywheel between adoption, scarcity and valuation.
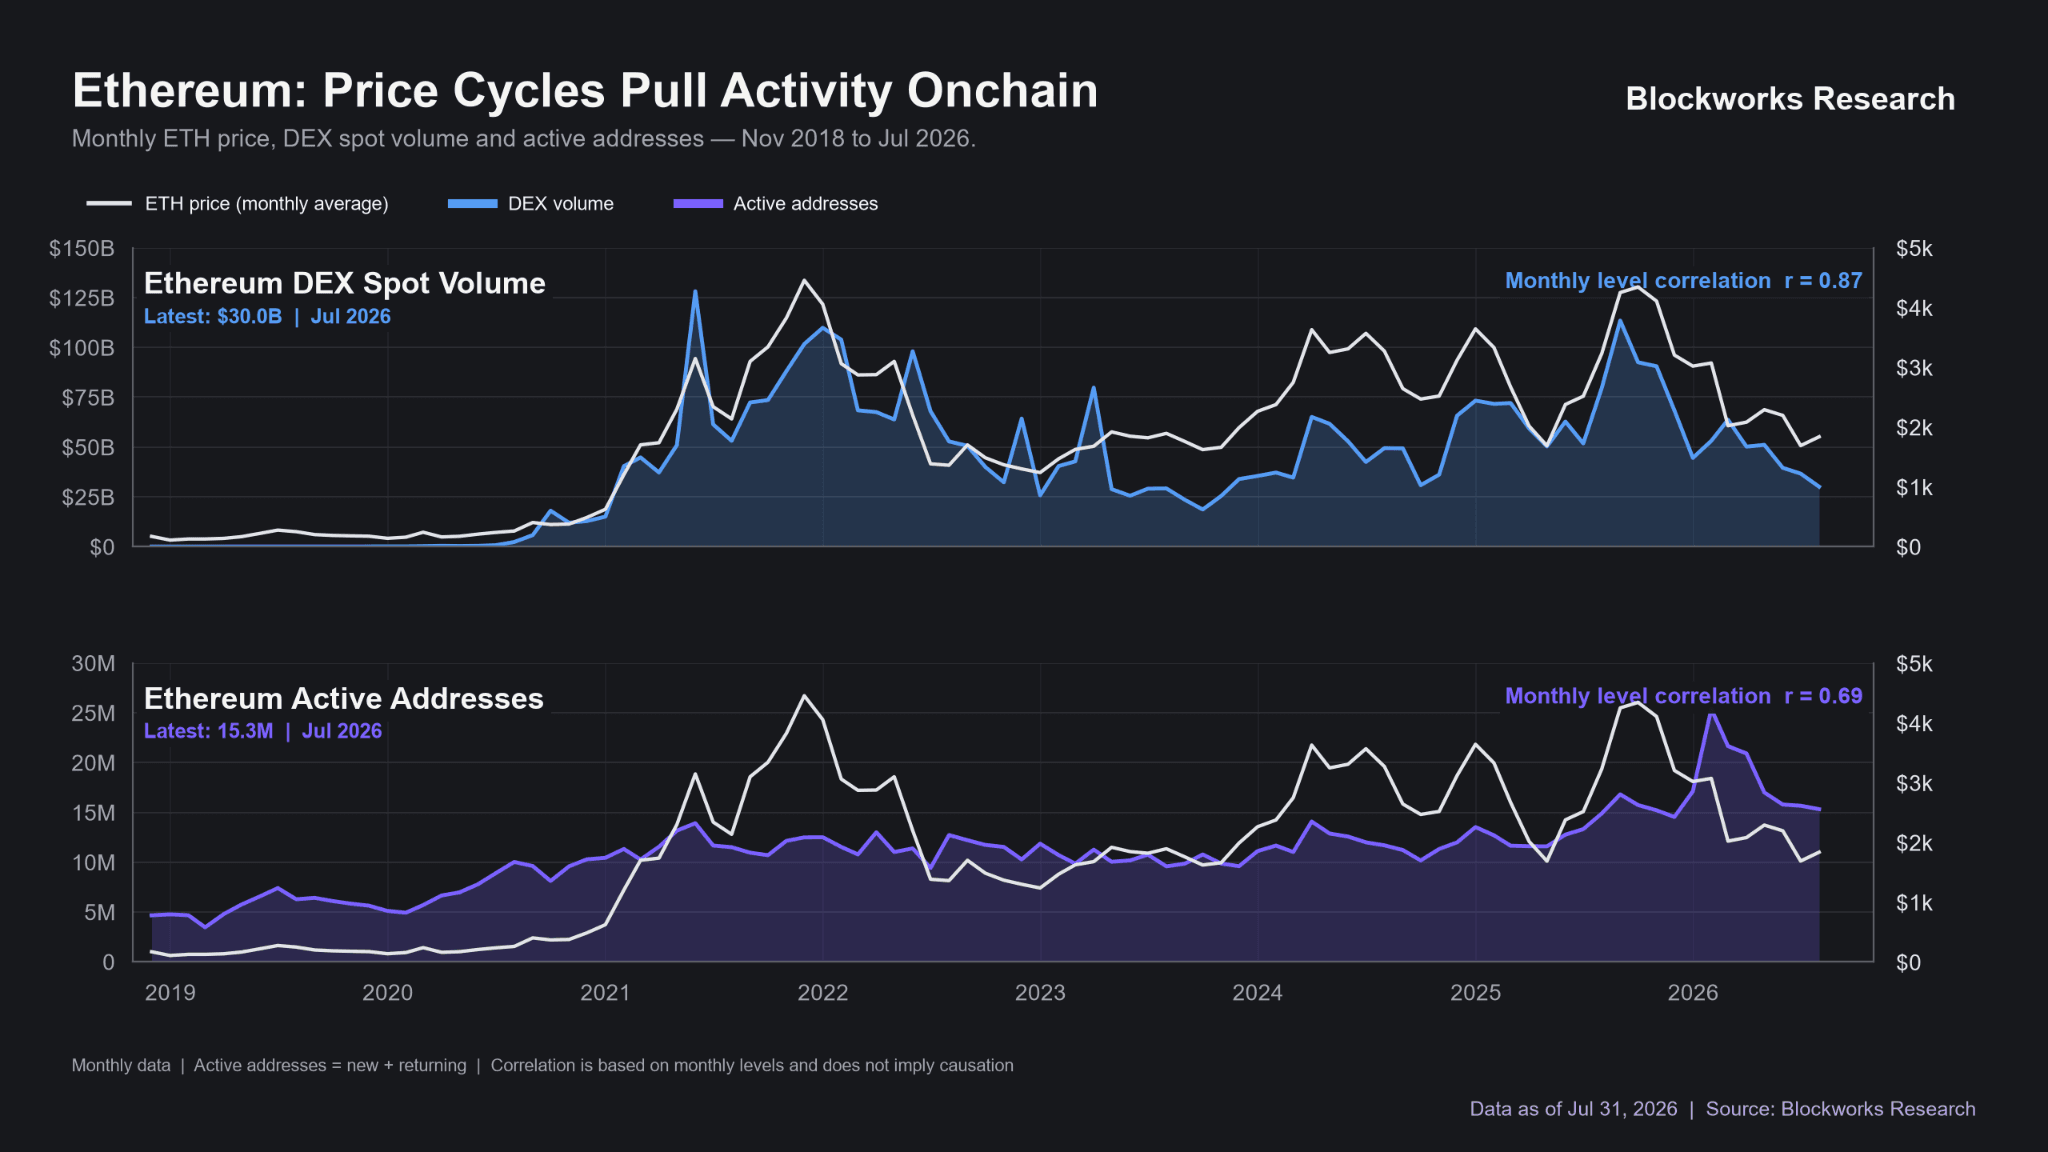
Counter: It is not guaranteed that a supply change to deflationary economics would drive material demand.
3) Moneyness
EIP-8363 could protect ETH’s monetary role by reducing the dilution penalty that encourages holders to replace native ETH with yield-bearing LSTs. When these tokens become collateral or settlement assets, applications inherit their issuer’s smart-contract, governance and counterparty risks. Lower issuance would make unstaked ETH more competitive, helping preserve a neutral, permissionless asset at the base of Ethereum’s economy.
Counter: If ETH is treated as base money, LSTs resemble a broader monetary layer: claims backed by staked ETH that add yield, liquidity and collateral utility. Products like money market accounts (M2 money) actually enhance the base currency (M1 money).
4) Capture Resistance
Ethereum’s ultimate defence against a censoring validator cartel is social slashing. Users, developers and infrastructure providers coordinate around a fork that removes the cartel’s stake. If most ETH is staked through the affected exchanges, custodians or LSTs, the economic majority would bear the loss and may instead demand a bailout, making a dominant provider “too big to fail.” EIP-8363 therefore treats 50% as an off-switch rather than a staking target. By ending the issuance incentive before a majority of ETH is staked, it aims to preserve an independent economic constituency capable of holding validators accountable.
Counter: That threat is credible only if a sufficiently large share of ETH holders remains independent of the validator system and is willing to support the fork.
5) Monetary Easing
Ethereum’s staking yield can be viewed (with some qualifications) as an onchain policy rate. It establishes a hurdle return against which other uses of capital are judged. Reducing issuance lowers this hurdle rate and may encourage capital to move from passive staking into DEX liquidity, lending markets, application tokens and new ventures.
Counter: Stakers may respond by holding or selling ETH rather than supplying it to riskier DeFi markets. Lower rewards could also reduce the value and use of LSTs, shrinking collateral, lending supply, leverage and onchain liquidity.
Drawbacks
1) No Real Yield to Compensate
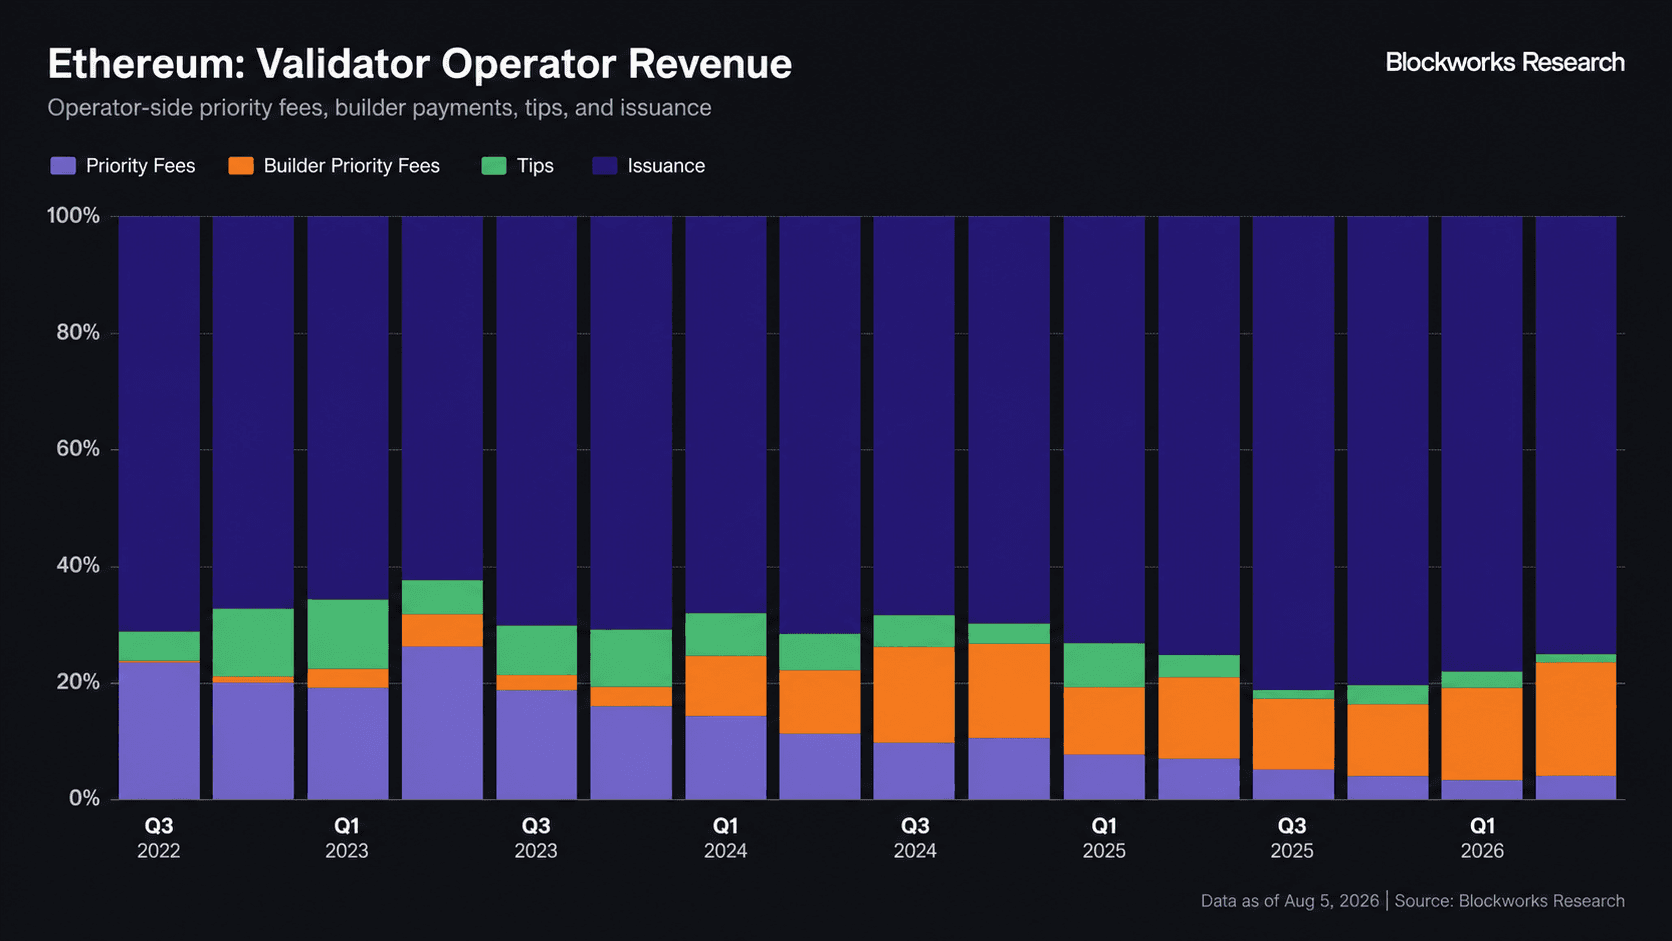
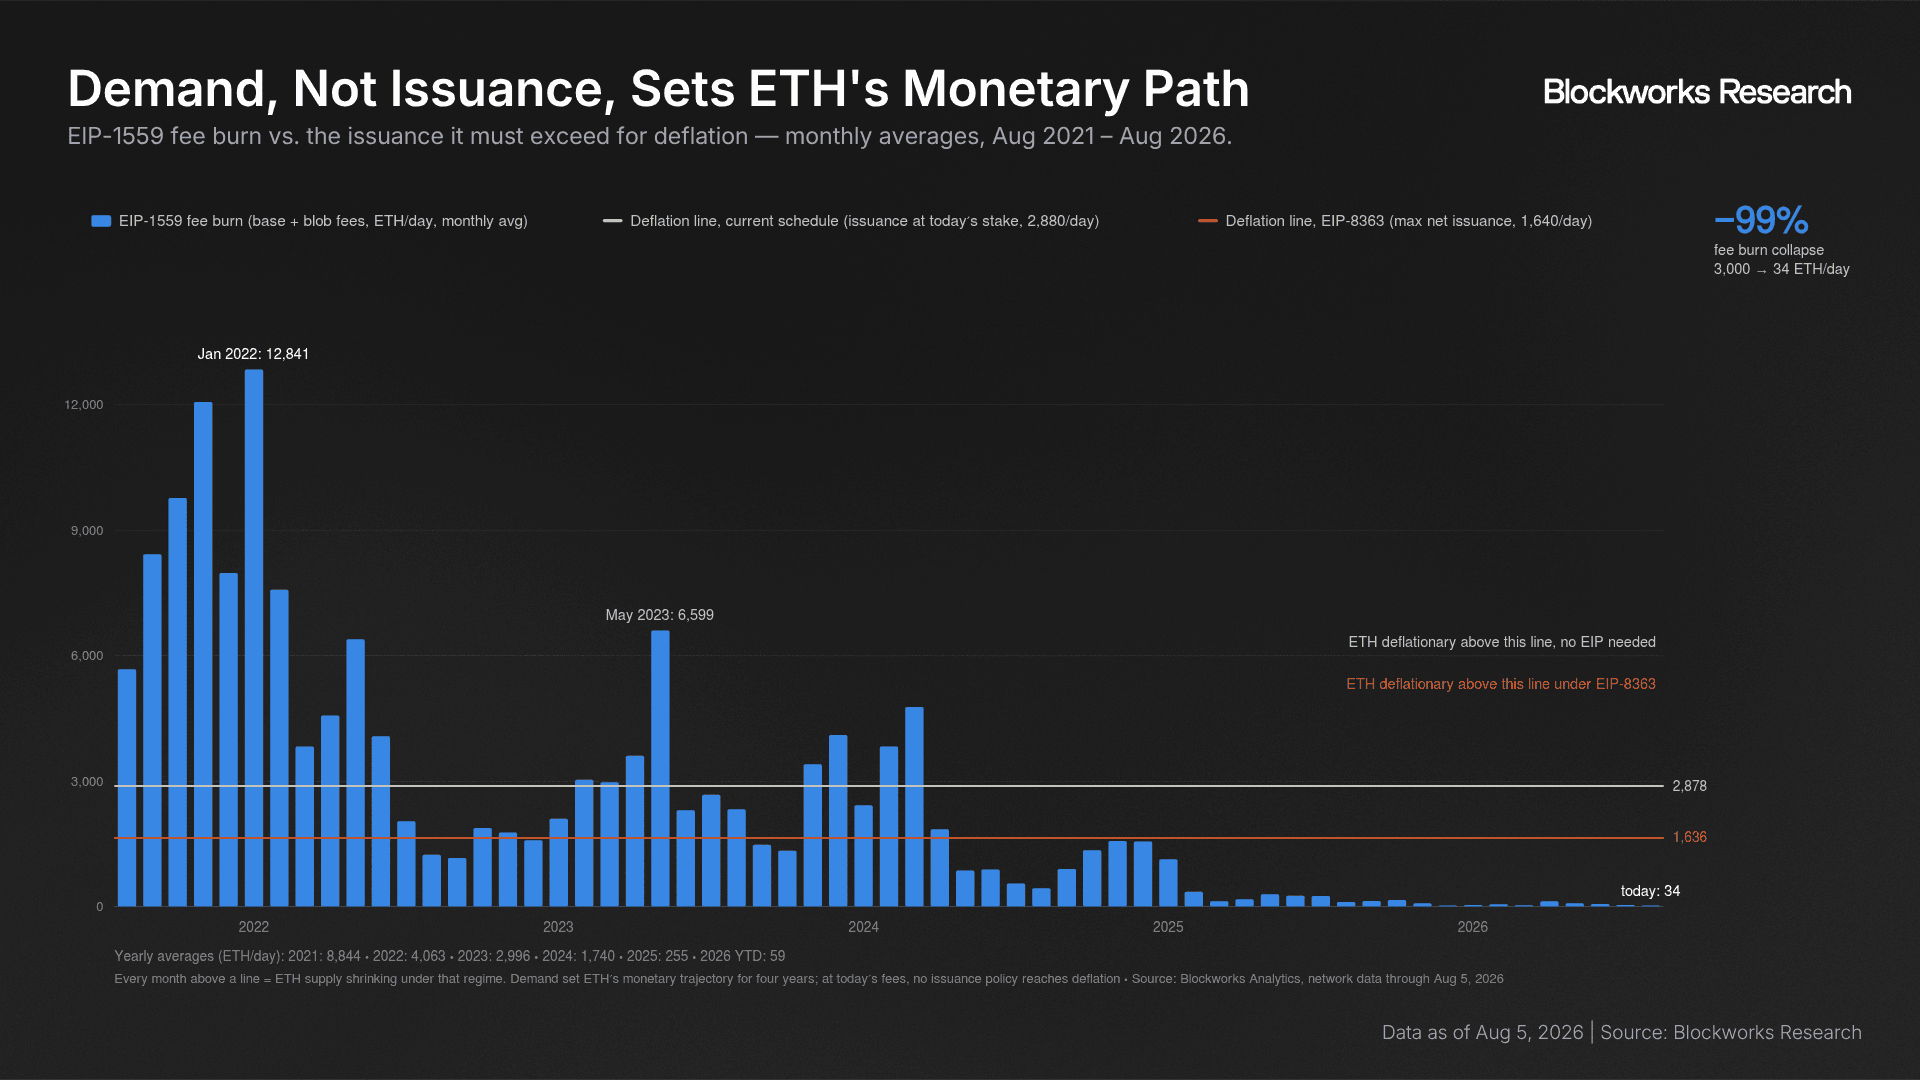
Ethereum's fee revenue today is insignificant (the burn collapsed from 3,000 ETH/day in 2023 to 34/day today), so this kills yield with no demand to compensate. Issuance now supplies 70-80% of validator revenue. The proposal focuses on the supply side when demand is the real problem: the rising staking ratio is a symptom of activity leaving L1. Focus should instead be on increasing L1 capacity, charging more to L2s, etc. Restoring 2024-level fee burn (~1,740 ETH/day) would make ETH deflationary at any staking ratio without touching yields.
Counter: Fee burn and issuance address different problems. The proposal does not prevent Ethereum from pursuing greater demand and capacity. It would not hinder increasing gas limits nor decreasing block times (both of which are still on the roadmap).
2) Forced Deleveraging of the LST Looping Trade
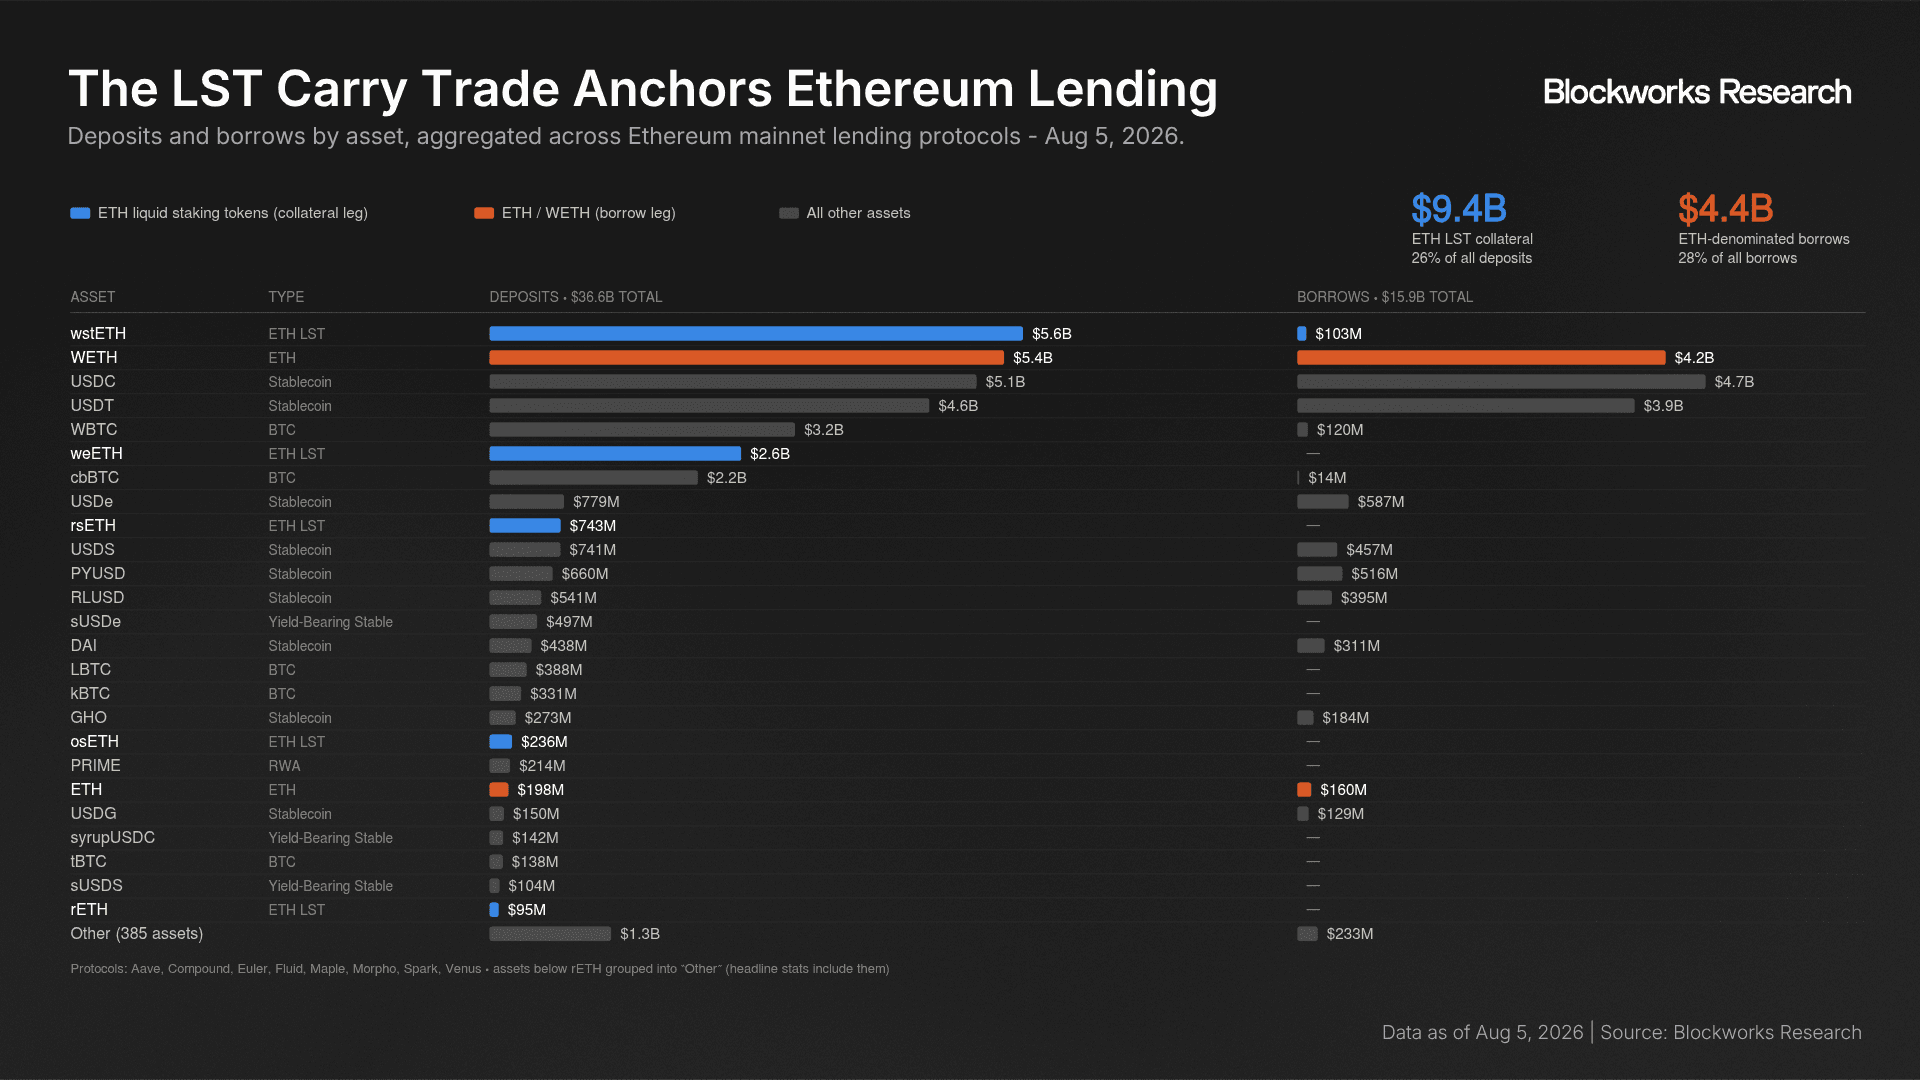
The LST loop is one of the largest and most popular strategies in DeFi: ETH LSTs account for 26% of deposits and ETH-denominated loans account for 28% of the active loan base across mainnet lending protocols.
Outside of stablecoin issuance, lending remains the only onchain financial sector for which Ethereum holds the majority market share, standing at 62%. Cutting yield to ~1.2%, or even lower should the staking ratio grow, risks killing the carry behind $18B in Lido and $4.4B of outstanding ETH-denominated loans across Aave, Spark, and Morpho, with over 90% of it borrowed against LST collateral. This proposal would likely lower the quantity and yields associated with ETH and LST utilization in DeFi, kneecapping a core economic driver of the only major apps still on Ethereum mainnet.
Counter: If enacted, the proposal would phase the burn over 18 months, allowing ample time for the onchain market to adjust. In addition, should the staking ratio fall as a result of the proposal, the nominal return on staking would not fall to the 1.2% level projected, and could still offer positive carry on loops.
3) ETP / Institutional Argument
Staked ETH ETPs and treasury products are sold on nominal yield, and issuers monetize via a take rate on it, which is why staking yield effectively functions as distribution spend. These players need yield that is both high enough and predictable; this proposal cuts it in half now and makes its future path a function of an unknowable staking equilibrium.
Counter: There is no relationship between ETH’s yield and its price (demand for ETH). ETP issuers can always add a management fee (as is standard practice).
Conclusion
EIP-8363 seeks to address valid concerns regarding stake centralization, the lack of an “off switch” on issuance, and capture-resistance. Judged against this purpose, the proposal is sound. However, the impact addresses nominal yield, when real yield from the demand side remains the core problem ETH faces. Similar to SIMD-228, EIP-8363 has a low probability of implementation. This is due to its complexity, pushback from the community (including LST issuers, lending protocols, and treasury companies) and the risks it poses to established staking and DeFi markets. If adopted, it would likely reduce the staking ratio in the short term, but not nearly enough to have a negative impact on security. However, the eventual equilibrium between participation, yield and issuance is uncertain, and markets do not enjoy uncertainty. At large, the benefits of this proposal are finite while the downside consequences may be large and unpredictable.
Marc covers Ethereum, Bitcoin and their L2s. Previously led Ethereum and DeFi research at CoinShares.
Carlos leads coverage on Solana and spends his time on DeFi applications. Previously held a research role at 21Shares.
Luke leads coverage on money markets, stablecoins, real world assets, interoperability, and intents-based infrastructure. Previously worked in market research and product at a startup incubator.