This report was commissioned by DoubleZero. By providing this disclosure, we aim to ensure that the research reported in this document is conducted with objectivity and transparency. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Blockworks. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Blockworks maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) submit financial conflict of interest (FCOI) disclosures on a monthly basis that are reviewed by appropriate internal parties and may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
DoubleZero: The Physical Layer of New Finance

Key Takeaways
- Distributed systems hit a physical ceiling before they hit software limitations: The public internet adds latency and jitter that cap throughput and skew fairness toward whoever sits closest to the data.
- DoubleZero is a purpose-built physical network layer that lifts that ceiling for any system willing to connect: capacity has reached ~10 terabits per second (Tbps) across a mesh of independently contributed private fiber, coordinated onchain and neutral by design.
- DoubleZero Edge turns the network's latency advantage into usage-based revenue: Edge is venue-agnostic market data transport, now carrying four venues (Solana, Kalshi, Hyperliquid, Phoenix) and selling seats to every feed the network delivers, priced in USDC per seat/epoch and funded from onchain escrow.
- Neutrality is enforced at the protocol layer: multicast delivers one feed to every subscriber in a single hop independent of stake weight or queue position, and RFC 18 lets the network classify links onchain and route latency-sensitive multicast separately from bandwidth-heavy unicast, so a tenant with a different traffic profile onboards without crowding existing feeds.
- Edge is the largest of several monetization paths built on the same backbone: the same fiber carries dedicated multicast groups that any organization can provision to distribute its own data, internally or out to its own customers, and wholesale terms let authorized resellers redistribute DoubleZero Edge's feeds downstream at better rates than the standard seat price. Geolocation verification is designed to add a 2Z-denominated line on the same footprint.
Introduction
Every distributed system inherits the physical limitations, or advantages, of the network it runs on. Physics-bound systems can optimize their execution layers, compress their state, and parallelize their runtime, and still lose time they cannot recover to the speed of light through fiber and the routing decisions of carriers that are not optimized for consensus. The public internet routes traffic by least cost, not best performance. For a system where the order and timing of messages determine who earns and who loses, that is a structural tax and a measurable networking design flaw for traders.
Four terms recur throughout this report and are worth defining now:
- Latency is the time a message takes to travel from sender to receiver.
- Jitter is the variance in that latency, the difference between a message that arrives in 30ms and the next that arrives in 80ms.
- Multicast is sending one message to many recipients at once rather than copying it separately for each, so every subscriber receives the same data on the same hop.
- Determinism, in a delivery context, is the property that every recipient sees the same state at the same instant, independent of who they are or where they sit in a queue.
The Performance Ceiling
Any system where the order and timing of messages determines economic outcome inherits the same constraint. A trading venue distributes its book only as fast as the slowest leg to each subscriber. A consensus system finalizes only as fast as messages propagate to enough of the validator set. Faster hardware and optimized software shrink the compute time around each message and do nothing about the time the message spends in transit. This is Amdahl's law applied to distributed systems: total speedup is bounded by the component left unoptimized, and for any system running over the public internet, that component is the network. That transit time is governed by distance and by path quality, and on the public internet both are adversarial to time-sensitive delivery.
Purpose-built physical network infrastructure is dedicated transport, fiber and the hardware at each end of it, configured for the latency and jitter profile of a specific class of applications’ needs, rather than the general-purpose, least-cost-optimized routing of the public internet. Today, this is typical for exchanges and high-frequency trading (HFT) firms, which run dedicated fiber lines and one-to-many feeds because execution quality is a function of the network, and the network is too important to rent from a carrier optimizing for video streaming.
Systems dependent on consensus inherit an acute version of the problem, and Solana is the clearest illustration. Blocks propagate through Turbine, a tree-based relay in which the leader sends shreds to the root node that fans them out layer by layer across the validator set, with position in the tree weighted by stake. Each hop adds queuing and replication delay, and the tree is geographically-blind, so a shred from a Frankfurt leader can route through New York before reaching a London validator, forcing two transatlantic crossings for what should be a local handoff, enabled only by latency-optimized network infrastructure. Larger validators sit higher in the tree and see blocks earlier due to a stake-weighted information asymmetry baked into the protocol.
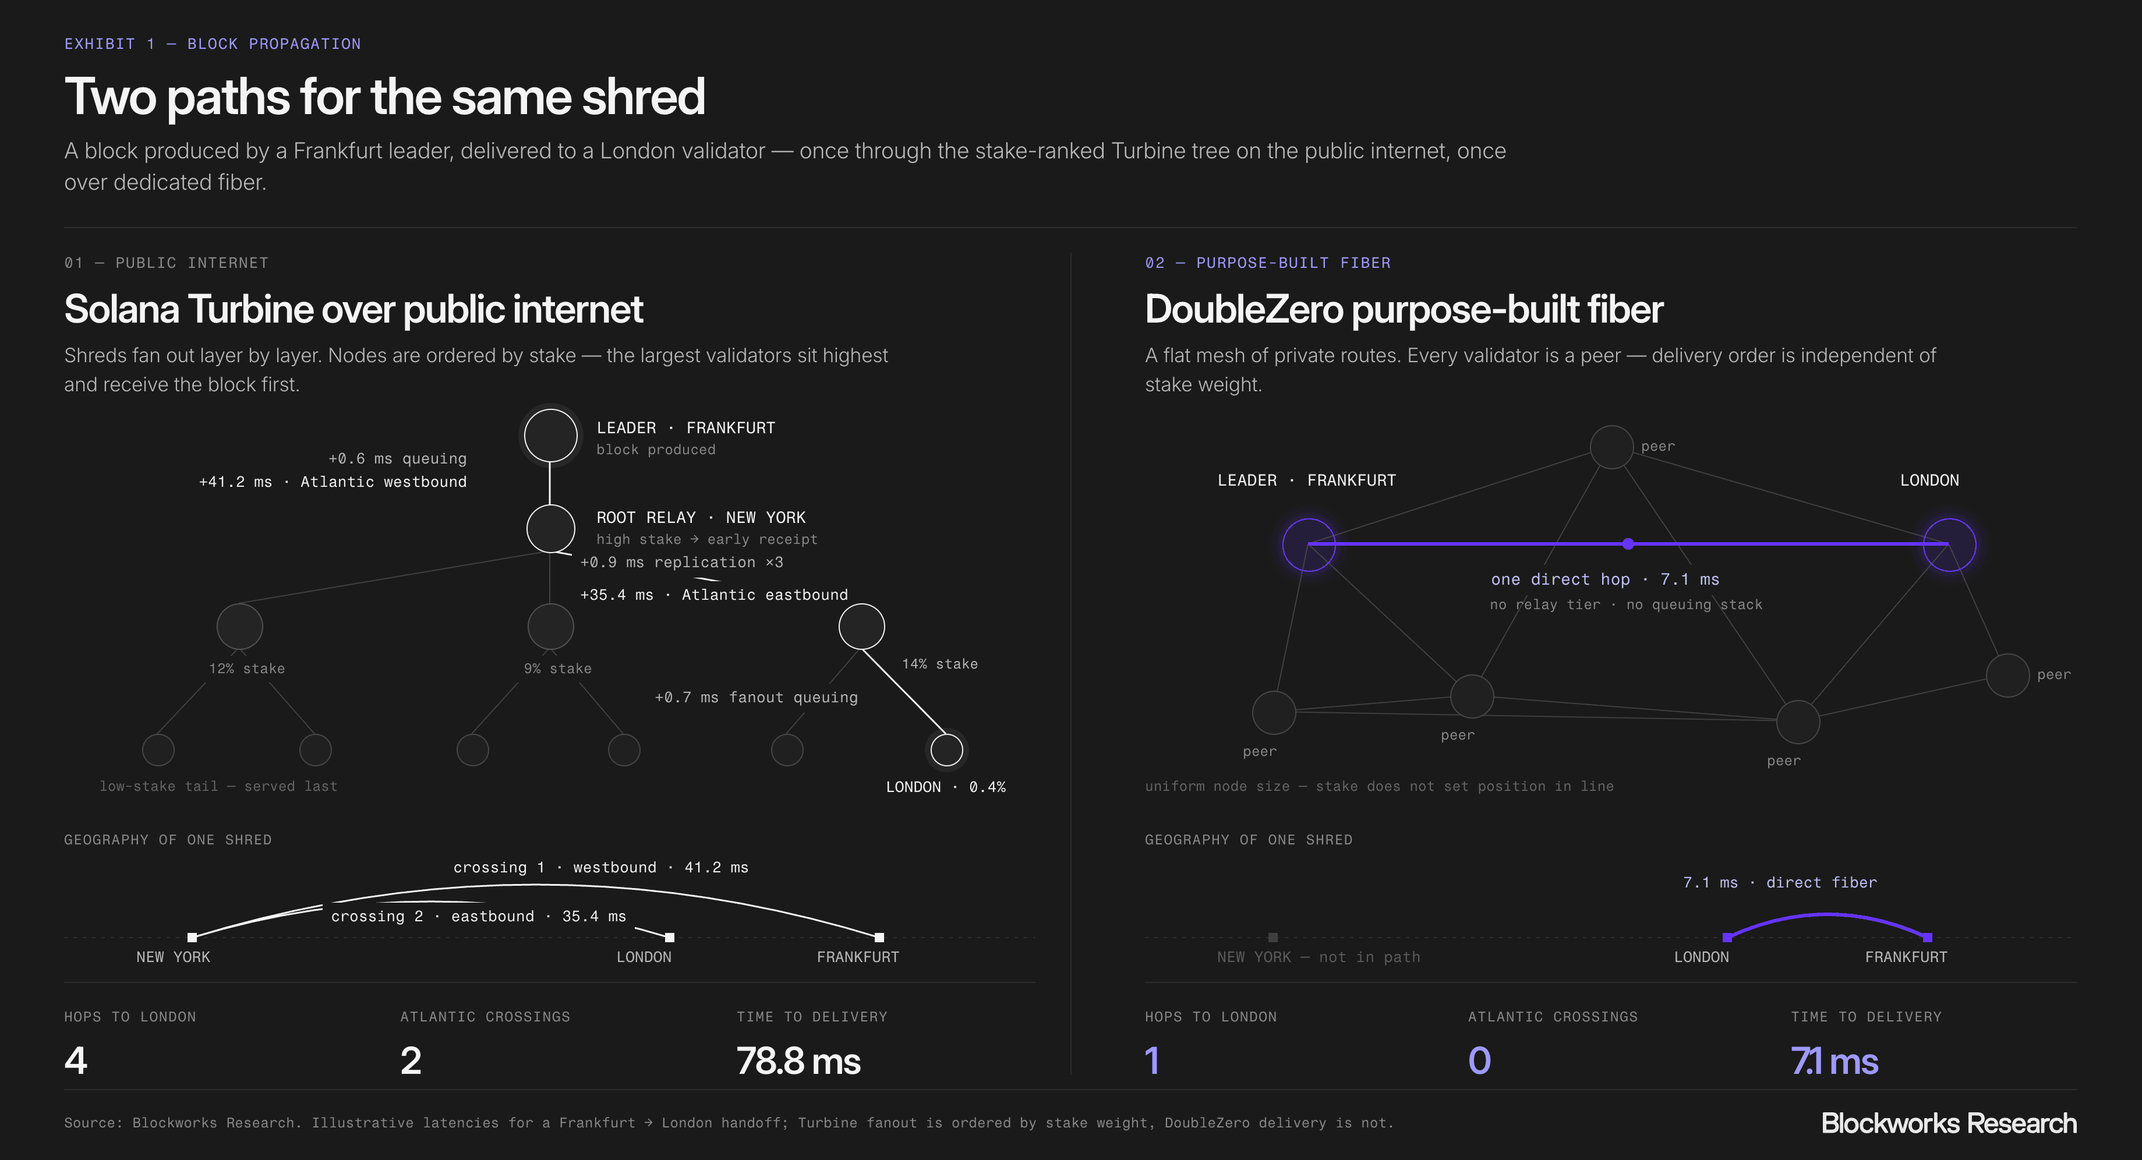
Any consensus system layered on the public internet pays a propagation tax it cannot tune for. The remedies the industry reached for first, centralized relays and mempools, trade one problem for another, cutting ingestion latency but adding a hop and broadcast transaction intent to potential front-runners. Stitching underutilized private fiber into a coherent, performance-optimized mesh is operationally difficult, capital-intensive at the contributor layer, and slow to replicate. The same difficulty that raises the barrier to building it is what makes the resulting network defensible.
The Physical Network Layer in Practice
DoubleZero is a neutral, high-performance transport layer that unifies independently contributed dedicated fiber links into a single global network, coordinated by smart contracts on its own blockchain-based ledger. In plain terms, independent operators lend their spare fiber, and DoubleZero combines it into one fast, dedicated path that traffic can travel instead of open public internet infrastructure. The architecture is two theoretical concentric “rings”, an outer ring designed to clean inbound traffic and an inner ring to carry it:
- The outer filter ring is the boundary layer designed to sit between the network and the public internet. Specialized hardware, field-programmable gate arrays (FPGAs, chips that can be wired to run one task at full hardware speed) deployed in DoubleZero Devices (DZDs), would inspect inbound traffic as fast as it arrives, defending against, for example, denial-of-service attacks before they reach a node. This is intended to offload work nodes otherwise do in software, freeing their compute for block production rather than spam filtering. This filtering layer is specified in the network design and is not yet fully active in production.
- The inner data-flow ring is the network of dedicated fiber links contributed by independent operators, where cleaned, validated traffic moves between nodes over the fastest available routes. The inner ring supports multicast, sending one message to many recipients at once rather than copying it separately for each, and prioritized routing, moving time-sensitive traffic ahead of bulk traffic. These are two capabilities the public internet does not natively offer any latency-sensitive distribution system, whether the payload is a block, an order book, or a model gradient.
Network operators with underutilized links contribute that capacity and earn 2Z for links that measurably improve overall network performance. Rewards are set by a Shapley-value model, a method from game theory that pays each link for its marginal contribution, meaning how much it improves performance over an alternative public-internet path, rather than for raw traffic carried. DoubleZero frames the design as resistant to gaming and incumbency. The current contributor set spans professional operators including Infinite Fiber, Jump Crypto, Galaxy, Distributed Global Technologies, and Teraswitch, among others. Connectivity is stitched together at DoubleZero Exchange points (DZXs), which aggregate links within a geography, much as public internet exchanges do. Every operationally meaningful action, registering a contributor, requesting a route, granting user access, is a smart-contract transaction on the DoubleZero Ledger. Anyone can therefore inspect the network's physical footprint onchain, and software can act on it automatically.
Adoption is the Demand Signal
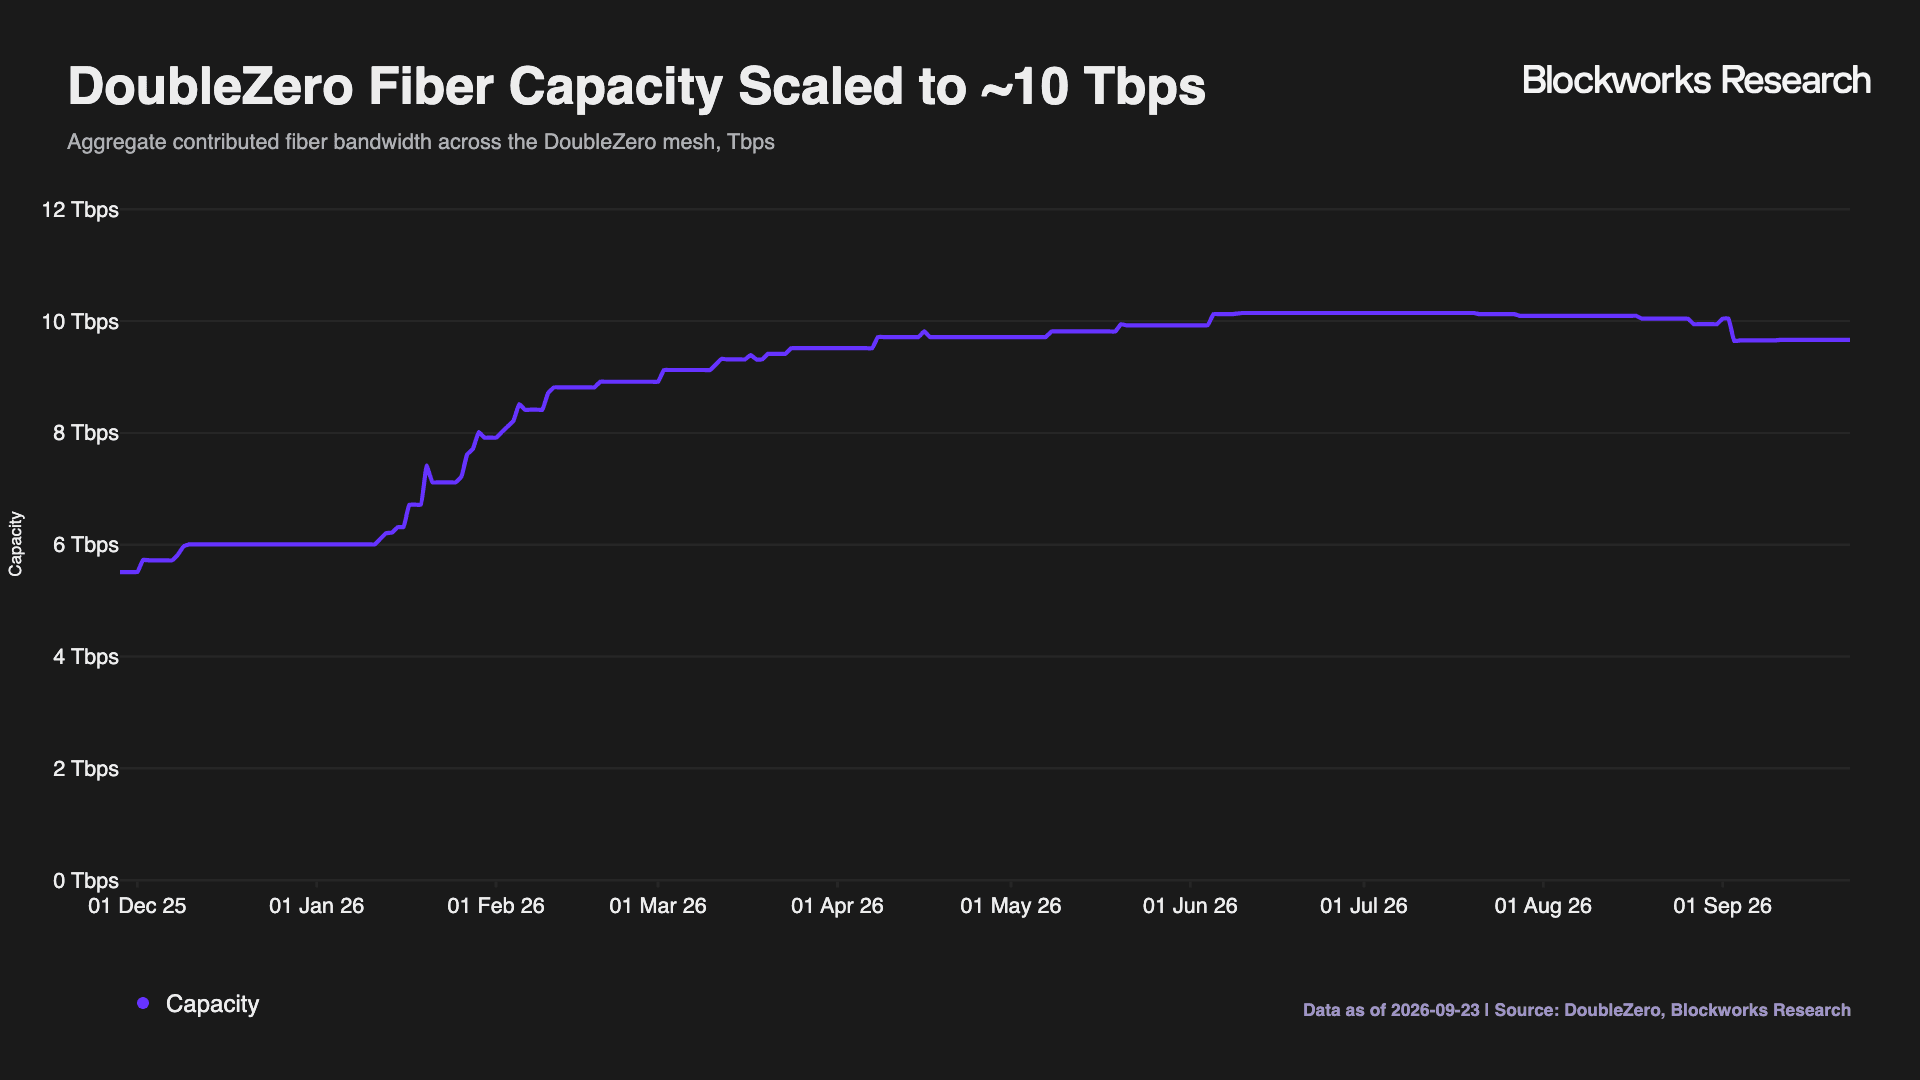
The test of a network like DoubleZero is whether the parties who would benefit most choose to connect. Aggregate network capacity stands at ~9.7 terabits per second (Tbps), up ~1.6x since January 2026, contributed by professional operators rather than built, owned or operated by the foundation. Fiber owners are lending capacity because the rewards exceed the opportunity cost of the idle asset, which is the supply-side signal the model needs.
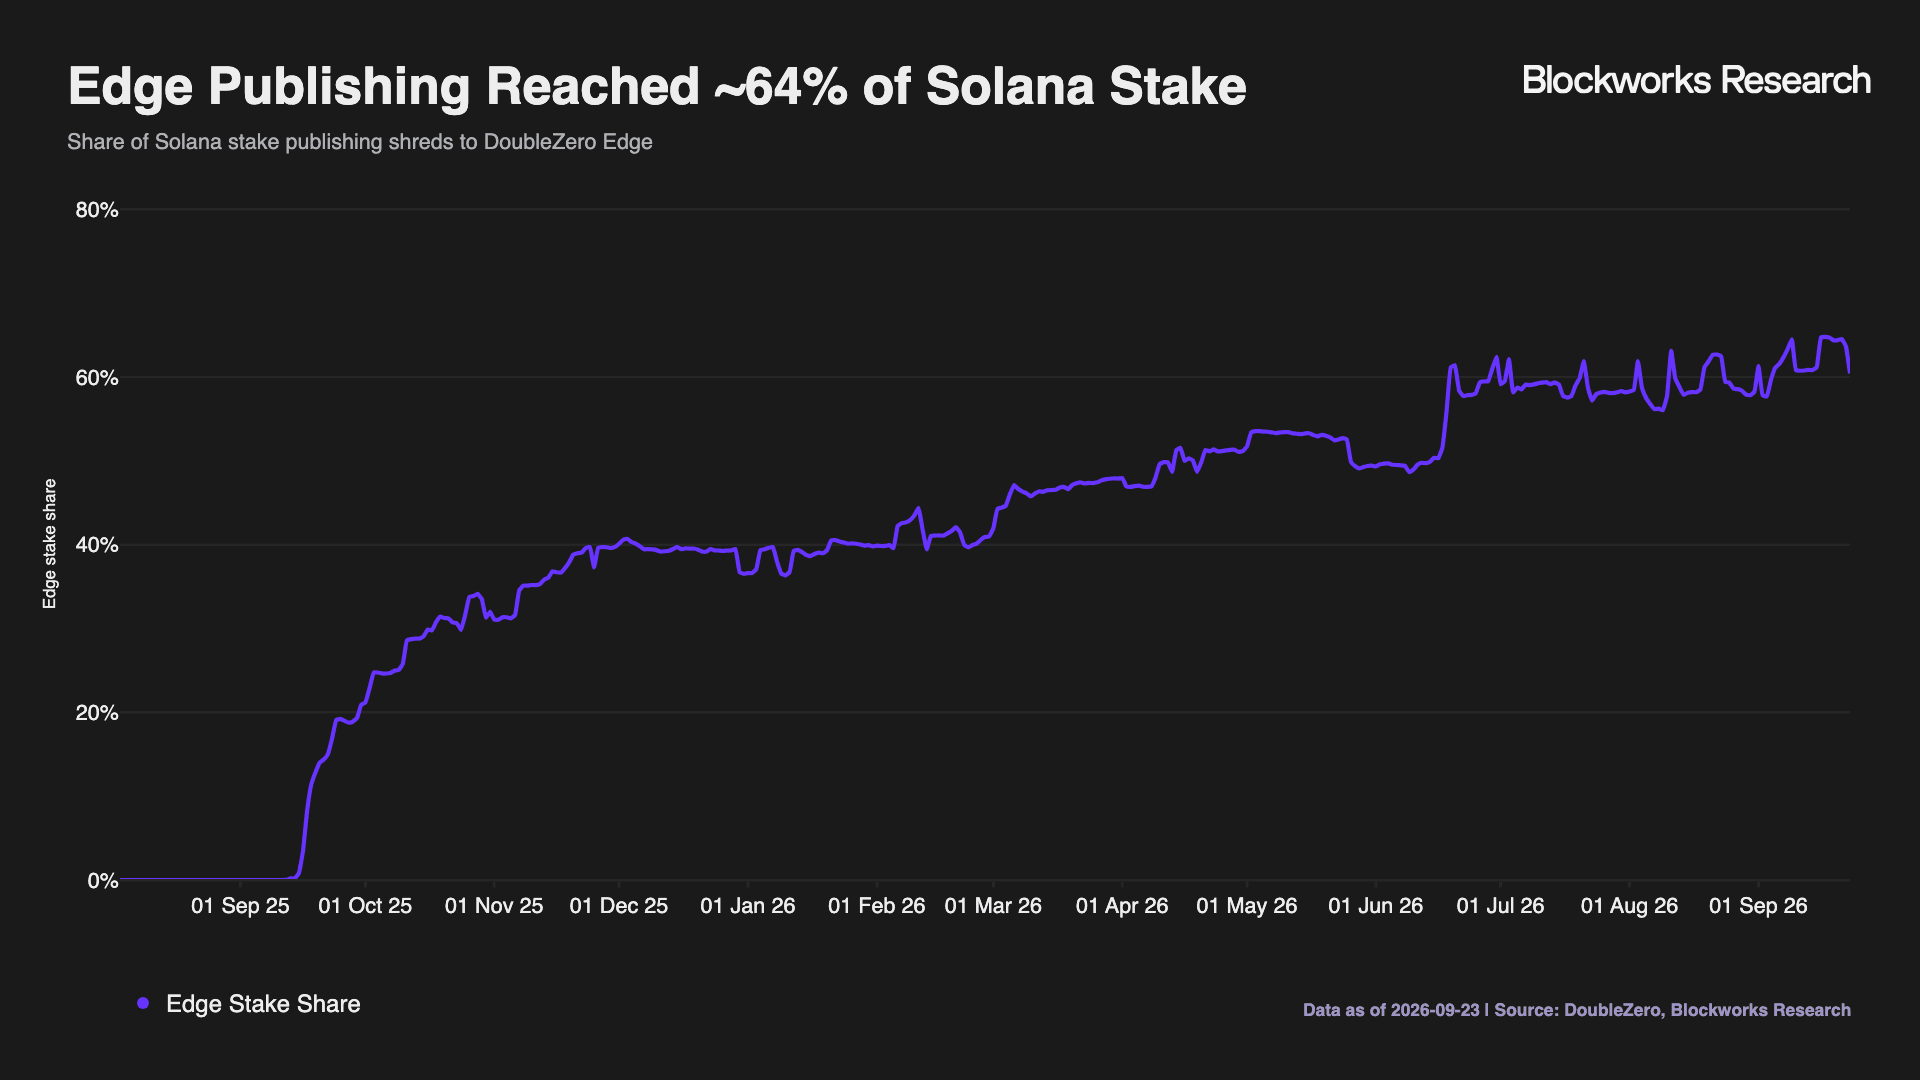
Solana was the network's first tenant, which makes it the available evidence base rather than the scope of the full network. 59.2% of Solana stake is connected across 446 validators, with 54.8% of stake (~260.3M SOL across 430 validators) publishing shreds to Edge.
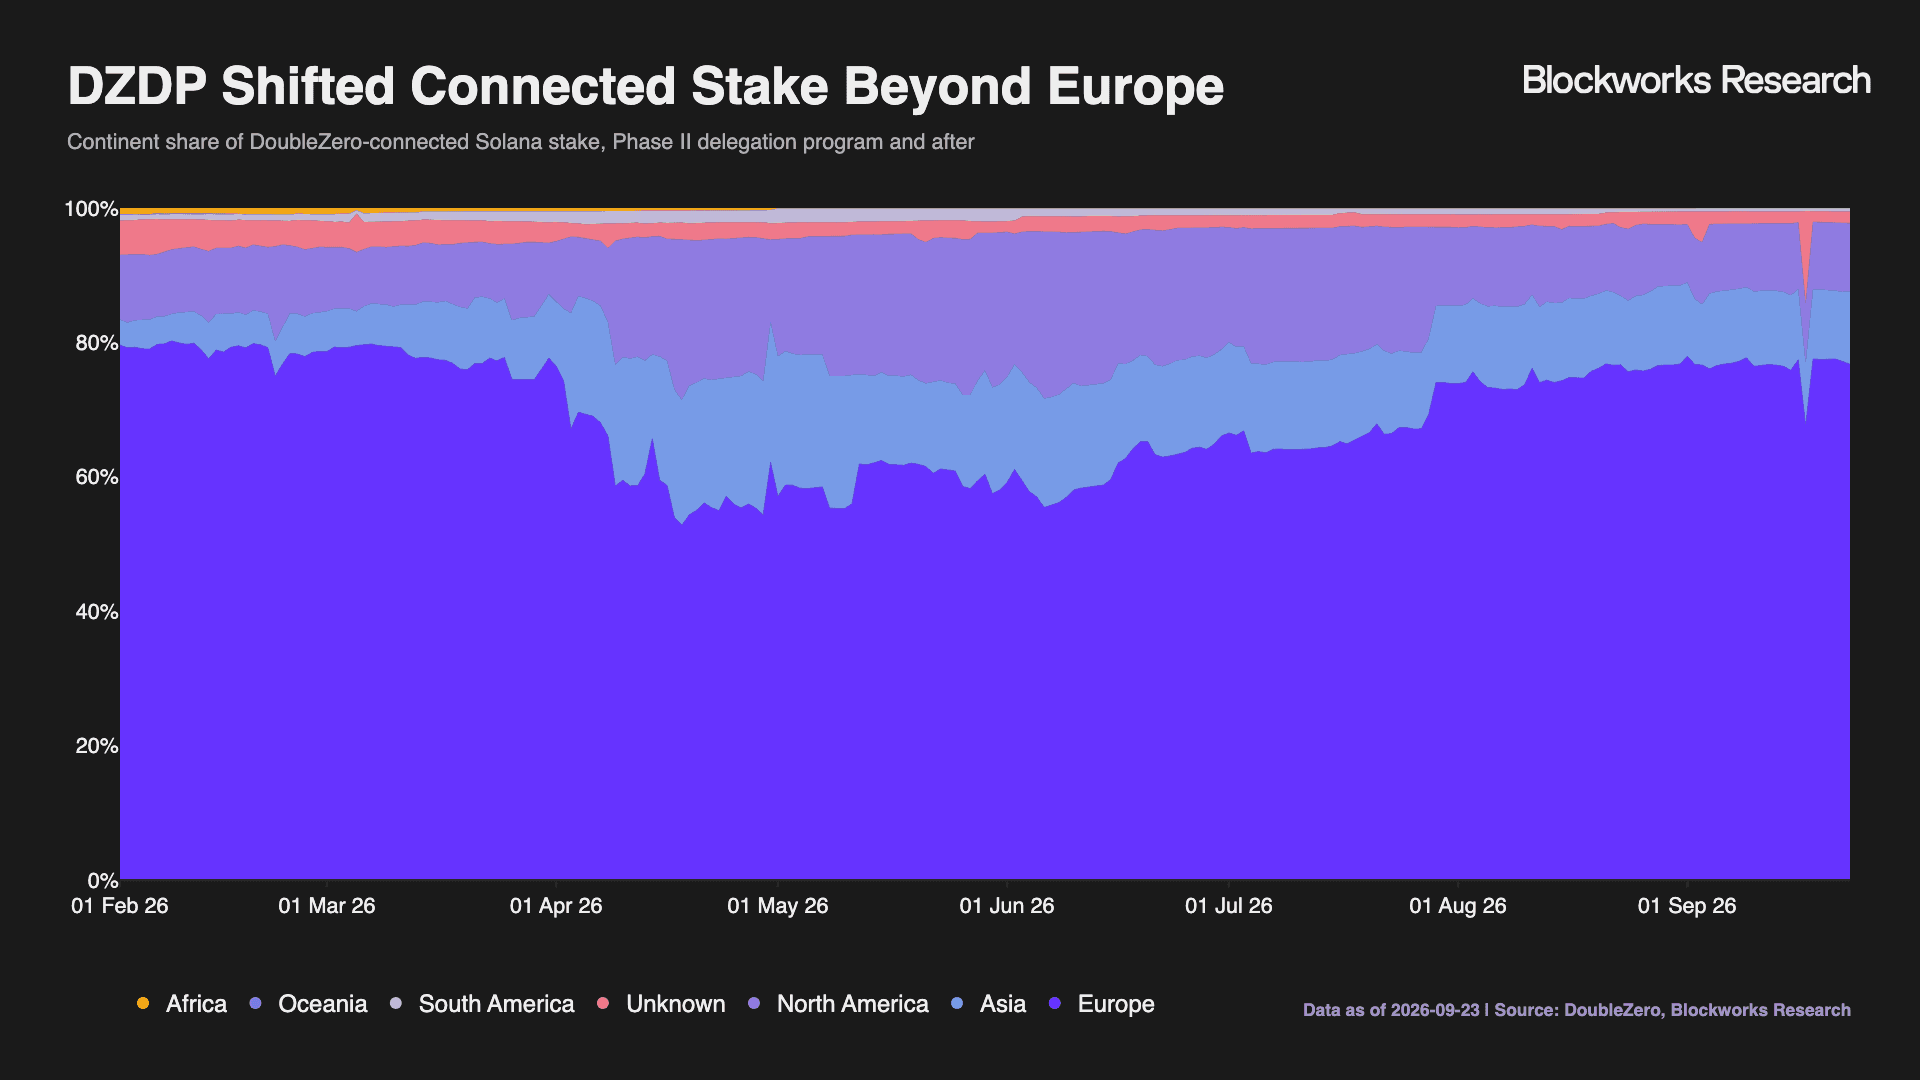
Part of that publishing growth was seeded by the DoubleZero Delegation Program (DZDP), a stake-incentive pool expanded from 3M to 13M SOL at the end of 2025 and since wound down, with the delegated stake redirected elsewhere. The program pointed delegation at geographic decentralization and multicast adoption, and delegated to Edge shred publishers directly, targeting the concentration that had 59.3% of Solana leader slots sitting in Amsterdam, Frankfurt, and London, a gravitational pull that kept new validators clustering where stake already was. During Phase II, DZDP ran a three-ring model:
- EU, where validators kept a baseline delegation for staying connected.
- US, Canada, and India, carried a decentralization bonus.
- The priority edge regions of Hong Kong, São Paulo, Singapore, and Tokyo added a device-level pool of 600K SOL per region distributed stake-weighted across DoubleZero-connected validators, 2.4M SOL in total.
With Phase II now concluded, DoubleZero's currently published DZDP criteria have simplified to three factors: timely shred publishing to Edge, total SOL publishing to Edge, and total DZDP staked SOL. Eligibility now requires connection to mainnet-beta, at least 10K SOL of activated stake, commission of 10% or less, 20 epochs of activity, reasonable performance metrics, and timely Edge shred publishing, with sandwiching or other manipulative behavior a disqualifier.
Between February 2026 and April 2026, DZDP helped contribute to the physical relocation of 82 validators representing ~42M SOL, ~10% of active stake, out of Europe and into Asia and North America. DoubleZero's official Impact Report measures the point-in-time effect as a drop in Europe's stake share from 82.3% to 71.4% over the six-week window, with North America adding 17.5M SOL and APAC more than doubling its validator count. On a 5-epoch rolling-average basis, Europe's share fell from 76.2% to 66.1%, below the two-thirds supermajority threshold for the first time in the recorded data. The absolute migration is consistent across both, ~42M SOL relocated; the level difference reflects a point snapshot versus a smoothed average, not a discrepancy in the underlying move.
The validator-level payoff has been measured empirically. Validators earn rewards by voting on blocks, so two metrics track how well they participate: vote credits, the rewards earned for voting on time, and skip rate, the share of a validator's turns as leader where it fails to produce a block. Higher vote credits and lower skip rates mean more reliable participation and more revenue. A selection-adjusted study of DoubleZero's initial cohort measured each validator against its own performance before connecting, which isolates the effect of the network from the possibility that better validators simply self-select into it. Connected validators earned 1.4% more vote credits and cut skip rates by 0.37 percentage points. Against a mean skip rate of 0.48%, that is a ~77% relative reduction.
The effect came from consistency rather than raw speed. The testnet was not uniformly faster than the public internet, but it removed the occasional extreme delays that cause a validator to miss its narrow window to vote. This is the same jitter argument Edge sells to traders, applied to consensus participation, steady delivery matters more than a fast average when a single late message costs a reward. Coinbase, in its Q2 2026 Solana validator review, reported its entire validator fleet, ~41.6M SOL across 23 validators in seven countries, running on DoubleZero at ~99.9% session uptime, with a 0.035% skip rate against a 0.136% network average and 6.5% staking APY against a 6.4% network average. The skip-rate gap is the load-bearing signal, the same missed-vote-window mechanism the testnet study isolated. Coinbase tied its connectivity work to readiness for Alpenglow, a coming Solana consensus upgrade that shortens finality, the time it takes for a transaction to become irreversible. When finality is faster, the window to get a message in on time is tighter, so reliable network placement is worth more, which reinforces the thesis.
DoubleZero frames the payoff in performance and the Solana roadmap, claiming geographic distribution over its links could cut average network latency ~11% versus the public internet. It cites this as a precondition for Multiple Concurrent Leaders, a design where several validators produce blocks at the same time instead of one at a time, and for the broader vision of transactions clearing near where the user is located rather than routing back to a few stake-concentrated hubs.
The Institutional Data and Latency Market
DoubleZero Edge is where the network's latency advantage becomes a price. Edge, launched in public beta on April 16, 2026, is venue-agnostic market data transport. A publisher emits its feed into a multicast group on DoubleZero fiber, the network replicates at points of path divergence, and every subscriber receives it in a single hop ahead of the public path most of the market relies on. Delivery is independent of stake weight, and queue position is equal across subscribers. This is the first revenue stream DoubleZero collects from the demand side of the network, and it is at the center of the commercial thesis.
The commercial unit is the seat rather than the feed, which is what makes the model scale across venues. Subscribers buy seats, subscriptions to a specific DZD for one epoch (~2 days), priced in USDC and funded from a self-custodied escrow that renews automatically while funded. Seats can be held across cities at once, and latency to a publisher is a function of distance, so a firm running listeners in Frankfurt, New York, Tokyo, and Chicago puts a nearby ear next to nearly every source. Each additional venue the network carries monetizes fiber and hardware already deployed.
Solana Shreds
The first feed on Edge was raw Solana block data. A shred is the smallest unit of block data a Solana leader propagates, and shred providers are services that deliver those shreds to subscribers faster than the default path. The Edge feed is deliberately raw, with subscribers receiving the leader's UDP packets with no deshredding, deduplication, or ordering, while reconstructing transactions themselves. The feed now ships as two groups: leader shreds, published into multicast simultaneously with Turbine on provisioned access, and a retransmission group split into AMER, EU, and APAC regions that carries the full shred set for subscribers assigned by location.
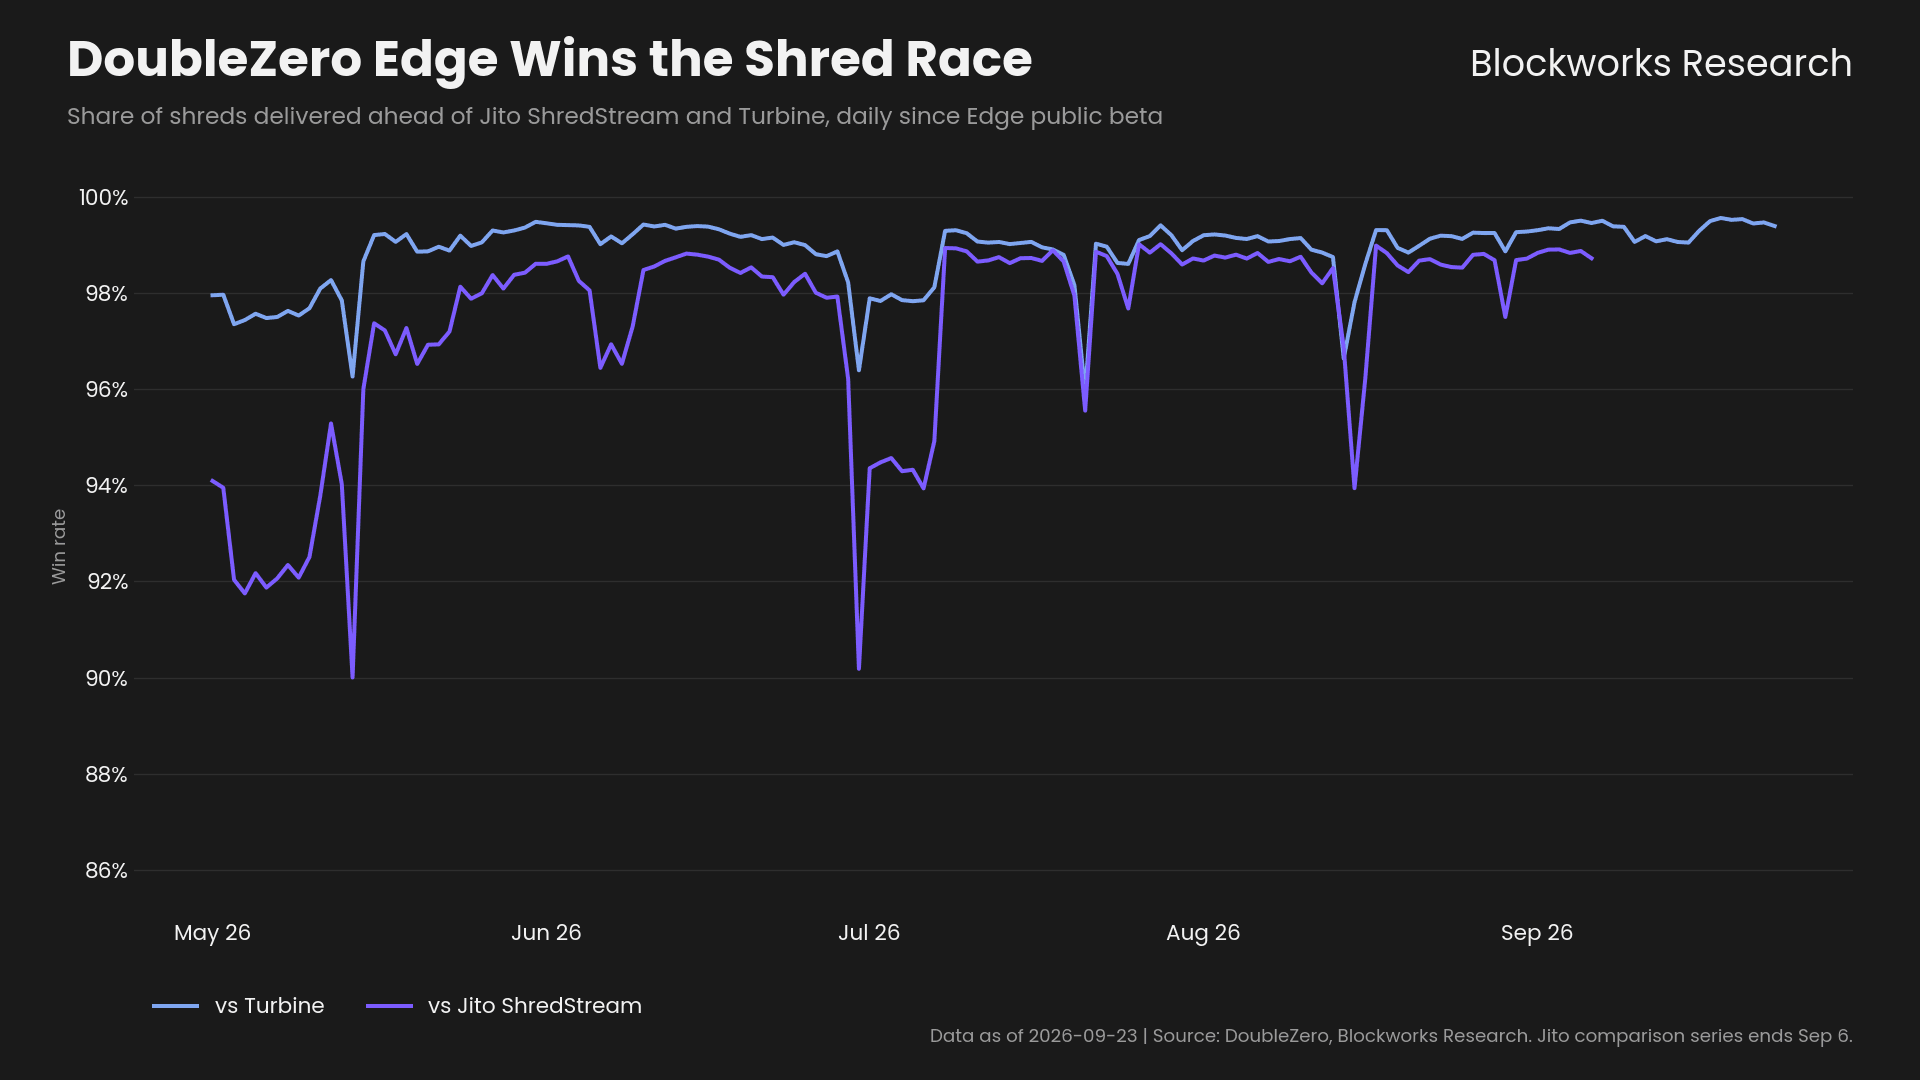
Edge’s competitive frame is worth stating precisely. DoubleZero reports Edge delivering shreds 14.8ms faster than Jito ShredStream on average (p95 54.9ms) and 26.0ms faster than Turbine (p95 224.1ms), winning the shred race 98.4% of the time. However, ShredStream is an overlay relay that forwards shreds over the public internet, cutting the latency and packet loss of vanilla Turbine while Edge is a network-layer service delivering over dedicated fiber via multicast. The two are not mutually exclusive at the point of production. MH Ventures, an Edge subscriber since the beta, reports running the feed alongside its existing ShredStream stack and citing better landing rates, execution consistency, and lower latency in Amsterdam and Frankfurt, the same EU leader hubs where stake concentrates. The durable edge is jitter rather than average latency. DoubleZero reports ~0.03ms median jitter across its routes against ~0.24ms median on the same metro pairs over the public internet, roughly an 8x gap, with internet mean jitter at ~0.77ms and the worst single path reaching ~13ms. The value of that consistency is structural: jitter spikes cluster during congestion and volatility, the moments market data is most valuable and most contested, and a trader cannot tune a strategy around a delivery time that swings. This is the advantage an overlay routing over the public internet cannot fully replicate, because it inherits the underlying path's variance no matter how well it optimizes the average.
An independent test by RPC Fast, an integration partner running Edge shreds through its RPC layer, offers partial corroboration: from a Frankfurt AWS instance, the Edge-enabled feed won 94.7% of same-transaction races over 50K transactions, with the non-Edge path trailing by 1.2ms at p50 and 15.3ms at p99. The delivered transaction count was identical across both paths. A separate independent benchmark by RPCEdge in July 2026 found DoubleZero’s advantage is distance-conditional. From a Frankfurt sender, nearby European leaders mostly tied the public path at coarse block-placement granularity, but for leaders at least 5K kilometers away, DoubleZero landed earlier in 85 of 90 same-slot pairs.
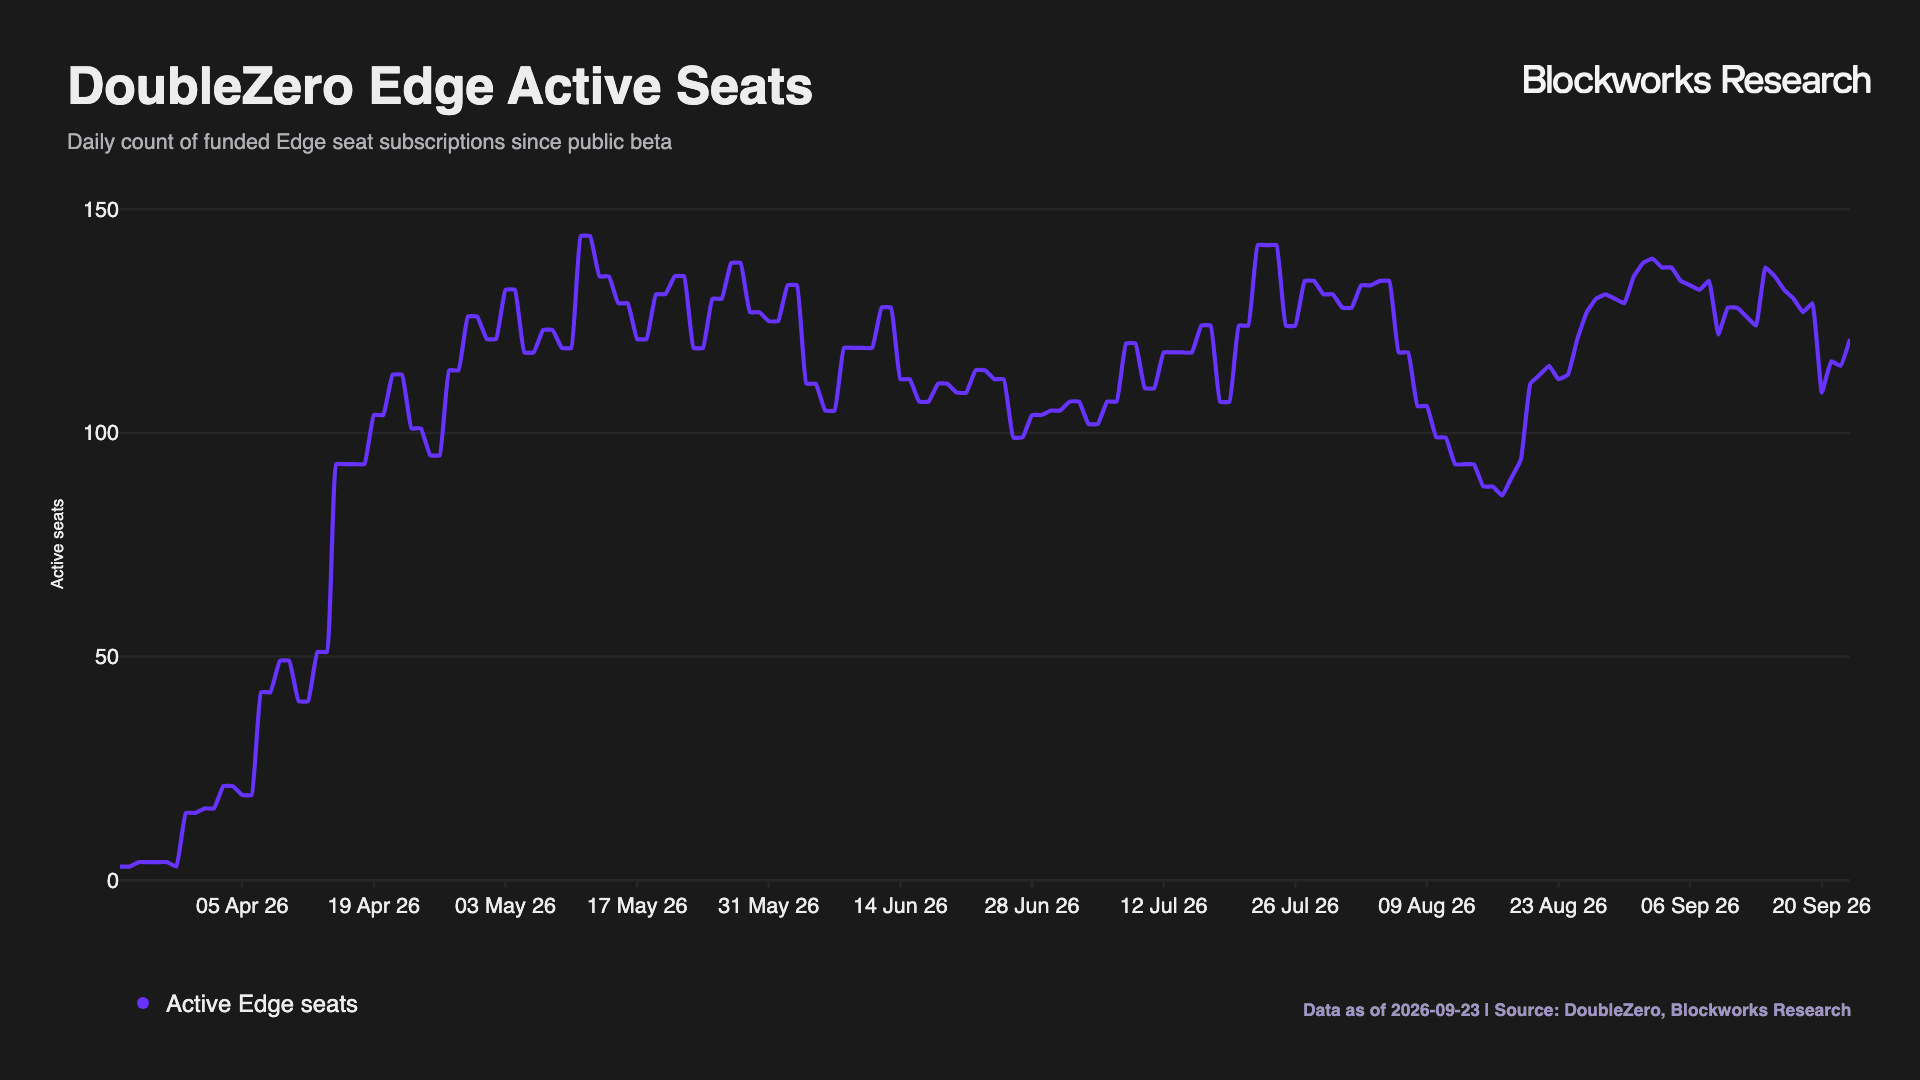
Early traction reads as a demand-side proof of concept. The publishing side scaled quickly and now includes institutional operators, with Coinbase connecting its Solana validator to Edge as a publisher in June 2026, a credibility signal on the supply side. RPC nodes began onboarding to the network in late 2025, extending connectivity to the inbound leg of the transaction path alongside the validator footprint. 683 distinct seat accounts have used Edge since launch, though it is cumulative rather than active, and it fragments across far fewer payers than the seat number implies: 274 distinct funding authorities all-time, 207 currently active, with a single payer holding 246 of 683 seat accounts (~36%). Current demand is better read as ~207 paying entities anchored by one large operator, not 683 independent subscribers. Named subscribers report concrete gains. Reflow, an ingest provider running Edge shreds through a Yellowstone gRPC-compatible feed, reports its gRPC feed moving from 35.6% to 73.3% first-seen transactions in San Francisco after switching to Edge as its upstream source, and a 90.5% first-place win rate in Frankfurt, the network's most contested metro. Reflow has also become DoubleZero's first licensed reseller, permitted to process and redistribute the stream to downstream clients who hold no direct seat. Because a seat is a finite provision but serves an unbounded number of downstream users, the reseller model extends Edge's reach past the raw seat count, while making that seat count a weaker proxy for end demand.
Established data vendors are also beginning to build on the same rails. Triton One, one of Solana's larger RPC and gRPC providers, launched a Shred Streaming product in beta in August 2026 that forwards raw shreds to subscriber servers sourced over DoubleZero's private fiber, with shreds entering at the point of presence (PoP) nearest the leader and multicast fanning them to all Triton’s five points of presence at once. The variables that decide whether Edge becomes material are active seat utilization, the depth of this downstream distribution layer, and whether the latency edge holds as subscriber counts rise and contend for the same feed.
Kalshi
Kalshi market data went live on Edge on August 12, 2026, the second venue on the transport layer and the first outside consensus infrastructure. The launch initially spanned Kalshi's two most actively traded categories, sports event contracts and crypto perpetual futures, and on September 9, 2026, elections and politics market data followed, timed ahead of the U.S. midterms. Each category ships in two tiers: full order book depth (L2, market-by-price) and top of book plus trades (L1).
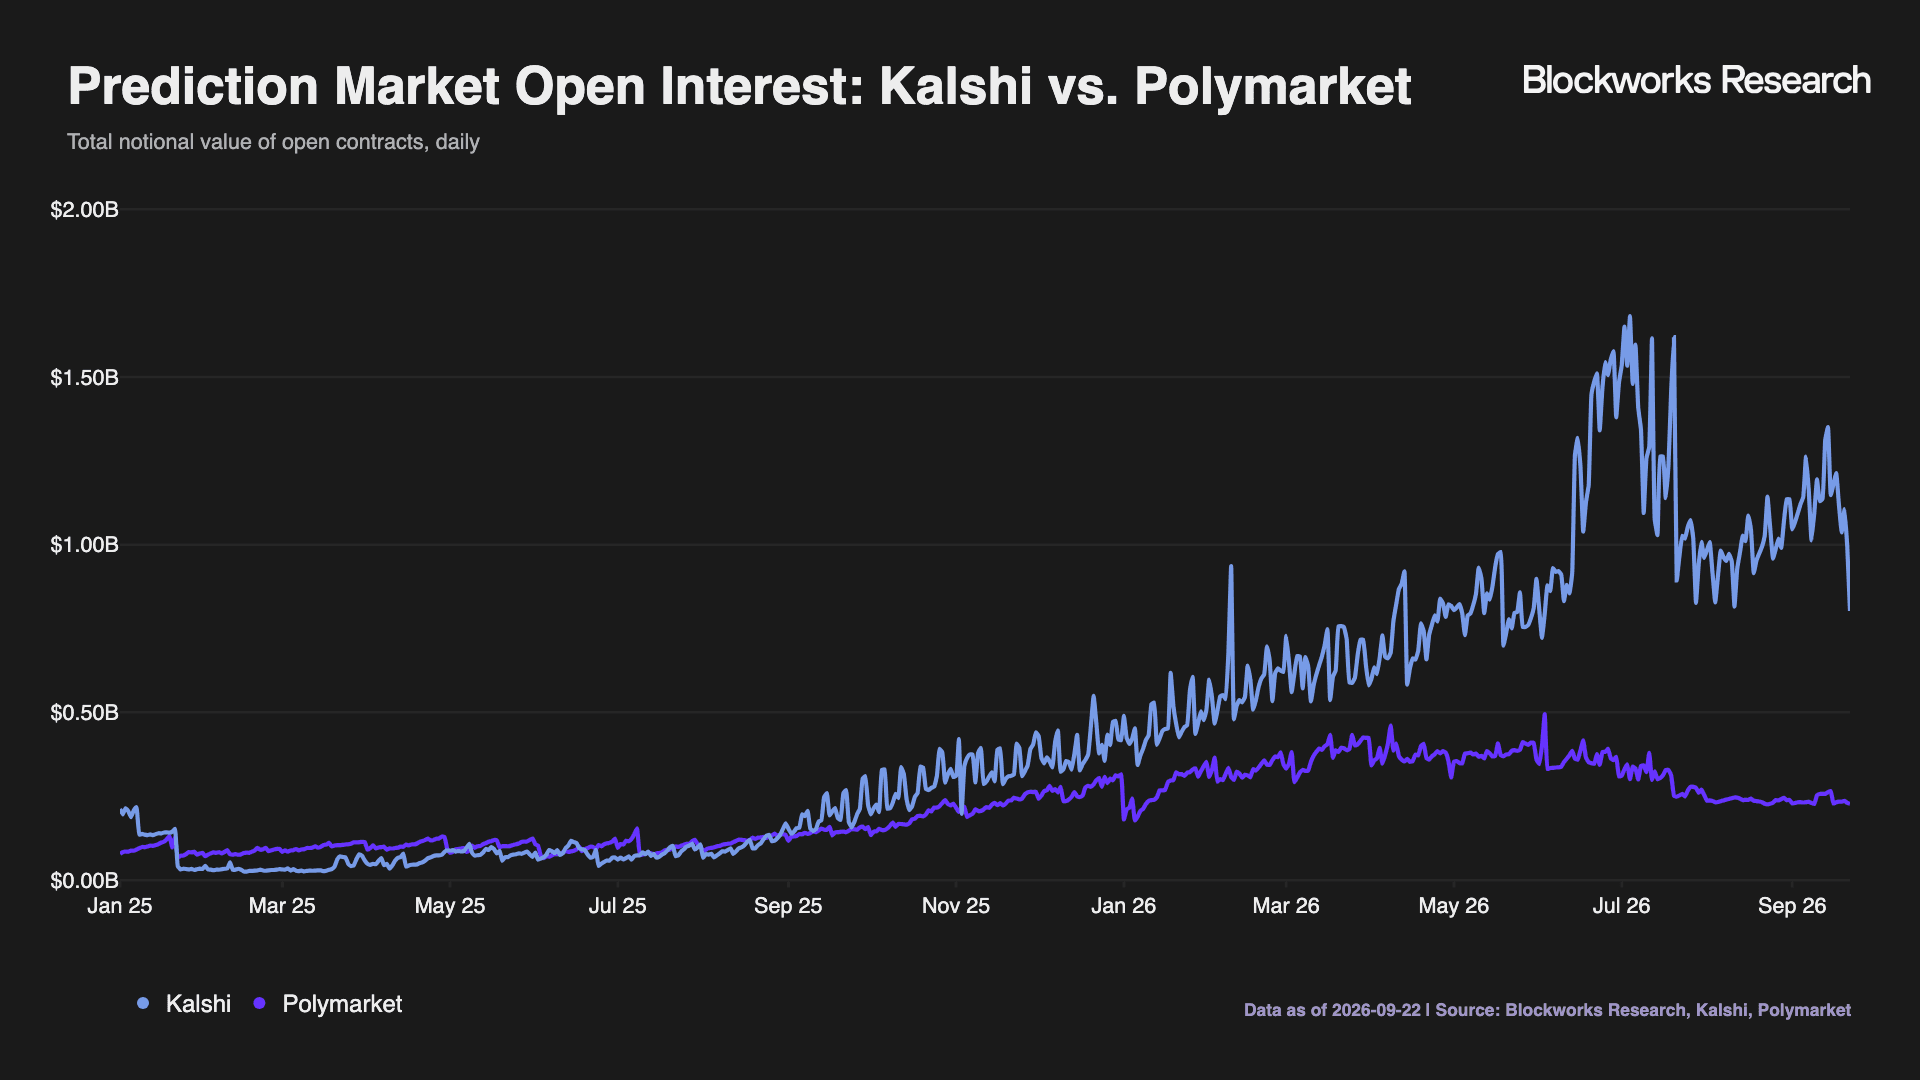
The integration is more revealing than a simple routing change because Kalshi's data structure required a second feed model on Edge. Kalshi's institutional interfaces publish state aggregated by price level rather than order by order, so DoubleZero built a market-by-price feed for the venue alongside the market-by-order model Edge already ran, the difference being whether the network carries every resting order or a collapsed view at each price. Supporting both models on one fabric is the substantive evidence that Edge is transport rather than a single-purpose product, since the second venue was accommodated by adding a feed model rather than by rebuilding delivery.
The feed is powered by Kalshi Research and rides DoubleZero Edge, an integration DoubleZero and Malbec Labs engineers built. It pulls Kalshi's live book off its institutional interface over dedicated connectivity, normalizes Kalshi's separate Yes and No quotes into one consistent book per market, and emits into the same multicast fabric that historically carried shreds, with delivery unchanged. Snapshots cycle continuously in the stream, so a subscriber that joins late or drops a packet rebuilds full book state from the feed itself without a separate snapshot channel.
The timing tracks Kalshi's own professionalization. Kalshi launched Kalshi Pro on July 13, 2026, a terminal built for speculators who trade multiple markets at once, move fast during live events, and run resting orders, with terminal-grade charting and position-risk tooling for its perps product. Edge data publishers typically retain a share of post-burn subscription fees, but Kalshi is waiving its publisher share for the first year, pricing the feed on network-delivery cost rather than data licensing to lower the cost of entry as firms wire it into production. A first-year fee waiver is a demand accelerant that flatters early traction, so seat counts on the Kalshi feed should be read against the subsidy rather than as unsubsidized willingness to pay.
Hyperliquid
Hyperliquid market data launched on September 24, 2026, making it the largest venue on DoubleZero Edge by underlying activity, having processed ~$653.1B in perpetuals trading volume in Q2 2026, ~$213B of it across HIP-3 builder-deployed markets. The launch spans four market data feeds, a market-by-order book and a top-of-book-plus-trades feed for each of Hyperliquid's native perpetuals and trade[XYZ]'s HIP-3 markets, which cover WTI, Brent, gold, silver, and the S&P 500 and Nasdaq 100. Ten independent publishers, built with validator operators and ecosystem partners including Hyperion, MAVAN, and Kinetiq, each read block output off their own non-validating node peered into the active set and publish the same venue into multicast. The wire format carries no publisher ID and deduplicates on event content, so a subscriber keeps whichever copy lands first, which makes feed latency the minimum across vantage points. The feed's onchain footprint dates to May 7, 2026, production multicast groups went live on September 16, and billable products across 31 metros followed on September 22 and 23, so by announcement day the feed carried 12 registered publishers and 15 paying subscribers. A separate peering service delivers deduplicated Hyperliquid gossip to non-validating nodes and carries no market data.
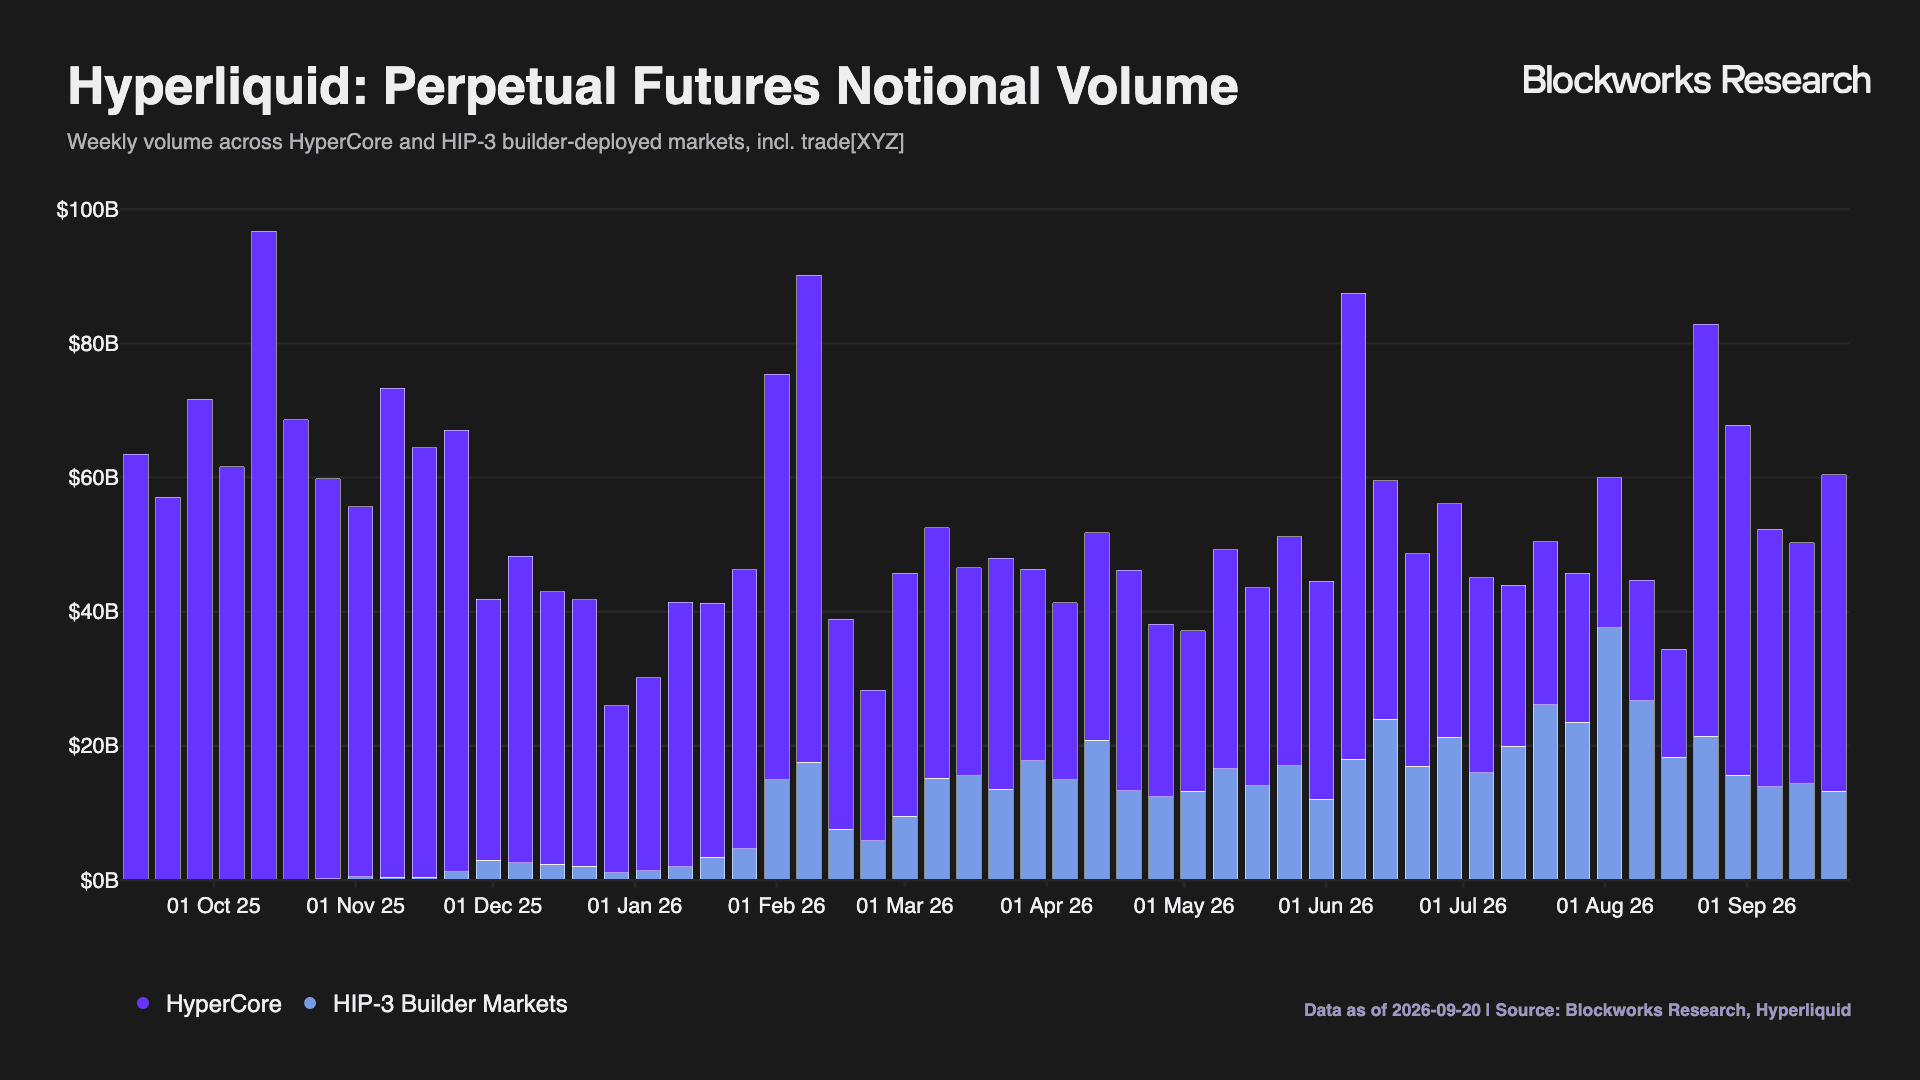
The demand case rests on a gap Hyperliquid itself created. Firms wanting a full, sequenced, machine-readable view of the book have historically assembled it themselves, reconstructing state from public API responses and maintaining large WebSocket estates across the instrument set, and changes to Hyperliquid's public APIs have reduced the update frequency and depth available over those endpoints, pushing automated traders toward node-based access. Hosted streaming APIs cap order-book streams at published tiers of roughly 5, 30, or 100 against several hundred live books, because unicast delivery costs the provider a copy per client per stream. Switch-level multicast replication means the marginal subscriber and the marginal instrument add no load, so every book on the venue is in the feed with no per-stream cap, and what gets counted is destinations: two receiving hosts per product, 8% of product price per additional host, capped at 50%. Feeds are priced flat per month by product and by where the data lands, $900 for top of book, $3,000 for full depth, and $5,500 for the suite delivered to Tokyo receivers, and $1,500, $5,000, and $9,000 anywhere else, payable in USD or USDC, with Edge Connect bridging the multicast session to a local WebSocket for stacks that do not consume raw UDP. DoubleZero markets it as the fastest commercially available Hyperliquid feed, and its own public data API reported Edge delivering order book updates first in 96.3% of 16.5M races against the public API and three commercial providers in the 24 hours after launch, with a median lead of 53.6ms, beating the closest competitor 87.3% of the time overall and 75.2% in Tokyo. That is vendor telemetry rather than independent benchmarking, and the Tokyo compression repeats the distance-conditional pattern RPCEdge found on Solana: the edge is real and narrowest where the validators are.
Phoenix
Phoenix, a Solana native perpetuals exchange built by Ellipsis Labs, followed on Edge on September 29, 2026, with two feeds, top of book plus trades and market-by-price, covering all Phoenix markets. Quarterly exchange volume grew ~12x QoQ to ~$769M in Q2 2026 and has already reached ~$2.3B in Q3, taking cumulative volume to ~$3.2B.
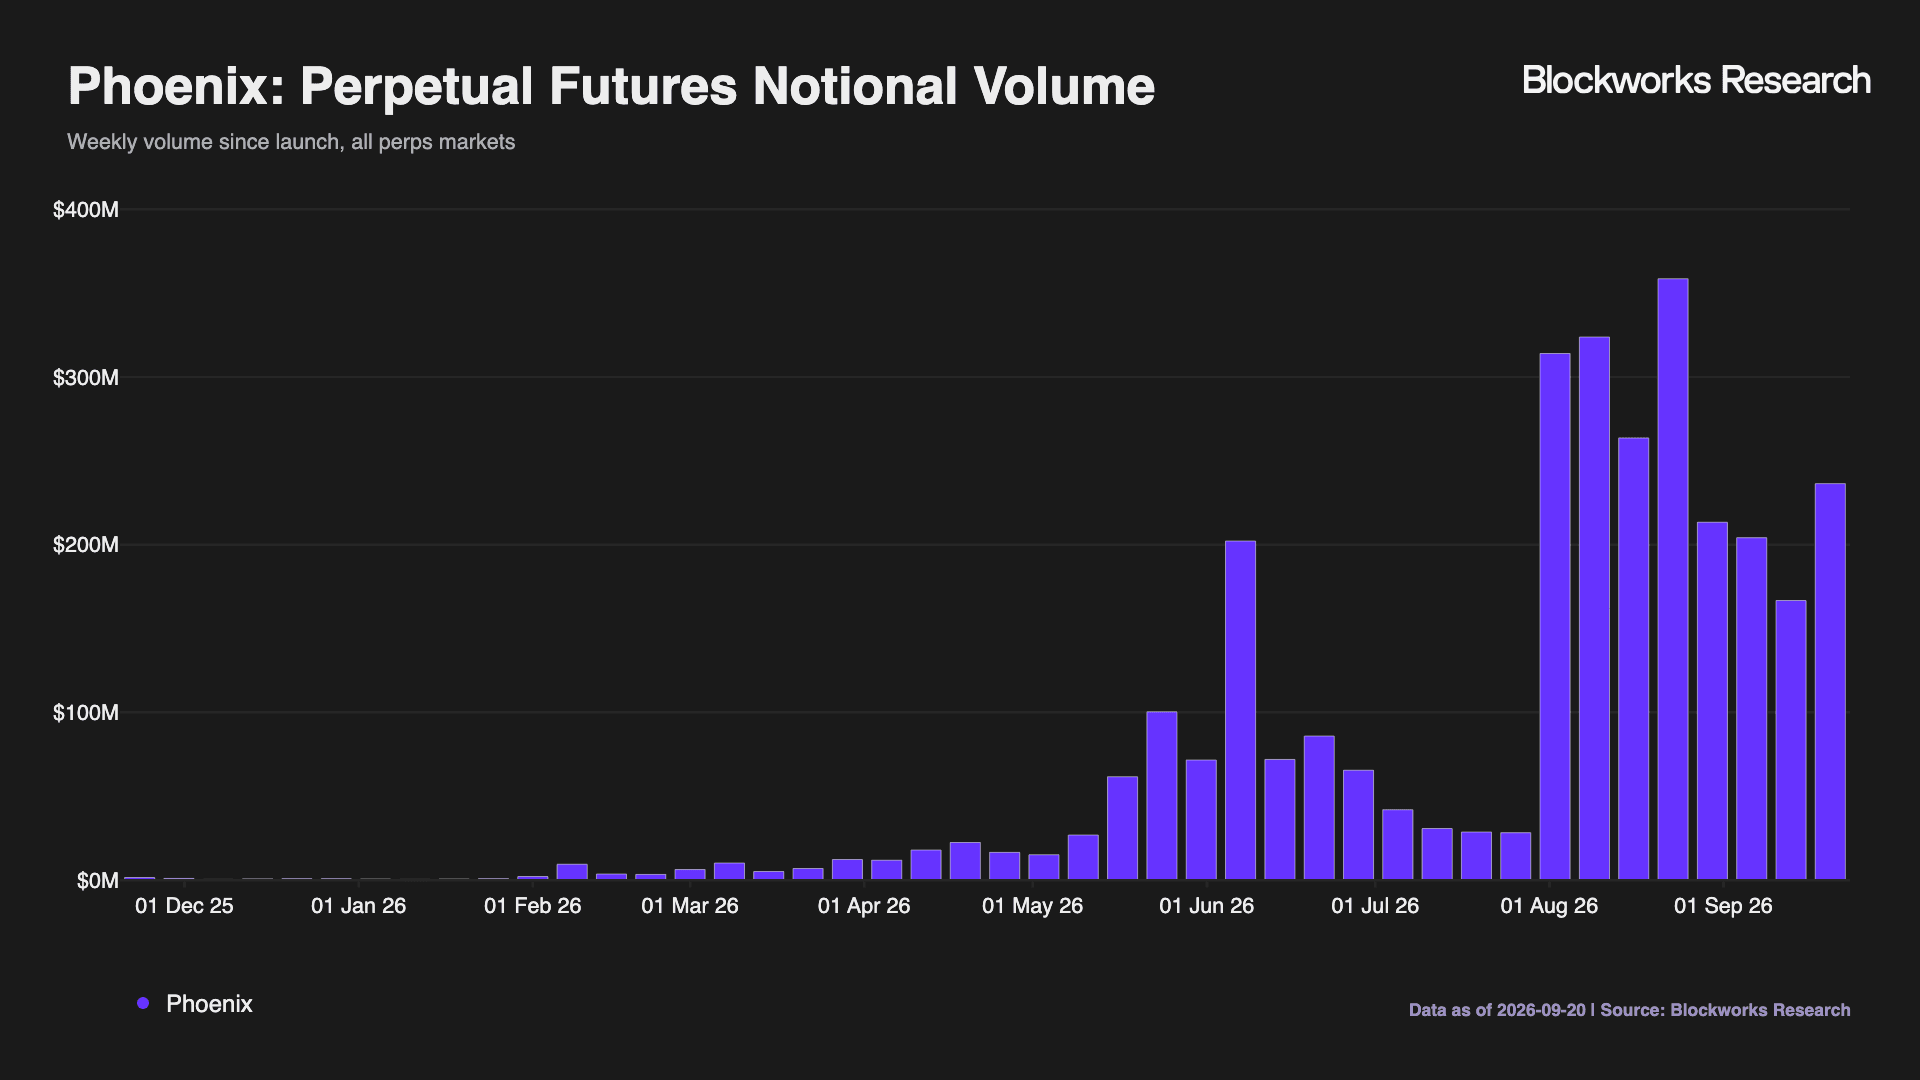
Phoenix is Edge's first decoded Solana feed: DoubleZero reconstructs the Phoenix book offchain from program state and publishes a finished market-by-price book, the same object shape subscribers already consume from Kalshi. That shifts reconstruction work from the subscriber onto the network and moves Edge up the stack from raw transport into processed data, the layer where its own resellers currently add value on the shred feed. DoubleZero's launch claim is that early benchmarking shows the decoded book arriving as much as ~750ms ahead of any other Phoenix feed, with no published methodology, sample size, or comparison set, so it is vendor telemetry until an independent race exists.
Proof-of-Location: The Precondition for the Guarantee
A network that sells latency and routing guarantees must prove where its nodes are physically located. IP geolocation databases deliver 50-70% city-level accuracy and degrade in cloud environments, GPS needs rooftop antennas datacenters lack, and self-attestation is trivially faked. DoubleZero's Geolocation Verification turns this into a product and a precondition rather than an afterthought. Light moves through fiber at ~200km/ms, and no software compresses real fiber distance below the speed of light. The system chains three tiers, each signing its measurement with Ed25519 keys:
- A DZD with latitude and longitude registered onchain as the root of trust.
- A co-located geoprobe that measures round-trip time to the target.
- A signed result the target can carry forward.
The honest limitation is that latency proves an upper bound on distance. The system can prove a node is close to a point but not far from one, since an attacker can add delay to look farther away but cannot fake being closer. For latency-sensitive nodes like validators, binding the proof to network identity defeats proxy attacks, because tunneling traffic through a distant proxy degrades the very performance the operator is protecting. For latency-tolerant workloads, the proxy attack remains viable, so compliance buyers should not read the output as proof of exact residence.
Provable placement is what makes the rest of the network's claims load-bearing. It also extends the addressable surface, compliance and data-residency proof, airdrop eligibility resistant to VPNs, validator-location verification, and verification of where a counterparty's infrastructure physically sits, a requirement that arrives with every venue carrying reporting obligations.
The 2Z Economy
2Z is the native token of DoubleZero. It pays for and rewards network connectivity, and may one day be stakeable to bolster network security. 2Z is not a governance token and carries no voting rights. The token launched in October 2025, with rewards paid to contributors and a partial burn of those rewards.
Ahead of that launch, DoubleZero Foundation successfully obtained a rare no-action letter from the SEC's Division of Corporation Finance, dated September 29, 2025. The staff stated it would not recommend enforcement action if the network's Programmatic Transfers go unregistered under Section 5 of the Securities Act and 2Z goes unregistered as an equity security under Section 12(g) of the Exchange Act. The position rests on DoubleZero's representations to the staff, speaks to enforcement only, and reaches no legal conclusion on whether 2Z is a security, so it is narrower than a finding that the token sits outside the securities laws. In an accompanying statement, Commissioner Hester Peirce framed DePIN reward tokens as compensation for work performed rather than investment contracts and argued the Howey test, the standard for an investment contract, is not met, though that reflects her individual view rather than a Commission determination. The letter gives 2Z a degree of US regulatory clarity few token issuers have obtained, contingent on the network continuing to operate as represented. The token supply was 10B 2Z at launch. DoubleZero's tokenomics provide for inflation to fund resource providers running compute and security, bounded over time by burns, but no inflation has been activated and contributor rewards carry no emissions component. Burns from network usage have retired ~1.93M 2Z since the first burn in October 2025, ~0.02% of supply, of which ~715K 2Z came from Edge fees across epochs 943-1044 on ~7.2M 2Z of Solana-shred revenue. At current scale the burn’s significance is the linkage it establishes between network revenue and token supply, which scales only if Edge revenue does.
Edge's launch changed how the network generates revenue. The original model charged 5% of priority fees, a variable, SOL-denominated cut taken at the validator layer, before Edge introduced the current model: a fixed USDC-per-epoch subscription billed to the demand side. The shift moves the network's revenue from a variable share of validator economics to a predictable subscription paid by the parties consuming the data, denominated in USDC rather than a volatile fee stream. Edge collects fees in USDC, or by card or ACH for firms that prefer fiat rails, and swaps the full amount into 2Z before distributing, so every dollar of Edge revenue is a market buyback of the token. Contributor rewards carry no passive emissions. The only 2Z a fiber operator receives is the fee-funded share, which ties supply-side pay directly to demand-side revenue. 10% of Edge revenue is burned and 90% distributed, with the distributed pool split 50% to network contributors, 32.5% to validators publishing shreds, and 17.5% to protocol client teams, so 45% of gross fees reach data originators and 45% reach fiber contributors. Geolocation verification is designed to work differently, it is paid directly in 2Z on a flat per-epoch basis, creating direct token demand rather than the indirect flow Edge produces.
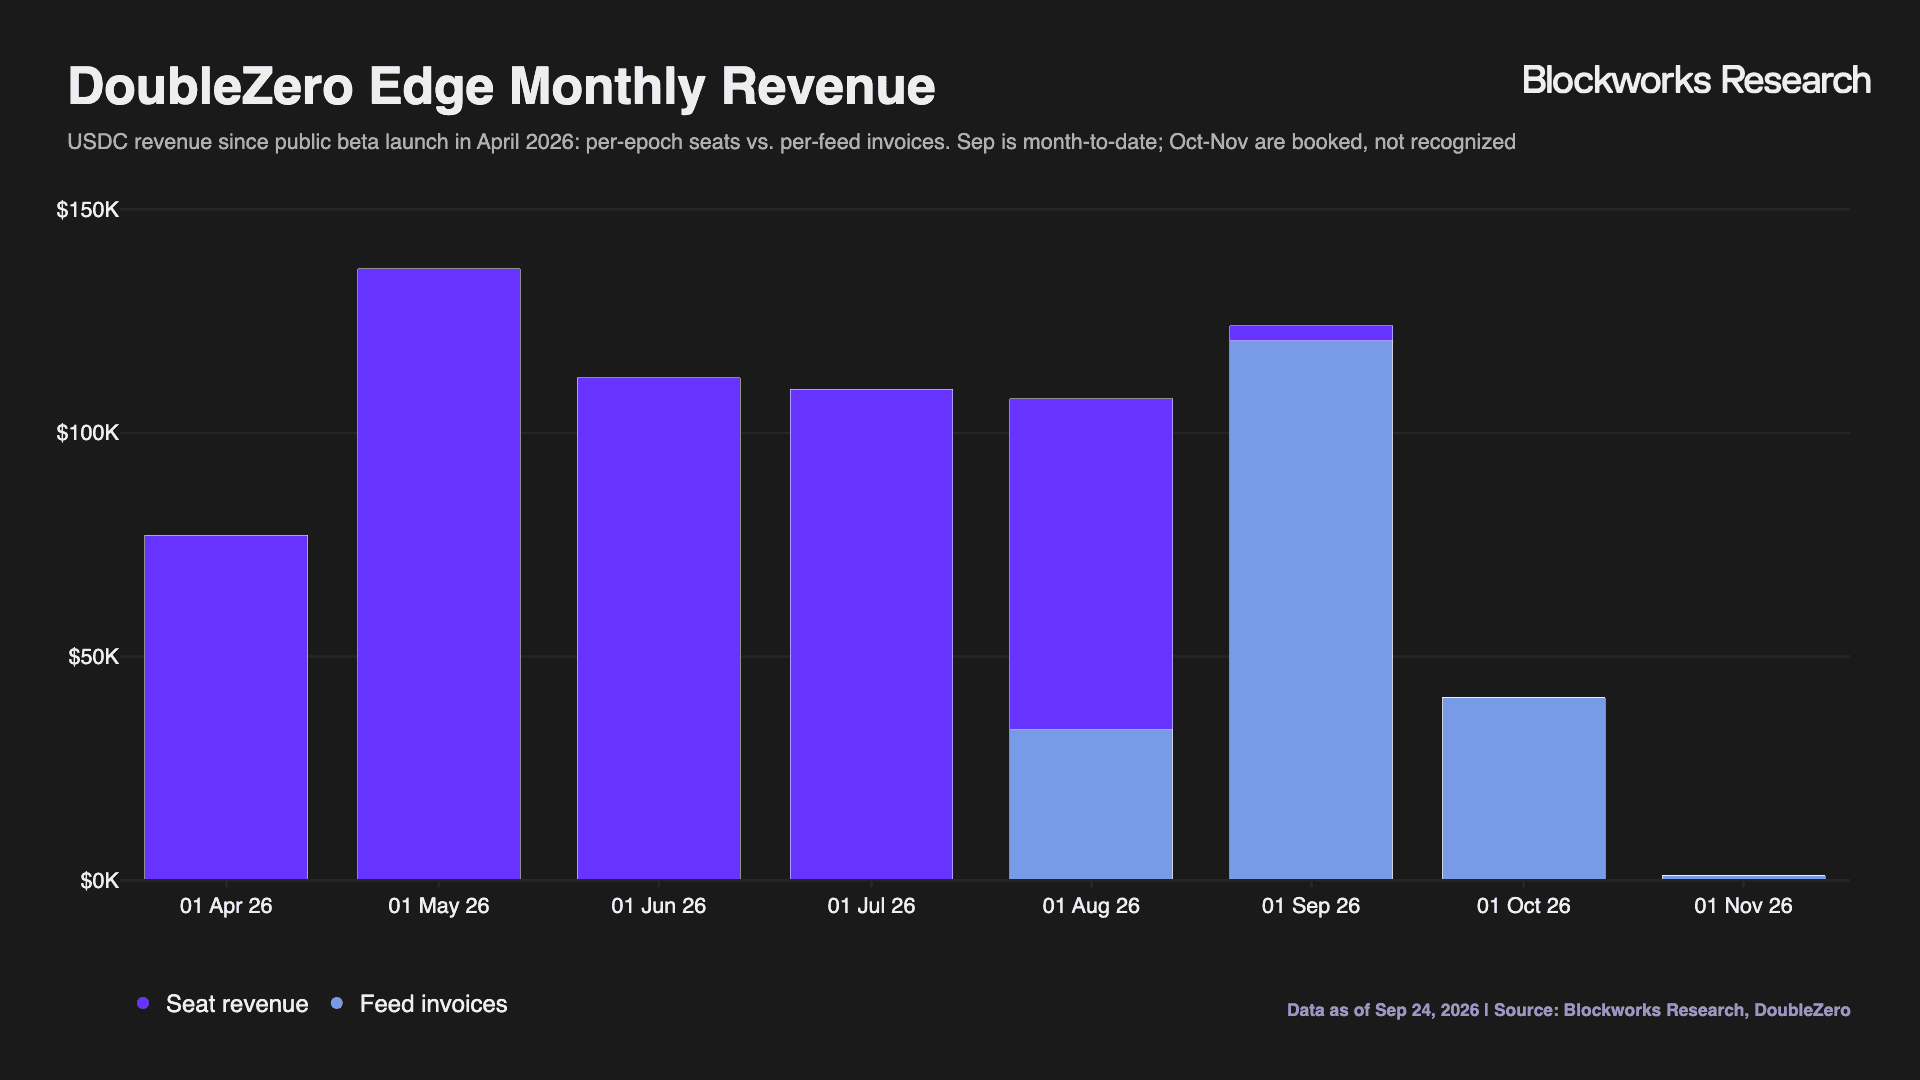
For a contributor, the operating leverage is built into the footprint. A co-located geoprobe is a new 2Z-denominated revenue line running on the same telemetry infrastructure its DZDs already use, creating additional yield on a fixed footprint. The contributor's economic case strengthens as the network adds product lines that monetize the same physical assets.
New Initiatives and Longer-Horizon Use Cases
DoubleZero is designed as a neutral transport layer for any distributed system, and Solana served as a natural testbed for the technology for a structural reason. A connected validator earns two independent returns on one connection: improved consensus performance from lower latency variance, measured in vote credits and skip rate, and a 32.5% share of distributed Edge revenue for publishing its shreds. DoubleZero removed the 5% block reward fee for connected validators at epoch 939, so the operator bearing only hardware and colocation cost collects both returns, which explains why the supply side filled in here first and fastest. On other systems the network is transport being sold to a venue, with no second return flowing back to the party that connected. Every venue past this point is a generalization away from that origin case, resting on the same fiber and multicast that serves Solana shreds, extended to any market where execution quality is network-bound. The Kalshi, Hyperliquid, and Phoenix feeds extend the Edge thesis, that raw, low-latency data delivery has value beyond validator shred distribution, into markets where speed of information is the product itself.
The throughline is what DoubleZero’s cofounder Austin Federa has called New Finance, markets that are natively global, continuous, and largely permissionless, yet still distribute their data over Web2 rails never built for competitive execution. The constraint is not only network distance but determinism. Websocket and CDN-based fan-out deliver market data to different participants at different moments, so no two traders see the same book at the same instant, an asymmetry that persists regardless of how open the market is at the settlement layer. DoubleZero's proposition is to make delivery fair by construction, a single multicast feed reaching every subscriber in one hop independent of stake weight or queue position, the same equal-access property traditional venues engineer into their physical infrastructure.
RFC 18 is the infrastructure piece that makes this expansion tractable. By letting the network classify links onchain and route latency-sensitive multicast feeds separately from bandwidth-heavy unicast traffic, DoubleZero can onboard a new venue with different traffic characteristics without the new tenant crowding out Edge's fast paths. The architecture was built to generalize past Solana from the start, and RFC 18 is the mechanism that lets it actually do so on a live network.
The nearest demand vector is any venue where a market maker prices latency variance into spreads. A maker quoting continuously is exposed to being picked off on stale prices, so delivery variance is a direct input to the spread, and lowering it lowers the stale-information premium the maker charges. The effect shows up as breadth before depth, since more reliable quote defense expands the set of instruments a maker will quote continuously. Onchain, Blockworks Research coverage of Solana execution frames DoubleZero as attacking exactly this cost for the prop AMMs now running above half of Solana spot DEX volume, though the network does not address transaction ordering, which remains a venue-layer function. Blink, a Solana-built ZK-rollup exchange for spot and perps, already wires this in directly, using a DoubleZero-timestamped transaction feed as the input to its matching engine. This positions Edge and the broader network against a demand base of prop AMMs, MEV searchers, and latency-sensitive execution venues that already pay for freshness, the same constituency Edge's shred feed targets.
Beyond the venues already in progress, the team and its ecosystem have pointed at a wider set of directions the network could grow into:
- Distributed AI Training and Inference: Austin Federa has argued that distributed AI's main disadvantage against centralized AI is that it runs over the public internet, and that the same latency and data-movement problems DoubleZero solved for blockchain and market data apply directly to training and serving large models across distributed compute.
- Owning the Fiber Layer: Federa has also floated the idea of applying the DoubleZero model to fiber installation itself, letting crypto-native capital build and own physical internet infrastructure rather than just routing over infrastructure others built.
- Exotic physical-layer communication: The DoubleZero Foundation's Science Research Initiative, a $100K open call on ResearchHub for neutrino- and muon-based communication research, sits outside the commercial roadmap entirely but reflects the same underlying focus that drives Edge and RFC 18: shrinking the physical distance data has to travel.
Risks
Demand Concentration: Edge revenue rests on a relatively small number of subscribers. A thin base makes the run-rate fragile and the annualized figure sensitive to a handful of churned accounts. Revenue durability is unproven until the base widens and seat utilization holds.
Supply Concentration: Five contributors receive ~92% of network-contributor rewards over epochs 943-1044, with the top two, Infinite Fiber and Jump Crypto, at ~55% combined. The concentration sits on the hardest-to-replace side of the network, professional fiber operators, so the dependence is structural. It also sits in tension with the reward design, since the Shapley-value model is built to reward incremental performance and resist incumbency, yet the contributor set remains heavily concentrated, which implies the largest operators are also delivering the largest marginal improvement rather than the concentration being a scoring artifact.
Partial-Adoption Ceiling: The network's benefit is a function of how much of a given message path sits on DoubleZero fiber. Communication between a connected and a non-connected validator still traverses the public internet for the non-connected leg, so the latency and jitter guarantees hold end-to-end only where both endpoints are on the network. At current adoption, a meaningful share of consensus traffic still crosses public routes, which caps the realized performance gain below the theoretical ceiling and makes broad adoption a precondition for full benefit rather than a nice-to-have. Each additional connected endpoint raises the share of paths that stay on fiber, so the network's value compounds with adoption and is discounted until it arrives. The same arithmetic applies feed by feed: a market data path is only as fast as the least-connected leg between publisher and subscriber.
Incumbent and Competitive Response: On trader-facing shred delivery, DoubleZero competes against a crowded field of shred and transaction-delivery providers, not Jito ShredStream alone. OrbitFlare forwards raw UDP shreds from top-of-turbine validators ahead of the RPC layer, Corvus Labs markets decoded shreds at a claimed ~8ms edge, and bloXroute runs a private global distribution network that, like DoubleZero, routes around the public internet, though as an overlay rather than dedicated fiber with multicast. The competitive picture is not uniform. Several delivery layers that look like rivals sit downstream of DoubleZero. Triton One's Shred Streaming product runs on Edge under the same authorized reseller model, alongside Reflow. That is what the model is designed to do, converting delivery-layer competitors into distribution. The RPC providers and market-data vendors that hold the spend today sit behind these delivery layers, and can choose which upstream they buy from.
Execution Risk: The single-balance-sheet alignment that made Solana the origin case does not travel with the architecture. Off Solana, Edge is network transport sold to a venue rather than a validator monetizing its own latency, and each new tenant requires bespoke integration: Kalshi forced a second feed model and a first-year fee waiver to seed adoption, Phoenix required DoubleZero to build in-network decoding of onchain program state, and Hyperliquid required a ten-publisher racing architecture and a four-month pre-production build. That thesis now spans four venues, at least one of which is subsidized, so the multi-venue revenue model is unproven until non-Solana feeds sustain paid, unsubsidized demand.
Conclusion
Distributed systems are bounded by network physics before they are bounded by any other factor, and the credible way to lift that bound is a purpose-built physical layer, independently contributed private fiber, coordinated onchain, with provable node placement. DoubleZero has demonstrated supply-side adoption, and the first tenant ecosystem connected more than half its stake, the majority of which publishes to Edge. Edge has shown initial trader demand for lower-latency data delivery, with named institutional publishers, a cumulative subscriber funnel, and a forming reseller layer, but active seat utilization and unsubsidized willingness to pay across venues remain the open questions that decide whether Edge becomes a material revenue primitive or stays a proof of concept.
The value-flow change is concrete and already underway. Edge converts the network's latency advantage into usage-based revenue, moving DoubleZero from a variable cut of validator economics to a USDC subscription paid by the parties consuming the data, with geolocation verification adding a second, 2Z-denominated demand line on the same physical footprint.
The trajectory from here is a generalization question. The first tenant adopted fastest because the operator that connected captured both returns, and every venue past it, Kalshi first, then Hyperliquid and Phoenix, among many other feeds in the pipeline, AI training and fiber ownership on a longer horizon, tests whether low-latency delivery holds value when the only return to the publisher is the fee share. Kalshi is the first read on that, and a subsidized one, so Hyperliquid and Phoenix are where the unsubsidized answer will show up first. A network that can prove where its nodes sit and reduce latency variance relative to public-internet routes is a primitive whose uses extend well past block propagation, and the coming year of non-Solana adoption is what will show how far past.

Nick leads coverage on the DePIN and Proof of Work sectors. Previously led research and engineering at a DePIN-focused accelerator.