Derive’s Next Leg

The Derive thesis is playing out across several of its central pillars. Options activity has continued to scale, broader asset coverage is attracting meaningful volume, and declining maker rebates have improved options monetization. These developments are translating into stronger financial results, with Derive recording its highest monthly net revenue of 2026.
Asset expansion is particularly encouraging. HYPE demonstrated that a relevant new listing can develop into a substantial standalone market, while XAUT is tracking ahead of HYPE at a comparable stage. This gives greater credibility to the view that Derive can differentiate through options markets that remain unavailable on larger venues.
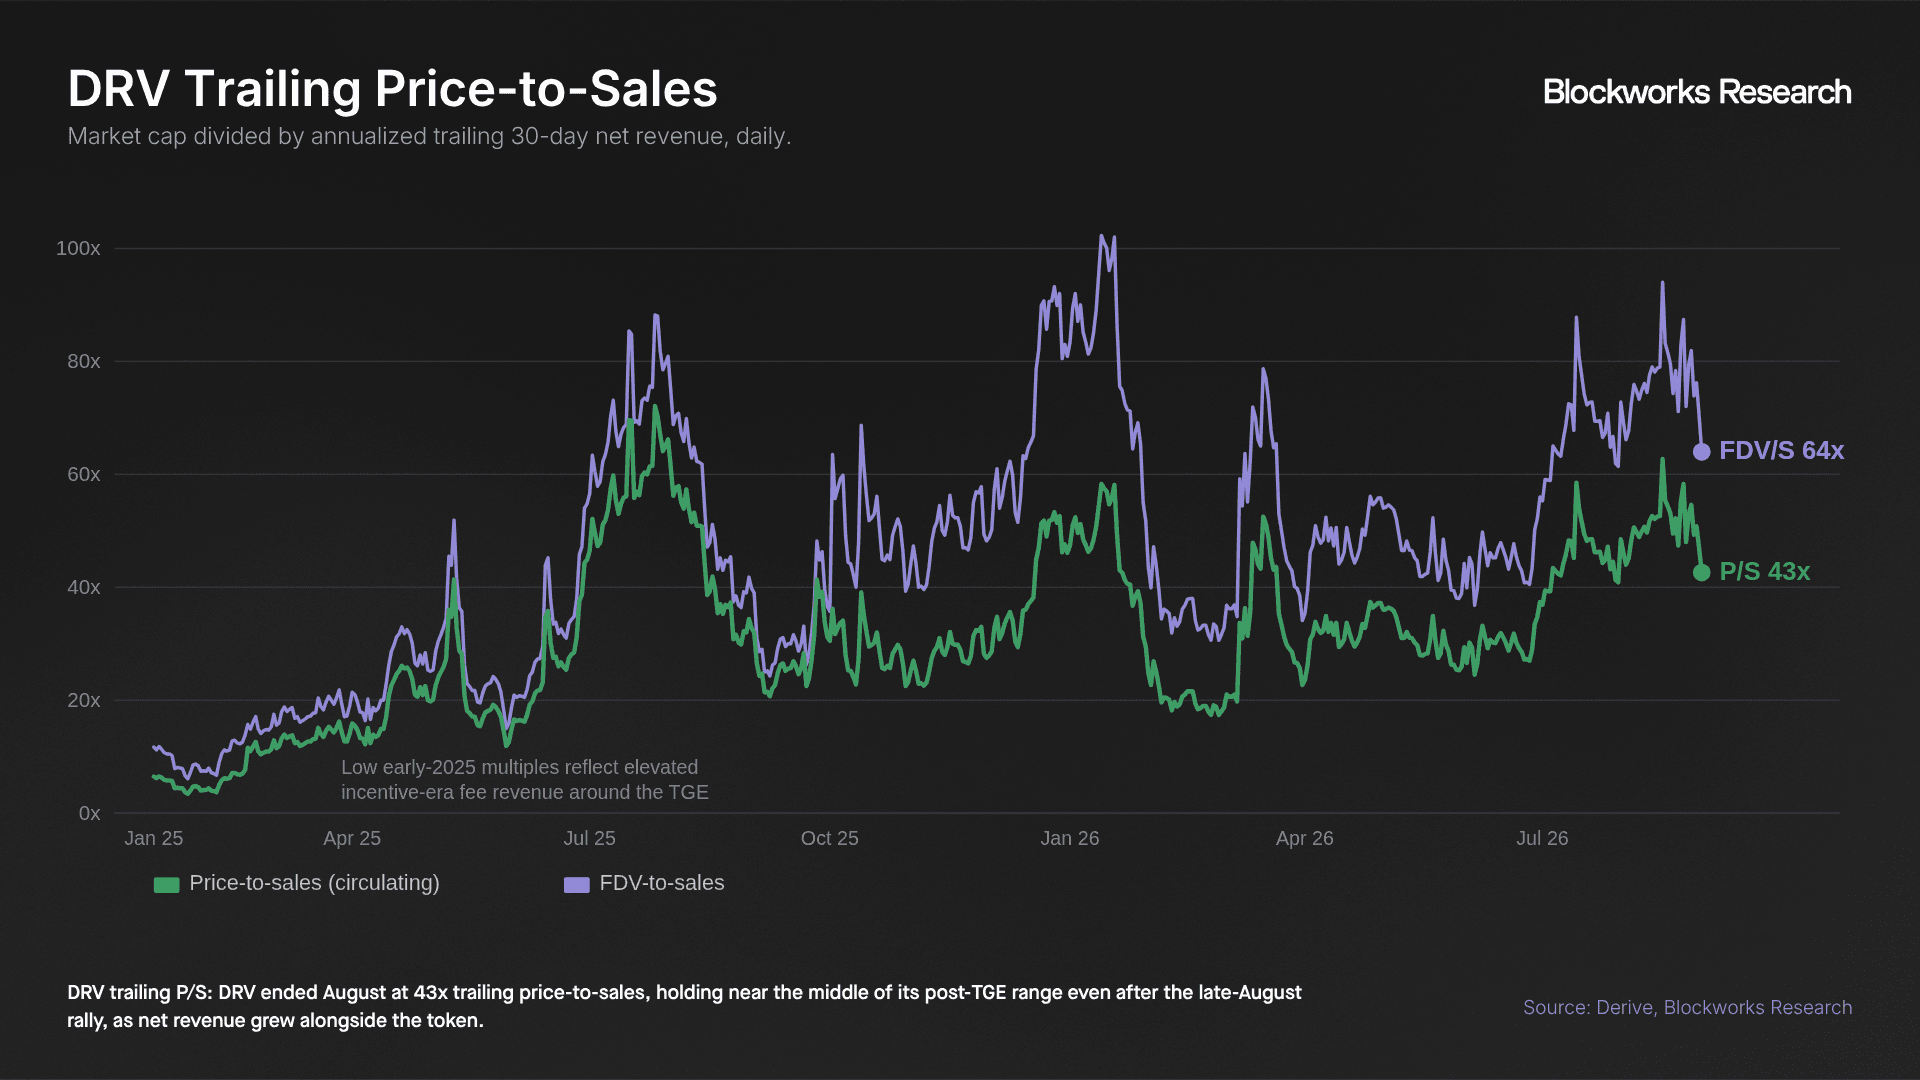
DRV ended August at 43x trailing price-to-sales and 64x FDV-to-sales. Despite the token’s rally, both multiples remained broadly within the ranges observed over the past year as net revenue grew alongside price. The current valuation embeds meaningful growth expectations, leaving Derive to grow into these multiples through sustained revenue expansion.
The structural setup has improved as buybacks now exceed staking emissions. Secondary market liquidity has also improved materially since our March report following listings on Coinbase and Upbit. Average daily DRV trading volume rose from roughly $0.4M in the 30 days before the report to $6.5M in August, while median daily volume increased from $0.1M to $3.3M.
Looking Forward
Four indicators will determine whether Derive can extend its current momentum:

Carlos leads coverage on Solana and spends his time on DeFi applications. Previously held a research role at 21Shares.