Bitcoin August 2026 Update

Market Commentary
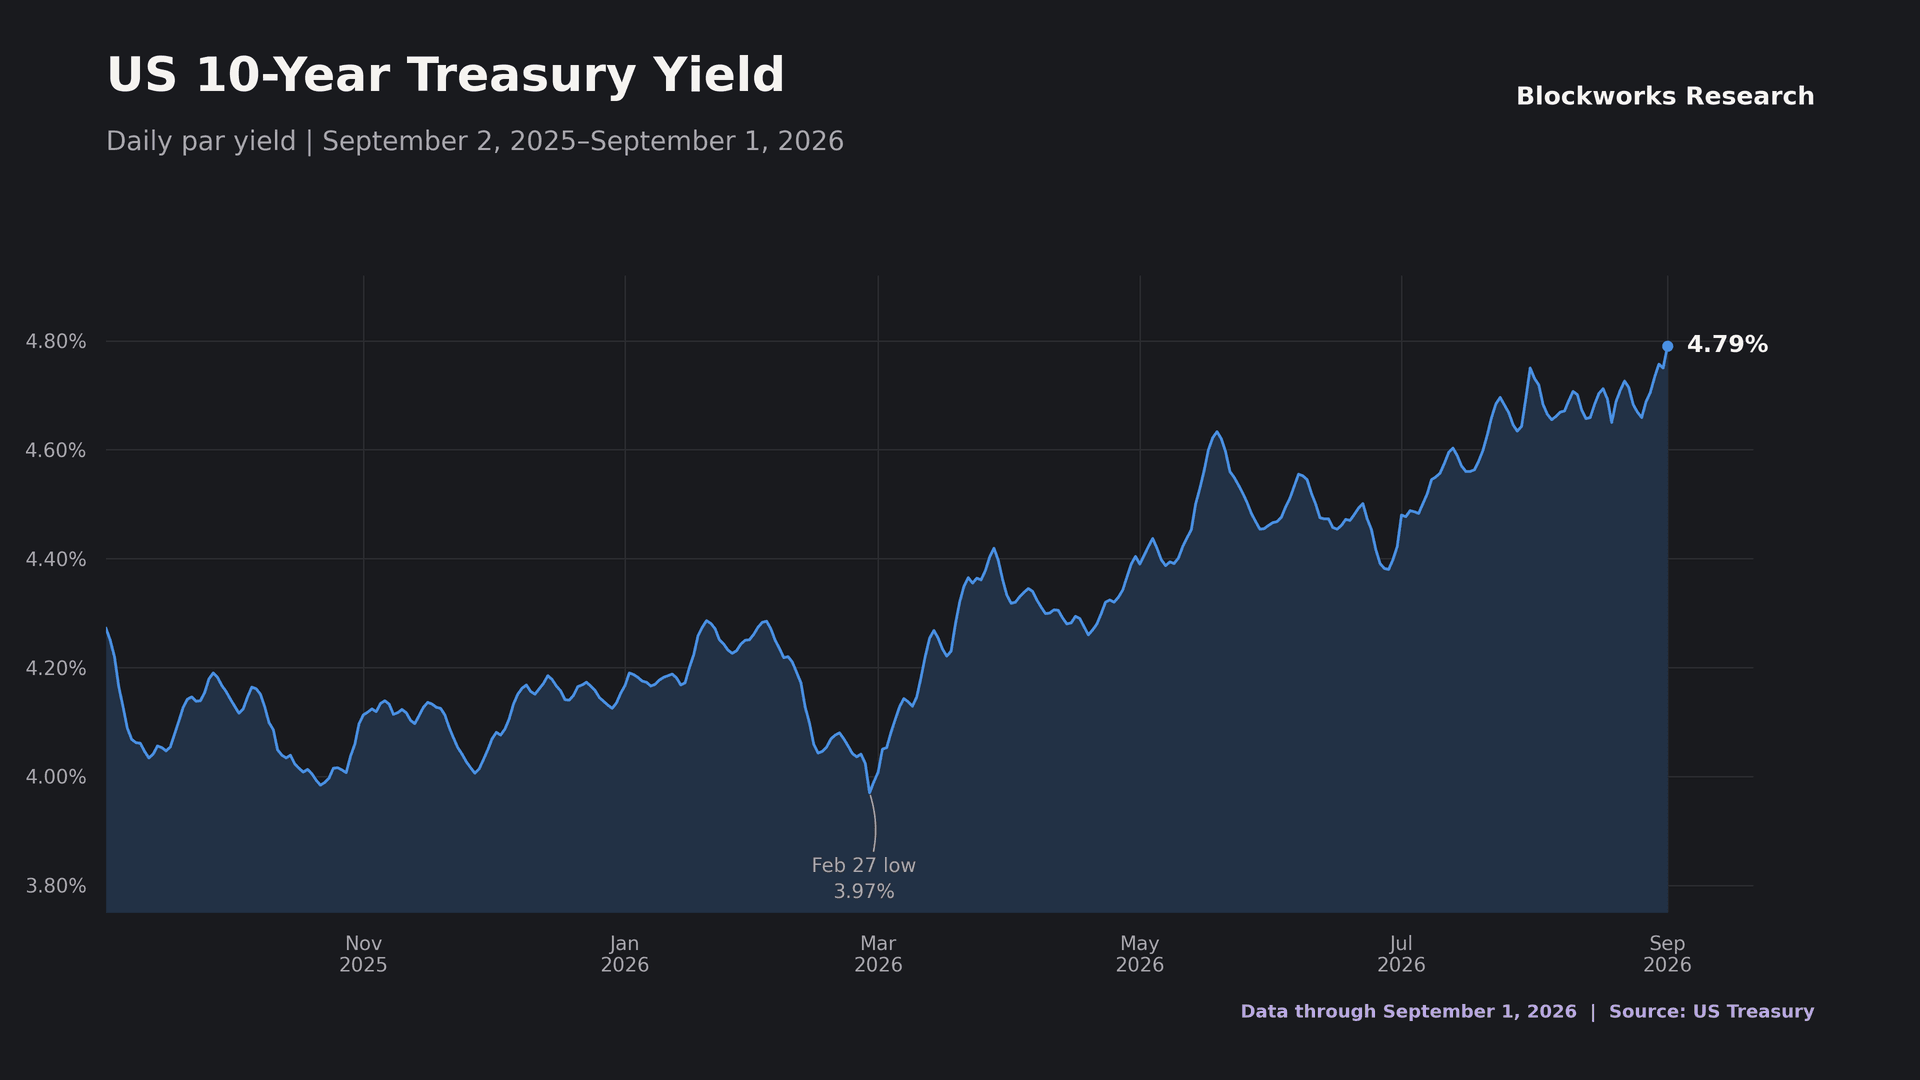
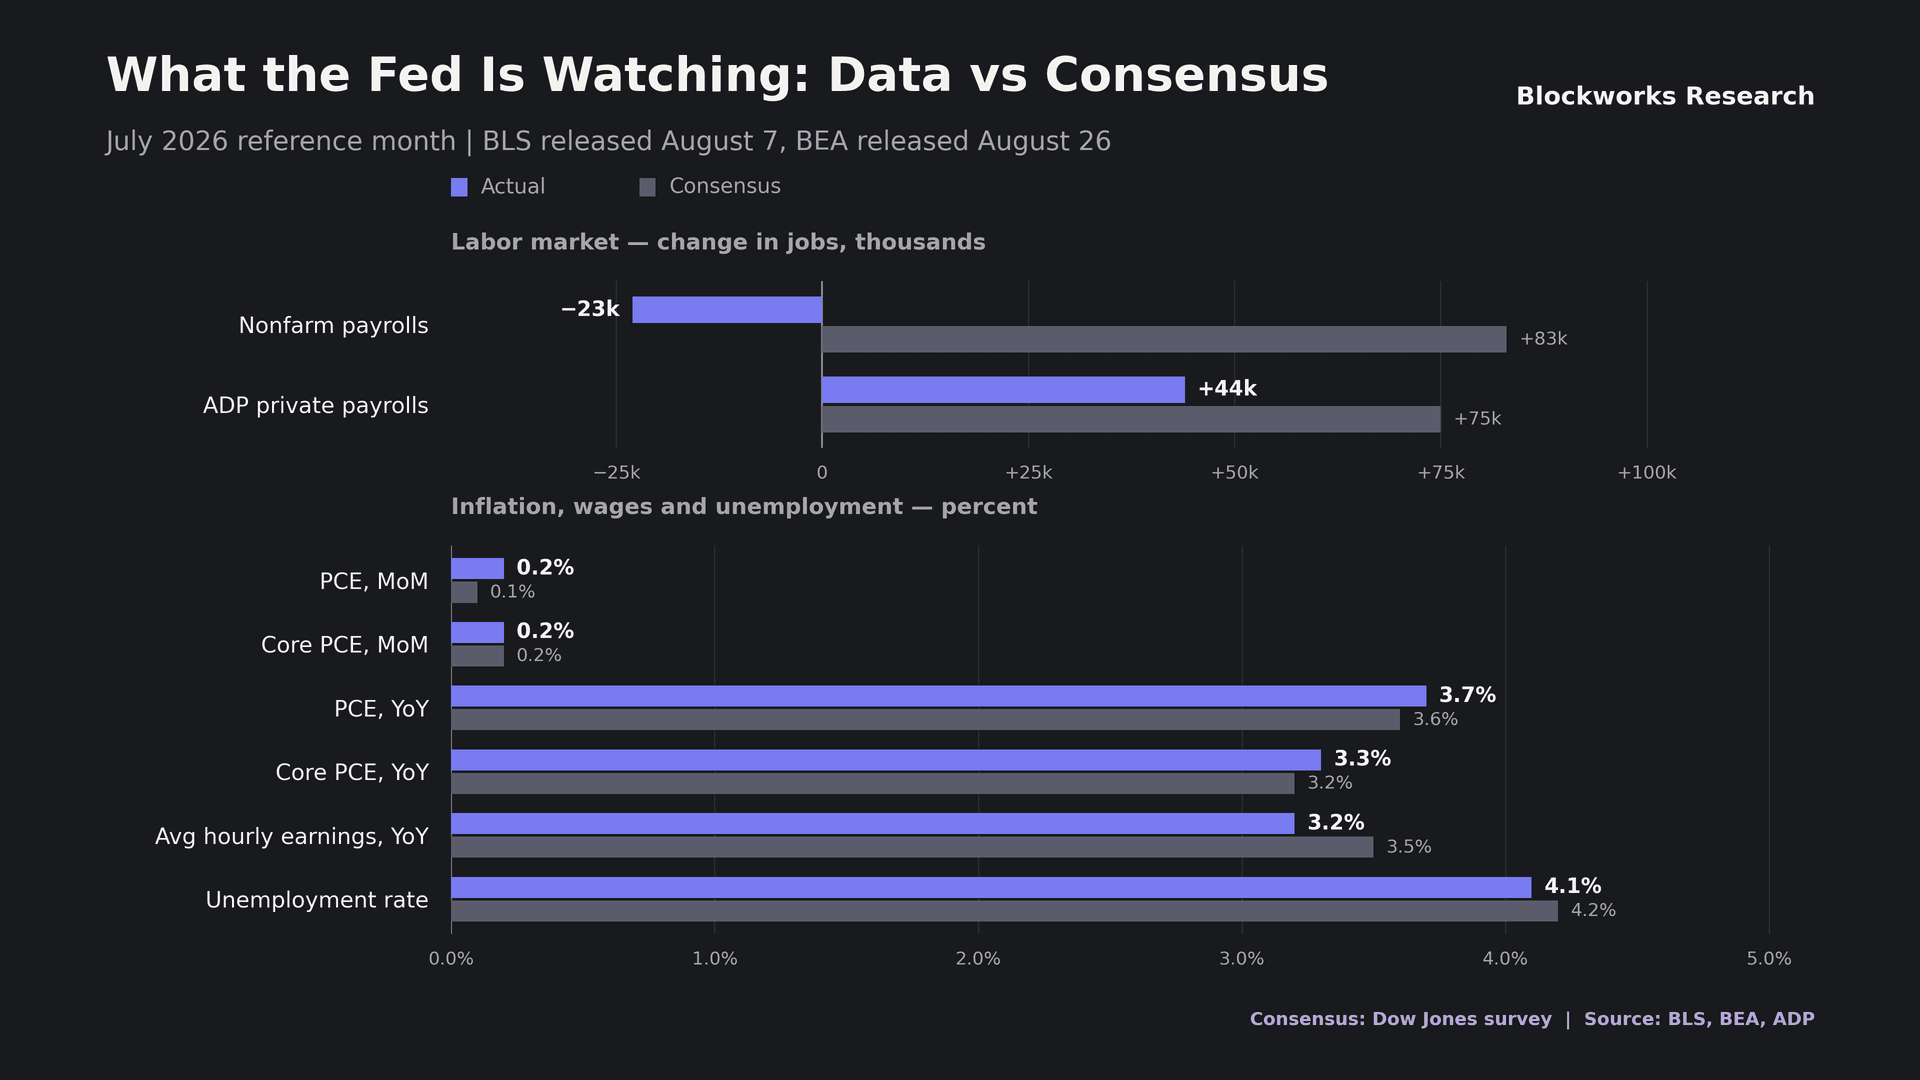
This is happening as the monetary backdrop has grown less favorable over the past month. The US 10-year Treasury yield closed at 4.79% on September 1, up from 4.28% a year earlier and 82bp off its February low of 3.97%. The move is global as rates in Europe are also on the rise and Japan's 10-year yield crossed 3% for the first time in three decades. While Treasury Secretary Scott Bessent argues that higher nominal bond yields reflect accelerating economic growth and fiscal term premiums rather than rising inflation expectations, the sell-off also reflects the need to get deficits under control. The Fed faces conflicting data: labor market momentum is slowing, as evidenced by a shrinking labor force and lower participation, while inflation (Core PCE 3.3% YoY) remains well above target. This disconnect has stalled policy, shifting the debate from whether the Fed will hike rates in September to whether it can justify any action at all.
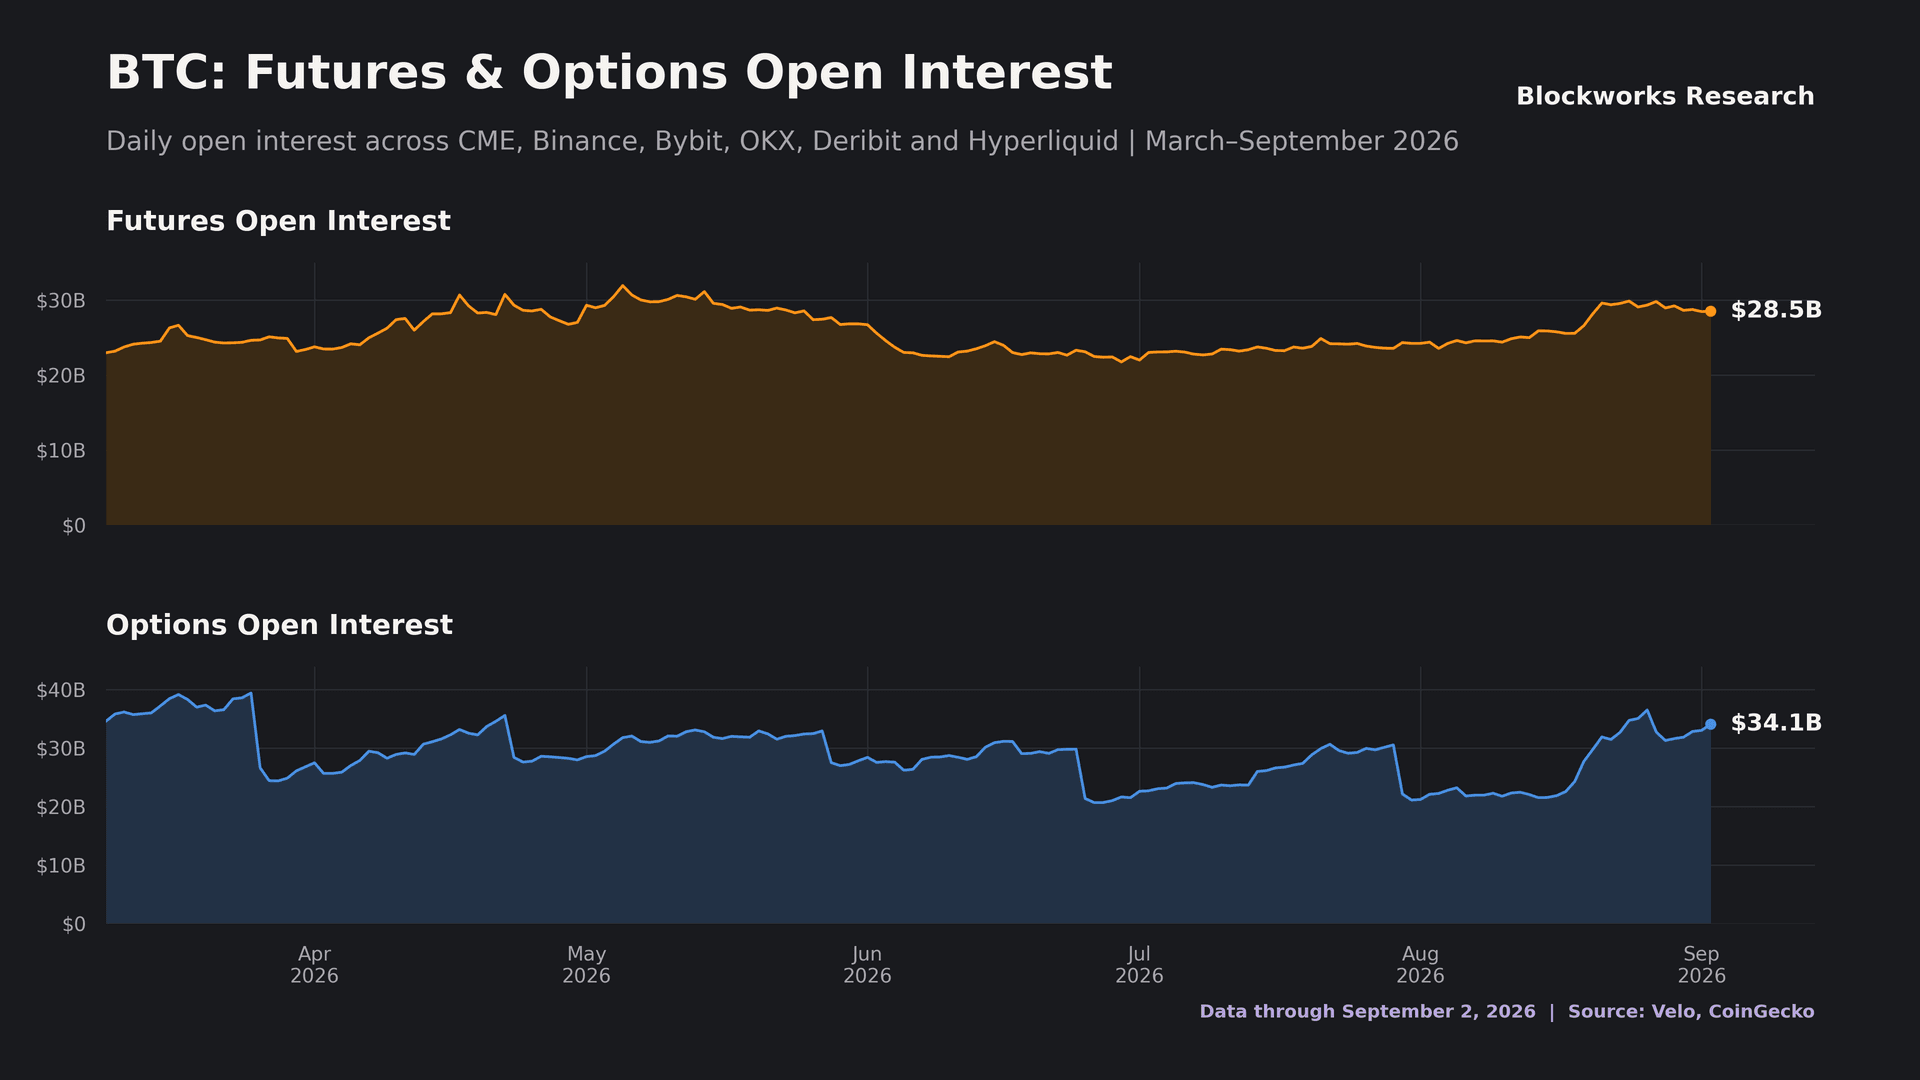
Meanwhile, futures open interest has recovered from its summer lows. Still, it remains below the May peak, and the rebuild lagged BTC's ~25% August gain, meaning the squeeze cleared leverage rather than replacing it, and spot absorbed the grind higher into month-end. Options open interest recovered far more aggressively, retracing most of the year's decline to sit near March highs.
The positive skew on options inverted after the August breakout, with the whole curve pushing negative for the first time in over a year. The front end flipped first and deepest, while the back end has since returned to roughly flat. Demand for upside is real but concentrated in short-dated terms, meaning the market is uncertain about BTC’s medium-term trajectory.

Marc covers Ethereum, Bitcoin and their L2s. Previously led Ethereum and DeFi research at CoinShares.