Bitcoin August 2025 Update

Flows
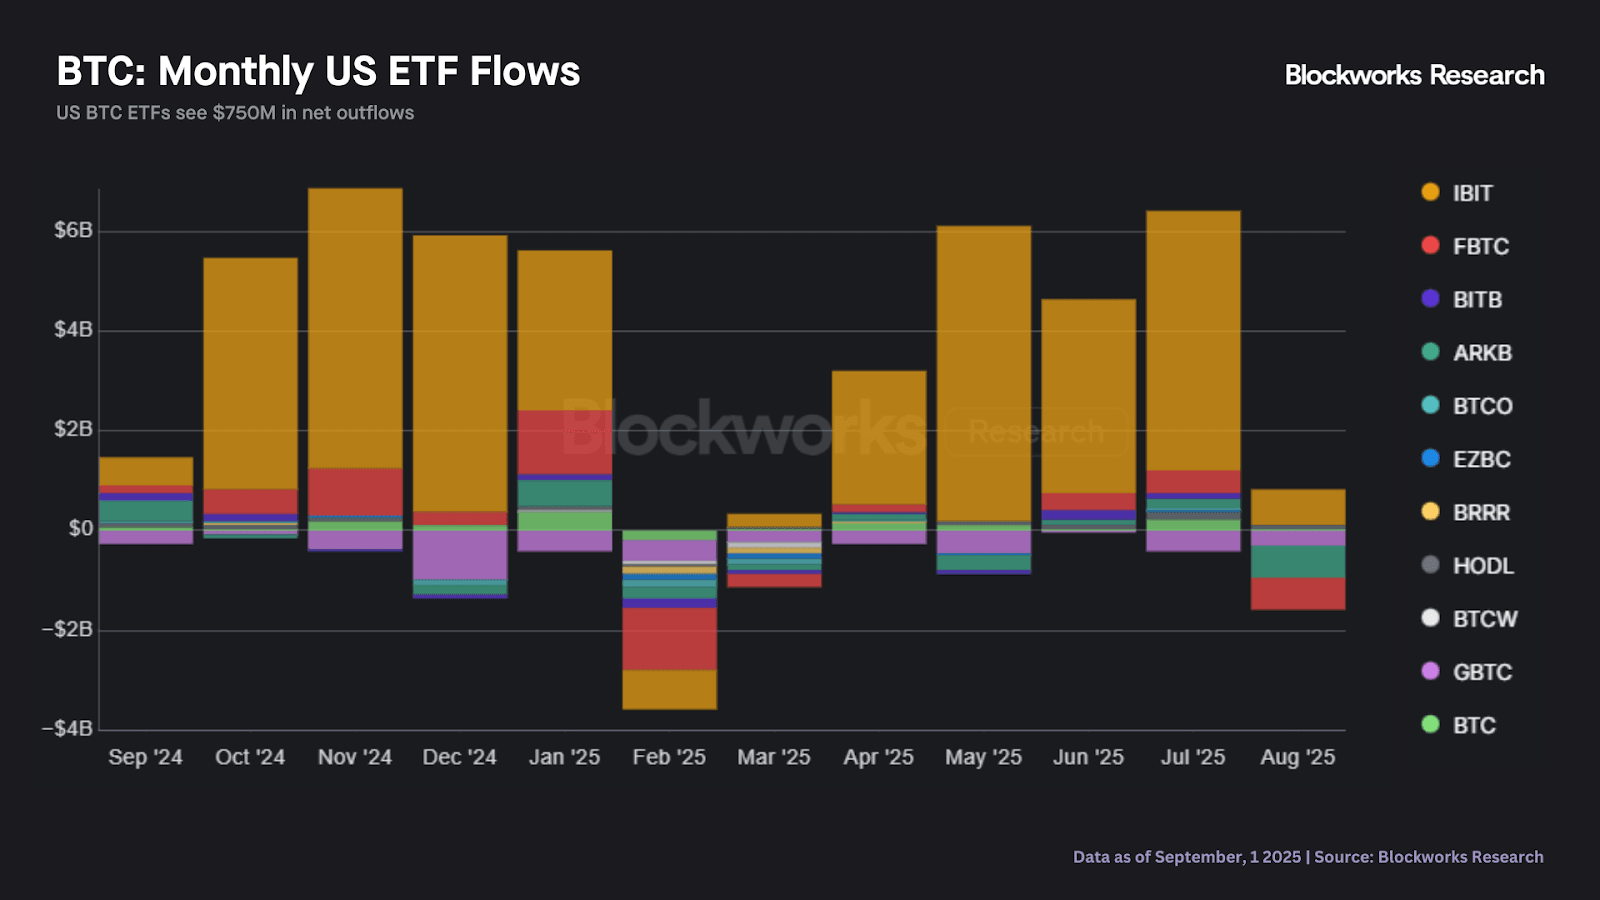
For BTC, the relationship between ETF flows and price movement, regardless of causality, continues to serve as a powerful momentum signal. In June, we highlighted that if ETF flows continued, a new all-time high would be imminent, and this played out in July. In August, we saw a reversal with net outflows of $750M, the third-worst month for ETF flows over the last year. As shown below, despite BlackRock taking in ~$600M of inflows, outflows from Ark (-$660M), Fidelity (-$620M), and Grayscale (-$300M) contributed towards the majority of the sell pressure.
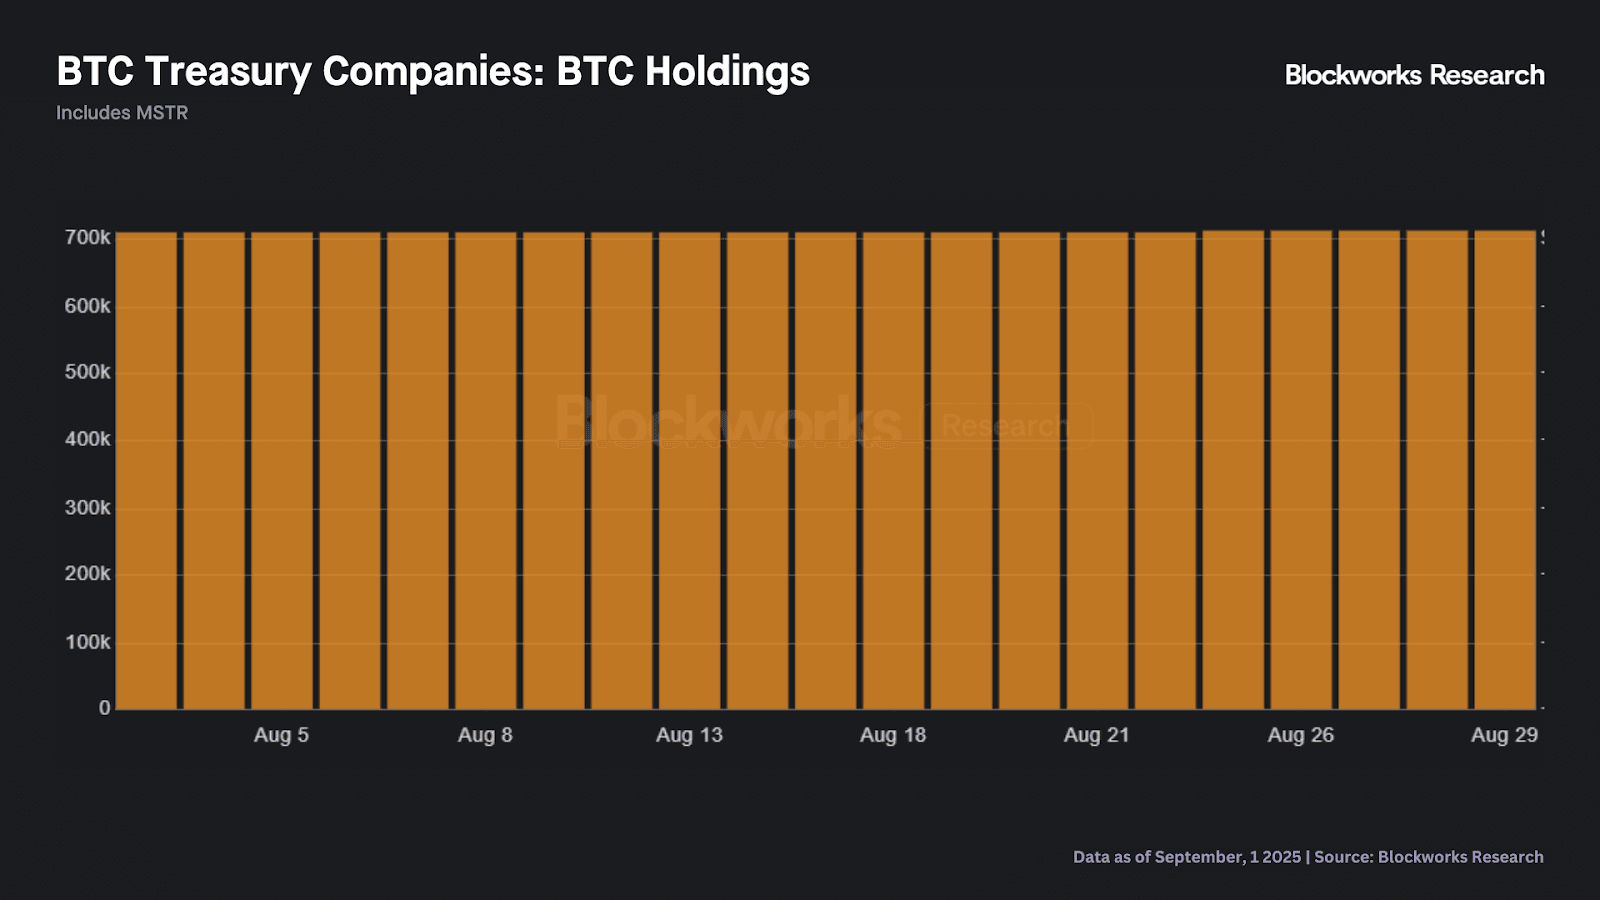
Simultaneously, while not a source of outflows, purchases by Digital Asset Treasuries (DATs) were relatively lackluster for the month of August. Less than 4K BTC were purchased in August, far less than the ~72K BTC purchased in July.
Looking at DAT valuations, while mNAVs continue to compress, there is still a sizable premium among many BTC DATs. This extends the window in which these companies can continue to raise money through at-the-market (ATM) offerings. Additionally, preferred shares can continue to be value accretive as we’ve seen in the case of Strategy (MicroStrategy). Notably, Strategy’s offerings have raised about $5.6B year-to-date, making up for 12% of all US IPO issuance (preferred or common) in 2025.
At the same time, the longer-term trend of declining BTC reserves continues. BTC held on exchanges fell by 2% MoM and 18% YoY (from 2.9M to 2.5M). Additionally, according to Glassnode data, BTC held by OTC desks was ~155K in early August. Below we show the BTC exchange reserves over the last twelve months.

Marc covers Ethereum, Bitcoin and their L2s. Previously led Ethereum and DeFi research at CoinShares.