USD.AI is an onchain credit structuring and funding protocol that finances GPU-backed, stablecoin-denominated loans for real-world AI infrastructure. Collateral is represented through the CALIBER framework, linking onchain representations to offchain legal claims.
The protocol uses a dual-token structure. USDai is designed for liquidity-sensitive capital, while sUSDai is yield-bearing and backed by longer-dated AI infrastructure loans. Redemption dynamics are managed through a queue-based mechanism.
Our valuation model treats execution as the binding constraint by separating pipeline originations from funded originationsusing an explicit funding realization rate to reflect hardware delivery, installation, and settlement latency.
CHIP is the governance and risk-policy token. It governs protocol parameters, treasury and capital policy, and insurance design. CHIP currently does not have a mechanically enforced claim on protocol cash flows, so value accrual is modeled as contingent.
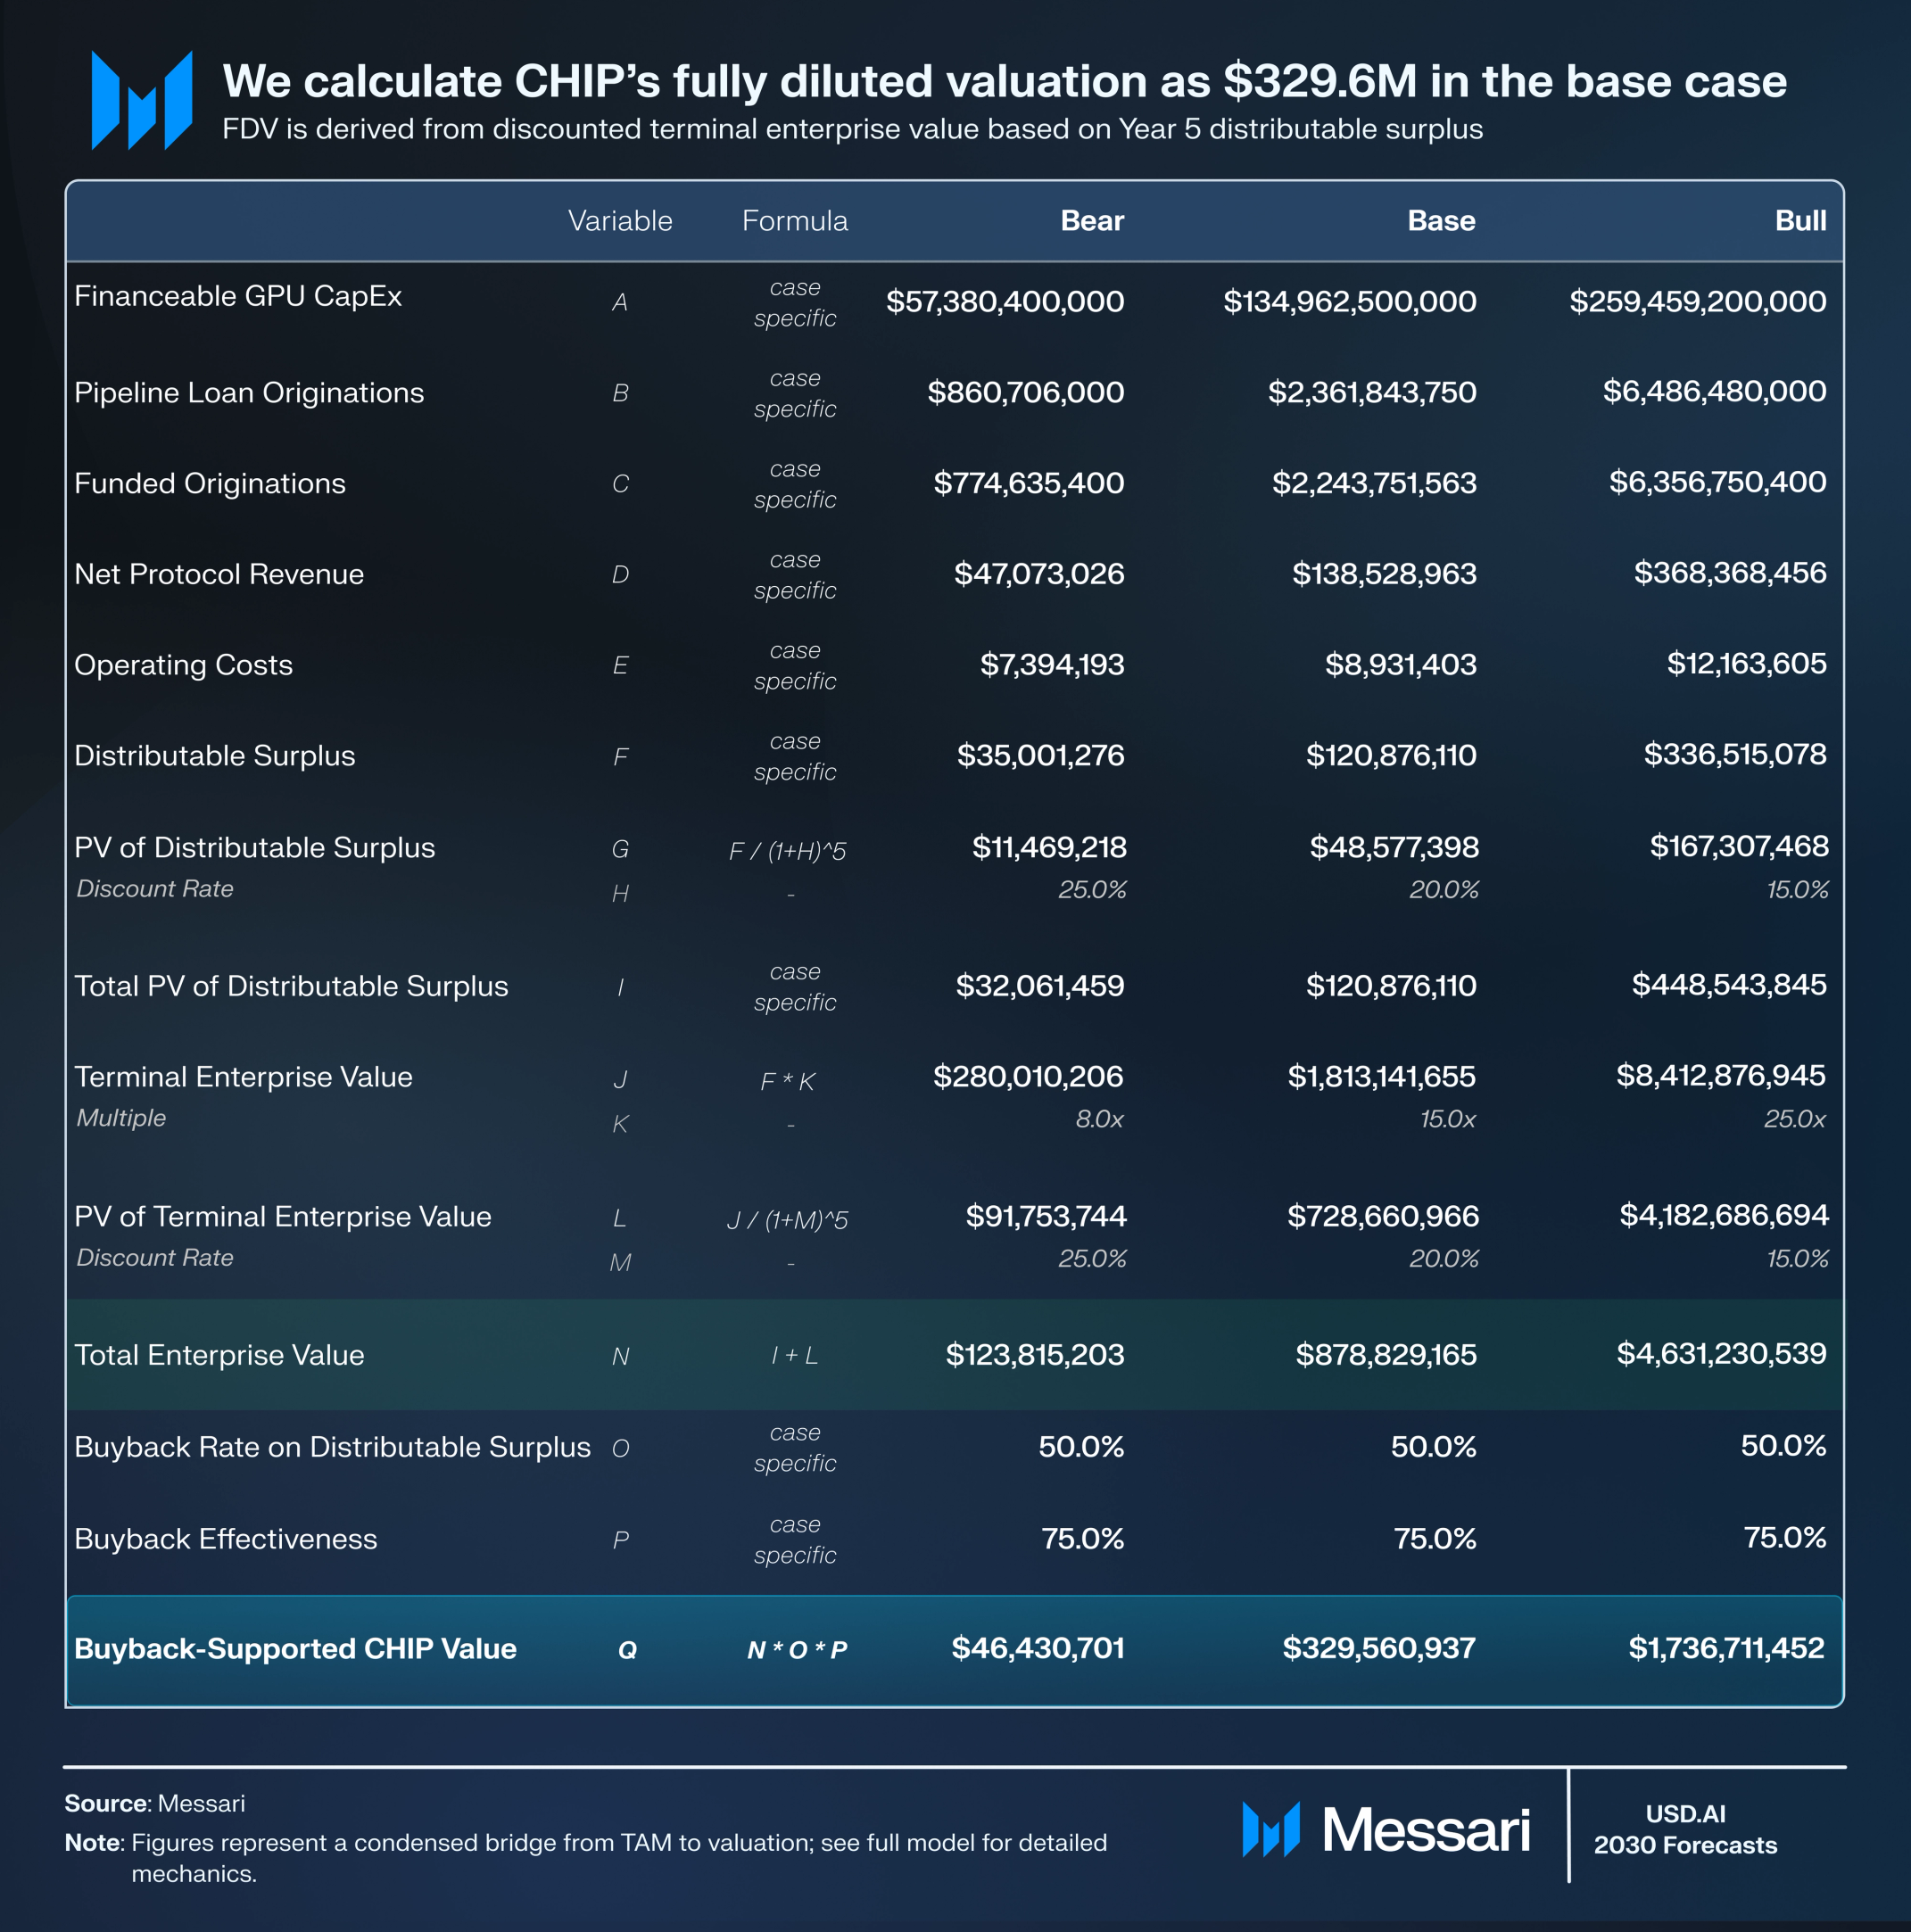
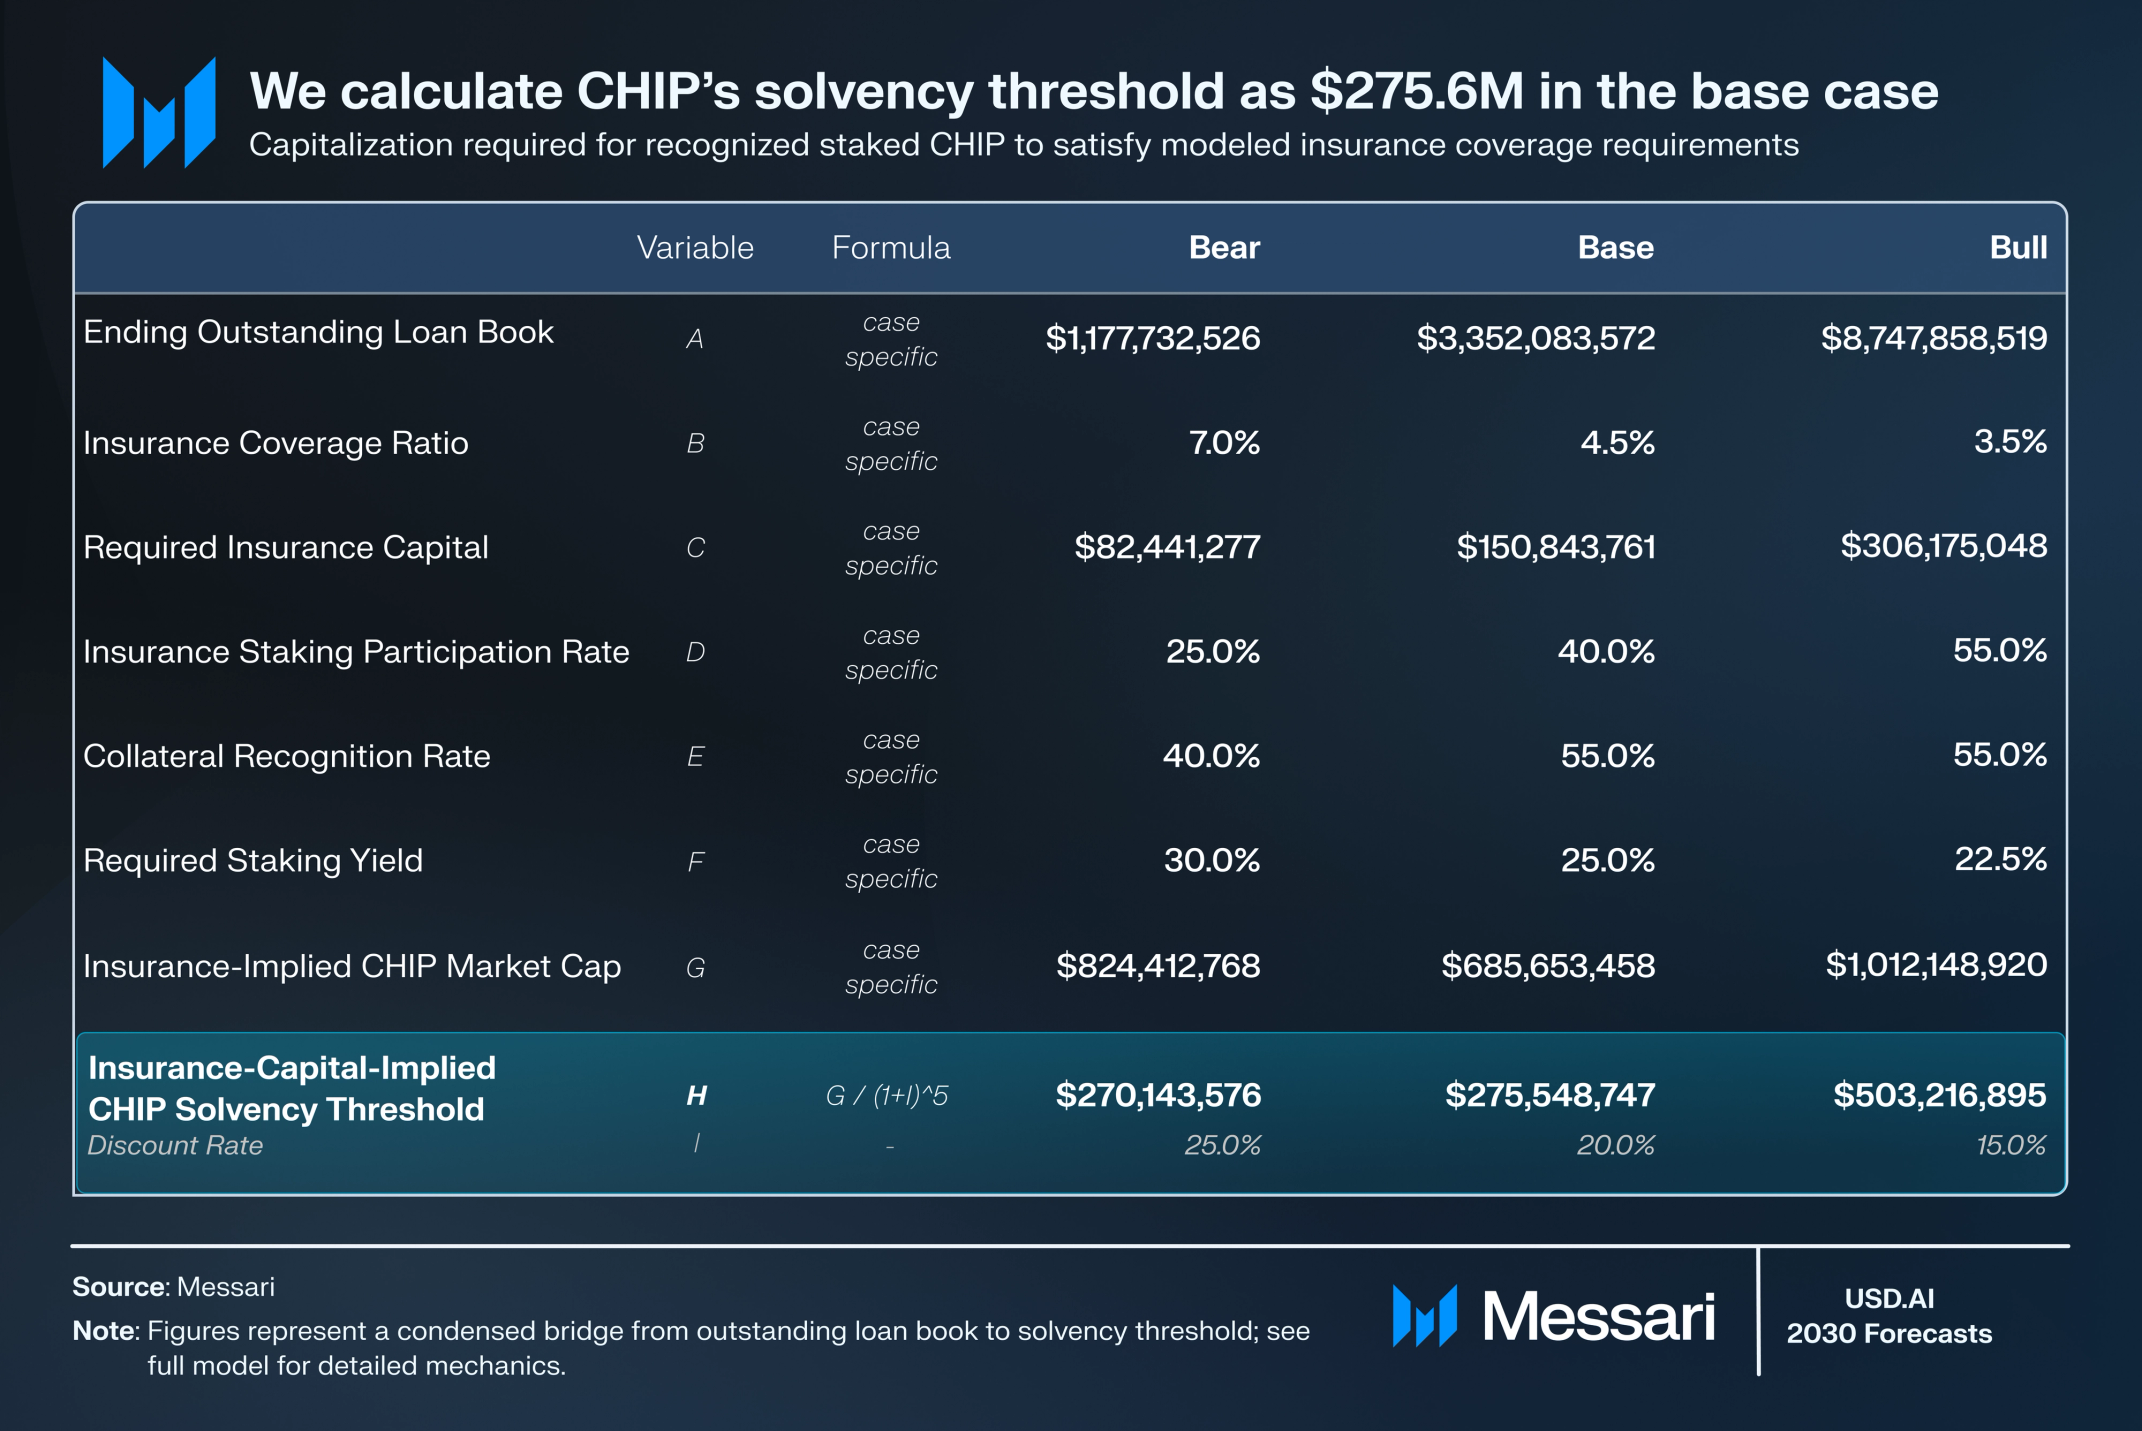
Valuation is anchored by two lenses. (1) A buyback-supported pathway (reflecting governance-directed surplus routing) and (2) an insurance-capital-implied solvency threshold (reflecting capital adequacy constraint). Outputs imply buyback-supported FDVs of $46.4M / $329.6M / $1.74B (bear/base/bull) and insurance-implied solvency thresholds of $270.1M / $275.6M / $503.2M.
Valuation Model:The full valuation model, including assumptions and scenario sensitivities, is available here.
Introduction
USD.AI is an onchain credit protocol financing real-world AI infrastructure. The protocol originates stablecoin-denominated loans backed by GPU hardware and related compute assets, bridging onchain capital with offchain infrastructure deployment.
The protocol issues two core tokens, USDai, a dollar-denominated token used for minting, funding, and redemption flows, and sUSDai, a yield-bearing vault share representing exposure to deployed AI infrastructure loans. This structure separates liquid balances from capital that is committed to longer-term loans. USDai does not directly absorb loan-level credit risk, while sUSDai holders explicitly bear amortization, redemption, and liquidity constraints in exchange for yield. This separation is central to USD.AI’s attempt to align onchain liquidity with real-world, longer-dated credit assets.
USD.AI’s architecture combines DeFi primitives with legal and operational frameworks tailored to real-world assets. CALIBER provides the legal and technical backbone for representing GPU hardware as enforceable onchain collateral. Queue Extractable Value (QEV) is the queue-based redemption mechanism used to manage liquidity against amortizing, illiquid collateral.
The sections that follow evaluate USD.AI as a credit infrastructure protocol and CHIP as a governance and risk policy asset whose value depends on funded origination throughput, capital efficiency, and execution credibility rather than on assumed cash flow rights.
Understanding USD.AI
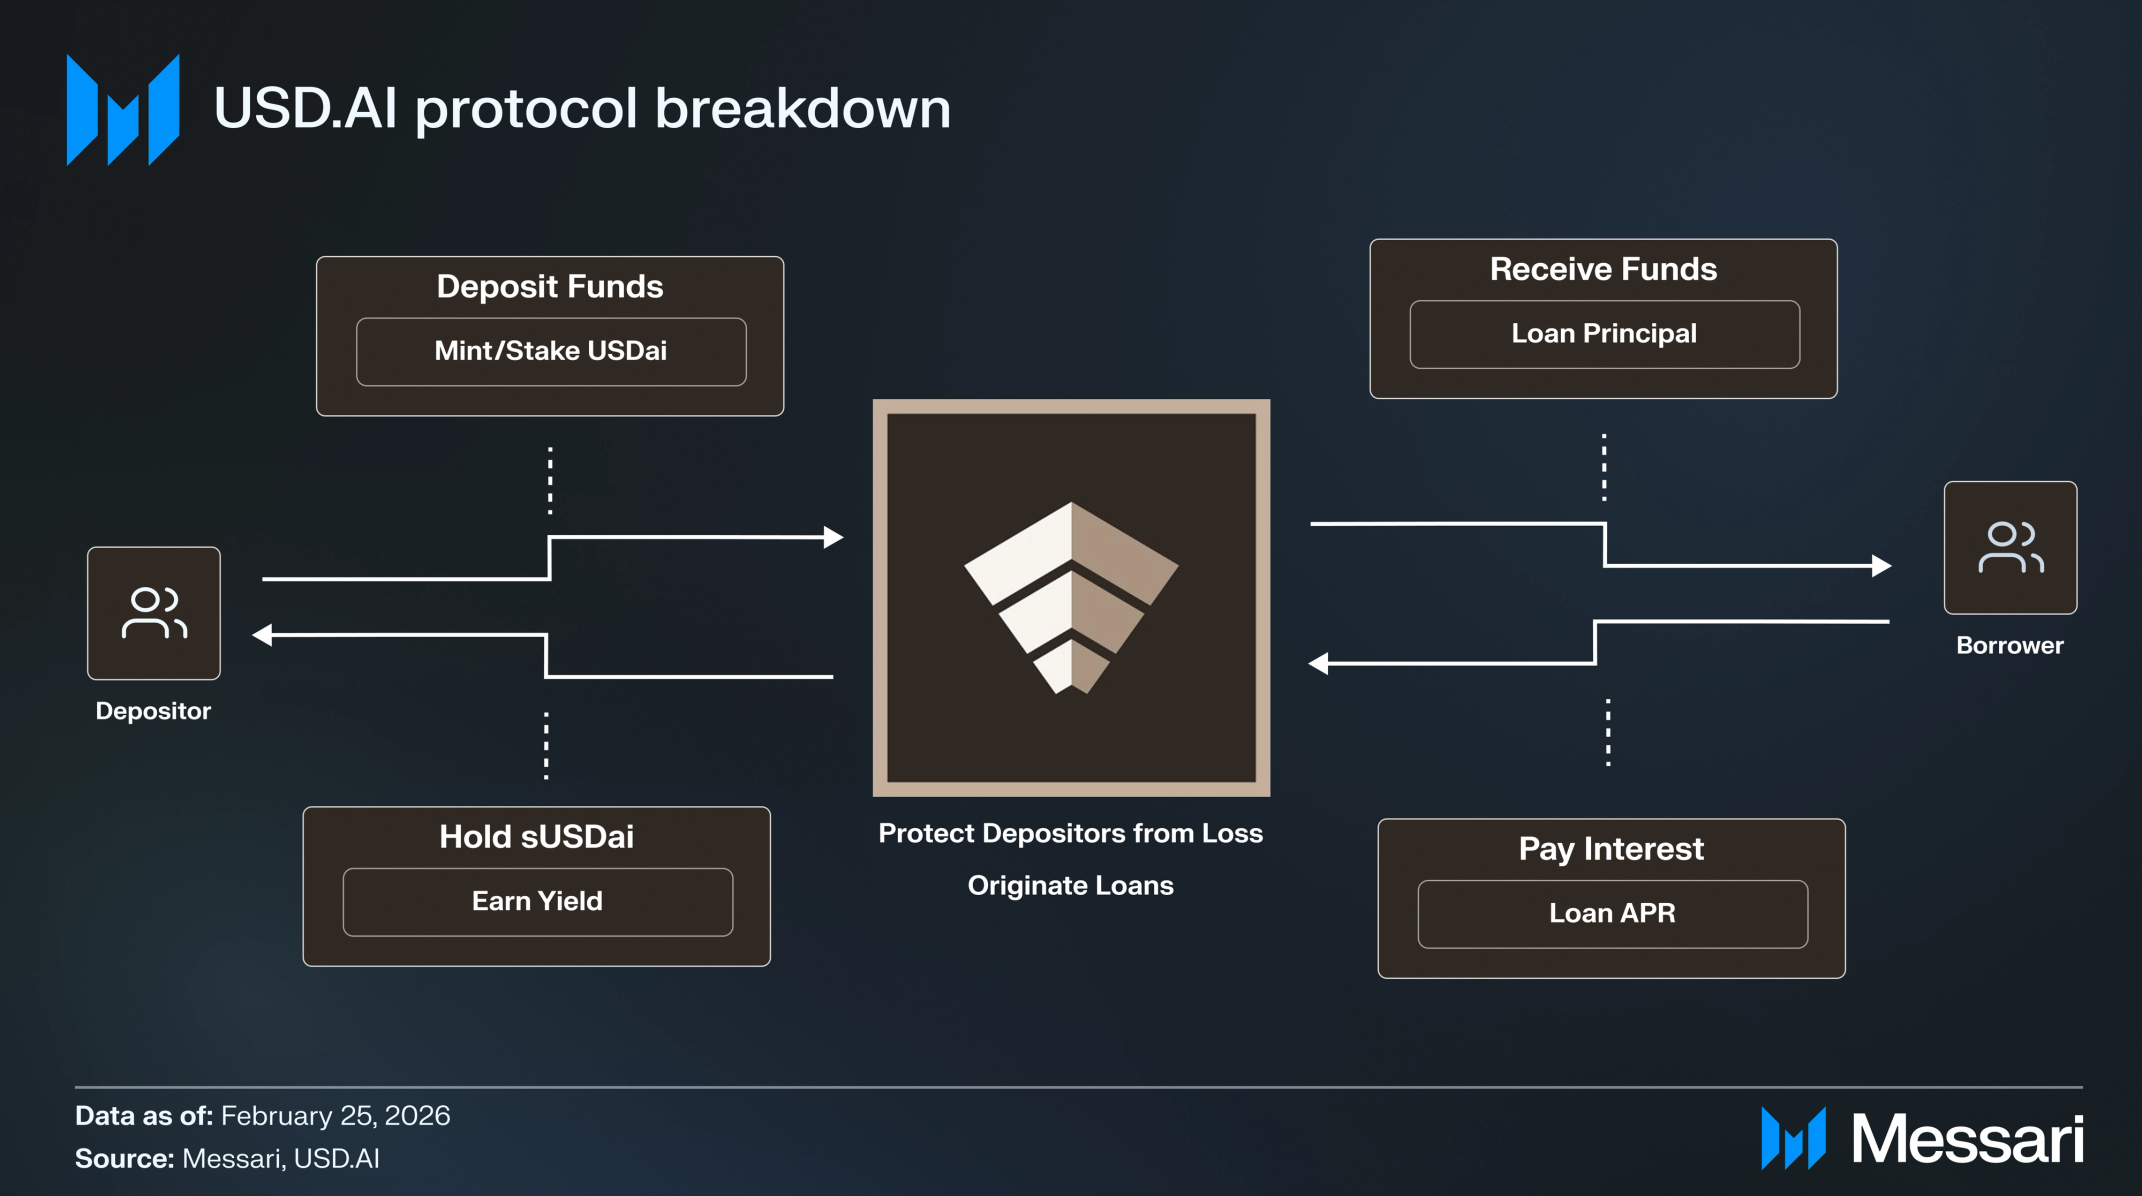
USD.AI sits between borrowers seeking upfront capital to deploy AI compute infrastructure and capital providers seeking dollar-denominated yield. The protocol structures collateral, underwrites risk, coordinates funding, and manages liquidity and redemption mechanics within an onchain framework.
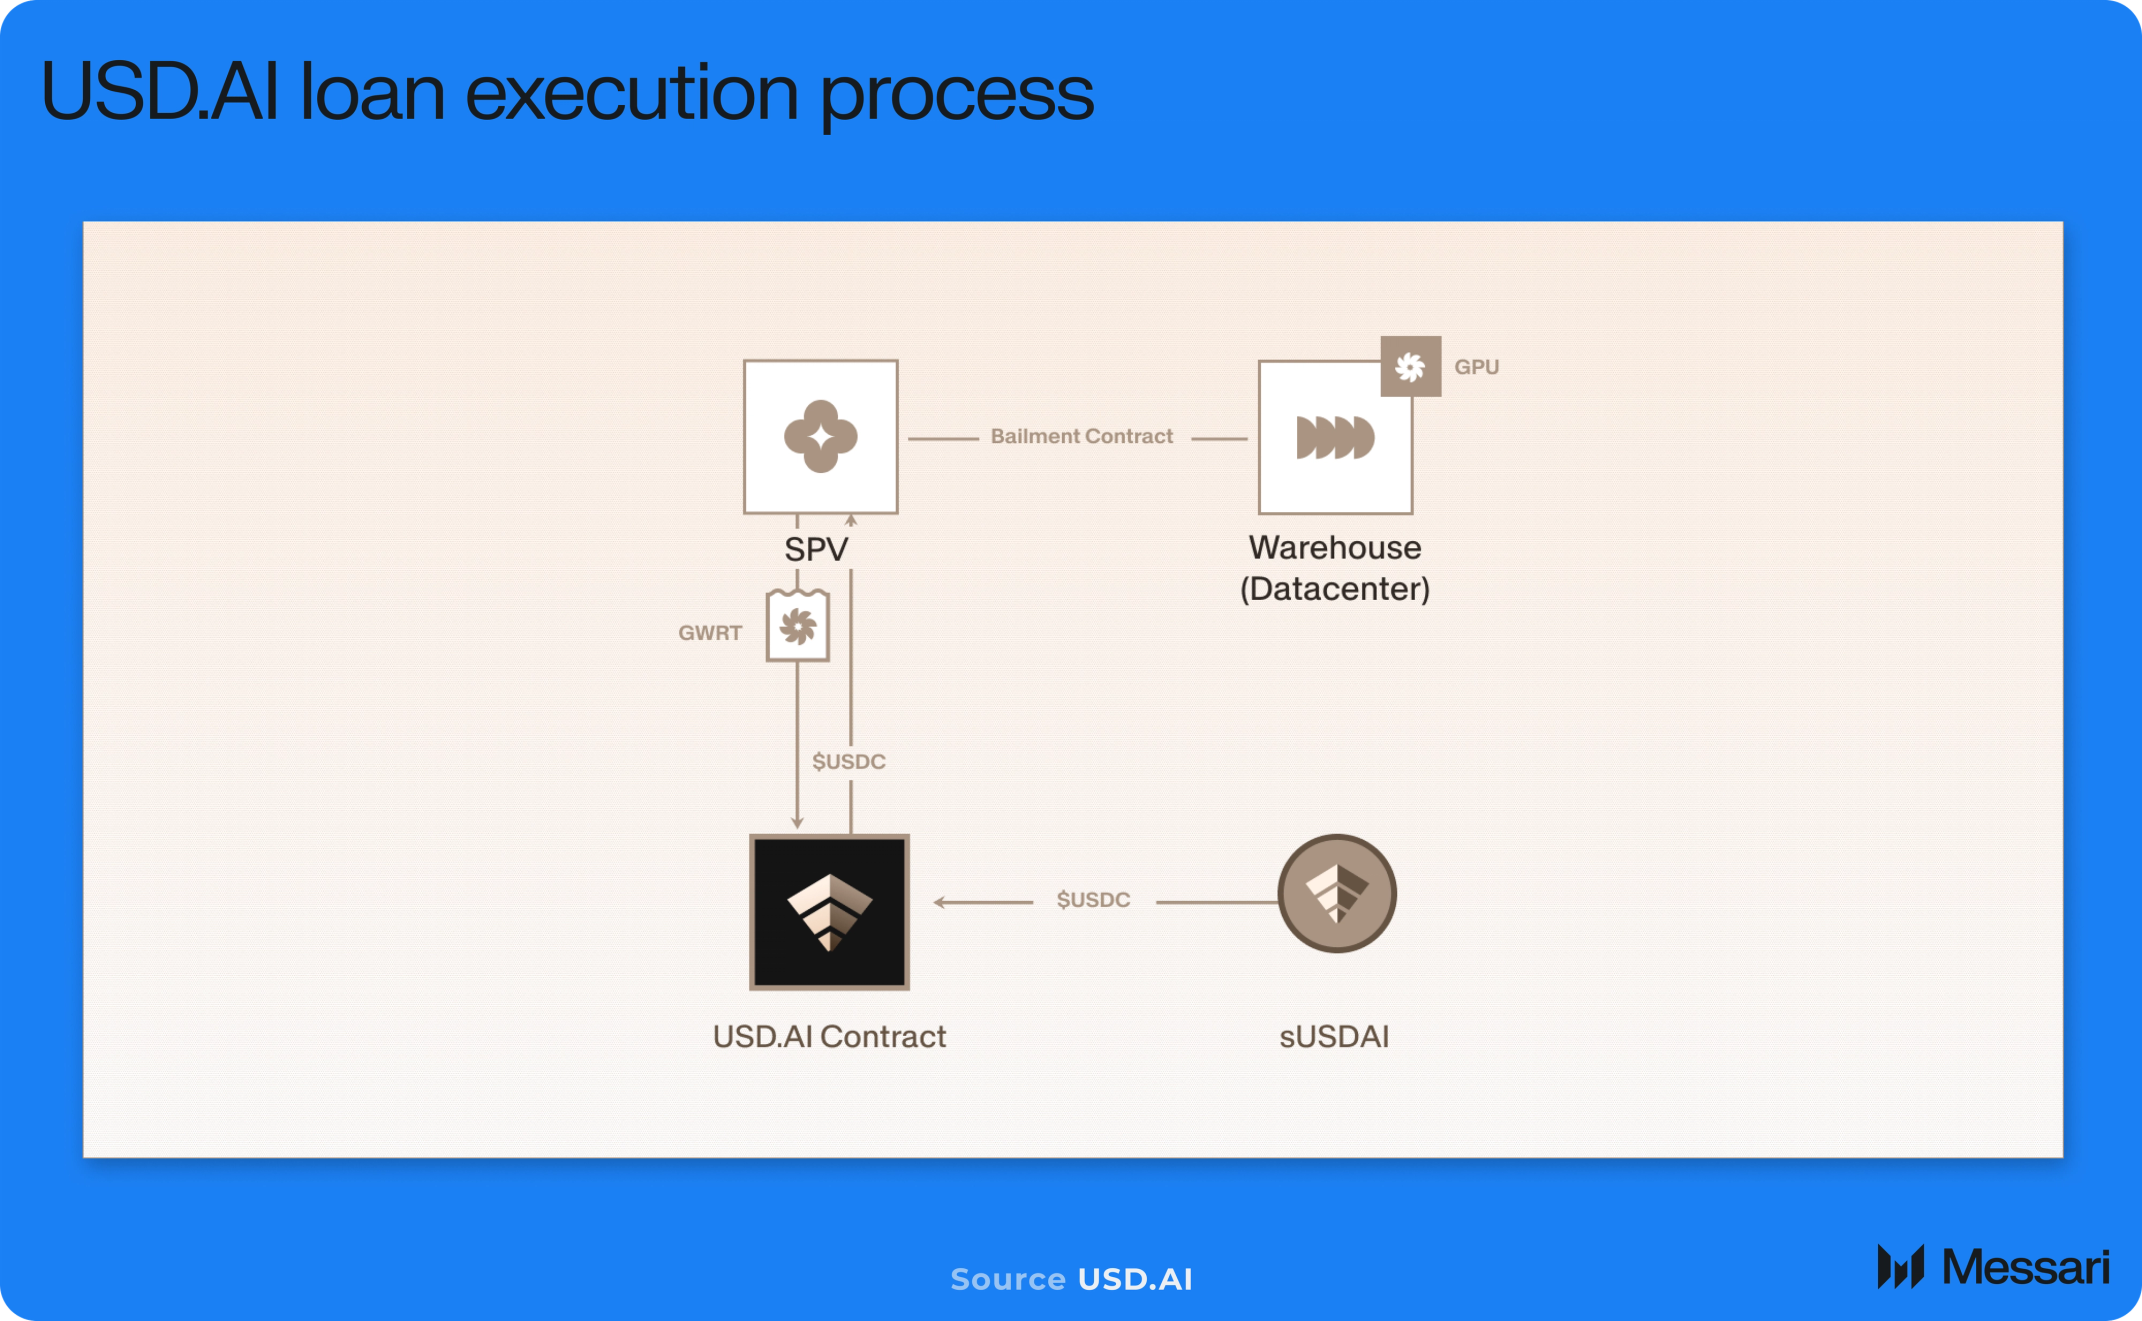
A central component of the architecture is CALIBER, the technical framework used to represent GPU hardware as enforceable collateral by linking onchain representations to offchain legal claims. The intent is to make physical compute assets eligible for pooled, standardized credit rather than structuring each loan as a bespoke private arrangement.
Once collateral is verified and approved, USD.AI originates stablecoin-denominated loans backed by that hardware. Borrower onboarding, underwriting, and legal structuring occur offchain, while loan balances, repayments, and related economic flows are recorded and managed onchain.
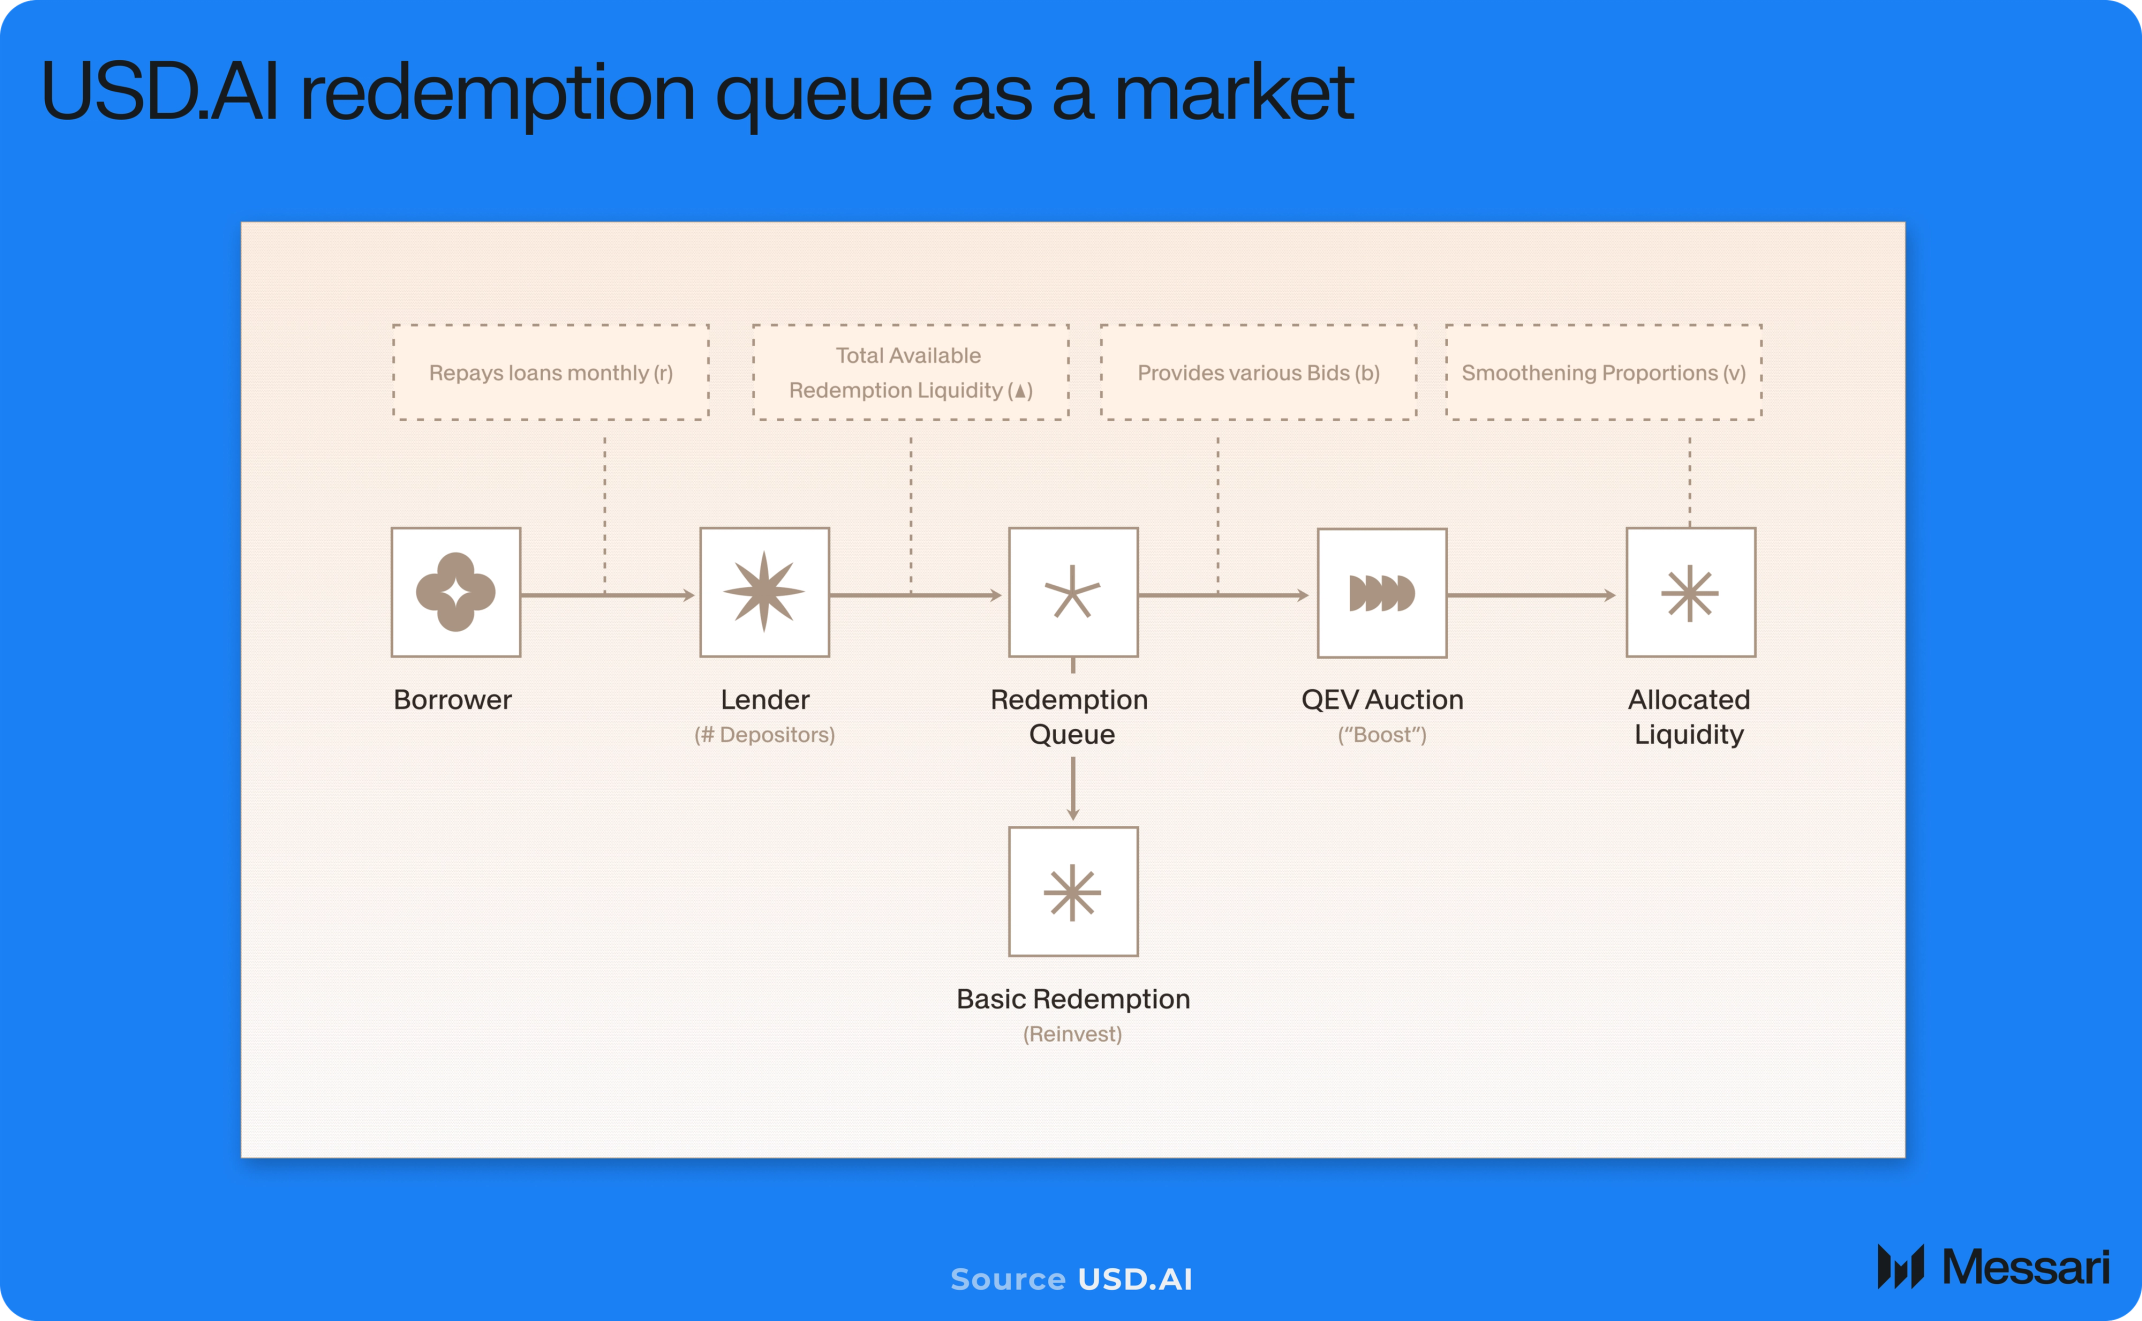
Infrastructure-backed lending inherently creates a structural liquidity mismatch. Underlying loans amortize over multi-year time horizons, while capital providers may seek redemption sooner. USD.AI addresses this through queue-based redemptions for sUSDai. When liquidity is constrained, Queue Extractable Value (QEV) prices redemption priority within the queue rather than relying on forced asset sales or fixed liquidity buffers.
Under this design, redemptions are processed sequentially rather than instantaneously. If demand exceeds immediately available liquidity, participants may pay for priority, allowing time preference to be expressed through market pricing. Liquidity constraints are made explicit at the protocol level and aligned with the amortizing profile of the underlying loan book.
USD.AI’s risk architecture incorporates third-party collateral value protection through Barker, an institutional valuation and risk-transfer platform. For GPU-backed loans originated through the protocol, Barker provides independent collateral valuations and issues a contractual warranty on those valuations. The warranty is fully reinsured by Munich Re through its aiSure performance guarantee.
Coverage is structured at 80% of Barker’s independently assessed collateral valuation. Because USD.AI caps loans at a maximum 80% loan-to-value (LTV) ratio, the structure is designed to provide coverage equal to the full outstanding principal amount at origination under standard underwriting assumptions.
If liquidation proceeds fall below the covered valuation threshold, the shortfall is contractually payable to the protocol, subject to the governing policy terms, conditions, and exclusions. For example, if collateral is valued at $10.0 million and a loan is originated at $8.0 million (80% LTV), coverage is set at $8.0 million. If liquidation yields $7.2 million net, the insured structure is designed to cover the $0.8 million difference, bringing total recovery to the covered threshold.
The premium for this coverage is paid by the protocol and embedded in loan economics, reducing net yield available to sUSDai holders. Relative to the prior FiLo tranche structure, the insurance-backed model is designed to be materially more capital-efficient. Coverage costs decline from the junior tranche model to the Barker warranty structure, while eliminating the need to fund and compensate a dedicated first-loss tranche.
This shift reduces structural capital intensity and redirects economics that would previously have accrued to junior tranche holders back toward sUSDai. While the structure materially mitigates principal loss severity under defined conditions, it does not eliminate valuation model risk, claims-processing risk, liquidity timing risk, contractual exclusions, or extreme market dislocation risk.
CHIP Tokenomics
CHIP is the governance and utility token of the USD.AI protocol. It governs protocol standards, risk parameters, fee surfaces and fee routing, interest rate controls, and capital policy. While protocol fees may be directed toward buybacks or staking rewards, there is currently not a mandatory or mechanically enforced claim on protocol cash flows.
CHIP’s utility can be grouped into three primary domains:
Governance and protocol control CHIP holders govern the USD.AI DAO and set high-level parameters that shape credit formation and system risk. These include collateral eligibility standards, underwriting thresholds, interest rate controls, liquidity and redemption settings, insurance coverage requirements, and treasury policy. Through these levers, governance determines how the protocol balances origination growth, capital efficiency, and systemic resilience.
Revenue governance and capital allocation CHIP governs the protocol’s fee surfaces, including origination and servicing fees, net interest margin, administrative fees, and liquidity-related fees. Governance also determines how collected fees are routed, including potential allocations to operating expenses, reinvestment, staking incentives, or token buybacks. Because fee routing is governed rather than hard-coded, surplus capture by tokenholders is policy-dependent rather than automatic.
Staking module and risk backstop CHIP can be staked into a protocol-defined staking module designed to support system safety and alignment. Stakers receive rewards sourced from protocol fees or designated incentives and accept predefined lock and slashing conditions tied to objective shortfall events. To the extent that staked CHIP is recognized as backstop capital within the insurance framework, token value becomes partially linked to coverage requirements, staking participation, and collateral recognition parameters.
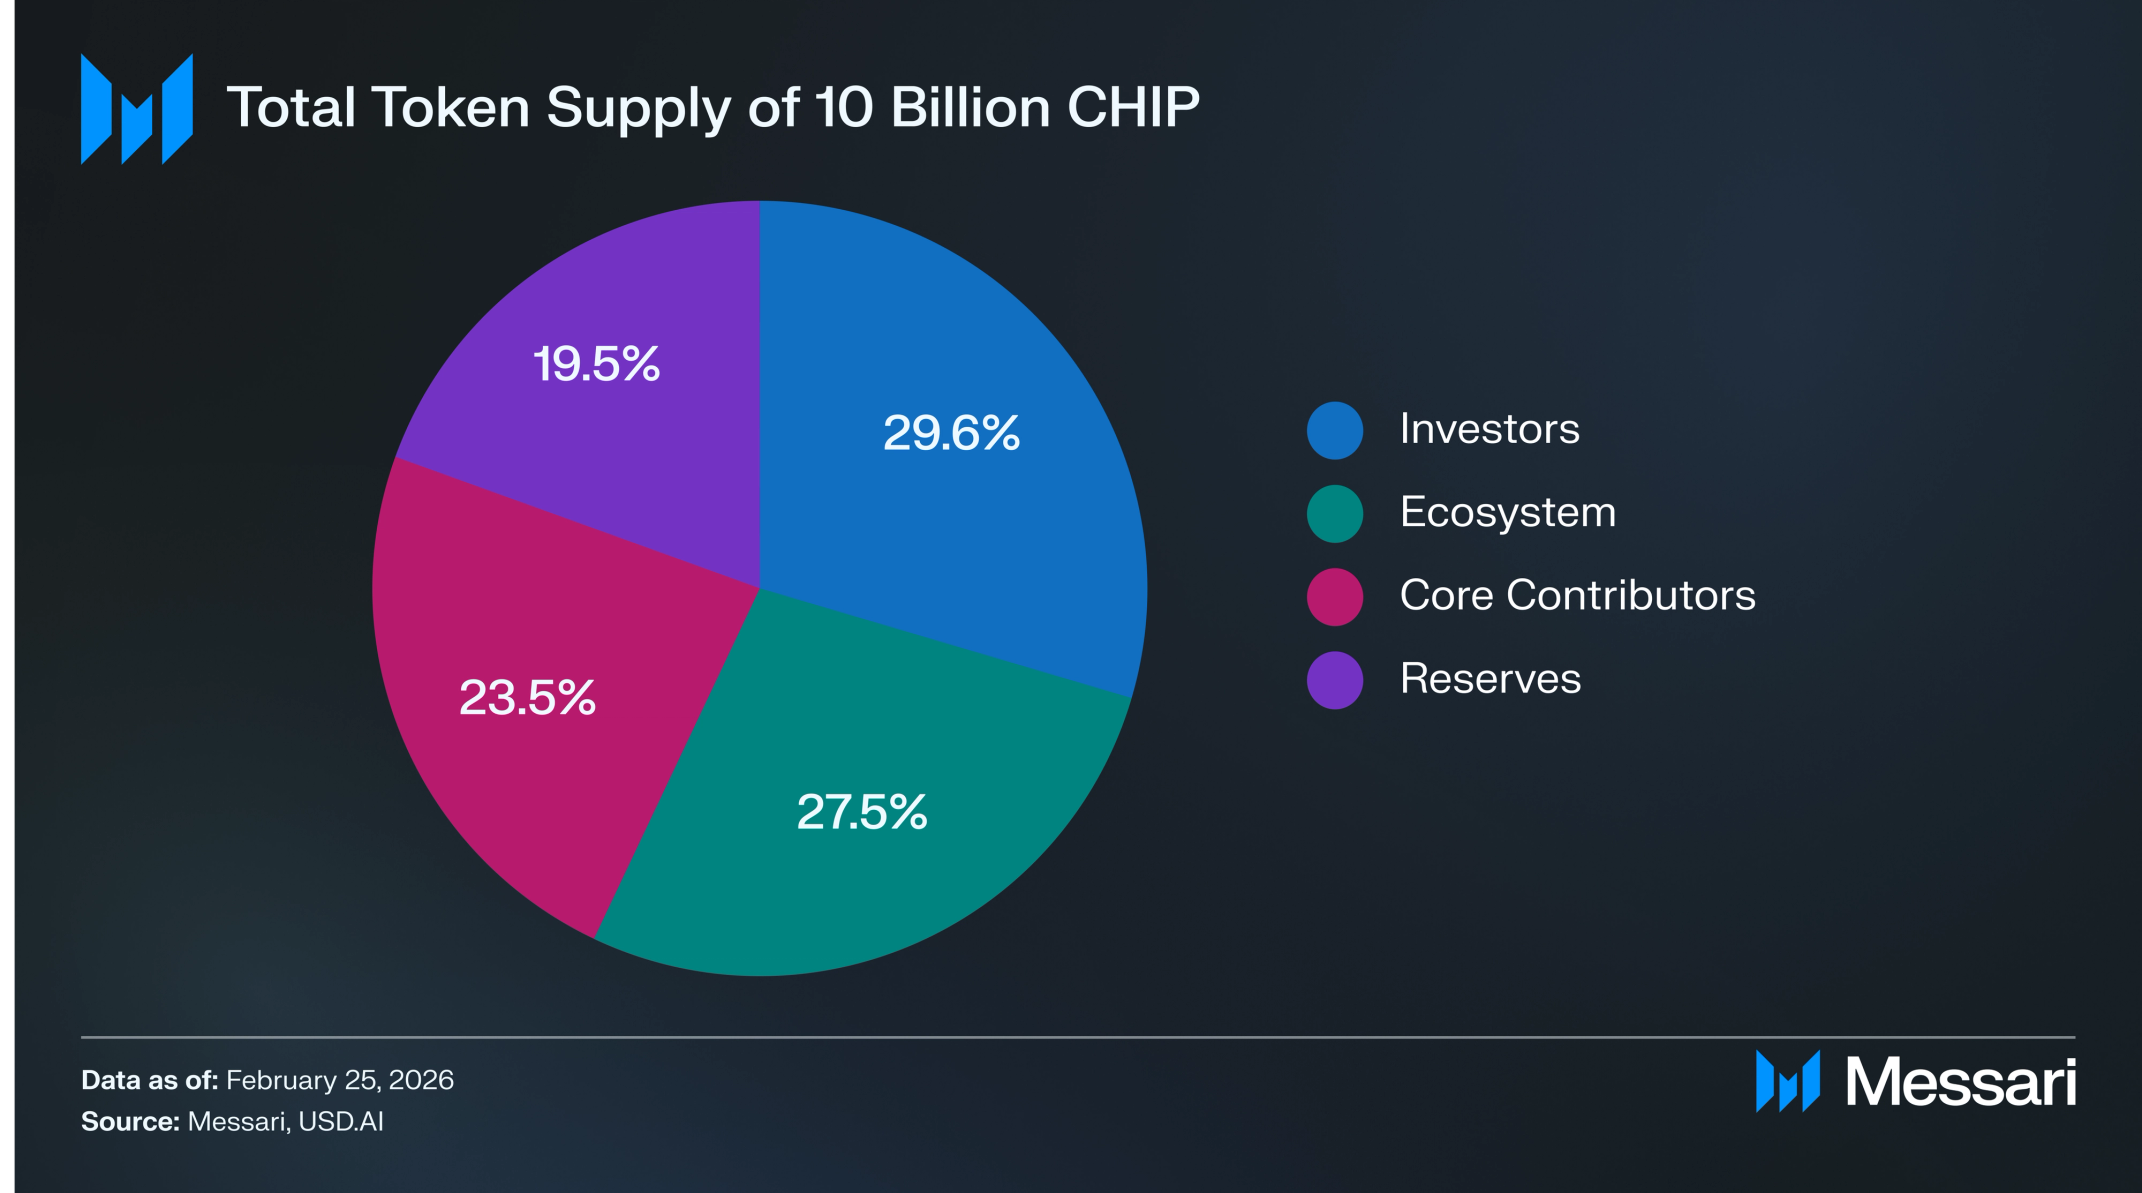
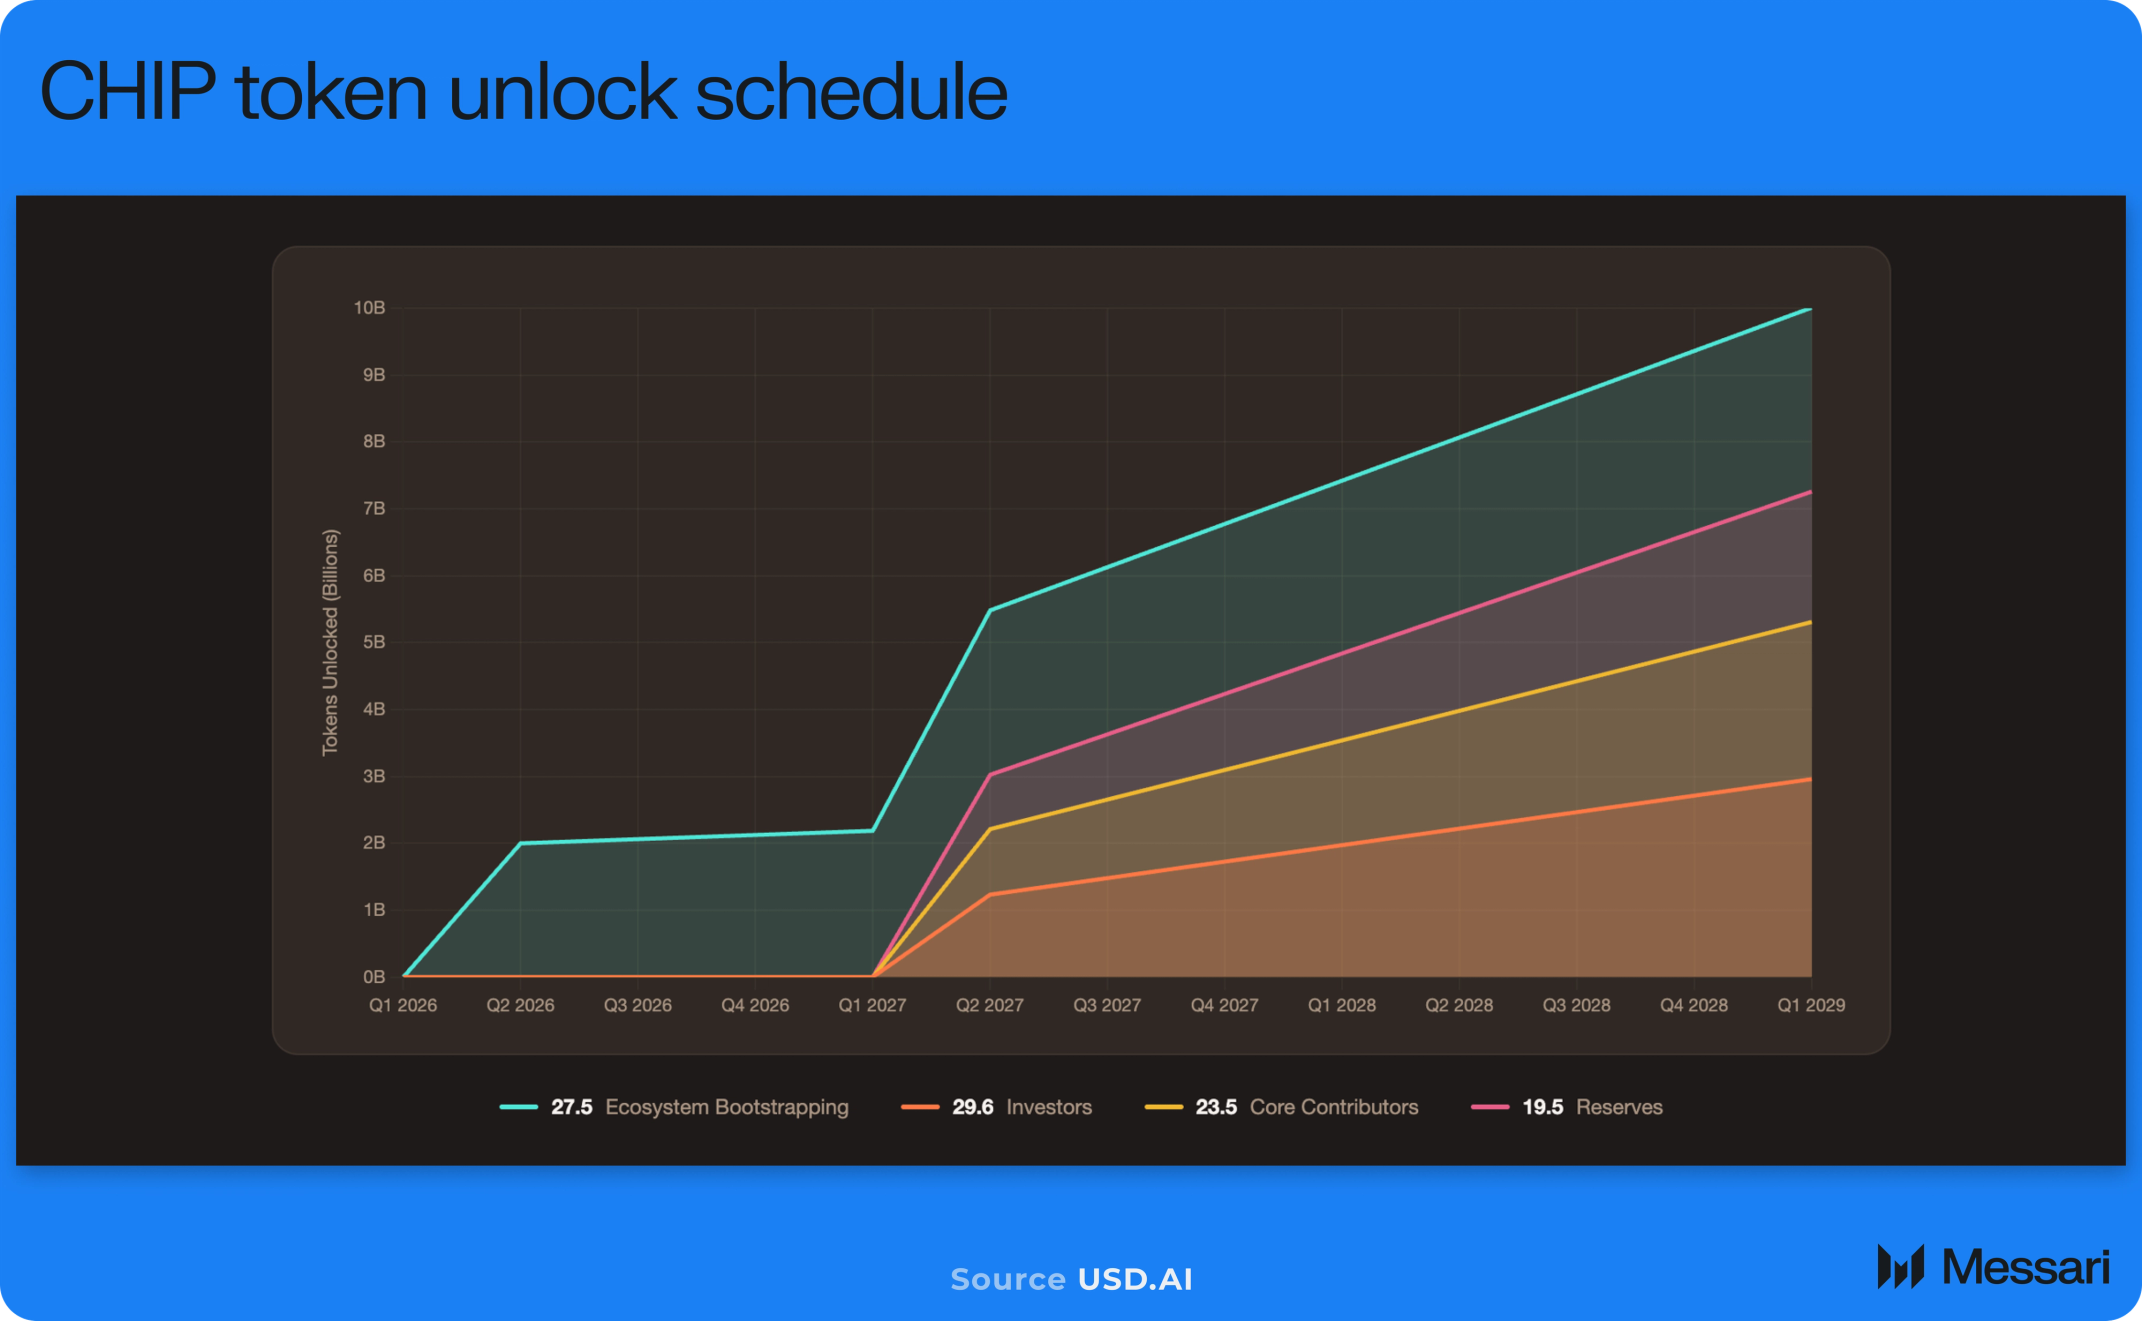
Vesting schedules and lockups: Investor and core contributor allocations follow the same schedule – 0% unlocked before month 12, 33% unlocked at month 12, and the remaining 67% unlocked in equal monthly installments over the following 24 months. Ecosystem and reserve allocations are subject to governance-directed deployment.
Valuation Framework
CHIP does not have an automatic claim on protocol cash flows. Governance controls fee routing and capital policy, but surplus allocation to tokenholders is discretionary rather than mechanically enforced.
Accordingly, we do not apply a traditional equity-style discounted cash flow that assumes durable and enforceable surplus routing. Instead, our valuation begins with observable protocol economics, such as pipeline originations, fee generation, and cost structure, and then explicitly models the conditions under which those economics may translate into tokenholder value.
We model CHIP using two complementary lenses:
Buyback-supported value CHIP is modeled as a governance asset that may capture surplus through discretionary buybacks. Buybacks are contingent on a DAO-enabled routing decision and are therefore modeled as a scenario-based policy variable rather than a guaranteed entitlement.
Insurance-capital-implied solvency threshold CHIP is modeled as backstop capital within the insurance module. This lens estimates the fully diluted valuation required for staked and recognized CHIP to satisfy stated coverage requirements under explicit assumptions about exposure, coverage ratios, staking participation, collateral recognition, and required staking yield. The output represents a solvency-consistent capitalization level, not a price target.
Together, these lenses create a coherent bridge from protocol activity to token value without imposing enforceable cash flow rights where none are encoded.
USD.AI’s primary execution risk is converting the pipeline into funded originations. The model therefore distinguishes between:
Pipeline loan originations: sales and underwriting throughput.
Funding realization rate: the latency-adjusted conversion rate from pipeline to funded volume.
Funded originations: the economically relevant volume that drives fee revenue and fee-funded incentives.
This separation prevents the pipeline from being treated as revenue and concentrates scenario differentiation on execution rather than demand.
Protocol revenue is modeled through discrete components rather than a blended take rate:
Origination fee revenue: modeled as funded originations multiplied by an origination fee rate.
Service fee revenue: included as an explicit line item but conservatively disabled in the base case due to undisclosed fee rates.
QEV-related fees: modeled as a function of redemption volume and a QEV fee rate, reflecting that QEV is an explicit liquidity primitive intended to manage redemption flows.
Liquidation fees: modeled as a tail-event revenue stream and disabled in the base case, given limited disclosure around realized default pathways and liquidation frequency.
This approach is intentionally conservative. It avoids inventing revenue sources while preserving a complete framework that can be updated as the protocol publishes fee schedules and realized fee mixes.
Because USD.AI is positioned as a credit structuring and funding protocol rather than a permanent balance-sheet lender, we do not apply a bank-style expected credit loss framework. Instead, the model assumes that the protocol earns net interest on outstanding exposure during the period loans are funded and held, net of depositor yield and required liquidity buffers. Residual risk is captured through an explicit friction adjustment rather than through lifetime expected credit losses.
The model, therefore, includes:
Collateral value protection premiums,modeled as a cost on the average loan book. This represents the protocol-paid premium for third-party collateral value warranties provided through the Barker framework and reinsured by Munich Re. The premium reduces net interest income and directly affects the yield available to sUSDai holders.
Operating costs, anchored to a largely fixed baseline with modest scaling, reflecting management guidance that OpEx is relatively predictable over the forecast horizon.
Operating surplus is defined as net protocol revenue less operating costs and protection premiums. Distributable surplus reflects the portion available after required reserves and system support costs.
Because surplus routing is governance-contingent, buybacks are modeled explicitly through:
Buyback rate: the share of distributable surplus routed to buybacks.
Buyback effectiveness: a buyback efficiency factor capturing execution quality and market impact, which prevents overstating how efficiently dollars translate into token support.
Terminal value is estimated by applying a multiple to Year 5 distributable surplus and discounting at scenario-specific rates. This functions as a market-pricing lens rather than an enforceable DCF.
Separately, we estimate an insurance-capital-implied solvency threshold to reflect CHIP’s potential role as recognized backstop capital within the protocol’s insurance framework. Under this lens, required backstop capital scales with the modeled outstanding funded exposure and an assumed insurance coverage ratio. That requirement is then adjusted for the share of tokens actively staked and for the proportion of staked tokens recognized as usable insurance capital. Finally, we incorporate a required staking yield to reflect the return demanded by capital providers for bearing tail risk.
The resulting threshold represents the fully diluted valuation at which staked and recognized CHIP would be sufficient to meet the protocol’s coverage requirement under modeled assumptions. Improvements in capital efficiency can reduce this threshold even as operating performance strengthens.
The scenario set is designed to bracket plausible outcomes by concentrating uncertainty in the handful of variables that matter:
Pipeline scale: how quickly annual originations expand.
Funding realization: the latency and conversion rate from pipeline to funded volume.
Fee rates and fee mix: primarily origination fees, with optional service and QEV fees gated until disclosed.
Capital policy: buyback rate and buyback effectiveness, explicitly treated as governance-contingent.
This structure preserves rigor under uncertainty. It avoids imposing cash flow rights that are not mechanically encoded yet, while still capturing the two credible pathways through which CHIP could accrue value if the protocol implements the mechanisms it has indicated publicly.
USD.AI’s near-term total addressable market (TAM) is not “global AI spend” in the abstract. The economically relevant TAM for CHIP is the subset of global GPU CapEx that is (1) financeable, (2) addressable by USD.AI’s collateral and underwriting stack (CALIBER), and (3) fundable onchain under the protocol’s liquidity design (QEV).
USD.AI is positioning itself as a credit origination and funding for real-world AI infrastructure, not as a generalized AI or stablecoin protocol. As a result, the binding constraint on scale is not the theoretical demand for AI compute, but the portion of GPU deployments that can be structured into enforceable, tokenized collateral and reliably funded through onchain capital markets.
This boundary is set by collateral enforceability and liquidity design, which determine what share of GPU CapEx can be financed onchain at scale.
Global GPU CapEx Assumptions
There is no single reported figure for global GPU CapEx. To construct a defensible baseline, we begin with broader data center capital expenditure and isolate the portion attributable to AI accelerators and GPU-based systems. However, industry research provides directional anchors. Omdiaprojects global data center CapEx reaching approximately $1.6 trillion annually by 2030, while McKinseyestimates cumulative data center investment of roughly $6.7 trillion through the end of the decade. Current hyperscaler disclosures and vendor revenue trajectories imply that present-day global data center CapEx is already in the several hundred-billion-dollar range.
Within that total, accelerator-driven investment is rapidly growing. Industry analysis from firms such as Dell’Oroindicates AI chips and accelerator systems account for roughly one-third of data center CapEx and are increasing as AI workloads expand.
Using these anchors, we estimate the current annual AI accelerator and GPU system CapEx at approximately $200-250 billion. This figure excludes non-financeable components, such as land, buildings, and power infrastructure, and focuses instead on hardware systems that could plausibly serve as collateral for structured credit. We anchor Year 1 of the model at $250 billion, the upper end of that range.
Growth assumptions reflect continued AI infrastructure scaling implied by hyperscaler investment plans and accelerator supply expansion:
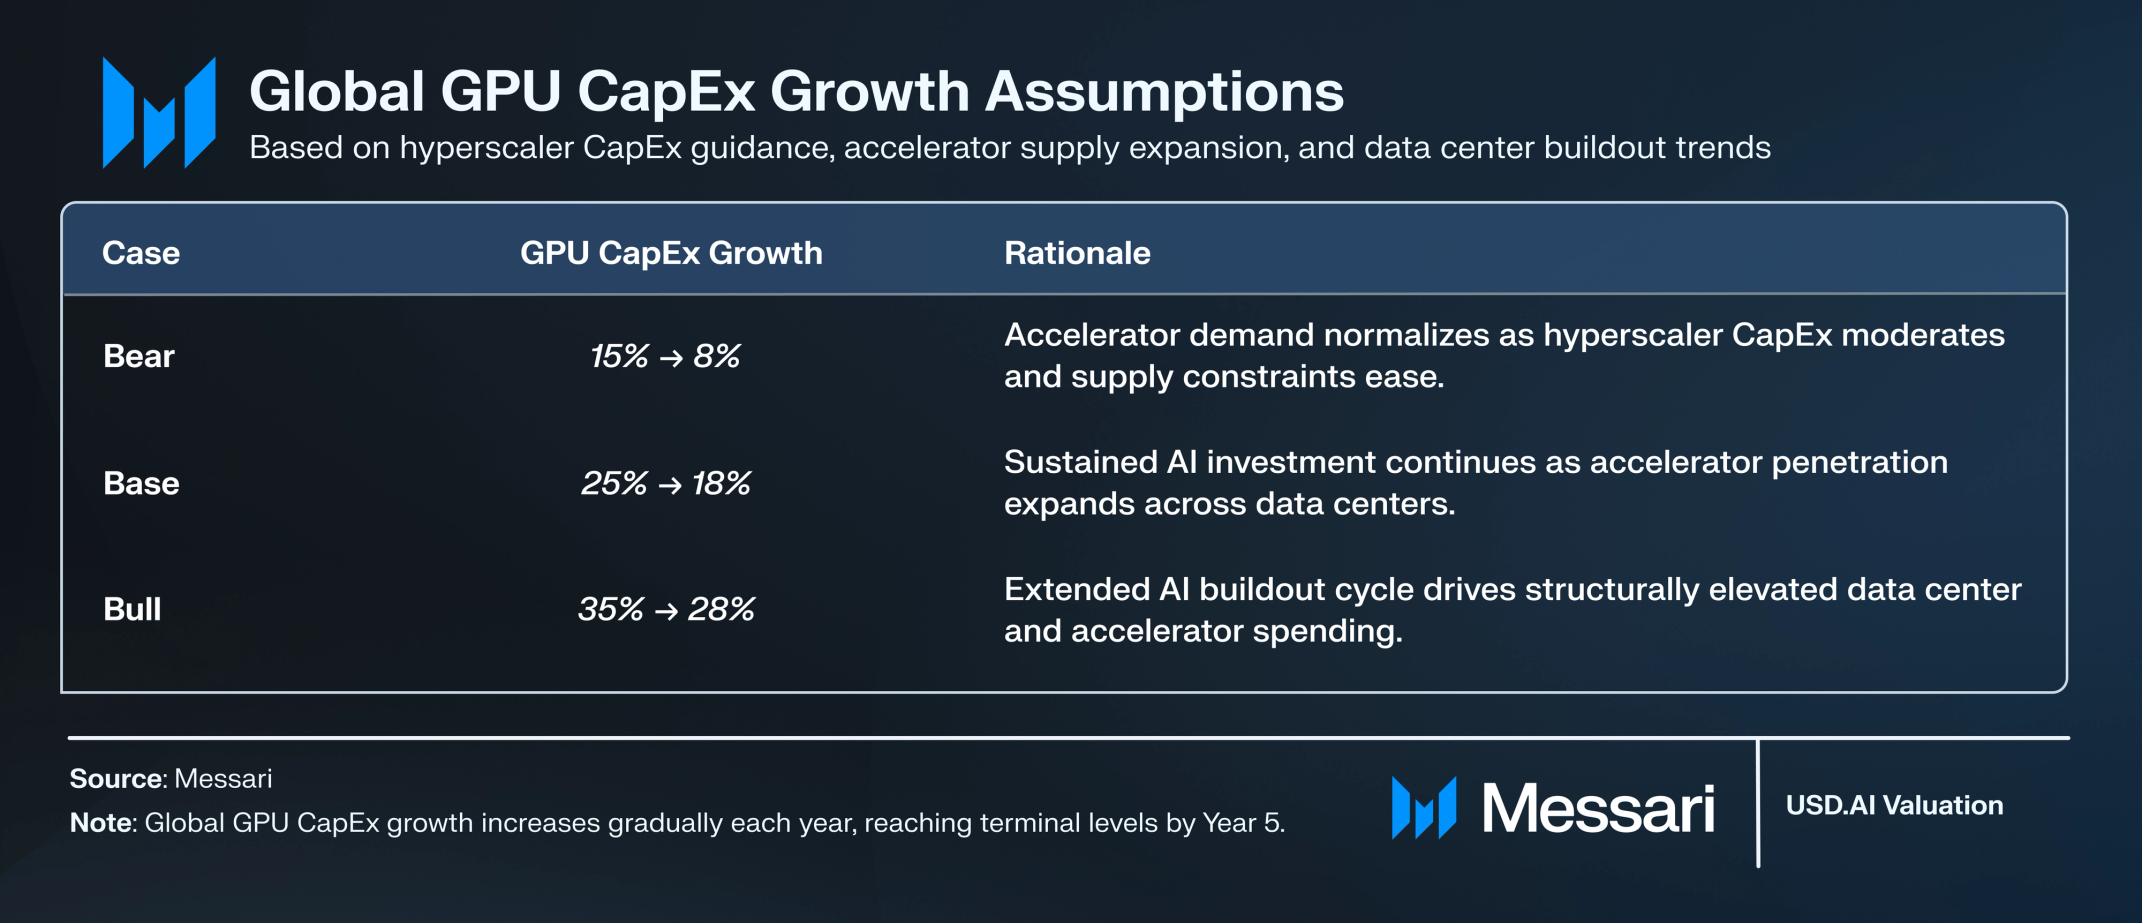
Bear case: 15% (Year 1) → 8% (Year 5) Assumes AI infrastructure growth decelerates meaningfully as supply constraints ease and hyperscaler CapEx normalizes. GPU system spending continues to expand but transitions toward a more mature mid-cycle growth profile by Year 5.
Base case: 25% (Year 1) → 18% (Year 5) Reflects sustained but moderating expansion consistent with hyperscaler disclosures and vendor backlog commentary. Growth slows as the installed base increases, but accelerator penetration in data centers continues to rise. Under this trajectory, annual AI accelerator CapEx approaches approximately $600 billion by Year 5.
Bull case: 35% (Year 1) → 28% (Year 5) Represents an extended infrastructure buildout cycle in which AI workloads drive continued acceleration in data center investment. Growth remains structurally elevated through the forecast period, supported by enterprise adoption and sustained accelerator supply expansion.
Under the base trajectory, annual AI accelerator CapEx approaches approximately $600 billion by Year 5, consistent with projected data center expansion and the rising accelerator share of total infrastructure investment.
Financeable share of GPU CapEx
Not all GPU CapEx is realistically financeable through structured credit. The model therefore applies a financeable share to global AI accelerator spending to reflect structural constraints, including:
hyperscaler self-funding and vertical integration,
strategic deployments financed directly off corporate balance sheets,
jurisdictional, legal, or custody limitations,
and asset characteristics that limit collateral enforceability.
We assume financeable shares ranging from 15% in the bear case, 25% in the base case, and 35% in the bull case.
This range is informed by broader infrastructure finance practice. In traditional infrastructure sectors, projects that use external financing often employ meaningful leverage, with debt representing a substantial share of total capital structure. However, infrastructure debt fundraising represents only a subset of overall infrastructure capital formation, reflecting that many assets are funded directly by corporate balance sheets or large sponsors rather than through formal project or structured debt vehicles.
Structured credit penetration, therefore, varies by asset class, sponsor strength, and market cycle. In early AI infrastructure buildouts, hyperscalers and well-capitalized technology firms are more likely to self-fund hardware investment, reducing third-party debt participation relative to mature infrastructure segments. Over time, independent operators, co-location providers, and mid-market facilities may increasingly rely on asset-backed financing as collateral frameworks mature.
Under this logic:
Bear case (15%) assumes continued concentration among self-funded hyperscalers and limited structured credit penetration.
Base case (25%) reflects moderate participation by third-party credit providers consistent with observed infrastructure debt market participation.
Bull case (35%) assumes broader adoption of asset-backed structures as collateral enforceability improves and financing markets deepen.
This parameter functions as a macro financing filter rather than a protocol adoption variable. It converts total accelerator investment into the portion realistically addressable by third-party credit providers. USD.AI’s market share assumptions are then applied to this financeable base, rather than to total GPU CapEx.
Adoption and Origination Volume
USD.AI’s economic model is origination-driven. Fee revenue is generated at origination, while outstanding exposure determines liquidity requirements, collateral protection costs, and capital allocation capacity. For this reason, adoption is modeled through origination throughput rather than notional TVL or passive balance growth.
USD.AI share of financeable CapEx
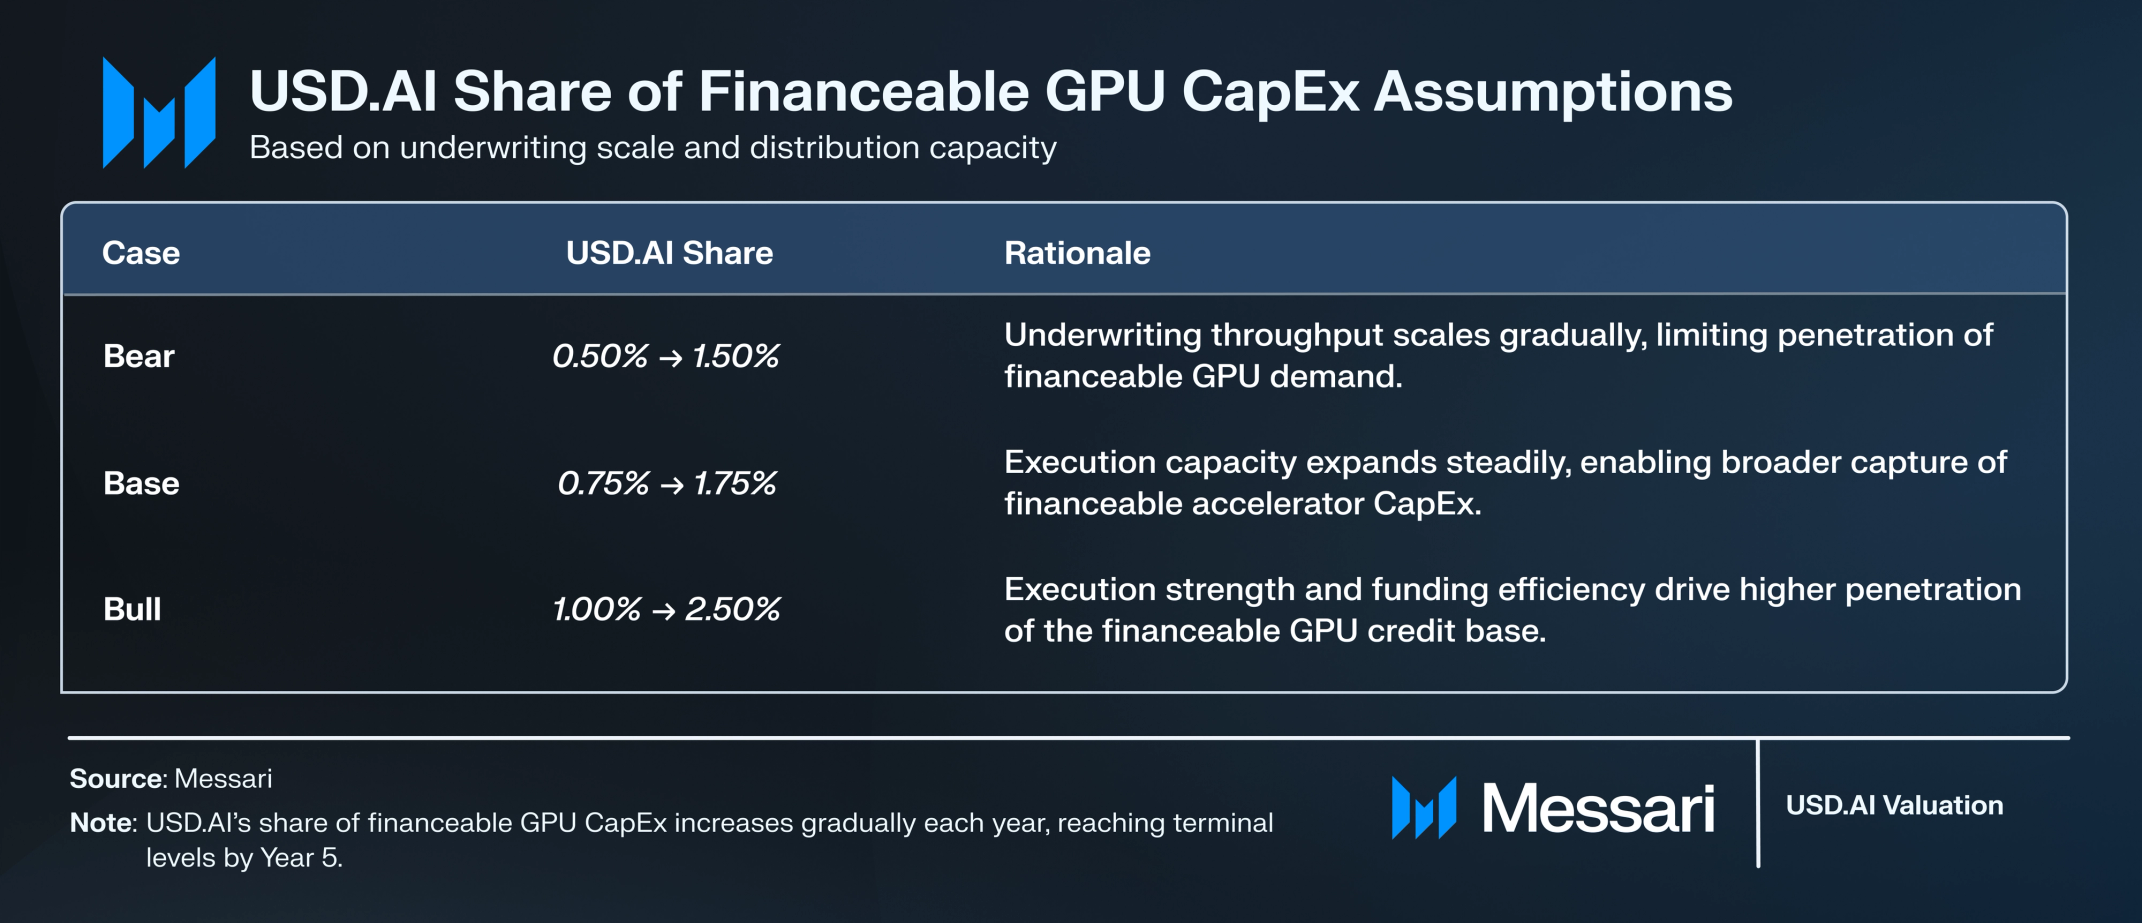
We model USD.AI’s adoption as a share of financeable GPU CapEx, with a five-year penetration ramp that varies by scenario. This share captures underwriting capacity, borrower acquisition, distribution reach, and competitive positioning in GPU infrastructure finance.
We assume the following penetration path of financeable CapEx:
Bear: 0.50% (Year 1) → 1.50% (Year 5)
Base: 0.75% (Year 1) → 1.75% (Year 5)
Bull: 1.00% (Year 1) → 2.50% (Year 5)
The bear case assumes underwriting throughput scales slowly, limiting penetration of the addressable financing base. The base case reflects steady execution improvement and gradual expansion of distribution capacity. The bull case assumes both strong funding realization and materially higher market share capture as USD.AI scales underwriting capacity, borrower acquisition, and capital formation in parallel.
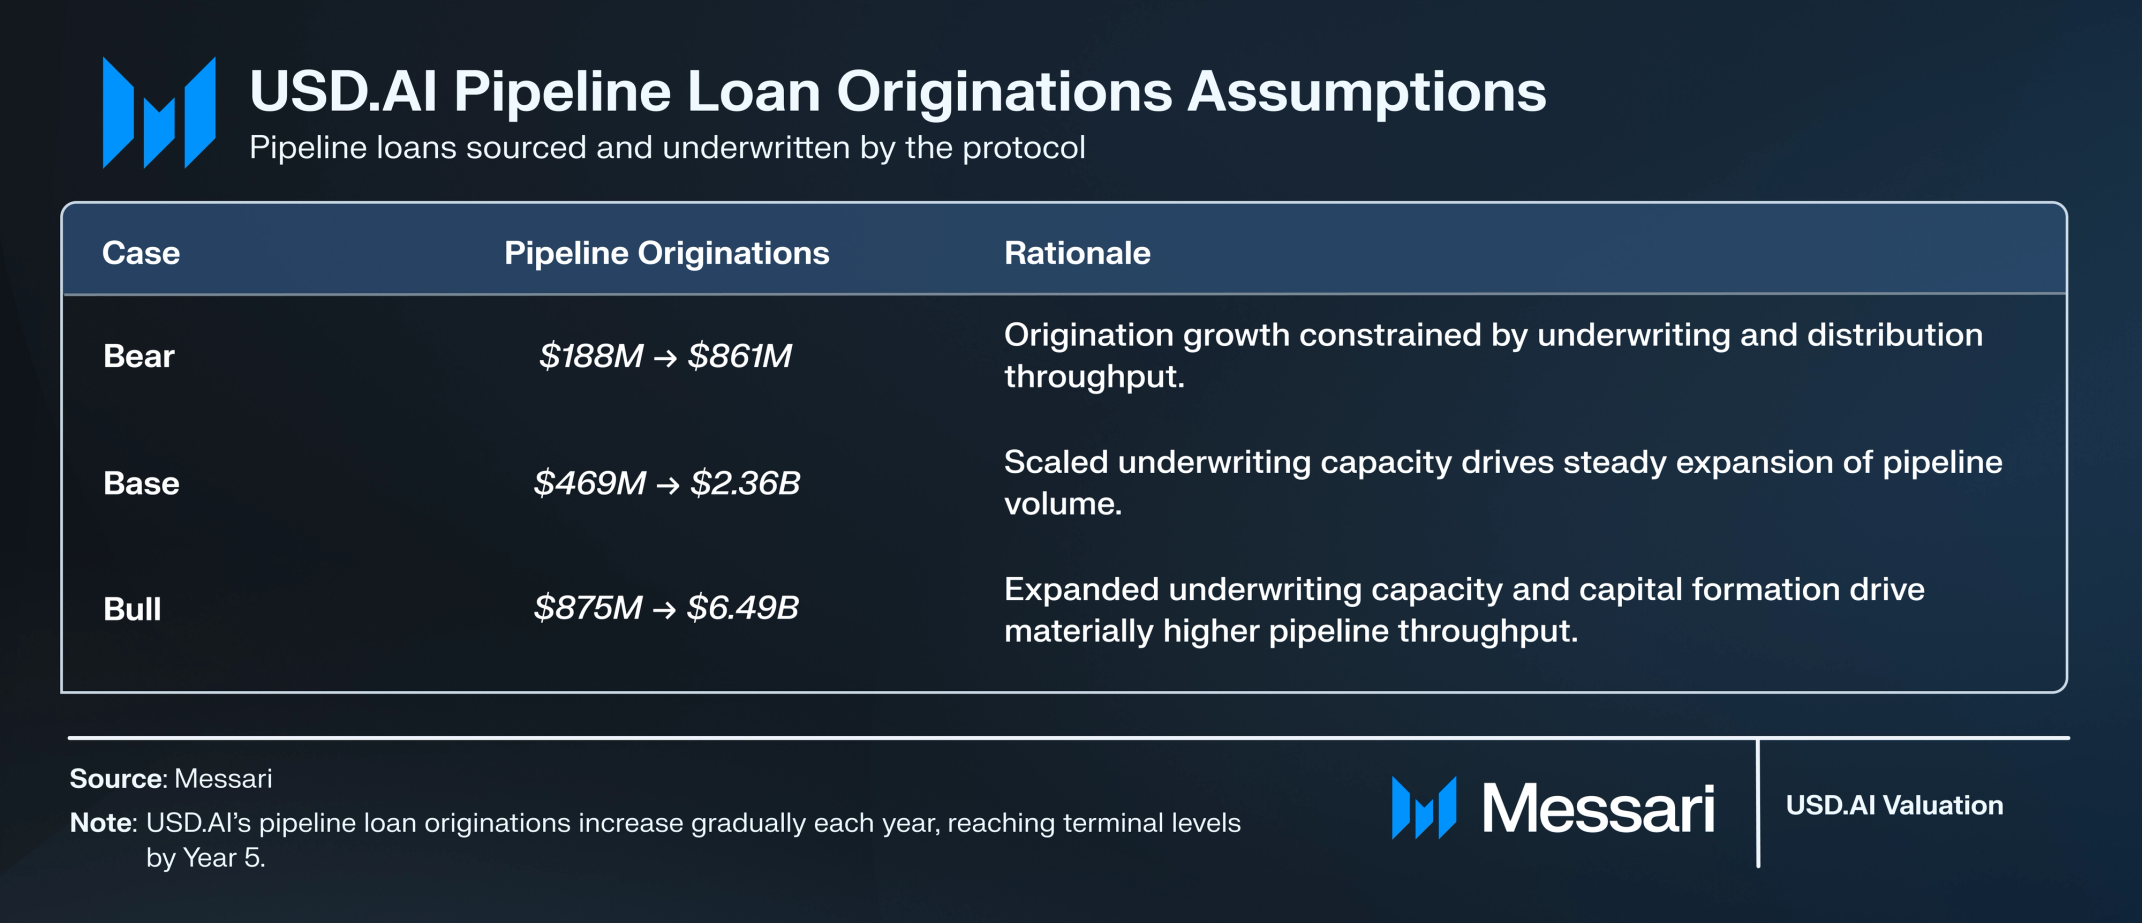
Applying these shares to the financeable CapEx base produces the following pipeline loan originations:
Bear: $188M (Year 1) → $861M (Year 5)
Base: $469M (Year 1) → $2.36B (Year 5)
Bull: $875M (Year 1) → $6.49B (Year 5)
These figures represent pipeline originations, defined as loans sourced, underwritten, and marketed by the protocol. They reflect underwriting and distribution throughput rather than funded volume.
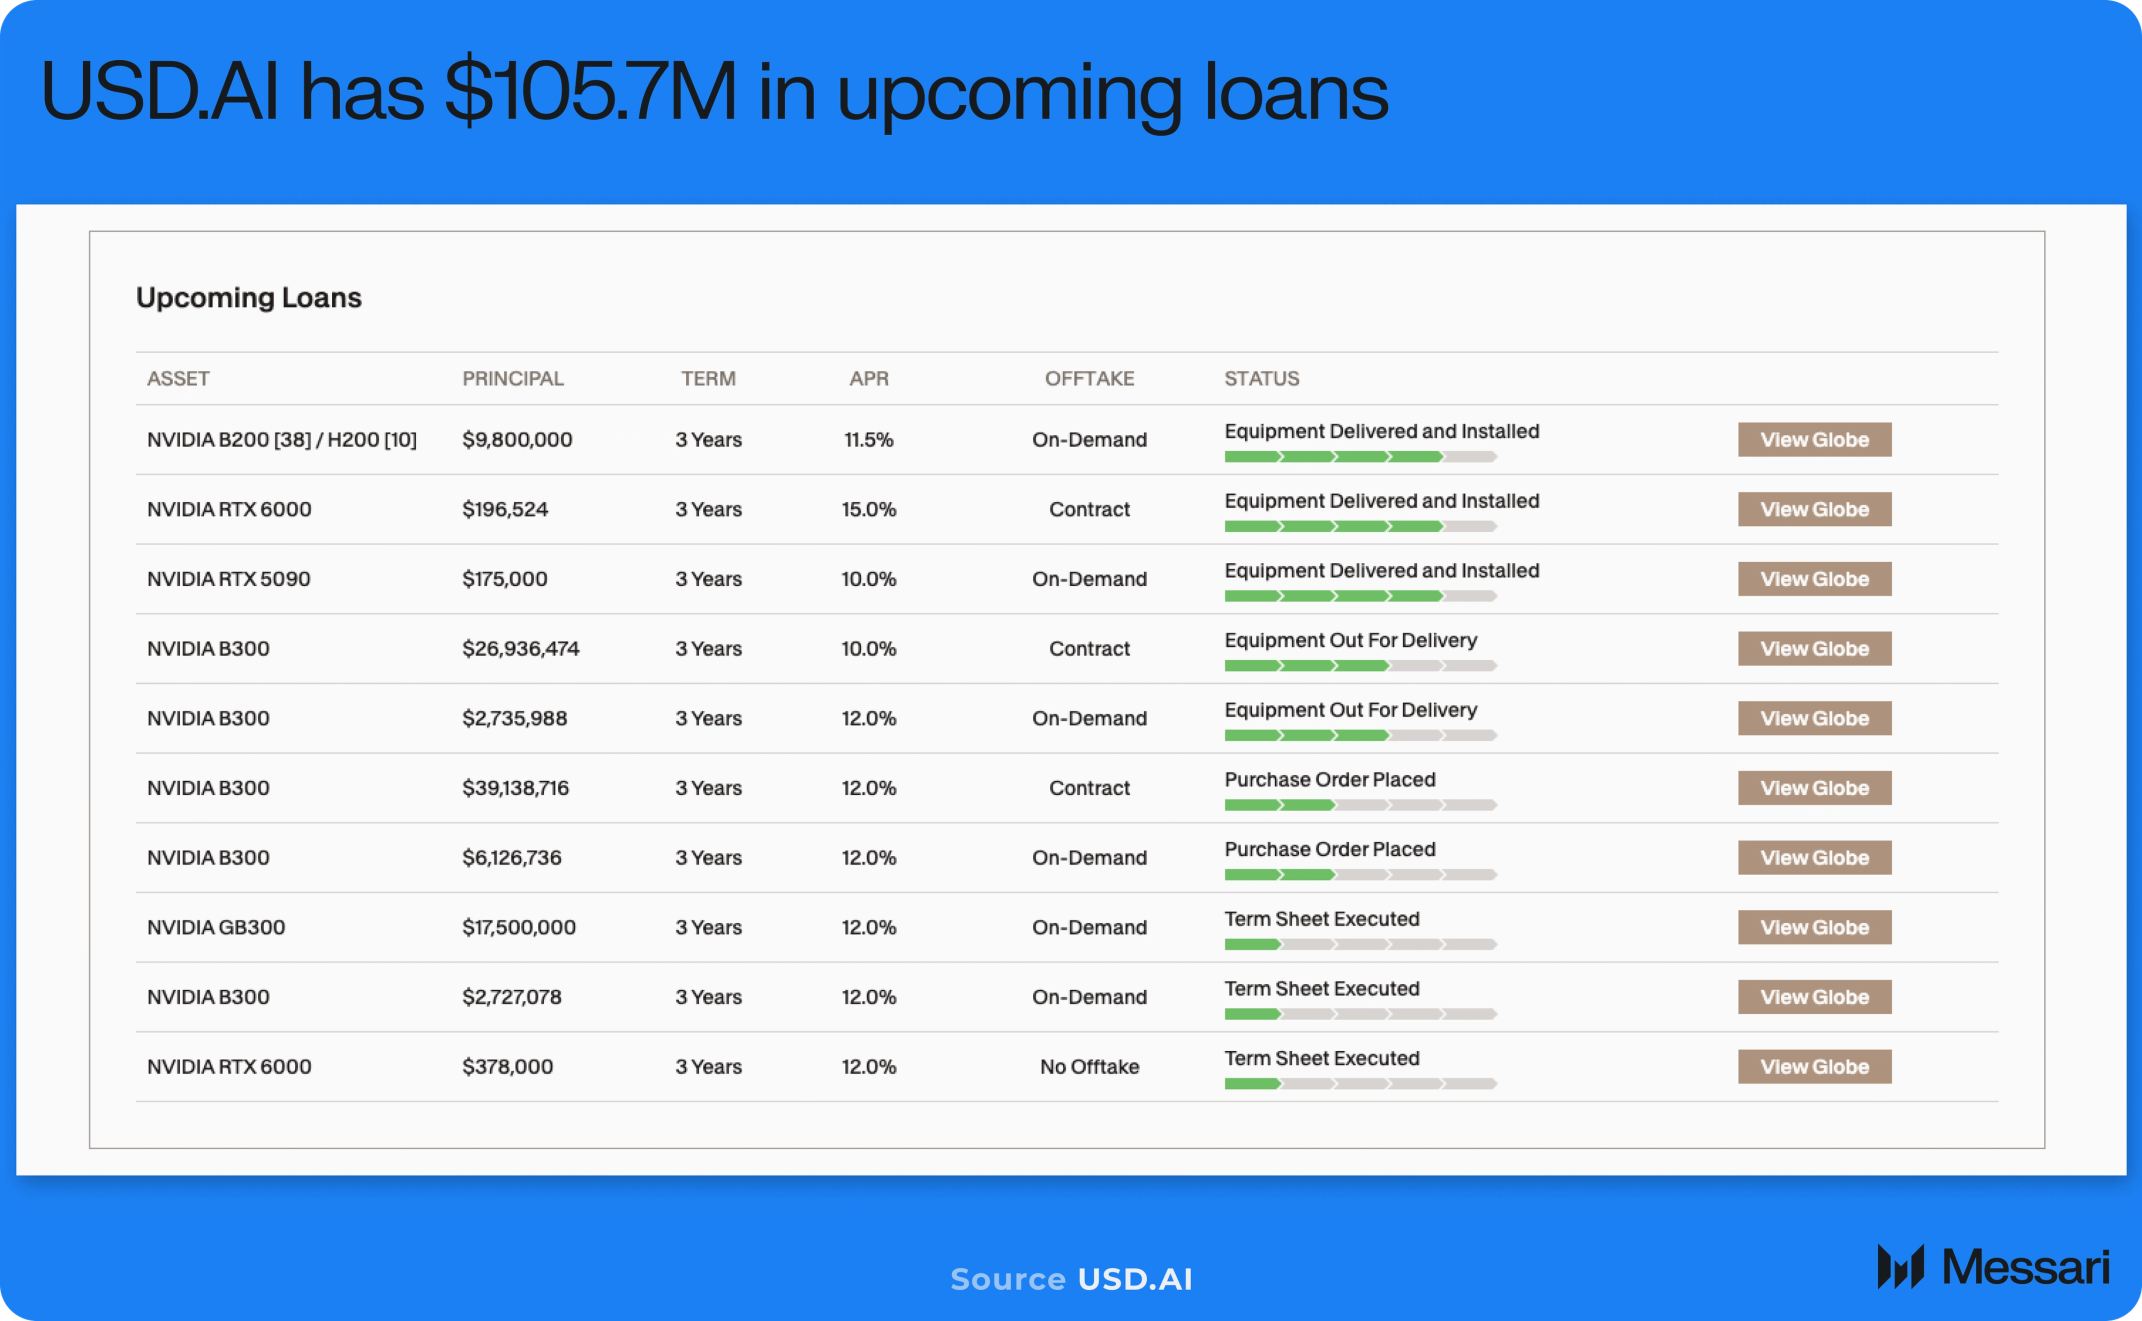
Upcoming loans total approximately $105.7 million in principal, anchoring the near-term pipeline against which the modeled origination ramps should be evaluated. Funding realization is modeled separately to convert pipeline into economically active exposure.
Loan latency and funding realization
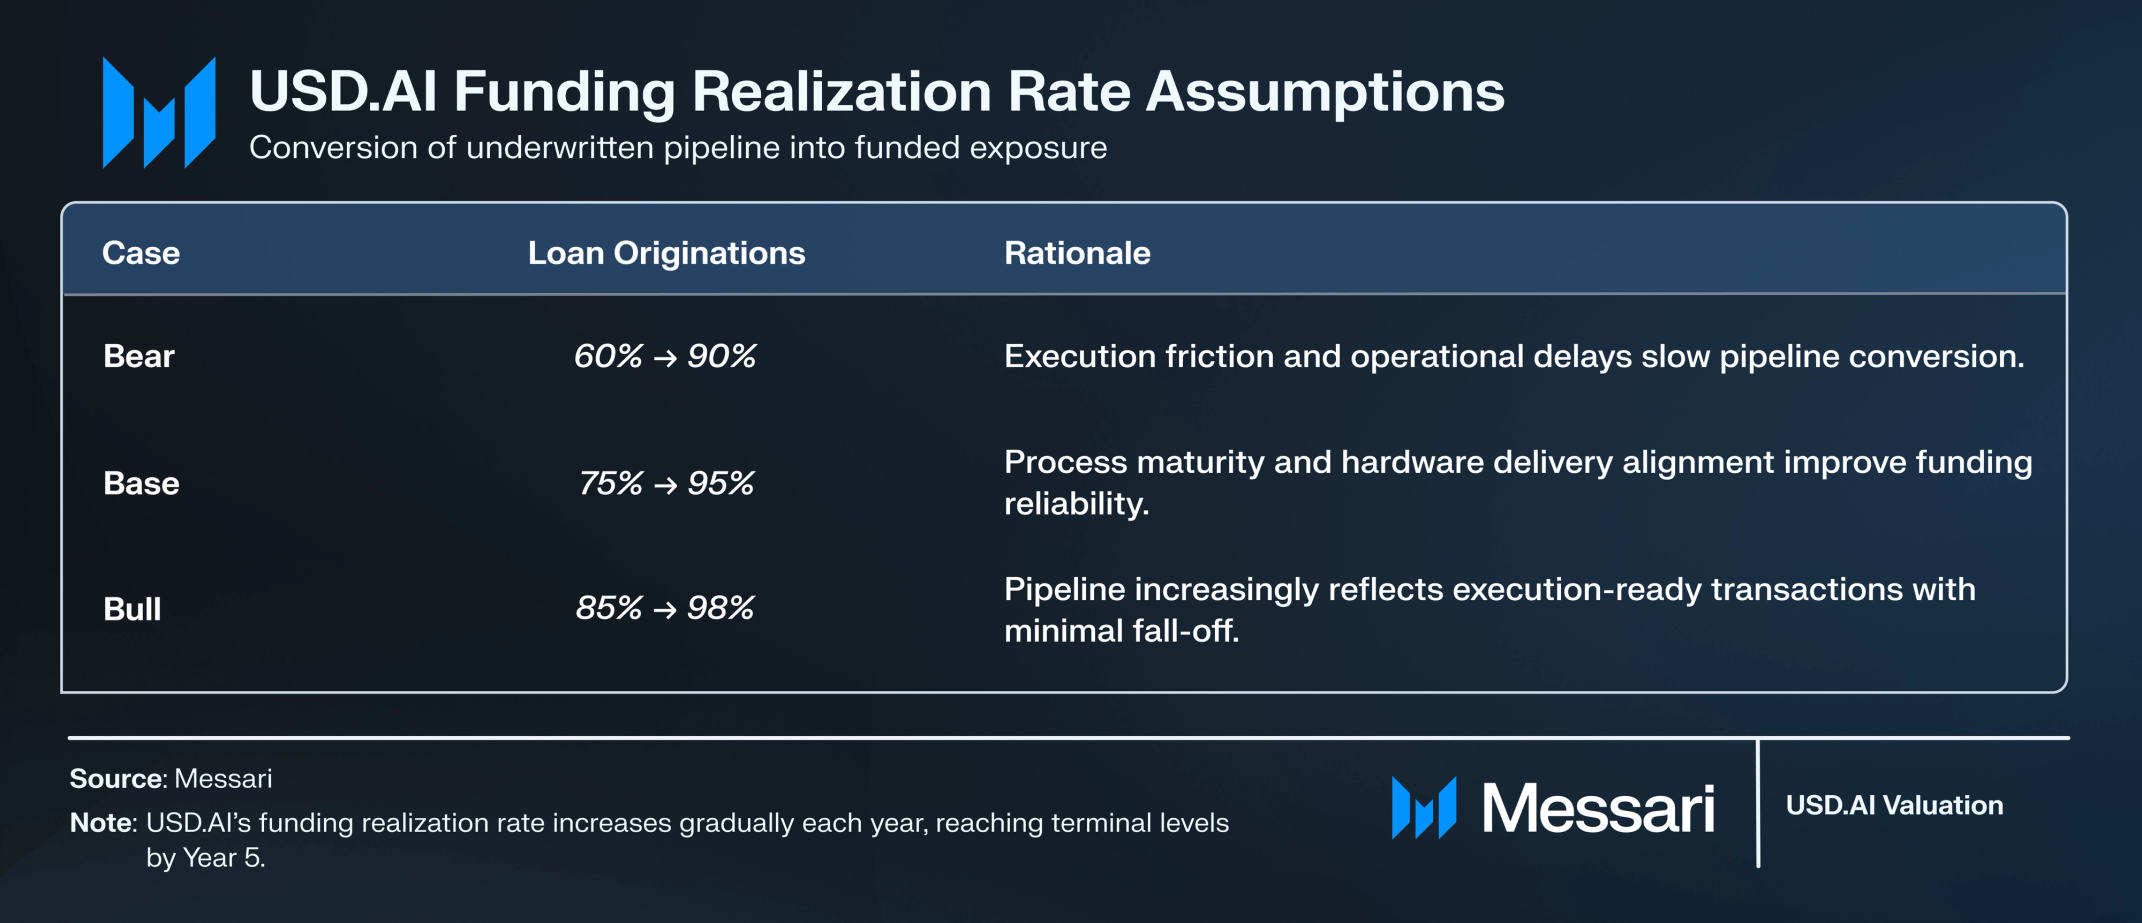
The model separates pipeline originations from funded originations through an explicit funding realization rate. This parameter captures execution constraints such as hardware delivery timelines, installation schedules, legal settlement, and collateral perfection.
We assume the following funding realization paths:
Bear: 60% (Year 1) → 90% (Year 5)
Base: 75% (Year 1) → 95% (Year 5)
Bull: 85% (Year 1) → 98% (Year 5)
The modeled realization rates assume pipeline reflects credit-vetted, operationally advancing transactions rather than early-stage marketing leads. In private credit and infrastructure finance, conversion varies significantly by stage: late-stage, mandated deals typically close at high rates, while early-stage pipeline exhibits greater fall-off. The bear case reflects sustained execution friction, while the base and bull cases assume pipeline increasingly represents execution-ready transactions as processes mature.
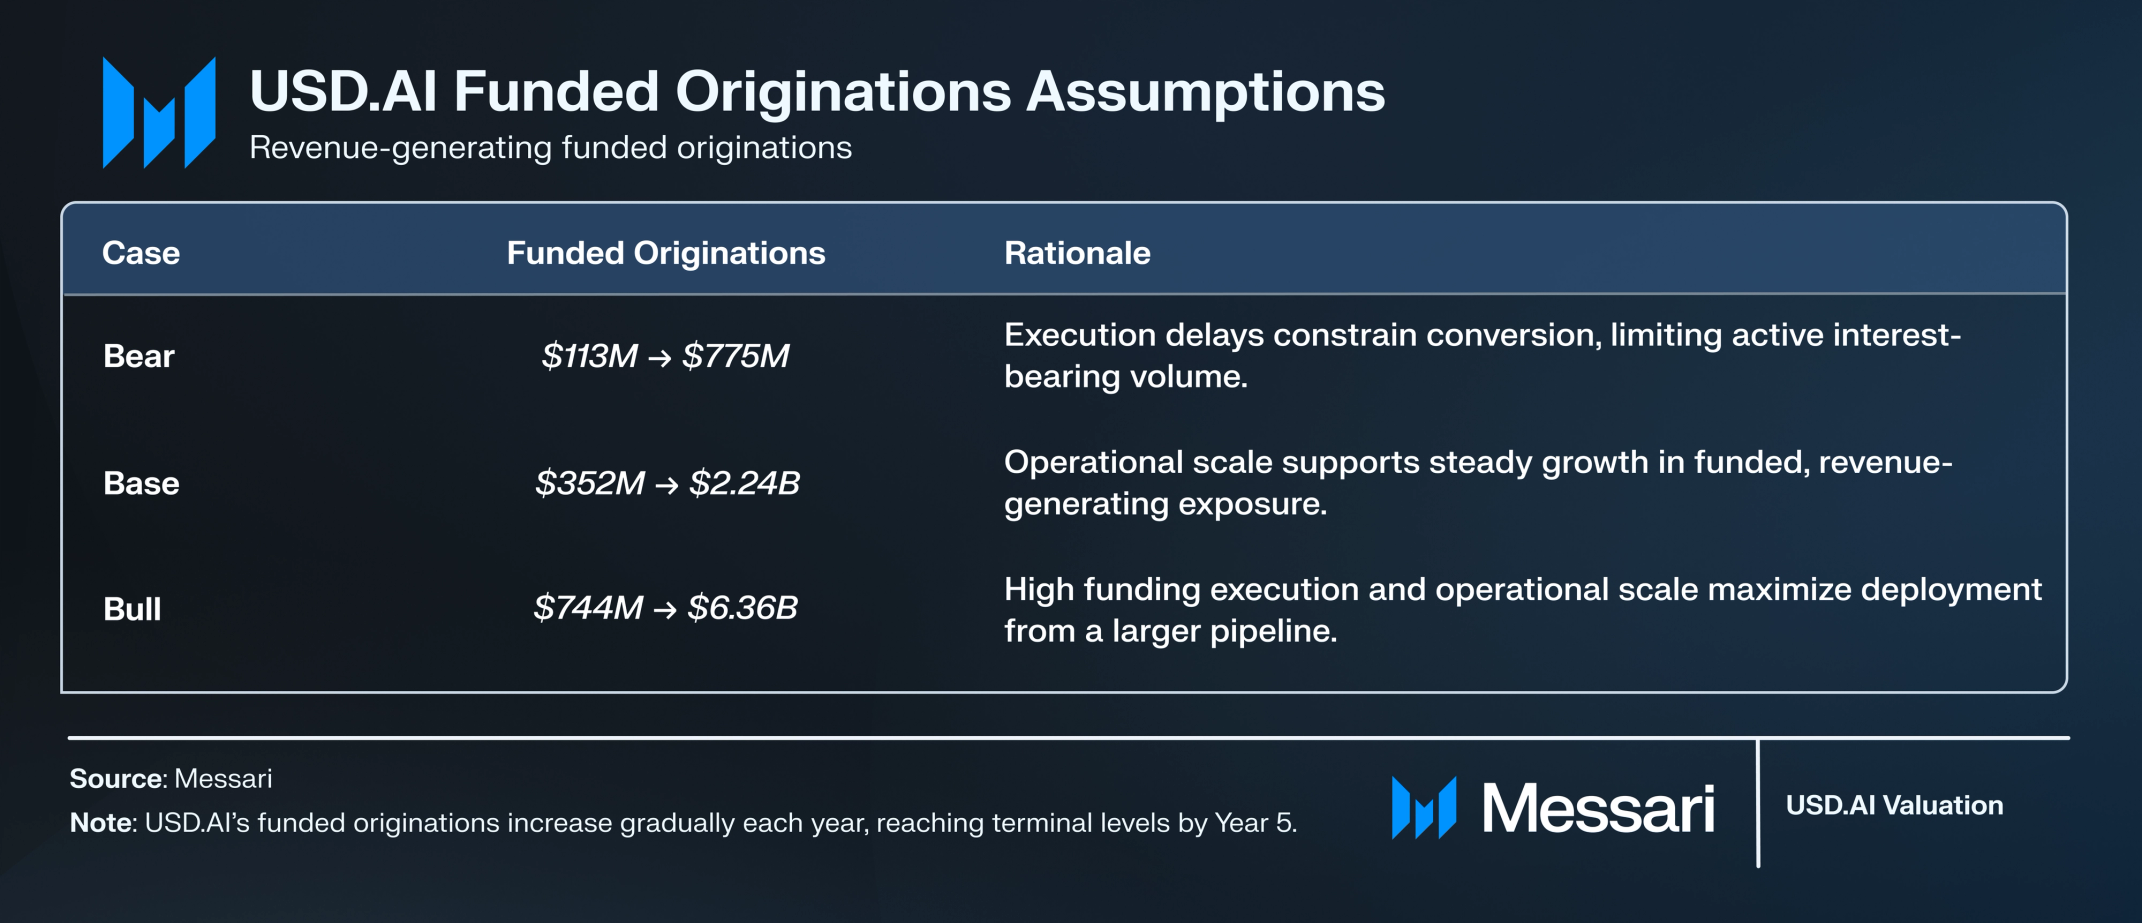
Applying these realization rates to pipeline originations yields the following funded volumes:
Bear: $113M (Year 1) → $775M (Year 5)
Base: $352M (Year 1) → $2.24B (Year 5)
Bull: $744M (Year 1) → $6.36B (Year 5)
Funded originations represent economically active volume. Fee generation, net interest income, liquidity requirements, and collateral protection sizing are all driven by funded exposure rather than the marketed pipeline. This separation prevents pipeline from being treated as revenue-bearing and concentrates valuation sensitivity on operational execution rather than headline demand.
Protocol Revenue Model
Protocol revenue is modeled through explicit economic components rather than a blended take rate. This approach ensures consistency between origination volume, outstanding exposure, liquidity buffers, funding costs, and fee streams, and prevents double-counting between spread income and explicit fees.
Net interest income and funding costs
Net interest income (NII) is modeled as the combination of three components:
Interest income on funded loans, calculated by applying borrower APR assumptions to average outstanding exposure.
Interest income on liquidity reserves, representing yield earned on unutilized capital held to support redemptions and operational liquidity.
Depositor yield expense, applied to the sUSDai-funded portion of average TVL and modeled as a time-varying series rather than a fixed constant.
In the base case, borrower APR is assumed at 15%, defining the gross yield on funded exposure. Idle liquidity is assumed to earn approximately 3.6%, consistent with short-duration T-bill equivalents. Depositor yield on sUSDai begins around 9.0% and gradually rises to 10.8% over the forecast horizon, reflecting competitive funding conditions and protocol maturity.
A 0.50% collateral protection premium is applied to the average loan book to reflect third-party valuation warranty costs under the Barker structure. The model also assumes a target utilization ramp and explicit liquidity buffers, which leave a portion of capital temporarily undeployed at any given time. Because not all capital is continuously earning borrower APR, this unused balance reduces effective net interest income relative to full deployment.
Net interest spread is therefore driven by borrower pricing, capital deployment efficiency, required liquidity buffers, and depositor yield dynamics.
Public liquidity incentives, including the PYUSD incentive program (4.5% on eligible deposits), can influence depositor economics. The model does not treat such programs as structural revenue or permanent spread enhancement. Instead, any effect is reflected through depositor yield assumptions and capital allocation into sUSDai. In the base case, net interest income reflects borrower pricing, liquidity buffers, and depositor yield expense without assuming ongoing external subsidy.
Fee revenue
In addition to spread-based income, the model includes four distinct fee streams, each tied to a defined protocol mechanism. Even where certain fees are set to zero in the base case, they are modeled separately rather than embedded in a blended take rate.
Origination fees, applied to pipeline loan originations and vary by scenario. This is the primary disclosed fee stream and the dominant driver of non-spread revenue.
Service fees, applied to the average outstanding loan book. These are parameterized but set to zero in the base case pending clearer disclosure of the fee base and rate.
QEV-related fees, modeled as a function of average TVL, an assumed redemption rate, and a QEV fee parameter. These are conservatively sized, reflecting QEV’s stated role as a liquidity coordination mechanism rather than a core revenue engine.
Liquidation fees, applied to funded originations. These are set to zero in the base case, given limited public disclosure of realized default frequency and fee-capture mechanics.
Modeling these components separately maintains internal consistency between origination flow, exposure, liquidity dynamics, and fee capture. As fee schedules and realized economics become clearer, individual lines can be adjusted without altering the broader revenue framework.
Residual risk and friction losses
Third-party collateral value protection materially reduces loss severity but does not imply zero economic leakage. Even in an insured structure, realized outcomes can diverge from modeled recoveries due to valuation basis risk, policy terms and exclusions, claims processing timelines, liquidation costs, and operational frictions.
To reflect this, the model applies a residual friction adjustment to funded exposure. This haircut represents a percentage reduction intended to capture economic leakage that may persist even when principal exposure is contractually protected.
The adjustment incorporates potential settlement inefficiencies, divergence between insured valuation benchmarks and realized liquidation proceeds, claims timing delays, contractual exclusions, and edge-case enforcement disputes. Although GPU collateral is covered by third-party value protection, real-world credit systems rarely achieve perfect recovery. The friction adjustment ensures the model does not overstate net economics while avoiding a full expected credit loss framework that would be inconsistent with USD.AI’s insured structure.
Operating Expenses
Operating expenses are modeled as a combination of fixed overhead and scale-linked servicing costs:
Operating Costs = $5 million fixed base + 0.25% × Ending Outstanding Loan Book
The $5 million fixed component in Year 1 is consistent with management guidance regarding the steady-state cost base required to support underwriting, legal structuring, insurance coordination, and protocol operations. This reflects a lean but institutionally credible operating footprint rather than a fully scaled financial platform.
Expenses scale with funded loan book growth rather than revenue. As outstanding exposure increases, incremental costs arise from credit monitoring, collateral oversight, reporting infrastructure, and compliance requirements. This structure aligns the model with specialty finance platforms, where operating intensity expands with assets under management rather than with top-line growth.
Operating Surplus and Capital Allocation Boundary
Operating surplus is defined as net protocol revenue after operating expenses and residual risk adjustments. It represents pre-allocation earnings generated by the protocol.
However, operating surplus is not automatically distributable. USD.AI requires ongoing capital to support liquidity buffers, collateral protection costs, and system resilience. The model, therefore, introduces an explicit boundary between operating performance and the value available for discretionary use.
Distributable surplus is defined as operating surplus net of required reserves and system support costs. This is the portion of earnings that governance could allocate toward buybacks, staking incentives, treasury strategy, or reinvestment.
Separating operating surplus from distributable surplus prevents the implicit assumption that all protocol earnings accrue to CHIP holders. In a system where liquidity management and capital adequacy are core design features, retained earnings may be structurally necessary.
This distinction is central to the valuation framework. It ensures that:
Value accrual to CHIP is contingent on governance, not mechanically assumed.
Capital policy is constrained by system safety requirements.
Surplus routing can be stress-tested independently from operating performance.
This capital boundary underpins the two lenses applied to CHIP: an upside lens tied to governance-directed surplus allocation, and a capital adequacy constraint tied to CHIP’s potential role as recognized insurance capital.
Token Value Accrual for CHIP
Buyback-supported value
The buyback-supported lens evaluates CHIP as a governance asset that may capture value through discretionary surplus allocation. A portion of distributable surplus may be directed toward token buybacks, subject to DAO policy. This pathway is modeled explicitly as a governance choice rather than a contractual entitlement.
The framework proceeds as follows:
Projected distributable surplus (Years 1-5) → discounted to present value = PV of distributable surplus
Year 5 distributable surplus × terminal enterprise multiple → terminal enterprise value → discounted to present value = PV of terminal enterprise value
PV of distributable surplus + PV of terminal enterprise value = total enterprise value
Total enterprise value × buyback rate × buyback effectiveness = buyback-supported CHIP value
We estimate a terminal enterprise value by applying an EV multiple to Year 5 distributable surplus. This multiple is a market-pricing assumption reflecting how investors may value a governance-directed surplus stream once scale, durability, and capital policy credibility are observable.
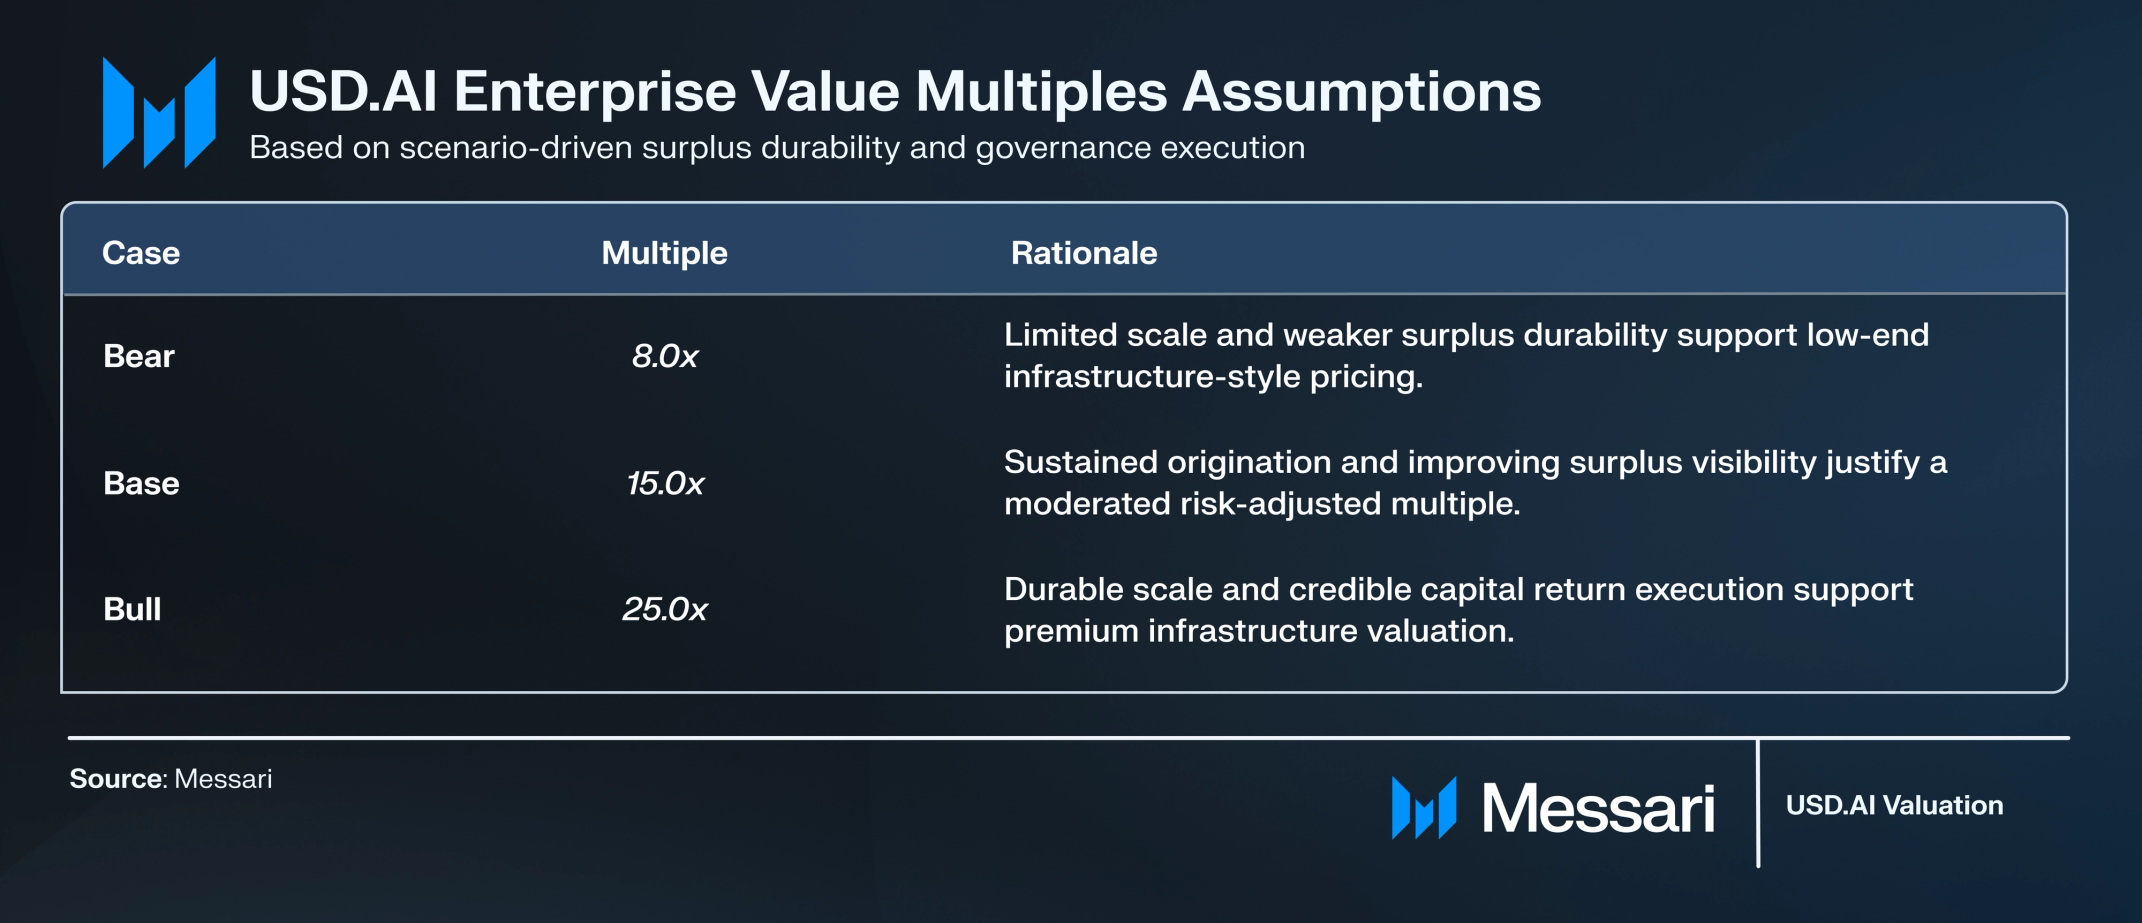
Terminal multiples vary by scenario:
Bear (8×): Assumes limited scale and weaker confidence in durable surplus formation and capital return policy, resulting in infrastructure-like low-end pricing.
Base (15×): Assumes sustained origination throughput and improving durability, but with governance-contingent capital return still priced with a risk premium.
Bull (25×): Assumes durable scale, improved predictability of distributable surplus, and credible, repeatable capital return execution, supporting a premium valuation consistent with scaled onchain credit platforms.
Both distributable surplus (Years 1-5) and terminal enterprise value are discounted to present value using scenario-specific discount rates of 25% (bear), 20% (base), and 15% (bull). These rates incorporate execution risk, governance-contingent surplus routing, crypto market cyclicality, and structural uncertainty inherent in an early-stage onchain credit platform. Higher rates in weaker scenarios reflect elevated uncertainty around origination scale, funding realization, and policy durability.
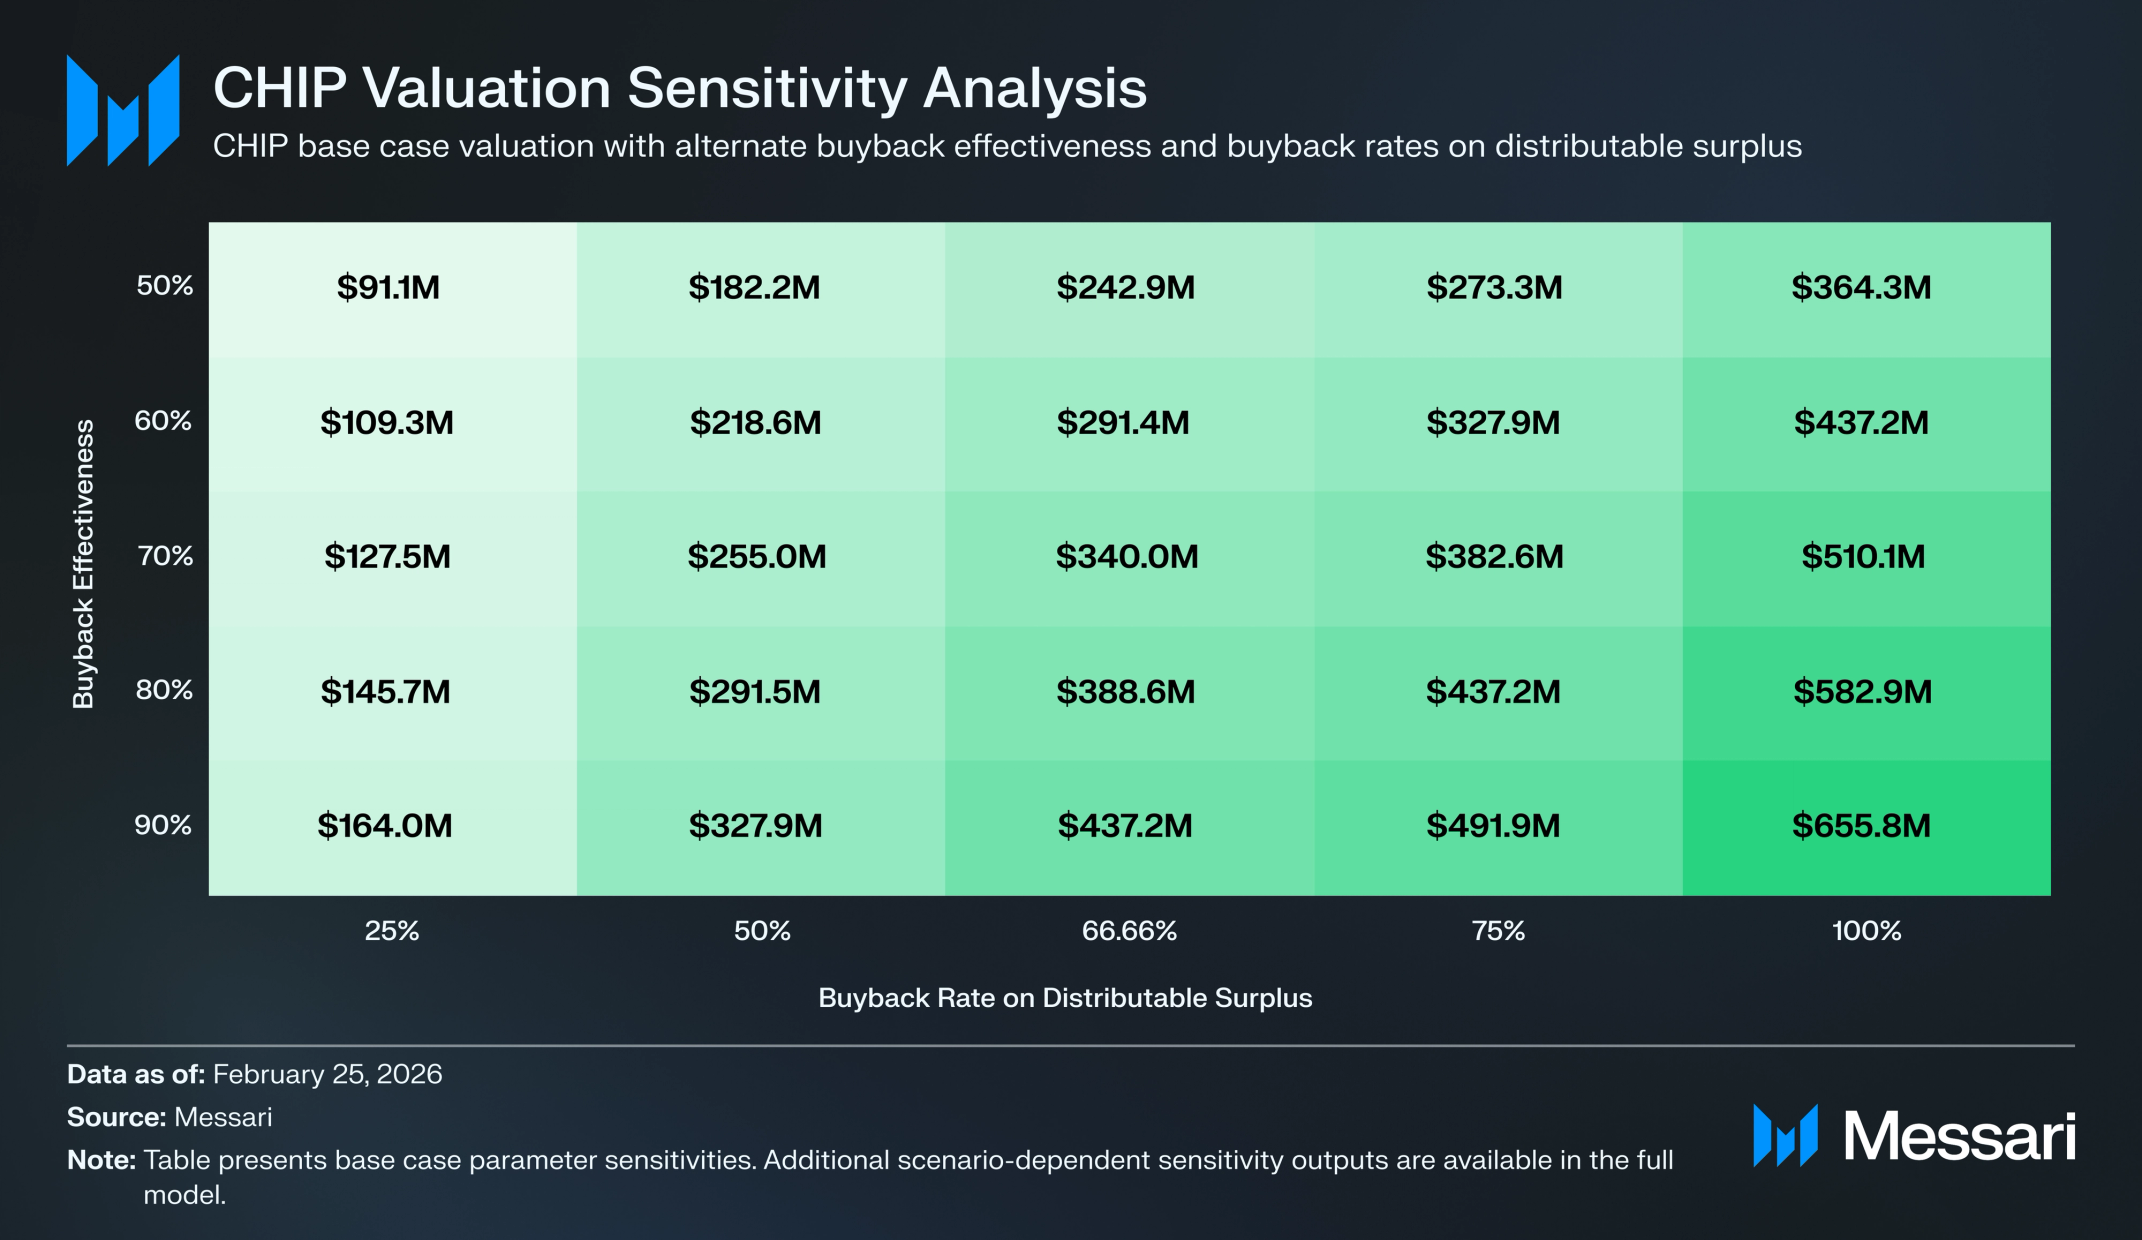
The buyback rate and buyback effectiveness govern how surplus translates into token support. In the core valuation, we assume a 50% buyback rate and 75% buyback effectiveness across cases. These parameters reflect partial surplus allocation and moderate execution efficiency, and are varied in the sensitivity analysis.
Under these assumptions, the model produces the following buyback-supported fully diluted valuations (FDV):
Bear: $46.4M
Base: $329.6M
Bull: $1.74B
Variation across scenarios is driven by differences in origination scale, funding realization, net interest economics, discount rates, and terminal multiples applied to distributable surplus. The analysis avoids circular price assumptions and derives token value strictly from modeled operating performance and explicitly defined capital policy parameters.
Insurance-capital-implied solvency threshold
We also model an insurance-capital-implied solvency threshold based on CHIP’s potential role as recognized backstop capital within the protocol’s insurance module.
This lens evaluates the fully diluted valuation at which staked and recognized CHIP would be sufficient to satisfy the protocol’s insurance coverage requirement under explicit assumptions about exposure, coverage ratios, staking participation, collateral recognition rates, and required staking yield.
The calculation begins with the modeled outstanding funded exposure of the protocol. A coverage ratio is applied to that exposure to determine the amount of required backstop capital. This capital requirement is then adjusted for staking participation, defined as the percentage of total token supply actively staked, and for the collateral recognition rate, defined as the proportion of staked CHIP recognized as usable insurance capital.
The solvency threshold is driven by four core parameters, which vary by scenario:
Insurance coverage ratio: 7.0% (bear), 4.5% (base), 3.5% (bull), representing required backstop capital as a percentage of outstanding funded exposure.
Staking participation: 25% (bear), 40% (base), 55% (bull), reflecting the portion of total token supply actively staked.
Collateral recognition rate: 40% (bear), 55% (base and bull), representing the percentage of staked CHIP recognized as usable insurance capital for coverage purposes.
Required staking yield: 30% (bear), 25% (base), 22.5% (bull), representing the return demanded by backstop capital providers given perceived protocol risk.
Insurance coverage ratio is the dominant mechanical driver of required capital. Staking participation and recognition rate determine how efficiently token supply translates into usable coverage, while required staking yield determines the capitalization necessary to compensate capital providers for risk. Higher required yields increase the implied threshold; lower required yields compress it.
Under the model assumptions, the resulting discounted insurance-capital-implied solvency thresholds are:
Bear: $270.1M
Base: $275.6M
Bull: $503.2M
This output should not be interpreted as a price floor or intrinsic valuation anchor. It reflects the capitalization required to maintain coverage at the modeled exposure level. Higher coverage requirements or lower recognition rates increase required capitalization, while improved staking participation or recognition efficiency reduce the capital required per unit of exposure.
Accordingly, the implied solvency threshold can decline in stronger operating scenarios if capital efficiency improves. Such declines reflect reduced capital intensity rather than weaker operating performance.
Reconciling the Two Analytical Lenses
The two analytical lenses applied to CHIP are intentionally not collapsed into a single point estimate because they answer different economic questions.
The buyback-supported pathway reflects discretionary upside participation in operating performance, conditional on governance credibility and capital return execution. It becomes most informative when the DAO demonstrates sustained, repeatable surplus allocation.
The insurance-capital-implied solvency threshold reflects the capitalization level required for the system to satisfy its coverage requirements if CHIP functions as recognized backstop capital. It does not represent intrinsic value or a price floor. Instead, it defines the valuation consistent with capital adequacy under specified assumptions about exposure, staking participation, coverage ratios, and collateral recognition.
Divergence between these outputs is expected. The buyback pathway scales with distributable surplus and market pricing of durability, while the solvency threshold scales with exposure and capital intensity. Improvements in capital efficiency can reduce the solvency threshold even as the surplus-driven valuation potential increases.
Sensitivity Analysis
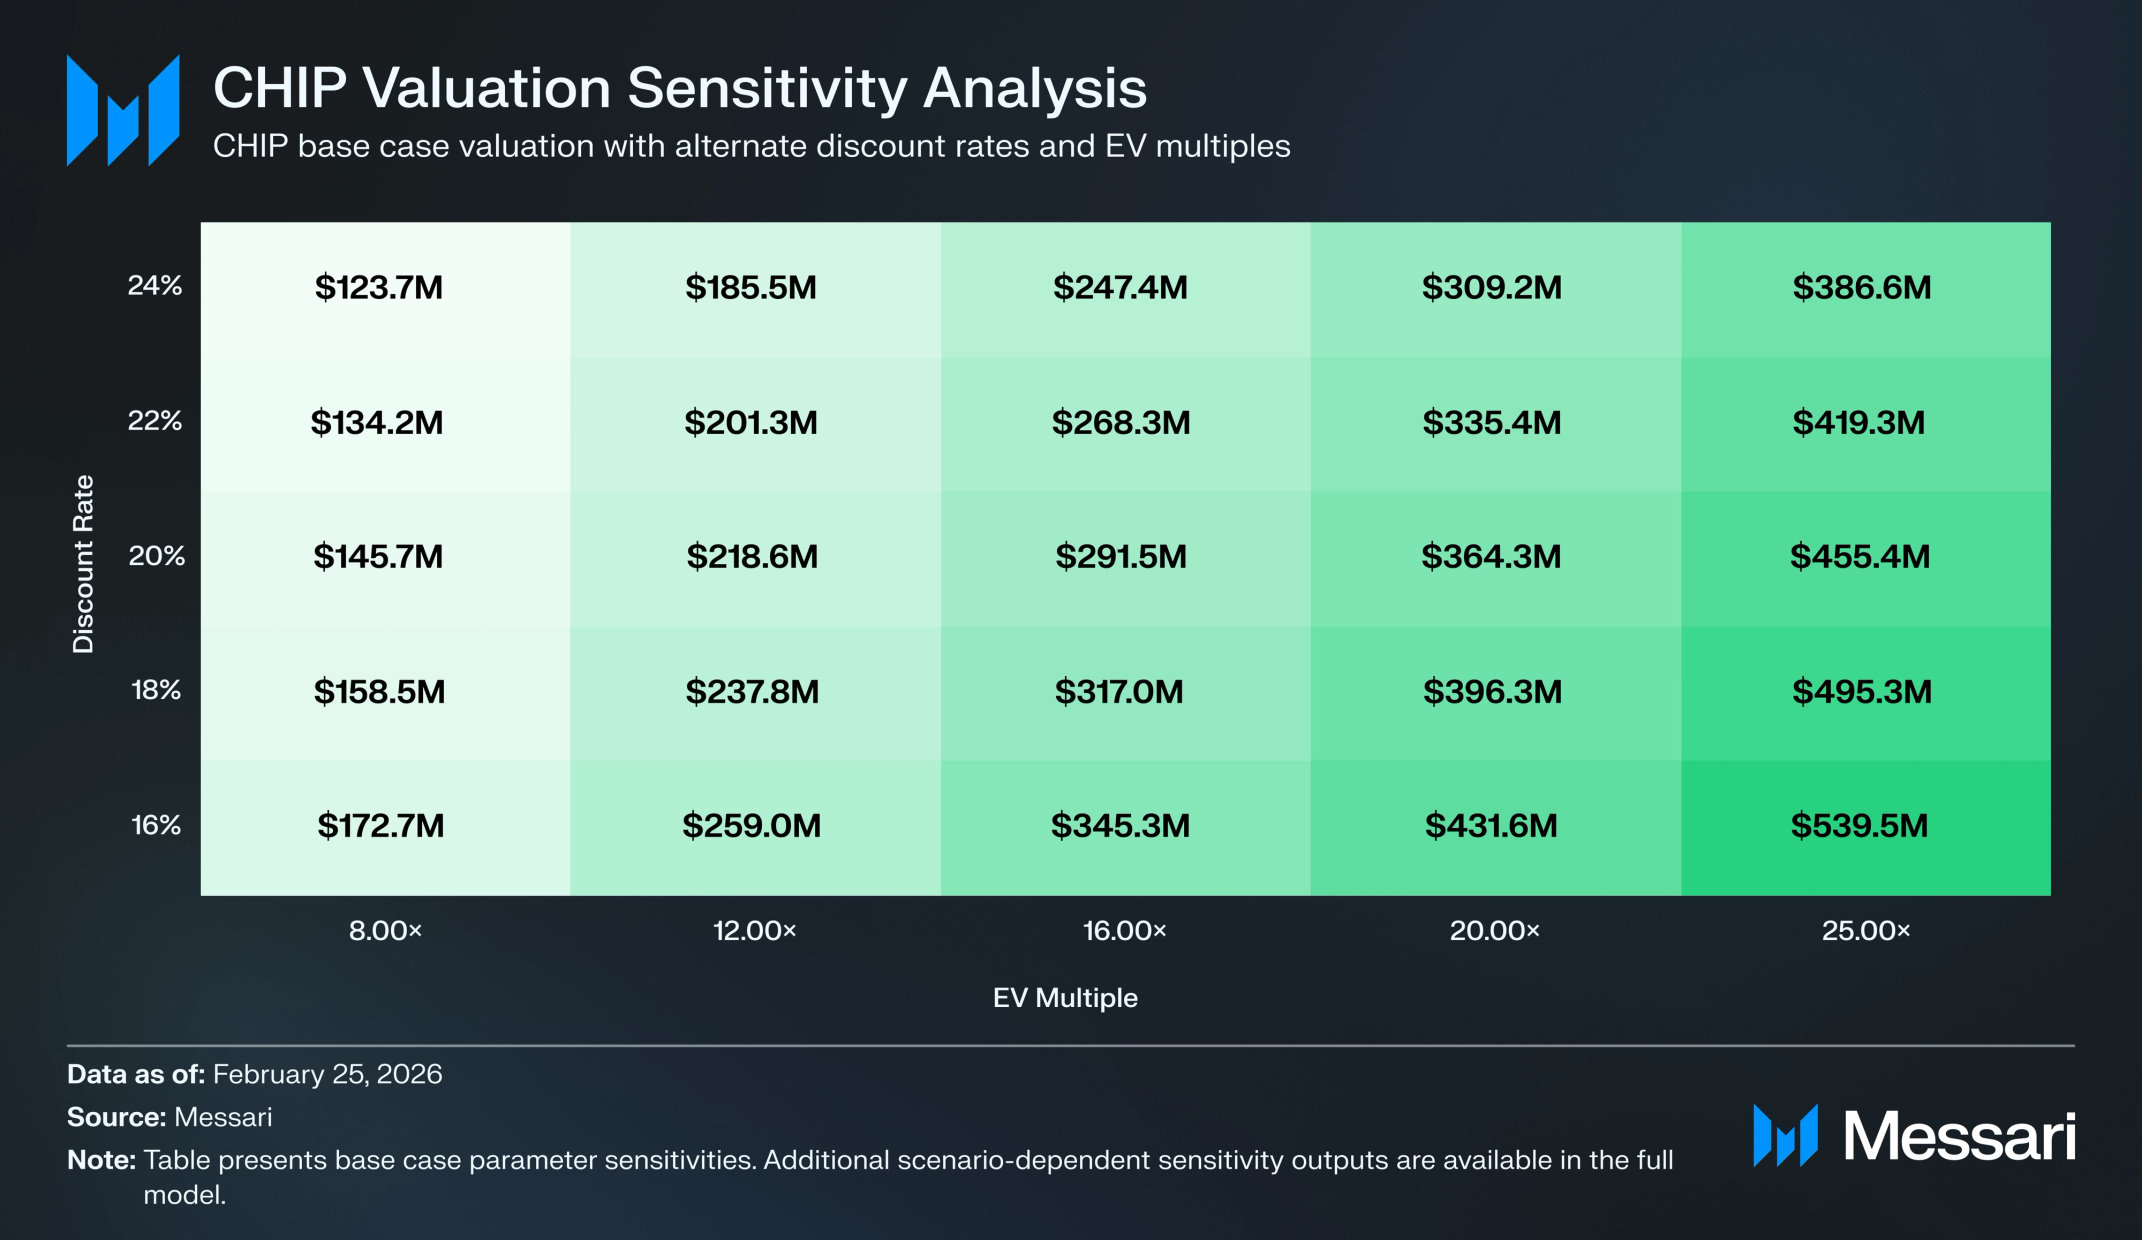
CHIP’s outcomes are evaluated across three sensitivity tables, each corresponding to a distinct economic layer of the framework: market pricing, governance execution, and capital adequacy.
The first sensitivity table evaluates the buyback-supported FDV across a grid of terminal EV multiples and discount rates, holding protocol mechanics constant. EV multiples range from 8× to 25×, while discount rates span 16% to 24%, reflecting a wide but defensible band for discretionary, governance-contingent surplus.
In weaker scenarios, valuation dispersion across this grid is relatively contained. At low origination scale and limited distributable surplus, even aggressive multiples or lower discount rates produce only incremental upside. This reflects a simple constraint that when surplus is small in absolute terms, changes in valuation multiples or discount rates have limited impact.
In the base scenario, sensitivity becomes more balanced. Moving from an 8× to a 16× multiple, or from a 24% to an 18% discount rate, produces meaningful changes in FDV, reflecting a point at which surplus exists and valuation depends on how investors price durability and governance credibility rather than on whether the system works at all.
In stronger scenarios, dispersion is driven primarily by the terminal multiple rather than the discount rate. At EV multiples between 16× and 25×, valuation outcomes expand rapidly, indicating that upside is increasingly determined by market re-rating of USD.AI as a durable onchain credit platform, rather than further improvements in origination throughput.
The second buyback sensitivity table evaluates how distributable surplus translates into token support, with two explicitly governance-contingent variables:
Buyback rate, ranging from 25% to 100% of distributable surplus.
Buyback effectiveness, ranging from 50% to 90%, represents the proportion of nominal buyback spend that translates into durable token supply reduction after accounting for liquidity depth and market impact.
This table makes clear that buyback-supported value is not simply a function of operating performance. Even at identical surplus levels, outcomes vary materially depending on whether governance prioritizes buybacks and whether those buybacks are executed efficiently.
At low buyback rates or low effectiveness, a large portion of economic value fails to translate into sustained buy-side pressure. Conversely, high buyback rates combined with strong effectiveness materially amplify token support. This sensitivity reinforces the model's core framing that buyback-supported value is a policy outcome, not an entitlement.
Insurance-capital-implied solvency threshold: capital adequacy sensitivity
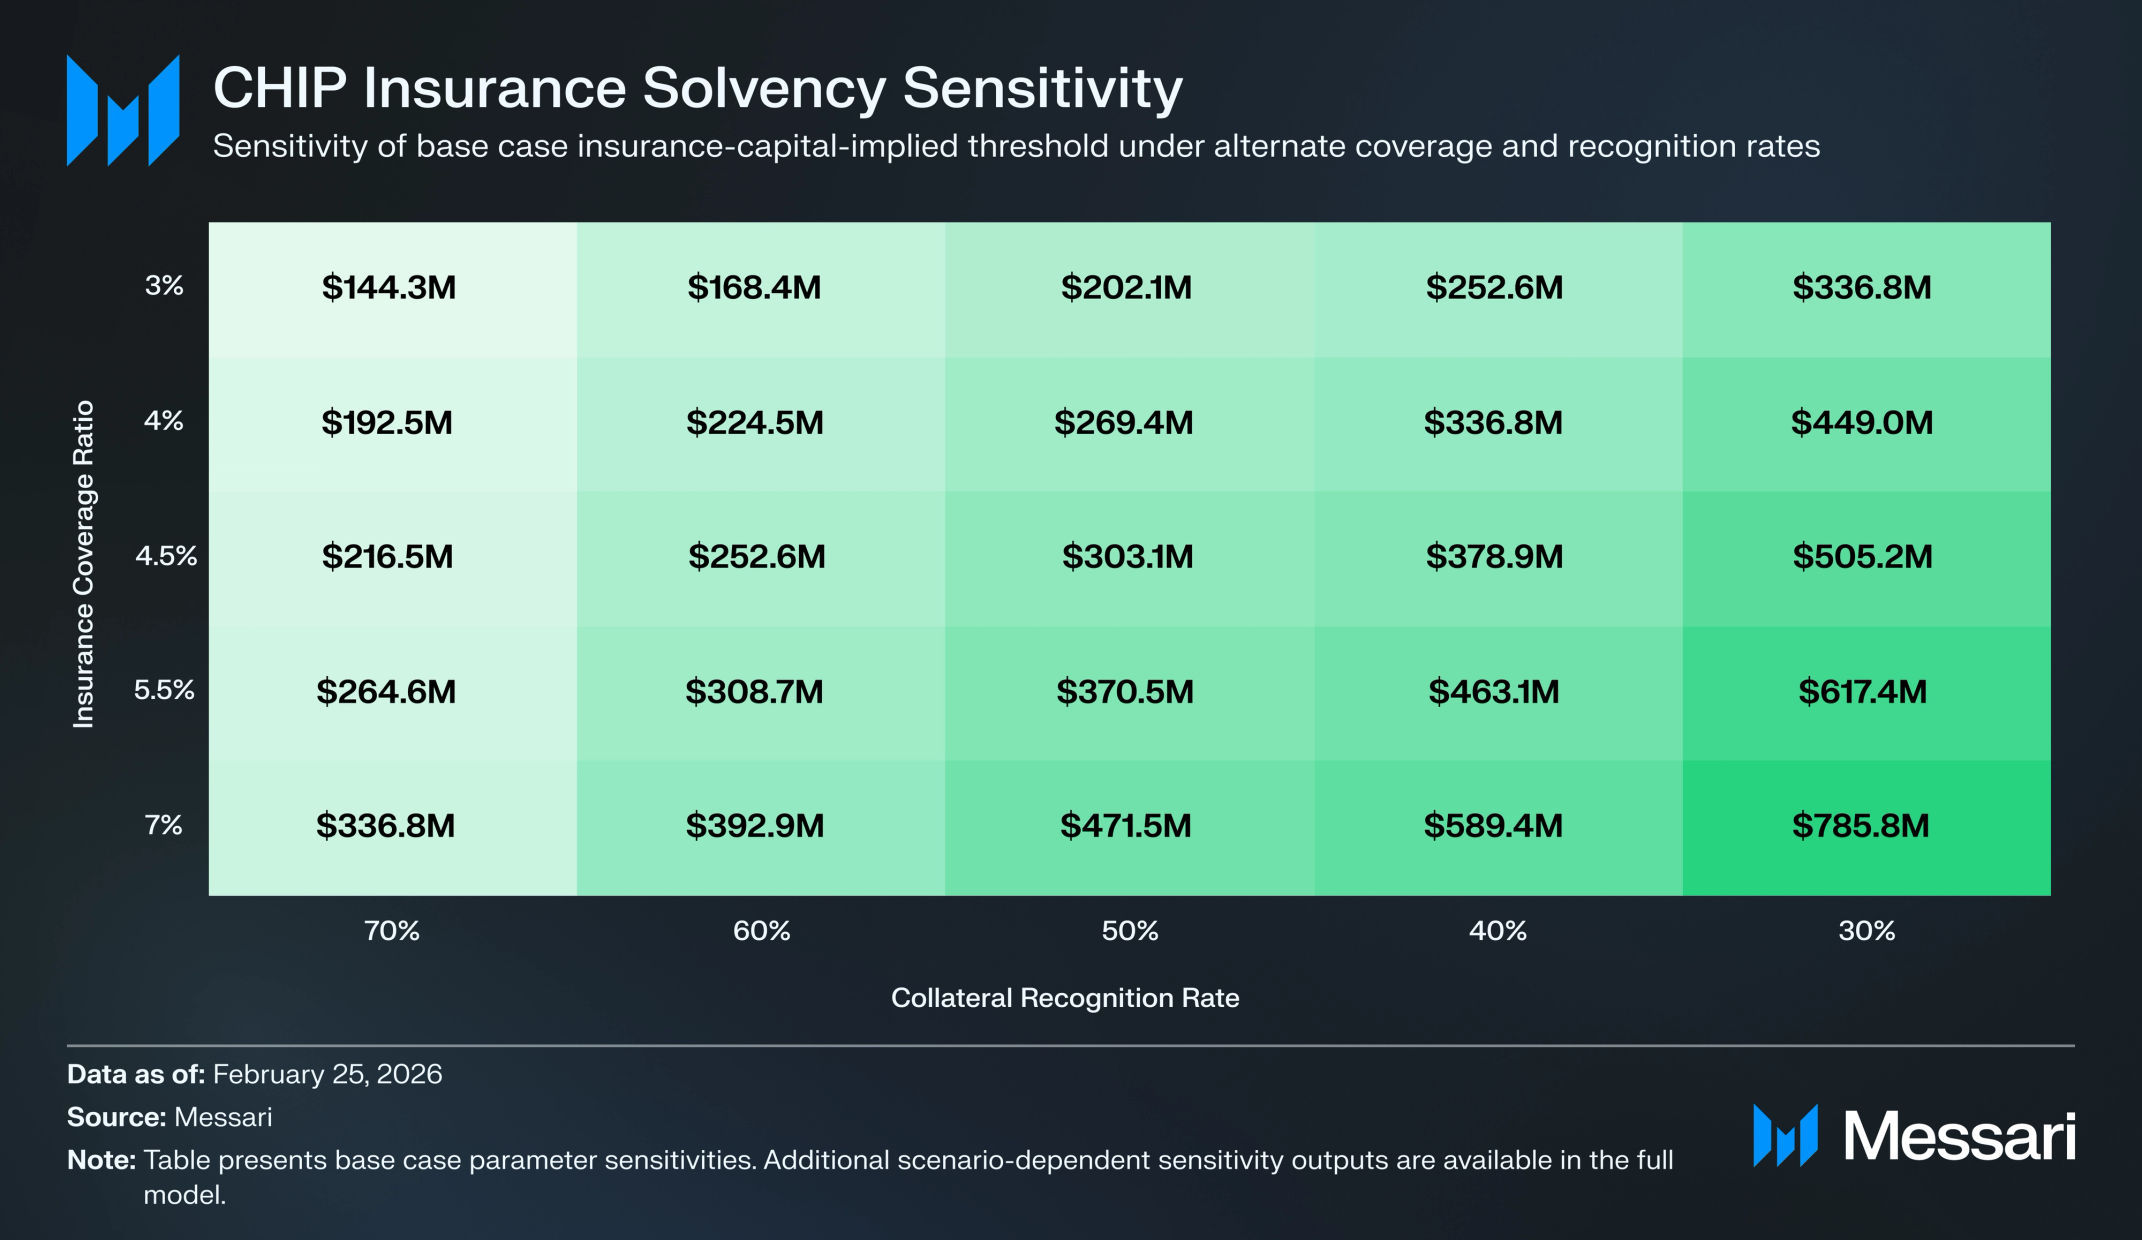
The third sensitivity table evaluates the insurance-capital-implied solvency threshold under varying:
Insurance coverage ratio, ranging from 3% to 7% of outstanding funded exposure.
Collateral recognition rate, ranging from 30% to 70% of staked CHIP.
This table behaves fundamentally differently from the buyback sensitivities. Higher coverage requirements or lower recognition rates increase the amount of capital the system must source, raising the implied solvency threshold required for CHIP to credibly function as backstop capital. Conversely, improved recognition or reduced coverage compress the implied threshold even in stronger operating scenarios.
This sensitivity explains why the insurance-implied solvency threshold can decline in bull cases. That outcome typically reflects improved capital efficiency rather than weaker fundamentals, as less backstop capital is required per unit of exposure.
Taken together, the sensitivity tables reinforce that CHIP’s valuation is constrained first by execution and mechanism design, and only secondarily by market pricing assumptions. Market multiples matter, but only after origination throughput, funding realization, governance capital policy, and insurance mechanics are credible.
The tables shown above reflect base-case assumptions. The full valuation model includes parallel sensitivity analyses for the bear and bull scenarios using scenario-specific inputs.
Risks
USD.AI operates at the intersection of onchain capital markets and real-world AI infrastructure finance. The primary risks are execution, margin, liquidity design, governance credibility, insurance adequacy, legal enforceability, concentration, and macro funding conditions.
The central operating risk is whether the $1.5 billion marketed pipeline converts into funded originations on predictable timelines. Key constraints include:
Hardware shipment and installation delays
Underwriting and legal settlement throughput
Borrower deployment readiness
Coordination across vendors, insurers, and custodians
Because protocol economics are driven by funded volume rather than signed pipeline, persistent delays would suppress fee generation, exposure growth, and net interest income. Upside scenarios are highly sensitive to funding realization.
Origination fees, servicing economics, and net interest spread may compress as additional capital targets AI infrastructure lending. Competitive borrower pricing or structurally higher depositor yields would reduce operating surplus even if origination volume grows. Since buyback-supported value scales with distributable surplus, margin compression directly pressures upside outcomes even in strong adoption scenarios.
USD.AI relies on QEV to manage redemptions against long-dated, illiquid collateral. The relevant risk is performance under stress. Potential failure modes include adverse selection in redemption timing, redemption clustering during macro or sector shocks, and mispricing of queue priority. If redemptions cannot be cleared predictably, sUSDai confidence could weaken, increasing funding costs or forcing more conservative system parameters that reduce capital efficiency.
CHIP’s value accrual is governance-contingent rather than mechanically enforced. Even if governance authority is real, the market will not price hypothetical surplus capture unless there is credible, repeated execution of tokenholder-aligned capital policies, such as buybacks, fee routing, or insurance-module incentives.
This creates two related risks: (1) governance may choose to prioritize reinvestment, growth, or risk buffers over tokenholder returns for extended periods, or (2) governance actions may be episodic, inconsistent, or poorly executed, reducing market confidence in future value accrual.
This uncertainty reinforces why our framework explicitly separates the implied solvency constraint from governance-contingent upside, rather than blending them.
The insurance module is a central pillar of USD.AI’s credit structuring and risk-transfer framework. However, the effectiveness of this structure depends on sufficient staking participation, realistic collateral recognition of staked CHIP, and sustained confidence in the insurance mechanism during stress events.
If coverage proves inadequate, or if staked CHIP is not perceived as credible backstop capital, the protocol may need to increase coverage ratios, raise incentives, or constrain growth. These adjustments would increase capital intensity and alter the solvency threshold required to maintain adequate coverage.
CALIBER is positioned as a legal and technical framework for tokenizing GPU hardware into enforceable onchain collateral. At scale, this exposes USD.AI to regulatory, jurisdictional, and enforcement risk, including mismatches between onchain representations and offchain legal claims, custody or insurance disputes, and regulatory changes affecting asset tokenization, secured lending, or stablecoin-denominated credit. Any breakdown in legal enforceability would undermine collateral credibility, impair recovery in default scenarios, and increase required risk buffers across the system.
Early GPU infrastructure finance is likely to exhibit borrower, vendor, and geography concentration, particularly around large facilities or marquee counterparties. Concentration increases tail risk from idiosyncratic failures, operational disruptions, or regulatory actions affecting specific counterparties or regions. While diversification may improve over time, early-stage concentration could amplify volatility in originations, defaults, and insurance outcomes relative to modeled averages.
Finally, USD.AI is exposed to broader macro and crypto market cycles. Periods of risk aversion, stablecoin contraction, or onchain liquidity stress could reduce available funding even when borrower demand remains intact. Because USD.AI monetizes credit flow and exposure, not just balances, prolonged capital market disruptions would directly impair throughput and revenue generation.
Closing Thoughts
USD.AI is attempting to build onchain credit infrastructure for one of the most capital-intensive markets, real-world AI compute deployment. Its core bet is not that demand for GPUs exists, but that this demand can be converted into a scalable, legally enforceable collateral and funding pipeline that onchain capital markets can underwrite. If successful, USD.AI would represent a meaningful step toward bridging DeFi liquidity with productive, non-crypto collateral.
The protocol’s differentiation is structural. CALIBER is intended to make physical GPU collateral enforceable and verifiable, while QEV is designed to manage redemption pressure against long-dated, illiquid assets through queue-based pricing rather than forced liquidity. This architecture is directionally consistent with the realities of infrastructure finance, but it also concentrates execution risk.
CHIP is best understood as a governance and risk-policy asset operating across two distinct economic mechanisms. The surplus-driven pathway depends on governance allocating distributable surplus toward buybacks and sustaining that policy over time. Separately, the insurance-capital-implied solvency threshold reflects the capitalization required if CHIP is relied upon as recognized backstop capital within the protocol’s coverage framework, where required coverage ratios and collateral recognition efficiency determine capital intensity. Under our modeled scenarios, buyback-supported FDVs range from $46.4 million (bear) to $329.6 million (base) and $1.74 billion (bull). The insurance-capital-implied solvency thresholds range from $270.1 million (bear) to $275.6 million (base) and $503.2 million (bull).
Ultimately, the investment question is whether USD.AI can consistently convert pipeline into funded originations at scale while maintaining capital efficiency and system stability, and whether governance establishes a repeatable, market-credible mechanism for CHIP value accrual. If funding realization improves, liquidity design performs as intended, and governance demonstrates disciplined capital policy, USD.AI can evolve into durable credit infrastructure with defensible economics. If execution latency persists, spreads compress before scale is reached, or governance value accrual remains aspirational rather than observable, CHIP’s upside case will be difficult for markets to underwrite regardless of AI infrastructure demand.
This report was commissioned by USD.AI. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.
Jake is a Research Analyst on the Protocol Research team. He previously worked as an Investment Analyst at an AI-driven crypto research platform and as a Venture Analyst at a digital assets venture fund. He advised multiple RWA tokenization projects on tokenomics. Jake graduated from the University of Southern California, where he studied Philosophy and Finance.
Jake is a Research Analyst on the Protocol Research team. He previously worked as an Investment Analyst at an AI-driven crypto research platform and as a Venture Analyst at a digital assets venture fund. He advised multiple RWA tokenization projects on tokenomics. Jake graduated from the University of Southern California, where he studied Philosophy and Finance.