The following report was written by Messari Hub Analyst(s) and commissioned by Terra, a member of Messari Hub. For additional information, please see the disclaimers following the article.
Real world financial markets could benefit from technology that makes them more widely available. They could also benefit from technology that allows fast, cheap, permissionless access. Robinhood promised wider access to stock markets for smaller retail investors, but has not completely delivered, nor are Robinhood-type apps readily available in less developed parts of the world. Decentralized protocols such as Mirror hope to disrupt the disruptors, and offer global access to financial assets for all.
Democratizing Financial Markets
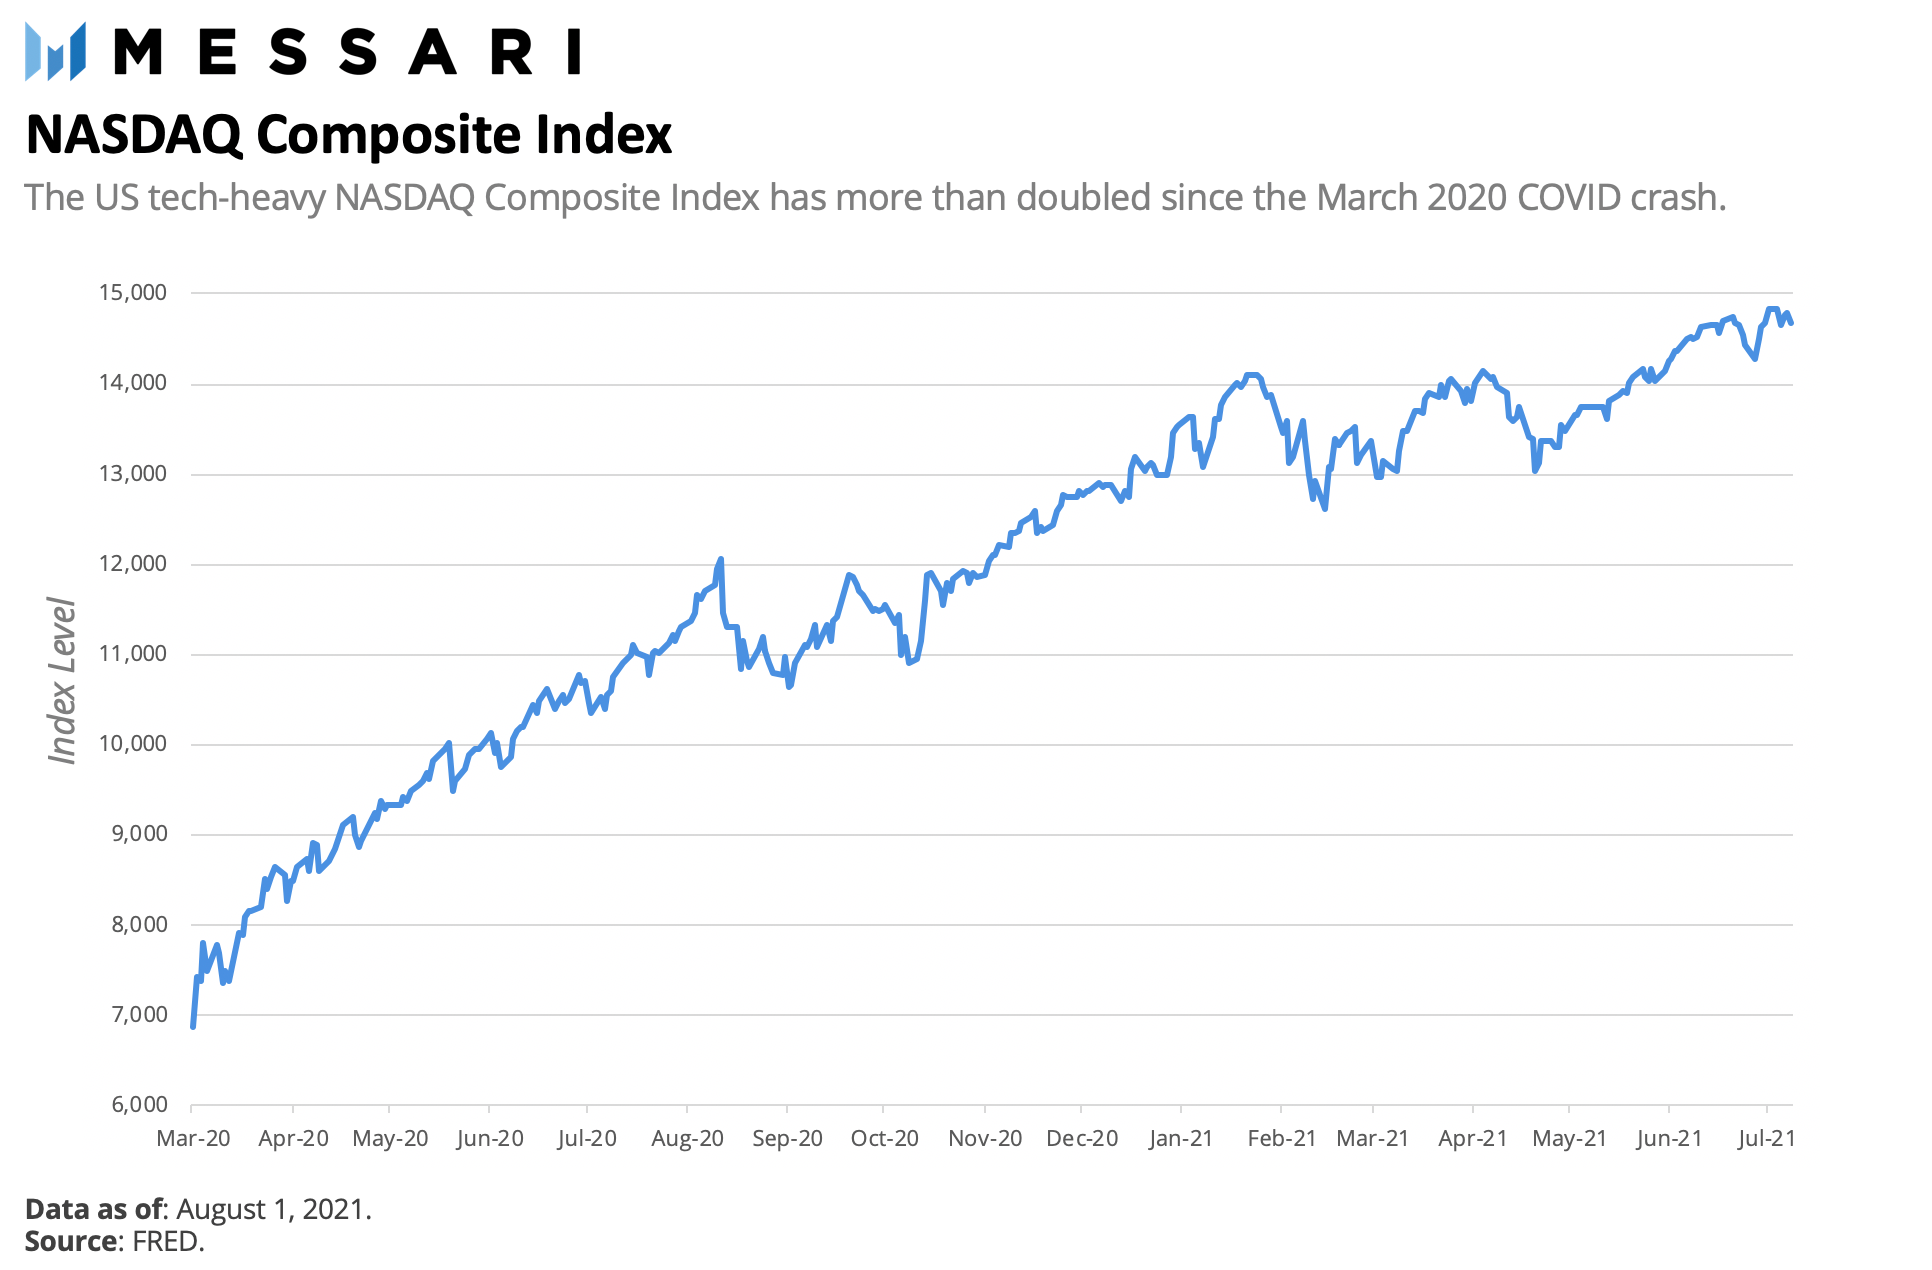
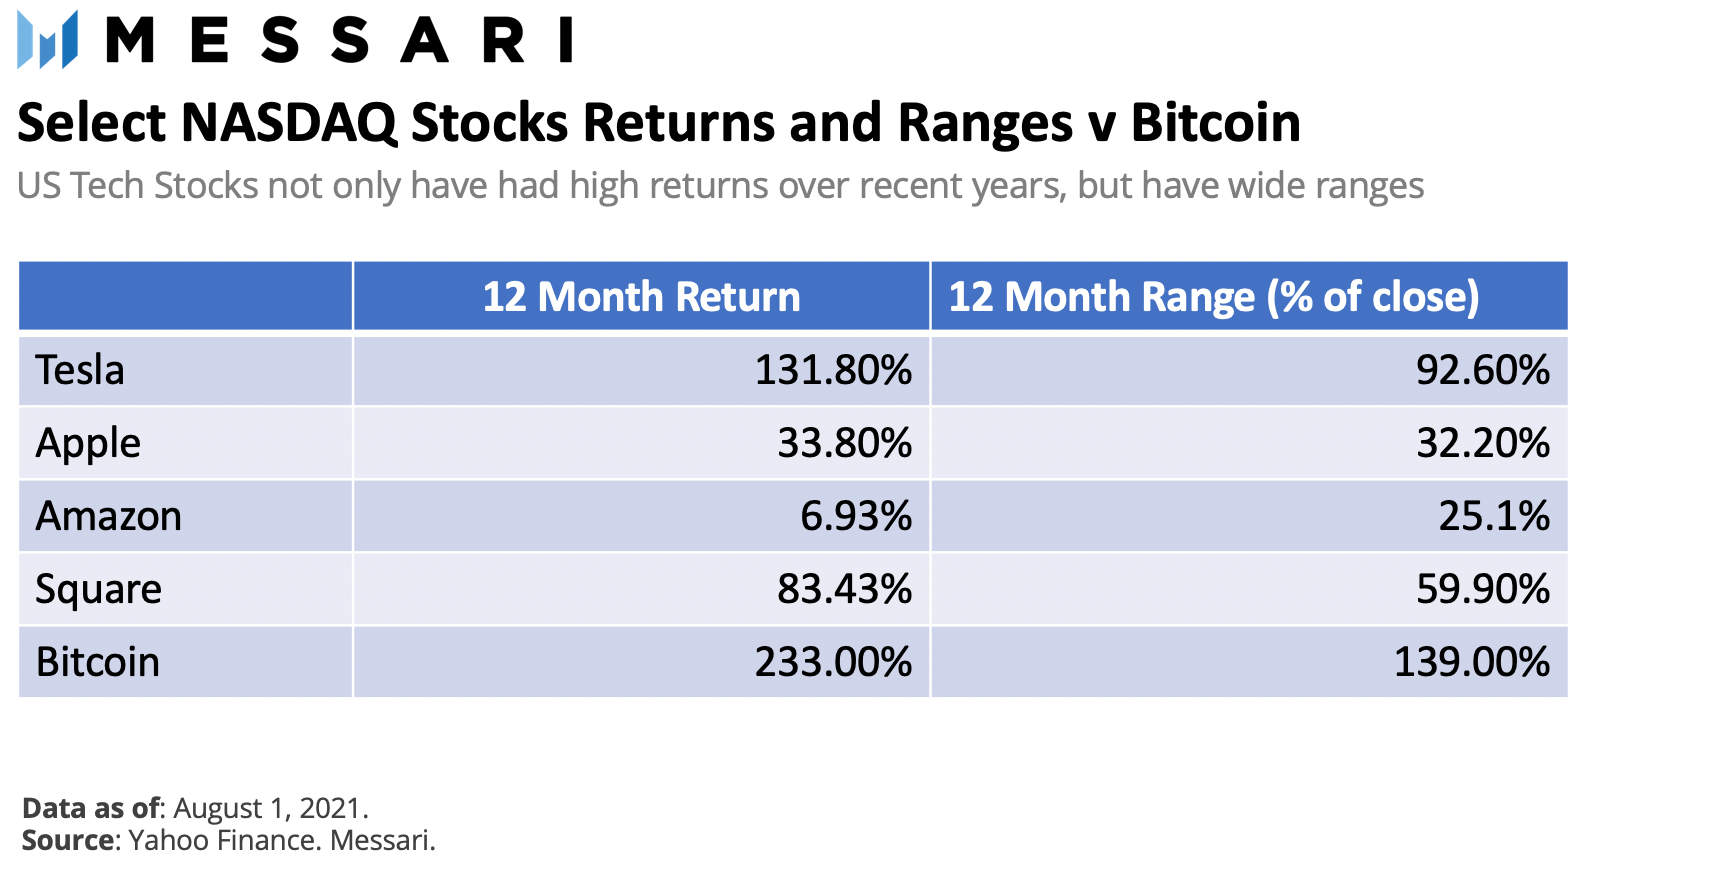
Retail interest in US stocks has never been higher, with many markets at near-record levels. The fastest growing US and global equities have provided their long-term owners with outsized gains and short-term traders the opportunity for profits given their volatile nature and deep liquidity. The NASDAQ has doubled since the COVID crash.
Though underperforming many cryptocurrencies, US growth stocks such as Tesla and Square have risen sharply this year, extending a bull market that began during the depths of the 2008-9 Global Financial Crisis. The NASDAQ is up more than 10x since then, and Amazon, for example, is up 45x.
While investors are attracted to US stocks for their long-term returns, more active traders favor the depth of the US equity and global currency (FX) markets. The NASDAQ and the NYSE together had a market capitalization of $45.7 trillion at the end of 2020, about 40% of the world’s total. The FX markets trade over $6.6 trillion per day.
Yet the stock and currency markets are weighed down by jurisdiction-specific regulation, multiple frictions (e.g. multiple fees and minimum order sizes) and the potential for market disruptions. Though new fintechs like Robinhood in the US democratize investing and trading by lowering commissions to zero and allowing the purchase of fractional shares, these apps are only available to residents of a select few countries. In Southeast Asia, which is Mirror’s primary target market, it is very difficult to get access to foreign stocks.
Even in the US, the recentGamestop debacle revealed that TradFi plumbing is broken: two day settlement in US equities allowed Robinhood’s partners toeffectively shut down access to the markets. Robinhood’s business model, selling order flow to intermediaries, is controversial in that it is unlikely to provide best execution to its clients.
Real World Assets, Mirrored
MakerDAO and Synthetix were early innovators in pegging tokens to real world assets. Initially they only supported tokens pegged to the US Dollar, but have since evolved to support other “synthetic assets”.
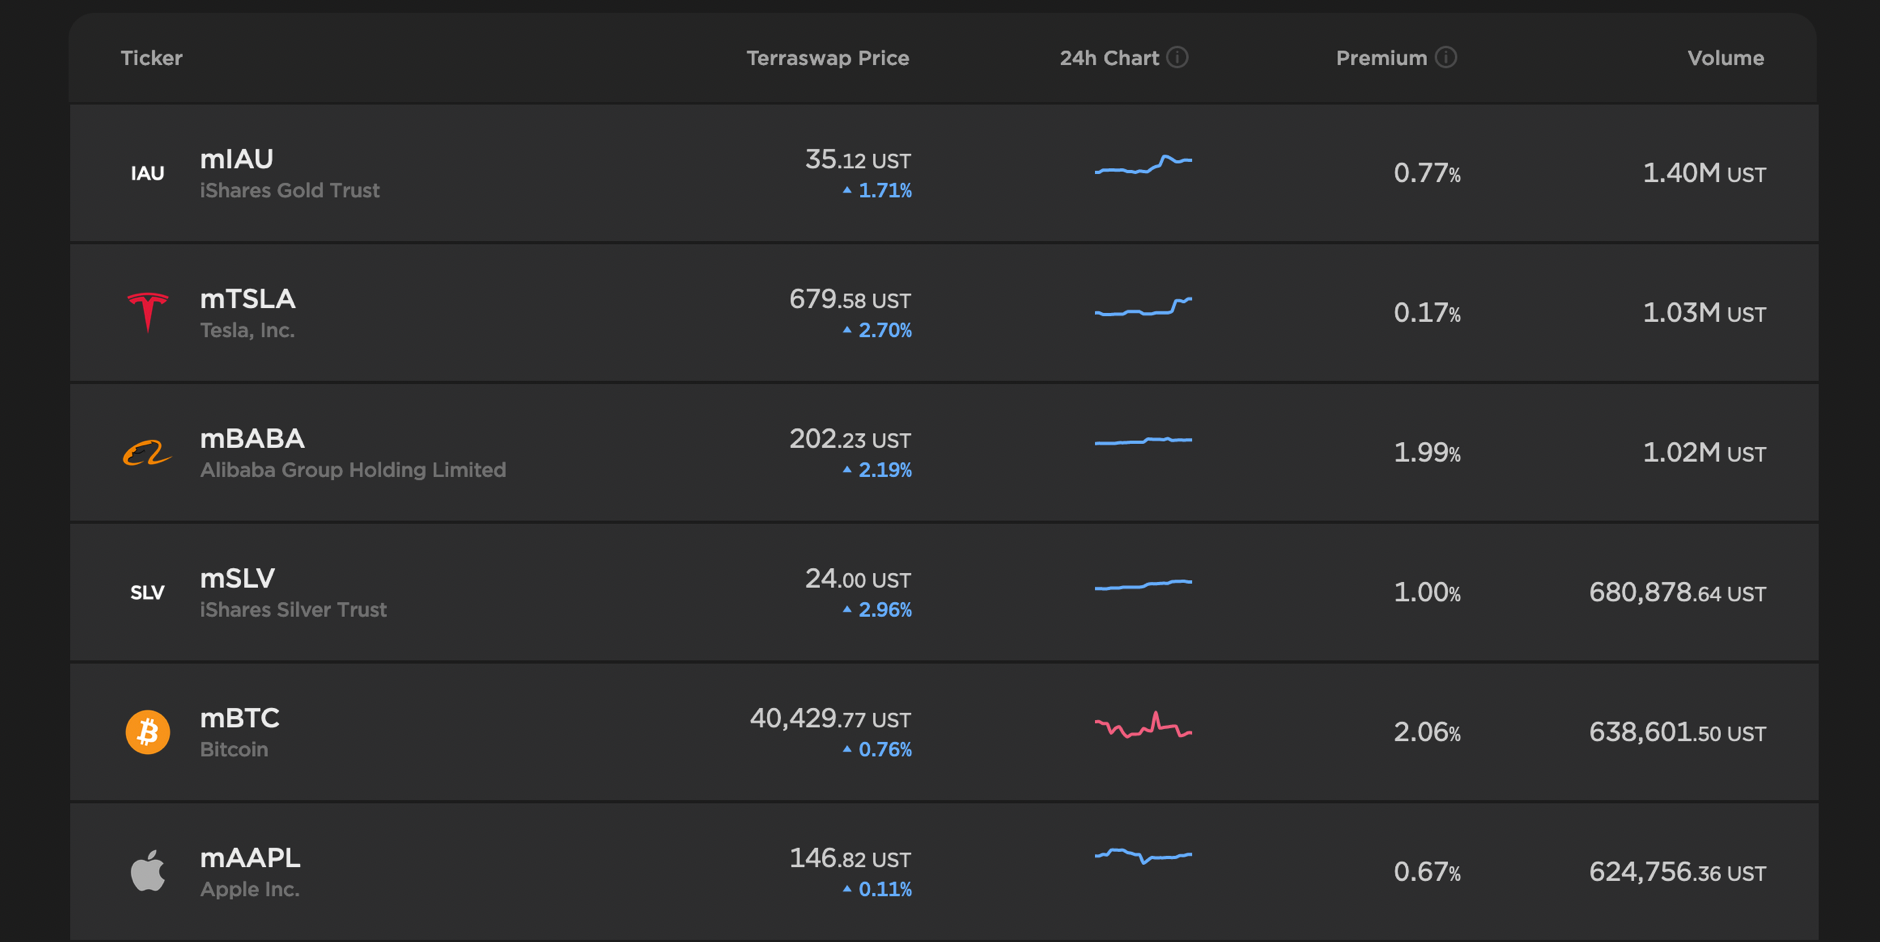
Mirror Protocol facilitates the creation of its synthetic asset tokens referencing real-world financial assets on the Terra blockchain. These “mirrored” mAsset tokens can be traded 24/7 on a range of venues including Terra’s own TerraSwap DEX, Uniswap, as well as a variety of other DEXs and centralized exchanges. mAssets can be minted and traded globally without permission, censorship, and at low cost on a variety of blockchains including Terra, Ethereum, Binanance Smart Chain, Solana, Polygon and Harmony.
mAssets and other crypto assets can be easily swapped in the same protocol and from the same wallet, making any asset re-allocation decisions fast, easy and inexpensive. Moving from crypto to cash equities could take days and require endless amounts of paperwork using traditional financial markets infrastructure.
Since its v1 launch in December 2020, Mirror’s mAssets have focused on Layer 1 cryptoassets, stocks, and ETFs. – . Currently, MIR holders can vote to whitelist any new real world asset as an mAsset: After the initial GME and AMC short squeeze, mGME and mAMC were added by the community. Mirror launched its v2 on Terra’s mainnet on June 25, 2021. This report focuses on the latest version, highlighting the innovations where applicable.
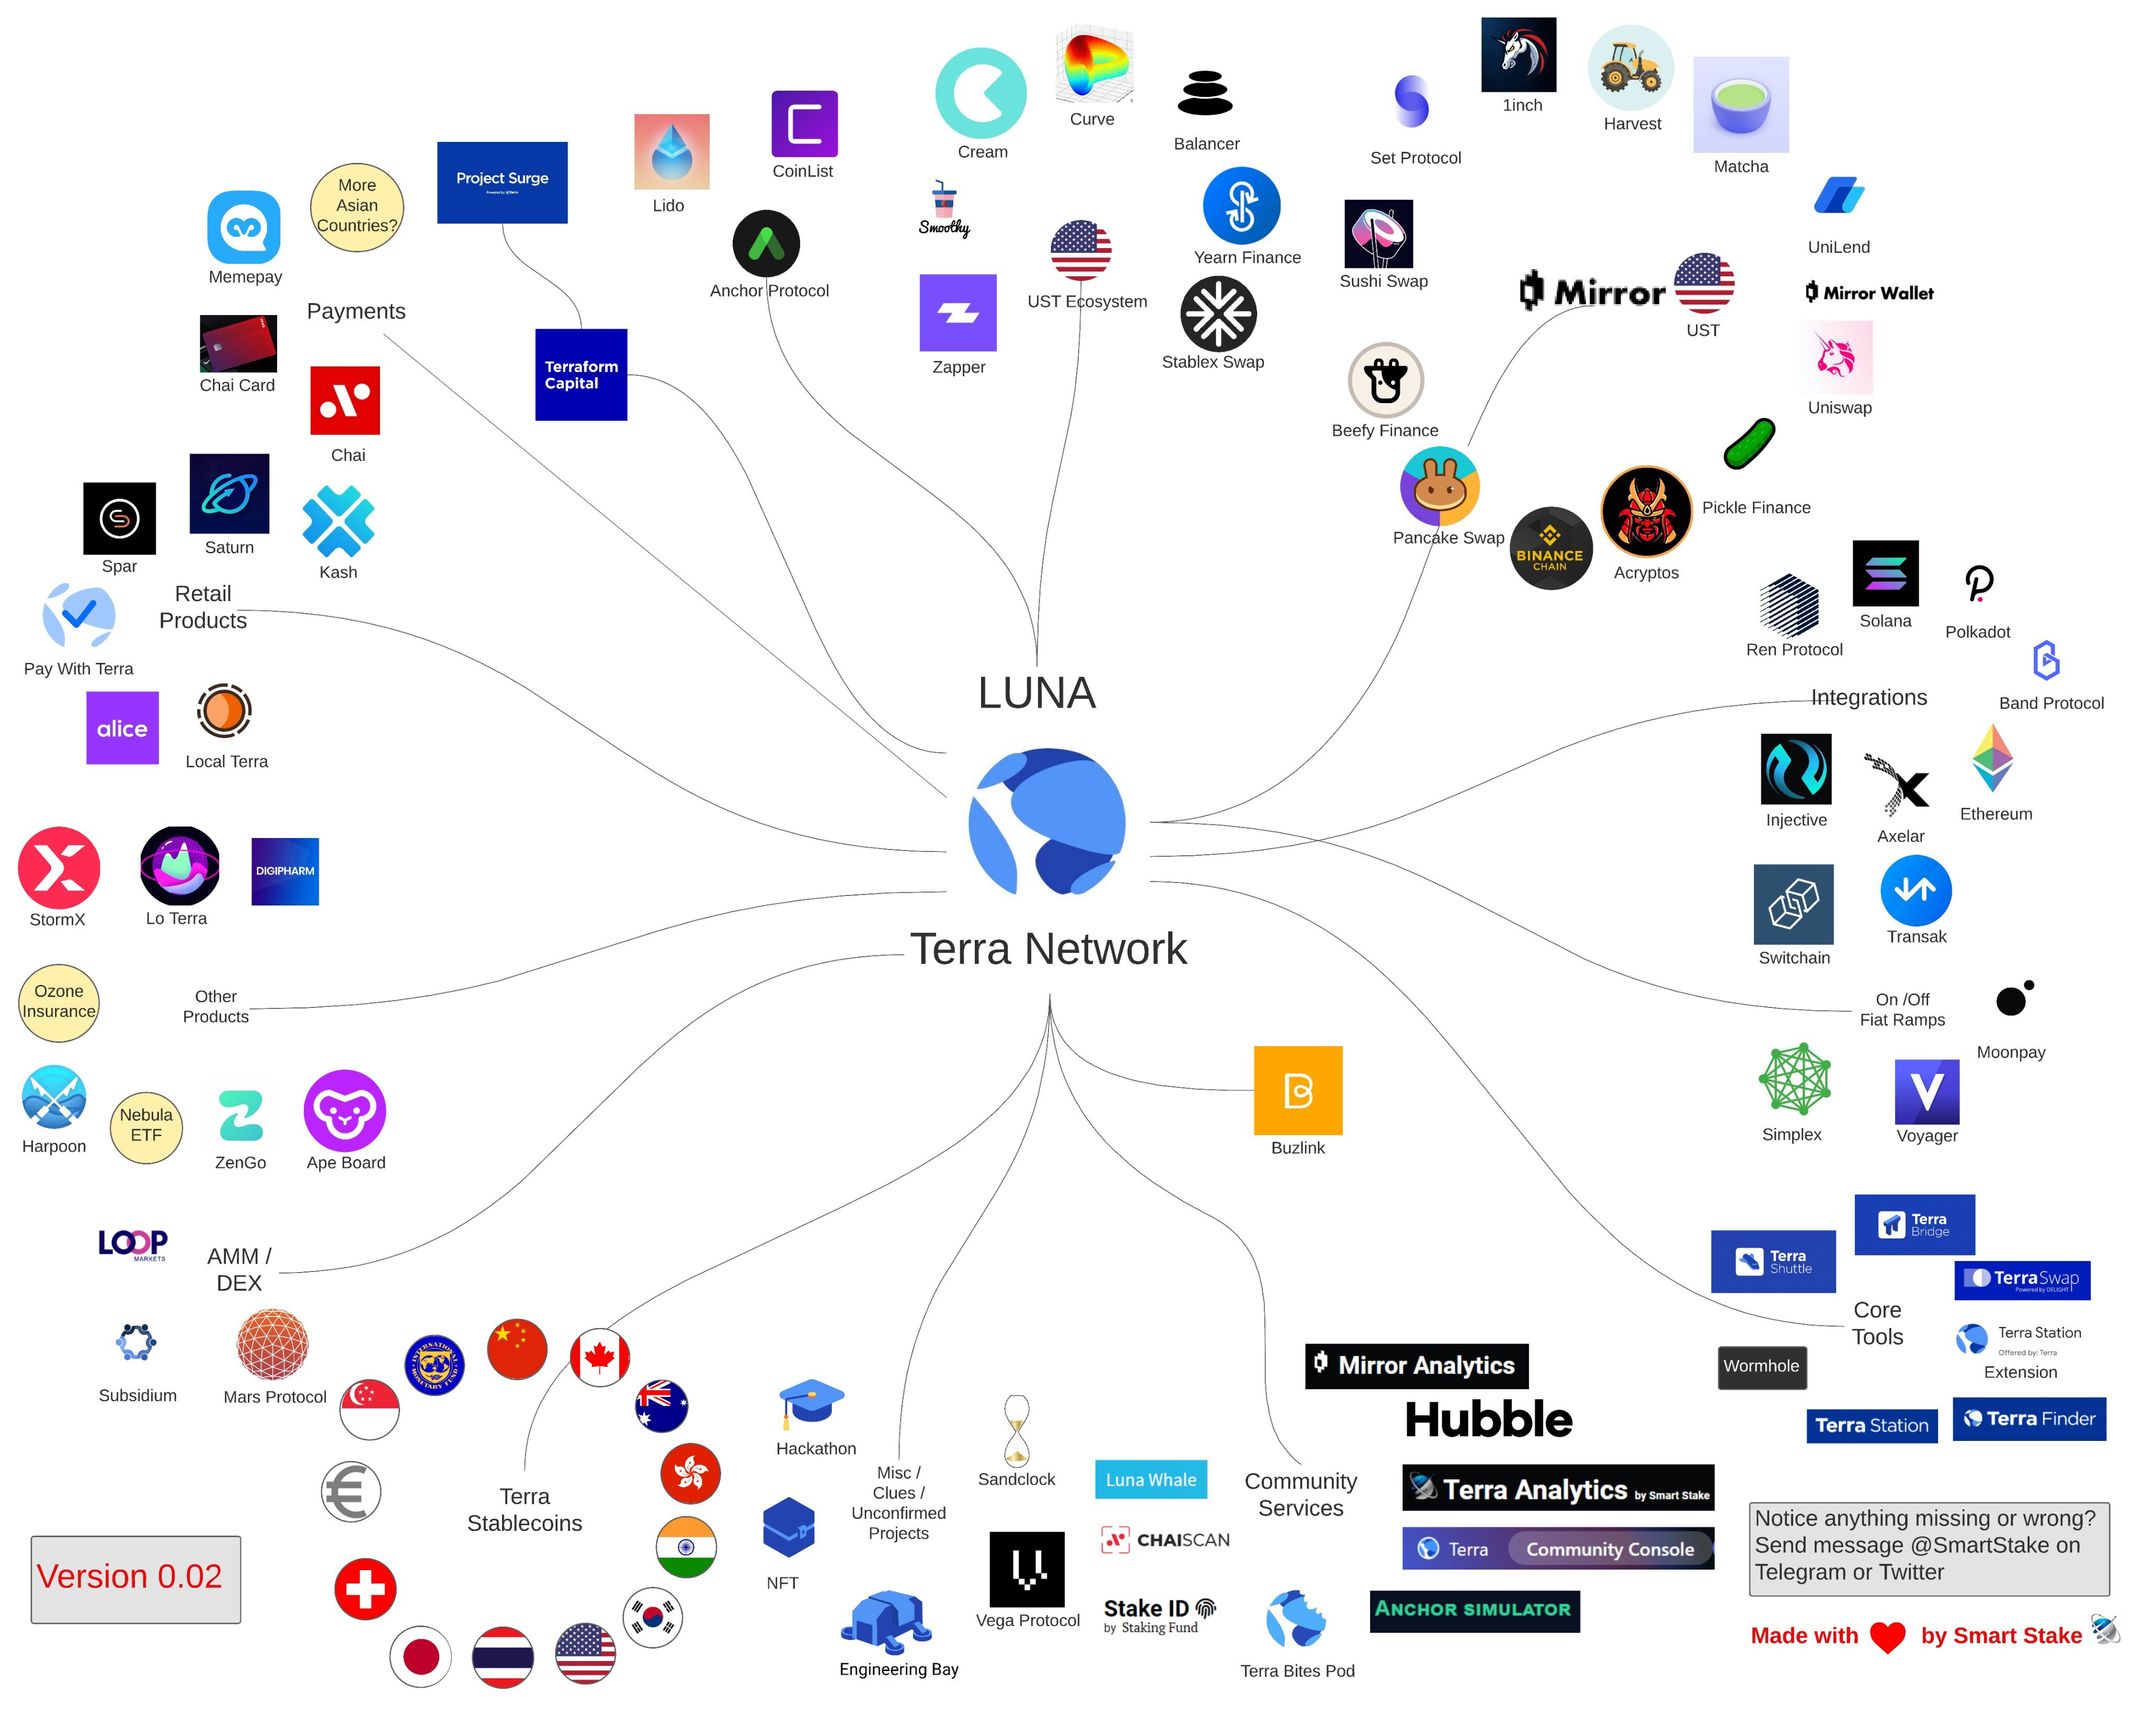
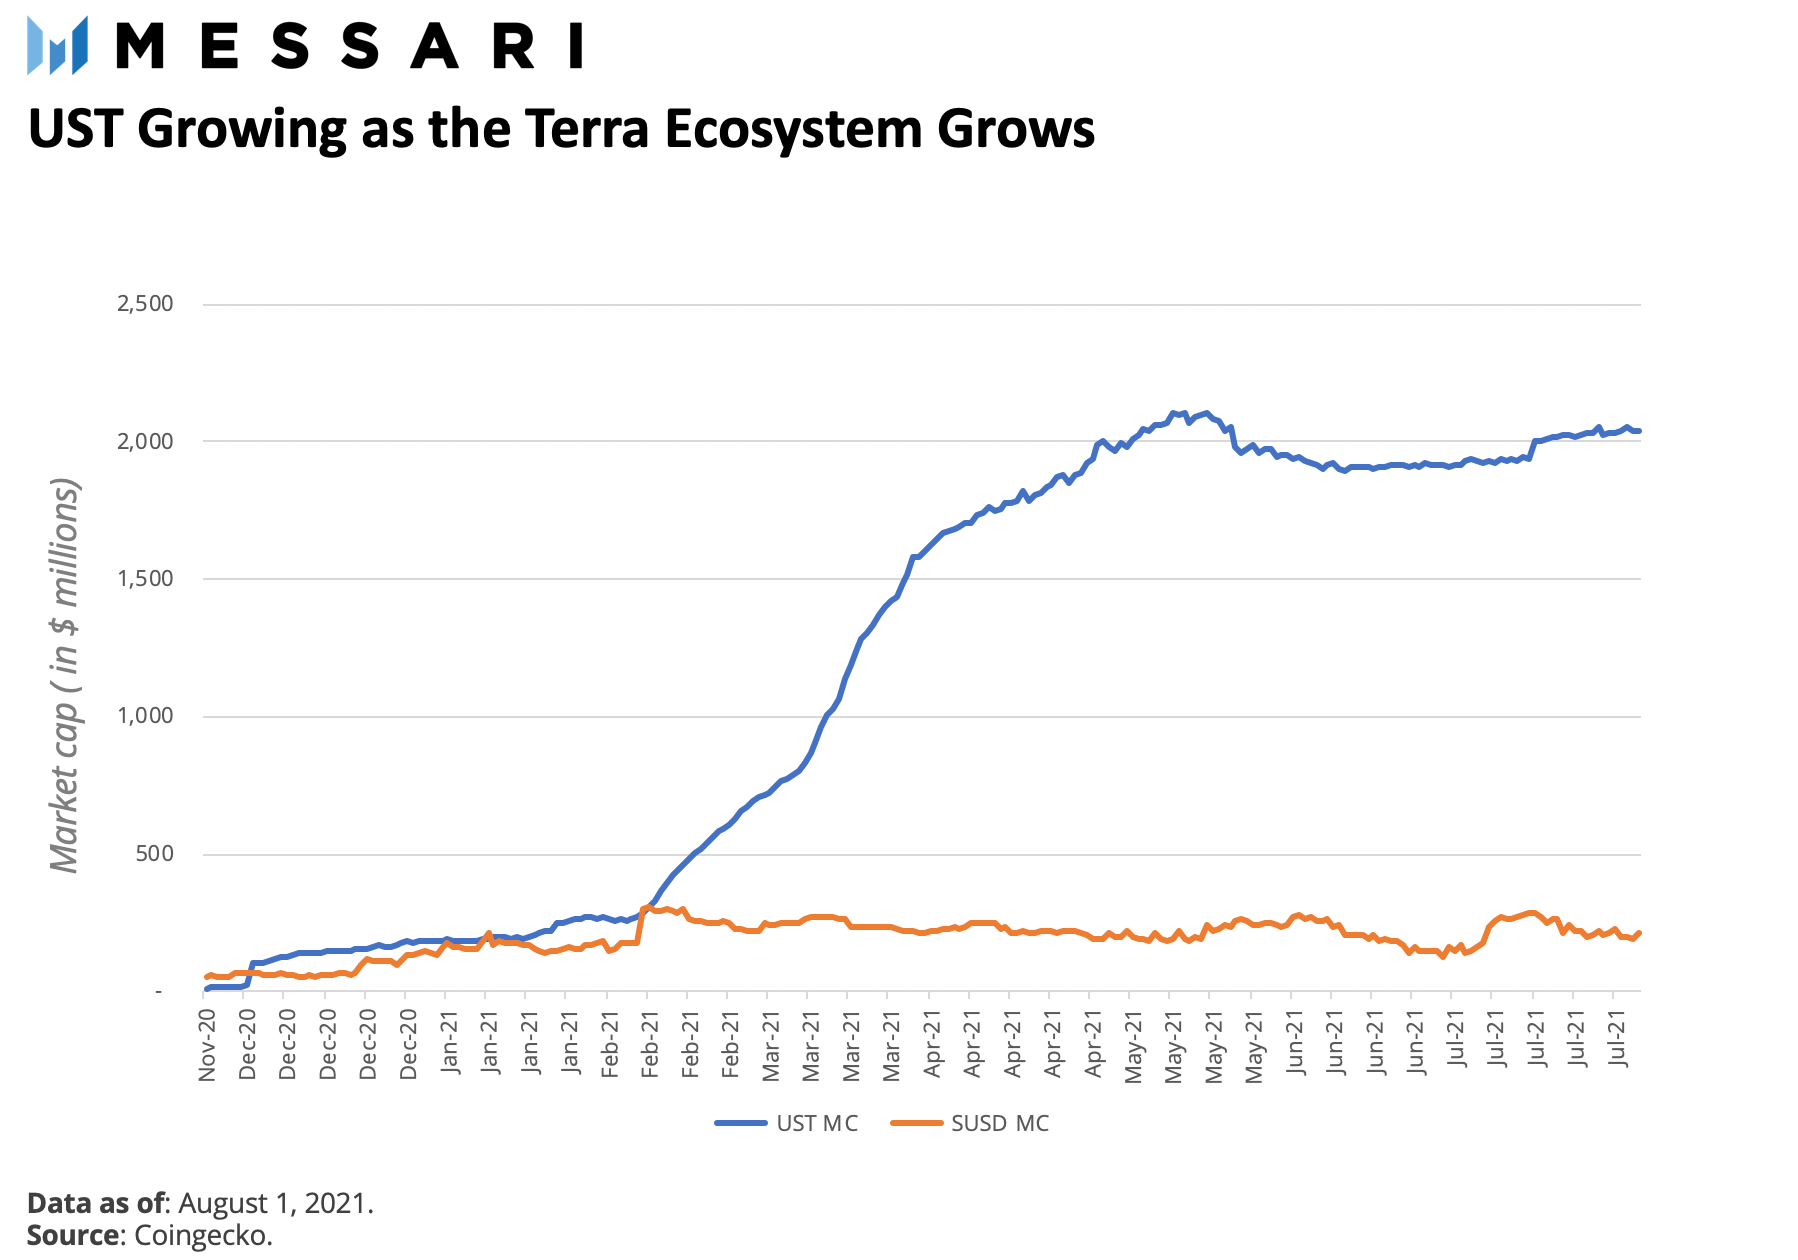
The Terra blockchain provides the foundation for Mirror. Terra is an application specific blockchain built using the Cosmos SDK that is dedicated to provisioning algorithmic stablecoins. In recent months since enabling smart contract functionality Terra has developed an ecosystem of applications around it that leverage its stablecoins to facilitate a wide variety of financial use cases. Mirror was the first major application launched on Terra and was a leading catalyst for the growth of Terra’s UST stablecoin which is the leading collateral asset for mAssets.
In order for an mAsset to be tradeable, it must be first minted. Users deposit collateral to create a collateralized debt position (CDP). In v1, a minimum loan-to-value of 150% in UST was required to mint and maintain an mAsset. V2 expands eligible collateral to Mirror’s governance token MIR, Terra’s native token LUNA and partner lending protocol Anchor’s token, ANC. These more volatile assets currently require 1.33x UST’s overcollateralization, or 200%. aUST, Anchor’s yield-bearing USD stablecoin, is also now eligible collateral with a 150% minimum.
The minting and current price of the underlying asset and its collateral are read through Band Protocoloracles. When a CDP’s collateral ratio falls below the minimum, by either the collateral falling in value or by the minted mAsset rising in price, other users can liquidate the CDP until it is brought back into compliance. The protocol will automatically readjust by burning mAssets.
A 1.5% protocol fee is paid whenever a withdrawal from a CDP is made, including through a liquidation.
One issue that is common with multi-collateral synthetic asset protocols is that minted assets often trade at a premium. Synthetic asset protocols always rely on arbitrage to minimize tracking error. When the mAsset is priced above the real asset, traders are incentivized to mint and sell the mAsset and purchase the financial asset. But this is costly and requires moving money and taking risk across markets that cannot be cross-collateralized. Additionally, the arbitrage cannot be properly executed when the cash markets are closed. Finally, minting costs are non-zero, meaning a premium could sustain itself for some time.
mAsset premiums have even greater tendency to persist in Mirror, as LP farming rewards incentivize mAsset long positions.
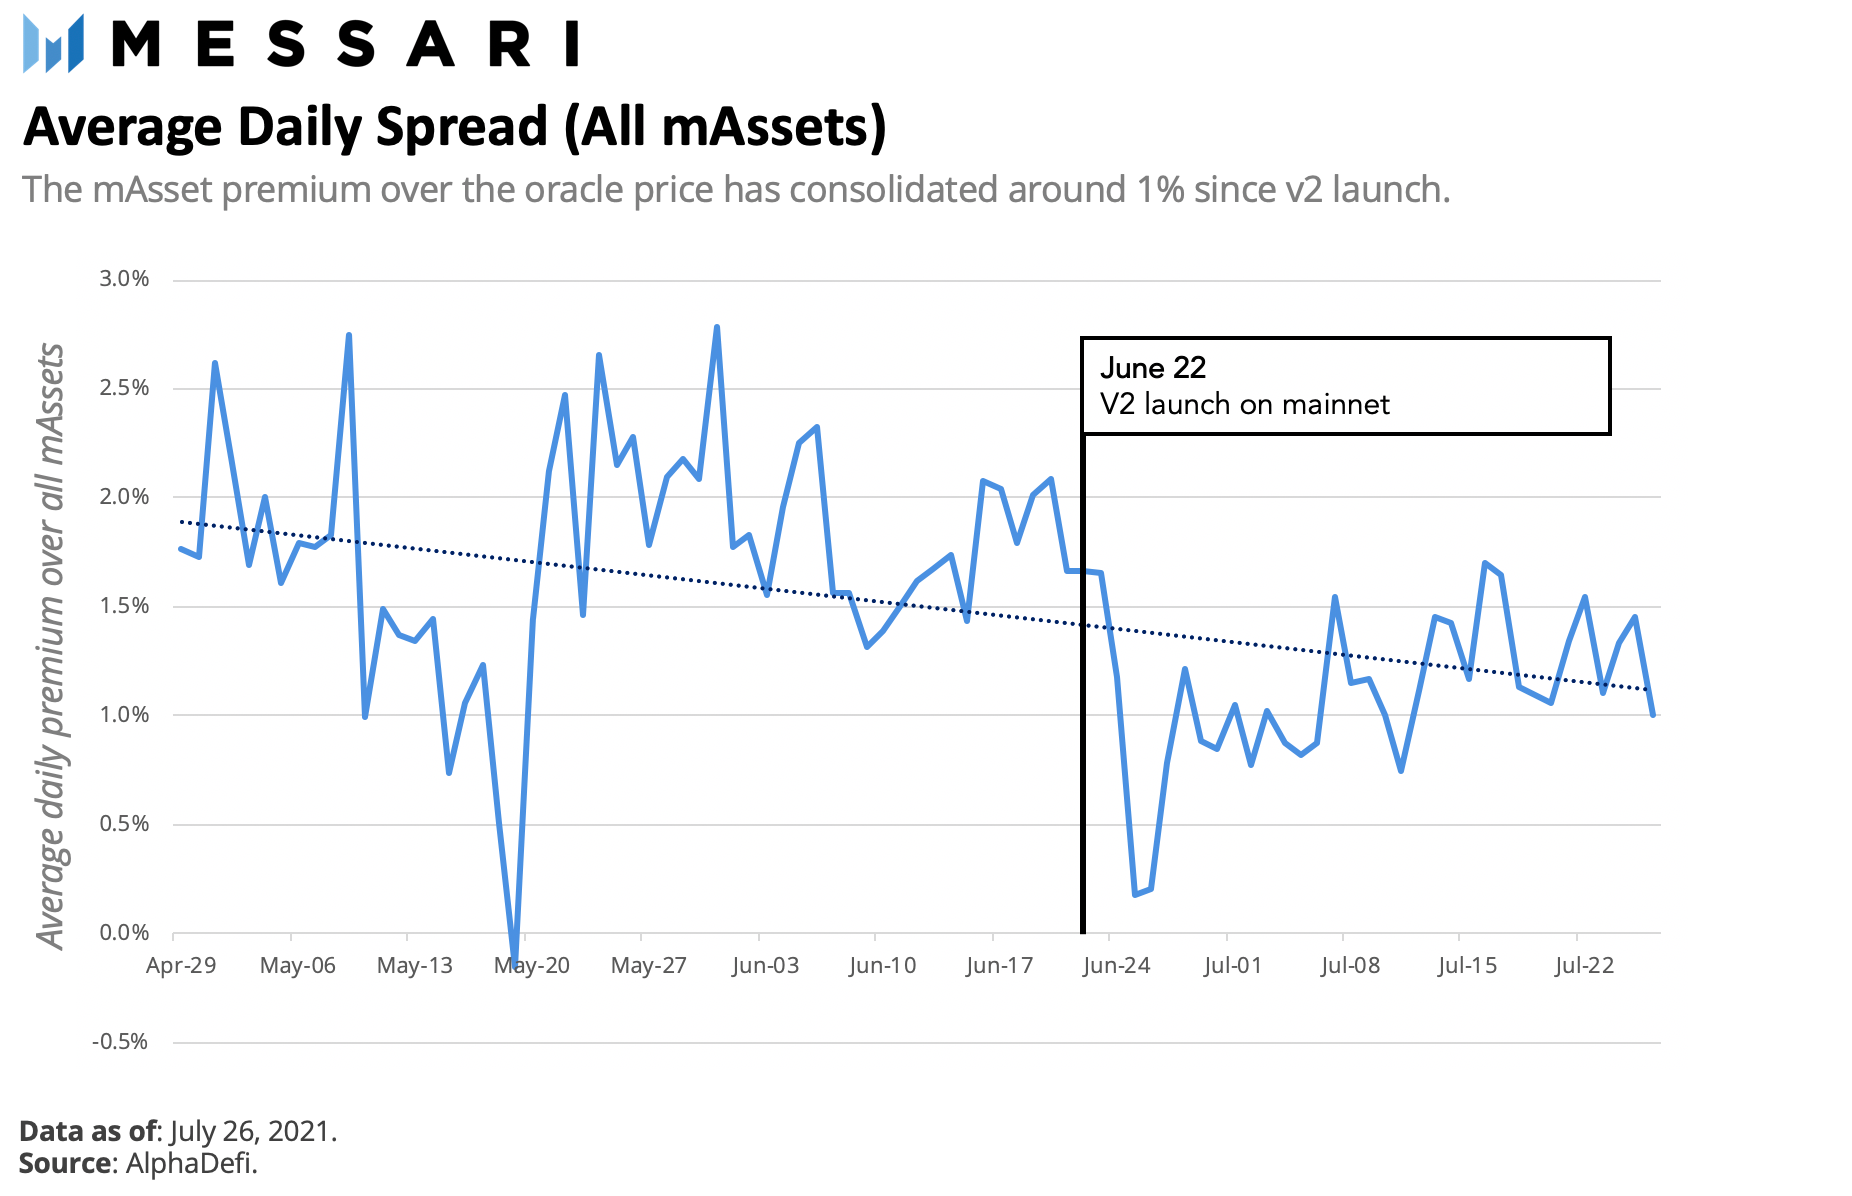
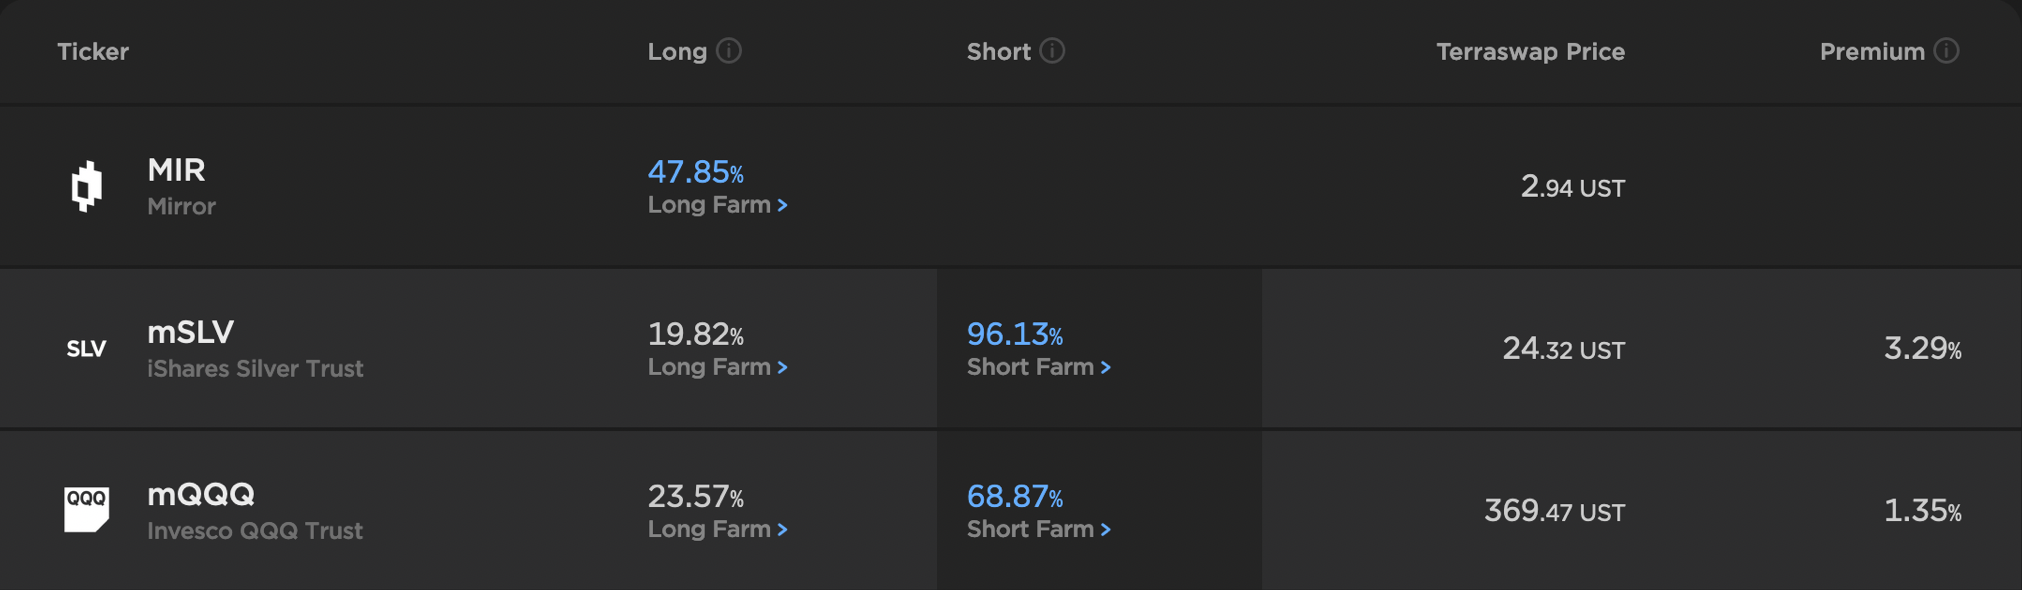
V2 promotes improved tracking by creating algorithmically-calculated rewards for minting a (non-tradeable) sLP (“short LP”) token that includes a short position in the mAsset that is immediately sold into the Terraswap AMM. The mAsset represented by the sLP token cannot be removed from Terraswap. The LP position profits from trades above the oracle price. sLP minting increases the mAsset/UST ratio in the automated market maker’s pool, putting downward pressure on the mAsset’s AMM price.
This new sLP functionality has resulted in somewhat smaller and less volatile premiums to date:
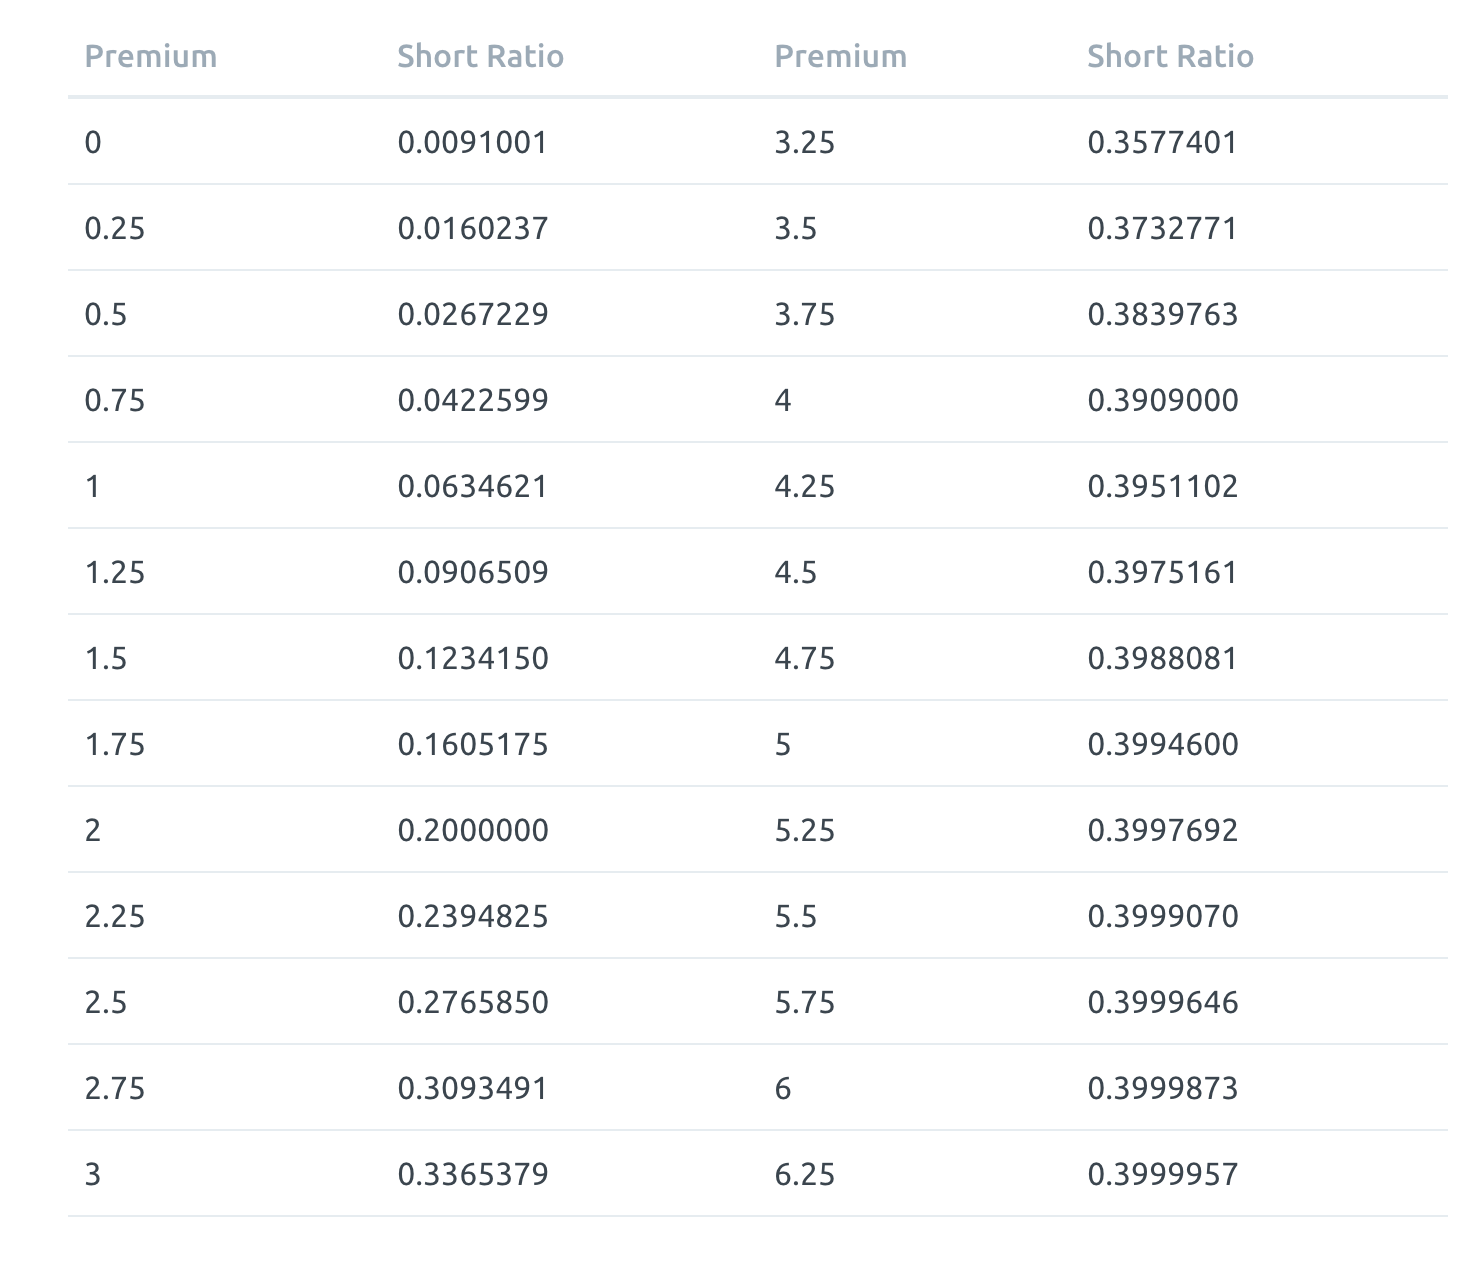
Incentives to mint and deposit mAssets or short sLP positions are paid in Mirror’s MIR token. Providing liquidity in mAssets and UST to TerraSwap creates a long farm position. Long farmers, who take LP positions on the TerraSwap DEX, earn LP commissions from Terraswap as well as MIR rewards. The short farm rewards are taken from the LP commissions plus long rewards – up to 40% as the premium increases:
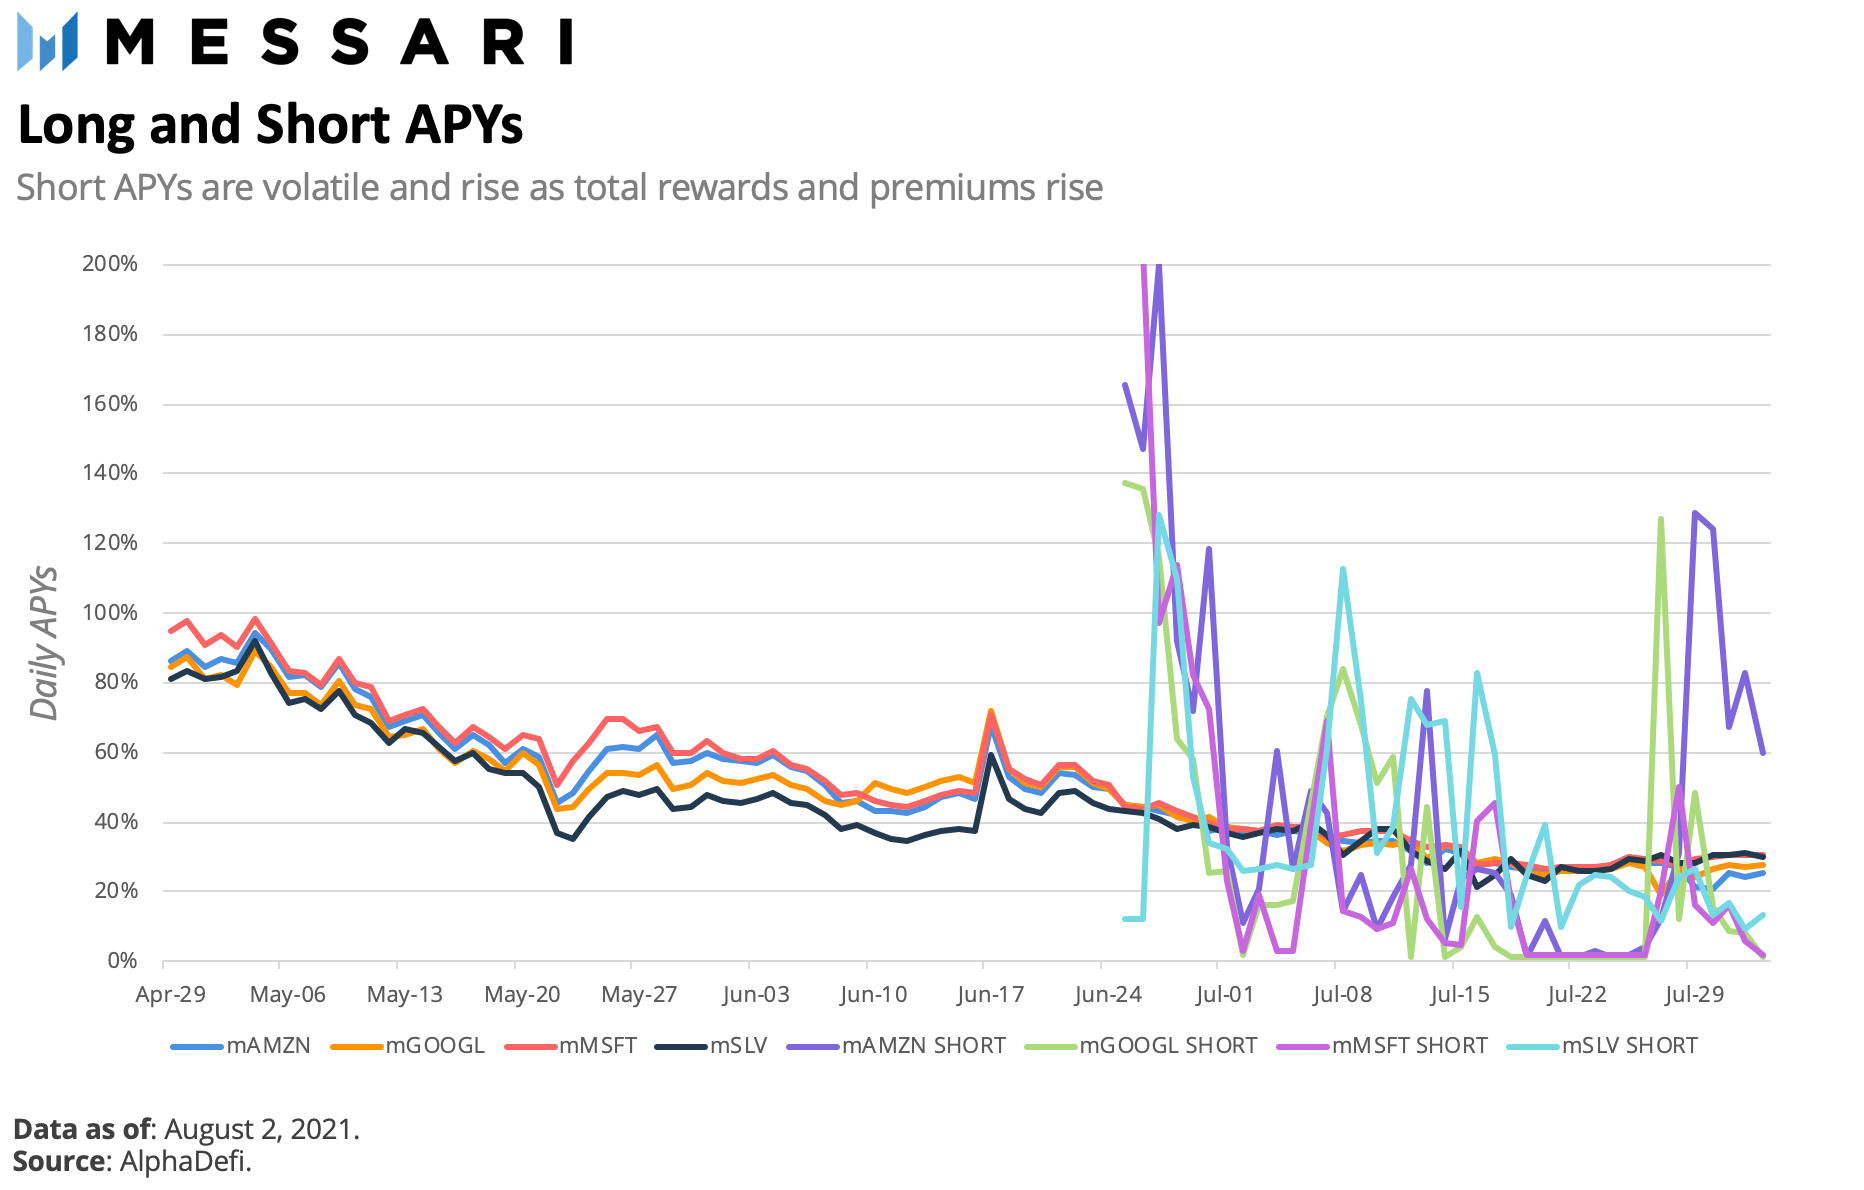
At a 6.25% premium, sLP holders receive the maximum of 40% of all LP rewards plus any decline in the premium when the short is closed out. Since v2 introduced short sLPs, the short APY has been extremely volatile as incentives adjust to dampen premiums.
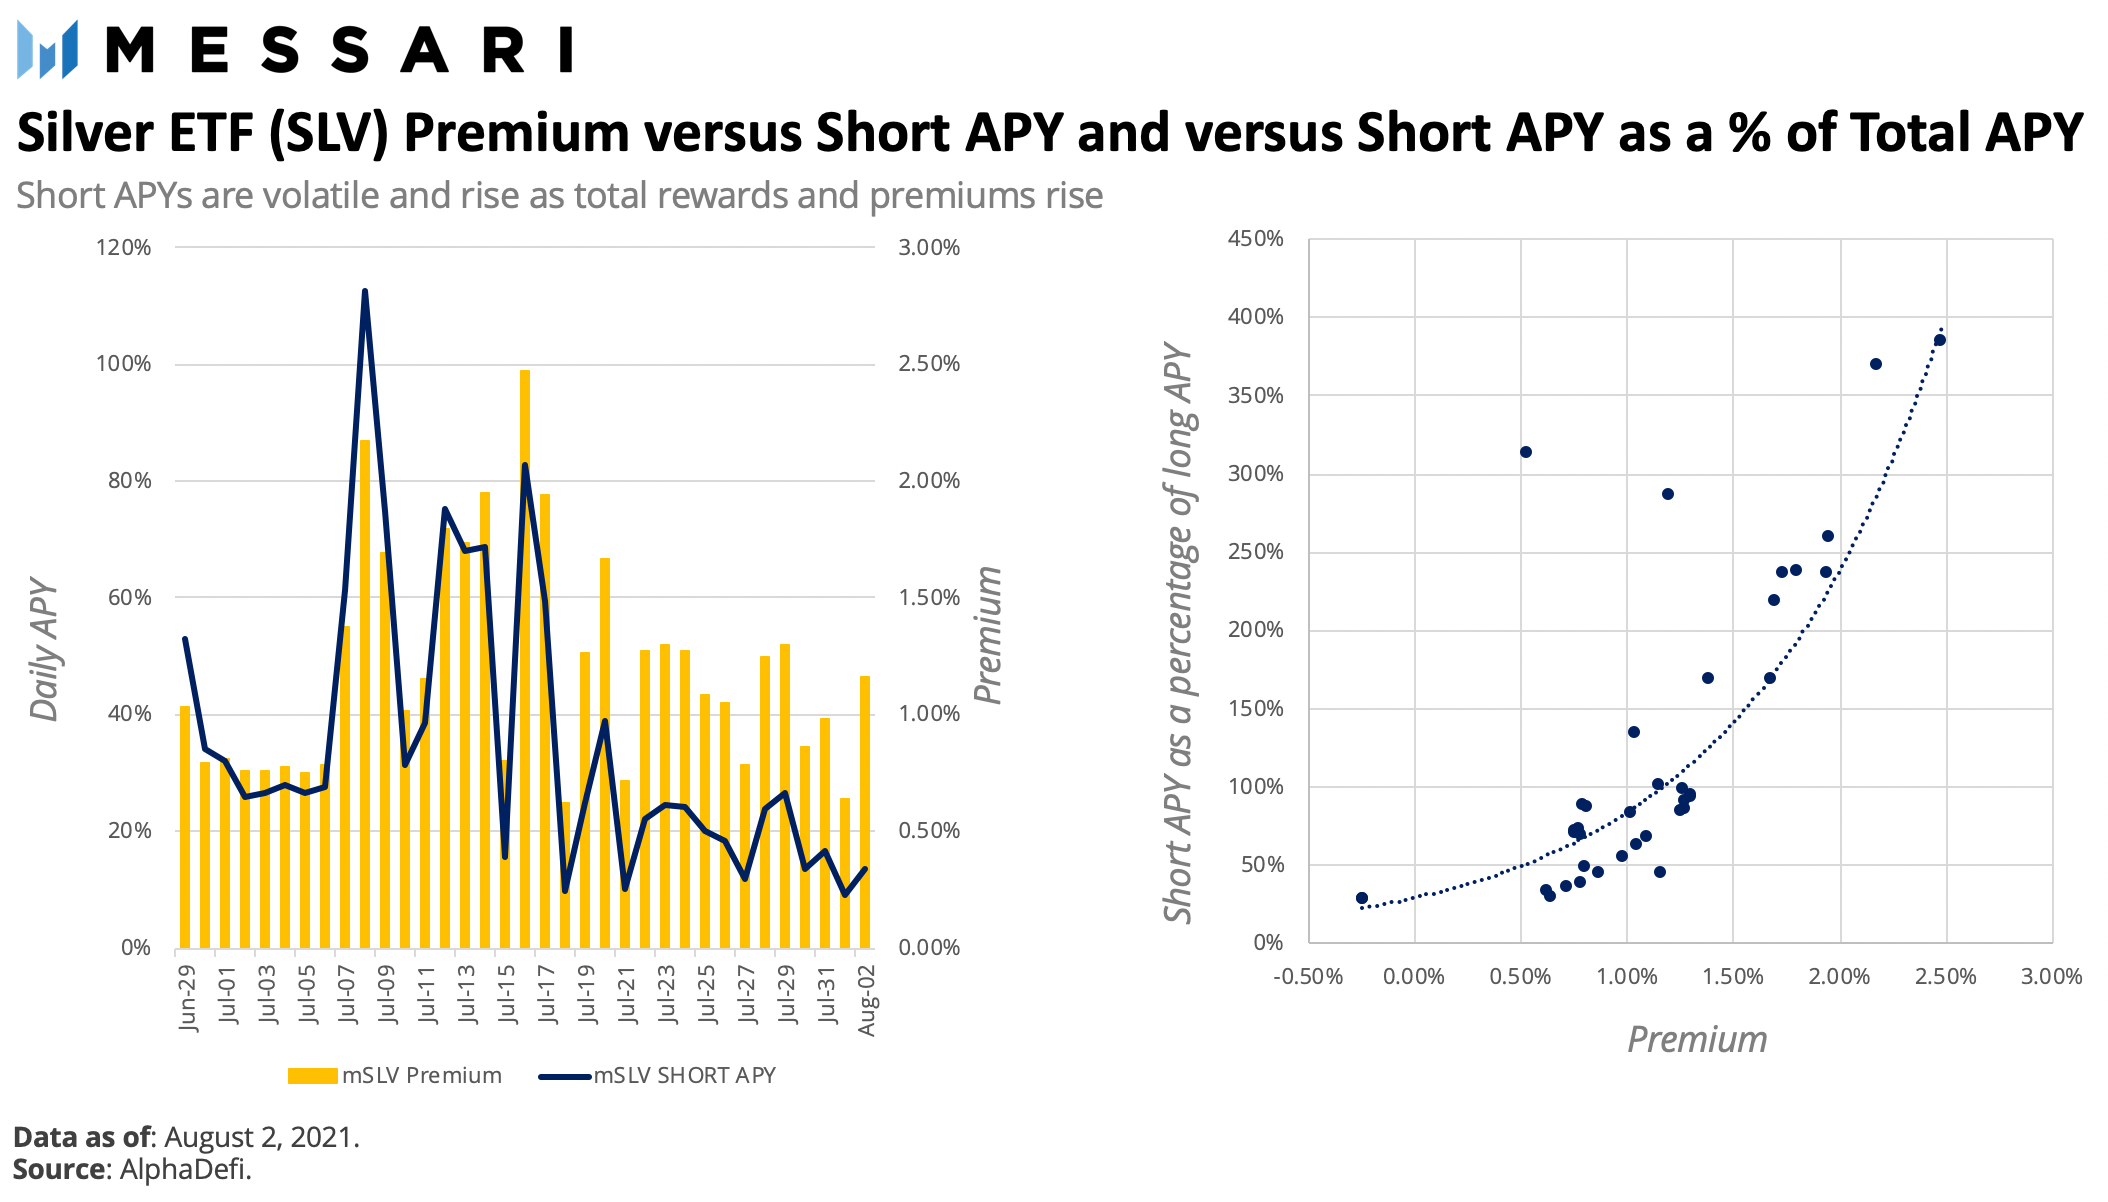
But the mechanism appears effective. Here is the (highly correlated) relationship between one asset’s premium and its APY. The premium for this one asset – mSLV based on a silver ETF – has been in a tight range since V2 launch.
Shorting through an sLP token has several complications. The resulting UST received in return for the sLP deposit is locked in for two weeks. To close out and burn an sLP token, the shorted mAsset needs to be provided and burned. A 1.5% fee is charged on the close-out.
The APY charts above also reveal that LP returns, whether short or long, generally remain well above 20%., thanks to MIR incentives.
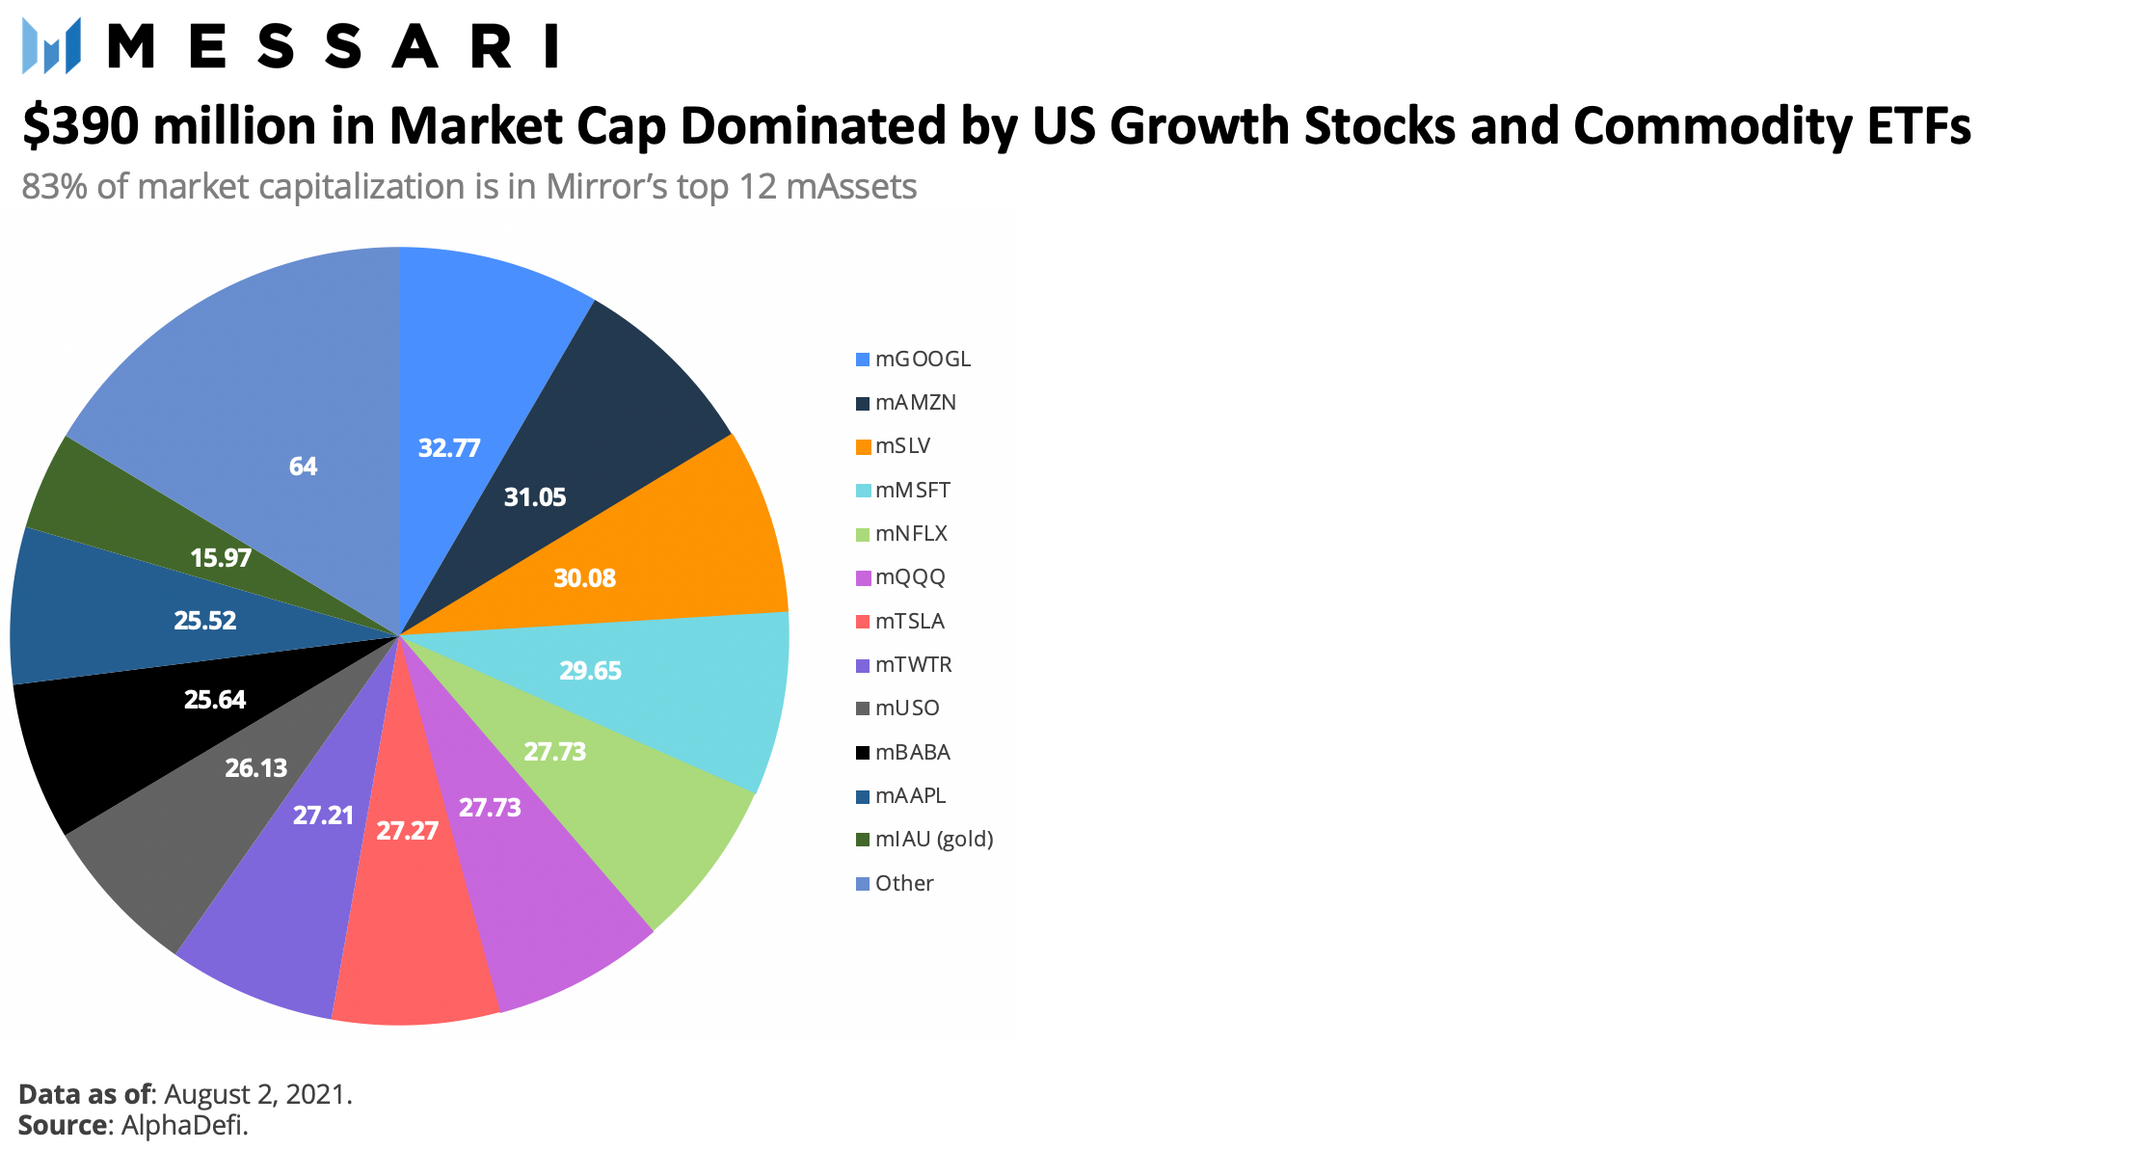
With an ARK Invest synth added in late July, there are currently 27 mAssets totalling $433 million in market cap:
Another v2 improvement was to allow for the minting and trading of pre-IPO assets, as FTX did with Coinbase. Mining requires a two-week lock up, so that the market gets a chance to settle before the mAssets can be burned and profits taken.
Growth and Competition
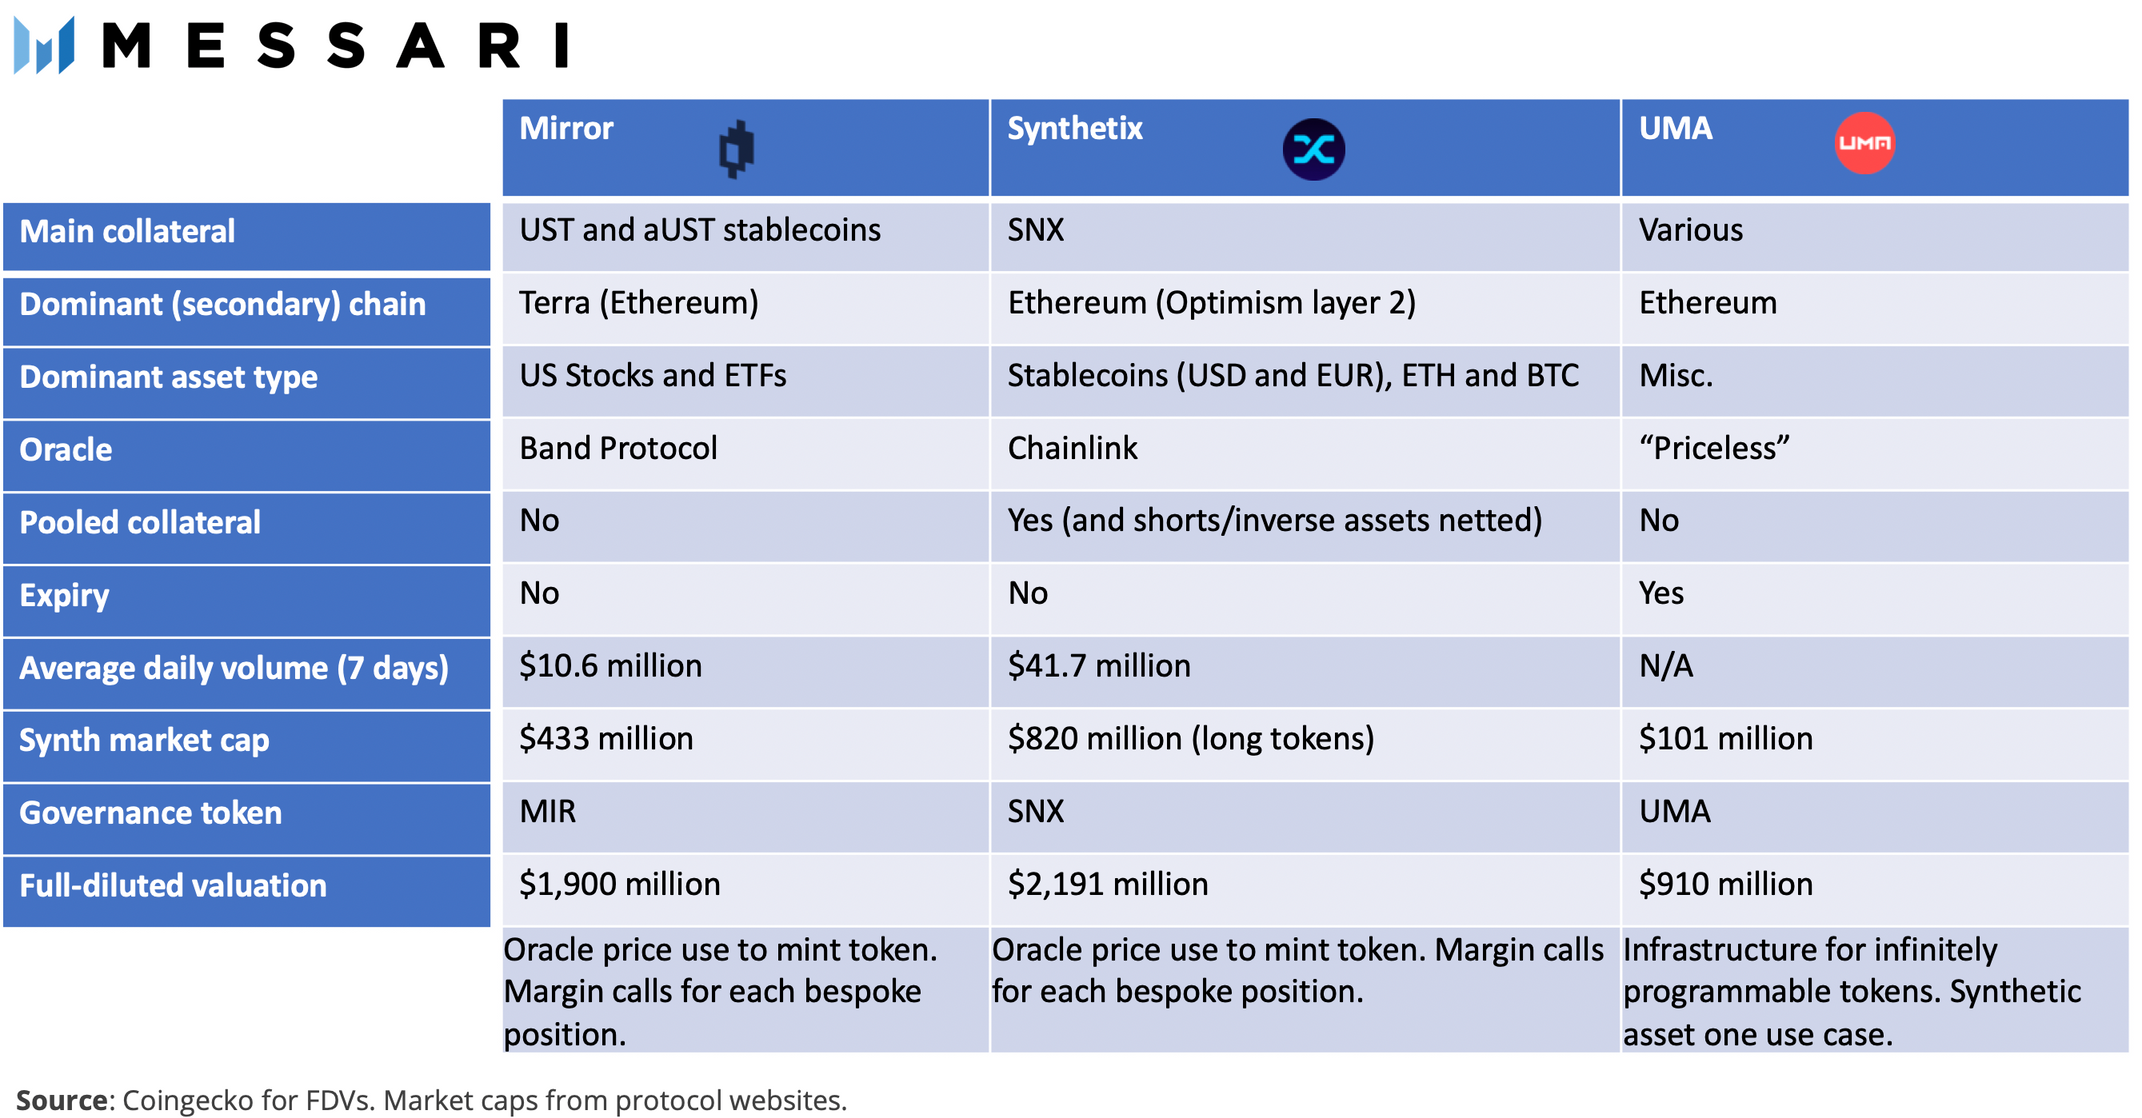
Mirror is a relative newcomer to the blockchain synthetic assets market. Synthetix and UMA have both had years of headstart.
Synthetix also focuses on minting tokens, dominated by its USD and EUR stablecoins sUSD and sEUR as well as synthetic ETH and BTC. These four account for $735 million in market cap, and are traded primarily on Curve and Kwenta.
Mirror does not mint any stablecoins, and currently has $13 million in layer 1 token synths including DOT, ETH and BTC. While Synthetix does allow for minting and trading real world assets, such as sTSLA, few of these trade regularly.
UMA aims to be a flexible toolkit to mint tokens referencing a variety of simple to complex payoffs: basically anything an oracle can measure. To date this has not included stocks or ETFs, but there has been small volume in one index of 10 stocks chosen by WallStreetBets. There is no reason, however, why protocols such as Yam Finance or PerlinX could not launch real world financial asset synths in the future using UMA’s tech. UMA specifically seeks to minimize the use of oracles using their “priceless” mechanism.
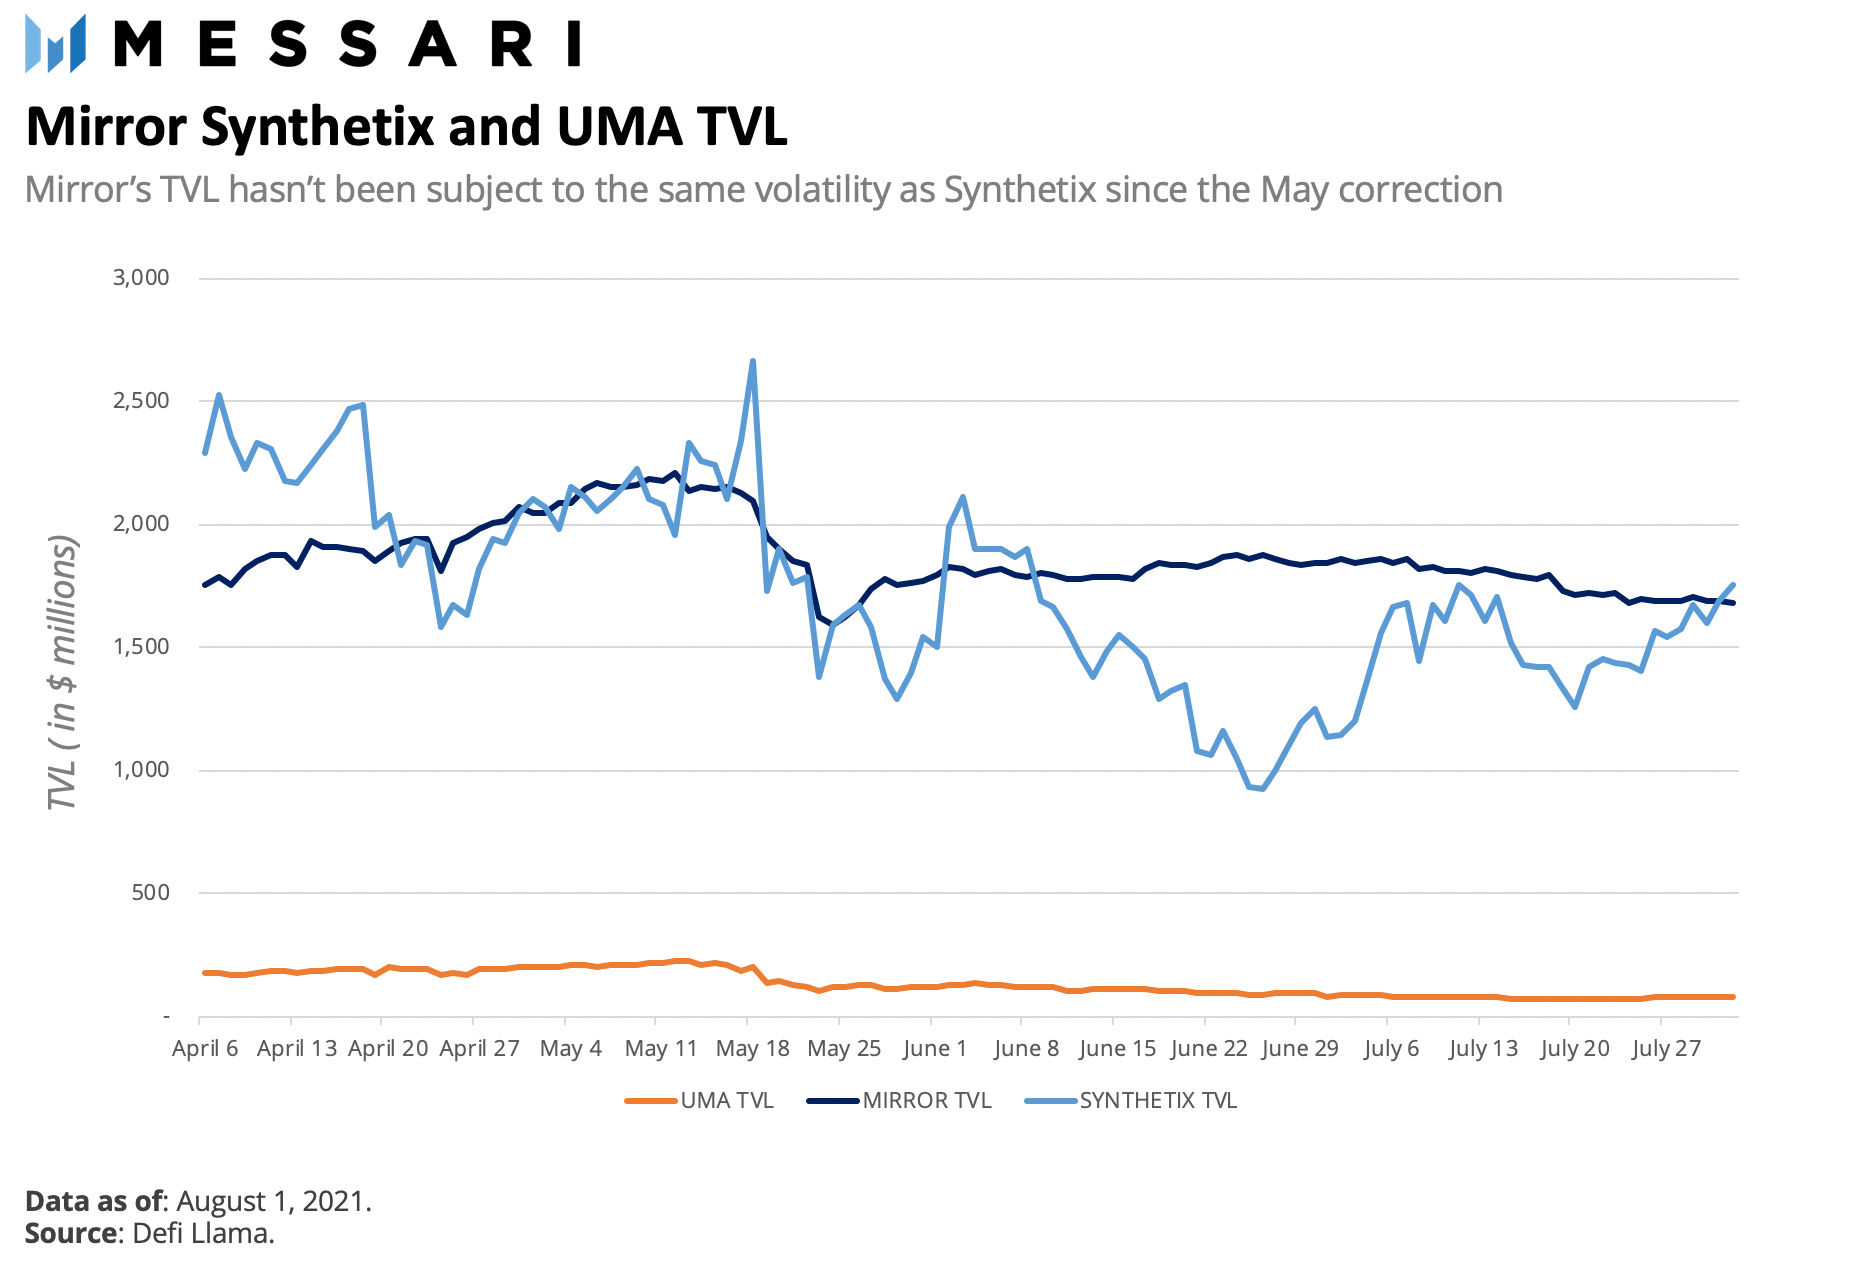
Because SNX rather than a stablecoin is used to collateralize synths on Synthetix, minimum overcollateralization ratios are much higher than Mirror’s. Mirror’s capital efficiency and focus on off-chain reference assets has allowed it to catch Synthetix in terms of total value locked (TVL). As measured by gross synthetic market cap, however Synthetix still dominates by a factor of almost 2 to 1. Measured by recent volume, Synthetix retains its dominance, with 4x the volume over the past week. Again, almost none of this is in real world assets.
In fact, Terra’s UST and Euro equivalent compete with Synthetix’s. sUSD is approximately ¼ of the total long synth market cap for Synthetix, with sEUR not far behind. At the same, it is possible that sETH and sBTC lose use cases as markets become more efficient.
Centralized exchanges such as Binance, Bittrex and FTX trade have launched synthetic stock trading. Decentralized synths, however, will always be favored by DeFi natives, those with privacy concerns and those in locations where exchanges are of questionable legal standing. Binance, having only launched syths in April with a synthetic Coinbase share, announced in July that it is withdrawing from many derivatives markets, including all synthetic stock tokens.
MIR Governance and Tokenecomics
MIR token rewards are fundamental to the development of the Mirror protocol: For the next 3.5 years, MIR inflation will reward long and short stakers as well as those active in governance. Rewards will grow the token supply from the current 78 million (just under 60 million initially airdropped in December 2020 ) to 370,575,000.
As MIR tokens were airdropped and belong to the community of users and devs, the founders at Terraform Labs, control of the protocol is in the hands of MIR stakers.
For governance, a proposal requires staking 100 MIR and MIR is required to vote. With v2, voters will be rewarded with 50% of MIR rewards, to incentivize widespread participation and allow more votes to hit the 10% quorum.
MIR stakers also earn MIR generated from CDP positions when users withdraw their collateral. Currently that withdrawal fee is 1.5%.
Challenges Ahead
Perhaps the single biggest hurdle for synthetic tokenized securities is US regulation. No stranger to cryptocurrency, US Securities and Exchange Commission (SEC) Chair Gary Gensler recently went on record to declare that single US stock trackers are securities. It is worth clarifying, however, that what the SEC cares about is preventing unregistered securities from being foisted on an ignorant public. The SEC’s reach is actually quite limited. Any regulations would not apply to Mirror’s main target market, southeast Asia. In any event, Robinhood and the discount brokerage such as TD Ameritrade are tough competitors in the US. Furthermore, commodities, currencies and indexes are subject to regulation in the US by the CFTC, and not the SEC.
More relevant for DeFi users of synths, Uniswapremoved Synthetix, UMA and Mirror assets from their front end. On the other hand, Uniswap was never a big market for Mirror’s mAssets, while the Uniswap protocol will still be able to provide liquidity when accessed through third party Dapps.
Tellingly, even with the regulatory uncertainty and clampdown on centralized entities such as Binance and, likely, Uniswap, new competitors in the synthetic asset space are launching regularly: Such as Deus Finance on Ethereum. However, the Terra/Luna/Mirror community, led by Terraform Labs’ Do Kwon has laid out an ambitious plan for further innovation in v3.
The Roadmap
The protocol’s community, devs and leadership have three key benchmarks for the future.
Mirror is seeking to power more front-end user interfaces. A recent project is planning a WallStreetBets-branded UI linking to the Mirror protocol. WSB has been successful at attracting younger and more aggressive equity traders to Robinhood and the like. Making trading cheaper and easier has paid off for Robinhood, who reported in its S1 that active users peaked at 20 million. Mirror is seeking to create the DeFi equivalent.
Leverage and income generation is possible for sophisticated users of real world securities. Leverage and leveraged yield-farming in DeFi is more challenging. Mirror is developing partnerships with other protocols in the Terra ecosystem. Mars Protocol will enable leveraged yield farming of mAssets, while Levana Finance will add leverage to the trading of mAssets themselves.
The final goal is composability. mAssets are composable tokens that can be easily combined into other tokens. Token Sets already has launched an mAsset FAANG index on Ethereum. Nebula, Phuture and others are focused on expanding mAsset-based tokenized financial products. Just as ETFs dominate single stocks for investors, perhaps mIndexes will lead mAssets.
Separately from Mirror projects, plans and partnerships, Terraform Labs will be working to improve AMM capital efficiency. mAssets exhibit significantly less volatility than most cryptoassets. As such, traditional passive AMM liquidity is even less capital efficient than for crypto. If Terraswap can evolve from its current passive AMM model to be the next Uniswap v3, the resultant capital efficiency should attract more liquidity providers and create deeper markets. Deeper markets attract traders.
Perhaps the best reason to use synths is the flexibility they offer. According to its founder Do Kwon, Terraform intends to provide use cases for traditional assets that “were previously super boring”. mAssets can be used for collateral, yield and leverage. Only time will tell how programmable financial assets will be used across DeFi, on Terra or on the other layer 1s and even layer 2s to come.
Disclaimer: On Feb. 16, 2023, the SEC stated that MIR is a "security". A couple notes: (1) Messari does not provide financial or trading advice - our services are for informational purposes only; and (2) Messari's services are impersonal - do your own due diligence. Please refer to our Terms of Use for more info.
This report was commissioned by Terra. All content was produced independently by the author(s) and does not necessarily reflect the opinions of Messari, Inc. or the organization that requested the report. The commissioning organization may have input on the content of the report, but Messari maintains editorial control over the final report to retain data accuracy and objectivity. Author(s) may hold cryptocurrencies named in this report. This report is meant for informational purposes only. It is not meant to serve as investment advice. You should conduct your own research and consult an independent financial, tax, or legal advisor before making any investment decisions. Past performance of any asset is not indicative of future results. Please see our Terms of Service for more information.
No part of this report may be (a) copied, photocopied, duplicated in any form by any means or (b) redistributed without the prior written consent of Messari®.